
Aerospace & Defense Ducting Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Aerospace & Defense Ducting Market Summary
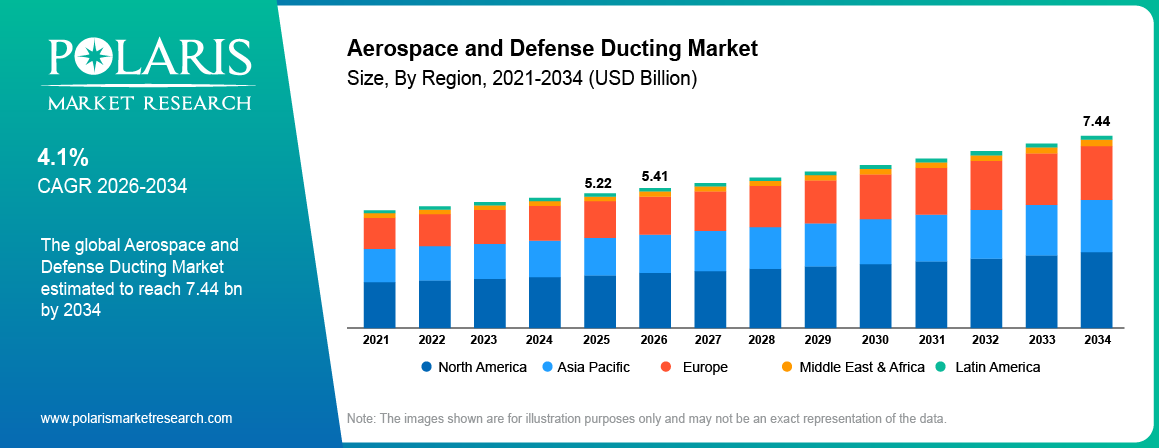
The global aerospace & defense ducting market was valued at USD 5.22 billion in 2025 and is expected to grow at a CAGR of 4.1% during the forecast period. The growth is driven by rising investment by key players, rising demand for air travel, and technological advancement.
Market Statistics
Aerospace & Defense Ducting Market Key Takeaways
- North America dominated the aerospace and defense ducting market with 38.6% share due to the presence of a robust aircraft manufacturing base, engine makers, component suppliers, and maintenance, repair, and overhaul (MRO) providers in the region
- Europe is expected to witness significant growth of CAGR 3.9% during the forecast period. The region has a majority of the manufacturer base including Airbus in France and Germany as well as the established aerospace supplier network in the United Kingdom, Italy, and the Netherlands
- Asia Pacific is expected to witness fastest growth of CAGR 5.2% during the forecast period in aerospace and defense ducting. The region is witnessing an increase in aircraft manufacturing activity, as well as a surge in air travel and defense spending
- HVAC and environmental control system (ECS) ducting is expected to witness growth of CAGR 4.3% and 4.6% respectively during the forecast period, as these facilitate regulation of temperature, ventilation, and pressure to maintain a livable environment
- Narrow-body aircraft account for the largest share of 42.7% in aerospace and defense ducting market due to the high production volumes of the Airbus A320 and Boeing 737 families
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is Aerospace & Defense Ducting?
Aerospace and defense ducting refers to ducting, tubes, hoses, and connecting parts used for carrying air, fuel, hydraulic fluid, oxygen, and other gases and liquids in aircraft and defense systems. It serves diverse purposes such as ventilating, regulating temperatures, powering aircraft engines, and transferring fluids and gases. This ducting must withstand high pressure, extreme temperatures, and vibrations while remaining as light as possible.
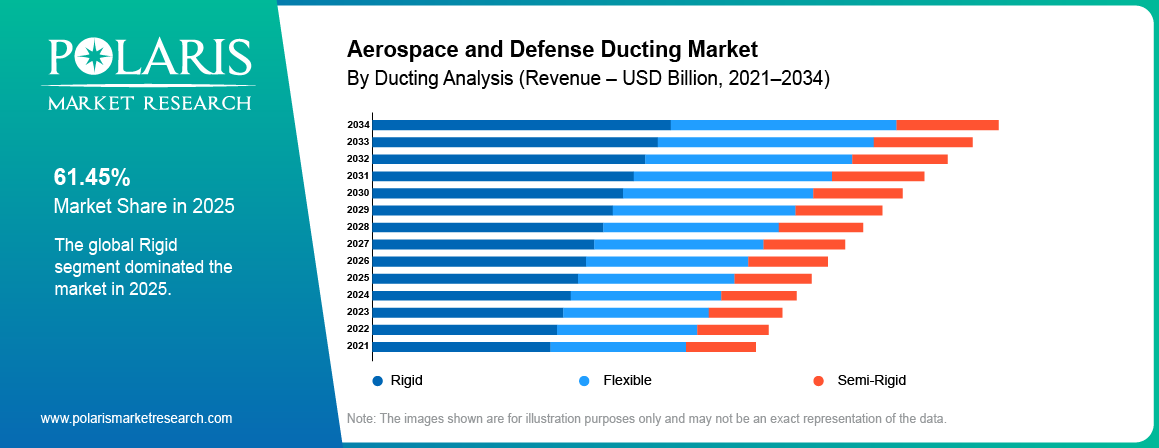
Aerospace ducting systems are made using titanium, stainless steel, nickel alloys, plastics and other advanced materials. The choice of material depends on the application, pressure, temperatures, and weight. Ducting systems can be rigid, flexible, or semi-rigid depending on the nature of the duct system and the required installation. Rigid ducts are commonly used in installations that require reinforced connections whereas flexible and semi-flexible ducts are commonly applied in narrow openings with limited space.
The ducting systems are applicable in commercial aircraft, regional aircraft, general aviation, helicopters, military aircraft, and spacecraft. The manufacturers have different needs and specifications for ducting systems. For example, commercial aircraft producers focus on reduced weight, cost, and improved fuel efficiency. However, military and spacecraft demand ducting systems that can withstand extreme operating conditions.
Market Dynamics
Driver: Rising Aircraft Production and Delivery Rates
Commercial aircraft manufacturers are ramping up their production of single-aisle and widebody aircraft in response to increased demand, as well as to address existing large order backlogs. For every aircraft produced, ducting systems are required for the airframe's ventilation system, heating and cooling systems, cabin's environmental control, and for the engines' operation. This has spurred demand for aerospace ducting suppliers, with manufacturers that have the capacity to scale their production, while also meeting quality control and certification standards.
Driver: Elevated Defense Spending and Fleet Modernization
Defense spending across NATO countries, as well as across several countries in the Asia-Pacific region is on the rise, and is supporting aircraft procurement by military organizations, as well as modernization of existing fleets, and development of new defense systems. This, in turn, is spurring demand for ducting systems that are capable of withstanding, high pressures, extreme temperatures, vibrations, and other difficult conditions. Similarly, military aircraft require upgraded ducting components, and those aging in service require replacement parts, which is another factor that is supporting the aerospace ducting market. Suppliers that are able to meet defense specifications are likely to see demand for their products rise, as the modernization drive gathers pace.
Restraint: High Qualification Costs and Long Certification Cycles
Aerospace ducting manufacturers are required to meet numerous rigorous safety and performance criteria as well as airworthiness standards to qualify products for aircraft installation. Testing and qualifying new materials and manufacturing processes for incorporation into aerospace ducting systems can be extremely time- and capital-intensive, particularly for advanced composite and additive manufacturing ducting solutions, involving additional validation steps. As a result, the high cost and long lead time of certification can be a significant barrier to entry for smaller suppliers, as well as a brake on innovation, lengthening the life cycle of metallic ducting alternatives.
Opportunity: Lightweight Composite and Thermoplastic Ducting
Aircraft manufacturers are becoming increasingly concerned with reduced weight of aircraft as much as possible in order to increase fuel efficiency, reduce costs, and reduce emissions. This creates an opportunity for composite and thermoplastic ducting solutions as they provide significant weight savings and corrosion resistance compared to traditional metal counterparts. The design has to withstand extreme temperatures, pressure and other factors, but be resistant to fire. Companies which can develop such products and get their certification for commercial aircraft use will have an advantage. The production of ducting parts which reduce weight while maintaining quality and safety standards is a potential opportunity.
Opportunity: Expansion of Aerospace Manufacturing Outside North America and Europe
The aviation sector is witnessing a rise in aircraft manufacturing outside the continent of North America and Europe, creating new markets for ducting suppliers. The growing need for aircraft parts and components from India will benefit suppliers by allowing them to qualify their production facilities directly with aircraft manufacturers. This could allow Indian companies to invest in equipment, machinery, and expertise needed to meet the quality standards of the global aviation industry. Meanwhile, China has its COMAC aircraft program which will require local ducting suppliers after the initial launch. Companies that will be able to open facilities and gain qualification in India and China will be able to take advantage of the opportunity.
Aerospace & Defense: Emerging Technology Trends
| Trend | Technical direction | Market impact |
| Thermoplastic composite ducting | Use of PEEK, PPS, PEI, and other high-performance thermoplastics for lightweight, corrosion-resistant, and complex duct structures | Reduces part count and manufacturing time while improving impact resistance and recyclability. Fire, smoke, pressure, and thermal-cycle qualification remain major barriers. |
| Carbon-fiber and glass-fiber composites | Use of CFRP, fiberglass, aramid, and hybrid laminates in applications where weight, corrosion resistance, and acoustic performance are important | Attractive for ECS, cabin-air, engine nacelle, UAV, and advanced-air-mobility platforms. Metal remains preferred in severe fire zones and very high-temperature applications. |
| Additive manufacturing | Production of complex bends, internal channels, integrated supports, lattice structures, manifolds, and rapid tooling using polymer and metal additive processes | Particularly suitable for prototypes, low-volume defense parts, tooling, brackets, manifolds, and geometries with high machining or assembly content. Certification, porosity, anisotropy, inspection, and repeatability remain concerns. |
| Automated composite fabrication | Expansion of automated fiber placement, automated tape placement, resin-transfer molding, vacuum-assisted processing, compression molding, and out-of-autoclave manufacturing | Improves repeatability, reduces scrap, and supports higher production volumes. Tooling economics favor aircraft and defense programs with recurring production. |
| Hybrid metal-composite ducting | Combination of metal liners, fittings, couplings, flexible sections, and composite shells | Balances fire resistance, pressure capability, weight, and manufacturability. Hybrid architectures are likely to remain important during the transition to fully composite duct systems. |
| Integrated thermal insulation | Integration of structural walls, thermal barriers, insulation layers, fire protection, and acoustic treatments into duct assemblies | Reduces assembly count and installation weight while improving thermal efficiency and cabin or equipment-bay noise performance. |
| Acoustic optimization | Use of microperforated liners, tuned acoustic treatments, lightweight absorbers, and flow-optimized duct geometries | Supports lower cabin noise and improved engine integration. Acoustic materials must also meet fire, moisture, erosion, and maintainability requirements. |
| Smart ducting and embedded sensing | Integration of pressure, temperature, vibration, strain, leakage, and flow sensors with aircraft health-monitoring systems | Enables predictive maintenance and early detection of leakage, blockage, delamination, overheating, and clamp failure. Sensor survivability and certification remain key issues. |
| Electrification-ready thermal management | Development of compact ducts for electric compressors, batteries, fuel cells, high-power electronics, and hybrid propulsion | Creates demand for thermally resilient ducts, cooling manifolds, high-voltage isolation solutions, and lightweight heat-management structures. |
| High-temperature alloys and advanced materials | Use of titanium, nickel alloys, ceramic coatings, and metal-matrix composites for severe-temperature and propulsion applications | Expands opportunities in engines, missiles, spacecraft, hypersonic systems, and high-temperature propulsion. Cost and manufacturability remain limitations. |
| Sustainable manufacturing and materials | Adoption of recyclable thermoplastics, low-waste near-net-shape forming, additive tooling, repairable designs, and lower-energy processing | Supports OEM sustainability targets and government procurement objectives, although aerospace qualification and end-of-life recovery systems remain developing. |
| Digital manufacturing and digital thread | Use of model-based definition, automated inspection, laser scanning, digital work instructions, and serial-number traceability | Improves first-pass yield, configuration control, and nonconformance analysis for complex duct assemblies. |
Source: Polaris Market Research Analysis
Key Segments
By Application: Airframe
Airframe ducting dominated with largest share of 46.8% in 2025. These are used in aircraft structures and facilitate distribution of air and other fluids between components. Every newly built aircraft makes use of airframe ducting assemblies, which directly ties aircraft production rates to market demand. Increasing production rates of narrow-body and widebody aircraft programs will therefore propel the growth of this segment.
HVAC systems and environmental control system (ECS) ducting is expected to witness growth of CAGR 4.3% and 4.6% respectively during the forecast period, as these facilitate regulation of temperature, ventilation, and pressure to maintain a livable environment. Manufacturers are constantly looking to improve these systems to be able to provide the best possible conditions for passengers, crews, and equipment.
Engine segment is expected to witness growth of CAGR 4.5% during the forecast period. This ducting are used in engine bleed-air systems, as well as auxiliary power unit (APU) exhaust lines, and have more stringent demands placed upon them because of the extreme conditions they are exposed to. While they represent a smaller overall share of demand, their production involves more specific requirements, leaving more room for manufacturers with the necessary expertise to benefit from the opportunity.
By Aircraft: Narrow-Body Aircraft
Narrow-body aircraft account for the largest share of 42.7% in aerospace and defense ducting market due to the high production volumes of the Airbus A320 and Boeing 737 families, which are widely used on domestic and short- to medium-haul routes. Their strong presence in airline fleets and continued demand for new aircraft support the need for ducting systems across multiple applications. The expansion of China's COMAC C919 program may provide an additional source of demand as production increases.
Widebody aircraft segment is expected to witness growth of CAGR 3.8% during the forecast period. They generally require more complex ducting systems because of their larger size and cabin configurations. However, their lower production volumes limit their overall contribution compared with narrow-body aircraft. Military aircraft and spacecraft account for smaller shares of total demand but remain important segments due to their specialized requirements. These platforms often need ducting systems made from high-performance aerospace materials that can withstand demanding operating conditions and meet strict qualification standards.
Regional Insights
North America Aerospace & Defense Ducting Market Trends
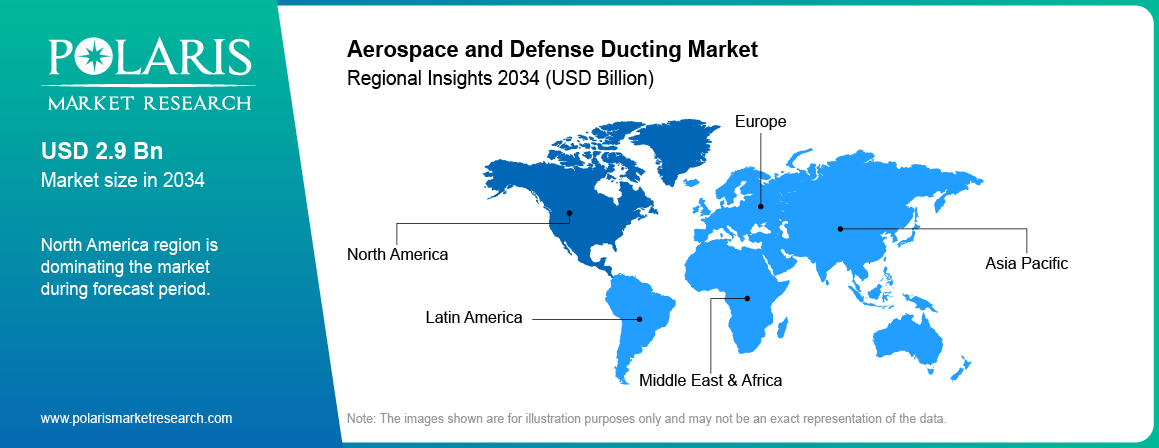
North America dominated the aerospace and defense ducting market with 38.6% share due to the presence of a robust aircraft manufacturing base, engine makers, component suppliers, and maintenance, repair, and overhaul (MRO) providers in the region. Further, the U.S. accounts for a significant share of the regional demand for aerospace and defense ducting. Additionally, North America has been one of the first regions to embrace the use of lighter composite ducting systems The demand in the region is further anticipated to be driven by defense spending, aircraft production, and the replacement of ducting components. Moreover, as aircraft count within regional commercial airlines increases, and aircraft maintenance becomes more frequent, the need for replacement ducting will also rise.
Europe Aerospace & Defense Ducting Market Trends
Europe is expected to witness significant growth of CAGR 3.9% during the forecast period. The region has a majority of the manufacturer base including Airbus in France and Germany as well as the established aerospace supplier network in the United Kingdom, Italy, and the Netherlands. Ongoing aircraft manufacturing and deliveries result in consistent demand for ducting components for commercial aviation. Increased defense spending contributes to the demand in the European region as countries look to upgrade their current fleet of aircraft and develop new programs for military aviation.
Asia Pacific Aerospace & Defense Ducting Market Trends
Asia Pacific is expected to witness fastest growth of CAGR 5.2% during the forecast period in aerospace and defense ducting. The region is witnessing an increase in aircraft manufacturing activity, as well as a surge in air travel and defense spending. The growing aircraft manufacturing sector in China, as represented by the gradual commissioning of the COMAC C919 program, is also driving demand for ducting components and associated systems, thereby driving the regional growth.
Middle East & Africa Aerospace & Defense Ducting Market Trends
The Middle East and Africa region is expected to witness growth of CAGR 3.5% during the forecast period driven by airline fleet expansion, increased defense procurement, and investments in local aerospace manufacturing and maintenance capabilities. Countries such as Saudi Arabia, the United Arab Emirates, and Israel are important markets due to their investments in aviation and defense infrastructure. Governments across the region are also working to reduce their reliance on overseas suppliers by developing domestic aerospace capabilities. These efforts are creating opportunities for local manufacturers and international suppliers seeking to establish regional operations. As fleet expansion and defense modernization continue, demand for aircraft components, including ducting systems, is expected to increase.
Latin America Aerospace & Defense Ducting Market Trends
Latin America is expected to witness a steady growth during the forecast period, supported by Brazil’s commercial and executive aircraft production and Mexico’s role as a parts and assembly base for North American programs. Embraer delivered 244 aircraft in 2025, including 78 commercial jets, 155 executive jets and 11 defense aircraft, and ended the year with a record backlog of USD 31.6 billion. Each aircraft needs ducting for environmental control, engine and airframe systems, which ties regional ducting demand to Embraer’s production rate. Mexico hosts nearly 400 aerospace companies across 19 states, concentrated in Querétaro, Chihuahua, Baja California, Sonora and Nuevo León. Its industry focuses on parts and assemblies for final systems, and about 80% of its aerospace exports go to the United States. Mexican ducting demand therefore follows North American aircraft production more closely than regional airline demand.
Aerospace & Defense: Regulations by Key Regions
| Region | Principal authorities and frameworks | Ducting-relevant requirements | Commercial implication |
| United States | FAA; 14 CFR Parts 21 and 25; FAA Advisory Circulars; PMA and TSOA | FAR 25.853 and Appendix F cover flammability of air ducting, insulation, joints, and related interior materials. FAR 25.869 addresses fire protection of systems, while fire-zone ducts generally require fireproof construction. | Suppliers must provide material test reports, configuration control, traceability, qualification data, and installation-specific compliance evidence. Replacement or modification parts may require PMA, while applicable standardized components may require TSO approval. |
| European Union and EASA states | EASA; CS-25 for large aeroplanes; Part 21; AMC/GM compliance guidance | CS-25 requires ventilating ducts passing through fire zones to be fireproof. It also addresses heater ducts, combustion-air ducts, flammable-fluid exposure, air-intake drainage, and fire, smoke, and toxicity performance. | EASA certification is broadly aligned with FAA requirements, but separate validation, approved design data, and EASA production or maintenance arrangements may be required. |
| United Kingdom | UK CAA; UK Part 21; UK-adopted certification specifications | Certification generally uses the applicable CS-25 or equivalent UK certification basis. Fire, smoke, toxicity, flammable-fluid isolation, and continued-airworthiness evidence are important for duct assemblies. | Suppliers must determine whether the aircraft, design approval, production approval, and installation fall under UK CAA, EASA, FAA, or bilateral arrangements. |
| Canada | Transport Canada Civil Aviation; CAR 525; Airworthiness Manual Chapter 525 | Canadian requirements include self-extinguishing air ducting and joints, fireproof ventilating ducts through fire zones, heater-duct containment, and protection against flammable-fluid ingress. | Requirements are substantially harmonized with FAA and EASA standards, although Canadian validation and approved-organization requirements must be checked for each program. |
| India | DGCA; Indian aircraft certification and continuing-airworthiness requirements | Ducting suppliers generally demonstrate compliance through the aircraft type-certification basis accepted by DGCA, often incorporating FAA- or EASA-derived standards. | India is important for MRO, aerospace manufacturing, and defense programs. Local suppliers require DGCA or OEM approvals, AS9100-quality systems, traceability, and customer-specific qualification capabilities. |
| China | CAAC; CCAR-25; CAAC design and production-approval procedures | CCAR-25 provides the principal transport-aircraft airworthiness basis. Composite APU and propulsion applications may require additional evidence regarding fire safety and toxic-gas generation. | Market access depends on CAAC validation, local OEM requirements, supply-chain localization, and technology-transfer or export-control considerations. |
| Japan | JCAB; Civil Aeronautics Law; Civil Aeronautics Regulations; Airworthiness Inspection Manual | JCAB standards incorporate equivalents of major international airworthiness requirements. JCAB distinguishes aircraft type certification from approvals for engines, critical parts, and other components. | Suppliers serving Japanese aircraft programs should plan for JCAB-recognized design, manufacturing, and component-approval routes. |
| International supply chain | ICAO principles; IAQG AS9100 series; Nadcap; OEM specifications | AS9100 standardizes aerospace quality-management requirements. Nadcap is commonly used for special processes such as welding, heat treatment, composites, nondestructive testing, chemical processing, and surface treatment. | Certification is a market-access requirement but does not replace product certification. Buyers should verify AS9100 registration, applicable Nadcap scopes, customer approvals, process capability, and counterfeit-part controls. |
Source: Polaris Market Research Analysis
Competitive Landscape
The competitive landscape of the aerospace and defense ducting market is changing as larger aerospace companies acquire specialist manufacturers. Through these acquisitions, companies aim to expand their product portfolios, strengthen their technical capabilities, and supply a wider range of components to aircraft manufacturers. This approach allows them to increase their presence across aircraft programs rather than relying solely on organic growth. As a result, ownership changes and consolidation are becoming important factors shaping competition in the market.
Another important trend is the expansion of aerospace manufacturing beyond traditional centers in North America and Europe. Indian suppliers, for example, are gaining direct qualification for tube and duct assembly programs with major aircraft manufacturers, including Boeing and Airbus. This marks a shift from their earlier role as lower-tier subcontractors and creates opportunities to participate more directly in global aerospace supply chains. These developments also reflect the growing capabilities of suppliers in emerging manufacturing markets.
Changes in company ownership are also affecting how market participants operate and compete. Some established ducting manufacturers have been acquired or have moved under new ownership structures. As a result, company names, business relationships, and market positions may have changed since earlier industry reports were published. These developments make it important to review supplier ownership and corporate structures when assessing the competitive landscape.
Vendor Positioning
| Vendor | Positioning | Ducting strengths and applications | Strategic advantages | Constraints |
| Arrowhead Products | Specialist ducting and propulsion-line supplier | High-pressure metallic, flexible metallic, elastomeric, and composite ducts; bleed air, ECS, anti-ice, APU, missile, rocket, and cryogenic lines | Deep ducting specialization, high-pressure capability, space-launch and defense relevance, engineering-to-production integration | Concentrated portfolio; exposed to aerospace program cycles |
| Eaton Corporation | Diversified fluid- and power-management supplier | Hydraulic, pneumatic, fuel, ECS, thermal-management, and high-pressure fluid-conveyance systems | Broad aircraft-systems portfolio, global customer access, qualification infrastructure | Ducting is one part of a broad portfolio; competes with Parker, ITT, Safran, and specialists |
| EnCore Aerospace | Composite structures and components specialist | Composite ducting and assemblies, aircraft interiors, structural components | Composite manufacturing capability; strong fit with lightweighting programs | Product-level differentiation and global capacity need verification by application |
| Parker Hannifin Corporation (Parker Aerospace) | Motion, fluid-, and thermal-management supplier | Flexible and rigid fluid conveyance, hydraulic and pneumatic systems, thermal-management components, seals, hoses, duct assemblies | Large installed base, system integration, global support, strong OEM access, aftermarket capabilities | Ducting competes with other Parker product families and outside suppliers |
| GKN Aerospace | Aerostructures, engine-structure, and composites supplier | Composite and metallic structures, engine components, nacelle applications, air-management structures | Global manufacturing footprint, composite expertise, commercial and defense platform access | Ducting often embedded in larger structures, not sold standalone |
| ITT Inc. — Aerospace | Engineered components and fluid-management supplier | Fluid conveyance, connectors, seals, pumps, valves, and duct-related systems for demanding environments | Engineered-component heritage, precision manufacturing, commercial and defense exposure | Broad scope; complete ducting solutions may require combining several capabilities |
| PFW Aerospace GmbH | Specialist piping and ducting supplier | Aircraft piping, ducts, tubes, engine and air-management systems, formed metallic components | Strong European position, complex tube and duct manufacturing, established OEM relationships | European production-cost exposure; dependence on large aircraft and engine programs |
| RMB Products, Inc. | Flexible ducting and hose specialist | Flexible air ducts, high-temperature hoses, silicone and elastomeric solutions for aircraft and defense | Flexibility, quick-turn engineering, high-temperature capability, niche responsiveness | Smaller scale than Eaton or Parker; assess qualification depth and global capacity by application |
| Safran | Major aerospace systems and propulsion group | Engine, nacelle, equipment, cabin, ECS, thermal, and propulsion ducting across business units | Strong OEM position, propulsion integration, global program access, certification capability | Competes for integrated systems rather than commodity duct supply |
| Saint-Gobain Performance Plastics | Advanced polymer and elastomer materials supplier | High-performance hoses, tubing, seals, fluoropolymer and silicone products, insulation | Materials science, chemical resistance, temperature capability | Typically a materials or component supplier, not a full duct-system integrator |
| SEKISUI Aerospace | Composite aerostructures specialist | Composite ducting and lightweight components for aircraft and defense platforms | Composite design, fabrication, lightweighting, integration with larger structures | Program concentration, long qualification lead times, low standalone-ducting visibility |
| Unison Industries | Engine-component supplier associated with GE Aerospace | Engine tubing, manifolds, ducts, ignition systems, precision fabrication | Engine-platform integration, precision manufacturing, strong engine-market access | Engine-centric rather than cabin-ECS-centric; depends on engine program content |
| Howmet Aerospace | Aerospace metals and engine/airframe component supplier | Nickel, titanium, and aluminum components, including duct-related engine, exhaust, structural, and formed parts | Strong metallurgy, casting, forging, machining, engine-component qualification | More upstream and component-oriented than a pure duct-system provider |
| Rangsons Aerospace | India-based manufacturing and fluid-conveyance supplier | Ducting, tubes, fluid-conveyance systems, fabricated assemblies, defense and aerospace components | India manufacturing base, cost competitiveness, localization potential, regional supply-chain access | Smaller global footprint and lower visibility than Western tier-1s; still building approvals, export capability, and program diversification |
Source: Polaris Market Research Analysis
List of Key Companies
- Arrowhead Products
- Eaton Corporation
- EnCore Aerospace
- GKN Aerospace
- ITT Inc. (Aerospace)
- Parker Hannifin
- PFW Aerospace GmbH
- RMB Products, Inc.
- Safran
- Saint-Gobain Performance Plastics
- SEKISUI Aerospace
- Unison Industries
- Howmet Aerospace
- Rangsons Aerospace
Recent Industry Developments
- October 2026, First Class Air partnered with Vertical Aerospace, expanding its aircraft structural repair, engineering, and fabricated parts manufacturing capabilities. The deal strengthened its maintenance services, increased in-house processing capacity, and broadened customer support across global aviation markets. (Source: bignewsnetwork.com)
- March 2026, ROBOZE launched its ARGO 500 HYPERSPEED MISSION READY platform, to manufacture high-performance aerospace and defense components. The system enabled on-demand production of lightweight parts, including advanced ducting, using durable polymers and carbon-fiber composites. (Source: prnewswire.com)
- December 2025, Howmet Aerospace agreed to acquire Consolidated Aerospace Manufacturing (CAM) from Stanley Black & Decker for approximately USD 1.8 billion, adding CAM's fastener, fluid-fitting, and ducting-component lines used on Boeing 737 MAX and 787 programs; the deal closed in April 2026. (Source: howmet.com)
Aerospace & Defense Ducting Market Segmentation
By Aircraft Outlook (Revenue, USD Billion, 2021–2034)
- Narrow-body Aircraft
- Wide-body Aircraft
- Regional Aircraft
- General Aviation
- Helicopter
- Military Aircraft
- Spacecraft
By Application Outlook (Revenue, USD Billion, 2021–2034)
- Airframe
- HVAC
- Environmental Control Systems
- Engine
- Others
By Material Outlook (Revenue, USD Billion, 2021–2034)
- Titanium Ducts
- Stainless Steel Ducts
- Nickel Alloy Ducts
- Composite Ducts
- Others
By Ducting Outlook (Revenue, USD Billion, 2021–2034)
- Rigid
- Flexible
- Semi-Rigid
By Regional Outlook (Revenue, USD Billion, 2021–2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Aerospace & Defense Ducting Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 5.22 Billion |
| Market Size in 2026 | USD 5.41 Billion |
| Revenue Forecast by 2034 | USD 7.44 Billion |
| CAGR | 4.1% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Aerospace & Defense Ducting Market FAQ's
The market was valued at USD 5.22 billion and is expected to reach USD 7.44 billion by 2034.
The market is expected to witness growth of CAGR 4.1% during the forecast period.
It covers the engineered tubing, hose, and fitting assemblies that carry air, fuel, hydraulic fluid, and oxygen through an aircraft's airframe, HVAC, environmental control, and engine systems, across both commercial and military platforms.
Growth is being driven primarily by rising commercial aircraft production rates working through record order backlogs, alongside elevated defense spending that is funding fleet modernization and new platform development across North America, Europe, and Asia Pacific.
The main materials are titanium, stainless steel, nickel alloys such as Inconel 718, and composite materials including thermoplastic and thermoset variants. Nickel alloy ducts currently see the widest use in HVAC and environmental control applications, while composite ducting is growing the fastest as OEMs prioritize weight reduction.
North America leads with 38.6% share, supported by its concentration of aircraft OEMs, engine manufacturers, and MRO providers, while Asia Pacific is growing the fastest on the strength of China's expanding aircraft production and India's emergence as a qualified supplier base for Boeing and Airbus.
Rigid ducting is used for structural, high-pressure runs that don't need to flex; flexible ducting is designed to move with airframe vibration and thermal expansion; and semi-rigid ducting sits between the two, offering some flexibility while holding its shape better than a fully flexible design — the choice generally comes down to where in the aircraft the duct sits and how much movement it needs to accommodate.
Key suppliers include Arrowhead Products, Eaton, GKN Aerospace, Safran, Parker Hannifin (including its Exotic Metals Forming and Meggitt businesses), Stelia Aerospace, Saint-Gobain Performance Plastics, SEKISUI Aerospace, and Unison Industries, alongside newer entrants such as Howmet Aerospace and Rangsons Aerospace.
Narrow-body aircraft account for the largest share, reflecting the high production volumes of the Airbus A320 and Boeing 737 families, which together represent the bulk of commercial aircraft currently on order worldwide.
Composite ducting is expected to be the fastest-growing material category through the forecast period, as OEMs and suppliers continue qualifying lightweight thermoplastic and thermoset designs to meet fuel-efficiency and weight-reduction targets across both commercial and military platforms.

Download Sample Report of Aerospace & Defense Ducting Market
Please fill out the form to request a customized copy of the research report.


