
Flame Retardants Market Share, Size, Trends, Industry Analysis Report, 2026 - 2034
REPORT DETAILS
What is the current market size?
Flame retardants market size was valued at USD 10.34 billion in 2025 and is projected to reach USD 18.18 billion by 2034, growing at a CAGR of 6.49% from 2026 to 2034. Improved fire-safety standards and increasing plastic penetration in the buildings and construction, electronics, and transportation industries are fueling the flame retardants market at the global level.
Market Statistics
Key Takeaways
- Aluminum trihydrate held the largest share of 29.84% in 2025, owing to its demand for halogen-free, low-smoke formulations in construction, electronics, cables, and transportation applications.
- The epoxy segment captured a substantial 24.38% share in 2025, as a result of its increasing application in electronic components, coatings, adhesives, composites, and electrical insulation systems.
- The electrical and electronics division commanded a 27.84% market share in 2025 , on account of the rising need for improved fire safety standards for electronic equipment, cables, circuit boards, and electrical enclosures.
- Asia Pacific led the global market with a 46.28% market share in 2025, owing to the expanding electronics production, construction activities, automotive manufacturing, and stringent industrial fire safety regulations in the region.
- North America held a 22.84% market share in 2025, driven by stringent building codes, electrical safety standards, and the demand for environmentally safer flame retardant formulations.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
Flame Retardants Market Definition
The flame retardants market is a mixture of chemicals and materials that are applied to plastics, textiles, coatings, rubber and construction products to increase the time it takes for the material to ignite, suppress the combustion process, reduce the rate at which flames spread and enhance fire protection in electrical, automotive, building, transportation, industrial and consumer applications globally.
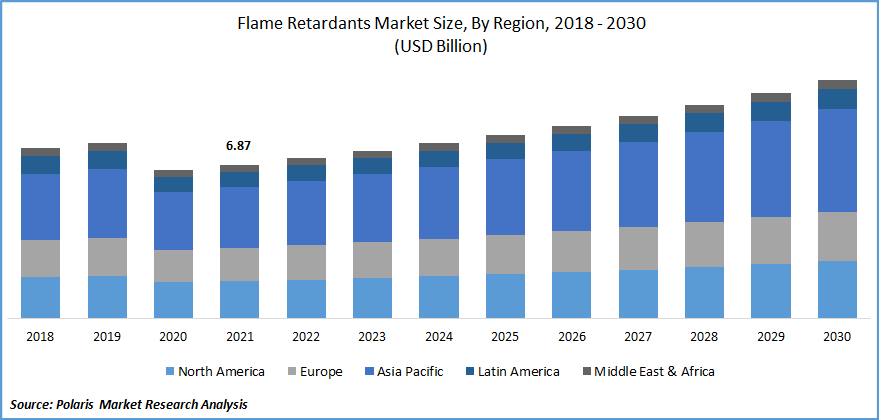
Source: Polaris Market Research Analysis
Know more about this report: Download Sample Report
They are utilized in varied applications such as furniture foam, electrical enclosures, e-mobility solutions, electronic components, and building products, among others. They are increasingly being incorporated in batteries for e-mobility, consumer electronics, and energy storage for improved safety and stability. The use of retardants in polymer housings, components, and electrolytes also enhances the performance of battery systems. Several leading companies in the market offer a wide range of phosphorus and bromine-based retardants for applications in electric vehicles.
There has been reduced demand for flame retardants during the pandemic owing to a negative impact on industries such as automotive and construction, among others. The global market was affected by transportation delays and operational challenges across the globe. There was disruption of the supply chain and restriction on manufacturing activities owing to the introduction of lockdown restrictions and low availability of workforce.
However, the industry is expected to experience growth with the relaxation of lockdown restrictions and economic growth. Factors such as favorable safety regulations and the development of sustainable solutions would support the growth of the industry during the forecast period.
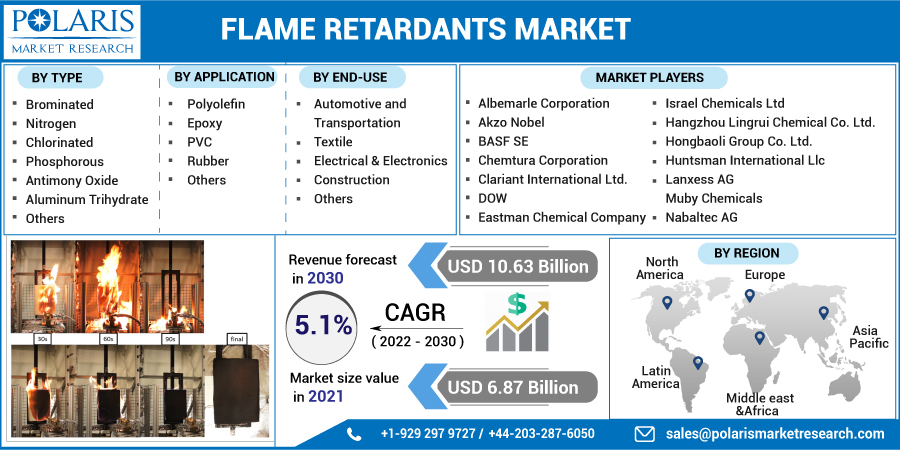
Source: Polaris Market Research Analysis
Know more about this report: Download Sample Report
Industry Dynamics
Driver: Stringent Fire-Safety Regulations and Building Codes
Fire-safety standards for buildings, vehicles, electrical equipment, textiles, and consumer goods are being made more stringent by governments and regulatory agencies, which is driving constant demand for flame-retardant materials. Building codes increasingly mandate ignition resistance, smoke development, and flame spread criteria for insulations, cables, wall covering materials, roofing materials, and building materials such as wood in structural members. Comparable rules are in place for cars, mass transit, planes, electronics, and industrial machinery, where combustibles such as polys were already creating inflated safety risks. As a result, producers are adding flame retardants to plastic, coatings, adhesives, foam, rubber and composite products to meet the mandatory safety approvals. An increasing construction of high-rise buildings, data centers, manufacturing plants, and transportation infrastructure is contributing to the growth of materials that are to be subject to these standards. The influence of the compliance demands is more evident in North America and Europe, while developing economies are also tightening up building and electrical standards. Increasing regulatory enforcement and heightened awareness of the potential for fire related hazards are prompting these markets to increasingly utilize, in this application and across the product spectrum, high performance certified flame retardant formulations.
Driver: Expanding Electrical, Electronics, and Electric Vehicle Production
The rapid expansion of electronics and electric mobility is boosting the need for better flame-retardant materials. Circuit boards, cables, connectors, device casings, insulation, and other plastic parts can overheat or be affected by electrical faults, so flame retardants help limit the risk of ignition and slow the spread of fire.
Electric vehicles add further demand. Battery packs, high-voltage connections, charging equipment, power electronics, and cooling systems all need dependable fire protection. To meet safety standards without harming electrical performance or durability, manufacturers are turning to phosphorus- and nitrogen-based additives, aluminum trihydrate, and other halogen-free options.
Growth in data centers, telecommunications, renewable energy, and smart appliances is also increasing the use of fire-resistant plastics and cable materials. As devices become smaller, more powerful, and prone to greater heat buildup, suppliers are working on additives that provide strong protection in smaller amounts while preserving strength, ease of manufacturing, and electrical insulation.
Opportunities: Transition Toward Halogen-Free and Sustainable Flame Retardants
Changes in the regulation of certain brominated and chlorinated compounds are presenting high value opportunities for halogen-free flame retardant suppliers. Environmental impact, chemical legislation, recycling directives and customers sustainability policies are pressuring manufacturers towards using phosphorus, nitrogen, mineral and bio based alternatives. Aluminum trihydrate (ATH) and magnesium hydroxide are being adopted as they provide flame suppression and smoke reduction advantages while having more environmentally acceptable profiles. Phosphorus- and nitrogen-based formulations dedicated to engineering plastics (EP), coatings, polyurethane (PU) foams, textiles, and electrical components are being researched and developed. Suppliers can meet new demand for formulations that do not include substances of very high concern, that are compatible with recyclable polymers, and that have the effect of allowing lower additive concentrations. There are huge opportunities in electric vehicles, green buildings, low-smoke cables, renewable energy equipments and consumer electronics. Application testing, regulatory approval, and tailored polymer formulations are areas where companies can set themselves apart from commodity suppliers. Collaboration with resin manufacturers and machinery producers will provide an even greater impetus to the commercial exploitation of safer, high-performance flame retardant systems.
Opportunities: Growth in Emerging Economies and Infrastructure Development
Rapid urban and industrial development and growth in manufacturing in the Asia Pacific region, Latin America, and the Middle East and Africa offer strong prospects worldwide for flame-retardant producers. Emerging markets are also focusing on investment in homes and office space, transport systems, renewable energy initiatives, communications infrastructure, factories and data centres. Such projects demand large quantities of insulation, plastics, cables, coatings, composites, and electrical parts that are sufficiently fire retardant. China, India, Southeast Asia, Saudi Arabia, the UAE, Brazil, and Mexico are promising markets as governments raise safety standards and encourage local manufacturing. Vendors can capitalize on this potential by developing regional production, technical services centers, distribution relationships, and application development capabilities. Local production can minimize transportation costs, increase product availability, and even facilitate formulations based on regional materials and process conditions. Manufacturers may also partner with producers of building materials, cable manufacturers, automotive suppliers and electronics firms to lock in demand over the longer term. Stricter implementation of fire codes and greater awareness about building safety will help advance these markets toward more high-end solutions, flame retardant-certified solutions.
Restraint: Environmental, Health, and Regulatory Concerns
Concerns about the effects of certain flame retardant chemicals on the environment and human health may limit market growth and result in higher compliance costs. A number of brominated, chlorinated, and organophosphorus compounds are under attention because of their persistence, potential to bioaccumulate, toxicity, smoke generation or emission from finished products. Certain chemicals are being reviewed or banned by regulatory bodies, causing manufacturers to re-formulate products, undergo further testing, and submit more extensive safety documentation. Formulating replacements can be costly and technically demanding since flame retardance has to be retained without adversely impacting polymer strength, color, electrical properties, recyclability, or processing efficiency. Halogen-free solutions may need higher levels of loading, which could lead to higher material costs and an alteration of the processing characteristics. Varying regulations in North America, Europe, and Asia also add to the challenge for companies that serve global markets. Negative consumer sentiment towards chemical additives could also provide additional incentive for product manufacturers to minimize flame retardant levels where regulatory requirements allow. Therefore, suppliers must continually invest in toxicology, lifecycle evaluation, certification, and sustainable chemistry to enable regulatory compliance and customer acceptance.
Report Segmentation
The market is primarily segmented based on type, application, end-use, and region.
| By Type | By Application | By End-Use | By Region |
|
|
|
|
Source: Polaris Market Research Analysis
Know more about this report: Download Sample Report
The Aluminum Trihydrate segment accounted for a significant market share
On the basis of type, the market is segmented into brominated, nitrogen, chlorinated, phosphorous, antimony oxide, aluminum trihydrate, and others. Aluminum trihydrate accounted for the largest share of 29.84% in 2025 owing to its capability of high flame retardance and smoke suppression. It offers properties such as non-corrosiveness, decreased toxicity, affordability, and high dispersibility.
Alumina trihydrate is used in varied applications as it does not emit toxic smoke upon combustion. It is used in applications such as automobiles, draperies, furniture, and wall coverings, among others. It is also incorporated in acrylic rubbers, PVC flooring, and thermoplastic cable sheathing, among others.
Epoxy segment accounted for the largest market share
The epoxy segment accounted for a significant share of 24.38% in 2025. The wide use of epoxy in the marine, construction, aerospace, and automotive sectors boosts the growth of this segment. There is expected to be a rise in demand for epoxy from the automotive sector during the forecast period.
The development of high-performing and lightweight vehicles by market players and the introduction of fire safety regulations associated with automobiles accelerate the growth of this segment.
The Electrical & Electronics segment dominated the global market in 2025
Based on end-use, the global market has been segmented into automotive and transportation, textile, electrical & electronics, construction, and others. The electrical and electronics segment held a 27.84% share in 2025 and is projected to grow at a 7.38% CAGR owing to wide use in mobile phones, laptops, computers, televisions, and cables, among other products. There have been several fire safety regulations and standards set across different regions to make electrical and electronic products safer for consumers.
Several companies are introducing new products to cater to the growing requirement of this segment. In January 2022, Lubrizol Engineered Polymers introduced a new non-halogenated flame retardants grade for wire and cable applications. The new product is manufactured to eliminate the use of halogens for enhanced performance and to meet the required regulations of the industry. The product has UL 94 V-0 and UL 105°C temperature ratings, along with superior mechanical properties.
The construction sector is expected to experience growth during the forecast period. Growth in urbanization, rise in construction activities, and development of infrastructure are some factors boosting the growth of this segment. In June 2022, Axalta introduced Plascoat PPA571 FR, which is a flame retardant. The new product is an anti-corrosion coating solution aimed at offering safety in buildings in case of a fire outbreak. Plascoat PPA571 is developed without the use of halogen to remove toxic fumes and their impact on the environment.
Asia-Pacific is expected to dominate the market
Implementation of strict fire safety regulations, strengthening the construction sector, and greater application in electrical and electronic sectors boost the adoption of flame retardants in the region. Growth in urbanization, industrialization and rising penetration of consumer electronics support the growth of the flame retardants market.
Increasing application in the automotive industry and greater adoption of electric and hybrid vehicles further boost the adoption of flame retardants in Asia-Pacific. Increasing investments in R&D, technological advancements, and rising inclination toward the use of environmentally friendly products are expected to increase the adoption of sustainable flame retardants during the forecast period.
Competitive Insight
Some leading companies profiled in the global flame retardants market include Albemarle Corporation, ICL Group Ltd., Clariant AG, LANXESS AG, BASF SE, Nabaltec AG, Huber Advanced Materials, Italmatch Chemicals S.p.A., THOR Group Limited, Daihachi Chemical Industry Co., Ltd.
These companies are introducing new products and solutions while offering enhanced customer services to cater to the growing demand across various industries. Partnerships and collaborations provide opportunities for these companies to enhance their market presence and enter new emerging markets.
Recent Developments
- September 2026: LANXESS launched Purventis, a flame-retardant platform led by Purventis Core, a reactive halogen-free phosphorus solution for rigid PU and PIR insulation foams. (Source: lanxess.com)
- September 2026: Avient introduced Nymax FR REC, a portfolio of flame-retardant recycled polyamide grades developed for electrification applications and circular-material requirements. (Source: avient.com)
- August 2026: Hindalco commissioned India’s first superfine precipitated aluminum trihydrate plant, targeting halogen-free cables, polymer insulators, composites, thermal insulation, and paints. (Source: hindalco.com)
- June 2026: Clariant launched Exolit AP 422 A, an SVHC-free, halogen-free ammonium polyphosphate flame retardant for insulation, composites, and intumescent coatings. (Source: clariant.com)
- March 2026: BASF began commercial production of its Elastollan flame-retardant TPU grade at its Shanghai facility, expanding regional availability of flame-retardant polyurethane materials. (Source: basf.com)
Flame Retardants Market Report Scope
| Report Attributes | Details |
| Market size value in 2026 | USD10.99 billion |
| Revenue forecast in 2034 | USD 18.18 billion |
| CAGR | 6.49% from 2026 - 2034 |
| Base year | 2025 |
| Historical data | 2021 - 2024 |
| Forecast period | 2026 - 2034 |
| Quantitative units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Segments covered | By Type, By Application, By End-Use, By Region |
| Regional scope | North America, Europe, Asia Pacific, Latin America; Middle East & Africa |
| Key companies | Albemarle Corporation, ICL Group Ltd., Clariant AG, LANXESS AG, BASF SE, Nabaltec AG, Huber Advanced Materials, Italmatch Chemicals S.p.A., THOR Group Limited, Daihachi Chemical Industry Co., Ltd. |
Source: Polaris Market Research Analysis
Frequently Asked Questions About the Flame Retardants Market
The global flame retardants market was valued at approximately USD 10.34 billion in 2025 and is estimated to reach USD 18.18 billion in 2034.
The market is anticipated to register a CAGR of 6.49% from 2026 to 2034.
Aluminum trihydrate held the largest type share of 29.84% in 2025, owing to its halogen-free properties, smoke suppression, and widespread polymer applications.
Nitrogen-based flame retardants are projected to register the highest CAGR of 7.68% during 2026–2034, supported by demand for environmentally preferable formulations.
The polyolefin segment dominated the application category with a 42.16% share in 2025, driven by its extensive use across construction, transportation, and electronics.
Asia Pacific dominated the global market with a 46.28% share in 2025, supported by extensive construction, electronics manufacturing, and automotive production.
Flame retardants are chemical substances added to materials to delay ignition, slow flame spread, suppress combustion, and reduce fire-related damage.
They interfere?with combustion, they release endothermic substances cooling the flame, they dilute flammable gases or form protective char layers that limit the flow of oxygen and heat.
They are gaining popularity due to environmental regulations, reduced smoke production, sustainability requirements, recycling concerns, and the reputation of some halogenated chemicals.
Download Sample Report of Flame Retardants Market Share, Size, Trends, Industry Analysis Report, 2026 - 2034
Please fill out the form to request a customized copy of the research report.


