Lithium-Ion Battery Anode Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Lithium-Ion Battery Anode Market Summary
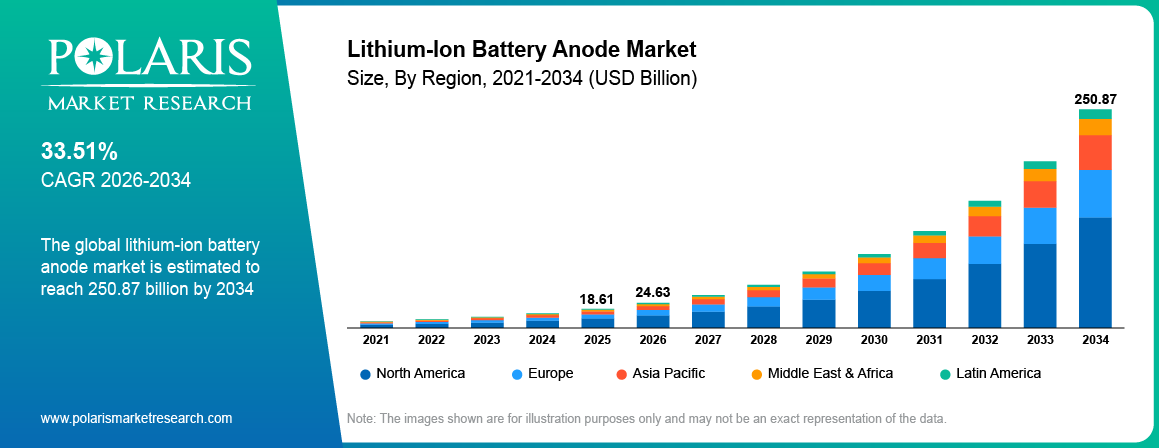
The lithium-ion battery anode market size was valued at USD 18.61 billion in 2025. The market is projected to grow at an 33.51% CAGR from 2026 to 2034. The growing adoption of electric vehicles and rising integration of renewable energy are a few of the key factors driving market development.
Market Statistics
Lithium-Ion Battery Anode Market Key Takeaways
- Asia Pacific led with a 55.0% share in 2025. This is owing to the increasing demand for consumer electronics in the region.
- North America is projected to account for the fastest growth at a 31.80% CAGR. This is due to increasing usage of lithium-ion battery anodes in electric mobility and renewable energy storage.
- The anode binders segment led with an 85.0% share in 2025. Their cost-effectiveness makes them an appealing choice for battery manufacturers.
- The active anode materials segment is projected to grow at a 29.80% CAGR. The active anode materials provide greater energy density in comparison to graphite anodes used conventionally.
- The automotive segment dominated with a 72.0% share in 2025. Their superior energy density compared to other electrical energy storage systems contributes to the segment’s leading position.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is a lithium-ion battery anode?
The lithium-ion battery anode market comprises materials and lithium-ion battery components that are used in making the negative electrode in rechargeable lithium-ion batteries. The anode helps to absorb and release lithium ions during battery charge and discharge cycles, making it necessary for the battery's functionality. Some common materials for making the anode are graphite, silicon, lithium titanate, hard carbon, and composite materials.
How Do Lithium-Ion Battery Anodes Work?
Charging: In the process of charging, lithium ions flow from the cathode to the anode using the electrolyte of the battery.
Storage of Lithium Ions: The anode holds the lithium ions inside the anode itself till the time comes for the battery to release the energy.
Generation of Energy: With the increase in storage of lithium ions, energy gets generated by the battery, which is required for running electronic devices and other vehicles.
Discharging: When the battery is used, lithium ions flow back to the cathode using the electrolyte.
Production of Electricity: The flow of lithium ions leads to the flow of electrons, which provides electricity.
Recharge Cycle: The process of charging and discharging can be repeated several times.
Graphite Anodes vs. Silicon Anodes
| Parameter | Graphite Anodes | Silicon Anodes |
| Energy Storage Density | Stable energy storage with reliable performance. | Higher energy storage density with increased lithium ion capacity. |
| Charging Speed | Stable operation with charging at normal operating conditions. | Faster charging can be achieved through proper engineering. |
| Cycle Life | Long life cycle with consistent performance. | Increasing cycle life due to advances in material technologies. |
| Manufacturing Cost | Lower manufacturing costs due to mature manufacturing technologies. | Higher manufacturing costs due to advanced material requirements. |
| Commercial Application | Mature technology used in lithium-ion batteries. | Increasing adoption due to its young age. |
| Material Availability | Adequate supply chain worldwide. | Material development is increasing to meet demand. |
| Performance Potential | Applicable for a wide variety of purposes. | Higher potential to increase battery capacities and EV mileage. |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
The lithium-ion battery anode market is expected to witness rapid growth as Li-ion batteries have emerged as the most dependable and appropriate solution for energy storage. They are used in a wide range of applications, from small-scale devices like mobile phones to larger applications such as electric vehicles. Li metal anodes offer several desirable qualities, including the highest theoretical capacity, lightweight construction, and high energy density. These factors make them an appealing choice for applications with the lowest electrochemical potential relative to the standard hydrogen electrode. Before being used in larger applications, advanced batteries must meet certain prerequisites, such as storing more energy, occupying less space, and delivering superior cyclic and rate capability.
In recent years, researchers have used various methods to improve the performance of silicon-based anode materials in lithium-ion batteries by addressing issues such as electrochemical properties, volume expansion, low conductivity, and inconsistent reaction kinetics. One popular technique involves applying a protective layer on the Si-based anodic material. The primary coating is carbon, deposited onto the silicon anode using chemical vapor deposition (CVD) to improve electrical conductivity.
Lithium-Ion Battery Anode Market Dynamics
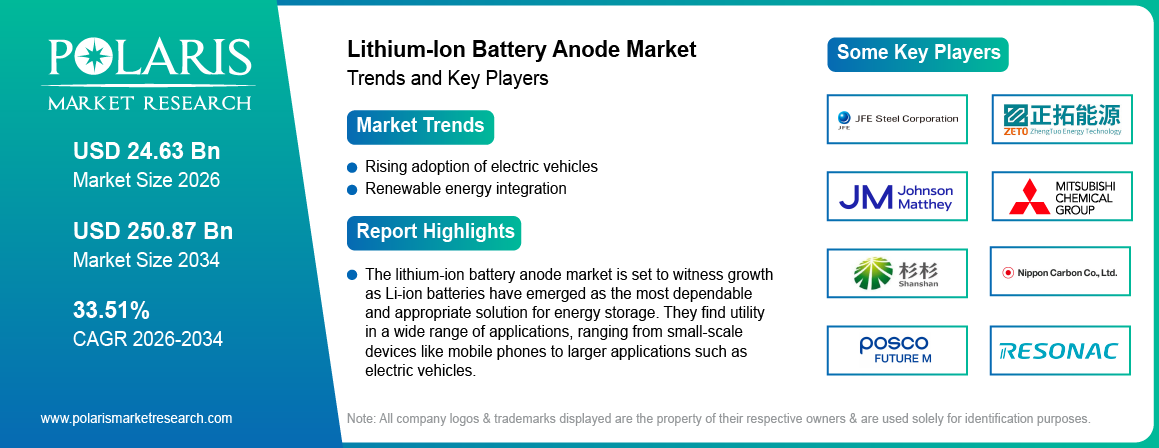
The market for lithium-ion battery anodes is influenced by the increasing popularity of electric vehicles, high demand for renewable energy storage solutions, innovations in anode materials technology, and resource limitations. All these factors influence the performance of batteries, their cost, and further innovations in energy storage solutions.
Driver: Rising Adoption of Electric Vehicles
The lithium-ion battery anode market is experiencing significant growth due to electric vehicle adoption. The increasing popularity of plug-in hybrids and electric vehicles (EVs) directly contributes to the rising demand for lithium-ion batteries. Consumers are embracing EVs more because they help reduce pollution and benefit the environment. Additionally, advances in battery technology are increasing EV range and reducing maintenance needs, further driving adoption. Given that EVs are widely regarded as the future of transportation, this trend is expected to persist and continue driving growth in the lithium-ion battery anode market. The increased need for longer driving range and fast charging is also prompting battery makers to produce advanced EV battery materials with higher energy density and superior charging capabilities.
Driver: Renewable Energy Integration
Lithium-ion batteries have become a popular choice for storing renewable energy due to their lightweight, high-energy density, and efficient electricity storage capabilities. They are considered a key solution for addressing the variability of wind and solar energy sources. The International Electrotechnical Commission (IEC) is responsible for developing the standards related to Li-ion cells (both anode and cathode) and has published the IEC 62660 series, which is particularly meant for secondary Li-ion cells used in electric vehicles (source: iecee.org). Additionally, it has published standards for renewable energy storage systems. Recent trends indicate a significant increase in the demand for lithium-ion batteries in the near future. Government programs aimed at expanding renewable energy projects, battery storage projects, and clean energy implementation are further driving demand for lithium-ion batteries and anodes.
Opportunities: Growing Demand for Silicon-Based Anode Materials
The shift towards high-energy-density batteries creates opportunities for silicon anodes and silicon-carbon composite anodes. The theoretical capacity of silicon is significantly higher than graphite. Therefore, silicon can be used in batteries with a high level of energy storage anode material requirements. The rising requirements for the range of electric cars boost the interest in silicon anodes. Battery systems for energy storage provide additional opportunities for the use of silicon anodes. The manufacturing companies develop solutions aimed at improving the properties of silicon anodes. This helps minimize the negative influence of silicon expansion while charging and discharging. With the development of these solutions, the use of silicon anodes is expected to grow.
Restraints: Limited raw material availability is likely to impede the market growth.
The lithium-ion battery anode market faces a significant challenge due to limited availability of raw materials such as Li, Sn, Gr, antimony (Sb), lithium titanium oxide, and silicon-based materials like silicon oxycarbide (SiOC), which are widely used as anode elements. The increasing demand from electric vehicles, portable electronics, and energy storage applications has raised concerns about the sustainable sourcing of these materials. Additionally, geopolitical factors, trade tensions, and mining constraints further complicate the issue, potentially disrupting the supply chain and causing price fluctuations. To address this challenge, efforts are underway to diversify supply sources, explore alternative battery chemistries that rely less on critical materials, and implement recycling initiatives to recover valuable battery metals. These measures aim to reduce dependence on virgin resources and ensure a more sustainable future for the industry.
Market Trends
Shift Toward High-Performance and Fast-Charging Anodes
There is a growing emphasis on the development of anodes that can enable more energy density to be stored. Fast charging is yet another area that is receiving considerable attention. Silicon-based materials have become popular as a possible replacement for graphite used for anodes. In addition, there are also silicon-carbon anodes for future batteries. The increasing need for extended ranges in electric vehicles is a major factor behind this trend. The demand for faster charging is contributing to additional pressure on anode developments. There are also efforts to develop protective layers for silicon anodes.
Source: Polaris Market Research Analysis
Lithium-Ion Battery Anode Market Segment Analysis
By Materials Analysis
The anode binders segment led with an 85.0% market share in 2025. The segment’s dominance is largely attributed to cost-effectiveness, which makes them an appealing choice for battery manufacturers who aim to decrease production expenses. Additionally, these binders can be synthesized using environmentally friendly methods and are less likely to release harmful compounds during the battery manufacturing process. Moreover, they exhibit exceptional adhesion properties, ensuring a strong connection between the anode materials and current collectors. This attribute can significantly enhance the overall performance and lifespan of lithium-ion batteries. Furthermore, anode binders can be customized to meet specific requirements, providing greater flexibility in the design of battery electrodes.
The active anode materials segment is projected to grow at a 29.80% CAGR. The segment’s growth is mainly driven by high-capacity materials like silicon or tin, which play a crucial role in improving the overall performance and efficiency of lithium-ion batteries. Unlike traditional graphite anodes with limited lithium-ion storage capacity, active anode segments offer much higher energy density, allowing batteries to store more energy in the same volume. This has resulted in increased battery capacity and longer runtime for a variety of applications, from consumer electronics to electric vehicles. Additionally, active anode segments help enhance charging rates and cycle life in battery technology.
Anode Material Segment Comparison
| Segment | Description | Primary Demand Driver |
| Anode Binders | Adhesive compounds bonding active material to current collectors | Cost-effective, customizable formulations |
| Natural Graphite | Mined and purified graphite | Cost advantage, established supply |
| Synthetic Graphite | Lab-produced high-purity graphite | Faster charging, longer cycle life |
| Silicon-Based Anodes | Silicon oxide, silicon-carbon composites, blended graphite-silicon | Higher energy density, EV range |
| Lithium Titanate (LTO) | Lithium-titanium oxide anode | Fast charging, long cycle life, safety |
| Li-Compounds & Metal | Lithium metal/compound anodes | Very high energy density (emerging/solid-state) |
Source: Polaris Market Research Analysis
By Production Technology Analysis
The slurry coating segment accounted for an 58.0% market share in 2025. The segment’s major market share is supported by the extensive use of the technology in the production of lithium-ion batteries. This lithium-ion battery anode production technology enables the even application of active materials for the anode on the current collector. It ensures that the electrodes are of constant thickness throughout the battery cell. Slurry coating is also compatible with battery mass production. Manufacturers have the ability to change the slurry formula depending on the desired battery performance. The technology can be used with various anode materials such as graphite and silicon materials.
The chemical vapor deposition (CVD) segment is projected to grow at a 37.20% CAGR. This growth is driven by the increased usage of CVD technology in the production of anode materials. CVD allows for the deposition of a thin and even layer on the surface of the anode. This technology may increase the electrical conductivity of silicon-based anodes. CVD coatings also help manage the volume expansion of silicon in charging and discharging cycles. The technology is increasingly becoming popular due to the growing need to enhance the performance of anodes and their longevity. An increasing demand for high-performance batteries in electric vehicles is expected to boost the usage of CVD technology.
By Battery Product Analysis
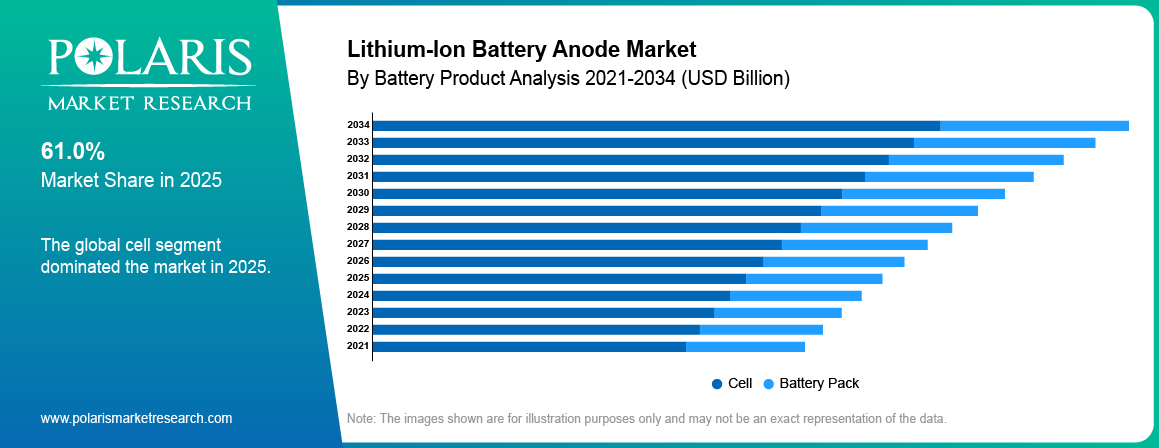
The cell segment led with an 61.0% share in 2025. The leading position of this segment is attributed to the extensive usage of lithium-ion batteries in electric vehicles, electronics, and energy storage systems. Higher demand for high-quality anode materials is being created due to higher production of battery cells. At the same time, battery cell manufacturers are focusing on improving performance and battery life. This has contributed to the use of advanced anode materials such as silicon and silicon carbide. The rise in the production of electric vehicles has added to the increased demand for lithium-ion batteries. Investments in battery manufacturing plants further drive the segment’s growth.
The battery pack segment is projected to account for an 35.50% CAGR. This growth is enabled by rising adoption of lithium-ion battery packs used in electric vehicles as well as energy storage systems. Battery packs use several cells to generate the required power for applications. Increased demand for extended vehicle driving range is leading to improvements in the performance of battery packs. This also drives the demand for anode materials that are capable of handling increased energy density. Increased investments in the production of EVs and batteries are also expected to propel the growth of this segment in the forecast period.
By End-User Analysis
The automotive segment dominated with a 72.0% share in 2025. Lithium-ion batteries are currently used in most electric vehicles because of their high energy density than that of other electrical energy storage systems. They also offer a remarkable power-to-weight ratio, excellent energy efficiency, strong high-temperature performance, and minimal self-discharge. Most lithium-ion battery components are recyclable. Furthermore, lithium-ion batteries offer exceptional charge and discharge efficiency, enabling fast charging and minimizing vehicle downtime.
The energy storage (non-automotive) segment is projected to grow at a 34.98% CAGR. Growth in this segment is attributed to the rising deployment of lithium-ion batteries in renewable energy storage applications. Solar and wind energy need some form of energy storage system, owing to their variations in electricity production. Lithium-ion batteries have the ability to store the surplus electricity and deliver it when required. This is leading to the demand for energy storage batteries that have high energy density and long life. The rise in the usage of grid-scale and home energy storage solutions is expected to further increase the demand for lithium-ion battery anodes.
Real-World Use Cases & Applications
Lithium-ion battery anodes can be used to store energy in many different sectors. Their performance influences battery capacity, charging speed, and cycling lifetime. The increasing popularity of lithium-ion batteries has led to the development of high-end anode materials in automotive, consumer, and energy sectors.
| Use Case | Description |
| Electric Vehicles | Anode materials are used in batteries of EVs to enhance the driving range, charging process, and life cycle of the battery. |
| Energy Storage for Power Grids | High-quality anode materials enable storage of electricity produced from renewable sources of energy through batteries of large capacities. |
| Smartphones and Laptops | Smartphone and laptop manufacturers utilize lithium-ion batteries with good-quality anodes to provide sufficient battery life for the phone. |
| Rechargeable Power Tools | Many rechargeable power tools have lithium-ion batteries. |
| Consumer Electronics | Anodes assist lithium-ion batteries in tablets, cameras, and other consumer electronics to provide sufficient battery life. |
| Industrial Backup Power | Batteries are used to provide backup electricity during interruptions. |
| Electric Buses and Commercial Fleets | Anode materials support batteries used in electric buses and commercial vehicles. |
| Marine and Aerospace | Anode materials support batteries used in marine and aerospace applications where low weight and high energy are important. |
Source: Polaris Market Research Analysis
Emerging Technologies in Battery Anodes
There are new anode technologies that are being introduced by battery manufacturers in order to increase their power capacity and increase their efficiency and lifespan. The introduction of these technologies is gaining importance due to increasing demand for electric cars and batteries.
- Silicon anodes: Silicon has a far greater theoretical capacity compared to graphite. There have been efforts to develop anodes based on silicon to help store more energy in lithium-ion batteries. Efforts are also being made to reduce the expansion of silicon during charging and discharging.
- Silicon-carbon anodes: Silicon is being combined with carbon to improve the conductivity and stability of the anode.
- Lithium-metal anodes: Lithium metal anodes have a very high theoretical capacity. They are being investigated for future batteries with enhanced energy densities.
- Carbon coatings: There are developments where carbon coating is used in order to improve the performance of silicon anodes by improving their conductivity and protecting the anode from deterioration due to charge-discharge cycles.
- Solid-state battery anodes: Solid-state batteries use a solid electrolyte, which is different from standard liquid electrolyte batteries. This technology is gaining prominence as it could help improve energy density.
Artificial Intelligence in Battery Material Development
Artificial intelligence is being applied to accelerate the process of creating new battery materials. The AI system analyzes the huge volume of data related to various materials and battery performance. This allows scientists to discover suitable anode materials quickly. Also, machine learning algorithms may be helpful in predicting the properties of materials before laboratory tests. Thus, researchers may use their predictions and thereby shorten the list of materials needed to perform experiments. Moreover, artificial intelligence is applied to optimize the battery production process. In anode development, AI systems can assist in discovering materials that have high energy density, charge fast, and last long.
Anode Materials in Solid-State Batteries
The development of solid-state batteries has opened up avenues for the development of new materials for anodes. Lithium-metal anodes have attracted increased attention due to their properties that allow them to achieve energy density that is higher than conventional graphite anodes. Solid electrolytes can address the safety issues that are associated with the use of liquid electrolytes. There has been a greater focus on ways to enhance the stability of the anode-electrolyte interface. Other methods, namely silicon anode materials, are being developed to make solid-state batteries more effective.
Battery Recycling & Circular Economy Initiatives
Battery recycling has become more significant due to the increasing demand for lithium-ion batteries. Through recycling, companies are able to recover useful materials from batteries while at the same time minimizing reliance on mining for raw materials. It is possible to recycle the anode materials, such as graphite, in order to minimize the need for extracting new materials from the earth. Battery producers are working with manufacturers to find ways of making battery material recovery more efficient. Green policies from governments have also played a role in the improvement of battery anode recycling practices.
Global Anode Material Supply Chain
The global anode materials supply chain involves the sourcing, processing, production, and distribution of materials used in lithium-ion anodes. Graphite is still one of the key materials used in manufacturing anodes, but silicon is becoming increasingly important as a potential material for the anodes of the future. China is the leading country in the processing of graphite and production of anode materials. Battery manufacturers are also seeking other sources of materials in order not to be dependent on a small number of suppliers. Many resources are now invested in local production in North America, Europe, and Asia Pacific. The recycling of batteries may help in further strengthening the supply chain since it will enable manufacturers to recover certain materials from old batteries.
Government Policies Supporting Battery Supply Chains
Governments are implementing policies to enhance the domestic battery supply chain and decrease reliance on imported materials. Many nations are offering subsidies to battery manufacturing and key mineral processing activities. These initiatives help enterprises expand local production of battery materials and parts. Additionally, governments are supporting battery recycling to improve the recovery of critical materials. Regulations promoting electric vehicle adoption are driving higher demand for lithium-ion batteries and anode materials. Furthermore, R&D funding is supporting the development of advanced battery technologies.
Source: Polaris Market Research Analysis
Lithium-Ion Battery Anode Market Regional Insights
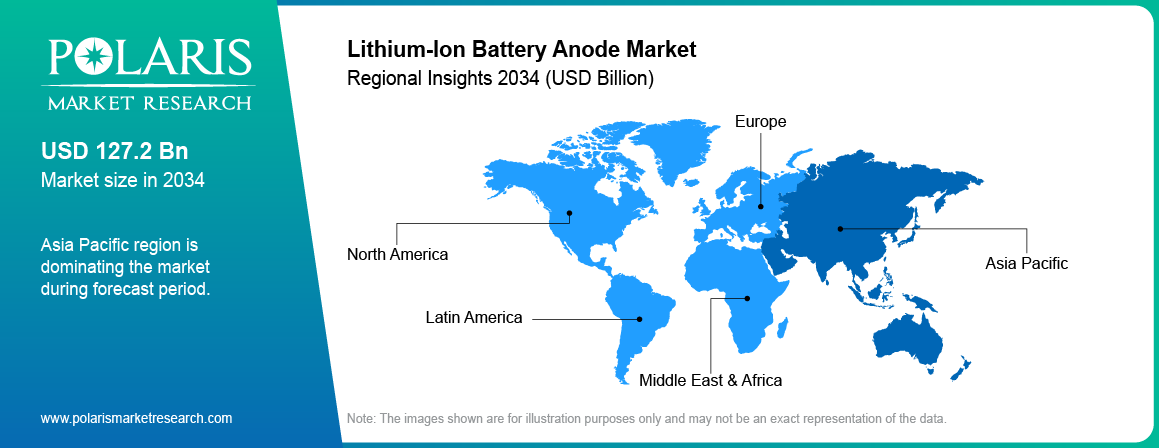
There is varied growth exhibited in the lithium-ion anode battery industry in terms of regions. Demand drivers in the market include battery production capacity, electric vehicle adoption rate, renewable energy projects, and investments in energy storage infrastructure. Asia Pacific is the largest market, while North America is expected to witness the fastest growth.
Asia Pacific
Asia Pacific accounted for an 55.0% market share in 2025. The market’s leading position can be largely attributed to the increasing demand for consumer electronics. This is particularly due to the popularity of portable devices such as laptops, gaming consoles, smartphones, torches, and digital cameras, as well as the availability of high-speed internet connectivity, which has had a positive effect on the market. Furthermore, the market is being accelerated by the growing demand for high-quality rechargeable batteries. These batteries are not only used in consumer electronics but also play a crucial role as an essential component in electric vehicles. Governments are implementing favorable initiatives to promote the sales of EVs, which in turn has a positive impact on the lithium-ion battery market. In addition, factors such as rapid urbanization, changes in lifestyle, increased investments, and higher consumer spending are all contributing to the growth of the lithium-ion battery market.
Europe
Europe held an 18.0% market share in 2025. This is owing to its applications in electric mobility, renewable energy storage, and grid stabilization. The transition to cleaner energy sources has led to the widespread adoption of electric vehicles equipped with lithium-ion batteries. Moreover, lithium-ion batteries are employed in residential and commercial battery energy storage systems, enabling consumers to optimize energy usage, cut costs, and contribute to a more sustainable energy landscape in Europe.
North America
North America is projected to witness the fastest growth at a 31.80% CAGR. The demand for lithium-ion battery anodes is rising in North America due to increased production of electric vehicles and energy storage projects. The region is also witnessing high investment in the development of local battery manufacturing capacities. In this respect, battery producers are working towards ensuring reliable procurement of anode raw materials such as graphite and silicon. The government has increased its assistance to clean energy and electric vehicle production, thus increasing investments in the battery supply chain. Additionally, the increasing use of renewable energy has raised the demand for energy storage systems.
Latin America & Middle East and Africa
Latin America and the Middle East & Africa represent emerging markets for lithium-ion battery anodes. Lithium-ion battery anode market growth in the region is driven by the adoption of electric mobility and renewable energy projects in the region. Several countries are increasing the capacity of solar and wind power and have a demand for energy storage solutions. Electric vehicle adoption is also rising in selected markets, leading to battery demand. Investments in battery manufacturing as well as energy infrastructure can further enhance the opportunities in these regions. Battery recycling is likely to also become crucial as there will be more used lithium-ion batteries.
Source: Polaris Market Research Analysis
Competitive Landscape
The lithium-ion battery anode market is fragmented and is anticipated to witness competition due to several players' presence. Major service providers in the market are constantly upgrading to meet the demand for battery electric cars, and vehicles are the main driving force behind the advancements in this field. In order to achieve widespread adoption of electric vehicles and enhance the durability and functionality of electronic devices and tools, it is crucial to make improvements in battery performance and cost, which has resulted in intense competition among developers to create next-generation Li-ion anode battery technologies that can meet these requirements to capture a significant market share.
Who are the top lithium-ion battery anode companies?
| Company | Headquarters | Positioning / Specialization |
| BTR New Material Group | Shenzhen, China | Anode materials, including natural and synthetic graphite. |
| BYD Company Co., Ltd. | Shenzhen, China | EV batteries and integrated battery manufacturing. |
| CATL (Contemporary Amperex Technology Co., Limited) | Ningde, China | EV and energy storage batteries. |
| JFE Chemical Corporation | Tokyo, Japan | Carbon materials and battery anode materials. |
| Jiangxi Zhengtuo New Energy Technology Co., Ltd. (Zeto) | Jiangxi, China | Graphite-based lithium-ion battery anode materials. |
| Seoul, South Korea | EV, mobility, and energy storage batteries. | |
| Tokyo, Japan | Advanced carbon and battery materials. | |
| Ningbo Shanshan Co., Ltd. | Ningbo, China | Natural graphite, synthetic graphite, and silicon-based anodes. |
| Nippon Carbon Co., Ltd. | Tokyo, Japan | Specialty carbon and graphite materials. |
| Panasonic Holdings Corporation | Osaka, Japan | Cylindrical lithium-ion batteries and battery technologies. |
| POSCO FUTURE M | Pohang, South Korea | Natural and synthetic graphite anodes; silicon-based anodes. |
| Resonac Holdings Corporation | Tokyo, Japan | Graphite and advanced battery anode materials. |
| Samsung SDI | Yongin, South Korea | EV, energy storage, and electronic batteries. |
| SGL Carbon | Wiesbaden, Germany | Synthetic graphite and specialty carbon materials. |
| SK On | Seoul, South Korea | EV batteries and fast-charging battery technologies. |
| Sumitomo Chemical Co., Ltd. | Tokyo, Japan | Battery materials and advanced energy technologies. |
| Umicore | Brussels, Belgium | Battery materials and battery recycling. |
Source: Polaris Market Research Analysis
Recent Developments
- July 2026: Sila announced securing $300 million in private funding. According to Sila, the funding will help accelerate U.S. production of its silicon-carbon (Si/C) anode technology, Titan Silicon. It will also support the planned Phase 2 expansion of the company’s plant in Moses Lake, Washington. (source: businesswire.com)
- June 2026: NOVONIX Limited announced the delivery of a mass production qualification sample of synthetic graphite anode active material to Panasonic Energy. The company stated that the development marks the first known delivery of a Synthetic Graphite AAM C-sample produced in North America. (source: novonixgroup.com)
- June 2026: Graphite One Inc. revealed the engagement of a leading global engineering and production line integration provider. The company said the development will support the design and integration of the manufacturing equipment it is procuring for its planned Ohio advanced graphite materials unit. (source: graphiteoneinc.com)
- June 2026: Sicona Battery Technologies announced securing a $45 million grant from the Australian Renewable Energy Agency (ARENA). According to Sicona, the grant is for the development of its first commercial-scale silicon-carbon battery anode material production unit in the Illawarra region. (source: prnewswire.com)
- May 2026: POSCO Future M secured mass-production technology for silicon anode materials. With the technology, the company intends to capture demand in high-value markets with faster charging speeds and energy storage capacity that is four times more than that of graphite-based anode materials. (source: posco.com)
- May 2026: NextSource Materials Inc. announced the approval of a Final Investment Decision (FID) on Phase 1 of its proposed battery anode facility in Abu Dhabi, UAE. The company stated that the FID marks a major step in its strategy to become a fully integrated, global producer of graphite anode materials. (source: nextsourcematerials.com)
- April 2026: Solidion Technology Inc. revealed a binding agreement with the IP Services Practice of Hilco Global. The company stated that the agreement focuses on the monetization of its foundational energy portfolio and enforcing its patent rights. (source: prnewswire.com)
- January 2026: Northern Graphite Corporation announced signing a term sheet with Obeikan Investment Group. The term sheet encompasses the formation of a joint venture company (JVCo). The JVCo will develop and operate a large-scale battery anode material (BAM) facility in Yanbu Industrial City, Kingdom of Saudi Arabia. (source: northerngraphite.com)
Report Coverage
The lithium-ion battery anode market report emphasizes key regions worldwide to help users better understand the product. The report also provides market insights into recent developments and trends and analyzes technologies gaining traction worldwide. Furthermore, the report covers in-depth qualitative analysis of various paradigm shifts associated with the transformation of these solutions.
The report provides a detailed market analysis, focusing on key aspects such as competitive analysis, materials, battery products, production technology, end-users, and future growth opportunities.
Future Outlook
An increase in the demand for electric vehicles, renewable energy storage, and consumer electronics is expected to lead to growth in the lithium-ion battery anode market. Battery manufacturers are expected to increase research and development to develop next-generation anode materials that improve energy density, fast charging, and battery longevity. Silicon-based anodes and other innovative materials are expected to be commercialized in the coming years. Furthermore, growing investments in battery manufacturing facilities are anticipated to fuel market growth. Sustainability and battery recycling will become the major focus areas in the industry. Government incentives to foster local battery supply chains are expected to drive market development in the coming years.
Lithium-Ion Battery Anode Market Segmentation Outlook
The market segmentation is based on materials, battery products, production technology, end-user, and region. Market segmentation of the industry reflects differences that exist between different anode materials, battery designs, applications, and demand.
| By Materials | By Battery Product | By Production Technology | By End-User | By Region |
|
|
|
|
|
Source: Polaris Market Research Analysis
Lithium-Ion Battery Anode Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 18.61 billion |
| Market Size Value in 2026 | USD 24.63 billion |
| Revenue Forecast by 2034 | USD 250.87 billion |
| CAGR | 33.51% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Lithium-Ion Battery Anode Market FAQ's
The market was worth USD 18.61 billion in 2025 and is expected to hit USD 250.87 billion by 2034—a 33.51% CAGR. That kind of growth doesn't happen by accident. EVs are scaling fast, renewable energy needs storage, and governments are pouring money into domestic battery supply chains.
The market is projected to account for a 33.51% CAGR during the forecast period.
The lithium-ion battery anode market segmentation is based on materials, production technology, battery product, and end-user.
Asia Pacific accounted for the largest market share of 55.0% in 2025. This is attributed to the growing need for consumer electronics in the region.
Most lithium-ion batteries use graphite — it's reliable, affordable, and has a well-established supply chain. Silicon is gaining ground fast because it stores far more energy, but it's tricky to work with. Lithium titanate and hard carbon show up in niche applications where fast charging or durability matters more than capacity.
Lithium-ion battery anodes are applied in energy storage devices that accumulate electricity produced by solar panels and wind turbines. Batteries provide balancing of electricity production and consumption, enhance the reliability of the electricity grid, and promote the use of renewable energy sources.
The automotive sector is the major consumer of lithium-ion battery anodes owing to the fast-growing production of electric vehicles. Investments in battery production and vehicle electrification constantly drive the demand for advanced anode materials for electric vehicles.
Silicon anodes are significantly better than graphite at storing energy. They offer up to ten times the theoretical lithium storage capacity and higher energy density. That's why most manufacturers blend small amounts of silicon into graphite rather than going all-in on silicon.
Download Sample Report of Lithium-Ion Battery Anode Market
Please fill out the form to request a customized copy of the research report.