Optical Transceiver Market Trends and Growth Drivers, 2026-2034
REPORT DETAILS
Optical Transceiver Market Summary
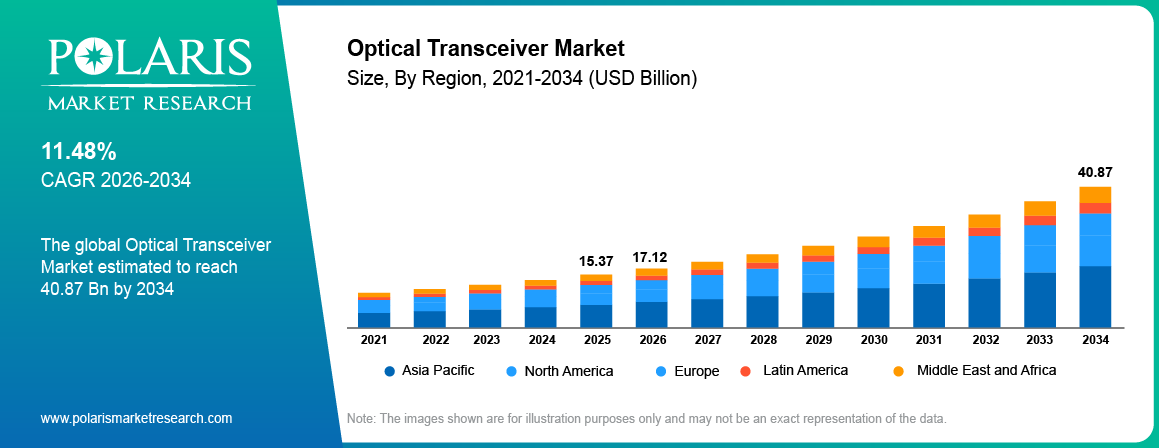
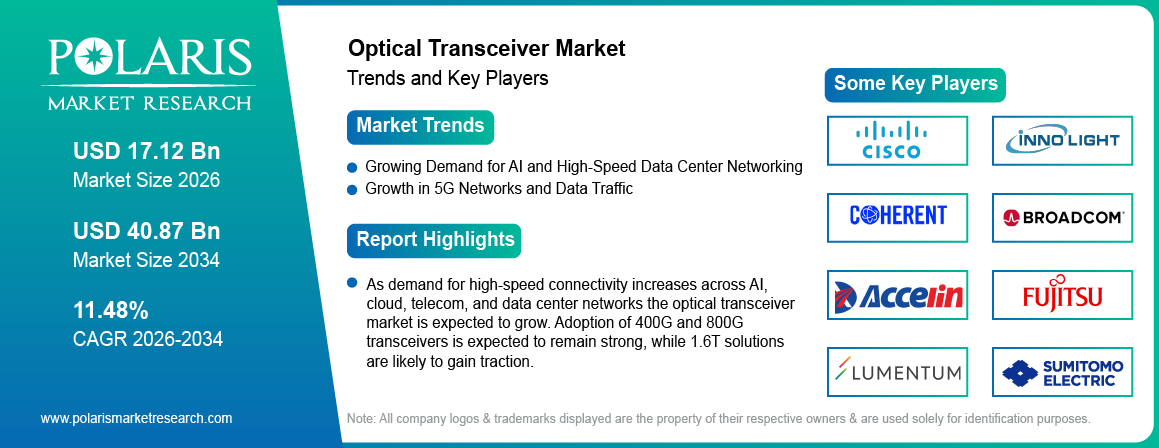
The optical transceiver market size was valued at USD 15.37 billion in 2025. The market is anticipated to grow from USD 17.12 billion in 2026 to USD 40.87 billion by 2034. The market will exhibit a CAGR of 11.48% during the forecast period.
Market Statistics
Optical Transceiver Market Key Takeaways
- North America held the largest market share of 37.3% in 2025. Growth is supported by advanced fiber infrastructure and expanding data center capacity.
- Asia Pacific is projected to exhibit the fastest growth at a CAGR of 13.2% during the forecast period. Growth is driven by telecom expansion, digitalization, and increasing data center investments.
- Data Center segment is expected to witness growth of 12.6% CAGR during the forecast period. Increasing data consumption, cloud computing and high speed connectivity are the major growth drivers.
- The Telecommunication segment dominated with largest share of 54.8% in 2025. Growth is supported by 5G deployment, fiber expansion, and network modernization.
- The 1310 nm band segment is expected to register a CAGR of 11.9% during the forecast period. This is due to the demand for high speed optical communication over long distances.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is the optical transceiver market?
An optical transceiver, commonly known as a "transceiver," is a crucial component in fiber optic communication systems. It integrates both a transmitter and a receiver within a unified unit, facilitating bidirectional data exchange over optical fiber networks.
The demand for high-speed internet and data transmission capabilities has surged in recent years due to the increasing reliance on digital technologies across various sectors. This demand is fueled by the exponential growth of data generated by activities such as video streaming, social media usage, online gaming, e-commerce, and enterprise applications. Traditional copper-based communication systems struggle to keep up with this demand due to their limited bandwidth and susceptibility to interference. Consequently, there has been a global push towards expanding fiber optic networks, which offer significantly higher bandwidth and reliability.
Fiber optic networks utilize optical fibers to transmit data in the form of light pulses over long distances. Optical transceivers are essential components in these networks as they facilitate the conversion of electrical signals into optical signals for transmission and vice versa. By combining a transmitter and receiver into a single unit, optical transceivers enable bidirectional communication over optical fibers. This capability is crucial for establishing high-speed, low-latency connections that can meet the demands of modern digital applications. Hence the optical transceivers market share is expected to grow in the upcoming years.
Moreover, the proliferation of data centers has been driven by the rapid growth of cloud computing, streaming services, and other data-intensive applications. Data centers serve as the backbone of the digital economy, hosting vast amounts of data and providing computing resources to support various online services. Within data centers, optical transceivers play a vital role in connecting servers, storage devices, and networking equipment. They enable high-speed communication between these components, ensuring efficient data processing and delivery. As a result, the optical transceivers market size is expected to grow in the upcoming years.
Furthermore, the adoption of Internet of Things (IoT) devices is expanding across industries, including manufacturing, healthcare, transportation, agriculture, and smart cities. These devices collect and transmit data from sensors and actuators, enabling real-time monitoring, automation, and process optimization. However, the widespread deployment of IoT devices requires robust communication infrastructure capable of handling the massive volume of data generated. As a result, the optical transceivers market size is expected to grow in the upcoming years. Optical transceivers play a crucial role in facilitating high-speed data transfer within IoT networks, ensuring reliable connectivity and efficient data transmission.
There is a continuous drive to enhance performance, increase bandwidth, and reduce form factors. With the rapid expansion of data-intensive applications such as cloud computing, streaming services, and 5G networks, there's an escalating demand for high-speed, reliable communication solutions. As a result, manufacturers are pushing the boundaries of technology to introduce new products that meet these evolving demands. As a result, significant growth is expected in the optical transceiver market share during the forecast period.
For instance, in March 2026, Broadcom announced the availability of its 3nm 400G/lane optical PAM-4 DSP, designed to support low-power 1.6T optical transceiver solutions for AI data centers. The technology is expected to support address the growing bandwidth and connectivity requirements of next-generation AI infrastructure (Source: investors.broadcom.com).
The increasing demand for high-speed internet access and bandwidth-intensive applications is driving the expansion of fiber optic networks globally. Optical transceivers are essential components in these networks, supporting both long-haul and last-mile connectivity. As fiber optic network deployments continue to grow, there is a corresponding increase in demand for optical transceivers. As a result, the optical transceivers market share is expected to grow in the upcoming years. The rollout of 5G networks requires high-speed and low-latency data transmission, which drives the demand for optical transceivers. As 5G networks continue to expand globally, there will be significant market opportunities for companies involved in providing optical transceiver solutions, thereby increasing in optical transceiver market share.
How Optical Transceivers Work
By combining a transmitter and receiver in a single device, optical transceivers enable two-way data communication over fiber optic networks. For transmission they convert electrical signals into optical signals and at the receiving end convert incoming optical signals back into electrical signals.
A server, computer or network device generates data, and it starts from there. The data is converted into an electrical signal. Using a laser or other light source the optical transceiver then converts the electrical signal into light. These light pulses are received by the receiving device via a fiber optic cable. The distance and speed of transmission depends on the type of transceiver, wavelength, type of fiber and network application.
The transceiver has a photodetector on the receiving side that detects the incoming light signal and converts the optical signal back into an electrical signal. The connected network device processes the signal and extracts the original data. While providing high-speed and reliable connectivity this allows communication between servers, switches, storage systems and other network equipment.
Market Dynamics
Market Driver- Growing Demand for AI and High-Speed Data Center Networking
AI workloads require fast connections between GPUs, servers, and storage systems. NVIDIA offers optical transceivers and cables supporting 100G, 200G, 400G, and 800G AI networking infrastructure, highlighting the rising need for high-bandwidth connectivity in AI clusters. Its Spectrum-X platform also supports 800 Gb/s networking and next-generation 1.6 Tb/s connectivity. These trends are creating demand for advanced optical transceivers in AI focused data centers (Source: www.nvidia.com).
Market Driver- Growth in 5G Networks and Data Traffic
The continuous growth of 5G networks is driving the demand for high speed optical connectivity. Ericsson has reported that 2.9 billion 5G subscriptions were in the world in 2025 and 5G carried 48% of the world’s mobile data traffic at the end of the year. The increasing traffic and network upgrades are generating a greater demand for optical transceivers across telecom backhaul, fronthaul and other high capacity network connections (Source: www.ericsson.com).
Market Opportunity- Rising Investments in AI and Hyperscale Data Centers
Large investments in AI infrastructure are creating opportunities for optical transceiver suppliers. In 2025, Amazon announced plans to invest up to USD 50 billion to expand AI and high-performance computing infrastructure for U.S. government customers, adding nearly 1.3 GW of compute capacity. Such large scale projects require high speed networking between computing systems, supporting demand for advanced optical connectivity (Source: www.aboutamazon.com).
Market Opportunity- Growing Adoption of 1.6T Optical Connectivity
The move toward higher-speed networking is creating opportunities for 1.6T optical transceivers. In March 2026 Broadcom introduced a 400G/lane optical DSP for 1.6T transceiver solutions, with the company saying it expects more than 100 million 1.6T and 3.2T optical transceivers to ship over the next five years. Such a shift creates opportunities for manufacturers developing higher-bandwidth and lower-power optical modules (Source: investors.broadcom.com).
Market Restraint- High Initial Investment & Complexity of Infrastructure
Deploying fiber-optic infrastructure requires significant investment in cables, network equipment, and optical transceivers. Integration can also require specialized skills for installation, testing, and maintenance. These costs and technical requirements can slow adoption among smaller organizations and in regions where fiber infrastructure is still developing.
400G, 800G and 1.6T Optical Connectivity
As data centers handle larger workloads and growing network traffic the shift toward higher data rates is reshaping optical networking. Operators can use higher bandwidth and port capacity 400G, 800G, and 1.6T optical technologies to scale networks and manage performance and power requirements. This transition is especially critical for cloud, hyperscale data centers, and high-performance computing environments.
400G Optical Modules Becoming Mainstream
400G optical modules are becoming an important upgrade path for modern data center networks. The technology supports higher bandwidth than earlier 100G and 200G offerings, to keep pace with rising data traffic between servers and switches, and is also being adopted by cloud and telecom networks that need faster, more scalable connectivity.
Rapid Adoption of 800G Optical Transceivers
800G optical transceivers are gaining adoption as data center operators increase network capacity. In AI and cloud environments, these modules help connect high-performance servers and switches while supporting large volumes of data traffic. Their higher bandwidth also helps reduce the number of optical connections needed for high-capacity networks.
Emergence of 1.6T Optical Connectivity
1.6T optical connectivity represents the next step in high-speed networking. To support future AI, hyperscale, and high-performance computing infrastructure that requires greater bandwidth per connection it is being developed. Advances in optical DSPs, silicon photonics, and other optical technologies are supporting enable these next-generation solutions.
Cloud Computing and Data Center Interconnect
Cloud computing is driving demand for faster and more reliable connections between data centers. Cloud providers need high-speed optical links to connect servers, storage systems, and network equipment while handling growing data volumes. Optical transceivers enable these connections by converting electrical signals into optical signals for transmission over fiber networks.
Data center interconnect (DCI) connects data centers across nearby or long distances. It supports data transfer, workload balancing, and business continuity. As cloud and data center networks require higher bandwidth the adoption of 400G and 800G transceivers is increasing. Emerging 1.6T solutions are expected to support future capacity needs. Growing AI workloads and distributed cloud infrastructure are further increasing demand for high-capacity DCI solutions.
Optical Transceivers vs Copper Connectivity
| Factor | Optical Transceiver + Fiber | Copper Connectivity |
| Bandwidth | Supports very high speeds, including 400G and 800G | Works well at lower speeds and shorter distances |
| Transmission Distance | Supports short- and long-distance connections | Best suited for short-distance connections |
| Signal Quality | Less affected by electromagnetic interference | More affected by electrical interference |
| Latency | Very low and suitable for high-speed networks | Low, especially for short connections |
| Energy Efficiency | Newer technologies help reduce power use | Efficient for short-distance connections |
| Scalability | Easy to scale for high-speed and dense networks | Better suited for smaller network setups |
| AI Infrastructure Suitability | Well suited for AI data centers and GPU clusters | More limited for high-bandwidth AI networks |
Source: Polaris Market Research Analysis
Emerging Technologies in Optical Transceivers
Optical transceiver technology is advancing to support higher data rates, lower power consumption, and growing connectivity needs. With the rise of AI, cloud computing and hyperscale data centers, manufacturers are bringing new solutions to support growing bandwidth and increase network efficiency.
Silicon photonics (SiPh) is becoming popular because it enables integration of optical components with silicon based technology. It can enable high speed data transmission while helping to reduce device size and power requirements. SiPh is also being studied for next generation 800G and 1.6T optical transceivers.
Co-packaged optics (CPO) is another emerging approach that places optical components closer to switching and processing hardware. In high-bandwidth data center networks this design can reduce electrical transmission distances and improve energy efficiency.
Advances in digital signal processors (DSPs) are also enabling higher-speed optical modules. Modern DSPs help manage signal processing, improve transmission quality and enable higher data rates such as 800G and 1.6T.
Photonic integrated circuits (PICs) combine multiple optical functions into a single, compact component that can improve scalability and enable smaller and more efficient transceiver designs. SiPh, CPO, advanced DSPs and PICs are collectively enabling the industry to develop higher-capacity and more energy-efficient optical connectivity.
Silicon Photonics Transforming Optical Communications
To support faster and denser data transmission silicon photonics integrates optical functions with silicon-based components. It can also reduce power consumption and device size. The technology is gaining importance in AI and cloud data centers and supports the development of 800G and 1.6T optical transceivers.
Co-Packaged Optics (CPO) Innovation
Co-packaged optics (CPO) places photonic engines close to networking chips. This reduces electrical signal distances and can improve bandwidth and power efficiency. As AI and cloud networks require higher-speed connections and better thermal management CPO is gaining attention.
Energy-Efficient Optical Networking
Higher data rates are increasing power and thermal challenges in data centers. To help deliver higher bandwidth while managing power consumption and cooling requirements, manufacturers are developing more efficient transceivers using technologies such as silicon photonics, advanced DSPs and CPO.
Market Segmentation
By Form Factor Insights
By form factor, the optical transceiver market is segmented into SFF & SFP, QSFP, CFP, XFP, and CXP. The QSFP segment accounted for 37.5% of the global optical transceiver market in 2025, making it the largest form factor segment. Its high port density and growing application in data centers, cloud networks and high-speed applications support strong adoption. QSFP versions such as QSFP28 and QSFP-DD are used for higher data rates and are widely used for 100G, 400G and 800G connectivity. The CFP family had 9.8% CAGR during the forecast period owing to its use in high capacity and long distance optical networks. CFP, CFP2 and CFP4 modules are mainly used in telecom and coherent optical applications.
By Data Rate Insights
By data rate, the optical transceiver market is segmented into Less than 10 Gbps, 10 Gbps to 40 Gbps, 40 Gbps to 100 Gbps, and More than 100 Gbps.
In 2025 the 10 Gbps to 40 Gbps segment accounted for nearly 42.6% of total shipments, making it the largest segment. They are widely used in telecom networks, enterprise infrastructure and data centers. However, they are still preferred for network upgrades due to their reliable performance, lower deployment costs and compatibility with existing infrastructure.
During the forecast period the more than 100 Gbps segment is projected to grow at a 15.4% CAGR. Growth is driven by rising demand for 400G and 800G optical connectivity in AI data centers, cloud computing, and high-performance networking. Across next-generation digital infrastructure increasing bandwidth requirements are accelerating the adoption of high-speed optical transceivers.
By Fiber Type Insights
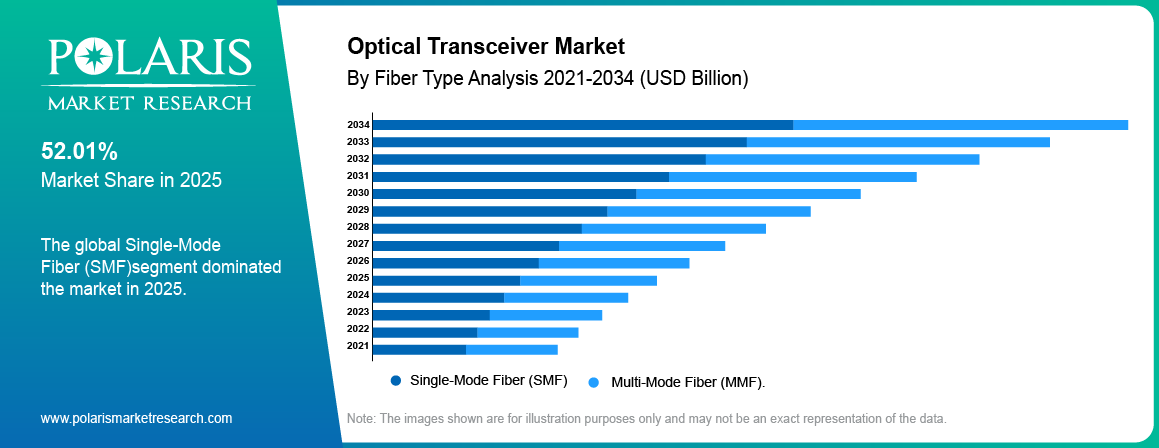
By fiber type, the optical transceiver market is segmented into Single-Mode Fiber (SMF) and Multi-Mode Fiber (MMF).
In 2025, Single-Mode Fiber segment held the dominant market share of 52.01%. The growth is attributed to its capability to transmit data over long distances with low signal loss. It is widely used in telecom networks, data centers, and high-speed communication systems. Multi-Mode Fiber segment is anticipated to register a CAGR of 9.2% during the forecast period. The growth of the segment is supported by the rising utilization of Multi-Mode Fiber for short-distance connections in data centers, enterprise networks, and high-speed server links.
By Distance Insights
By distance, the optical transceiver market is segmented into Less than 1 km, 1–10 km, 11–100 km, and More than 100 km.
The 11–100 km segment accounted for 38.7% of the market in 2025, making it the largest distance segment. It is widely used in metropolitan networks, telecom infrastructure, and connections between data centers and network nodes. The More than 100 km segment is projected to register the fastest growth during the forecast period with 13.8%. The demand for long-distance optical connectivity is rising as telecom networks and 5G infrastructure expand and high-capacity data transmission grows.
By Wavelength Insights
By wavelength, the optical transceiver market is segmented into 850 nm band, 1310 nm band, 1550 nm band, and others.
The 850 nm band accounted for 34.2% of the global market in 2025. It is widely used for short-distance data transmission over multimode fiber. The band enables high speed connections between servers, switches and storage systems. It has strong use in data centers and enterprise networks. The growing demand for fast and reliable short distance connectivity continues to support the adoption of 850nm optical transceivers.
The 1310 nm band segment is expected to grow at the fastest CAGR during the forecast period with 11.9%. This wavelength is well-suited for transmission over single-mode optical fibers, which are commonly used in long-distance communication networks. Single-mode fibers offer lower signal attenuation and higher bandwidth compared to multimode fibers, making them ideal for high-speed and long-distance data transmission applications.
Optical transceivers operating at 1310 nm offer flexibility in wavelength selection and are compatible with various optical networking standards and protocols. This versatility makes them suitable for a wide range of applications, including telecommunications, data centers, enterprise networks, and metropolitan area networks (MANs). As demand for higher bandwidth and faster data transmission speeds continues to grow, the 1310 nm band segment becomes increasingly attractive for applications requiring high-performance optical communication solutions.
By Connector Insights
By Connector the optical transceiver market is segmented into LC connector, SC connector, MPO connector, and RJ-45.
The LC connector segment accounted for 46.8% of the global market in 2025, making it the largest segment. Its compact size makes it suitable for high-density fiber connections. It is widely used in data centers, telecom networks, and enterprise networks where reliable and space-efficient connectivity is required.
During the forecast period the MPO connector segment is projected to grow at a 14.1% CAGR. Its multi-fiber design supports high-speed connections and helps to save cabling space. The demand for 400G and 800G networks, particularly for AI and hyperscale data centers, is driving adoption.
By Application Insights
Based on application analysis, the market is segmented into telecommunication and data centers. The data center is expected to witness significant growth of CAGR 12.6% during the forecast period. With the rise of digitalization, cloud computing, and the Internet of Things (IoT), there has been an exponential increase in data consumption. Data centers serve as the backbone of this digital infrastructure, necessitating high-speed and reliable optical transceivers to manage the vast amounts of data being processed. The demand for data centers has surged with the proliferation of online services, e-commerce, social media, and streaming platforms. As data centers expand to accommodate growing data loads, the need for optical transceivers increases proportionally to support high-speed data transmission within and between these facilities.
Data centers require high-speed connectivity to ensure efficient data processing, storage, and distribution. Optical transceivers offer high-speed data transmission capabilities over optical fibers, enabling rapid and reliable communication between servers, storage devices, and networking equipment within data center environments.
The Telecommunication segment dominated with largest share of 54.8% in 2025. The growth is driven by the expansion of 5G networks, upgrades in metro networks, and the growing demand for high-speed data transmission. To handle the increasing traffic and network capacity telecom operators are also upgrading their optical infrastructure.
Real-World Optical Transceiver Use Cases
| Use Case | How Optical Transceivers Are Used |
| AI Clusters | Connect GPUs, servers, and switches for high-speed data transfer. |
| Hyperscale Data Centers | Support high-capacity connections between servers and data center networks. |
| Telecommunications | Enable high-speed connections across telecom and fiber networks. |
| 5G Networks | Support fronthaul, midhaul, and backhaul connections for 5G networks. |
| Enterprise Networks | Connect servers, switches, and storage systems across business networks. |
| Broadband Networks | Support fast and reliable data transmission over fiber networks. |
| Smart Cities | Connect cameras, sensors, traffic systems, and other smart infrastructure. |
| High-Performance Computing (HPC) | Enable fast communication between computing systems handling large workloads. |
Source: Polaris Market Research Analysis
Optical Networking Ecosystem
The optical networking ecosystem includes component suppliers, transceiver manufacturers, network equipment providers, cloud providers, and telecom operators. Component suppliers provide key technologies such as lasers, DSPs, and PICs. Optical modules for data centers and communication networks are built using these components, which are then utilized by cloud and telecom operators to deliver high-speed and reliable connectivity.
Regional Insights
Why North America Holds the Largest Optical Transceiver Market Share (37.3%)
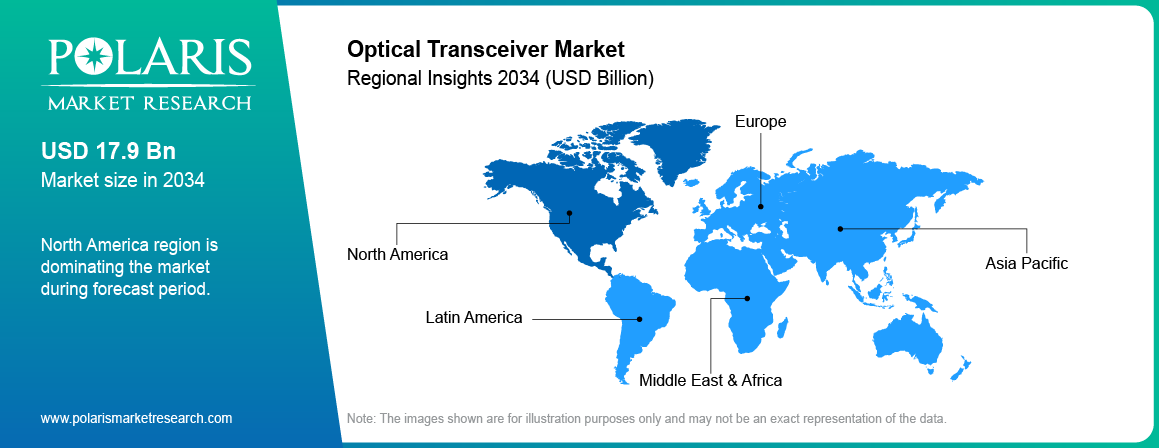
The North American region accounted for the largest market share with 37.3% in 2025. North America, particularly the United States, boasts one of the most advanced telecommunications infrastructures globally. This infrastructure is characterized by extensive fiber optic networks deployed across the region to support high-speed data transmission, internet connectivity, and telecommunications services.
North America is home to a significant number of large-scale data centers operated by tech giants, cloud service providers, and enterprises. These data centers require robust optical transceiver solutions to facilitate high-speed data communication within the facilities and across networks, driving the demand for optical transceivers in the region. This demand necessitates the deployment of advanced optical transceiver technologies to support high-speed data transmission and bandwidth-intensive applications. As a result, in the North American region, the optical transceivers market share is expected to dominate in the forecast period.
Asia Pacific Optical Transceiver Market is growing at the fastest CAGR of 13.2%.
During the forecast period Asia Pacific is expected to grow at the fastest CAGR of 13.2%. The Asia Pacific region is experiencing rapid economic growth, driven by emerging economies such as China, India, and Southeast Asian countries. This growth is accompanied by increasing investments in telecommunications infrastructure, data centers, and digitalization initiatives, creating significant demand for optical transceivers to support high-speed data transmission and connectivity.
Asia Pacific is witnessing extensive expansion and modernization of telecommunications networks to meet the growing demand for broadband services, mobile connectivity, and digital infrastructure. Optical transceivers are essential components in these networks, enabling high-speed data transmission over fiber optic cables to support voice, data, and multimedia services. This trend is driving the demand for optical transceivers in various applications, including access networks, metro networks, and long-haul transmission networks, to accommodate the growing volume of internet traffic and digital services.
Europe Optical Transceiver Market Growth Driven by 5G and Fiber Upgrades
Europe is expected to witness a CAGR of 10.6% during the forecast period. Europe is seeing steady demand for optical transceivers as telecom operators upgrade fiber networks and expand 5G services. The development of data centers and cloud adoption are also driving the demand for high-speed connectivity. The increasing investments in digital infrastructure and network modernization are also driving the adoption of advanced optical transceivers in telecom, enterprise, and data center applications.
MEA Optical Transceiver Market Trends: Data Centers and 5G Expansion
The Middle East & Africa market is expected to witness growth of CAGR 9.1% during the forecast period supported by growing investments in digital infrastructure, data centers, and telecommunications. To meet rising connectivity needs, countries in the region are expanding fiber networks and 5G services. The demand for optical transceivers that provide fast and reliable data transmission is also driven by data center development as well as cloud adoption.
Latin America Optical Transceiver Market Outlook: Broadband and Cloud Growth
Latin America is expected to witness growth of CAGR of 10.2% during the forecast period due to increasing demand for optical transceivers due to expanding broadband networks, cloud services, and data center infrastructure. Telecom operators are investing in fiber networks to improve connectivity and support rising data traffic. The expansion of 5G services and digital transformation across businesses is further supporting the adoption of high-speed optical networking solutions.
Competitive Landscape
The competitive landscape of the optical transceiver market is characterized by intense competition among key players striving to maintain and expand their market presence. The companies leverage their strong research and development capabilities, technological expertise, and strategic partnerships to innovate and introduce advanced optical transceiver solutions catering to diverse applications such as telecommunications, data centers, enterprise networking, and consumer electronics. Additionally, the market witnesses significant collaboration and merger activities aimed at expanding product portfolios, enhancing market reach, and gaining a competitive edge.
Coherent Corp. is a major provider of optical communications technologies and components. For data centers, telecommunications, and high-speed networking the company offers optical transceivers and related solutions. Its portfolio includes solutions designed for 400G, 800G, and next-generation optical connectivity. The company continues to invest in optical technologies to meet growing bandwidth needs from cloud computing, AI infrastructure and hyperscale data centers.
Lumentum Holdings Inc. develops optical and photonic technologies for data center and telecommunications applications. Its portfolio includes high-speed optical transceivers designed to support increasing network capacity and data traffic. The company offers solutions for 400G and 800G networks and is advancing technologies for next-generation optical connectivity. Its products support cloud, AI, telecommunications, and other high-performance networking applications.
Leading Optical Transceiver Manufacturers
- Coherent Corp.
- Cisco Systems, Inc.
- Broadcom Inc.
- Lumentum Holdings Inc.
- Accelink Technologies Co., Ltd.
- Sumitomo Electric Industries, Ltd.
- Fujitsu Optical Components Limited
- INNOLIGHT Technology
- Eoptolink Technology Inc., Ltd.
- Source Photonics, Inc.
- Applied Optoelectronics, Inc.
- Hisense Broadband
- Marvell Technology, Inc.
- Intel Corporation
- Molex, LLC
Vendor Positioning Table
| Company | Market Positioning | Key Focus Areas |
| Coherent Corp. | Optical components and transceivers | 400G, 800G, AI, data centers |
| Lumentum Holdings Inc. | Optical components and transceivers | 800G, coherent optics, DCI |
| Broadcom Inc. | Networking and optical technologies | 200G/lane, AI, data centers |
| Cisco Systems, Inc. | Networking and optical solutions | Ethernet, data centers, telecom |
| Marvell Technology, Inc. | Connectivity and optical technologies | 5G, data centers, optical links |
| Applied Optoelectronics, Inc. | Optical networking products | 800G, cloud, data centers |
| Accelink Technologies Co., Ltd. | Optical communication products | Telecom, 5G, data centers |
| INNOLIGHT Technology | High-speed optical modules | 400G, 800G, data centers |
| Sumitomo Electric Industries, Ltd. | Optical communication products | Telecom, transceivers, x-Haul |
| Fujitsu Optical Components Limited | Optical components and modules | Telecom, data centers |
| Intel Corporation | Optical connectivity technologies | Silicon photonics, data centers |
| Eoptolink Technology Inc., Ltd. | Optical transceiver products | High-speed modules, data centers |
| Source Photonics, Inc. | Optical transceivers | 400G, 800G, 1.6T, data centers |
| Hon Hai Technology Group (Foxconn) | Electronics and optical solutions | Data centers, telecom, connectivity |
| Hisense Broadband | Optical modules and transceivers | Data centers, telecom, optical networks |
Source: Polaris Market Research Analysis
Recent Developments
- April 2026: Applied Optoelectronics received a $71 million order for 800G single-mode data center transceivers from a major hyperscale customer. (Source: investors.ao-inc.com)
- March 2026: Coherent demonstrated 1.6T and 3.2T optical transceiver technologies for next-generation AI data centers. (Source: www.coherent.com)
- March 2026: Lumentum demonstrated a 1.6T DR4 OSFP optical transceiver for high-speed AI data center networks. (Source: investor.lumentum.com)
Future Outlook
As demand for high-speed connectivity increases across AI, cloud, telecom, and data center networks the optical transceiver market is expected to grow. Adoption of 400G and 800G transceivers is expected to remain strong, while 1.6T solutions are likely to gain traction. Advances in silicon photonics, optical DSPs, and energy-efficient designs will support higher bandwidth and improved network performance. Rising data traffic and investments in AI infrastructure will create new opportunities for optical transceiver manufacturers.
Research Methodology
The optical transceiver market research combines primary and secondary research. Secondary research uses company reports, industry publications, government sources, trade associations, and other reliable databases. Primary research includes inputs from manufacturers, technology providers, distributors, and industry experts.
Market size and forecasts are estimated using historical data, industry trends, company information, and key growth factors such as AI, cloud computing, data center expansion, 5G, and fiber network development. The market is analyzed by major segments and regions to provide a detailed view of market growth and competitive developments.
Optical Transceiver Market Report Scope
| Report Attributes | Details |
| Market size value in 2025 | USD 15.37 billion |
| Market size value in 2026 | USD 17.12 billion |
| Revenue Forecast in 2034 | USD 40.87 billion |
| CAGR | 11.48% from 2026 – 2034 |
| Base year | 2025 |
| Historical data | 2021 – 2024 |
| Forecast period | 2026 – 2034 |
| Quantitative units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Segments Covered | By Form Factor, By Data Rate, By Fiber Type, By Distance, By Wavelength, By Connector, By Application, And By Region |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Optical Transceiver Market FAQ's
Key companies include Accelink Technologies Co., Ltd., Cisco Systems, Inc., Coherent Corp., Lumentum Holdings Inc., Broadcom Inc., and Sumitomo Electric Industries, Ltd.
The market is expected to grow at a CAGR of 11.48% during the forecast period.
The key segments include form factor, data rate, fiber type, distance, wavelength, connector, application, and region.
Growing cloud services, AI workloads, data center expansion, and rising data traffic are key growth factors.
The market is expected to reach USD 40.87 billion by 2034.
Asia Pacific is expected to register the fastest growth during the forecast period.
The Data Center segment holds the largest share of the market.
Silicon photonics, 400G, 800G, and 1.6T optical technologies are shaping the market.
Growing AI, cloud computing, and high-speed networking needs are increasing demand.
High infrastructure costs, power consumption, and supply chain challenges are major market challenges.
Download Sample Report of Optical Transceiver Market
Please fill out the form to request a customized copy of the research report.