Spatial OMICS Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Spatial Omics Market Summary
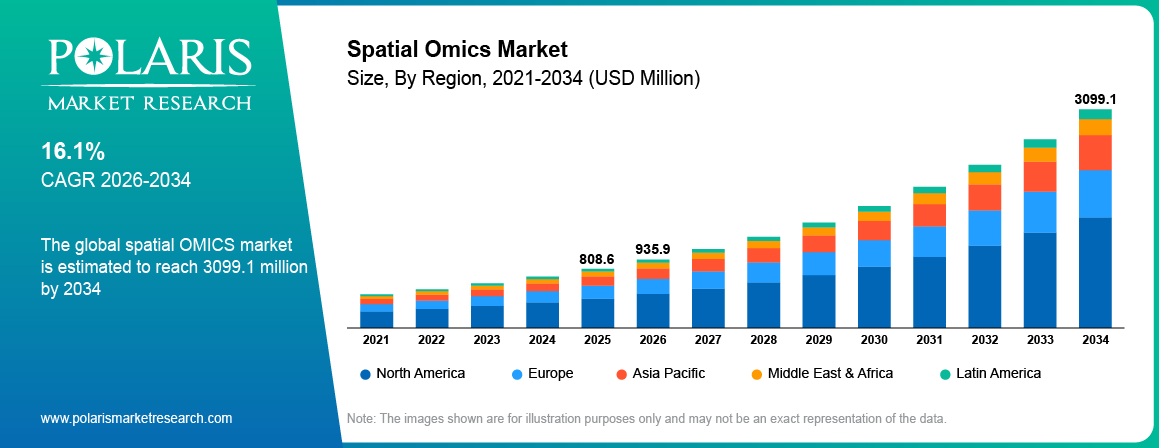
The spatial omics market is valued at USD 808.6 Million in 2025 and is estimated to reach USD 3,099.1 Million by 2034, registering a CAGR of 16.1% from 2026 till 2034. Growth is supported by increasing demand for tissue-level molecular analysis, broader adoption of spatial transcriptomics, development of spatial multi-omics, and expansion of clinical translation initiatives.
Market Statistics
Spatial OMICS Market Key Takeaways
- North America is expected to hold the dominant regional share of 41.3% in 2025, supported by the concentration of platform vendors, research institutions, NIH-funded technology programs, and early clinical-diagnostics collaborations.
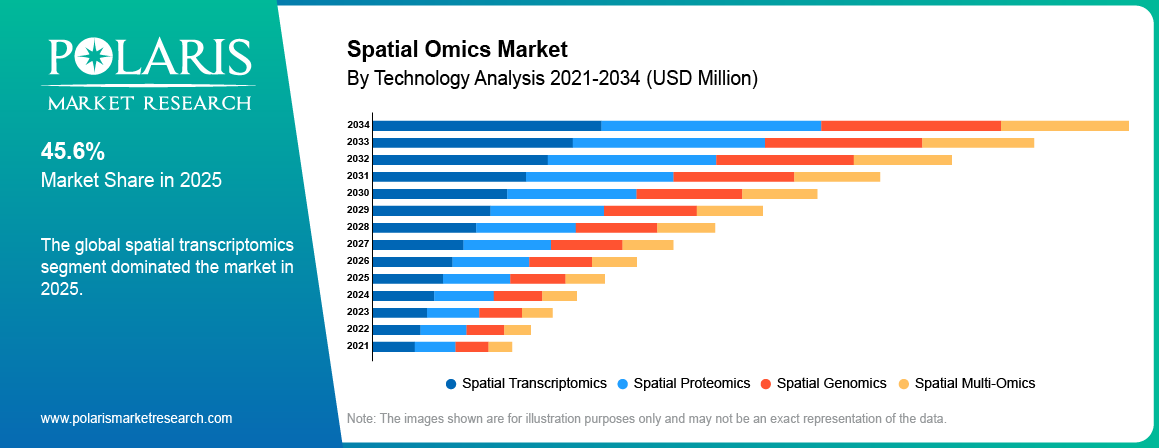
- Spatial transcriptomics leads the technology segment with a market share of 45.6% in 2025, while spatial multi-omics is projected to register the fastest growth, at a CAGR of 23.6%, as researchers increasingly seek integrated molecular profiling while retaining spatial context
- Oncology research represents the leading application area with the market share of 31.6% in 2025, while clinical diagnostics is expected to be the fastest-growing application as vendors develop CLIA-certified laboratory infrastructure and outcome-linked datasets.
- Pharmaceutical and biotechnology companies represent the leading end-user segment, holding 40.54% share in 2025, while academic and government research institutes are expected to register the fastest growth, at a CAGR of 16.5%, during the forecast period
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
Market Definition and Growth Analysis
The global spatial omics market is projected to expand significantly during the forecast period, supported by growing adoption of spatial transcriptomics, spatial proteomics, and spatial multi-omics platforms across research and translational applications. Unlike conventional bulk or single-cell sequencing, spatial omics preserves the physical location of molecular signals within tissue, allowing researchers to evaluate gene expression, protein abundance, and cellular interactions within their original tissue architecture.
The market ecosystem includes instrument manufacturers, consumables and reagent suppliers, software providers, academic and translational research institutions, pharmaceutical and biotechnology companies, and emerging clinical and diagnostic laboratories. Spatial transcriptomics represents the more commercially mature technology base, while spatial multi-omics is gaining momentum as researchers seek to combine transcriptomic, proteomic, and epigenomic information without sacrificing spatial context. The development of large spatial biology datasets is also creating a new layer of market infrastructure around data comparison and atlas-based analysis. Clinical translation is becoming an increasingly important part of the market's commercial direction.
Source: Polaris Market Research Analysis
The commercial opportunity extends beyond instrument placements. Consumables and reagents create recurring revenue as laboratories process additional tissue sections, while instrument installations influence long-term platform commitment and associated software and reagent purchases. The development of clinical applications provides an additional revenue pathway as vendors seek to move beyond academic and pharmaceutical research budgets.
Technology development is also improving the economics of adoption. NIH-funded programs are directly addressing cost accessibility and workflow throughput, while large-scale spatial biology datasets such as STELA are creating opportunities for organizations to derive insights from shared datasets without independently building every component of a spatial omics infrastructure.
Market Dynamics
Driver Impact Analysis
| Market Driver | Est. CAGR Impact | Geographic Relevance | Impact Timeline |
| Vendor expansion into clinical diagnostics | +3.8% | Global, led by North America | Short to medium term |
| NIH-funded cost and throughput technology development | +2.6% | US, spillover global | Medium term, 2-4 years |
| Large-scale shared spatial biology datasets | +2.2% | Global, three-continent specimen sourcing | Medium term, 2-4 years |
| FDA LDT rule reversion and near-term commercialization pathway | +1.4% | US | Short term, ongoing |
| Outcome-linked multimodal dataset construction | +1.8% | Global, led by North American academic medical centers | Medium to long term |
Source: Polaris Market Research Analysis
Clinical Translation as an Emerging Growth Mechanism
Clinical translation is emerging as a major growth mechanism for the spatial omics market. In January 2026, 10x Genomics announced its Dana-Farber Cancer Institute collaboration to support treatment-response biomarker analysis and plans for a CLIA-certified laboratory. Its June 2026 Cleveland Clinic collaboration extended this direction into bladder cancer treatment-response research through multimodal datasets linking spatial and single-cell information with patient outcomes (Source: prnewswire.com). These developments indicate that vendors are increasingly building infrastructure around future diagnostic use rather than relying exclusively on research applications.
Government-Funded Technology Development
Government funding is reinforcing the technology-development pipeline. The USD 2.68 million NIH award to the New York Genome Center targets cost-accessible spatial multi-omic profiling, while the USD 2.1 million award to the University of Washington targets throughput through a large spectrally barcoded probe library designed for single-round spatial transcriptomics (Source: biotechnetworks.org). Progress on these two constraints can lower adoption barriers for laboratories that currently face high platform costs or complex multi-round workflows.
Restraint: - Regulatory Uncertainty in Spatial Diagnostics Deployment
Regulatory uncertainty represents a key restraint as spatial omics moves closer to clinical diagnostics. The FDA's May 2024 final rule asserting direct authority over laboratory developed tests was vacated by a federal district court in March 2025. The FDA subsequently reverted to the prior regulatory text in September 2025, leaving most laboratory developed tests under the CMS/CLIA framework rather than direct FDA premarket review in the near term (Source: fda.gov). The change may support faster commercialization, but the possibility of future regulatory changes remains an important consideration for vendors investing in dedicated clinical infrastructure.
Opportunity - Multimodal, Outcome-Linked Dataset Development
Outcome-linked multimodal datasets represent an important opportunity as they connect spatial molecular observations with patient-level treatment outcomes. The Dana-Farber and Cleveland Clinic collaborations and the STELA atlas illustrate this direction by linking spatial information with broader datasets and clinical research questions. Platforms capable of generating reproducible spatial data that can be compared across patient cohorts are positioned to become increasingly important as the market moves toward clinical translation.
Source: Polaris Market Research Analysis
Market Segment Analysis
The report analyzes the spatial omics market across technology, application, end user, and region. The segmentation provides a basis for identifying both the largest revenue pools and the areas expected to generate the strongest incremental growth over the forecast period.
Technology Insights
Spatial transcriptomics accounted for the largest share of 45.6% in 2025. Its relatively earlier commercial maturity and established platform ecosystem have supported adoption across academic, pharmaceutical, and translational research settings. Platforms such as 10x Genomics' Xenium have contributed to the development of spatial transcriptomics as a major commercial technology category. The company's expansion toward the Atera platform also indicates increasing emphasis on broader multimodal capabilities.
Spatial multi-omics is projected to register the fastest growth of 23.6% during the forecast period. The segment benefits from increasing interest in measuring transcriptomic, proteomic, and epigenomic information within the same spatial context. The NIH-funded New York Genome Center program is directly targeting this capability, supporting development of more accessible platforms that can preserve spatial information while integrating multiple molecular modalities.
Product Insights
Consumables represent the largest product segment in the spatial omics market, with a market size of USD 458.1 million in 2025. Unlike instrument purchases, which are one-time capital investments, consumables generate recurring, per-experiment revenue as laboratories process additional tissue sections, run repeat panels, and scale up sample throughput. This recurring-spend dynamic, combined with a growing installed base of spatial omics instruments across research centers, pharmaceutical companies, and biotech firms, each requiring ongoing reagent and consumable supply, makes consumables the largest revenue contributor in the product segment despite instruments carrying the higher individual price point.
Instruments continue to represent a substantial share of the product segment, supporting the specialized image acquisition and tissue-processing capabilities required for spatial profiling. Growth in this segment is comparatively steady, as instrument purchases are capital-intensive and less frequent than consumable restocking, with adoption tied more closely to new laboratory buildouts and platform upgrades than to experiment volume.
The software segment is expected to grow at a CAGR of 17.4% during the forecast period because spatial omics experiments are expected to produce high-dimensional data sets that require specialized software for processing, mapping, visualization, and analysis. The increasing volume of spatial data and growing integration of spatial omics with single-cell sequencing and multi-omics workflows are expected to increase demand for advanced analytical software.
Workflow Insights
The marker size of Instrumental analysis segment was estimated to be USD 384.7 million in 2025. This segment is at the forefront of workflow segments in the spatial omics sector since at this level, molecular information in tissue can be detected and mapped. Spatial profiling instruments offer researchers detailed insights on gene expressions, proteins, and cell interactions but maintain tissue structure. The rising use of spatial omics techniques in disease studies, biomarker identification, and pharmaceutical development is spurring demand for instrumental analysis.
Data analysis is expected to register the highest growth rate of more than 16% over the forecast period due to the complex nature of data generated from spatial omics technologies that need advanced computational power to interpret. In May 2026, the Parker H. Petit Institute for Bioengineering and Bioscience (IBB) established the SODA Center to advance spatial omics by using next-generation analytics, computational methods, and biomedical engineering. Scientists require advanced techniques to analyze spatial, genomic, transcriptomic, and imaging data to understand cellular interactions and biological insights (Source: research.gatech.edu). The growing adoption of AI and advanced analytics in spatial biology will further boost the demand for data analysis solutions.
Sample Type Insights
The FFPE segment holds the dominant market size of USD 514.4 million in 2025. This is largely due to the wide availability of formalin-fixed paraffin-embedded samples through existing tissue banks and their ability to preserve tissue morphology over extended periods. Retrospective studies, biomarker discovery, and research on disease can be performed using such samples owing to the availability of a large number of archived clinical samples. Advancements in technologies that allow the use of FFPE samples within the spatial omics space are increasing the usage of FFPE samples.
Fresh frozen samples are estimated to be the fastest-growing category during the forecast period. This segment is expected to grow at a CAGR of 16.5% owing to the preservation of RNA, DNA, proteins, and various other molecular entities relatively intact with little chemical alteration. Thus, the application of fresh frozen samples is quite relevant for those that require molecular and spatial analysis of such components. Growth in research activities on genetic expression, heterogeneity, and various diseases is expected to increase the application of fresh frozen samples.
Application Insights
Neuroscience is projected to grow at the fastest rate among applications, at a CAGR of 16.8% during the forecast period. Clinical diagnostics, growing at 15.2%, is expanding from an early commercial base as vendors establish clinical laboratory infrastructure and build datasets capable of supporting diagnostic interpretation. The planned CLIA-certified laboratory associated with 10x Genomics represents a specific example of this transition from research-focused platforms toward clinical workflows.
Oncology research accounted for the largest application share of more than 31% in 2025. Tumor microenvironment mapping and treatment-response analysis remain important use cases because spatial information allows researchers to evaluate relationships between tumor cells, immune cells, and surrounding tissue structures.
For broader coverage of multiomics applications in precision medicine beyond spatial resolution, see Polaris's Multiomics for Precision Medicine Market report.
End User Insights
Pharmaceutical and biotechnology companies accounted for the largest end-user share in 2025, at 40.54%. Academic and government research institutes represent the second-largest and fastest-growing end-user group, at 34.27% share and a CAGR of 16.5%, supported by NIH awards to the New York Genome Center and University of Washington that demonstrate the role of government-funded research in advancing spatial biology capabilities. The market size of Clinical and diagnostic laboratories end use was estimated at USD 102.5 million in 2025, supported by the expansion of CLIA laboratory infrastructure and a growing number of academic medical center collaborations focused on treatment-response and biomarker applications.
The market size of Clinical and diagnostic laboratories end use was expected to be USD 102.5 million in 2025. The segment is being supported by the expansion of CLIA laboratory infrastructure and the increasing number of academic medical center collaborations focused on treatment-response and biomarker applications. Broader adoption will depend on the ability of vendors and laboratories to establish reproducible clinical workflows and navigate the evolving regulatory environment.
Market Segment Performance Summary
| Segment | Category | Base-Year Status | Key Driver |
| By Technology | Spatial Transcriptomics | Largest share (45.6%) | Earlier commercial maturity |
| By Technology | Spatial Multi-Omics | Fastest growing | NIH-funded capability development |
| By Application | Oncology Research | Largest share (31.6%) | Tumor microenvironment mapping |
| By Application | Neuroscience | Fastest growing | Large-scale brain cell-type atlas development |
| By End User | Pharmaceutical & Biotechnology Companies | Largest share (40.54%) | Pharma-backed spatial biology partnerships |
| By End User | Academic / Government Institutes | Fastest growing | NIH-funded platform development |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
Regional Insights
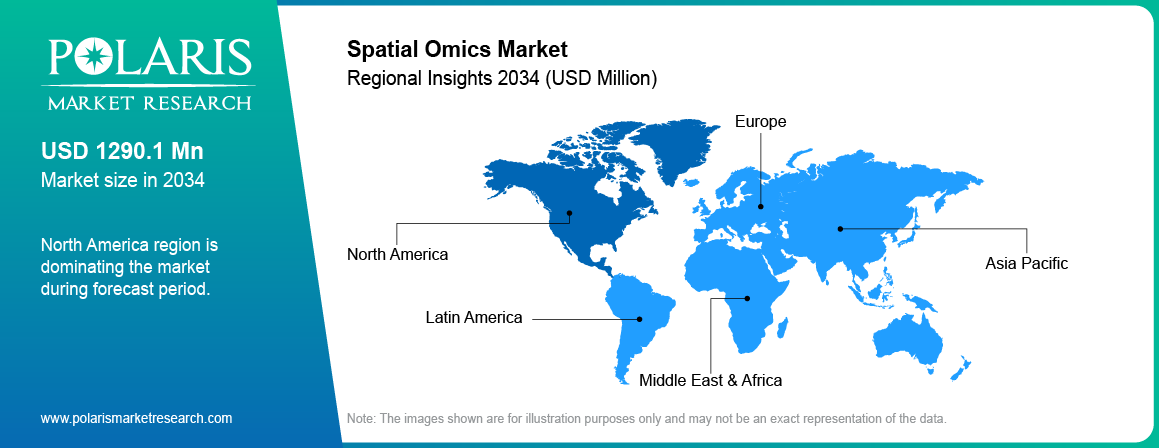
North America Spatial Omics Market Trends
North America dominated the spatial omics market with the estimated market size of USD 334.4 million in 2025. This growth was supported by a strong presence of platform vendors, research institutions, and clinical translation programs. The U.S. remains the regional hub, with continued advances in spatial biology platforms strengthening its position in commercialization and technology development.
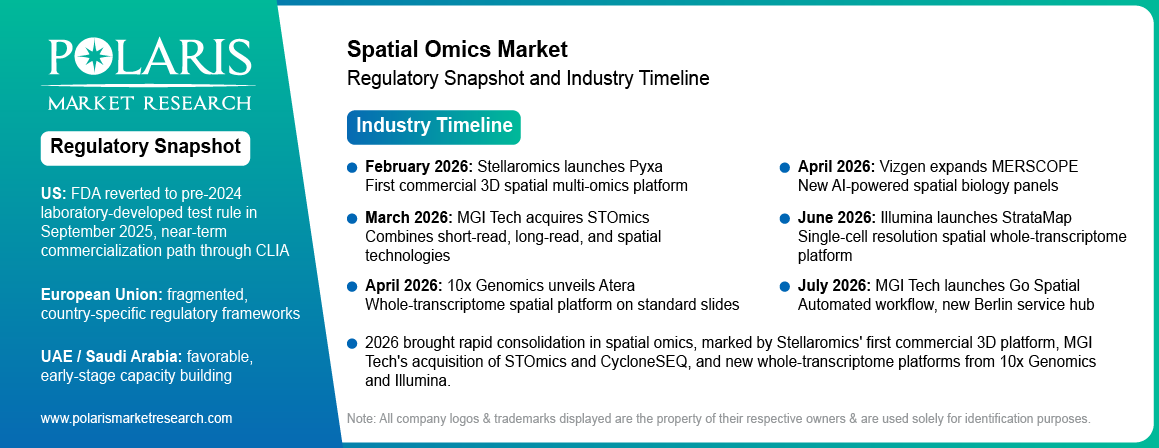
The region's advantage is also supported by expanding clinical and research infrastructure. In June 2026, Illumina launched the StrataMap Spatial Solution, an end-to-end spatial whole-transcriptome platform designed to deliver true single-cell resolution for spatial biology research (Source: illumina.com). Such platform developments are improving research capabilities and are expected to support North America's leading position during the forecast period.
Europe Spatial Omics Market Trends
The European market is the second largest, valued at USD 226.3 million in 2025. Europe represents an important market for spatial omics due to its established academic research base and growing pharmaceutical and biotechnology activity. Germany, the UK, and Switzerland are important markets for translational research and biomarker development, while European laboratories are evaluating clinical applications under regulatory frameworks that differ from the US CMS/CLIA model.
The regional market is expected to benefit from continued adoption across academic and pharmaceutical research environments. Differences in laboratory test regulation across European countries result in a more fragmented path toward clinical-grade spatial diagnostics compared with the US.
The UK spatial omics market is expected to grow at a substantial rate during the forecast period. The UK maintains an established academic genomics and translational research base that supports spatial biology adoption. Existing genomics infrastructure provides a foundation for researchers evaluating spatial transcriptomics, spatial proteomics, and multimodal tissue analysis.
The country is also positioned to participate in translational collaborations linking academic research with clinical applications. However, the scale of the domestic market remains smaller than the US, limiting the number of institutions able to support large clinical-translation programs.
Asia Pacific Spatial Omics Market Trends
Asia Pacific is projected to register strong growth of 16.7% during the forecast period, supported by increasing pharmaceutical R&D investment and expanding biomedical research capabilities. China and Japan represent important regional markets, while participation in multinational spatial biology initiatives is creating additional opportunities for research institutions and translational programs.
Large-scale spatial datasets with international specimen sourcing are also supporting greater participation from research centers outside North America and Europe. The STELA initiative, which targets specimens across three continents, illustrates the increasing importance of geographically diverse tissue datasets for spatial biology research (Source: biopharmaapac.com).
Middle East and Africa Spatial Omics Market Trends
The Middle East and Africa represent an emerging market for spatial omics. The UAE and Saudi Arabia are building biomedical research capacity through national healthcare and research initiatives, while South Africa represents an important center for academic research in Africa.
Adoption remains constrained by platform costs and the availability of specialized technical expertise. The region is therefore expected to remain focused primarily on research applications during the near term, with clinical and large-scale commercial deployment developing more gradually.
Source: Polaris Market Research Analysis
Regulatory Scenario
| Region / Country | Policy Environment | Key Regulations / Programs | Market Implication | Trend |
| US | Neutral | FDA LDT oversight reverted to pre-2024 rule in September 2025; CMS/CLIA governs most spatial diagnostic tests near term | Near-term commercialization path through CLIA laboratories rather than FDA premarket review | Uncertain |
| US | Favorable | NIH R01 grants supporting spatial biology technology development | Sustained public investment in cost and throughput bottlenecks | Expanding |
| European Union | Neutral | National laboratory-test regulatory frameworks distinct from US CMS/CLIA model | Divergent path toward clinical-grade spatial diagnostics | Developing |
| UK | Neutral | National genomics and translational research infrastructure programs | Academic-to-clinical translation supported by existing genomics infrastructure | Stable |
| China | Neutral | Domestic biomedical research investment and data governance requirements | Growing academic medical center participation in global spatial datasets | Developing |
| Japan | Neutral | National biomedical research funding programs | Enterprise and academic co-investment in spatial biology capacity | Stable |
| UAE / Saudi Arabia | Favorable | National biomedical research and healthcare innovation programs | Early-stage capacity building for genomics and spatial biology | Early stage |
Source: Polaris Market Research Analysis.
Source: Polaris Market Research Analysis
Spatial Omics Market Competitive Landscape
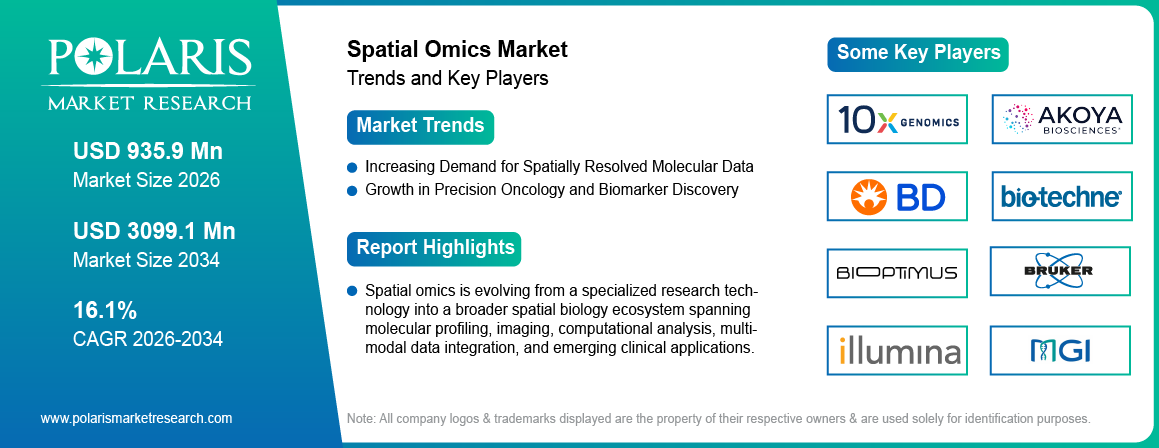
The global spatial omics market includes platform vendors, imaging and proteomics companies, sequencing technology providers, and data infrastructure specialists. Competition is increasingly moving beyond instrument specifications toward clinical translation, academic partnerships, data assets, and the ability to support broader spatial biology workflows.
10x Genomics has established a visible clinical-translation strategy through collaborations with Dana-Farber Cancer Institute and Cleveland Clinic and its planned CLIA-certified laboratory. Illumina represents a parallel competitive model supported by its established in vitro diagnostic portfolio and reimbursement relationships. NanoString Technologies, Akoya Biosciences, Becton Dickinson, and Bioptimus provide additional capabilities across spatial imaging, proteomics, life sciences instrumentation, and spatial data infrastructure.
Competitive Landscape Snapshot
| Company | Est. Market Position | Primary Strength | Geographic Focus | In Report |
| 10x Genomics, Inc. | Top 3 | Xenium platform and vertically integrated clinical diagnostics push | Global | Yes |
| Illumina, Inc. | Top 3 | FDA-approved IVD portfolio and CMS reimbursement relationships | Global | Yes |
| NanoString Technologies (Bruker) | Top 5 | CosMx spatial imaging platform and established research base | Global | Yes |
| Becton Dickinson | Top 5 | Life sciences instrumentation and reagent distribution reach | Global | Yes |
| MGI Tech Co., Ltd. | Top 5 | STOmics spatial multi-omics and integrated sequencing portfolio | Global, led by China | Yes |
| Akoya Biosciences | Regional leader | PhenoCycler spatial proteomics imaging platform | North America, expanding globally | Yes |
| Bio-Techne Corporation | Regional leader | Reagents and protein detection tools for spatial workflows | North America; Europe | Yes |
| PerkinElmer, Inc. | Regional leader | Imaging and analytical instrumentation for spatial biology | Global | Yes |
| Bioptimus | Niche leader | STELA spatial biology data atlas co-development with 10x Genomics | Global, three-continent specimen sourcing | Yes |
| Stellaromics, Inc. | Niche leader | Pyxa platform, first commercial 3D spatial multi-omics system | North America | Yes |
| Vizgen, Inc. | Niche leader | MERSCOPE platform and pre-designed spatial biology panels | North America; Europe; Asia | Yes |
| PathAI, Inc. | Niche leader | AI-driven digital pathology for spatial data interpretation | North America; Europe | Yes |
| S2 Genomics, Inc. | Niche leader | Tissue dissociation and sample-prep instrumentation for spatial workflows | North America | Yes |
| RareCyte, Inc. | Niche leader | Rare-cell detection and spatial imaging systems | North America | Yes |
| Resolve Biosciences GmbH | Niche leader | Molecular Cartography spatial transcriptomics platform | Europe | Yes |
| Ultivue, Inc. | Niche leader | Multiplex tissue imaging reagents and workflows | North America; Europe | Yes |
Source: Company publications, Polaris Market Research Analysis
Spatial Omics Market Technology and Innovation Landscape
Technology development in the spatial omics market is progressing along two important dimensions: workflow throughput and multimodality. Reducing the number of staining and imaging rounds can lower reagent use, processing time, and opportunities for tissue degradation. The University of Washington's NIH-funded probe library is designed to support single-round spatial transcriptomics across thin and thick tissue samples, directly addressing workflow complexity.
Multimodality is addressing a different limitation by combining transcriptomic, proteomic, and epigenomic information while preserving spatial coordinates. The New York Genome Center's NIH-funded platform is designed around simultaneous spatial profiling of multiple molecular modalities, supporting the broader movement toward single-cell spatial multi-omics.
Data infrastructure is also becoming an important technology category. STELA treats large-scale spatial data linkage as core infrastructure, allowing individual experiments to be compared against broader reference datasets. This development may become increasingly important as pharmaceutical and translational research teams seek reproducible spatial signatures across larger patient populations.
Technology and Innovation Landscape Snapshot
| Technology | Adoption Stage | Key Development | Market Impact |
| Single-round, high-resolution spatial transcriptomics probes | Pilot / early research | University of Washington NIH R01 award; 1,000+ probe library, May 2026–April 2030 | Reduces staining and imaging rounds, lowering time and reagent requirements |
| Cost-accessible spatial multi-omic profiling platforms | Pilot / early research | New York Genome Center NIH R01 grant of USD 2.68 million | Lowers the cost barrier limiting broader laboratory adoption |
| Vertically integrated clinical diagnostics infrastructure | Early commercial deployment | 10x Genomics CLIA laboratory plans and Dana-Farber/Cleveland Clinic collaborations | Creates a direct pathway from spatial platform to clinical testing |
| Large-scale shared spatial biology data atlases | Early commercial deployment | STELA atlas targeting up to 100,000 specimens, March 2026 | Lowers the entry barrier for organizations without a complete instrument stack |
Source: Polaris Market Research Analysis.
Premium Insights
Competitive differentiation is expected to shift from instrument resolution alone toward clinical-translation infrastructure. CLIA-certified laboratory capability, established academic medical center partnerships, and outcome-linked spatial datasets can provide vendors with stronger positioning as the market moves toward clinical diagnostics. The pace of this transition will depend on successful clinical validation, development of reproducible spatial assays, and stability in the regulatory framework governing laboratory-developed tests.
The development of spatial biology atlases also creates a broader opportunity for vendors to participate in data infrastructure rather than compete solely through instruments and consumables. Organizations capable of connecting spatial profiles with patient outcomes and large reference datasets can create additional value for pharmaceutical and translational research users.
Use Case Analysis
| Buyer / Investor Type | Primary Use Case | Key Insight Sought | Decision Horizon |
| Academic / translational research lab | Map tissue architecture and cell-type interactions | Resolution, analyte breadth, and sample compatibility | 1–3 years |
| Pharmaceutical biomarker discovery team | Identify treatment-response biomarkers in tumor microenvironments | Clinical-translation credibility of the platform | 2–5 years |
| Clinical laboratory director | Build toward a future spatial diagnostic offering | CLIA compliance pathway and regulatory clarity | 1–3 years |
| Biotech / life sciences investor | Assess platform vendor's clinical-translation trajectory | Named academic partnerships and outcome-linked data assets | 3–7 years |
Source: Polaris Market Research Analysis.
Buyer priorities vary by application and organizational role. Academic and translational research laboratories primarily seek to map tissue architecture and cellular interactions that cannot be retained through conventional dissociation-based methods. Pharmaceutical biomarker teams place greater emphasis on clinical-translation potential, while clinical laboratory directors prioritize the regulatory pathway and CLIA compliance requirements associated with future diagnostic workflows.
Market Entry Barriers
Entry barriers extend beyond instrument investment. Platform capital requirements, recurring consumables, specialized analytical capabilities, and workflow complexity remain important considerations. Data-linkage credibility is becoming an additional barrier as buyers increasingly evaluate whether platform-generated data can be compared against large shared references such as STELA.
Barriers to Entering the Spatial Omics Market:
- Platform Capital Requirements: Spatial omics instruments require substantial upfront investment, while laboratories also need recurring consumables and analytical infrastructure.
- Technical Complexity: Spatial transcriptomics, spatial proteomics, and spatial multi-omics require specialized workflows, tissue preparation, imaging, sequencing, and analytical capabilities.
- Consumables Ecosystem Lock-In: Once a laboratory adopts a platform, continued use of compatible reagents and consumables can influence future purchasing decisions.
- Regulatory Uncertainty: The changing regulatory position surrounding laboratory developed tests creates uncertainty for vendors developing clinical diagnostic applications.
- Clinical Validation Requirements: Vendors seeking clinical adoption need collaborations, outcome-linked datasets, and laboratory infrastructure capable of supporting diagnostic workflows.
- Specialized Talent: Advanced spatial biology workflows require expertise spanning molecular biology, imaging, sequencing, bioinformatics, and tissue analysis.
Key Players in the Spatial Omics Market
- 10x Genomics, Inc.
- Akoya Biosciences, Inc.
- Becton, Dickinson and Company
- Bio-Techne Corporation
- Bioptimus
- Bruker Corporation
- Illumina, Inc.
- MGI Tech Co., Ltd.
- NanoString Technologies, Inc.
- PathAI, Inc.
- PerkinElmer, Inc.
- RareCyte, Inc.
- Resolve Biosciences GmbH
- S2 Genomics, Inc.
- Stellaromics, Inc.
- Ultivue, Inc.
- Vizgen, Inc.
Spatial Omics Industry Developments
- July 2026: MGI Tech launched Go Spatial in Europe, an automated spatial transcriptomics workflow, and partnered with Omics Empower GmbH as a new STOmics-certified service provider, establishing a spatial biology service hub in Berlin (Source: prnewswire.com)
- April 2026: 10x Genomics unveiled Atera, a new whole-transcriptome spatial platform using standard glass microscopy slides, at the AACR annual meeting (Source: genengnews.com)
- April 2026: Vizgen launched new pre-designed spatial biology panels and AI-powered segmentation tools, expanding its MERSCOPE platform for research across human tissue, mouse biology, and oncology (Source: vizgen.com)
- March 3, 2026: MGI Tech acquired STOmics and CycloneSEQ, combining short-read sequencing, long-read nanopore sequencing, and spatial multi-omics technologies under one provider (Source:
prnewswire.com) - February 2026: Stellaromics launched Pyxa at AGBT, the first commercially available platform for 3D spatial multi-omics analysis in intact tissue, moving beyond flat tissue sections to capture cellular architecture in three dimensions (Source: the-scientist.com)
Spatial Omics Market Segmentation
By Technology Outlook (Revenue, USD Million, 2021–2034)
- Spatial Transcriptomics
- Spatial Proteomics
- Spatial Multi-Omics
- Spatial Genomics
By Product Outlook (Revenue, USD Million, 2021–2034)
- Instruments
- By Mode
- Automated
- Semi-automated
- Manual
- By Type
- Sequencing Platforms
- IHC
- Microscopy
- Flow Cytometry
- Mass Spectrometry
- Others
- By Mode
- Consumables
- Software
- Bioinformatics Tools
- Imaging Tools
- Storage & Management Databases
By Workflow Outlook (Revenue, USD Million, 2021–2034)
-
- Sample Preparation
- Instrumental Analysis
- Data Analysis
By Sample Type Outlook (Revenue, USD Million, 2021–2034)
-
- FFPE
- Fresh Frozen
By Application Outlook (Revenue, USD Million, 2021–2034)
- Oncology Research
- Neuroscience
- Immunology
- Developmental Biology
- Drug Discovery & Development
- Clinical Diagnostics
- Other Applications
By End User Outlook (Revenue, USD Million, 2021–2034)
- Academic & Government Research Institutes
- Pharmaceutical & Biotechnology Companies
- Clinical & Diagnostic Laboratories
- Contract Research Organizations
- Other End Users
By Regional Outlook (Revenue, USD Million, 2021–2034)
North America
- US
- Canada
Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Rest of Europe
Asia Pacific
- China
- Japan
- India
- South Korea
- Taiwan
- Australia
- Rest of Asia Pacific
Latin America
- Brazil
- Mexico
- Argentina
- Rest of Latin America
Middle East & Africa
- Saudi Arabia
- UAE
- South Africa
- Rest of Middle East & Africa
Spatial Omics Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 808.6 Million |
| Market Size in 2026 | USD 935.9 Million |
| Revenue Forecast by 2034 | USD 3099.1 Million |
| CAGR | 16.1% from 2026–2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Million and CAGR |
| Report Coverage | Revenue Forecast, Growth Factors, Competitive Landscape, Industry Trends, and Strategic Analysis |
| Segments Covered | By Technology, Product, Workflow, Sample Type, Application, End User, and Region |
| Regional Scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Competitive Landscape | Company Profiling, Product Benchmarking, Financial Analysis, Market Developments, and Strategic Initiatives |
| Report Format | PDF + Excel |
| Customization | Available by Country, Region, and Segment |
Spatial OMICS Market FAQ's
The global spatial omics market was valued at USD 935.9 million in 2026 and is projected to reach USD 3,099.1 million by 2034, registering a CAGR of 16.1% during the forecast period.
The market is driven by increasing demand for spatially resolved molecular information, growth in precision oncology, and expanding biomarker discovery efforts.
North America leads the global market, holding 41.3% share in 2025, due to its concentration of spatial technology vendors, pharmaceutical and biotechnology companies, academic medical centers, research funding, and early clinical translation initiatives.
Asia Pacific is expected to register the fastest growth during the forecast period, at a CAGR of 16.7%, supported by expanding biotechnology research, pharmaceutical R&D, genomics infrastructure, and adoption of advanced molecular profiling technologies.
Spatial transcriptomics accounts for the largest market share, at 45.6% in 2025, due to its mature commercial ecosystem and broad adoption across oncology, neuroscience, developmental biology, pharmaceutical research, and translational applications.
Spatial multi-omics is expected to register the fastest growth among technology segments, at a CAGR of 23.6%, as researchers increasingly seek simultaneous analysis of transcriptomic, proteomic, and epigenomic information within preserved tissue architecture.
Major participants include 10x Genomics, Illumina, Bruker, Akoya Biosciences, Becton Dickinson, MGI Tech, NanoString Technologies, Vizgen, Bio-Techne, Resolve Biosciences, RareCyte, Ultivue, Bioptimus, PathAI, PerkinElmer, S2 Genomics, and Stellaromics.
Major opportunities include clinical translation of spatial biomarkers, AI enabled spatial data analysis, spatial multi-omics, large scale spatial biology atlases, and FFPE compatible workflows.
Pharmaceutical and biotechnology companies lead the end user segment, holding a 40.54% share in 2025. Academic and government research institutes represent the fastest growing end user group, at a CAGR of 16.5%, supported by NIH funded platform development.
Consumables account for the largest product segment, with a market size of USD 458.1 million in 2025, reflecting recurring per experiment reagent and consumable spend as laboratories process additional tissue sections.
Neuroscience is projected to grow at the fastest rate among applications, at a CAGR of 16.8%, supported by large scale spatial brain atlas initiatives such as the Allen Institute's ABC Atlas.
FFPE samples represent the dominant sample type, with a market size of USD 514.4 million in 2025, due to their availability through existing tissue banks. Fresh frozen samples are the fastest growing category, at a CAGR of 16.5%, owing to better preservation of RNA, DNA, and protein integrity.
Spatial transcriptomics measures gene expression while preserving the location of that activity within tissue, and currently leads the market with 45.6% share. Spatial multi-omics goes a step further by capturing transcriptomic, proteomic, and epigenomic information at the same time within the same spatial context, and is the fastest growing technology segment, at a CAGR of 23.6%.
Download Sample Report of Spatial OMICS Market
Please fill out the form to request a customized copy of the research report.