Aerospace Materials Market Growth Drivers, Industry Outlook, 2026–2034
REPORT DETAILS
Aerospace Materials Market Summary
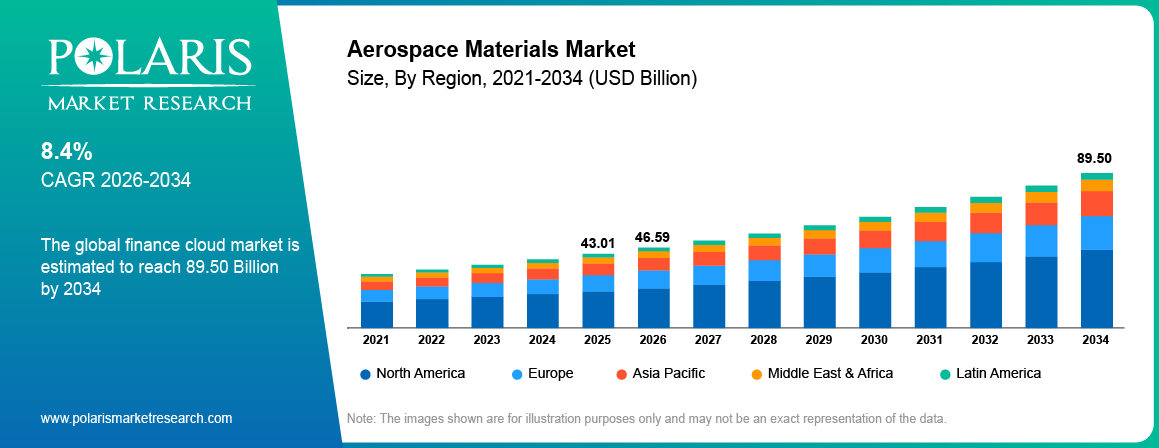
The global aerospace materials market size was valued at USD 43.01 billion in 2025, growing at a CAGR of 8.4% from 2026 to 2034. Rising global air travel driven by urbanization along with increasing military modernization programs fuels the demand for aerospace materials.
Market Statistics
Aerospace Materials Market Key Takeaways
- As per our aerospace materials market analysis, Europe dominated with a 36.8% share in 2025. The leading position is supported by established aerospace manufacturing. Strong defense programs and advanced material R&D boost the demand for aerospace materials.
- North America is expected to exhibit the highest CAGR of 9.2% during the forecast period. Rising commercial aircraft production and increasing regional air travel drive the market growth.
- The U.S. led the North American market with 78.4% share in 2025. Increasing defense modernization programs and advancements in additive manufacturing fuel the dominance.
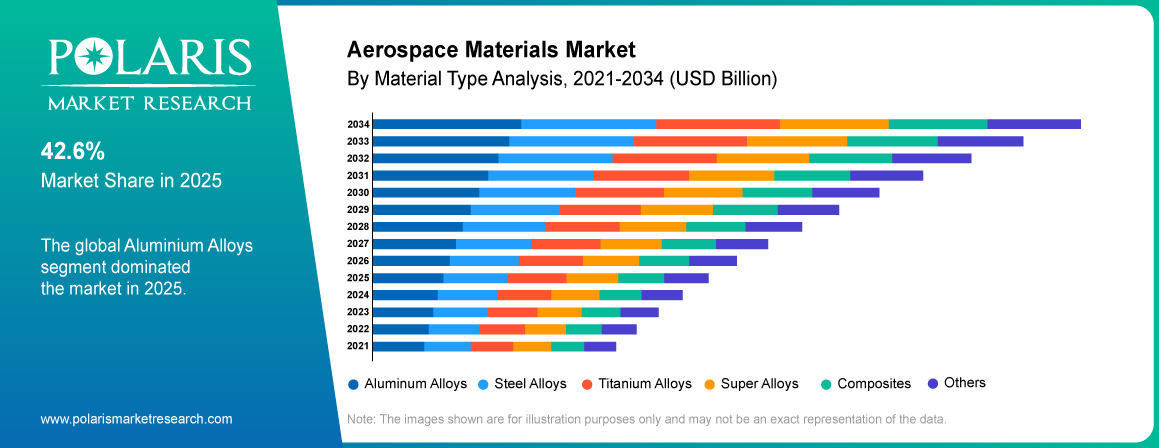
- Aluminum alloys dominated with a 42.6% share in 2025. It is driven by their widespread use in commercial and defense aircraft.
- The composites segment is projected to register the highest CAGR of 10.1% during the forecast period. Rising adoption in next-generation aircraft and increasing demand for high-strength, lightweight materials drive the segment growth.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observation.
What are Aerospace Materials?
Aerospace materials are used in the manufacturing of planes, aircraft, spacecraft, satellite, and various other components. Some aerospace materials include aluminum, titanium, steel, composite materials, and plastics. These materials exhibit high strength, lightweight nature, and can withstand extreme conditions. They are required in building and assembling aircraft and spacecraft, enabling safe and reliable operation. The aerospace materials market is expected to grow in the future due to the increasing popularity of air transport, propelling the demand for aircraft. Also, increasing space projects across the countries increase the demand for spacecraft, driving market expansion. Additionally, the demand for cost-effective and efficient aircraft and spacecraft will also contribute to the growth of the aerospace materials market.
Leading manufacturers in the industry provide a wide range of materials, including aluminum, titanium, and carbon fiber composites. They even offer materials for various other uses, such as structures, engines, and interiors. They emphasize high-performance formulae, low costs, and adherence to regulatory requirements. It assists them in meeting their goals concerning aircraft performance and sustainability. These firms are focusing on developments of additive manufacturing, hybrid metals, and digital material testing. These strategies are increasingly enhancing design flexibility and production efficiency.
How are Aerospace Materials Manufactured?
- Aerospace materials, including titanium, aluminum, steel, and composite materials, require specialized production processes.
- Production process, including casting, forging, molding, or machining, is selected depending on material type.
- Other processes include curing, smelting, and heat treatment.
- Aerospace-grade materials are subjected to stringent testing and certification processes before use.
- The aerospace grade materials have to undergo extreme pressure and temperatures to meet the various safety standards and ensure they can withstand the extreme conditions they will endure when in use.
Composites vs Aluminum vs Titanium in Aerospace
| Attribute | Composites | Aluminum Alloys | Titanium Alloys |
| Relative weight | Lightest (highest strength-to-weight) | Light, ~2.7 g/cm³ density | Moderate, ~4.5 g/cm³ density |
| Corrosion resistance | Excellent (inert to most corrosion) | Good, requires coatings/anodizing | Excellent, naturally corrosion-resistant |
| Temperature tolerance | Moderate (resin-dependent, typically <200°C) | Moderate (loses strength above ~150°C) | High (stable at 400°C+, ideal for engines) |
| Relative manufacturing cost | High (layup, curing, tooling) | Low–moderate (mature, scalable processes) | High (machining and alloying are energy-intensive) |
| Typical aerospace use | Wings, fuselage skins, next-gen airframe materials | Fuselage, wing structures, legacy platforms | Engine components, landing gear, fasteners |
| Recyclability | Limited (improving with thermoplastic composites) | High (widely recycled) | High (but reprocessing is costly) |
Source: Polaris Market Research Analysis
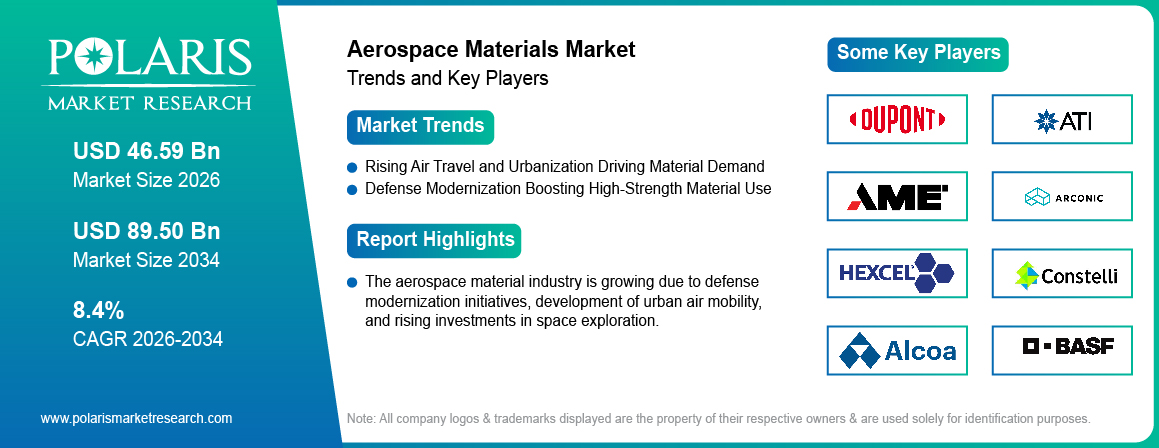
The aerospace material industry is growing due to defense modernization initiatives, development of urban air mobility, and rising investments in space exploration. Support from governments, development of aerospace infrastructure, and fast-emerging economies such as India and Brazil are opening up new opportunities. Furthermore, aftermarket aerospace materials are increasingly used in aircraft maintenance, repair, overhaul, and fleet modernization activities. Increasing demand for such activities propels the requirement for MRO materials.
Source: Polaris Market Research Analysis
Market Dynamics
Driver: Rising Air Travel and Urbanization Driving Material Demand
Increasing urbanization and growing middle-class populations are boosting worldwide air travel. Rising preference for air travel prompts airlines to build and modernize their fleets. According to the United Nations, 55% of the population lives in urban areas and will increase to 68% by 2050, with an additional 2.5 billion urban residents mostly from Asia and Africa (Source: un.org). Expanding urbanization leads to a growing demand for passenger aircraft. This factor increases the use of aerospace materials in production and MRO activities. Further, aerospace firms are considering using lightweight materials such as aluminum and composites because of their lighter weight and increased fuel efficiency. These materials improve performance and reduce operating costs, which fuels their demand.
Driver: Defense Modernization Boosting High-Strength Material Use
The U.S., China, India, and other economies are expanding defense modernization initiatives. Defense aircraft need materials with better endurance and performance at extreme temperatures and conditions. Thus, growing defense modernization programs demand high-strength metals and composite materials. These materials are required in producing next-generation fighter aircraft, unmanned aerial vehicles (UAVs), and military transport aircraft. Rising defense spending and strategic acquisition programs continue to drive the consistent growth of aerospace material consumption in the defense industry.
Restraint: High Material & Processing Costs
High material and processing costs are a major restraint to the aerospace materials market. The high-performance materials such as titanium alloy, carbon fiber-reinforced plastics, and other special metals require expensive processing equipment for manufacturing and additional high-cost finishing processes. The processing of materials demands highly experienced manpower, which increases the overall production cost. Moreover, the aerospace industry emphasizes adhering strictly to the quality control and safety regulations. This increases the material testing and certification costs. These factors impede the aerospace materials industry growth.
Restraint: Raw Material Supply & Certification Constraints
Raw material supply and certification constraints are restraining the growth of the aerospace materials market. Aerospace manufacturers are highly dependent on the constant supply of raw materials for their production process. Disruptions in mining, manufacturing, transportation, and global trade of these materials cause scarcity and price fluctuations. Moreover, aerospace materials must undergo certification and testing before they can be used to make aircraft and spacecraft. This process can be both time-consuming and expensive, particularly when it comes to new materials and new suppliers. Supply chain disruptions and lengthy certification processes can delay the manufacturing and development of aircraft, thus impeding market expansion.
Opportunity: Growing Demand for Lightweight and Fuel-Efficient Aircraft
The need for lightweight and fuel-efficient aircraft is expected to create an opportunity. Lightweight aerospace materials help reduce the weight of aircraft and spacecraft. They are also preferred to maintain aircraft safety and performance. Transportation is one of the leading causes of carbon emissions. Thus, reducing weight lowers carbon emissions and benefits the environment. Further, lowered weights of airplanes and spacecraft lead to increased payload capacity, enhanced speed, and better performance.
Airlines and aircraft manufacturers are looking to lower their fuel consumption, costs, and emissions. For instance, in January 2025, easyJet announced the use of lower-weight paint to cut the CO2 emission by 4,095 tonnes when rolled out fleet-wide. This shows the efforts manufacturers are taking to promote emission control. Thus, the demand for advanced aircraft materials is growing worldwide. Aircraft lightweighting can be made with the help of carbon fiber, titanium, aluminum alloys, or other modern materials. In spacecraft, every superfluous pound increases the cost of the launch. Therefore, it is essential to reduce weights to make space exploration affordable. Modern aircraft producers will be compelled to use innovative and lightweight materials to make planes more efficient. Thus, the increasing production of commercial aircraft and spacecraft and the need for cost-effective and ecological planes will create lucrative opportunities (Source: simpleflying.com).
Key Areas of Aerospace Material Market
Growth of Aerospace Composite Materials
The application of composite materials to the aerospace sector is rising due to a growing need to cut aircraft weight while maximizing performance. Composite materials consist of two or more physical elements that combine to form a structure possessing outstanding mechanical characteristics. Composite materials exhibit unique qualities compared to conventional metallic counterparts while providing a better strength-to-weight ratio. This enables reduced weight, fuel consumption, and emissions. The high degree of resistance to fatigue and corrosion that composites possess is vital in enhancing the longevity of aircraft parts. Additionally, the increased production rate of next-gen commercial and military aircraft coupled with the high rate of technological innovations is anticipated to propel the demand for aerospace composites.
Titanium Alloys in Aerospace
Titanium Alloys are primarily used in modern aircraft due to their incredible strength to weight ratio, and resistance to corrosion. Moreover, titanium is a relatively lightweight material with a higher melting point than many other metals. As a result, titanium alloys exhibit a better strength-to-weight ratio compared to alloys such as aluminum and alloy steel. Although titanium is expensive, it is used in applications that require high tensile strength and have to withstand extreme temperatures. Consequently, the growing demand for titanium alloys in the commercial, defense, and aerospace sectors is anticipated to boost titanium alloy usage in the next decade.
High Temperature Superalloys
High-temperature superalloys are typically metal alloys that possess extraordinary resistance to pressure and deformation even at elevated temperatures. They are primarily used to manufacture aircraft engine parts, gas turbines, and other high-performance parts. High-performance superalloys are typically characterized by excellent creep strength, oxidation resistance, and fatigue resistance. Moreover, the demand for high-temperature superalloys is growing as aircraft manufacturers are required to design planes capable of withstanding higher temperatures. The rising production rates of commercial aircraft and the growing demand for military aircraft will propel the high-temperature aerospace superalloys market during the forecast period.
Role of Additive Manufacturing in Aerospace Materials
Additive manufacturing in aerospace materials is primarily projected to revolutionize the industry. Additive manufacturing is a form of 3D printing that facilitates the production of products with minimal waste. Additionally, it enables faster production of high-quality aircraft parts with complex geometries. As a result, aerospace companies are adopting additive manufacturing to produce titanium, aluminum, and high-performance alloys to manufacture next-gen aircraft parts and prototypes. Additive manufacturing is vital in ensuring reduced weight and increased performance of modern aircraft. Aerospace materials companies are investing significantly in this technology. This enables faster and more efficient production of 3D-printed aerospace parts.
Sustainable Aerospace Materials Development
Sustainable aerospace materials development involves the utilization of aerospace materials to meet the needs of present and future aircraft while minimizing environmental impact. Sustainable development in aerospace materials typically focuses on using lighter materials to reduce fuel burn and, consequently, carbon emissions. For example, manufacturers are gradually replacing heavier materials with lighter and recyclable aluminum. The use of recycled aluminum will minimize environmental pollution and save energy as there is no need to extract and process raw materials into new products. Additionally, the sustainable development of advanced aerospace materials is projected to reduce global warming and help in meeting emissions regulations.
The shift toward bio-based and recyclable aerospace materials is advancing global sustainability goals and supporting long-term industry growth. For instance, in May 2025, HH Chemical launched a bio-based materials brand, BIODEX. It is expected to lower carbon emissions. It promotes sustainable material use across various applications, including aerospace (Source: PRNewswire).
Segmentation and Regional Market Summary
| Segment Axis | 2025 Leading Segment | Fastest-Growing Segment (2026–2034) |
| Material Type | Aluminum Alloys | Composites |
| Aircraft Type | Large Wide Body | Single Aisle |
| Application | Commercial Aircraft | Defense Aircraft |
| Region | Europe | North America |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
Segmental Insights
Material Type Analysis
On the basis of material, the market is segmented into aluminum alloys, steel alloys, titanium alloys, super alloys, composites, and others. Aluminum alloys held the largest share of 42.6% in 2025. This is because these materials are light, resistant to corrosion, and economical. They reduce the overall weight of the aircraft, which reduces fuel consumption. This implies low cost for operating aircraft. They are durable as well as flexible and can therefore, be manufactured into different shapes with ease. They are also resistant to weather conditions and can be recycled, thus promoting sustainability. The versatility of this material allows its usage in several parts of the aircraft such as fuselage, wings and other structural systems, thereby dominating the segment growth.
The composites segment is projected to register the fastest growth of CAGR 10.1% during the forecast period. This is because they have an improved strength to weight ratio. Therefore, they can reduce the weight of the aircraft without compromising on the strength and rigidity. These materials are also highly durable and resistant to corrosion. Thus, they improve the overall performance and longevity of the aircraft. The demand for fuel-efficient aircraft is increasing, which prompts manufacturers to use advanced materials instead of conventional ones. Technological developments are also taking place to improve the properties of composites, making them more desirable. Therefore, their demand is expected to grow at a considerable rate during the forecast period.
Aircraft Type Analysis
On the basis of aircraft type, the market is segmented into large wide body, medium wide body, small wide body, single aisle, and regional jets. Large wide body aircraft held the largest share of 44.8% in 2025. This is because they are majorly used in international and domestic commercial flights. The aircraft have a higher capacity as compared to other aircraft types. Thus, they require substantial amount of aerospace materials in their manufacturing process. These aircraft are used in long haul flights. Thus, they are in high demand as compared to narrow body aircraft. The increase in demand for long distance international travel is expected to propel the demand for large wide-body aircraft during the forecast period. Additionally, aircraft manufacturers are using advanced materials to enhance the performance of these aircraft while also making them lighter, thereby driving the segment growth.
Single-aisle aircraft segment is anticipated to witness the highest CAGR of 9.6% during the forecast period. This is due to the rising demand for short and medium haul aircraft. They are largely used by commercial aircraft and low cost carriers. This is because these aircraft are cost efficient as compared to wide body aircraft. Moreover, increasing number of short haul and regional commercial flights is expected to drive the demand for single-aisle aircraft. Manufacturers are also using lighter materials to make them more economical and enhance fuel efficiency. Moreover, increasing demand for air travel is expected to propel the growth of this segment, since these aircraft mainly serve short distances.
Application Analysis
On the basis of application, the market is segmented into commercial aircraft, defense aircraft, helicopters, space vehicles, and other applications. Commercial aircraft held the largest share of 68.5% in 2025. This is because they are produced in a larger number as compared to other applications. According to the International Air Transport Association (IATA), the number of international passengers travelling through commercial aircraft reached 109.7 million in 2025, with a 4.5% Y-o-Y growth. Moreover, increasing demand for commercial air travel and fleet modernization would enhance the demand for aerospace materials across other commercial aircraft applications (Source: iata.org).
The defense aircraft segment is projected to witness the highest CAGR of 9.3% during the projected period. This is due to the growing number of military programs worldwide. Moreover, there is an increasing trend of using high-performance metals and composites in manufacturing fighters aircraft, drones, combat aircraft and transport planes. In addition, various government agencies are involved in buying defense aircraft across the globe.
Real-World Use Cases & Applications
Most aerospace materials are used in the production of aircraft and spacecraft. For example, aluminum is used to manufacture plane fuselages and wings due to its remarkable strength and lightweight. Composite materials are used to make commercial airplanes such as the Boeing 787 Dreamliner. These materials are used in plane manufacturing because they are light, thereby reducing fuel consumption. On the other hand, titanium is used to manufacture jet engines and landing gear due to its high tensile strength and ability to resist high temperatures. Moreover, superalloys find their application in the production of turbines. In spacecrafts, advanced materials are used to ensure the spacecraft can withstand the extreme temperatures, pressure, and other environmental conditions it will encounter during its mission.
Source: Polaris Market Research Analysis
Regional Analysis
Europe Aerospace Materials Market Overview
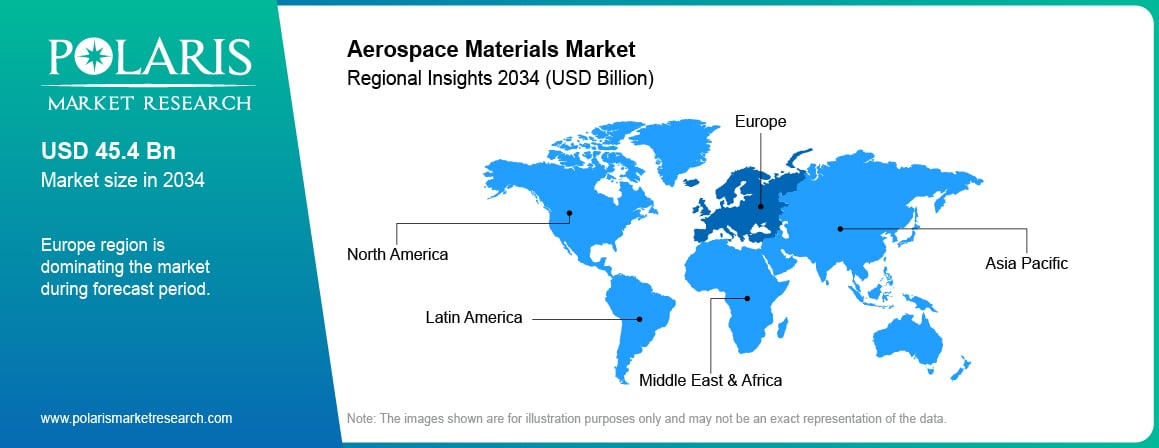
In 2025, Europe led the global aerospace materials market with 36.8% share. The dominance is attributed to the presence of Airbus and entrenched aerospace supply chains. Further, the region is facilitated by government policies for green aviation and fuel-efficient aircraft. According to the European Federation for Transport and Environment AISBL, European airports recorded an aviation emission level of 195 million tonnes CO₂ in 2025. The region has also made efforts toward sustainability targets by increasing sustainable aviation fuels and efficiency measures that reduce emissions by two-thirds by 2050. Further, use of advanced composites for commercial and defense applications drives market growth (Source: transportenvironment.org).
France Aerospace Materials Market Insight
The market in France is expected to register the highest CAGR of 8.9% in Europe during the forecast period. France's market is fueled by government-backed aerospace programs and Airbus operations. Further, investments in renewable aircraft materials increase demand. Advances in composites and high-performance alloys also boost material adoption.
Asia Pacific Aerospace Materials Market
Asia Pacific held a 28.7% share in the global market in 2025. This is due to the fast growth of commercial aircraft manufacturing in China and India. Further, growing urban air travel and regional connectivity drive fleet needs. Population Reference Bureau estimates Asia to be responsible for more than 60% of world urban growth, having 2.6 billion urban dwellers by 2030 with an urbanization level of 53%. Further, government incentives for aerospace manufacturing and defense modernization also accelerate the growth of the market.
North America Aerospace Materials Market
The market in North America is expected to record the highest CAGR of 9.2% during the forecast period. The growth is driven by the availability of major aircraft producers and sophisticated defense programs. Further, increased spending in commercial airplane manufacture and fleet renewal propels material demand. Furthermore, composites and additive manufacturing innovations improve productivity.
U.S. Aerospace Materials Market Overview
The U.S. dominated the regional market with a 78.4% share in 2025. This is due to the presence of commercial and defense aerospace programs. In March 2026, GE Aerospace announced its plan to invest USD 1 billion in manufacturing sites and supplier base across the U.S. during 2026. The investment will increase engine deliveries and strengthen defense production to meet rising military demand (Source: geaerospace.com). Additionally, government initiatives and defense modernization schemes drive the adoption of high-performance composites. Additionally, growing emphasis on sustainable materials fuels market growth.
India's Emerging Aerospace Manufacturing Ecosystem
India’s aerospace manufacturing base is growing exponentially due to the country’s increasing need for aircraft fabrication and defense aircraft production. India’s growing space program propels the growth of the aerospace materials market in India. The India aerospace manufacturing industry will benefit from supportive policies of indigenous aircraft manufacturing by the government for both domestic and foreign aircraft manufacturers. India is emerging as an important supplier of commercial aircraft and is poised to meet the demand for both commercial and military aircraft.
Source: Polaris Market Research Analysis
Technological Advancements in Aerospace Materials
Technological developments in aerospace materials will lead to the creation of stronger and more durable aircraft parts. Manufacturers are developing new composite materials, titanium alloys, and high-performance materials. Adaptive materials that change characteristics when exposed to certain stimuli are also being developed. Additionally, new approaches to aircraft manufacturing will certainly lead to higher rates of material recycling and improved production methods. Advanced materials and new production techniques will make aircraft more sustainable by decreasing greenhouse gas emissions from aircraft on the ground and from engines, and by improving fuel economy.
Competitive Analysis
The aerospace materials market is moderately competitive. Aerospace material suppliers are developing capability in lightweight alloys, composites, and high-performance metals. Additionally, investment in additive manufacturing, advanced fabrication technologies, and emerging regions, as well as strategic collaborations, drive material quality, production efficiency, and worldwide market positioning.
List of Aerospace Materials Key Players
- Alcoa Corporation
- Allegheny Technologies (ATI)
- AMETEK Inc.
- Arconic Corporation
- BASF SE
- Constellium SE
- DuPont
- GKN Aerospace
- Global Titanium Inc.
- Hexcel Corporation
- Howmet Aerospace
- Materion Corporation
- Precision Castparts Corp. (PCC)
- SGL Carbon
- Solvay S.A. (Syensqo)
- Spirit AeroSystems, Inc.
- Teijin Limited
- Toray Industries Inc.
- VSMPO-AVISMA
Vendor Positioning
| Company | Headquarters | Core Aerospace Material Focus | Notable Recent Development |
| Alcoa Corporation | United States | Aluminum alloys | Ongoing aerospace-grade aluminum capacity investment |
| Arconic Corporation | United States | Aluminum, engineered products | Extrusion capacity consolidation activity |
| Hexcel Corporation | United States | Carbon fiber, composites, prepreg | Sept. 2025 — corrosion-resistant composite pressure vessel with HyPerComp |
| Toray Industries Inc. | Japan | Carbon fiber, composites | Continued prepreg capacity expansion for commercial programs |
| Solvay / Syensqo | Belgium | High-performance polymers, composites | Sept. 2025 — Syensqo launch of aerospace polymer portfolio at K 2025 |
| Teijin Limited | Japan | Composites, thermoplastics | Prepreg supply agreements with major OEMs |
| GKN Aerospace | United Kingdom | Structures, engine systems | European composite repair capacity expansion |
| Howmet Aerospace | United States | Titanium, superalloy castings/forgings | Structural castings capacity growth |
| Materion Corporation | United States | Metal matrix composites, specialty alloys | June 2025 — SupremEX MMC selected for U.S. Army tiltrotor prototypes |
| SGL Carbon | Germany | Carbon fiber, composite materials | Energy-efficiency investment in fiber production |
| AMETEK Inc. | United States | Precision instruments, specialty metals | Continued aerospace instrumentation supply |
| Global Titanium Inc. | United States | Titanium alloys, powders | Titanium powder capacity for additive manufacturing |
| BASF SE | Germany | Global chemicals & advanced materials giant | Broad portfolio spanning composite resins, adhesives, sealants, and coatings (Ardrox, Naftoseal, Tech Cool, Oakite) for airframe, engine, and MRO applications, plus 3D-printed high-temperature tooling materials |
| VSMPO-AVISMA | Russia | World's largest titanium producer | Supplies long-term titanium forging partner to Boeing (737, 767, 777, 787) and Airbus (A350) via joint ventures like Ural Boeing Manufacturing |
| Allegheny Technologies (ATI) | United States | Specialty metals & alloys manufacture | Advanced titanium, nickel-based superalloys, and specialty steel for jet engine components, airframe structures, and landing systems; historically also a domestic titanium sponge producer |
| Precision Castparts Corp. (PCC) | United States | Complex metal components & structures (Berkshire Hathaway) | Leading manufacturer of investment castings, forgings, and fasteners in titanium, nickel, and steel alloys for engines, airframes, and structural aerospace applications |
| Constellium SE | France | Advanced aluminum solutions provider | Aluminum-lithium alloys and Airware® technology offering high strength-to-weight ratios for aerostructures, a key lightweight alternative/complement to composites |
| DuPont | United States | Diversified specialty materials science company | Kevlar® aramid fiber, high-performance resins, and thermal/flame-resistant materials used across airframes, radomes, and protective aerospace applications |
| Spirit AeroSystems, Inc. | United States | Aerostructures manufacturer (Tier-1 supplier) | Major fabricator of fuselage sections, wings, nacelles, and pylons using advanced metallic and composite materials for Boeing and Airbus programs (currently being integrated into Boeing) |
Source: Polaris Market Research Analysis
Industry Developments
- August 2026: Sarla Aviation signed a Memorandum of Understanding (MoU) with Hexcel. It is a long-term supply and technology partnership for the composite materials used in its aircraft. Under the agreement, Sarla plans to purchase Hexcel aerospace-grade prepregs and carbon and glass fiber reinforcements for airframe, honeycomb core, adhesives, and surfacing films. The materials will be used for primary and secondary structures. (Source: jeccomposites.com)
- July 2026: Hyperion Materials & Technologies launched its Aerospace Manufacturing Guide. The guide helped aerospace toolmakers and OEMs select advanced carbide and diamond materials for machining superalloys, titanium, and composites, and it became available through the company’s online resource library. (Source: cagexam.in)
- June 2026: Toray Composite Materials America launched 3960-FC, a fast-cure composite material for aerospace and defense manufacturing. The material reduced cure time by up to 45% while maintaining mechanical performance, helping manufacturers increase production rates, reduce costs, and improve processing efficiency. (Source: toraycma.com)
- September 2025: Constellium extended its long-term partnership with Embraer to supply high-performance aluminum solutions, such as advanced aluminum-lithium alloy, Airware®. With this deal, Constellium will support Embraer’s executive jets, commercial aviation, and defense & security divisions. (Source: constellium.com)
Future Outlook
According to our aerospace materials market forecast, the market size is estimated to witness high growth during the forecast period. The increasing demand for aircraft, commercial and defense, and rising need for lightweight and fuel-efficient materials are some of the key factors driving the market growth. Moreover, the growth of the space industry and development of advanced technologies such as composites, titanium, super alloys, and 3D printing are also contributing factors to the market growth.
Aerospace Materials Market Segmentation
By Material Type Outlook (Revenue, USD Billion, 2021–2034)
- Aluminum Alloys
- Steel Alloys
- Titanium Alloys
- Super Alloys
- Composites
- Others
By Aircraft Type Outlook (Revenue, USD Billion, 2021–2034)
- Large Wide Body
- Medium Wide Body
- Small Wide Body
- Single Aisle
- Regional Jets
By Application Outlook (Revenue, USD Billion, 2021–2034)
- Commercial Aircraft
- Defense Aircraft
- Helicopters
- Space Vehicles
- Other Application
By Regional Outlook (Revenue, USD Billion, 2021–2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Aerospace Materials Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 43.01 Billion |
| Market Size in 2026 | USD 46.59 Billion |
| Revenue Forecast by 2034 | USD 89.50 Billion |
| CAGR | 8.4% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Formatt |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Aerospace Materials Market FAQ's
The global market size was valued at USD 43.01 billion in 2025 and is projected to grow to USD 89.50 billion by 2034.
The global market is projected to register a CAGR of 8.4% during the forecast period.
Europe led the market with a 36.8% share due to advanced aerospace manufacturing, established aircraft OEMs, and strong defense programs.
A few of the key players in the market are Alcoa Corporation, Arconic Corporation, Hexcel Corporation, Toray Industries Inc., Solvay S.A., Teijin Limited, GKN Aerospace, Howmet Aerospace, Materion Corporation, SGL Carbon, AMETEK Inc., and Global Titanium Inc.
Aluminium alloys led the market with a 42.6% share due to their extensive application in commercial and military aircraft for lightweight and fuel-efficient structures.
Defence aircraft is expected to grow fastest, driven by rising military modernization programs and increasing high-performance material adoption.
Increasing aircraft production, rising air travel, defense modernization, and growing space activities are driving market growth.
Lightweight materials help reduce aircraft weight, improve fuel efficiency, lower operating costs, and reduce carbon emissions.
High material costs, complex manufacturing processes, supply chain disruptions, and strict certification requirements are major challenges.
The market is expected to grow steadily, supported by technological advancements, sustainable materials, aircraft modernization, and increasing space exploration activities
Download Sample Report of Aerospace Materials Market
Please fill out the form to request a customized copy of the research report.