
Global Cyber Warfare Market Size, Share, Trends and Forecast, 2026–2034
REPORT DETAILS
Cyber Warfare Market Summary
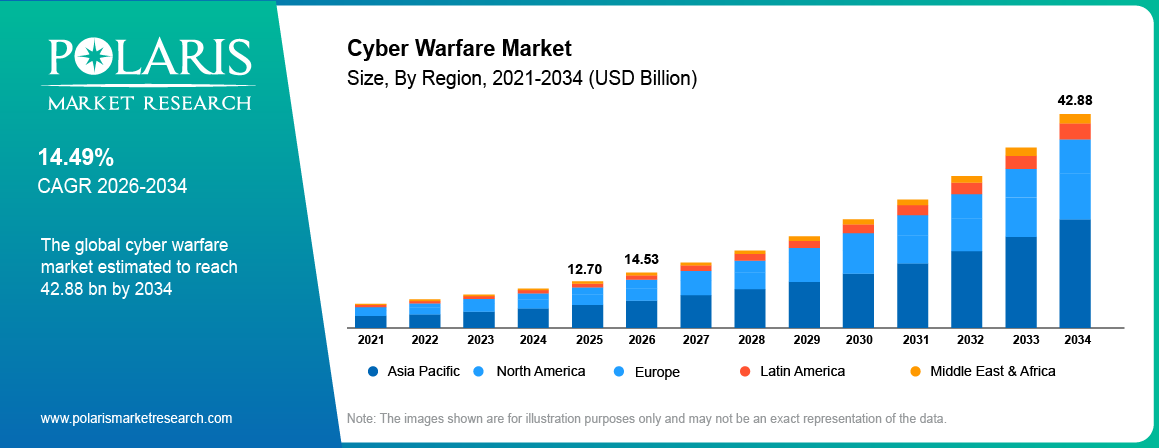
The global cyber warfare market size was valued at USD 12.70 billion in 2025. The market is expected to exhibit a CAGR of 14.49% from 2026 to 2034. Market growth is attributed to rising state-sponsored cyber operations and higher investments in the defense cybersecurity market. Additionally, integrating artificial intelligence into offensive and defensive cyber capabilities is driving market expansion.
Market Statistics
Key Takeaways
- North America accounted for 39.62% share of the cyber warfare market in 2025, attributed to defense modernization, established cyber command capabilities, and investments in military network security and cyber operations.
- The Asia Pacific market is projected to experience a 17.26% CAGR during the forecast period. The modernization of the military, development of national cyber commands, and increase in investments in the protection of critical infrastructure boost regional market growth.
- In 2025, the solutions sector accounted for 67.18% of the total revenue generated by the market due to increasing demand for cyber mission platforms, threat intelligence, network defense, and cyber range solutions.
- The cyber sabotage segment is expected to record a CAGR of 15.83% during 2026–2034, driven by the priorities of national security, infrastructure exposure, technical requirements, and investment in cyber resilience.
- In 2025, the defense segment dominated the global cyber warfare market with 31.26% share, owing to the need for conducting both offensive and defensive cyber operations as well as network security within the military.
- The government segment is expected to grow at a CAGR of 14.92% during 2026–2034, due to rising demands for threat intelligence, national cybersecurity programs, and public-sector cyber resilience initiatives.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is Cyber Warfare?
Cyber warfare is the use of digital attack by a nation state, its proxies or armed forces to disrupt, degrade or destroy an adversary’s networks, critical infrastructure and military systems or to obtain sensitive information for strategic advantage. In simple terms, it is war conducted over computer networks, or in conjunction with physical weapons.
The market for cyberwarfare is composed of solutions and services bought by governments, militaries and defense contractors to conduct, deter and defend against these operations. Solutions include threat intelligence platforms, network and endpoint defense, cyber mission platforms, and cyber range and simulation environments. Services include cyber operations support, managed detection and response, training, and consulting. Demand comes from defense, government, aerospace, homeland security, and corporate users involved in national security or the defense industrial base. General enterprise cybersecurity spending without a national-security or defense-industrial purpose is excluded from this market cyber warfare definition.
Some of the key forces are shaping the market outlook. Firstly, state-sponsored campaigns increasingly target critical infrastructure and maintain access to networks that could become strategically important during a crisis. The Volt Typhoon and Salt Typhoon events have increased fears of continued access to communications and infrastructure systems. Secondly, defense organizations are investing in cyber mission capabilities, operational resilience, threat intelligence and specialized training. Third, artificial intelligence is changing cyber operations, with faster data analysis, automated security workflows and new kinds of AI-powered reconnaissance and intrusion activity.
North America is expected to stay a dominant player, buoyed by US defense programs, established cyber commands and a massive defense technology ecosystem. Asia Pacific is anticipated to register the fastest growth, due to expansion of cyber defense capabilities and modernization of military infrastructure by governments. These regional positions must be validated against the approved 2025 market dataset before publication.
Cyber Warfare vs Cybersecurity vs Electronic Warfare
Cyber warfare, cyber security and electronic warfare are related terms, but they are not the same. Cyber warfare is the use of digital operations to achieve military or strategic objectives. Cybersecurity is the body of technologies, processes, and services designed to protect systems, networks, and information against unauthorized access, destruction, or change. Electronic warfare is the control of the electromagnetic spectrum by electronic attack, protection and support.
These fields overlap in modern military environments. A coordinated operation may involve cyber access, electronic interference, intelligence collection, and conventional military action. Market sizing should nevertheless maintain clear boundaries to prevent double-counting products that serve several operational areas.
| Dimension | Cyber warfare | Cybersecurity | Electronic warfare (EW) |
| What it is | State or military use of cyber means to attack or defend national interests | Protecting any organization's systems and data from compromise | Use of the electromagnetic spectrum to sense, attack or protect |
| Primary buyers | Defense ministries, cyber commands, intelligence agencies, primes | Every sector, mostly enterprises | Armed forces |
| Includes offense? | Yes (authorized OCO) | No | Yes (jamming, spoofing) |
| Tools | Cyber mission platforms, cyber weapons, cyber ranges, threat intelligence | Firewalls, EDR/XDR, IAM, SIEM | Jammers, signals intelligence, radar warning |
| Overlap | Uses cybersecurity tools for defense; converges with EW in cyber-electromagnetic activities | Supplies many defensive components | Converges with cyber in multi-domain operations |
| In this report's scope? | Yes | Only where it serves a defense or national-security mission | No (separate market) |
Source: Polaris Market Research Analysis
Market Dynamics
Driver: State-Sponsored Attacks on Critical Infrastructure
State sponsored cyber attacks targeting telecommunications, energy, water, transport, and government networks increase demand for advanced cyber defense capabilities. In October 2026, Ransomware attacks hit all-time high with 2,627 reported incidents in Q3 2026, up 61% YoY, putting pressure on government, healthcare, finance and critical infrastructure entities These nation state cyber attacks can help in intelligence gathering, unauthorized network access, service disruption, and strategic preparation during geopolitical tensions. These activities also emphasize the significance of cyber-espionage, as adversaries may want to get their hands on sensitive government information, military plans, and access to critical systems. Governments therefore allocate funds to threat intelligence, network monitoring, identity security and incident response to identify intrusions and defend critical infrastructure. These requirements create demand for cyber warfare solutions and services that enhance national security, secure sensitive networks and strengthen operational resilience (Source: Infosecurity Magazine).
Driver: Rising Defense Cyber Budgets
Increased investment in defense creates demand for cybersecurity solutions for military systems, specialist services, and for trained cyber personnel. Defense agencies need safe communication, threat intelligence, mission planning, network protection and operational technology security to protect military systems and sensitive information. Investment in cyber command capabilities also provides governments the ability to coordinate defensive cyber operations and prepare offensive cyber operations where authorized by national policy. PwC Reports 84% of Senior Leaders Expect Cybersecurity Budgets to Increase Over the Next 12 Months, with 58% Prioritizing AI-Related Cybersecurity Investment, in October 2026. These requirements provide opportunities for suppliers of cyber mission platforms, cyber ranges, security monitoring systems, and mission-specific services. However, government cyber security budgets can include general IT security and other activities outside the cyber warfare market (Source: PwC).
Restraint: Classification Barriers and Cyber Workforce Shortages
Classified procurement procedures diminish transparency of the cyber warfare market. Governments may restrict access to contract values, technical specifications, supplier information, and operational requirements to protect sensitive military capabilities. These restrictions make it more difficult to size the market and to benchmark against competitors. A further constraint is the shortage of personnel, because defensive cyber operations require personnel trained in threat intelligence, malware analysis, digital forensics, network defense and mission planning. The requirement for security clearances may constrain the pool of available candidates and competition from commercial technology companies may raise recruitment and retention costs. These challenges can increase service cost, delay system deployment, and limit operational capacity. Hence, government procurement requires suppliers to have the technical teams, delivery mechanisms and training capabilities in place.
Opportunity: AI-Enabled and Multi-Domain Cyber Operations
The growing use of AI in cyber warfare provides opportunities for vendors of threat intelligence, security analytics, simulation and decision-support systems. AI security operations are used to evaluate vast amounts of network data, detect anomalous activity, prioritize alerts, and assist analysts in investigating potential threats. October 2025 Vectra AI Acquires Netography to Augment Its AI-Driven Cybersecurity Platform and Enhance Cloud-Native Network Monitoring, Threat Detection and Cyber Defense. These features can enhance response speed and diminish manual workloads, supported by dependable data and human supervision. Cyber ranges are also in demand, these allow military personnel to train for incident response and test the durability of networks in simulated situations. Additional demand for multi-domain platforms can be driven by integrating cyber operations, communications, intelligence, space cyber security systems and electronic warfar (Source: Vectra AI).
Challenge: Attribution and Gaps in International Cyber Norms
Attributing cyber operations to specific states or state-linked groups has been difficult. Attackers can also use compromised infrastructure, shared software tools, and third parties to mask their identity, or impersonate other threat actors. Technical evidence might indicate means of attack, but not state direction or authorization. These limitations also hinder the coordination of national responses, intelligence sharing and cooperation transnationally. Differences in international legal interpretations also create uncertainty about state responsibility and rules governing cyber operations. Such uncertainty can impact procurement priorities, operational planning, and cooperation among allied governments. Security, compliance and data handling requirements are strict for suppliers, which can slow procurement and hamper international growth. These considerations complicate the implementation of cyber warfare capabilities across different jurisdictions.
AI in Cyber Warfare: How AI Is Changing Cyber Operations
Artificial intelligence is growing in importance for cyber warfare. An AI cyberattack can use AI capabilities to support activities such as threat analysis, intelligence gathering, and automated attack planning. The military and government organizations have a lot of network logs, alerts, intelligence reports, system telemetry, and threat indicators. AI in cybersecurity can help analysts to structure this information, find patterns and rate possible incidents. Their value depends on data quality, integration with existing systems and the ability of trained personnel to check findings.
During defensive operations, standard artificial intelligence can assist security operations centers by correlating related alerts, identifying anomalous activity, and assisting analysts in investigating suspicious behavior. These functions can help reduce the repetition of work and improve the consistency of dealing with incidents. AI does not eliminate the need for human decision-making, especially in a situation where an action might impact military systems, critical infrastructure, or sensitive information. It is important to secure model access, audit trails, escalation rules and safeguards against manipulated inputs.
AI cyber warfare will influence offensive cyber operations. Threat actors may use AI-assisted tools to speed up reconnaissance, translate technical material, customize social engineering messages, or process stolen information. The use of these tools does not, in and of itself, make an operation a state-directed cyber warfare campaign. Analysts have to untangle confirmed state-linked activity from criminal operations, broad cybercrime and speculative claims about the use of AI. In 2025, Google Threat Intelligence revealed a case named GTG-1002 as an AI-led espionage operation. Its inclusion underscores the increasing importance of AI for cyber operations, but any detailed technical description should be left to the primary source.
Training and simulation represent another opportunity. Cyber ranges allow military personnel to rehearse incident response, practice defensive cyber operations, and evaluate team coordination in simulated environments. NATO’s Locked Shields exercise provides a prominent example of large-scale cyber defense training. AI-assisted scenarios may support dynamic exercise conditions and help instructors evaluate responses, although the extent of AI use in a specific exercise must be confirmed before making a direct claim.
AI in cyber operations: use cases and named examples
| Use case | How AI is applied | Named example | Side |
| AI-enabled security operations centre | Automated triage, correlation and response across military networks | U.S. Air Force: USD 40 mn IDIQ to World Wide Technology for an AI-Enterprise Enabled SOC (May 2026) | Defensive |
| Cyber analytics for defensive cyber operations | AI/ML threat detection and cyber situational awareness | U.S. Army Defensive Cyber Operations Cyber Analytics Platform, ~USD 476 mn ceiling (Feb 2026; verify against Army award notice) | Defensive |
| AI-orchestrated intrusion | Agentic AI runs reconnaissance, exploitation and exfiltration with minimal human input | GTG-1002 espionage campaign disclosed Nov 2025 | Offensive (adversary) |
| AI-assisted phishing and reconnaissance | Generative AI used for lures, target research and malware support | State-backed actors misusing commercial AI models, as reported by Google threat intelligence | Offensive (adversary) |
| Cyber ranges and simulation | AI-generated adversaries and scenarios for operator training and mission rehearsal | NATO Locked Shields 2026 (~4,000 participants); U.S. Persistent Cyber Training Environment | Training |
| Budget signal | Dedicated AI/ML funding inside cyber budgets | ~USD 1.8 bn a year within DoD cyber budget | Both |
Source: Polaris Market Research Analysis
The market opportunity is not limited to standalone AI products. Established cyber defense providers, defense contractors, cloud security suppliers, and specialist analytics firms may integrate AI into existing platforms. Procurement will depend on system accreditation, secure deployment options, compatibility with classified networks, and evidence of operational performance. Vendors must also manage model vulnerabilities, data leakage, false positives, and adversarial manipulation. AI is therefore best assessed as a capability layer across the cyber warfare value chain rather than a separate market that can be added to cyber warfare revenue without adjustments.
Cyber Warfare Examples: Major Incidents Timeline, 2025–2026
Publicly documented cyber incidents provide context for government investment in threat intelligence, infrastructure protection, and operational resilience. However, an incident should not automatically be classified as cyber warfare. State attribution, operational intent, and the target environment vary by case. Some incidents are criminal attacks, and others involve suspected state-sponsored espionage or pre-positioning activity.
| Date | Incident | Attributed to | Target / impact | Source to cite |
| May 2025 | Allied advisory on GRU campaign | Russia (GRU) | Logistics and tech firms supporting Ukraine and NATO | Joint U.S./UK/EU advisory |
| Jul 2025 | Interlock ransomware attack | Interlock group | St. Paul, MN city services; state of emergency and National Guard deployed | City of St. Paul; Minnesota Governor's office |
| Sep-Nov 2025 | First documented AI-orchestrated espionage campaign (GTG-1002) | China (state-sponsored) | ~30 organizations; AI performed most of the intrusion work | Anthropic threat report (13 Nov 2025) |
| 2025 (full year) | 273,000+ cyber incidents in Poland, up 144% on 2024 | Russia and Belarus (per Polish government) | Water, gas and electricity systems | Polish Ministry of Digital Affairs, May 2026 |
| Mar 2026 | Heightened warnings of AI-enabled Iranian cyber retaliation | Iran (IRGC-linked actors) | Energy and infrastructure in the U.S., Israel and Gulf states (risk, not a confirmed attack) | Fortune, 2 Mar 2026 |
Source: Polaris Market Research Analysis
These cases illustrate the breadth of cyber threats facing government and critical infrastructure organizations. Persistent access to networks may require different defenses from ransomware, espionage, or destructive activity. Procurement priorities can therefore include endpoint and network detection, threat intelligence, incident response, identity protection, secure communications, and cyber range training. The effect on market revenue cannot be inferred from incident counts alone. A defensible market estimate requires evidence of contracts, budgets, supplier revenue, and the portion attributable to the defined cyber warfare market.
Defense Budget Allocations for Cyber Warfare
Defense budgets provide an indicator of government priorities in cyber operations, but budget categories are not directly interchangeable. Some documents report cyber mission spending, others include broader information technology, intelligence, research, and network modernization. A market assessment must identify the relevant program lines and avoid counting the same spending under several agencies or procurement categories.
The US Department of Defense budget figures identified in the refresh brief show cyberspace activities requests rising from USD 13.5 billion in FY2024 to USD 15.1 billion in FY2026. These values should be described as requests unless final appropriations and expenditure records confirm actual spending. They also cover a broader set of cyberspace activities than commercial cyber warfare market revenue. Only the portion linked to the defined solutions and services should inform market sizing.
Poland is another relevant example. The refresh brief identifies plans for more than PLN 5 billion in cybersecurity spending in 2026 and a broader set of investments in digital resilience. These programs demonstrate the importance of national security, infrastructure protection, and civil-military coordination in influencing demand. Exact amounts, funding periods and program categories covered should be checked against Polish government publications before the final RD is published.
NATO allies also signed up to a broader target of 5% of GDP for defense and security spending by 2035, with up to 1.5% for wider security related areas under the agreed framework. This target should not be seen as a cyber warfare budget. Defense modernization, resilience, communications, intelligence and critical infrastructure programs could fund cyber capabilities, but the exact amount is country-specific.
| Country / bloc | Allocation | Period | What it funds | Source to cite |
| United States (DoD) | USD 13.5 bn > 14.5 bn > 15.1 bn (budget requests) | FY2024 > FY2025 > FY2026 | Cyberspace activities; ~USD 1.8 bn a year earmarked for AI/ML | DoD Comptroller cyberspace activities budget exhibits |
| Poland | > PLN 4 bn (2025) > PLN 5 bn, ~EUR 1.2 bn (2026) | 2025-2026 | Integrated Cybersecurity Operations Centre, "Cyber Legion" volunteer force, critical infrastructure protection | Polish Ministry of Digital Affairs, May 2026 |
| Poland (programme) | ~PLN 10 bn for cybersecurity and digital resilience | 2025-2026 combined | Includes PLN 1.5 bn for local-government cyber resilience | Polish Ministry of Digital Affairs, Oct 2024 |
| NATO allies | 5% of GDP target, of which up to 1.5% for resilience incl. network and critical-infrastructure protection | By 2035 | Cyber defense eligible within the 1.5% resilience envelope | NATO Hague Summit Declaration, Jun 2025 |
Source: Polaris Market Research Analysis
National cyber spending supports the market through procurement of secure infrastructure, cyber mission force, threat intelligence, specialist training, cyber ranges, and operational services. However, annual budgets do not necessarily translate into annual supplier revenue. Timing of the contract, multiyear procurement, internal government staffing and classified programs are factors that may impact the relationship. Hence, market forecasting should triangulate budget trends with contract awards, vendor disclosures and primary interviews.
Cyber Warfare Market Segmentation Analysis
The cyber warfare market is segmented by component, type, and application. These categories distinguish the products and services purchased, the operational purpose of the capabilities, and the organizations using them. The precise revenue allocation depends on Polaris’s approved dataset and the definitions used to classify contracts and supplier sales.
Component Analysis
The solutions segment accounted for 67.18% of the cyber warfare market share in 2025. Cyber warfare solutions include threat intelligence platforms, network defense systems, cyber mission platforms, security analytics, and simulation technologies. These solutions help defense agencies and government organizations identify threats, protect sensitive networks, and coordinate cyber operations. Increased dependence on networked military systems and digital infrastructures increases the need for specialized security tools. Organizations also need technologies that can work with existing defense networks and classified environments. The demand for scalable platforms, real-time threat detection and secure mission systems are driving the adoption of cyber warfare solutions across national security and defense applications.
Services segment is anticipated to register a CAGR of 16.28% during the 2026–2034 forecast period. The cyber warfare services include cyber operations support, threat intelligence analysis, incident response, consulting, training and managed security services. These services help governments tackle specialist skill shortages and enhance the operational readiness of cyber teams. Complex military networks also require constant monitoring, system assessment, and technical support. Demand is a function of the availability of qualified personnel, security clearance requirements, procurement budgets, and the complexity of government infrastructure. As defense organizations bolster their cyber capabilities, specialist service providers have the potential to leverage opportunities to support training, mission preparation, and network protection.
Type Analysis
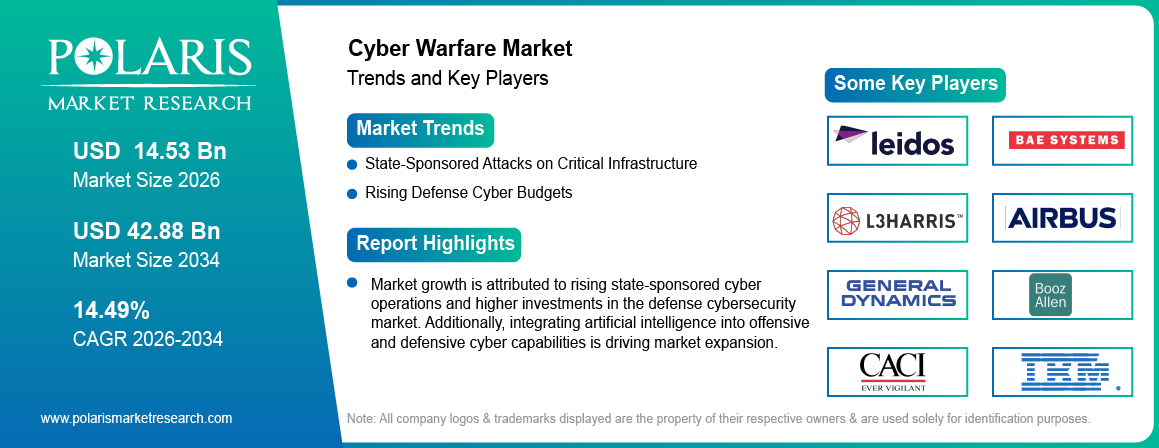
The cyberattack segment captured 48.36% share of the cyber warfare market in 2025. Cyberattacks are attempts to gain unauthorized access to systems, disrupt digital services, or compromise sensitive information. In a cyber warfare context, such activities may be directed at military networks, government systems, communications infrastructure, and other strategically significant assets. Organizations’ exposure to risks from disruption, data theft and unauthorized access increases demand for detection and response capabilities. Defense agencies are investing in network monitoring, threat intelligence, incident response, and defensive cyber operations to decrease exposure. But not all cyberattacks are cyber war; criminal acts and other events can occur without state sponsorship or military purpose.
The cyber sabotage segment is expected to grow at a CAGR of 15.83% during the forecast period 2026–2034. Cyber sabotage is the deliberate disruption, damage, or degradation of digital systems and connected infrastructure. Potential targets include military command and control networks, energy systems, transportation infrastructure, and industrial control environments of national security importance. Such risks increase the need for system monitoring, control of access, operation technology protection and recovery planning. Defense and government organizations need capabilities to help identify malicious activity, limit its impact and restore essential services. Market demand will be driven by the priorities of national security, infrastructure exposure, technical requirements, and investment in cyber resilience.
Comparison Matrix by Type
| Attribute | Cyberattacks (disruptive) | Espionage | Sabotage |
| Objective | Deny or degrade systems and services | Steal intelligence, IP or credentials | Cause physical or lasting functional damage |
| Typical actors | State units, state-aligned hacktivists, ransomware proxies | Intelligence services and APT groups | Military cyber units and pre-positioned APTs |
| Operation posture | Offensive cyber operations (OCO) | Intelligence collection, often persistent | OCO, usually timed to a crisis |
| Defensive response | DDoS mitigation, incident response, resilience planning | Threat hunting, zero trust, data protection | OT/ICS security, segmentation, hunt-forward teams |
Source: Polaris Market Research Analysis
Application Analysis
The defense segment accounted for 31.26% of the cyber warfare market share in 2025. Military communications, intelligence systems, command infrastructure, logistics networks and connected equipment need to be protected with cyber capabilities by defense organizations. The military's reliance on digital technology across all domains makes it vulnerable to hacking, data breaches and attacks that could knock out critical systems. These risks are driving investment in defensive cyber operations, offensive cyber operations, threat intelligence, and secure mission platforms. Defense cybersecurity agencies also require trained personnel and simulation environments to prepare themselves for complex cyber assaults. Military modernization programs, national security priorities and availability of budgets drive procurement demand. These requirements make defense a core application area for cyber warfare solutions and services.
The government segment is anticipated to grow at a CAGR of 14.92% during the period 2026-2034. Government agencies house sensitive information, offer public services, maintain national records and operate communications networks that are susceptible to cyber operations. The proliferation of digital government systems has brought about an increased need for secure infrastructure, threat detection, incident response, and coordinated cyber defense. National cyber command structures and interagency cooperation also shape procurement priorities. Government agencies may need specialized consulting, cyber intelligence, and training to improve operational readiness. Demand is driven by public sector funding, national strategies for cybersecurity, government procurement processes and the sensitivity of the government systems.
Cyber Warfare Market Regional Insights
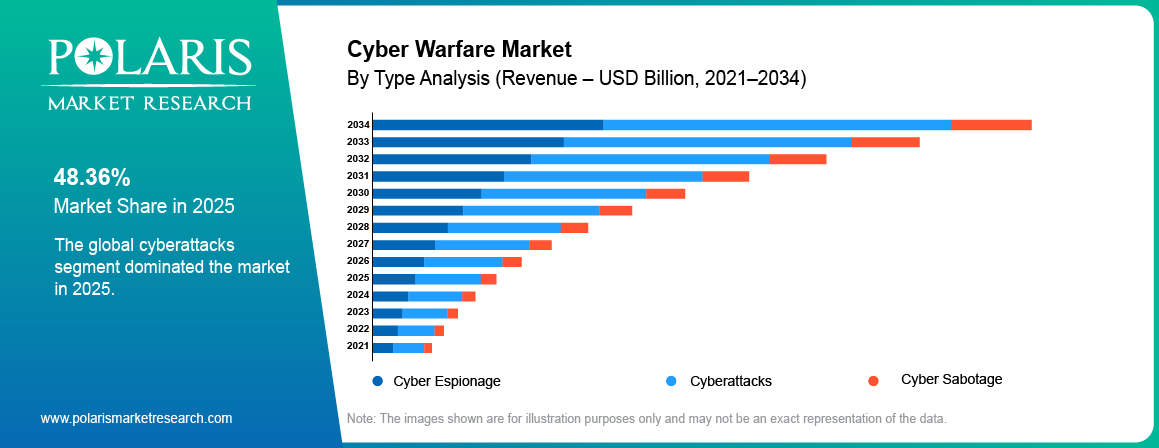
Regional performance reflects defense procurement, national cyber strategies, the scale of military digital infrastructure, and the maturity of domestic cyber capabilities. Comparisons must use the same market definition across all five regions. The refresh blueprint identifies North America as the leading region and Asia Pacific as a potential growth leader, but both positions require confirmation against the revised forecast.
North America Cyber Warfare Market Trends
In 2025, North America was the largest contributor to the cyber warfare market, accounting for 39.62% of the total revenue. Demand in the region is driven by defense modernization, entrenched cyber command capabilities and investment in protecting military networks. The U.S. market is reaping the rewards of demand for threat intelligence, defensive cyber operations, offensive cyber operations and specialized cyber mission platforms. Shield AI and US Government Announce USD 400 Million Investment in Autonomous Military Aviation and Defense Modernization with X-BAT AI-Piloted Aircraft Program October 2026 Government agencies and defense contractors require the ability to communicate securely, monitor their networks, and respond to incidents to protect sensitive systems. The established defense technology ecosystem in the region also provides opportunities for companies that provide solutions, services, and training for cyber warfar (Source: PR Newswire).
Asia Pacific Cyber Warfare Market Trends
The Asia Pacific region captured 22.86% of the cyber warfare market share in 2025 and is estimated to witness the fastest CAGR of 17.26% in the forecast period of 2026-2034. Military modernization, expansion of digital infrastructure, and increased investment in national cyber defense capabilities are driving growth in China, India, Japan, South Korea, and Australia. Southeast Asian Nations boost defense spending in Jan 2026; Philippines to spend $35 billion on modernization, Indonesian military spending rises. Governments are building up their cyber command structures, investing in threat intelligence, network defense and defensive cyber operations to protect sensitive systems. The increased geopolitical tensions also increase the importance of detecting cyber espionage and protecting critical infrastructure. The pace of market expansion will be determined by national defense budgets, procurement priorities, technical expertise, and the development of specialized cyber operations capabilities (Source: The Diplomat).
Europe Cyber Warfare Market Trends
Europe had a market share of 26.14% in 2025. Regional demand fueled by defense cooperation, military modernization, protection of critical infrastructure and growing concern over cyber risks associated with hybrid warfare. In January 2026, the EU and India Sign a Security and Defense Partnership to Boost Cooperation in Cyber Defense, AI, Hybrid Threats and Space Security. Secure military communications, threat intelligence, cyber ranges and incident response capabilities are required by governments and defense organizations to secure sensitive networks. By working together, European countries and NATO members can increase demand for interoperable systems and for coordinated defensive cyber operations. Investment priorities are the protection of government infrastructure, aerospace systems and strategically important digital resources (Source: EEAS).
Latin America Cyber Warfare Market Trends
Latin America cyber warfare market made up 5.17% of global market revenue in 2025. Demand is driven by factors such as government digitalization, protection of critical infrastructure, and the need to secure public-sector and defense networks. Countries such as Brazil and Mexico represent important markets for cybersecurity investment because of the size of their digital economies and public infrastructure. To enhance cyber resilience, agencies may require threat intelligence, incident response, secure communication, and specialist training. But adoption rates may be affected by things like different defense budgets, technical know-how and procurement abilities. Market expansion will be driven by investment in military cybersecurity, the development of specialized cyber teams, and national security priorities.
Middle East & Africa Cyber Warfare Market Trends
The Middle East & Africa region held 6.21% of the cyber warfare market share in 2025. Regional demand is supported by national security priorities, expansion of digital infrastructure, and the need to protect energy, government, telecommunications, and defense systems. Governments need threat intelligence, network defense, incident response, and secure communication to reduce exposure to cyber operations against strategically important assets. Further support for demand for cyber warfare solutions and services can be achieved through investment in cyber command capabilities and specialist personnel. However, market adoption depends on government budgets, technical readiness, procurement structures and access to qualified professionals. Future growth will depend on the investment levels in dedicated cyber operations and critical infrastructure protection.
Competitive Landscape
The cyber warfare market includes defense contractors, specialist cyber operations providers, intelligence and analytics companies, and technology suppliers serving military and government customers. Competitive positioning depends on secure delivery capabilities, experience with classified programs, interoperability, technical depth, compliance, and long-term support. Suppliers may participate as prime contractors, subcontractors, platform providers, or service specialists.
The market is not limited to companies selling products labelled specifically as “cyber warfare.” Some providers supply cyber mission systems, threat intelligence, secure communications, cyber ranges, or operational support within larger defense contracts. Inclusion in the table below indicates relevant capabilities or market adjacency, not a verified market share ranking. Each company’s direct exposure to the defined market should be confirmed before publication.
List of Top Cyber Warfare Companies
- Airbus SE
- BAE Systems plc
- Booz Allen Hamilton Holding Corporation
- CACI International Inc
- General Dynamics Corporation
- International Business Machines Corporation (IBM)
- L3Harris Technologies, Inc.
- Leidos Holdings, Inc.
- Leonardo S.p.A.
- Lockheed Martin Corporation
- Microsoft Corporation
- Northrop Grumman Corporation
- RTX Corporation
- Science Applications International Corporation (SAIC)
- Thales S.A. (Thales Group)
Vendor Positioning
| # | Company | HQ | Core cyber warfare capability | Posture | Positioning |
| 1 | Airbus SE | Netherlands (ops in France) | Defence and space cybersecurity, secure communications, sovereign European cyber defence | DCO | Strong |
| 2 | BAE Systems plc | UK | Digital intelligence, cyber defence for governments | DCO, intel | Strong |
| 3 | Booz Allen Hamilton Holding Corporation | U.S. | Cyber operations and mission support for DoD and the intelligence community | OCO, DCO, training | Leader |
| 4 | CACI International Inc | U.S. | Signals intelligence, cyber and electronic warfare support for DoD and the intelligence community | OCO, DCO | Strong |
| 5 | General Dynamics Corporation (GDIT) | U.S. | Network operations, secure communications, defence IT | DCO | Leader |
| 6 | International Business Machines Corporation | U.S. | Security operations centres and incident response | DCO | Specialist |
| 7 | L3Harris Technologies, Inc. | U.S. | Tactical communications security, EW-cyber convergence | DCO | Strong |
| 8 | Leidos Holdings, Inc. | U.S. | Cyber operations support, cyber ranges and defensive cyber for DoD and federal agencies | DCO, OCO support | Strong |
| 9 | Leonardo S.p.A. | Italy | National cyber defence programmes, critical-infrastructure security | DCO | Strong |
| 10 | Lockheed Martin Corporation | U.S. | Platform cyber resilience and mission assurance (e.g., F-35 cyber worthiness) | DCO | Strong |
| 11 | Microsoft Corporation | U.S. | Cloud security, threat intelligence, defence cloud environments | DCO | Leader (cloud) |
| 12 | Northrop Grumman Corporation | U.S. | Air Force Cyber Mission Platform; Unified Platform cyber enterprise services | OCO, DCO | Leader |
| 13 | RTX Corporation | U.S. | Multi-domain threat assessment and mission cyber | DCO | Strong |
| 14 | Science Applications International Corporation | U.S. | Cyber engineering and mission IT for DoD and civil agencies | DCO | Specialist |
| 15 | Thales S.A. | France | Cyber threat intelligence platform, cyber ranges, sovereign defence | DCO, training | Strong |
Source: Polaris Market Research Analysis
Recent Developments
- October 2026, Poland announced an approximately USD 26 billion investment in civil defense and population protection for 2027–2031 to strengthen national preparedness, emergency response, and infrastructure resilience. (Source: Euronext)
- August 2026, Leidos secured a USD 301 million contract to strengthen cyber defenses across US department of war networks through 24/7 cyber operations and enhanced cyber resilience. (Source: Leidos)
- April 2026, NATO CCDCOE concluded locked shields 2026 with over 4,000 participants from 41 countries testing cyber defense capabilities across critical infrastructure and military systems. (Source: NATO CCDCOE)
- February 2026, the U.S. army awarded Enlighten IT Consulting a USD 476.26 million contract for cyber analytics platform maintenance, development, and AI/ML integration to strengthen defensive cyber operations. (Source: Govly)
- November 2025, Google threat intelligence group reports that state-sponsored actors and cybercriminals are experimenting with AI to enhance reconnaissance, phishing, malware development, and other cyber operations. (Source: Google)
- November 2025, U.S. and international agencies issued an advisory on salt typhoon activity targeting telecommunications and related networks. (Source: CISA)
Future Outlook
The cyber warfare market is expected to evolve as governments strengthen national security and expand military cyber capabilities. Rising state-sponsored cyber attacks, cyber espionage, and threats to critical infrastructure are increasing the need for advanced threat intelligence and network defense. Investment in cyber command structures, defensive cyber operations and offensive cyber operations is also driving demand for specialized platforms and services. Artificial intelligence can be used in cyber warfare to improve threat detection, data analysis and operational decision-making, but only if human supervision and security controls are in place. Cyber ranges can improve training and readiness through the simulation of complex attack scenarios. Defense budgets, technical capabilities, workforce availability and procurement priorities across regions will drive the growth of the market.
Research Methodology
For evaluation of market trends, technologies, applications, fluids, architectures and regional opportunities, the report on cyber warfare market is based on secondary research, estimation of market size, primary validation, forecasting and data triangulation.
Secondary Research & Data Collection
The research will incorporate analysis of government documents, defense budgets, cybersecurity policies, company reports, procurement data, and reports from leading cybersecurity organizations to evaluate cyber command capabilities, threat intelligence, and critical infrastructure protection.
Market Estimation & Modelling
The market is segmented by Type, Component, Application and Region. Forecasts consider defense spending, investment in cyber command, national security priorities, and demand for specialized cyber capabilities, which is not unrelated to cybersecurity spending.
Primary Validation
Industry input from defense technology providers, cybersecurity vendors, specialist service firms and subject matter experts validates procurement priorities, technology adoption, workforce constraints and market assumptions.
Data Triangulation & Final Review
Market estimates, CAGR, segmentation, and regional positions are cross-validated with government spending data, procurement records, company disclosures and regional indicators. Budget requests are not the same as actual spending, and unsupported numbers are not included.
Cyber Warfare Market Report Segmentation
By Component Outlook (Revenue, USD Billion, 2021–2034)
- Solutions
- Services
By Type Outlook (Revenue, USD Billion, 2021–2034)
- Cyberattacks
- Cyber Espionage
- Cyber Sabotage
By Application Outlook (Revenue, USD Billion, 2021–2034)
- Defense
- Government
- Aerospace
- Homeland Security
- Corporate
By Regional Outlook (Revenue, USD Billion, 2021-2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Cyber Warfare Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 12.70 Billion |
| Market Size in 2026 | USD 14.53 Billion |
| Revenue Forecast by 2034 | USD 42.88 Billion |
| CAGR | 14.49% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Cyber Warfare Market FAQ's
The global cyber warfare market was valued at USD 12.70 billion in 2025 and is projected to reach USD 42.88 billion by 2034, at a CAGR of 14.49% during 2026–2034.
Cyber warfare is the use of digital technology to attack enemy systems, collect confidential data, or achieve military and national security goals.
Cyber warfare is the use of cyber activities for military or national security purposes. Cybersecurity is the protection of systems and data.
AI can help detect threats, analyze intelligence, prioritize incidents, and simulate cyber ranges, but only with security controls and human supervision.
The U.S. is the biggest investor in military cyber power across the world.
Cyber warfare example are state-linked cyber espionage, disruptive cyberattacks, and sabotage targeting military networks or critical infrastructure.
North America was the leading region in 2025, accounting for 39.62% of revenue
A few key companies are Airbus SE; BAE Systems plc; Booz Allen Hamilton Holding Corporation; CACI International Inc.; General Dynamics Corporation; International Business Machines Corporation (IBM); L3Harris Technologies, Inc.; Leidos Holdings, Inc.; Leonardo S.p.A.; Lockheed Martin Corporation; Microsoft Corporation; Northrop Grumman Corporation; RTX Corporation; Science Applications International Corporation (SAIC); and Thales S.A. (Thales Group).
The solutions segment, based on component, led the market share in 2025, driven by the rising demand for threat intelligence, cyber mission platforms, network defense systems, and cyber operations technologies.
A few main types of cyber warfare are cyber espionage, cyberattacks, and cyber sabotage, targeting sensitive information, digital systems, and critical infrastructure.

Download Sample Report of Cyber Warfare Market
Please fill out the form to request a customized copy of the research report.


