Diabetic Ketoacidosis Treatment Market Size, Share, Trends & Forecast, 2026-2034
REPORT DETAILS
Diabetic Ketoacidosis Treatment Market Summary
The global diabetic ketoacidosis treatment market size was valued at USD 899.36 million in 2025, growing at a CAGR of 4.10% from 2026–2034. Rising prevalence of type 1 diabetes worldwide and the integration of digital health platforms in acute care settings are collectively driving demand for timely diagnosis, continuous monitoring, and standardized treatment of diabetic ketoacidosis.
Market Statistics
Key Takeaways
- North America held the major share of the global diabetic ketoacidosis treatment market with 42.7% in 2025, due to the advanced healthcare infrastructure and high prevalence of diabetes.
- The U.S. market is expected to grow at a CAGR of 8.9% during 2026–2034. This is driven by advanced diabetes management technologies.
- Asia Pacific accounted for 27.4% of the global market in 2025. This is attributed to rising type 1 diabetes cases and better access to DKA treatment.
- The China market is expected to grow at a CAGR of 10.6% during 2026–2034. Supported by the increasing emergency care infrastructure and point-of-care testing.
- The insulin therapy segment held the largest market share of 51.8% in 2025. This is because of its role as the standard DKA treatment.
- The electrolyte replacement segment is expected to grow at the fastest CAGR of 10.2% during 2026–2034. This is encouraged by a growing emphasis on correction of electrolyte imbalances.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Is Diabetic Ketoacidosis Treatment?
The medical management of a serious diabetes complication caused by high blood glucose, ketone buildup, and metabolic imbalance it is referred to as Diabetic Ketoacidosis (DKA) treatment. It includes insulin therapy, fluid replacement, electrolyte correction, glucose monitoring, and supportive care to restore normal metabolism and prevent complications.
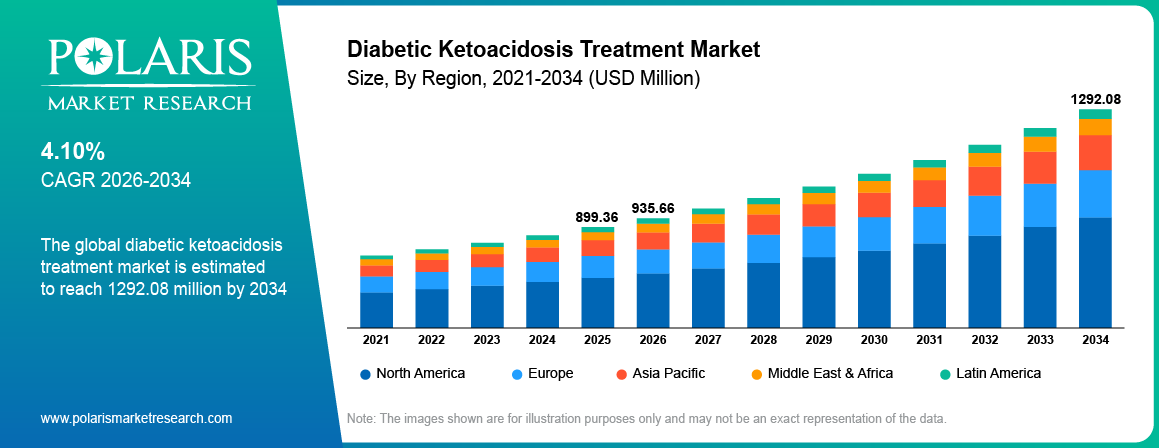
Source: Polaris Market Research Analysis
How Is Diabetic Ketoacidosis Treated? Fluids, Insulin, Potassium Monitoring & Transition to Subcutaneous Therapy
Diabetic ketoacidosis (DKA) treatment begins once symptoms such as thirst, frequent urination, nausea, or confusion are present. Healthcare providers will check the blood glucose and ketone levels to make the diagnosis. Once diagnosed, intravenous (IV) fluids are given to treat dehydration, and insulin therapy is given to lower blood glucose and stop the production of ketones. Electrolyte levels, especially potassium, are monitored and corrected during the treatment. As glucose, ketone, and electrolyte levels return to normal, the body’s metabolic balance is restored. Patients will be monitored until they recover and are stable.
Diabetic ketoacidosis (DKA) treatment involves fluid resuscitation, insulin therapy, and electrolyte replacement to stabilize blood glucose and reverse metabolic acidosis. Hospitals and emergency departments are the primary users of DKA treatment protocols due to the condition’s acute onset and life-threatening nature. Intravenous insulin infusions and rapid fluid administration are widely adopted to restore metabolic balance in patients presenting with severe hyperglycemia and ketonemia. The demand for point-of-care ketone testing and continuous glucose monitoring is rising in intensive care and emergency settings to enable faster diagnosis and reduce treatment delays. For instance, in April 2025, Medtronic announced the expansion of its real-time CGM systems across acute care settings in the US to support better glycemic control in DKA management.
DKA Treatment vs Routine Diabetes Management: Emergency Stabilization vs Long-Term Glycemic Control
| Parameter | DKA Treatment | Routine Diabetes Management |
| Purpose | Treats a medical emergency | Controls diabetes over the long term |
| Insulin | IV insulin is given | Daily insulin or diabetes medicines are used |
| Fluids | IV fluids are required | IV fluids are usually not needed |
| Care Setting | Hospital treatment | Home care with regular check-ups |
| Main Goal | Stabilize the patient quickly | Keep blood sugar under control |
Source: Polaris Market Research Analysis
AI in DKA Care: Risk Detection, Triage Support, Glucose/Ketone Trends & Clinical Decision Support
- AI helps detect diabetic ketoacidosis earlier by analyzing glucose and ketone data in real time.
- AI supports accurate insulin dosing, helping clinicians make better treatment decisions.
- AI improves patient monitoring through continuous tracking of glucose levels.
- AI helps hospitals respond faster by supporting clinical decisions during emergency care.
Market Dynamics
Driver: Rising Prevalence of Type 1 Diabetes Worldwide
The rising prevalence of type 1 diabetes globally is contributing to increasing incidence of diabetic ketoacidosis, particularly among children and young adults. As per the International Diabetes Federation, more than 1.8 million individuals under the age of 20 are currently living with type 1 diabetes worldwide. The growing insulin dependency combined with delays in diagnosis, therapy initiation, or treatment adherence is contributing to rising emergency admissions for diabetic ketoacidosis. This trend is accelerating the demand for acute care resources, including intravenous insulin, fluid replacement, and electrolyte correction. Health systems are expanding capacity to manage acute diabetic crises, while manufacturers are scaling production of insulin analogs and emergency-use treatment kits. The increasing disease burden is boosting public health agencies to strengthen early screening and prevention efforts. In May 2025, Sequel Med Tech announced to integrate its Twiist automated insulin delivery (AID) system with Abbott’s upcoming dual glucose-ketone sensor to create a closed-loop diabetes management solution. This integration is expected to enhance early detection and intervention for diabetic ketoacidosis (DKA) by enabling real-time monitoring of glucose and ketone levels, thereby reducing the risk of severe DKA episodes.
Opportunity: Integration of Digital Health Platforms in Acute Care Settings
The integration of digital health platforms into acute care settings is transforming diabetic ketoacidosis management by improving diagnostic speed, treatment accuracy, and real-time monitoring. The increasing adoption of continuous glucose monitoring systems, smart insulin pumps and hospital-based analytics are enabling faster clinical decisions and reducing delays in intervention. These technologies support data-driven care by alerting providers to critical changes in patient condition and guiding precise insulin dosing. Moreover, the integration with electronic health records enhances treatment continuity during emergency admissions. The growing adoption of connected care systems in hospitals is driving demand for interoperable devices and algorithm-based treatment tools to standardize DKA management across intensive care and emergency departments.
Challenges: High Cost Burden of Acute Care Infrastructure
The diabetic ketoacidosis (DKA) treatment market continues to face several challenges. The high cost of advanced diabetes technologies is a barrier to their implementation, especially in the cost-sensitive healthcare systems. Limited access to emergency care in developing areas can result in delayed diagnosis and treatment. Furthermore, low awareness of early DKA symptoms can raise the risk of severe complications. Particularly, in resource-limited settings the need for trained healthcare professionals to manage DKA also continues to be a major challenge.
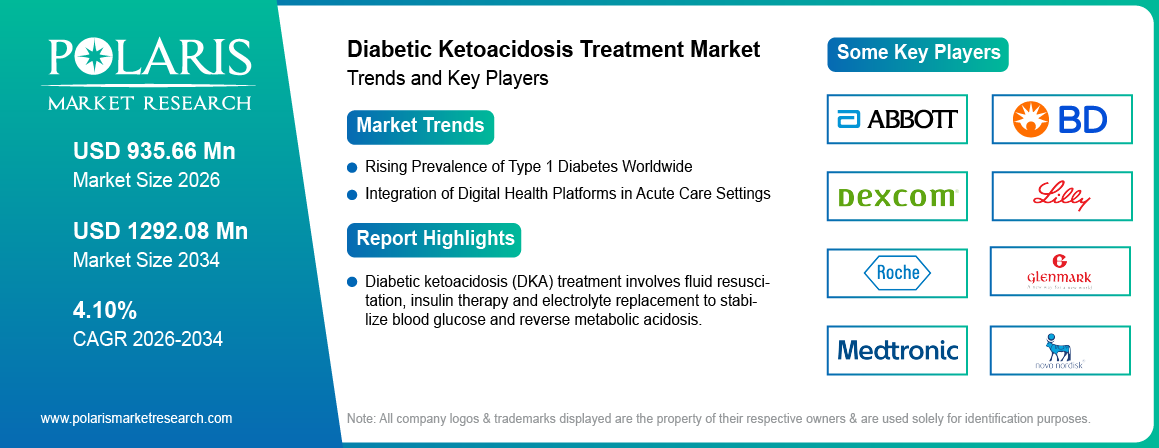
Source: Polaris Market Research Analysis
Diabetic Ketoacidosis Treatment Market Segmentation Analysis
Treatment Type Analysis
Based on treatment type, the segmentation includes insulin therapy, fluid replacement, and electrolyte replacement. The insulin therapy segment held the largest market share of 51.8% in 2025, due to its central role in stabilizing hyperglycemia and reversing ketogenesis. Insulin is the first-line intervention in DKA treatment protocols and administered intravenously to rapidly normalize blood glucose levels. For instance, in June 2024, the Insulet launched SECURE-T2D pivotal trial showed that the Omnipod 5 automated insulin delivery system significantly improved glycemic control and quality of life in adults with type 2 diabetes. These findings support the potential of wearable insulin technologies, including Omnipod 5, to enhance diabetic ketoacidosis (DKA) prevention by maintaining stable glucose levels in high-risk patients. Moreover, the rising hospitals' reliance on standardized insulin infusion regimens for pediatric and adult cases to support consistent clinical use. This segment benefits from the widespread availability of analog insulins along with adherence to clinical guidelines and integration into emergency care workflows. The rising advancements in ultra-rapid insulin formulations and the adoption of smart pump technologies continue to improve the segment's effectiveness in acute care settings.
The electrolyte replacement segment is expected to grow at the fastest CAGR of 10.2% during 2026–2034. This growth is attributed to the increasing clinical recognition of electrolyte imbalances such as hypokalemia and bicarbonate deficits that frequently accompany DKA episodes. Healthcare facilities are adopting tailored potassium and bicarbonate replacement strategies to mitigate complications such as cardiac arrhythmias and cerebral edema. The demand for electrolyte replacement is also driven by the use of real-time electrolyte analyzers and pre-mixed hospital-grade formulations. The rising complexity in DKA cases and institutional preference for complete metabolic correction protocols are expected to drive growth in this segment across emergency and critical care settings.
Types of DKA Treatment Approaches
| Treatment Approach | Purpose | Use |
| Insulin Infusion Therapy | Lowers blood glucose | Stops ketone production and controls blood sugar |
| IV Fluid Replacement | Restores hydration | Replaces lost fluids and improves circulation |
| Potassium & Electrolyte Correction | Maintains electrolyte balance | Replaces potassium and other electrolytes as needed |
| Glucose Monitoring | Tracks blood sugar | Helps adjust treatment during recovery |
| Bicarbonate Therapy | Corrects severe acidosis | Used only in selected severe cases |
| Supportive Emergency Care | Stabilizes the patient | Includes monitoring and treatment of underlying causes |
Source: Polaris Market Research Analysis
Application Analysis
Based on the application, the segmentation includes pediatric and adult. The adult segment accounted for largest revenue share in 2025, owing to the higher prevalence of insulin omission, non-compliance, and comorbid conditions among the adult diabetic population. Adults with poorly managed type 1 diabetes are expected to experience repeated DKA episodes, with the increasing reliance on structured hospital-based interventions. Hospitals and emergency departments prioritize adult care protocols that include glucose monitoring, electrolyte correction, and intravenous insulin therapy. The availability of advanced diagnostic infrastructure and growing awareness of adult-onset autoimmune diabetes are further contributing to the segment’s dominance.
The pediatric segment is projected to grow at the fastest pace during the forecast period, driven by rising incidence of type 1 diabetes in children and adolescents. In this age group, delayed diagnosis and early-stage misidentification of the disease frequently result in critical presentations of diabetic ketoacidosis (DKA). Pediatric care units are integrating age-appropriate insulin dosing algorithms, fluid resuscitation guidelines, and non-invasive monitoring solutions to enhance clinical management and improve patient outcomes. The rising technological advancements such as wearable glucose sensors and pediatric-focused insulin pumps are improving treatment outcomes. Additionally, increased screening initiatives, targeted educational programs and early intervention campaigns led by public health authorities are facilitating the faster adoption of DKA treatment protocols within the pediatric population.
End User Analysis
By end user, the market includes hospitals, ambulatory care centers, and specialty clinics. The hospitals segment held the largest revenue share in 2025, due to their ability to provide full-spectrum acute care services for severe DKA cases. Hospitals are equipped with the infrastructure necessary for continuous patient monitoring, intravenous therapies and laboratory diagnostics. Emergency departments and intensive care units (ICUs) frequently manage diabetic ketoacidosis (DKA) cases that require intensive insulin therapy and fluid administration. The strong reimbursement support, integration of electronic health records and institutional compliance with diabetes management guidelines are contributing to hospital dominance in this market.
The ambulatory care centers segment is anticipated to grow at the fastest rate. The shift toward outpatient-based care models and decentralized emergency response is increasing the relevance of ambulatory centers in managing mild-to-moderate DKA cases. These centers are equipped with point-of-care glucose and ketone testing along with ready-to-administer insulin and electrolyte kits. The features including cost efficiency, faster triage and lower hospitalization rates are making ambulatory care centers an attractive option for payers and healthcare providers in the management of diabetic ketoacidosis (DKA). Additionally, manufacturers are forming distribution partnerships to ensure timely availability of DKA treatment solutions in outpatient settings, driving further segment expansion.
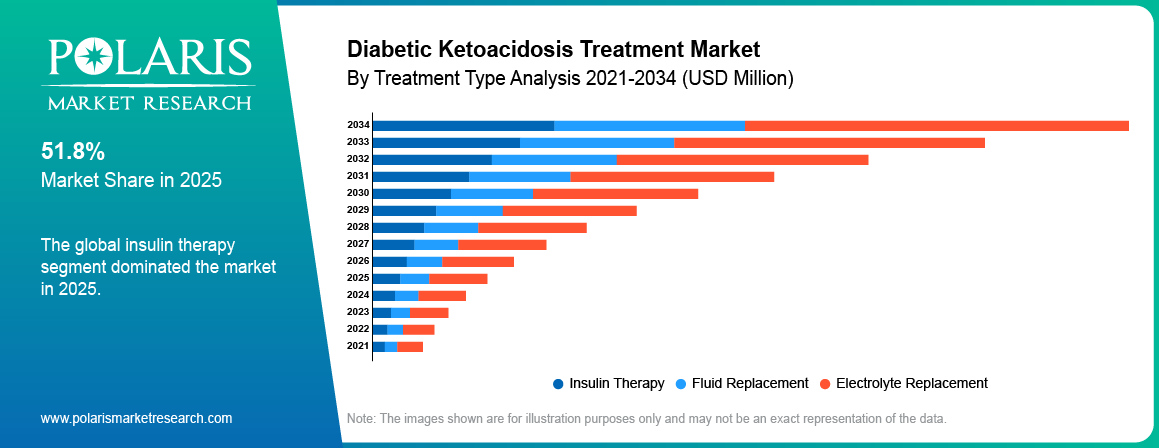
Source: Polaris Market Research Analysis
Diabetic Ketoacidosis Treatment Market by Region
The North American diabetic ketoacidosis treatment market accounted for 42.7% of global market share in 2025.
The high prevalence of type 1 diabetes coupled with a well-established emergency care infrastructure is driving the demand for DKA treatment across the region. As per the Breakthrough T1D report, approximately 300,000 individuals in Canada are currently living with type 1 diabetes (T1D), with the national prevalence increasing at an annual rate of 4.4%, significantly outpacing the population growth rate of 1%. Based on current trends, the total number of T1D cases is projected to reach 455,580 by 2040. Each year, an estimated 12,000 new cases are reported across all age groups, with adults accounting for nearly 71% of diagnoses. Additionally, the standardized DKA management protocols followed by hospitals in the US and Canada support early screening and improve insulin accessibility, thereby accelerating market growth. In addition, the presence of major healthcare companies, along with high investments in advanced insulin therapies and diagnostic technologies, continues to boost North America diabetic ketoacidosis treatment market.
The US Diabetic Ketoacidosis Treatment Market Insight
The U.S. market is expected to grow at a CAGR of 8.9% during 2026–2034, due to the rising prevalence of type 1 diabetes across all age groups, which is contributing to increasing emergency admissions for diabetic ketoacidosis, pushing hospitals to maintain continuous readiness with standardized treatment protocols. Additionally, the adoption of real-time digital monitoring platforms and EHR-linked insulin infusion systems is enhancing clinical decision-making and enabling faster guideline-based interventions for pediatric and adult DKA cases in high-volume healthcare settings.
Asia Pacific Diabetic Ketoacidosis Treatment Market
The market in Asia Pacific accounted for 27.4% of the global market in 2025. This growth is driven by the rising number of diabetes cases, limited early diagnosis, and improving access to healthcare. In countries such as India and China, the growing incidence of type 1 diabetes in children and young adults is leading to more emergency admissions for diabetic ketoacidosis (DKA). Also, government efforts to strengthen emergency care in rural and urban areas are helping improve access to insulin and fluid therapies. In addition, increasing awareness programs are helping patients and caregivers recognize symptoms and seek timely treatment.
China Diabetic Ketoacidosis Treatment Market Overview
The China market is expected to grow at a CAGR of 10.6% during 2026–2034 due to the growing number of type 1 diabetes cases among younger populations is resulting in a higher frequency of DKA-related hospitalizations, boosting government efforts to strengthen acute care capacity in provincial health systems. According to the World Health Organization (WHO), diabetes-related healthcare costs in China are projected to rise from USD 250.2 million in 2020 to USD 460.4 million by 2030, with per-capita spending increasing from USD 231 to USD 414. This growing economic burden is expected to drive greater investment in early diagnosis, insulin access, and acute care infrastructure, driving the expansion of diabetic ketoacidosis (DKA) treatment services across the country. At the same time, national initiatives to digitize emergency care and introduce automated glucose monitoring tools are enabling faster diagnosis and more effective metabolic correction in high-risk patients.
Europe Diabetic Ketoacidosis Treatment Market
The diabetic ketoacidosis treatment landscape in Europe is projected to hold a substantial share in 2034, fueled by the presence of universal healthcare systems, early-stage diabetes screening programs and adherence to international clinical guidelines. Also, countries such as Germany, the UK, and France are improving DKA management through the integration of electronic health records and clinical decision support systems. Furthermore, the presence of key companies in this region is extensively engaged in delivering DKA treatment through various business strategies such as acquisition and expansion of product portfolio, which in turn contributes to the growth of DKA treatment in this region. As an example, in March 2023, Sanofi acquired Provention Bio, adding TZIELD to its portfolio, the first approved therapy designed to delay the onset of Stage 3 type 1 diabetes. By slowing disease progression, TZIELD is expected to lower the likelihood of diabetic ketoacidosis (DKA). This acquisition fuels Sanofi’s commitment to advancing innovative, disease-modifying therapies that address critical gaps in diabetes management.
Source: Polaris Market Research Analysis
Diabetic Ketoacidosis Treatment Competitive Landscape & Core Acute-Treatment Suppliers
The diabetic ketoacidosis treatment industry is moderately competitive, with key players focusing on technology integration, product innovation, and strategic collaborations to strengthen their market position. Companies are investing in rapid-acting insulin formulations, point-of-care diagnostics and digital health tools to improve treatment outcomes. In addition, rising partnerships with healthcare providers and public health agencies are enhancing protocol adoption and expanding regional reach.
Key Players
- Abbott Laboratories
- Becton, Dickinson and Company (BD)
- Dexcom, Inc.
- Eli Lilly and Company
- F. Hoffmann-La Roche Ltd
- Glenmark Pharmaceuticals Ltd
- Insulet Corporation
- Medtronic plc
- Novo Nordisk A/S
- Sanofi
- Tandem Diabetes Care, Inc.
- Ypsomed AG
DKA Treatment Innovation: Faster Insulin Protocols, Acute-Care Monitoring & Safer Electrolyte Management
Future developments in diabetic ketoacidosis (DKA) treatment will focus on improving diabetes management and patient care. Smart insulin delivery systems are making insulin treatment more accurate and easier to manage. Predictive glucose analytics can help to detect changes in blood sugar levels at an early stage. Personalized treatment approaches are supporting care based on the needs of each patient. At the same time, integrated digital healthcare platforms are improving monitoring, data sharing, and communication between patients and healthcare providers.
Future Outlook: Protocol Optimization, Digital Triage & Prevention Integration
The diabetic ketoacidosis (DKA) treatment market is expected to grow as the number of people with diabetes continues to increase. Better insulin therapies and improved emergency care services will support market expansion. Digital monitoring tools are also helping healthcare professionals to treat the patients in a better way. AI, connected healthcare systems, and personalized treatment methods are likely to improve the early diagnosis, treatment and the overall patient outcomes in the future.
Industry Developments
- May 2026: Abbott received CE Mark approval for Libre Duo and Libre Duo 10 Day, the first systems to continuously monitor both glucose and ketone levels. The technology helps detect rising ketone levels early and supports timely treatment of diabetic ketoacidosis. (Source: abbott.mediaroom.com)
- June 2025: Ypsomed announced plans to integrate Abbott’s upcoming dual glucose-ketone sensor into its mylife Loop system, which combines the mylife YpsoPump and mylife CamAPS FX. This integration is expected to enhance diabetic ketoacidosis (DKA) management by enabling continuous monitoring of glucose and ketone levels, supporting timely intervention in high-risk patients.
Market Segmentation Outlook
By Treatment Type Outlook (Revenue, USD Million, 2021–2034)
-
Insulin Therapy
-
Fluid Replacement
-
Electrolyte Replacement
By Application Outlook (Revenue, USD Million, 2021–2034)
-
Pediatric
-
Adults
By End User Outlook (Revenue, USD Million, 2021–2034)
-
Specialty Clinics
-
Ambulatory Care Center
-
Hospitals
By Regional Outlook (Revenue, USD Million, 2021–2034)
-
North America
-
US
-
Canada
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
Netherlands
-
Russia
-
Rest of Europe
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Malaysia
-
South Korea
-
Indonesia
-
Australia
-
Vietnam
-
Rest of Asia Pacific
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
Israel
-
South Africa
-
Rest of Middle East & Africa
-
-
Latin America
-
Mexico
-
Brazil
-
Argentina
-
Rest of Latin America
-
Diabetic Ketoacidosis Treatment Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 899.36 Million |
| Market Size in 2026 | USD 935.66 Million |
| Revenue Forecast by 2034 | USD 1,292.08 Million |
| CAGR | 4.10% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Million and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Diabetic Ketoacidosis Treatment Market FAQ's
The global market size was valued at USD 899.36 million in 2025 and is projected to grow to USD 1,292.08 million by 2034.
The global market is projected to register a CAGR of 4.10% during the forecast period.
The North America region accounted for the largest market share of 42.7% in 2025, driven by rising demand and increasing market adoption.
A few of the key players in the market are Novo Nordisk A/S, Sanofi, Eli Lilly and Company, Becton, Dickinson and Company (BD), Dexcom, Inc., Medtronic plc, F. Hoffmann-La Roche Ltd, Abbott Laboratories, Insulet Corporation, Tandem Diabetes Care, Inc., Ypsomed AG, and Glenmark Pharmaceuticals Ltd.
The adult segment dominated the market in 2025. This dominance is attributed to a larger patient base, higher hospitalization rates due to insulin omission or non-compliance, and established treatment infrastructure in hospitals managing adult DKA cases.
The insulin therapy segment accounted for the largest market share of 51.8% in 2025, driven by its widespread use in the treatment of diabetic ketoacidosis (DKA).
Diabetic ketoacidosis treatment is emergency care for severe high blood sugar and ketone buildup. It includes IV fluids, insulin, and electrolyte replacement.
Diabetic ketoacidosis happens when the body does not have enough insulin. This leads to high blood sugar, ketone buildup, and dehydration.
DKA is treated with IV fluids, insulin, and electrolyte replacement. Doctors also monitor blood sugar, ketone levels, and vital signs during recovery.
Insulin is the main medicine used to treat diabetic ketoacidosis. Electrolytes and other supportive medicines may also be given if needed.
Download Sample Report of Diabetic Ketoacidosis Treatment Market
Please fill out the form to request a customized copy of the research report.