Continuous Glucose Monitoring Device Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Continuous Glucose Monitoring Device Market Summary
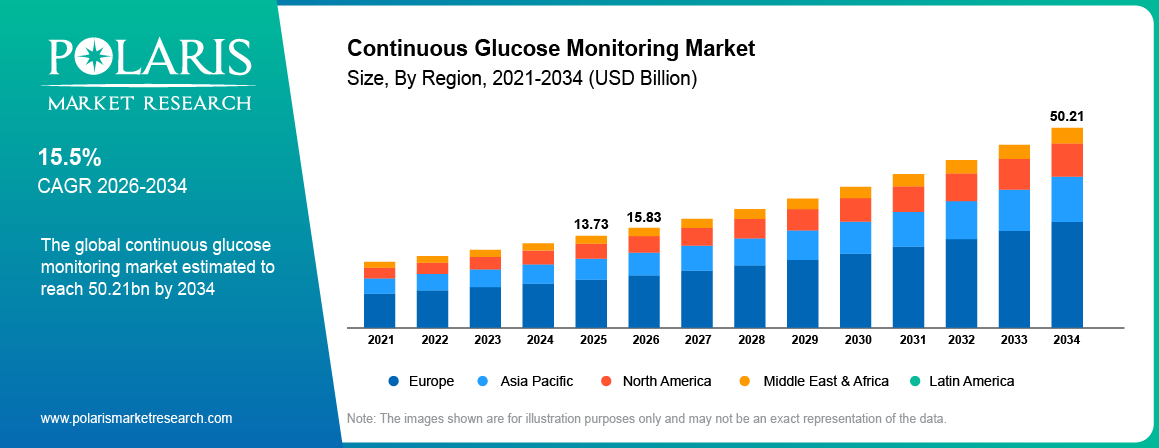
The global continuous glucose monitoring market size was valued at USD 13.73 billion in 2025. The market is projected to account for a CAGR of 15.5% from 2026 to 2034. The rising prevalence of diabetes and technological advancements in sensor accuracy are driving market growth. The market is also benefiting from supportive policies and increasing integration with digital health platforms.
Market Statistics
Key Takeaways
- North America accounted for the largest continuous glucose monitoring market share of 63.30% in 2025. This is owing to the high prevalence of diabetes and advanced healthcare systems in the region.
- Asia Pacific is projected to witness rapid growth at an 18.41% CAGR. Rising cases of diabetes and increasing healthcare expenditures are driving market growth in the region.
- By component, the sensors segment led with an 62.80% CGM market share in 2025. Technological advancements have enabled the development of smaller and longer-lasting sensors.
- By component, the transmitters segment is projected to grow at an 18.41% CAGR. This is because transmitters are crucial for enabling wireless communication of data between sensors and external devices.
- By indication, the type 1 diabetes segment accounted for an 64.90% continuous glucose monitoring market share in 2025. This is owing to the lifelong requirement for continuous glucose monitoring.
- By end use, the homecare diagnostics segment held an 67.10% CGM market share in 2025. The growing preference for personal health management contributes to the segment’s leading position.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is a Continuous Glucose Monitor?
A continuous glucose monitoring (CGM) device is a type of wearable medical equipment that allows users to measure their glucose levels in the interstitial fluid on a continuous basis via a tiny sensor that is placed just beneath the skin (subcutaneously), with a transmitter worn on the skin's surface. CGM systems are part of the wider range of diabetes devices used to manage the condition. It provides glucose levels and alerts in real time. Users can track changes without relying on repeated fingerstick tests.
How Does a CGM Device Work?
Positioning of the Sensor: The small-sized sensor is placed beneath the skin of either the upper arm or abdomen region. This sensor will continuously remain in contact with the interstitial fluid.
Glucose Detection: The sensor detects the presence of glucose concentration within the fluid.
Production of Electrical Signals: The enzyme present in the sensor interacts with the glucose, thus generating electrical signals.
Transferring of Data: The transmitter transfers the data to the receiver or the smartphone, which the user can access.
Notification: The device can send notifications when the glucose level rises above or falls below the predefined limit. Thus, the user can detect a sudden change in glucose level.
Recording of Data: The application records the glucose levels of the users. Thus, users can monitor the glucose level over a period of time.
CGM Market Dynamics
There is increased demand for continuous glucose monitoring systems, as more individuals and healthcare practitioners seek means of measuring glucose levels that go beyond regular finger pricking. The increasing prevalence of diabetes is promoting its use, while its expanded use in type 2 diabetes is introducing CGM into the lives of patients who do not use insulin. Government support and changing guidelines can affect access to CGM. However, costs of devices and insurance coverage may limit access, especially in cases where there are no reimbursement programs. Accuracy of sensors is essential since the information from them helps to make decisions regarding treatment. Over-the-counter products (OTC) CGM have expanded access to patients who were not traditionally included in this category. Improved interpretation of data with the help of artificial intelligence techniques is also transforming the way users as well as clinicians interpret glucose patterns.
Driver: Rising Prevalence of Diabetes
The increased prevalence of diabetes around the world is another factor driving the continuous glucose monitoring market growth, particularly CGM devices. CGM systems allow for real-time management of the disease. The International Diabetes Federation (IDF) Diabetes Atlas 2025 states that about 589 million adults between the ages of 20 and 79 years (i.e., one in every nine adults worldwide) have diabetes. This number is expected to rise to 853 million by 2050. Furthermore, nearly 252 million adults remain undiagnosed. This underscores the need for early detection and for diabetes devices. There is a growing burden of the disease and increasing awareness of the importance of diabetes management and the prevention of complications. Thus, the use of advanced glucose monitoring technologies is being accelerated in healthcare settings.
Driver: Government Initiatives and Healthcare Policies
Government support measures and health policies are crucial for increasing access to glucose monitoring equipment and for speeding up market growth. In the United States, the Centers for Medicare & Medicaid Services (CMS) has broadened Medicare Part B CMS coverage to include therapeutic continuous glucose monitoring (CGM) devices. Eligible patients who suffer from diabetes and who either rely on insulin or have a history of problematic hypoglycemia can be reimbursed for their CGM devices along with related accessories. Additionally, CMS requires that standardized coding verification is conducted for all CGM products eligible for coverage. It ensures transparency in the matter of reimbursement and provides easy market access to all the approved devices. Because of these reimbursement policies, patients have lower out-of-pocket expenses. Thus, they are more likely to adopt advanced glucose monitoring technologies. Also, there is a rising use of CGMs that are better integrated into regular diabetes management.
Driver Impact Table
| Driver | Key Factor | Impact on the CGM Market |
| Rising Prevalence of Diabetes | Growing diabetic population and a rising number of undiagnosed cases | Expands the potential user base for CGM manufacturers. The need for regular monitoring also creates repeat demand for replacement sensors. Wider adoption among people with type 2 diabetes is extending demand beyond insulin-dependent patients. |
| Government Initiatives and Healthcare Policies | Medicare coverage, reimbursement support, and wider access to approved devices | Reduces the financial burden on eligible patients and makes long-term CGM use more affordable. Favorable coverage policies can also encourage manufacturers to expand distribution and improve access across healthcare channels. |
Source: Polaris Market Research Analysis
Market Restraints: Reimbursement Policies and Sensor Accuracy
Insurance limitations may limit the availability of CGM devices among some patients. There are several conditions that must be met by patients to cover their needs for these products. For example, patients need to take insulin or meet other medical criteria. Prior authorizations can also prevent patients from gaining access to such devices. The devices that do not meet coverage conditions need to be purchased and replaced by patients at their own expense. This may become a challenge for people who require continuous glucose monitoring. The accuracy of sensors is another issue that affects the adoption rate of CGM devices. These tools monitor glucose levels in the interstitial fluid but not in blood. Therefore, the readings of the device can differ from fingerstick test results. Moreover, some sensor corrections and product notices in 2025 also raised concerns about the unreliability of CGM devices. These factors can affect user confidence.
Market Opportunities: Expanding CGM Adoption Beyond Insulin Users
Continuous glucose monitoring use is no longer limited to those using insulin to manage their diabetes. With greater availability of over-the-counter (OTC) CGMs, more type 2 diabetes patients can use glucose monitoring devices without requiring a prescription. Thus, manufacturers will have an increased audience to target. OTC availability will also afford consumers more leeway in choosing the monitoring device that suits them best. Further distribution channel changes can help drive adoption. Pharmacies offer a convenient point of sale for those seeking CGMs. A stronger pharmacy benefit structure can help increase the accessibility of the devices through insurance. However, access to such devices can be affected by prior authorization conditions. Manufacturers and distributors can collaborate with a DME supplier network to reach out to consumers using CGM devices covered under DME.
Market Trends: Advancements in Smart CGM Devices and Predictive Glucose Monitoring
CGMs are becoming more advanced due to manufacturers' efforts to enhance the quality of sensors and their analysis. In comparison to the earlier generation, the new CGMs provide higher accuracy and longer sensor wear times. Moreover, many devices are now integrated with smartphones, allowing for easier access to information about glucose levels throughout the day. AI and digital health solutions are changing the way CGM information is analyzed. Some devices can analyze glucose levels using predictive algorithms and thus warn about potential highs and lows in glucose levels. The development allows users to respond to the changes in glucose levels faster. AI-based analysis also allows recognizing patterns in glucose level readings. Besides, manufacturers are developing smaller sensors and non-invasive CGM technology.
CGM Technology and Product Landscape
The CGM devices have variations in terms of how the glucose measurements are collected and how they are accessible to the users. Some devices provide automatic measurement transfer, whereas others need user scanning. There are implantable devices that provide a longer monitoring period. In addition, there are now more available products for self-monitoring through over-the-counter devices. Sensing technologies are currently being developed to measure other health parameters along with glucose.
Real-Time vs Intermittently Scanned vs Implantable CGM
Continuous glucose monitoring devices vary in their ways of acquiring and transmitting glucose data. Real-time continuous glucose monitors send the results automatically to the connected devices. Intermittent scanning requires the person to scan the sensor to acquire the glucose information. The implantable continuous glucose monitors have the sensors located underneath the skin. Implantable CGMs can remain in use for longer periods.
| Type | Real-time CGM (rtCGM) | Intermittently scanned CGM (isCGM) | Implantable CGM | OTC glucose biosensor | Dual glucose-ketone sensor |
| How readings reach the user | Automatically transmitted to a receiver or smartphone | User scans the sensor with a reader or smartphone | Transmitted through an external transmitter | Readings accessed through a compatible smartphone app | Depends on the device and its data transmission system |
| Typical wear | Usually 7–15 days, depending on the product | Usually up to 14 days | Up to 365 days | Varies by product, commonly around 15 days | Depends on the product design |
| Alerts | High and low glucose alerts | Depends on the device; some offer optional alerts | High and low glucose alerts | Features vary by product | May include glucose and ketone alerts |
| Example products | Dexcom G7, Medtronic Simplera | FreeStyle Libre 2, FreeStyle Libre 3 | Senseonics Eversense 365 | Dexcom Stelo, Abbott Lingo | Abbott Libre Duo 10 Day (FDA authorized Aug 2026) |
| Primary users | People with diabetes requiring continuous glucose tracking | People with diabetes who prefer scan-based monitoring | Offered by implantable CGM market players for people requiring long-term glucose monitoring | Adults seeking glucose insights, including eligible non-insulin users | People who need information on both glucose and ketone levels |
Source: Polaris Market Research Analysis
OTC vs Prescription CGM
Access to CGM products can be obtained through various means. Prescription CGM requires authorization by a health care provider. Over-the-counter CGM enables a consumer who qualifies to buy a CGM without a prescription. This difference may impact the accessibility of glucose monitoring among consumers. Availability of each option depends on regulatory approval and the market where the product is sold.
| Parameter | Prescription CGM | Over-the-counter CGM |
| Intended user | People on insulin or with hypoglycemia risk | Adults and children 2+ not using insulin; wellness users |
| Purchase route | Pharmacy benefit, DME supplier, manufacturer | Retail, e-commerce, manufacturer-direct |
| Reimbursement | Medicare Part B and private insurance (eligibility rules) | Mostly self-pay |
| Alerts and dosing use | Hypo/hyper alerts; used for insulin dosing and AID | Insights and trends; not for insulin dosing |
| Examples | Dexcom G7, FreeStyle Libre 3 Plus, Simplera, Eversense 365 | Dexcom Stelo, Abbott Lingo, Libre Rio |
| Market role | Core revenue base | Volume expansion into type 2 and prediabetes |
Source: Polaris Market Research Analysis
Next-Generation Sensing: Glucose-Ketone and Needle-Free Sensors
The technology used in CGM is evolving beyond monitoring only glucose levels. Studies on using a glucose-ketone sensor that will be capable of measuring the two factors using one device are ongoing. This technology is referred to as dual-analyte sensing technology and will assist individuals who monitor their ketones together with their glucose levels.
Research is being conducted on needle-free sensor technology. These devices are designed to detect glucose without the insertion of any kind of sensor under the skin. Non-invasive glucose monitoring is being researched using different optical sensor technologies. The biggest challenge faced by researchers in developing these sensors is getting accurate readings without contact with body fluid.
Other advancements involve sensor life. Currently, there are implantable CGM sensors with a 365-day sensor life compared with shorter wear periods for conventional devices. These developments have increased interest in the glucose ketone monitor market.
CGM vs Fingerstick Blood Glucose Testing
CGM systems measure glucose levels in the interstitial fluid, while fingerstick measures the glucose levels directly from the blood sample. CGM gives repeated measurements throughout the day, while fingerstick gives a single measurement during testing.
| Parameter | Continuous Glucose Monitoring (CGM) | Conventional Fingerstick Testing |
| Method | Continuous, real-time monitoring | Single-point testing |
| Availability | 24/7 glucose trends and notifications | Readings available only when tested |
| User Convenience | Minimal finger pricking | Frequent finger pricking is needed |
| Notifications | High/Low glucose notifications | Notifications not available |
| Trending | Monitoring of glucose trend patterns | Limited glucose history |
| Connectivity | Integration with smartphones and cloud platforms | Standalone glucometers |
Source: Polaris Market Research Analysis
CGM Market Segment Insights
The CGM market segments are categorized on the basis of component type, indication, connectivity, end use, and distribution channel. In each category, there is a different part involved in the process of monitoring, ranging from the sensing devices to the delivery system of information to the users. Analysis of all these continuous glucose monitoring device market segments helps explain how product design and user requirements influence the demand for CGM.
By Component
The sensors segment accounted for the largest continuous glucose monitoring market share of 62.80% in 2025. Sensors are an integral part of the CGM solution since they monitor the concentration of glucose in interstitial fluid under the skin. The effectiveness of sensors will impact the results of glucose measurements directly. The need for CGM sensor market solutions is facilitated by the periodic necessity of replacing them. There is an interval during which most wearable sensors have to be changed. The development and improvement of sensors are aimed at increasing their effectiveness and wear duration. Modern CGM solutions provide users with sensors that can last for prolonged periods before being changed. The size of sensors is also getting smaller. These developments are improving the usability of CGM systems in the management of diabetes.
The transmitters segment is projected to grow at an 13.64% CAGR. The shift towards real-time glucose monitoring is fueling demand for this component segment. Real-time CGMs differ from scan-based glucose monitoring in that they transmit the glucose reading to a linked device automatically. This makes the transmitter an essential element for users requiring regular glucose level updates. Manufacturers are developing compact transmitters that are better at connecting wirelessly. Some CGM device manufacturers are integrating the transmitter into the sensor. The shift towards smaller and more connected CGM devices is shaping demand in this segment.
By Indication
The Type 1 segment led the continuous glucose monitoring market with an 64.90% share in 2025. This is due to the lifelong requirement for intensive glucose monitoring and insulin therapy. Individuals affected by Type 1 diabetes require frequent glucose monitoring. This helps prevent hypoglycemia and hyperglycemia. Thus, CGMs are becoming an essential part of daily disease management. Their use provides timely hypoglycemia alerts. Adoption of automated insulin delivery systems and sensor-integrated insulin pumps is rising in pediatric diabetes management. This strengthens demand in this segment. Favorable reimbursement policies in several developed markets support higher CGM penetration among Type 1 diabetes patients.
The Type 2 segment is projected to grow at an 18.36% CAGR. The rising number of patients diagnosed with Type 2 diabetes has led to an increase in the need for constant glucose monitoring. The utilization of CGM devices by this particular group of patients has gained traction as CGMs give a better representation of the fluctuations in glucose during the day. CGM devices are no longer limited to those individuals dependent on insulin. Patients with type 2 diabetes may use CGM in order to monitor their blood sugar level and see what affects it in terms of eating, exercise, and medication. Another factor that has led to increased CGM for type 2 diabetes market utilization is the wide distribution of over-the-counter CGM devices.
Type 1 Diabetes vs. Type 2 Diabetes vs. Gestational Diabetes
| Parameter | Type 1 Diabetes | Type 2 Diabetes | Gestational Diabetes |
| 2025 share | 64.90% | 32.30% | 2.80% |
| CAGR 2026–2034 | 13.52% | 18.36% | 17.63% |
| Monitoring need | Continuous, lifelong monitoring; helps identify high glucose levels that may increase the risk of diabetic ketoacidosis | Varies by therapy; rising for non-insulin and basal insulin users | Time-bound, through pregnancy |
| Device demand | rtCGM paired with insulin pumps and AID | rtCGM and OTC biosensors | rtCGM during prenatal care |
| Key growth driver | AID adoption, pediatric coverage | Coverage expansion to non-insulin users; OTC launches | Rising prevalence (5–9 per 100 U.S. pregnancies, CDC) |
| Outlook | Stable, high value | Largest volume opportunity | Small, fast-growing niche |
Source: Polaris Market Research Analysis
By Connectivity
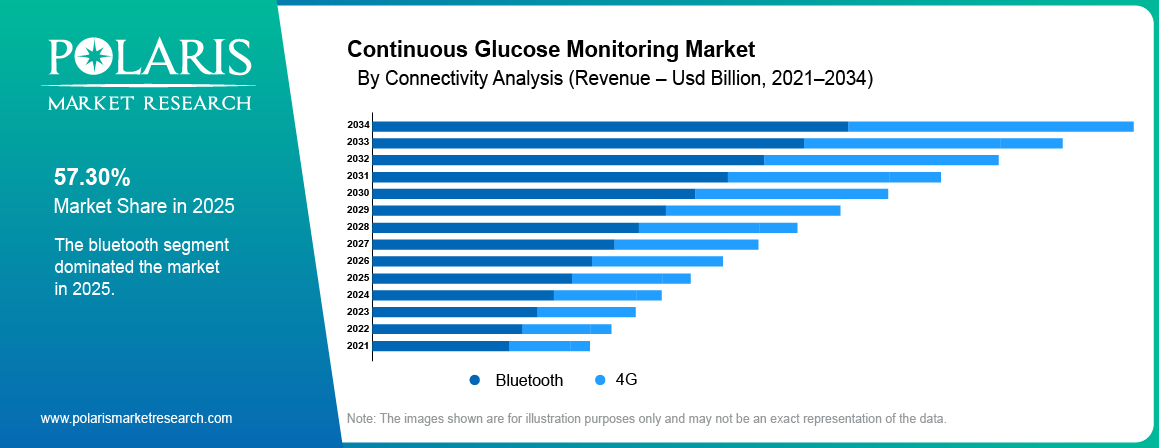
The Bluetooth segment led with a 57.30% continuous glucose monitoring market share in 2025. This leadership position is due to the common application of Bluetooth technology in CGM sensors to enable data transfer wirelessly. This enables glucose measurements to be transferred straight from the sensor to a smartphone or to a receiver. Users do not need to scan the sensor to see their measurements. The technology enables real-time alarms if glucose levels fall outside the target range. For instance, the Dexcom G7 is based on Bluetooth Low Energy to transmit glucose measurements to compatible smartphones or receivers. The sensor can even connect directly to an Apple Watch that is compatible with it. Users do not need to have their smartphones close by, as they can view their measurement readings on the watch itself. Increased use of interconnected CGM devices is contributing to the demand for Bluetooth systems.
The 4G segment is projected to witness rapid growth at an 15.34% CAGR. The utilization of 4G connectivity for CGM systems means that the glucose measurements will be sent through the mobile network without the need for a nearby smartphone. This is especially important in cases where it becomes necessary for patients' glucose measurements to be transmitted to caregivers or health care providers without physical contact. It also helps to make glucose measurement possible when away from home. The increased availability of mobile networks makes it easier for people to monitor glucose remotely in various environments. The demand for 4G-enabled CGM systems is also being driven by the rise in the adoption of remote patient monitoring services.
By End Use
The homecare diagnostics segment accounted for the largest market share of 67.10% in 2025. The increasing adoption of CGM devices in the home environment is contributing to its dominant position. CGM devices enable diabetics to measure blood glucose levels throughout the day without the need to visit healthcare institutions often. Patients can access information on their condition using their smartphones and exchange it with their doctors during consultations. Monitoring at home is especially valuable for patients who require constant monitoring of their glucose levels as a part of their everyday routine. In addition, the availability of user-friendly glucose sensors and OTC CGM solutions has brought glucose monitoring to a wider group of consumers.
The hospital segment is projected to witness rapid growth at an 17.82% CAGR. The growing number of patients using CGM devices in hospitals is leading to an increased need for CGM while providing care for the patients. The technology enables healthcare professionals to monitor changes in glucose levels without depending solely on blood glucose measurements taken from time to time. It is especially beneficial for patients whose glucose levels may fluctuate rapidly while receiving treatment. Clinical teams could use information received from CGM to detect glucose variations and make changes to the care being provided in due time. In addition, hospitals are considering the implementation of CGM in the care of patients with newly discovered glucose disturbances during their hospitalization. Growing clinical interest in continuous monitoring is anticipated to fuel its adoption in hospitals.
By Distribution Channel
The pharmacies segment held an 59.40% continuous glucose monitoring market share in 2025. This is attributed to their availability, trusted position in chronic disease management, and new business models that facilitate the sale of prescription and over-the-counter (OTC) glucose monitors. Alliances between CGM producers and national pharmacy chains also solidify dominance in the market. For instance, DexCom, Inc. and Abbott have established partnerships with CVS Health, Walgreens, and Walmart to make their devices available in-store and through online prescription services.
The e-commerce segment is projected to grow at an 19.36% CAGR. Many customers are adopting the online channel to purchase CGM devices and sensors. Through this channel, buyers get the opportunity to compare and review the features of different products before making their purchase decision. This channel is also convenient for customers who need constant replacement of their sensors. Some manufacturers of CGM devices sell their products directly through their websites. Customers therefore have access to both information about the product and subscription services. Availability of OTC glucose monitoring devices is expected to contribute to increased online sales because they can be purchased without a prescription. Increased availability of online purchasing is likely to drive the development of this segment.
CGM Applications and Use Cases
Real-World Use Cases of CGM Devices
Type 1 Diabetes: CGMs allow for accurate insulin dosing based on glucose trends in real time and decrease the risk of hypoglycemia/hyperglycemia. In the U.S., data from the CDC indicate that 2.1 million people have diagnosed type 1 diabetes, and 314,000 of those are children, which has fueled strong CGM adoption for the daily management of insulin (Source: cdc.gov).
Sleep Hypoglycemia Alerts: CGM systems can monitor glucose levels while someone sleeps. The systems send alerts when glucose levels are approaching or reach hypoglycemic ranges. The alerts that occur during the night can help enable a timely response. This decreases the chances of having prolonged nocturnal hypoglycemia.
Gestational Diabetes: Glucose monitoring allows pregnant women to keep track of changes in their glucose levels without having to carry out frequent finger-pricks. The CDC reports that between 5 and 9 out of every 100 pregnant women in the U.S. are affected by gestational diabetes each year (Source: cdc.gov). Thus, there is a growing need for continuous monitoring in prenatal care guidelines.
Key Areas of CGM Devices Market
Wearable Health Device & Digital Health Ecosystem Integration: Wearable health devices can be integrated with digital health apps. The integration leads to continuous, connected diabetes care. CGM devices send glucose readings to smartphones, smartwatches, and mobile apps. Patients and doctors can monitor glucose patterns remotely. This way, integration with digital health ecosystems supports remote patient monitoring devices. It also helps in personalized treatment management.
Closed-Loop Insulin Delivery Systems (Artificial Pancreas System): Closed-loop insulin delivery systems consist of CGM and insulin pumps. In closed-loop insulin delivery systems, algorithms are used to control the delivery of insulin on the basis of varying glucose level changes. MiniMed 780G with SmartGuard can deliver automatic basal dose adjustments according to changes in CGM. Tandem Control-IQ+ system uses a predictive algorithm that increases, decreases, or suspends insulin delivery based on predicted glucose changes. The integration of CGMs with automated insulin delivery is enhancing time-in-range outcomes. This is decreasing manual effort and fulfilling the requirement for advanced glucose monitoring technologies.
Non-Diabetic and Wellness Uses: Apart from traditional approaches, glucose monitoring is becoming popular in areas such as wellness, metabolism, and lifestyle. For example, Abbott Lingo includes a biosensor and an app that provides real-time glucose data to the user. Users receive personalized coaching about diet, metabolism, and overall wellness through the app. Expansion into non-diabetic and wellness uses would be an opportunity for CGM companies and would increase the consumer base of the CGM firms.
Digital Diabetes Management Ecosystem
The digital diabetes management ecosystem involves the integration of CGM devices, automated insulin delivery (AID), mobile applications, wearables, digital therapeutics, telehealth platforms, and AI-enabled data analytics tools. This allows for individualized feedback and automatic notifications. Patients receive their glucose levels in real-time via smartphone applications or wearables. Telemedicine platforms operating in the cloud allow health professionals to provide remote treatment. The use of AI technology provides information about changes in glucose levels. It allows health professionals to make appropriate decisions based on the information. Thus, the shift toward insulin pump integration and other innovations results in improved diabetes management.
CGM Market Regional Insights
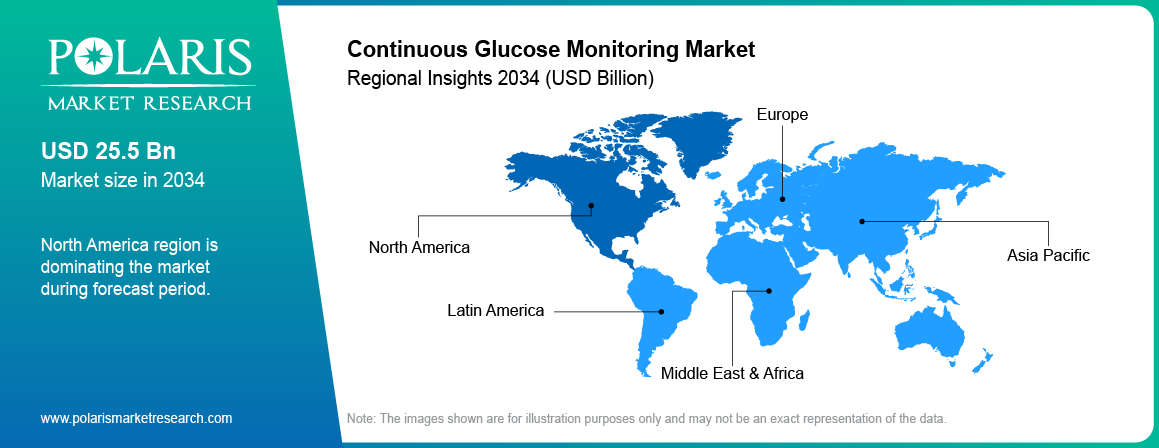
The continuous glucose monitoring market exhibits varying growth trends across regions. North America leads the adoption trend, backed by robust healthcare facilities and insurance coverage. Europe benefits from healthcare support and increased use of diabetes management software. In Asia Pacific, demand for CGM devices is growing owing to the high prevalence of the diabetic population and increased access to healthcare. Markets like China, Japan, and India are increasingly adopting CGM devices.
| Region | 2025 value (USD bn) | 2025 share | 2034 value (USD bn) | CAGR 2026–2034 | Key countries |
| North America | 10.42 | 63.30% | 21.24 | 14.12% | U.S., Canada |
| Europe | 3.04 | 18.40% | 6.68 | 14.68% | Germany, U.K., France |
| Asia Pacific | 2.11 | 12.80% | 6.22 | 18.41% | China, Japan, India |
| Latin America | 0.51 | 3.10% | 1.27 | 17.34% | Brazil, Mexico |
| Middle East & Africa | 0.4 | 2.40% | 1.04 | 17.82% | Saudi Arabia, UAE |
| Global | 16.48 | 100.00% | 36.45 | 9.20% | — |
Source: Polaris Market Research Analysis
North America CGM Devices Market
North America held the largest CGM market share of 63.30% in 2025. The region benefits from high diabetes management awareness and the availability of CGM devices. The existence of well-known manufacturers has also contributed to product availability in the region. Insurance coverage and reimbursement are impacting the adoption rate, especially for patients who need frequent glucose monitoring. Increased availability of OTC products has also been contributing to the increase in the number of CGM users outside the insulin-using population. The largest share of the regional market demand comes from the U.S., while Canada also contributes through the use of digital solutions for diabetes management.
U.S.
The U.S. continuous glucose monitoring market size was valued at USD 9.25 billion in 2025. The U.S. market is positively impacted by the large diabetes population and strong healthcare infrastructure. The region also benefits from a well-established U.S. diabetes devices market. Private insurance and Medicare have expanded access to CGM devices among the patients covered under them. The availability of products from well-known manufacturers like Dexcom and Abbott has positively influenced the market. Recent OTC launches are also increasing the accessibility of CGM devices to adults who do not use insulin. Clinical applications of CGM technology are increasing as well, since physicians use glucose information to monitor their patients.
Europe CGM Devices Market
The Europe continuous glucose monitoring market accounted for an 18.40% share in 2025. The demand for CGM is driven by the awareness of the importance of diabetes treatment and access to modern glucose monitoring devices. Public healthcare insurance is one of the ways of providing access to CGM products in several countries. Continuous glucose monitoring is used by healthcare providers to help patients control their glucose levels outside clinics. Nevertheless, there are different approaches to reimbursement of devices and policies of device access in Europe. Germany and the U.K. are significant markets due to the well-established healthcare system and digital diabetes treatment.
Germany and U.K.
Germany and the U.K. accounted for 24.86% and 22.43% of the European market, respectively.. These countries are contributing to the regional demand for CGM devices. In Germany, the system of statutory health insurance allows patients to have access to the products. Besides that, the established system of diabetes treatment in Germany is the reason for device adoption. In the U.K., the NHS provides patients with access to CGM devices. NICE guidelines influence the use of these tools in the treatment of diabetes. Availability through healthcare services is making it easier for more patients to monitor glucose continuously as part of their treatment for diabetes.
Asia Pacific CGM Market
Asia Pacific is projected to witness rapid growth at a 18.41% CAGR. This is due to rising diabetes cases, increasing healthcare expenditure, and improving awareness of advanced glucose monitoring solutions. Countries such as China, India, and Japan are leading this growth, supported by expanding healthcare infrastructure and government initiatives promoting diabetes care. The demand for cost-effective CGM devices is increasing as affordability and accessibility improve. Additionally, the region is witnessing a surge in telemedicine and digital health adoption, further accelerating CGM adoption in both urban and rural areas.
China, Japan, India
China accounted for a 39.48% share of the Asia Pacific market in 2025. The growing diabetic population of China is contributing to the rising demand for CGM devices. Increasing knowledge about diabetes care and improved access to healthcare facilities have made patients adopt CGM devices. Digital healthcare initiatives in China are also contributing to the adoption of connected monitoring devices.
Japan is projected to grow at an 16.62% CAGR. The aging population of Japan, along with the prevalence of diabetes cases, has created the need for constant glucose monitoring. The advanced healthcare structure of Japan makes it an ideal candidate for CGM adoption. Rising demand for remote patient monitoring has also been contributing to CGM use.
The CGM market in India is projected to grow at a 16.48% CAGR. The growing diabetic population is driving the demand for CGM in India. According to the International Diabetes Federation, the number of people having diabetes is expected to increase to 123.5 million by 2040. Govt NCD programs (NP-NCD, under National Health Mission) are focusing more and more on diabetes management, fostering awareness and diagnostic infrastructure. Increasing insulin consumption, urban lifestyle-associated diabetes, and better healthcare access are driving CGM penetration beyond metros into tier-2 cities, making India one of the fastest-growing CGM markets globally (source: www.icmr.gov.in).
Latin America CGM Devices Market
The Latin America continuous glucose monitoring market is projected to grow at an 17.34% CAGR. The regional growth is anticipated to be driven by the high incidence of diabetes, the growing penetration of advanced glucose monitoring solutions, and increasing awareness levels. Although historically access has been restricted due to cost and poor reimbursement coverage, urban populations in countries such as Brazil, Argentina, and Colombia are now beginning to see wider adoption of CGM devices, particularly among patients with Type 1 diabetes and insulin-dependent Type 2 cases.
Brazil
Brazil is projected to grow at a 14.42% CAGR. The growth in Brazil is being propelled by its large diabetic population, a progressive regulatory environment, and an increasing private healthcare sector. The need for more accurate and continuous glucose monitoring systems is increasing, with 16.6 million people diagnosed with diabetes. Several CGM systems of the type previously marketed in the U.S. have been approved by the Brazilian National Health Surveillance Agency (ANVISA), including those from Abbott and Medtronic, that can be used in the private sector and, in certain cases, through public health options (source: idf.org).
Middle East & Africa
The Middle East and Africa continuous glucose monitoring market is projected to grow at an 17.82% CAGR. The regional market is driven by growing awareness regarding digital health solutions, government initiatives towards the modernization of chronic disease management, and the rising cases of diabetes. Diabetes prevalence is among the highest in the world in some parts of the Gulf region, such as the UAE and Saudi Arabia, where CGM is gaining a foothold due to a high-income population, a developed healthcare system, and the availability of private insurance.
CGM Market Competitive Landscape
The continuous glucose monitoring market is highly competitive, and manufacturers are pursuing product advancements to gain an edge. Efforts are being made to enhance the accuracy of sensors and prolong their period of wear. Reduced device size and enhanced connectivity are other key areas of focus for manufacturers. With real-time monitoring becoming important, devices with automatic connectivity to phones are gaining popularity. Manufacturers are broadening their range of products in order to cater to various patient populations. The availability of over-the-counter CGM devices has increased competition in the market, as it provides access to consumers who do not use insulin. Strategic alliances and distribution are playing an important role in increasing the product reach.
CGM Market Share by Company
The CGM industry is dominated by companies with existing product portfolios and a well-established presence in the major regional markets. Market shares differ depending on the product availability, quality of the sensors used, cost of the products, and access to healthcare networks. Companies with a broad portfolio of CGM solutions can cover different patient segments, such as insulin-dependent patients or adults who need glucose monitoring but do not require any insulin medication. Product approvals and insurance coverage influence the presence of a company in specific markets. The existing competitors benefit from their customer base and partnerships within the healthcare community. Nevertheless, the emergence of new products and additional competitors makes the situation more competitive. The rise of over-the-counter CGM devices creates room for companies to enter the market without prescription-based sales.
| Company | Market Share, 2025 |
| Abbott Laboratories | 38.46% |
| Dexcom, Inc. | 34.72% |
| MiniMed Group, Inc. | 10.38% |
| F. Hoffmann-La Roche Ltd | 4.65% |
| Other companies | 11.79% |
Source: Polaris Market Research Analysis
Vendor Positioning
| Company | Key CGM products | Core technology | Positioning |
| Abbott Laboratories | FreeStyle Libre 3 Plus, Libre Rio, Lingo, Libre Duo 10 Day | Electrochemical glucose sensing; dual glucose-ketone monitoring technology in Libre Duo | Major global CGM provider with prescription and OTC products; expanding into dual glucose-ketone monitoring |
| Dexcom, Inc. | G7, G7 15 Day, ONE+, Stelo | Real-time electrochemical glucose sensing with wireless data transmission | Leading real-time CGM provider with prescription and OTC offerings; strong integration with automated insulin delivery systems |
| MiniMed Group, Inc. (separated from Medtronic in October 2026) | Simplera, Simplera Sync, Guardian 4 | Continuous glucose sensing integrated with insulin delivery systems | Integrated diabetes technology provider focused on CGM and automated insulin delivery |
| Senseonics Holdings, Inc. | Eversense 365 | Fluorescence-based implantable glucose sensor | Specialist in long-duration implantable CGM systems |
| F. Hoffmann-La Roche Ltd | Accu-Chek SmartGuide | Wearable electrochemical glucose sensing with AI-enabled predictive algorithms | Established diabetes care provider expanding its CGM portfolio with predictive glucose monitoring |
| A. Menarini Diagnostics S.r.l. | GlucoMen Day | Wearable continuous glucose sensing | European diabetes care provider with an established CGM offering |
| i-SENS, Inc. | CareSens Air | Wearable electrochemical sensor with Bluetooth connectivity | South Korean CGM provider offering a real-time glucose monitoring system |
| Sinocare / SiBionics / MicroTech Medical / Medtrum | iCan CGM, GS1, GS1 Pro, AiDEX, LinX, TouchCare Nano | Wearable electrochemical glucose sensing with wireless data transmission | Chinese CGM manufacturers offering products across domestic and international markets |
Source: Polaris Market Research Analysis
List of Key Companies
- Menarini Diagnostics S.r.l.
- Abbott Laboratories
- Biolinq Inc.
- Dexcom, Inc.
- F. Hoffmann-La Roche Ltd
- FiberSense AG
- GlySens Incorporated
- i-SENS, Inc.
- Infinovo Medical Co., Ltd.
- Insulet Corporation
- Medtrum Technologies Inc.
- MicroTech Medical
- MiniMed Group, Inc.
- mylife Diabetes Care AG
- Senseonics Holdings, Inc.
- Shenzhen Silicon-based Intelligent Technology Co., Ltd.
- Tandem Diabetes Care, Inc.
Recent Industry Developments
- October 2026: Medtronic completed the separation of its diabetes business into an independent publicly traded company, MiniMed Group, Inc. With the separation, Medtronic intends to increase its focus across its cardiovascular, neuroscience, and surgical portfolios. (source: medtronic.com)
- October 2026: Dexcom announced the upcoming Canadian launch of its Dexcom G7 15 Day system. The device offers up to 15.5 days of sensor wear and is expected to become available to eligible adults in November 2026. (source: dexcom.com)
- October 2026: Senseonics initiated the first human study of its investigational Freedom CGM system. The device is being developed to monitor glucose for one year without requiring an external transmitter worn on the body. (source: senseonics.com)
- September 2026: Senseonics entered into a partnership with Beta Bionics to integrate its Eversense 365 CGM system with the iLet Bionic Pancreas. Commercial launch of the integrated system is planned for the fourth quarter of 2026. (source: senseonics.com)
- August 2026: The U.S. FDA authorized Abbott's Libre Duo 10 Day system. It is the first wearable device authorized in the U.S. to continuously monitor both glucose and ketone levels through a single sensor. (source: fda.gov)
- June 2026: FiberSense AG received CE marking for its CGM system in Europe. The company highlighted its focus on commercialization. Initial deliveries are expected in late 2026. (source: fibersense-cxm.com)
CGM Market Future Outlook
The future market growth of CGM devices will depend on patient access to such devices as well as on the ability of manufacturers to meet patients' requirements for monitoring. The increase in use among type 2 diabetes patients will broaden the number of device users to include those who do not need insulin. Accuracy improvements and longer time of use are likely to shape product development. Manufacturers are also focusing on the production of small devices that are comfortable to wear on a daily basis. Reimbursement and affordability of products are likely to influence the CGM market growth prospects. Insurance coverage will increase patients' likelihood to switch to continuous glucose monitoring. The growth in emerging markets will be driven by increased diabetes awareness and improved access to healthcare. Based on these developments, the CGM market forecast 2034 can be seen as promising.
How Polaris' Estimate Compares
The market size estimation for the CGM market by Polaris involves the revenue that is generated through the commercially available CGM systems and their components. The estimation of the market size includes sensors, transmitters, and receivers used in glucose monitoring in clinical and non-clinical settings. Moreover, it takes into account the revenue from various diabetes indications, connectivity, end-use, and distribution channels.
Published numbers may differ based on what kind of products are included, geographic area covered, and revenue types. Some reports cover only CGM devices, while others cover other elements of the products. Polaris considers these differences when comparing its estimate with external benchmarks. Comparison involves the same base year, and it checks if the estimates cover the same product categories. The selected third-party benchmark for 2025 falls between USD 12.40 billion and USD 13.86 billion, while Polaris’s current published estimate stands at USD 13.73 billion. The estimate aligns with this range, subject to differences in component coverage and revenue definitions.
Research Methodology
The study defines the CGM market based on revenue from commercially available systems and their core components, including sensors, transmitters, and receivers. Standalone insulin pumps are excluded. The analysis covers 2021–2024 as the historical period, 2025 as the base year, and 2026–2034 as the forecast period.
Secondary research draws on company annual reports and SEC filings from Abbott Diabetes Care, Dexcom, and MiniMed Group. Other sources include FDA 510(k) and De Novo records, EU MDR and CE-marking information, CMS coverage publications, IDF Diabetes Atlas 2025, CDC and ICMR data, and peer-reviewed clinical studies.
Primary research includes interviews with CGM manufacturers, distributors, endocrinologists, and healthcare payers. Approximately 42 interviews were conducted, with 57.14% from the supply side and 42.86% from the demand side.
Market sizing follows a bottom-up approach. Country estimates are based on active users, sensor replacement rates, and average selling prices. These figures are checked against reported CGM revenue from leading manufacturers. Forecasts consider diabetes prevalence, reimbursement, OTC adoption, and device pricing. Data is validated through source comparisons and analyst review. Further details are available in How Polaris' Estimate Compares. The latest revision was completed on November 17, 2026.
Market Segmentation
By Component Type Outlook (Revenue – USD Billion, 2021–2034)
- Transmitters
- Receivers
- Sensors
By Indication Outlook (Revenue – USD Billion, 2021–2034)
- Type 1 Diabetes
- Type 2 Diabetes
- Gestational Diabetes
By Connectivity Outlook (Revenue – USD Billion, 2021–2034)
- Bluetooth
- 4G
By End Use Outlook (Revenue – USD Billion, 2021–2034)
- Hospitals
- Homecare Diagnostics
- Others
By Distribution Channel Outlook (Revenue – USD Billion, 2021–2034)
- Pharmacies
- E-commerce
- DME
- Manufacturer-Direct
- Other
By Regional Outlook (Revenue – USD Billion, 2021–2034)
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
Continuous Glucose Monitoring Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 13.73 billion |
| Market Size Value in 2026 | USD 15.83 billion |
| Continuous Glucose Monitoring Market Forecast 2034 | USD 50.21 billion |
| CAGR | 15.5% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Continuous Glucose Monitoring Device Market FAQ's
The continuous glucose monitoring market size was valued at USD 13.73 billion in 2025. The market is projected to reach USD 50.21 billion by 2034.
The market is projected to grow at a CAGR of 15.5% from 2026 to 2034.
The U.S. market size was valued at USD 9.25 billion in 2025. The market is positively impacted by the large diabetes population and strong healthcare infrastructure.
North America accounted for an 63.30% market share in 2025. High diabetes prevalence and an advanced healthcare ecosystem contribute to the regional market dominance.
Asia Pacific is projected to witness rapid growth at an 18.41% CAGR. Increasing healthcare expenditures are driving market growth in the region.
Key companies include Menarini Diagnostics S.r.l.; Abbott Laboratories; Biolinq Inc.; Dexcom, Inc.; F. Hoffmann-La Roche Ltd; FiberSense AG; GlySens Incorporated; i-SENS, Inc.; Infinovo Medical Co., Ltd.; Insulet Corporation; Medtrum Technologies Inc.; MicroTech Medical; MiniMed Group, Inc.; mylife Diabetes Care AG; Senseonics Holdings, Inc.; Shenzhen Silicon-based Intelligent Technology Co., Ltd.; and Tandem Diabetes Care, Inc.
The sensors segment led with an 62.80% market share in 2025. The introduction of compact and long-lasting sensors contributes to the segment’s leading position.
Type 1 diabetes accounts for a major share of the CGM market owing to the high need for CGM in insulin-dependent patients. However, type 2 diabetes is anticipated to grow faster owing to growing CGM adoption in non-insulin-dependent individuals.
The OTC CGM market has growth potential because it provides glucose monitoring without a prescription. Such devices can be used by adults who are not insulin-dependent but would like to monitor their glucose levels.
The factors include the growing number of diabetes patients who need glucose monitoring, increased adoption of CGM by people with type 2 diabetes, and the increase in wear time and accuracy of sensors.
The cost of CGM devices and sensors may limit the adoption of CGMs in markets where insurance coverage is low. Reimbursement constraints also play a significant role. Some people may experience problems with wearing the sensors and the accuracy of readings.
There is growth potential for the CGM market in India because of the large number of diabetic patients in the country and rising awareness about the management of glucose levels. Access to healthcare facilities and availability of devices are some factors that could aid in adoption.
Uninsured costs are approximately $70/month for the Libre 3, but can exceed $350/month for the Dexcom G7. (Coverage varies by country, insurance, and type of?diagnosis)
Ideal for type 1 diabetes, insulin-dependent type 2 diabetes, pregnant women with gestational diabetes, elderly with supportive caregivers and increasingly for healthy non-diabetic users interested in wellness and metabolism tracking.
Growing global burden of diabetes fuels the demand, 589 adults are living with it in whole world with large undiagnosed and prediabetic populations that increase the?addressable patient base across the hospital and homecare settings.
Real-time CGM (Dexcom G7) is continuously sending data?with alerts while intermittently scanned CGM (Libre) needs?to be scanned to see the readings, but newer models are now introducing optional real-time alarm functionalities.
Download Sample Report of Continuous Glucose Monitoring Device Market
Please fill out the form to request a customized copy of the research report.