Direct Air Capture Systems Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Direct Air Capture Systems Market Summary
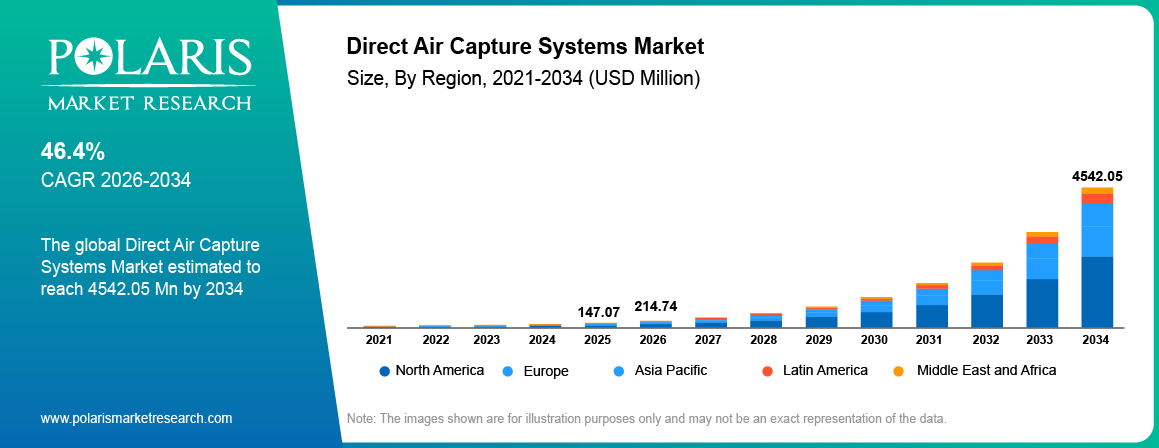
The global direct air capture systems market size was valued at USD 147.07 million in 2025. The market is projected to account for an 46.4% CAGR from 2026 to 2034. Rising focus on achieving global net-zero emissions is driving the direct air capture systems market growth. The market is also benefiting from the implementation of favorable government rules and incentives promoting carbon capture and storage.
Market Statistics
Key Takeaways
- North America accounted for the largest Direct Air Capture Systems market share of 45.8% in 2025. Technological advancements and supportive policy frameworks contribute to the regional market dominance.
- Asia Pacific is projected to grow at a CAGR of 49.7%. A confluence of technological and regulatory factors drives market growth in the region.
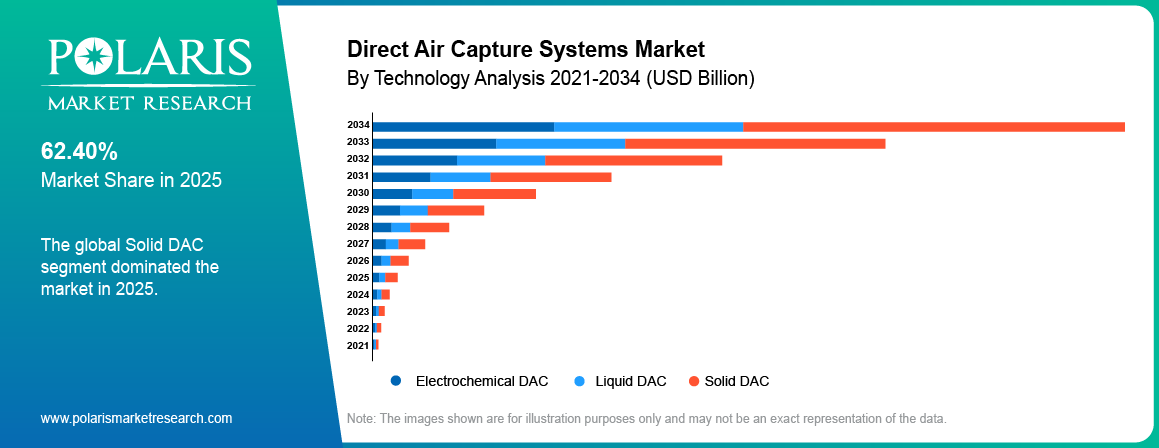
- The solid DAC segment led the global market with a 62.4% share in 2025. Lower operating temperatures and material advancements drive the segment’s leading position.
- The liquid DAC segment is projected to grow at a CAGR of 48.1%. The segment’s growth is driven by increasing demand for carbon removal solutions across industries.
- The carbon capture and storage (CCS) segment accounted for the largest market share of 68.7% in 2025. Growing regulatory pressure to limit carbon emissions contributes to the segment’s market dominance.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Is Direct Air Capture?
Direct air capture (DAC) systems involve direct absorption of carbon dioxide from ambient air. This process uses particular techniques or chemicals to capture the carbon dioxide and separate it from other air components. The absorbed carbon dioxide can either be permanently stored or utilized for any production processes. Direct air capture technology is becoming popular because companies and government organizations are increasing efforts towards carbon dioxide removal (CDR) from the atmosphere.
How Does Direct Air Capture Work?
Direct air capture removes carbon dioxide from the atmosphere through a capture and regeneration process. First, air comes into contact with a material capable of capturing CO₂. Captured CO₂ is then separated from the material and collected for storage or further use. The method of separation is dependent on the technology of capture.
Solid Sorbent Systems
Air passes through a porous solid material with sites that hold CO₂ molecules. When the material has captured the maximum possible amount of the gas, it is released through heating or a change in pressure. The sorbent can then be reused for more CO₂ capture.
Liquid Solvent Systems
Air is introduced to a solvent that reacts with carbon dioxide. The mixture is then treated to isolate CO₂. Heating is a common means of regenerating the solvent for further use.
Electrochemical Capture
This method makes use of an electrical potential to regulate the capture and release of carbon dioxide. An electrical energy input leads to a chemical transformation in the capture medium, which helps transport carbon dioxide independently of thermal regeneration.
Direct Air Capture vs. Traditional Carbon Capture
The table below highlights the differences between DAC vs carbon capture and storage:
| Factor | Direct Air Capture | Traditional Carbon Capture |
| CO₂ source | Ambient air, anywhere | Point-source industrial emissions |
| Deployment | Location-flexible | Must sit near the emission facility |
| Main goal | Remove legacy/historical atmospheric CO₂ | Prevent new emissions from being released |
| Technology complexity | High | Moderate |
| Primary application | Carbon removal / negative emissions technology | Emission reduction at source |
Source: Polaris Market Research Analysis
Direct Air Capture Systems Market Dynamics
The direct air capture systems market is shaped by demand for carbon removal, project economics, policy support, and investment in emerging capture technologies.
Driver: Rising Demand for Durable Carbon Removal
Demand for durable carbon removal is fuelling interest in DAC solutions. Companies are seeking out technologies capable of addressing emissions that are challenging to reduce through operational changes. DAC enables capturing CO₂ directly from the air and storing it for long periods. This has also created a need for contracted removal volumes. In January 2026, 1PointFive signed a contract with Bain & Company for 9,000 metric tons of carbon removal credits based on DAC technology over three years. The credits will come from the STRATOS facility in Texas and will be geologically stored (source: 1pointfive.com). Such deals increase the commercial demand for DAC-based carbon removal. Moreover, they indicate that companies are starting to commit themselves to certain volumes of carbon removal. As more companies seek durable removal solutions, such contracts may help drive market growth.
Driver: Progress Toward Large-Scale DAC Deployment
Investments in demonstration projects are facilitating the shift of direct air capture technology from the testing stage to commercial application. Developers are working on improvements in the performance of these systems under varied operating conditions. They are also assessing suitable energy sources and sites for bigger plants. This can help address the technical uncertainties that may arise in future projects. In February 2026, Climeworks and the Royal Commission for Jubail and Yanbu signed an agreement to assess a DAC demonstration plant at Jubail in Saudi Arabia. In addition to the assessment of low-carbon energy sources and appropriate sites, the work includes a regulatory assessment. Climeworks also reported successful testing of its mobile DAC facility in both Jubail and Riyadh (source: climeworks.com). These activities provide operating data for future projects. They also support the wider effort to establish DAC facilities in new markets.
Driver: Advancements in DAC Technologies
Progress is being made in direct air capture through advancements in capture materials and design. Researchers are developing sorbents to improve CO₂ capture efficiency and effectiveness while maintaining performance over multiple cycles. Efforts are also underway to develop sorbents that can function effectively at lower CO₂ concentrations. Progress in contactor design is increasing contact between the air and the capture material. Enhancements in the control systems are providing a way to monitor the changes in the performance of the capture through its operations. Developments in component durability under multiple capture-and-release cycles can help minimize performance degradation. Continued testing of new materials and system components can improve DAC system performance.
Restraint: High Cost of Direct Air Capture
High operational costs continue to act as one of the primary barriers to adoption in direct air capture. CO₂ is present in very low levels in atmospheric air, hence requiring large amounts of air processing in the DAC facilities. There is also the cost of energy in capture and regeneration processes. According to the International Energy Agency, the current direct air capture cost per ton of CO₂ is estimated to range from USD 500 to USD 1,900 (source: iea.org). Costs will depend on technology, among other variables including type of energy and scale of operations. Such economic considerations may make the installation of DAC technologies unfeasible without having contracts for the removal of carbon or policy support in place.
Restraint: Policy Uncertainty & Funding Risk
Shifts in government funding priorities can become a risk for large DAC projects. This became a concern in the US when federal funding reviews put some clean energy programs at risk of budget cuts, and these programs included Project Cypress and South Texas DAC Hub projects. The availability of incentives such as the 45Q tax credit can also influence the financial outlook for DAC projects. In April 2026, the DOE confirmed that the two projects would retain previously granted federal funding (source: reuters.com). This shows that funding priorities can shift and put projects at risk, even when funding has already been committed. Changes in funding priorities can be critical for DAC because large plants need substantial funding in the early stages of implementation. Therefore, continuity of public funding and limiting direct air capture funding cuts are critical for large DAC projects.
Opportunities: Expansion of Carbon Removal Credit Markets
The carbon removal credit marketplace represents yet another source of revenue for DAC plants. It would be possible to acquire durable removal credits to cover those emissions which cannot be reduced through other measures. This also creates opportunities to develop potential customers that do not operate their own DAC plants. Long-term purchase contracts can help predict future revenues for the company, thus financing the new project or expanding the existing one. The market may improve further as more buyers become concerned about the durability of the purchased carbon removal. In addition, improved measurement and verification processes for carbon credits can make them more desirable to buy.
Opportunities: Co-Location With Permanent CO₂ Storage
With appropriate storage facilities, DAC projects could be developed near available CO₂ storage resources. This can avoid long-distance CO₂ transport by minimizing the distance between capture and storage facilities. This can simplify planning and reduce the need for additional infrastructure. Appropriate geological features in some regions could therefore encourage investment in DAC projects. Co-location can also help scale up projects because it provides an assured destination for CO₂ captured at the facilities. Developers can evaluate the storage facility while considering location selection, rather than as an independent process. This would be especially helpful when considering DAC projects based on permanent carbon removal.
Trend: Shift Toward Modular DAC Plant Designs
The trend in DAC plant development is towards modular plants that can be built in smaller increments. It allows developers not to build a complete big plant right away. It is also flexible in regard to further capacity expansion because individual modules can be tested prior to adding more modules. Modular technology can be used when existing infrastructure constrains the construction of a bigger facility. It allows staged investments rather than paying all costs upfront. As experience in commercial installation grows, modularity becomes a key factor for DAC plants.
Trend: Greater Use of Low-Carbon Energy Sources
DAC projects are increasingly considering the energy required to capture and regenerate CO₂. The positive effect of carbon removal may be reduced if the plant relies on energy that produces high emissions. As a result, efforts are underway to understand how DAC systems can be coupled with lower-carbon energy and heat sources. Energy availability is also important because it affects the project's location and operating hours. Access to nearby energy sources will reduce emissions from the DAC project. It will also help the project address one of the major operational aspects of carbon capture.
Direct Air Capture Systems Market Segmentation
The direct air capture systems market is primarily segmented based on technology, source, application, end-use, and region.
| By Technology | By Source | By Application | By End-Use | By Region |
|
|
|
|
|
Source: Polaris Market Research Analysis
By Technology
The solid DAC segment led the global market with an 62.4% share in 2025. This dominance reflects the number of projects using this technology at various stages of development. Moreover, the technology has drawn interest among developers looking to build facilities for large-scale carbon capture. The modular nature of the technology has also helped the developers add capacity incrementally as needed, which can be helpful to projects that need to grow gradually. Research in the development of materials continues as developers seek better material performance and less demanding operational parameters. The segment is also expected to benefit from greater deployment of DAC facilities commercially. These factors will help the segment maintain its leading position in the global market.
The liquid DAC segment is projected to witness rapid growth at a 48.1% CAGR. This growth is driven by the ongoing development of DAC projects using liquid capture methods. Efforts have focused on improving system performance and reducing energy consumption during operation. This method also enables large-scale operations as more projects move from the pilot stage. The increasing number of investments in DAC commercial facilities will create opportunities for liquid DAC facilities. As more projects scale up, demand for this equipment will increase.
By Application
The carbon capture and storage (CCS) segment dominated the global market with an 68.7% share in 2025. Permanent storage continues to be a key way to store captured CO₂ in DAC projects. Growing interest in CCS is encouraged by the development of carbon storage infrastructure specifically aimed at it. The availability of carbon storage infrastructure allows DAC companies to have a way to dispose of the captured CO₂. Existing carbon transport and storage infrastructure further encourages project development in areas that already have carbon management infrastructure. As more DAC plants transition to commercial operations, the need for permanent storage will likely remain an important component of the market. This can ensure investments in storage infrastructure. CCS will also remain important as the market focuses more on carbon removal.
The carbon capture, utilization and storage (CCUS) segment is projected to grow at an 47.8% CAGR. Growth will be driven by increased use of captured CO₂ in commercial and industrial applications. The DAC facility can provide CO₂ for applications that require carbon dioxide as a feedstock, not as a final storage material. This gives project developers another opportunity to generate value from the captured carbon. The growing demand for synthetic fuel and chemicals from the chemical industry can support this approach as technology improves. CCUS will have more flexibility regarding the post-separation CO₂ handling. This could help in areas where permanent storage is limited. As carbon utilization facilities grow, DACs can gain access to new commercial outlets for captured CO₂.
By End Use
The oil & gas segment accounted for a 31.6% share in 2025. The industry is showing increasing interest in carbon removal technologies as companies seek solutions for hard-to-abate emissions. DAC offers a different pathway because it removes CO2 from the atmosphere rather than from direct emission sources. Moreover, the industry has experience with CO₂ management and underground storage, which may fuel the industry’s interest in DAC projects. Oil and gas companies can combine DAC with other solutions when they seek to reduce their emissions. Thus, further investment in carbon removal projects is expected to drive further demand for DAC technologies in the industry.
The chemicals & fuels segment is projected to grow at an 48.9% CAGR. Growth in the segment is expected to be driven by the use of captured CO₂ as a feedstock for producing fuels and chemicals. There would be an opportunity for the use of DAC technology as another feedstock for the processes that presently use fossil feedstock. The development of synthetic fuels and low-carbon chemistry is another factor driving interest in applying DAC technology. As the need for low-emission feedstocks grows, DAC technology could be used more widely in industry. Further advances in carbon utilization technologies would create additional opportunities to use CO₂ captured by DAC.
Real-World Applications & Use Cases
| Application | Use Case | How DAC is Applied |
| Permanent carbon removal | Long-term CO₂ removal from the atmosphere | DAC systems have the ability to remove CO₂ from the ambient atmosphere and sequester it to create permanent carbon removal, as opposed to emission avoidance from a point source. |
| Synthetic fuels | Carbon feedstock for fuel production | Captured CO₂ can be converted along with hydrogen to create synthetic fuels. This creates an opportunity for carbon supply to the fuel production process independent of fossil carbon. |
| Carbon-based products | CO₂ feedstock for manufacturing | Captured CO₂ can supply processes requiring carbon as an input in their manufacturing processes. Applications may include chemicals and building material manufacturing. |
| Industrial carbon management | Removal linked with industrial operations | DAC systems can support industrial decarbonization efforts by capturing emissions that cannot be avoided due to inefficiency or process limitations. |
Source: Polaris Market Research Analysis
Regional Insights
North America Direct Air Capture Systems Market Share (45.8% in 2025)
North America led the global direct air capture systems market with an 45.8% share in 2025. The US continues to be the major player in DAC regional development, with initiatives and technology developers operating in various states within the region. The US Department of Energy has been actively engaged in the development of DAC hubs through various initiatives in states such as Louisiana, Texas, California, Utah, and North Dakota. Canada is also emerging as another major player in terms of DAC developments. This country has an increasing number of DAC companies and is being considered for large-scale carbon removal projects. The presence of technology developers, carbon sequestration, and infrastructure in both nations lays a solid foundation for further growth. This will help North America retain its dominance in the DAC market.
Asia Pacific Direct Air Capture Systems Market Growth (49.7% CAGR)
Asia Pacific is projected to grow at an 49.7% CAGR. The regional growth is being driven by increasing focus on carbon removal technologies by countries such as Japan, Australia, South Korea, and China. In Japan, efforts are being made to create a domestic carbon removal market, while Australia is attracting providers of DAC technology, along with carbon storage projects. In March 2026, Skytree made an announcement about entering the Australian market to facilitate the deployment of DAC technology in the region (source: skytree.tech). In Australia, efforts are also being made to demonstrate DAC technology in various projects along with carbon storage. Another significant market is Japan, where efforts are being made to explore carbon removal technologies and the application of the technologies in producing synthetic fuel. These developments are expected to drive increased adoption of DAC technology in the Asia Pacific region.
Europe Direct Air Capture Systems Market Share (27.4% in 2025)
Europe accounted for an 27.4% direct air capture systems market share in 2025. There have been ongoing developments in direct air capture as the authorities and companies explore carbon removal as a part of their decarbonization process. Market activity is distributed among key countries such as Germany, France, the UK, Italy, the Netherlands, and Spain, while other European countries also contribute to regional demand. Research and pilot activity will help enhance the technical readiness of DAC technologies. The development of carbon transport and storage infrastructure is another factor that may support further projects. Besides, there is a trend in Europe towards the creation of carbon removal measurement and certification frameworks, which will help the developers and buyers to gain more clarity. These trends are expected to create a favorable climate for DAC implementation. Further investments in carbon removal are expected to solidify the region’s market position during the forecast period.
Latin America Direct Air Capture Systems Market Growth (43.2% CAGR)
Latin America is projected to account for an 43.2% CAGR. Interest in direct air capture is gradually increasing as companies and governments consider carbon removal solutions. Brazil, Mexico, and Argentina are the key markets identified for the region, although activity across the rest of Latin America can also help create future demand. This region has potential for DAC development where energy sources and carbon storage capacity are adequate. Growing interest in emissions reduction can further boost the development of carbon removal solutions. Market development will depend on many factors across countries in the region. Latin America is expected to increase its interest in DAC solutions over the forecast period.
Middle East & Africa Direct Air Capture Systems Market Growth (41.7% CAGR)
The Middle East & Africa is anticipated to register an 41.7% CAGR. This region is receiving more focus as interest in carbon capture technologies grows across markets like Saudi Arabia, UAE, Israel, and South Africa. The energy resources will help in the application of DAC technologies, and the availability of sites for storage will help in the permanent removal of carbon from the atmosphere. Emissions-reduction initiatives in the region have increased interest in technologies that can address remaining carbon emissions. Market development will vary depending on the country and a number of other factors, like policies and project economics. As carbon management technologies develop, interest in DAC technologies will rise.
Competitive Landscape
The direct air capture systems market is highly competitive, with companies pursuing different technological pathways and business models. The competition in the market is focused on optimizing the capture technology and making systems ready for scaled deployment. Market differentiation is defined not only by project size but also by capture materials, energy requirements, and integration opportunities between DAC and carbon dioxide storage or utilization.
Established developers like Climeworks and 1PointFive are advancing larger projects, while firms like Mission Zero Technologies and RepAir Carbon are developing alternative ways of capturing CO2. Other participants are targeting specific applications of direct air capture, such as distributed capture and integration of DAC technology with water treatment plants. Therefore, the competitive environment includes companies working on big centralized projects and small technology firms that develop specialized systems for particular purposes. Project collaboration and demonstration projects will remain crucial for validating new approaches in the direct air capture systems market.
Vendor Positioning
| Company | Primary Technology | Notable Differentiator | Stage |
| Climeworks (Switzerland) | Solid DAC (sorbent filters) | Largest operating capacity to date; Generation 3 tech claims 2x capacity and roughly half the energy use of its predecessor | Commercial, megaton-scale pipeline |
| 1PointFive (U.S.) | Liquid DAC (solvent-based) | Operates under Occidental's 1PointFive; large corporate offtake deals (Microsoft, United Airlines Ventures) | Commercial — first large-scale plant online |
| Heirloom Carbon Technologies (U.S.) | Solid DAC (mineral looping) | Stores captured CO₂ by embedding it in concrete via a CarbonCure partnership; Project Cypress partner | Commercial-scale first facility |
| RepAir Carbon (Israel) | Electrochemical DAC | Claims substantially lower energy intensity; partnerships in Greece and the U.S. Gulf Coast | Pilot / early commercial |
| Skytree (Netherlands) | Modular solid DAC | Compact units for vertical farming and industrial CO₂ supply; expanded to North America via a manufacturing partnership | Modular, high-volume small-scale |
| Octavia Carbon (Kenya) | Solid DAC | First commercial DAC operator in Africa; geothermal-powered with Rift Valley storage | Early commercial, emerging market |
Source: Polaris Market Research Analysis
Direct Air Capture Companies List
- 1PointFive
- Avnos, Inc.
- Capture6
- Carbon Capture Inc.
- Carbon Collect Limited
- Carbyon (Acquired by Airhive)
- Climeworks
- Deep Sky
- Heirloom Carbon Technologies
- Infinitree LLC
- Mission Zero Technologies
- Noya PBC
- Octavia Carbon
- Prometheus Fuels
- RepAir Carbon
- Skytree
- Soletair Power
- Spiritus
- Sustaera Inc.
- Zero Carbon Systems
Recent Industry Developments
- July 2026: Airhive acquired Carbyon, combining their solid-sorbent DAC technologies and aiming to develop next-generation systems with lower capture costs. (source: carbyon.com)
- June 2026: Siemens partnered with Ucaneo to support the scale-up of electrochemical DAC through automation and digitalization technologies. (source: siemens.com)
- June 2026: Deep Sky and Isometric issued North America's first certified DAC carbon-removal credits from the Deep Sky Alpha facility in Alberta. The credits were delivered to Microsoft and Royal Bank of Canada. (source: prnewswire.com)
- May 2026: The California Energy Commission launched a funding opportunity for pre-commercial DAC demonstration projects. The program focuses on testing advanced DAC technologies under real-world conditions. (source: energy.ca.gov)
Future Outlook
The direct air capture systems market is expected to shift toward more commercial, large-scale projects during the forecast period. Developers will focus more on proving system performance at scale. The market is also anticipated to witness more project designs directly coupled with permanent CO2 storage. Carbon removal buyers will be an additional revenue source for projects. In turn, technology providers will have the opportunity to explore new CO2-capture technologies under various conditions.
Standardized project designs can speed up project development as the industry gains more operating experience. The importance of carbon removal certification will increase as buyers will require more assurance about the volume of CO2 captured. Regional development will depend on the availability of appropriate facilities, infrastructure, and policies. As these factors develop, DAC is expected to evolve from early commercial projects to a broader market for atmospheric carbon removal.
Research Methodology
The direct air capture systems market study uses a two-track data collection approach. Secondary research draws on public agency sources, including U.S. Department of Energy award databases, International Energy Agency (IEA) and International Renewable Energy Agency (IRENA) publications. Company press releases and investor updates are also reviewed. Verified news coverage is used to track funding and policy developments. Primary research includes structured interviews with DAC technology providers, project developers, and policy analysts.
Market sizing combines top-down and bottom-up approaches. The estimates are cross-checked against publicly disclosed project capacities measured in tonnes of CO₂ per year and announced offtake agreement values. Results from both approaches are compared before the market is segmented by technology, energy source, application, end use, and region.
The base year is selected as the most recent full calendar year for which sufficient data can be verified and cross-checked. Forecast estimates account for uncertainty related to changing policies and funding conditions. Sensitivity or scenario considerations are used where policy changes could materially affect project development.
DAC remains a nascent industry with a limited number of commercial-scale plants. As a result, some market estimates rely on company-reported capacity and cost figures that may not have been independently audited.
Direct Air Capture Systems Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 147.07 million |
| Market Size Value in 2026 | USD 214.74 million |
| Direct Air Capture Systems Market Forecast 2034 | USD 4,542.05 million |
| CAGR | 46.4% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD million and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Direct Air Capture Systems Market FAQ's
The direct air capture systems market size was valued at USD 147.07 million in 2025. The market is projected to reach USD 4,542.05 million by 2034.
The market is projected to account for an 46.4% CAGR from 2026 to 2034.
North America led with an 45.8% direct air capture systems market share in 2025. Technological advancements and supportive policy frameworks drive the region’s leading market position.
The liquid DAC segment is anticipated to account for 48.1% CAGR. This is owing to increasing demand for carbon removal solutions across industries.
A few of the key market players include 1PointFive; Avnos, Inc.; Capture6; Carbon Capture Inc.; Carbon Collect Limited; Carbyon (Acquired by Airhive); Climeworks; Deep Sky; Heirloom Carbon Technologies; Infinitree LLC; Mission Zero Technologies; Noya PBC; Octavia Carbon; Prometheus Fuels; RepAir Carbon; Skytree; Soletair Power; Spiritus; Sustaera Inc.; and Zero Carbon Systems.
Direct air capture is a method of carbon removal that captures carbon dioxide directly from the air. The captured carbon dioxide is then separated from the air capture material and can either be stored permanently or utilized in applications of choice. This differs from point-source carbon capture in that it does not have to be captured from a particular emission source.
In direct air capture technology, ambient air passes through a substance that selectively traps carbon dioxide. The carbon dioxide is later removed from the substance once the maximum capture capacity is attained. The concentrated gas produced may either be sequestered or sent for carbon utilization.
Performance of the DAC process depends on features of the capture material and the design of the system. The material should be capable of capturing CO? efficiently despite being in very small amounts in the air. Its ability to maintain performance through cyclic operations is also important.
The process of direct air capture necessitates energy to push vast amounts of air into the capture unit and regenerate the materials used for capturing the CO?. The amount of energy needed varies depending on the technology and configuration used. Different technologies use heat and/or electricity in different amounts.
Yes, it is possible to scale up direct air capture. However, the industry is currently in its nascent state. Larger-capacity plants would require more machinery and energy to extract carbon dioxide from the atmosphere, as well as access to adequate storage or utilization facilities. Developers are building larger projects to assess the performance of DAC systems at commercial scale.
The difference between DAC and carbon capture and storage is in terms of capturing the carbon dioxide. In the case of DAC, carbon dioxide is captured directly from ambient air. The carbon dioxide in the case of carbon capture and storage is normally captured at industrial plants prior to release into the atmosphere.
Download Sample Report of Direct Air Capture Systems Market
Please fill out the form to request a customized copy of the research report.