
DNA Manufacturing Market Size, Growth Drivers, 2026-2034
REPORT DETAILS
DNA Manufacturing Market Summary
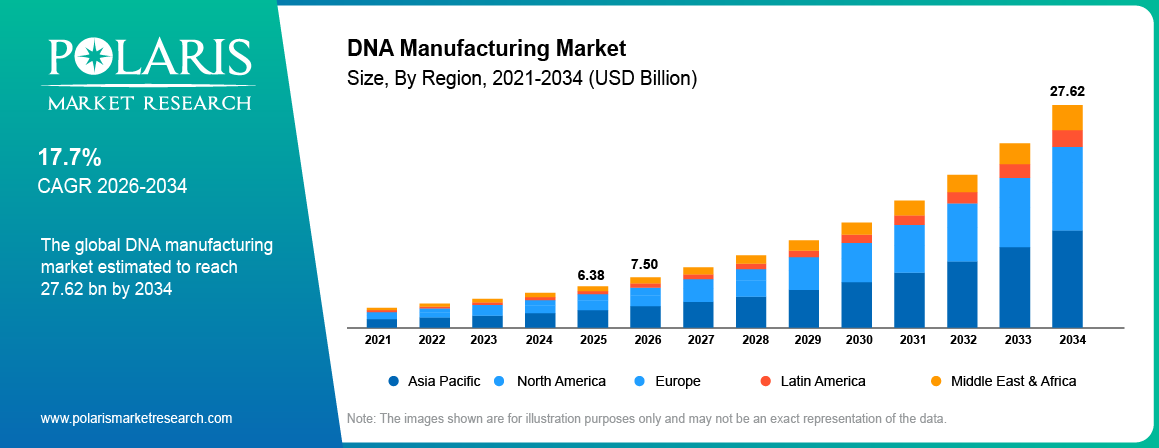
The global DNA manufacturing market was valued at USD 6.38 billion in 2025 and is projected to reach USD 27.62 billion by 2034, registering a CAGR of 17.7% from 2026 to 2034. The market is estimated to reach USD 7.50 billion in 2026, supported by growing demand for synthetic DNA, plasmid DNA, and high-quality DNA products across biotechnology and healthcare.
Market Statistics
Key Takeaways
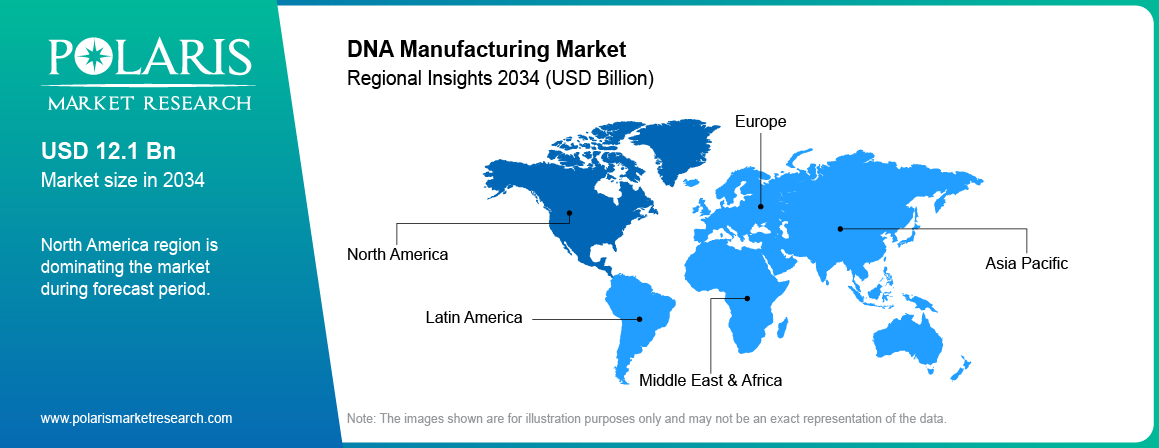
- North America accounted for 44.1% of the global DNA manufacturing market revenue in 2025. Growth is supported by its strong biotechnology ecosystem and investment in gene-based therapies.
- Asia Pacific is projected to register a CAGR of 19.8% during the forecast period. Growth is driven by rising R&D investments, biotechnology expansion, and government support for genomics.
- The synthetic DNA segment held the largest market share in 2025, accounting for 60.2% of revenue. Its dominance is driven by demand for therapeutic development, diagnostics, and synthetic biology.
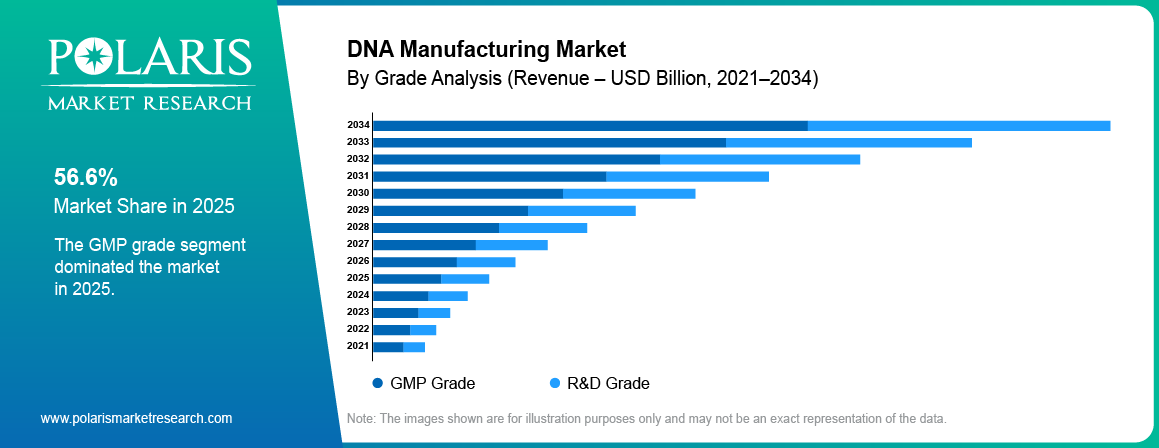
- The GMP-grade segment dominated the market in 2025, accounting for 56.6% of revenue. Demand is driven by clinical-grade DNA requirements for gene therapies, cell therapies, and DNA-based vaccines.
- The cell and gene therapy segment led the market in 2025, accounting for 43.8% of revenue. Growth is supported by expanding clinical pipelines and rising investments in advanced therapies.
- The contract research organizations (CROs) segment is projected to grow at a CAGR of 18.9% during the forecast period. Outsourcing helps biopharmaceutical companies reduce development timelines and access specialized DNA manufacturing capabilities.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Is the DNA Manufacturing Market?
The DNA manufacturing market involves the production of DNA molecules for use in biotechnology, medicine, and scientific research. These products include synthetic DNA, plasmid DNA, and DNA vectors used in genetic engineering, therapeutic development, and diagnostics. Manufactured DNA supports research and the development of advanced medical treatments.
DNA manufacturing plays an important role in gene therapy, mRNA vaccines and therapeutics, and cancer research. DNA can serve as a template for producing messenger RNA (mRNA), which helps cells produce specific proteins. Researchers also use manufactured DNA to study gene functions, develop diagnostic tools, and create crops with improved traits in agricultural biotechnology.
The growing demand for gene therapies is supporting DNA manufacturing market growth. Pharmaceutical and biotechnology companies require high-quality DNA molecules to develop treatments for genetic disorders, cancers, and rare diseases. These applications increase demand for synthetic DNA, plasmid DNA, and other DNA materials used in therapeutic development.
Rare diseases are another factor driving demand in the DNA manufacturing market. According to a 2025 review published in the Orphanet Journal of Rare Diseases, rare diseases affect an estimated 3.5–5.9% of the global population. Many rare diseases have a genetic origin, increasing the need for DNA-based research, diagnostic tools, and gene therapy development. As pharmaceutical and biotechnology companies develop targeted treatments, demand for customized DNA molecules is expected to grow, supporting expansion of the DNA manufacturing market (Source: pmc.ncbi.nlm.nih.gov).
How DNA Manufacturing Works
DNA manufacturing involves several steps to produce DNA molecules for research, biotechnology, and medical applications. The process may vary depending on the type of DNA and its intended use.
DNA Sequence Design: The process begins with designing the DNA sequence based on the required application. Researchers identify the genetic information needed for the project.
DNA Synthesis: The designed sequence is created using chemical or enzymatic DNA synthesis methods. The choice of method depends on the sequence length and production requirements.
Amplification and Cloning: When required, the DNA is copied or inserted into a suitable carrier to produce larger quantities. This step is common in plasmid DNA manufacturing.
Purification: The DNA is separated from unwanted materials and impurities to improve its quality.
Quality Control and Testing: The manufactured DNA is tested for identity, purity, and other quality requirements. Clinical and therapeutic applications may require additional testing and strict quality controls.
Final Use: The finished DNA is used in gene therapy development, vaccine research, genetic engineering, diagnostics, and other biotechnology applications.
Market Dynamics
Market Driver: Growing Government Initiatives and Genomics Research
Government support for genomics and personalized medicine is increasing the need for DNA manufacturing. In June 2026, the U.S. National Institutes of Health reported that its All of Us Research Program had made data from more than 747,000 participants available to researchers, including over 535,000 whole-genome sequences. Such large research programs support genetic studies, disease research, and precision medicine. These activities create demand for customized DNA molecules for laboratory research and diagnostic development (Source: nihs-all-us-research-program).
Market Driver: Rising Integration of Artificial Intelligence (AI)
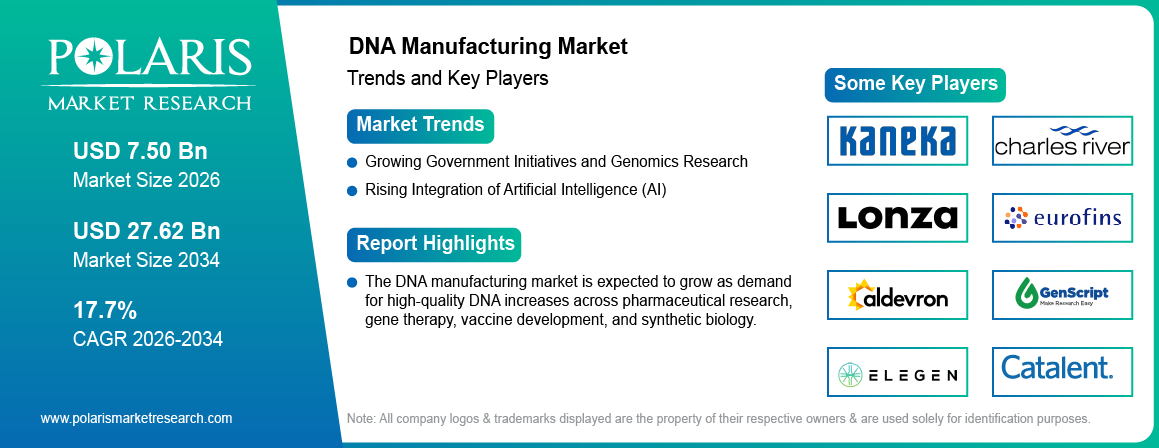
Artificial intelligence is creating new opportunities to improve DNA sequence design and manufacturing workflows. AI tools can help researchers assess gene sequences, identify useful designs, and plan experiments before production begins. These tools may reduce repeated laboratory work and support faster development of synthetic DNA for research and therapeutic applications. As biotechnology companies adopt AI-assisted design and automated production systems, demand for reliable DNA synthesis and quality testing may increase.
Market Opportunity: Expanding Cell and Gene Therapy Development
The growing development of cell and gene therapies creates opportunities for DNA manufacturing companies. According to the International Society for Cell & Gene Therapy's 2025 report, its global pipeline review covered 322 active clinical trials. These therapies often require plasmid DNA, synthetic DNA, or DNA templates during development and production. Manufacturers that expand reliable, high-quality production and meet clinical-grade requirements may benefit from growing demand from pharmaceutical companies and biotechnology developers (Source: isctglobal.org).
Market Opportunity: Growing Demand for Precision Medicine and Genetic Diagnostics
Growing investment in precision medicine creates opportunities for customized DNA manufacturing. In June 2026, the U.S. National Institutes of Health reported that the All of Us Research Program had made more than 535,000 whole-genome sequences available to researchers. This expanding genomic resource supports studies of genetic variation, disease risk, and treatment response. These research activities may increase demand for synthetic DNA, gene constructs, and DNA materials used in diagnostic development and personalized treatment research (Source: nihs-all-us-research-program).
Market Restraint: High Manufacturing Costs and Scale-Up Challenges
High production costs can limit growth in the DNA manufacturing market. Manufacturing complex DNA sequences requires specialized equipment, skilled staff, purification processes, and quality testing. Clinical-grade production also requires strict quality systems and documentation. Scaling up production while maintaining DNA purity, identity, and consistency can add further costs. These requirements may create challenges for smaller biotechnology companies and research institutions, particularly when developing products for clinical trials or commercial use.
Synthetic DNA vs. Plasmid DNA
Synthetic DNA and plasmid DNA are important products in the DNA manufacturing market. Both support biotechnology research and the development of medical treatments. However, they differ in their structure, production methods, and applications. Synthetic DNA is created to match a specific genetic sequence, while plasmid DNA is commonly used to carry genetic material for research and therapeutic development.
| Factor | Synthetic DNA | Plasmid DNA |
| What it is | DNA created to match a specific genetic sequence using chemical or enzymatic synthesis methods. | Circular DNA molecules used to carry and maintain specific genetic sequences. |
| Production Route | Produced through chemical or enzymatic synthesis, followed by assembly when needed. | Produced through plasmid construction, cell-based propagation or other production methods, followed by purification and quality testing. |
| Common Uses | Gene synthesis, genetic research, diagnostics, and synthetic biology. | Gene therapy development, vaccine research, viral vector production, and genetic research. |
| Flexibility | Allows customized DNA sequences for different research and biotechnology needs. | Allows specific genes to be carried within a designed DNA backbone for targeted applications. |
| Key Considerations | Sequence length, accuracy, production method, purity, and turnaround time. | DNA identity, purity, supercoiled content, residual impurities, endotoxin levels, and quality requirements. |
Source: Polaris Market Research Analysis
Advanced Technologies and Innovation Trends
Advanced technologies are improving DNA manufacturing by making production faster, more accurate, and easier to scale. Biotechnology companies are adopting new methods to meet the growing demand for synthetic DNA and plasmid DNA across research, diagnostics, and therapeutic development.
Automation and High-Throughput Synthesis: Automated systems help manufacturers produce DNA sequences with less manual work. High-throughput synthesis allows multiple DNA sequences to be produced and tested in parallel, supporting research and drug development.
Enzymatic DNA Synthesis: Enzymatic DNA synthesis uses enzymes to build DNA sequences. This approach is gaining attention as an alternative to conventional chemical synthesis and may support new DNA production methods.
AI-Assisted DNA Design: Artificial intelligence tools help researchers design and assess DNA sequences before production. These tools can support sequence optimization and reduce repeated design work.
Cell-Free DNA Production: Cell-free methods support the production of biological materials without relying on living cells for the full production process. These approaches may offer new options for specific biotechnology applications.
Sequencing-Based Quality Control: DNA sequencing helps verify whether a manufactured DNA sequence matches the intended design. Combined with other quality tests, it supports product accuracy and consistency.
DNA Manufacturing Technologies: Comparison and Applications
| Technology | How It Works | Key Benefits | Limitations |
| Chemical Oligonucleotide Synthesis | Builds short DNA strands by adding nucleotides through repeated chemical reactions. | Established method widely used in research, diagnostics, and biotechnology. | Efficiency decreases across repeated cycles, affecting full-length product yield and purification needs. |
| Enzymatic DNA Synthesis | Uses enzymes to add nucleotides and build DNA sequences. | May reduce chemical use and support new approaches to producing longer DNA sequences. | Performance, accuracy, production scale, and commercial availability vary across technologies. |
| Plasmid-Based Production | Produces plasmid DNA through DNA construct development, production, and purification. | Established approach for producing DNA used in gene therapy, vaccine development, and research. | Requires controlled production processes and quality testing to meet application-specific requirements. |
| Automation and High-Throughput Platforms | Automate DNA production steps and allow multiple sequences to be processed in parallel. | Can improve production speed, consistency, and throughput. | Performance depends on system integration, maintenance, and quality control. |
| AI-Assisted DNA Design | Uses artificial intelligence to design, assess, and optimize DNA sequences. | Can speed up design processes and help researchers identify promising sequences. | Designed sequences still require synthesis, quality checks, and experimental validation. |
Source: Polaris Market Research Analysis
Factors Influencing DNA Manufacturing Adoption
The adoption of DNA manufacturing depends on product quality, production needs, and the intended application. GMP-grade DNA requires stricter quality controls than research-grade DNA, which can increase production requirements. Longer or more complex DNA sequences may also need additional synthesis, purification, and testing.
Production scale affects manufacturing efficiency, as larger orders may require greater capacity and specialized equipment. Quality control is important to confirm DNA identity, purity, and consistency, particularly for therapeutic applications. Turnaround time also influences purchasing decisions, as research and biotechnology companies often need DNA materials within specific development timelines.
Outsourcing DNA manufacturing to specialized providers can help companies access advanced technologies and production expertise without investing in their own facilities. These factors influence how pharmaceutical and biotechnology companies select DNA manufacturing services for research, diagnostics, and therapeutic development.
Segment Insights
Type Analysis
The DNA manufacturing market is segmented into synthetic DNA and plasmid DNA. The synthetic DNA segment held the largest market share, accounting for 60.2% of total revenue in 2025. Its growth is driven by rising demand for customized DNA in drug development, diagnostics, and synthetic biology. Synthetic DNA is also used in CRISPR-based gene editing and vaccine development. Advances in DNA synthesis and AI-based design tools are supporting its wider use.
The plasmid DNA segment is projected to grow at a CAGR of 18.6% during the forecast period. Plasmid DNA is widely used in gene therapy, vaccine development, and viral vector production. Growing investment in cell and gene therapies is increasing demand for plasmid DNA manufacturing. Improvements in production and purification methods are also supporting its use in research and medical applications.
Grade Analysis
The DNA manufacturing market is segmented into GMP grade and R&D grade. The GMP-grade segment held the largest market share, accounting for 56.6% of total revenue in 2025. Its growth is driven by rising demand for high-quality DNA used in gene therapy, cell therapy, and DNA-based vaccines. Pharmaceutical and biotechnology companies require GMP-grade DNA to meet strict quality and regulatory standards. The growing number of clinical trials and the development of advanced therapies are further increasing demand for GMP-grade DNA manufacturing. Consistent product quality and purity are important for clinical and commercial applications.
The R&D-grade segment is projected to grow at a CAGR of 19.4% during the forecast period. R&D-grade DNA is widely used in genetic research, drug discovery, and early-stage therapeutic development. It helps researchers study gene functions, test new genetic designs, and develop potential treatments. Growing investment in biotechnology research is increasing demand for these products. Their use in gene editing, synthetic biology, molecular diagnostics, and laboratory testing is also supporting segment growth. As research activities expand, demand for customized R&D-grade DNA is expected to increase.
Application Analysis
The DNA manufacturing market is segmented into cell and gene therapy, vaccines, oligonucleotide-based drugs, and others. The cell and gene therapy segment held the largest market share, accounting for 43.8% of total revenue in 2025. Growth is driven by rising demand for DNA used in gene therapy development, viral vector production, and genetic engineering. Pharmaceutical and biotechnology companies use plasmid and synthetic DNA to develop treatments for cancer, rare diseases, and genetic disorders. The growing number of clinical trials and investment in advanced therapies are further supporting demand for high-quality DNA manufacturing. Improvements in gene delivery methods are also creating new opportunities for market growth.
The oligonucleotide-based drugs segment is projected to grow at a CAGR of 20.2% during the forecast period. Increasing research into antisense oligonucleotides and RNA interference therapies is creating demand for DNA materials used in drug development. DNA templates also support the production of RNA-based medicines. Advances in synthetic biology and DNA synthesis are helping companies produce customized genetic sequences for research and therapeutic applications. Growing investment in targeted treatments and genetic medicine is further supporting demand for DNA manufacturing services.
End Use Analysis
The DNA manufacturing market is segmented into pharmaceutical and biotechnology companies, academic and research institutes, and contract research organizations (CROs). Pharmaceutical and biotechnology companies accounted for 48.4% of total market revenue in 2025, driven by their use of synthetic DNA and plasmid DNA in drug development, gene therapy, and vaccine research. Growing investment in advanced therapies is increasing demand for reliable DNA manufacturing services. These companies also require high-quality DNA to support clinical trials and commercial production.
The contract research organizations segment is projected to grow at a CAGR of 18.9% during the forecast period. CROs provide specialized services, scalable production, and faster turnaround times for DNA-related research and development. Growing demand for CRISPR-based therapies, synthetic DNA, and genetic research is supporting the segment. Smaller biotechnology companies also rely on CROs to access manufacturing facilities and technical expertise without making large investments in their own infrastructure. These factors are expected to support CRO segment growth.
Applications and Real-World Use Cases
DNA manufacturing supports research, drug development, and medical innovation across several industries. The following table highlights its key applications and practical uses.
| Application | Use Case | Role of DNA Manufacturing | Key Benefit |
| Gene Therapy | Developing treatments for genetic disorders and cancer | Produces DNA used in gene therapy vectors and therapeutic development | Supports targeted treatment development |
| CRISPR Research | Studying and editing specific genes | Supplies DNA templates and genetic constructs for gene editing research | Helps researchers study gene function |
| Vaccine Development | Developing DNA vaccines and mRNA vaccines | Provides DNA constructs and templates used in vaccine development | Supports vaccine research and production |
| Molecular Diagnostics | Developing genetic tests for diseases | Supplies DNA sequences used in diagnostic assays and test development | Supports accurate genetic testing |
| Drug Discovery | Identifying and testing potential treatments | Provides DNA constructs for laboratory experiments and target validation | Supports early-stage drug development |
| Synthetic Biology | Designing and building biological systems | Produces customized DNA sequences for engineered biological systems | Enables new biotechnology applications |
| Agricultural Biotechnology | Developing crops with improved traits | Supplies DNA for plant genetic engineering and crop research | Supports crop improvement research |
| Personalized Medicine | Studying genetic differences between individuals | Provides DNA materials for genetic research and treatment development | Supports research into tailored treatments |
Source: Polaris Market Research Analysis
Regional Insights
North America DNA Manufacturing Market Trends
The North America DNA manufacturing market accounted for 44.1% of global revenue in 2025. Growth is supported by advances in biotechnology, pharmaceuticals, and synthetic biology. Strong research activity in gene therapy, personalized medicine, and CRISPR-based technologies is increasing demand for synthetic DNA and plasmid DNA. Government funding for genomics and investment in biotechnology companies are also supporting market expansion. The growing use of DNA in vaccine development and advanced therapies further contributes to regional demand.
U.S. DNA Manufacturing Market
The U.S. DNA manufacturing market benefits from a strong biotechnology industry, leading research institutions, and investment in genetic medicine. Growing use of precision medicine, next-generation sequencing, and CRISPR gene editing is increasing demand for customized DNA. Federal research initiatives and collaboration between pharmaceutical companies and biotechnology firms are also supporting innovation and the development of advanced therapies.
Canada DNA Manufacturing Market
Canada's DNA manufacturing market is supported by investments in genomics, biotechnology research, and advanced medical treatments. Universities, research institutions, and biotechnology companies are exploring genetic engineering, personalized medicine, and synthetic biology applications. These activities are creating demand for synthetic DNA and plasmid DNA for research and therapeutic development.
Asia Pacific DNA Manufacturing Market Trends
The Asia Pacific DNA manufacturing market is projected to grow at a CAGR of 19.8% during the forecast period, driven by expanding biopharmaceutical industries, rising R&D investments, and government support for genomics. Increasing activity in vaccine development, gene therapy, and synthetic biology is creating demand for DNA manufacturing services. Improvements in biotechnology infrastructure are also attracting investment in the region.
China DNA Manufacturing Market
China's DNA manufacturing market is supported by investment in biotechnology, precision medicine, and genetic research. Growing activity in gene therapy, vaccine development, and synthetic biology is increasing demand for synthetic DNA and plasmid DNA. Government support for biotechnology research and expanding domestic manufacturing capabilities are also contributing to market growth.
Japan DNA Manufacturing Market
Japan's DNA manufacturing market benefits from its established pharmaceutical industry and focus on regenerative medicine. Research into gene therapy, genetic disorders, and advanced treatments is creating demand for high-quality DNA products. Collaboration among pharmaceutical companies, universities, and biotechnology firms is also supporting innovation in DNA manufacturing.
India DNA Manufacturing Market
India's DNA manufacturing market is supported by its growing pharmaceutical, vaccine, and biotechnology industries. Government initiatives such as Make in India and increased investment in biotechnology research are encouraging domestic innovation. Demand for synthetic DNA is also growing in drug development, disease diagnostics, agricultural biotechnology, and genetic research.
Europe DNA Manufacturing Market Trends
The European DNA manufacturing market is supported by strong academic research, biotechnology innovation, and investment in advanced therapies. Research programs, including Horizon Europe, support work in genomics and synthetic biology. Pharmaceutical companies and biotechnology firms across the region are increasing their focus on gene therapy, vaccine development, and precision medicine, creating opportunities for DNA manufacturing providers.
UK DNA Manufacturing Market
The UK DNA manufacturing market benefits from established research institutions, biotechnology companies, and government support for genomics. Research into precision medicine, synthetic biology, and gene-based treatments is increasing demand for customized DNA. Collaboration among universities, pharmaceutical companies, and biotechnology firms also supports the development of DNA-based therapeutics and diagnostics.
Germany DNA Manufacturing Market
Germany's DNA manufacturing market is supported by its strong pharmaceutical industry, biotechnology research, and advanced manufacturing capabilities. Investment in genetic medicine, molecular diagnostics, and synthetic biology is creating demand for DNA products. Collaboration between research institutions and biotechnology companies also supports innovation in DNA synthesis and therapeutic development.
France DNA Manufacturing Market
France's DNA manufacturing market is driven by biotechnology research, pharmaceutical development, and investment in genomics. Growing interest in gene therapy, vaccine research, and personalized medicine is increasing the need for synthetic DNA and plasmid DNA. Collaboration between academic institutions, research organizations, and biotechnology companies is further supporting market development.
Middle East & Africa DNA Manufacturing Market Trends
The Middle East & Africa DNA manufacturing market is expected to grow during the forecast period, supported by increasing investments in biotechnology, healthcare research, and genomics. Growing interest in genetic diagnostics, vaccine development, and personalized medicine is creating demand for DNA manufacturing services. Government initiatives to strengthen healthcare infrastructure and expand research capabilities are also supporting market development across the region.
Latin America DNA Manufacturing Market Trends
The Latin America DNA manufacturing market is projected to expand during the forecast period, driven by growing biotechnology research, pharmaceutical development, and investments in healthcare. Increasing demand for genetic testing, vaccine development, and gene-based therapies is creating opportunities for DNA manufacturing services. Improvements in research infrastructure and collaborations between academic institutions, pharmaceutical companies, and biotechnology firms are also expected to support regional market growth.
Key Players and Competitive Analysis
The DNA manufacturing market is driven by rising demand for synthetic DNA and plasmid DNA for applications such as gene therapy, vaccine development, CRISPR-based research, and synthetic biology. Companies compete through advances in DNA synthesis, manufacturing capacity, product quality, and their ability to support research and therapeutic development. Established companies such as Thermo Fisher Scientific, Danaher Corporation through Aldevron, and Lonza offer capabilities that support DNA production and the development of advanced therapies. Specialized companies such as Elegen and Touchlight are developing alternative DNA manufacturing technologies to address the need for faster production and scalable DNA supply.
Thermo Fisher Scientific Inc. is a major life sciences company that provides products and services for biotechnology research and pharmaceutical development. Its capabilities across laboratory technologies, genetic analysis, and bioproduction support research and the development of DNA-based applications. These offerings help researchers and pharmaceutical companies advance genetic research and therapeutic development.
Danaher Corporation (Aldevron) participates in the DNA manufacturing market through Aldevron, which specializes in plasmid DNA, messenger RNA, and related biological products. Its manufacturing capabilities support gene therapy development, vaccine research, and other advanced therapeutic applications. The company serves biotechnology and pharmaceutical organizations that require specialized DNA materials for research and clinical development.
Key Players
- Catalent, Inc.
- Charles River Laboratories International, Inc.
- Danaher Corporation (Aldevron)
- Elegen, Inc.
- Eurofins Scientific SE (Eurofins Genomics)
- GenScript Biotech Corporation
- Kaneka Corporation
- Lonza Group AG
- ProBioGen AG
- Thermo Fisher Scientific Inc.
- Touchlight Genetics Ltd.
- VGXI, Inc.
- WuXi AppTec Co., Ltd.
Vendors Positioning Table
| Company | Headquarters | Key Capabilities | Role in the DNA Manufacturing Market |
| Catalent, Inc. | Somerset, New Jersey, USA | Biologics development and manufacturing | Supports pharmaceutical and advanced therapy development. |
| Charles River Laboratories International, Inc. | Wilmington, Massachusetts, USA | Plasmid DNA and cell and gene therapy services | Supports genetic medicine research and development. |
| Danaher Corporation (Aldevron) | Washington, D.C., USA | Plasmid DNA and nucleic acid manufacturing | Supports gene therapy and vaccine development. |
| Elegen, Inc. | San Carlos, California, USA | High-quality synthetic DNA production | Provides synthetic DNA for biotechnology research and development. |
| Eurofins Scientific SE (Eurofins Genomics) | Luxembourg City, Luxembourg | Custom DNA synthesis and genomics services | Supports genetic research and molecular biology applications. |
| GenScript Biotech Corporation | Nanjing, China | Gene synthesis and custom DNA production | Supplies DNA for research, drug development, and synthetic biology. |
| Kaneka Corporation | Osaka, Japan | Biotechnology and biopharmaceutical manufacturing | Supports biotechnology and related manufacturing applications. |
| Lonza Group AG | Basel, Switzerland | Contract development and manufacturing services | Supports biopharmaceutical and advanced therapy production. |
| ProBio | Suzhou, China | Cell and gene therapy development and manufacturing | Supports advanced therapy development, including plasmid DNA-related applications. |
| Thermo Fisher Scientific Inc. | Waltham, Massachusetts, USA | Life science products, DNA-related services, and bioprocessing solutions | Supports genetic research and pharmaceutical development. |
| Touchlight Genetics Ltd. | Hampton, United Kingdom | Doggybone DNA (dbDNA™) technology | Provides alternative DNA manufacturing technology for biotechnology and therapeutic applications. |
| VGXI, Inc. | The Woodlands, Texas, USA | Plasmid DNA manufacturing | Supports gene therapy, DNA vaccine, and other therapeutic development programs. |
| WuXi AppTec Co., Ltd. | Shanghai, China | Contract research, development, and manufacturing services | Supports pharmaceutical and biotechnology product development. |
Source: Polaris Market Research Analysis
Recent Developments in the DNA Manufacturing Market
- October 2026: ProBio successfully completed a pre-approval inspection by China’s National Medical Products Administration (NMPA) at its biologics manufacturing facility in Nanjing, China. The milestone supports the facility’s readiness to serve biologics programs progressing toward commercial manufacturing. (Source: probiocdmo.com)
- July 2026: Touchlight’s doggybone DNA (dbDNA™) technology supported the first UK patient dosing in a Phase I clinical trial of a personalized lung cancer vaccine. The vaccine was manufactured using Touchlight’s cell-free DNA platform, highlighting its potential role in personalized cancer treatment development. (Source: touchlight.com)
- January 2026: Elegen announced price reductions across its ENFINIA™ DNA portfolio, with prices starting at $0.07 per base pair. The company attributed the lower pricing to its GEN II Cell-Free DNA Platform, which supports the production of complex DNA sequences for biotechnology research and development. (Source: elegenbio.com)
- April 2025: ProBio launched a Good Manufacturing Practice (GMP) plasmid DNA manufacturing service at its facility in Hopewell, New Jersey. The service supports biotechnology and pharmaceutical companies developing advanced therapies. (Source: probiocdmo.com)
- January 2025: Touchlight received Good Manufacturing Practice (GMP) certification for its facility in Hampton, United Kingdom. The certification supports the manufacture of active pharmaceutical ingredients for clinical development, including DNA vaccines and non-viral gene therapies. (Source: touchlight.com)
Future Outlook
The DNA manufacturing market is expected to grow as demand for high-quality DNA increases across pharmaceutical research, gene therapy, vaccine development, and synthetic biology. Rising demand for GMP-grade DNA is likely to support investment in manufacturing capacity and quality control. Advances in enzymatic DNA synthesis, automation, and AI-assisted design may improve production efficiency and expand manufacturing options. Growing applications in personalized medicine, genetic diagnostics, and advanced therapies could create further opportunities for market growth. However, progress will depend on production costs, technical performance, and regulatory requirements.
Research Methodology
The study of the DNA manufacturing market draws on company records, industry data, regulatory documents, scientific publications, and information on biotechnology research and development. Both top-down and bottom-up approaches may be used to estimate market size, subject to the methodology applied by Polaris Market Research.
Secondary Research: Company annual reports, official product and service pages, government statistics, regulatory publications, clinical trial databases, trade publications, and peer-reviewed research were reviewed. The research focuses on DNA synthesis, plasmid DNA manufacturing, GMP-grade production, and applications in gene therapy, vaccine development, and synthetic biology.
Primary Research: Interviews with 23 participants across NA, APAC, and EU were conducted. Participants may include DNA synthesis providers, plasmid DNA manufacturers, contract development and manufacturing organizations (CDMOs), biotechnology companies, research institutions, and industry experts. Their feedback helps assess manufacturing capacity, demand trends, outsourcing, and technology adoption.
Market Estimates and Forecast: Market estimates are based on the defined market scope, available industry data, company information, and relevant demand indicators. The forecast covers 2026–2034, using 2025 as the base year. Key factors include investment in gene and cell therapies, vaccine development, advances in DNA synthesis, and demand for high-quality DNA products.
Scope and Validation: The study covers plasmid DNA and synthetic DNA, including gene synthesis and oligonucleotide synthesis, across grades, applications, end uses, and regions. Estimates are reviewed against available industry data for consistency. The data cutoff was September 2026.
DNA Manufacturing Market Segmentation
By Type Outlook (Revenue, USD Billion, 2021–2034)
- Plasmid DNA
- Synthetic DNA
- Gene Synthesis
- Oligonucleotide Synthesis
By Grade Outlook (Revenue, USD Billion, 2021–2034)
- GMP Grade
- R&D Grade
By Application Outlook (Revenue, USD Billion, 2021–2034)
- Cell & Gene Therapy
- Vaccines
- Oligonucleotide-Based Drugs
- Others
By End Use Outlook (Revenue, USD Billion, 2021–2034)
- Pharmaceutical and Biotechnology Companies
- Academic & Research Institutes
- Contract Research Organizations
By Regional Outlook (Revenue, USD Billion, 2021–2034)
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
DNA Manufacturing Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 6.38 Billion |
| Market Size in 2026 | USD 7.50 Billion |
| Revenue Forecast by 2034 | USD 27.62 Billion |
| CAGR | 17.7% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
DNA Manufacturing Market FAQ's
The global DNA manufacturing market was valued at USD 6.38 billion in 2025, according to Polaris Market Research.
The global DNA manufacturing market is projected to reach USD 27.62 billion by 2034, growing at a CAGR of 17.7% from 2026 to 2034.
The DNA manufacturing market includes the production of synthetic DNA, plasmid DNA, and other DNA materials used in biotechnology research, drug development, diagnostics, and therapeutic applications.
Market growth is supported by rising demand for gene and cell therapies, increasing biotechnology research, expanding vaccine development, and growing applications of synthetic biology. Advances in DNA synthesis technologies are also creating new opportunities.
The major types are plasmid DNA and synthetic DNA. Synthetic DNA includes gene synthesis and oligonucleotide synthesis, while plasmid DNA is used in genetic research, vaccine development, and gene therapy applications.
Asia Pacific is expected to experience growth due to expanding biotechnology research, pharmaceutical investment, and government support for genomics and advanced therapies. North America also remains an important market because of its established biotechnology industry and research infrastructure.
DNA manufacturing supports cell and gene therapy, vaccine development, oligonucleotide-based drug development, genetic engineering, molecular diagnostics, and synthetic biology. These applications rely on DNA materials for research and therapeutic development.
High production costs, complex manufacturing processes, quality control requirements, and regulatory standards are key challenges. At the same time, advances in enzymatic DNA synthesis, automation, and AI-assisted design may improve production efficiency and support growing demand for advanced therapies and customized DNA products.
Download Sample Report of DNA Manufacturing Market
Please fill out the form to request a customized copy of the research report.


