
Electric Aircraft Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Electric Aircraft Market Summary
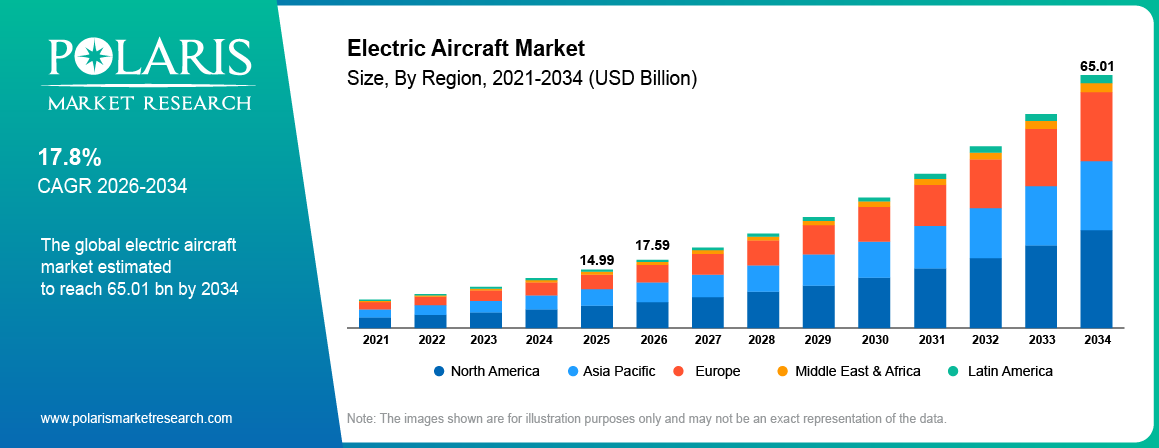
The global electric aircraft market was valued at USD 14.99 billion in 2025 and is expected to grow at a CAGR of 17.8% during the forecast period. The growth is driven by rising government investment, technological advancement, and growing demand for urban air mobility.
Market Statistics
Electric Aircraft Market Key Takeaways
- VTOL platforms dominated with largest share of 61.10% in 2025. Their ability to take off and land without a runway makes them particularly suitable for point-to-point urban air-taxi services
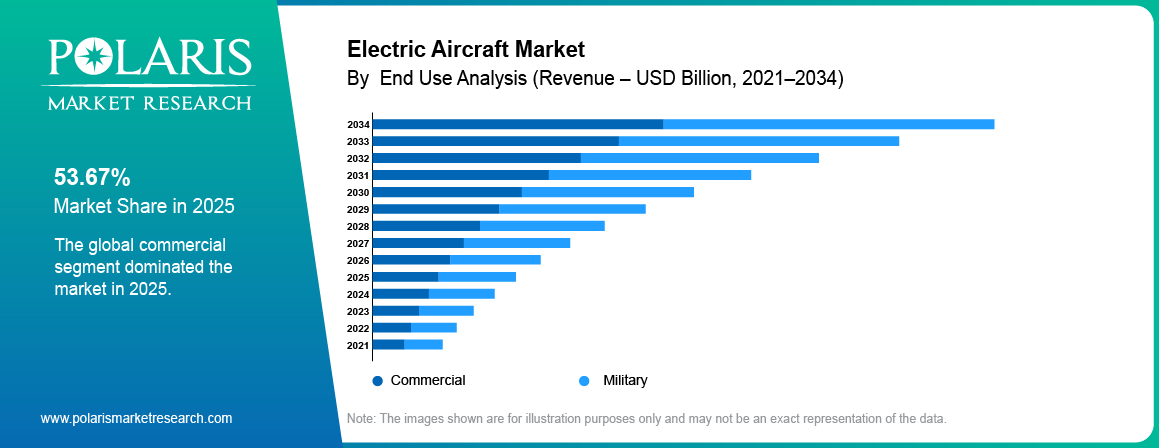
- Commercial segment dominated with largest share of 53.67% in 2025 as air-taxi operators move from pilot programs toward scheduled, revenue-generating services
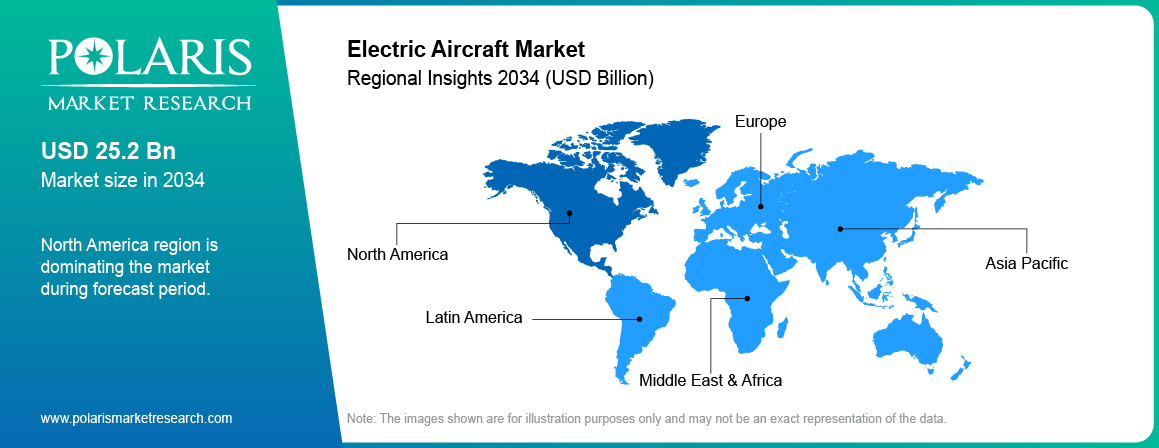
- North America dominated the electric aircraft market share of 44.31% in 2025. This growth is driven by strong funding, active investment from aerospace and technology companies, and steady progress in FAA approvals
- Asia Pacific is expected to witness fastest growth of CAGR 20.3% during the forecast period driven by government support in the region
- Europe is expected to witness growth of CAGR 17.1% during the forecast period driven by strong government efforts to reduce emissions
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is Electric Aircraft?
Electric aircraft are aircraft that use some or all of their power from stored or generated electricity instead of burning fossil fuels. They use electric motors instead of traditional turbine or piston engines. These motors can get power from batteries, hydrogen fuel cells, or a mix of both. This change affects almost every part of the aircraft. It changes how the aircraft produces lift and thrusts. It also changes how it is charged, maintained, and approved for flight.
The market covers several types of aircraft. Fixed-wing aircraft work much like traditional small planes. However, they use electric power instead of fuel. They are mainly suited to short flights and training, where lower running costs are important. Rotary-wing and vertical-takeoff-and-landing aircraft, often called eVTOLs, are designed for short trips in busy cities. They can take off and land without a runway. Hybrid-wing aircraft sit between these two types. They use a fuel engine or fuel cell along with electric power. This helps them fly longer than current batteries can support on their own.
How Electric Aircraft Works?
- The aircraft batteries store electrical energy needed for flight.
- Power electronics regulate the electricity before sending it to the motor.
- The motor converts electrical energy into mechanical power.
- The motor turns the propeller, which pushes air backward.
- The moving air creates thrust that propels the aircraft forward.
- The wings generate lift, allowing the aircraft to take off, climb, cruise, and land.
Electric Aircraft vs Traditional Aircraft
| Factor | Electric Aircraft (incl. eVTOL / hybrid-electric) | Traditional Aircraft (turboprop / jet) |
| Development cost (program-level) | Often $0.5–2+ billion for certified eVTOL/regional programs; heavy spend on batteries, flight controls, and certification. | $2–10+ billion for new narrowbody/regional jets; mature supply chains and certification playbooks. |
| Battery / energy system cost share | Battery packs and thermal management can be 30–50%+ of airframe cost in early generations. | Fuel system and engines are significant but amortized over long production runs; fuel is operating cost, not capex. |
| Propulsion efficiency (tank/well-to-wake) | Electric motors >90% efficient; overall aircraft efficiency limited by battery energy density and weight. | Gas turbines ~30–40% thermal efficiency; high energy density fuel enables long range and high payload. |
| Energy density (current tech) | Li-ion packs ~250–300 Wh/kg (cell); pack-level lower; targets 400–500+ Wh/kg by 2030–2035 for larger aircraft. | Jet fuel ~12,000 Wh/kg (chemical); mature infrastructure. |
| Operating cost (fuel/energy + maintenance) | Studies show 50–90% lower fuel/energy cost and ~30–50% lower maintenance in some concepts; but higher CASK in early generations due to battery replacement and lower utilization. | Fuel is major OPEX; maintenance well-understood; CASK typically $0.20–0.45/ASK for conventional regional/narrowbody. |
| Range / mission profile | Today: mostly <250–400 km for pure electric; hybrid-electric regional concepts target 400–800+ km. | Regional jets: 1,000–3,000+ km; narrowbodies 3,000–6,000+ km. |
| Infrastructure needs | Requires charging/energy management at vertiports/airfields; grid upgrades may be needed for high-throughput hubs. | Mature global fueling, MRO, and airport infrastructure. |
| Noise & emissions (local) | Much lower local noise and zero in-flight CO₂ (depending on grid mix for electricity). | Higher noise and direct CO₂/NOₓ emissions. |
| Certification complexity | New categories (e.g., FAA powered-lift, EASA SC-VTOL); evolving rules for batteries, distributed propulsion, and autonomy. | Mature certification bases (Part 23/25/27/29); well-understood compliance paths. |
Source: Polaris Market Research Analysis
Market Dynamics
Driver : Sustainability Pressure Is Changing Aviation's Traditional Choice
Airlines, regulators, and city governments are focusing on jet fuel alternative as a long-term solution. This is driven by rising concern regarding environmental impact, high cost of the fuel and health hazards. Electric power directly addresses this concern. It produces no direct emissions during flight. It further creates much less noise than traditional aircraft. This makes electric aircraft more suitable for flying over busy cities and residential areas. These environmental and noise benefits are now becoming part of buying decisions and airport rules. This gives electric aircraft an advantage as older aircraft are replaced with newer fleets, thereby driving the market growth.
Driver : Urban Air Mobility Is Moving from Idea to Real Service
The growth of urban air mobility solution is rising. Vertiports are being built in several cities around the world. For instance, in August 2026, VDX in Dubai received regulatory certification for electric vertical takeoff and landing operations. Operators are also announcing launch plans instead of only sharing long-term visions. Electric aircraft support this transition by offering lowering emission, noise and by supporting vertical takeoffs. Electric aircraft further offer lower operating costs, thereby driving the electric aircraft market (Source: newatlas.com).
Restraint : High Initial Costs and Long Approval Times Still Slow Growth
Battery systems, specially designed motors, and large flight-testing programs make electric aircraft expensive to develop. They also take more time to approve than traditional small aircraft. Charging stations and vertiports are also still being built in different cities. There is no common system across most countries yet. At the same time, aviation regulators are dealing with new safety and approval questions. Many of these concerns are yet to address, which delay the development process and limits its adoption, thereby restraining the electric aircraft industry growth.
Opportunities : Growing Government Approval
Government-backed test programs and the first full aircraft and operating approvals are supporting industry to develop commercial service. Companies operating in the market are now focusing product launch to capture the market share early. Every approval reduces concerns among regulators, airport operators, and investors. This includes new operating licenses, new pilot-program cities, and the first commercial passenger flights. Therefore, growing government approvals are creating opportunities for aircraft manufacturers for market entry, thereby expanding the industry growth.
Opportunities : Partnerships and Investment are Helping Companies Increase Production
Large aerospace and automotive companies are strategically collaborating and partnering for production of the aircraft at a large scale. Emerging players are further investing in manufacturing facilities for faster production of the electric aircrafts. For instance, in July 2026, Electra, an hybrid electric aircraft startup, announced investment of USD 850 million to build manufacturing unit in Ohio U.S, with supporting investments by Honeywell and Safran. The facility will focus on assembling its nine-passenger hybrid-electric aircraft. Such investment gives electric aircraft companies access to better production systems and quality controls. It further gives them a clearer path from small numbers of handmade aircraft to larger fleet production. For established companies, these partnerships provide an early position in a new market (Source: reuters.com).
Segment Analysis
By Technology Assessment: Vertical Takeoff and Landing (VTOL)
VTOL platforms dominated with largest share of 61.10% in 2025. Their ability to take off and land without a runway makes them particularly suitable for point-to-point urban air-taxi services. This capability further supports other applications, including medical evacuation, cargo delivery in congested or infrastructure-limited areas, military reconnaissance, and disaster response. The segment is expected to grow over conventional and short-takeoff aircraft as certification programs progress and commercial VTOL routes begin operations across major markets. Moreover, growing investment in vertiports and urban air mobility infrastructure is further expected to support further adoption.
By End Use Assessment: Commercial
Commercial segment dominated with largest share of 53.67% in 2025 as air-taxi operators move from pilot programs toward scheduled, revenue-generating services. Several factors are supporting this transition, including lower operating costs per passenger compared with helicopters, stronger government support for sustainable aviation, and increased investment in infrastructure for urban air mobility. Additionally, rising investment is vertiports and urban air mobility solutions are further driving the demand, thereby driving the segment growth.
Regional Insights
North America dominated the electric aircraft market share of 44.31% in 2025. This growth is driven by strong funding, active investment from aerospace and technology companies, and steady progress in FAA approvals. Aircraft certifications, test flights, and pilot programs are taking place more frequently in the region. Partnerships between aircraft developers and major aerospace companies are further helping address production challenges. These partnerships are allowing companies to move from prototype development toward larger-scale manufacturing. Moreover, government-backed early-service programs are further supporting the market by allowing companies to begin limited operations while they work toward full aircraft certification, thereby driving the regional growth.
Asia Pacific
Asia Pacific is expected to witness fastest growth of CAGR 20.3% during the forecast period driven by government support in the region. China is leading the market with strong investment and faster approval of air-taxi services. Other countries, such as Japan, South Korea, and Singapore, are also developing electric aircraft programs. Large cities are creating demand for faster short-distance travel. Growing investment in landing areas and charging systems is supporting this demand. Partnerships between local companies and major aircraft makers are further helping the market move from testing toward commercial use.
Europe
Europe is expected to witness growth of CAGR 17.1% during the forecast period driven by strong government efforts to reduce emissions. Many countries are funding cleaner aviation projects. Major aircraft makers are further investing in electric and hybrid aircraft. This is fueling the market growth. Demand for cleaner and quieter air travel is further increasing. Urban air mobility is creating new opportunities for short-distance flights. Cities are further investing in charging points and landing areas. Europe already has a strong aviation industry. This gives electric aircraft companies access to skilled workers, technology, and established industry networks, thereby driving the industry growth.
Middle East and Africa
The Middle East and Africa market is expected to witness significant growth of CAGR 17.3% during the forecast period due to rising investment in new aviation technologies. Gulf countries are leading this growth. They are investing in air taxis and related infrastructure. Government support is further driving the growth of the industry. The region is focused on smart cities, tourism, and aviation growth. These areas can create demand for electric aircraft. Partnerships with global aircraft companies are also supporting market development. In Africa, demand is mainly linked to medical transport and cargo delivery.
Regulatory Framework: By Key Region
| Regulator | Core Framework / Rule | What It Covers (electric/eVTOL relevance) | Current Status / Notes |
| FAA (USA) | Part 21.17(b) – Special Class; AC 21.17-4 (Powered-Lift) | Type certification for powered-lift/eVTOL up to 12,500 lb and ≤6 seats (initial focus); includes battery safety, flight control, emergency performance. | FAA and EASA aligning on powered-lift approach; multiple eVTOLs in final certification stages (TIA, flight testing). |
| FAA (USA) | Part 135 (Air Carrier) | Commercial passenger/cargo operations (air taxi, on-demand); operator certification, maintenance, crew, and safety management. | Required for commercial eVTOL air taxi services in the U.S. |
| EASA (EU) | SC-VTOL (Special Condition for VTOL) | Dedicated airworthiness standard for VTOL with Basic and Enhanced categories (the latter for commercial passenger ops over congested areas). | Basis for European eVTOL type certificates; harmonizing with FAA on key safety expectations. |
| CAAC (China) | Type certification under Chinese airworthiness rules; EH216-S certified for autonomous passenger flights. | First full type certificate for an eVTOL globally (EHang), enabling limited commercial operations subject to local approvals. | China is ahead on formal eVTOL type certification; Western authorities still in testing phases. |
| UK CAA | SC VTOL (aligned with EASA approach) | Similar to EASA SC-VTOL for UK-registered eVTOL operations. | Used for UK-specific approvals and test corridors. |
| ICAO / Global | Guidance on harmonization of eVTOL rules; cross-border recognition of type certificates and operations. | Long-term goal: consistent safety and operational standards to enable international eVTOL services. | Still evolving; most commercial ops initially domestic/regional. |
Source: Polaris Market Research Analysis
Competitive Landscape
Competition in the electric aircraft market has increased significantly over the past years. The focus is also shifting from prototype development to commercial deployment. Companies are now competing to achieve aircraft certification and begin revenue-generating operations ahead of their rivals. Access to capital has become a major competitive factor alongside technology. Developers with strong funding and established manufacturing partners are gaining an advantage, while financially weaker companies have faced insolvency or asset sales. Partnerships with major aerospace and automotive companies are also becoming increasingly important. These relationships provide access to manufacturing capacity, supply chains, and production expertise needed for large-scale fleet deployment. Regulatory approvals are creating another competitive advantage. Early approvals in markets such as China and the Gulf states are allowing leading developers to enter commercial operations sooner. This early lead may make it more difficult for later entrants to gain market share.
Vendor Positioning
| Vendor | Primary Electric Aircraft Focus | Certification / Program Status (2026) | Strategic Positioning / Notes |
| AeroVironment, Inc. | Mostly unmanned systems / defense; limited direct civil electric aircraft. | Not a leading civil eVTOL cert candidate. | Strong in defense UAVs; less central to civil air taxi/regional electric market. |
| Airbus | eVTOL (CityAirbus concepts), hybrid/electric regional, technology demonstrators. | Multiple tech demos; no certified civil eVTOL yet; heavy R&D in electrification/hydrogen. | Incumbent OEM leveraging scale, supply chain, and certification expertise; long-term play. |
| Archer Aviation | 4–6 seat eVTOL (“Midnight”) for urban air taxi. | FAA Phase 3 closed, in TIA/testing; targeting TC ~2026–2027; LA28 Olympics anchor. | Well-funded, strong airline/auto partners (United, Stellantis, Boeing stake); focused on U.S. urban routes. |
| Beta Technologies | Fixed-wing eVTOL (ALIA) for cargo and passenger; conventional STOL electric. | FAA G-1 / pre-TIA for CX300; progressing through requirements definition. | Emphasis on cargo and regional “Direct Aviation”; strong U.S. defense/cargo partnerships. |
| Boeing | eVTOL via Wisk Aero (autonomous air taxi), electric/hybrid research. | Wisk in advanced testing; no FAA type certificate yet; Boeing taking stake in Archer. | Portfolio approach: Wisk for autonomous air taxi, investments in Archer; leveraging certification and manufacturing depth. |
| EHang | Autonomous 2-seat eVTOL (EH216-S) for urban air mobility. | CAAC type certified; limited commercial operations in China; EASA/FAA processes ongoing. | First globally certified eVTOL; strong in China, expanding internationally via partnerships. |
| Elbit Systems Ltd. | Defense UAVs, some electric/hybrid concepts; not a primary civil eVTOL player. | No major civil eVTOL certification program public. | Focused on defense and homeland security; peripheral to civil electric aircraft market. |
| Eviation Aircraft | 9-seat all-electric regional (Alice). | Flight testing ongoing; certification path with FAA/EASA; targeting late-2020s entry. | Pure-electric regional niche; aims to disrupt short-haul regional airlines if battery/range targets met. |
| Heart Aerospace | 30–36 seat hybrid-electric regional (ES-30/ES-36). | Development and partner agreements (e.g., JSX); targeting first flight ~2028, service ~2031. | Bridges electric and conventional regional markets; attractive to airlines seeking lower emissions with existing route structures. |
| Joby Aviation | 4–5 seat eVTOL (S4) for air taxi and military use. | FAA Stage 5 (TIA); first conforming aircraft flying; TC expected ~2026–2027; EASA application in progress. | Leading Western eVTOL candidate; strong airline (Delta, United) and defense (USAF) partnerships; vertical integration of manufacturing and operations. |
| MagniX | Electric propulsion systems (motors) for aircraft; not an airframe OEM. | Supplies motors to multiple electric aircraft programs; no type certificate as an aircraft manufacturer. | Key enabler for electrification; positioned as a component supplier rather than operator. |
| Pipistrel (Textron eAviation) | Light electric/trainer aircraft (e.g., Velis Electro), eVTOL concepts. | Velis Electro certified (EASA) as electric trainer; expanding electric portfolio under Textron. | Strong in training and GA segments; leverages Textron’s certification and distribution network. |
| Vertical Aerospace | eVTOL (VA-X4) for urban and regional air mobility. | In certification testing with FAA/EASA; partnerships with airlines (e.g., British Airways, United). | Airline-backed model; targeting scheduled urban/regional services with established carrier partners. |
| Volocopter | Multi-rotor eVTOL (VoloCity, VoloRegion) for urban air taxi. | Advanced certification work with EASA; commercial service plans in multiple cities. | Early mover in European UAM; focus on city-by-city rollout with local regulators and operators. |
| Wisk Aero | Autonomous 4-seat eVTOL (Boeing-backed). | Advanced flight testing; no FAA type certificate yet; close Boeing integration. | Autonomous-first strategy; benefits from Boeing’s certification and safety culture. |
| XTI Aircraft Company | Hybrid-electric tiltrotor concepts (e.g., XTI 400). | Early-stage development; no advanced certification milestone public. | Niche tiltrotor concept; longer-term, higher-risk positioning vs pure eVTOL players. |
Source: Polaris Market Research Analysis
List of Key Companies
- AeroVironment, Inc.
- Airbus
- Archer Aviation
- Beta Technologies
- Boeing
- Ehang
- Elbit Systems Ltd.
- Eviation Aircraft
- Heart Aerospace
- Joby Aviation
- MagniX
- Pipistrel (Textron eAviation)
- Vertical Aerospace
- Volocopter
- Wisk Aero
- XTI Aircraft Company
Industry Developments
- October 2026: Colorado-based Bye Aerospace successfully test-flew its eFlyer 2, an all-electric aircraft designed primarily for flight schools. The company said the plane could cut operating costs significantly, while ongoing FAA testing will determine when production can begin. (Source: cbsnews.com)
- September 2026, Heart Aerospace unveiled its redesigned 36-seat hybrid-electric ES-36 regional aircraft and secured a 50-plane purchase commitment from JSX. The company targeted a first flight in late 2028 and entry into service by 2031 after FAA certification, promising 40%lower operating costs than conventional regional jets. (Source: infra.economictimes.indiatimes.com)
- July 2026: NASA and GE Aerospace demonstrated a megawatt-class hybrid-electric aircraft system aboard a modified Saab 340B at the Farnborough International Airshow. The technology completed historic high-altitude flights and aimed to reduce fuel consumption and operating costs for future regional aircraft. (Source: nasa.gov)
Electric Aircraft Market Segmentation
By Type Outlook (Revenue – USD Billion, 2021–2034)
- Rotary Wing
- Fixed Wing
- Hybrid Wing
By Component Outlook (Revenue – USD Billion, 2021–2034)
- Aerostructures
- Avionics
- Batteries
- Motors
- Others
By Technology Outlook (Revenue – USD Billion, 2021–2034)
- Conventional Takeoff and Landing (CTOL)
- Vertical Takeoff and Landing (VTOL)
- Short Takeoff and Landing (STOL)
By End Use Outlook (Revenue – USD Billion, 2021–2034)
- Military
- Commercial
By Regional Outlook (Revenue – USD Billion, 2021–2034)
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of the Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Electric Aircraft Report Scope
| Report Attributes | Details |
| Market size value in 2025 | USD 14.99 billion |
| Market size value in 2026 | USD 17.59 billion |
| Revenue forecast in 2034 | USD 65.01 billion |
| CAGR | 17.8% from 2026 - 2034 |
| Base year | 2025 |
| Historical data | 2021 - 2024 |
| Forecast period | 2026 - 2034 |
| Quantitative units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Segments covered | By Type, By Component, By Technology, By End Use |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Customization | Report customization as per your requirements with respect to countries, region, and segmentation. |
Source: Polaris Market Research Analysis
Electric Aircraft Market FAQ's
The market was valued at USD 14.99 billion in 2025 and is expected to reach USD 65.01 billion by 2034
The market is expected to witness growth of CAGR 17.8% during the forecast period of 2026 – 2034.
North America dominated with largest share of 44.31% in 2025 due to presence of major companies and government support.
An electric aircraft is an aircraft that generates thrust using electric motors powered by batteries, hydrogen fuel cells, or a hybrid combination of the two, instead of a conventional combustion engine. The category ranges from fixed-wing light aircraft to vertical-takeoff eVTOL air taxis and hybrid-wing designs with extended range.
Growth is driven primarily by sustainability and noise-reduction pressure on the aviation sector, combined with the rapid maturation of urban air mobility from a concept into a bookable transportation category. Regulatory approvals and OEM manufacturing partnerships are reinforcing that momentum by lowering both certification risk and production-cost barriers.
Vertical takeoff and landing (VTOL) platforms are leading growth, since their ability to operate without runway infrastructure is what makes urban air-taxi, medical evacuation, and last-mile cargo use cases viable.
Leading companies include Airbus, Boeing, Joby Aviation, Archer Aviation, EHang, Beta Technologies, Vertical Aerospace, Volocopter, Wisk Aero, Heart Aerospace, and Elbit Systems, among others. See the Competitive Landscape section for the full updated list.
eVTOL aircraft take off and land vertically, like a helicopter, which lets them operate from small urban pads without a runway. Fixed-wing electric aircraft take off and land conventionally on a runway and are generally used for longer, point-to-point regional or training routes where runway access isn't a constraint.
The market is moving from a test-and-certification phase into early commercial service. Several developers now hold type, production, or operating certificates and have launched limited paying-passenger or pilot-program routes, though industry-wide profitability and fleet-scale operations remain a work in progress.
Download Sample Report of Electric Aircraft Market
Please fill out the form to request a customized copy of the research report.


