Electric Vehicles Battery Recycling Market Size, Share, Trends and Forecast, 2026–2034
REPORT DETAILS
Electric Vehicles Battery Recycling Market Summary
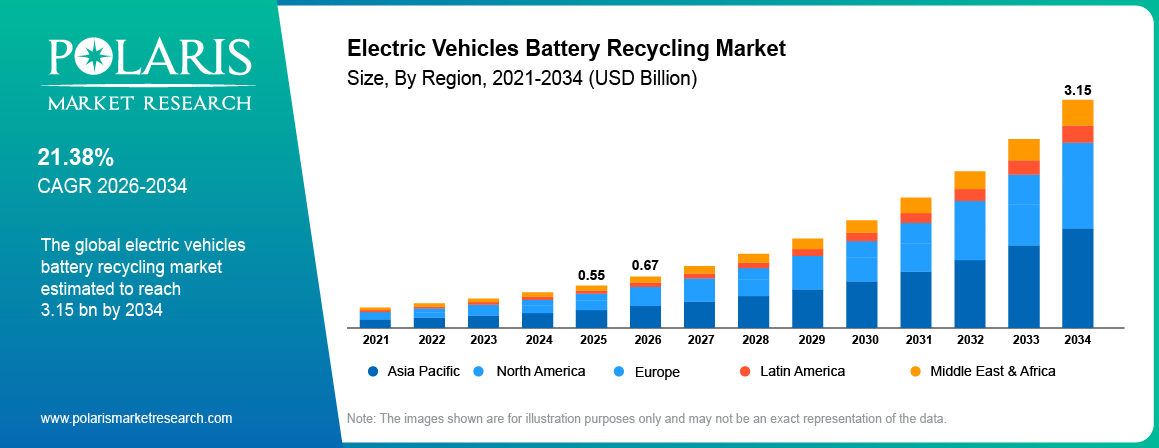
The global electric vehicle battery recycling market size was valued at USD 0.55 billion in 2025. The EV battery recycling market forecast 2034 CAGR is projected to be 21.38%. The rising global production of electric vehicles (EVs) has created the need for battery recycling to manage end-of-life batteries responsibly. Rising environmental regulations and sustainability goals are also having a favorable impact on the EV battery recycling market size.
Market Statistics
Key Takeaways
- Asia Pacific is the leading region in the electric vehicle battery recycling market, accounting for 61.66%. Asia Pacific's dominance is driven by the increasing popularity of electric two-wheelers in India and the strong manufacturing sector in China.
- North America is anticipated to register rapid growth at an 22.6% CAGR. The increasing adoption of electric vehicles in both the U.S. and Canada fuels the regional EV battery recycling market growth.
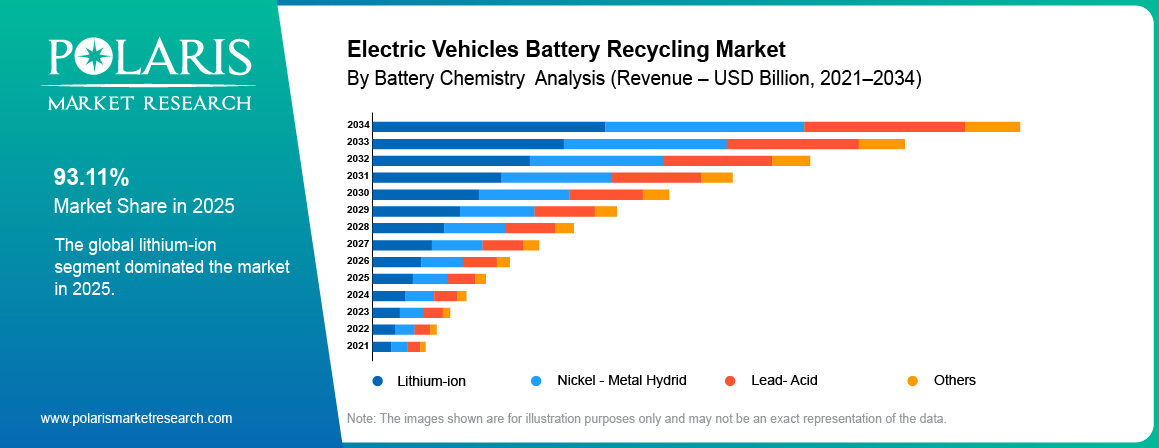
- By battery chemistry, the lithium-ion segment accounted for 93.11% of the share in 2025. The reason behind this is that lithium-ion is the predominant battery chemistry in all types of vehicles.
- By source, the EV-production scrap segment held an 38.5% share in 2025. The rapid battery manufacturing across major economies has generated an immediate volume of factory waste.
- By recycling process, the direct/mechanical segment is projected to grow at an 22.4% CAGR. This is because direct regeneration preserves the cathode structure and provides cost advantages.
- By vehicle type, the two-wheeler segment is anticipated to grow at an 23.7% CAGR. The high electric two-wheeler sales in Asia have resulted in rapid retirement cycles.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is EV Battery Recycling?
Battery recycling for electric vehicles is the method whereby batteries of EVs are collected and recycled through various processes aimed at separating the parts of such batteries. The materials separated through the processes include lithium, nickel, cobalt, manganese, copper, and graphite. These recovered materials can be used to manufacture new batteries. Battery recycling for EVs can help reduce the need for newly mined resources.
How Does EV Battery Recycling Work?
The EV battery recycling process steps depend on the type of battery, the state of the battery, and the recycling method used. These stages involve preparing the battery to be handled properly and having its components extracted. This process typically follows seven steps.
Collection: Used batteries are obtained from automobile manufacturers, repair shops, dealers, and end-of-life vehicles.
Safety Inspection: Workers inspect the battery for any sign of damage, leakage, and other safety hazards.
Discharge: The battery is discharged in order to minimize chances of electrocution, short-circuit, and fire hazards during the processing stage.
Dismantling: Workers dismantle the battery and take out the battery’s components, including modules, cells, wiring, and housing.
Separation and Black Mass: The cells are further separated into small components, and the materials are separated and then converted to fine powder; this powder is referred to as black mass.
Metal Recovery: Through chemical process and/or high temperatures, recyclers extract metals like lithium, nickel, and cobalt from black mass.
Reuse in Cell Manufacturing: Extracted metals are then processed for use as raw materials in manufacturing new cells if they are of satisfactory quality.
EV Battery Recycling vs Battery Disposal
The difference between EV battery recycling vs disposal comes down to how battery materials are used after their useful life ends. Battery recycling allows for reuse of valuable metals for the production of new batteries. Disposing of batteries outside the recommended channels is likely to waste resources and risk the environment and health. The two approaches also differ in cost and regulatory compliance.
| Dimension | Recycling | Disposal Outside Certified Channels |
| Environmental impact | Controlled handling of hazardous electrolytes and metals; reduces new mining | Fire (thermal-runaway) and toxic-leaching risk |
| Material recovery | Recovers lithium, cobalt, nickel, copper, and other materials. EU targets for 2031 require 95% recovery of cobalt, copper, and nickel, and 80% for lithium. | Valuable materials are lost when batteries are discarded without recovery |
| Waste reduction | Cuts hazardous waste volume and feeds materials back into supply | Adds to hazardous waste volume |
| Cost | Processing costs are estimated at USD 1–3/kg of battery material and may be offset by recovered-material value and compliance requirements. | May avoid immediate recycling costs but can lead to regulatory penalties for non-compliance with applicable battery collection and recycling requirements |
| Supply security | Provides a secondary source of battery materials and can reduce reliance on concentrated mining and refining supply chains. | Does not recover materials for reuse, leaving manufacturers dependent on other sources |
| Resource conservation and sustainability | Closed-loop, circular | Linear, single use |
Source: Polaris Market Research Analysis
Electric Vehicle Battery Recycling Market Dynamics
Driver: Rise in Electric Vehicle Adoption
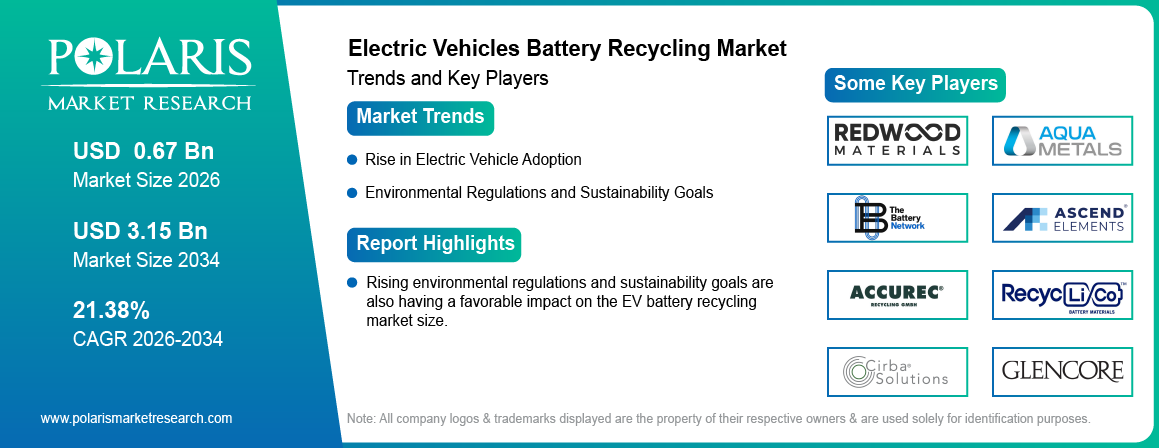
With the increasing sale of electric vehicles, there is a growing number of batteries that will soon need to be recycled. Most of the batteries used by EVs last several years, but increased sales of vehicles are creating a future supply of batteries for recycling. Recycling companies have started to increase their recycling capacity and improve recovery techniques. Recovered lithium, nickel, and cobalt can then be used in making more batteries. This can help lower the need for newly mined materials.
Driver: Environmental Regulations and Sustainability Goals
Battery recycling legislation is forcing manufacturers to enhance their collection and recycling processes. The EU Batteries Regulation contains provisions on recycling performance and recycling rates, such as an 80% lithium recycling rate provision by 2031. In September 2026, the European Commission stated that the current recovery targets are still relevant, thus highlighting the need to invest in battery recycling infrastructure (source: europa.eu). Battery recycling requirements help develop a circular economy EV batteries supply chain.
Driver: Critical-Mineral Supply Security
Battery recycling provides manufacturers with additional sources of lithium, nickel, and cobalt. Their extraction from old batteries could lessen the reliance on mining and refining activities conducted in a few selected countries. In May 2026, the EU and India initiated a €15.2 million project aimed at improving EV battery recycling technologies. This includes highly efficient material recovery along with the creation of a pilot recycling facility in India. The initiative links recycling research with efforts to secure critical raw materials for future battery production (source: pib.gov.in).
Driver: Closed-Loop OEM Commitments
Some automakers have begun using recycled battery materials in vehicle production. Through this process, the manufacturers gain some degree of control over their material supply chain, as well as reduced dependence on mining of fresh materials. In September 2026, a recycling pilot project carried out by General Motors Company and its partners was completed. The recycled materials from end-of-life batteries were used in making new EV cells, where all the cathode active material is made of recycled nickel, cobalt, and manganese (source: gm.com). The milestone highlights how closed-loop recycling can link the used batteries with the production of new batteries.
Restraint: High Recycling Costs and Operational Barriers
For battery recycling, special machinery, safety protocols, and skilled workers are needed. Also, there is an additional cost for collecting and transporting spent batteries, especially when the recycling plants are located far from the centers where batteries are collected. The battery chemistry is another difficulty that must be considered during the recycling process. There is no cobalt or nickel in the composition of LFP batteries. This makes the value of the recovered metals low and influences the economics of LFP battery recycling. Recyclers must rely on lithium recovery and efficient processing to improve returns. The lack of uniform regulation across regions poses additional challenges. This is because companies must meet certain requirements for battery collection, transport, and metal recovery. All these factors can make recycling less profitable.
Opportunity: Second-Life Use Before Recycling
Used EV batteries might contain usable energy even after their life in vehicles is over. These batteries can be tested and upgraded to store stationary energy. Use cases include backup energy for buildings and storage of energy from solar and wind projects. Suitability of second-life EV batteries is determined by the energy content left, quality of the battery, and costs of upgrade. Some batteries require thorough testing before reuse, while some are not worth repairing at all. Firms able to test the quality of used batteries and prepare them for new uses will have opportunities in this field. Reuse also delays recycling; therefore, firms should consider both second-life applications and eventual material recovery.
Opportunity: Emerging Markets
With increased use of electric vehicles in India and Southeast Asia, there will be greater demand for collecting and recycling of used batteries. India’s Battery Waste Management Rules stipulate that battery manufacturers should fulfill their responsibilities as per extended producer responsibility (EPR) requirements for batteries put into circulation. This necessitates the need for a collection system as well as authorized recycling facilities. Business opportunities exist in the EV battery recycling market India, as well as for companies specializing in lithium recovery and processing other battery materials. In Southeast Asia, battery recycling facilities are still in the process of development in several countries. Local partnerships will help recyclers gain access to used batteries as well as recovery pathways for these batteries.
Opportunity: OEM Closed-Loop and Take-Back Partnerships
Automobile and battery manufacturers can partner with recyclers to manage used batteries and recover material that can be reused in the manufacturing process. Through take-back programs, used batteries are directed to authorized plants rather than ending up in informal streams. Recycled lithium, nickel, and cobalt may then become a part of the battery supply chain if they meet the manufacturing standards. Thus, opportunities arise for recyclers that have long-term cooperation with vehicle manufacturers. Battery recycling is also associated with closed-loop processes which imply proper coordination of battery collection, logistics, material ownership, and quality assessment. Stellantis and Orano had earlier stated their intention to develop a battery recycling joint venture; however, the joint project was never developed. Their announcement clearly shows industry interest in partnerships, while also indicating that commercial viability remains significant when planning their recycling operations.
EU Battery Regulation: Compliance Timeline for EV Battery Recycling
The EU Battery Regulation (EU) 2023/1542 sets requirements for battery collection, recycling, material recovery, and recycled content. It also introduces digital battery passports and supply-chain due diligence obligations. Recyclers need to track these deadlines because they affect processing standards, material traceability, and demand for recovered metals. The EU Battery Regulation timeline extends from current waste-management rules to recovery targets through 2031.
EU Battery Regulation Timeline
| Date | Milestone | Relevance to Recyclers & Operators | Current Status (As of 2026) |
| 17 August 2023 | Regulation entered into force | Establishes the framework for battery recycling and circular lifecycle management. | Adopted & Active |
| 18 February 2024 | General application begins | Basic requirements and initial CE marking rules take effect. | Applicable |
| 18 August 2025 | Core framework replaces previous Directive | Replaces the old 2006 Batteries Directive; fully enforces new collection and treatment architectures. | Applicable |
| 31 December 2025 | First recycling-efficiency targets | Targets: 65% for Lithium-based; 75% for Lead-acid; 80% for Nickel-cadmium. Measured by average weight. | Enforced (Compliance data currently being generated) |
| 18 February 2026 | Carbon Footprint Declarations | Mandatory carbon tracking expands to include industrial batteries > 2 kWh. | Enforced |
| 26 July 2026 | Commission due diligence guidelines due | Formal interpretive guidelines helping companies set up sourcing policies. | Guidance Provided (Timeline shifted forward by amendments) |
| 18 August 2026 | Harmonized Labeling Requirements | Full informational labeling (chemistry, capacity, manufacturer) becomes mandatory. | Enforced |
| 18 February 2027 | Digital Battery Passport (DBP) & Removability | Mandatory unique QR-linked passports for EV, LMT, and industrial batteries > 2 kWh. Portable batteries must be end-user removable/replaceable. | Upcoming (Data systems must be unified now) |
| 18 August 2027 | Battery Due Diligence Obligations Apply | Responsible sourcing verification for cobalt, lithium, nickel, and graphite. | Postponed Deadline (Delayed 2 years by Regulation (EU) 2025/1561) |
| 31 December 2027 | Interim material-recovery targets | Recyclers must recover 90% of cobalt, copper, lead, and nickel; 50% of lithium. | Upcoming |
| 31 December 2030 | Higher recycling-efficiency targets | Targets increase to 70% for Lithium-based and 80% for Lead-acid batteries. | Upcoming |
| 18 August 2031 | Minimum recycled-content requirements | New batteries must contain mandatory minimums: 16% cobalt, 85% lead, 6% lithium, and 6% nickel. | Upcoming |
| 31 December 2031 | Higher material-recovery targets | Aggressive recovery mandates: 95% for cobalt, copper, lead, and nickel; 80% for lithium. | Upcoming |
| 18 August 2036 | Higher recycled-content requirements | Mandates step up to 26% cobalt, 85% lead, 12% lithium, and 15% nickel. | Upcoming |
Sources: EU Batteries Regulation and European Commission implementation updates.
What the 2025–2026 Changes Mean for Recyclers
The August 2025 transition brought waste-battery management and producer responsibility requirements under the new regulatory framework. Extended producer responsibility batteries rules require producers to meet applicable obligations for collection and treatment. In July 2025, the EU postponed battery due diligence obligations from August 2025 to August 2027. The Commission's guidelines were due by 26 July 2026.
The battery passport February 2027 deadline is another important milestone. EV batteries placed on the EU market must have a digital passport from 18 February 2027. Recyclers can use accessible battery information to identify battery characteristics and plan treatment, subject to their access rights. In August 2026, the Commission published a draft methodology for calculating and verifying recycled content. It remains important to distinguish draft measures from adopted legal requirements.
Recovery Targets and Recycled-Content Demand
The EU Battery Regulation recycling targets set minimum levels for recycling efficiency and recovery of specific materials. By the end of 2027, recyclers must meet 90% recovery targets for cobalt, copper, lead, and nickel, and 50% for lithium. By the end of 2031, these targets rise to 95% for the four other metals and 80% for lithium. Recycling efficiency is measured separately from the recovery of individual materials.
The EU recycled content 2031 cobalt lithium nickel requirements apply from 18 August 2031 to specified battery categories, including EV batteries. Minimum recycled content is set at 16% for cobalt, 6% for lithium, and 6% for nickel. Lead has an 85% minimum. These requirements may influence sourcing across the lithium-ion battery cathode market, as manufacturers will need verifiable recycled inputs to meet the rules. Higher thresholds apply from August 2036 for cobalt, lithium, and nickel. Battery manufacturers will therefore need verifiable recycled inputs, giving recyclers a clearer regulatory basis for supplying recovered materials.
Report Segmentation
| Segmentation Axis | Segments |
| By Battery Chemistry | Lithium-Ion · Nickel-Metal Hydride · Lead-Acid (EV Auxiliary) · Others |
| By Source | EV-Production Scrap · End-of-Life Batteries · Others |
| By Recycling Process | Hydrometallurgical · Pyrometallurgical · Direct / Mechanical · Others |
| By Vehicle Type | Two-Wheelers · Three-Wheelers · Passenger Cars · Commercial Vehicles |
| By Recovered Material | Lithium · Cobalt · Nickel · Manganese · Copper · Aluminium · Others |
| By Region | North America (U.S., Canada) · Europe (France, Germany, UK, Italy, Netherlands, Spain, Russia, Rest of Europe) · Asia Pacific (Japan, China, India, Malaysia, Indonesia, South Korea, Rest of Asia Pacific) · Latin America (Brazil, Mexico, Argentina, Rest of Latin America) · Middle East & Africa (Saudi Arabia, UAE, Israel, South Africa, Rest of Middle East & Africa) |
Source: Polaris Market Research Analysis
By Battery Chemistry
The lithium-ion segment led the electric vehicle battery recycling market with an 93.11% share in 2025. Its dominance is attributed to the extensive application of lithium-ion batteries in automobiles and electric commercial vehicles. Lithium-ion batteries consist of materials such as lithium, nickel, cobalt, copper, and aluminum, which can be recovered for industrial reuse. The value of the raw materials determines whether recycling is cost-effective and dictates the appropriate method of recovery. Battery chemistry plays an important role because it dictates the economics of the recovery process, as nickel-based and LFP batteries have different recovery economics. Battery recyclers have to adjust their methods in accordance with the chemical properties of batteries.
The lead-acid (EV auxiliary) segment is projected to grow at an 12.6% CAGR. Lead-acid batteries remain in use in electric vehicles for providing auxiliary energy for lights, control systems, and low-voltage electrical devices. Even though they are not used for driving the vehicle, they provide an additional flow of spent batteries, which needs to be collected and recycled. Existing techniques of lead recovery and available battery collection systems can facilitate the recycling process in this segment. The lead acid battery recycling market demand is influenced by number of EVs utilizing lead-acid auxiliary batteries and the efficiency of returning spent batteries to recyclers. Future volumes can be impacted by battery design modifications and the development of other low voltage energy sources.
By Source
The EV-production scrap segment held an 38.5% electric vehicle battery recycling market share in 2025. This scrap is generated during the production process of batteries. Rejected electrodes, faulty cells, and residual materials are found in this scrap. This scrap is usually easy to trace compared to batteries that have been recovered after several years of usage in vehicles. The chemistry and composition of this material might even be known prior to processing. This makes it easier to choose appropriate processing techniques. The amount of this scrap depends on the production rate of the factory. As the manufacture of batteries grows, the amount of scrap available for recycling may also increase.
The end-of-life batteries segment is projected to grow at an 24.3% CAGR. This segment covers batteries that have been taken out of the EVs because they no longer satisfy vehicle performance criteria. Age, degradation, and damage can influence when this occurs. Furthermore, there is variance depending on how the vehicle has been used. With the growing number of EVs reaching the end of their useful life cycle, there will be an increasing amount of batteries available for recycling. However, this depends on tracking batteries once they have been removed. The availability of efficient channels for collection of this waste material will determine the quantity of materials recycled.
By Recycling Process
The hydrometallurgical segment is expected to witness growth of CAGR 22.8% during the forecast period. Demand for the process is driven by the need to recycle battery-grade metals for further use in cell fabrication. Battery companies seek to find stable sources of lithium, nickel, and cobalt in order to produce more batteries. Hydrometallurgical processing helps them do this by providing recovered metal, which can be processed in accordance with manufacturing requirements. Its applicability in various forms of lithium-ion batteries further supports its market position. This method is especially applicable to the recyclers who supply battery manufacturers that require uniform material quality.
The direct/mechanical segment is projected to grow at an 22.4% CAGR. These techniques have been gaining popularity due to efforts to keep most of the value in recovered battery materials. For example, direct recycling keeps cathode materials available for restoration and reuse, while mechanical treatment assists in the separation of battery components. As manufacturers seek more efficient ways to recycle batteries while minimizing material losses, these techniques are becoming increasingly popular. The development of these processes will further be dependent upon the amount of batteries containing known chemistry and production background, as these can help in determining materials suitable for direct recycling. A greater emphasis on resource efficiency may result in the widespread application of these methods.
| Attribute | Physical pre-treatment / black mass | Pyrometallurgy | Hydrometallurgy | Direct recycling |
| What happens | Discharge, dismantling, shredding and separation into black mass | High-temperature smelting | Acid or chemical leaching and selective separation | Cathode material recovered intact by relithiation and re-sintering |
| Typical output | Black mass; copper and aluminum fractions | Metal alloy; needs further refining | Battery-grade lithium, nickel, cobalt, manganese compounds | Regenerated cathode active material |
| Feedstock tolerance | Any pack once discharged | High; chemistry-agnostic | Moderate; yield improves with known chemistry | Low; needs known, homogeneous feedstock |
| Lithium recovery | Concentrated in black mass | Generally needs additional refining | High | Preserved in the cathode structure |
| Energy profile | Low to moderate | High energy intensity | Lower energy than smelting; reagent use | Lower energy than hydrometallurgy |
Source: Polaris Market Research Analysis
By Vehicle Type
The passenger vehicles segment held an 94.59% electric vehicle battery recycling market share in 2025. Its dominance is due to the high sales volume of electric passenger cars on the market. These cars use battery packs with recyclable components and create a large recycling base from end-of-life vehicles. The growing number of electric passenger cars creates a greater volume of batteries that should be collected and recycled. Battery replacements provide a source of used packs before the vehicle reaches the end of its useful life. Automakers and battery pack makers have a direct interest in recovering materials from these packs. This helps ensure there is demand for the service as the number of electric cars increases.
The two-wheelers segment is projected to grow at an 23.7% CAGR. Electric scooters and bikes are increasingly being used as daily transport and for delivery purposes, especially in the Asian region. This shift is anticipated to lead to an increased number of batteries that need to be either replaced or recycled. Frequent usage by commercial firms could also reduce battery lifespan, making some of these batteries available for collection relatively earlier. In addition, battery swapping systems are yet another way for the recycling industry to access second-hand batteries since batteries end up back at the respective battery swap stations instead of being kept by their respective owners. The system makes battery recycling easier. As e-two-wheeler sales rise, recyclers will have access to more batteries.
By Recovered Material
The lithium segment held an 35.6% electric vehicle battery recycling market share in 2025. The demand for recycled lithium is linked to its use in manufacturing rechargeable batteries. Battery manufacturers require lithium compounds in sufficient amounts for the manufacturing of cells. Recycling provides additional raw materials from old batteries and manufacturing waste. The increased use of lithium iron phosphate batteries makes it necessary for lithium recovery. These batteries do not contain either nickel or cobalt. Better extraction and refining techniques will assist recyclers in obtaining lithium that can be processed for future use in batteries.
The nickel segment is projected to grow at an 20.7% CAGR. Nickel remains an integral part of many lithium-ion battery technologies used in electric vehicles, with nickel-rich cathodes enabling maximum energy storage. Nickel can thus be recovered from these batteries during their recycling process when they reach the end of their lifecycle. The demand will be partly determined by the choice of battery technology by the car manufacturers, as some do not make use of nickel in their batteries. Growth in the production of nickel-rich batteries can increase the amount of nickel-containing scrap and used batteries available for recycling.
Critical mineral recovery (lithium, cobalt, nickel) helps return valuable materials from used EV batteries to the cell supply chain. Other recovered materials also serve important manufacturing functions.
| Recovered Material | Role in Cell Supply |
| Lithium | A key battery raw material for cathode production in lithium-ion cells. Recovered lithium can be refined into compounds used in new batteries. |
| Cobalt | Used in cathodes such as nickel-manganese-cobalt (NMC). Recycled cobalt can replace part of the primary material used in cathode manufacturing. |
| Nickel | Added to several cathode chemistries to increase energy density. Its recovery helps supply manufacturers producing nickel-rich cells. |
| Manganese | Present in NMC and lithium manganese oxide cathodes. Manganese plays a role in the formation of cathode chemistry and performance. |
| Copper | Recycled copper can be treated and used as anode current collectors. |
| Aluminum | Aluminum from battery foils and cases can be recycled for use in industrial processes. |
| Others | Graphite may be recovered for anode use after suitable processing. Steel, plastics, and other materials can enter separate recycling streams. |
Source: Polaris Market Research Analysis
Regional Insights
Asia Pacific
Asia Pacific accounted for the largest electric vehicle battery recycling market share of 61.66% in 2025. China dominates the region because of its large EV market as well as its developed battery manufacturing industry. China has a network of companies engaged in battery collection and materials recovery. Japan and South Korea add value through the development of the battery manufacturing industries as well as material recovery. India is yet another developing market where there is an increasing uptake of EVs, which is expected to increase the supply of used batteries in the future. Regional demand will also be driven by battery manufacturers and automakers who need the recovered raw materials. Differences in recycling policies between countries will influence how quickly the Asia Pacific EV battery recycling market develops.
Europe
The Europe EV battery recycling market accounted for the second-largest share of 11.4% in 2025. This region benefits from its existing automotive industry and the presence of battery manufacturers in the region. Countries such as Germany and France are key markets since they are centers of manufacturing for electric vehicles and battery material recovery. The market development for recyclers will also be shaped by the European Union’s battery regulations, which set standards for material recovery and recycled materials. The recycling business will therefore be encouraged to take into account material recovery in its production chain. As more batteries reach the end of their lifespan, recyclers will have higher volumes of used batteries to recycle.
North America
North America is projected to witness rapid growth at an 22.6% CAGR. Recycling is directly related to the need to minimize dependence on imports of raw battery materials. Recycling represents a viable means through which automotive and battery makers can acquire the minerals lithium and nickel without relying on mining. The U.S. plays an important role in recycling as it has businesses involved in battery recycling as well as battery manufacturing. Canada offers another avenue for recycling owing to its mineral sector as well as its involvement in the production chain of batteries.
Latin America
Latin America is anticipated to grow at an 20.1% CAGR. Brazil is a key market due to the rise in electric mobility and growing concerns about battery waste. There are also lithium minerals in the region, which could facilitate investments in the battery industry. However, lithium mining and recovery from used batteries are two different processes. The growth of recycling efforts will depend on the availability of spent batteries that the local processing plants can get access to. Technical assistance from foreign recyclers will help build knowledge and use of lithium battery recycling technology. The market development process will vary in different countries based on the extent of EV uptake and recycling capacity.
Middle East & Africa
The Middle East & Africa is projected to witness an 19.2% CAGR. Market development will vary across regions. In the Middle East, development of investments in electric mobility is likely to slowly drive demand for battery recycling. Electric vehicle sectors are currently being developed in the UAE and Saudi Arabia. These countries may see demand for battery collection and processing. South Africa has a well-developed automotive industry and mineral processing facilities. This may become the basis for battery recycling. But in most countries, the market is still in its early stages. Its development will depend on the availability of collection centers and processing facilities for EV batteries.
Key Market Players & Competitive Insights
The electric vehicle battery recycling market includes businesses that recycle valuable materials from end-of-life batteries and production scraps. Industry competitiveness depends on the recovery efficiency of these companies, the scale of processing, and the quality of the recovered materials. EV battery recycling companies are also working to secure a steady supply of these materials. Access to these materials is critical to plant utilization and costs of operations. Some players concentrate on the extraction of certain metals. Others handle several steps in the recycling process. The top players compete through process innovation and recycling collaborations. Market participants also seek partnerships with battery makers and automobile manufacturers to boost their EV battery recycling market share.
| Company | Footprint | Positioning |
| Germany, Europe | Battery recycling specialist focused on recovering materials from lithium-ion and other battery chemistries. Operates dedicated recycling facilities in Germany. | |
| RecycLiCo Battery Materials Inc. | Canada, North America; international technology reach | Critical minerals recovery company developing hydrometallurgical processes for battery materials and mineral feedstocks. Focuses on producing materials suitable for reuse. |
| Aqua Metals, Inc. | United States, North America | Battery materials recycling technology developer using its water-based AquaRefining process. Focuses on recovering valuable metals from lithium-ion batteries. |
| Ascend Elements, Inc. | United States, North America; expanding presence in Europe | Battery recycling and materials company that converts used batteries and manufacturing scrap into engineered cathode materials and other battery inputs. |
| The Battery Network | United States, nationwide collection network | Battery collection and stewardship organization that connects collection points with approved recycling partners. Its role centers on collection programs rather than operating as a major EV battery materials refiner. |
| United States and Canada, North America | Battery recycling and management company handling multiple battery chemistries. Its services include collection, processing, and recovery of materials from end-of-life batteries and manufacturing scrap. | |
| Fortum Oyj (Fortum Battery Recycling) | Finland and other European markets | Battery recycling provider offering collection, pre-treatment, and hydrometallurgical recovery of materials from EV batteries and production waste. |
| Glencore plc | North America, South America, and Europe; global commercial network | Global metals and recycling group that processes battery-bearing materials and recovers metals such as cobalt, nickel, and copper. Connects recycling operations with established metal refining and marketing networks. |
| Redwood Materials, Inc. | United States, North America; expanding into Europe | Battery materials recycler that recovers critical minerals and processes them into materials for domestic battery supply chains. Also works on battery materials refining and production. |
| Umicore | Europe, with international battery materials activities | Materials technology and recycling company with established metallurgical expertise. Its battery recycling operations recover valuable metals from production scrap and end-of-life lithium-ion batteries. |
| Guangdong Brunp Recycling Technology Co., Ltd. | China, with battery supply-chain links across Asia | Battery recycling and resource recovery company associated with CATL. Connects battery collection and recycling with the production of recovered materials for the battery industry. |
| GEM Co., Ltd. | China, with joint ventures in South Korea and Indonesia | Resource recycling company with a battery lifecycle business covering battery recovery, material regeneration, reuse, and recycling. Supplies recovered materials to the battery supply chain. |
| Duesenfeld GmbH | Germany, Europe | Battery recycling technology and processing specialist focused on lithium-ion batteries. Develops processes for battery treatment and material recovery. |
| Veolia Environnement S.A. | Global, with operations across Europe and other regions | Environmental services company engaged in waste management and resource recovery operations. Its stance on battery recycling reflects its broader recycling expertise and battery-related activities. |
| Ganfeng Lithium Group Co., Ltd. | China, with international lithium industry operations | Lithium industry group with activities across the lithium value chain, including battery recycling and resource recovery. Connects recovered materials with its wider lithium and battery materials business. |
| Société Nouvelle d'Affinage des Métaux (SNAM) | France and Europe | Battery collection and recycling specialist handling end-of-life batteries. Its activities include processing batteries from electric mobility and other applications. |
| SK Tes | Global, with facilities across Asia-Pacific, Europe, and North America | Technology lifecycle services provider with battery recycling capabilities. Handles battery collection, logistics, processing, and recovery of materials such as lithium, nickel, and cobalt. |
Source: Polaris Market Research Analysis
Recent Developments
- September 2026: R3 Lithium announced the commencement of operations for the production of lithium carbonate from 100% recycled battery materials. The company stated that the production will be carried out at a commercial-scale lithium carbonate recovery facility in Covington, Georgia. (source: businesswire.com)
- September 2026: Aqua Metals, Inc. made an announcement about its entry into a letter of intent (LOI) with a leading Midwest metals recycler. The LOI is for the purchase of recovered aluminum and copper. The recovered materials will be produced at Project Headwaters, which is Aqua Metals’ planned commercial-scale lithium-ion battery recycling facility in the Midwestern United States. (source: globenewswire.com)
- September 2026: Fortum Battery Recycling and Talga entered into a memorandum of understanding with regard to testing graphite recycling technology in making battery anode materials. The collaboration is intended to test the feasibility of recycling the graphite contained in used batteries for reuse in manufacturing new battery materials. (source: fortum.com)
Future Outlook
The EV battery recycling market forecast 2034 points to continued growth owing to the increasing number of end-of-life electric vehicle batteries. Battery manufacturers could use the recycled products to supplement their supply of mined metals. However, recycling companies will need to enhance their efficiencies in recovering the batteries while at the same time ensuring affordable processing costs. The growth of the market will also depend on the availability of used batteries and the demand for recovered materials. Businesses that can supply materials for manufacturing new batteries can cater to future demand.
Research Methodology
The study of the electric vehicle battery recycling market draws on company records, industry data, regulatory documents, and interviews with market participants. Both top-down and bottom-up methods were used to estimate market size.
Secondary Research: Annual reports, investor presentations, government statistics, trade publications, and patent records were examined. Regulation (EU) 2023/1542 was also reviewed to understand battery recycling and material recovery requirements. The research focused on battery retirement volumes, recycling plant capacity, and the value of recovered materials.
Primary Research: Interviews with 23 participants across Europe, Asia Pacific, North America were conducted. Participants included battery recyclers, automakers, cell manufacturers, cathode producers, and policy specialists. Their feedback helped assess battery availability, recycling practices, and material pricing.
Market Estimates and Forecast: Market estimates were calculated using the volume of batteries available for recycling, expected recovery yields, and recovered-material prices. These figures were checked against EV fleet data and company revenues. The forecast covers 2026–2034, using 2025 as the base year. It considers EV adoption, battery chemistry, metal prices, and regulatory changes.
Scope and Validation: The study covers end-of-life EV batteries and battery manufacturing scrap. These include lithium-ion, nickel-metal hydride, and lead-acid auxiliary batteries. Estimates were compared with published industry data to identify major differences. The data cutoff was September 2026.
Electric Vehicle Battery Recycling Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 0.55 billion |
| Market Size Value in 2026 | USD 0.67 billion |
| Electric Vehicle Battery Recycling Market Forecast 2034 | USD 3.15 billion |
| CAGR | 21.38% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Electric Vehicles Battery Recycling Market FAQ's
EV battery recycling is the process of recovering usable materials from batteries removed from electric vehicles or battery production lines. It helps return valuable resources to manufacturing and reduces battery waste. The process generally covers 3 stages: collection, processing, and material recovery.
The global EV battery recycling market size was estimated at USD 0.55 billion in 2025. The EV battery recycling market forecast 2034 projects growth at a 21.38% CAGR from 2026 to 2034.
Asia Pacific led the electric vehicle battery recycling market with a 61.66% share in 2025. China’s large electric vehicle market and battery manufacturing base support regional demand for recycling and recovered materials.
Steps that are commonly part of EV battery recycling could include battery collection, battery discharging and disassembly, mechanical processing, and recycling of material components. As part of processing, there is creation of black mass, which is made up of material components of the battery that can be reused.
The pyrometallurgical segment dominated due to its high processing efficiency, ability to handle diverse battery chemistries, and established industrial infrastructure for metal recovery.
Critical minerals recovery can provide lithium, cobalt, nickel, and manganese from appropriate battery chemistry. Recovery through recycling can provide copper and aluminum as well. The recovered materials can be processed into battery-grade material for fabrication, such as feedstocks for cathode active material production.
The EU Battery Regulation recycling targets require recovery of 90% of cobalt, copper, lead, and nickel, and 50% of lithium by the end of 2027. By the end of 2031, the targets rise to 95% for the four metals and 80% for lithium.
The EU battery passport becomes mandatory on 18 February 2027 for electric vehicle batteries placed on the EU market or put into service. The digital record will provide battery-specific information to support traceability, responsible handling, and end-of-life management.
Materials can be recovered from the batteries through the process of recycling, while secondary use of the batteries of the EVs is done in other uses, where they have to be functional. This helps extend the useful life of the batteries before they are recycled.
A few of the key companies include ACCUREC-Recycling GmbH; RecycLiCo Battery Materials Inc.; Aqua Metals, Inc.; Ascend Elements, Inc.; The Battery Network; Cirba Solutions; Fortum Oyj (Fortum Battery Recycling); Glencore plc; Redwood Materials, Inc.; Umicore; Guangdong Brunp Recycling Technology Co., Ltd.; GEM Co., Ltd.; Duesenfeld GmbH; Veolia Environnement S.A.; Ganfeng Lithium Group Co., Ltd.; Société Nouvelle d'Affinage des Métaux (SNAM); and SK Tes.

Download Sample Report of Electric Vehicles Battery Recycling Market
Please fill out the form to request a customized copy of the research report.