Lithium-Ion Battery Cathode Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Lithium-Ion Battery Cathode Market Summary
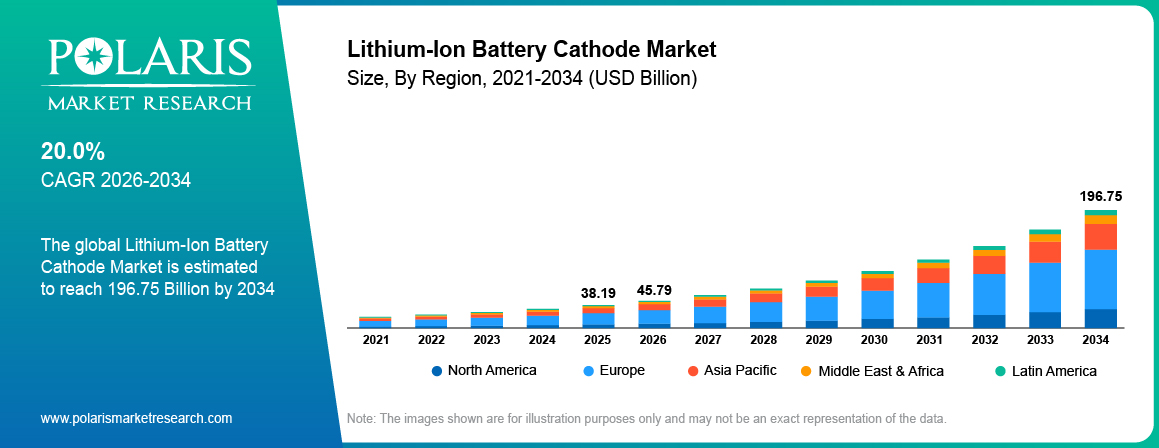
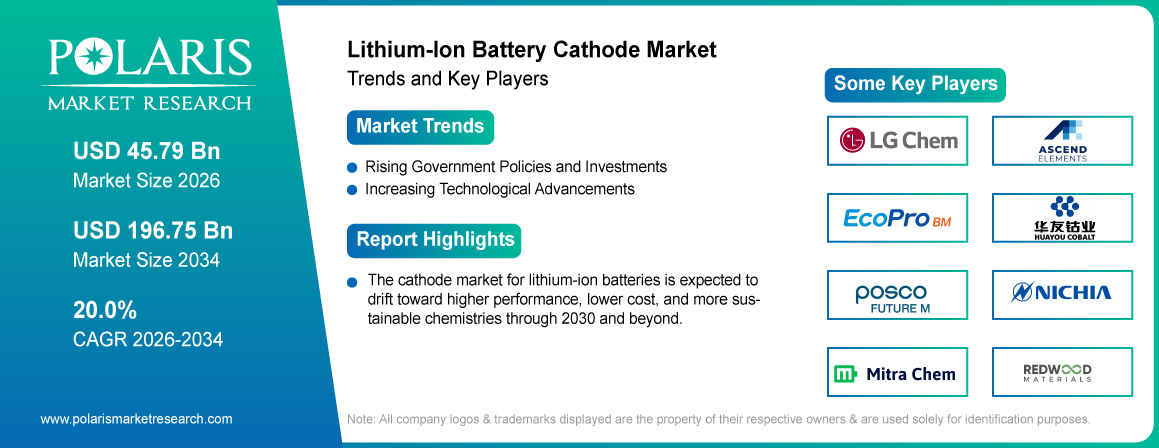
The lithium-ion battery cathode market size was valued at USD 38.19 billion in 2025. The market is projected to exhibit a CAGR of 20.0% from 2026 to 2034. Rising investments in renewable energy storage solutions propel the market growth. Increasing adoption of portable electronic devices such as smartphones, laptops, and tablets drives the market expansion.
Market Statistics
Lithium-Ion Battery Cathode Market Key Takeaways
- In 2025, Asia Pacific accounted for 57.40% market share due to its dominance in battery manufacturing.
- The North America market is expected to witness 19.80% CAGR over the forecast period due to increasing investments in domestic battery production and rising adoption of electric vehicles (EVs).
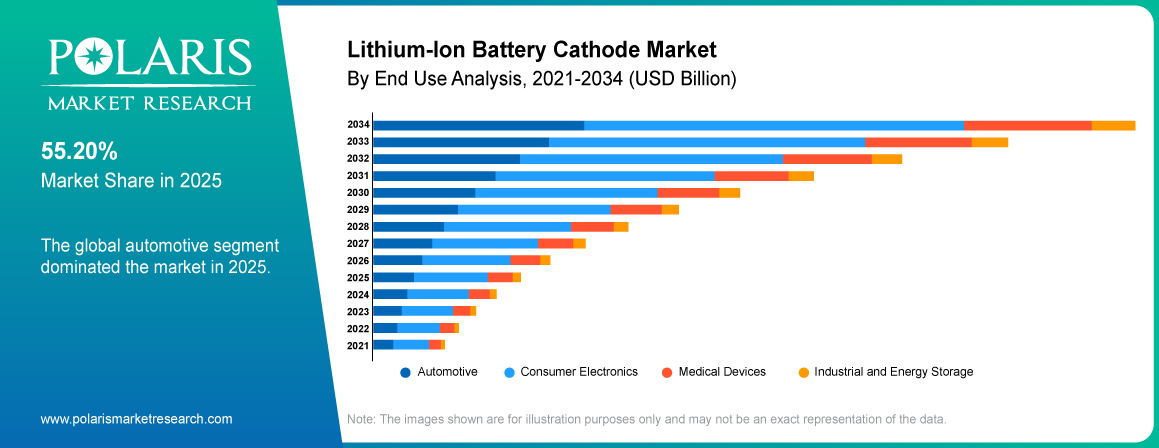
- In terms of end use, in 2025, the automotive segment accounted for 55.20% market share in the market due to rising electric vehicle production, increasing battery capacity requirements, and strong demand for high-performance cathode materials.
- The lithium manganese oxide segment, based on chemical composition, is expected to witness 16.30% growth over the forecast period due to its high thermal stability, safety features, cost-effectiveness, and extensive use in power tools.
- The cylindrical segment held the largest market share of 46.80% in 2025. This is due to its high energy density.
- The polymer segment is expected to grow at 22.40% CAGR during the forecast period due to its lightweight architecture.
- The lithium nickel manganese cobalt oxide (NMC) segment held the largest market share of 38.60% in 2025, owing to its high energy density.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is a Lithium-Ion Battery Cathode Market?
The lithium-ion battery cathode market is a part of the overall cathode material Industry. The market focuses on lithium-ion batteries and the processing of cathode materials. The cathode is one of the essential parts in the structure of a lithium-ion battery, and it has a significant influence on the energy density, cost, and power of lithium-ion batteries.
Lithium-ion batteries are essential for solar and wind energy to be stored effectively, a driver for growing market demand. In addition, the technological advancements in batteries have led to improved efficiency and lower production costs, which has also driven the market growth.
Increasing penetration of portable electronic devices, including smartphones, laptops, tablets etc., is fueling the market size. This trend may reflect increasing dependence on high-performance batteries and could be a driver for further market research.
Types of Lithium-Ion Battery Cathode Materials
| Cathode Material | Description |
| Lithium Cobalt Oxide (LCO) | LCO has a high energy density and good electrochemical stability, and thus is used in the production of smartphones, laptops and the like. However, the high cost of cobalt and the associated thermal management limit its use in large battery system |
| Lithium Manganese Oxide (LMO) | LMO offers excellent thermal stability, high power, and fairly good safety. It is employed in power tools, medical devices and some electric vehicle batteries, but the lower energy density prohibits its adoption in long-distance EV use. |
| Lithium Nickel Manganese Cobalt Oxide (NMC) | NMC is a combination of the metals nickel, manganese, and cobalt and offers high energy density, good cycle life, and balanced safety. It is prevalent among electric vehicles and continues to be a high revenue-producing cathode chemistry in 2025. |
| Lithium Iron Phosphate (LFP) | LFP offers good thermal stability, long cycle life, lower material costs and less reliance on nickel and cobalt. Its uptake has increased significantly in mainstream EVs and stationary energy storage with LFP representing c.41% of cathode-material demand in 2025 according to volume-based industry estimates. |
| Lithium Nickel Cobalt Aluminum Oxide (NCA) | NCA provides high specific energy and strong power output for applications with long driving distances and high battery capacity demand. It is used almost exclusively in a small number of high-end electric cars and some high-performance battery packs. |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
How Lithium-Ion Battery Cathodes Work?
Lithium-ion battery cathodes store and release lithium ions during charging and discharging. During charging, lithium ions flow from the cathode through the electrolyte to the anode, and electrons flow through the external circuit. During discharge, lithium ions return to the cathode, producing electric energy that drives the load or vehicle.
The cathode is usually made from lithium-based metal oxides or phosphates such as NMC, LFP, LCO, or NCA. Its chemical composition significantly impacts the energy density, voltage, safety, cycle life, charging ability, and cost of the battery. High-performance cathode materials are intended to facilitate lithium-ion transport and maintain mechanical and structural stability. They have high thermal margins. These features allow batteries to provide higher capacity, longer life, faster charging, and safer operation in automotive applications, consumer electronics, and energy storage systems.
LFP Cathode Material vs NMC Cathode Materials
| Feature | LFP (Lithium Iron Phosphate) | NMC (Nickel Manganese Cobalt) |
| Full Chemical Name | LiFePO₄ | LiNiₓMnᵧCo₁₋ₓ₋ᵧO₂ |
| Safety Rating | Very High, excellent thermal stability; no thermal runaway | High, risk increases with nickel content |
| Energy Density | Moderate: ~150–180 Wh/kg | High: ~250–300 Wh/kg (NMC 811) |
| Cost per kWh | Lower (~$80–100/kWh cell-level) | Higher (~$120–160/kWh cell-level) |
| Cycle Life | Longer: 3,000–6,000+ cycles | Moderate: 1,000–2,000 cycles |
| Cobalt Dependency | None | High (NMC 532) to Low (NMC 811) |
| EV Application | Mass-market, commercial vehicles, BESS | Premium EVs, high-range applications |
| Key Adopters | BYD (Blade), Tesla (Model 3 Standard), CATL | BMW (NMC 811 Neue Klasse), Panasonic-Tesla |
| Thermal Runaway Risk | Very low | Moderate to High (high-nickel) |
| Future Trend | Dominant in entry EV + stationary storage | Premium EV + portable electronics retention |
Source: Polaris Market Research Analysis
Market Dynamics
Driver: Rising Government Policies and Investments
Growing government policies positively impact the lithium-ion battery cathode market growth. Strategic battery gigafactory investments are being announced to build up large-scale battery manufacturing capacity. In August 2026, the U.S. Department of Energy announced USD 500 million for seven selected projects to expand domestic critical mineral processing, battery manufacturing, and recycling capacity. The funding is intended to strengthen U.S. battery supply chains, reduce reliance on foreign sources, and support domestic production of battery-grade materials, including lithium and other critical inputs used in lithium-ion battery cathodes. (Source: energy.gov) Developing resilient cathode material supply chains that are improving manufacturing capacity and supporting market expansion. In addition, specific incentives and grants for electric vehicles (EVs) and clean energy projects are increasing the demand for lithium-ion batteries and their cathode materials.
Driver: Increasing Technological Advancements
The global battery cathode materials market is experiencing growth due to technological advancements in battery cathode materials. Advances in high-performance cathode materials such as NMC, NCA, and LFP are enhancing energy density, durability, cost-effectiveness, and battery safety. Additionally, new research into sustainable cathode chemistries and enhanced manufacturing processes contributes to lower material consumption and reduced environmental impact. Researchers at the SLAC-Stanford Battery Center announced a new manufacturing method for nickel-rich layered-oxide cathodes in May 2026 that enhanced their longevity without adding chemicals or manufacturing steps. Researchers were able to create more consistent nanoscale structures that enhanced resistance to cracking and degradation by optimizing the heating process used in cathode production. Batteries made with the new cathodes retained almost 93% of their energy after 500 charge-discharge cycles. These improvements in cathode manufacturing can increase battery life without significantly increasing production costs, which in turn facilitates the growth of the lithium-ion battery cathode market (Source: 6.slac.stanford.edu).
Technology Innovation Tracker
| Technology | Status (2026) | Benefit | Key Risk / Limitation | Market Impact Timeline |
| High-Nickel NMC 811/9x1 | Commercial (BMW, Panasonic) | Higher energy density (>280 Wh/kg) | Thermal management complexity | Near-term (1–3 years) |
| Cobalt-Free NMC / LMFP | Pilot to early commercial | Eliminates cobalt supply risk; cost reduction | Energy density gap vs cobalt-NMC | Medium-term (2–4 years) |
| Solid-State Cathode Integration | R&D / limited prototype | High voltage tolerance; safer; thinner cathode | Manufacturing scale; high cost | Long-term (5+ years) |
| sodium-ion battery cathode | Early commercial (CATL 160 Wh/kg) | Abundant raw materials; no lithium needed | Lower energy density vs Li-ion | Medium-term – city cars, UPS |
| Single-Crystal NMC | Commercial (Ecopro BM) | Improved cycle life; crack resistance | Complex manufacturing | Near-term in premium EV |
| Recycled CAM from Black Mass | Commercial (Redwood Materials) | 95% metal recovery; 20% cost below virgin | Feedstock consistency; collection logistics | Growing now – regulatory pull |
Source: Polaris Market Research Analysis
Opportunity: Rising Adoption of Electric Vehicles and Expansion of Battery Manufacturing Capacity
The rising sales of electric vehicles (EVs) are fueling the demand for lithium-ion battery cathodes. Automakers are increasing their EV models and investing in EV battery plants to ensure a reliable long-term supply of cells. This growth is increasing the demand for cathode materials for EV batteries, such as lithium iron phosphate, lithium nickel manganese cobalt oxide, and lithium nickel cobalt aluminum oxide. Government agencies are also facilitating electric mobility through purchase incentives, charging infrastructure, fuel-economy standards, and domestic battery manufacturing initiatives.
At the same time, battery manufacturers are building gigafactories in the Asia Pacific, North America, and Europe. Cathode producers are taking advantage of this growth by entering into long-term supply agreements with cell manufacturers and automotive OEMs. Such strategies help them increase localized production and create advanced chemistries that deliver higher energy density, enhanced safety, extended cycle life, and lower costs. The lithium cathode recycling market is also growing as manufacturers are looking to recover valuable materials, reduce reliance on mined resources, and build circular battery supply chains. Consequently, the electrification of passenger and commercial vehicles will continue to generate long-term opportunities for cathode material suppliers and recycling companies.
Opportunity: Growing Demand for Energy Storage Systems and Advanced Cathode Chemistries
The growing adoption of renewables and grid-scale battery storage also represents yet another major demand driver for lithium-ion battery cathode producers. Solar and wind generation need energy storage systems to compensate their intermittent electricity production, to stabilize the grid and to enhance power availability. This is fueling the growth of power storage Lithium-ion batteries in large scale utility, commercial, and industrial, as well as home storage applications. Thermal stability cycles life cost advantages and suitability for stationary storage makes lithium iron phosphate battery cathode certainly the best positioned.
Companies are developing advanced cathode compositions such as manganese-rich, high-nickel, cobalt-depleted, and other advanced cathode formulas, as well as optimum anode and electrolyte materials. Developers of scalable, lower-cost, safer, and more sustainable cathode chemistries that gain traction can address expanding opportunities outside of automotive. Growth in renewable capacity, data centers, microgrids, and backup power systems will boost the market penetration in the future.
Restraints: Volatility in Lithium, Nickel, Cobalt, and Other Critical Raw Material Prices
Price volatility in critical raw materials remains a significant hindrance to the lithium-ion battery cathode market. The cathode consists of layers of processed materials such as lithium, nickel, cobalt, and manganese, whose prices fluctuate due to supply shortages, geopolitical disruptions, mining constraints, trade policies, and changes in battery demand. As a result, a sudden surge in input costs can severely impact the economics of cathode production and erode margins for manufacturers with long-term supply contracts. The concentration of mining and refining capacity in a small number of countries adds additional strain to the supply chain. Furthermore, scaling up mining and refining capacity requires significant capital outlays and lengthy permitting procedures, limiting how quickly supply can respond to demand. Producers are increasingly seeking long-term sourcing deals, recycling, chemistry diversification, and lower-cobalt formulations. However, ongoing commodity-price volatility may raise battery costs, hinder capacity expansion, and cause procurement issues at each step of the cathode value chain.
Source: Polaris Market Research Analysis
Segmental Insights
By Chemical Composition Outlook
The global lithium-ion battery cathode market segmentation, based on chemical composition, includes lithium cobalt oxide, lithium manganese oxide, lithium nickel manganese cobalt oxide, lithium iron phosphate, and lithium nickel cobalt aluminum oxide.
The lithium nickel manganese cobalt oxide (NMC) segment held the largest market share of 38.60% in 2025, driven by its high energy density, strong cycle performance, and extensive use in electric vehicle batteries. Its unique, optimized blend of nickel, manganese, and cobalt allows for longer range, higher power, and dependable performance. These features enable mass adoption in passenger and commercial electric vehicles.
The lithium manganese oxide segment is projected to experience 16.30% growth during the forecast period. This is due to its widespread use in power tools, medical devices, and hybrid electric vehicles (HEVs). Lithium manganese oxide cathodes are valued for their high thermal stability, safety, and cost-effectiveness, making them suitable for applications requiring moderate energy density. Additionally, the increasing adoption of lithium-ion batteries in industrial and energy storage solutions drives demand for LMO materials, contributing to its robust market expansion.
Cathode Chemistry Comparison
| Chemistry | Abbreviation | Key Advantage | Key Limitation | Primary Application |
| Lithium Iron Phosphate | LFP | Safety, long cycle life, low cost | Lower energy density | Mass-market EVs, BESS, e-buses |
| Lithium Nickel Manganese Cobalt | NMC | High energy density, versatile | Cobalt cost, thermal risk at high-Ni | Premium EVs, laptops, smartphones |
| Lithium Cobalt Oxide | LCO | Very high energy density | Expensive, safety concerns | Smartphones, tablets, cameras |
| Lithium Manganese Oxide | LMO | High power output, thermal stability | Lower energy density, cycle degradation | Power tools, HEVs, medical devices |
| Lithium Nickel Cobalt Aluminum | NCA | High energy density + power | Expensive, manufacturing complexity | Long-range EVs, Tesla legacy packs |
Source: Polaris Market Research Analysis
By Cell Type
The cell type segment includes cylindrical, prismatic, and polymer. The cylindrical segment led the lithium-ion battery cathode market share by holding 46.80% in 2025, owing to its high energy density, good mechanical stability, standardized design, and cost-effective mass production. The established production system and good thermal management enabled even stronger position in the market due to demand driven by the broad application in electric vehicles, consumer electronics, power tools, and energy storage systems.
The polymer segment is expected to register a 22.40% CAGR during the forecast period. This is due to its lightweight architecture, flexible form factor, high energy density, and compatibility with compact battery configurations. Increasing penetration in portable electronics, medical devices, and high-end energy storage applications is propelling segment growth. In this segment, there are constant advancements in safety, packaging efficiency, and cell design.
By End Use Outlook
The global market segmentation, based on end use, automotive, consumer electronics, medical devices, industrial and energy storage. In 2025, the automotive segment held 55.20% of the Li-ion battery cathode market share, driven by rising demand for high-energy-density batteries and growing battery manufacturing capacity. Rising automaker investments in electrification, longer driving-range requirements, and broader adoption of NMC and LFP cathode chemistries have also boosted cathode material consumption in the automotive industry.
The expanding penetration of electric vehicles (EVs) is also a key factor driving the growth of the lithium-ion battery cathode market. For instance, EV momentum is expected to expand by the end of 2026, accounting for 29% of global new-car sales, as per the International Energy Agency (IEA). The growth is supported by government incentives, charging infrastructure expansion, tougher emissions regulations, and electrification-friendly policies worldwide (Source:iea.org).
The industrial and energy storage segment is expected to witness growth at a CAGR of 24.10% during the forecast period. This is due to growing deployments of grid-scale battery storage, renewable energy integration, and escalating demands for dependable backup power. Growing investments in solar and wind projects are driving the demand for lithium-ion batteries to manage intermittency and maintain grid stability. Battery energy storage systems (BESS), meanwhile, are also seeing uptake at industrial companies, data centers, utilities, and commercial buildings, to reduce peak demand charges and bolster energy reliability.
End-Use Segment Comparison (Market Share & Growth Profile)
| End-Use Segment | Est. 2025 Share | Key Driver | Dominant Chemistry | Growth Outlook |
| Consumer Electronics | 18.10% | Smartphones, laptops, wearables, AI devices | LCO, NMC | Steady – AI/IoT feature density driving battery upgrades |
| Automotive / EVs | 55.20% | EV adoption, fleet electrification | LFP (mass), NMC (premium) | Fastest growing |
| Industrial & Energy Storage | 20.30% | Grid BESS, renewable integration, peak shaving | LFP | High – utility-scale BESS expanding |
| Medical Devices | 6.40% | Implantables, portable diagnostics, MRI systems | LCO, LMO | Stable – regulatory-driven quality demand |
Source: Polaris Market Research Analysis
Real-World Use Cases & Applications
Cathodes for lithium-ion batteries enable numerous applications in transportation, electronics, energy storage, medical, and industrial fields. Tesla employs lithium-ion battery packs in the entire vehicle range. Tesla's Megapack enables big battery energy storage for utility-scale grid stabilization, renewable integration, data centers and commercial sites; more than 58 gigawatt-hours of Megapack capacity is operational worldwide (Source: tesla.com). BYD’s Blade Battery employed LFP chemistry to enhance safety, durability and packaging efficiency (Source: media.byd.com).
Apple employs rechargeable lithium-ion batteries in its products such as the iPhone and MacBook, where high power density, lighter weight, and fast charging are important (Source: apple.com). Panasonic is active in grid-scale BESS projects, such as a 2026 demo project in Japan that centers on monitoring battery storage systems in actual grid operating environments (Source: news.panasonic.com). In addition to consumer and grid uses, lithium-ion batteries are also employed in rechargeables medical devices and implants where small size and reliable energy delivery are imperative. Industrial plants increasingly use lithium-ion UPS and backup-power systems to ensure uninterrupted production, protect data centers, and prevent downtime even during grid failures.
Sustainable Cathode Materials & Battery Recycling
Sustainability is now the focus of lithium-ion battery cathode development as manufacturers target material recovery, less-carbon footprint processing, and reduced reliance on critical elements. Battery recycling now depends largely on black mass processing, where batteries at the end of their lifespan are mechanically treated to extract lithium, nickel, cobalt, copper, and other precious substances to be used in the creation of new batteries. Redwood Materials says its recycling methods enable recovering more than 95% of critical battery elements, such as lithium, cobalt, nickel, and copper (Source: redwoodmaterials.com).
The European Union Battery Regulation is reinforcing circular-economy obligations through recycled-content targets, recovery-efficiency rules, traceability, and battery-lifetime obligations. Meanwhile, cathode research and development is moving toward cobalt-free and reduced-cobalt chemistries (especially LFP and Mn-rich formulations) to slash cost, supply-chain risk, and environmental consequences. These are leading cathode manufacturers to pursue recycling, recycled feedstocks, and more sustainable chemistry routes as part of their long-term production strategies.
Source: Polaris Market Research Analysis
Regional Analysis
By region, the study provides market insights into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
In 2025, Asia Pacific held the largest market share in the lithium- ion battery cathode market, accounting for 57.40%. This is due to its strong battery manufacturing ecosystem, robust electric vehicle production, cathode-material processing capacity, and massive investments in gigafactories. China remained the region's main growth pillar; new energy vehicle output reached 16.52 million units in 2025, according to government figures (Source: stats.gov.cn). Also, the IEA indicates that China accounts for about 85% of global cathode active material production.
China accounted for the largest share of the Asia Pacific market in 2025, which was expected to be 68.40% of the regional market. The China lithium-ion battery cathode market growth is attributed to the country’s dominance in battery manufacturing and high EV production. Its well-established cathode-material supply chains and favorable policies for electrification also drive the market expansion. Meanwhile, China’s output of cathode material has increased by more than 40% year on year in the first four months of 2025, reaching around 1.15 million tons, reinforcing the demand domestically for cathodes, according to China’s Ministry of Industry and Information Technology.
Indonesia is emerging as a cathode-material hub through policies promoting domestic nickel processing and downstream investment in refining, precursor, and battery-material production. Vietnam is supporting battery and EV assembly through manufacturing incentives, industrial-zone development, and policies aimed at attracting foreign investment into advanced electronics and clean-energy supply chains. Together, Indonesia, Vietnam, and India are broadening Asia Pacific’s battery manufacturing base and reducing overdependence on China-centered supply chains.
The North America lithium-ion battery cathode market size is anticipated to grow at a significant CAGR of 19.80% during the forecast period owing to increasing investments in domestic battery production and growth of electric vehicle manufacturing. The U.S. Department of Energy is increasingly investing in North America’s battery and EV supply chain. These strategies are reinforcing local cathode supply chains, decreasing import dependency, and meeting demand for locally manufactured lithium-ion battery materials.
Further, North America is strengthening its lithium-ion battery cathode ecosystem through domestic production incentives, supply chain localization, and new battery investments. In July 2025, Panasonic Energy started mass production at the new De Soto, Kansas lithium-ion battery plant and that the plant is aiming for an annual capacity of approximately 32 GWh, increasing Panasonic’s total U.S. capacity to about 73 GWh once the De Soto plant is fully operational (Source: na.panasonic.com). Also, Ascend Elements is progressing its Apex 1 project in Kentucky with a US$316 million U.S. Department of Energy grant still active to back commercial-scale precursor cathode active material production (Source: ascendelements.com). These capital expenditures, together with Section 45X manufacturing credits, are enabling an expansion of the region's supply of cells and cathode materials, thereby minimizing dependency on foreign battery supply chains.
The U.S. lithium-ion battery cathode manufacturers market will grow at the highest rate at an estimated CAGR of 20.30% during the forecast period due to the activities to the reduce dependency on foreign battery supply chains and increasing demand from electric vehicle (EV), consumer electronics, and energy storage systems.
Europe held a 17.20% market share in 2025. Localized cathode production and stronger battery sustainability demands in the region are driving regional growth. BASF operates the first fully automated large-scale CAM facility in Europe at Schwarzheide in Germany, and Umicore is further expanding its Nysa, Poland, site to approximately 45 GWh by 2028 (Source: basf.com). The EU Battery Regulation is also creating a need for lower-carbon, traceable cathode materials facilitated by carbon-footprint, recycled content, and battery-passport rules.
Latin America accounted for a share of around 3.80% in 2025, supported by lithium reserves in Chile and Argentina. Chile continued to be a main global supplier of lithium in 2025, and Argentina reported lithium export values of nearly USD 0.91 billion on account of new projects coming online (Source: subrei.gob.cl).
The market in the Middle East & Africa is expected to record an 18.70% CAGR. Morocco is moving from a raw-materials center towards battery-materials production, with COBCO planning to invest around USD 2.00 billion to produce NMC precursor and LFP cathode capacity based on locally sourced cobalt, manganese, and phosphate (Source: mcinet.gov.ma).
Regional Market Snapshot (2025 Baseline)
| Region | 2025 Market Share | Key Countries | Primary Driver | Forecast Trend |
| Asia Pacific | 57.40% | China (#1), Japan, South Korea, India | Battery manufacturing dominance; EV production; consumer electronics exports | Sustained leader; Indonesia nickel; India PLI scheme adds sub-regional growth |
| North America | 18.30% | USA (#1), Canada, Mexico | IRA Section 45X incentives; domestic EV production ramp; Panasonic, LG Chem plants | Fastest growing region; USD 3.5B DOE investments; USMCA near-shoring |
| Europe | 17.20% | Germany, France, UK, Sweden | EU Battery Regulation; European Battery Alliance; BASF, Umicore capacity | Rapid growth; 550 GWh target by 2030; sustainability-driven demand |
| Latin America | 3.80% | Brazil, Chile, Argentina, Mexico | Raw material sourcing (lithium triangle); growing EV market | Emerging – lithium export growth; domestic demand nascent |
| MEA | 3.30% | Saudi Arabia, UAE, South Africa | Energy storage for renewables; Saudi Vision 2030; EV infrastructure | Early-stage but strategic – raw material richness |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
Regulatory Landscape
The lithium-ion battery cathode industry is increasingly influenced by regulations advocating for localized production, sustainability, traceability, and supply-chain resilience. Within the European Commission, Regulation (EU) 2023/1542 sets lifecycle requirements for battery carbon footprints, recycled content, labeling, and responsible sourcing. Battery Due Diligence Requirements will apply as of August 2027, and the requirements to declare carbon footprint for electric vehicle and industrial rechargeable batteries are being introduced. These laws are motivating cathode manufacturers to enhance material traceability, limit manufacturing emissions, and increase recycled usage of lithium, nickel, and cobalt (Source: eur-lex.europa.eu).
The U.S. offers incentives for domestically manufactured battery components under Section 45X of the Inflation Reduction Act. The credit is USD 35/kWh capacity for eligible battery cells and USD 10/kWh for eligible battery modules, instead of USD 10/kWh for cells. The framework allows for the development of U.S. battery and cathode-material supply chains (Source: irs.gov).
Value Chain Analysis
The lithium-ion battery cathode value chain has five stages: sourcing raw materials, processing or refining, producing precursor cathode active material (p-CAM), producing cathode active material (CAM), and manufacturing the cell. The linear sourcing chain includes lithium, nickel, cobalt, manganese, iron, and phosphate derived primarily from mining. These are refined into battery-grade chemicals with the purity needed for electrochemical applications. At the subsequent step, precursor cathode active material, or pCAM, metals are refined and combined into engineered precursor formulations that define much of the final cathode chemistry. pCAM is then processed into cathode active material, or CAM, for example NMC, LFP, LCO, LMO, or NCA via lithiation, calcination, coating, and other processing activities. Cell makers receive CAM to produce electrodes and subsequently assemble cells, which they form, test, and integrate into packs.
A key chokepoint of the cathode material value chain is the high concentration of midstream processing capacity in China, particularly in chemical refining, pCAM, and CAM manufacturing. This concentration gives Chinese suppliers significant influence over global cathode supply, pricing, and lead times. Governments and battery manufacturers in North America, Europe, and elsewhere are investing in localized refining, precursor production, cathode manufacturing, recycling, and secure long-term sourcing of raw materials to mitigate supply-chain risk and enhance resilience.
Competitive Analysis
Competition for battery materials is between well-established Asian manufacturers and Western newcomers who focus on supply chain sustainability. Vertically integrated firms with large-scale chemistry processing and manufacturing include customers such as CATL, LG Chem, and Samsung SDI. Cathode material production for CATL partly benefits from the company's large-scale battery production and expanding investment in battery gigafactories. Japanese firms such as Sumitomo Metal Mining and Nichia continue to be key providers of high-nickel cathode NMC 811 and other innovative cathode materials.
BASF and Umicore are spearheading the response in Europe with scaled production in-region and global precursor sourcing. Redwood Materials and Ascend Elements in the U.S. are making strides in closed-loop recycling and direct cathode synthesis, minimizing reliance on linear supply chains. POSCO Future M and Korea’s EcoPro BM are also making strides across the globe, excluding China. Mitra Chem and NEI Corporation are working on iron-based materials, cobalt-free battery chemistry, and other next generation solutions. Competition is further heating up to develop solid-state battery cathode technology. Thus, the market is shifting from a volume-driven race to one defined by regional production, technology differentiation, supply security, and ESG compliance.
Market Concentration & Strategy
The market for lithium-ion battery cathodes is moderately concentrated by capacity, as the top 5 suppliers hold about 52% of global production capacity. Top producers are increasingly vertically integrating from raw-material sourcing, precursor production, cathode active material production, and recycling to enhance supply security and margin control. Recycling is also becoming a strategic cost lever as it mitigates exposure to the volatile prices of lithium, nickel, and cobalt, and helps meet recycled-content requirements. Automotive OEMs and battery cell manufacturers are signing long-term supply contracts with battery cathode manufacturing companies to ensure availability of materials, stabilize procurement costs, and support localized battery manufacturing. These models are refashioning the competitive landscape on the basis of scale, supply-chain control, sustainability, and contract security.
List of Key Lithium-Ion Battery Cathode Companies
- Ascend Elements
- BASF SE
- CATL (Contemporary Amperex)
- Ecopro BM
- Huayou Cobalt (Guangxi CNGR)
- LG Chem Ltd.
- Mitra Chem
- NEI Corporation
- Nichia Corporation
- POSCO Future M
- Redwood Materials
- Samsung SDI
- Sumitomo Metal Mining Co.
- Targray Technology Intl.
- Umicore SA
Lithium-Ion Battery Cathode Industry Developments
- April 2026: TSR Group and BASF have joined forces to enhance European EV battery recycling by means of battery dismantling, logistics, black-mass processing, and recovery activities for circular cathode-material supply chains. (Source: .basf.com)
- March 2025: Umicore has entered into medium- to long-term pCAM supply contracts with CNGR and Eco&Dream to further diversify its precursor sourcing and serve EV battery clients in North America and Asia. (Source: umicore.com)
- March 2025: LG Energy Solution, Ltd. announced the opening of a large-scale lithium-ion battery assembly plant in the UAE, aimed at meeting the region's growing demand for energy storage and electric mobility solutions. The plant specializes in producing high-capacity battery packs for renewable integration projects, electric buses, and grid stabilization efforts.
- March 2025: Life Insurance Corporation of India (LIC) is set to enter the health insurance sector, with the acquisition of a health insurer in the final stages, CEO Siddhartha Mohanty told CNBC-TV18, marking a significant expansion into the growing health insurance market.
Future Outlook
The cathode market for lithium-ion batteries is expected to drift toward higher performance, lower cost, and more sustainable chemistries through 2030 and beyond. Solid-state batteries are an important long-term roadmap, and sulfide-, oxide-, polymer- and hybrid-electrolyte systems are progressing from pilot production to wider commercialization while manufacturers tackle interface stability, manufacturing scale, and cost issues. LMFP is also progressing to commercialization from validation, with approximately 15–20% higher theoretical energy density than LFP, and with comparatively good safety and cost metrics. Industry developments in 2025-2026 demonstrate that LMFP is emerging from early industrial development stage, with pilot and commercial-scale initiatives focusing on EV and energy storage applications through the late 2020s.
The global cathode and battery manufacturing capacity is forecast to continue growing at pace to 2030 due to increasing demand for electric vehicles and stationary storage. Yet these public sources do not align with a forecast for global cathode capacity of 550 GWh by 2030; IEA data instead suggests demand for EV batteries will be in excess of 3 TWh by 2030. This rising demand will propel the adoption of cathode materials for EV batteries.
Research Methodology
The lithium-ion battery cathode market analysis uses a proven research methodology that combines primary and secondary research with an analysis of market dynamics. Secondary sources include company annual reports, investor presentations, regulatory filings, government publications, industry associations, trade databases, technical literature, and publicly available market information. Primary research includes interviews with battery manufacturers, cathode material suppliers, raw material processors, automotive OEMs, energy storage companies, distributors, and other industry stakeholders to validate market trends and assumptions.
Market sizing processes examine historical demand, production capacity, pricing trends, chemistry adoption, end-use penetration, regional manufacturing activity, and supply-chain developments. Bottom-up and top-down approaches have been applied to forecast the market values in terms of value for the chemical composition, cell type, end use, and region. Forecasts consider EV adoption and battery manufacturing growth, as well as energy storage deployment, regulations, technology transitions, and availability of raw materials. The final estimates are checked for consistency across segment and regional forecasts through data (referred as the data triangulation) and review of analysts.
Lithium-Ion Battery Cathode Market Segmentation
By Chemical Composition Outlook (Revenue, USD Billion; 2021–2034)
- Lithium Cobalt Oxide
- Lithium Manganese Oxide
- Lithium Nickel Manganese Cobalt Oxide
- Lithium Iron Phosphate
- Lithium Nickel Cobalt Aluminum Oxide
By Cell Type Outlook (Revenue, USD Billion; 2021–2034)
- Cylindrical
- Prismatic
- Polymer
By End Use Outlook (Revenue, USD Billion; 2021–2034)
- Automotive
- Consumer Electronics
- Medical Devices
- Industrial and Energy Storage
By Regional Outlook (Revenue, USD Billion; 2021–2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Lithium-Ion Battery Cathode Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 38.19 billion |
| Market Size in 2026 | USD 45.79 billion |
| Revenue Forecast by 2034 | USD 196.75 billion |
| CAGR | 20.0% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion, 2021–2034 and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Lithium-Ion Battery Cathode Market FAQ's
The global market size was valued at USD 38.19 billion in 2025 and is projected to grow to USD 196.75 billion by 2034. Rising demand from electric vehicles and consumer electronics sectors drives the market growth.
The global market is projected to register a CAGR of 20.0% during the forecast period. Rising government initiatives to boost EV charging infrastructure will fuel the market expansion.
In 2025, Asia Pacific accounted for a 57.40% share in the market due to its established dominance in battery manufacturing and the presence of leading market players in countries like China, Japan, and South Korea.
A few key players in the market are Ascend Elements; BASF SE; CATL (Contemporary Amperex); Ecopro BM; Huayou Cobalt (Guangxi CNGR); LG Chem Ltd.; Mitra Chem; NEI Corporation; Nichia Corporation; POSCO Future M; Redwood Materials; Samsung SDI; Sumitomo Metal Mining Co.; Targray Technology Intl.; Umicore SA
In 2025, the automotive accounted for 55.20%market share in the lithium-ion battery cathode market.
LFP demand is rising, owing to its high thermal stability, long cycle life, cost-effectiveness, and free of nickel and cobalt, which made it preferable for EV and stationary energy storage.
The lithium manganese oxide segment is projected to experience the significant growth of 16.30% during the forecast period due to its widespread use in power tools, medical devices, and hybrid electric vehicles (HEVs).
LFP is safer and has longer lifecycle and better cost efficiency, while NMC has higher energy density and longer driving range, thus NMC is more suitable for performance-oriented electric vehicle.
Electrodes demand is dominated by EVs as every EV battery needs a significant amount of cathode active material. Expanding EV production, increasing battery sizes, and range expectations are driving up cathode consumption.
The industrial and energy storage end users are anticipated to grow at a high rate with strong growth in utility-scale BESS, renewable energy integration, data centers, microgrids, and a growing preference for long-life LFP batteries.
Regulations are promoting local and sustainable production of batteries. The EU Battery Regulation enhances carbon-footprint, recycling and traceability requirements, and U.S. Section 45X provides incentives for domestic battery production.
Future growth will be driven by LFP ramp-up, LMFP commercialization, high-nickel cathodes, recycling, localized supply chains, solid-state development, and surging demand for EV and stationary-storage batteries.
Download Sample Report of Lithium-Ion Battery Cathode Market
Please fill out the form to request a customized copy of the research report.