Lithium-Ion Battery Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Lithium-Ion Battery Market Summary
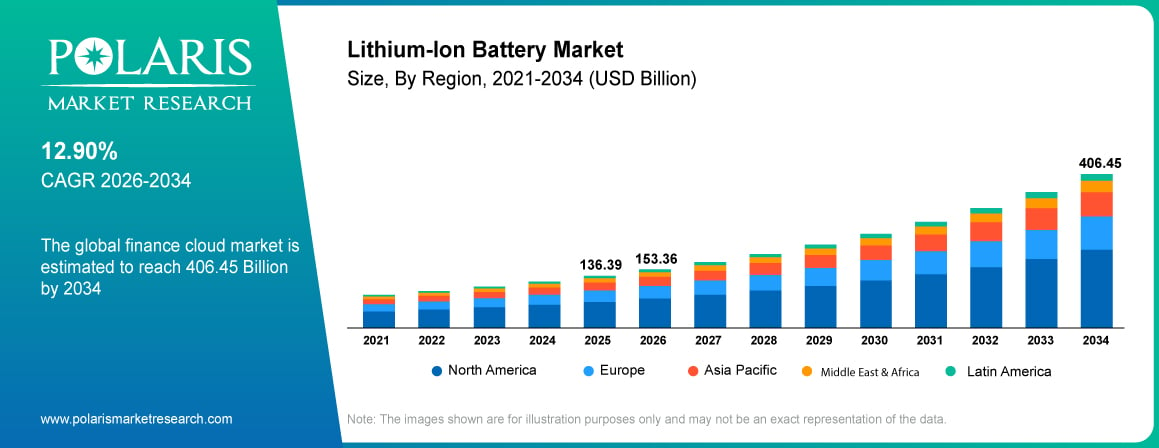
The global lithium-ion battery market was valued at around USD 136.39 billion in 2025 and is projected to reach USD 406.45 billion by 2034, registering a CAGR of 12.90% from 2025 to 2034. Rising government initiatives promoting electric vehicle (EV) adoption boost the demand for lithium-ion batteries. Advancements in battery technologies are expected to propel the industry expansion during the forecast period.
Market Statistics
Lithium-Ion Battery Market Key Takeaways
- In 2025, Asia Pacific accounted for the largest share of 52.0%. The strong presence of key battery manufacturers and increasing demand for consumer electronics boost the regional market growth.
- The North America industry is expected to witness the fastest growth at a CAGR of 12.55% during the forecast period. The increasing EV adoption and advancements in renewable energy storage solutions drive the industry expansion.
- The energy storage systems segment is?anticipated to witness a robust growth at 15.20% CAGR during the forecast period. It is driven by increasing demand for home energy storage.
- The cathode material segment accounted for the largest share of 40.0% of the?lithium-ion battery market in 2025. This is attributed to the growing cell manufacturing capacity.
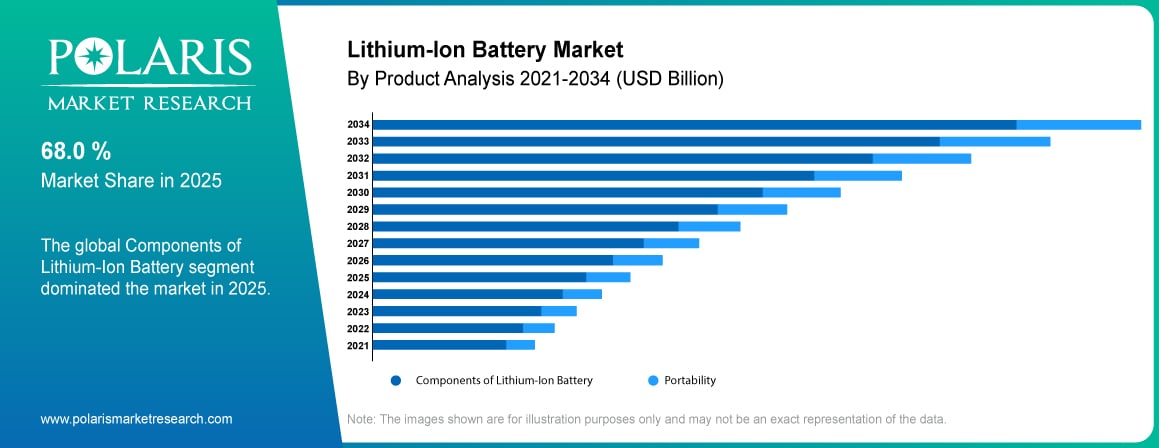
- In 2025, the portable segment captured a 68.0% share. This is due to the mass adoption of?lithium-ion batteries in consumer electronics, portable medical devices, power tools, and other mobility-related applications.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observation.
What is Lithium-Ion Battery?
A lithium-ion battery is a type of rechargeable energy storage device. In this battery, electricity is generated through the movement of lithium ions between a cathode (positive electrode) and anode (negative electrode) during charging and discharging. Li-ion batteries offer high energy density and lightweight construction. The batteries have a long cycle life. They have relatively lower self-discharge than conventional rechargeable batteries.
The batteries are used broadly in EVs, consumer electronics, industrial applications and battery energy storage systems (BESS). Different chemistries such as LFP, NMC, LCO, and NCA can fulfill different performance needs. Also, a battery management system (BMS) assists with regulating the charge and temperature, as well as the operational safety.
How Does a Lithium-Ion Battery Work?
Lithium-ion batteries work by moving lithium ions between the anode and cathode during charging and discharging, while electrons travel through an external circuit to deliver usable electrical power.
- Charge Cycle: An external power source moves lithium ions from cathode through the electrolyte to the anode during charging. In this, they are intercalated into the anode material. Electrons travel between the anode and cathode through the external circuit to maintain electrical neutrality. So it controls that flow. It enables energy storage in a battery, and then battery releases this energy later. Fast-charging solutions enhance this process while managing heat dissipation and protecting cell performance over different charge iterations.
- Discharge Cycle: Lithium ions, just like electrons, cannot travel through the electrolyte directly. Hence, they flow through the external circuit to power electronic device. Electrons can’t travel through the electrolyte, so they take the long way around through the external circuit and power where they are connected. This is the output to applications as an EV battery, consumer electronics battery, industrial battery, and energy storage system. The discharge process continues until the battery's stored energy is exhausted.
- Function of Battery Management System: The battery management system continuously monitors the voltage, current, temperature, state-of-charge, and overall cell health of the cells within the system to ensure that the battery operates safely and efficiently. BMS equalizes the individual cells and controls the charging and discharging. The system assists on the prevention of overcharge, overdischarge, overheat and overcurrent. In larger lithium-ion battery systems, the BMS also enables the management of heat. It provides early indication of conditions that could lead to thermal runaway. State-of-the-art systems increasingly leverage intelligent monitoring technology to improve battery performance and longevity, as well as charge efficiency, reliability, and performance in EV and BESS applications.
Lithium-Ion vs Lead-Acid vs Sodium-Ion Batteries
| Feature | Lithium-Ion | Lead-Acid | Sodium-Ion |
| Energy density | High | Low | Moderate |
| Cycle life | Long (1,000–5,000+ cycles) | Short (200–500 cycles) | Moderate, improving |
| Cost per kWh (raw material exposure) | Moderate. Sensitive to lithium/cobalt/nickel prices | Low | Low. No lithium/cobalt dependency |
| Weight | Lightweight | Heavy | Lightweight |
| Charging speed | Fast | Slow | Fast, still maturing |
| Primary use today | EVs, consumer electronics, BESS | Automotive starter batteries, backup power | Emerging. Stationary storage, entry EVs (e.g., JAC, China Southern Power Grid pilots) |
| Commercial maturity | Fully mature, mass-manufactured | Fully mature, legacy technology | Early commercial stage |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
AI Impact on Lithium-Ion Battery Market
- AI-powered computer vision assists in identifying microscopic flaws that occur during manufacturing. It helps improve yields and decreases waste.
- AI is used for forecasting machine breakdowns. It helps minimize downtime and improve production scheduling.
- AI integration helps track information across the battery lifecycle. It is used to implement recycling and reuse approaches effectively.
Market Dynamics
Driver: Rising Adoption of Electric Vehicles (EVs)
The expanding demand for electric vehicles (EVs) and stationary energy storage applications drive the market growth. A June 2026 European Commission report states that sales of battery electric vehicle (BEVs) cars increased by 26% y-o-y in 2025. It exceeded 13 million units and accounted for 16% of all new cars sold globally (Source: climate.ec.europa.eu). This transition is being supported by government policies to reduce emissions from the transport sector and promote the adoption of zero-emission mobility.
UK government backing for the ending of new petrol and diesel cars and for the growth of ultra-low emission vehicles remains, through both regulatory and financial means. Carmakers are emphasizing electric vehicle production. Hence, the demand for EV battery chemistries such as LFP and NMC is increasing. This factor is fueling the expansion of battery production capacity. In response to this rising demand, the automotive industry is investing heavily in the production of lithium-ion batteries. Various car manufacturers have also announced commitments to mass produce electric models. Some are even partnering with battery manufacturers to obtain a steady supply of good-quality batteries. This has accelerated a shift in the vehicle industry, where the availability of lithium-ion batteries is now cementing as a crucial determinant to support the electrification of vehicles.
Driver: Government Policies and Incentives
Governments are implementing policies and financial incentives to boost the production and supply system of lithium-ion batteries. In March 2026, the U.S. Department of Energy stated that the government is funding USD 500 million to support expansion of processing of critical minerals and materials in the U.S., along with related battery manufacturing and battery recycling. The program is designed to expand supply chains for batteries that enable transportation, grid resilience, manufacturing and other key industries (Source: energy.gov).
Government funding through subsidies, tax incentives and loan guarantees is starting to boost U.S. production of batteries and associated materials, including cathodes and anodes, as well as battery recycling. DOE also offers separate Battery Materials Processing Grants and Battery Manufacturing and Recycling Grants that are intended to scale up U.S. production and address supply-chain vulnerabilities. These initiatives strengthen domestic supply, improve the circular economy, and support deployment in EV battery and BESS applications. It is driving growth of the lithium-ion battery market.
Challenge: Raw Material Price Volatility and Supply Chain Risk
Price and supply volatility for lithium, nickel, cobalt, graphite, and other essential battery materials create cost and planning pressures in the market. Battery makers rely on mining and refining operations that are concentrated in certain areas of the world. Thus, output is susceptible to geopolitical tensions, trade restrictions, transportation mishaps, permit bottlenecks, and demand fluctuations. Cell producers have higher production costs when cathode and anode material costs increase, which translate such costs to EV battery, consumer electronic battery, and BESS prices.
Supply-chain consolidation increases vulnerability to interruptions in refining and processing availability. Expansion in battery manufacturing capacity can place a premium on quality supplies of raw materials when many gigafactory projects ramp up production simultaneously. Manufacturers are required to secure long-term supply contracts and develop alternative sourcing regions. They must commit capital to recycling infrastructure, potentially on a large scale.
Price fluctuation is an additional factor complicating the planning of production and long-term purchasing. Some producers can not cope with the increased material costs. The lithium-ion battery market is expanding rapidly. Thus, ensuring the availability of the necessary minerals at affordable prices remains one of the key challenges for battery manufacturers, automakers, and energy storage developers.
Restraint: Competition from Alternative Battery Chemistries
Increasing competition from other battery chemistries restrain the market expansion. Producers and consumers focus on reducing costs and ensuring safety, longer service life, and less reliance on critical minerals. Sodium-ion batteries are attracting interest as they help reduce dependence on lithium, nickel, and cobalt and could be economically competitive, particularly in stationary energy storage and low-range mobility use cases.
Traditional lead-acid batteries are also significant in some applications due to their low initial cost, recyclability, and reliability, rather than energy density. The newly invented solid-state batteries can be a threat to lithium-ion batteries as well because they provide high energy density and safety, as compared to others, if commercialization is economically viable for them. Alternative batteries hold significant market share in some applications such as BESS, cost-effective EVs, and backup systems.
Opportunity: Expanding Demand for Battery Energy Storage Systems
A strong development opportunity for the lithium-ion battery market is the increasing usage of BESS. Utilities today seek more flexible storage solutions to match renewable power generation with electricity load. In February 2026, the U.S. Energy Information Administration stated that all-time high growth of 15 gigawatts (GW) in utility-scale battery storage capacity by developers was reported in 2025. Additional 24 GW are in the works for 2026. This rapid growth of capacity will propel demand lithium-ion batteries for grid energy storage systems (Source: eia.gov).
Growth in solar and wind penetration drives BESS deployment. Storage systems can store electricity when supply is abundant and release it when demand is high. This translates into new revenue streams for cell manufacturers, battery pack suppliers, and battery management system providers. Increasing investment in grid infrastructure will fuel growing battery manufacturing capability and the development of large-scale gigafactory projects. As a result, energy storage is becoming an important growth avenue alongside traditional EV battery and consumer electronics applications.
Source: Polaris Market Research Analysis
Segmentation Analysis
The report provides a comprehensive analysis of the market by material, product, type, capacity, voltage, and industry to identify key revenue-generating and high-growth segments.
Market by Industry
The energy storage systems segment is anticipated to witness a robust growth at 15.20% CAGR during the forecast period as integration of renewable power leads to higher demand for flexible and reliable electricity storage. Battery energy storage systems are being frequently deployed by utilities and commercial installations to firm intermittent solar and wind production. It helps meet peak demands and provides other grid stability functions. Due to the long cycle life and good thermal stability, LFP batteries are becoming more and more preferred in stationary storage applications. Moreover, increasing demand for home energy storage is further diversifying the applications for lithium-ion batteries. Innovations in battery management systems and declining costs at the system level are driving deployments. Thus, energy storage is becoming a more significant end user in the lithium-ion battery market.
Material Analysis
The cathode material segment accounted for the largest share of 40.0% of the lithium-ion battery market in 2025, owing to factors such as its importance in determining the energy density, voltage, safety, cycle life, and performance of the battery. Materials of lithium-ion battery cathodes also represent a substantial proportion of the cell level material value, which underpins their ability to generate more revenue within battery manufacturing. Demand is still heavily inclining toward the LFP, NMC, LCO and NCA chemistries that have been used for many years in EVs, consumer electronics, and energy storage systems. Increasing adoption of LFP, owing to its thermal stability and long cycle life, with sustained usage of nickel-based chemistries for low-energy applications, is driving demand for cathode materials. Growth in cell manufacturing capacity will boost consumption of cathode active materials.
Market by Product
In 2025, the portable segment captured 68.0% share in 2025. This is due to the mass adoption of lithium-ion batteries in consumer electronics, portable medical devices, power tools, and other mobility-related applications. This category generates high battery consumption as demand for smartphones, laptops, tablets, wearables, and cordless tools is growing. Lithium-ion batteries are suitable for portable applications due to their high energy density, lightweight, and rechargeable nature. They can provide dependable performance even when packaged in small sizes. On the other hand, continuous development of cell design also makes longer operating time available for users without a massive size/weight increase. Increasing demand for fast charging and longer battery life will contribute to the growing adoption of portable products.
Type Analysis
Lithium cobalt oxide held the largest share of 34.0% in 2025. This is attributed to its high suitability in small, high energy density battery applications. It delivers high specific energy that appeals to its use in smartphones, laptops, tablets, cameras, and other portable consumer electronics where size and weight are still critical design parameters. This chemistry also provides a constant voltage and high energy efficient delivery of energy, which results in prolonged run time for miniaturized devices. It also has solid manufacturing/widespread portable electronic integration, which is driving demand. While other chemistries such as LFP and NMC are gaining traction in other sectors, Lithium Cobalt Oxide continues to be very applicable in high-end consumer electronics. These factors contributed to its growth in the lithium-ion battery type segment in 2025.
| Type | Full Name | Key Strength | Primary Application | 2025/26 Market Position |
| LCO | Lithium Cobalt Oxide | High energy density, compact form factor | Smartphones, laptops, wearables | Largest share (34.0%, 2025) |
| LIP | Lithium Iron Phosphate | Thermal stability, long cycle life, lower cost | EVs, stationary energy storage, buses | fastest-growing (~13.15% CAGR) |
| NMC | Lithium Nickel Manganese Cobalt Oxide | Balanced energy density, safety, and performance | Premium EVs, consumer electronics | Widely used in premium EV platforms |
| NCA | Lithium Nickel Cobalt Aluminum Oxide | Very high energy density | High-performance/premium EVs | Preferred for range-focused EV models |
| LMO | Lithium Manganese Oxide | Safety, moderate cost | Power tools, e-mobility, industrial equipment | Niche/stable demand |
| LTO | Lithium Titanate Oxide | Fast charge/discharge, very long cycle life | Electric buses, grid storage, industrial equipment | Small share |
Source: Polaris Market Research Analysis
Market by Capacity
0 to 3000 mAh is expected to grow at 11.75% CAGR during the forecast period, owing to the continued demand for small and lightweight battery operated gadgets. Compact, small-sized batteries remain in high demand for smartphones, wearable electronics, wireless accessories, portable medical devices, and consumer electronics, where they must deliver a reliable power source in a small form factor. Advances in cell design and energy density are providing device manufacturers with the possibility to increase operating time while at the same time working on smaller device form factors. Increasing penetration of connected and rechargeable electronic devices is further boosting the demand for low capacity lithium-ion cells. Developments in fast charging technology and battery management systems are also contributing to enhanced usability and longer battery life. Hence, the 0 to 3000 mAh Li-ion battery segment witnesses strong growth in portable application.
Voltage Assessment
High above 36 V accounted for 50.0% in 2025. This is due to strong demand from applications that require a higher power output, higher energy capacity, and continuous operating performance. High-voltage lithium-ion battery architectures are being increasingly adopted in EV, industrial machinery, energy storage systems and other heavy-load applications, aiming to boost efficiency and mitigate losses due to currents. These systems also enable faster power delivery and more compact electrical architectures for the same level of output. Increasing utilization of sophisticated battery packs, power electronics, and battery management systems further drives penetration in this voltage region. Higher-voltage solutions can also be exploited for larger battery packs with NMC and LFP chemistries. These factors collectively contributed to this section’s leading position in the lithium-ion battery market in 2025.
Source: Polaris Market Research Analysis
Regional Analysis
Asia Pacific Lithium-Ion Battery Market
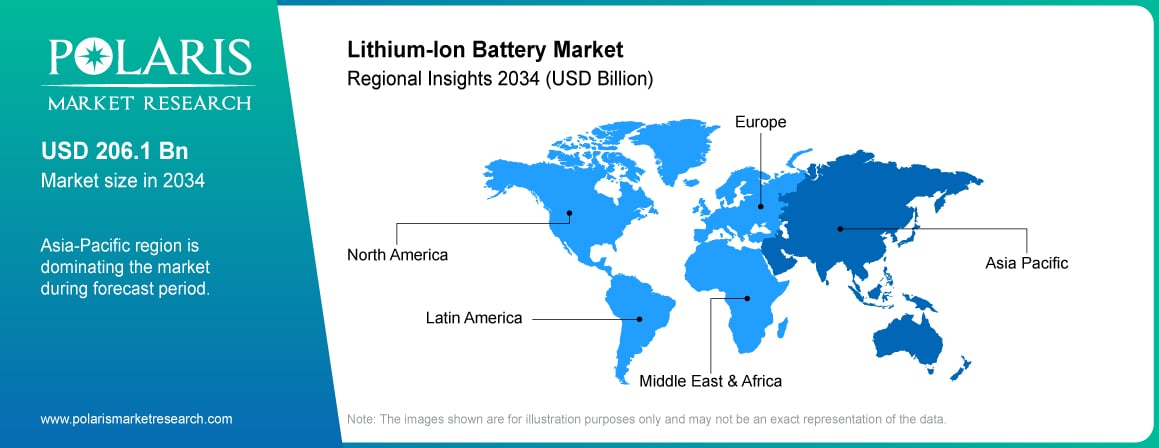
Asia Pacific led the global lithium-ion battery market share by holding 52.0% in 2025, owing to the presence of major lithium-ion battery manufacturers in the region and dominance throughout cathode material, anode material, cell and battery pack production. The region has the advantage of a massive battery production capacity and a relatively concentrated supplier network among automotive, consumer electronics, industrial, and energy storage customers. Stable electric vehicle production and growing battery energy storage system deployment continue to drive the demand for LFP and NMC chemistries. The existence of large gigafactory project further supports economies of scale and supply-chain integration. Meanwhile, increasing supply of domestic portable electronics and electric mobility solutions stimulates the regional battery demand. Together, these ensure Asia Pacific’s dominant share in the market for lithium-ion battery.
China
The lithium-ion battery market in China captured 67.0% share of APAC in 2025, owing to the large-scale production capacity of the country and the fully developed battery supply chain. China’s dominance is further driven by massive investments in cell manufacturing, cathode material, anode material, separator and electrolyte production, enabling producers to benefit from significant economies of scale. According to China's Ministry of Industry and Information Technology, June 2025 report, the country produced more than 473 GWh of lithium ion batteries from January to April, with a 68% YoY growth and between January and July, energy-storage battery production exceeded 110 GWh, and the capacity of power batteries for new energy vehicles (NEVs) was approximately 184 GWh. Furthermore, robust domestic demand in EVs, consumer electronics, and industrial equipment drives the market growth. Also, growth of the battery energy storage systems market boosts the expansion opportunities. Thus, these factors continue to support its position in the lithium-ion battery market (Source: miit.gov.cn).
North America Lithium-Ion Battery Market
The rapid increase in demand for electric vehicles, energy storage systems, industrial and consumer electronics is driving the growth of the North America lithium-ion battery market at 12.55% CAGR. Increasing battery manufacturing capacity is reducing reliance on imported cells and enabling more regional supply chains to be developed for cathode material, anode material, and battery packs. Utility-scale and commercial BESS deployment trends are also stretching the demand base beyond automotive applications. Producers are also investing more in sophisticated battery management systems, fast charging systems, and better thermal management. Increasing focus on battery recycling and circular economy practices in the region is another factor bolstering the regional value chain. This is expected to help the market expand further in North America.
U.S. Lithium-Ion Battery Market Insight
In 2025, the U.S. held a dominating share of 78.0% in the North American market. This attributes to the increasing electric mobility, grid-scale energy storage, and domestic battery production. Expansion of cell and battery pack manufacturing capacity is resulting in increased supply for automotive and stationary storage uses. Robust demand for high-voltage battery systems is driving broader penetration of lithium-ion technology in electric vehicles and industrial equipment. In addition, the expanding application of BESS in grid balancing and renewable energy integration also brings about higher battery consumption. These developments make the U.S. the largest contributor to the growth of the North American lithium-ion battery market.
Europe Lithium-Ion Battery Market
Europe held 18.0% share in 2025 which was driven by continued demand for lithium-ion batteries in electric vehicles, energy storage, industrial tools, and consumer products. The region’s automotive sector is also contributing to the growth as automakers develop new electrified vehicles and high-voltage architectures. The expanding installation of BESS is also boosting the demand for LFP and other stationary-storage chemistries. At the same time, Europe is building up local battery production to enhance supply security and to reduce outside dependence. Growing focus on battery recycling, second-life battery utilization, and circular economy principles is influencing procurement and production. Thus, these factors contributed to Europe holding a strong position in the global lithium-ion battery market.
Latin America Lithium-Ion Battery Market
The market in Latin America is anticipated to record a CAGR of 12.21% in the market owing to the growing penetration of electric mobility, renewable energy storage, telecom backup systems, and industrial battery applications. Rise in solar and wind generation are fueling demand for BESS that can improve grid flexibility and power reliability. The expansion of commercial and home energy storage is also broadening the base of applications for lithium-ion batteries. Batteries are in high demand as battery tools grow in popularity in industries such as mining, construction and logistics in the region. Rising investment in electric buses, and fleet electrification, is further expected to create the need for automotive batteries. Collectively, these trends will enable lithium-ion battery market to grow across Latin America.
Middle East & Africa Lithium-Ion Battery Market
The Middle East & Africa lithium-ion battery market anticipates to witness a steady CAGR of 10.91% during the forecast period owing to increasing demand from energy storage, telecommunication, electric mobility and industrial applications. The growth of renewable power generation is resulting in rising demand for battery energy storage system for enhancing grid stability and ensuring power supply reliability. Meanwhile, battery usage is also being boosted by widespread rollout of backup power systems at commercial buildings, infrastructure for data and remotely. The regional battery supply chain and energy storage system infrastructure improvements are also gradually expected to boost the market growth in the long term.
Source: Polaris Market Research Analysis
Use Cases & Real-World Applications
Electric mobility and transport
Demand for lithium-ion batteries continues to grow for electric cars, light commercial vehicles and other electrified transport platforms given the demand from vehicle manufacturers for higher energy density, longer range and better charging performance. According to UK Department for Transport April 2026 data, 473,000 new- and second-hand zero-emission cars were registered in 2025, accounting for 23% of all new car registrations, a 24% rise on 2024. This expansion of electric mobility, is boosting for demand for EV battery packs and advanced battery management systems (Source: gov.uk).
Energy Storage at the Utility Scale
Utility energy storage is witnessing growth as a major commercial lithium-ion battery application since grids are increasingly required to provide the flexibility to balance renewables generation and electricity demand. According to the U.S. Energy Information Administration August 2026 report, approximately 43.6 GW of operational utility-scale battery storage capacity exists, and another 8.3 GW added in the first half of 2026, bringing the total capacity to nearly 52 GW. This rapid deployment boost demand for large-format BESS solutions, in particular LFP-based systems.
Commercial and Industrial Energy Resilience
Advancements in technology are rapidly improving the quality and cost of battery storage and commercial and industrial users are beginning to embrace the technology to enhance power quality, control peak demand and provide resilience in the event of grid disruptions. In January 2025, the U.S. Department of Energy (DOE) closed a USD 289.7 million loan guarantee for Project Polo, focused on the installation of a maximum 1,000 solar photovoltaic (SPV) and BESS units in possibly 27 states, mostly at commercial and industrial sites. These deployments are extending the applications for lithium-ion batteries in distributed energy infrastructure.
Solar-Plus-Storage Systems
Solar-plus-storage solutions are growing as lithium-ion solutions make it possible for excess solar production to be stored and used when renewable production slows down or when power demands are high. For instance, in January 2025, U.S. Energy Information Administration stated that utility-scale developers are expected to develop 43.4 GW of solar capacity paired with 24 GW of battery storage in 2026. Tehuacana Creek 1 project is anticipated to be a 837 MW solar plus 418 MW BESS project, further contributing to the increased penetration of solar and BESS solutions.
Technology & Innovation Trends
Complex Cell Chemistry and Energy Density: Cell chemistry LFP, NMC, NCA and emerging cell chemistries in Li-ion battery technology are continuously being improved to increase energy density, cycle life and thermal stability. The producers and manufacturers worldwide are making progress in development of cathode and anode materials to increase capacity and reduce weight, increase safety and life in applications of electric mobility and stationary storage.
Fast-Charging and Battery Management Systems: The fast-charging ability is becoming an important development direction with car manufacturers trying to shorten the charging time as far as possible without speeding up battery ageing. Sophisticated BMSs are now being employed to track voltage, temperature, state of charge (SOC), and cell balance, which allow for safer charging, enhanced thermal management, and more uniform performance of EV battery packs and BESS installations.
Thermal Management and Safety Engineering: Li-ion battery research is now largely focused on enhancing the thermal stability of the battery and suppressing the deterioration in the performance under the severe operating conditions. Companies are making advances in cooling, safer separator materials and cell architecture, as well as better detection of thermal runaway. These advancements are particularly important for EV battery packs and large grid-scale BESS manufacturers, where safety, reliability, and long operating life remain critical performance In EV battery packs and large grid-scale BESS, these innovations are more important because safety, reliability and long operating life still define the key performance benchmarks.
Battery Recycling & Circular Economy
Battery recycling and other circular economy approaches are receiving more attention in the lithium-ion battery value chain as battery use increases in electric vehicles (EVs), consumer electronics, industrial machinery and energy storage systems. Battery recycling allows recovery of lithium, nickel, cobalt, graphite and other valuable materials, which can help reduce battery manufacturers' reliance on raw materials and increase supply-chain resilience. Another area of circularity practice is in second-life battery application, EV batteries for example can be used for stationary storage, or as backup power. For example, in June 2025, LG Energy Solution and Toyota Tsusho formed the Green Metals Battery Innovations, a battery recycling JV based in North Carolina with an annual processing capacity of 13,500 tons of scrap, or over 40,000 automotive batteries. This is reflective of the growing focus of the sector on the closed-loop production, material recovery and re-use of reused materials in the battery-making process. As production volumes grow, efficiencies in recycling, traceability, and more aware use of recycled material will all become increasingly important for the long-term viability of the lithium-ion battery industry (Source: news.lgensol.com).
Competitive Landscape
The global battery market is characterized by intense competition across chemistry, geography, and application. Chinese producers dominate the LFP (Lithium Iron Phosphate) space, with CATL as the largest Li-ion producer world-wide and BYD using its own Blade Battery in EVs and energy storage solutions. Emerging as large-scale players CALB and EVE Energy, once again extending the dominance of China in cheap, high-cycle-life batteries. South Korean trio LG Energy Solution, Samsung SDI and SK On, are heavily concentrated in high-nickel NMC/NCMA chemistries for premium long-range EVs. In addition, LG and Samsung are active in industrial and stationary storage, while SK On is still purely focused on electric vehicles. Japan's Panasonic stands out due to its lengthy NCA partnership with Tesla, and Toshiba in LTO (Lithium Titanate) for rapid-charging industrial usage. The U.S. adds Tesla, which alone vertically integrates cell and pack manufacturing for its EVs and Megapack storage, and specializes in LFP for low-voltage automotive systems, A123 Systems LLC, specializing in LFP for low-voltage automotive systems. Yet, Clarios retains a powerful position as the world's leading low-voltage lead acid and AGM battery provider for all makes and models of vehicles, a legacy segment largely unchallenged by Li-ion pure-plays.
List of Key Companies
- A123 Systems LLC
- BYD Company Limited
- CALB, China Aviation Lithium Battery Co.
- CATL, Contemporary Amperex Technology Co., Ltd.
- Clarios
- EVE Energy Co., Ltd.
- LG Energy Solution Ltd.
- Panasonic Holdings Corporation
- Samsung SDI Co., Ltd.
- SK On Co., Ltd.
- Tesla, Inc.
- Toshiba Corporation
Vendor Positioning
| Company | HQ | Chemistry / Focus Area | Segment Presence |
| CATL (Contemporary Amperex Technology Co., Ltd.) | China | LFP, NMC | World's largest Li-ion manufacturer; EV + BESS |
| BYD Company Limited | China | LFP (Blade Battery) | EV, consumer electronics, energy storage |
| LG Energy Solution Ltd. | South Korea | NMC, NCMA | EV, BESS, industrial |
| Panasonic Holdings Corporation | Japan | NCA, cylindrical cells | EV (Tesla partnership), consumer electronics |
| Samsung SDI Co., Ltd. | South Korea | NMC | EV, energy storage, industrial |
| Tesla, Inc. | United States | NCA/LFP (cell + pack integration) | EV, residential/utility storage (Megapack) |
| SK On Co., Ltd. | South Korea | NMC | EV |
| Toshiba Corporation | Japan | LTO | Industrial, fast-charging applications |
| CALB (China Aviation Lithium Battery Co.) | China | LFP | EV — emerging-scale player |
| EVE Energy Co., Ltd. | China | LFP, cylindrical | EV, energy storage — emerging-scale player |
| A123 Systems LLC | United States | LFP | Automotive (12V/48V systems), commercial vehicles, energy storage |
| Clarios | United States | Lead-acid, AGM, Lithium-ion (LTO cells) | Global leader in low-voltage batteries for all vehicle types (1 in 3 cars); also energy storage |
Source: Polaris Market Research Analysis
Lithium-Ion Battery Industry Developments
- August 2026: Schaeffler and CATL signed an MoU to co-develop Battery Management Systems and integrated powerbox solutions for Europe, expanding their strategic partnership and building on an existing customer project. (Source: eqs-news.com)
- July 2026: Ather Energy announced a partnership with LICO Materials. With this deal, the company aims to develop a system to collect, recycle, and recover materials from end-of-life Li-ion EV batteries. Under this arrangement, recycling facility of LICO Materials will process Ather's fleet. (Source: autocarindia.com)
- June 2026: Semiconductor Energy Laboratory Co., Ltd. (also known as "SEL") announced the development of Li-ion rechargeable battery. The battery has fire resistance and high energy density. (Source: PRNewswire)
- July 2025: Panasonic Energy Co., Ltd. began operations at its new lithium-ion battery plant in De Soto, Kansas, expanding its North American footprint. The facility produces 2,170 cylindrical cells for EVs and is expected to reach about 32 GWh annual capacity, strengthening Panasonic’s ability to meet rising regional EV demand. (Source: na.panasonic.com)
Future Outlook
As per our lithium-ion battery industry analysis, demand from EVs, energy storage systems, consumer electronics, industrial equipment, and new mobility applications will drive strong market growth in the future. The development in the future will focus on the increasing energy density, faster charging, better safety, longer cycle life and lower cost of production. The LFP and NMC chemistries will continue to be key, with technologies such as silicon anodes and solid-state batteries gaining traction. The increasing BESS penetration will create further demand from beyond the automotive application. Meanwhile, battery recycling, second-life battery usage, localized production, circular economy practices to name a few, will play even greater roles in the future lithium-ion battery industry.
Market Segmentation
By Material Outlook (Revenue, USD Billion; Volume, GWh; 2021–2034)
- Cathode Material
- Lithium Iron Cobalt Oxide
- Lithium Iron Phosphate
- Lithium Nickel Manganese Cobalt
- Others
- Anode Material
- Natural Graphite
- Artificial Graphite
- Others
- Electrolyte Material
- Separator Material
- Current Collector Material
- Others
By Product Outlook (Revenue, USD Billion; Volume, GWh; 2021–2034)
- Components of Lithium-Ion Battery
- Cells
- Battery Packs
- Portability
- Stationary
- Portable
By Type Outlook (Revenue, USD Billion; Volume, GWh; 2021–2034)
- Lithium Nickel Manganese Cobalt Oxide
- Lithium Iron Phosphate
- Lithium Cobalt Oxide
- Lithium Titanate Oxide
- Lithium Manganese Oxide
- Lithium Nickel Cobalt Aluminum Oxide
By Capacity Outlook (Revenue, USD Billion; Volume, GWh; 2021–2034)
- 0 To 3000 mAh
- 3000 To 10000 mAh
- 10000 To 60000 mAh
- 60000 To mAh and above
By Voltage Outlook (Revenue, USD Billion; Volume, GWh; 2021–2034)
- Low (Below 12 V)
- Medium (12 V- 36 V)
- High (Above 36 V)
By Industry Outlook (Revenue, USD Billion; Volume, GWh; 2021–2034)
- Consumer Electronics
- Smartphones
- UPS
- Laptops
- Others
- Energy Storage Systems
- Battery Energy Storage Systems (BESS)
- Residential Energy Storage
- Automotive
- Plug-In Hybrid Vehicles
- Aerospace
- Commercial Aircraft
- Marine
- Commercial
- Tourism
- Medical
- Industrial
- Mining Equipment
- Construction Equipment
- Forklifts, Automated Guided Vehicle (AGV), And Automated Mobile Robots (AMR)
- Power
- Telecommunications
By Regional Outlook (Revenue, USD Billion, Volume, GWh; 2021–2034)
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Lithium-Ion Battery Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 136.39 Billion |
| Market Size in 2026 | USD 153.36 Billion |
| Revenue Forecast by 2034 | USD 406.45 Billion |
| CAGR | 12.90% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Volume, GWh; Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Lithium-Ion Battery Market FAQ's
• The global lithium-ion battery market size was valued at USD 136.39 billion in 2025 and is projected to grow to USD 406.45 billion by 2034.
• The global market is projected to register a CAGR of 12.90% during the forecast period.
• In 2025, Asia Pacific accounted for the largest share of 52.0% in the lithium-ion battery market due to the region's strong presence of key battery manufacturers, rapidly growing electric vehicle (EV) industry, and increasing demand for consumer electronics.
• A few key players in the market are A123 Systems LLC; BYD Company Limited; CALB, China Aviation Lithium Battery Co.; CATL, Contemporary Amperex Technology Co., Ltd.; Clarios; EVE Energy Co., Ltd.; LG Energy Solution Ltd.; Panasonic Holdings Corporation; Samsung SDI Co., Ltd.; SK On Co., Ltd.; Tesla, Inc.; Toshiba Corporation
• A lithium-ion battery is a rechargeable battery using lithium ions to store and release energy, composed of a graphite anode, lithium-based cathode, electrolyte, and separator.
• Lithium cobalt oxide held largest share of 34.0% in 2025, due to its high suitability in small, high energy density battery applications.
• BESS expands battery demand through grid balancing, renewable integration, backup power, and peak management.
• Lithium ions move between the anode and cathode, while electrons deliver electrical power.
• In 2025, the consumer electronics segment held the largest share. Rising demand for portable devices, including smartphones, tablets, and wearables, drives the dominance.
• The cathode material segment accounted for the dominant share of 40.0% in 2025. This is attributed its importance in determining the energy density, voltage, safety, cycle life, and performance of the battery.
Download Sample Report of Lithium-Ion Battery Market
Please fill out the form to request a customized copy of the research report.