
Orthopedic Surgical Robots Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Orthopedic Surgical Robots Market Summary
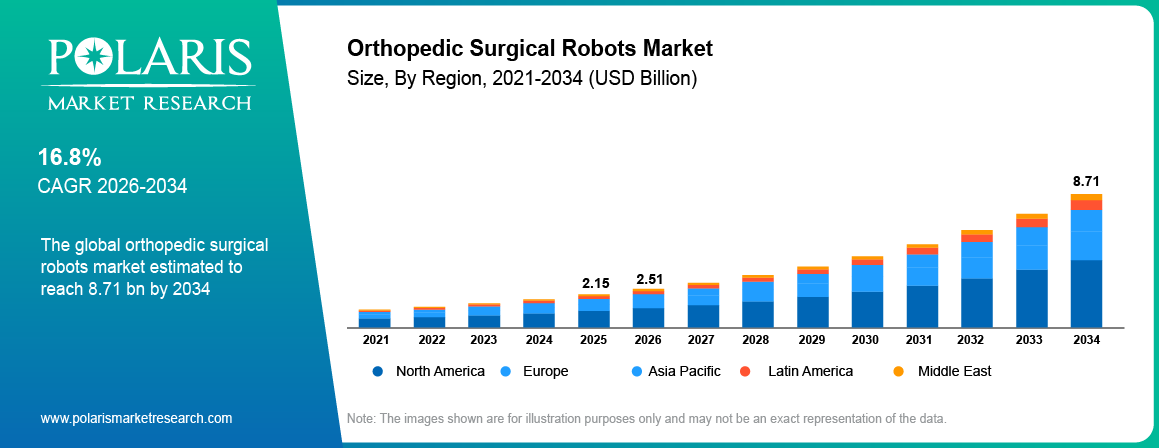
The global orthopedic surgical robots market size was valued at USD 2.15 billion in 2025. The market is projected to account for an 16.8% CAGR from 2026 to 2034. Market growth is supported by the aging population and rising cases of osteoarthritis, along with the wider use of minimally invasive surgery (MIS). Advances in technology and the shift toward ambulatory surgery centers (ASCs) are also supporting demand.
Market Statistics
Orthopedic Surgical Robots Market Key Takeaways
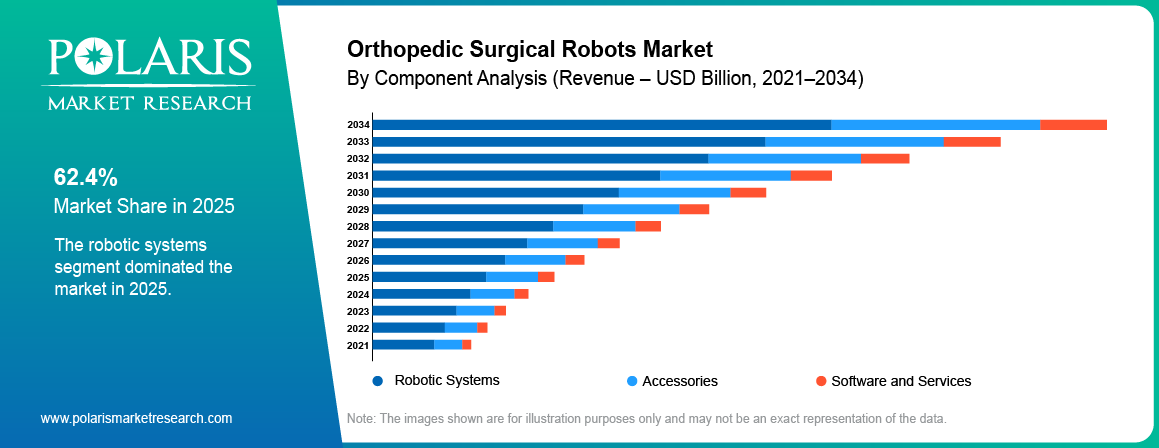
- North America held the largest orthopedic surgical robots market share of 38.6% in 2025. This is owing to the presence of a highly efficient healthcare infrastructure in the region.
- Asia Pacific is projected to witness the fastest growth at an 18.9% CAGR. The introduction of favorable government initiatives is driving the adoption of technologically advanced medical devices.
- By application, the knee segment dominated with a 46.8% share in 2025. The growing prevalence of osteoarthritis drives the segment’s leading position.
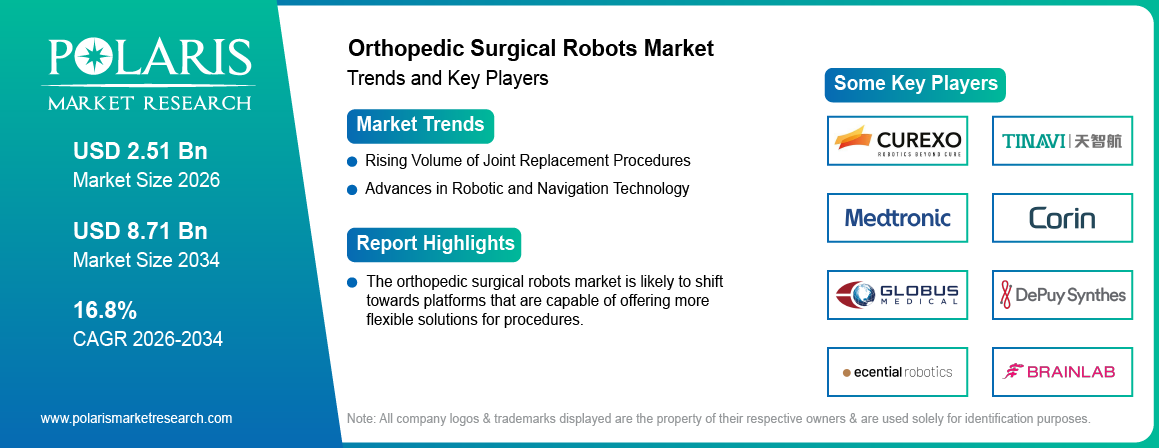
- By component, the robotic systems segment accounted for a 62.4% orthopedic surgical robots market share in 2025. This is because integrated hardware platforms serve as the essential core infrastructure required to execute high-volume joint replacement procedures.
- By end user, the specialty orthopedic clinics segment is projected to grow at an 18.2% CAGR. The shift towards decentralized and patient-centric care drives the segment’s growth.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Are Orthopedic Surgical Robots?
Orthopedic surgical robots are robotic devices that help surgeons during surgeries related to bones and joints. These robots help in the planning and conducting of surgical procedures with more precision. They are used in operations on knees, hips, spines, and other areas. The usage of orthopedic surgical robots is contributing to the development of the orthopedic robotics market.
In simple terms, these robots assist surgeons during surgery. They can be used in planning, preparing the bones, and placing surgical instruments. The surgeon performs and manages the operation. The robot follows the surgical plan and the patient's anatomy.
How Robotic Orthopedic Surgery Works?
Patient evaluation: First, the patient is evaluated to diagnose the disease. Images from an X-ray, a CT scan, or any other imaging may be taken to evaluate the joint that needs surgery.
Surgical planning: From the imaging results, the surgeon plans the surgery. This includes the removal of bone and implantation.
System preparation: The devices used in robotic surgery are assembled before the surgery. The surgeons check the system and load the treatment plan into it.
Patient positioning: The patient is placed on the surgical bed. The joint that is supposed to be operated on is well positioned for the surgery.
Bone preparation: Bone preparation in the case of robotic orthopedic surgery is done using a planned measurement technique. The robotic devices help control the movement of the surgical tools.
Implant placement: Once the bones are prepared, the surgeon places the artificial joint in the joint space. Robot-assisted joint replacement surgery helps in the placement of the implant.
Final assessment: The joint is then assessed by the surgeon after placing the implant. The surgical area is closed, and the patient is moved to recovery.
Orthopedic Robots vs Traditional Surgery
The difference between orthopedic robots vs traditional surgery is in the planning and execution of the surgery itself. Orthopedic robots can help provide additional information to the surgeon performing the surgery. Traditional surgery, however, involves much more direct evaluation of the patient by the surgeon and conventional surgical procedures.
| Factor | Orthopedic Robots | Traditional Surgery |
| Surgical Planning | Utilizes patient imaging for the development of a surgical plan | Based on imaging and assessment of the surgeon |
| Guidance | Gives guidance during bone resection and implant placement | Surgeon depends mostly on visualization and surgical tools |
| Precision | Helps achieve consistency in positioning according to the surgical plan | Highly depends on the skill of the surgeon |
| Role of Surgeon | Surgeon performs the surgery while using robots as assistants | Surgeon performs the surgery themselves |
| Equipment Needs | Needs robotic equipment and personnel to handle the process | Normally utilizes standard surgical tools and equipment |
| Cost | Normally comes with higher equipment and operational costs | Usually has lower specialized equipment costs |
| Training | Training of staff on robotic surgery techniques | Training focuses on conventional surgical methods |
Source: Polaris Market Research Analysis
Evidence from clinical studies shows that robotic assistance could make certain orthopedic operations and measurement techniques more accurate. However, this doesn’t mean that robotic procedures are better for every patient or condition. The results may vary according to the surgeon, type of procedure, implants used, and the characteristics of the patients.
Types of Orthopedic Robotic Platforms
Different orthopedic robotic systems offer varying levels of support during surgeries. There are platforms that are guided manually by the surgeon, while there are those that have a robotic arm that performs certain motions. The shift towards more autonomous platforms is also influencing the way that these platforms are being used in orthopedic surgery.
| Platform Types | Description | Use |
| Handheld Robotic Platforms | The platform is small-sized, and the surgeon operates it manually. It assists in guidance or feedback when the surgeon operates the instrument. | Bone preparation and implant placement |
| Robotic Arm Platforms | Here, the robotic arm manipulates the surgical tool. The surgeon conducts the operation while the robot moves according to the programmed trajectory. | Knee and hip replacement |
| Semi-autonomous Robotic Platforms | These platforms perform certain actions within the limits set by the surgeon. The surgeon intervenes in the procedure and retains control of it. | Bone preparation and joint preparation |
| Autonomous Robotic Platforms | These robots can perform certain operations based on pre-programmed criteria. Human assistance in the procedure is inevitable. | Controlled bone preparation and implant procedures |
Source: Polaris Market Research Analysis
Handheld devices allow more mobility, while robotic arm-based systems allow better guidance when positioning is required. Recent platforms are being designed to incorporate more automation, but the degree of autonomy differs based on the type of platform and surgery.
Orthopedic Surgical Robots Market Dynamics
Driver : Rising Volume of Joint Replacement Procedures
As the population ages, joint replacements are increasing. Osteoarthritis is one of the causes of joint replacement in the knee and hips, especially in older adults. This increases the number of procedures where there is a need for the use of robotics in aiding the procedures. Surgeons are seeking tools to help with implant placement and bone preparation during procedures; hence the increased demand for robotic platforms in orthopedics. This growing demand was evident in Stryker's July 2026 product release. The company introduced its Mako RPS in the U.S. for total knee replacement, where it added the Mako robotic arm system in addition to its robotic handheld system. This system uses intraoperative planning and robotic assistance during bone preparation in the handheld process (source: stryker.com). With increasing numbers of knee and hip replacements being performed, there is growing scope for orthopedic robotic platforms.
Driver : Advances in Robotic and Navigation Technology
Technological advances have expanded the use of orthopedic surgical robots market solutions in surgery. The newer versions of these platforms offer more information for the surgeons during bone preparation and implant positioning. Moreover, the navigation systems have become increasingly interconnected with software and imaging tools. Another area of development is the use of artificial intelligence to process surgical images and identify anatomical landmarks. In June 2026, DePuy Synthes reported the U.S. commercial availability of its VELYS Hip Navigation with AI Assistance for total hip arthroplasty. The technology allows automating image analysis and landmark recognition as well as delivering patient-specific information during surgery (source: jnj.com). Additionally, DePuy Synthes reported that in May 2026, it agreed to acquire the rights to Gemtrack tracking technology for utilization within navigation and robotic platforms for hip, knee, and shoulder surgeries (source: jnj.com). Such advancements have increased the capabilities that orthopedic surgeons can use, and they have helped in the adoption of robotic and navigation systems.
Challenges and Restraints : High Costs, Training Needs, and Uncertain Clinical Value
Orthopedic robotic systems are relatively expensive, which may hamper their implementation, especially in hospitals with a limited budget. Costs related to purchasing the robot may be accompanied by expenses for maintenance, updating software, obtaining special instruments, and staff training. It is important to note that reimbursement can influence the financial justification of robotic surgeries in case of unaccounted technology expenses. Surgeons and the OR team need time to master robotic technologies, which in turn affects operation duration at the start of system implementation. The lack of long-term data is another factor that may prevent the implementation of robots in orthopedics. While robots improved surgical accuracy and implant placement, these gains did not translate into better long-term outcomes. Regulations and approval requirements are also to be considered. Developers should meet specific requirements for certain procedures and use cases before implementing their technology.
Opportunities : Expansion of Robotic Surgery in Ambulatory Surgery Centers
The shift of orthopedic surgeries from hospitals to ambulatory surgery centers (ASCs) enables the use of robots that fit the outpatient workflow. ASC's are likely to have smaller staff and limited space compared with large hospitals. It makes sense to expect an increased need for robots, which are compact and easy to maintain. A handheld robotic system could potentially be better suited for this environment due to a lower amount of equipment needed in comparison to bigger robotic-arm systems. The software for surgical planning and navigation presents an opportunity to grow as demand for technological processes increases.
Opportunities : Development of Handheld and Software-Based Platforms
Handheld systems allow companies to produce smaller and more versatile alternatives to the traditional robotic systems. In addition, the systems may be incorporated into the existing surgical routine without using large robotic systems. Software is another area of development. Better planning, navigation, imaging, and data management capabilities may be implemented into the system without making radical alterations in hardware. Another software improvement option is to develop versatile software applicable to a variety of surgical procedures and instruments. It can make robotic technology more flexible for the demands of orthopedic surgeons and healthcare institutions. Thus, the development of handheld and software-based platforms is presenting orthopedic surgical robots market opportunities.
Trend : Greater Use of Patient-Specific Surgical Planning
Current orthopedic robot planning techniques have shifted toward more personalized approaches based on individual patient anatomy. Surgeries can be planned based on the information collected from imaging before surgery to better match the patient's anatomy. This is especially helpful when general measurements do not fully represent the anatomy of the patient. Personalized planning can also assist surgeons in comparing different positioning of implants before the surgery commences. The strategy is gaining popularity, especially as robotic systems continue integrating with imaging and planning applications. It can help surgeons better visualize the surgery before stepping into the operating room. This shift is creating demand for imaging, planning, and guidance integration platforms.
Trend : Growing Focus on Data Collection During Surgery
The robotic systems used in orthopedic surgeries today collect more and more data throughout the process. This includes data on bone preparation, implant placement, joint alignment, and the movements performed during surgery. Hospitals and vendors can analyze this data to provide better feedback on procedures and plan better in the future. Over time, it will become possible to compare procedures and pinpoint areas where the workflow of surgical operations needs improvement. The emergence of more procedure-level data is thus changing perceptions of robotic systems. They are becoming not only surgical devices but also a source of information to improve orthopedic procedures.
Orthopedic Surgical Robots Market Segmentation
| Segmentation Axis | Segments |
| By Component | Robotic Systems · Accessories · Software and Services |
| By Application | Knee Replacement · Hip Replacement · Shoulder Replacement · Spinal Surgeries · Other Applications |
| By End-User | Hospitals · Ambulatory Surgical Centers · Specialty Orthopedic Clinics · Others |
| By Region | North America (U.S., Canada) · Europe (Germany, UK, France, Italy, Spain, Netherlands, Russia, Rest of Europe) · Asia Pacific (China, Japan, India, South Korea, Malaysia, Indonesia, Australia, Rest of Asia Pacific) · Latin America (Brazil, Mexico, Argentina, Rest of Latin America) · Middle East & Africa (Saudi Arabia, UAE, Israel, South Africa, Rest of Middle East & Africa) |
Source: Polaris Market Research Analysis
By Component
The robotic systems segment accounted for an 62.4% orthopedic surgical robots market share in 2025. This shift is driven by the adoption of this technology in various procedures requiring controlled bone preparation and proper implant positioning. The need for such systems is further fueled by hospitals' desire to integrate systems into existing orthopedic workflows without needing to reconfigure the entire surgical procedure. This segment includes robotic arms, navigation-assisted technology, and other medical devices used during procedures. In addition, technological advances have broadened the range of procedures surgeons can perform. As more orthopedic practices adopt robotic systems, surgical tool expenditures are increasingly directed toward acquiring full-fledged robotic systems.
The software and services segment is projected to grow at an 18.5% CAGR. Demand for this segment is increasing because robot-based surgery requires software to plan, control, manage, and upgrade the systems. Hospitals will need technical expertise to maintain the robot-based platform's functionality in operations. Software upgrades are less expensive than physical machine upgrades, giving manufacturers room to improve their products. Maintenance, training, system support, and equipment management can become additional sources of revenue generation for the players in this industry. As hospitals increasingly use robotic platforms, demand will rise for ongoing software and service support rather than one-time purchases. This creates broader revenue streams for companies operating in this segment.
By Application
The knee segment led the orthopedic surgical robots market with an 46.8% share in 2025. Knee replacement is among the most established applications for orthopedic robots. Robotic systems have been used here owing to the precision that is required for bone cutting and implant placement. The increasing incidence of knee replacement surgery among elderly patients has also helped in growing the potential patient population. Robotic devices can be used by surgeons to plan bone cuts and implant positioning in advance of the surgery. Hospitals have more experience with robotic systems for knee replacement than in other orthopedic applications. This has helped keep the knee surgery segment prominent in robotic adoption. The segment is expected to maintain its leadership as hospitals continue to expand their capabilities for knee replacements and similar procedures.
The spine segment is projected to grow at an 17.6% CAGR. The need for robotic assistance in spine surgeries is increasing because complicated procedures require better manipulation. Spine surgery requires precision and caution because it involves delicate structures. Robotic assistance platforms can provide image guidance to help surgeons navigate operations according to the surgeon's plan. Robotic assistance is used in various procedures, including spinal implants, screw insertions, and deformity corrections. Advancements in imaging and navigation have made robotic platforms more useful in this regard. Some hospitals have installed these platforms as part of their efforts to improve surgical workflows for complex spine surgeries. Robotic spine surgeries have gained popularity among surgeons and other health care professionals; thus, the use of robotic assistance in orthopedics has increased.
| Application | How Orthopedic Robots Are Used |
| Knee Replacement | Robots can assist with bone preparation and help surgeons position knee implants according to the surgical plan. |
| Hip Replacement | Robotic systems can support implant planning and placement while helping the surgeon assess the position of the components. |
| Robotic Shoulder Replacement | Shoulder arthroplasty robots can help with preoperative planning and guide bone preparation and implant positioning during shoulder procedures. |
| Spinal Surgeries | Robotic platforms can assist with surgical planning and guide instruments or implants during procedures such as spinal fusion. |
| Other Applications | Orthopedic robots are also being explored for trauma procedures, revision surgeries, and other bone and joint operations where controlled instrument placement is needed. |
Source: Polaris Market Research Analysis
By End-User
The hospitals segment accounted for the largest orthopedic surgical robots market share of 68.2% in 2025. Hospitals perform a wide variety of orthopedic procedures, creating greater potential for robotic systems. Additionally, many complex conditions require careful surgical planning and orthopedic specialists. There is potential for the use of the robotic platform in many departments, such as joint replacements and spinal surgery. All of these factors create greater opportunities for more frequent application of the technology. Hospitals have well-established processes of preoperative evaluation, surgical process, and postoperative care of patients. Moreover, hospitals' role in treating patients with complex orthopedic conditions further drives the use of robotic systems. Thus, hospitals will continue to be the main users of robotics technology in orthopedic surgery.
The specialty orthopedic clinics segment is anticipated to grow at an 18.2% CAGR. These clinics specialize primarily in musculoskeletal problems, which helps them develop a service portfolio of orthopedic operations. This can facilitate the implementation of robots intended for particular joint surgery and other orthopedic procedures. Moreover, clinics face increasing pressure from patients who want to undergo a specific treatment procedure but not in large hospital organizations. With the miniaturization of robotic platforms, it has become easier for clinics to integrate them into their surgical process. Having access to an orthopedic team will also encourage the implementation of robotic systems. Therefore, the development of specialty care among clinics opens up more space for the introduction of robotic technology into orthopedic clinics.
| End User | Analysis |
| Hospitals | Hospitals remain the main users of orthopedic robotic systems. They handle a high number of orthopedic cases and offer several types of surgical services. This gives hospitals more opportunities to use robotic technology across different procedures. |
| Ambulatory Surgical Centers | The use of orthopedic robotics ambulatory surgery center solutions is growing as more orthopedic procedures move to outpatient settings. Knee replacement is one area where these systems can be used. Interest in ASC robotic knee replacement is also linked to the growing number of planned procedures performed in same-day surgical settings. |
| Specialty Orthopedic Clinics | These clinics deal mainly with bone, joint, and musculoskeletal conditions. Their focused patient base can support robotic use in selected orthopedic procedures. Adoption may be stronger where clinics perform a regular volume of elective surgeries. |
| Others | The others segment covers healthcare facilities and specialized surgical settings outside the main end-user groups. Use of robotic systems in these facilities depends on the procedures performed and the level of orthopedic care available. |
Source: Polaris Market Research Analysis
Use Cases: Where Orthopedic Robots Are Used
| Use Case | Platform Examples | Typical Setting |
| Knee procedures | Mako SmartRobotics, ROSA knee, VELYS, and CORI are used for robotic-assisted knee procedures. Platform selection can vary by surgeon preference, implant system, and hospital setup. | Hospitals and ambulatory surgical centers |
| Hip procedures | Robotic and navigation platforms support planning and component positioning during hip procedures. Mako SmartRobotics is used in robotic-assisted hip surgery, while other systems may combine navigation with intraoperative guidance. | Mainly hospitals, with selected use in outpatient settings |
| Spine procedures | Mazor X and ExcelsiusGPS are designed for spinal applications. They support surgical planning and guidance for instrument and implant placement. | Hospitals and specialized spine centers |
| Shoulder procedures | Robotic and navigation technologies can be used to support planning and positioning in shoulder arthroplasty. Platform use depends on the procedure and available technology. | Hospitals and specialty orthopedic facilities |
| Complex and revision procedures | TSolution One and other robotic platforms can be used in selected complex orthopedic cases where detailed planning and controlled bone preparation are needed. | Hospitals and specialized orthopedic centers |
Source: Polaris Market Research Analysis
AI in Orthopedic Robotics
Artificial intelligence (AI) is positively impacting the orthopedic surgical robots market. AI in orthopedic robotics is enhancing the software capabilities of robotic surgery systems. Surgical planning using AI involves analyzing medical images and developing a surgical plan that can include measurements, anatomical references, and implant placement suggestions. Another application of AI-assisted surgery is decision support through consolidating the information needed for the surgical team. Another application is analytics. The data obtained from the surgical procedures is analyzed to determine the surgical performance and results. These are applications of AI that provide more information to surgeons without stripping them of control of the procedure. AI has been integrated into imaging and robotic technology to enhance personalized surgical workflows.
Surgical Navigation Systems
These devices allow for tracking of surgical instruments and anatomical structures throughout the surgical process. Some orthopedic navigation systems use images that create a digital model of the operating field. Three-dimensional visualization allows surgeons to determine the position of surgical instruments and implants. Other systems may include haptic boundaries that define areas where the instruments can or cannot enter. This can help in planning the preparation of bone tissue and implant placement. Navigation technologies are used together with robotic systems and standard surgical tools.
Digital Orthopedics & Smart Operating Rooms
In digital orthopedics, imaging, patient data, surgical instrumentation, and procedural data all come together. A smart operating room integrates information from various systems into a single cohesive process. EHR data and medical imaging could be available, along with data from surgical planning procedures. This supports improved data flow prior to and during the procedures. Smart surgical robots can also interface with other healthcare mobile robot systems and hospital software. Integration with systems like medical telepresence robots can reduce manual data transfer and give the surgical team a more complete view of the procedure.
Benefits of Robot-Assisted Orthopedic Surgery
Robot-assisted orthopedic surgery offers potential benefits for certain bone and joint procedures. One primary benefit is the control gained during surgery. Robotic systems can operate based on a preoperative plan and provide data during surgery. It might help surgeons maintain the planned surgical approach.
The technology can also facilitate uniform bone preparation. This is important in cases where the difference in the removal of the bone will influence the implant fitting. Better control can help the surgeon ensure that the intended implant position is attained. The robot can help get precise measurements that cannot be easily done visually.
One advantage is the ability to use the information during the surgery in an efficient manner. With digital tools and robotics, all necessary measurements and additional information regarding the procedure can be stored and used at a later date to evaluate surgical performance.
In some cases, robotic assistance can make minimally invasive orthopedic surgeries possible. Smaller incisions mean less damage to adjacent tissues, but the effectiveness of this advantage depends greatly on the procedure being performed.
Research has confirmed the benefits of robotic assistance in orthopedic procedures, particularly in implant placement precision and overall procedure quality. Improved device placement, however, doesn't necessarily lead to better patient outcomes. Outcomes depend on the procedure, the patient, the implant, and even the surgeon's experience.
Economics and Hospital Adoption
The financial side of robotic surgery is an important consideration for any healthcare organization. The initial investment can be substantial as robotic systems involve special equipment and installation of additional infrastructure. Apart from that, hospitals need to take into account yearly expenses related to maintenance of the robotic system, updating its software, procurement of special surgical instruments, and so on.
Disposable devices add to the cost of orthopedic surgical robot procedures. This means that the volume of procedures carried out using the robot becomes critical when it comes to the economic aspect. High utilization helps to spread out the fixed costs over many procedures. Few procedures can make the investment harder to justify.
The return on investment (ROI) goes beyond the acquisition price. The hospital needs to examine operating expenses, the number of procedures performed, and staff needs, along with changes in surgical efficiency. They can also consider whether one robot can be used for multiple procedures or is limited to a single type of procedure.
All of these elements affect the decision-making process when hospitals compare the value of using the robotic platforms. Vendors are offering various payment options for equipment and services to lower the hospital's financial burden. Thus, adoption depends more on the suitability of robotic technology in terms of procedure volume and cost.
Regional Analysis
North America
The North America orthopedic surgical robots market led with an 38.6% share in 2025. The region has a developed orthopedic treatment network, where a high number of procedures are performed annually. The U.S. forms a significant share of regional demand owing to the presence of several orthopedic devices and technology companies in the country. In addition, Canada is adding to the regional market because of growth in advanced surgical treatment. Hospitals and surgery centers are becoming more interested in robotics for conducting operations that need thorough planning and precision. In addition to this, there exists a developed pool of orthopedic surgeons who are able to adopt newer technologies for surgical operations. Development in clinical research and product development is further aiding in bringing new robotic platforms to the market. Access to advanced medical technology is another driving force behind regional demand.
Asia Pacific
The orthopedic surgical robots market Asia Pacific is projected to grow at an 18.9% CAGR. The growth in the region is driven by the increase in advanced orthopedic care in major healthcare providers. Countries like China, Japan, South Korea, and India are showing increasing interest in surgical technologies capable of handling complex surgeries. The orthopedic surgical robots market India is also growing due to increased investment by hospitals in major cities in advanced surgical technologies and orthopedic services. Japan and South Korea have built up the medical technology industry, while China has invested in advanced healthcare infrastructure and medical devices. Rising healthcare spending in some countries has improved access to advanced surgical technologies. Moreover, the region is home to a large number of patients with orthopedic conditions. This creates a broad base for future demand.
Europe
The Europe orthopedic surgical robots market accounted for an 27.4% share in 2025. Countries such as Germany, the UK, France, and Italy have implemented orthopedic care programs that help promote adoption of advanced surgical technologies. Moreover, the demand for advanced surgical technologies is further fueled by the region's growing elderly population and, therefore, the need for joint and orthopedic surgery. Healthcare organizations are considering robotic solutions to facilitate the expansion of their surgeries and procedure uniformity. Germany has a strong medical technology industry. The UK and France are investing in surgical infrastructure. Moreover, European hospitals are now focusing more on clinical proof when evaluating robotic technologies. This means procedure success rates, training needs, and value play a significant role in the decision-making process.
Latin America
The Latin America orthopedic surgical robots market is projected to grow at an 15.2% CAGR. Brazil and Mexico are projected to account for a large share of demand in the region as healthcare providers seek ways to expand access to innovative orthopedic solutions. Private hospitals are a major component of the market because these surgical procedures can be performed in large cities with well-established facilities. The development of hospital infrastructure is contributing to better adoption of robotics. There is growing interest in robotic devices that can assist doctors in carrying out difficult procedures and planning surgeries. Yet, the high cost of the platforms and the need to train personnel may limit adoption in countries that have different healthcare systems. Greater access to training can help address the challenge. With increasing investments in the provision of specialist orthopedic services, the use of robots is expected to become more common in the region.
Middle East & Africa
The Middle East & Africa orthopedic surgical robots market is anticipated to account for an 13.8% CAGR. Adoption is supported by investments in advanced healthcare infrastructure facilities, especially in Gulf countries such as Saudi Arabia and the UAE, where there is an improvement in the level of specialized medical facilities and hospital infrastructure. There is therefore increased room for advancement in orthopedic robotic technology in such hospitals and medical facilities. South Africa, on the other hand, has an existing private healthcare system which may favor adoption of robotic surgery platforms. Demand is tied to rising orthopedic cases and the presence of specialized surgeons in medical institutions. At the same time, high equipment prices and disparities in healthcare infrastructure may restrict adoption in some African countries. Adoption also requires training and technical expertise. With ongoing investment in the healthcare sector, the region will gradually adopt orthopedic robotic technology.
Competitive Landscape and Key Players
The orthopedic surgical robots market is characterized by competitive dynamics based on product capability, procedure breadth, and relationships with hospitals. The industry is expanding its robotic technology across various orthopedic procedures rather than specializing in any one application. In terms of innovation, there is a trend towards increasing integration of imaging, navigation, planning software, and information management systems.
Competition levels are influenced by unit sales and the training and support companies provide. Hospitals also consider compatible instrumentation and how easily the platform integrates into the surgical process.
The positioning of orthopedic surgical robots market companies varies by geography and procedure type. Established market leaders have a wider array of product lines and larger installed bases. New entrants enter the market with advanced platforms and software capabilities. Market share by company depends on system sales, recurring revenue from accessory and service sales, procedure volume, and geographic presence. Competition will continue to center on platform extension and healthcare provider partnerships.
Vendor Positioning
| Vendor | Flagship orthopedic robotics | Core strength |
| Beijing Tinavi Medical Technologies Co., Ltd. | Tianji Robot | Spine surgery, orthopedic navigation, robotic-assisted implant placement |
| Brainlab AG | Cirq Robotic Alignment System; Spine & Trauma Navigation | Surgical navigation, image-guided surgery, digital planning |
| Corin Group | Optimized Positioning System (OPS) | Patient-specific planning, hip and knee arthroplasty, implant positioning |
| Curexo, Inc. | CUVIS-joint | Robotic-assisted knee surgery, bone preparation, implant positioning |
| DePuy Synthes | VELYS Robotic-Assisted Solution; VELYS Hip Navigation | Knee and hip arthroplasty, navigation, AI-assisted surgical planning |
| eCential Robotics | eCential Robotics Unified Spine System | Spine surgery, navigation, robotic guidance, integrated surgical platform |
| Globus Medical, Inc. | ExcelsiusGPS; Excelsius3D | Spine surgery, robotic guidance, navigation, implant placement |
| Medtronic plc | Mazor X Stealth Edition | Spine surgery, surgical planning, navigation, robotic guidance |
| CORI Surgical System | Knee and hip surgery, handheld robotics, image-based planning | |
| Mako SmartRobotics; Mako RPS | Knee, hip, spine, shoulder; implant ecosystem | |
| THINK Surgical, Inc. | TMINI; TSolution One | Active robotic surgery, implant-agnostic systems, knee arthroplasty |
| Zimmer Biomet Holdings, Inc. | ROSA Robotics; ROSA Shoulder; ROSA Spine | Knee, hip, shoulder, spine; robotic assistance and implant compatibility |
Source: Polaris Market Research Analysis
Recent Industry Developments
-
September 2026: Smith+Nephew received FDA 510(k) clearance for the LANDMARK Total Knee System and completed its first surgical case. The implant is designed for use with the CORI KNEE Handheld Robotics platform. (source: smith-nephew.com)
-
September 2026: Enovis entered into a binding offer to acquire eCential Robotics for upfront enterprise value of €155 million. The deal is intended to expand Enovis' capabilities in orthopedic robotics and surgical navigation. (source: enovis.com)
-
September 2026: Stryker announced new orthopedic technology at the 2026 AOFAS Annual Meeting, including Prophecy Surgical Planning for the Incompass Total Ankle System. (source: stryker.com)
Future of the Orthopedic Surgical Robots Market
The orthopedic surgical robots market is likely to shift towards platforms that are capable of offering more flexible solutions for procedures. Greater compatibility with different implant manufacturers may provide hospitals with higher flexibility when choosing equipment. Moreover, developers are expected to target platforms that are suitable for various orthopedic procedures. Clinical evidence is anticipated to play an important role in the purchase decision process, as hospitals compare robotic procedures with traditional surgery. Additionally, more emphasis will be placed on training procedures and integration of orthopedic robots in surgical practice. These trends can positively impact the adoption of orthopedic robotics in various medical settings.
Research Methodology
This orthopedic surgical robots market study covers the market for robotic systems, accessories, software, and services used in orthopedic procedures. The scope includes knee, hip, shoulder, and spine surgeries. Soft-tissue surgical robots are outside the scope of this study. Market values are presented in USD million, with 2025 used as the base year.
The research draws on company filings, investor presentations, regulatory records, clinical studies, medical journals, trade publications, and industry conference material. Sources from organizations such as the FDA, WHO, and AAOS have also been considered where relevant.
The orthopedic surgical robots market estimates have been developed using information on robotic system sales, procedure volumes, accessories, software, and related services. These numbers are assessed across application, end user, and geographic markets. Estimates are verified through company reports and industry information.
The forecast has been made taking into account the volume of orthopedic procedures performed, the technology, healthcare expenditures, and regulatory environment. These findings are compared among various sources prior to preparing the final market estimates and forecasts.
Orthopedic Surgical Robots Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 2.15 billion |
| Market Size Value in 2026 | USD 2.51 billion |
| Orthopedic Surgical Robots Market Forecast 2034 | USD 8.71 billion |
| CAGR | 16.8% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Orthopedic Surgical Robots Market FAQ's
Orthopedic robots are machines used to aid surgeons in bone and joint surgeries. These robots are used for tasks such as surgical planning, bone cutting, and implant positioning. The surgeon controls the procedure.
The global orthopedic surgical robots market was valued at USD 2.15 Billion in 2025. It is estimated to reach USD 8.71 Billion by 2034. The market is expected to grow at a CAGR of 16.8% from 2026 to 2034.
Based on application, the knee segment accounted for an 46.8% orthopedic surgical robots market share in 2025. The growing prevalence of osteoarthritis drives the leading market position of the segment.
Some of the major orthopedic surgical robots market companies are Beijing Tinavi Medical Technologies Co., Ltd.; Brainlab AG; Corin Group; Curexo, Inc.; DePuy Synthes; eCential Robotics; Globus Medical, Inc.; Medtronic plc; Smith & Nephew plc; Stryker Corporation; THINK Surgical, Inc.; and Zimmer Biomet Holdings, Inc.
In most cases, a robot-assisted procedure begins with obtaining imaging and planning a surgical process. During the surgery, the surgeon uses the robot to perform certain parts of the operation. It might involve instrument guidance, bone preparation, and implant positioning. The surgeon remains responsible for the entire process and may make changes if needed.
Yes, they are safe and might increase accuracy when performed by skilled surgeons. Studies have proved that robotic assistance could lead to better outcomes in certain orthopedic procedures. However, the effect may differ depending on variables such as the surgeon, procedure type, implants used, and the patient.
There isn't a specific price for an orthopedic surgical robot. It differs depending on the system itself and may involve the robot itself, software, instrumentation, installation, and service. Hospitals also incur expenses after purchasing the system.
Asia Pacific is projected to account for the fastest growth at an 18.9% CAGR. Favorable government initiatives are driving adoption of advanced medical devices in the region.
Download Sample Report of Orthopedic Surgical Robots Market
Please fill out the form to request a customized copy of the research report.


