Prescription Drugs Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Prescription Drugs Market Summary
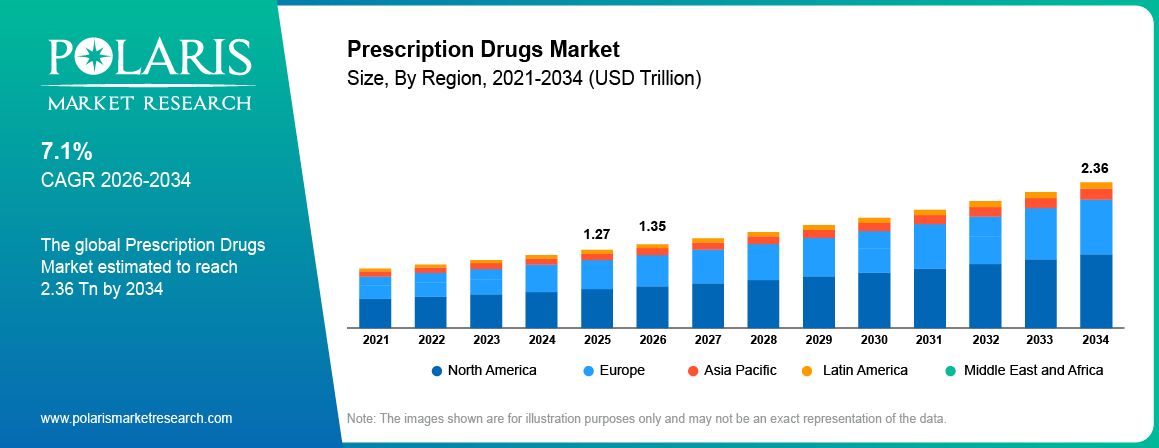
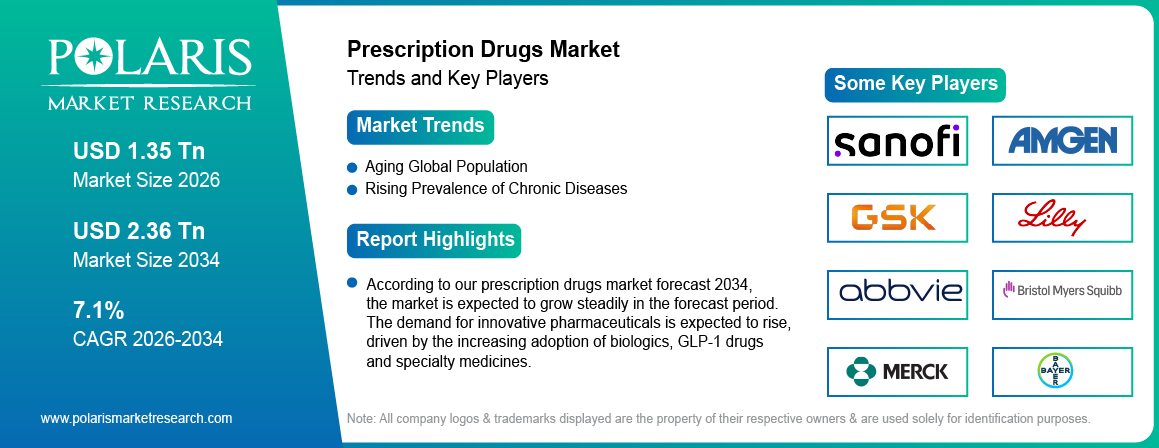
The global prescription drugs market size was valued at USD 1.27 trillion in 2025, and is expected to record a CAGR of 7.1% from 2026 to 2034. Increased healthcare spending and access and the rising focus on technological and scientific innovation drive the market growth. Also, increasing aging global population and growing prevalence of chronic diseases fuel the market expansion.
Market Statistics
Prescription Drugs Market Key Takeaways
- North America dominated the global market with a 49.6% revenue share in 2025, attributed to its advanced healthcare infrastructure, high adoption of novel therapies, strong pharmaceutical R&D investments, and favorable reimbursement policies.
- The U.S. accounted for 72.4% of the North American market in 2025. Its leading position is supported by a sophisticated healthcare system, rapid uptake of innovative CNS therapeutics, a strong pipeline of pharmaceutical products, and a high prevalence of neurological and psychiatric disorders.
- Asia Pacific is projected to register the fastest CAGR of 9.8% during the forecast period. Rising healthcare expenditure, improving access to prescription medications, expanding healthcare infrastructure, and a growing health-conscious middle-class population are expected to accelerate regional market growth.
- The Alzheimer's segment generated the highest revenue share of 21.7% in 2025. Growth is driven by the increasing prevalence of Alzheimer's disease among the aging population, greater awareness of early diagnosis, and the need for long-term disease management.
- The Parkinson's segment is expected to witness the fastest CAGR of 10.4% during the forecast period. The increasing global incidence of Parkinson's disease, growing geriatric population, and rising demand for advanced long-term therapeutic management continue to drive segment growth.
- The branded drugs segment held the largest revenue share of 58.4% in 2025. This is supported by constant innovation and new product launches in the industry.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Is the Prescription Drugs Market?
Prescription drugs include medicines that are used to prevent, manage, and treat various diseases and health conditions. The prescription drugs market covers the development, manufacturing, distribution, and sale of prescription drugs. These drugs require approval from a licensed healthcare professional before use.
Healthcare spending and access are rising as both public and private investments continue to strengthen healthcare infrastructure globally. According to the American Hospital Association, health spending in the U.S. alone was USD 5.7 trillion in 2025, which is an increase of 7.3% from the previous year, 2024. Increasing personalized medicine, government initiatives, and expanding access to hospitals and pharmacies are enabling larger sections of the population to access medical treatment and prescribed therapies. This growing accessibility boosts demand and supports greater adherence to prescribed regimens, reinforcing the critical role of prescription drugs in improving patient outcomes.Further, rising demand for biosimilars, specialty drugs, and blockbuster drugs fuels the market expansion (Source: aha.org).
Technological and scientific innovation, which is transforming drug development and delivery, further drives growth opportunities. Advances in biotechnology, genomics, and precision medicine are creating the way for more targeted therapies, enhancing both the effectiveness and safety of treatments. For instance, in July 2026, Casgevy (exagamglogene autotemcel) received the U.S. FDA approval. It can be used for patients aged 2 years and above with sickle cell disease (SCD) with recurrent vaso-occlusive crises (VOCs) or transfusion-dependent β thalassemia (TDT). The integration of digital health technologies, such as AI-driven drug discovery and smart drug delivery systems, further supports faster development cycles and improved patient compliance. These innovations are expanding the therapeutic potential of prescription drugs while also addressing unmet medical needs, thereby positioning the industry at the forefront of modern healthcare transformation (Source: fda.gov).
Branded vs Generic vs Orphan Drugs: Key Differences
Branded drugs are original medicines developed and marketed under a company name. Generic drugs contain the same active ingredient but are usually sold at lower prices after patent expiry. Orphan drugs are developed to treat rare diseases affecting a small number of patients and often receive special regulatory support.
| Attribute | Branded Drugs | Generic Drugs | Orphan Drugs |
| Patent protection | Yes. Market exclusivity during patent term | No. Sold after branded patent expiry | Often yes, plus extended regulatory exclusivity for rare-disease indications |
| Relative drug pricing | Highest | Lowest (typically 50–90% below branded price) | Very high per-patient cost due to small patient populations |
| Typical development cost/timeline | Highest. Full clinical trial pathway | Lower. Bioequivalence studies only | High, but often eligible for expedited/incentivized regulatory pathways |
| Market share pattern | Largest revenue share despite fewer prescriptions | Largest prescription volume (often 8–9 of 10 U.S. scripts) | Smallest volume, fastest-growing revenue segment |
| Example use cases | Novel oncology drugs and CNS therapies under patent | Cardiovascular drugs, antidiabetic, and antibiotic staples off patent | Rare metabolic, hematologic, and genetic disorders |
Source: Polaris Market Research Analysis
AI Impact on Prescription Drugs
- AI algorithms analyze vast biological datasets to identify new drug candidates and predict their effectiveness. AI drug discovery reduces the time and cost associated with early-stage research.
- The adoption of AI improves trial design by selecting ideal participants and predicting outcomes. It also enhances monitoring for safety and efficacy, resulting in faster and more successful trials.
- It analyzes patient data to predict individual responses to medications, enabling more personalized and effective treatment plans and dosing.
- The technology is used to forecast drug demand and optimize manufacturing processes. It also helps manage inventory, reduce costs and prevent shortages across the pharmaceutical supply chain.
Market Dynamics
Driver: Aging Global Population
The aging global population is driving the adoption of prescription drugs, as older adults typically require more frequent medical care and long-term treatment for age-related conditions. According to a February 2025 report by the World Health Organization, the worldwide number of individuals aged 60 and older is projected to increase from 1.1 billion to 1.4 billion by 2030. There is a higher incidence of diseases such as arthritis, cardiovascular disorders, neurodegenerative conditions, and other chronic ailments that demand continuous pharmacological intervention with increasing life expectancy. This demographic shift places prescription drugs at the center of healthcare management, ensuring sustained demand across therapeutic categories. Furthermore, advancements in geriatric medicine and the development of tailored formulations specifically designed for older patients continue to enhance the role of prescription drugs in improving quality of life and managing complex health needs among aging populations.
Driver: Rising Prevalence of Chronic Diseases
The rising prevalence of chronic conditions is boosting the demand for prescribed drugs for chronic disease management. Conditions such as diabetes, cancer, cardiovascular diseases, and respiratory disorders require long-term treatment regimens. According to the Centers for Disease Control and Prevention, 60% of younger adults aged 18–34 in the U.S. have at least one chronic condition. Lifestyle changes, urbanization, and genetic predispositions have contributed to the increasing global burden of chronic illnesses, making prescription drugs essential in disease management and prevention of complications. Continuous medication is often essential for maintaining patient stability, reducing hospitalizations, and improving survival rates, which highlights the critical role of prescription drugs in modern healthcare. The demand for innovative and effective drug therapies is expected to remain robust across all age groups as chronic diseases increasingly affect younger demographics (Source: cdc.gov).
Driver: Rising Focus on Sustainable Pharmaceutical Manufacturing
Sustainability is emerging as one of the key priorities among pharmaceutical producers seeking to minimize their impact on the environment, without compromising on the quality of products or failing to comply with all necessary regulatory requirements. Companies are increasingly applying eco-friendly manufacturing practices and striving to increase energy efficiency, reduce waste generation, and use raw materials in a more rational manner. Companies are also reducing water use, lowering greenhouse gas emissions, and improving pharmaceutical waste disposal through various measures. Manufacturers are also focusing on implementing environmentally safe manufacturing technology and packaging of the products. The increasing pressure from regulators and consumers regarding sustainable practices will make sustainability even more important in the future development of pharmaceutical manufacturing.
Restraint: High Drug Development Costs
High development costs can restrain the prescription drugs market growth. This process requires substantial amounts of time and money to bring a new drug to market. Additionally, companies need to conduct clinical trials and meet stringent approval guidelines. Such conditions raise the financial barrier for pharmaceutical companies. Smaller firms face such a financial burden as they do not have the resources to fund long-term research and development processes. Failed trials can inflict additional losses on the firms. Moreover, large-scale development costs lead to higher drug prices, restricting patient access in lower-income countries. Thereby, restraining the growth of the prescription drugs market.
Restraint: Patent Expiry and Generic Competition
Patent expiry presents a major challenge to pharmaceutical companies. New generic producers introduce their versions of the drug, which are usually considerably cheaper than the original. Such competition can cause a significant drop in sales of the developing company, adversely impacting its revenues. Additionally, intense price competition reduces profit margins for the original producers. Generic drugs are further more attractive to the cost-conscious healthcare sector as they provide similar clinical outcomes at a lower price. Therefore, as more drugs lose their patent protection, branded manufacturers face the threat of lower sales and profits. Thus, patent expiry and generic competition can restrain the growth of the global prescription drugs industry.
Opportunity: Shift Toward Personalized Medicine
Personalized medicine is being increasingly practiced in the healthcare industry, in which medication is determined through a combination of genetics, disease, and individual health characteristics of patients. Research into genetic analysis and biomarker-driven therapy will facilitate the identification of medications likely to work better in specific cases, hence improving drug efficacy and lowering the likelihood of adverse reactions. Pharmaceutical firms have been focusing their efforts on developing targeted medications as well as diagnostics that determine whether a certain drug is likely to benefit a particular individual, and this is particularly critical in oncology. As personalized medicine continues to develop, pharmaceutical companies are expected to develop novel approaches to drug design and prescription, offering growth prospects for the prescription drugs share.
Prescription Drugs Market Trends
Technological Advancements in Drug Development
Technological advancements are enabling the development of new drug modalities. Pharmaceutical companies are developing advanced treatments such as biologics, cell therapies, gene therapies, and RNA-based medicines. These treatments are capable of addressing disease pathways that traditional therapeutics cannot. Additionally, these treatment classes provide an effective cure for several diseases such as cancers, genetic diseases, and rare diseases. Moreover, technological advancements in research and manufacturing processes enable pharmaceutical companies in developing these new drug modalities. Additionally, a rise in investment in innovative pharmaceuticals will fuel the expansion of the market in the future.
Growing Pipeline of Next-Generation GLP-1 and Biologic Drugs
An increase in chronic disease prevalence and the rising need for personalized treatment have fueled the demand for GLP-1 receptor agonists. GLP-1 drugs market impact is positive on the prescription drugs industry, due to emerging weight-loss drug market trends. Players in the market are focusing on expanding their drug pipeline with new candidates for obesity, diabetes, cardiovascular disease, cancer, and orphan diseases. According to the Obesity Medicine Association, Amgen is developing MariTide injection for weight loss and type 2 diabetes, which entered phase 3 clinical trials in March 2025. Furthermore, the need for pharmaceuticals is being driven by the growing focus on developing more effective targeted therapeutics. Advanced GLP-1 drugs are being developed to improve the efficacy of treatment while minimizing the side effects. Key players are also developing oral formulations to simplify administration and improve patient compliance. For instance, in January 2025, FDA approved JOURNAVX (suzetrigine) oral formulation developed by Vertex Pharmaceuticals for moderate-to-severe acute pain. The pipeline candidates are expected to drive the prescription drugs market in the forecast period with the growing R&D investment in the development of blockbuster biologics (Source: obesitymedicine.org, news.vrtx.com).
Major Pipeline Drugs
| Drug (Candidate) | Sponsor/Company | Therapy Area | Indication (Key) | Development Stage (2026) |
| Lorundrostat | Mineralys Therapeutics | Cardiovascular | Treatment‑resistant hypertension | Phase 3 complete; NDA accepted by FDA |
| Mezigdomide | Bristol Myers Squibb | Oncology / Hematology | Relapsed/refractory multiple myeloma (combo) | Phase 3 complete; NDA accepted by FDA |
| Atirmociclib | Pfizer | Oncology | HR+/HER2‑negative breast cancer (next‑gen CDK4 inhibitor) | Phase 3 |
| Muvalaplin | Eli Lilly | Cardiovascular / Metabolic | Elevated lipoprotein(a); CV risk reduction | Phase 3 (CV outcomes trial) |
| Elecoglipron | AstraZeneca | Metabolic / Obesity | Obesity / weight management (oral GLP‑1 pathway) | Phase 3 (after positive Phase 2b) |
| Orforglipron | Eli Lilly | Metabolic / Obesity | Obesity / type 2 diabetes (oral GLP‑1 RA) | Phase 3 |
| Darolutamide (new regimens) | Bayer / Orion | Oncology | Adjuvant / high‑risk hormone‑sensitive prostate cancer | Phase 3 |
| Finerenone (new indications) | Bayer | Cardiovascular / Renal | Non‑diabetic chronic kidney disease | Phase 3 |
| Olverembatinib | Ascentage Pharma | Oncology | BCR‑ABL1 T315I‑mutant CML / Ph+ leukemias | Global Phase 3 / registration‑enabling |
| Lisaftoclax (APG‑2575) | Ascentage Pharma | Oncology / Hematology | CLL and other hematologic malignancies (BCL‑2 inhibitor) | Multiple Phase 3 trials |
| Plozasiran | Arrowhead Pharmaceuticals | Metabolic / Cardiovascular | Severe hypertriglyceridemia (apoC‑III siRNA) | Phase 3 |
| Eplontersen | Ionis Pharmaceuticals / AstraZeneca | Rare disease / Cardiovascular | Transthyretin‑mediated amyloid cardiomyopathy | Phase 3 |
| Ritlecitinib | Pfizer | Immunology / Dermatology | Nonsegmental vitiligo (JAK3/TEC inhibitor) | Phase 3 |
| Elafibranor | Ipsen | Hepatology | Primary biliary cholangitis (PPAR agonist) | Phase 3 |
| Ravulizumab (new indications) | AstraZeneca / Alexion | Immunology / Hematology | TMA post‑HSCT and other complement‑mediated disorders | Phase 3 |
| TLX591‑Tx (¹⁷⁷Lu‑rosopatamab) | Telix Pharmaceuticals | Oncology | Prostate cancer (radioligand therapy) | Pivotal / late‑stage |
| TLX101‑Tx (¹³¹I‑iodofalan) | Telix Pharmaceuticals | Oncology | Recurrent glioblastoma (radioligand therapy) | Pivotal / late‑stage |
| Zasocitinib | Takeda | Immunology / Dermatology | Psoriasis (JAK inhibitor) | Late‑stage / registration in some regions |
| Rusfertide | Takeda / Protagonist | Hematology | Polycythemia vera (TMPRSS6 inhibitor) | Late‑stage / registration path |
| Orzefy / ORZEYFUL (daridorexant‑class) | Takeda / Idorsia | Neurology | Narcolepsy type 1 (orexin‑2 receptor agonist) | Late‑stage / early launch in some markets |
Source: Polaris Market Research Analysis
Segmental Insights
Product Type Analysis
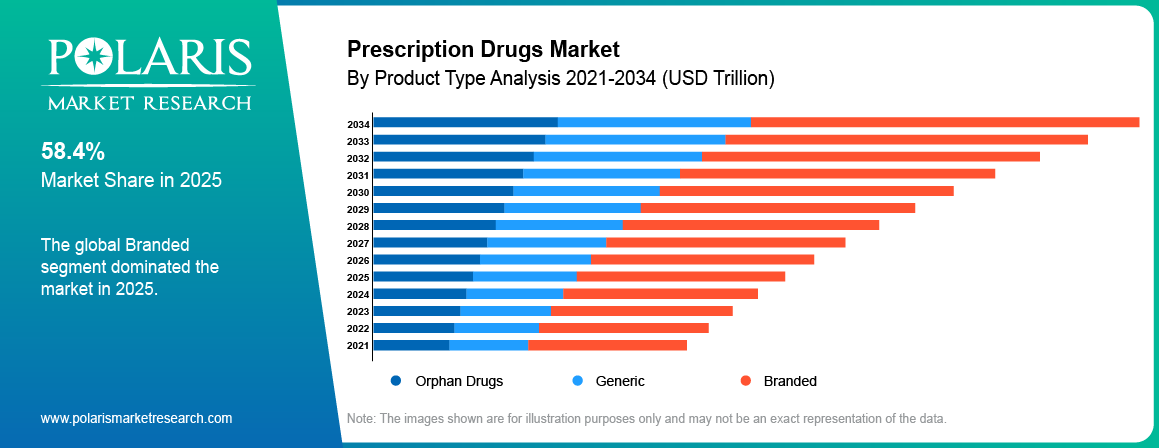
Based on product type, the segmentation includes branded, generic & orphan drugs. The branded drugs segment accounted for largest revenue share of 58.4% in 2025 driven by constant innovation and new product launches in the industry. The increasing demand for advanced treatment options for diseases such as cancer, diabetes, and auto-immune disorders is likely to propel the segment’s growth. Additionally, the increase in research and development activities in the pharmaceutical industry is further anticipated to drive the expansion of the branded drugs segment. Companies are concentrating on developing innovative therapeutics with patents to offer better treatment options, thereby driving the segment growth.
The generic drugs segment is expected to record significant growth of CAGR 7.2% during the forecast period driven by the increase in need for cost-effective treatment alternatives. The expiry of patent-protection of many branded drugs is also a fueling the growth of this segment. Furthermore, governments across the world are encouraging the use of generic drugs to provide affordable treatment options to populations in need. The growing healthcare industry across developing countries and the overall demand for cost-effective treatment alternatives are further driving the segment growth.
The orphan drugs segment is expected to witness a CAGR of 8.1% during the forecast period, driven by the increasing focus on the treatment of rare diseases. Advancements in genetic research and biotechnology have enabled pharmaceutical companies to develop potential therapeutics for various rare diseases. Government incentives for the treatment and management of rare diseases and disorders are further driving the segment’s growth. Moreover, increasing awareness about rare diseases and conditions and availability of better diagnostic tools are fueling the demand for orphan drugs.
Distribution Channel Analysis
The prescription drugs market by distribution channel is segmented into hospital pharmacies, retail pharmacies, and online pharmacies. The hospital pharmacy segment accounted for the largest revenue share of 46.7% in 2025, driven by the increasing number of hospital admissions and the rising prevalence of chronic and critical illnesses. According to the American Hospital Association, in 2025, 34,426,650 hospital admissions were recorded in the U.S. alone. Moreover, hospitals are major suppliers of expensive and specialized drugs and are providers of care for oncology, biologic, and emergency therapies. Additionally, an increase in the number of hospitals and the improvement of healthcare infrastructure promote and ease the distribution of medicines. The rising complexity of therapy and the need for professional supervision are further driving the segment growth (Source: aha.org).
The retail pharmacy segment is expected to witness growth at a CAGR of 6.5%, driven by easy access to prescription medicines and the trust and comfort of consumers. The growing prevalence of chronic illnesses fuels the need for regular refilling of prescriptions. Additionally, an increase in the aging population boosts the demand for convenient pharmacies. The presence of a larger variety of retail chains, which provide better accessibility to medicines in both urban and remote areas, further fuels the expansion, thereby driving the growth.
The online pharmacy segment is expected to maintain a CAGR of 9.3% during the forecast period, driven by the increasing use of the Internet and modern approaches to ordering medicines through e-commerce. Also, rising adoption of digital therapeutics propels the segment growth. Customers increasingly favor online pharmacies due to their convenience, home delivery, and easy access to a range of prescription and OTC drugs. Additionally, the availability of digital prescriptions and telehealth services and coupons for online pharmacies drives the growth of the e-pharmacy segment.
Distribution Channel Comparison
| Channel | Primary Use Case | Growth Driver | Typical Drug Types |
| Hospital Pharmacies | Inpatient/outpatient administration under clinical supervision | High-acuity prescription volume; IV/injectable oncology and critical-care drugs | Oncology, biologics, injectables, orphan drugs |
| Retail Pharmacies & Drug Stores | Routine, self-administered maintenance medication | Broad population access; daily chronic-disease refills | Antidiabetics, cardiovascular, generics |
| Online / e-Pharmacies | Home delivery and prescription refills | Convenience, telehealth integration, fastest projected CAGR of the three channels | Chronic-disease maintenance drugs, generics |
Source: Polaris Market Research Analysis
By Therapy Type
The oncology segment dominated with the largest share of 18.6% in 2025, driven by the rising incidence of cancer worldwide. An increase in geriatric populations has fueled the need for effective cancer therapeutics. According to Eurostat, 450.6 million people in Europe alone (i.e., 22.0% of the region's population) are aged 65 years and above. Moreover, with growing screening initiatives, cancer diagnosis has improved, thus fueling the demand for treatment. Additionally, pharmaceutical companies are focusing on developing novel treatment modalities for various cancers. The adoption of targeted therapies and personalized treatment approaches is further driving the demand for prescription cancer drugs. Increased healthcare expenditures and availability of quality medicines are further expected to propel the segment growth. [Source: ec.europa.eu]
The cardiovascular segment is expected to witness a CAGR of 6.8% during the forecast period. The growth is primarily driven by the high prevalence of cardiovascular diseases. Increased incidences of hypertension, dyslipidemia, and obesity fuel the demand for cardiovascular drugs. An aging population is further driving the need for long-term therapeutic interventions. Moreover, the rising awareness about cardiovascular diseases and their effective management propels the demand for early diagnosis. The increased emphasis on regular health check-ups has improved detection rates among patients. The availability of quality healthcare and pharmaceutical services has improved, thereby driving the segment’s growth.
The neurological disorders segment is expected to record a CAGR of 8.1% during the forecast period. Increasing prevalence of neurological disorders and nervous system-related conditions bolsters the segment growth. The rise in the geriatric population is contributing to a higher incidence of Alzheimer’s disease, Parkinson’s disease, and other age-related neurological conditions. An increase in epilepsy cases, migraine, multiple sclerosis, and other neurological problems create the need for neurological prescription drugs. Moreover, pharmaceutical companies are focusing on developing new drugs for neurological indications. The increased healthcare expenditures and improved treatment accessibility are further driving the segment growth.
The pain management segment is expected to exhibit a CAGR of 6.5% during the projected period. This is supported by the growing prevalence of chronic and acute pain across the globe. The geriatric population is highly susceptible to musculoskeletal disorders, which fuels the demand for drugs. Moreover, the rising number of surgeries performed globally has driven the need for analgesic drugs. Chronic pain conditions are being detected and treated in a timely manner with improved screening initiatives and improved awareness, thereby driving the growth.
The gastrointestinal segment is projected to record a CAGR of 6.7% during the forecast period. The growth is attributed to the surging prevalence of gastrointestinal tract disorders. The prevalence of chronic conditions such as gastroesophageal reflux disease, peptic ulcer, and constipation is rising across the world. This is due to poor dietary habits and unhealthy lifestyle adoption. Unhealthy eating patterns, increased stress levels, and a sedentary lifestyle are also responsible for the rising incidence of indigestion and other gastrointestinal diseases. Moreover, the improved healthcare infrastructure and easy accessibility of quality medicines support the segment’s growth.
The immunology and autoimmune segment is expected to witness a CAGR of 8.4% during the forecast period. It comprises various diseases such as rheumatoid arthritis, psoriasis, and inflammatory bowel disease. The growing prevalence of chronic immunological diseases has increased the need for effective therapeutic interventions. Additionally, the rising awareness about the available treatment options has improved the diagnosis rates among patients. Increased healthcare expenditure and the availability of quality medicines are expected to propel the segment growth.
The others segment is expected to witness a CAGR of 6.2% during the forecast period. Surging prevalence of various chronic diseases across the globe contribute to the segment growth. The segment includes respiratory and diabetic conditions, which require effective therapeutic interventions. Improving healthcare accessibility and availability of quality healthcare services are also expected to propel segment growth.
By Route of Administration
The oral segment held the largest market share of 52.8% in 2025. Benefits of oral drugs such as ease of self-administration and high patient compliance propel the segment growth. These drugs have lower delivery costs than injectable or topical formats. This makes them preferred for managing diabetes, hypertension, cardiovascular diseases, and other chronic conditions. Oral drugs are widely available as tablets, capsules, and liquid forms. Oral formulations benefit from established manufacturing processes and consistent bioavailability. These features reinforce their dominant market position. Biologics increasingly pursue oral bioavailability. Thus, the oral segment continues to anchor overall prescription volumes.
The injectable segment is expected to register the highest CAGR of 8.2% from 2026 to 2034. Growth is fueled by rising use of injectable therapies in oncology, diabetes, and immunology, including monoclonal antibodies and insulin analogs. Injectable drugs are delivered via prefilled syringes and auto-injectors. These drugs are mostly used in hospitals and clinics. In such settings, the high volume of inpatient and outpatient procedures requires rapid, controlled drug administration. Self-administration devices are now extending injectable use into homecare settings, driving the segment expansion.
The topical segment is projected to record a CAGR of 6.5% during the forecast period. Dermal drug delivery led the segment with a 54.6% share in 2025. This is driven by rising emphasis on targeted treatment and ease of application. The growth is fueled by improved patient compliance over injections. Topical medicines are mainly prescribed for psoriasis, eczema, acne, and bacterial or fungal skin infections. These drugs allow active ingredients to be delivered directly to affected areas.
The other segment would register a substantial CAGR of 6.8% during the projected period. The segment covers inhalation, nasal, rectal, vaginal, and ophthalmic delivery. Ophthalmic drug delivery is expected to grow lucratively in the coming years. This is attributed to the rising prevalence of eye disorders, including glaucoma and age-related macular degeneration. It is also driven by advances that improve efficacy while reducing systemic side effects. Inhalation remains central to respiratory prescriptions such as asthma and COPD therapy. However, nasal sprays serve rapid-onset conditions. They are individually smaller than oral, injectable, or topical. Also, with rising emphasis on precision-delivery technologies, these routes are gaining a significant share.
By End Users
The hospitals segment led the market by holding 46.7% in 2025. High patient volume and availability of advanced therapies contributed to the leading position of the segment. Hospitals are the main treatment setting for complex procedures such as oncology infusions, CAR-T therapies, gene therapies, radiopharmaceuticals, and high-risk biologics, supported by trained specialists, multidisciplinary care teams, pharmacy departments, cold-chain storage, and reimbursement support services.
The specialty clinics segment contributed to a substantial market share of 21.4% in 2025. The segment growth is driven by rising demand for the treatment of cancer, autoimmune conditions, dermatological disorders, and other diseases in specialized outpatient settings. Specialty clinics commonly administer provider-supervised therapies, including oncology infusions and biologics. These clinics also support disease-specific monitoring. The increasing specialization of pharmacy and clinical services supports this segment.
The homecare settings segment is expected to exhibit a CAGR of 7.8% from 2026 to 2034. The growth is fueled by rising preference for convenient health care and increasing geriatric population. Also, market players are offering innovative home-based care models, supporting the segment growth. In the injectable drug delivery devices market specifically, homecare is projected to witness the fastest growth. Due to the introduction of self-administration devices, such as autoinjectors and prefilled syringes, patients can manage chronic conditions independently at home.
Regional Analysis
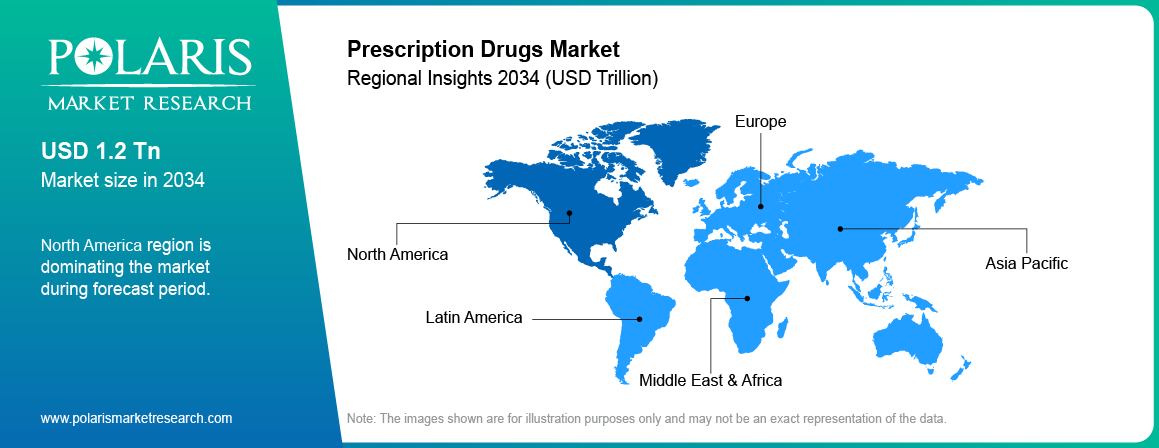
North America accounted for 49.57% of the global prescription drugs market share in 2025. This dominance is attributed to the presence of strong healthcare infrastructure and high adoption of advanced therapeutics. Also, robust investments in pharmaceutical innovation propel the North America prescription drugs market size. For instance, in January 2025, the Centers for Medicare & Medicaid Services selected 15 more Medicare Part D drugs for price negotiation. These drugs, used by 5.3 million beneficiaries, accounted for USD 41 billion in gross costs over a recent 12-month period. The region also benefits from well-established regulatory frameworks and greater affordability of drugs through insurance coverage, which ensures widespread access. Furthermore, the concentration of major pharmaceutical companies and research institutions fosters continuous innovation, solidifying North America’s leadership position in the global market.
U.S. Prescription Drugs Market Insights
U.S. held the largest market share of 72.4% in the North America prescription drug landscape in 2025 due to its advanced healthcare infrastructure, high rate of drug adoption, and continuous pharmaceutical innovation. A strong presence of leading drug manufacturers, vast insurance coverage, and high patient awareness further reinforce the country’s dominant position. Additionally, the U.S. regulatory environment promotes the development and commercialization of new therapies, thereby supporting the country's leadership in the regional market.
Asia Pacific Prescription Drugs Market
The market in Asia Pacific is projected to witness the highest CAGR of 9.8% from 2026 to 2034, driven by rising healthcare investments, increasing access to prescription medications, and a growing middle-class population with increased health awareness. The region is witnessing the rapid adoption of modern healthcare practices and the expansion of pharmaceutical distribution networks, which are enabling a wider reach of therapies. Additionally, the increasing prevalence of chronic and lifestyle-related diseases is driving demand for long-term prescription treatments. This evolving healthcare landscape positions the Asia Pacific as one of the most dynamic growth regions for the prescription drugs market.
India Prescription Drugs Market Overview
The market in India is expanding with a CAGR of 8.7% during the forecast period, due to rising healthcare expenditure, increasing access to medical facilities, and a rapidly growing population seeking modern treatment options. The expansion of pharmaceutical manufacturing capabilities and a robust generics industry have also made prescription drugs more affordable and widely accessible. Moreover, growing awareness of chronic diseases and government initiatives to improve access to medicines continue to accelerate the adoption of prescription therapies in the country.
Europe Prescription Drugs Market
The prescription drugs landscape in Europe held a substantial share of 26.8% in 2025, driven by the region’s strong focus on patient safety, quality healthcare standards, and a robust pharmaceutical industry. The region benefits from coordinated regulations and collaborative research initiatives that accelerate the development and availability of innovative therapies. Widespread healthcare coverage ensures accessibility of prescription medications, further supporting demand across various therapeutic areas. Europe maintains a major position with a growing focus on addressing unmet medical needs and advancing personalized medicine.
Germany Prescription Drugs Market
The Germany prescription drugs market is expected to witness a CAGR of 6.4% during the projected period. It is driven by its strong focus on innovation, high healthcare standards, and a robust regulatory framework that ensures patient safety and drug quality. The country’s focus on research and development, particularly in biotechnology and specialty medicines, supports steady market expansion. Additionally, widespread health insurance coverage and a well-structured healthcare system provide broad access to prescription drugs, reinforcing Germany’s role in the European market.
Competitive Analysis
The companies in the industry are focused on research and development new medicines to expand their portfolio, form strategic partnerships, and operate at a global level. The industry contains players such as AbbVie, Amgen, AstraZeneca, Bayer, Bristol-Myers Squibb, Eli Lilly, GSK, Johnson & Johnson, Merck, Sanofi, Teva Pharmaceutical Industries, among others. The main companies compete in fields such as oncology, immunology, cardiovascular, and rare diseases. Generic manufacturers compete on price, while innovative companies develop new molecules and invest heavily in research and development (R&D). Moreover, business development strategies, such as mergers and acquisitions, and invest in R&D. Such strategies are playing a crucial role in the industry.
Novartis AG, Pfizer, Inc., and F. Hoffmann-La Roche Ltd. are considered top prescription drugs companies due to their strong presence in the global market and the variety of prescription pharmaceuticals they offer. Similarly, these companies continuously invest in the R&D of innovative pharmaceuticals and participate in different therapeutic areas that are appealing to customers
List of Prescription Drugs Market Key Players 2026
- AbbVie, Inc.
- Amgen Inc.
- AstraZeneca
- Bayer AG
- Bristol-Myers Squibb Company
- Eli Lilly and Company
- F. Hoffmann-La Roche Ltd
- GlaxoSmithKline plc.
- Johnson & Johnson Services, Inc.
- Merck & Co., Inc.
- Novartis AG
- Pfizer, Inc.
- Sanofi
- Teva Pharmaceutical Industries Ltd.
Prescription Drugs Industry Developments
- August 2026: Teva announced a proposed acquisition of BioXcel Therapeutics’ neuroscience asset, BXCL501, for potential at-home treatment of agitation associated with schizophrenia and bipolar disorder, strengthening its psychiatry portfolio and supporting its broader Pivot to Growth strategy. (Source: bioxceltherapeutics.com)
- May 2026: UCB announced a definitive agreement for the acquisition of Candid Therapeutics (Candid). As per UCB, this acquisition will enable it to improve its immunology pipeline and advance into next-generation biologics. (Source: ucb.com)
- May 2026: AbbVie announced receiving U.S. FDA approval for DECNUPAZ (pivekimab sunirine-pvzy). According to AbbVie, the regulatory authority approved DECNUPAZ for the treatment of adult patients with BPDCN. The approval is supported by the data from the Phase 1/2 CADENZA trial. (Source: prnewswire.com)
- June 2025: Teva and Fosun Pharma announced a strategic partnership to co-develop TEV-56278, an investigational anti-PD1-IL2 therapy for oncology. The therapy utilizes a novel ATTENUKINE technology platform designed to improve efficacy and reduce toxicity. (Source: ir.tevapharm.com)
Future Outlook
According to our prescription drugs market forecast 2034, the market is expected to grow steadily in the forecast period. The demand for innovative pharmaceuticals is expected to rise, driven by the increasing adoption of biologics, GLP-1 drugs and specialty medicines. Additionally, there is likely to be a rise in the use of generic drugs, as well as more personalized medicines. Moreover, novel gene and cell therapies is further expected to record substantial growth opportunities. Chronic diseases will continue to fuel the need for prescription drugs. The burgeoning healthcare markets of emerging countries will also contribute to the growth of the prescription drug market, as compared to developed countries.
Prescription Drugs Market Segmentation
By Therapy Type Outlook (Revenue, USD Trillion, 2021–2034)
- Oncology
- Cardiovascular
- Pain Management
- Neurological Disorder
- Gastrointestinal
- Immunology & Autoimmune
- Others
By Product Type Outlook (Revenue, USD Trillion, 2021–2034)
- Branded
- Generic
- Orphan Drugs
By Distribution Channel Outlook (Revenue, USD Trillion, 2021–2034)
- Hospital
- Retail
- Online Pharmacies
By Route Of Administration Outlook (Revenue, USD Trillion, 2021–2034)
- Oral
- Injectable
- Topical
- Others
By End Users Outlook (Revenue, USD Trillion, 2021–2034)
- Hospitals
- Specialty Clinics
- Homecare Settings
By Regional Outlook (Revenue, USD Trillion, 2021–2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Prescription Drugs Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 1.27 Trillion |
| Market Size in 2026 | USD 1.35 Trillion |
| Revenue Forecast by 2034 | USD 2.36 Trillion |
| CAGR | 7.1% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Trillion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Prescription Drugs Market FAQ's
The global market size was valued at USD 1.27 trillion in 2025 and is projected to grow to USD 2.36 trillion by 2034.
The global market is projected to register a CAGR of 7.1% during the forecast period.
North America prescription drugs market accounted for a 49.6% global market share in 2025.
A few of the key players in the market are AbbVie, Inc.; AstraZeneca; Bristol-Myers Squibb Company; F. Hoffmann-La Roche Ltd; GlaxoSmithKline plc.; Johnson & Johnson Services, Inc.; Merck & Co., Inc.; Novartis AG; Pfizer, Inc.; and Sanofi.
The Alzheimer’s segment accounted for the largest market revenue share of 21.7% in 2025, driven by the growing prevalence of Alzheimer’s disease and increasing demand for effective treatments.
Branded drugs are original patented medicines, while generic drugs contain similar active ingredients and are usually sold at lower prices.
Biologic drugs are medicines made from living cells or organisms. They are mainly used to treat complex diseases, including cancer and autoimmune disorders.
Prescription drugs require approval from a healthcare professional. Over-the-counter drugs can be purchased directly without a prescription.
Orphan drugs are medicines developed to treat rare diseases affecting a small patient population. They often receive special government incentives.
Key drivers include rising prevalence of chronic diseases, increasing aging populations, drug innovation, growing healthcare spending, and increasing demand for specialized treatments.
Specialty drugs are high-cost medicines used for complex or chronic conditions. They often require special handling, monitoring, or patient support
Download Sample Report of Prescription Drugs Market
Please fill out the form to request a customized copy of the research report.