Rare Earth Metals Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Rare Earth Metals Market Summary
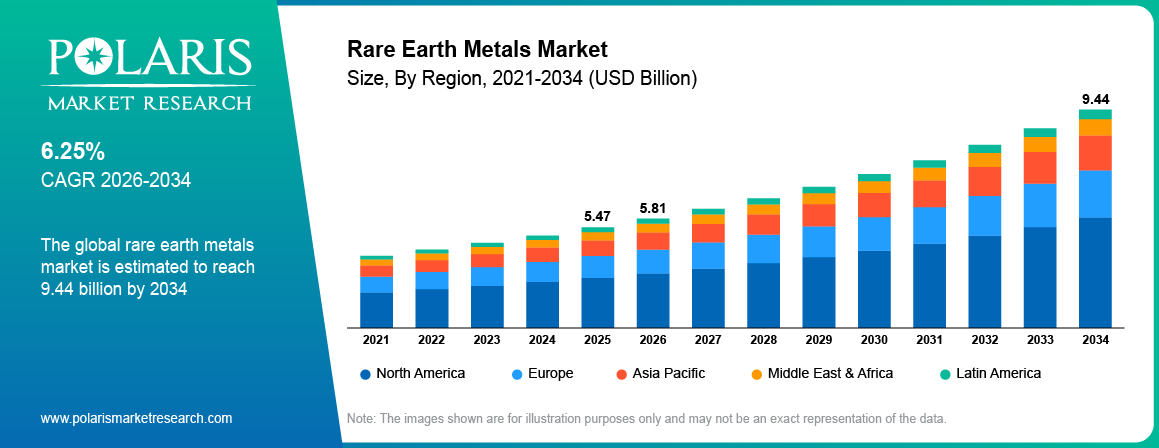
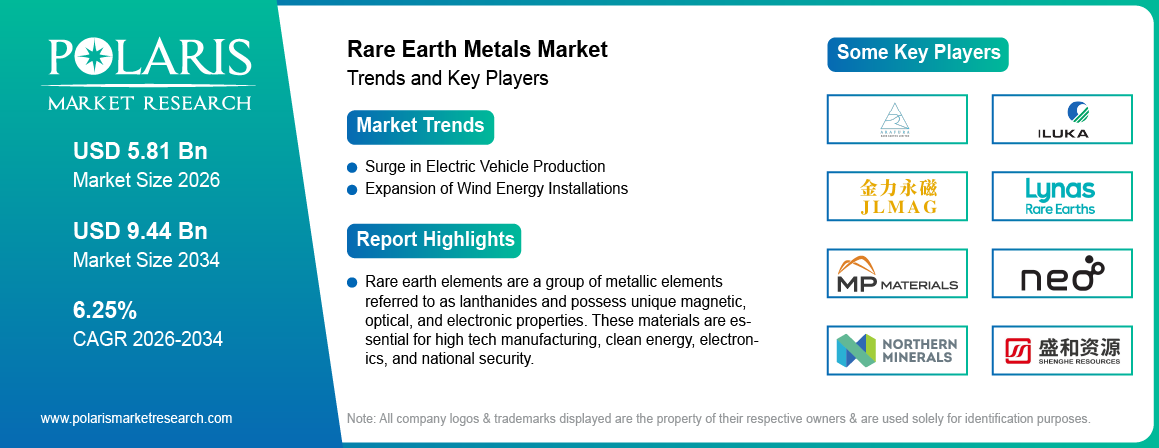
The global rare earth metals market size was valued at USD 5.47 billion in 2025, growing at a CAGR of 6.25% from 2026 to 2034. Rising global demand for electric vehicles is driving the consumption of rare earth magnets such as neodymium and dysprosium in permanent magnet motors. The emerging rare earth magnet recycling market will create lucrative opportunities for market players in the coming years.
Market Statistics
Rare Earth Metals Market Key Takeaways
- In 2025, Asia Pacific held the largest revenue share of 84.50%, due to dominant production volumes, extensive refining capacity, and presence of leading rare earth processors.
- The market in China is expected to record a 5.40% CAGR during 2026-2034, due to its vast resource base, well-developed separation technologies, and strategic focus on value-added applications.
- North America is expected to exhibit the highest CAGR of 8.90% during the forecast period. This is due to increased exploration activities and policy support aimed at reducing dependency on overseas supply chains.
- The U.S. captured 78.0% regional revenue share in 2025. The dominance is supported by aggressive policy frameworks targeting mineral independence.
- The neodymium segment led with a 31.0% share in 2025. Neodymium is essential in high-performance permanent magnets used in EVs, robotics, and renewable energy systems. This factor boosts its dominance.
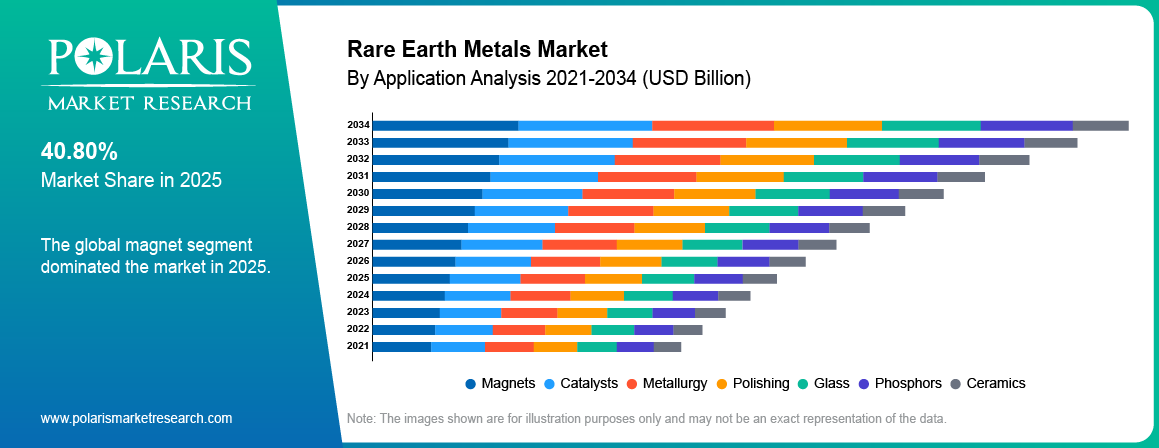
- The magnet segment dominated with 40.80% revenue share in 2025 due to the critical importance of rare earth magnets in modern technologies.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Are Rare Earth Metals?
Rare earth elements are a group of metallic elements referred to as lanthanides and possess unique magnetic, optical, and electronic properties. These materials are essential for high tech manufacturing, clean energy, electronics, and national security. Neodymium and praseodymium are the main feedstocks for manufacturing NdFeB magnets and permanent magnets for electric vehicles and wind turbines. Dysprosium improves magnet performance at high temperatures. Rare earth oxides are also the basis for catalysts, polishing compounds, ceramics, phosphors, and specialized alloys. This means that rare earth metals are considered strategic and critical minerals involved in critical supply chains across the world.
Rare earth elements are divided into Light Rare Earth Elements (LREEs) and Heavy Rare Earth Elements (HREEs). Their end-user spectra are based on their magnetic, optical, catalytic, and metallurgical properties.
Light Rare Earth Elements vs Heavy Rare Earth Elements (LREE vs. HREE)
| Parameter | Light Rare Earth Elements (LREE) | Heavy Rare Earth Elements (HREE) |
| General Classification | Relatively lighter lanthanides within the rare earth group | Relatively heavier rare earth elements, generally including the later lanthanides |
| Common Elements | Lanthanum, cerium, praseodymium, neodymium, samarium | Gadolinium, terbium, dysprosium, holmium, erbium, ytterbium, lutetium; yttrium is also commonly grouped with HREEs |
| Relative Availability | Generally more abundant in economically viable rare earth deposits | Typically less abundant and more geographically concentrated |
| Key Applications | Rare earth permanent magnets, catalysts, polishing compounds, batteries, specialty alloys | High-temperature magnets, phosphors, lasers, medical applications, defense and advanced electronics |
| Magnet Applications | Neodymium and praseodymium are major inputs for NdFeB magnets and permanent magnets | Dysprosium and terbium are added to improve thermal stability and coercivity of high-performance magnets |
| Commercial Importance | High-volume consumption across manufacturing and technology industries | Lower-volume but often higher-value applications requiring specialized performance |
| Supply Chain Characteristics | Larger production volumes but still exposed to concentrated rare earth mining, separation and refining | Greater supply risk due to limited deposits and complex separation requirements |
| Strategic Significance | Important critical minerals for industrial manufacturing and advanced technologies | Particularly strategic for defense, aerospace, electronics, and other supply-sensitive applications |
| Market Relevance | Neodymium is among the most commercially significant LREEs in the rare earth metals market | Dysprosium and other HREEs attract attention because of tighter availability and supply-chain concentration |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
What does Rare Earth Metals Market Include?
Rare earth metals market size and its influence on the world economy is related to high quality of output obtained using advanced technologies. Supply availability is also affected by the fact that their production generally requires complex rare earth mining and separation processes, with availability not only a function of mineral reserves but also of processing capacity downstream. The production of rare earth magnetic materials in China rose by 31.1% year on year in January–February 2025, as reported by the National Bureau of Statistics in March 2025 (Source: stats.gov.cn).
A rising emphasis on critical minerals policy is reshaping the competitive environment for governments and manufacturers seeking greater diversity in the rare earth supply chain. It also leads to less reliance on highly concentrated processing networks. Strategic investments are increasingly focused on domestic mining, separation facilities, refining infrastructure, security of inventory, and alternative sourcing arrangements.
Market Dynamics
Drivers: Surge in Electric Vehicle Production
Growing production of electric vehicles (EVs) drives the market expansion. Producers of electric vehicle increasingly demand high-power rare-earth magnets, in particular neodymium and dysprosium. These materials are used to power the small and energy-efficient electric motors used in EVs. According to the International Energy Agency’s Global EV Outlook 2026, the number of new electric cars produced globally is 22 million in 2025, an increase of over 25% from 2024. The NdFeB magnets and permanent magnets contribute to more powerful motors, better acceleration performance of a vehicle and greater energy efficiency of the drive train. The increasing transition from ICE to electrified powertrains is solidifying the strategic importance of rare earth elements in vehicle manufacturing. Leading EV manufacturers secure vital supplies of essential minerals. They are developing in-house supply chains or signing joint ventures. Increasing customer preference for environment-friendly vehicles and favorable government policies boost the EV adoption. Governments are establishing stringent emission standards, fueling EV demand. Rising EV production propels the requirement for EV batteries. Thus, the growing electric vehicle market fuels the EV magnet demand (Source: iea.org).
Drivers: Expansion of Wind Energy Installations
Expanding wind energy installations across countries drive demand for wind turbine magnets. Wind turbines, in particular offshore turbines, depend on rare earth magnets to provide stable and efficient energy conversion. According to the February 2026 report of China’s National Energy Administration, newly added wind and solar capacity in China in 2025 exceeds 430 GW, up 22% year on year to a new high. Permanent magnet generators contain neodymium and praseodymium. They reduce mechanical wear and increase performance in harsh environments. These NdFeB magnets and other permanent magnets allow turbines to produce a high-power density. They have reduced maintenance needs and enhanced reliability. The build-out of wind power infrastructure is also increasingly buoying demand for the rare earth elements integrated into sophisticated generator systems. Governments are supporting renewable energy development with long-term capacity targets and infrastructure schemes that incentivize large-scale onshore and offshore projects. As wind farms grow in number, the demand for superior magnetic materials is likely to rise. It increases the strategic importance of reliable rare earth supply chains, driving the market expansion (Source: gov.cn).
Drivers: Rising Investment in Domestic Supply Chains and Critical Minerals Policy
The rare earth metals market is being driven by increasing investment in domestic supply chains and critical minerals policy. Governments of different countries are focusing on minimizing reliance on the tightly clustered mining, separation, and refining networks. Rare earth elements are critical feedstocks for high end electronics, defense systems, permanent magnets, clean energy solutions and niche industrial applications. Thus, securing supply of these elements is a strategic concern.
Many countries are providing public funding and offering tax incentives for the domestic production of rare earth magnets. They are entering strategic partnerships and signing long-term sourcing agreements to support the mining, processing, separation, refining, and production rare earth metals. This is leading to the development of new capacity outside of the established areas of rare earth production. It helps diversify the rare earth supply chain. At the same time, investment is also being made in recycling and in the recovery of rare earths from secondary sources. It underscores the role of a circular economy in future supply strategies. In February 2026, MP Materials announced that it had decided to locate its 10X rare earth magnet manufacturing campus in Northlake, Texas. The company revealed its plan to invest over USD 1.25 billion in the project (Source: mpmaterials.com).
Critical mineral policies will also enhance project visibility for producers by providing assurance of long-term government support for domestic production and processing. This would help mitigate the risk of investment and encourage the private sector to engage in new mining, processing and NdFeB magnet production plants. Light rare earth elements and heavy rare earth elements are seeing increasingly strong policy focus on being able to secure access to both quantities of LREEs and HREEs. This is highly relevant given that certain materials continue to be difficult to substitute in high performance applications.
Restraint: High Extraction and Processing Costs
The costs of processing and extracting continue to create a high barrier of entry for rare earth metals market as the viable production entails several technically difficult stages. The individual elements in rare earth ores are often bonded together. This makes separation and purification more challenging compared to standard metal processing. Producers face substantial expenses related to mineral concentration, chemical separation, refining, waste disposal, and compliance with environmental regulations. The process is energy and water intensive. It uses special reagents and entails specific knowledge. This leads to very high production expenses. This can adversely impact the economic viability of the project, particularly in cases of smaller deposits or when the scale of operation is low. Also, very high investment needs may prevent the development of new rare earth mining/refining projects.
Challenge: Supply Chain Concentration and Geopolitical Risk
Supply risk is amplified by the fact that rare earth mining, separation, processing, and material production is geographically concentrated within a very small number of countries and processing hubs. Such reliance can leave companies vulnerable to shortages of raw materials, transportation, trade policy, and foreign commercial relations. China's application in rare earth export controls is a reminder of how availability and flow of strategically important materials can be impacted by regulations and actions. LREE, HREE, and permanent magnet materials, such as neodymium magnets, are more difficult to source. Those sectors exposed to light rare earth elements, heavy rare earth elements, and permanent magnet material are generally exposed to more uncertainty in sourcing and potential supply constraints. Few substitute processing avenues can impede swift supplier diversification, particularly for specialized high-purity materials. Consequently, geopolitical tensions and supply concentration have the potential to add more complexity to the procurement process and help create the need for firms to hold greater inventories, diversify their supplier base and develop more resilient rare earth supply chains.
Opportunity: Rare Earth Recycling and Circular Economy Expansion
The growth of rare earth recycling and circular economy initiatives would offer lucrative market opportunities in the coming years. Recycling of rare earth metals and the circular economy play an increasingly important role as the industries are seeking critical minerals from secondary sources to enhance supply chain resilience. High-value REEs can also be recycled from end-of-life permanent magnets, electronics, industrial machinery, manufacturing waste and other waste streams, reducing dependence on primary sources. Materials like neodymium, dysprosium and praseodymium are also the most attractive to recover due to their use in high-performance NdFeB magnets and various other specialized applications. In December 2025, the U.S. DOE announced a funding opportunity of up to USD 134 million for projects focused on commercial-scale demonstration of recovery and refining of rare earth elements (REEs) from unconventional feedstocks such as mine tailings, e-waste, and other waste materials. Recycling may lead to a more efficient use of resources, and at the same time reduce the sensitivity to rare earth mining and processing networks that are regionally concentrated.
Advances in collection, separation, refining and material recovery are also making circular sourcing approaches more feasible. As recovery technologies become commercially scalable, recycled materials can serve as a source of raw materials to augment primary supply and provide additional processing, materials reuse, and supply chain diversification benefits to the rare earth element supply chain (Source: energy.gov).
Source: Polaris Market Research Analysis
Segmental Insights
The rare earth metals market is segmented by product and application to reflect differences in material properties, commercial utilization, and end-use requirements. Product demand varies across individual rare earth elements, while applications span magnets, catalysts, metallurgy, polishing, glass, phosphors, ceramics, and other specialized uses.
Rare Earth Metals Market by Product
Based on product, the segmentation includes cerium, dysprosium, gadolinium, lutetium, neodymium, praseodymium, yttrium, and others.
- Neodymium: The neodymium segment accounted for 31.0% of the revenue share in 2025, because of its key role in the production of high-quality permanent magnets used in electric cars, robotics, and applications in renewable energy. The demand from the automotive and electronics sectors ensured its consistent acquisition. This is due to its unique magnetic property-to-size ratio. Neodymium magnets offer good torque and energy efficiency. Thus, they are essential for the design of lightweight and small motors for future electric vehicles and wind turbines. They are also used in the production of miniaturized components for headphones, hard disks, and automated machinery. The growing use of advanced motion control and energy-efficient motors in different industries boost demand for neodymium.
- Praseodymium: Praseodymium is projected to record a CAGR of 7.20% between 2026 and 2034, owing to the rising application of praseodymium in combination with neodymium in improving the resistance of magnets against corrosion and heat. There is an increase in demand for praseodymium in the making of alloys. Its use is rising in the aerospace sector, where it helps manufacture metals used in jet engines and turbines. Companies that manufacture consumer electronics have started using praseodymium in order to enhance performance in display technologies. The material offers a wide range of uses in green energy applications and high-tech electronics. Participants in the market are focusing on improving production and sourcing strategies to fulfil the rising requirements, especially in lightweight alloys and magnetic materials.
- Gadolinium: The gadolinium segment will witness a 5.90% CAGR during the forecast period, due to its expanding application in medical imaging and nuclear reactor components. The magnetic nature of gadolinium makes the metal valuable contrast agent in MRI procedures, where it helps improve image quality. Gadolinium is used in the production of control rods for nuclear reactors due to its ability to absorb many neutrons. The metal play a crucial role in magneto-caloric refrigeration systems and alloy used for high-temperature environment. Recent technological developments in the field of medicine and clean nuclear energy have contributed to increased use of gadolinium by various establishments such as research facilities, hospitals, and energy companies. Its growing relevance in healthcare and power sectors is supporting its rising adoption.
- Cerium: Growth of the cerium segment with 22.0% share in 2025 is attributed to its high application rate in polishing, catalysts, glass processing, metallurgy, and specialized industrial applications. The demand is also supported by the extensive use of cerium-based material for applications such as glass finishing, polishing for semiconductors, systems for auto emission control, and processes for refining oil. The availability of cerium in the rare earth supply chain also allows for uniform commercial utilization in high volume applications. A growing advanced glass and precision surface finishing industry is fueling demand for polishing compounds and catalyst applications provide a stable industrial demand. Cerium is also being used more in specialty alloys and in chemical processes, building the opportunity for the element beyond its traditional end uses. Moreover, the broad appeal of cerium in various industries allows for the demand to be somewhat diversified, limiting exposure to an overreliance on a single use application. As processing capabilities are established, cerium will continue to be a significant component of the rare earth metals market.
- Dysprosium: The demand is expected to grow witnessing 7.80% CAGR. This is because of the increasing demand for a high performance permanent magnet system that requires higher thermal stability and magnetic power. Improvements in neodymium-based magnets are making it particularly interesting for applications where motors and generators operate at high temperatures, as well as in heavy-duty applications. Increasing use of high-tech electronics, defense machinery, aerospace systems, and specialized industrial equipment is driving the demand for dysprosium-based magnetic material. Scarcity relative to many light rare earth elements further augments its strategic value in the rare earth supply chain.
- Others: The growth of the lutetium, yttrium, and others segment, with lanthanum, samarium, and europium, is attributable to its increasing application in high-value and high-technology-specific end-users. These rare earth elements are the backbone of the phosphors, lasers, ceramics, optical materials, specialty alloys, batteries, medical technology, electronics and advanced industrial systems. Yttrium continues to be advantageous due to its role in the production of phosphors, ceramics, optical components and high-performance material systems, and lutetium is progressively tied to niche markets with the demand for extremely high purity and unique physical features.
Lanthanum, samarium and europium also serve as demand drivers for catalysts, battery materials, optical glass, permanent magnets, phosphors, displays and specialty industrial uses. The segment is gaining traction due to the use in electronics, health care, aerospace, defense, and precision manufacturing. Increasing demand for high-purity functional materials and further diversification of rare earth supply chains is poised to continue to support utilization in these niche, high-value applications.
| Element | Category | 2025 Revenue Share | Primary Application |
| Neodymium | Light REE (LREE) | 31.0% | Permanent magnets — EV motors, wind turbines |
| Praseodymium | Light REE (LREE) | Highest CAGR segment | Alloyed with neodymium for magnet corrosion resistance; aerospace alloys |
| Gadolinium | Heavy REE (HREE) | Growing | MRI contrast agents; nuclear reactor control rods |
| Cerium | Light REE (LREE) | Established | Polishing (glass, LCD panels); catalysts (FCC, auto-catalysts) |
| Dysprosium | Heavy REE (HREE) | Growing | High-temperature magnet stability in EV and defense motors |
| Lutetium, Yttrium & Others (incl. Lanthanum, Samarium, Europium) | Mixed LREE/HREE | Niche, high-value | Phosphors, lasers, ceramics, NiMH batteries |
Source: Polaris Market Research Analysis
Rare Earth Metals Market by Application
In terms of application, the segmentation includes magnet, catalysts, metallurgy, polishing, glass, phosphors, ceramics, and others.
- Magnet: In 2025 the magnet sector had the largest revenue share at 40.80% owing to the importance of rare earth magnets in modern-day technology such as drivetrain in electric vehicles, generator in wind turbines, and high-performing consumer electronics. Rare earth magnets are known for their magnetic and durable nature. As a result, energy-efficient motors can be designed with these magnets. The transition toward electrification in transport and infrastructure industries has led to the acquisition of large quantities of neodymium, samarium, and praseodymium-based magnets. The manufacturers have chosen these materials to cater to the growing requirements, reduce carbon emissions, and comply with the environmental regulations. Continued strong investments in renewable energy projects and in the electrification of automobiles drive global demand for rare earth magnets.
- Catalyst: The catalyst segment is anticipated to record a CAGR of 5.60% as a result of the increasing use of rare earth metals in the refining and chemical industries. Elements such as cerium and lanthanum are commonly used as fluid catalytic cracking (FCC) catalysts in the oil refinery sector to increase fuel output. They offer greater chemical reactivity and stability at high temperatures. Thus, these catalysts are essential for use in petroleum processing and in emission control. In the automotive industry, rare earth catalysts are used in the exhaust system. They help reduce the emissions from vehicles. The growing level of environmental regulation and rising demand for cleaner fuel production propel the need for advanced catalytic materials. Thus, they are establishing rare earth elements as essential for sustainable chemical and industrial operations.
- Metallurgy, Polishing, Glass, Phosphors, Ceramics, Others: Demand for rare earth metals is sustained by their use in metallurgy, polishing, glass, phosphors, ceramics, and a host of other high-tech applications, wherein they contribute to enhancements in the properties of materials and quality of products. They also are used to improve the strength, corrosion resistance, thermal stability and processibility of alloys used in aerospace, defense, automotive and industrial applications. Polishing applications include precision finishing of glass, displays, optical components and the surfaces of semiconductors.
Rare earth products find applications in the manufacturing of glass in the form of optical glass, speciality coatings, colouration, decolouration and UV-protection. Phosphors that use europium and yttrium are employed in lighting, displays, and imaging, while ceramics utilize rare earth materials in electronic parts, high-temperature goods, structural materials, and speciality coatings.
Other applications are in healthcare, lasers, sensors, chemical processing, and precision electronics. While smaller than magnets and catalysts on an individual basis, these applications collectively constitute a very stable demand base, and one that is only becoming more demanding in terms of purity of materials and functionality.
| Application | 2025 Revenue Share | Key Driver |
| Magnets | 40.80% | EV drivetrains, wind turbine generators, consumer electronics |
| Catalysts | Growing steadily | Fluid catalytic cracking (refining), auto-emission control |
| Metallurgy | Established | Aerospace and defense alloys |
| Polishing | Established | Glass, LCD, semiconductor wafer finishing |
| Glass & Ceramics | Niche | Optical glass, UV-resistant coatings |
| Phosphors | Niche, high-value | LED lighting, display technology |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
Regional Analysis
Asia Pacific Rare Earth Metals Market Trends
The Asia Pacific region held the largest share of the revenue in the global market in 2025, by nearly 84.50%, owing to the large production volumes, high refining capacity, and the presence of major rare earth producers. China, Myanmar and Australia are key to the world supply of rare earth elements, notably the ones needed for magnets and batteries. Regional producers have the advantage of geology and the extraction methods that are more established, as well as more developed logistics and processing. Asia Pacific’s development of rare earths as essential materials in its electronics, automotive, renewable energy, and advanced manufactured good industries drives steady demand for rare earth across the entire value chain. In January 2026, the government of Australia announced a USD 1.2 billion Critical Minerals Strategic Reserve, with rare earth elements among the first minerals to be focused on, intended to boost domestic production and ensure stable critical mineral supply chains. Active research and development in material science, investment in downstream processing and government attention on critical minerals development further solidifies the region’s dominance in rare earth processing and application innovation (Source: minister.industry.gov.au).
China Rare Earth Metals Market Overview
China is showing strong growth capturing 76.0% regional share in 2025 due to its vast resource base, well-developed separation technologies, and strategic focus on value-added applications. The country is working to consolidate mining operations and regulate pricing arrangements, enabling long-term market dominance. Domestic demand for rare earth metals remains strong, driven by the expansion of EVs, green energy initiatives, and 5G telecommunications. The policies regarding rare earths in China aim at achieving technological self-sufficiency. They also emphasize increasing export value through magnet and battery manufacturing. Environmental regulations have encouraged more sustainable mining practices, which improve both capacity and global competitiveness. The country’s continued investments in strategic reserves and downstream innovation further boost its influence in the global markets.
India Rare Earth Metals Market Outlook
The India market is projected to record a CAGR of 6.1% during 2026–2034. Government support for the localization of the rare-earth metal-to-magnet value chain drives the market growth. In November 2025, the Union Cabinet approved the 'Scheme to Promote Manufacturing of Sintered Rare Earth Permanent Magnets', with an investment of USD 763.45 million. This initiative focuses on promoting the domestic manufacturing of 6,000 MTPA of integrated Rare Earth Permanent Magnet (REPM). This improves self-reliance and positions India as a key player in the global REPM market (Source: pib.gov.in).
Japan Rare Earth Metals Market Trends
The Japan market is projected to register a 5.1% CAGR during the forecast period. The country’s market growth is driven by increasing demand for high-value manufacturing and supply-security requirements. Rising penetration of EVs, robotics and electronics propels the need for NdPr. Concerns over concentrated heavy-REE supply boost investments and long-term arrangements for Dy and Tb from Australia and Namibia. Strategic overseas investments in heavy rare earths strengthen the country's access to feedstocks needed for high-temperature permanent magnets. For instance, in March 2026, Toyota Tsusho joined as a joint development partner in JOGMEC's Rare Earth Development Project in Lofdal, Namibia. Through this project, Toyota Tsusho emphasizes future commercialization and the start of development. It will work with JOGMEC and other parties to strengthen Japan's critical mineral supply chains (Source: toyota-tsusho.com).
North America Rare Earth Metals Market Assessment
North America is gradually strengthening its rare earth metals market witnessing 8.90% CAGR through increased exploration activities and policy support aimed at reducing dependency on overseas supply chains. Manufacturers are focusing on diversifying sourcing and boosting domestic extraction, particularly for critical elements such as neodymium and dysprosium used in EVs and defense technologies. Investments in rare earth separation and processing facilities are increasing to address downstream value chain gaps. Government-backed incentives for critical mineral security and strategic collaborations between private players and research institutions are driving regional innovation. The region’s push to support electrification, clean energy, and national security is creating a robust environment for the North America rare earth elements market.
U.S. Rare Earth Metals Market Insights
The U.S. led the rare earth metals market share with 78.0% in 2025, owing to the positive momentum resulted from strong policy support on mineral self-reliance. The core strategy is to build vertically integrated rare earth supply chains for growing needs of electric vehicle production, renewable energy systems, and defense. According to the U.S. Energy Information Administration 2026 report, wind energy generated approximately 464 billion kilowatthours of electricity in the United States in 2025, representing approximately 10% of total utility-scale electricity generation and growing at about 3%. Companies are diversifying into domestic mining operations and strategic alliances for refining capabilities to mitigate supply risks. Federal funding programs and critical minerals legislation fuel engagement from the private sector. The nation’s transition to clean technology adoption and digital infrastructure modernization are making rare earths more important in permanent magnets, electronics and optical instruments and is driving long term market demand (Source: eia.gov).
Canada Rare Earth Metals Market Overview
The market in Canada is expected to exhibit a CAGR of 8.7% during the forecast period. The Canada rare earth metals industry is at an emerging commercialization stage. Rising focus on the domestic separation and metal production drives the market growth. For instance, the Rare Earth Processing Facility of Saskatchewan Research Council (SRC) is the most significant rare-earth metallization project of Canada. The facility focuses on producing magnet-grade neodymium praseodymium (NdPr) metal, dysprosium (Dy), and terbium (Tb) oxides. Partnership between SRC and REalloys extends the value chain into Dy/Tb metallization. (Source: src.sk.ca) Such initiatives create a domestic supply base and reduce reliance on imported rare earth metals.
Europe Rare Earth Metals Market Assessment
The European market is expected to register a CAGR of 8.20% during the projected period. The region focuses on setting up secure and sustainable supply chains. Mining projects in countries such as Sweden and Greenland are underway to reduce reliance on imports from Asia. The European Union's policy measures consider rare earth elements to be strategic resources. They are essential for achieving climate objectives and for digital transformation. Funds are being announced for recycling technologies. Also, there are rising investments in the extraction of these elements from industrial waste. Such initiatives boost self-sufficiency. Rising focus on developing domestic processing capabilities and promoting green manufacturing drives industry growth. Increasing use of rare earths in wind turbines, electric mobility, and electronics expand regional production and encourage innovation.
Latin America and the Middle East & Africa
Latin America and the Middle East & Africa are becoming new frontiers in the rare earth metals market, driven by increasing activities in resource exploration and development, as well as in supply chain diversification. The geological potential within Latin America is favorable, particularly in those countries seeking to grow critical minerals production and attract investment in mining and processing. The Middle East & Africa is also emerging as governments explore their own mineral endowments and seek to broaden their industrial bases. Both areas are still relatively nascent in rare earth separation and refining when compared to the Asia Pacific, thus providing for recourse in later infrastructure construction. Growing applications in electronics, clean energy, defense and advanced manufacturing are gradually enhancing the strategic significance of these markets. Thus, with stronger exploration activity, valuation, processing capabilities and global alliances, they are expected to strengthen their position in the global rare earth market over time.
Regional Market Comparison
| Region | 2025 Market Position | Key Dynamic |
| Asia Pacific | Dominating market revenue share | China dominates production/refining; India, Australia scaling |
| North America | With highest CAGR | Policy-driven reshoring — MP Materials, critical minerals legislation |
| Europe | Hold significant share | EU Green Deal, recycling and alternative-material investment |
| Latin America | Developing | Early-stage exploration — Brazil, Argentina |
| Middle East & Africa | Emerging | Emerging exploration — South Africa |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
China Rare Earth Export Controls and Global Supply Chain Impact
The China’s rare earth export control policy has a significant influence on the international rare earth supply chain due to the China’s dominance in mining, separation, refining, and downstream material processing. Controls over the export of certain rare earth materials may cause a procurement uncertainty for the manufacturers who rely on a steady supply of these critical raw materials. It is particularly profound for heavy rare earth (HREE) and special magnet materials for use in defense systems, advanced electronic, industrial machinery, and high-performance, permanent magnets.
Furthermore, export controls may add to lead times, spur inventory buildups, and impose further compliance burdens on foreign purchasers. This processing power concentration exposes the weakness in the industries that depend on a small number of supply providers. In response, manufacturers and governments are giving more attention to rare earth supply chain diversification, alternative sourcing, domestic processing and strategic stockpiling. These efforts are slowly spurring investment in new separation and refining capacity, particularly outside China. In the longer term, however, China’s rare earth export restrictions are expected to continue to be a key strategic issue for purchasers, affecting how they source materials, their supplier relationships and their ability to develop more resilient critical minerals supply chains.
Competitive Analysis
The competitive landscape of the rare earth metals market is defined by strategic shifts toward supply chain diversification, downstream integration, and value-added processing capabilities. The competitive landscape of the rare earth metals market is defined by strategic shifts toward supply chain diversification, downstream integration, and value-added processing capabilities. Rare earth metal market players increasingly focus on market expansion strategies. They are emphasizing establishing refining plants outside traditional production hubs. They are securing long-term raw material access through mining rights and exploration projects. Companies are now engaging in joint ventures and forming strategic partnerships. It helps them create complete rare earth ecosystems, especially in areas that are trying to decrease their dependence on imports.
There is an increase in mergers and acquisitions in the market. With these, firms can integrate their capabilities and utilize technology. This enables them to gain a competitive edge in application segments such as electric mobility, wind energy, and electronics. Post-merger actions will involve integration of supply chain management, manufacturing technology, and customer relationship management for better market penetration. Solvent extraction, separation, and magnet production technologies have improved efficiency and reduced the environmental footprint. Firms get a competitive advantage due to these developments. Policy makers' support and collaborations between governments have increased research and development expenditure and innovations in sustainable mining and recycling. Generally, the market for rare earth metals continues to be quite dynamic, with all the players striving for geopolitical resilience, specialization in functional materials, and control over the value chain of critical minerals.
Rare Earth Metals Companies List
- Arafura Rare Earths Limited
- Iluka Resources Limited
- JL MAG Rare-Earth Co., Ltd.
- Lynas Rare Earths Ltd.
- MP Materials
- Neo Performance Materials Inc.
- Northern Minerals Limited
- Shenghe Resources Holding Co., Ltd.
- Shin-Etsu Chemical Co., Ltd.
- Ucore Rare Metals Inc.
Key Player Positioning
| Company | HQ / Region | Strategic Focus |
| Arafura Rare Earths Limited | Perth, Australia | Nolans NdPr project (Northern Territory) reached Final Investment Decision in May 2026; fully integrated ore-to-oxide model targeting ~4% of world NdPr supply from 2032; binding offtakes with Hyundai/Kia and Siemens Gamesa, backed by ~US$775M senior debt facilities and a $200M NRFC equity commitment. |
| Iluka Resources Limited | Perth, Australia | Building Australia's first fully integrated rare earths refinery at Eneabba, WA (light + heavy REOs incl. Nd, Pr, Dy, Tb), fed by legacy monazite stockpile from mineral sands processing; backed by A$1.65B non-recourse Australian government loan; commissioning targeted from 2027. |
| JL MAG Rare-Earth Co., Ltd. | Ganzhou, China (dual-listed Shenzhen/HK) | World's largest sintered NdFeB magnet producer; vertically integrated from mining ties through magnet production; expanding into humanoid robot motor rotors, rare earth recycling, and soft magnetics; capacity scaling toward 60,000 tonnes/year by 2027, with a new plant under construction in Mexico. |
| Lynas Rare Earths Ltd. | Sydney, Australia | Largest rare earth producer outside China; integrated Mt Weld (WA) mine to Kalgoorlie/Malaysia processing; producing separated heavy rare earths (Dy, Tb, and now Sm) at Kuantan; DoD-linked supply agreement; Texas (Seadrift) heavy rare earths facility development remains uncertain pending U.S. offtake terms. |
| MP Materials | Las Vegas, US | Vertically integrated U.S. mine-to-magnet supply chain; Mountain Pass (CA) mining/processing plus Independence (Fort Worth, TX) magnet facility now in commercial NdFeB production; new $1.25B "10X" Northlake, TX campus announced to reach ~10,000 tpa magnet capacity by 2028; backed by U.S. DoW partnership and GM/Apple offtakes. |
| Neo Performance Materials Inc. | Toronto, Canada | Global materials platform (Magnequench, Chemicals & Oxides, Rare Metals segments); opened a new NdFeB magnet manufacturing facility in Narva, Estonia (2025) to build an independent European supply chain; Bosch capacity-reservation partnership and Cyclic Materials recycling collaboration. |
| Northern Minerals Limited | Perth, Australia | Developing Browns Range Heavy Rare Earths Project (WA/NT) around the high-grade Wolverine deposit; focused on dysprosium and terbium production; strategic supply agreement with Iluka Resources for concentrate feedstock to the Eneabba refinery. |
| Shenghe Resources Holding Co., Ltd. | Sichuan, China | State-linked, internationally embedded producer spanning mining, separation, and downstream magnet-precursor materials; overseas positions in Mountain Pass (MP Materials stake), Greenland (Kvanefjeld), and Tanzania (Ngualla); 2026 strategy prioritizes global market expansion, non-ferrous metals diversification, and risk management. |
| Shin-Etsu Chemical Co., Ltd. | Tokyo, Japan | High-purity rare earth materials for electronics, magnetics, and optics; strong in-house R&D base; long-standing global leader in sintered NdFeB magnets alongside its core specialty chemicals business. |
| Ucore Rare Metals Inc. | Halifax, Canada | Commercializing patented RapidSX™ solvent-extraction separation technology; building a Strategic Metals Complex in Alexandria, Louisiana (targeting ~5,000–7,500 tpa TREO); backed by U.S. DoD and Canadian government funding; retains 100%-owned Bokan-Dotson Ridge heavy REE project in Alaska as a longer-term resource |
Source: Polaris Market Research Analysis
Industry Development
- August 2026: American Rare Earths signed an MoU with Novex to convert oxides from its Wyoming project into metals for magnets. The agreement covers process optimization, demonstration plant metallization, and joint design of a U.S. production facility. (Source: globenewswire.com)
- July 2025: Apple invested USD 500 million to strengthen its U.S. supply chain for rare earth magnets through a partnership with MP Materials. The company will establish a recycling facility to process rare earth elements from recycled sources, promoting sustainable manufacturing practices. (Source: apple.com)
- January 2025: MP Materials began commercial production of neodymium-praseodymium (NdPr) metal and initiated trial production of automotive-grade, sintered neodymium-iron-boron (NdFeB) magnets at its Independence facility in Texas. This marks a significant milestone in reestablishing the U.S. rare earth magnet supply chain. (Source: investors.mpmaterials.com)
Future Outlook
As per our rare earth metals market forecast 2034, the market will expand steadily in the coming year. Demand for NdPr, dysprosium, and terbium metals will increase from permanent magnets used in EVs, wind turbines, industrial motors, robotics, electronics, and defense systems. Supply-chain diversification will remain a key priority as China dominates refining and magnet production. Consequently, investments in rare-earth metallization, refining, recycling, alloy production, and magnet manufacturing outside China are expected to accelerate, strengthening global supply resilience.
Rare Earth Metals Market Segmentation
By Product Outlook (Revenue, USD Billion, 2021–2034)
- Cerium
- Dysprosium
- Gadolinium
- Lutetium
- Neodymium
- Praseodymium
- Yttrium
- Others
By Application Outlook (Revenue, USD Billion, 2021–2034)
- Magnets
- Catalysts
- Metallurgy
- Polishing
- Glass
- Phosphors
- Ceramics
- Others
By Regional Outlook (Revenue, USD Billion, 2021–2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Report scope to-Quantitative Units- Volume Tons; Revenue in USD billion and CAGR from 2026 to 2034
| Report Attributes | Details |
| Market Size in 2025 | USD 5.47 billion |
| Market Size in 2026 | USD 5.81 billion |
| Revenue Forecast by 2034 | USD 9.44 billion |
| CAGR | 6.25% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Rare Earth Metals Market FAQ's
Rare earth metals comprise seventeen elements classified as LREEs, HREEs.
LREEs are generally more abundant, while HREEs are relatively scarcer.
Neodymium, praseodymium, dysprosium, and terbium are widely used in magnets
Neodymium provides magnetic strength, while dysprosium improves high-temperature performance significantly.
A few of the key players in the market are Arafura Rare Earths Limited; Iluka Resources Limited; JL MAG Rare-Earth Co., Ltd.; Lynas Rare Earths Ltd.; MP Materials; Neo Performance Materials Inc.; Northern Minerals Limited; Shenghe Resources Holding Co., Ltd.; Shin-Etsu Chemical Co., Ltd.; Ucore Rare Metals Inc.
The global market size was valued at USD 5.47 billion in 2025 and is projected to grow to USD 9.44 billion by 2034.
The global market is projected to register a CAGR of 6.25% during the forecast period.
In 2025, Asia Pacific accounted for the largest revenue share of 84.50% due to dominant production volumes, extensive refining capacity, and presence of leading rare earth processors.
The neodymium segment accounted for 31.0% of the revenue share in 2025. This is fueled by its importance in high-performance permanent magnets used in EVs, robotics, and renewable energy systems.
The magnet segment held the largest revenue share of 40.80% in 2025. This is attributed to their importance in electric vehicle drivetrains, wind turbine generators, and high-performance consumer electronics.
Download Sample Report of Rare Earth Metals Market
Please fill out the form to request a customized copy of the research report.