Sonar Systems Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Sonar Systems Market Summary
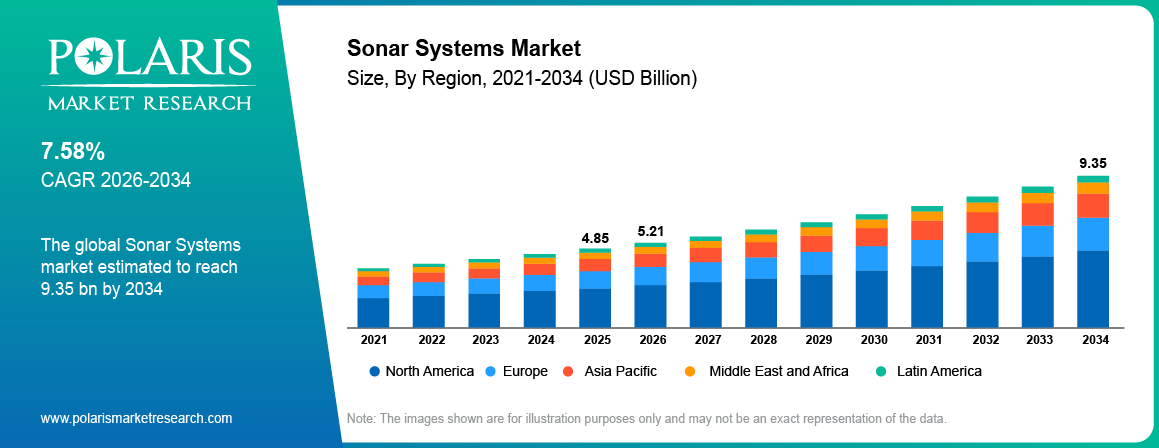
The global sonar systems market size was valued at USD 4.85 billion in 2025. The market is projected to account for a CAGR of 7.58% from 2026 to 2034. Rising defense expenditure and growing demand for underwater surveillance and anti-submarine warfare are a few of the key factors shaping the sonar systems market landscape.
Market Statistics
Sonar Systems Market Key Takeaways
- North America led the global sonar systems market with an 33.0% share in 2025. This is owing to the region’s substantial defense investments and advanced technological capabilities.
- Asia Pacific is projected to witness rapid growth at an 8.99% CAGR. The regional market growth is driven by increasing maritime security challenges.
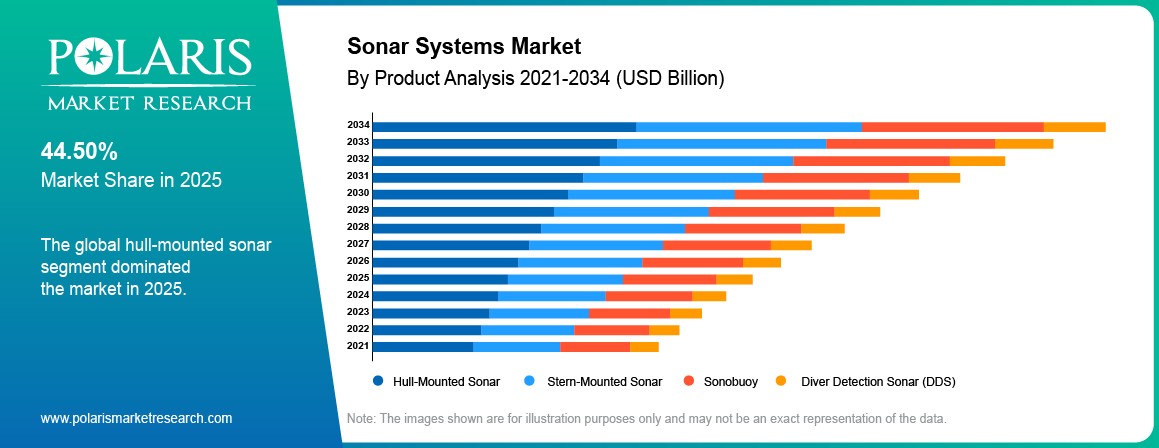
- By product, the hull-mounted sonar segment led the global market with an 44.50% share in 2025. This is due to the capability of hull-mounted sensors to enhance maritime security by detecting underwater mines and submarines.
- By platform, the airborne segment is projected to witness the fastest growth at an 7.69% CAGR. The segment’s growth is attributed to its critical role in expansive underwater surveillance.
- By application, the defense segment held the largest sonar systems market share of 68.00% in 2025. Rising maritime threats are driving the need for advanced underwater detection and surveillance capabilities.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Is a Sonar System?
A sonar system uses sound waves in order to detect, locate, and recognize any object or feature existing underwater. This underwater acoustic technology sends acoustic signals, analyzing their reflections in order to obtain information about the position and other properties of the target. Sonar devices are used in navigation, surveillance, underwater communication, and sea bottom exploration.
How Does Sonar Work?
Transmission of signal: Acoustic pulses are generated by the sonar device and are transmitted through the water medium through the transducer.
Propagation of sound: The acoustic wave travels through the water medium till it comes across any underwater object, seabed, or other objects.
Echo detection: The echo coming back is detected by the sonar device. The echo is captured by the transducer and converted into an electrical signal.
Processing of signal: The signal is processed by the sonar device in order to distinguish between the useful echoes and the surrounding noise and interference in acoustic form.
Detection of target: Detection of the target object and distance is done based on the processed data.
Displaying information: Information obtained is displayed through the display or software program for navigation and other purposes in underwater applications.
Sonar Systems Market Dynamics
Market Drivers : Rising Defense Expenditure and Naval Modernization
Higher defense expenditure is supporting the procurement and modernization of naval platforms, especially as governments improve their capability in submarine tracking and underwater surveillance. Sonar continues to play a crucial role in such modernization efforts since it enables naval forces to identify and locate underwater objects. In addition to these developments, there is a need for advanced performance in detection, signal processing, and operation under various underwater environments. In August 2026, India’s Defence Research and Development Organisation (DRDO) highlighted the deployment of indigenous sonar systems aboard recently commissioned naval ships (source: drdo.gov.in). This reflects continued investment in naval underwater operations. It is also creating demand for both new and upgraded sonar systems in the sonar systems market.
Market Drivers : Growing Importance of Environmental Monitoring and Marine Conservation
Sonar technology is expanding in ocean mapping and marine research. In particular, multibeam sonar is capable of giving in-depth details about the characteristics of the seafloor and the topography of the undersea terrain, allowing for studies to be made concerning marine habitats and unmapped regions. Sonar technology can therefore be applied outside the scope of defense uses, and is also gaining opportunities from research organizations and government ocean programs. In June 2026, NOAA carried out an expedition of Pacific Islands Mapping using multibeam sonar for deepwater mapping in areas such as Hawaii, Kingman Reef and Palmyra Atoll, Jarvis Island, and the Cook Islands (source: oceanexplorer.noaa.gov). The mapping also helped in collecting data on the environment, highlighting how sonar mapping may contribute to other oceanographic studies.
Market Restraints and Challenges : High System Costs and Complex Integration
Advanced sonar systems necessitate considerable expenses related to the acquisition, installation, integration, and maintenance of the system over time. In some cases, the costs are likely to rise even more for sonar systems developed for submarines, warships, or other types of specialized underwater platforms. The integration with existing navigation, combat management, communications, and surveillance systems requires considerable engineering effort. Older ships may also need to undergo certain changes in terms of their structure and the electrical system in order to incorporate new sonar systems. All of these aspects contribute to increased time frames for the procurement and installation of new systems. Additionally, commercial operators and research institutions with limited budgets may experience financial difficulties when adopting such systems.
Market Opportunities : Expansion of Sonar Use in Underwater Infrastructure Inspection
The growth of offshore and subsea facilities presents new opportunities for the application of sonars in the inspection and monitoring of assets. Sonars can be used by operators to inspect their pipeline networks, cables, subsea foundations, port structures, and other assets situated in environments where it might be hard to do visual inspection of the asset directly. Acoustic imaging can detect any alterations in the structure, sedimentation, debris, and other aspects of the underwater environment. Sonars can also inspect assets in poor visibility or when conditions are unfavorable for divers. There are new opportunities for sonar systems market manufacturers to provide services to offshore oil companies, marine construction companies, ports, and specialized companies providing inspection services. Demand can also extend to small-size sonars that can be mounted in remotely operated and autonomous vehicles.
Market Opportunities : Integration of Advanced Signal Processing and Imaging
Advances in signal processing and acoustic imaging can facilitate enhancements in the effectiveness and usability of sonar systems. Increased signal processing capabilities can assist in differentiating the signals from the noise and detecting targets in complex underwater environments. Acoustic imaging capabilities can assist in providing clear information about the target's size, shape, and location. With the assistance of software tools for signal processing, the scope increases for analyzing the collected acoustic information in an effective manner and displaying the analyzed information in a user-friendly way. Such capabilities can be added to the sonar system or the upgrade packages provided for the existing sonar system. Hence, in addition to manufacturing the sonar hardware, manufacturers can develop special software packages, which include signal processing and imaging capabilities along with data analysis capabilities. This can support the demands of defense operators as well as commercial and scientific users who have more demanding data requirements.
Market Trends : Shift Toward Compact and Modular Sonar Systems
Compact and modular sonar systems are increasingly being designed to accommodate a greater variety of marine platforms and environments. Modular sonar architecture enables the mounting of sonar systems on autonomous underwater vehicles, autonomous surface vessels, and other platforms where size constraints are an issue. A modular design further enables system customization according to mission needs rather than the existing system architecture. It makes upgrading easy and also allows replacement of faulty components without the need to replace the entire sonar system. This is particularly relevant for applications that demand portability, deployment, or platform independence of acoustic sensors.
Market Trends : Growing Use of Multi-Frequency Sonar
Manufacturers of sonar equipment have started to develop multi-frequency systems to suit varied applications requiring different levels of information. Low frequencies enable detection at a greater distance, whereas high frequencies can help to get greater detail but for a shorter range. Multi-frequency systems allow users to tailor the performance of sonar systems depending on the depth of water, types of objects being scanned, and other factors. This method has gained importance in hydrographic surveys, underwater inspection, and fishing. It is also being explored in other fields where a single frequency may not provide sufficient information.
Market Trends : Increasing Integration of AI in Sonar Systems
AI is helping sonar systems process and analyze underwater acoustic information much more efficiently. AI sonar detection can identify patterns in the large quantity of acoustic information and separate targets from the background noise. Machine learning algorithms may help automatically classify the targets and decrease the quantity of information analyzed by the operator. AI-based information processing can also help track targets and detect them in complex acoustic environments. With the increasing generation of data through sonar systems, AI can facilitate quicker analysis of data and enhance the ability of the operators to utilize the acoustic information.
Market Segmentation
The sonar systems market is primarily segmented on the basis of product, technology, platform, component, installation type, application, end user, and region:
| Segmentation Axis | Segments |
| By Product | Hull-Mounted Sonar · Stern-Mounted Sonar · Sonobuoy · Diver Detection Sonar (DDS) |
| By Technology | Active Sonar · Passive Sonar · Dual-Mode Sonar |
| By Platform | Ship · Submarine · Airborne · Unmanned Underwater Vehicle (UUV) · Seabed |
| By Component | Transmitters · Receivers · Transducers · Signal Processing Systems · Software · Other Components |
| By Installation Type | Line Fit · Retrofit |
| By Application | Defense · Commercial |
| By End User | Naval Forces · Coast Guards · Commercial Shipping · Oil & Gas · Fisheries · Research & Survey Organizations |
| By Region | North America (US, Canada) · Europe (Germany, France, UK, Italy, Spain, Netherlands, Russia, Rest of Europe) · Asia Pacific (China, Japan, India, Malaysia, South Korea, Indonesia, Australia, Rest of Asia Pacific) · Middle East & Africa (Saudi Arabia, UAE, Israel, South Africa, Rest of Middle East & Africa) · Latin America (Mexico, Brazil, Argentina, Rest of Latin America) |
Source: Polaris Market Research Analysis
By Product
The hull-mounted sonar segment led the global sonar systems market with an 44.50% share in 2025. Its leading position is supported by the wide usage of the technology on naval ships and other vessels in water where accurate detection is required underwater. The hull-mounted system is installed directly on the vessel and provides continuous acoustic surveillance without additional equipment. The application areas include target recognition, navigation, and underwater situation assessment. The fixed nature of the installation ensures the accessibility of the sonar system throughout the vessel’s mission, which is essential for vessels performing their mission for a long period. The modernization of existing fleets and replacement of the old systems is also creating a favorable market environment for hull-mounted sonar.
The sonobuoy segment is anticipated to account for a significant CAGR of 8.28%. Demand is driven by the utilization of sonobuoys in underwater surveillance and anti-submarine warfare (ASW) operations, where sonobuoys provide acoustic data from regions that might not be accessible through ship-mounted devices alone. Because they can be dropped from an aircraft, operators can search larger areas and examine potential underwater contacts remotely. Development of more powerful maritime patrol aircraft and airborne ASW operations is driving the use of sonobuoys in undersea detection networks. Acoustic sensing, data communication, and buoy technology are some of the factors that contribute to the growth of the market segment.
By Technology
The passive sonar segment held the largest sonar systems market share of 49.00% in 2025. The market position of this segment is driven by the ongoing requirement for systems that have the capability to perform continuous acoustic monitoring underwater through prolonged missions. Sonar technology has the capability to work continuously without any need for the transmission phase that comes with active sonar systems. The improved sensitivity of hydrophones and advances in acoustic data processing are helping these systems collect information in the difficult underwater environment. In addition to naval ships and submarines, special underwater monitoring systems are also becoming potential buyers of these products. The renewal of old acoustic systems with new ones further contributes to the segment’s leading position.
The dual-mode sonar segment is projected to grow at an 10.08% CAGR. Demand is supported by the adaptability of the systems, which allow the use of both active and passive properties in a single sonar system. Thus, it is possible to change sonar operation depending on the mission objectives without using additional equipment to perform specific operations. Dual-mode systems can also simplify shipboard equipment configuration when space and weight are limited. Their use is relevant in cases when naval vessels are required to perform several acoustic operations at once. Advances in transducer technology and system integration are promoting the development of dual-mode systems. As there is a need to upgrade current sonar systems, dual-mode systems may present an option for enhancing acoustic systems in current platforms.
Active Sonar vs Passive Sonar
Passive and active sonars have different methods of detecting objects under the water surface, with the difference lying in how each sonar detects its target. The active sonar works by emitting sound and interpreting the reflection received from the source, whereas the passive one receives sounds emitted from vessels or animals below the water surface. Selection between the two depends on detection requirements, operating environment, and the need for active ranging of targets.
| Feature | Active Sonar | Passive Sonar |
| Operating method | Sends a sound pulse and receives the echo back | Only listens to the sounds made by underwater objects |
| Target identification | Identifies targets through reflected sound | Identifies targets by sounds produced |
| Distance measurement | Measures the distance using the echo back | Can't measure target distance |
| Target information | Provides target location, distance, and other details | Provides target location and acoustic characteristics |
| Detectability | Tends to expose sonar platform through transmission | Detection doesn't require any signal transmission |
| Typical applications | Navigation, seabed mapping, obstacle detection, and target identification | Underwater surveillance, acoustic intelligence, and submarine identification |
| Main limitation | Sound transmission can expose the sonar platform | The efficiency depends on the sound from the target |
Source: Polaris Market Research Analysis
By Platform
The ship segment held the largest sonar systems market share of 46.0% in 2025. The segment includes a wide variety of military and non-military vessels that are fitted with sonar systems on board. Surface vessels are able to carry various types of sonar systems depending on their size and design, as well as operational needs. Military ships are equipped with these systems in order to improve their undersea awareness systems, while other ships utilize them for navigation, depth sounding, and other marine activities. The market demand is also driven by the installation of sonar systems in newbuilds and retrofitting of existing vessels with older systems. There exists a vast fleet of surface ships, which forms a solid customer base for providers of sonar systems. In addition, there is a certain demand for the upgrading of vessels, whereby the ships are fitted with new acoustic systems without being fully replaced.
The airborne segment is projected to grow at an 7.96% CAGR. Airborne sonar equipment provides a way to acquire underwater acoustic data without putting the aircraft too close to the target area. Such equipment is often used on maritime patrol aircraft and helicopters, especially when there is a need for quick coverage of a wide area. Sonobuoys are often dropped from such aircraft to gather acoustic data from selected areas. The airborne method also allows for searches in locations where there might be restrictions for the surface vessel to conduct operations. The demand for the system is associated with the adoption of new maritime surveillance aircraft and upgrades to existing mission systems. The improvements in the acoustic gear used in aircraft, data-link, and launching gear are supporting the incorporation of sonars into newer platforms.
By Component
The transducers segment held an 34.60% share of the sonar systems market in 2025. Transducers are a key component of sonar systems because they help convert electrical energy into sound waves and transform the sound waves reflected back into an electrical signal for further processing. The demand for this component is directly linked to the production and upgrading of sonar systems for different underwater vehicles. This segment also benefits from the demand for transducers for different depths, frequencies, and installations. Manufacturers are focusing on developing transducers with better sensitivity, longevity, and miniaturization capabilities according to the demands of the new sonar systems. Replacements from vessels already in service can also provide another revenue stream when the transducers have reached their operational life or can no longer meet the requirements of the system.
The software segment is projected to account for an 10.12% CAGR. Sonar software is being increasingly adopted for managing the information generated by various sensing and detection operations carried out by a sonar system. Software can help configure the equipment, monitor system performance, log acoustic information, and analyze collected data. It enables manufacturers to add new capabilities through updates instead of full replacement of the sonar system. This is especially important for operators who want to prolong the lifecycle of installed equipment. Integration with ship systems can be another segment demand driver, as sonar information must be shared with navigation or command and control systems, for example. Software for handling acoustic information and analyzing mission data can also support the segment. As sonar systems incorporate more software, demand in the segment is expected to be driven by software upgrades as well as new system installations.
By Installation Type
The retrofit segment led with an 54.00% sonar systems market share in 2025. Retrofit installations provide an option to incorporate the capabilities of more modern sonars into platforms that have not been configured with modern system configurations. This may become necessary where the design of the platform, the availability of installation space, or the current interfaces limit the ability to install new equipment. Retrofit efforts may include modifications to the mountings, cabling, power supply, or software interfaces to facilitate installation of the sonar equipment. The suppliers who can configure their products to suit various designs of the vessels can thus support a much larger number of platforms already in operation. Retrofit work can also be planned alongside scheduled maintenance programs, making it possible to avoid any additional periods of downtime for the vessels.
The linefit segment is projected to grow at an 8.35% CAGR. Installation of the linefit system involves incorporating sonar equipment into a ship during construction. In this way, the integration of sonar is made right from the start of building the platform. It offers more flexibility for the builders concerning the placement of sensors, cables, power connections, and other equipment. The demand for linefit sonar systems is linked to the production of new ships. The building of new ships can provide opportunities for sonar suppliers to install their products as part of an onboard system package. The market is driven by the rising popularity of the installation of underwater sensing devices in new vessels.
Sonar Market by Application
The defense segment accounted for the largest market share of 68.00% in 2025. Demand comes from the application of sonar on naval platforms and underwater missions requiring acoustic data while performing the tasks. The sonar devices are installed on surface ships, submarines, and aircraft used in marine missions. Different configurations of the systems are selected based on the platform and mission requirements. The segment also includes replacement and upgrade activities as older equipment is replaced by defense operators. The procurement of special sonar systems for new ships creates yet another area of demand. These factors support the strong position of defense applications in the sonar systems market.
The commercial segment is projected to grow at an 8.35% CAGR. The growth in use of sonar systems among the commercial users is driven by the rise in use of marine services requiring specialized underwater sensors. Operators need sonar systems that are either integrable on existing ships or can be used as stand-alone systems. Product requirements vary by ship type, environmental conditions, and the level of underwater information desired. There are different types of configurations being offered by suppliers of these products to cater to the needs of both large commercial fleets as well as specialized marine operators.
By End User
The naval forces segment accounted for the largest share of 46.00% in 2025. The naval industry is an important customer base for sonar solutions owing to the integration of such systems within various naval vessels. Procurement needs arise from the requirement to provide new commissions with specialized underwater surveillance systems. Procurement needs also arise within existing naval fleets to maintain, replace, or upgrade sonar equipment and systems. Procurement needs vary by surface ships, submarines, and other naval vessels, leading to varied sonar requirements. Additionally, the segment stands to benefit from long-term defense procurement programs in which naval sonar systems form part of the overall equipment required for new vessels.
The oil & gas segment is projected to grow at an 7.61% CAGR. Sonar systems are deployed by oil & gas companies as part of offshore and subsea activities. The requirement is driven by the necessity of accurate underwater information about marine assets and operational regions. The sonar equipment may be chosen on the basis of water depth, environmental conditions, and the nature of the vessel or subsea structure. The segment is also expected to benefit from operators & contractors using specialized marine equipment for offshore operations. Since offshore assets operate for a long time period, the sonar equipment may require regular upgrades or replacement in order to sustain system performance. The launch of new offshore projects that include underwater sensing equipment further contributes to the demand for sonar systems.
Use Cases of Sonar Systems
| Use Case | Function of Sonar Systems |
| Seabed Mapping | Sonar is used for mapping the underwater topography and detecting alterations in seabed depths and contours. |
| Underwater Search | Acoustic scanning aids in locating the wreckage, debris, and other submerged objects in hard-to-reach areas. |
| Marine Surveying | Sonar technology is used by survey teams to obtain underwater measurements for assessment of marine locations. |
| Fish Finding | Provides information about fish concentrations and fish locations with the help of fish-finding sonar. |
| AUV Based Surveys | Autonomous Underwater Vehicle (AUV) sonar technology enables unmanned vehicles to conduct acoustic scanning while traversing defined underwater locations. |
| High Resolution Imaging | Synthetic aperture sonar is used for producing high-resolution acoustic imaging, which can be used to detect smaller objects and features in or around the seabed. |
| Obstacle Detection | Sonar systems can detect submerged obstacles and provide their location information. |
| Underwater Inspection | Acoustic technologies can inspect submerged objects in case water conditions do not permit conventional visual inspection. |
| Aquaculture Monitoring | The sonar can be used to monitor fish stocks and to study the distribution of the fish population in the aquaculture farm. |
| Arctic Under-Ice Operations | The sonar equipment is used to gather information under ice-infested water surfaces. |
| Mine Countermeasures | Sonar is used to detect underwater mines and other items during mine countermeasure operations. |
Source: Polaris Market Research Analysis
Sonar Systems Market by Region
North America
North America accounted for the largest sonar market share of 33.0% in 2025. The regional market benefits from ongoing investments in naval fleets, maritime surveillance, and underwater detection systems. Sonar equipment is used in surface ships, submarines, and other equipment needing underwater detection during marine missions. Demand is further driven by marine research, seabed surveys, and offshore missions needing underwater information. The presence of established sonar equipment suppliers and defense equipment manufacturers contributes to the development and supply of state-of-the-art sonar equipment in the region. Modernization of naval fleets drives demand for new and updated sonar systems. Growing deployment of unmanned underwater systems is further creating the need for compact sonar equipment. All these factors contribute to the dominant position of North America in the global sonar systems market.
Asia Pacific
Asia Pacific is projected to witness rapid growth at an 8.99% CAGR. Market expansion is driven by the investments being made in naval ships and capabilities in the region. Several nations are also modernizing their underwater monitoring equipment as part of their efforts to modernize their navies. There is an increasing demand for sonar systems in various applications such as surface vessels, submarines, and unmanned underwater systems. Marine commercial activities such as offshore operations and seabed surveying activities have contributed to the demand for underwater sensing. The demand for compact sonar systems, which can be used in unmanned systems, is also on the rise owing to the increasing utilization of autonomous underwater vehicles. Further, the local development of defense and marine technologies strengthens the regional supply base.
Europe
Europe accounted for an 25.50% sonar systems market share in 2025. The growth in the regional market is driven by continuous efforts toward the modernization of naval fleets and the development of underwater surveillance systems. Several European nations are investing in upgrading sonar systems used aboard ships and submarines. The other factor driving the demand includes requirements for sonar systems in marine research, underwater mapping, and offshore activities. The presence of companies involved in the design and production of sonar systems contributes to the regional market development. The other major driver of demand is replacement, especially as aging equipment continues to be maintained and updated.
Latin America
The Latin America sonar systems market is projected to account for an 7.32% CAGR. The long coastline and extensive marine activities in the region give a wide array of uses for sonar. Some of the areas where sonar is used include fisheries, wherein the acoustic system assists in determining fish clusters and the conditions of the water body. Other areas where sonar is used include port development and hydrographic surveys, which need information about the depths of the seabed. The offshore energy projects present yet another opportunity for the use of sonar, especially in the case of subsea surveys and operations of vessels. Nations with established maritime industries have upgraded their survey and sensory equipment. Increased use of remote and unmanned vessels can also expand the use of compact sonar devices.
Middle East & Africa
The Middle East & Africa sonar systems market is projected to grow at an 8.22% CAGR. The coastlines, offshore energy assets, and shipping lanes within the region create unique needs for underwater sensing devices. Sonar technology can be used in surveying the seabed near the offshore energy facilities and assisting ships in navigating areas where there is reduced underwater visibility. Acoustic surveying can also play an important role in port and other marine infrastructure construction projects. Within Africa, fisheries and marine research add to the applications of the technology within the field. Unmanned underwater devices for survey and inspection can further increase demand for the technology.
Key Players & Competitive Landscape
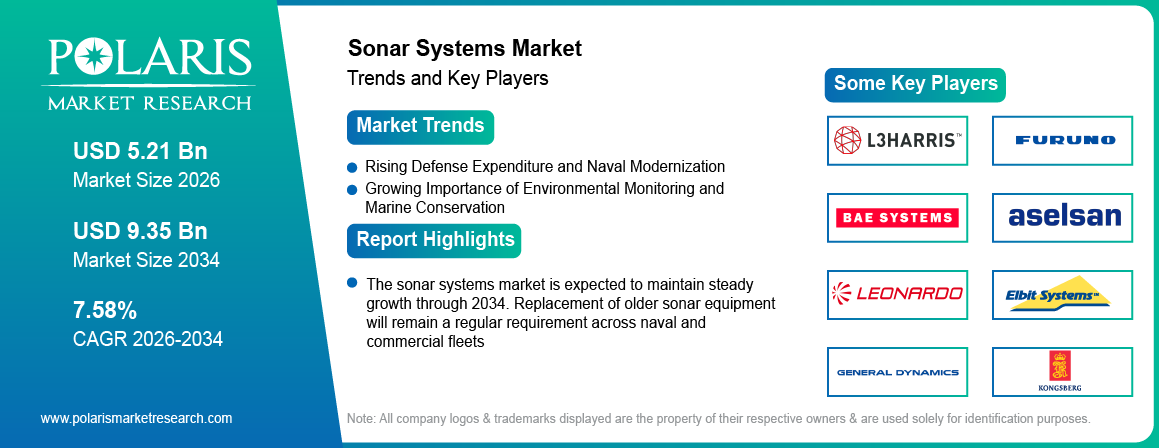
The sonar systems market includes established defense technology providers, marine electronics vendors, and specialty sonar solution companies. Competition is shaped by performance, reliability, compatibility, and the capability to deliver according to operating requirements. Sonar solutions are being developed for surface ships, submarines, aircraft, and unmanned underwater systems. Product differentiation will depend on factors such as acoustic sensors, signal processing capabilities, imaging, and system integration.
Retrofitting represents another form of competition, as vendors customize their products to fit existing ship designs. In the commercial segment, the vendors are concentrating on providing systems that are easy to install and are suitable for specialist surveys and inspections. Collaboration with the shipbuilding companies, military organizations, and marine technology providers can help the companies gain access to new programs and applications. The overall competition goes beyond a particular sonar unit, and the vendors have started providing an integrated suite of hardware, software, and processing capabilities.
Vendor Positioning
| Company | Headquarters | Primary Focus |
| Ankara, Turkey | Naval sonar, underwater surveillance, and acoustic systems | |
| BAE Systems plc | London, UK | Naval sonar, submarine systems, and underwater warfare technologies |
| Elbit Systems Ltd. | Haifa, Israel | Naval sonar, underwater sensing, and acoustic surveillance systems |
| FURUNO ELECTRIC CO., LTD. | Nishinomiya, Japan | Marine sonar, fish finding, navigation, and hydrographic equipment |
| Reston, Virginia, U.S. | Submarine sonar, undersea systems, and naval platform technologies | |
| Kongsberg Gruppen ASA | Kongsberg, Norway | Multibeam sonar, hydrographic systems, underwater sensing, and marine robotics |
| L3Harris Technologies, Inc. | Melbourne, Florida, U.S. | Sonar systems, acoustic processing, and undersea surveillance technologies |
| Leonardo S.p.A. | Rome, Italy | Naval sonar, underwater surveillance, and defense electronics |
| Lockheed Martin Corporation | Bethesda, Maryland, U.S. | Undersea warfare systems, sonar, and submarine technologies |
| Northrop Grumman Corporation | Falls Church, Virginia, U.S. | Sonar processing, undersea systems, and acoustic technologies |
| RTX Corporation | Arlington, Virginia, U.S. | Naval sensors, sonar-related systems, and undersea defense technologies |
| Saab AB | Stockholm, Sweden | Naval sonar, underwater surveillance, and submarine systems |
| Teledyne Technologies Incorporated | Thousand Oaks, California, U.S. | Imaging sonar, acoustic sensors, and marine survey equipment |
| Thales Group | Paris, France | Naval sonar, mine detection, underwater surveillance, and acoustic systems |
| TKMS ATLAS ELEKTRONIK GmbH | Bremen, Germany | Naval sonar, submarine sensors, mine warfare, and underwater systems |
Source: Polaris Market Research Analysis
Recent Industry Developments
- August 2026: ELAC SONAR, a subsidiary of Cohort, received a €140.7 million contract from Saab. The contract is for integrated sonar systems for Poland's Orka submarine program. Work started immediately, with deliveries planned through the mid-2030s. The contract includes active and passive sonar systems for the submarines. (source: londonstockexchange.com)
- July 2026: Lockheed Martin announced an agreement to acquire Ultra Maritime for $3.45 billion. Ultra Maritime's products include sonobuoys, towed sonar arrays, and hull-mounted sonar systems. The transaction is subject to closing conditions. (source: lockheedmartin.com)
Future Outlook
The sonar systems market is expected to maintain steady growth through 2034. Replacement of older sonar equipment will remain a regular requirement across naval and commercial fleets. New vessel programs will add further installations as sonar becomes part of the onboard equipment package. Manufacturers are likely to offer systems in different sizes and configurations to suit vessel and mission requirements. This will allow the market to serve both large platforms and smaller underwater systems.
Research Methodology
This sonar systems market report is developed using a structured, multi-stage research methodology that combines primary and secondary research with rigorous data triangulation. Secondary research draws on company annual reports, defense procurement disclosures, government and naval budget filings, industry association publications, and reputable trade and technical journals to establish the initial market landscape, key players, and historical trends.
Primary research follows. It involves structured interviews and discussions with C-level executives, product managers, and technical experts across sonar-system manufacturers, defense contractors, and end-user organizations such as naval forces, commercial marine operators, and research institutions. These conversations validate secondary findings and surface unpublished pipeline and pricing insight. They also help identify emerging technology and regional trends.
Market sizing and forecasting apply a combined top-down and bottom-up approach: top-down analysis anchors the total addressable market against defense and marine-technology spending, while bottom-up analysis builds estimates from segment-level revenue by product, platform, application, and region. Figures are cross-validated through triangulation between the two approaches and reconciled against primary-interview data.
The final dataset undergoes internal quality review, including consistency checks across historical, base-year, and forecast figures, before publication. A full breakdown of data sources, sample composition, and estimation techniques is available in the complete Research Methodology annex of the underlying report.
Sonar Systems Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 4.85 billion |
| Market Size Value in 2026 | USD 5.21 billion |
| Sonar Systems Market Forecast 2034 | USD 9.35 billion |
| CAGR | 7.58% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Sonar Systems Market FAQ's
The sonar systems market size was valued at USD 4.85 billion in 2025. The market is projected to reach USD 9.35 billion by 2034.
The market is projected to account for an 7.58% CAGR from 2026 to 2034.
North America held the largest market share of 33.00% in 2025. This is due to the region’s substantial defense investments.
The airborne segment is projected to grow at an 7.96% CAGR. This is owing to its critical role in expansive underwater surveillance.
A few of the key market players include ASELSAN A.?.; BAE Systems plc; Elbit Systems Ltd.; FURUNO ELECTRIC CO., LTD.; General Dynamics Corporation; Kongsberg Gruppen ASA; L3Harris Technologies, Inc.; Leonardo S.p.A.; Lockheed Martin Corporation; Northrop Grumman Corporation; RTX Corporation; Saab AB; Teledyne Technologies Incorporated; Thales Group; and TKMS ATLAS ELEKTRONIK GmbH.
Active sonar sends out a signal to detect and measure the distance to the target, while passive sonar just receives the sounds from the underwater source. Active sonar is extensively employed when the ranging of the target is required directly, while passive sonar is very useful when monitoring is required without any transmission of signals.
Sonar systems are applied in both defense and commercial activities on water bodies. Defense sector users deploy the sonar systems for underwater surveillance and target detection. Commercial users apply sonar systems for seabed surveys, marine surveys, and underwater inspections.
The depth of the water can influence the transmission of acoustic waves. Temperature and salinity may influence sound propagation. The background noise level may decrease the efficiency of signal detection.
The sonar system supplies information on the presence of objects or activities underwater. Sonar systems are used by naval forces to scan and identify targets in the underwater environment.
The sonar systems may either be integrated during the building process of the vessel or retrofitted on a vessel that has already been built. The linefit integration is where the sonar system is integrated while designing the vessel. The retrofitting is where the sonar system is integrated into an already existing vessel.
Download Sample Report of Sonar Systems Market
Please fill out the form to request a customized copy of the research report.