Stablecoins & CBDCs Market Size, Share, Trends and Forecast, 2026–2034
REPORT DETAILS
Stablecoins & CBDCs Market Summary
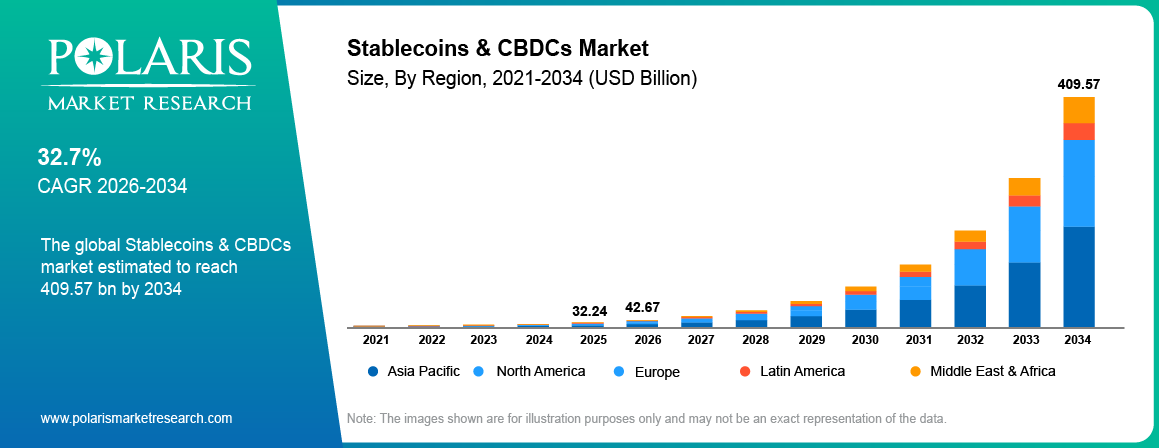
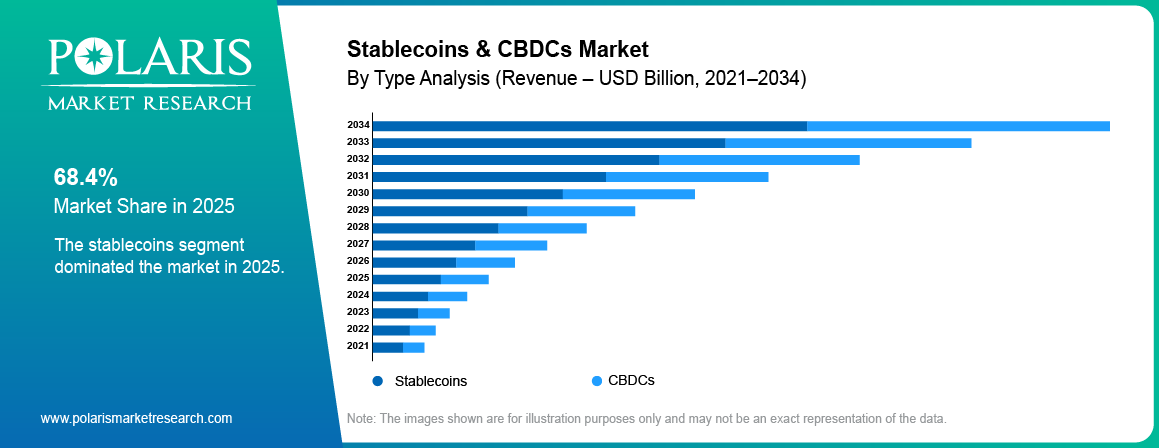
The global stablecoins & CBDCs market size was valued at USD 32.24 billion in 2025. The market is expected to exhibit a CAGR of 32.7% during 2026–2034. The stablecoin market size is driven by the demand for digital payment infrastructure, private digital currencies, and sovereign digital money. The central bank digital currency market growth is supported by regulatory clarity, banking participation, cross-border payment systems, digital asset settlement, and enterprise treasury applications.
Market Statistics
Key Takeaways
- In 2025, North America led the stablecoins & CBDCs market with 38.6% share. This dominance is attributed to well-established financial institutions, digital asset infrastructure, and stablecoin payment transactions.
- Asia Pacific is expected to register the highest CAGR of 35.8% during the forecast period, due to the presence of CBDC pilots, adoption of digital payment systems, and cross-border payments.
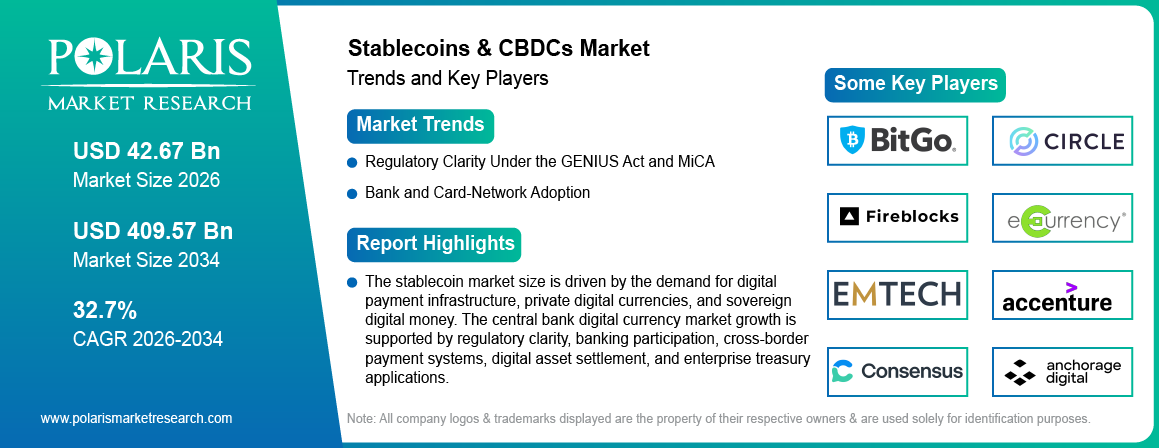
- The stablecoins segment held the largest market share of 68.4% in 2025, owing to the need for digital asset liquidity, cross-border payments, and private digital payment systems.
- The banks segment accounted for 42.7% share in 2025, due to growing needs for digital settlement systems, tokenized deposits, custody services, and issuance of stablecoins.
- The payments and settlements segment is forecasted to record the fastest CAGR of 34.6% during 2026–2034. This is owing to growing demand for cross-border payments, remittances, and round-the-clock settlements.
- The issuance segment accounted for 38.6% revenue share in 2025, due to regulatory guidelines, institutional participation, and growing demand for stablecoin issuance platforms.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What are Stablecoins & CBDCs?
Stablecoins are tokens pegged to a reference asset (typically a fiat currency) so as to have stable prices. Fiat-backed stablecoins are backed by reserve assets that support their target value. One of the most popular examples is the use of USDC and USDT in digital asset trading, payments, and liquidity management. Their issuers require mechanisms for issuing tokens, redeeming them, tracking reserves, and monitoring transactions.
Central bank digital currencies (CBDCs) are digital versions of sovereign money issued by a central bank. The central bank digital currency (CBDC) market includes the technology and services for the design, issue, distribution, and management of these instruments. Retail CBDCs are meant for payments by consumers and businesses. Wholesale CBDCs are intended for use in transactions between financial institutions, such as interbank settlement and some capital market activities.
The Stablecoin and CBDC market includes cryptocurrencies and blockchain-based digital assets, enabling secure, efficient, and transparent digital payments and financial transactions
The market also includes providers of infrastructure for issuance platforms, digital asset custody, payment processing, compliance tools, and ledger technology. A platform for issuing stablecoins handles minting, burning, redemption and records of reserves for tokens. Custodial services for stablecoins ensure protection of cryptographic keys, and digital assets. Payment services connect digital assets to merchants’ acceptance and payments. Compliance vendors supply identity verification, sanctions screening, transaction monitoring, and reporting systems. In May 2026, BTQ Technologies was selected to provide post-quantum security infrastructure for South Korea’s first bank-led Korean won stablecoin proof of concept with iM Bank and Finger (Source: PR Newswire).
Tokenized deposits fall under the same category of digital money. They represent commercial bank deposits in token form and remain liabilities of the issuing bank. Their legal structure differs from privately issued stablecoins and central bank money. Tokenized deposits may be employed by banks for making institutional payments, liquidity management, and financial transactions.
Stablecoins vs CBDCs vs Tokenized Deposits
The key differentiating factors between a stablecoin and CBDC are the issuer, liability of the entity, backing, and purpose. Tokenized deposits create a third category because they are commercial bank money in digital form. These differences affect redemption rights, regulatory obligations, settlement design, and institutional adoption.
| Attribute | Stablecoins | CBDCs | Tokenized deposits |
| Issuer | Licensed private issuer (fintech, bank subsidiary, trust company) | Central bank | Commercial bank |
| Whose liability | Issuer | Central bank | Issuing bank |
| Backing | 1:1 reserves of cash and short-term government securities | Sovereign money | Bank balance sheet (deposit) |
| Typical ledger | Public blockchains (Ethereum, Tron, Solana, Layer-2s) | Central or permissioned DLT | Permissioned bank ledgers |
| Yield to holder | Prohibited for payment stablecoins under the GENIUS Act | Usually none; holding limits common | Can pay interest like a deposit |
| Governing rules | GENIUS Act (US), MiCA (EU), HK Stablecoins Ordinance, MAS framework | National central bank law | Banking regulation |
| Main use today | Trading liquidity, cross-border payments, treasury | Retail payments pilots, interbank settlement | Institutional payments, intraday liquidity |
| Examples | USDT, USDC, PYUSD, RLUSD, EURC | e-CNY, e₹, Sand Dollar, eNaira; digital euro (planned) | JPM Coin (Kinexys), Citi Token Services |
Source: Polaris Market Research Analysis
Stablecoins offer private digital value transfer and may operate on public blockchains. Their reliability depends on reserve quality, redemption arrangements, issuer controls, and the relevant legal framework. CBDCs represent central bank money and follow the design selected by the issuing authority. Tokenized deposits remain part of the commercial banking system and follow applicable deposit rules.
The commercial choice depends on the transaction. A payment provider may use stablecoins for selected international transfers. A central bank may assess a retail CBDC for domestic payment access. A commercial bank may use tokenized deposits for institutional settlement. The three instruments therefore serve related but distinct financial needs.
Impact of AI in Stablecoins & CBDCs Market
- Artificial intelligence (AI) adoption could enhance transaction monitoring, compliance reviews, and payment automation for digital currency platforms. AI-powered anti-money laundering solutions can examine transaction patterns, flag unusual activity, and prioritize cases for analysts to review. These tools can help compliance teams handle high transaction volumes. However, their effectiveness depends on data quality, model validation, and effective oversight by humans.
- Another possible AI application would be that of agentic payments. The AI agent could initiate or prepare transactions upon verification of limits, rules, and authorization. An enterprise treasury system, for example, might review an invoice, confirm payment instructions, and prepare a transfer for approval. Stablecoin payments would still require identity checks, controls over access, transaction limits and audit records.
- Artificial intelligence can also help issuers gauge redemption demand, watch liquidity, and find strange wallet activity. CBDCs could use AI tools to help detect fraud and monitor payments, subject to the privacy and governance requirements of the issuing central bank. AI does not replace reserve management, financial controls or independent compliance reviews. The combination of AI and digital currency infrastructure may create demand for programmable money and automated 24/7 settlement. Commercial adoption will depend on secure execution, clear accountability, reliable transaction records, and evidence of operating benefits.
Market Dynamics
Driver: Regulatory Clarity Under the GENIUS Act and MiCA
Regulatory clarity is driving the stablecoins and CBDCs market by defining rules for issuer licensing, reserve management, redemption, and disclosures. the US GENIUS Act became law in July 2025, creating the first federal framework for payment stablecoins. The act provides regulation of payment stablecoins, with permissible issuers and reserve requirements. In February 2026, the Office of the Comptroller of the Currency published a rulemaking proposal in accordance with the Act's provisions. EU’s MiCA transition period closed in July 2026. MiCA establishes requirements for e-money tokens, asset-referenced tokens, and crypto-asset service providers in the EU. Such frameworks increase the demand for stablecoin compliance systems and reserve attestation services. There is a need for reliable reporting, customer identification and transaction monitoring services by the issuers to facilitate regulated markets (Source: OCC).
Driver: Bank and Card-Network Adoption
Rising demand for digital currency issuance, custody, and settlement services is being driven by adoption by banks and card networks. Banks need secure systems to handle transactions, customer funds, and regulatory reporting. A bank-issued stablecoin would provide a pathway for eligible banks or entities affiliated with banks to offer private digital currency products subject to applicable rules. Banks could also use a third-party issuance platform to track token creation, redemption, and reserve holdings. Other options for institutional settlement are tokenized deposits and wholesale CBDCs. Visa and Mastercard are expanding the reach of digital currency infrastructure via payment networks and settlement services. In October 2026, StraitsX explained how its integrated card issuing, processing, and stablecoin settlement infrastructure makes it easier to roll out multi-market card programs. These activities offer opportunities for stablecoin payments, custody services and technology vendors. Adoption will depend on licensing, integration costs, liquidity, and customer demand (Source: StraitsX).
Driver: Real-Time Cross-Border Settlement and Remittances
The increasing demand for faster cross-border payments and remittances is creating opportunities for stablecoin-based payment services. Conventional transfer methods involve several intermediaries, different processing times, and foreign exchange fees. Payments companies can leverage stablecoins to move value across specific corridors and settle transactions outside traditional banking hours. In September 2026, U.S. Bank ran a successful live cross-border payments pilot between its North American and European entities using its USBDC stablecoin on the Stellar blockchain. Businesses can also use stablecoin settlement for supplier payments and international treasury transfers. Digital wallets can be integrated with local payout networks if customer KYC is done and local regulations are followed. The commercial case is based on total transfer costs, liquidity, redemption access, and local currency conversion. Settlement on a 24/7 basis would make transactions more available, but providers would still be required for fraud controls, sanctions screening, and reliable cash-out services (Source: Ledger Insights).
Restraints: Reserve Transparency, Fragmented Licensing, and Deposit Flight
Reserve transparency remains a major constraint in the stablecoin and CBDC market. Institutional buyers want to know about reserve assets, redemption terms, custody arrangements, and issuer financials. Weak disclosures may undermine confidence and increase redemption risk. License fragmentation is another obstacle, as providers must follow different authorization and reporting requirements across markets. These differences increase the cost of compliance and decrease product availability. Issuers and service providers have to invest in secure wallets, private key management, transaction monitoring, and redemption systems. These requirements raise operating costs and create barriers to entry for smaller vendors.
Opportunities: Tokenized Assets, Enterprise Treasury, and Non-USD Stablecoins
Asset tokenization bridges stablecoins to settling digital securities and other financial transactions. Money that can be programmed could tie payments to approved invoices, the terms of a contract, or the transfer of an asset. Enterprises may also look to stablecoins for supplier payments, treasury transfers, and international liquidity management. Such applications generate demand for custody, payment processing, treasury integration and compliance software. Non-dollar stablecoins, including those pegged to the euro, may appeal to firms that trade in other currencies and seek to minimize the number of conversions required. In August 2026, Revolut launched a euro-pegged stablecoin, EURR, expanding its digital asset offerings and its ability to make euro-denominated payments. Usage depends on reserve quality, liquidity, redemption processes, and local regulations. Providers must ensure that they have the capacity to incorporate the digital currencies into their finance system and that the processes of authorization, reconciliation, and auditing are clear (Source: Revolut).
Stablecoins & CBDCs Market Segmentation Analysis
The stablecoins & CBDCs market is segmented on the basis of component (issuance, custody, payments & settlement, and compliance), end user [banks, fintechs and payment service providers (PSPs), and merchants & enterprises], type [stablecoins and central bank digital currencies (CBDCs)], and technology [blockchain, consensus mechanisms, and interoperability solutions; and by application into payments & settlement, remittances, decentralized finance (DeFi), forex, and others]. The reasons behind the demand for these services include digital payment needs, stablecoin infrastructure, international payments, and institutional payments.
By Component
The issuance segment accounted for 38.6% market share in 2025. The leading position is driven by high demand from issuers for stablecoin issuance, token minting, redemption, and reserve management solutions. Issuers require secure platforms to facilitate asset tokenization and comply with regulations. Stablecoin issuance platforms help in managing issuance processes and linking digital assets to payment platforms for banks and fintechs. Regulatory frameworks such as the GENIUS Act in the U.S. and MiCA in the EU will drive demand for issuance solutions. Fiat-backed stablecoins show the importance of such solutions for digital asset liquidity and payments (for example, USDC, USDT).
As per our stablecoin market forecast 2034, the payments & settlement segment is expected to exhibit the CAGR of 34.6% during the projected period. Financial institutions and payment service providers are looking at faster cross-border transfers, merchant payments, and institutional settlement, propelling demand for stablecoin payments. Settling in stablecoin also allows for transactions outside of traditional banking hours, subject to liquidity and regulatory requirements. Payment networks and fintechs are integrating digital currency infrastructure into the existing financial system. More opportunities include remittances and enterprise treasury transfers. Adoption depends on transaction costs, currency conversion, customer access, and local payment rules.
Component Segment Comparison
| Component | What it covers | Main buyers | Representative vendors | 2026 demand trigger | Revenue model |
| Issuance | Minting/burning, reserve management, redemption, white-label issuance | Banks, fintechs, corporates | Paxos, Circle, Fireblocks; CBDC: EMTECH, eCurrency, Soramitsu | GENIUS Act licensing; bank consortia | Reserve yield, platform fees |
| Custody | Wallets, MPC key management, qualified custody of tokens and reserves | Banks, exchanges, PSPs | Anchorage Digital, BitGo, Fireblocks; CBDC wallets: Giesecke+Devrient, IDEMIA | Custody rules in GENIUS and MiCA | Assets-under-custody fees, SaaS |
| Payments & settlement | Merchant acceptance, payouts, cross-border rails, interbank settlement | PSPs, merchants, remittance firms, banks | Visa, Mastercard, Stripe, Circle Payments Network, Ripple, Stellar | 24/7 settlement; stablecoin payouts in new corridors | Transaction and FX fees |
| Compliance | KYC/AML, sanctions screening, Travel Rule, reserve attestation, reporting | Issuers, banks, VASPs | Blockchain analytics and RegTech vendors; audit firms for attestation | AML duties under GENIUS; MiCA reporting | Subscription SaaS, audit fees |
Source: Polaris Market Research Analysis
By Type
The global stablecoins & CBDCs market by type is bifurcated into stablecoins and central bank digital currencies (CBDCs). Based on our analysis, the stablecoins segment accounted for the largest market share of 68.4% in 2025. The dominance is supported by the rising adoption in digital payments, decentralized finance (DeFi), and cross-border transactions. Stablecoins such as USDC and USDT, backed by fiat currency, enable the transfer of digital value and liquidity across crypto exchanges and payment networks. Integration has increased the application of payment processors and institutional services. The segment is also commercially strong because of expanding regulated issuance, custody, and redemption infrastructure.
The CBDCs segment is expected to register a higher CAGR of 34.8% during 2026–2034. Sovereign digital currencies are being considered by central banks to make payments more efficient and to facilitate access to financial services and institutional settlements. Retail CBDCs are targeted at consumer and business payments. However, wholesale CBDCs are targeted at transactions between financial institutions. CBDC development at different stages includes projects like the e-CNY, e-rupee, and digital euro. Distributed ledger technology and interoperability solutions can enable the interface with existing financial infrastructure of digital currency systems. Growth depends upon central bank policy, project implementation, technology procurement, and public adoption.
Stablecoins vs CBDCs
| Attribute | Stablecoins | CBDCs |
| Issuer | Licensed private entity (fintech, bank subsidiary, trust company) | Central bank |
| Liability of | Issuer | Central bank |
| Backing | 1:1 reserves of cash and short-term government securities | Sovereign money (no reserves needed) |
| Ledger | Mostly public blockchains (Ethereum, Solana, Tron, Layer-2s) | Central or permissioned DLT |
| Yield to holder | Prohibited for U.S. payment stablecoins under the GENIUS Act | Usually none, holding limits common |
| Types | Fiat-backed (USDC, USDT, PYUSD, RLUSD, EURC) | Retail (consumers/businesses) and wholesale (interbank) |
| Key end use | Trading liquidity, cross-border payments, treasury | Retail payment pilots, interbank settlement |
| Privacy and control | Issuer can freeze or claw back, public-chain transparency | Central bank design choice, privacy set by policy |
| Examples | USDC, USDT, PYUSD, RLUSD, EURC | e-CNY, e₹, Sand Dollar, eNaira, digital euro (planned) |
| Market status | Live and scaling, bank issuance moving from pilot to launch | Mixed, pilots and early launches (the U.S. has ruled out a retail CBDC) |
Source: Polaris Market Research Analysis
By Application
The global stablecoins & CBDCs market by application is segmented into payments & settlement, remittances, decentralized finance (DeFi), forex, and others. The payments & settlements segment captured the largest share of 34.6% in 2025 on account of rising demand for instant, efficient, and cost-effective transactions. Stablecoins and CBDCs provide digital means for merchant payments, corporate transactions, and institutional settlements. Stablecoin settlement may reduce reliance on some intermediaries in selected transactions. Integration with payment networks and financial platforms also creates opportunities for cross-border payments.
The remittances segment is projected to register the highest CAGR of 35.6% over the forecast period. Efficient cross-border payments have opened up opportunities for stablecoin-based money transfers. In certain corridors, considering transaction fees, liquidity, and regulation, cryptocurrencies may cut transaction time and costs. Payment service providers can connect their digital wallets to local payout channels to access end-users in different countries. Adoption needs customer access, reliable cash-out services & compliance with financial crime controls. Growth also depends on collaborations between digital currency platforms, remittance companies and local payment providers.
By End User
The banks segment accounted for an estimated 42.7% share in 2025, propelled by demand for digital transaction management, custody, and regulated payment infrastructure. Banks are looking at bank-issued stablecoins, tokenized deposits, and wholesale CBDC projects for institutional transactions. These tools support different legal frameworks and applications for these operations. Digital assets’ storage, transaction monitoring and reconciliation services are required from banks for management of digital currency operations. Regulatory issues and integration into the banking infrastructure will play an important role in the usage of digital currencies. Commercial prospects depend on customer needs, licensing, liquidity management, and digital currencies' impact on deposit funding.
The fintechs and payment service providers segment is projected to witness the highest CAGR of 36.4% during 2026–2034. Fintechs and PSPs use digital currency infrastructure for cross-border transfers, payment processing, payouts, and crypto wallets. Stablecoins could help these providers establish international payment corridors and reduce settlement lags in certain transactions. Demand is also coming from stablecoin infrastructure providers for custody, issuance, and compliance services. Providers are responsible for customer verification, sanctions screening, liquidity, and local currency conversion. Adoption depends on regulatory access, the costs of integrating, and the ability to offer reliable payment services to businesses and consumers.
| Attribute | Banks | Fintechs & PSPs | Merchants & enterprises |
| Main use cases | Own stablecoin issuance, tokenized deposits, client custody | Settlement, payouts, wallets, on/off-ramps | Acceptance, supplier payments, treasury |
| Preferred instrument | Bank-issued stablecoin, tokenized deposits, wholesale CBDC pilots | USDC, USDT, PYUSD | Via PSP; USDC most common |
| Adoption stage (2026) | Moving from pilot to issuance | Live, scaling | Early |
| Key barrier | Deposit-flight concerns | Licensing fragmentation across markets | Low consumer demand; accounting and tax treatment |
| Named examples | 21-bank USD stablecoin consortium (Sep 2026); Qivalis euro stablecoin (12 EU banks) | Circle CPN Managed Payments with Thunes, Worldline, Veem (Apr 2026); MoneyGram–NALA (Apr 2026) | Visa USDC settlement for US banks (Dec 2025); Kyriba–Circle treasury integration (Apr 2026) |
Source: Polaris Market Research Analysis
By Technology
The market, based on technology, is segmented into blockchain, consensus, and interoperability & cross-chain. The blockchain segment held the largest market share of 46.8% in 2025. Blockchain technology plays a key role in digital currency ecosystems. The technology underpins issuance, settlement, and transaction transparency for stablecoins and CBDCs. Regulatory acceptance, rising institutional adoption, and integration of CBDCs into national payment systems, driving the demand for blockchain-based infrastructure. The technology provides enhanced transparency, immutability, and resilience against fraud. Due to these benefits, central banks and financial institutions are increasingly adopting blockchain-based solutions.
Interoperability and cross-chain segment is projected to record the highest CAGR of 38.1% during the forecast period. The growth is supported by the rising demand for seamless cross-border payments, multi-chain utility, and liquidity integration. Expanding multi-blockchain stablecoin ecosystems also propel the segment growth. Initiatives such as BIS’s mBridge project, along with the need to reduce reliance on legacy systems like SWIFT, also boost expansion. Interoperability ensures that CBDCs and stablecoins can move fluidly across jurisdictions and platforms. It will support treasury management, trade finance, and DeFi integration. This segment growth reflects its role in shaping the next generation of global settlement infrastructure.
Stablecoins & CBDCs Market Regional Insights
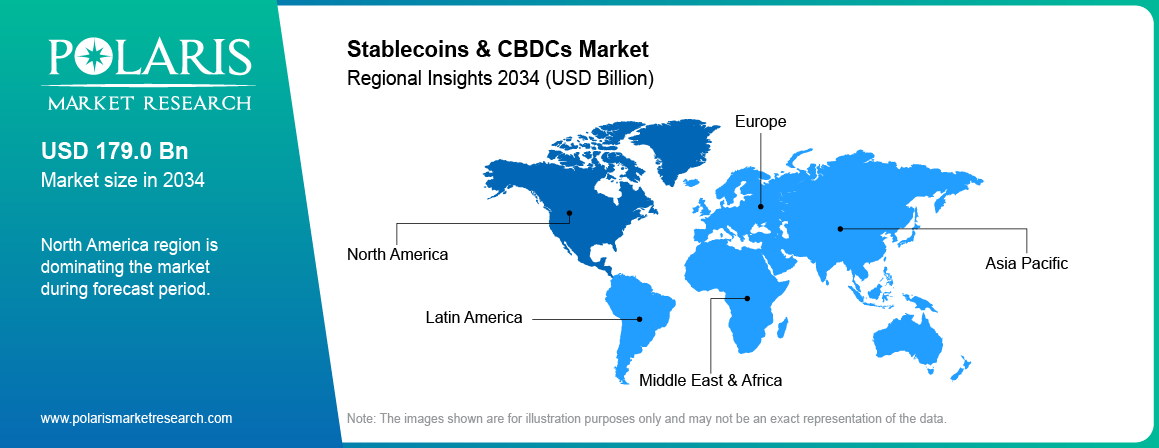
Regional demand relies on the acceptance of digital payments, regulation, banking system, international business transactions, and initiatives from central banks. North America used to be the leading region in the market previously, whereas Asia Pacific was considered to be the fastest-growing region.
North America Stablecoins & CBDCs Market Trends
North America held an estimated 38.6% share of the stablecoins & CBDCs market in 2025. The presence of strong financial infrastructure, institutional participation, and digital payment adoption drives demand in the region. It outlines clearer requirements for eligible issuers and reserve management. Banks are exploring the provision of stablecoin issuance, custody, and settlement services. In June 2026, Open Standard announced Open USD (OUSD), a business-oriented stablecoin that aims to reduce minting and redemption costs and distribute reserve earnings to participating partners. Further opportunities are arising from the demand for stablecoin infrastructure providers, digital asset custody and stablecoin compliance solutions. Such factors are expected to continue to sustain North America’s market position through 2034 (Source: Open Standard). The U.S. stablecoins & CBDCs market size was 82.4% in 2025. The GENIUS Act stablecoin would create a federal framework for payment stablecoins in the U.S.
Europe Stablecoins & CBDCs Market Trends
Europe accounted for the 27.4% share of the stablecoins & CBDCs industry in 2025. MiCA will apply rules to issuers of stablecoins and crypto-asset service providers across the European Union countries. BNY announced in October 2026 the expansion of its digital asset custody platform to selected EU institutions under the MiCA framework. This will offer custody, administration and transfer services for assets such as BTC, ETH, SOL and USDC. These requirements drive the need for licensing, reserve reporting, redemption controls and compliance systems. Financial institutions are experimenting with stablecoin payments, tokenized deposits and digital currency settlement. The digital euro project also is creating opportunities for vendors of payment technology and CBDC technology. Germany, France, and the UK offer opportunities in the areas of financial services, digital payments, and adoption of institutional technology. Demand for stablecoin-issuing platforms, custody services and compliance tools could rise through 2034. The rate of regional growth will be driven by regulation implementation, enterprise adoption, and costs of integration (Source: BNY).
Asia Pacific Stablecoins & CBDCs Market Trends
Asia Pacific is projected to record a CAGR of 35.8% during the forecast period. The region has high digital payment adoption, strong fintech development, and government-led digital currency initiatives. China’s e-CNY program and India’s e-rupee pilots are extending research into sovereign digital money. Japan, Singapore and other markets in the region are also looking at digital currency infrastructure and payment innovation. These initiatives will create demand for CBDC technology vendors, digital wallets, and secure settlement systems. In September 2026, dtcpay raised investments from SBI Group to take its Series A funding to USD 25 million to expand its stablecoin payment business (Source: dtcpay).
There will be advantages for stablecoins due to the increasing number of cross-border transactions and the e-commerce market in the region. Firms and payment service providers are testing out digital currencies to allow for faster payment and more access to settlements. The regulatory environment of Singapore is also favorable for stablecoins services. Increased demand for issuing stablecoin, storing, and compliance infrastructure will facilitate growth in the region. Local regulations, liquidity, interoperability, and institutional adoption will determine market growth until 2034.
Latin America Stablecoins & CBDCs Market
Latin America accounted for 8.2% of the revenue share in 2025. There are opportunities across the region for cross-border payments, remittances, and digital financial services in demand. Organizations and payments service providers are considering stablecoins for cross-border transactions and treasury payments. Such services could reduce processing delays in chosen corridors, depending on foreign exchange costs and local regulations. Brazil, Mexico, and Argentina are markets of relevance for digital currency services. Banks will improve their digital transaction facilities, which may boost the demand for digital wallet, stablecoin settlement, and payments infrastructures. Growth until 2034 will be driven by the regulatory environment, bank access and liquidity, and ease of currency conversions.
Middle East & Africa Stablecoins & CBDCs Market
The Middle East & Africa held an estimated 6.1% share of the market in 2025. Demand for digital currency infrastructure is being created by digital payment adoption, international trade, and remittance activity. The UAE’s Payment Token Services Regulation provides a framework for regulated payment token activity. Its Digital Dirham program creates opportunities for CBDC infrastructure. Stablecoin-backed transfers could also have potential use cases for African remittance corridors. Payment providers need secure wallets, stablecoin compliance systems, and reliable conversion services to serve these markets. Local licensing, financial infrastructure, customer access and institutional participation will drive regional growth through 2034.
Regulatory and CBDC Snapshot by Region
| Jurisdiction | Stablecoin framework | CBDC position |
| United States | GENIUS Act signed 18 Jul 2025; final rules due Jul 2026; OCC prudential rules pending ahead of an effective date no later than 18 Jan 2027 | Retail CBDC ruled out by January 2025 executive order |
| European Union | MiCA e-money token rules in force since Jun 2024; CASP transition ended 1 Jul 2026 | Digital euro: 12-month pilot from H2 2027; first issuance targeted for 2029, subject to legislation |
| China | Private stablecoins restricted on the mainland | e-CNY pilot expanding; cross-border e-CNY service joined by 26 institutions (Jun 2026) |
| Hong Kong | Stablecoins Ordinance in force since 1 Aug 2025 (HKMA licensing) | e-HKD focused on wholesale and tokenized-deposit trials |
| Singapore | MAS single-currency stablecoin framework (2023) | Wholesale CBDC and tokenization trials |
| India | No dedicated stablecoin framework | e₹ retail and wholesale pilots; programmable e₹ used in Gujarat public distribution system |
| UAE | CBUAE Payment Token Services Regulation (2024) | Digital Dirham program |
Source: Polaris Market Research Analysis
Stablecoins & CBDCs Market Competitive Landscape
The stablecoins & CBDCs market includes private issuers, custody providers, payment networks, compliance vendors, and CBDC technology specialists. Circle, Tether, Paxos, and PayPal focus on stablecoin issuance, while Anchorage Digital, BitGo, and Fireblocks provide custody and digital asset infrastructure. Visa and Mastercard integrate digital currencies with payment systems; Ripple and Stellar provide digital assets and payment solutions. Digital currency technology providers create the ledger systems, wallets, offline payments, and transaction systems for central banks. Competition depends on regulatory access, platform security, transaction capacity, and institutional relationships. Stablecoin infrastructure providers and CBDC technology vendors are taking strategic initiatives, such as partnerships, mergers, and acquisitions, to stay ahead in the competitive market.
Vendor Positioning Matrix
●● = core strength ● = present – = limited or none
| Company | Role | Issuance | Custody | Payments | Compliance | Focus |
| Circle | Issuer (USDC, EURC) + payments network | ●● | ● | ●● | ● | Stablecoin |
| Tether | Issuer (USDT, USAT) | ●● | – | ● | – | Stablecoin |
| Paxos | Regulated issuer, issuance-as-a-service | ●● | ●● | ● | ● | Stablecoin |
| PayPal | Issuer (PYUSD) + wallet | ●● | ● | ●● | ● | Stablecoin |
| Visa / Mastercard | Card-network settlement | – | – | ●● | ● | Stablecoin |
| Ripple | Issuer (RLUSD) + cross-border rails + custody | ●● | ●● | ●● | ● | Both |
| Fireblocks | Tokenization and MPC custody platform | ● | ●● | ● | ● | Both |
| Anchorage Digital / BitGo | Qualified custodians | ● | ●● | – | ● | Stablecoin |
| J.P. Morgan (Kinexys) | Tokenized deposits | ●● | ● | ●● | ● | Tokenized deposits |
| R3 / Stellar / Hedera | DLT platforms for issuers and central banks | ● | – | ● | – | Both |
| EMTECH, eCurrency, Soramitsu | CBDC infrastructure | ●● | ● | ● | ● | CBDC |
| Giesecke+Devrient / IDEMIA | CBDC wallets, secure hardware, offline payments | ● | ●● | ● | – | CBDC |
| Accenture / Consensys | Advisory and integration for central banks | ● | – | ● | ● | CBDC |
Source: Polaris Market Research Analysis
List of Major Stablecoins and CBDCs Companies
- Accenture
- Anchorage Digital
- BitGo
- Circle Internet Group
- Consensys
- eCurrency
- EMTECH
- Fireblocks
- Giesecke+Devrient
- Hedera
- IDEMIA
- J.P. Morgan Kinexys
- Mastercard
- Paxos
- PayPal
- R3
- Ripple
- Soramitsu
- Stellar Development Foundation
- Tether
- Visa
Recent Developments
- October 2026: Circle and Tereina announced a partnership to integrate USDC and EURC into enterprise payment workflows, starting with the SAP Cloud ERP ecosystem to support stablecoin payments and treasury operations. (Source: Circle)
- September 2026: Circle and Volante Technologies announced a collaboration to integrate USDC workflows into Volante’s payments platform. It will enable financial institutions to manage stablecoin minting, redemption, wallet registration, funding, and wallet-to-wallet payments. (Source: in.investing.com)
- September 2026: The Monetary Authority of Singapore (MAS) proposed legislative amendments to implement its single-currency stablecoin framework, including issuer eligibility, safeguards and cross-border issuance arrangements. (Source: MAS)
- July 2026: Visa launched the Visa Stablecoin Platform (VSP) in order to facilitate the management of stablecoin entry, minting, redemption, custody and burning in one place for financial institutions and payment networks. (Source: Visa)
- December 2025: Visa launches USDC settlement for U.S. issuer and acquirer clients, naming Cross River Bank and Lead Bank as the first members. The service allows for the settlement of eligible Visa payments in USDC on Solana blockchain. (Source: learn.backpack.exchange)
Research Methodology
The stablecoins and CBDCs market study combines secondary research, primary validation, market sizing, forecasting, and data cross-checks to develop estimates for the 2025 base year and 2026–2034 forecast period.
Secondary Research: The study reviews company disclosures, annual reports, product announcements, regulatory releases, central bank publications, technical documentation, and industry reports. It covers stablecoin issuance, digital asset custody, payment networks, reserve attestation, CBDC infrastructure, and tokenized deposits. Sources include issuers, payment networks, technology vendors, financial institutions, central banks, and regulators.
Primary Research: The research involves interviews with stablecoin issuers, banks, fintechs, payment service providers, custody firms, compliance vendors, CBDC technology vendors, and industry experts. Discussion topics include adoption, revenue models, licensing, implementation costs, buyer preferences, liquidity, settlement, and compliance requirements.
Market Sizing and Forecasting: Bottom-up and top-down approaches are used to estimate revenue for components, end users, types, technologies, applications, and regions. Issuer revenue, custody fees, payment charges, compliance revenue, technology licensing are evaluated. Validated estimates for 2025 are used as the baseline for the forecast for 2026–2034.
Data Validation: Estimates with company disclosures, regulatory material, product portfolios, customer adoption, and validated developments in the industry have been cross-checked. Segment and regional totals are reconciled and assumptions are documented. Impact assessment of regulatory changes, institutional adoption, technology costs, and implementation periods is done.
Stablecoins & CBDCs Market Segmentation
By Component Outlook (Revenue, USD Billion, 2021–2034)
- Issuance
- Custody
- Payments & Settlement
- Compliance
By End User Outlook (Revenue, USD Billion, 2021–2034)
- Banks
- Fintechs & PSPs
- Merchants
By Type Outlook (Revenue, USD Billion, 2021–2034)
- Stablecoins
- CBDCs
By Application Outlook (Revenue, USD Billion, 2021–2034)
- Payments & Settlement
- Remittances
- DeFi
- Forex
- Others
By Technology Outlook (Revenue, USD Billion, 2021–2034)
- Blockchain
- Consensus
- Interoperability & Cross-Chain
By Regional Outlook (Revenue, USD Billion, 2021-2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Stablecoins & CBDCs Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 32.24 Billion |
| Market Size in 2026 | USD 42.67 Billion |
| Revenue Forecast by 2034 | USD 409.57 Billion |
| CAGR | 32.7% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Stablecoins & CBDCs Market FAQ's
Stablecoins are privately issued and are supported by reserves. A CBDC is a type of digital currency that is issued by a central bank. Tokenized deposits represent commercial bank liabilities.
The stablecoins & CBDCs market size was valued at USD 32.24 billion in 2025 and is projected to reach USD 409.57 billion by 2034.
The market is projected to register a CAGR of 32.7% from 2026 to 2034.
Issuance led the market share with 38.6% in 2025. Its dominance is driven by the demand for platforms to issue stablecoins, mint tokens, and manage reserves.
The GENIUS Act sets forth rules for U.S. payment stablecoins, including rules for issuers, reserves, and oversight. The EU’s MiCA regulates relevant stablecoin activities.
Banks are looking at bank-issued stablecoins, tokenized deposits, and wholesale CBDCs for digital payments and institutional settlement, subject to regulatory requirements.
North America dominated the market share with 38.6% in 2025. This leading position is fueled by the presence of well-established fintech companies and digital asset infrastructure.
The e-CNY and e-rupee are being tested in China and India. The Bahamas introduced the Sand Dollar. Nigeria introduced eNaira, and the digital euro is in development.
Circle, Tether, Paxos, PayPal, Ripple, Visa, Mastercard, Fireblocks, BitGo, Anchorage Digital, EMTECH, and IDEMIA are a few key players.
Tokenized deposits are commercial bank deposits in digital form. Stablecoins are privately issued electronic assets backed by reserves. Issuer liability, regulatory and use cases are different.
Download Sample Report of Stablecoins & CBDCs Market
Please fill out the form to request a customized copy of the research report.