Wind Turbine Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Wind Turbine Market Summary
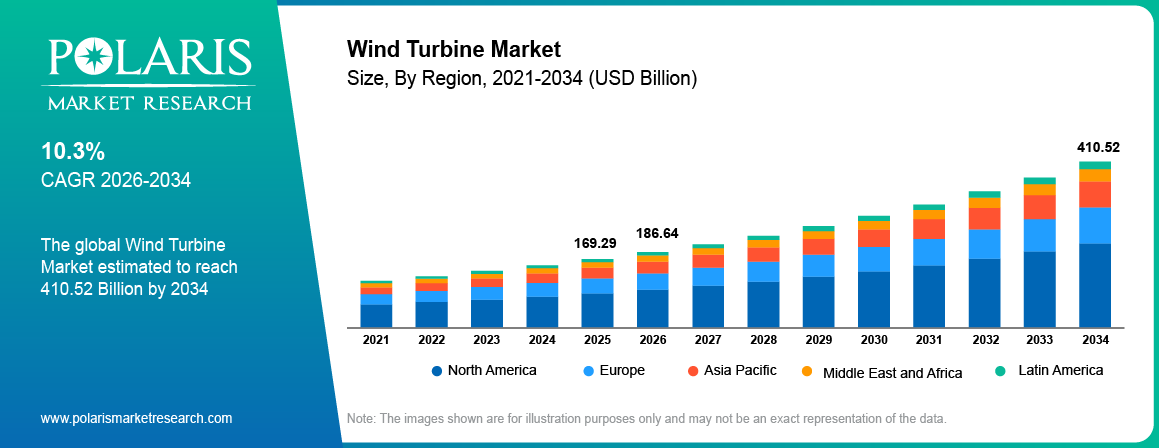
The global wind turbine market size was valued at USD 169.29 billion in 2025 and is projected to register a CAGR of 10.3% from 2026 to 2034. Key factors driving demand include rapid expansion of offshore wind development, rising global energy demand, and increasing advancements in wind turbine composites.
Market Statistics
Key Takeaways
- The Asia Pacific market dominated the revenue share with 48.60% in 2025, primarily due to the presence of major manufacturing hubs, rising electricity demand, and strong government initiatives promoting the adoption of renewable energy.
- North America is expected to register the highest CAGR of 9.45% during the forecast period due to robust policy frameworks supporting renewable energy, rising demand for clean power, and substantial investments in wind energy infrastructure.
- The U.S. held the market share of 64.36% in North America landscape in 2025 owing to its well-developed infrastructure, supportive regulatory environment, and strong federal and state-level renewable energy targets.
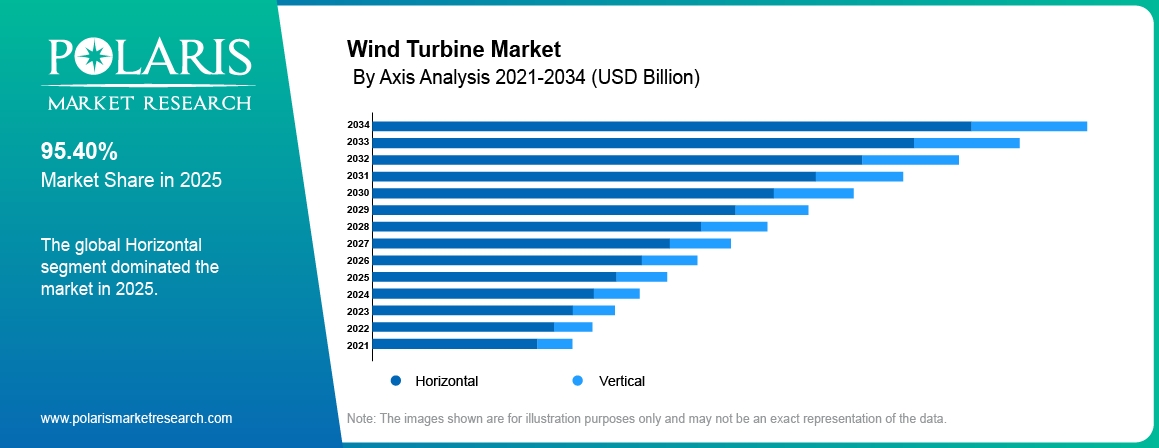
- The horizontal segment accounted for 95.40% revenue share in 2025 due to its superior efficiency, scalability, and widespread adoption across utility-scale wind farms.
- The offshore segment is expected to witness 16.20% growth during the forecast period, driven by increasing investments in large-scale renewable energy projects and the availability of stronger, more consistent wind resources at sea.
- The rotator blade segment dominated the market in 2025, with a market share of 30.20%. This is due to its crucial role in capturing energy and enhancing conversion efficiency within turbine systems.
- The utility segment dominated the market with an 82.10% share in 2025, driven by the need for large-scale energy production and the requirement for grid integration.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations
What is the Wind Turbine Market?
A wind turbine is a rotating machine that has blades acted upon by wind, and the kinetic energy of the moving air is converted into mechanical energy of the rotation of the blades. The wind turbine market focuses on the development, production, supply chain, and commercialization of wind turbines. The surge in offshore wind development provides many opportunities for market growth. Offshore wind energy farms consistently have higher and more predictable wind speeds than their onshore counterparts, allowing them to produce more electricity and run at higher capacity factors.
International Energy Agency's Electricity Mid-Year Update 2026 forecasted global renewable electricity generation growth of more than 8% in 2026, with the electricity source solar PV expected to pass wind power in the year to become the world’s second-largest renewable source of electricity generation, behind only hydroelectricity, according to its Electricity Mid-Year Update 2026. It also projects that global wind electricity generation will continue to grow at an average rate of ~ 10%/year until 2030 (Source: iea.org). This is yet another indication of how wind projects are becoming more economically viable due to improving technologies in turbine design, bigger rotor diameters, offshore foundation structures, digital monitoring, and grid connectivity. As countries work to expand their energy portfolios and decrease reliance on fossil fuels, strategic placement of offshore and utility-scale wind farms development will become even more critical to meet goals for renewable energy and decarbonization.
Wind Turbine Supply Chain
The wind turbine supply chain includes providers of raw materials, components, and logistics, as well as wind turbine OEMs, project developers, installation contractors, and providers of operation and maintenance services. The upstream phase of the supply chain includes materials such as steel, copper, aluminum, fiberglass, carbon fiber, rare earth elements, resins, and others used to manufacture blades, towers, generators, gearboxes, and nacelles.
Materials suppliers are component manufacturers that transform these into rotor blades, bearings, drivetrains, generators, power electronics, control systems, and structural elements. Turbine OEMs add these sub-systems into complete systems and manage quality testing and certification. The midstream phase focuses on the movement of large components in the logistics chains of a series of different specialized road vehicles, vessels, cranes, ports, and installation equipment to onshore and offshore project sites.
Project developers, engineering companies, and utilities then manage foundations, electrical infrastructure, grid connections, and turbine commissioning. Downstream operations also consider electricity production, asset management, maintenance, component replacement, monitoring via digital condition, and repowering. Increasing local content mandates, offshore wind growth, recycling activities, and supply-chain diversification are impacting procurement policies and manufacturing investment decisions in the wind turbine business.
How Do Wind Turbines Generate Electricity?
Wind Captures the Blades
Wind passes over the turbine blades, and this suction effect draws them toward the wind, causing the rotor to turn. Shape, length, and pitch angle of a blade influence how efficiently it captures wind energy.
Rotor Converts Wind into Mechanical Energy
It consists of rotating blades attached to the central part called the rotor. As it rotates, the rotor transforms the wind's kinetic energy into rotational mechanical energy.
Drivetrain Transfers Rotational Power
The main shaft of the rotor transfers energy to the drivetrain. In geared wind turbines, a gearbox is used to increase rotational speed, whereas direct-drive wind turbines transfer energy directly to the generator.
Generator Produces Electricity
Due to the principle of electromagnetic induction, the generator produces electrical energy when mechanical rotation is applied. Contemporary turbines utilize sophisticated generator technologies to enhance performance in a wide range of wind conditions.
Power Electronics Regulate Output
Converters and control systems regulate voltage and frequency so the output power complies with grid requirements. A transformer is then used to step the voltage up for transmission efficiency.
Electricity Is Delivered to the Grid
The processed electric power is transmitted via underground or undersea cables to substations and transmission systems. Sensors, pitch control, yaw mechanics, and digital monitoring systems constantly fine-tune the turbine performance, safety, and maintenance.
The global push toward decarbonization and sustainability goals supports the growth opportunities. Wind turbines play a vital role in reducing dependence on fossil fuels by offering a clean, renewable energy, and scalable energy source. Governments and private stakeholders are aligning their energy policies and investments with climate commitments, which has significantly boosted demand for wind energy infrastructure. This transition is further reinforced by increasing regulatory support, carbon pricing mechanisms, and growing corporate commitments to net-zero emissions, collectively driving the adoption as a sustainable energy solution.
Advanced Materials in Wind Turbines
| Advanced Material/Innovation | Application in Wind Turbines | Key Benefits |
| Fiberglass Composite Materials | Used in turbine blades | Improves durability, flexibility, and resistance to fatigue |
| Carbon Fiber Reinforced Polymers (CFRP) | Used in large blade sections and structural components | Provides high strength-to-weight ratio and enables longer blades |
| Lightweight Structural Materials | Used in towers, turbine gearbox generator nacelle, and internal components | Reduces overall turbine weight, improves efficiency, and lowers mechanical stress |
| Advanced Protective Coatings | Applied on blades and external surfaces | Protects against erosion, moisture, and harsh environmental conditions |
| Smart Materials & Embedded Sensors | Integrated into turbine components | Supports condition monitoring, predictive maintenance, and improved reliability |
| Recyclable Thermoplastic Composites | Used in next-generation turbine blades and structural components | Enables easier material separation, remelting, and reuse compared with conventional thermoset composites, supporting closed-loop blade manufacturing. |
| Recyclable Epoxy Resin Systems | Applied in blade laminates and composite structures | Designed to improve end-of-life recovery of fibers and resin, reducing landfill dependence and enabling higher-value recycling of retired blades. |
| Recovered Carbon Fiber | Reused in secondary composite components, reinforcement materials, and non-critical structures | Reduces dependence on virgin carbon fiber and lowers embodied energy and material-related emissions across the turbine lifecycle. |
| Recycled Fiberglass | Used in cement co-processing, construction materials, fillers, and selected composite applications | Provides an alternative disposal route for decommissioned blades while recovering material value and reducing waste volumes. |
| Bio-Based Resins and Polymers | Used experimentally in blade composites, coatings, and structural materials | Reduces reliance on petroleum-based feedstocks and lowers the environmental footprint of composite manufacturing. |
Source: Polaris Market Research Analysis
Technological Advancements and AI in Wind Turbine Operation
Technological innovations and AI are redefining the wind energy market size and renewable energy market projections. On the off‐shore wind energy market level, IoT sensors and SCADA system monitor wind turbine MW, equipment performance, and wind farm progress. The turbine gearbox generator nacelle can be treated as an integrated asset chain for fault detection. AI predictive maintenance wind turbine examines vibration, temperature, sound, and output information with fault accuracy of 92% and downtime reduction of 35%. Digital twins’ model operating environments, forecast and optimize maintenance schedules, and lower wind energy LCOE. These features fortify green Hydrogen wind energy cultivation by enabling better electricity readiness. Together, intelligent operations deliver wind energy decarbonization, net zero wind energy ambitions, and improved profits.
Market Dynamics
Driver: Rising Energy Demand
Rising global energy demand is driving market expansion as economies expand and urbanization accelerates, increasing electricity consumption across residential, commercial, and industrial sectors. According to a March 2025 IEA report, global energy demand increased by 2.2% in 2024, a substantial rise compared to the historical annual growth rate (Source: iea.org). Governments and energy providers are turning to wind power as a reliable and renewable alternative to conventional fossil fuels to meet this surge in demand in a sustainable manner. Wind turbines provide a scalable, low-emission solution that supports both base-load and peak energy needs. The deployment of these turbines is gaining momentum as part of integrated power generation strategies, as energy security and long-term supply stability become critical concerns.
Driver: Increasing Advancements in Wind Turbine Composites
Increasing advancements in wind turbine composites are enhancing the performance and efficiency of wind energy systems, driving further wind turbine market growth. Innovations in composite materials for turbine blades, such as carbon fiber and advanced resin systems, have significantly improved the strength-to-weight ratio. It enables longer, more durable blades without compromising structural integrity. For instance, in February 2025, ACCIONA's Turbine Made initiative began repurposing decommissioned wind turbine blade materials in Australia, starting with a blade from the Waubra Wind Farm for sustainable manufacturing purposes. These technological improvements contribute to higher energy output and lower maintenance costs over a turbine’s lifecycle. The adoption of advanced composites is becoming a crucial enabler in expanding the feasibility and competitiveness of wind power as manufacturers prioritize lightweight and high-performance materials to optimize turbine design and efficiency.
| Driver | Estimated CAGR Impact | Potential CAGR With Driver Effect |
| Rising Energy Demand | +0.85 percentage points | 11.15% |
| Increasing Advancements in Wind Turbine Composites | +0.55 percentage points | 10.85% |
Source: Polaris Market Research Analysis
Opportunity: Declining Wind LCOE and Expansion of Corporate PPAs
Wind turbines manufacturers and projects developers are set to benefit significantly from the increasing cost competitiveness of wind power. The global weighted average levelized cost of electricity for newly commissioned onshore wind reached around USD 33 per MWh in 2025, confirming wind energy as one of the most competitive sources of new power. Over 90% of utility-scale renewable projects commissioned during the year, also produced power with lower expenses than the cheapest new fossil-fuel option in their individual markets (Source: irena.org). Falling production costs enhance the economics of projects and make wind farms more attractive to utilities and private electricity buyers. Meanwhile, corporate power purchase agreements (PPAs) are increasingly delivering long-term revenue certainty to developers and providing companies a pathway to meet their renewable energy and decarbonization commitments. The well-balanced LCOE competitiveness, secured long-term procurement contracts, an increasing corporate electricity demand, as well as a strong demand for clean power from data centers and industrial consumers, are expected to drive new turbine installations and repowering activities.
Opportunity: Green Hydrogen and Floating Offshore Wind Development
Sustaining high growth in the long term will depend on further development of floating offshore wind technology and the integration of wind energy with green hydrogen production, which represent significant potential for the wind turbine market. Green hydrogen projects necessitate large meanders of renewable electricity, which could be wind farms dedicated to electrolyzers that supply the chemical, refining, steel, shipping and other sectors where decarbonization is hard to achieve. While renewable hydrogen is still more costly than traditional fossil hydrogen, its commercial outlook will be enhanced by further build out of renewable electricity and electrolyzer capacity. (Source: iea.org) Floating wind is also enabling offshore development in areas where traditional fixed-bottom foundations are technically challenging or cost prohibitive. IRENA found around 244 GW of floating wind projects in the global development pipeline, showing strong momentum. Floating foundations allow access to deeper waters with strong, consistent wind, opening up potential new markets in Europe, the Asia Pacific and North America. Changes to bigger turbines, more advanced floating platforms, specialized ports and offshore H2 production could thus drive major additional demand for wind turbine equipment.
Restraint: High Wind Turbine Installation Cost, Supply Chain Constraints, Permitting and Grid Bottlenecks
High project costs and infrastructure limitations continue to pose significant barriers to expansion of the wind turbine market, especially for offshore wind projects. Offshore wind involves considerable upfront costs for the turbines, foundations, subsea cables, specialized installation vessels and ports, as well as for the transmission infrastructure and long-term maintenance. Increased financing along with supply-chain costs have already dampened the economics of projects, leading to postponed projects, cancelled developments, and auctions with insufficient supply in a number of markets. Thereby the IEA revised down its global growth in offshore wind capacity forecast for 2025–2030 by 27 % from the previous forecast (Source: iea.org).
Grid availability is yet another major problem. The IEA indicated that nearly 1,650 GW of mature solar and wind projects have been stalled due to lack of grid connections in 2024, highlighting the extent to which transmission is a bottleneck for renewable developers. Prolonged permitting processes, transformer and high-voltage cable shortages, specialized vessel availability, port constraints, volatile raw-material prices, and rising interest rates can contribute to extended project schedules and increased capital costs. These challenges are greatest for nascent floating wind projects and can limit turbine orders when developers have too little visibility into project completion and anticipated returns on investment.
| Restraint | Key Market Impact | Estimated CAGR Impact |
| High Wind Turbine Installation Cost | High initial costs for turbines, foundations, vessels, transmission infrastructure, financing and maintenance can hold back project investment, particularly in offshore wind. | -0.60 % points |
| Supply Chain Constraints | The scarcity and price fluctuations of steel, rare earth materials, blades, gearboxes, transformers, cables, specific vessels and other essential parts prolong delivery times and enhance the cost of the project. | -0.45 % points |
| Permitting and Grid Bottlenecks | Long approval procedures, limited transmission capability, interconnection queues, and deferred grid upgrades may delay the completion of projects and constrain additions of wind capacity. | -0.75 % points |
Source: Polaris Market Research Analysis
Segmental Insights
Axis Analysis
Based on axis, the segmentation includes vertical and horizontal.
The horizontal segment accounted for a larger revenue share of 95.40% in 2025 due to its superior efficiency, scalability, and widespread adoption across utility-scale wind farms. Horizontal axis wind turbine (HAWT) are favored due to their good aerodynamic efficiency, higher hub height for accessing stronger winds, and ability to be designed for utility scale power generation. Additionally, their well-established design architecture and far-reaching global manufacturing network make them ideal candidates for scale adoption. They typically have three blades, which are positioned perpendicular to the wind direction and attached to a rotor, that transfers the rotational energy to a generator through a drivetrain. Energy conversion performance is being enhanced through ongoing advances in blade materials, pitch-control systems, gearbox efficiency and direct-drive technologies. Horizontal-axis designs can also be better suited to high-capacity turbines, such as offshore installations with multi-megawatt tonnes.
Installation Analysis
In terms of installation, the segmentation includes offshore (Fixed-bottom, Floating) and onshore.
The offshore segment is expected to witness significant growth of CAGR 16.20% during the forecast period, driven by favorable renewable energy market trends and the availability of stronger, more consistent wind resources at sea. Offshore installations also have the potential to accommodate much larger turbines than many onshore sites, enabling developers to produce more power from fewer turbines.
Governments in Europe, Asia Pacific, and North America are promoting offshore wind energy market through auctions, long-term procurement programs, renewable-energy targets, and support for transmission infrastructure. Advances in fixed-bottom foundations, floating platforms, subsea cables, and specialized installation vessels are also increasing water depth-driven technical feasibility. Simultaneously, increasing rotor diameters and turbine ratings are leading to higher capacity factors and better project economics. While offshore projects typically require greater capital investment and more complex maintenance than onshore projects, better wind conditions and economies of scale give them the potential to be more profitable in the long term. The addressable market is also expected to be further extended by floating offshore wind.
The floating sector held around 3.80% of the offshore wind turbine market in 2025. Its penetration currently is limited by its higher cost of installation and because of its early stages of commercialization. However, the rate of its deployment is gaining momentum as floating platforms make it possible to develop wind projects in much deeper waters where even stronger wind resources are found and where fixed-bottom solutions face severe limitations.
Comparison Matrix: Onshore vs Offshore Wind Turbines
| Feature | Onshore Wind Turbines | Offshore Wind Turbines |
| Location | Installed on land | Installed in seas or oceans |
| Cost Structure | Lower capital and operating costs | Higher investment due to marine infrastructure |
| Wind Availability | Variable wind conditions | Stronger and more stable wind resources |
| Maintenance | Easier access and lower complexity | Difficult access and higher maintenance challenges |
| Power Generation | Lower energy yield per turbine | Higher output due to larger turbines and better wind speeds |
| Project Scale | Limited by land availability | Suitable for large-scale wind farms |
| Development Time | Faster installation and commissioning | Longer planning, construction, and approval cycles |
Source: Polaris Market Research Analysis
Components Analysis
The segmentation based on components includes, rotator blade, generator, gearbox, and nacelle. The rotator blade segment dominated the market with 30.20% share in 2025 due to its crucial role in capturing energy and enhancing conversion efficiency within these turbine systems. Rotor blades are essential in the wind energy conversion; they are used to intercept the wind energy and transfer it into rotating mechanical energy. The length, weight, aerodynamics and material of the blade affect the efficiency of the turbine and the amount of electricity that it can produce. Increasingly, manufacturers are developing longer, lighter blades that can capture more energy from the wind at lower wind speeds by utilizing high-tech fiberglass composites, carbon-fiber reinforcements, hybrid materials, and optimized blade geometries. Rising offshore wind continues to contribute to the segment growth, with offshore wind turbines necessitating extraordinarily large blades to withstand severe marine conditions and high mechanical loads.
Other developments include modular blades, recyclable composite materials, erosion-resistant coatings and sensor-based condition monitoring, all contributing to improved durability and lifecycle performance. As the global average turbine capacities are expected to further increase, the need for advanced technology for rotor blades is anticipated to continue in both new installation and replacement market.
Application Analysis
In terms of application, the segmentation includes residential, utility, industrial, and commercial. The utility segment dominated the market in 2025 with 82.10% share. The leading position is driven by the need for large-scale energy production and the requirement for grid integration of wind power. Large-scale wind projects usually involve many high-capacity turbines that are linked to centralized transmission systems and serve to provide power to regional or national grids. Expanding renewable portfolio standards and decarbonization goals, along with competitive power auctions and long-term power purchase contracts, are propelling continued investment in utility-scale wind capacity. The reduced cost of wind-produced electricity has also increased its competitiveness versus traditional fossil-fuel generation in numerous markets.
Utilities are also using more and larger turbines with greater hub heights and rotor diameters, to harvest more energy and thus fewer turbines per project are needed. Offshore wind development is also bolstering demand from the utility sector by unlocking multi-gigawatt projects that provide electricity to major population hubs. Integration with battery storage, green hydrogen production, and sophisticated grid-management systems are also increasing the flexibility and value of utility-scale wind generation.
Capacity Analysis
In terms of capacity, the segmentation includes small, medium, and large.
The large segment held the largest market share of 48.00% in 2025, driven largely by utilities and project developers that need more electricity with fewer turbines on each wind farm. Higher power output, improved capacity factors, and better utilization of land or offshore lease areas are enabled by the larger turbines.
Among them, offshore projects account for the largest proportion, with international new installed capacity increasingly consisting of multi-megawatt turbines optimized for stronger and more consistent winds. Advances in lightweight blade materials, tower structures, drivetrain systems and digital controls are enabling producers to increase turbine capacity without a corresponding increase in operating costs. Bigger turbines also improve project economics by reducing foundation, cabling, installation, and maintenance needs per megawatt of energy. With developers focusing on higher energy yields and more efficient layouts, large-capacity turbines are anticipated to deliver the best long-term growth for both onshore and offshore applications.
Connectivity Analysis
In terms of capacity, the segmentation includes grid-connected and stand-alone.
The grid-connected segment dominated the wind turbine market share of 86.70% in 2025, because of the extensive application of wind power for utility-scale and commercial electricity generation. Grid-connected wind turbines also make up essential infrastructure for renewable energy, generating electricity that is fed directly into local, regional, or national transmission and distribution grids.
Ambitious renewable-energy targets, grid modernization initiatives, and transmission capacity investments are fueling the development of large wind farms served by centralized power systems. Today's wind turbines use advanced power electronics, converters, transformers and controls to match their output to grid frequency and voltage requirements. Digital prediction and energy management systems are also enabling better integration of intermittent wind production into power grids. On the other hand, grid-connectable and standalone wind turbines are intended for settlements, telecommunication stations, farms, islands, and industrial locations with poor or no access to grids. While the standalone segment accounts for a smaller share of revenue, it is gaining traction as hybrid wind-solar and battery-storage solutions see rising adoption. However, the continued growth of utility-scale renewable generation will keep grid-connected systems as the largest connectivity type.
Rating Analysis
The above 2 MW segment accounted for approximately 45.90% of the wind turbine market in 2025. Wind turbine producers are now designing and manufacturing more highly rated turbines that yield greater power per unit, and the overall economics of wind farms benefit from economies of scale. Turbines over 2 MW are standard for today’s onshore projects, and offshore projects are also moving to significantly higher ratings. Higher-rated turbines decrease the number of towers, foundations, electrical connections, access roads and maintenance locations needed to obtain a project capacity, thereby aiding in reducing balance-of-plant costs. Developments in blade design, permanent-magnet generators (PMG), direct-drive technology, tower design, and digital control systems are enabling turbine ratings to keep rising. Offshore wind expansion is particularly crucial because big turbines take advantage of stronger marine wind resources to generate substantially more annual energy, and demand is likely to continue escalating. Smaller ratings are still critical for distributed and off-grid solutions, but the global trend toward utility-scale renewable development will continue to favor turbines larger than 2 MW.
Market Share & Growth by Segment (2025)
| Segment Dimension | Dominant Sub-Segment (2025 Share) | Key Driver |
| By Axis | Horizontal (95.40%) | HAWTs dominate utility farms; VAWTs gaining in urban/offshore niches |
| By Installation | Onshore (91.8%) | Stronger wind, higher output, no land constraints offshore |
| By Component | Rotor Blades (30.20% | Blade size critical for energy yield; smart grid compliance drives power electronics |
| By Application | Utility-Scale (82.10%) | Large-scale grid supply dominates; C&I driven by corporate PPAs and net-zero mandates |
| By Capacity Rating | Large (48.00%) | Developers seeking fewer, higher-output machines to cut O&M costs |
| By Connectivity | Grid-Connected (86.70%) | Rural electrification and energy access driving off-grid turbines |
| By Region | Asia Pacific (48.60%) | China manufacturing + policy drive APAC; MEA driven by low-cost auctions |
Source: Polaris Market Research Analysis
Regional Analysis
North America wind turbine market is expected to witness a significant CAGR of 9.45% during the forecast period. This is due to positive policy incentives and increasing investments in renewable energy. A positive wind turbine market forecast 2034 in the region is attributed to growing onshore and offshore wind power installations. Technological advancements, combined with favorable land availability and strong interconnection systems, are accelerating project development across the region. Additionally, increased collaboration between the private and public sectors is promoting a dynamic environment for the deployment of wind energy.
U.S. Wind Turbine Market Insights
U.S. Wind Turbine Market is anticipated to grow significantly at a 10.2% CAGR during the forecast period owing to its well-developed infrastructure, supportive regulatory environment, and strong federal and state-level renewable energy targets. The country’s vast land availability and favorable wind conditions, particularly in the Midwest and coastal regions, have enabled the large-scale wind farm development. Additionally, robust investment in grid modernization and technological advancements in turbine design continue to support expansion opportunities.
Asia Pacific Wind Turbine Industry Overview
The Asia Pacific wind turbine market dominated the revenue share in 2025 with 48.60% market share. This is due to major manufacturing hubs, rising electricity demand, and strong government initiatives promoting renewable energy adoption. For example, in April 2026, the Ministry of Economy, Trade and Industry of Japan announced that renewable energy made up 23.1% of Japan’s electricity generation, and the total share of non-fossil power sources was 32.5%. In addition, Japan aims for 10 GW of offshore wind capacity by 2030 and 30-45 GW by 2040, further bolstering long-term demand for wind turbine installations (Source: meti.go.jp). Countries across the region are aggressively scaling up wind power capacity to reduce reliance on fossil fuels and meet carbon neutrality goals. The region also benefits from cost-effective labor, favorable climatic conditions, and a growing domestic supply chain, supporting the rapid deployment of both onshore and offshore wind projects.
China Wind Turbine Market Overview
China held a 35.52% revenue share of Asia Pacific market in 2025. The market in China is expanding due to aggressive government policies aimed at reducing carbon emissions and increasing the share of renewables in the national energy mix. China’s extensive manufacturing capabilities and cost-effective supply chain have made it a global hub for wind turbine production. The country's focus on both onshore and offshore project development, supported by substantial infrastructure investments, is accelerating deployment and driving growth.
Europe Wind Turbine Market Outlook
The wind turbine landscape in Europe is projected to hold a substantial share of 24.70% in 2025 due to the region’s long-standing commitment to sustainability, strict emissions regulations, and well-established wind energy infrastructure. European nations are continuously investing in offshore wind capacity and cross-border energy interconnectivity to enhance energy security and meet climate targets. The presence of major industry players, advanced research and development capabilities, and supportive policy mechanisms further position Europe as a stronghold in the future of wind energy deployment.
UK Wind Turbine Market Analysis
The UK accounted for the 6.84% share of the European market in 2025. The growth of UK sector is driven by the country’s leadership in offshore wind development and its long-term commitment to achieving net-zero emissions. The UK has leveraged its favorable coastal geography to establish high-capacity offshore projects, supported by a mature regulatory framework and a competitive auction system. Innovation in floating wind technology, combined with consistent government backing, is further boosting the sector’s expansion.
Middle East & Africa Wind Turbine Market Trends
The MEA wind turbine market is anticipated to experience robust growth, registering a CAGR of around 13.20% during the forecast period from 2026 to 2034. Growth is being driven by concerted renewable energy efforts from Egypt, Saudi Arabia, Morocco, South Africa, and other burgeoning markets seeking to diversify electricity generation and reduce reliance on fossil fuels (Source: sis.gov.eg).
Egypt held a significant revenue share of 2.75% in the MEA market in 2025. Egypt is becoming particularly important for wind investment. The government of Egypt declared an MoU in June 2026 for the country’s first wind turbine manufacturing plant along with a 2,000 MW wind farm in the Gulf of Suez boosting local manufacturing and project development skills. Part of Egypt's FY2025/26 development plan also includes a pipeline of some 6.47GW in solar and wind capacity (Source: moic.gov.eg). Smart Grid infrastructure development, green hydrogen projects and enhanced wind resources in coastal and desert regions may lead to additional turbine outside the MEA.
Latin America Wind Turbine Market Assessment
Latin America represented around 5.50% of the world wind turbine market in 2025 and will grow at a CAGR of roughly 10.70% in the forecast period 2026 to 2034. Rising regulatory changes, combined with the region’s transition toward a renewable energy and the eastward movement of regional green hydrogen incentives, could push turbine deployment beyond traditional onshore developments. Brazil continues to be the largest wind market in the region with good onshore wind resources and a mature domestic supply chain, as well as continuing renewable energy investment. A significant new opportunity is offshore and possibly floating wind, mainly along the long Brazilian coast, where higher and more stable winds might be suitable for large-scale projects. Brazil consolidated the regulatory basis for offshore wind with the promulgation of Law No. 15,097/2025 and further, by CNPE Resolution No. 1 of April 2026, which determines the guidelines for the law's implementation (Source: epe.gov.br). Also in July 2026, a national procedure on how to select offshore wind areas for subsequent awarding was issued by the Ministry of Mines and Energy. Such initiatives are fueling the market expansion across the country.
Role of Wind Power in Global Decarbonization
Wind power will play an important role in global decarbonization as it substitutes fossil fuel-based electricity generation and supports long-term net-zero targets. Governments and utilities alike are scaling wind capacity to curb power-sector emissions, boost energy security, and complement generation portfolios. Carbon pricing regimes and emissions trading schemes make wind more competitive by driving up the cost of carbon-intensive generation and making low-carbon electricity more economically attractive. With transmission expansion and storage, onshore and offshore wind projects at scale can displace coal- and gas-fired power. Wind is also increasingly combined with green hydrogen, whereby dedicated wind farms provide the renewable electricity to electrolyzes to generate low-carbon hydrogen. This unlocks further decarbonization potential in steel, chemicals, refining, shipping and other difficult-to-abate industries. Co-locating wind developments with hydrogen production facilities is also a means of enhancing renewable power utilization and reducing curtailment thus amplifying the contribution of wind energy to reducing emissions across the economy.
Regulatory Landscape & Government Incentives section
Renewable-energy standards, technical requirements, trade actions and financial subsidies are increasingly influential market shaping drivers. The Renewable Energy Directive (fifth edition) in the European Union also reinforces support for continuous wind capacity growth and for quicker permit granting, by specifying a binding renewable energy target of at least 42.5% by 2030, with a potential 45% as a target (Source: energy.ec.europa.eu). Technical aspects are developing with IEC 61400-15-1:2025 (Onshore and Offshore Wind-site Evaluation - Part 15-1: Outdoor Suitability Assessment). The government is also eliminating tariffs on these same offshore wind products beginning April 1, 2026, in the UK, which will reduce the cost of inputs and boost the competitiveness of domestic supply chains (Source: gov.uk). India is backing offshore wind via a USD 890.6 million Viability Gap Funding scheme for 1 GW of offshore wind projects (around USD 818.9 million) and for port infrastructure upgrades (about USD 71.7 million) (Source: pib.gov.in). Together, they enhance project economics, incentivize domestic manufacturing, speed up offshore and onshore deployment, and drive regulatory consistency in the wind turbine value chain globally.
Competitive Analysis
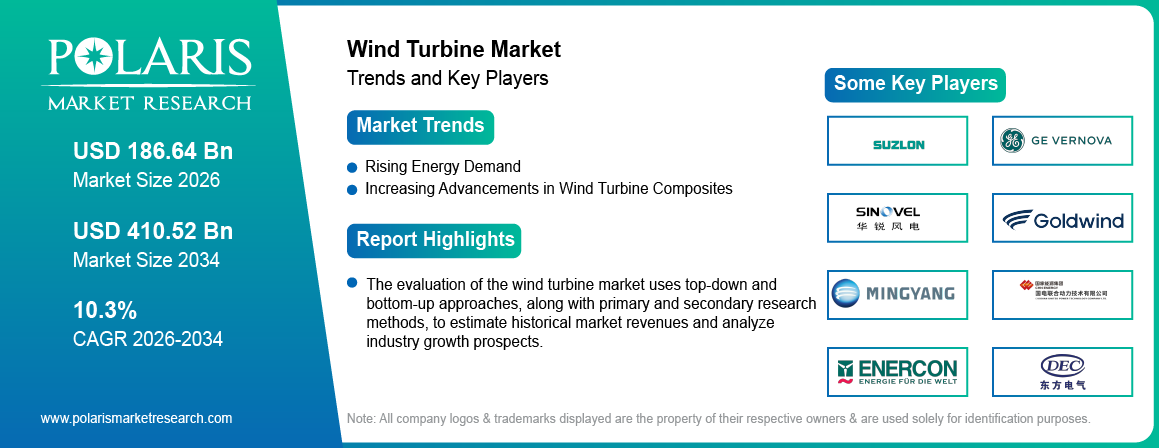
The global wind turbine industry is becoming increasingly competitive as Western OEMs compete with Chinese manufacturers across turbine capacity, pricing, offshore technology, localization, and lifecycle service capabilities. Key market participants include Vestas, Siemens Gamesa, GE Vernova, Goldwind, Mingyang Smart Energy, Nordex, ENERCON, Envision Energy, Suzlon Energy, Dongfang Electric, Sinovel Wind Group, and Guodian United Power. The competitive landscape has shifted increasingly toward Chinese OEMs, supported by their extensive domestic manufacturing base, vertically integrated supply chains, competitive pricing, and expanding international presence. Goldwind and Envision Energy have emerged as major global suppliers, while Western OEMs continue to maintain strong positions outside China, with Vestas operating across a particularly diverse international market base.
Competition increasingly centers on higher turbine ratings, large offshore platforms, low-wind optimization, localized manufacturing, digital monitoring, and long-term service agreements. GE Vernova offers onshore platforms extending into the multi-megawatt range alongside its Haliade-X offshore platform. ENERCON is expanding its higher-capacity portfolio through the E-175 EP5 platform, while Nordex continues to develop its Delta4000 series for large-scale onshore and repowering projects.
Siemens Gamesa, Mingyang, Vestas, and Dongfang Electric are advancing next-generation offshore turbine platforms. Envision Energy is integrating artificial intelligence with smart wind farm management, whereas Suzlon is strengthening its position in India through cost-efficient turbines and hybrid tower solutions. These strategies demonstrate growing competition based on technological scale, regional manufacturing, operational efficiency, and lifecycle value.
List of Major Wind Turbine Companies
- Dongfang Electric Corporation
- ENERCON Global GmbH
- Envision Energy
- GE Vernova
- Goldwind Science & Technology
- Guodian United Power Technology
- Mingyang Smart Energy Group
- Nordex SE
- Siemens Gamesa Renewable Energy
- Sinovel Wind Group
- Suzlon Energy Limited
- Vestas Wind Systems A/S
Key Players Vendor Positioning Table
| Company | HQ | Key Markets | Notable Products / Platforms | Strategic Focus (2025–2026) |
| Vestas Wind Systems A/S | Denmark | Europe, North America, Global | V236-15 MW offshore platform | Offshore expansion, blade recycling program, digital services |
| Siemens Gamesa Renewable Energy | Spain/Germany | Europe, Americas, Asia | SG 21-22 MW offshore prototype | Floating wind R&D, mega-turbine commercialization, onshore repowering |
| GE Vernova (formerly GE Renewable Energy) | USA | North America, India, Europe | 3.8 MW–154m onshore; Haliade-X offshore | India ALMM certification, Pune manufacturing (1,500 MW/yr capacity), IRA benefits |
| Goldwind Science & Technology | China | Asia Pacific, Global Export | PMDD (permanent magnet direct-drive) turbines | Gearbox-free PMD technology, international market expansion |
| Mingyang Smart Energy Group | China | China, Southeast Asia, Europe | MySE 16-260 offshore; 22 MW under dev. | Ultra-large offshore turbines (18–22 MW), floating wind, export growth |
| Nordex SE | Germany | Europe, Americas, Africa | N163/6.X; Delta4000 series | 700 MW UKA order (Jul 2026), onshore repowering, MEA market entry |
| ENERCON Global GmbH | Germany | Europe, Latin America | E-160 EP5 gearless turbines | Direct-drive technology, service optimization, Europe stronghold |
| Envision Energy | China | China, Asia Pacific, Global | EN-234/10.X, smart energy platform | Digital wind farm management, smart turbine AI integration |
| Suzlon Energy Limited | India | India, South Asia | S144-2.8 MW hybrid lattice tower | India PSP market leadership, cost-efficient hybrid tower solutions |
| Dongfang Electric Corporation | China | China, Asia Pacific | 16 MW offshore turbine (2024 install) | World-first commercial 16 MW offshore installation, floating wind R&D |
| Sinovel Wind Group | China | China | 3–5 MW onshore and offshore | Domestic China market, offshore development |
| Guodian United Power Technology | China | China | UP series 2–6 MW turbines | Utility-scale China onshore projects |
Source: Polaris Market Research Analysis
Industry Developments
- June 2026: GE Vernova Inc. signed an agreement with Powerica Limited. With this deal, GE Vernova will supply 28 of its 3.8 MW–154m onshore wind turbines for the Botad Wind Farm in Gujarat, India. (Source: gevernova.com).
- May 2026: KP Group commissioned India’s first native 4.2 MW WTG bolstering the domestic wind manufacturing base and enabling higher capacity turbine for utility-scale renewable energy projects. (Source: energy.economictimes.indiatimes.com)
Future Outlook
The outlook for the wind turbine market is expected to remain positive as digitalization, enabling policy frameworks, and technological convergence will shape project economics and operational performance. Wind turbine AI monitoring IoT solutions are anticipated to be adopted on a broad scale since operators are making extensive use of embedded sensors, machine learning, digital twins, and predictive analytics to track vibration, temperature, blade condition, gear box performance, and power production in real time. These solutions may contribute to a reduction in unplanned shutdowns, an enhancement in the scheduling of maintenance, and an extension of the lifecycles of turbines.
Government policy wind turbine incentives will continue to be a significant growth driver and will be supported by renewable energy auctions, tax credits, offshore wind leasing programs, local manufacturing incentives, grid investments, and decarbonization goals for capacity additions in global key markets. Regulatory focus on recycling, local content, permitting reform, and transmission development is also expected to shape future project deployment.
From a competitive energy standpoint, the analysis of solar energy vs wind turbines will increasingly rely on factors such as resource availability, generation profiles, land use, capacity factors, and system integration readiness. Solar is modular and can be installed rapidly, but wind provides better nighttime and seasonal generation. Therefore, with hybrid wind-solar-storage systems (projects) are expected to grow quite well and utilities will be able to use these to enhance renewable power availability, grid stability, and the overall utilization of their assets.
Wind Turbine Market Research Methodology
The evaluation of the wind turbine market uses top-down and bottom-up approaches, along with primary and secondary research methods, to estimate historical market revenues and analyze industry growth prospects. Primary sources include interviews with wind turbine manufacturers, component suppliers, wind farm owners, utilities, service providers, distributors and industry experts. Secondary research is conducted using company annual reports, presentations to investors, government energy databases, wind installation data, data by trade organizations, regulatory publications, and project announcements. Market size is based on factors such as number of turbines sold annually, capacity installed, average selling price, demand for replacement, and revenues coming from onshore and offshore turbines. Information by turbine type, capacity, component, installation, application, and region are available. The analyst team validates the report’s findings from the supply and demand sides and triangulates them with company revenue analysis. The projections account for policy targets, auction pipelines and technology development, project economics, supply chain challenges, and regional renewable energy investment trends.
Wind Turbine Market Segmentation
By Axis Outlook (Revenue, USD Billion, 2021–2034)
- Vertical
- Horizontal
By Installation Outlook (Revenue, USD Billion, 2021–2034)
- Offshore
- Fixed-bottom
- Floating
- Onshore
By Components Outlook (Revenue, USD Billion, 2021–2034)
- Rotator blade
- Generator
- Gearbox
- Nacelle
By Application Outlook (Revenue, USD Billion, 2021–2034)
- Residential
- Utility
- Industrial
- Commercial
By Capacity Outlook (Revenue, USD Billion, 2021–2034)
- Small
- Medium
- Large
By Connectivity Outlook (Revenue, USD Billion, 2021–2034)
- Grid Connected
- Stand Alone
By Rating Outlook (Revenue, USD Billion, 2021–2034)
- < 100 kW
- 100 kW to 250 kW
- > 250 kW to 500 kW
- > 500 kW to 1 MW
- 1 MW to 2 MW
- >2 MW
By Regional Outlook (Revenue, USD Billion, 2021–2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Wind Turbine Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 169.29 Billion |
| Market Size in 2026 | USD 186.64 Billion |
| Revenue Forecast by 2034 | USD 410.52 Billion |
| CAGR | 10.3% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Wind Turbine Market FAQ's
The global market size was valued at USD 169.29 billion in 2025 and is projected to grow to USD 410.52 billion by 2034. Rapid expansion of offshore wind development and rising global energy demand drive the market.
The global market is projected to register a CAGR of 10.3% during the forecast period. Rising advancements in wind turbine composites will boost the market expansion in the coming years.
Asia Pacific dominated the market with a 48.60% share in 2025. The growth is attributed to the presence of major manufacturing hubs and rising electricity demand.
A few global key market players include ENERCON Global GmbH; GE Vernova; Goldwind Science & Technology; Guodian United Power Technology; Mingyang Smart Energy Group; Siemens Gamesa Renewable Energy; Sinovel Wind Group; Suzlon Energy Limited; and Vestas Wind Systems A/S.
The horizontal segment accounted for 95.40% revenue share in 2025, driven by its superior efficiency and scalability.
The offshore segment is expected to witness significant growth during the forecast period. This is due to the rising investments in large-scale renewable energy projects and the availability of stronger, more consistent wind resources at sea
The rotor blade segment dominated the wind turbine market with a 30.20% share in 2025. This is due to their size, the specialized composite materials and the manufacturing complexity. Higher turbine ratings, longer blades, development of offshore wind and use of carbon-fiber-reinforced materials are some of the additional trends driving demand for high-performance rotor blades.
The utility segment dominated the wind turbine market with an 82.10% share in 2025. Large-scale utility wind farms comprise the bulk of turbine installations, as they participate in large renewable energy procurement programs, power purchase agreements, and government decarbonization goals. Increased installation of multi-megawatt onshore and offshore turbines together with grid extension and renewable energy tenders are expected to keep the segment in the first place.
The large-capacity segment accounted for approximately 48.00% of the market in 2025. Utilities and wind developers are driving demand as they want to get more electricity from less turbines. Larger turbines also enhance project economics by reducing the number of foundations, cables, land area and maintenance points per megawatt. Their penetration is especially strong in utility-scale onshore projects and they are taking hold in the fledgling offshore wind market.
The grid-connected segment dominated the market with approximately 86.70% share in 2025. As grid connectivity is necessary for utility-scale deployment, the majority of large wind farms provide electricity directly to regional or national transmission grids. Targets for renewable energy, transmission enhancements, smart-grid investments, and better wind-battery integration are boosting market demand for grid-connected turbines in many established and nascent electricity markets.
The above 2 MW segment held the largest share of approximately 45.90% in 2025. Higher-rated turbines are increasingly preferred by wind developers as they produce more electricity per unit and have potentially lower balance-of-plant costs. This trend is especially steep in offshore wind as ever more potent turbines enhance project-scale economics while technology advances in blades, drivetrains, towers and generators allow even higher turbine ratings.
Major opportunities are falling wind LCOE, corporate renewable PPAs, floating offshore wind and green hydrogen development. Improved generation cost means more competitive wind projects with corporate off-takers for long-dated electricity procurement. Floating platforms can access high-quality wind resources farther offshore, and co-location of wind farms with electrolyzers generates additional demand from nascent green hydrogen projects and energy-heavy industries.
Stronger wind resources, larger turbine capacities, higher energy yields, supportive policies, and the development of floating wind are driving faster growth for offshore wind.
Download Sample Report of Wind Turbine Market
Please fill out the form to request a customized copy of the research report.