
Automotive ADAS Sensor Market Size, Share, Trends and Forecast, 2026–2034
REPORT DETAILS
Automotive ADAS Sensor Market Summary
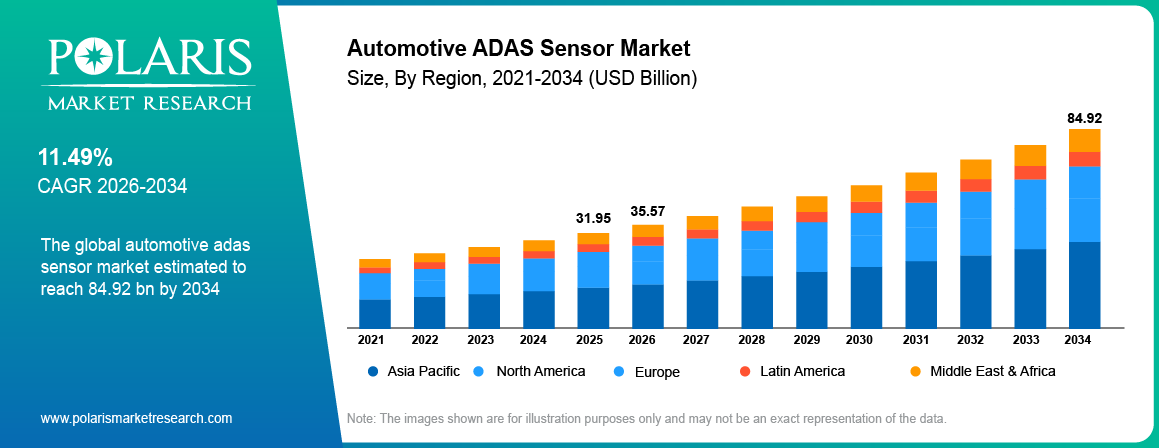
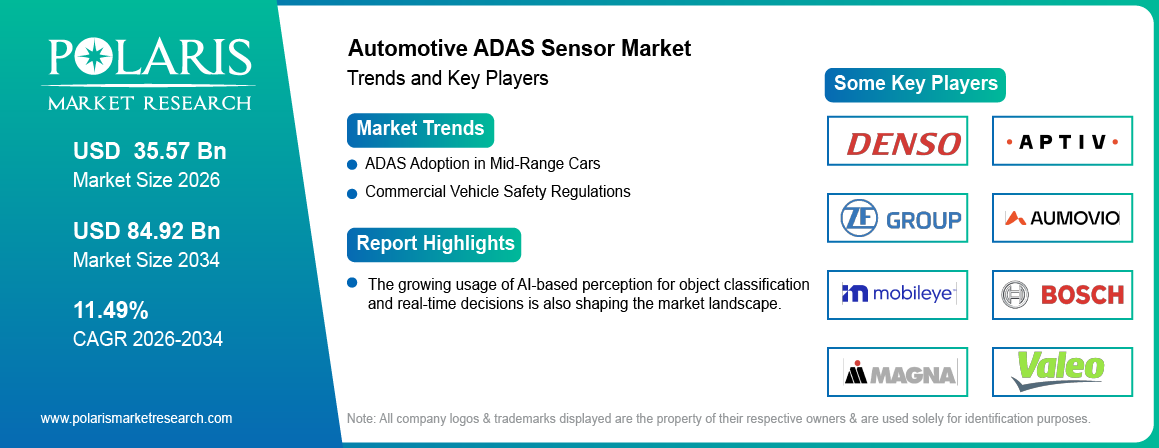
The global automotive ADAS sensor market size was valued at USD 31.95 billion in 2025. The market is projected to grow at an 11.49% CAGR from 2026 to 2034. Advanced driver assistance systems (ADAS) are increasingly being installed in mid-range cars. This is driving the demand for automotive ADAS sensors. The growing usage of AI-based perception for object classification and real-time decisions is also shaping the market landscape.
Market Statistics
Key Takeaways
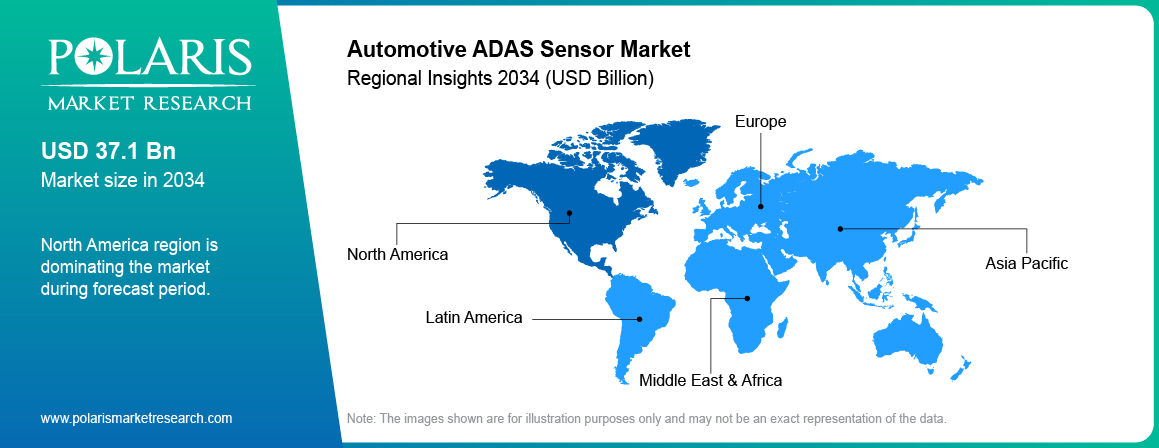
- North America leads the global market. The regional automotive ADAS sensor market share was 33.16% in 2025. Stringent safety regulations and high consumer awareness contribute to the regional market dominance.
- Asia Pacific is projected to witness the fastest growth at a 12.48% CAGR during the ADAS sensors market 2026 to 2034 forecast period. This is owing to the increasing integration of ADAS by automakers to meet regional safety requirements.
- By offering, the hardware segment accounted for an 73.84% automotive ADAS sensor market share in 2025. This is because physical sensor units are required for mandatory safety fitments.
- By vehicle type, the passenger cars segment held an 73.18% market share in 2025. The rising consumer demand for safety features contributes to the segment’s major market share.
- By system, the blind spot detection (BSD) segment is projected to grow at an 9.72% CAGR. BSD helps reduce accidents resulting from lane changes made without checking blind spots.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Are Automotive ADAS Sensors?
Automotive ADAS sensors are physical devices that gather data from the surrounding environment of the vehicle. These sensors are used in advanced driver assistance systems. They help detect other vehicles, pedestrians, road lanes, and other obstacles around the car. Types of ADAS sensors include radar, camera sensors, LiDAR, and ultrasonic sensors.
To put it simply, ADAS sensors are like the eyes and ears of the car. They give all the required data for various systems of the vehicle, including automatic emergency braking and adaptive cruise control systems.
How Do Automotive ADAS Sensors Work?
Automotive ADAS sensors assist vehicles in sensing their environment and possible hazards. They use onboard processors to process data and facilitate driver assistance functions. There are five major steps involved in this process.
Detect: Using radar, cameras, LiDAR, and ultrasonic sensors, the sensors detect other vehicles, pedestrians, objects, and road markings.
Collect: Data is collected on the distance, motion, position of the object, and the surrounding environment of the vehicle.
Process: Information is processed using onboard processors to provide useful data.
Recognize: Potential hazards are detected by the system in the form of vehicles stopping ahead and pedestrians crossing the road using the vehicle perception system.
Decide: Based on the processed data, the ADAS function alerts the driver and performs an action such as emergency braking when needed.
Types of ADAS Sensors
Cars equipped with ADAS have different types of sensors since a single one cannot manage all situations. The radar sensor determines distance and velocity, the camera records the visuals, and LiDAR gives a 3D perspective of nearby objects.
Radar Sensors
Radar sensors for ADAS measure the distance to an object and the velocity at which it is approaching. The operating range of sensors used in automotive radar depends on their usage. Short-range radar assists in parking and blind-spot detection, whereas long-range radar is used in adaptive cruise control applications. Most radar sensors used in automotive applications use the 76-81GHz frequency band. The frequency band must be verified against the relevant market and product scope. Radar sensors work well under conditions that may limit visibility of the camera, such as fog and rain.
Camera Sensors
The camera is capable of spotting things like lane markings and signs that might be missed by a radar. While mono cameras have one lens, stereo cameras have two lenses to gauge depth. These variations influence how camera-based ADAS systems analyze the road situation. There are forward cameras used for lane departure alerts and traffic sign recognition, and there are also cameras monitoring the behavior of the driver for signs of distraction or tiredness. Some night vision cameras can use infrared imaging to spot humans and other animals at night.
LiDAR Sensors
LiDAR sensors for vehicles emit light pulses and evaluate the time it takes them to come back. In this way, a 3D picture of the road and surrounding things is generated from the data. That is why it is useful when it comes to having precise spatial awareness for the vehicle. Solid-state LiDAR is getting more attention now because of the fewer mechanical components required. But its relatively high cost should still be taken into account.
Ultrasonic Sensors and Processors
The ultrasonic parking sensors work with the help of sound waves that detect any obstacles around the car when traveling at slow speeds. These sensors are often installed in vehicles' bumpers for easy parking. On the other hand, processors are used for a completely different function in ADAS. They process information from the sensors and perform necessary calculations.
Radar vs Camera vs LiDAR vs Ultrasonic Sensors in ADAS
Every sensor in the automotive ADAS sensor market has its own strength. Radar determines distance and speed, cameras record visual data, LiDAR records the surroundings, and ultrasonic sensors detect nearby objects. The following table describes their functions and constraints.
| Factor | Radar | Camera | LiDAR | Ultrasonic |
| Main function | Distance, relative speed, and angle of objects | Visual recognition of lanes, signs, pedestrians, and driver state | 3D mapping and object-shape detection | Very short-range obstacle detection |
| Data type | Millimeter-wave radio signals | Images from video frames | Laser-based depth point cloud | Ultrasonic sound pulses |
| Strengths | Works in rain, fog, and darkness; measures speed directly | Rich detail; classifies objects; low unit cost | High-resolution 3D geometry | Low cost; reliable at parking speeds |
| Limitations | Lower resolution; multipath interference in dense urban scenes | Degrades in low light, glare, fog, rain and snow | Degrades in heavy rain, dust and snow; higher cost | Range of only a few meters |
| Typical ADAS functions | Adaptive cruise control, emergency braking, blind spot, cross-traffic alert | Lane keeping, sign recognition, pedestrian detection, driver monitoring | Higher-level automation, 3D perception | Parking assist, low-speed maneuvering |
| Relative cost | Lower | Lower to moderate | Higher | Lower |
Source: Polaris Market Research Analysis
Automotive ADAS Sensor Market Dynamics
The automotive ADAS sensor market is shaped by the increased adoption of driver assistance systems, the difficulties in the integration of sensors in automobiles, and technological advancements in sensor technology.
Driver: ADAS Adoption in Mid-Range Cars
ADAS features are no longer limited to luxury cars. Auto manufacturers are integrating driver assistance functionalities into their mid-level cars to attract customers who want enhanced safety without resorting to premium segments. Functionalities like forward collision warning (FCW), lane departure warning, and automatic emergency braking are becoming increasingly accessible due to the reduction in the prices of the sensors and the development of systems for various price points. Camera-based systems can help provide several functionalities with one camera, which would help in managing the cost of hardware. Distance and speed sensing are added by radar sensors for functionalities like adaptive cruise control (ACC). In July 2026, Kia India launched new Seltos GTX(O) and X-Line(O) models with enhanced ADAS functionality comprising 28 ADAS capabilities against 21 in the earlier models (source: kia.com). Such product launches indicate the availability of multiple assistance functionalities in the mid-level SUV category. With the growing trend of customer consideration towards safety technology, there is more need for ADAS across a broader range of car segments and trim levels.
Driver:Commercial Vehicle Safety Regulations
Safety standards are creating a clear demand for ADAS sensors in commercial vehicles. Trucks and buses have a special risk profile, as they are large, have long braking distances, and operate during prolonged periods. Such systems as obstacle detection, driver alertness monitoring, or warnings about a vehicle leaving a driving lane may address certain risks. These systems use sensors to determine vehicles around, lane boundaries, and any possible dangers. Indian government, through the Ministry of Road Transport and Highways, introduced new safety standards for heavy commercial vehicles in February 2026. According to the announced schedule, Advanced Emergency Braking System and electronic stability control systems will become mandatory for all trucks starting October 1, 2027. Also, blind spot information system, moving off information system, driver drowsiness monitoring, and lane departure warning systems are scheduled to become mandatory from January 1, 2028 (source: pib.gov.in). Safety standards create a set timeframe for the integration of new technologies for vehicle manufacturers. This requires fleet operators to include these systems when purchasing or updating the vehicles, which drives automotive ADAS sensor market demand.
Restraints and Challenges : Cost and Technical Challenges in ADAS Sensor Integration
Integration costs can hinder the application of ADAS sensors on low-cost cars. The implementation of radar and cameras is costly, while LiDAR cost remains a concern for models that need accurate environmental mapping. The combination of several types of sensors will also demand increased computing capacity and software development. Installation and ADAS sensor calibration increase costs, as sensors should be accurately installed and calibrated again after repair or replacement of windshields. The performance of the sensor could also decline under heavy rain or fog and when dirt contaminates the sensors. Companies will have to test systems in different driving environments to evaluate their performance. There are risks of delays due to shortages of semiconductor supplies, and cybersecurity threats should continue to be considered. Lack of testing stations and technicians can create further barriers to implementation in certain regions.
Market Opportunities : Growing Role of Centralized Computing in ADAS
Centralized computing presents new opportunities for automotive ADAS sensor market providers and software vendors to assist with advanced driver assistance systems. Rather than using separate controllers to operate each individual function, the automaker can use one computing platform to perform multiple ADAS functions. This approach can simplify vehicle electronics and make it more convenient to update software. It provides new possibilities for suppliers that offer high-powered processors and software for managing sensor data. As vehicles will need to process more data from cameras, radar, and LiDAR sensors, the demand for computing platforms capable of efficient processing may rise. Suppliers that are able to provide more than one ADAS application on one platform can address manufacturers looking for versatile vehicle platforms.
Technology Trends in ADAS Sensors
The automotive ADAS sensor market sensor technology is evolving to be more efficient in terms of object detection and faster data processing. Vehicle architecture is another area being explored by automobile manufacturers.
Sensor Fusion and Centralized Compute
Radar, camera, and LiDAR all collect different information from the environment. By combining these sensors, sensor fusion offers a more complete view of the environment to the car. This assists the vehicle in evaluating situations where the information collected by any of the sensors might not be complete. The type of computing architecture can influence the speed at which the information is utilized. The ADAS domain controller is capable of performing various functionalities through a single processing unit, without having to resort to individual controllers for each functionality. Centralized compute also makes the process of adding software capabilities easy. Edge computing ensures that data analysis takes place in the vehicle itself, without having to transmit real-time data to any other system. This is important considering that automakers have started to create more complex driver assistance systems.
AI-Based Perception
AI is changing the way cars interpret information captured through their sensors. Previously, vehicle sensors could only make use of preprogrammed rules for recognizing objects as well as reacting to different situations. AI perception is capable of classifying objects and predicting their movements. For instance, the AI system can recognize whether an object on the street is approaching or moving away from the street. More advanced autonomous vehicle sensors can provide useful information to machine learning models to enhance the recognition of objects and scenes. The performance of such models depends on the quality of information provided by the sensors as well as the training required for the model. Advances in the broader field of artificial intelligence are contributing to this area.
4D Imaging Radar and Solid-State LiDAR
While conventional radar detects distance and velocity of an object, the new generation of radars can also provide more accurate details of the object’s location and altitude. 4D imaging radar ADAS can assist in identifying vehicles, road obstructions, and other objects in the driving scene. The Gen 8 radar product line by Aptiv was launched in October 2025, providing enhanced detection and resolution capabilities (source: aptiv.com). In May 2026, Aptiv announced that the radar platform had been chosen by Volvo Cars for future vehicles; implementation is expected to start in 2028 (source: aptiv.com). In addition to radar and camera systems, LiDAR systems are designed with fewer moving components than mechanical ones. LiDAR systems provide another option for constructing a 3D image of the road environment.
Software-Defined Vehicles and V2X
A software-defined vehicle enables better management of the functions of a vehicle via software. Automakers can have the ability to enhance ADAS functionalities even after the sale of the car. In addition, over-the-air updates can enable changes even without bringing the car to the workshop, although not all changes are made through this method. Vehicle-to-everything communication is another way of getting more information because the vehicles can communicate not only among each other but also with other infrastructure around. For instance, a car can get a warning of traffic conditions outside the field of view of the driver. These functions require compatible communication infrastructure. Therefore, the wider adoption will differ across markets.
ADAS Sensors in Autonomous and Electric Vehicles
The ADAS sensor specifications depend on the vehicle's level of automation and its application. Electric vehicle platforms also create new applications for these systems.
Level 2+/Level 3 automation necessitates the development of sensors capable of monitoring traffic and managing driving tasks. The Level 2 automation system aids the driver in steering and managing the speed while maintaining their alertness. A Level 3 system handles the driving tasks in particular situations. Here, the driver can take control when needed.
Self-driving cars use cameras and radar to perceive road users and analyze the environment. Some models have LiDARs that give more precise data on spatial awareness. The more automation in the vehicle, the higher the requirements for reliability of the system. In some cases, manufacturers employ redundant self-driving car sensors and computing modules to keep essential functions operating in case of malfunction.
Electric vehicles provide another field of application. Electronic architecture allows installing sensors and computers while designing a vehicle. Electric commercial vehicles, which include electric buses and delivery trucks, can utilize ADAS for lane detection, collision avoidance, and slow movement. The sensor configuration will depend on the vehicle dimensions, working conditions, and level of assistive functions.
Safety Regulations and Standards
Are ADAS sensors necessary? These are required to be equipped in systems that require sensors to function, such as automatic emergency braking systems and lane departure warning systems. The requirement for such systems is determined by the laws in the markets where such cars will be sold. Safety rating agencies also affect automakers’ choices despite their voluntary status.
| Regulation or Program | Region | Requirements and Status |
| FMVSS 127 | United States | Requires automatic emergency braking (AEB) and forward collision warning in light vehicles. The compliance date for most manufacturers is September 1, 2029, subject to any subsequent regulatory changes. |
| EU General Safety Regulation (EU) 2019/2144 | European Union | Introduces mandatory safety features in phases. Requirements cover systems such as emergency braking, lane-keeping assistance, and driver drowsiness warning. It depends on vehicle category and implementation date. |
| Euro NCAP | Europe | Assesses vehicle safety and awards ratings based on performance in areas such as emergency braking and lane support. Automakers may use these ratings to guide sensor selection and improve vehicle safety scores. |
| C-NCAP and Bharat NCAP | China and India | Assess vehicle safety as well as the safety systems incorporated in the vehicle. However, their rating is not a substitute for compulsory safety standards. |
Source: Polaris Market Research Analysis
These regulations don’t mean that all vehicles have to have the same type of sensors. Some functions may be achieved by cameras and radars, and the final solution will depend on the vehicle and the equipment it has. In addition, the manufacturers should take into account the relevant legislation in the respective markets.
Automotive ADAS Sensors Market Segmental Analysis
The automotive ADAS sensor market is primarily segmented based on offering, vehicle type, component, system, sales channel, and region.
| Segmentation Axis | Segments |
| By Offering | Hardware · Software · Others |
| By Vehicle Type | Commercial Vehicles (Heavy Commercial Vehicle, Light Commercial Vehicle) · Passenger Cars · Trucks · Buses |
| By Component | Sensor (Radar, Camera Unit, LiDAR, Ultrasonic Sensor) · Processor |
| By System | Blind Spot Detection (BSD) · Adaptive Front Lights (AFL) · Cross Traffic Alert (CTA) · Adaptive Cruise Control (ACC) · Driver Monitoring Systems (DMS) · Automatic Emergency Braking (AEB) · Intelligent Park Assist (IPA) · Forward Collision Warning (FCW) · Night Vision System (NVS) · Lane Departure Warning System (LDW) · Road Sign Recognition (RSR) · Pedestrian Detection System (PDS) · Traffic Jam Assist (TJA) · Tire Pressure Monitoring System (TPMS) |
| By Sales Channel | Aftermarket · Original Equipment Manufacturer (OEM) |
| By Region | North America (U.S., Canada) · Europe (France, Germany, UK, Italy, Netherlands, Spain, Russia, Rest of Europe) · Asia Pacific (Japan, China, India, Malaysia, Indonesia, South Korea, Australia, Rest of Asia Pacific) · Latin America (Brazil, Mexico, Argentina, Rest of Latin America) · Middle East & Africa (Saudi Arabia, UAE, Israel, South Africa, Rest of Middle East & Africa) |
Source: Polaris Market Research Analysis
By Vehicle Type
The passenger cars segment led the automotive ADAS sensor market with an 73.18% share in 2025. Various passenger cars have a broad array of driver-assistance technologies such as parking sensors, automatic emergency braking, and adaptive cruise control. These features are becoming increasingly popular among drivers because of the growing importance of safety technology in car purchase decision-making process. Cameras and radar sensors are common since they can be used to perform various functions such as lane departure warnings and forward collision detection. In addition, some cars use data collected by various sensors to improve detection performance in various driving conditions. The availability of features depends on the particular car model and trim level. Premium cars provide more advanced systems, while economy models concentrate on a selection of safety features.
The commercial vehicles segment is projected to grow at an 11.42% CAGR. Trucks, buses, and other commercial vehicles have unique challenges compared to regular passenger vehicles due to long operating hours, bigger blind spots, and longer stopping distances. The sensors used in commercial vehicle ADAS enable monitoring of nearby vehicles, detection of objects, and warnings of possible collisions to the drivers. Radar is helpful in identifying other vehicles surrounding large trucks, while cameras facilitate lane and object detection. These systems can also be considered by fleet operators in evaluating their safety and operation costs. New regulations requiring the installation of automatic emergency braking and lane departure warnings are becoming the driving forces behind adoption of compatible sensing systems in some vehicle categories.
By Component
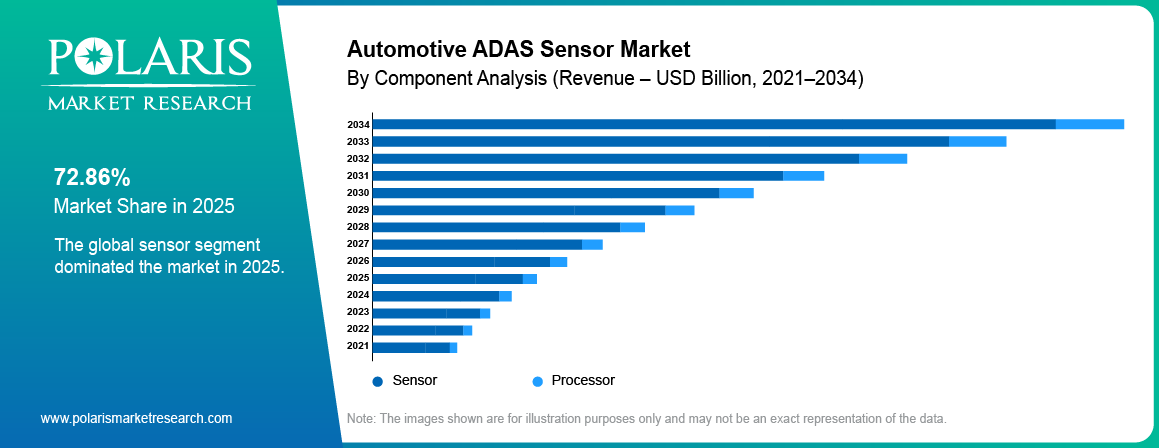
The sensor segment dominated the automotive ADAS sensor market with an 72.86% share in 2025. The sensors constitute a significant part of ADAS hardware because every sensing function depends on information gathering from the environment surrounding the car. They include radar, camera, Lidar, and ultrasonic sensors. Manufacturers select from these hardware elements depending on the safety specifications of the automobile, design specifications, and cost range. There are vehicles that utilize one camera to facilitate several applications, whereas there are other cars that incorporate several types of sensors. There is also room for suppliers to cater to several types of vehicles due to increased production of ADAS automobiles. The demand for sensors will vary based on the number of applications within the vehicle and the level of automation.
The processor segment is projected to grow at an 10.92% CAGR. The processors interpret sensor inputs and run the software powering ADAS functionalities. The relevance of processors increases with the amount of data and assistance functions handled by cars. Another shift seen among car manufacturers is that of computing platforms capable of handling multiple vehicle functions through a common hardware platform as opposed to individual control units. This results in the need for automotive processors with enough computing capabilities to perform timely calculations. Processor manufacturers must also meet the needs of the vehicles in terms of reliability, power efficiency, and operational environment. It is the complexity of the system and its functions that determines the kind of processors needed. The growth of this segment will be shaped by vehicle computing architecture and the sophistication of ADAS features.
By System
The adaptive cruise control (ACC) segment led the automotive ADAS sensor market with an 24.28% share in 2025. ACC manages the vehicle speed in relation to a preset distance from the preceding vehicle. Since its application is on highways, it has become a standard feature in cars used for long distances and regular trips. The feature comes in various packages, from simple speed management to stop-and-go capability on congested roads. This feature is especially useful in cars where the traffic speed changes regularly. The operation of ACC requires consistent detection of the preceding vehicles and therefore makes sensor capability an important aspect of the system. Moreover, its availability across different vehicle classes provides manufacturers with the flexibility in how they package the feature.
The blind spot detection (BSD) segment is projected to grow at an 9.72% CAGR. The BSD warns drivers in case there is a vehicle approaching in areas that are hard to see through the mirrors. The technology is most appropriate for use while changing lanes on multi-lane roads and when driving large vehicles. Car manufacturers may decide to incorporate this feature independently or as part of driver assistance features. In certain vehicles, the technology gives the driver an extra warning when they start moving from one lane to another, but there is another vehicle close by. BSD is important in commercial vehicles because of their lengths and poor rear views when changing lanes. The adoption of this technology will be influenced by vehicle safety requirements, preferences of buyers, and availability of blind spot detection as part of ADAS packages.
By Offering
The hardware segment held an 73.84% automotive ADAS sensor market share in 2025. It includes physical parts that need to be placed on the vehicle for implementing driver assistance functions, along with the electronic devices necessary for the functioning of these systems. The demand for hardware is directly associated with the number of ADAS features being introduced into new vehicles. It is important for manufacturers to pick hardware according to the specifications of their vehicle. The choice of hardware influences the cost of manufacturing vehicles, especially in inexpensive vehicles where manufacturers have to consider safety systems against the price of vehicles. There is also demand for replacement after accidents or malfunctioning of hardware systems. With an increasing number of vehicles offering ADAS systems as part of the standard equipment, the application areas for hardware manufacturers become diverse.
The software segment is projected to witness rapid growth at an 11.86% CAGR. The software determines how the hardware will interpret information and react to driving conditions. Car makers are paying more attention to software updates to improve the functionality of the system after the car leaves the production line. The software can also aid car manufacturers in adjusting the features to fit various car models without re-designing the whole hardware configuration. This is important considering that the architecture of cars is moving towards integrated computing platforms. However, the development of software requires substantial validation to ensure that software updates do not interfere with the safety-critical functions of the system. Suppliers with experience in perception algorithms, system integration, and software testing for the automotive industry can serve manufacturers that need to upgrade their ADAS systems.
By Sales Channel
The original equipment manufacturer (OEM) segment dominated with an 87.94% automotive ADAS sensor market share in 2025. The ADAS sensors are incorporated into vehicles by the OEMs as part of the vehicle manufacturing process to ensure compatibility with the vehicle’s electronics and safety components. Sensor manufacturers work with automakers to match the design requirements, budgets, and timelines of production. Incorporation of the sensors at the factory stage enables their proper installation and calibration in the manufacturing process. With the growing number of new cars equipped with built-in driver assistance systems, the OEMs still represent an important sales channel for the sensor producers.
The aftermarket segment is projected to grow at an 12.47% CAGR. The source of demand is vehicle owners or fleets that have to replace their sensors or fit chosen driver assistance technologies on their existing cars. Needs for replacement may emerge after accidents or window repairs when the sensor has to be recalibrated. Proper diagnostic equipment and skilled technicians are needed in order to perform this task properly. The existing fleet of vehicles represents a potential customer base beyond new car sales. Compatibility with earlier vehicle generations may limit the variety of available aftermarket systems.
Automotive ADAS Sensor Real-World Use Cases
Automakers have started integrating ADAS in various vehicle segments, including passenger cars like SUVs and even trucks. The following developments highlight the real-world uses of automotive ADAS sensor market solutions:
| Company / Automaker | Vehicle or Technology | Real-World Application | Deployment Update |
| Mahindra & Mahindra | Scorpio-N Z8L | Adds Level 2 ADAS features, including automatic emergency braking (AEB), adaptive cruise control, and lane departure warning. | Mahindra announced the new features in June 2025. (source: auto.mahindra.com) |
| BMW and Qualcomm | Snapdragon Ride Pilot in the BMW iX3 | Supports highway driving assistance, lane changes, and parking assistance using cameras and radar. | Unveiled in September 2025. The BMW iX3 was the system's first production vehicle. (source: qualcomm.com) |
| Magna and a German automaker | Driver monitoring system | Uses an in-cabin sensing system to monitor the driver and vehicle occupants. | Magna reported scaled global production in 2025. (source: magna.com) |
| Bosch and Chinese automakers | Bosch ADAS product family | Combines cameras, radar, and software to support functions such as adaptive cruise control, emergency braking, and lane keeping. | Bosch reported in April 2025 that its mid-range system was scheduled to enter serial production with a Chinese manufacturer in mid-2025. It also named BAIC, Dongfeng, and Jetour among its customers for mid- and high-end systems. Bosch announcement |
| Valeo and an Indian commercial vehicle manufacturer | Valeo Smart Safety 360 (VSS360) | Combines radar and camera technology to support emergency braking, lane departure warning, and driver attention monitoring in commercial vehicles. | Valeo announced the program in May 2026. Production is planned at its Sanand facility in Gujarat. The vehicle manufacturer was not named. (source: valeo.com) |
| Nissan and Wayve | Next-generation ProPILOT | Uses cameras, radar, LiDAR, and AI-based driving software to support assistance on highways and complex urban roads. | Nissan demonstrated prototype vehicles in September 2025 and announced a production collaboration in December 2025. The first model with the new system is planned for Japan in fiscal year 2027. (source: nissannews.com) |
Source: Polaris Market Research Analysis
Regional Analysis
The automotive ADAS sensor market varies by region based on vehicle production, safety regulations, and the adoption of driver assistance technologies.
North America
North America dominated the automotive ADAS sensor market with an 33.16% share in 2025. North America continues to be a significant market for automotive ADAS sensors driven by the presence of safety regulations and automaker spending. In the United States, the National Highway Traffic Safety Administration (NHTSA) introduced FMVSS 127, which mandates automatic emergency braking and pedestrian detection in light vehicles by September 2029 for most manufacturers (source: nhtsa.gov). NHTSA's FMVSS 127 announcement, Ford's BlueCruise, and General Motors' Super Cruise have also demonstrated that the automakers are venturing into hands-free driving assistance. The radar technology is also evolving. For instance, in May 2025, Mobileye revealed that a global automaker chose its 4D imaging radar for an eyes-off driving system to be rolled out in 2028 (source: mobileye.com). Such advancements create avenues for sensor suppliers in vehicles with tougher demands in terms of detection and driver assistance.
Asia Pacific
The Asia Pacific automotive ADAS sensor market is projected to witness the fastest growth at an 12.48% CAGR. Asia Pacific is an important market for automotive ADAS sensors, where China, Japan, and India contribute through the manufacturing and development of technology. China has a strong supply chain for LiDAR sensors, where local manufacturers have developed sensors that can be used in advanced driver assistance and automated driving. The Japanese auto companies have been working on vehicle safety technology for some time now, whereas ADAS technology is growing in India beyond premium vehicles. NOVELIC made an announcement in April 2026 about entering the Indian market and partnering to produce in-cabin radar modules in collaboration with Sona Comstar (source: novelic.com). The partnership is a continuation of local initiatives geared towards producing sensors for vehicles. For automakers in the region, there will be a need to balance sensors' performance and cost of the vehicle as well as the driving environment.
Europe
Europe accounted for an 30.08% automotive ADAS sensor market share in 2025. The automotive ADAS sensor market in Europe is aided by stringent safety regulations and good manufacturing capabilities of premium cars. The EU General Safety Regulation mandates specified safety systems for certain vehicle types that include emergency braking and lane-keeping assistance. Safety ratings done by Euro NCAP can also contribute to influencing the design of automobiles by ensuring improved collision avoidance and driver assistance. Premium car brands like BMW, Mercedes-Benz, and Volvo have introduced advanced sensing technologies to some of their latest automobiles. These sensing technologies are based on camera and radar sensors for monitoring the road and identifying hazards. Europe has an established automotive value chain for sensors. Deployment beyond premium cars depends on cost and manufacturer adoption.
Latin America
The Latin America automotive ADAS sensor market is projected to grow at an 10.74% CAGR. Brazil and Mexico represent important markets owing to the presence of their automotive manufacturing facilities and car purchases. Safety awareness is also driving an interest in ADAS features like auto-braking and lane departure warning systems. The adoption of ADAS varies in this market owing to the price of vehicles and the features that automobile manufacturers install. Increased ADAS installations in mid-range cars are expected to boost demand for ADAS.
Middle East & Africa
The Middle East & Africa automotive ADAS sensor market is projected to grow at an 11.36% CAGR. Demand differs in the region, with UAE and Saudi Arabia putting effort into the development of road safety and smart mobility programs. Premium cars account for a significant portion of ADAS adoption in the Gulf market. The wider availability in mid-sized cars may boost sales. South Africa sees affordability of vehicles and the availability of newer cars as factors influencing adoption. Road conditions and local safety regulations will affect the development of the market as well.
ADAS Sensor Ecosystem and Supply Chain
The automotive ADAS sensor market supply chain includes semiconductor providers, who manufacture chips for sensor devices and data processing. Sensor manufacturers create systems based on those components, such as radar, camera, LiDAR, and ultrasonic sensor devices. Afterward, the tier-1 supplier integrates those sensor devices with processors, control units, and vehicle software. Finally, the vehicle manufacturer will include the whole system in its vehicle model depending on its safety elements and cost.
Software developers also contribute to this ecosystem. Software developers are responsible for creating algorithms that assist cars in comprehending data provided by those sensors. In the case of autonomous driving developers, they can collaborate with sensor producers and the car manufacturer to test advanced systems. Availability of manufacturing capabilities, hardware and software compatibility, and availability of components influence how rapidly new technology gets to production.
Competitive Landscape
The automotive ADAS sensor market comprises sensor providers, automotive technology providers, and semiconductor vendors. Key ADAS sensor firms compete based on performance, integration, reliability, and manufacturing capability of sensors. Some companies specialize in radar- and camera-based solutions, while some provide broader sensing hardware and software capabilities for ADAS applications. Collaborations with automotive firms and Tier-1 providers also influence their market position. As car manufacturers incorporate more ADAS functions in their cars, supplier companies have to consider technical abilities along with cost factors. Alliances between automakers and top ADAS sensor companies are also crucial to their market positioning as more ADAS functionality is provided in vehicles by automakers at all pricing levels.
Vendor Positioning
| Vendor Classification | Companies | Key Offerings | Market Positioning |
| Tier-1 Supplier | AUMOVIO SE | Radar sensors, camera systems, ultrasonic sensors, assisted driving control units | Offers sensor hardware and integrated ADAS platforms for different levels of driving assistance. |
| Tier-1 Supplier | Aptiv PLC | Radar and camera-based sensing, ADAS computing, perception software, integrated ADAS platforms | Provides hardware and software platforms for driver assistance, from foundational safety features to more advanced automation. |
| Tier-1 Supplier | DENSO Corporation | Vision sensors, stereo vision sensors, driver status monitoring, integrated safety systems | Focuses on sensing and vehicle safety technologies that support automated driving and driver assistance. |
| Tier-1 Supplier | Magna International Inc. | Driver monitoring, in-cabin sensing, camera-based systems, driver assistance technologies | Supplies sensing and vehicle electronics, including technologies for monitoring drivers and supporting safer vehicle operation. |
| Tier-1 Supplier | Robert Bosch GmbH | Radar, camera systems, driver assistance software, integrated ADAS solutions | Combines sensing hardware and software to support a range of driver assistance functions. |
| Tier-1 Supplier | Valeo SE | Radar, cameras, ultrasonic sensors, LiDAR, ADAS software, parking assistance systems | Offers technologies spanning sensing, perception, parking, and driving assistance. |
| Tier-1 Supplier | ZF Friedrichshafen AG | Automotive sensing and driver assistance technologies, including radar-based systems | Has supplied integrated vehicle safety and ADAS solutions. Confirm the status of its passenger-car ADAS business following the announced sale to Harman before publication. |
| Vision and Compute | Mobileye Global Inc. | EyeQ system-on-chips, computer vision, perception software, ADAS platforms | Specializes in vision-based ADAS and computing platforms for driver assistance and advanced automation. |
| Semiconductor | Infineon Technologies AG | Automotive microcontrollers, radar-related semiconductors, power and safety chips | Supplies semiconductor components used in automotive sensing, processing, and electronic control systems. |
| LiDAR Specialists | Hesai Group | Automotive LiDAR sensors and related sensing technologies | Focuses on LiDAR hardware for vehicle perception and advanced driving applications. |
| Semiconductor | Valens Semiconductor Ltd. | High-speed automotive connectivity chipsets and in-vehicle data transmission technologies | Supports high-bandwidth data transfer between automotive sensors, computing units, and other electronic systems. |
Source: Polaris Market Research Analysis
List of Key Companies
- AUMOVIO SE
- Aptiv PLC
- DENSO Corporation
- Valeo SE
- Magna International Inc.
- ZF Friedrichshafen AG
- Robert Bosch GmbH
- Mobileye Global Inc.
- Infineon Technologies AG
- Valens Semiconductor Ltd.
- Hesai Group
Industry Developments
- September 2026: Aptiv began mass production of a new ADAS camera for a Chinese electric vehicle manufacturer targeting the European market. The system uses an 8-megapixel camera and was designed to meet Euro NCAP's 2026 five-star safety requirements. Aptiv also reported a 20% reduction in hardware size and power consumption compared with its previous design benchmarks. The launch gives the automaker another option for equipping vehicles for overseas markets. (source: aptiv.com)
- September 2026: OMNIVISION announced its OX08D30, an 8-megapixel image sensor for automotive cameras. The sensor is designed to reduce flickering from LED traffic lights, which can affect camera readings. It also improves image capture in difficult lighting conditions. OMNIVISION said the sensor was already in mass production at the time of the announcement. (source: businesswire.com)
- September 2026: Valens Semiconductor and onsemi announced a collaboration to develop a cost-optimized solution for 3-megapixel automotive cameras. The planned product will combine onsemi's image sensor technology with Valens' MIPI A-PHY connectivity technology. The companies aim to simplify camera system design and make the solution suitable for high-volume vehicle production. The announcement reflects suppliers' efforts to reduce the cost of camera components used in ADAS. (source: valens.com)
Future Outlook
The automotive ADAS sensor market is expected to benefit from the greater availability of driver assistance and advances in sensing technologies. Radar and cameras will continue to be used for applications like collision warning and adaptive cruise control. Adoption of LiDAR will depend on pricing and the requirement for object detection. Safety regulations are expected to drive the choice of sensors, especially for those markets where there is mandatory braking and lane assistance. Centralized computing and software updates will allow greater flexibility in managing ADAS applications. Growth in the market will be dependent on pricing and how quickly manufacturers launch these ADAS features in different classes of vehicles.
Research Methodology
Scope and Definitions: The study covers sensors, processors, and supporting software used in automotive driver assistance systems across passenger and commercial vehicles. It uses 2025 as the base year and covers the 2026–2034 forecast period, with market values expressed in USD billion. The scope follows the report's segmentation by offering, vehicle type, component, system, sales channel, and region.
Secondary Data Sources: The research utilizes data on vehicle manufacturing, registrations, safety standards, company filings, investor presentations, industry literature, patents, and technical papers. Sources include government agencies such as NHTSA and safety programs from Europe.
Primary Data Sources: Discussions with original equipment manufacturers (OEMs), Tier-1 suppliers, semiconductor companies, and distributors provide insight into sensor fitment, pricing, specifications, and vehicle platforms
Market Size Estimation: Top-down estimation is done using vehicle manufacturing numbers and estimates of ADAS fitment. Bottom-up estimation is done using supplier revenue figures, shipments, and ASPs. Both methods are compared across all segments and geographies.
Validation and Limitation: The estimates are cross-validated using the information from various sources. Discrepancies are analyzed prior to coming to any conclusions. Differences can occur due to changes in regulations, vehicle production, sensor pricing, and technology adaptation. Market figures represent estimates based on the information available during the study.
Automotive ADAS Sensor Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 31.95 billion |
| Market Size Value in 2026 | USD 35.57 billion |
| Automotive ADAS Sensor Market Forecast 2034 | USD 84.92 billion |
| CAGR | 11.49% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Automotive ADAS Sensor Market FAQ's
The automotive ADAS sensors market size was valued at USD 31.95 billion in 2025. The market is projected to witness rapid growth. It is projected to reach USD 84.92 billion by 2034.
The automotive ADAS sensor market is projected to grow at an 11.49% CAGR from 2026 to 2034.
ADAS sensors are used by a vehicle to detect objects around it and monitor the condition of the road. There are four major sensor types: radar, cameras, LiDAR, and ultrasonic sensors. These sensors help vehicles to achieve functionalities such as automatic emergency braking, lane departure warnings, adaptive cruise control, and parking assistance.
The radar detects the distance and speed of approaching objects. The camera captures visual data, such as road signs and lanes. The LIDAR uses laser pulses of light to measure distances and form a three-dimensional image of the surroundings. Different types of sensors are selected by automobile companies based on functionality and cost.
Sensor fusion combines data from two or more sensors. For example, radar can measure how quickly a vehicle ahead is moving. A camera identifies the vehicle and its position. Using both inputs gives the system more information to assess the driving situation.
North America led the global automotive ADAS sensor market with an 33.16% share in 2025. Stringent safety regulations contribute to the regional market dominance. Asia Pacific is projected to witness the fastest growth at an 12.48% CAGR. This is owing to the increasing integration of ADAS by automakers to meet regional safety requirements.
Key companies include AUMOVIO SE; Aptiv PLC; DENSO Corporation; Valeo SE; Magna International Inc.; ZF Friedrichshafen AG; Robert Bosch GmbH; Mobileye Global Inc.; Infineon Technologies AG; Valens Semiconductor Ltd.; and Hesai Group. Their offerings range from automotive sensors and ADAS systems to processors, connectivity chips, and LiDAR.
The market is divided by offering, vehicle type, component, system, sales channel, and region. There is demand due to the adoption of ADAS in mid-level cars and safety requirements in commercial vehicles. Improved sensors and increased adoption of autonomous emergency braking also influence the market.

Download Sample Report of Automotive ADAS Sensor Market
Please fill out the form to request a customized copy of the research report.


