Blood Glucose Monitoring Devices Market Size, Share, Trends and Forecast, 2026–2034
REPORT DETAILS
Blood Glucose Monitoring Devices Market Summary
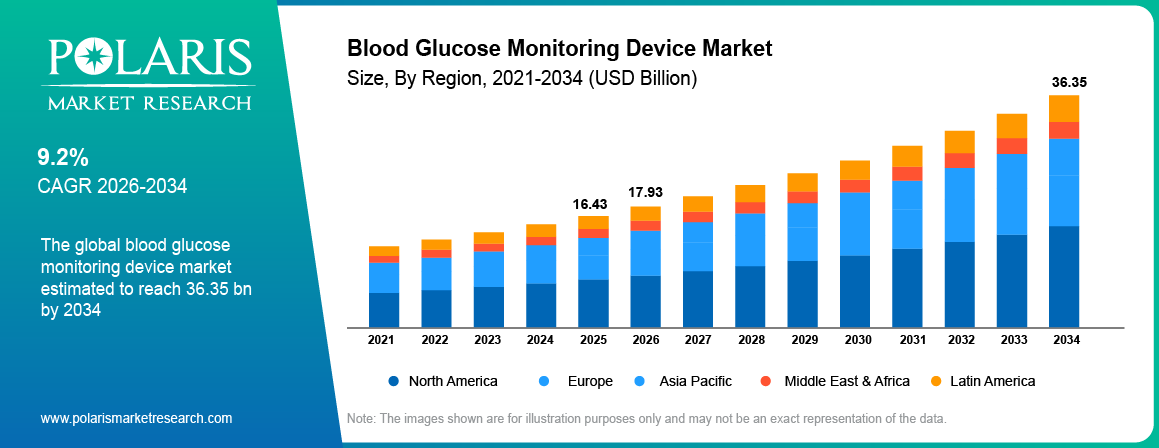
The global blood glucose monitoring device market size was valued at USD 16.43 billion in 2025. The market is projected to grow at a CAGR of 9.2% from 2026 to 2034. The shift towards continuous glucose monitoring (CGM) is one of the key factors driving the blood glucose monitoring market growth. The adoption of over-the-counter (OTC) CGM has expanded the addressable population for blood glucose monitoring devices.
Market Statistics
Key Takeaways
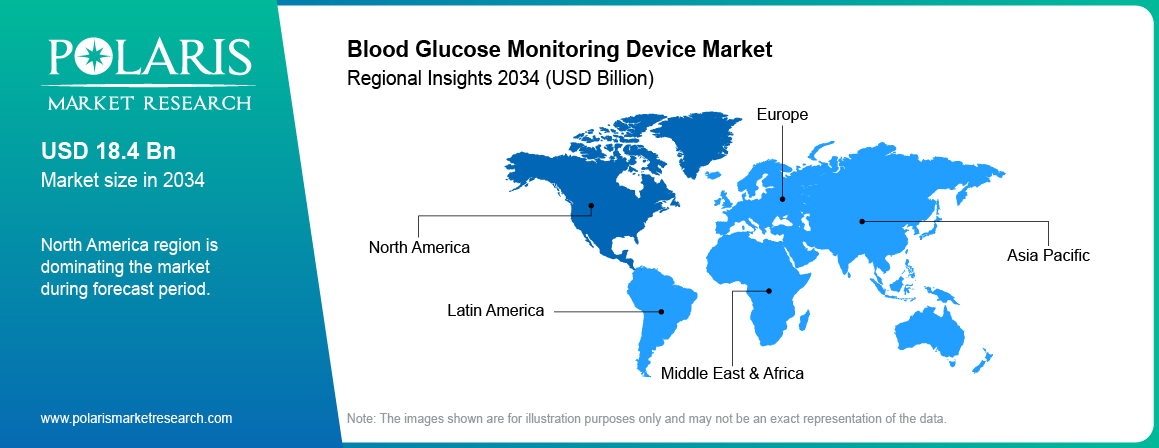
- North America leads the market. The regional blood glucose monitoring devices market share was 38.00% in 2025. The high prevalence of diabetes drives higher demand for blood glucose monitoring devices in the region.
- Asia Pacific is projected to witness rapid growth at an 12.75% CAGR. A large patient base drives the demand for blood glucose monitoring devices across the region.
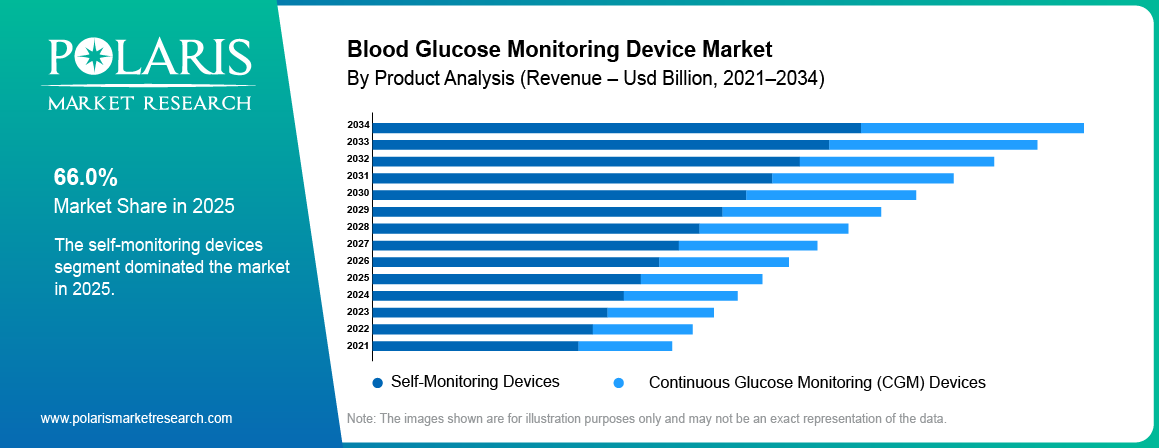
- By product, the self-monitoring devices segment accounted for an 66.00% share in 2025. Their affordability and user-friendly nature contribute to the segment’s leading position.
- By product, the continuous blood glucose monitoring (CBGM) devices segment is projected to grow at an 15.09% CAGR. This is owing to the critical role of these devices in managing type 1 diabetes.
- By connectivity, the Bluetooth-enabled devices segment led with an 50.20% blood glucose monitoring device market share in 2025. The segment’s leading position is due to reduced manual entry errors.
- By end use, the home care segment is projected to witness rapid growth at an 11.82% CAGR. The shift towards patient-centric self-management drives the segment’s leading position.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Is a Blood Glucose Monitoring Device?
A blood glucose monitoring device is a medical device used for measuring glucose concentration in blood or interstitial fluid. It assists diabetic patients in tracking changes in the levels of glucose in their body. Some common types of devices are self-monitoring blood glucose (SMBG) meters and continuous glucose monitoring (CGM) systems. SMBG uses test strips and lancets to monitor glucose. The CGM system makes use of wearable sensors to measure glucose levels throughout the day.
How Blood Glucose Monitoring Devices Work
The blood glucose test kit measures glucose levels in a blood sample or through the glucose sensor. Depending on the use a conventional glucose meter or a continuous glucose monitor (CGM), glucose testing may vary.
Sampling or Placing a Sensor: In the case of a glucose meter, a blood sample is obtained from a finger prick. In the case of the sensor-based glucose meter, a sensor is placed under the skin.
Glucose Detection: The glucose level is measured through a chemical reaction or sensor measurement.
Data Analysis: The measurement of glucose level takes place using a device based on the signal that is obtained. The sensor's performance is measured by MARD accuracy.
Displaying Results: The glucose values are shown on the device display or in the connected app.
Trends Tracking: CGMs monitor glucose trends and calculate the time in range.
Dosage Adjustment: The results allow insulin dosage control and regulate the automated insulin delivery system.
Evaluating Results by Health Care Specialists: The results are evaluated by health care specialists through remote patient monitoring.
Blood Glucose Monitoring Device Market Dynamics
The blood glucose testing equipment market is driven by the increasing use of modern glucose test equipment and a growing population of older adults with diabetes. However, the high cost of the devices and their accessories and concerns about the precision of new technology can be limiting factors.
Driver : Shift Toward Continuous Glucose Monitoring
More people with diabetes are switching from the conventional blood glucose monitoring methods to continuous glucose monitoring. Blood glucose measurement is done for an instant measurement, while the glucose level monitoring system monitors the patient’s glucose levels continuously throughout the day, allowing the patient to monitor their levels during the various activities of their normal routine. The adoption of these systems is also due to the increasing trend of using CGM for patients who require constant monitoring. In some systems, the glucose levels measured can be shared with the health practitioner, allowing them to examine changes between appointments. Their wider acceptance is also contributing to their adoption in diabetes management.
Driver : Increasing Aging Population
The incidence of diabetes among the elderly population continues to increase. Some require glucose monitoring on a regular basis to help them manage their condition. Glucose monitoring through finger sticks becomes tough for elderly individuals with challenges in terms of mobility and vision. One way of overcoming this challenge is through the use of CGM. This requirement has also been acknowledged by the American Diabetes Association in its 2026 Standards of Medical Care in Diabetes. The Association recommends the use of CGM among older people with type 1 diabetes and type 2 diabetes patients using insulin (source: diabetes.org). The broader clinical recommendation could lead healthcare professionals to consider CGM and advanced diabetes devices more often when developing diabetes treatment plans for older patients.
Restraints and Challenges : High Monitoring Costs and Accuracy Concerns
The cost of blood glucose monitoring remains a concern for many patients. Continuous glucose monitoring devices require upfront expenditure on the reader or the transmitter itself. Furthermore, sensors have to be changed after a certain period. In certain regions, insurance programs do not cover the expenses. There is also the issue of reimbursement rules that are different in various healthcare systems. Accuracy is another issue associated with new types of monitoring. Indeed, there might be some discrepancies between sensor measurements and the actual blood glucose levels in certain situations. It may impact medical decision-making if the user uses such measurements to adjust insulin doses.
Opportunity : Rising Demand for Personalized Diabetes Management
The increased popularity of personalized diabetes treatment provides a business opportunity for manufacturers of blood glucose monitors. Different people may have different glucose patterns even though they undergo a similar treatment. Having access to the complete history of glucose levels can help healthcare specialists determine how patients react to their treatment. Thus, it becomes possible to develop blood glucose monitors that provide useful information for personal treatment. Manufacturers can also concentrate on developing better features for data sharing to make it easier to analyze patients' glucose levels during follow-up visits. They could enhance the use of monitoring systems in managing the disease.
Trend : Over-the-Counter (OTC) CGM Expands the Addressable Population
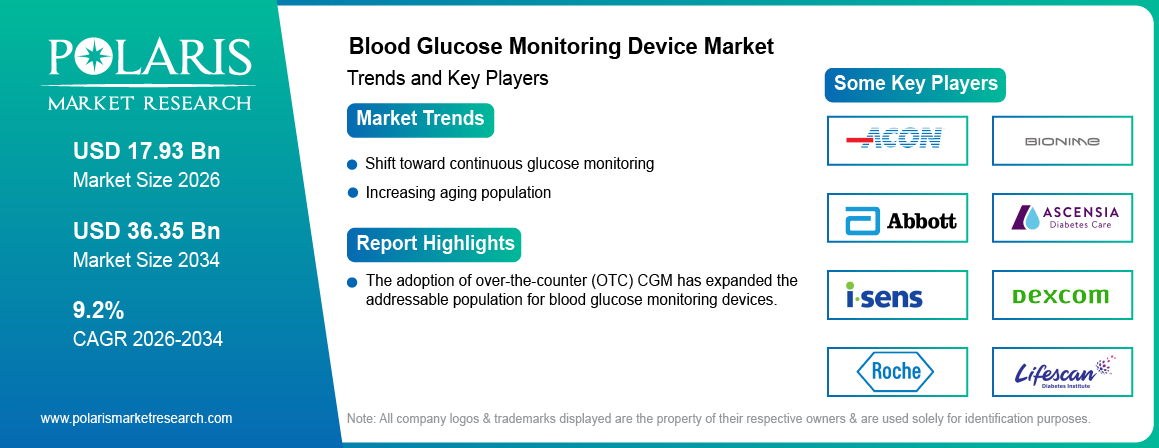
Glucose monitor devices being available over the counter are making CGM technology accessible to more people. An over-the-counter CGM does not require one to first get a prescription before they buy and start using the device. This has expanded the market beyond individuals who have diabetes. Dexcom Stelo is meant for people who do not use insulin. Abbott has come up with Lingo, which is for people who want to learn about the impact of their lifestyles on glucose. The Libre Rio of Abbott is meant for people with type 2 diabetes who do not use insulin.
Though they are used for different purposes, both use the same kind of technology. It is important to know the difference between wellness monitoring and diabetes management in order to identify their purpose. Stelo was also cleared by the FDA in June 2026 for children two years and older who do not use insulin (source: fda.gov). The wider availability of an OTC continuous glucose monitor helps companies reach out to potential customers who could not consider getting one through a prescription.
| Attribute | Dexcom Stelo | Abbott Lingo | Abbott Libre Rio |
| FDA clearance | March 5, 2024; first OTC CGM cleared by FDA | May 29, 2024 | June 7, 2024 |
| Intended users | People aged 2+ who do not use insulin | Adults aged 18+; general wellness monitoring | Adults aged 18+ with type 2 diabetes who do not use insulin |
| Sensor wear | Up to 15 days | Up to 14 days | Up to 15 days |
| U.S. availability | Available since August 2024 | Available since September 2024 | No confirmed retail launch as of November 2026 |
| Low-glucose alarm | No | No | No |
| Indicative price | USD 99 for two sensors | USD 49–54 per sensor | Not announced |
Source: Polaris Market Research Analysis
15-Day Sensors and Longer Wear Time
Sensor longevity is increasingly becoming a significant area of product development in the CGM industry. Conventional sensors need to be changed at the end of a certain period of wear. Increasing this period will lower the frequency with which users change the sensor. In April 2025, Dexcom got FDA approval for its G7 15 Day system. This product is aimed at adult diabetic patients and lasts up to 15 days (source: dexcom.com). Moreover, Abbott has launched its FreeStyle Libre 3 Plus sensor that provides 15 days of wear. The previous sensor by Abbott, namely, FreeStyle Libre 3, allows 14 days of wear. These examples illustrate the efforts of manufacturers to make a longer-lasting product usable without changing the user’s monitoring habits.
Non-Invasive and Needle-Free Glucose Monitoring Pipeline
Non-invasive glucose monitoring wearable technology has received more focus as manufacturers seek an alternative to glucose sensors that are implanted under the skin. Currently, CGM monitors rely on a small sensor filament that measures glucose in the interstitial fluid. There are needle-free technologies that attempt to measure glucose via the skin or biological signs. Afon Technology has developed Glucowear, a wearable glucose monitor that does not pierce the skin in order to measure glucose levels. Know Labs has also been trying to create their own product – KnowU, which uses electromagnetic sensing technology. However, these products are still under development and thus cannot be considered a replacement for the currently available CGM monitors. Biolinq Shine was granted a De Novo clearance by the FDA for its glucose range monitoring system in September 2025. Its technology relies on a minimally invasive intradermal microsensor array rather than a needle-free one. In September 2026, it obtained another clearance through the 510(k) pathway for over-the-counter use. It may offer manufacturers another angle for the glucose-measuring process (source: globenewswire.com). It is, however, essential to have clinical validations and regulatory approvals before any new technology becomes applicable.
AI Impact on the Blood Glucose Monitoring Device Market
AI is impacting how the collected glucose data is being interpreted and utilized in the field of diabetes. The early glucose monitoring tools were focused primarily on collecting glucose levels. Modern tools are starting to employ AI algorithms to recognize patterns and assist users in responding to changes. The impact of artificial intelligence on the market includes the following:
- Glucose prediction: An AI algorithm analyzes historical and current glucose readings in order to predict possible fluctuations in their levels. This will provide users with an opportunity to react in advance to glucose levels moving away from target levels.
- Insulin delivery algorithms: AI-driven tools analyze CGM readings and deliver insulin based on such analysis.
- Individual glucose analysis: Artificial intelligence tools are capable of analyzing individual glucose patterns and recognizing the effect of food intake or exercise on such levels. The obtained insights can be used by healthcare professionals when reviewing the treatment plan.
- Diabetes management: AI-driven analysis of glucose data can be used by clinicians when evaluating the recorded glucose data sent by connected devices.
Segment Analysis
By Product
The self-monitoring devices segment led with an 66.00% blood glucose monitoring device market share in 2025. These devices are utilized extensively among individuals who have diabetes to measure their blood sugar levels. These devices are easy to operate and can be used in regular screening without the need to visit health institutions constantly. Users like such meters because of their relatively lower prices compared to those of continuous glucose monitoring systems. The presence of test strips in pharmacies allows for the convenience of conducting such tests every day. The use of a new strip in each test makes it necessary for users to keep buying more strips. Self-monitoring devices have also been preferred for individuals who require glucose testing occasionally rather than continuously. Their established use in diabetes care continues to support segment revenue.
The continuous glucose monitoring segment is projected to grow at an 15.09% CAGR. The increasing demand for such devices is due to the rising number of diabetic patients searching for convenient methods of measuring their glucose. Compared to conventional meters, CGM devices measure glucose levels on a continuous basis. They eliminate the need for multiple finger pricks during the day. This is especially beneficial for patients who require continuous testing or have fluctuating glucose levels. With advancements in sensor technology, these devices have become compact and more comfortable for the wearer. Another aspect is that many sensors are able to connect with smartphones. This enables patients to monitor their glucose levels without carrying an additional reader. Moreover, the increasing availability of CGM devices among patients who are non-insulin-dependent is also driving the segment’s growth.
| Parameter | Continuous Glucose Monitoring (CGM) | Self-Monitoring Blood Glucose (SMBG) Meters |
| Measurement method | Measures glucose in interstitial fluid through a sensor worn on the body. | Measures glucose in a blood sample obtained through a finger prick. |
| Monitoring frequency | Tracks glucose levels throughout the day and night. | Provides a reading each time the user performs a test. |
| Testing process | Uses a wearable sensor that sends readings to a receiver or smartphone. | Requires a test strip and a blood sample for each reading. |
| Real-time alerts | Many systems provide alerts when glucose levels move above or below set limits. | Generally does not provide automatic alerts between tests. |
| Trend information | Shows changes in glucose levels and helps users identify patterns over time. | Provides individual readings that users can record and compare. |
| User convenience | Reduces the need for repeated finger-prick testing, but sensors need periodic replacement. | Easy to carry and use, though frequent testing requires repeated finger pricks. |
| Cost | Usually has a higher upfront and recurring cost due to sensors and related components. | Generally has a lower device cost, with ongoing expenses for test strips and lancets. |
| Suitable users | Often preferred by people who need frequent or continuous glucose monitoring. | Commonly used by people who need periodic glucose checks. |
Source: Polaris Market Research Analysis
By Connectivity
The Bluetooth-enabled segment accounted for the largest blood glucose monitoring device market share of 50.20% in 2025. These devices make it possible for users to send glucose levels to smartphones or other connected devices. This eliminates the need for manual recording of the test results and also allows users to monitor their previous results. Moreover, users can share their glucose results with their health care practitioners during consultations. Many connected meters are compatible with mobile applications that record glucose levels over time. This is beneficial for individuals who need to keep track of their glucose levels. The increased adoption of smartphones and connected health care solutions has fueled the demand for Bluetooth-enabled glucose meters.
The near field communication (NFC) devices segment is projected to grow at an 12.18% CAGR. These devices make it possible for users to get glucose readings by bringing a compatible monitor or a smartphone close to the sensor. This increases convenience for individuals who do not want to carry another monitoring device along. It also enables users to transfer readings to applications on mobile phones for future reference. The growing use of smartphones in healthcare is driving the interest in this type of connectivity. NFC-based glucose monitoring devices also prove to be helpful for individuals who are required to monitor their readings several times a day. An increase in the usage of monitoring devices is anticipated to drive segment growth.
By End Use
The hospitals & clinics segment accounted for an 41.10% blood glucose monitoring device market share in 2025. These devices are utilized by hospitals to measure blood glucose levels during routine testing and treatment of patients. Monitoring is crucial, especially when patients who have been admitted have complications resulting from diabetes or need their glucose levels monitored during their recovery process. Glucose monitors continue to be used while CGM is gaining popularity in some hospitals. The requirement to monitor patients before and after surgery has contributed to the demand for these devices. Hospitals also need a constant supply of test strips as well as other consumables that are used in testing. The large number of patients treated in such institutions continues to make hospitals a significant end-user segment.
The home care segment is projected to grow at 11.82% CAGR. The majority of people who have diabetes monitor their health condition at home using glucometers in order to measure glucose levels in their blood. The high popularity of glucose meters is due to the convenience of using these devices and the comparatively low cost of glucose meters in comparison with other kinds of advanced technology. The increasing popularity of glucose monitoring is an additional factor that causes people to start using such devices without visiting healthcare facilities. Some people prefer to monitor glucose levels using CGM to control their blood glucose at any time during the day and transmit this information to their doctors. Another growing trend is the increased popularity of monitoring devices available from pharmacies and online resources.
Use Cases and Real-World Applications
| Device / System | Use Case | Real-World Application |
| Dexcom Stelo | Glucose monitoring for adults with type 2 diabetes who do not use insulin. | Allows users to track glucose patterns without a prescription-based CGM system. |
| MiniMed 780G with Simplera Sync | Continuous glucose monitoring with automated insulin delivery. | Uses sensor readings to guide insulin adjustments for people with type 1 diabetes. |
| FreeStyle Libre 2 Plus with Tandem t:slim X2 | CGM integration with an insulin pump. | Shares glucose readings with the pump to support automated insulin delivery. |
| Prevounce Pylo GL1-LTE | Connected glucose monitoring for remote patient monitoring. | Allows glucose readings to be transmitted to healthcare providers for review outside routine visits. |
| Eversense Implantable CGM | Long-term glucose monitoring through an implantable sensor. | Provides continuous readings and alerts to help users review their time in range. |
| CGM Accuracy Assessment | Evaluation of sensor performance using MARD accuracy. | Helps compare CGM readings with reference blood glucose measurements. |
Source: Polaris Market Research Analysis
Regional Insights
North America
The blood glucose monitoring market North America share was 38.00% in 2025. There is an established network for treating diabetes in the region that includes regular glucose level testing as part of treatment. The large number of patients who have diabetes in the U.S. has facilitated the need for monitoring devices. Continuous glucose monitoring systems are becoming increasingly popular as the trend moves towards continuous monitoring. Insurance coverage and reimbursement schemes contribute to making these products accessible. However, these vary depending on the device and the eligibility criteria of the patient. Canada also plays an important role in facilitating demand in the region due to its healthcare programs and availability of diabetes monitoring services. There is a presence of major companies in North America contributing to the development and availability of the technology.
Asia Pacific
Asia Pacific is projected to witness rapid growth at an 12.75% CAGR. The rise in the number of patients who suffer from diabetes is leading to the requirement of routine glucose testing in the region. Countries like China and India have a large patient base, creating a market for low-cost glucose monitoring products. Healthcare is becoming more aware, and more patients are being diagnosed and treated for diabetes. CGM usage is rising, especially in urban areas where advanced healthcare products are widely available. Low-cost glucose monitoring products are also being made available by local vendors, making them accessible to a larger customer base. Improvements in the healthcare infrastructure are likely to fuel the growth in the market.
Europe
Europe accounted for an 27.18% blood glucose monitoring device market share in 2025. There is an already developed health infrastructure in the region, along with heightened diabetes management awareness among the local populations. Countries like Germany, the UK, and France have seen increasing adoption of glucose meters through increased testing as part of diabetes treatment. Insurance coverage for the public healthcare system also increases access to these monitoring devices despite the varying reimbursement policies in each country. There is also rising demand for CGM products due to increased recommendations for continuous monitoring among eligible patients by healthcare professionals. An aging population in a number of European countries is contributing to the demand for routine glucose monitoring. There are also well-developed medical device companies in the region.
Latin America
The Latin America blood glucose monitoring device market is projected to grow at an 10.18% CAGR. With an increase in the number of individuals having diabetes, there is a requirement for routine glucose tests in the region. Brazil and Mexico are important countries for the market owing to the large number of diabetic patients. There is also a rise in health awareness among people, leading to an increase in the number of diagnosed patients with diabetes. Blood glucose meters are widely used as they are less expensive compared to other monitoring systems. The use of CGMs is also gaining popularity in the region. There is likely to be an improvement in the country's healthcare system and, hence, in the accessibility of monitoring products at pharmacies.
Middle East & Africa
The Middle East & Africa blood glucose monitoring device market is projected to grow at an 10.73% CAGR. Due to the increasing incidence of diabetes, the importance of glucose testing in the region is gaining ground. Countries such as Saudi Arabia and the UAE have been making investments in terms of building up their healthcare infrastructure, which has led to easier access to diabetes treatment. Government health programs are increasingly emphasizing the diagnosis and treatment of diabetes. Blood glucose monitors continue to be a preferred tool owing to their relatively lower prices. Nonetheless, the use of CGMs continues to increase gradually for individuals who require constant monitoring. The difficulty of accessing advanced technology in some parts of Africa persists. Better health insurance coverage and product accessibility may help address this gap in the coming years.
Key Players and Competitive Landscape
Several producers are operating in the blood glucose monitoring device market, producing devices in various segments. The top blood glucose monitoring device companies provide both glucose meters and CGMs. The competition among the leading companies mainly concentrates on the usability and accuracy of blood glucose monitoring devices. In addition, some companies strive to develop devices with a longer sensor lifetime. Some manufacturers target the development of affordable devices that will be available for patients who do not have access to advanced devices. Moreover, the production of smartphone-compatible devices plays an important role because many patients check results through connected applications. Cooperation with pharmacies and healthcare providers can help in reaching more patients.
Vendor Positioning
| Company | Main Products | Vendor Positioning |
| On Call glucose meters and test strips | Competes mainly in the affordable blood glucose meter segment, with products for home testing. | |
| Abbott Laboratories | FreeStyle Libre, FreeStyle meters | One of the leading vendors in the market. Its portfolio covers both CGM systems and traditional glucose meters. |
| ARKRAY, Inc. | GLUCOCARD meters and test strips | Established glucose testing manufacturer with a strong background in diagnostic equipment. |
| Ascensia Diabetes Care Holdings AG | CONTOUR glucose meters and test strips | Focuses on self-monitoring products. Its CONTOUR range is its main presence in the market. |
| Bionime Corporation | Rightest glucose meters and test strips | Supplies blood glucose meters and related consumables, with a focus on self-testing products. |
| Dexcom G-series and Stelo | A major CGM specialist. Its business is centered on sensor-based glucose monitoring rather than traditional meters. | |
| F. Hoffmann-La Roche Ltd. | Accu-Chek meters and test strips | Long-established supplier of blood glucose monitoring products, particularly in the self-monitoring segment. |
| i-SENS, Inc. | CareSens meters and test strips | Focuses on blood glucose meters and testing strips. It also supplies products under OEM arrangements. |
| LifeScan, Inc. | OneTouch meters and test strips | Well-known SMBG vendor with an established presence in home glucose testing. |
| Medtronic plc | Guardian and Simplera CGM systems | Competes in CGM, with a particular focus on integration with its insulin pump systems. |
| Nova Biomedical Corporation | StatStrip glucose testing systems | Primarily serves hospitals and clinical laboratories through point-of-care glucose testing products. |
| Senseonics Holdings, Inc. | Eversense CGM systems | Differentiates itself through implantable CGM sensors designed for longer wear periods. |
| Sinocare Inc. | Safe-Accu meters and test strips | Competes in the mass-market glucose monitoring segment, with a focus on affordable products and international distribution. |
| TaiDoc Technology Corporation | Blood glucose meters and connected monitoring devices | Supplies glucose monitoring products and develops devices for OEM and private-label customers. |
| Terumo Corporation | Medisafe glucose monitoring products | Has a presence in blood glucose monitoring as part of its wider medical device business, particularly in Japan. |
Source: Polaris Market Research Analysis
Blood Glucose Monitoring Device Industry Developments
- October 2026: Senseonics initiated the first human study of its investigational Freedom CGM system. The device is being developed to monitor glucose for up to one year without an external component worn on the body. The company is targeting a potential commercial launch in 2028. (source: senseonics.com)
- October 2026: Dexcom announced that its G7 15 Day continuous glucose monitoring system would launch in Canada in November. The system extends sensor wear time and is intended to reduce the frequency of sensor replacement for users. (source: dexcom.com)
- September 2026: Senseonics entered into a partnership with Beta Bionics to integrate its Eversense 365 CGM system with the iLet Bionic Pancreas. The planned integration will combine long-term glucose monitoring with automated insulin delivery. Commercial launch was planned for the fourth quarter of 2026, subject to testing and regulatory requirements. (source: senseonics.com)
Future Outlook
The blood glucose monitoring device market is expected to witness greater adoption of advanced monitoring devices in the upcoming years. There is expected to be an increased demand for CGM devices, driven by a shift from conventional methods of blood glucose monitoring among the patients. The availability of OTC products might attract other new consumers who don't take insulin. There have been advances being made towards the development of sensors with extended wear times and ease of use. This could facilitate frequent glucose tracking. Nonetheless, there will be continued variations in cost and reimbursements, which will impact the adoption in different regions. Affordable devices will still be significant in areas where diabetes care remains limited.
Research Methodology
The blood glucose monitoring device market covers self-monitoring blood glucose (SMBG) devices and continuous glucose monitoring (CGM) devices. The SMBG segment includes meters, testing strips, and lancets. CGM devices are covered through sensors, transmitters & receivers, and insulin pumps. The market is further divided by connectivity, with separate coverage of Bluetooth, Wi-Fi, NFC, and USB-enabled devices. End-use analysis covers hospitals and clinics, home care, and diagnostic centers. The regional assessment includes five major regions and their respective country markets.
Secondary research draws on company annual reports and investor presentations. Product information is checked against regulatory records from sources such as the FDA. Diabetes prevalence data from the IDF, CDC, and WHO helps assess demand across countries. Industry publications are also reviewed for market information.
Primary research includes discussions with industry participants. These inputs help verify product pricing and adoption patterns. Interviews also provide a better understanding of CGM demand and reimbursement conditions.
Market estimates use both top-down and bottom-up approaches. Country-level revenue is assessed using diabetes prevalence and device adoption. Average selling prices are also considered while preparing regional estimates. The figures are cross-checked before finalization.
The analysis is reviewed before publication. New product approvals and company updates are considered during revisions. Differences in market scope can affect comparisons with estimates published by other research firms.
Market Segmentation
By Product Outlook (Revenue, USD Billion, 2021–2034)
- Self-Monitoring Devices
- Meters
- Testing Strips
- Lancets
- Continuous Glucose Monitoring (CGM) Devices
- Sensors
- Transmitter & Receiver
- Insulin Pumps
By Connectivity Outlook (Revenue, USD Billion, 2021–2034)
- Bluetooth-Enabled Devices
- Wi-Fi-Enabled Devices
- Near Field Communication (NFC) Devices
- USB Connectivity Devices
By End Use Outlook (Revenue, USD Billion, 2021–2034)
- Hospitals & Clinics
- Home Care
- Diagnostic Centers
By Regional Outlook (Revenue, USD Billion, 2021–2034)
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of the Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Blood Glucose Monitoring Device Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 16.43 billion |
| Market Size Value in 2026 | USD 17.93 billion |
| Blood Glucose Monitoring Device Market Forecast 2034 | USD 36.35 billion |
| CAGR | 9.2% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Blood Glucose Monitoring Devices Market FAQ's
The global blood glucose monitoring devices market size was valued at USD 16.43 billion in 2025. The market is projected to grow to USD 36.35 billion by 2034.
The market is expected to grow at a CAGR of 9.2% during the blood glucose monitoring devices market forecast 2034 period.
North America leads the market. blood glucose monitoring market North America share was 38.00% in 2025. The region has wider access to diabetes care and advanced monitoring products. The U.S. accounts for a major part of regional demand.
Asia Pacific is expected to record rapid growth at an 12.75% CAGR. The region has a large population living with diabetes, particularly in China and India. Growing awareness of diabetes care is also encouraging more people to check their glucose levels regularly.
The self-monitoring devices segment held the largest share of the market in 2025, accounting for 66.00% of revenue. Blood glucose meters remain a common choice for daily testing. Their relatively low cost and simple operation make them accessible to many people with diabetes.
The home care segment is expected to register the fastest growth at an 11.82% CAGR. More people are checking their glucose levels at home as part of regular diabetes management. Wider availability of monitoring devices through pharmacies and online stores is also making home testing easier.
An over-the-counter (OTC) CGM is a continuous glucose monitoring device that can be purchased without a prescription. It uses a wearable sensor to track glucose levels throughout the day. These products are bringing CGM technology to people who may not need prescription-based monitoring.
CGM sensor life varies by product. Many commonly used sensors last between 10 and 15 days. Users need to replace them once the approved wear period ends. Some implantable systems, such as Eversense 365, offer a much longer monitoring period.
CGM systems track glucose levels through a sensor worn on the body. They provide readings throughout the day. SMBG meters require a finger-prick blood sample for each test. They are generally used for occasional checks rather than continuous monitoring.
A few of the key players include ACON Laboratories, Inc.; Abbott Laboratories; ARKRAY, Inc.; Ascensia Diabetes Care Holdings AG; Bionime Corporation; DexCom, Inc.; F. Hoffmann-La Roche Ltd.; i-SENS, Inc.; LifeScan, Inc.; Medtronic plc; Nova Biomedical Corporation; Senseonics Holdings, Inc.; Sinocare Inc.; TaiDoc Technology Corporation; and Terumo Corporation.
Download Sample Report of Blood Glucose Monitoring Devices Market
Please fill out the form to request a customized copy of the research report.