CAR T-Cell Therapy Market Size, Share & Growth Forecast 2026–2034
REPORT DETAILS
CAR T-Cell Therapy Market Summary
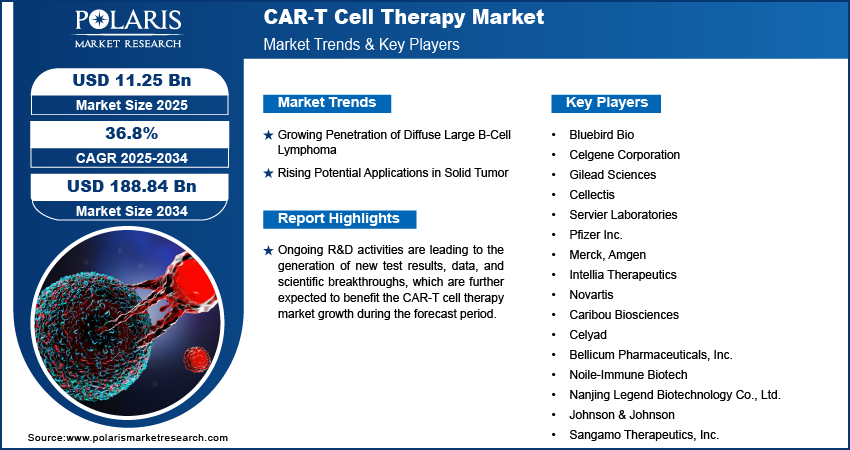
The global car t-cell therapy market was valued at around USD 5.59 billion in 2025 and is projected to reach USD 19.15 billion by 2034, registering a CAGR of 14.66% during the forecast period. Rising adoption of precision medicine, increasing commercialization of advanced cell therapies, and growing investments in cancer immunotherapy are driving growth. Advancement in research studies and technological progressions in cell engineering are helping to facilitate industry growth.
Market Statistics
Key Takeaways
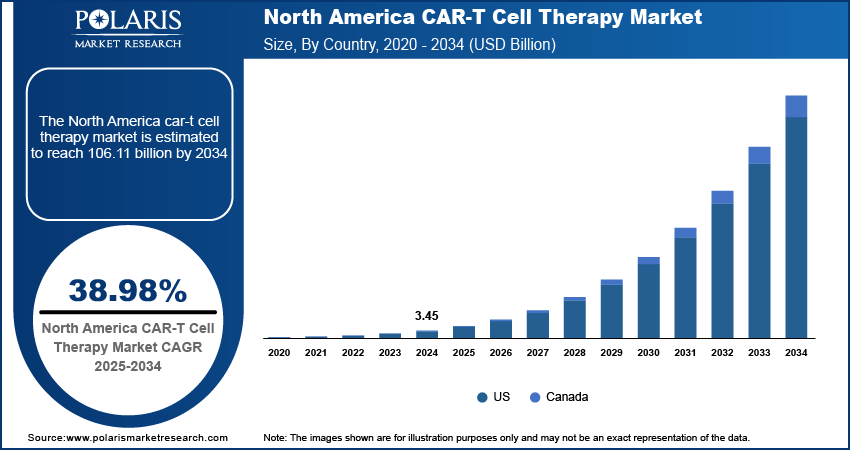
- North America led with a 43.0% CAR-T cell therapy market share in 2025. The regional dominance is attributed to its increasing investments in cancer immunotherapy.
- Asia Pacific is projected to grow at the fastest CAGR of 38.9% during the forecast period. This is due to rising healthcare spending in the region.
- Europe held a 25.0% market share in 2025. Strong healthcare infrastructure and favorable reimbursement frameworks contribute to the regional growth.
- CD19 accounted for the largest target segment with a 49.0% share in 2025 owing to its extensive use in approved therapies.
- Lymphoma held the largest indication segment with a 40.0% share in 2025 due to growing treatment utilization.
- Hospitals dominated the end-user segment with a 45.0% share in 2025 due to higher treatment volumes.
- The cancer centers segment is projected to grow at a CAGR of 37.2% due to rising investments in oncology care facilities.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observation
What Is CAR-T Cell Therapy?
CAR-T cell therapy is a type of cancer treatment that involves modification of the T cells from the body of a cancer patient in order to kill the cancer cells. This treatment method is mainly used for blood cancers like lymphoma, leukemia, and multiple myeloma. It involves the combination of genetic engineering and immunotherapy techniques.
The CAR-T Value Chain
The value chain of the industry consists of raw material vendors, cell engineering companies, contract manufacturers, biotechnology companies, hospitals, cancer centers, and healthcare providers. The patient's cells are harvested, genetically engineered, expanded in laboratories, and then administered via treatment centers.
The process also involves specialized laboratories, quality control, logistics, regulatory authorities, and payers in the healthcare sector. All of these entities facilitate cell harvesting, production, quality control, transport, administration, regulation, payment, and access to patients. The value chain links the process of developing and producing the CAR-T treatments to their application. It also facilitates the movement of patient-derived cells at each stage.
How Does CAR-T Cell Therapy Work?
Collection of T-cells: The patient goes through a process referred to as leukapheresis for harvesting T-cells from the blood stream.
Modification of T-cells: The harvested T-cells go through modification in the laboratory to form chimeric antigen receptors (CARs).
Identifying the cancer cell: The CARs allow the modified T-cells to recognize cancer cell antigens.
Proliferation of T-cells: The modified T-cells are cultured in laboratories to multiply in number.
Initial chemotherapy: The following stage involves receiving chemotherapy before the introduction of the CAR-T cells into the body to prepare it for the modified T-cells.
Introduction of the CAR-T cells: The modified T-cells get introduced into the patient’s body.
Elimination of the cancer cells: The CAR-T cells target cancer cells and destroy them by releasing proteins that kill the cancer cells.
Persistence of cells in the body: Some of the CAR-T cells remain as memory cells in the body for recognition of the cancer target.
CAR-T Therapy vs. Chemotherapy vs. Conventional Immunotherapy
| Feature | CAR-T Therapy | Chemotherapy | Conventional Immunotherapy |
| Personalization | High. Patient-specific engineered T cells | Low. Standardized treatment | Moderate. Selected based on tumor biomarkers |
| Target Specificity | High. Precisely targets cancer antigens | Low. Affects both cancerous and healthy rapidly dividing cells | Moderate. Enhances immune response against cancer |
| Immune System Activation | Direct. Engineered T cells actively eliminate cancer cells | Limited. Primarily destroys cancer cells without immune activation | Moderate. Stimulates the body's natural immune response |
| Long-Term Response | Potentially durable with immune memory | Variable and often temporary | Variable depending on therapy and cancer type |
| Manufacturing Complexity | High. Requires individualized cell collection and engineering | Low. Mass-produced pharmaceutical drugs | Moderate. Biologics with standardized manufacturing |
| Treatment Cost | High. Personalized manufacturing and specialized care | Moderate. Comparatively lower treatment costs | High. Expensive biologic therapies and repeated dosing |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
Autologous vs. Allogeneic CAR-T Therapy
Treatment options using CAR-T cell-based technology may be grouped based on where the T cells originate from. Autologous CAR-T treatment involves the use of the patient’s own T cells, whereas allogeneic CAR-T treatment involves the use of T cells from a healthy donor. The two treatment options differ in manufacturing, availability, and scalability.
| Feature | Autologous CAR-T | Allogeneic CAR-T |
| Cell source | Patient’s own T cells | Healthy donor T cells |
| Manufacturing | Patient-specific production | Standardized, batch-based production |
| Availability | Requires time for cell collection and manufacturing | Potentially available as an off-the-shelf treatment |
| Scalability | More difficult to scale | Greater potential for large-scale production |
| Treatment time | Longer due to individualized manufacturing | Potentially shorter due to ready-to-use products |
| Manufacturing cost | Generally higher | Potentially lower with larger-scale production |
| Key challenge | Complex logistics and variable cell quality | Risk of immune rejection and graft-versus-host disease |
| Current development | Established in several approved therapies | Active area of research and clinical development |
CAR-T Cell Therapy Market Dynamics
Driver: Precision Medicine and Personalized Immuno-Oncology Therapies Fueling CAR T-Cell Demand
Increased adoption of precision medicine has created high demand for CAR T-cell therapy in the healthcare sector. Healthcare providers have been working towards personalizing treatments in order to allow patients to improve their conditions and avoid recurrence of diseases. An increasing number of approvals and clinical trials of cell therapies has led to the adoption of such treatments. In June 2026, CARsgen Therapeutics received approval in China for its CAR-T therapy, satri-cel. CARsgen Therapeutics stated the approval is for patients with CLDN18.2-positive, HER2-negative gastric or gastroesophageal junction cancer. The approval expanded CAR-T therapy into solid tumors. It highlights the growing role of biomarker-based patient selection in treatment (source: carsgen.com).
Driver: Cell Engineering Innovations Enhancing CAR T-Cell Efficacy and Production Scalability
Developments in the field of cell engineering technologies have led to increasing efficacy of treatment as well as greater efficiencies in production processes. There have been significant developments in the area of CAR-T cell therapies that possess better targeting abilities and higher safety levels. In June 2026, VectorBuilder collaborated with MaxCyte to improve cell engineering technologies for clinical purposes using MiniVec gene delivery systems along with MaxCyte's electroporation technologies. Research and development have broadened the spectrum of diseases that can be treated (source: vectorbuilder.com).
Restraints: High Treatment Costs and Manufacturing Complexity Limiting Broader Market Access
Treatment cost remains among the top barriers to growth. This is due to the fact that CAR T-cell treatment entails complex production techniques, unique healthcare infrastructure and monitoring of patients throughout the process. The costs of treatment and difficulty in accessibility have become issues in some parts of the world due to lack of reimbursement and long manufacturing time frames.
Opportunity: Emerging Applications in Autoimmune Diseases and Solid Tumors Creating New Growth Avenues
Growth of regenerative medicine and cellular therapy technology has created many growth opportunities. Companies are now investing more in next-generation CAR T-cell platforms and exploring their use beyond hematological cancers. Research in autoimmune disorders and solid tumors has widened opportunities. Sjögren’s Foundation stated that over 50 million Americans are affected by autoimmune diseases, with global incidence increasing by 19.1% annually, while rheumatological conditions such as Sjögren’s syndrome and lupus are rising by 7.1% per year (source: sjogrens.org). Strong growth is expected due to precision medicine, regenerative therapies, and organoid commercialization.
Driver Impact
| Market Driver | Est. CAGR Impact | Geographic Relevance | Impact Timeline |
| Precision medicine adoption | +2.2% | North America, Europe, Asia Pacific | Medium to long term |
| Cell engineering advancements | +1.9% | US, Europe, China, Japan | Short to medium term |
| Manufacturing capacity expansion | +1.6% | US, Europe, China, South Korea | Medium term |
| Strategic partnerships and collaborations | +1.2% | Global | Short to medium term |
| Regulatory approvals and reimbursement support | +1.0% | US, EU, UK, Japan | Medium to long term |
* Indicative estimates based on market context and analyst judgment. Figures reflect relative driver weight, not additive CAGR contributions. Source: Polaris Market Research Analysis.
CAR-T Cell Therapy Market Trends
Rise of Allogeneic ("Off-the-Shelf") CAR-T
The development of allogeneic (or “off-the-shelf”) CAR-T therapies is emerging as one of the market's most significant trends. Autologous therapies use a patient's own T cells. However, allogeneic CAR-T products are manufactured from healthy donor cells. They allow standardized manufacturing and faster treatment availability. These medications provide better scalability. These treatments can lower manufacturing costs and reduce turnaround time. Thus, these benefits make them a key focus of research and commercial investment.
Expansion into Non-Oncology & Autoimmune Indications
CAR-T therapy has primarily been developed for hematologic cancers. Its application is increasingly spreading to non-oncologic indications. Researchers are exploring applications of CAR-T treatment in autoimmune diseases. The diseases may include systemic lupus erythematosus, multiple sclerosis, and rheumatoid arthritis. They are emphasizing the use of CAR-T treatment for organ transplantation and fibrotic disorders. Positive early clinical outcomes and continued innovation in immune cell engineering are expected to broaden the therapeutic scope of CAR-T technology. Thus, the increasing role of CAR-T therapy in treating non-oncology indications is emerging as a key market trend.
In Vivo CAR-T & Next-Generation Manufacturing
In vivo CAR-T therapy is increasingly being viewed as a possible way to make CAR-T creation easier. Though traditional CAR-T treatment involves the removal of T-cells and alteration of those cells outside the body, in vivo approaches involve direct introduction of necessary instructions to the T-cells. This way, it may reduce the need for production and speed up the process. Researchers are also focused on creating modern CAR-T production techniques involving automation of cell processing, new gene delivery approaches, and closed-system production. The new approaches for CAR-T treatment can help in reducing production challenges and standardizing production, hence enabling increased accessibility to CAR-T treatments.
Dual/Multi-Antigen & CRISPR-Engineered CAR-T
Advances in CRISPR CAR-T and dual- and multi-antigen CAR-T therapies are gaining attention as organizations seek to improve therapy accuracy and overcome tumor resistance. The dual/multi antigen strategies allow the modified T cells to attack several targets of cancer, minimizing the chance of tumor escaping the therapy. CRISPR might be useful for modifying T cells and improving their properties. These technologies are being researched to improve the persistence, specificity, and safety of CAR-T cells. Future research is likely to result in better CAR-T therapies.
AI’s Impact on the CAR-T Cell Therapy Market
-
AI-based target discovery is really important for finding cancer antigens and biomarkers. It drives the creation of advanced CAR-T treatments.
-
Machine learning (ML) advances CAR-T design. It predicts how the receptors perform. ML enhances efficacy while minimizing off-target reactions.
-
AI is used to improve patient selection. It analyzes genomic, clinical, and biomarker data. This information helps determine who will benefit from the treatment. AI is used to improve treatment outcomes.
-
AI analytics makes the process of cell handling and quality control easier. It saves time and increases consistency.
-
Potential adverse events are predicted using AI-based models. It allows for timely interventions.
-
AI is used in recruiting patients, optimizing protocols, and analyzing real-time data. This speeds up the whole process of conducting the trials.
Source: Polaris Market Research Analysis
CAR-T Cell Therapy Market Segmentation Analysis
The report provides a comprehensive analysis by target antigen, type of therapy, technology, manufacturing method, disease indication, end user, and product to identify key revenue-generating and high-growth segments.
By Target Antigen
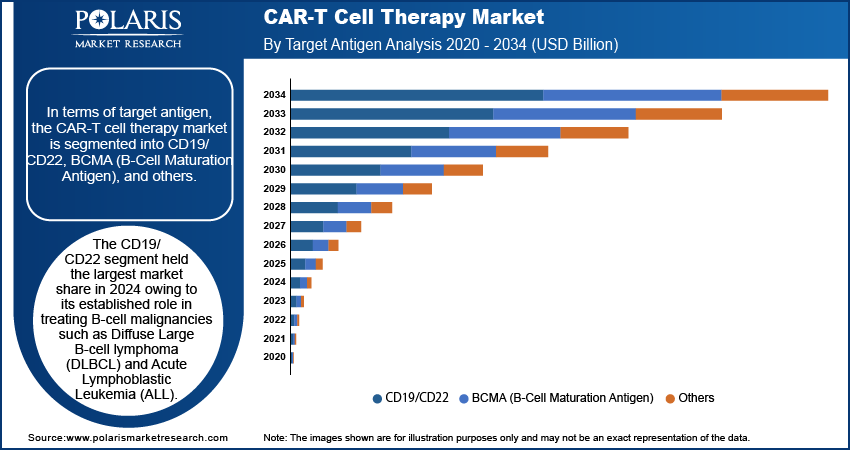
The CD19 segment dominated with 49.0% in 2025 owing to its widespread use in approved CAR T-cell therapies for lymphoma and leukemia. In April 2026, Allogene Therapeutics revealed pre-clinical results suggesting that ALLO-329 is a dual-targeted CAR-T cell therapy targeting CD19/CD70 for the treatment of autoimmune disorders (source: ir.allogene.com). Excellent clinical performance, extensive commercialization, and rising adoption are expected to drive segment growth. Also, the rising adoption of CD19-based therapeutics in various applications has been fuelling the growth of this segment. The research and development of next-generation CD19-based therapies is expected to further strengthen the segment’s market position.
The BCMA segment is projected to grow at the fastest CAGR of 37.8% during the forecast period. Increasing use of BCMA-targeted therapies for multiple myeloma and growing investments in clinical development activities are supporting segment expansion. There is ongoing research aimed at developing faster manufacturing processes for BCMA-targeted CAR-T treatments as well as enhancing their durability and availability. Some recent clinical trials have included rapid-manufactured and allogeneic treatment approaches that could prove useful in reducing treatment time and increasing availability. Moreover, BCMA CAR-T treatments are being studied in earlier treatment settings as well as in combination with additional targets. This is expected to widen the application of BCMA-targeted treatments and drive the BCMA CAR-T market growth.
| Target Antigen | Market / Clinical Focus |
| CD19 | Established target widely used in CAR-T therapies for B-cell leukemia and lymphoma. |
| BCMA | Major target for multiple myeloma and a key area of CAR-T development. |
| CD22 | Being studied as an alternative or complementary target to CD19 for B-cell malignancies, including leukemia and lymphoma. |
| GD2 | Emerging target for solid tumors and cancers such as neuroblastoma and certain brain tumors. |
| HER2 | Emerging target being investigated for CAR-T applications across HER2-positive solid tumors. |
| GPC3 | Emerging solid-tumor target, particularly for liver and other GPC3-positive cancers. Clinical studies continue to evaluate GPC3-targeted CAR-T approaches. |
| Other Targets | Includes additional tumor antigens under preclinical and clinical investigation for broader CAR-T applications. |
By Type of Therapy
The autologous segment led the market in 2025. The autologous CAR-T treatment method makes use of T cells of the patient that are harvested, genetically engineered, expanded, and finally administered back to the patient. This segment benefits from the widespread application of autologous CAR-T products within leukemia, lymphoma, and multiple myeloma. The approval of new therapeutic methods, advances in manufacturing processes, and wider treatment use will support segment growth. Clinical research is increasing to improve treatment effectiveness, shorten manufacturing time, and expand the use of autologous CAR-T treatments across different cancers.
The allogeneic segment is projected to witness the fastest growth. This segment is becoming increasingly important since it has the capability to produce ready-to-use CAR-T treatments through batch production that will then be accessible whenever necessary. Advancements in gene editing, donor cell engineering, and enhanced manufacturing capabilities are also boosting the progress of this segment. These innovations are expected to ensure consistency in the products produced.
By Technology
The viral vectors segment accounted for the largest market share in 2025. Lentiviral vectors and retroviral vectors are some of the types of viral vectors that are popularly utilized to deliver the CAR-encoding genes into the T cells while manufacturing CAR-T therapies. The usage of the vectors in approved CAR-T treatments supports their strong market position. Advances in technology and manufacturing are making the vectors safer and more efficient. The increase in the production of CAR-T treatments and research on new cell-based treatments is anticipated to drive the demand for viral vectors. The viral segment is also benefiting from manufacturing practices and regulatory experience with viral vector-based CAR-T treatments.
The non-viral vectors segment is projected to witness the fastest growth. Non-viral delivery techniques involve the use of different technologies like transposons, mRNA, plasmid DNA, and gene editing techniques that can help deliver CAR genes to the T-cells without the need for using any viral vectors. Such techniques have gained popularity owing to the potential of simplifying manufacturing processes, as well as reducing costs involved in production. New developments in technologies like transposon-based systems and CRISPR gene editing will facilitate the creation of the next generation of CAR-T drugs. The future scalability of these technologies will drive segment growth.
| Platform | Process | Benefit | Limitation |
| Viral vectors (lentiviral/retroviral) | Integration of CAR gene into T-cell genome | High transduction rate and stable long-term expression | Complex manufacturing process, site of integration monitoring |
| Non-viral vectors (CRISPR/Cas9, transposons, mRNA electroporation) | Gene editing or non-integrative gene delivery | Lower costs and fast generation times (CRISPR), precise site of insertion (CRISPR) | Lower efficiency compared to viral methods, although growing |
| Armored CAR-T | Modification of T-cell to have extra cytokine/co-stimulatory signaling | Increased survival in unfavorable tumor microenvironment | Additional engineering process, increased complexity |
| Multiple antigen recognition | CAR-T cells designed to recognize multiple antigens | Decreased chance of antigen escape | More complex design and validation |
By Manufacturing Method
The centralized segment accounted for the largest market share in 2025. The centralized manufacturing approach is predominantly used for CAR-T therapy due to the presence of the manufacturing facility with quality control systems in place. This approach makes standardization of production and quality assurance possible. This approach also allows for the employment of infrastructure, equipment, and staff trained in cell handling. The presence of such infrastructure and expertise in centralized manufacturing has contributed to its strong market position.
The in vivo segment is projected to witness the fastest growth. In vivo CAR-T therapies can create CAR-T cells within the body itself, thereby minimizing the necessity of harvesting the cells from the body, modifying them in a lab environment, expanding them, and then re-administering them into the body. Research in the fields of viral vectors, lipid nanoparticles, and other such methods is contributing to the development of in vivo CAR-T therapies. Clinical trials are also now extending into the field of hematologic malignancies, solid tumors, and autoimmune disorders. This development will help increase scalability and availability, resulting in increased growth prospects in the coming years.
By Disease Indication
The lymphoma segment dominated with a 40.0% share in 2025 due to increasing use of approved CAR T-cell therapies for relapsed and refractory lymphoma patients. Growing treatment success rates and expanding patient eligibility continue to support segment growth. The potential use of CAR-T cells is also being studied in a number of solid cancers, such as glioblastoma, pancreatic cancer, hepatocellular carcinoma, colorectal cancer, lung cancer, breast cancer, ovarian cancer, and prostate cancer. Research is ongoing regarding various targets and ways of treating solid cancers.
The leukemia segment is projected to grow at the fastest CAGR of 36.0% during the forecast period. Rising adoption of advanced immunotherapies and increasing clinical research activities are contributing to segment expansion. Simultaneously, increasing clinical studies on solid tumors are generating new opportunities for the use of CAR-T therapy. Research has been done to identify potential targets such as HER2, GPC3, GD2, mesothelin, PSMA, and EGFR for cancers such as pancreatic cancer, liver cancer, colorectal cancer, prostate cancer, lung cancer, ovarian cancer, and breast cancer. These advances can expand the use of CAR-T therapy to non-hematological cancers.
By End User
The hospitals segment dominated with a 45.0% share in 2025 owing to the availability of specialized treatment infrastructure and skilled healthcare professionals. Increasing patient admissions and treatment volumes are supporting segment growth. Hospitals are also capable of handling the intensive monitoring and support necessary for CAR-T treatment. Their multidisciplinary teams can react to any complications as well as offer subsequent treatment. The presence of cellular therapy units, oncology centers, and critical care departments also facilitates the administration of CAR-T treatment in hospitals.
The cancer centers segment is projected to grow at the fastest CAGR of 37.2% during the forecast period. Rising investments in oncology care facilities and growing availability of advanced treatment services are driving segment expansion. Specialized cellular therapy programs and clinical research activities are being developed by cancer centers in increasing numbers. They can enable patients' access to novel CAR-T therapies and clinical trials and ensure collaboration between oncologists and other healthcare practitioners. The development of such specialized cancer treatment facilities will promote the use of CAR-T therapy and the growth of the segment.
By Product
The Yescarta segment accounted for the largest market share in 2025. Yescarta (axicabtagene ciloleucel) is a CAR-T treatment targeting CD19 that can be used for treating a variety of large B-cell lymphomas and follicular lymphomas. The existing commercial application and wide treatment scope of the drug have led to high adoption. In 2025, the sales of Yescarta reached around USD 1.50 billion worldwide, indicating its leading position in the CAR-T therapy market (source: gilead.com). The use of Yescarta in recurrent or refractory lymphoma, along with clinical trials, can drive segment growth.
The Carvykti segment is projected to witness strong growth. Carvykti (ciltacabtagene autoleucel) is a BCMA-based CAR-T therapy that treats adult patients suffering from relapsed and refractory multiple myeloma. Increasing adoption of the therapy in prior lines of treatment has resulted in a greater number of patients being eligible for the treatment. Demand for BCMA-based therapies and ongoing clinical trials for multiple myeloma are factors driving the segment. Increased availability of treatment options and growing usage of CAR-T therapy in multiple myeloma will drive the growth of Carvykti in the forecast period.
| Product (INN) | Manufacturer | Target | Key Indication(s) |
| Kymriah (tisagenlecleucel) | Novartis Pharmaceuticals Corporation | CD19 | B-cell precursor ALL in patients up to 25 years; relapsed/refractory large B-cell lymphoma; relapsed/refractory follicular lymphoma after 2 or more lines of systemic therapy |
| Yescarta (axicabtagene ciloleucel) | Kite Pharma, Inc. | CD19 | Large B-cell lymphoma, including DLBCL, primary mediastinal large B-cell lymphoma, high-grade B-cell lymphoma, and DLBCL arising from follicular lymphoma; relapsed/refractory follicular lymphoma after 2 or more lines |
| Tecartus (brexucabtagene autoleucel) | Kite Pharma, Inc. | CD19 | Relapsed/refractory mantle cell lymphoma; relapsed/refractory B-cell precursor ALL in adults |
| Breyanzi (lisocabtagene maraleucel) | Juno Therapeutics, Inc., a Bristol Myers Squibb company | CD19 | Large B-cell lymphoma; follicular lymphoma; mantle cell lymphoma; relapsed/refractory chronic lymphocytic leukemia or small lymphocytic lymphoma; marginal zone lymphoma |
| Abecma (idecabtagene vicleucel) | Celgene Corporation, a Bristol-Myers Squibb company | BCMA | Relapsed/refractory multiple myeloma after 2 or more prior lines of therapy, including an immunomodulatory agent, proteasome inhibitor, and anti-CD38 monoclonal antibody |
| Carvykti (ciltacabtagene autoleucel) | Janssen Biotech, Inc. | BCMA | Relapsed/refractory multiple myeloma in adults who have received at least 1 prior line of therapy, including a proteasome inhibitor and immunomodulatory agent, and are refractory to lenalidomide |
| Aucatzyl (obecabtagene autoleucel) | Autolus Limited | CD19 | Relapsed/refractory B-cell precursor ALL in adults |
Segment Summary Table
| Segment | Category | 2025 Status | Forecast CAGR | Key Driver |
| CD19 | Target Antigen | Largest Share | Moderate | Approved therapies |
| BCMA | Target Antigen | Fastest Growing | 37.8% | Multiple myeloma treatment |
| Autologous | Type of Therapy | Largest Share | Moderate | Established treatment approach |
| Allogeneic | Type of Therapy | Fastest Growing | High | Off-the-shelf potential |
| Viral | Technology | Largest Share | Moderate | Established vector use |
| Non-viral | Technology | Fastest Growing | High | Simplified manufacturing |
| Centralized | Manufacturing Method | Largest Share | Moderate | Standardized production |
| In Vivo | Manufacturing Method | Fastest Growing | High | Scalable treatment |
| Lymphoma | Disease Indication | Largest Share | Moderate | Higher patient adoption |
| Leukemia | Disease Indication | Fastest Growing | 36.0% | Clinical research expansion |
| Hospitals | End User | Largest Share | Moderate | Treatment infrastructure |
| Cancer Centers | End User | Fastest Growing | 37.2% | Oncology investments |
| Yescarta | Product | Largest Share | Moderate | Established use in lymphoma |
| Carvykti | Product | Strong Growth | High | Multiple myeloma treatment |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
Real-World Applications of CAR-T Cell Therapy
The CAR-T cell treatment approach can be mostly applied to certain types of blood cancers, where available treatment options target diseases like leukemia, lymphoma, and multiple myeloma. Innovations and advances in treatment approaches are broadening the scope of therapeutic options. The examples below illustrate how T-cell therapies are already being used.
| Application | Real-World Example |
| Treatment of relapsed leukemia | CD19-targeted CAR-T therapies, such as Kymriah (tisagenlecleucel), demonstrated durable remission in relapsed or refractory B-cell acute lymphoblastic leukemia (B-ALL). |
| Diffuse large B-cell lymphoma (DLBCL) | Approved CAR-T therapies, including Yescarta (axicabtagene ciloleucel) and Breyanzi (lisocabtagene maraleucel), are widely used for relapsed or refractory DLBCL after multiple prior therapies. |
| Multiple myeloma therapy | BCMA-targeted CAR-T therapies, such as Carvykti (ciltacabtagene autoleucel) and Abecma (idecabtagene vicleucel), provide treatment options for heavily pretreated multiple myeloma patients. |
| Follicular lymphoma treatment | Yescarta has been approved for relapsed or refractory follicular lymphoma. It offers high response rates in patients who have exhausted standard therapies. |
| Treatment of mantle cell lymphoma | Tecartus (brexucabtagene autoleucel) is indicated in eligible patients having relapsed or refractory mantle cell lymphoma. |
| B-cell malignancies | Aucatzyl (obecabtagene autoleucel) is a CD19-directed CAR-T drug indicated for certain adults having relapsed or refractory B-cell precursor acute lymphoblastic leukemia. |
| Uses in solid tumors | Tecelra (afamitresgene autoleucel) is an engineered T-cell therapy used for certain patients suffering from unresectable or metastatic synovial sarcoma. |
Solid Tumor CAR-T: Emerging Applications
The use of CAR-T cells in cancer treatment is now extending from blood malignancies to solid tumors. Several solid tumor CAR-T therapy options have been developed to address concerns such as tumor heterogeneity and the tumor microenvironment. The latest advancement in T cell-based therapy for solid tumors is Tecelra (afamitresgene autoleucel), approved for selected patients with unresectable or metastatic synovial sarcoma. Another novel therapeutic approach targeting solid tumors, particularly gastric and pancreatic cancers, is Satri-cel (CT041). Further research could enable broader use of CAR-T and other engineered T-cell treatments for solid tumors.
Safety Considerations in CAR-T Therapy
Following are a few adverse effects of CAR-T Cell therapy. These reactions require close monitoring and prompt supportive care.
- Cytokine Release Syndrome (CRS): CRS is the most common adverse event. It is caused by rapid immune activation. It leads to fever, hypotension, and systemic inflammation.
- Neurological Toxicities (ICANS): Confusion and headaches may occur. Other symptoms may include seizures and speech problems. Encephalopathy is also a symptom.
- Immune-Related Adverse Events: Overactivity of immune may lead to inflammation, infection, and prolonged cytopenias.
- B-cell Aplasia and Hypogammaglobulinemia: Treatment that targets CD19 destroys healthy B cells and therefore requires immunoglobulin supplementation in some patients.
- Tumor Lysis Syndrome (TLS): Rapid removal of cancer cells leads to metabolic abnormalities.
CAR-T Cell Therapy Market Regional Insights and Country Outlook
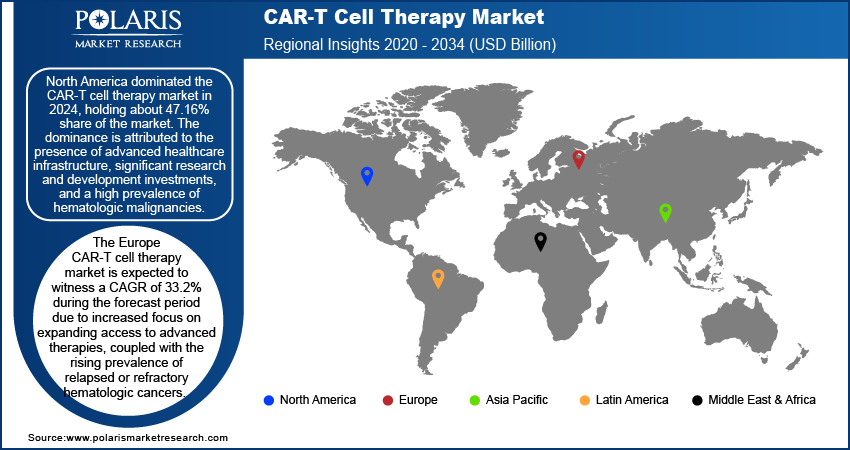
Europe CAR T-Cell Therapy Market Size and Share
Europe held a 25.0% share in 2025 due to strong healthcare infrastructure, favorable reimbursement frameworks, and increasing adoption of advanced cancer therapies. Germany, France, the UK, Italy, Spain, and the Netherlands continue to invest in cell therapy development and oncology research. In February 2026, Lyell Immunopharma disclosed positive Phase 1/2 study data for ronde-cel, a dual-targeted CAR-T cell therapy, in patients with relapsed or refractory large B-cell lymphoma. Increasing activity in clinical trials and supportive regulations have been fueling regional growth.
North America CAR T-Cell Therapy Market Analysis
North America held a 43.0% share of the market in 2025, owing to its ability in biotechnologies as well as increasing investments in cancer immunotherapy. The US leads the region in terms of share due to rising acceptance, approval by regulatory bodies, and growing research activities. In March 2026, Caribou Biosciences received an RMAT designation from the FDA for CB-011, which is its allogeneic anti-BCMA CAR-T therapy for relapse or refractory multiple myeloma (Source: investor.cariboubio.com).
Asia Pacific CAR T-Cell Therapy Market Growth Rate and Forecast
Asia Pacific is projected to grow at the fastest CAGR of 38.9% during the forecast period due to rising healthcare spending and increasing investments in biotechnology innovation. China, Japan, South Korea, India, and Australia are increasing their clinical trial activities and manufacturing capacity. In June 2025, Jiahui International Cancer Center started providing satri-cel (CT041), the first approved CAR-T treatment for solid tumors in the world, to treat advanced gastric and pancreatic cancers. Increasing awareness about advanced cancer treatments is aiding regional growth.
Latin America CAR T-Cell Therapy Market Size and Share
Latin America has been experiencing slow but consistent growth owing to increasing investments in healthcare and improvements in accessing better treatments. Countries such as Brazil, Mexico, and Argentina are setting up infrastructure for cancer treatment facilities as well as developing biotechnologies. Increasing awareness and initiatives for modernizing healthcare have resulted in growth.
Middle East & Africa CAR T-Cell Therapy Market Size and Share
The market in the Middle East & Africa has been experiencing steady growth due to rising investments in healthcare and oncology facilities. Countries such as Saudi Arabia, UAE, Israel, South Africa, and Egypt have been making efforts towards expanding access to advanced treatments. In April 2025, Burjeel Holdings joined hands with Caring Cross to produce CAR-T treatments locally in the MENA region in order to reduce treatment costs by 90%(Source: caringcross.org). The growing emphasis on specialized cancer care has supported this growth.
Regional Market Trends
The regional growth of the CAR-T cell therapy market is driven by factors such as access to treatment, healthcare infrastructure, clinical studies, reimbursement, and regulation. North America dominates the market, while Asia Pacific holds potential for the fastest growth.
| Region | Market Trend |
| North America | Dominates the market due to strong R&D investments, advanced healthcare infrastructure, favorable reimbursement, and early regulatory approvals for CAR-T therapies. |
| Europe | Expanding access through increasing adoption of advanced cell therapies, supportive regulatory initiatives, and growing clinical research activities. |
| Asia Pacific | Asia Pacific is emerging as a major innovation and manufacturing hub. This is fueled by rising biotechnology investments and expanding clinical trials. Also, increasing healthcare spending boosts the regional CAR-T cell therapy market growth. |
| China | China leads in CAR-T clinical development and commercialization across Asia Pacific. The market growth is supported by a robust biotechnology ecosystem and numerous clinical trials. Domestic product approvals also boost the growth. |
| India | Witnessing growing investments in cell therapy infrastructure, local CAR-T development programs, academic collaborations, and efforts to improve treatment affordability. |
Regulatory Heatmap
Regulatory requirements are key considerations in developing, approving, manufacturing, and commercializing CAR-T therapies. Regulatory methods differ by market depending on the regulatory structure, manufacturing guidelines, clinical guidelines, and long-term safety considerations for cell therapy products.
| Country | Policy Environment | Key Regulations | Market Implication | Trend |
| US | Favorable | FDA Cell Therapy Framework | Supports commercialization | Expanding |
| Canada | Neutral | Federal Healthcare Guidelines | Supports controlled adoption | Developing |
| Germany | Favorable | EMA Cell Therapy Regulations | Encourages adoption | Expanding |
| UK | Neutral | MHRA Regulatory Framework | Creates entry requirements | Stable |
| China | Favorable | Biotechnology Development Policies | Supports manufacturing expansion | Expanding |
| Japan | Favorable | Regenerative Medicine Regulations | Supports innovation | Stable |
| India | Developing | Biotechnology Promotion Programs | Long-term growth opportunity | Developing |
| Australia | Neutral | Clinical Research Framework | Supports selective deployment | Developing |
Source: Polaris Market Research Analysis
Technology and Innovation Landscape
CAR T-cell therapy is advancing rapidly through innovations in automation, artificial intelligence, advanced analytics, platform integration, and manufacturing optimization, improving production efficiency, enhancing product quality, and reducing commercialization timelines.
| Technology | Adoption Stage | Key Development | Market Impact |
| Automated Manufacturing | Growing Deployment | Process optimization | Reduces production time |
| Advanced Gene Editing | Early Commercial | Improved targeting | Enhances effectiveness |
| AI-Based Analytics | Growing Deployment | Treatment optimization | Improves patient outcomes |
| Digital Monitoring | Mainstream Adoption | Real-time patient tracking | Improves safety |
| Manufacturing Scale-Up | Early Commercial | Capacity expansion | Improves availability |
Source: Polaris Market Research Analysis
Buyer Use Cases and Market Entry Barriers
The CAR-T cell therapy market offers prospects to pharmaceutical companies, biotech companies, healthcare organizations, investors, and the government. Buyers leverage market data to evaluate treatment demand, technology development, investment, and access needs. However, factors such as expensive manufacturing processes, complicated logistics, specialized facilities, regulations, and reimbursement may present challenges to market entry.
| Buyer / Investor Type | Primary Use Case | Key Insight Sought | Decision Horizon |
| Pharmaceutical Companies | Pipeline expansion | Clinical potential and commercialization opportunities | 3 to 7 years |
| Biotechnology Companies | Product development | Technology advancement and market demand | 2 to 5 years |
| Hospitals and Cancer Centers | Treatment adoption | Clinical outcomes and patient accessibility | 1 to 3 years |
| Institutional Investors | Investment evaluation | Growth potential and competitive landscape | 3 to 7 years |
| Government and Healthcare Agencies | Healthcare planning | Regulatory compliance and treatment access | 3 to 7 years |
Source: Polaris Market Research Analysis
Competitive Landscape and Key Players
The market is moderately fragmented due to the presence of biotechnology companies, pharmaceutical manufacturers, and specialized cell therapy developers. Competitiveness is measured using clinical performance, innovations in products, manufacturing skills, and regulatory clearances. The companies are adopting strategic alliances, expanding capacity, mergers and acquisitions, and developing new products to improve their position.
The leading CAR-T cell therapy companies include Bristol Myers Squibb, Gilead Sciences, Novartis AG, Johnson & Johnson, Legend Biotech Corporation, Autolus Therapeutics plc, Cellectis S.A., Fate Therapeutics, Inc., Cabaletta Bio, Inc., Precision BioSciences, Inc., Sana Biotechnology, Inc., and other participants.
Competitive Positioning
| Company | Est. Market Position | Primary Focus | Geographic Focus |
| Top 5 | Oncology portfolio | Global | |
| Gilead Sciences, Inc. | Top 5 | Commercial scale | Global |
| Johnson & Johnson | Top 10 | Research capability | Global |
| Legend Biotech Corporation | Regional Leader | Cell therapy expertise | Asia Pacific |
| Novartis AG | Top 5 | Product innovation | Global |
| Autolus Therapeutics plc | Niche Leader | Technology development | North America & Europe |
| Emerging Player | Clinical pipeline | US | |
| Cellectis S.A. | Emerging Player | Gene-edited CAR-T therapies | North America & Europe |
| Fate Therapeutics, Inc. | Emerging Player | Cell therapy development | US |
| Precision BioSciences, Inc. | Emerging Player | Gene editing and cell therapy | US |
| Sana Biotechnology, Inc. | Emerging Player | Cell engineering and gene therapy | US |
Key Players
- Autolus Therapeutics
- Bristol Myers Squibb
- Cabaletta Bio
- Cellectis
- Fate Therapeutics
- Gilead Sciences
- Johnson & Johnson
- Legend Biotech
- Novartis AG
- Precision BioSciences
- Sana Biotechnology
- TCR² Therapeutics
Recent Developments, Approvals, and Partnerships
August 2026: AbelZeta Pharma, Inc. revealed that it received the U.S. Food and Drug Administration (FDA) clearance of IND application for C-CAR039 for the treatment of relapsed or refractory (r/r) Large B-cell Lymphoma (LBCL). (source: abelzeta.com)
August 2026: CARsgen Therapeutics Holdings Limited announced that CT1190B, an allogeneic CAR T-cell product targeting CD19/CD20, received IND clearance from the NMPA. The company revealed that CT1190B has been cleared for treating patients with relapsed/refractory large B-cell lymphoma (R/R LBCL) who have failed at least two prior lines of standard therapy. (source: carsgen.com)
June 2026: The US FDA fully approved Tecelra (afamitresgene autoleucel), the first T-cell receptor (TCR) therapy for solid tumors, for treating unresectable or metastatic synovial sarcoma after chemotherapy (source: prnewswire.com).
June 2026: A Penn Medicine Phase I trial showed that dual CAR-T cell therapy can reduce harmful antibodies, helping highly sensitized kidney failure patients become eligible for kidney transplantation (source: pennmedicine.org).
Future Outlook of CAR-T Cell Therapy Market
The CAR-T cell therapy industry is expected to grow significantly in the coming years. Rising cancer prevalence and expanding regulatory approvals would boost the market. Breakthroughs in cell engineering technologies will drive the expansion. The market witnesses continuous developments in allogeneic CAR-T therapies and AI-assisted drug development. Market players emphasize automated manufacturing and solid tumor applications. They are expected to improve accessibility and broaden therapeutic use. Personalized medicine is becoming a central pillar of oncology. Thus, CAR-T therapy is poised to become one of the most transformative segments of the global cancer treatment landscape.
Global CAR T-Cell Therapy Market Report Segmentation
By Target Antigen Outlook
- CD19
- BCMA
- CD22
- GD2
- HER2
- GPC3
- Other Targets
By Type of Therapy Outlook
- Autologous
- Allogeneic
By Technology Outlook
- Viral Vectors
- Non-Viral Vectors
- Armored CAR-T
- Dual/Multi-Antigen Targeting
By Manufacturing Method Outlook
- Centralized
- Point-of-care
- In Vivo
By Disease Indication Outlook
- Lymphoma
- Leukemia
- Multiple Myeloma
By End User Outlook
- Hospitals
- Cancer Centers
- Cell Therapy Centers
- CDMOs
- Academic/Research Institutes
By Product Outlook
- Yescarta
- Kymriah
- Carvykti
- Abecma
- Breyanzi
- Tecartus
- Aucatzyl
By Regional Outlook
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Car T-Cell Therapy Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 5.59 Billion |
| Market Size in 2026 | USD 6.40 Billion |
| Revenue Forecast by 2034 | USD 19.15 Billion |
| CAGR | 14.66% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
CAR-T Cell Therapy Market Frequently Asked Questions
The market was valued at USD 5.59 billion in 2025 and is projected to reach USD 19.15 billion by 2034, growing at a CAGR of 14.66% from 2026 to 2034.
North America led with an estimated 43.0% share in 2025, supported by commercial product availability, specialist treatment centers, reimbursement infrastructure and clinical research.
The CD19 segment dominated the market in 2025 with a 49.0% share due to widespread use in approved therapies.
Major companies include Bristol Myers Squibb, Gilead Sciences, Novartis, Johnson & Johnson, and Legend Biotech, and other.
Growing adoption of precision medicine, increasing oncology investments, and expanding cell therapy commercialization are driving growth.
Strong growth is expected due to precision medicine, regenerative therapies, organoid commercialization, and next-generation cell therapy development.
There are certain types of blood cancers that are responsive to CAR-T therapy such as acute lymphoblastic leukemia, diffuse large B-cell lymphoma, follicular lymphoma, mantle cell lymphoma, and multiple myeloma.
CAR-T therapy acts directly on the cancer cells. This therapy provides patients with clinical responses and • personalized treatment. It is also possible to reduce the risk of disease relapse in some patients.
Cytokine release syndrome, neurologic symptoms, and extended low blood cell counts are a few side effects of CAR-T treatment. Infections, fatigue, and immune system disorders are other adverse effects.
High product and care-delivery costs, manufacturing time, limited treatment-center capacity, reimbursement variation, patient eligibility and serious toxicities continue to limit adoption.
Download Sample Report of CAR T-Cell Therapy Market
Please fill out the form to request a customized copy of the research report.