Electric Commercial Vehicle Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Electric Commercial Vehicle Market Summary
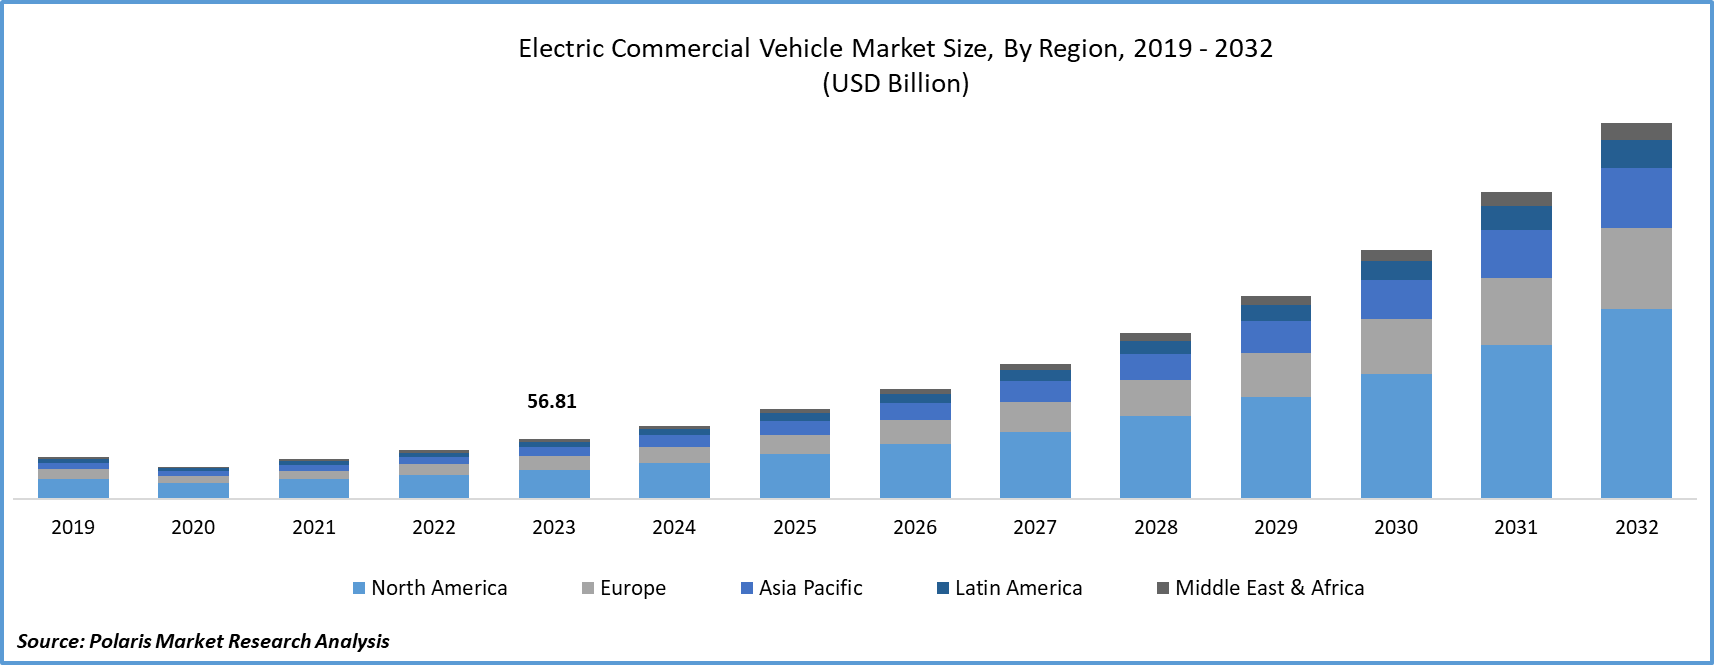
The global electric commercial vehicle market size was valued at USD 75.79 billion in 2025. The market is projected to grow at an 12.10% CAGR from 2026 to 2034. Rising costs of traditional fuels have led to increased adoption of electric commercial vehicles. The shift towards favorable regulations is also contributing to the electric commercial vehicle market growth.
Market Statistics
Electric Commercial Vehicle Market Key Takeaways
- Asia Pacific led the global electric commercial vehicle market with an 51.60% share in 2025. The robust Chinese electric bus industry contributes to the regional market dominance.
- North America is projected to witness rapid growth at an 13.20% CAGR. Tightening environmental regulations are driving market growth in the region.
- The BEV segment dominated with an 61.40% share in 2025. The segment benefits from mature supply chains and reduced cell pricing.
- The above 250 kW segment is projected to witness rapid growth at an 13.85% CAGR. This is because the segment powers heavy-duty applications like long-haul freight trucks and intercity buses.
- The last-mile delivery segment led with an 33.40% electric commercial vehicle market share in 2025. The segment’s leading position is attributed to the increasing electrification of regional freight corridors.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Are Electric Commercial Vehicles?
Electric commercial vehicles are equipped with electric engines and batteries and are meant for commercial use and transport. They include electric vans, trucks, and other commercial vehicles used for carrying goods and passengers. These vehicles use electric energy rather than conventional fuel such as diesel or gasoline.
How Electric Commercial Vehicles Work?
Battery Charging: Battery charging is done through an external charging station or system.
Power Source: At the onset of the functioning of the vehicle, the battery supplies electricity to the motor.
Motor Functioning: The motor gets electrical energy from the battery and generates mechanical energy.
Operation of the Vehicle: Energy from the motor is transferred to the wheels of the vehicle for its operations.
Recharging: Some energy that is generated by the regenerative braking process is used to recharge the battery.
Management of Energy: The vehicle control system manages the energy usage for effective operations.
Source: Polaris Market Research Analysis
Market Dynamics
Drivers: Increasing Costs of Fossil Fuels
Rising costs of fossil fuels are resulting in higher operational costs for commercial fleet operators. Fuel is a continuous cost for business enterprises operating trucks, buses, vans, and other commercial fleets. Hence, fuel prices are an essential factor to be considered during the process of evaluating the company’s plan to replace its fleet and expand it. Electric commercial vehicles offer an alternative because their energy source is electricity and not gasoline or diesel. The economic factor becomes more significant for vehicles used frequently and those covering long distances. According to the Global EV Outlook 2026 report from the International Energy Agency, electric vehicles were able to reduce consumption of 1 million barrels of oil per day in China in 2025 alone. It is predicted that by 2030, globally, electric vehicles will save about 5 million barrels of oil per day (source: iea.org). The gradual decline in oil usage reflects increased electric vehicle adoption.
Drivers: Expansion of Electric Commercial Vehicle Model Availability
A larger number of commercially available models of electric vehicles makes fleet electrification across a range of operations. Firms are increasingly introducing a diverse set of models across different vehicle types and operating modes. Consequently, companies can choose among different replacements for conventional vehicles. This option can be beneficial for selecting electric models to match existing transportation services. In April 2026, Volvo Trucks released a new generation of electric trucks with a maximum range of up to 700 kilometers. The company positioned the launch as an expansion of the electric heavy-duty transport options (source: volvotrucks.com). Such innovations are widening the scope of commercial operations that can use electric vehicles as part of their fleet.
Drivers: Total Cost of Ownership Benefits
Total cost of ownership plays an essential role in commercial operators' decisions about electric vehicles. Vehicle purchase price is just one of the components of the total cost of ownership electric truck\bus. Under suitable operating conditions, electricity can be cheaper than fuel. Moreover, electric vehicles can have fewer mechanical components subject to maintenance. This economic advantage becomes increasingly important for vehicles that travel long distances under normal operating conditions. Operators can assess these benefits in relation to the vehicle purchase price, electricity charges, and costs related to batteries. As operators become more concerned about fleet economics, total cost of ownership will continue to play a vital role in purchasing decisions.
Restraints: High Development and R&D Costs
High development costs and the high cost associated with research & development can hinder electric commercial vehicle market expansion. Companies require significant investments in order to develop power trains and vehicle platform designs. Such costs also include testing and validation, as well as software development and improvements. These costs are especially prohibitive for heavy-duty trucks, as manufacturers have to meet specific specifications and requirements. Smaller companies may feel more pressure because they cannot spread these expenses across large production runs. Large capital expenses may thus hinder innovation and intensify competition in the electric commercial vehicles market.
Opportunities: Second-Life Applications for Commercial EV Batteries
The increasing number of commercial electric vehicles will create opportunities for the reuse of batteries that are no longer capable of being used in the vehicle. These batteries could be used in stationary energy storage where the power and energy densities may be acceptable. This can help increase the lifespan of the batteries and keep the materials from ending up in the recycling process. Reusing batteries would also create business opportunities for battery manufacturers, energy storage companies, and commercial electric vehicle fleets. Developing battery management and testing processes will also help assess the safety of used batteries.
Opportunities: Vehicle-to-Grid and Energy Management
Electric commercial vehicles can become a component of the broader energy management systems when the batteries are integrated into the power grid. Vehicles in commercial fleets that remain parked for long periods may offer an opportunity to store electricity and use it again as needed. This would bring additional economic value to fleet owners, enabling more flexible use of electricity. It is especially applicable to commercial fleets with regular schedules. Vehicle-to-grid technology is also useful to businesses in managing electricity consumption without entirely depending on the existing grid structure.
Opportunities: Battery Recycling & Circular Economy Opportunities
Battery recycling is becoming a crucial part of the ecosystem for electric commercial vehicles due to the growing battery base. Commercial EV batteries contain materials that can be recycled once their lifespan ends. Recycling such batteries will help decrease battery waste and use raw materials efficiently. Recycling will also help manufacturers to collect input materials for future batteries. Improvements in the process of dismantling batteries and recovering their materials are making recycling of batteries more efficient in the coming years. As a result, all companies involved in the battery value chain are paying increasing attention to their capacity to collect and recycle batteries. In the long run, better recycling capacity will enable a circular strategy for commercial EV battery production.
Trends: Advancements in EV Battery Technology
There is ongoing development of EV battery technology to cater to the demands of commercial vehicles. Manufacturers are working to create batteries that have higher energy density, better service life, and thermal performance. Higher energy density allows vehicles to store more energy without increasing the size of the battery pack. This helps achieve higher ranges in electric trucks, vans, and buses. There are improvements in the design of battery packs that are making it easier for the manufacturers to make better use of space available in the vehicle. Research into new chemistries and cell designs is expanding technology options for commercial vehicles. Advancements in battery management systems are also helping monitor cell performance and battery efficiency while driving.
Trends: Fast-Charging Infrastructure Expansion
Fast-charging infrastructure is being developed to cater to the demands for charging by commercial electric vehicles. Commercial trucks and buses often need large amounts of energy and may have limited charging time. Commercial EV charging infrastructure can make it possible to reduce these interruptions and allow practical functioning of vehicles. CV depot charging is becoming more important because fleet operators can set up dedicated charging equipment at locations where their vehicles return frequently. This enables charging to be planned based on the fleet schedule. Hyperchargers are also emerging as high-power charging options for commercial applications. Depot charging and hyperchargers can ensure higher charging power and shorter charging time periods for suitable vehicles. Thus, the development of both depot charging and hypercharger commercial vehicle systems has become an enabling factor for the adoption of commercial EVs.
Trends: Integration with Smart Transportation Ecosystems
Integrating electric commercial vehicles with connected transport systems is increasingly common. Vehicle connectivity enables the exchange of operational information between vehicles, charging stations, and the digital platform. This helps the operator monitor the vehicle's status and energy consumption. Vehicle connectivity also enables vehicles to interface with traffic and transport systems. This will support decision-making on vehicle availability and energy consumption. Connectivity underpins real-time data integration in the commercial transport system. As digital technologies become more integrated with electric vehicles, connectivity is expected to play a larger role in the future.
Source: Polaris Market Research Analysis
Report Segmentation
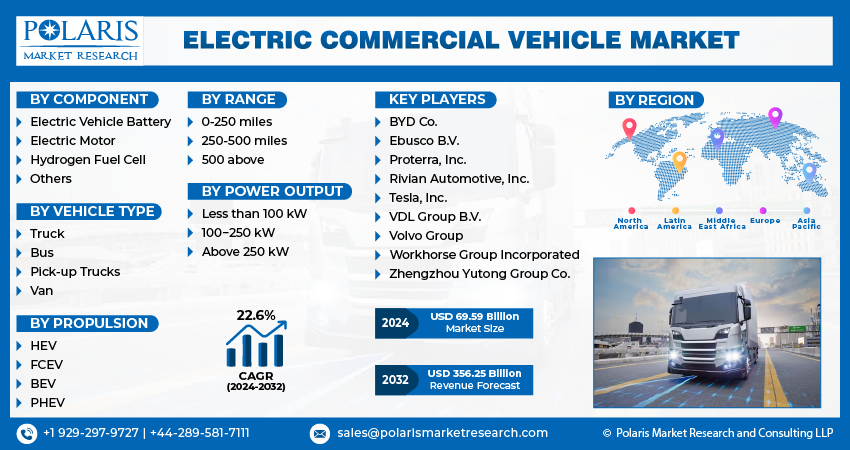
| Segmentation Axis | Segments |
| By Component | Electric Vehicle Battery · Electric Motor · Hydrogen Fuel Cell · Others |
| By Vehicle Type | Truck · Bus · Pick-up Trucks · Van |
| By Propulsion | Battery Electric Vehicles (BEV) · Hybrid Electric Vehicles (HEV) · Plug-in Hybrid Electric Vehicles (PHEV) · Fuel-cell Electric Vehicles (FCEV) |
| By Range | Less than 150 miles · 150-300 miles · More than 300 miles |
| By Power Output | Less than 100 kW · 100−250 kW · Above 250 kW |
| By Battery Capacity | Less than 100 kWh · 100-200 kWh · Greater than 200 kWh |
| By Charging Type | Depot (AC) · Opportunity / En-route (DC) |
| By End-Use | Last-Mile Delivery · Public Transport · Municipal · Freight |
| By Region | North America (U.S., Canada) · Europe (UK, Germany, France, Italy, Spain, Netherlands, Russia, Rest of Europe) · Asia Pacific (China, India, Japan, Malaysia, Indonesia, South Korea, Rest of Asia Pacific) · Latin America (Brazil, Mexico, Argentina, Rest of Latin America) · Middle East & Africa (Saudi Arabia, UAE, Israel, South Africa, Rest of Middle East & Africa) |
Source: Polaris Market Research Analysis
By Component
The electric vehicle battery segment led with an 46.20% electric commercial vehicle market share in 2025. Batteries are an essential energy storage system for electric commercial vehicles. Their importance increases in commercial vehicles since trucks, buses, and vans operate for a longer duration and have higher loads. Fleet owners need batteries that are capable of providing enough energy according to the requirements of the vehicles. The demand is also being driven by the increase in production of electric commercial vehicles in various categories of vehicles. With more and more electric vehicles being produced, battery systems continue to play an integral part in vehicle production. This is expected to drive continued demand for EV batteries.
The hydrogen fuel cell segment is projected to grow at an 15.75% CAGR. Hydrogen fuel cells produce electrical energy through electrochemical reactions of hydrogen and oxygen, thereby delivering energy without depending on traditional internal combustion engines. The technology is becoming popular in commercial vehicles, which need long distances of operation and high utilization of the vehicles. Faster refueling as compared to the battery charging process could be possible in certain cases using fuel cells. These characteristics support their potential use in heavy-duty trucks, buses, and other commercial vehicles where scheduling issues can affect the amount of time taken to charge them. As a result, this market segment is expected to grow rapidly during the forecast period.
By Vehicle Type
The bus segment led the electric commercial vehicle market with an 29.60% share in 2025. Electric buses are increasingly being used in urban transportation applications, which involve following fixed routes and schedules. Their frequent use makes fuel and maintenance an important consideration for transit operators. Moreover, electric buses can help in quieter operations in heavily populated areas. The segment includes vehicles used for urban transportation, school transportation, and other passenger services. The ongoing replacement of aging bus fleets is aiding the growth of electric buses in many regions. This is helping the bus market segment maintain a strong position in the electric commercial vehicle market.
The truck segment is projected to witness rapid growth at an 13.25% CAGR. Electric trucks are gaining attention among freight and commercial transporters. Manufacturers have increased the number of electric trucks for various load-carrying capacities and working environments. Electric trucks in the medium- and heavy-duty categories are being evaluated in urban and regional transport services. This market is also being fueled by increasing interest in the reduction of fuel consumption in high-mileage fleets. Electric trucks may be suitable for trips that require a predictable distance and schedule. Innovations in vehicle designs have helped develop models suitable for more challenging commercial environments. As electric vehicles continue to be evaluated for freight transportation, demand for electric trucks is expected to increase during the forecast period.
By Propulsion
The battery electric vehicles (BEV) segment captured the largest electric commercial vehicle market share of 61.40% in 2025. BEVs run entirely on energy from the batteries installed in the vehicle and do not have an internal combustion engine. As such, these types of vehicles are ideal for commercial uses whereby the vehicles can be charged at designated charging stations. These vehicles come in various classes of commercial vehicles such as vans, buses, and trucks. BEVs are particularly relevant for commercial uses in which there is a predictable route. In addition, the segment is also benefiting from the rise in the number of electric commercial vehicles. As companies continue to develop new battery electric vehicle (BEV) commercial models, the segment will likely remain prominent in the future.
The fuel-cell electric vehicle (FCEV) segment is projected to grow at an 16.40% CAGR. There is increased emphasis by manufacturers on FCEVs as one of their commercial vehicle offerings. There is also increased consideration by fleet operators of these vehicles in applications where consistent utilization of the vehicle is needed. The market segment is growing in importance in freight transport as well as mobility applications. Infrastructure investments for hydrogen refueling stations are also facilitating market development in certain regions. Growing interest in alternative powertrain technology is prompting fleet owners to evaluate fuel cell electric vehicles against battery-electric vehicles.
| Attribute | Battery Electric Vehicle (BEV) | Plug-in Hybrid Electric Vehicle (PHEV) | Fuel Cell Electric Vehicle (FCEV) |
| Typical use case | Urban delivery vans, city buses, municipal fleets | Transitional fleets needing range flexibility | Long-haul trucking, intercity buses |
| Range profile | Short to medium; depot-charging dependent | Extended via backup combustion engine | Long range with fast hydrogen refueling |
| Refuel/recharge time | Longer (charging cycle) | Shorter (can also use liquid fuel) | Comparable to conventional refueling |
| Infrastructure dependency | Depot and public charging network | Lower — works with existing fuel infrastructure as backup | Hydrogen refueling network, still developing |
| Cost trend | Falling fastest as battery costs decline | Moderate; carries cost of two drivetrains | Highest upfront cost; declining as hydrogen production scales |
| Growth outlook cited by competitors | Currently largest propulsion share | Declining share as pure BEV options mature | Fastest-growing propulsion segment in heavy-duty/long-haul use cases |
Source: Polaris Market Research Analysis
By Range
The 150-300 miles segment led the market with an 46.50% share in 2025. The segment represents a practical balance between fleet vehicle coverage and operation requirements for numerous commercial fleets. It allows daily trips to go beyond short urban driving without requiring vehicles suited for long-haul trips. This segment is relevant to operators that need flexibility across different routes during regular operations. Moreover, it enables better routing coverage for vehicles covering multiple locations in a single working day. Demand for this segment will grow due to the long-distance requirements of commercial transport services. Commercial fleet owners can choose suitable vehicles in this segment based on distance and operational requirements. As commercial fleet owners consider electric vehicles for various transport needs, this segment will remain relevant during the forecast period.
The more than 300 miles segment is projected to grow at an 14.25% CAGR. This range has become popular amid the adoption of electric vehicles by commercial vehicle operators for longer-distance activities. This helps address situations where a vehicle must travel long distances before returning to a charging point or depot. It applies to commercial vehicle operators handling long-distance operations from one city to another. A longer driving range gives commercial vehicle operators an added advantage in scheduling vehicle trips. This eliminates the need for the vehicle to operate only over short distances. This will be further supported by the emergence of commercial vehicle models that operate over longer distances in future years.
By Power Output
The 100−250 kW segment accounted for the largest market share of 47.80% in 2025. This power level is ideal for commercial vehicles that have moderate to high power requirements for everyday operations. The output level is adequate for commercial vehicles running under load variation. The segment caters to a wide variety of commercial transport needs and is, hence, applicable to different vehicle fleets. The demand for this segment is fueled by the increasing popularity of electric powertrains in commercial vehicles having varied requirements. Automakers are also producing vehicles having power outputs that meet specific operational requirements. Commercial vehicle users can have an array of options to choose from based on factors such as load carried, operational route, and other operational requirements. This segment is set to remain in the lead as adoption of electric commercial vehicles becomes more widespread.
The above 250 kW segment is projected to grow at an 13.85% CAGR. This power output segment is becoming increasingly important as electric commercial vehicles are designed to function in harsher environments. Larger power capacity ensures adequate power for operations in heavier commercial vehicles or on roads demanding higher performance levels. In addition, larger power is more applicable in cases where power needs to be provided constantly while the vehicle is in motion. The demand for this power segment may increase as companies explore the idea of using electric commercial vehicles. Manufacturers continue improving electric vehicle powertrains to provide better performance and power for these kinds of applications. Moreover, the segment may benefit from the increasing availability of more powerful electric commercial vehicles. As electric commercial vehicles are used in more demanding activities, the segment is expected to grow strongly during the forecast period.
By End Use
The last-mile delivery segment led the electric commercial vehicle market with an 33.40% share in 2025. The segment is driven by the increasing requirement for effective transportation of goods from distribution centers to end users. Delivery fleets normally have set geographic service regions, where the use of electric commercial vehicles may be ideal. The last-mile delivery segment includes deliveries from e-commerce and retail, food-related, and other businesses that utilize vehicles frequently. Electric vehicles can also help businesses control operating costs across their delivery fleets. The use of such vehicles in urban areas is driven by the requirement for quieter vehicles for their frequent deliveries. Vehicle choice by fleet operators is now increasingly based on daily distances, payloads, and delivery schedules. As more deliveries are made directly to consumers, the last-mile delivery electrification segment will continue to be a key market segment for electric commercial vehicles.
The public transport segment is projected to grow at an 10.85% CAGR. Public transport companies are emerging as a crucial customer base for manufacturers of electric commercial vehicles. The transit authorities are increasingly focusing on fleet upgrades and improvements in service quality. Electric buses are one option in such fleet upgrade programs. The segment also benefits from large-scale procurement programs, whereby the transport agencies purchase vehicles in batches to serve expanding passenger networks. Urban growth is leading to the rise of demand for public transport capacity in various cities. This provides an opportunity for manufacturers that can offer electric vehicles to cater to varying capacities and passenger needs.
Electric Commercial Vehicles vs. Conventional Commercial Vehicles
Electric commercial vehicles differ from conventional commercial vehicles in the following ways: the power train used in the vehicle, source of energy, operating cost, and impact on the environment. An electric vehicle uses an electric motor that is powered by batteries, while conventional vehicles use an internal combustion engine that works on fuel such as diesel and gasoline. The following table describes differences between the vehicles.
| Factor | Electric Commercial Vehicle | Conventional (Diesel/Gasoline) Commercial Vehicle |
| Fuel/energy cost | Lower and more predictable; runs on electricity priced independently of oil markets | Higher and volatile; exposed to fossil fuel price swings and supply disruptions |
| Maintenance requirements | Fewer moving parts, no oil changes or exhaust systems; lower servicing frequency | Regular engine, transmission, and exhaust-system servicing required |
| Emissions impact | Zero tailpipe emissions; supports emission-zone and net-zero compliance | Direct CO2 and NOx emissions; increasingly restricted in urban low-emission zones |
| Upfront vehicle cost | Higher purchase price, offset by incentives and lower running costs | Lower purchase price, no subsidy dependency |
| Total cost of ownership | Favorable over a multi-year duty cycle once fuel and maintenance savings accrue | Higher over the vehicle lifetime as fuel and maintenance costs compound |
| Operational efficiency | Regenerative braking and instant torque suit stop-start urban and depot routes | Consistent range and refueling speed suit long-haul and remote-route operations |
| Range/refueling time | Improving, but still constrained on very long-haul heavy-duty routes; charging takes longer than refueling | Long range and fast refueling remain an advantage for uninterrupted long-haul freight |
Source: Polaris Market Research Analysis
Government Incentives & Regulatory Support
Several governments have implemented financial incentives and regulations to promote the uptake of electric commercial vehicles. Government incentives for electric commercial vehicles could reduce the cost of purchasing electric vehicles and encourage fleet owners to adopt them. Several governments are also introducing policies to promote environmentally friendly transportation and reduce vehicle emissions.
Other regulatory initiatives would help further convince fleet owners of the feasibility of electric vehicles while expanding and upgrading their fleets. Public procurement programs are also critical to promoting the uptake of electric vehicles, especially electric buses used in public transportation. Governments in certain markets are developing long-term strategies to promote electric commercial vehicle market solutions.
Role in Decarbonization & Net-Zero Goals
Electric commercial vehicles could help address the emissions associated with road commercial transport operations. By adopting this approach, companies can mitigate the emissions arising from the use of transport mechanisms like delivery vans, freight trucks, and cars. This would be crucial, especially if transport usage is relatively high in a given year. This would also assist in measuring and mitigating the emissions arising in the future through transport. The use of electric vehicles can also enable companies to achieve their environmental goals by using an alternative means of transport to fossil fuels.
Source: Polaris Market Research Analysis
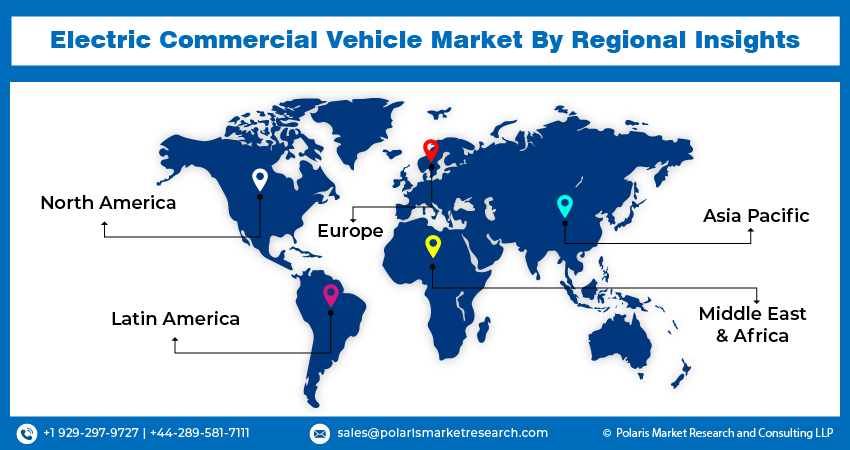
Regional Insights
Asia Pacific
Asia Pacific led the global electric commercial vehicle market with an 51.60% share in 2025. Rapid demand and uptake of electric commercial vehicles have driven growth, supported by the region's large manufacturing and transportation businesses. China accounts for a significant part of regional demand for electric commercial vehicles due to the increasing use of electric vehicles for commercial transport purposes within the country. India has contributed to increased demand for electric commercial vehicles, as interest in electric buses, delivery vans, and other commercial vehicles has grown. Vehicle and battery producers in the region also support the supply of electric commercial vehicles. Urbanization is further driving demand for commercial transportation services in the region.
North America
North America is projected to grow at an 13.20% CAGR. The region has a mature commercial vehicle industry with a growing focus on electric fleet adoption. The U.S. constitutes an important market in the region due to demand from freight companies, delivery services, and transit companies. Electric commercial vehicles are being introduced across various vehicle categories as companies evaluate alternatives to traditional vehicles. Moreover, charging station infrastructure for commercial applications has increased in the region. Increasing investments from automotive manufacturers and fleet management companies have been driving market growth. Future demand is expected to remain high due to ongoing evaluation of electric vehicles for commercial transportation. These factors are likely to drive steady growth in North America during the forecast period.
Europe
Europe accounted for an 22.40% electric commercial vehicle market share in 2025. There is an increasing trend toward electric commercial vehicles in freight, deliveries, and passenger transportation. Fleet operators in major European countries are driving growing demand as companies update their commercial vehicle fleets. Electric buses have also become more popular in public transport. The region has a developed automotive industry that includes automobile manufacturers offering electric commercial vehicles. The number of electric commercial vehicles is also increasing across different types of automobiles. European countries are developing at different paces, depending on fleet demand and market conditions.
Latin America
The Latin America electric commercial vehicle market is projected to grow at an 14.10% CAGR. Adoption of electric mobility solutions is becoming more frequent as transportation companies look into their capabilities for improving their operations. Cities have been showing interest in using electric buses in order to provide modern public transport services. Commercial delivery services have started considering electric vans for deliveries in the city. The increasing number of people living in urban areas of the region has raised the demand for transporting people and cargo efficiently. Local government agencies and fleet management companies have started considering electric vehicles in order to improve their transportation system. The market growth varies in each country based on the supply of electric vehicles, infrastructure development, and fleet requirements.
Middle East & Africa
The Middle East & Africa electric commercial vehicle market is projected to grow at an 12.80% CAGR. Adoption is gradually rising as nations seek more environmentally friendly commercial transportation methods. Electric buses are attracting more interest in urban mass transport systems, while electric vans and trucks are being considered for deliveries and logistics work. Market development varies by country, depending on vehicle availability and transport needs. Major cities in the region are expected to remain key centers for electric commercial vehicle adoption. More interest among vehicle manufacturers will also lead to a wider array of electric models becoming available to the regional market.
Source: Polaris Market Research Analysis
Key Players & Competitive Landscape
The competition in the electric commercial vehicle market is high, with established vehicle manufacturers and startups looking to expand their electric portfolios. Companies are concentrating on launching new models, developing battery-electric platforms, and providing solutions for diverse commercial applications. Manufacturers have also been making efforts to enhance their position through partnerships and fleet orders. Development of products is increasingly being concentrated on increasing the range, power, and commercial viability of the vehicle. Manufacturers have also been reaching into various segments of vehicles such as buses, vans, and trucks. Competition in the industry is likely to continue as manufacturers seek to increase their share in the growing electric commercial vehicle market.
| Company | Primary Focus Area | Segment Strength | Recent Notable Move |
| BYD Co. | Electric buses and trucks | Buses and commercial EVs | Expanded its presence in overseas markets |
| Ebusco Holding N.V. | Electric buses | Urban and regional buses | Added new long-range electric bus models |
| Rivian Automotive, Inc. | Electric commercial vans | Delivery vans | Developing new commercial van variants |
| Tesla, Inc. | Electric trucks | Heavy-duty trucks | Preparing the Semi for wider commercial deployment |
| VDL Group B.V. | Electric buses | Public transport buses | Continued work on zero-emission bus solutions |
| Volvo Trucks | Electric trucks | Heavy-duty and regional trucks | Introduced electric truck models with ranges of up to 700 km |
| Workhorse Group Incorporated | Electric delivery vehicles | Medium-duty commercial vehicles | Advanced its next-generation commercial vehicle programs |
| Zhengzhou Yutong Group Co. | Electric buses and coaches | Electric buses | Introduced new electric bus models for 2026 |
| Mack Trucks | Electric trucks | Medium-duty and refuse trucks | Added charging providers to its EV Turnkey Solutions program |
| EKA Mobility | Electric buses and commercial vehicles | Buses and light commercial vehicles | Entered the African market with electric buses |
| Ford Motor Company | Electric commercial vans | Fleet and delivery vans | Expanded its Ford Pro electric vehicle offering |
| General Motors | Electric commercial vans | Delivery vehicles | Continued development of its BrightDrop EV business |
| Mercedes-Benz Group AG | Electric commercial vans | Light commercial vehicles | Expanded its electric van range |
| Daimler Truck AG | Electric and fuel-cell trucks | Heavy-duty trucks | Added new electric truck offerings to its portfolio |
| Renault Group | Electric vans | Light commercial vehicles | Planned production of the Renault Trafic Van E-Tech electric |
| Tata Motors Limited | Electric trucks, buses, and small commercial vehicles | Buses and small commercial vehicles | Received more than 3,400 electric commercial vehicle orders |
Source: Polaris Market Research Analysis
Recent Developments
- September 2026: UltraTech Cement Limited announced the scale up of its electric vehicle fleet in its logistics operations. The company stated that it will expand its fleet to 600+ EV trucks by December 2026. It has partnered with major EV prime mover manufacturers, their subsidiaries, and third-party logistics providers for the deployment of EV trucks. (source: ultratechcement.com)
- August 2026: Advanced Electric Machines (AEM) announced its plans to introduce Titan, the next evolution of its heavy-duty electric motor technology, at IAA Transportation 2026. The company stated that the development represents a step forward in its commercial vehicle strategy. It is part of AEM’s continued effort towards expanding its rare earth-free product portfolio. (source: advancedelectricmachines.com)
Future Outlook
Projections indicate continued growth in the electric commercial vehicle market due to increased use by businesses and public transportation operators. The use of electric commercial vehicles is likely to increase in buses, vans, trucks, and other vehicles. Manufacturers are projected to produce more vehicle varieties for different operating conditions. Improved battery features will boost adoption of electric commercial vehicles. Charging facilities are expected to contribute greatly to the development of the market, especially those operating under intense conditions. Operators will also consider operating costs when selecting the right vehicle. Moreover, connected-vehicle technology is advancing to help manage electric commercial fleets.
Research Methodology
The electric commercial vehicle market estimates and forecasts are developed through a combination of primary and secondary research. Secondary research involves the review of company annual reports, regulatory filings, government transportation and emissions databases, industry association publications, and trade journals covering the electric commercial vehicle and automotive sectors. This phase establishes the historical data set and validates preliminary market boundaries, segmentation, and competitive landscape.
This is followed by primary research through structured interviews with fleet owners, OEM leaders, component makers, and subject matter experts for validation of secondary results, qualitative trends, and assumptions about adoption, geographic differences, and pricing. Data triangulation reconciles top-down estimates (derived from overall commercial vehicle production and electrification rates) with bottom-up estimates (built from company-level revenue and unit-shipment data) to arrive at a consistent market size.
The base year and forecast period are validated for each report refresh cycle using the latest available full-year data and regulatory changes and company information. The CAGRs, segment split, and regional share analysis are recalculated based on the new base year rather than carried unchanged, ensuring that the published numbers are current and not those of the original publish date assumptions.
Electric Commercial Vehicle Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 75.79 billion |
| Market Size Value in 2026 | USD 84.83 billion |
| Electric Commercial Vehicle Market Forecast 2034 | USD 211.54 billion |
| CAGR | 12.10% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Electric Commercial Vehicle Market FAQ's
The electric commercial vehicle market was valued at USD 75.79 billion in 2025. The market is projected to reach USD 211.54 billion by 2034.
The market is projected to grow at an 12.10% CAGR from 2026 to 2034.
Asia Pacific accounted for the largest market share of 51.60% in 2025. The robust Chinese electric bus industry contributes to the market’s leading position.
The last-mile delivery segment held an 33.40% share in 2025. This is attributed to the increasing electrification of regional freight corridors.
A few of the key market players include BYD Co.; Ebusco Holding N.V.; Rivian Automotive, Inc.; Tesla, Inc.; VDL Group B.V.; Volvo Group; Workhorse Group Incorporated; Zhengzhou Yutong Group Co.; Mack Trucks; EKA Mobility; Ford Motor Company; General Motors; Mercedes-Benz Group AG; Daimler Truck AG; Renault Group; and Tata Motors Limited.
The electric bus vs diesel bus cost depends on the initial cost of purchasing the bus and operational costs in the long run. Electric buses are usually more expensive initially, while diesel buses are less costly to purchase. However, electric buses are usually cheaper to operate because of lower energy and maintenance costs.
Electric commercial vehicles run on electric drivetrains, whereas conventional commercial vehicles use internal combustion engines. The difference between the two types is reflected in how they use energy, maintenance, costs, and emissions. Electric vehicles emit no exhaust emissions during operation and can therefore be used in commercial operations, provided they meet the required range.
Download Sample Report of Electric Commercial Vehicle Market
Please fill out the form to request a customized copy of the research report.