Fiber Optic Components Market Size, Share, Trends and Forecast, 2026–2034
REPORT DETAILS
Fiber Optic Components Market Summary
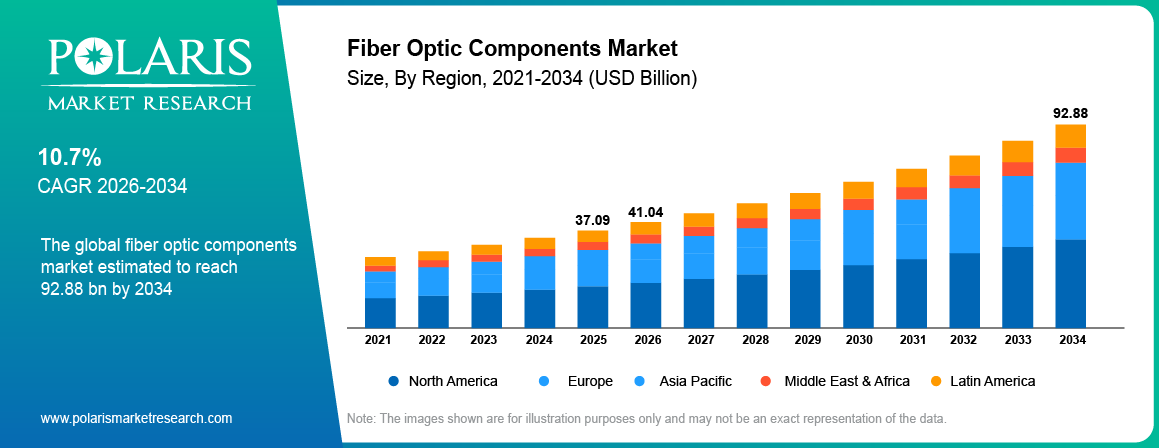
The global fiber optic component market size stood at USD 37.09 billion in 2025. The market is anticipated to expand at a CAGR of 10.7% during the forecast period from 2026 to 2034. The increase in the expansion of the 5G network has led to higher demands for fiber optic cables. The growth of the service industry in the emerging countries has also increased the demand for networks with low latency and high bandwidth capacity.
Market Statistics
Key Takeaways
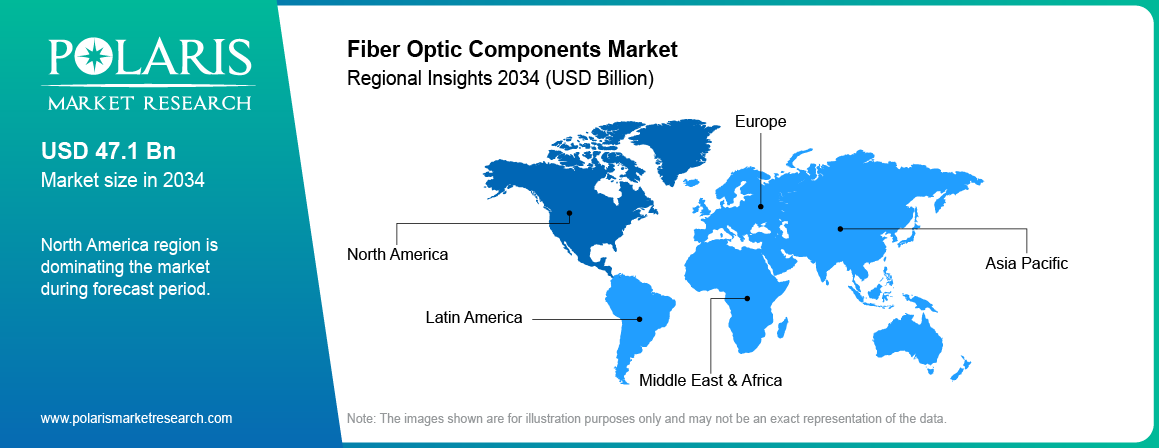
- North America led the global fiber optic components market with an 36.28% share in 2025. Rising investments in high-speed internet infrastructure drive the region’s leading market position.
- Asia Pacific is projected to witness rapid growth at an 12.68% CAGR. Rapid digital transformation across emerging economies contributes to the regional fiber optic components market growth.
- By component, the cables segment held 21.64% share in 2025. This is owing to the rising deployment of fiber-optic networks across telecommunications and data centers.
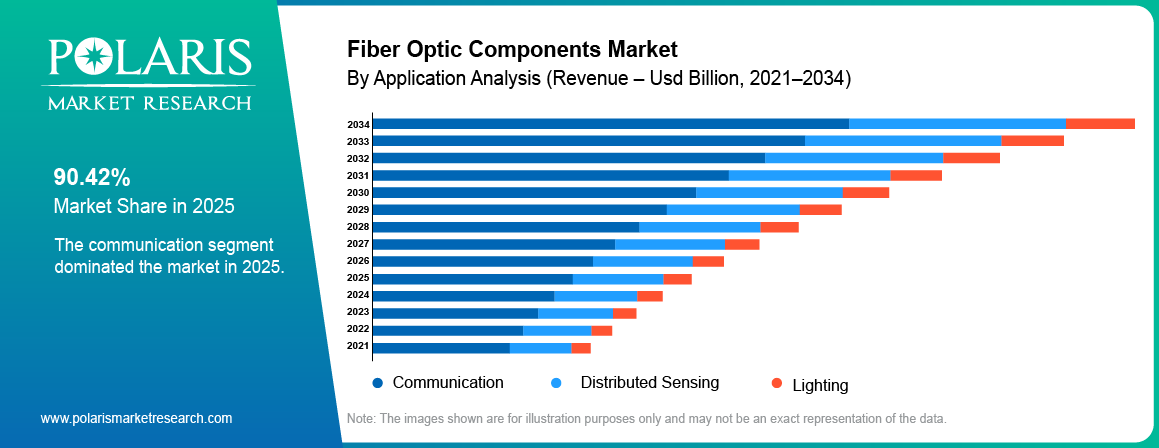
- By application, the communication segment held an 90.42% fiber optic components market share in 2025. The rapid expansion of high-speed internet services drives its major market share.
- By data rate, the 41 GBPS to 100 GBPS segment accounted for an 36.58% fiber optic components market share in 2025. Its high bandwidth capabilities are suited for data-heavy environments.
- By data rate, the 10 GBPS to 40 GBPS segment is projected to grow at an 8.46% CAGR. The data rate segment is an emerging option that offers a balance between cost and performance.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Are Fiber Optic Components?
Fiber optic components refer to the different components that make up the fiber optic communication system. The components facilitate the transfer of data through light signals via optical fibers. The various fiber optic components include fiber optic cable, connectors, transceivers, splitters, couplers, and amplifiers. Each component has its role in the network. For instance, transceivers convert electrical signals to optical signals and vice versa. Connectors attach fiber cables to the networking equipment, whereas splitters allow distribution of optical signals through different paths. Such devices are applied in telecom networks, data centers, broadband networks, and enterprise communications networks.
How do Fiber Optic Components Work
Signal Transformation: In the first step, the transmitter transforms the electrical signal into an optical signal. This prepares the signal for transmission through the optical fiber.
Transmission of Signal: The light travels through the fiber core, trapped inside by total internal reflection using the cladding around the core. It enables long-distance signal transmission with minimum losses.
Distribution of Signal: The splitters split the optical signal into multiple directions. This is done to ensure that one signal is received by different connected devices.
Signal Amplification: Optical amplifiers increase the strength of the weak signal after it travels long distances.
Signal Reception: At the destination, a photodetector transforms the optical signal into an electrical signal. The receiving equipment then processes the data for further use.
Market Overview and Industry Trends
The fiber optics component industry is evolving due to the rising need for faster data transfers in various industries. Data center growth and the roll-out of 5G networks have increased the need for dependable optical connections. New innovations like silicon photonics and co-packaged optics have influenced the design and usage of optical components. Apart from that, fiber optics also finds use in the defense, aerospace, and healthcare industries. Energy efficiency is another aspect that influences product design, especially in data centers. All these fiber optic components market trends are expected to shape the market landscape in the coming years.
AI and Cloud Data Center Demand
With the widespread adoption of cloud computing and AI technologies, there is an increasing need for faster connectivity in data centers. AI applications require large amounts of data to be transferred between servers and GPUs. There are limitations to copper interconnects with the increase in data rates and distance for transmission. This is creating a need for AI data center optical interconnect solutions for faster data transfer between computing devices.
There is an expansion in cloud providers’ data center infrastructure to cater to the growing demand for compute and storage. There is a need for interconnection in data centers to transfer data from one location to another. Data center interconnect (DCI) enables the connection of multiple data centers using high-bandwidth optical networks. It results in increased usage of optical transceivers, optical connectors, and optical amplifiers.
5G and Broadband Build-Out
The increasing number of 5G networks calls for additional fiber links, which connect mobile towers to the core network and transmit data produced by subscribers. Also, the popularity of small cells increases the necessity of installing fiber close to populated areas. Fiber is actively being used by broadband providers to get more homes connected. The use of FTTH ensures the installation of fiber to home, while PON is necessary to share the fiber connection with multiple people. The increased usage of fiber to the home leads to increased needs for optical splitters, fiber connectors, and fiber links. Many telecom providers are expanding their networks into rural areas, where broadband access is limited.
Silicon Photonics, Co-Packaged Optics and 800G/1.6T
An increase in network traffic requires increased speed for optical links. It has resulted in growing interest in the development of silicon photonics that enables using silicon chips to process optical signals. This technology can contribute to making optical devices smaller and more energy-efficient. Furthermore, it allows increasing data rates in new data center networks. The development of co-packaged optics is also taking place. This approach implies installing optical elements closer to switching chips. In this way, the distance over which electrical signals should be transmitted is reduced. At the same time, 800G and 1.6T optical transceivers are being created to address the problem of increased bandwidth. Another emerging trend is research related to hollow-core fiber that implies using a hollow core for signal transmission. These developments are shaping the design of next-generation fiber optic components.
Military, Aerospace and Healthcare Applications
The military uses fiber optics in its communication and data transfer systems. They are not highly susceptible to interference from electromagnetic waves compared to copper cables. Thus, they can be used in equipment such as radars, UAVs, and other defense gear. Optical fibers play an important role in monitoring aircraft systems through fiber optic sensors. The sensors are able to detect changes in temperature and pressure in addition to being lightweight enough to be installed in aircraft. Healthcare professionals employ fiber optic technology in their medical instruments. Optical fibers transport light into hard-to-reach body parts through endoscopes, thus allowing doctors to examine them. Optical fibers are also used in laser surgeries.
Energy Efficiency and Sustainability
Energy efficiency is another factor becoming increasingly significant in data center architecture. Fiber optic components could play an essential role in saving power in high-speed networks. Besides, optical signals produce less heat compared to the corresponding electrical signals transmitted through the same channel. It could be useful for cooling systems in specific applications. Manufacturers are working on creating optical components that consume less power while transmitting more information. These improvements are relevant as operators seek ways to manage their energy costs.
Market Dynamics
The growth of the fiber optic components market is due to the rising demand for fast data transmission. Network coverage is also a factor influencing the market. Investments in the data center market and telecommunications sector are contributing to market growth. Installation cost is one of the key challenges in the industry.
Driver: Rising Investment in 5G Network Expansion
Telecommunications companies are investing heavily in 5G technologies in order to enhance network coverage as well as data traffic. All new mobile sites require an effective backhaul link through which data will be transmitted into the main network. These backhauls use fiber optic cables extensively due to their capacity to transmit large amounts of data. The adoption of small cell technology is also leading to the need for fiber connections. In March 2026, Vodafone Idea announced that it would launch its 5G services in 90 new Indian cities by May 2026 (source: myvi.in). Such network expansion requires additional fiber infrastructure. This generates demand for fiber optic cables and other related components.
Driver: Growing Service Sector in Emerging Nations
The services industry is also witnessing growth in developing countries because companies are shifting their operations online. Services like banking, retail, healthcare, and IT services require robust internet connectivity, which is creating a need for better telecom and broadband infrastructure. There is also growth in the data center industry in order to accommodate the rising number of online transactions. In April 2026, the African Development Bank approved a $200 million loan to Nigeria's Project BRIDGE. The project is aimed at expanding the fiber network of the country by 90,000 km (source: afdb.org). Projects like these are creating a market demand for the purchase of optical fibers and network equipment. The expansion of service-based businesses in developing countries is fueling demand for fiber optics.
Restraints and Challenges: High Installation Costs and Infrastructure Limitations
The high fiber optic components tariffs and cost involved in implementing the fiber optic network is a major barrier to its adoption. Laying fiber optic cables demands significant investments in trenching and other forms of installation. The cost will be even higher in rural regions where there are low population levels and less developed network infrastructure. It is essential that the components of the fiber optics are handled carefully while installing them. Bending and physical damage can affect the performance of the network. Lack of qualified technicians to implement the fiber optic network is another challenge faced by businesses when trying to expand their network. Compatibility of the network with other network infrastructures is yet another issue faced by companies.
Opportunities: Growth in Submarine Optical Cable Networks
The rising demand for international data exchange is increasing the need for submarine cable installations that interconnect countries and help facilitate international internet communication. Providers of cloud services and telecoms are building up their subsea network assets to increase their international connectivity. The construction of new submarine networks involves optical components capable of providing long-haul transmission in challenging conditions. It also includes amplification systems and other special components required to ensure signal power on long routes. This development presents new business opportunities for fiber optic component manufacturers.
Market Segment Analysis
| Segmentation Axis | Segments |
| By Component | Cables · Active Optical Cables (AOC) · Amplifiers · Splitters · Connectors · Circulators · Transceivers · Others |
| By Data Rate | Less Than 10 GBPS · 10 GBPS to 40 GBPS · 41 GBPS to 100 GBPS · More Than 100 GBPS |
| By Application | Communication · Distributed Sensing · Lighting |
| By Region | North America (US, Canada) · Europe (Germany, France, UK, Italy, Spain, Netherlands, Russia, Rest of Europe) · Asia Pacific (China, Japan, India, Malaysia, South Korea, Indonesia, Australia, Vietnam, Rest of Asia Pacific) · Middle East & Africa (Saudi Arabia, UAE, Israel, South Africa, Rest of Middle East & Africa) · Latin America (Mexico, Brazil, Argentina, Rest of Latin America) |
The fiber optic components market is segmented by component, data rate, and application. Each segment covers a different area of the optical communication system. Demand varies by segment based on network requirements, transmission capability, and end-use applications.
By Component
The cables segment accounted for significant market share of 21.64% in 2025. Optical fibers serve as the base infrastructure for an optical communication network. These fibers transmit information in the form of light signals at very high speeds across long distances. Telecom companies deploy these fibers in order to increase broadband connectivity and link mobile network facilities. Fiber cables are also used by data centers to accommodate increased information traffic. Rising demand for network infrastructure, as well as upgrades in network infrastructure, has been driving the usage of fiber cables. High capacity demands have also boosted the demand for fiber cables. The widespread use of the cables in various communications networks contributes to their dominant market position.
The transceivers segment is projected to grow at an 11.58% CAGR. These transceivers enable conversion of electrical signals into optical signals for data transmission over fiber cables and vice versa. They are commonly used in data centers and telecommunications networks. As the use of AI workloads continues to increase, there is an increased need for fast connections between servers and other computing devices. This has led to demand for high-speed transceivers that offer transmission speeds of 800G and 1.6T bits per second. Operators are also replacing their equipment with equipment that can handle large amounts of traffic. This shift is fueling demand for optical transceivers.
| Component | What it Does | Where it Sits | Demand Signal |
| Cables | Carry light signals between points | Long-haul, metro, access, inside data centers | Broadband and FTTH rollout; high-fiber-count data-center builds |
| Active optical cables (AOC) | Cable with transceivers built into both ends | Short links between servers and switches | AI and storage clusters; low weight and EMI immunity |
| Optical amplifiers (EDFA, Raman) | Boost optical signals without electrical conversion | Long-haul and subsea routes | Higher channel counts and longer reach |
| Splitters/ couplers | Divide or combine light across fibers | Passive optical networks, FTTH | Fiber-to-the-home expansion |
| Fiber Optic Connectors (LC, MPO/MTP) | Join fibers with low loss | Patch panels, data-center and field terminations | Rising port counts; high-density MPO/MTP formats |
| Circulators | Route light directionally between ports | Bidirectional links, sensing, amplifiers | Coherent and sensing deployments |
| Optical transceivers (QSFP-DD, OSFP) | Convert electrical signals to light and back | Switch and router ports, transport gear | AI clusters; 400G to 800G upgrades |
| Others (filters, attenuators, WDM / DWDM multiplexers) | Condition and combine wavelengths | WDM systems, test and measurement | Capacity added on existing fiber |
Source: Polaris Market Research Analysis
By Data Rate
The 41 Gbps to 100 Gbps segment accounted for the largest fiber optic components market share of 36.58% in 2025. This data rate range is popular in data center networking and telecommunications infrastructure. Data centers use 100G connections to transfer huge amounts of data from one server to another or between servers and network devices. At the same time, telecom providers use these connections to transport more data in their networks. The shift towards higher capacity networks led to an increase in the number of optical transceivers supporting these rates. Coherent optics is becoming relevant as well for telecom operators who are interested in increasing transmission capacity on their existing fiber routes. New technologies like 400ZR and 800G ZR+ represent the continuation of this shift towards higher data rates beyond the 100G range. The established 100G connections continue to support demand.
The 10 Gbps to 40 Gbps segment is projected to grow at an 8.46% CAGR. Such data transfer rates remain relevant in the context of networks where the bandwidth of higher-speed links is not required. A number of enterprise networks and telecom providers utilize the infrastructure that is built specifically for 10G and 25G transmissions. It may be expensive to replace the infrastructure; therefore, networks continue to develop gradually. Another source of demand is applications where lower speeds are enough. As the traffic of the network grows, some users switch to fast links, and others still utilize 10G and 40G solutions. Thus, the demand for optical transceivers remains steady. The segment’s growth will also be influenced by the rate of transition to new technology.
By Application
The communication segment held an 90.42% fiber optic components market share in 2025. Fiber optic components are commonly used to transmit data within telecom networks. It is necessary for operators to accommodate the increasing amount of internet traffic through the provision of fast connections to the customers. The construction of 5G networks also contributes to this trend since there is a need for high-capacity fiber-optic links for the connection of mobile towers to the core network. Broadband providers utilize optical parts in order to supply fiber connections to consumers' residences and enterprises. Data centers are another source of demand since their networks require the use of optical transceivers and fibers to transfer data from one server to another.
The distributed sensing segment is projected to witness rapid growth at an 13.86% CAGR. While traditional sensors provide information regarding conditions at one point only, distributed fiber sensing is capable of providing measurements of any alterations along the optical fiber. It makes it possible for users to measure the temperature, strain, or vibration in a certain area. Distributed fiber-optic sensing is applied for monitoring facilities such as pipelines, power lines, railway tracks, and other types of infrastructure. Distributed fiber-optic sensing is also used in detecting some changes that might indicate equipment malfunction. An increased interest in distributed fiber-optic sensing is observed in the energy industry, where it is necessary to monitor distant assets. These applications are creating demand for fiber optic sensing components and related equipment.
Single-Mode vs Multimode Fiber Components
The key distinction between single-mode fiber and multimode fiber is in the propagation of light in the cable. Single-mode fiber components have a narrow core through which light propagates along one path. Therefore, it can be used for transmission over long distances, such as from one city to another or even for long-range telecommunication purposes. Multimode fibers have a wide core through which light propagates along multiple paths. For this reason, their effective range of transmission is much shorter. They are typically used in short-range transmissions in such places as office buildings or data centers. The choice of fibers used is dependent on the length of the transmission range and equipment involved.
| Attribute | Single-mode | Multimode |
| Core size | About 9 microns | 50 or 62.5 microns |
| Reach | Tens of kilometers to long-haul with amplification | Short reach: hundreds of meters (shorter at higher speeds) |
| Cost profile | Higher-cost optics (lasers, precise alignment) | Lower-cost optics and easier installation |
| Typical use | Telecom backbones, metro, access, data center interconnect, dark fiber network | Enterprise LANs, intra-data-center links |
| Common components | Coherent transceivers, amplifiers, WDM modules | Short-reach transceivers, AOCs, MPO connectors |
Source: Polaris Market Research Analysis
Fiber Optics vs Copper Communication
Fiber optic cables and copper cables are used for connecting devices and transmitting data. The main difference between the two is that fiber optic cables transmit data through light pulses while copper cables transmit data through electric current pulses. Fiber cables can transmit more data over long distances compared to copper cables, and they keep their quality when traveling long distances. Copper cables are popular in domestic and office environments, where connections are not that far. Also, they can be easily integrated with existing hardware. In a fiber optic vs copper cable comparison, the choice comes down to the distance and speed requirements of the network.
| Attribute | Fiber optics | Copper |
| Bandwidth | High. Scales with new optics on the same fiber | Limited. Falls off with speed and distance |
| Distance | Long reach with low loss | Short reach before signal degrades |
| Interference | Immune to electromagnetic interference | Susceptible |
| Security | Harder to tap | Easier to tap |
| Weight and size | Lighter and thinner per unit capacity | Heavier and bulkier |
| Cost and skills | Higher install cost; specialist termination skills | Cheaper for short-range, basic networks |
Source: Polaris Market Research Analysis
Regional Analysis
Regional analysis for the fiber optic components market includes the demand analysis in North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Growth in each region is determined by investments made in telecommunication networks, data centers, and broadband infrastructure.
North America Fiber Optic Components Market
North America accounted for the largest market share of 36.28% in 2025. The region boasts an efficient telecommunications network and also has several data centers. The U.S. is contributing to the rising demand through the expansion of cloud data centers. The increase in investments in the infrastructure of artificial intelligence (AI) also calls for fast server connectivity. The telecom operators are updating their networks in a bid to cope with the rising volumes of data flow. The fiber optic components will be used in this process in order to ensure fast and reliable connectivity. There has also been growth in the demand for fiber optic cables by broadband providers who seek to cover more residential and business premises.
Asia Pacific
The fiber optic components market Asia Pacific is projected to grow at an 12.68% CAGR. China, Japan, South Korea, and India are some of the major markets in the region. There is a huge telecom base in China that continues to expand the 5G network. India is also expanding its fiber broadband network, connecting more users. The demand in Japan and South Korea stems from the highly developed telecom infrastructure and fast internet connection services. Growth in data centers is contributing to the increase in the demand for optical fibers and transceivers in the region. The number of companies that are setting up their operations in cloud-based applications is also increasing. This calls for faster connectivity, thus driving network expansion in these countries.
Europe
Europe accounted for an 20.36% fiber optic components market share in 2025. Countries like Germany, the UK, France, and Italy make up regional demand. Telecom companies throughout Europe have been developing fiber broadband infrastructure to enhance internet penetration. The rollout of 5G services has also been contributing to increased demand for fiber infrastructure that connects mobile towers to core networks. Data centers are another factor driving demand for optical cables and transceivers. Cloud service providers have been building more infrastructure to accommodate growing traffic. Additionally, several countries in Europe have been investing in digital infrastructure to enable connectivity. These developments are creating demand for fiber optic components across the region.
Latin America
Latin America held an 4.38% share of the fiber optic components market in 2025. Both Brazil and Mexico have played a significant part in the telecommunications industry of the region. The nations are seeking to increase access to the internet by means of fiber broadband networks. Additionally, telecom operators are expanding their 5G footprint, including fiber connectivity to the 5G network. Data center investments have been another source of demand, as there is an increase in the use of cloud solutions, thereby resulting in higher demand for data connections. In addition, fiber networks have been installed in regions where internet access is still limited.
Middle East & Africa
The Middle East & Africa market is projected to grow at an 11.42% CAGR. Some countries, like Saudi Arabia, UAE, and South Africa, are making investments in telecom infrastructure. Fiber network extensions are needed to increase internet availability and handle higher data volume. The deployment of 5G technologies has led to the increasing demand for fiber. Data center projects in the Gulf countries have contributed to the growth of this demand. Some regions in Africa require expansion of broadband networks, which will require the use of fiber.
Competitive Landscape and Key Players
The fiber optic components market comprises companies supplying components to telecommunication networks, data centers, and broadband networks. Competitiveness in this market is based on the quality of the products, pricing strategy, and capability to cater to evolving network needs. Fiber optic components companies are developing components that can cater to faster data transmission and improved signaling performance. In addition, some vendors are exploring innovative optical components in order to fulfill the requirements of AI data centers and communication networks. There are vendors with extensive portfolios of products and vendors catering to individual components. Fiber optic component manufacturers also compete on the basis of product development and regional reach.
Top Fiber Optic Components Manufacturers 2026
| Vendor | Group | Fiber Optic Component Offering |
| Corning Incorporated | Optical Fiber and Cable Specialists | Optical fibers, fiber optic cables, connectors, cable assemblies, and connectivity hardware. |
| Coherent Corp. | Active Optical Component Suppliers | Optical transceivers, lasers, photodetectors, amplifiers, filters, and photonic components. |
| Lumentum Holdings Inc. | Active Optical Component Suppliers | Optical transceivers, semiconductor lasers, optical amplifiers, and wavelength management products. |
| Broadcom Inc. | Optical Semiconductor and Interconnect Suppliers | Optical transceiver modules, optical transmitters, receivers, lasers, and photodetectors. |
| Sumitomo Electric Industries, Ltd. | Optical Fiber and Cable Specialists | Optical fibers, fiber optic cables, connectors, and optical devices. |
| Accelink Technologies Co., Ltd. | Optical Transceiver and Module Suppliers | Optical transceivers, optical modules, and components for telecom and data communication networks. |
| Furukawa Electric Co., Ltd. | Optical Fiber and Cable Specialists | Optical fibers, fiber optic cables, and optical communication components. |
| Fujikura Ltd. | Fiber and Connectivity Products | Optical fibers, fiber optic cables, connectors, fusion splicers, and optical couplers. |
| Yangtze Optical Fibre and Cable Joint Stock Limited Company (YOFC) | Fiber and Cable Manufacturing | Optical fiber preforms, communication fibers, fiber optic cables, and specialty fibers. |
| Prysmian S.p.A. | Fiber Cable Manufacturing | Optical fibers, submarine cables, and high-density fiber optic cables. |
| Cisco Systems, Inc. | Optical Networking Solutions | Coherent optical transceivers and optical interconnect products through its Acacia business. |
| O-Net Technologies (Shenzhen) Group Co., Ltd. | Optical Modules and Components | Optical transceivers, passive optical components, and optical subassemblies. |
| InnoLight Technology (Suzhou) Ltd. | High-Speed Optical Transceivers | Optical transceivers used in AI data centers and telecom networks. |
| Eoptolink Technology Inc., Ltd. | High-Speed Optical Transceivers | Optical transceivers and optical subassemblies for data center and telecom applications. |
| Amphenol Corporation | Fiber Connectivity Products | Fiber optic connectors, cable assemblies, and interconnect systems. |
Source: Polaris Market Research Analysis
List of Key Companies
- Accelink Technologies Co., Ltd.
- Amphenol Corporation
- Broadcom Inc.
- Cisco Systems, Inc.
- Coherent Corp.
- Corning Incorporated
- Eoptolink Technology Inc., Ltd.
- Fujikura Ltd.
- Furukawa Electric Co., Ltd.
- InnoLight Technology (Suzhou) Ltd.
- Lumentum Holdings Inc.
- O-Net Technologies (Shenzhen) Group Co., Ltd.
- Prysmian S.p.A.
- Sumitomo Electric Industries, Ltd.
- Yangtze Optical Fibre and Cable Joint Stock Limited Company (YOFC)
Recent Industry Developments
- October 2026: NVIDIA and Cisco released a new optical pluggable module called Ultra-Dense Small Form Factor Pluggable (USFP). The new module provides 400 Gbps per lane with a capability to reach a total speed of up to 12.8 Tbps. TE Connectivity and Amphenol are also working with these two vendors to develop hardware for the USFP module. (source: nvidia.com)
- October 2026: Lumentum, Astera Labs, and Corning introduced a PCI-e over optics connectivity technology solution for rack-scale servers. This solution is based on Lumentum's VCSEL transmitter and receiver and Corning multimode fibers. Data transfer was demonstrated using several optical channels operating at 32 Gbps each. (source: lumentum.com)
- September 2026: STL introduced fiber trunk assemblies as a new offering in its data center portfolio. These assemblies come in versions with fiber counts from 48 to 6,912. They have factory-installed and tested connectors to eliminate on-site fiber termination during installation. (source: stl.tech)
- September 2026: Coherent Corp. launched a complete C-Band amplifier system to expand its portfolio of pluggable optical line systems. It can be used with 800G ZR/ZR+ coherent optics. It can handle up to 32 DWDM wavelengths in a single fiber pair. Its capacity is up to 25.6 Tbps. (source: coherent.com)
Future Outlook
The fiber optic components market forecast indicates that the industry is likely to witness steady demand in the upcoming years. Data center build-outs are expected to be one of the key sources of revenue for companies that manufacture optical transceivers and fiber optic cables. The trend towards 800G and 1.6T connections is likely to shape product demand as well, since network upgrades will be needed. There is still work to be done to extend fiber broadband access in many countries. New subsea cable builds will create demand for dedicated optical equipment. Manufacturers may face supply shortages as optical fiber demand rises.
Research Methodology
Polaris Market Research builds this estimate in four stages. Data mining first scopes the market, identifies suppliers and applications, and sets the segment taxonomy (component, data rate, application, region).
Secondary research then draws on company annual reports and investor presentations, regulatory and industry-association data, trade publications, and paid databases to establish historical figures for 2021 to 2024 and the 2025 base year. Primary research follows. Structured interviews with component manufacturers, network operators, data center builders, and industry experts across North America, Asia Pacific, Europe, Latin America, and the Middle East & Africa are used to validate assumptions and fill gaps. Market size is estimated with both a bottom-up build (vendor revenues, shipments and prices) and a top-down split from the parent optical networking market, then triangulated. Forecasts through 2034 apply stated assumptions for demand drivers, restraints, and technology adoption. Figures are in USD billion. Analysts review every segment value before publication, and figures are re-verified.
Fiber Optic Components Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 37.09 billion |
| Market Size Value in 2026 | USD 41.04 billion |
| Fiber Optic Components Market Forecast 2034 | USD 92.88 billion |
| CAGR | 10.7% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Fiber Optic Components Market FAQ's
The fiber optic components market size was valued at USD 37.09 billion in 2025. The market is projected to grow to USD 92.88 billion by 2034.
The fiber optic components market CAGR is projected to be 10.7% from 2026 to 2034.
North America accounted for the largest fiber optic components market share of 36.28% in 2025. This is owing to rising investments in high-speed internet infrastructure across the region.
Key players include Accelink Technologies Co., Ltd.; Amphenol Corporation; Broadcom Inc.; Cisco Systems, Inc.; Coherent Corp.; Corning Incorporated; Eoptolink Technology Inc., Ltd.; Fujikura Ltd.; Furukawa Electric Co., Ltd.; InnoLight Technology (Suzhou) Ltd.; Lumentum Holdings Inc.; O-Net Technologies (Shenzhen) Group Co., Ltd.; Prysmian S.p.A.; Sumitomo Electric Industries, Ltd.; Yangtze Optical Fibre; and Cable Joint Stock Limited Company (YOFC).
The communication segment held an 90.42% fiber optic components market share in 2025. The rapid expansion of high-speed internet services drives the segment’s leading market position.
Fiber optic components refer to parts used in optical communication systems. They facilitate the transmission of data in the form of light signals. The fiber cables act as the pathway for the light signals. Other components include those that join up cables and facilitate conversion of signals from electric to optical forms.
An optical fiber communication system begins when the electric signal is first transformed into light signals. The signals are transmitted through the optical fiber by the transmitter. The light travels through the core of the optical fiber to its end, where it is converted back into electrical signals by the receiver.
The fiber optic system utilizes different parts to send and manage light signals. Cables transport the signals from one point to another. The connectors join cables with devices. Transceivers convert the electrical signal to an optical signal. They also convert optical signals to electrical signals. The amplifiers increase the strength of weak signals. The splitters split the optical signals into multiple lines.
5G requires fast connectivity because mobile traffic increases. Fiber optic cables link mobile cell towers to the core network. They are capable of carrying large quantities of data over long distances with minimal signal attenuation. Operators use fiber optic cables to connect small cells and increase the coverage of 5G networks.
Single-mode fiber optic cable features a narrow core that carries light in a single path. The fiber is used for long distance transmission of data. Multimode fiber cable features a broader core that supports multiple paths of light transmission. The fiber is typically used for shorter connections, including links in data centers and offices.
AI data centers require fast data transmission from servers to GPU chips. The need for faster connectivity is increasing the demand for optical transceivers and cables capable of transmitting large volumes of data at very high speeds. In addition, there is a shift towards 800G and 1.6T connections.
Download Sample Report of Fiber Optic Components Market
Please fill out the form to request a customized copy of the research report.