High Strength Steel Market Share, Demand, Industry Analysis Report, 2026-2034
REPORT DETAILS
High Strength Steel Market
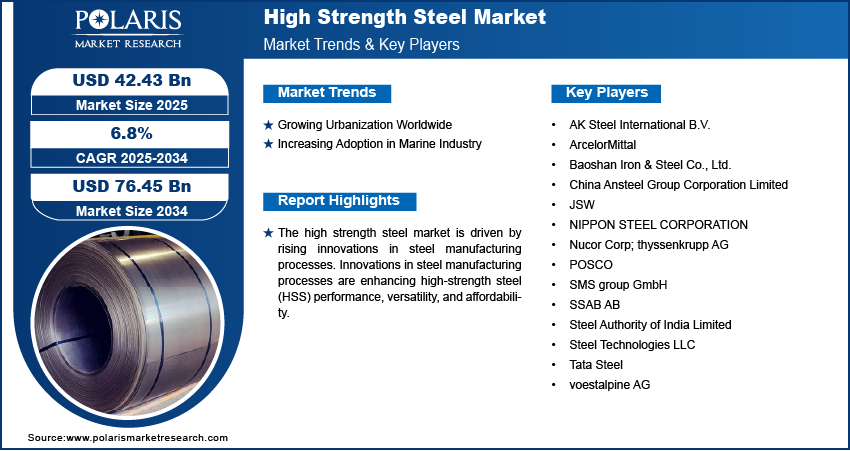
The global high strength steel market size was valued at USD 40.67 billion in 2025, growing at a CAGR of 7.01% during 2026–2034. The market is driven by increased vehicle production, innovations in steel manufacturing, growing urbanization, and the rising adoption in the marine industry for enhanced safety, durability, and cost-effectiveness.
Market Statistics
Key Takeaways
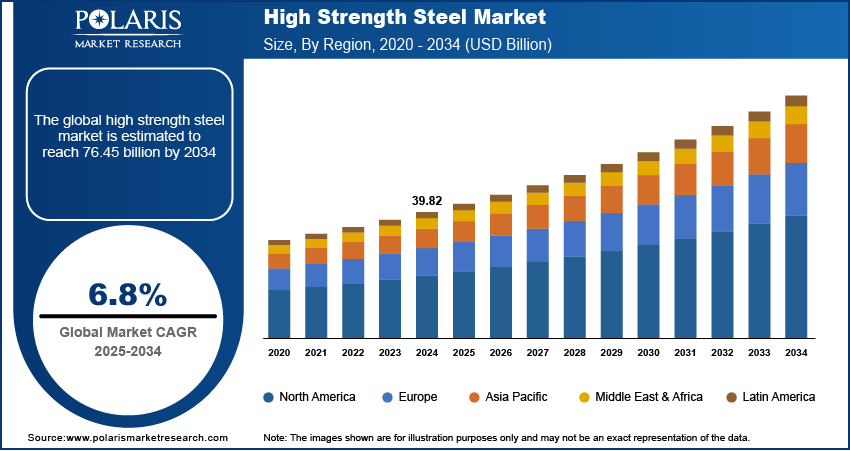
- Asia Pacific had the largest market share of 44.0% in 2025. The regional market dominance is attributed to its industrial growth and infrastructure development.
- North America is projected to experience significant growth at a 6.55% CAGR. This is due to advancements in automotive manufacturing and infrastructure renovation projects.
- High strength low alloy steel dominated with a 36.0% share in 2025. This is due to its cost efficiency and versatility in multiple industries.
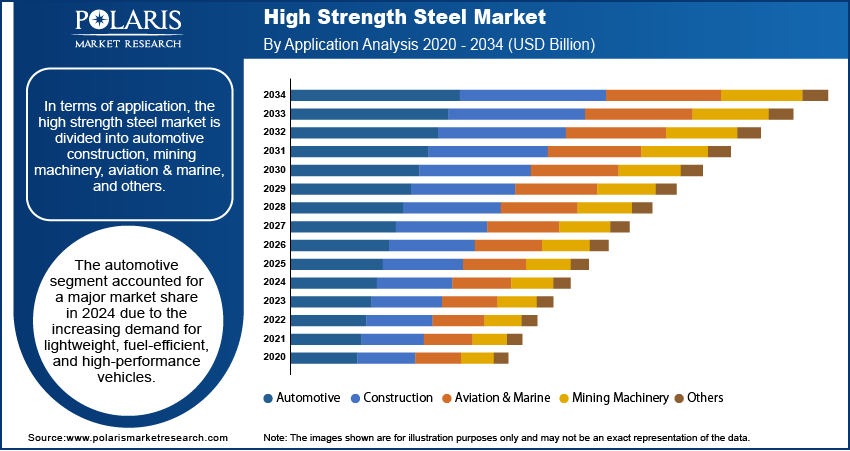
- The construction sector is projected to grow at a 6.32% CAGR. Rising urbanization and demand for sustainable materials in infrastructure projects drive the segment’s growth.
- The 600–900 MPa segment led with a 32.0% share in 2025. Its high usage in the automotive sector contributes to the segment’s dominance.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
Industry Dynamics
- Rising vehicle production and innovations in steel manufacturing are boosting demand for high-strength steel in automotive and aerospace applications.
- Urbanization and increased adoption in the marine industry are driving demand for high-strength steel in construction and shipbuilding.
- Growing demand for lightweight, energy-efficient materials creates potential for the further use of high-strength steel in various sectors.
- High production costs and competition from alternative materials such as aluminum and carbon fiber may hinder the market growth of high-strength steel.
AI Impact on High Strength Steel Market
- AI helps in enhancing the process of manufacturing high-strength steels through process optimization and minimizing wastage of materials.
- AI contributes to ensuring quality control by detecting defects and maintaining consistency in strength.
- AI assists companies in monitoring the production process in real-time.
- AI facilitates more accurate forecasting, inventory control, and logistics planning.
Source: Polaris Market Research Analysis
To Understand More About this Research: Download Sample Report
High-strength steel (HSS) is a specialized category of steel characterized by its enhanced mechanical properties, specifically high yield and tensile strength. HSS has a yield strength ranging from 210 to 550 MPa (30 to 80 ksi) and a tensile strength between 270 to 700 MPa (40 to 100 ksi). The unique properties of HSS are achieved through specific alloying elements and controlled manufacturing processes that result in fine-grained microstructures, allowing for better formability and weldability compared to conventional steels.
The rising production of motor vehicles is projected to boost the global high strength steel market demand. High-strength steel enables the production of safer motor vehicles that withstand higher impact forces while being lighter and more energy-efficient. This steel further offers a more cost-effective solution compared to alternative materials such as sum or carbon fiber for mass vehicle production. This makes it attractive for automobile manufacturers across different vehicle segments, from economy cars to luxury vehicles. Therefore, as the production of motor vehicles increases, the demand for high strength steel also spurs.
The rising innovations in steel manufacturing processes propel the high strength steel market development. Innovations in steel manufacturing processes are enhancing high-strength steel (HSS) performance, versatility, and affordability. Advances such as hot stamping improved alloying techniques, and the development of advanced high-strength steel (AHSS) grades have enabled the production of stronger, lighter, and more ductile steel. These innovations make HSS suitable for complex designs and applications, thereby propelling adoption in industries such as automotive, construction, and aerospace, where lightweight and durable materials are crucial.
High Strength Steel vs Conventional Steel
| Parameter | High Strength Steel (HSS/AHSS) | Conventional Steel |
| Ratio of Strength/Weight | Has high strength and low weight ratio | Low ratio of strength to weight |
| Performance in Durability | Increased durability and performance during bearing loads | Has ordinary durability and performance |
| Safety Performance | Greater structural stability and protection during collision | Low safety performance as compared to HSS |
| Resistance to Corrosion | May have improved resistance due to use of coating | Generally needs additional protection to improve resistance to corrosion |
| Contribution to Fuel Economy | Helps in lowering weight and enhancing fuel economy | Less contribution to improvement in fuel economy |
| Complexity in Manufacturing Process | Needs special procedures for manufacturing | Established process for manufacturing |
Market Dynamics
Growing Urbanization Worldwide
The growing urbanization worldwide is projected to propel the global high strength steel market demand during the forecast period. Urban areas require durable and sustainable materials for constructing skyscrapers, bridges, and transportation systems, where HSS is used majorly due to its superior strength-to-weight ratio and resilience. Its ability to support innovative architectural designs and withstand dynamic loads makes it an essential material for modern construction in urban areas.
Increasing Adoption in Marine Industry
Ships, offshore platforms, and marine structures require materials that withstand high loads, corrosive saltwater environments, and extreme weather while maintaining structural integrity. HSS meets these requirements by enabling lighter and stronger constructions, which improve fuel efficiency and reduce operational costs. It is particularly favored in shipbuilding for hulls, decks, and other critical components, as it allows for increased cargo capacity without compromising safety or performance. Furthermore, as the marine industry focuses on sustainability and efficiency, the use of HSS aligns with goals to optimize designs and reduce emissions, further driving its adoption. Therefore, the increasing adoption of high strength steel in the marine industry is driving the high strength steel market growth.
Sustainability and Carbon Reduction Benefits
The significance of high-strength steel is growing because of the rising focus on both sustainability and performance within various industrial sectors. The fact that high-strength steel requires less material compared to other steels for the same weight due to its favorable strength-to-weight ratio makes it easy to create light vehicles and equipment. With cars being lighter, better fuel economy can be achieved, reducing CO2 emissions from gasoline-powered cars, while electric cars would have a higher range and energy efficiency. Furthermore, it can be reused multiple times without affecting its properties. This adds to its appeal for companies pursuing a circular economy model.
Source: Polaris Market Research Analysis
Segment Analysis
Assessment by Product
Based on product, the high strength steel market is categorized into high strength low alloy, dual phase, transformation induced plasticity, bake hardenable, martensitic, and others. The high strength low alloy segment dominated the market with 44.0% share in 2025 due to its superior mechanical properties, cost efficiency, and versatility across various industries. HSLA steels offer excellent strength-to-weight ratios, which make them highly suitable for automotive, construction, and infrastructure applications where lightweight and durable materials are essential. The enhanced corrosion resistance of high strength low alloy further drives their adoption in environments exposed to moisture and harsh weather conditions, such as bridges and pipelines. The rising demand for energy-efficient and environmentally friendly materials also contributes to the growth of this segment, as HSLA steels reduce material consumption and improve fuel efficiency in automotive manufacturing.
The dual-phase (DP) steel segment is projected to witness 7.57% during the forecast period due to its blend of strength and ductility. This unique combination is achieved through a microstructure consisting of a soft ferrite matrix and hard martensite, enabling superior crash absorption in automotive applications. DP steels are becoming increasingly indispensable as automotive manufacturers focus on vehicle safety and lightweight to comply with stringent emission standards and safety regulations. Furthermore, advancements in manufacturing technologies, such as hot-stamping and tailored blanks, are making these steels more accessible and cost-effective. The growing adoption of electric vehicles (EVs), which require lightweight and strong materials to enhance battery efficiency, also boosts demand for dual-phase steel.
Evaluation by Application
In terms of application, the high strength steel market is divided into automotive, construction, mining machinery, aviation & marine, and others. The automotive segment accounted for a major market share of 43.0% share in 2025 due to the increasing demand for lightweight, fuel-efficient, and high-performance vehicles. Automakers prioritize HSS as it offers high strength-to-weight ratios to enhance vehicle safety, improve fuel economy, and comply with stringent emission standards. High strength steel finds extensive use in manufacturing critical components such as body panels, structural reinforcements, and crash zones due to their ability to withstand high stress while reducing overall vehicle weight. The rise in electric vehicle (EV) production further amplifies this demand, as lightweight materials play a crucial role in improving battery efficiency and vehicle range.
The construction segment is projected to witness significant growth with 6.32% CAGR in the coming years due to rapid urbanization and infrastructure development across the globe. Governments and private investors are allocating substantial resources to build sustainable and resilient infrastructure, including bridges, high-rise buildings, and transportation networks. Steel with high strength properties supports these efforts by offering exceptional load-bearing capacity, durability, and resistance to environmental stressors such as corrosion and seismic activity. The push for green building practices and energy-efficient structures further increases the reliance on advanced materials such as HSS, as they help reduce material usage without compromising performance. Additionally, innovations in fabrication and joining technologies simplify the integration of high strength steels into complex architectural designs, driving their adoption in construction projects.
Source: Polaris Market Research Analysis
Regional Analysis
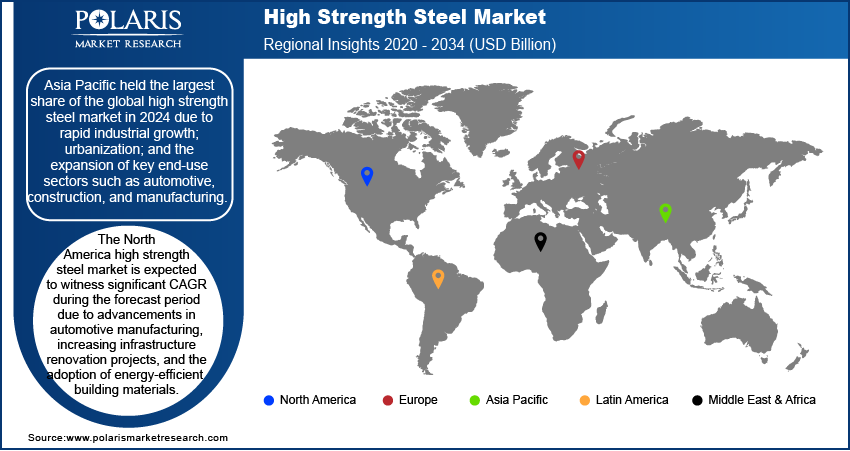
By region, the study provides the high strength steel market insights into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Asia Pacific held the largest share of the high strength steel market revenue with 44.0% share in 2025 due to rapid industrial growth; urbanization; and the expansion of key end-use sectors such as automotive, construction, and manufacturing. Countries such as China, India, and Japan significantly contributed to this dominance. China emerged as the largest market in the regional market, driven by its massive infrastructure development projects, high vehicle production rates, and substantial investments in renewable energy. The region’s strong focus on industrialization and government-backed initiatives to modernize infrastructure further fueled the demand for advanced materials such as HSS.
The North America high strength steel market is expected to witness significant CAGR of 6.55% during the forecast period due to advancements in automotive manufacturing, increasing infrastructure renovation projects, and the adoption of energy-efficient building materials. The US, as the leading market in the region, drives this growth with its focus on lightweight vehicle production to meet stringent fuel efficiency and emission standards. Additionally, substantial investments in modernizing aging infrastructure, including bridges, roads, and public buildings, have created a strong demand for durable, high-performance materials. The growing adoption of electric vehicles, coupled with the rising development of wind energy projects, further accelerates the adoption of high strength steel in the region.
Source: Polaris Market Research Analysis
Key Players and Competitive Analysis Report
Major market players are investing heavily in research and development to expand their offerings, which will help the high strength steel market grow even more. Market participants are also undertaking a variety of strategic activities to expand their global footprint, with important market developments such as innovative launches, international collaborations, higher investments, and mergers and acquisitions between organizations.
The high strength steel market is fragmented, with the presence of numerous global and regional market players. A few major players in the market include ArcelorMittal; Baoshan Iron & Steel Co., Ltd.; British Steel; China Ansteel Group Corporation Limited; Cleveland-Cliffs Inc.; Hyundai Steel Company; JSW; NIPPON STEEL CORPORATION; Nucor Corp; POSCO; SSAB AB; Steel Authority of India Limited; Tata Steel; thyssenkrupp AG; United States Steel Corporation; voestalpine AG.
List of Key Companies
- ArcelorMittal
- Baoshan Iron & Steel Co., Ltd.
- British Steel
- China Ansteel Group Corporation Limited
- Cleveland-Cliffs Inc.
- Hyundai Steel Company
- JSW
- NIPPON STEEL CORPORATION
- Nucor Corp
- POSCO
- SSAB AB
- Steel Authority of India Limited
- Tata Steel
- thyssenkrupp AG
- United States Steel Corporation
- voestalpine AG
High Strength Steel Industry Developments
- June 2026: AK Steel International announced its participation at ILA Berlin 2026. The company stated that it would highlight its expertise in providing high-performance steel and pure iron products for defense and aerospace applications. (source: aksteel.nl)
- April 2026: JSW Steel Ltd. formed a landmark joint venture with South Korea’s POSCO Group. The joint venture intends to set up a 6 MTPA greenfield integrated steel plant in Dhenkanal, Odisha. (source: jsw.in)
Future Outlook
The demand for high-strength steel is anticipated to witness steady growth during the forecast period, owing to its properties such as lightweight, strength, and high performance. The demand for high-strength steel is driven by industries such as the automotive industry, construction, aerospace, energy, and industrial segments that have a continuous need for lightweight and high-strength metals due to factors such as increased investments in electric vehicles, expansion of construction activities, safety regulations, and emission regulations. Innovation in advanced high-strength steel (AHSS), low-carbon steel production, and coatings technologies would result in improved quality.
High Strength Steel Market Segmentation
By Product Outlook (Revenue, USD Billion, 2021–2034)
- High Strength Low Alloy
- Dual Phase
- Transformation Induced Plasticity
- Bake Hardenable
- Martensitic
- Others
By Tensile Strength Outlook (Revenue, USD Billion, 2021–2034)
- Upto 600 MPa
- 600–900 MPa
- 900–1200 MPa
- 1200–1500 MPa
- Above 1500 MPa
By Application Outlook (Revenue, USD Billion, 2021–2034)
- Automotive
- Construction
- Mining Machinery
- Aviation & Marine
- Others
By Regional Outlook (Revenue, USD Billion, 2021–2034)
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
High Strength Steel Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 40.67 billion |
| Market Size Value in 2026 | USD 43.46 billion |
| Revenue Forecast by 2034 | USD 74.82 billion |
| CAGR | 7.01% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
high strength steel market FAQ's
• The global high strength steel market size was valued at USD 40.67 billion in 2026 and is projected to grow to USD 74.82 billion by 2034.
• The global market is projected to register a CAGR of 7.01% during the forecast period
• Asia Pacific had the largest market share of 44.0% in 2025.
• A few of the key market players are ArcelorMittal; Baoshan Iron & Steel Co., Ltd.; British Steel; China Ansteel Group Corporation Limited; Cleveland-Cliffs Inc.; Hyundai Steel Company; JSW; NIPPON STEEL CORPORATION; Nucor Corp; POSCO; SSAB AB; Steel Authority of India Limited; Tata Steel; thyssenkrupp AG; United States Steel Corporation; voestalpine AG
• High strength low alloy steel dominated with a 36.0% share in 2025.
• The automotive segment dominated the high strength steel market with 43.0% share in 2025.
Download Sample Report of high strength steel market
Please fill out the form to request a customized copy of the research report.