
Hydrogen Compressors Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Hydrogen Compressors Market Summary
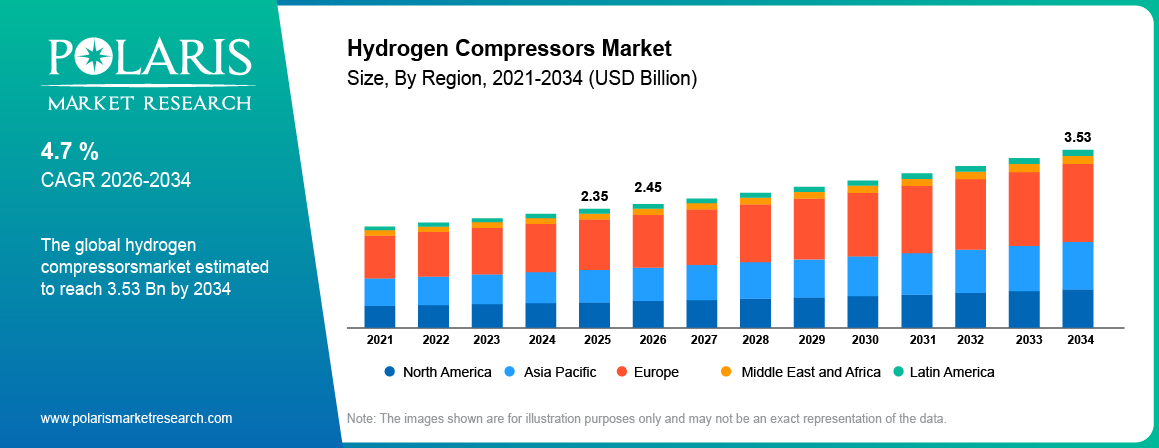
Global hydrogen compressors market size was valued at USD 2.35 billion in 2025. The market is anticipated to grow from USD 2.45 billion in 2026 to USD 3.53 billion by 2034, exhibiting the CAGR of 4.7% during the forecast period. The growth is driven by rising investment by governments, increase in strategic partnership between key players, and rising investment.
Market Statistics
Key Takeaways
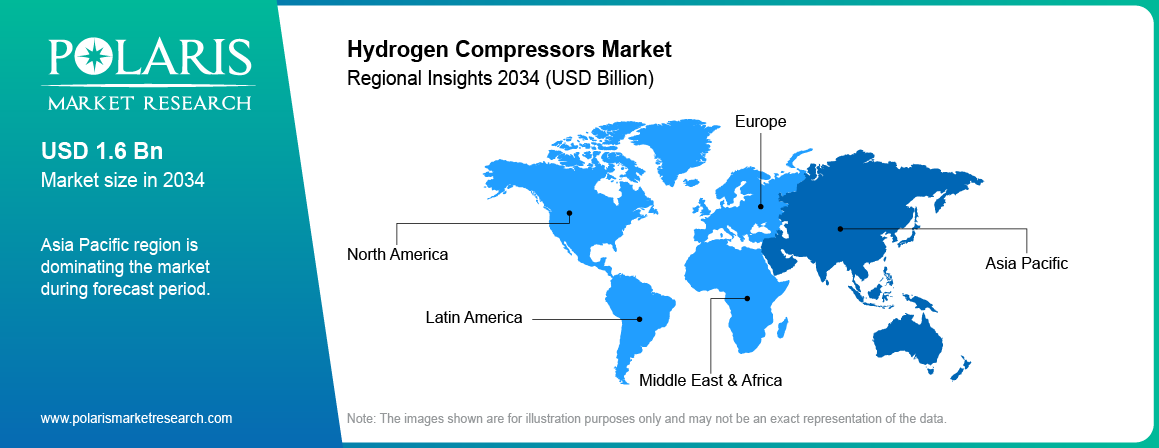
- Asia Pacific continues to hold the market's largest regional share of 41.2% in 2025, underpinned by rapid industrialization and government-backed clean-energy programs.
- Europe is expected to witness growth of CAGR 5.2% during the forecast period as clean-hydrogen funding programs translate into actual electrolyzer and infrastructure orders.
- North America is expected to witness growth of CAGR 4.5% during the forecast period driven by industrial gases, oil and gas, refining, and a rising need for hydrogen infrastructures
- The Multi-Stage segment is expanding fastest rate of CAGR 4.9% during the forecast period, a reflection of how well multi-step compression suits hydrogen's high compressibility and low molecular weight for pipeline and facility-filling applications.
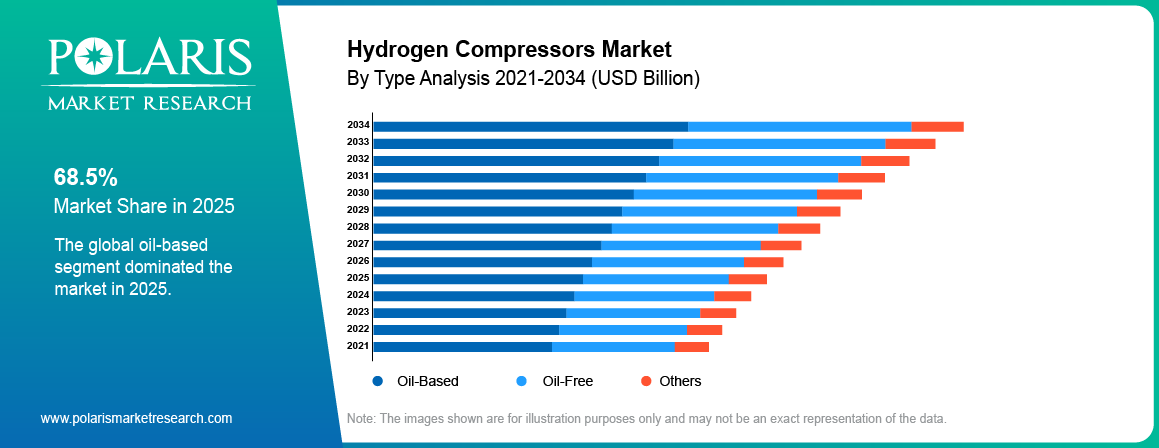
- Oil-Based compressors continue to hold the largest share of 68.5% in 2025, valued for their lower cost and longer service life relative to oil-free alternatives, even as oil-free technology gains ground in contamination-sensitive applications.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is Hydrogen Compressors?
A hydrogen compressor is a machine that increases the pressure of hydrogen gas to allow for its convenient storage, transportation, and supply. The compression of light gas like hydrogen is a complicated process compared to methane or CO₂ compression. This is because hydrogen molecules are smaller and the equipment requires stronger materials, tight-sealing valves, and proper cooling mechanisms to prevent gas leakage and damage to the machine. Hydrogen compressors are used in production, storage, pipeline transfer, and end-use at refueling stations.
As governments worldwide push toward net-zero targets and back that ambition with real electrolyzer and infrastructure spending, hydrogen compressors have moved from a specialized industrial component to a foundational piece of clean-energy infrastructure, This equipment determines whether hydrogen produced at scale can actually get to where it's needed.
Hydrogen Compressor Vs Traditional Compressor
| Feature | Hydrogen Compressor | Air / Natural Gas Compressor |
| Gas properties handled | Very low molecular weight, high diffusivity, embrittlement risk; requires specialized materials and seals. | Higher molecular weight gases; less stringent material compatibility. |
| Purity requirements | Fuel-cell-grade purity often required; oil-free designs (diaphragm, ionic liquid) to avoid contamination. | Industrial-grade purity typically sufficient; lubricated systems common. |
| Pressure range | Up to 700–900 bar for refueling; multi-stage compression common. | Typically lower pressures (up to ~300 bar for natural gas pipelines). |
| Efficiency & energy use | Electrochemical and ionic liquid designs offer higher efficiency vs traditional mechanical compressors. | Mature mechanical designs; efficiency gains more incremental. |
| Safety & regulations | Stringent safety codes (AFIR, SB-804, ISO 19880); hydrogen-specific oversight expanding. | Established codes (ASME, API) but less hydrogen-specific regulation. |
| Cost & CAPEX | Higher CAPEX due to specialized materials, safety systems, and emerging tech. | Lower CAPEX; mature supply chains and standardized designs. |
| Applications | Hydrogen refueling stations, electrolyzer integration, pipeline injection, industrial hydrogen loops. | General industrial, HVAC, natural gas transmission, manufacturing. |
Source: Polaris Market Research Analysis
Market Dynamics
Drivers : Clean-Energy Investment Pipelines Are Pulling Compressor Demand Forward
Government spending on clean energy is increasing investment in hydrogen production. Most hydrogen produced at low pressure needs to be compressed before it can be stored, transported, or sold. More hydrogen plants are being built as governments provide more funding and incentives for hydrogen projects. This increases the demand for hydrogen compressors, because they are an essential part of the production and storage process. Thereby driving the industry growth.
Drivers : Expanding Industrial Use Cases Are Broadening the Buyer Base
The hydrogen compressors market is expanding beyond the traditional oil and gas and petrochemical end-use sectors. Hydrogen compressors are being adopted in a growing number of applications in the food and beverage, pharmaceuticals, electronics, and textile industries, among others. Moreover, governmental initiatives to boost food and agricultural production will also contribute to the demand for hydrogen compressors. Diversification of the product applications is key to reducing market concentration by expanding the product usage base in different industrial sectors that follow divergent investment cycles.
Restraint : Lifecycle and Maintenance Costs Keep Oil-Free Compressors a Hard Sell
One of the major restraining factors for the hydrogen compressors market is high equipment and maintenance costs. Due to flammable nature of gas, compressors require special equipment to avoid leaks. Consequently, hydrogen compressor is more expensive than traditional gas compressor. Maintenance and safety check needed, which adds significantly to the costs, which may discourage small companies to adopt the technology and hence limits the growth of the market, especially in developing countries.
Opportunities : The Global Electrolyzer Buildout Is Creating a New Wave of Large-Project Demand
Hydrogen compressors are witnessing a surge in demand as hydrogen players around the world scale up their electrolyzer projects. Global hydrogen markets are seeing an increase in the number of projects under construction, which require compressors in their installations. For example, Germany’s Clean Hydrogen Coastline and the Hamburg Green Hydrogen Hub projects are large hydrogen projects, which involve multiple compressors. Therefore, for companies involved in the manufacture of compressors, the growing capital expenditures in the green hydrogen segment can be a great opportunity to secure continuous revenue through long-term contracts instead of shorter-term equipment sales.
Opportunities : Digital Monitoring and Predictive Maintenance Open an Aftermarket Services Runway
Compressor manufacturers can use digital technologies, including digital twins, artificial intelligence-enabled systems, and IoT technology enabled control systems, to help hydrogen companies maximize their compressor performance. These benefits attract customers to the manufacturers’ products. Additionally, the maintenance and energy account for a significant amount of the costs related to a compressor’s lifetime. Therefore, the technology helps in maximizing profits for both sides. Moreover, providing service solutions helps the manufacturers secure recurring revenues from post-sale services and maintenance contracts while enabling the clients to of performance monitoring and maintenance.
Market Segment Analysis
By Type: Oil-Based Compressors
Oil-based compressors dominated with 68.5% in 2025 in hydrogen compressors market due to their lower cost, durability, and longer operating life as compared to their oil-free counterparts. Moreover, the oil in them helps to reduce the temperature during the compression process, thus enabling the attainment of higher compression ratios. The oil-free compressors are used in applications where gas purity is of utmost importance. Nevertheless, in most cases, industrial and commercial entities prefer oil-based compressors because of their benefits over oil-free ones.
By Stage: Multi-Stage Compressors
The multi-stage segment is expected to witness significant growth of CAGR 4.9% during the forecast period due to its superior adaptability to hydrogen pipelines, storage tanks, and production facilities. These compressors enable dividing the compression process into several stages, which allows attaining better temperature control, improved efficiency, and reduced labor intensity. Due to the unique properties of the gas, single-stage compression is usually less efficient and, therefore, rarely used in large-scale industrial activities. Hence, the rising need for multi-stage compressors for achieving higher operational efficiency and reducing costs is driving this segment’s growth.
Emerging Technology Trends
| Trend | Description |
| Oil-free diaphragm & ionic liquid compressors | Shift from mechanical piston systems to oil-free designs delivering fuel-cell-grade purity; ionic liquid structures reduce contamination risk. |
| Electrochemical compression | Solid-state or electrochemical compressors replace mechanical systems, offering higher efficiency, lower energy use, and compact footprints for distributed refueling. |
| Modular & skid-mounted packages | Pre-engineered, plug-and-play compressor skids integrating compression, heat management, and controls in a single footprint. |
| IoT & AI integration | Embedding sensors and analytics for predictive maintenance, remote monitoring, and performance optimization. |
| High-pressure & multi-stage systems | Development of compressors capable of 700+ bar for FCEV refueling and pipeline injection. |
Source: Polaris Market Research Analysis
Regional Insights
Asia Pacific
Asia Pacific dominated with largest market share of 41.2% in 2025 due to rapid industrialization, urbanization, and supportive government policies for the growing need for hydrogen and renewable energy in the Asia Pacific region. China, Japan, and South Korea are making substantial investments in developing hydrogen fuel cells and associated infrastructure. Thus, the presence of major hydrogen compressor manufacturers such as Mitsubishi Power, is anticipated to propel the market growth substantially. This makes it evident that the region is self-reliant concerning the production of hydrogen compressors and hydrogen.
Europe
Europe is expected to witness growth of CAGR 5.2% during the forecast period. Government climate programs and investments in clean hydrogen are increasing demand for compressors. Funding from the European Commission, along with major hydrogen projects in Germany and other countries, is supporting new electrolyzer facilities and creating large compressor orders. In addition, rising investments in Europe’s oil and gas industry are creating further demand. This combination of clean-energy projects and traditional industrial applications is supporting strong regional market growth.
North America
North America is expected to witness growth of CAGR 4.5% during the forecast period driven by industrial gases, oil and gas, refining, and a rising need for hydrogen infrastructures. The growing need for industrial applications, cooling systems, and mobility products creates an increase in demand for compressors. Hence, manufacturers of compressors are developing and designating their distribution and service networks to address the rising demand in the region. Additionally, the presence of a strong industrial base allows companies to penetrate the market and build relationships with existing customers in the industrial gas equipment and hydrogen compressor sales sectors, supporting the growth of the hydrogen compressors market.
Middle East & Africa
Middle East & Africa region is expected to witness growth of CAGR 4.1% during the forecast period as several countries are planning to develop low-carbon hydrogen production for export purposes. The region has natural resource advantages and a legacy of oil and gas production and engineering know-how that can be leveraged to produce hydrogen compressors. Nevertheless, hydrogen projects require more time from project initiation to actual construction and installation of equipment, which may affect the market’s growth rate compared to more developed regions such as Europe.
Regulations and Standards in Key Region
| Region | Key Regulations / Standards | Relevance to Hydrogen Compressors |
| European Union | AFIR (Regulation (EU) 2023/1804); EN 17127:2024 for hydrogen refueling points; REPowerEU plan. | Mandates technical compliance for refueling stations; drives compressor performance and safety standards. |
| United States | Inflation Reduction Act (IRA) incentives; California SB-804 (hydrogen pipeline safety standards by 2028). | IRA accelerates infrastructure buildout; SB-804 imposes inspection regimes and safety oversight for compression/pipeline systems. |
| Asia-Pacific (China, India, Japan) | National hydrogen strategies; growing refueling infrastructure targets; industrial decarbonization policies. | Supports rapid market growth; APAC expected to dominate demand and highest CAGR. |
| Global / Cross-regional | ISO 19880 (hydrogen refueling), ISO 15869 (gaseous hydrogen storage), IEC 62282 (fuel cell technologies). | Provides international safety and performance benchmarks for compressor design and integration. |
Source: Polaris Market Research Analysis
Competitive Landscape
The hydrogen compressors market remains fragmented, with competition playing out project by project rather than through dominant market share held by any single vendor. Established industrial gas and turbomachinery players such as Atlas Copco, Siemens, Baker Hughes, Ingersoll Rand, compete alongside specialist compressor manufacturers such as Neuman & Esser, Hoerbiger, Howden Group, and PDC Machines, many of which have decades of experience adapting reciprocating and diaphragm compression technology specifically for hydrogen's technical demands. Recent competitive activity centers heavily on winning compressor-supply contracts for flagship electrolyzer and green hydrogen hub projects, particularly across Germany and wider Europe, rather than on M&A consolidation — vendors are competing primarily on technical track record, reliability, and total cost of ownership rather than on scale alone.
Key Companies List
-
Atlas Copco AB
-
Baker Hughes
-
HIPERBARIC
-
Hoerbiger
-
Howden Group
-
Hycomp Inc.
-
Mehrer Compression GmbH
-
Mitsubishi Power
-
Neuman & Esser Group
-
PDC Machines
-
Pure Energy Centre
-
Siemens
-
Sundyne
-
Burckhardt Compression AG
-
Ariel Corporation
-
HYDRO-PAC, Inc
-
SIAD Macchine Impianti S.p.A.
Recent Industry Developments
-
December 2025, KAJI TECHNOLOGY CORPORATION launched high-pressure hydrogen compressors in South Korea through its collaboration with KOREA GASGEN. KOREA GASGEN assembled the compressors into packaged units, completed hydrogen trials, and began sales for hydrogen stations and shipping facilities across the Korean market. (Source: kajitech.com)
-
March 2025, Atlas Copco Inaugurated a 270,000 sq. ft. manufacturing facility in Talegaon, Pune, producing air and gas compressors for CNG, biogas, and hydrogen applications, powered in part by a 1.3 MW rooftop solar installation. (Source: manufacturingtodayindia.com)
-
January 2024, REJOOL adopted Siemens Xcelerator as a Service to develop its PIONYR hydrogen compressors. The startup used NX, Teamcenter X, and Teamcenter Share to streamline engineering, simulation, product lifecycle management, and collaboration with suppliers and customers through a secure cloud-based digital workflow. (Source: semiwiki.com)
-
April 2024, Mitsui E & S Commercially launched a high-flow hydrogen compressor for refueling stations and production facilities, capable of compressing hydrogen up to 50 MPa at a 95 kg/hour flow rate. (Source: mes.co.jp)
Report Coverage
The hydrogen compressors market report emphasizes on key regions across the globe to provide better understanding of the product to the users. Also, the report provides market insights into recent developments, trends and analyzes the technologies that are gaining traction around the globe. Furthermore, the report covers in-depth qualitative analysis pertaining to various paradigm shifts associated with the transformation of these solutions.
Market Segmentation
By Stage Outlook (Revenue – USD Billion, 2021–2034)
-
Single-Stage
-
Multi-Stage
By Type Outlook (Revenue – USD Billion, 2021–2034)
- Oil-Based
- Oil-Free
- Others
By End User Outlook (Revenue – USD Billion, 2021–2034)
- Oil & Gas
- Chemical
- Transportation & Automotive
- Petrochemicals
By Regional Outlook (Revenue – USD Billion, 2021–2034)
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Hydrogen Compressors Market Report Scope
| Report Attributes | Details |
| Market size value in 2025 | USD 2.35 billion |
| Market size value in 2026 | USD 2.45 billion |
| Revenue forecast in 2034 | USD 3.53 billion |
| CAGR | 4.7% from 2026 – 2034 |
| Base year | 2025 |
| Historical data | 2021 – 2024 |
| Forecast period | 2026 – 2034 |
| Quantitative units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Segments covered | By Stage, By Type, By End-User, By Region |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Customization | Report customization as per your requirements with respect to countries, region, and segmentation. |
Source: Polaris Market Research Analysis
Hydrogen Compressor Market FAQ's
The hydrogen compressors market was valued at USD 2.35 billion in 2025 and is expected to reach value of USD 3.53 billion by 2034.
The Asia Pacific dominated with largest share of 42.8% share in 2025 driven by rapid industrialization and strong government support for hydrogen and renewable energy.
The market is expected to witness growth rate of CAGR 4.7% during the forecast period.
Some of the players operating in the industry Include Atlas Copco AB, Baker Hughes, Cook Compression, HIPERBARIC, Hoerbiger, Howden Group, Hycomp Inc., Ingersoll Rand, Mehrer Compression GmbH, Mitsubishi Power, Neuman & Esser Group, PDC Machines, Pure Energy Centre, Siemens, Sundyne, Burckhardt Compression AG, Ariel Corporation, HYDRO-PAC, Inc., SIAD Macchine Impianti S.p.A.
Oil-Based compressors continue to hold the largest share of 68.5% in 2025 due to their lower cost and longer service life relative to oil-free alternatives
A hydrogen compressor is mechanical equipment that raises the pressure of hydrogen gas so it can be safely stored, transported, and dispensed, which is an essential step because hydrogen produced by electrolyzers or reforming plants comes out at low pressure and must be compressed before it can move through pipelines, tanks, or refueling equipment.
Oil-based compressors use oil as a lubricant and cooling agent, making them less expensive and longer-lasting, which is why they hold the largest market share. Oil-free compressors avoid any risk of oil contamination and are preferred in applications where purity is critical, though they typically cost more upfront and over their operating life.
Multi-stage compressors split the compression process into several steps, which reduces the temperature rise, cuts labor requirements, and improves overall efficiency
Oil & gas and chemical processing remain the largest end-user industries, but demand is broadening into transportation & automotive, petrochemicals, food & beverage, pharmaceuticals, and other sectors that need the clean, dry, oil-free air these systems can deliver.
Growth is being driven primarily by rising clean-energy investment from governments and developing nations, the expanding buildout of electrolyzer and green hydrogen production facilities, and growing industrial demand for hydrogen across oil & gas, chemical, and transportation applications.
Download Sample Report of Hydrogen Compressor Market
Please fill out the form to request a customized copy of the research report.


