Laboratory Developed Tests Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Laboratory Developed Tests Market Summary
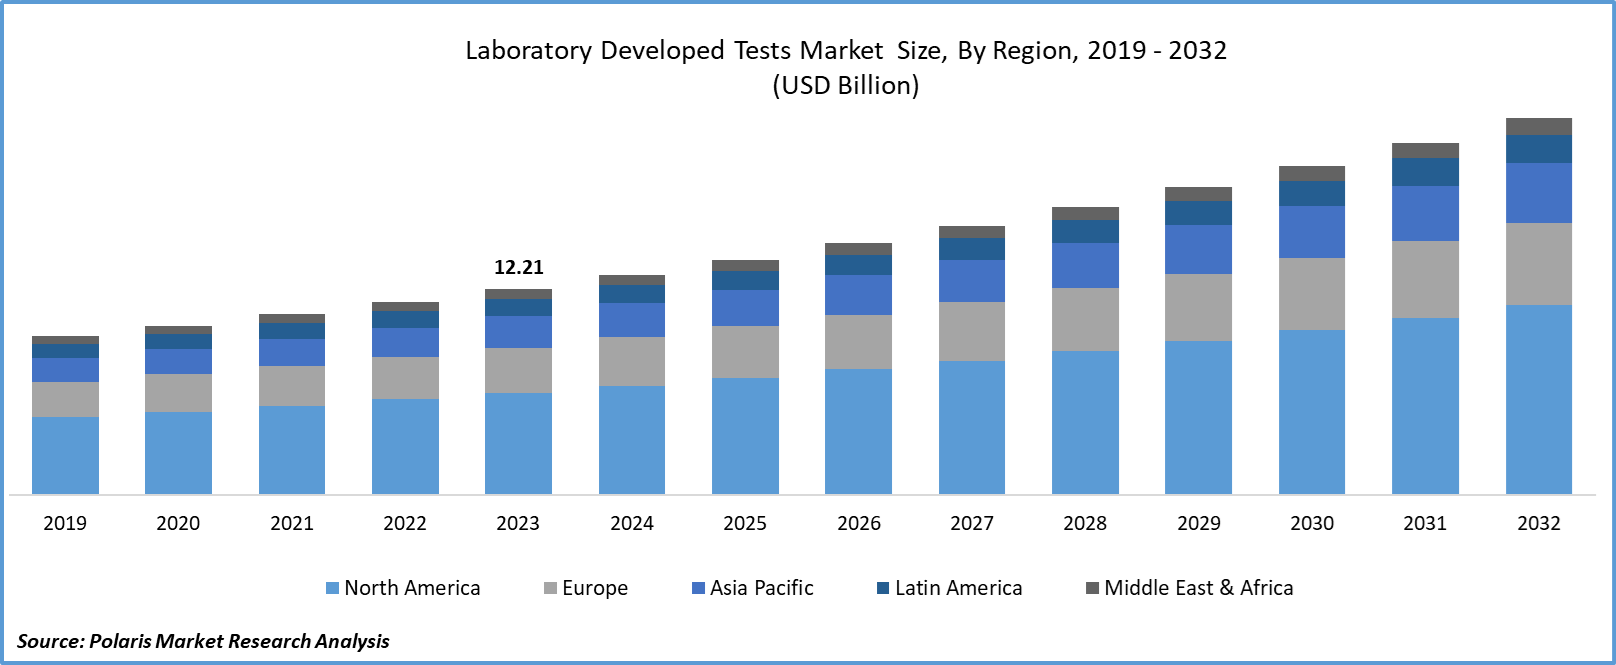
The global laboratory developed tests market size was valued at USD 14.16 billion in 2025. The market is projected to account for an 7.4% CAGR from 2026 to 2034. The LDT market growth is primarily driven by the rising prevalence of chronic diseases. The rising demand for personalized medicine is also having a favorable impact on the market landscape.
Market Statistics
Laboratory Developed Tests Market Key Takeaways
- North America led the global laboratory developed tests market with a 37.8% revenue share in 2025. Rising healthcare expenditure and government support contribute to the regional market dominance.
- Asia Pacific is projected to grow at an 8.6% CAGR. Increased initiatives towards the development and commercialization of laboratory developed tests drive the regional market growth.
- The molecular diagnostics segment led with a 26.1% share in 2025. This is due to the widespread use of the technology for the detection of all major viral and bacterial infections.
- The nutritional & metabolic disease segment is projected to grow at an 8.2% CAGR. The expansion of neonatal and genetic screening drives the segment’s rapid growth.
- The hospital laboratories segment held a 40.21% laboratory developed tests market share in 2025. The segment’s leading position is owing to the direct integration of hospital laboratories with clinical care.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What are laboratory-developed tests?
Laboratory-developed tests (LDTs) are diagnostic tests that are designed, manufactured, and performed within a single clinical laboratory. They assist in detecting various diseases, measuring biomarkers, or making therapeutic decisions. In contrast to commercial diagnostic tests, LDTs are created for the purposes of the very laboratory that performs them.
How Do Laboratory-Developed Tests Work?
Clinical need: A laboratory detects a particular need for the test that may not be fulfilled with the existing tests.
Development: The laboratory develops a testing methodology based on the target disease, biomarker, or a question from a clinical perspective.
Validation: The test result is validated to ensure reliability and reproducibility of the result.
Sampling: Patient samples such as blood or other types of samples are obtained based on the needs of the test.
Testing: Laboratory professionals process the samples using the developed testing methodology to detect or quantify the target.
Interpretation: The laboratory reviews the test results and interprets their clinical meaning.
Clinical decision: The laboratory delivers the test result to healthcare providers, which can assist with diagnosis, treatment selection, or patient monitoring.
Laboratory Developed Tests vs. Commercial Diagnostic Tests
Laboratory-developed tests (LDTs) are designed to be used in a particular clinical lab, while commercial diagnostic tests are designed to be used in a broader setting and are generally marketed to several health care facilities. The LDT vs FDA-approved test difference mainly revolves around their development, validation, authorization, and application.
| Comparison | Laboratory Developed Tests (LDTs) | Commercial Diagnostic Tests |
| Development | Created and developed by an individual laboratory | Created and developed by a diagnostic firm/manufacturer |
| Purpose | Performs the test in the same laboratory that created the test | Aims at performing the test in many laboratories |
| Test access | Tests for specialized and emerging medical purposes | Serves as standardized commercial tests |
| Test validation | Performance is set up by the laboratory for its purpose. | Performance is set up by the manufacturer in the process of creation of the product. |
| Test regulation | Subject to the regulation that applies to LDTs | Regulated and cleared under FDA approval |
| Modification of the test | The test method can be modified by the laboratory. | Test modifications usually require approval from the manufacturer. |
| Distribution | Not generally distributed as a commercial diagnostic product | Manufactured and distributed for clinical use |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
Laboratory Developed Tests Market Dynamics
Driver: Growing Prevalence of Chronic Diseases
The rising prevalence of chronic diseases is increasing demand for diagnostic services. According to the April 2026 OECD report, the number of newly diagnosed cases of noncommunicable diseases may increase by 31% in OECD countries by 2050. In addition, the report projects a 29% increase in the EU countries (source: oecd.org). Testing usually depends on where a patient is in the treatment process. Testing may be required at the beginning of treatment to diagnose the disease or even to monitor the disease progress during treatment. There will be a continued need for diagnosis in fields such as cancer, diabetes, heart-related diseases, and other chronic respiratory diseases. LDTs are useful when the lab needs to carry out tests that cannot be carried out using any other commercial test. Therefore, the continuous rise in chronic disease cases is expected to support increased demand for specialized lab testing over the longer term.
Driver: Rising Demand for Specialized Diagnostic Testing
Molecular diagnostics innovations are enabling the detection of a wider range of biomarkers. This creates a need for tests tailored to particular diseases, patients, or clinical conditions. LDTs can help bridge the gap for existing commercial test kits that do not provide sufficient data to meet clinical needs. This is especially true in fields like oncology diagnostics, where the treatment requires the analysis of molecular details. Testing strategies may also change as new biomarkers are discovered. In June 2026, Myriad Genetics announced improved accessibility of its Precise MRD test for breast, colorectal, and renal cancers. Such developments reflect the broader movement towards increasingly specific tests for cancer treatment.
Restraint: Reimbursement Uncertainty and Variation in Test Standards
Reimbursement remains a challenge for some laboratory-developed tests, especially if the test is new or addresses a special clinical condition. The payers might evaluate the clinical usefulness of the LDT differently and might offer reimbursement for the service. This may make it difficult for laboratories to predict how much revenue they will gain from the new test. The prices for the test might also differ depending on the testing company and health care setting. At the same time, the different methodologies of testing may complicate the comparability of results between laboratories. Validation and quality control procedures in laboratories should be consistent to ensure that the tests conducted are valid. These aspects may create uncertainty in the adoption of LDTs.
Opportunities: Expansion of Companion and Precision Diagnostics
The increasing shift toward biomarker-driven therapies has allowed laboratories to offer assays that support more specific therapeutic decision-making. Furthermore, drug manufacturers are increasingly developing drugs intended for small population groups, for whom existing diagnostic tests are not suitable. LDTs could be an option for laboratories to design assays based on new emerging biomarkers and clinical uses of them. This can become especially important in oncology when molecular findings affect the choice of a therapy. New laboratory developed test market opportunities may arise as new biomarkers enter clinical practice.
Opportunities : Development of Tests for Emerging Clinical Needs
Emerging areas of medicine may require testing before commercial assays are available. Genomics, infectious diseases, and rare diseases are creating testing targets for new assays. Specialized laboratories with the requisite skill sets can meet these needs by creating assays for biomarkers with few testing alternatives. This is an area where there is the potential for development due to low population numbers or fast-moving testing requirements. LDTs may also facilitate clinical adoption of new technologies while evidence and testing methods are being developed.
Trend: Greater Use of Multiplex Testing
Laboratories are now developing assays that allow multiple targets to be analyzed from a single patient sample. Multiplex testing may be relevant when symptoms overlap across diseases or when several biomarkers must be analyzed simultaneously. Development of LDTs is especially relevant for such an approach, as laboratories have an opportunity to design testing panels according to their needs. The method is becoming increasingly relevant in infectious disease testing, oncology, and genomics. Increased use of multiplex assays could influence LDT development and shift demand toward testing panels rather than single-target tests.
Trend: Increasing Integration of Advanced Molecular Methods
The use of new molecular approaches in LDT development is becoming more common as laboratories gain better access to testing platforms that enable them. Approaches such as next-generation sequencing (NGS) and digital PCR may aid in identifying genetic mutations that cannot be evaluated using traditional techniques. The relevance of using these new approaches becomes evident when there is a need for increased sensitivity or a more comprehensive approach toward genetic markers. As clinical laboratories develop, LDT developers may use them to address many diagnostic questions. This laboratory developed tests market trend likely expand the types of tests laboratories can develop.
Regulatory Landscape: FDA LDT Rule Status (2026 Update)
Are laboratory developed tests regulated by the FDA in 2026? The FDA’s policies relating to LDTs have been revised following a ruling from a U.S. federal court that struck down the 2024 FDA rule. LDTs are not currently regulated under the new framework for medical devices introduced through this rule. Clinical laboratories remain regulated through CLIA guidelines; other government guidelines may also apply.
In May 2024, the FDA issued a final rule that brought LDTs more clearly within its medical device regulations. The rule included plans to phase out the agency's general enforcement discretion for these tests. Laboratory and pathology groups challenged the rule in court.
On March 31, 2025, the U.S. District Court for the Eastern District of Texas vacated the rule in American Clinical Laboratory Association v. FDA and related litigation. The FDA chose not to appeal the decision. The agency later removed the regulatory changes introduced in 2024, returning the relevant regulatory text to its earlier form (source: congress.gov).
The FDA LDT rule vacated decision is important for laboratories because the additional FDA requirements planned under the 2024 rule no longer form the basis of LDT oversight. Laboratories do not have to prepare for the phased FDA requirements that would have followed under that framework.
The CLIA vs FDA regulation laboratory tests distinction is therefore important in 2026. CLIA, which is regulated by CMS, continues to set standards related to laboratory quality. Such standards pertain to matters relating to laboratory personnel, test methods, quality control, and reporting. Regulations imposed by FDA may still pertain to specific products or services that fall within the agency’s authority.
For LDT developers, the change removes a significant source of anticipated compliance costs. It also gives laboratories more clarity on the regulatory framework currently governing their testing activities. Future policy changes could still affect the market.
Source: Polaris Market Research Analysis
Laboratory Developed Tests Market Report Segmentation
| Segmentation Axis | Segments |
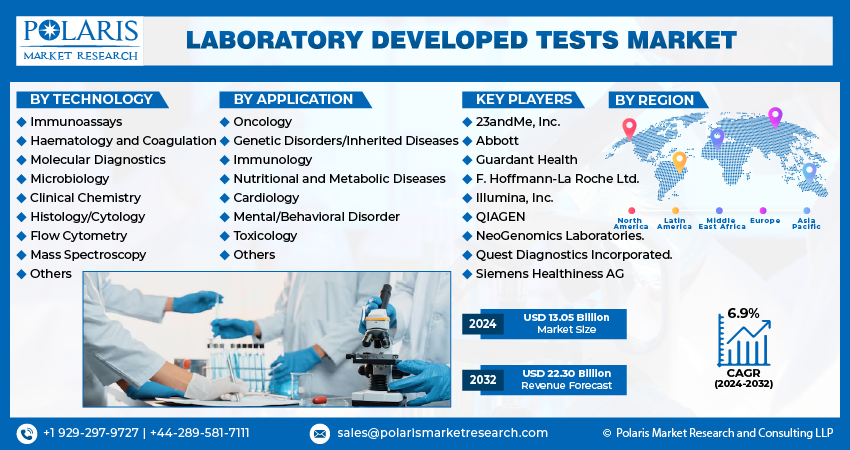
| By Technology | Immunoassays · Hematology & Coagulation · Molecular Diagnostics · Microbiology · Clinical Chemistry · Histology/Cytology · Flow Cytometry · Mass Spectrometry · Others |
| By Application | Oncology · Genetic Disorders/Inherited Diseases · Infectious Diseases · Immunology · Nutritional & Metabolic Disease · Cardiology · Mental/Behavioral Disorder · Toxicology · Others |
| By End Use | Hospital Laboratories · Private/Independent Reference Laboratories · Specialty Diagnostic Laboratories · Other (Academic/Research) |
| By Region | North America (U.S., Canada) · Europe (UK, Germany, France, Italy, Spain, Netherlands, Russia, Rest of Europe) · Asia Pacific (China, India, Japan, Malaysia, Indonesia, South Korea, Rest of Asia Pacific) · Latin America (Brazil, Mexico, Argentina, Rest of Latin America) · Middle East & Africa (Saudi Arabia, UAE, Israel, South Africa, Rest of Middle East & Africa) |
Source: Polaris Market Research Analysis
By Technology
The molecular diagnostics segment led the global laboratory developed tests market with an 26.1% share in 2025. Molecular methods help laboratories analyze genetic material and detect specific disease markers. They are thus useful in various applications of clinical testing. Laboratories utilize molecular methods for the detection of infectious agents and genetic mutations. Other applications include the analysis of biomarkers that are related to cancers and inherited diseases. The increasing number of molecular targets provides laboratories with opportunities for the development of tests according to their specific clinical needs. They may also adapt their molecular diagnostics to newly discovered biomarkers and new testing requirements. All these factors contribute to its leading position in the LDT market.
The immunoassays segment is projected to witness rapid growth at an 8.1% CAGR. Immunoassays are commonly used to detect and measure specific components in patient samples. They can be applied in several areas, including infections, hormonal measurement, cancer detection, and autoimmune diseases. This technique gives laboratories a way to test specific proteins, antibodies, or other biomarkers. LDTs also allow laboratories to develop their own immunoassays when existing commercial tests do not meet clinical needs. The increased interest in biomarker-based testing has opened up new avenues for the development of specialized immunoassays. Improvements in assay techniques have also supported the development of specialized testing methods. This is expected to fuel growth in this segment over the forecast period.
By Application
The oncology segment led the global laboratory developed tests market with a 22.8% share in 2025. Cancer diagnosis can require testing for certain genetic and molecular markers. LDTs are useful in assisting laboratories in developing tests for biomarkers that may not be covered in the available commercial tests. These tests can assist in cancer detection as well as identifying molecular alterations in the tumor. They are also utilized in evaluating biomarkers that can be useful in choosing a treatment and monitoring the disease. The growing demand for precision oncology has made LDTs increasingly important. As new biomarkers and therapeutic targets are developed, LDTs can be adapted accordingly. The wide application of LDTs has made oncology the dominant market segment.
The nutritional & metabolic disease segment is projected to grow at an 8.2% CAGR. Tests are widely used to diagnose metabolic and nutritional disorders. LDTs could prove to be valuable in helping laboratories develop tests for specific needs related to metabolic testing. Such tests can aid in the diagnosis of metabolic markers that might not necessarily be included in routine testing packages. They can also be customized in case the laboratory requires tests to be performed for other diseases. The rising focus on early diagnosis of diseases and the increasing use of biomarker-based diagnosis should contribute to increased demand for metabolic testing. This is projected to drive the market growth of the nutritional & metabolic diseases segment over the forecast period.
Real-World Applications / Use Cases
| Application | Recent Laboratory Development Test Examples |
Cancer biomarker detection | June 2026: Mayo Clinic Laboratories highlighted its newly introduced Genome-Wide Methylation Array for brain tumor testing. The assay examines methylation patterns across the genome and can help classify difficult CNS tumors. It is a practical example of specialized laboratory testing being used when routine pathology does not provide enough information. (source: mayocliniclabs.com) |
Companion diagnostics | April 2025: Quest Diagnostics launched AD-Detect Abeta 42/40 and p-tau217 Evaluation is a laboratory-developed test that combines blood biomarkers to identify patients who may be candidates for early Alzheimer’s antibody treatment. The example shows how an LDT can provide biomarker information that supports treatment decisions. (source: questdiagnostics.com) |
Rare-disease identification | April 2026: Mayo Clinic Laboratories reported advances in testing for Birt-Hogg-Dubé syndrome, a rare inherited kidney cancer syndrome. Its updated testing helped address gaps in genetic diagnosis. The example shows how specialized laboratory testing can be used when rare disorders are difficult to identify through routine testing. (source: mayocliniclabs.com) |
Source: Polaris Market Research Analysis
By End Use
The hospital laboratories segment led the global laboratory developed tests market with a 40.21% share in 2025. Hospital labs conduct different types of tests on their patients who are admitted to the hospital. There might be a need for testing in situations where the condition requires specialized testing. The use of LDTs enables such labs to create a method of testing that meets their clinical needs, which is essential in situations where there is no commercial test available. Hospital labs can use LDTs to facilitate diagnosis of complicated cases. Timely testing will also enhance the use of laboratory-developed tests in hospitals. These are some reasons hospital labs remain at the forefront of the LDT industry worldwide.
The private/independent reference laboratories segment is projected to grow at a 7.8% CAGR. Such laboratories conduct specialty tests for hospitals, doctors, and other healthcare institutions. Their portfolio may comprise tests that need certain lab-specific skills. LDTs can assist reference labs in developing tests for specific biomarkers or rarer diseases. This enables them to provide testing services for which no standard product is available. In-demand specialized testing services can also support the development of LDT services. Reference laboratories can continue developing their tests upon the introduction of new biomarkers into practice. These factors are expected to promote growth in the private/independent reference laboratories market share over the forecast period.
Source: Polaris Market Research Analysis
Regional Insights
North America
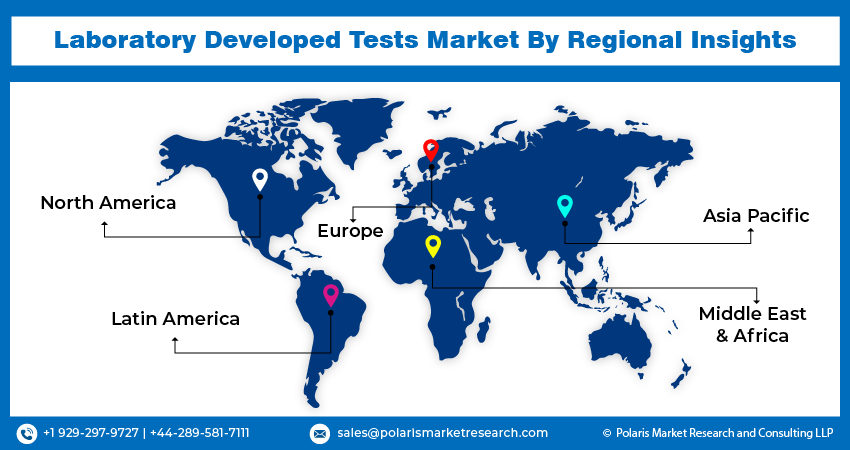
North America led the global laboratory developed tests market with an 37.8% share in 2025. This region has a large number of hospitals and private laboratories offering specialized tests. There is also high demand for molecular tests within this region in cancer and genetic diseases. Private laboratories within this region have established specialized tests for medical needs not covered by commercial tests. This makes the presence of major diagnostic services an added advantage to the regional market. The U.S. constitutes most of the demand from this region because of the advanced healthcare and laboratory systems in place. Canada also contributes to regional demand due to its adoption of specialized diagnostic services. All these factors have helped North America maintain its leading position in the global LDT market.
Asia Pacific
Asia Pacific is projected to grow at an 8.6% CAGR. There is an increasing demand for diagnostic testing because of the expansion of healthcare services. Many nations, including China, Japan, India, and South Korea, have invested in laboratory infrastructure and testing technology. The use of molecular diagnostics is also contributing to the increasing demand for specialized laboratory testing. LDTs help fill gaps in testing not covered by commercial assays. Growing awareness of the importance of early diagnosis is driving adoption of diagnostic services across the region. Growth in private diagnostic laboratories is also adding value to the opportunity for specialized testing.
Europe
Europe accounted for a 29.6% share of the laboratory developed tests market in 2025. A well-established network of hospitals' laboratories and independent centers for diagnostics exists in the region. There is a need for specialized tests in the fields of oncology, genetic disease, and infections. Laboratories apply advanced molecular and immunological methods in order to meet the needs of diagnostics. The presence of developed healthcare systems is favorable for the implementation of laboratory tests. Germany, the UK, France, and Italy make up part of the regional demand through their laboratory networks. Research in genomics and multiomics-driven precision medicine contributes to the development of specialized tests as well. These factors have helped the Europe laboratory developed tests market to maintain a significant share in the global market landscape.
Latin America
The Latin America laboratory developed tests market is projected to grow at an 6.9% CAGR. Demand for diagnostic tests is rising as medical practitioners expand lab services. Brazil and Mexico are the two leading contributors to the region’s testing activity. Additionally, private laboratories are expanding their range of diagnostic tests in key markets. This has increased the need for specialized tests which have been developed to cater to certain clinical needs. Molecular testing is becoming increasingly important, especially in cancer and genetic diseases. When no commercial diagnostic tests meet a specific testing need, laboratories can use LDTs. Improvements in laboratory facilities are expected to promote the use of specialized testing in Latin America.
Middle East & Africa
The Middle East & Africa laboratory developed tests market is anticipated to account for an 6.4% CAGR. There has been increased demand for diagnostic services with the growth of healthcare systems through laboratory expansion. Countries such as Saudi Arabia, UAE, Israel, and South Africa have established specialized diagnostic centers. The markets are increasingly using molecular and genetic tests for diagnostics. The laboratories can utilize LDTs to fulfill their clinical requirements where the commercial tests cannot be utilized. The demand for LDTs will rise on account of the expansion of the oncology and genetic testing segments. Moreover, private healthcare providers are making investments in laboratory testing facilities to support more complex testing needs. This is expected to boost the adoption of LDTs in the region during the forecast period.
Source: Polaris Market Research Analysis
Competitive Landscape
The laboratory developed tests market has a fragmented competitive landscape, with large diagnostics networks competing against specialized laboratories. Competition is influenced by the ability to offer tests based on specific clinical needs and consistent test performance. Laboratories with strong molecular test development capabilities are favored in areas like oncology, genetic diseases, and rare diseases. Laboratories also compete based on the availability of test types not offered in commercial diagnostics.
Test development remains an area of competition. Laboratories are developing technologies such as sequencing and molecular testing to develop more tests. The ability to develop and validate assays within the workflow process is another area that influences competitive position. Turnaround times also play a role in determining which laboratory gets selected when a test helps inform treatment decisions.
Commercial diagnostic companies also compete in the marketplace. Commercial diagnostic companies provide standardized testing, which can be performed in multiple laboratories. LDT providers must focus on testing situations where customization provides a clinical advantage. Regulations, reimbursement policies, laboratory accreditation, and quality measures also shape the competitive approach. As demand for diagnostics grows, the trend toward more specialized testing is expected to continue.
Vendor Positioning
| Tier | Representative Players | Positioning |
| Established reference & hospital-network laboratories | Labcorp, Quest Diagnostics Incorporated, Mayo Clinic Laboratories, ARUP Laboratories, Inc., NeoGenomics Laboratories, Inc. | Large testing networks with established clinical laboratory operations. Their LDT presence is supported by broad test menus and specialized reference testing. |
| Diagnostic technology providers | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers AG | Strong presence in laboratory diagnostics and testing platforms. These companies supply technologies used across routine and specialized clinical testing. |
| Genomics & molecular testing companies | Illumina, Inc., QIAGEN N.V., Guardant Health, Inc., 23andMe | More focused on genetic and molecular testing. Their offerings cover sequencing, biomarker analysis, and other forms of genomic testing. |
| Specialized testing technology | Quanterix Corporation | Focuses on highly sensitive biomarker measurement. Its technology is suited to specialized testing where low levels of biological markers need to be detected. |
Source: Polaris Market Research Analysis
Top Laboratory Developed Test Companies
- 23andMe
- Abbott Laboratories
- ARUP Laboratories, Inc.
- F. Hoffmann-La Roche Ltd
- Guardant Health, Inc.
- Illumina, Inc.
- Laboratory Corporation of America Holdings (Labcorp)
- Mayo Clinic Laboratories
- NeoGenomics Laboratories, Inc.
- QIAGEN N.V.
- Quanterix Corporation
- Quest Diagnostics Incorporated
- Siemens Healthineers AG
Recent Developments
- September 2026: Quest Diagnostics announced that U.S. Apple Health app users can conveniently purchase a tailored Quest laboratory test panel directly through the app on iPad and iPhone later this year. The company stated that the panel is designed to deliver preventive health insights and includes over 50 biomarkers for the assessment of organ function and cardiometabolic health. (source: questdiagnostics.com)
- September 2026: Guardant Health received FDA approval for Guardant360 CDx as a companion diagnostic for AstraZeneca’s camizestrant in patients with advanced breast cancer. The approval expands the use of blood-based biomarker testing to guide treatment selection. (source: guardanthealth.com)
Future Outlook
The laboratory test market is likely to remain relevant as laboratories adapt to changing diagnostic needs. The need for specialized tests would enable the development of more assays for conditions such as cancer, genetic conditions, and rare diseases. Molecular testing advancements would also enable laboratories to test for more biomarkers. The regulatory status of LDTs in the U.S. is significant in the market, particularly following the overturning of the 2024 FDA ruling. The laboratories would also look at testing for specialization due to the rising importance of accuracy. Growth in the precision medicine industry could also drive demand for tests that support treatment decisions. However, reimbursement and practice differences could pose challenges. In summary, the market would develop around clinical needs for specialization.
Research Methodology
The laboratory developed tests market analysis draws on a blended primary- and secondary-research process. Secondary research establishes the initial market map, using regulatory filings (FDA, CMS/CLIA records), company annual reports and investor presentations, peer-reviewed clinical literature, and proprietary industry databases to identify segment boundaries, historical revenue trends, and the competitive landscape. This desk research builds an initial top-down estimate of global and regional market size.
Primary research follows, consisting of structured interviews with laboratory directors, clinical pathologists, reimbursement specialists, and executives at diagnostic and reference-laboratory companies. These conversations validate segment-level assumptions, surface emerging technology adoption patterns (e.g., NGS, AI-assisted interpretation), and confirm regulatory interpretation. They include current treatment of LDTs under CLIA following the 2025 vacatur of FDA's LDT Final Rule. Bottom-up estimates built from primary inputs are triangulated against the top-down secondary figures to reconcile any variance.
Final figures pass through multi-stage analyst review before publication, and the laboratory developed tests market is revisited on a defined cadence to incorporate new regulatory developments, company disclosures, and competitive moves as they occur.
Laboratory Developed Tests Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 14.16 billion |
| Market Size Value in 2026 | USD 15.19 billion |
| Market Forecast 2034 | USD 26.97 billion |
| CAGR | 7.4% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Laboratory Developed Tests Market FAQ's
The laboratory developed tests market size was valued at USD 14.16 billion in 2025. The market is projected to grow to USD 26.97 billion by 2034.
The market is projected to account for an 7.4% CAGR from 2026 to 2034.
North America held the largest market share of 37.8% in 2025. This is owing to rising healthcare expenditure in the region.
The nutritional & metabolic disease segment is anticipated to account for an 8.2% CAGR. The segment’s growth is driven by the expansion of neonatal and genetic screening.
A few of the key market players include 23andMe; Abbott Laboratories; ARUP Laboratories, Inc.; F. Hoffmann-La Roche Ltd; Guardant Health, Inc.; Illumina, Inc.; Laboratory Corporation of America Holdings (Labcorp); Mayo Clinic Laboratories; NeoGenomics Laboratories, Inc.; QIAGEN N.V.; Quanterix Corporation; Quest Diagnostics Incorporated; and Siemens Healthineers AG.
Not in the same way as under the FDA's 2024 LDT rule. A federal court vacated that rule in March 2025, and the FDA did not appeal the decision. The agency later removed the related changes from its regulations. Clinical laboratories still have to meet CLIA regulations. State rules and other federal requirements can also apply.
An LDT is made and used by the laboratory that developed it. A commercial test is made by a diagnostic company and sold for use by other laboratories or healthcare providers. Commercial tests can go through FDA clearance or approval. LDTs are generally handled within the laboratory's own testing system and are subject to CLIA requirements.
Download Sample Report of Laboratory Developed Tests Market
Please fill out the form to request a customized copy of the research report.