
Medical Exoskeleton Market Size, Share, Trends and Forecast, 2026–2034
REPORT DETAILS
Medical Exoskeleton Market Summary
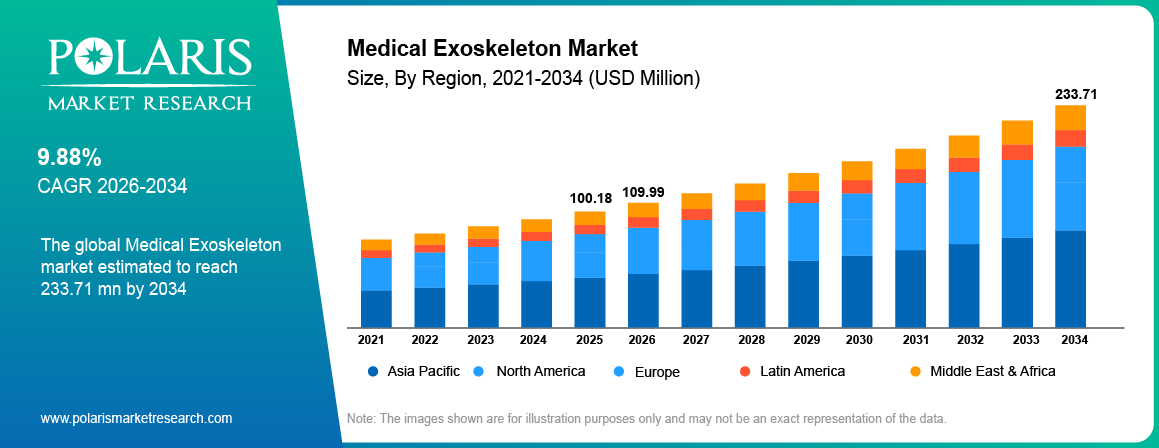
The global medical exoskeleton market was valued at approximately USD 100.18 million in 2025 and is projected to reach USD 233.71 million by 2034, growing at a CAGR of 9.88% during 2026–2034. The growth is driven by rising prevalence of spinal cord injury, increase in geriatric population, and technological advancement.
Market Statistics
Key Takeaways
- In 2025, North America medical exoskeleton market accounted for the largest share of 46.21%, driven by the region’s advanced healthcare facilities and extensive rehabilitation services
- Europe is expected to witness growth of CAGR 9.4% during the forecast period driven by the region’s ageing population and well-developed healthcare services
- The Asia Pacific is anticipated to witness growth of CAGR of 11.2% during the forecast period driven by a rise in healthcare infrastructure and investment in advanced rehabilitation services across the region
- The rigid exoskeletons segment dominated with largest share of 58.6% in medical exoskeleton market size driven by the demand for equipment that offers a firm attachment to the body to aid movement and assist in rehabilitation
- The lower-limb exoskeleton segment with largest share of 62.4% in medical exoskeleton industry driven by the increasing demand for rehabilitation devices and body movement support equipment for the lower limbs.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is Medical Exoskeleton?
A medical exoskeleton is a wearable robotic or orthotic device worn over the legs, hips or arms which support, restore or train the motor function of individuals with disabilities resulting from spinal cord injury, stroke, multiple sclerosis, cerebral palsy or other neurological and musculoskeletal diseases. In other words, it is a mechanical or electromechanical structure worn on limbs that enables patients to stand up, walk or perform other movements during treatment or in everyday life.
The market for medical exoskeletons is bifurcated into rehabilitation exoskeletons and personal exoskeletons. While the former is procured by clinics and physiotherapy centers for physical therapy-assisted gait training, the latter is purchased by individuals for home use and received upon physician prescription. Personal exoskeletons are used by people with spinal cord injury to stand or walk and is increasingly popular in the U.S. due to developments in reimbursement policies and self-balancing technologies that reduce the need for crutches.
How Does a Medical Exoskeleton Work?
Medical exoskeletons can be described as external mechanisms that aid the normal body functions in humans through the application of wearable external devices. These machines are usually attached to the limbs or torso and function by allowing, assisting, or even improving the movement range of the body part being supported. Medical exoskeletons consist of sensors that track the user’s body movements and respond accordingly by transmitting information to a control center. These exoskeletons also have built-in small motors that enable them to provide mechanical power. The control system, therefore, regulates and oversees the operation of these external mechanized devices. Some exoskeletons utilize mechanical components such as springs or gears. This technology is used mainly to increase or restore a person’s mobility and functionality following an injury, illness, or the effects of aging.
The growing global demand for rehabilitation services is driving the medical exoskeleton market. A high incidence of injuries and diseases among populations requires long-term patient care and post-surgery rehabilitation. Medical exoskeletons can be used during rehabilitation to help patients regain motor skills and mobility. For instance, medical exoskeletons can provide clinicians with an effective tool for gait training. In addition, medical exoskeletons can reduce therapists’ workload and offer patients a greater range of motion during rehabilitation. The rising emphasis on improving therapeutic recovery has prompted the increased use of medical exoskeletons in hospitals, rehabilitation centers, and clinics.
The rising global geriatric population drives the medical exoskeleton market. According to the Eurostat, about 22.0% of the EU’s roughly 450.6 million residents are aged 65 or older of population are aged 65 years and above. The growing number of aged individuals is associated with a higher prevalence of chronic diseases, such as Parkinson’s disease, which severely limits lower limb mobility and causes motor dysfunction. For instance, elderly people often complain of muscle weakness, lack of coordination, and reduced balance, which increases the risk of falls and injuries. Medical exoskeletons can be used to offer physical assistance and support to senior patients. Moreover, medical exoskeletons can help the aged regain motor function and mobility after an accident or surgery. These characteristics make medical exoskeletons highly suitable for use in rehabilitation centers and hospitals (Source: ec.europa.eu).
Impact of AI on Market
- Artificial intelligence (AI) helps medical exoskeletons detect patient movements and provide suitable support during rehabilitation.
- AI-powered systems can adjust assistance based on patient needs, improving comfort and movement control.
- AI helps therapists monitor patient progress and personalize rehabilitation programs.
- Machine learning can improve movement prediction, helping devices respond more naturally to user actions.
- Growing AI integration is encouraging innovation and may improve the safety, usability, and effectiveness of medical exoskeletons.
Market Dynamics
Driver: Rising Prevalence of Spinal Cord Injury (SCI) and Stroke
Spinal cord injury and stroke incidence is increasing, which elevates the need for medical exoskeletons. According to the Spinal Injuries Association, an estimated 4,400 individuals are diagnosed with SCI every year. Spinal cord injuries can occur at multiple levels of the spine, while stroke affects the brain, thus, causing serious damage to motor function or balance. Additionally, these patients usually require a long-term therapy to relearn or improve motor function and mobility. Medical exoskeletons can be used in rehabilitation to train patients to walk and perform certain movements repetitively. Moreover, therapists can integrate these devices into their rehabilitation programs. With the growing demand for effective post-stroke therapy, the medical exoskeleton market will continue to grow due to increased adoption in hospitals and rehabilitation centers (Source: spinal.co.uk).
Driver: Growing Reimbursement for Personal-Use Products
Reimbursement of hospital expenditures on personal-use products spurs the global medical exoskeleton market growth. These devices are unaffordable for several patients. Introducing insurance and health-related reimbursement programs can impact the number of patients who can use these expensive devices. Therefore, personal-use medical exoskeletons reimbursement will increase the market growth as patients can choose an appropriate treatment option. However, insurance coverage varies depending on the type of country, exoskeleton devices, and indications. Overall, reimbursement growth will drive the global medical exoskeleton market.
Driver: Increasing Clinical Adoption of Medical Exoskeletons
The high clinical adoption of medical exoskeletons contributes to the market growth. Clinical adoption is considered as one of the critical factors influencing the growth trajectory of the medical exoskeleton market. Exoskeletons can be used in hospitals and rehabilitation centers to provide a better rehabilitation program for patients with various conditions. The devices can be utilized for repetitive upper- and lower-body movements or can provide weight support during walking training. Moreover, therapists can integrate medical exoskeletons into their rehabilitation programs and treatments to achieve a better result. The rising clinical adoption of medical exoskeletons and increasing awareness of these devices among clinicians can drive the market growth. Moreover, relevant clinical research and training programs on medical exoskeletons can support market growth in the future.
Restraining Factor and Adoption Challenge: High Cost of Medical Exoskeletons
The high cost of medical exoskeletons acts as a primary barrier to market entry. These products are complex and require a lot of maintenance and service. Their exorbitant purchase price may prove to be unviable for the hospital and the individual buyer. With this, the capital required for sustaining such exoskeletons becomes a concern, especially for small-scale rehabilitation facilities. This impacts the growth of the market, especially in underdeveloped countries.
Restraining Factor and Adoption Challenge: Variation in Payer Coverage
The variation in coverage by payers is a significant challenge in the medical exoskeleton market. For instance, some insurers may cover particular products but not others. The same coverage terms may also differ from one payer to the other. This may discourage individual buyers and healthcare facilities from considering such an investment.
Restraining Factor and Adoption Challenge: Patient Suitability
The suitability of medical exoskeletons for use by patients presents a significant restraint to the market. Not all patients are considered suitable for upper-body and lower-body robotic rehabilitation devices. A patient’s body type and muscle capacity, among other factors, must be considered before determining if they can use a medical exoskeleton. Conditions such as reduced muscle strength and range of motion and the ability to perform coordinated movements may prevent a patient from using a medical exoskeleton.
Restraining Factor and Adoption Challenge: Lack of Skilled Professionals
A significant portion of healthcare professionals does not have the skills and knowledge to operate and monitor medical exoskeletons. For instance, healthcare workers must understand how the robots work, how they fit into the patient’s body, and how to operate them. Moreover, they must also learn how to deal with complications that may arise during the treatment. This may prove to be a challenge, mainly for small-scale rehabilitation facilities.
Restraining Factor and Adoption Challenge: Device’s Weight and Comfort
The weight and comfort of medical exoskeletons impact the rate at which they are used in rehabilitation facilities. For instance, devices that are heavy and uncomfortable may prove to be more of a burden than a solution. These may discourage the healthcare workers from using them and thus lower the adoption rate. Manufacturers are considering developing a lighter and more comfortable model for the patients.
Restraining Factor and Adoption Challenge: Battery Limitations
The limitation of the battery of a medical exoskeleton may present a challenge in its adoption. The battery plays a role of a power supply, providing electricity to operate the robotic device. The fact that the power supply has its limits is a significant hindrance to the extensive use of medical exoskeletons. A healthcare professional would want to utilize their investment by ensuring that the battery can last longer between charges.
Restraining Factor and Adoption Challenge: Problem of Device Fit
The problem of fitting lies in the fact that medical exoskeletons must be adjusted to fit every patient’s body. A patient’s body size, range of motion, and degree of the support required must be considered when adjusting the robots. This may be a problem, especially for a healthcare worker with limited skill in the field of robotic rehabilitation. Moreover, it may require extra time to adjust the device, thus lowering the productivity of the rehabilitation facility.
Opportunity: Rising Need for Home-Based Care
The increasing need for home-based care leads to the expansion of the medical exoskeleton market. Nowadays, patients tend to opt for an opportunity to rehabilitate at home and in a community care facility rather than in a clinic. Thus, medical exoskeletons that are portable or easy to use can enable ambulatory activities such as upper body and lower body rehabilitation.
Opportunity: Growing Demand for Upper-Limb Exoskeletons
The growing demand for upper-limb exoskeletons can create growth opportunities for manufacturers. Products addressing the need for movement of the arms, wrists, and fingers have the potential to gain traction. The occurrence of debilitating diseases such as stroke and spinal cord injury can challenge the motor abilities of the patients. The need for repetitive physiotherapy for such diseases can motivate the adoption of exoskeletons in rehabilitation centers and hospitals.
Opportunity: Expansion in APAC and GCC in Rehabilitation Centers
The expansion of rehabilitation centers in the APAC and GCC regions can create growth opportunities for medical exoskeleton manufacturers. The increasing need for rehabilitation services in emerging APAC and GCC countries can drive the demand for exoskeletons. The manufacturers can establish partnerships with hospitals and local distributors to facilitate the sales process. The provision of affordable products and training to professionals can increase adoption in the targeted region.
Emerging Trends in Medical Exoskeleton Market
| Trend | What It Means | Key Technologies / Enablers | Primary Medical Applications | Market / Clinical Impact |
| Self-balancing exoskeletons | Systems that stabilize the user during standing, walking, turning, and terrain transitions with reduced dependence on crutches or continuous therapist support. | Inertial measurement units, force/pressure sensors, balance controllers, real-time center-of-mass estimation, terrain-aware motion planning. | Spinal cord injury, stroke rehabilitation, neurological gait disorders, elderly mobility support. | Improves hands-free mobility, safety, and usability in real-world environments; supports progression from treadmill-based therapy to community ambulation. |
| AI-adaptive control | Exoskeletons dynamically adjust torque, timing, resistance, and assistance based on the user’s movement, fatigue, intent, and rehabilitation progress. | Machine learning, reinforcement learning, recurrent neural networks, model predictive control, sensor fusion, closed-loop feedback. | Personalized rehabilitation, gait retraining, post-stroke recovery, orthopedic and neurological rehabilitation. | Enables patient-specific therapy, reduces manual tuning, improves movement naturalness, and supports adaptive assistance across tasks. |
| Upper-limb exoskeleton systems | Powered or semi-powered devices assisting shoulder, elbow, wrist, and hand movement for rehabilitation and functional assistance. | Lightweight actuators, soft robotics, EMG sensors, force sensors, adaptive grasp assistance, ergonomic exosuits. | Stroke, spinal cord injury, neuromuscular disorders, brachial plexus injury, upper-limb weakness. | Rapidly growing segment driven by demand for assistive devices in stroke and neurodegenerative disease rehabilitation; supports repetitive task-specific therapy and daily-living assistance. |
| Physical AI | AI embedded in the exoskeleton’s sensing, decision-making, and actuation loop, allowing the device to perceive and respond to the patient and environment. | Computer vision, wearable sensor fusion, edge AI, digital twins, predictive models, cloud-connected rehabilitation platforms. | Autonomous gait assistance, fall-risk mitigation, remote monitoring, precision rehabilitation. | Moves exoskeletons from pre-programmed assistive machines toward intelligent, context-aware robotic partners; enables predictive maintenance and outcome tracking. |
| Gait analytics | Continuous measurement and interpretation of walking patterns, joint angles, ground reaction forces, symmetry, cadence, and gait phases. | IMUs, pressure insoles, joint encoders, electromyography, AI-based gait-phase classification, cloud dashboards. | Neuro-rehabilitation, orthopedic recovery, fall prevention, clinical outcome measurement. | Provides objective, quantifiable progress data; supports adaptive assistance and evidence-based therapy decisions. |
| Bioelectrical control | Use of the user’s biological signals—especially muscle activity—to recognize movement intent and trigger or modulate assistance. | Surface EMG, EEG, electrooculography, machine-learning intent recognition, hybrid FES-exoskeleton systems. | Stroke rehabilitation, partial paralysis, upper-limb assistive devices, severe mobility impairment. | Makes control more intuitive and user-centered; particularly important for upper-limb systems such as myoelectric arm supports. |
| Sensor fusion and wearable integration | Combining multiple body and environmental signals to create a more complete picture of user state and movement intent. | IMUs, EMG, force sensors, pressure sensors, IoT connectivity, wearable health monitors. | Home-based rehabilitation, remote therapy, continuous mobility monitoring. | Supports real-world use outside clinics and integration with tele-rehabilitation and connected-care platforms. |
| Lightweight, ergonomic, and modular designs | Shift toward softer, lighter, modular devices that improve comfort, fit, and adoption across different patient populations. | Soft exosuits, compact actuators, 3D-printed components, backdrivable transmissions, modular joints. | Pediatric rehabilitation, long-duration daily assistance, home and community use. | Reduces user burden and expands addressable use cases beyond hospital-based rehabilitation. |
| Hybrid FES-exoskeleton therapy | Combining robotic joint assistance with functional electrical stimulation to activate the user’s own muscles. | Exoskeleton actuators, FES electrodes, muscle-response sensing, closed-loop control. | Stroke, spinal cord injury, muscle re-education, neuroplasticity-focused therapy. | May improve muscle activation and rehabilitation outcomes by pairing mechanical assistance with neuromuscular stimulation. |
| Connected rehabilitation ecosystems | Exoskeletons becoming part of a broader digital therapy workflow involving clinicians, cloud analytics, and remote monitoring. | IoT, cloud platforms, digital twins, AI performance dashboards, remote firmware updates. | Hospital rehabilitation, outpatient care, home therapy, clinical research. | Enables longitudinal patient tracking, personalized protocol updates, and scalable deployment across care settings. |
Source: Polaris Market Research Analysis
Who Can Use an Exoskeleton?
Medical exoskeletons can be used by patients with spinal cord injuries, stroke, multiple sclerosis, and other conditions that affect movement. However, eligibility depends on the device type, the patient's health, body size, and ability to use the system safely. A medical assessment is required before use. Unlike wheelchairs, which provide mobility for daily activities, exoskeletons mainly support standing, walking practice, and rehabilitation. Both can complement each other, as exoskeletons do not replace wheelchairs for all users or mobility needs.
Exoskeleton vs Wheelchair
| Factor | Medical Exoskeleton | Wheelchair |
| Primary purpose | Enables assisted standing and walking, mainly for rehabilitation or selected community mobility. | Provides reliable seated mobility for daily independence. |
| Health benefits | May support upright posture, circulation, bone density, muscle activity, and reduced secondary complications. | Does not provide upright walking but offers efficient, low-effort mobility. |
| Ease of use | Requires fitting, training, practice, and often a trained companion or clinician. | Generally easier to use; manual chairs are lighter and simpler to transport. |
| Environment | Best on smooth, level indoor and outdoor surfaces; stairs, uneven terrain, and water remain challenging. | More versatile for daily navigation, though access still depends on ramps and accessible infrastructure. |
| Cost and coverage | High device cost, limited reimbursement, and significant training requirements restrict adoption. | Usually lower cost and more established coverage pathways, especially for medically necessary wheelchairs. |
| Best use case | Rehabilitation, standing practice, exercise, and ambulation for suitable users with spinal cord injury or neurological impairment. | Everyday mobility, work, travel, and long-distance independence. |
Source: Polaris Market Research Analysis
Safety Considerations
Medical exoskeletons should be handled carefully due to the possibility of falling associated with decreased balance or sensation or reduced bone density. Improper fit or prolonged use might lead to skin rubbing leading to abrasions and pressure ulcers as well as bruising and soft tissue damage around bony areas. Reduced weight-bearing after spinal cord damage could result in fractures of bones that are weak; thus, a bone mineral density test should be done. The use of this equipment requires professional supervision, and the environment should be suitable for the task. Labels must indicate precautions, contraindications, warnings, safeguards, training, and limitations associated with the equipment use.
Regulations and Reimbursement : FDA Regulation of Powered Exoskeletons
FDA Regulation of Powered Exoskeletons: In the United States, powered lower-extremity medical exoskeletons are regulated as Class II prescription devices under 21 CFR § 890.3480. Manufacturers generally must obtain 510(k) clearance by demonstrating substantial equivalence to a legally marketed predicate and meeting special controls covering biocompatibility, electrical, mechanical, thermal, battery, EMC/EMI, wireless, software validation, performance testing, clinical evidence, training, and labeling. FDA clearance indicates that the device is substantially equivalent to a legally marketed device for the cleared indication, but it does not establish payer coverage, reimbursement, or medical-necessity policy (Source: fda.gov, govinfo.gov).
Reimbursement: Medicare, Medicare Advantage and Private Payers
Medicare coverage for exoskeletons is typically assessed under the leg-brace/orthotic benefit category within DMEPOS, subject to medical necessity, enrolled-supplier requirements, and applicable coding and coverage rules. Medicare Advantage plans must cover the same medically necessary DME categories as Original Medicare, though prior authorization and network rules can differ. Reimbursement pathways also include the Department of Veterans Affairs, workers’ compensation, and private payers, where coverage often depends on diagnosis, functional need, documentation, and payer policy. Outside the U.S., reimbursement varies substantially by national health system, device classification, indication, and local coverage decisions (Source: medicare.gov, cms.gov).
Report Segmentation
By Component Analysis
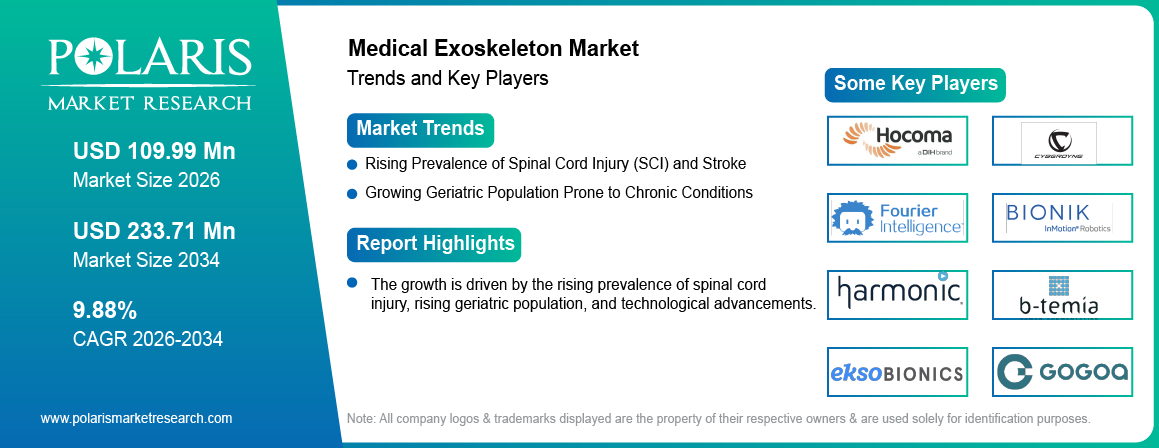
In 2025, the hardware accounted for the largest medical exoskeleton market share of 68.4% driven by the rising demand for motors, sensors, frames, and control systems that aid body part movement. The continuous improvement in device strength, comfort, and control over body movement will encourage healthcare providers to utilize medical exoskeletons for rehabilitation purposes.
The software segment is anticipated to witness the fastest growth of CAGR 12.1% during the forecast period driven by the rising demand for advanced control of body movement and personalized patient rehabilitation. The adoption of advanced software to operate medical exoskeletons, which offers response, adjustment, and control over body part movement, will increase the ease of operation and aid therapists in monitoring the progress of rehabilitation.
By Type Analysis
The powered segment accounted for the highest market share of 81.6% in 2025 driven by the rising demand for devices that offer active-assisted movement. Powered exoskeletons, which utilize batteries and engines to assist the user in sitting, standing, and rehabilitation activities, will see increased adoption due to the rising number of cases of body movement disorders.
The passive segment is anticipated to experience the growth of CAGR 8.9% during the forecast period driven by the demand for simple and cost-effective medical devices to aid movement. Passive exoskeletons utilize mechanical components, such as springs and joints, instead of powered equipment. Their ease of operation and reduced energy requirements can make them viable options for selected rehabilitation and body movement applications.
Powered vs Passive Medical Exoskeletons
| Attribute | Powered exoskeletons | Passive exoskeletons |
| How assistance is generated | Electric motors at hip, knee and sometimes ankle drive joint movement | Springs, elastic elements and linkages store and release the user's own energy |
| Power source | Rechargeable battery | None |
| Movement assistance | Can move limbs the user cannot move; programmable gait patterns | Supports or redistributes load; cannot generate net movement |
| Typical users | Severe impairment, including complete SCI and early post-stroke gait training | Users with residual strength who need partial support |
| Clinical complexity | Requires fitting, calibration and trained therapist or companion | Simpler fitting; minimal training |
| Weight and cost | Heavier; high capital or unit cost | Lighter; lower cost |
| U.S. regulatory route | Powered exoskeleton, 21 CFR 890.3480, Class II prescription device | Generally regulated under orthosis classifications. |
| Examples | ReWalk 7, EksoNR, Ekso Indego Personal, HAL, Atalante X, Eve | Armeo Spring (Hocoma), a spring based arm exoskeleton for rehabilitation |
Source: Polaris Market Research Analysis
By Structure Analysis
The rigid exoskeletons segment dominated with largest share of 58.6% in medical exoskeleton market size driven by the demand for equipment that offers a firm attachment to the body to aid movement and assist in rehabilitation. Rigid medical exoskeletons are designed with strong frames to meet the requirements of leg, joint, and body movement support and control. Their utilization in hospitals and rehabilitation centers will drive their adoption.
The soft exosuits segment is expected to witness fastest growth of CAGR 12.4% during the forecast period driven by the rising demand for light-weight and easy-to-wear equipment that aids body movement and rehabilitation. Medical exoskeletons made of soft materials are utilized to provide comfort and flexibility while supporting leg, joint, and other body movement functions during rehabilitation. Their flexible design can increase their utilization in rehabilitation and certain home healthcare settings.
Rigid Exoskeletons vs Soft Exosuits
| Attribute | Rigid exoskeletons | Soft exosuits |
| Structure | Metal or composite frame aligned with limb joints | Textile garment with anchors and cables |
| Actuation | Motors at the joints | Cable drives from a waist-mounted unit |
| Support level | Can bear body weight; enables standing and walking in paralysis | Augments existing movement; no body-weight support |
| Weight and comfort | Heavier; longer donning and doffing | Light; quicker to put on |
| Typical role | SCI walking, intensive gait training | Post-stroke gait (e.g., ankle assistance), partial weakness |
| Examples | ReWalk 7, EksoNR, Eve | ReStore (Lifeward), EU sales ceased May 2024. |
Source: Polaris Market Research Analysis
By Extremity Analysis
The lower limb exoskeleton segment with largest share of 62.4% in medical exoskeleton industry driven by the increasing demand for rehabilitation devices and body movement support equipment for the lower limbs. Medical exoskeletons are utilized to aid hip, knee, and leg movement during sit-stand, gait, and other rehabilitation activities. The rising number of spinal cord injury and stroke cases will drive the demand for lower limb rehabilitation exoskeletons.
The upper limb exoskeletons segment is expected to witness growth of CAGR 10.2% during the forecast period driven by the rising incidence of stroke and body movement disorders, which require rehabilitation solutions to restore upper body functionality. The application of upper limb medical exoskeletons can aid stroke patients in performing repetitive rehabilitation activities and regain motor control of the arms and hands. Their utilization in rehabilitation settings will drive their demand.
By Application Analysis
The spinal cord injury segment with largest share of 39.8% in medical exoskeleton industry driven by the need to restore the body movement and functional capacity of patients with spinal cord injury. Ekso Bionics acquired Parker Hannifin’s Indego exoskeleton business in December 2022 for USD 10 million to extend into outpatient and home settings. The rising need for specialized rehabilitation will drive the adoption of medical exoskeletons in this segment.
The multiple sclerosis is expected to witness growth of CAGR 10.6% during the forecast period driven by the need to manage the varying degrees of body movement impairment and provide support for patients living with multiple sclerosis. Medical exoskeletons can aid eligible patients in sitting, standing, and participating in selected rehabilitation activities. Increasing awareness of the benefits of such medical equipment for movement support will drive their adoption
The cerebral palsy segment is expected to witness growth of CAGR 9.8% during the forecast period driven by the need for specialized rehabilitation to manage the limited body coordination and movement range seen in people living with cerebral palsy. Medical exoskeletons can assist eligible patients in practicing controlled rehabilitation activities, such as sitting and leg movements, under the supervision of clinicians. Their utilization in rehabilitation settings will increase due to the rising interest in advanced body movement management approaches
The Stroke segment is expected to witness significant growth of CAGR 11.3% during the forecast period driven by the need to restore body movement and walking ability in stroke survivors. Stroke patients require repetitive rehabilitation activities to regain motor control of the body. Medical exoskeletons can support the performance of such activities and aid therapists in facilitating organized rehabilitation programs for these patients
Application Segment Comparison
| Application | Device role | Setting | Representative products | Typical Clinical Use |
| Spinal cord injury | Standing and walking in paralysis; gait training | Rehab + personal | ReWalk 7, Ekso Indego Personal, Eve, EksoNR | Standing and over-ground walking |
| Stroke | High-repetition gait retraining; upper-limb therapy | Rehab (personal for upper limb) | EksoNR, HAL, ReStore (U.S. only), MyoPro | Gait retraining and upper-limb therapy |
| Multiple sclerosis | Gait training adjusted for fatigue | Rehab | EksoNR | Gait training adjusted for fatigue |
| Cerebral palsy | Gait training; pediatric vs adult | Rehab | HAL; pediatric lower-limb systems | Gait training and assisted walking practice |
| Acquired brain injury | Gait retraining | Rehab | EksoNR | Gait retraining in rehabilitation |
| Neuromuscular disorders | Assisted gait | Rehab | HAL (region-specific approvals) | Assisted gait in rehabilitation |
Source: Polaris Market Research Analysis
By End Use Analysis
The hospital and specialty clinics dominated the medical exoskeleton market size with 52.7% share in 2025 due to access to trained physicians. Hospital facilities contain better infrastructure for patient centric care. This in turn drives the demand for orthopedic devices and treatments, fueling the demand for medical exoskeletons in these facilities, thereby driving the segment growth.
Rehabilitation centers segment is expected to witness growth of CAGR 10.8% during the forecast period driven by the rising need for rehabilitation services and advanced equipment to facilitate organized activity programs for patients with body movement impairments. Such patients require regular rehabilitation sessions that involve repetitive movement, sit-stand, and walking exercises. Medical exoskeletons can support these patients by enabling them to participate in the necessary rehabilitation activities and help therapists provide such programs effectively.
Physiotherapy centers is anticipated to record the growth rate of 10.4% during the medical exoskeleton market forecast 2034 driven by the rising need for physical therapy centers to offer advanced rehabilitation programs for people with limited body movement. Medical exoskeletons can assist such facilities in facilitating various movement and walking exercises for eligible patients who require such activities to regain body control and mobility. Their utilization in physiotherapy settings will increase due to the need for organized rehabilitation programs
Home and Community is expected to witness growth of CAGR 12.2% during the forecast period driven by the rising need for body movement rehabilitation equipment at home and in the community. Medical exoskeletons designed to offer sit-stand support and assist in body movement exercises can enable eligible users to participate in rehabilitation programs. Increasing product development and improvements in the device’s comfort and ease of use can improve the adoption rate
Rehabilitation vs Personal Medical Exoskeletons
| Attribute | Rehabilitation exoskeletons | Personal exoskeletons |
| Buyer | Hospital or rehabilitation centre (capital purchase) | Individual user via prescription; funded by Medicare, Medicare Advantage, VA, workers' compensation or private payer |
| Setting | Inpatient and outpatient clinics | Home and community |
| Users per device | Many patients; adjustable sizing | One user; individually fitted |
| Supervision | Physical therapist | User with a trained companion |
| Typical indications | SCI, stroke, acquired brain injury, MS (per device labeling) | Mainly SCI (per device labeling) |
| Revenue model | Device sale plus service, software and training | Per-unit sale tied to payer approval, plus service |
| Main adoption barrier | Capital cost, therapist time, session throughput | Reimbursement, eligibility, training and service network |
| Examples | EksoNR, HAL, Atalante X | ReWalk 7, Ekso Indego Personal, Eve |
Source: Polaris Market Research Analysis
Regional Insights
North America Accounted for the Largest Market Share in 2025
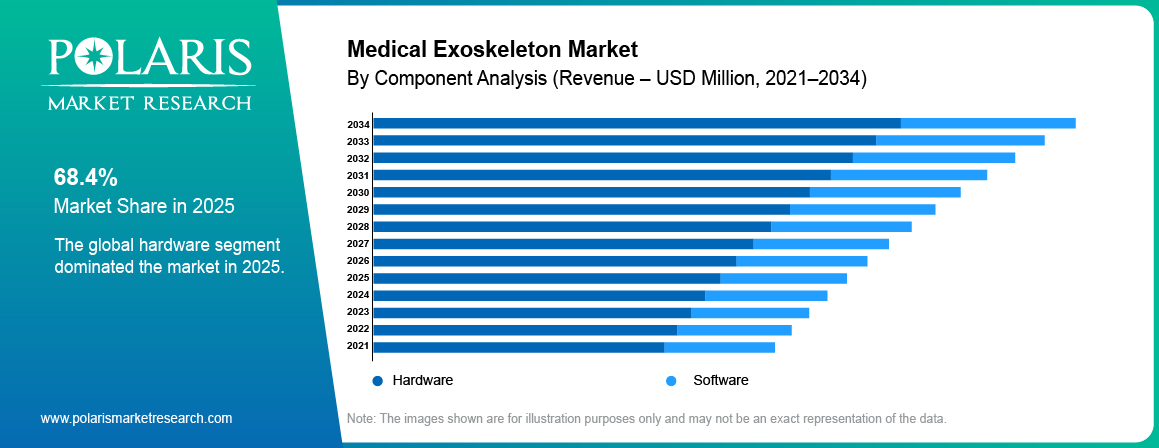
In 2025, North America medical exoskeleton market accounted for the largest share of 46.21%, driven by the region’s advanced healthcare facilities and extensive rehabilitation services. The U.S. is home to a number of R&D initiatives and medical device manufacturing companies. Moreover, the country is witnessing a heightened incidence of cerebrovascular accidents, spinal cord injury, and other debilitating diseases. In contrast, the Canadian market is primarily driven by the growing emphasis on rehabilitation services and the country’s improving healthcare infrastructure. The rising awareness about advanced mobility solutions and the increased investments in technologies that focus on patient rehabilitation are also expected to propel the market.
Europe is expected to witness growth of CAGR 9.4% during the forecast period driven by the region’s ageing population and well-developed healthcare services. The market in Germany is propelled by the presence of an extensive network of engineering companies and medical infrastructure. The UK market, on the other hand, is driven by the country’s growing rehabilitation programs and clinical research initiatives. By contrast, the France market is influenced by the growing focus on patient rehabilitation and mobility in the wake of an increase in the incidence of debilitating diseases. The increased investments in the healthcare sector, along with strategic partnerships and collaborations, are also anticipated to augment the market growth in the near term.
The Asia Pacific is anticipated to witness growth of CAGR of 11.2% during the forecast period driven by a rise in healthcare infrastructure and investment in advanced rehabilitation services across the region. Japan’s aging population and the subsequent need for elderly care present lucrative growth opportunities for the medical exoskeleton market. Similarly, China’s growing focus on medical device manufacturing and advanced healthcare services are anticipated to drive the market for the next few years. Moreover, Malaysia’s heightened focus on rehabilitation services and the rising incidence of debilitating diseases are also expected to augment market growth in the years to come.
The Latin America region is expected to witness growth of CAGR 9.6% during the forecast period driven by the region improving healthcare infrastructure and heightened emphasis on advanced rehabilitation services. The growing investment in the development of specialized medical facilities across the region is also anticipated to augment the market. The region is home to a high incidence of cerebrovascular accidents and spinal cord injury. Moreover, the heightened awareness regarding the use of advanced mobility aids among the healthcare professionals is also projected to propel the Latin American market during the forecast period.
The Middle East and Africa is anticipated to record growth rate of 10.1% during the forecast period driven by the rising healthcare infrastructure and the recent investment in advanced rehabilitation facilities. The high incidence of debilitating diseases and the subsequent need for patient rehabilitation in these regions are also likely to contribute to market growth. Additionally, Middle East countries such as Saudi Arabia and the United Arab Emirates are witnessing a heightened emphasis on the development of specialized healthcare infrastructure. Thus, a similar trend is also anticipated to emerge across Africa.
Medical Exoskeleton Product Comparison
| Product | Company | Setting | Design | Broad indication | Status note |
| ReWalk 7 | Lifeward | Personal | Rigid, powered, lower limb | SCI | FDA cleared exoskeleton Mar 2025; Medicare Advantage coverage from Aetna, Humana, UnitedHealthcare |
| EksoNR | Ekso Bionics | Rehabilitation | Rigid, powered, lower limb | Stroke, SCI, ABI, MS | MS indication added Jul 2022 |
| Ekso Indego Personal | Ekso Bionics | Personal | Rigid, powered, modular | SCI | CMS HCPCS coding Dec 2023 |
| HAL (lower limb, single joint, lumbar) | CYBERDYNE | Rehabilitation | Powered; bioelectrical-signal control | Neurological and neuromuscular gait impairment (by region) | 65 units at PERKESO centre, Malaysia, Jun 2026 |
| Atalante X | Wandercraft | Rehabilitation | Rigid, powered, self-balancing, hands-free | Neurological gait impairment (per label) | Used in 150+ rehabilitation and research centers |
| Eve | Wandercraft | Personal | Rigid, powered, self-balancing | SCI, eligible wheelchair users | FDA clearance announced 11 Aug 2026; U.S. launch 17 Sep 2026 |
| Keeogo | B-Temia | Clinical / personal | Powered knee-assist orthosis | Mobility impairment with residual function | FDA 510(k) cleared (K201539) |
| ReStore | Lifeward | Rehabilitation | Soft exosuit, powered | Post-stroke gait | FDA cleared June 2019; EU sales ceased May 2024. |
| MyoPro | Myomo | Personal | Powered upper-limb orthosis, EMG-driven | Upper-limb weakness (e.g., stroke) | FDA Class II, 510(k) exempt listed device; Medicare brace benefit category since January 2024 (HCPCS L8701, L8702) |
Source: Polaris Market Research Analysis
Key Market Players & Competitive Insights
The medical exoskeleton market is competitive, with established medical technology companies and specialized robotics manufacturers focusing on product development and clinical adoption. Key players include Lifeward Ltd., Ekso Bionics Holdings, CYBERDYNE, Wandercraft, and Ottobock. Other participants, such as Myomo, Fourier Intelligence, B-Temia, and Hocoma, focus on different rehabilitation and mobility needs. Companies compete through technological improvements, product comfort, clinical partnerships, and geographic expansion. Growing demand for rehabilitation solutions is encouraging manufacturers to develop more accessible, effective, and user-friendly medical exoskeletons.
Vendor Positioning
| Company (HQ) | Key products | Rehab | Personal | Upper limb | Positioning |
| Lifeward (US/Israel) | ReWalk 7, ReStore; upper-body system in development | Yes | Yes | Pipeline | Payer-coverage leader in U.S. personal SCI devices |
| Ekso Bionics (US) | EksoNR, Ekso Indego Personal / Therapy | Yes | Yes | No | Dual clinic and personal portfolio after Indego acquisition |
| CYBERDYNE (Japan) | HAL lower limb, single joint, lumbar | Yes | Limited | Single joint | Bioelectrical control; scale deployments in Japan and Malaysia |
| Wandercraft (France) | Atalante X, Eve | Yes | Yes | No | Self-balancing, hands-free design across clinic and personal channels |
| Ottobock (Germany) | suitX portfolio; orthotics | Limited | Limited | No | O&P fitting and distribution network |
| Hocoma / DIH (Switzerland) | Lokomat (stationary robotic gait) | Yes | No | Yes (Armeo Spring) | Stationary gait-robotics benchmark in clinics |
| Fourier Intelligence (China) | ExoMotus M4 (lower limb); ArmMotus M2 Pro and ArmMotus EMU (upper limb) | Yes | No | Yes | Cost-competitive APAC supplier |
| B-Temia (Canada) | Keeogo | Yes | Yes | No | Assistive rather than full-support design |
| Myomo (US) | MyoPro | No | Yes | Yes | Upper-limb powered orthosis specialist |
| Human in Motion Robotics (Canada) | XoMotion | Yes | No | No | Health Canada authorization September 2024 |
Source: Polaris Market Research Analysis
Some of the medical exoskeleton companies include:
- BIONIK Laboratories Corp.
- B-Temia Inc.
- CYBERDYNE Inc.
- Ekso Bionics Holdings, Inc.
- Fourier Intelligence
- Gogoa Mobility Robots S.L.
- Harmonic Bionics, Inc.
- Hocoma AG (DIH)
- Human in Motion Robotics Inc.
- Lifeward Ltd.
- Marsi Bionics S.L.
- Myomo, Inc.
- Ottobock SE & Co. KGaA
- Rex Bionics Ltd.
- Wandercraft SAS
- Wearable Robotics srl
Recent Developments
- October 2026: Wandercraft acquired Ekso Bionics from a subsidiary of ChronoScale Holdings, combining EksoNR and Atalante X in clinical rehabilitation and Indego Personal and Eve in personal mobility. Financial terms were not disclosed.
- July 2026: Onyx Healthcare, Intel, and FREE Bionics launched FREE Walk, an AI-powered lower-limb rehabilitation exoskeleton. It uses Intel Core Ultra processors and OpenVINO to process EMG, pressure, and inertial-sensor data, enabling real-time gait assistance and supporting neuroplasticity during clinical rehabilitation. (Source: intel.com)
- February 2026: Lifeward announced an agreement to acquire Skelable’s AI-enabled powered upper-body exoskeleton technology for USD 480,000 in milestone-based equity and a nominal cash payment. The system will assist weakened or paralyzed arms and hands, primarily after stroke, and is expected to launch commercially in 18–24 months from the announcement. (Source: ir.rewalk.com)
- December 2025: Verita Neuro partnered with Lifeward to introduce the ReWalk Personal Robotic Exoskeleton into spinal cord injury rehabilitation programs in Thailand, Mexico, and the UAE. The wearable system will support standing, walking, and stair climbing alongside epidural stimulation, LamiSpine, and personalized physical therapy. (Source: veritaneuro.com)
Future Outlook
The medical exoskeleton market is expected to grow as demand for rehabilitation and mobility support increases. Technological advancements may improve device comfort, affordability, and ease of use. Growing investments in healthcare and rising cases of stroke and spinal cord injuries will create new opportunities. Wider clinical adoption, home-based rehabilitation, and expanding healthcare infrastructure are also expected to support future market growth.
Medical Exoskeleton Market Segmentation
By Component Outlook (Revenue – USD Million, 2021–2034)
- Hardware
- Sensor
- Actuator
- Control System
- Power Source
- Software
By Type Outlook (Revenue – USD Million, 2021–2034)
- Powered
- Passive
By Structure Outlook (Revenue – USD Million, 2021–2034)
- Rigid Exoskeletons
- Soft Exosuits
By Extremity Outlook (Revenue – USD Million, 2021–2034)
- Lower-Limb
- Upper-Limb Exoskeletons
By Application Outlook (Revenue – USD Million, 2021–2034)
- Spinal Cord Injury
- Multiple Sclerosis
- Cerebral Palsy
- Stroke
- Acquired Brain Injury
- Neuromuscular Disorder
- Others
By End Use Outlook (Revenue – USD Million, 2021–2034)
- Rehabilitation Centers
- Physiotherapy Centers
- Hospitals and Specialty Clinics
- Home and Community
- Others
By Regional Outlook (Revenue – USD Million, 2021–2034)
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of the Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Medical Exoskeleton Market Report Scope
| Report Attributes | Details |
| Market size value in 2025 | USD 100.18 million |
| Market size value in 2026 | USD 109.99 million |
| Revenue forecast in 2034 | USD 233.71 million |
| CAGR | 9.88% from 2026 – 2034 |
| Base year | 2025 |
| Historical data | 2021 – 2024 |
| Forecast period | 2026 – 2034 |
| Quantitative units | Revenue in USD million and CAGR from 2026 to 2034 |
| Segments Covered | By Component, By Type, By Structure, By Extremity, By Application, By End Use, By Region |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Customization | Report customization as per your requirements with respect to countries, region, and segmentation |
Source: Polaris Market Research Analysis
Medical Exoskeleton Market FAQ's
The market size was USD 100.18 million in 2025 and is expected to reach USD 233.71 million by 2034.
The Medical Exoskeleton Market is growing at a CAGR of 9.88% during the forecast period.
North America dominated the market with 46.21% share in 2025.
A medical exoskeleton is a wearable device that supports body movement and helps patients improve mobility during rehabilitation and recovery.
Medical exoskeletons use sensors, control systems, and sometimes motors to support body movements and assist patients during rehabilitation exercises.
Powered exoskeletons use motors and batteries to assist movement, while passive exoskeletons use mechanical parts such as springs and joints.
Eligible patients with spinal cord injuries, stroke, multiple sclerosis, or other movement disorders may use medical exoskeletons following professional medical assessment.
Some medical exoskeletons have FDA clearance, while Medicare coverage depends on device classification, eligibility requirements, and applicable coverage policies.
Key companies include Lifeward, Ekso Bionics, CYBERDYNE, Wandercraft, Ottobock, Myomo, Fourier Intelligence, and B-Temia, among other specialized manufacturers.
Rigid exoskeletons are the largest structure segment, holding 58.6% of the market in 2025. They carry body weight, which enables standing and walking in paralysis.
Asia Pacific is projected to grow the fastest, at a CAGR of 11.2% during 2026–2034, ahead of Middle East and Africa (10.1%), Latin America (9.6%), and Europe (9.4%).
Download Sample Report of Medical Exoskeleton Market
Please fill out the form to request a customized copy of the research report.


