
AI Camera Market Size, Share, and Forecast 2026 to 2034
REPORT DETAILS
AI Camera Market Summary
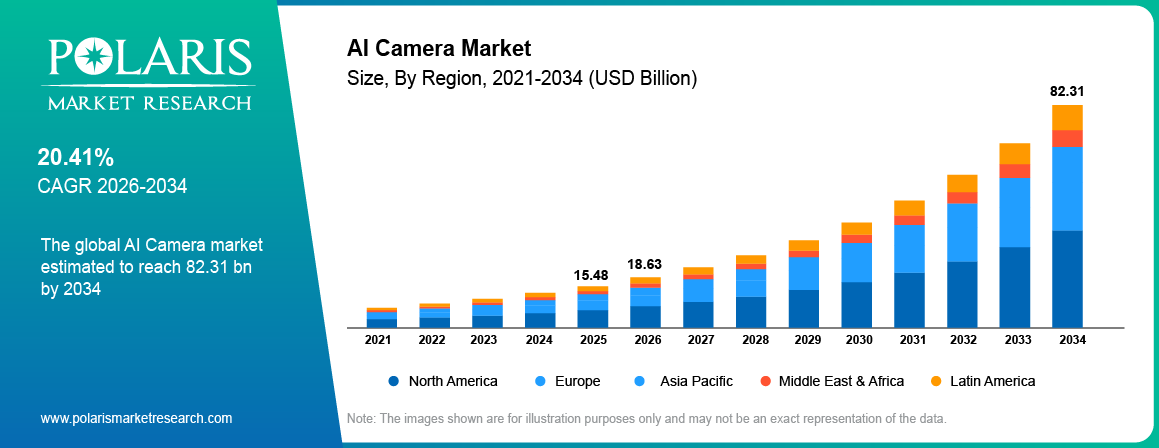
The global AI camera market size was valued at USD 15.48 billion in 2025. The market is expected to exhibit a CAGR of 20.41% from 2026 to 2034. Market growth is driven by rising demand for intelligent video surveillance, wider adoption of edge AI cameras, and growing use of computer vision across security, retail, healthcare, industrial automation, and automotive applications.
Market Statistics
Key Takeaways
- North America led the global AI camera market share with 34.00% in 2025, owing to rising security spending and AI adoption.
- The Asia Pacific region is expected to show the highest CAGR of 23.16% during 2026-2034 on account of smart infrastructure and AI adoption.
- Hardware was the leading segment of the market with 52.40% market share in 2025 owing to demand for AI cameras.
- Surveillance camera held a market share of around 34.20% in 2025 owing to its applications in security surveillance and video analytics.
- The context awareness is anticipated to hold the largest CAGR of 24.21% between 2026 and 2034 because of increasing demand for intelligent scene analysis.
- The services segment is projected to grow at the fastest rate among all segments with a CAGR of 23.18% in 2026-2034.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is an AI Camera?
An AI camera is a camera system that employs artificial intelligence (AI) software to optimize camera performance and help users take better photos. Use of AI and computer vision in cameras helps analyze images or videos and produce useful information. By using AI technologies such as computer vision, deep learning, and natural language processing, AI cameras can automate and refine several camera functions. AI cameras can also offer unique creative modes and filters, letting photographers experiment with interesting effects and styles. Conventional cameras mainly record and transmit visual information. AI cameras can detect objects, classify activities, recognize selected visual features, count people or vehicles and generate alerts based on defined rules or trained models.
AI cameras use image capture, image enhancement, model inference, and event analysis to process visual data. Depending on the design, analysis can run on the camera, an edge server, a customer-managed data center, or a cloud platform. Edge AI cameras execute select models close to the image source using an integrated system-on-chip (SoC), neural processing unit (NPU), or other accelerator. This set up can reduce response time and limit the amount of video sent to outside systems.
AI cameras have made their way into several devices and fields, such as smartphone photography, consumer and professional cameras, surveillance and security systems, wildlife and sports photography, and cinematography and filmmaking. The need comes from organizations that seek faster monitoring, more efficient workflows, and better use of visual data. AI video surveillance is used by security experts in the identification of individuals, vehicles, and events. Video analytics are used by retailers in measuring foot traffic, managing queues, and conducting business. Computer vision is used by manufacturers for defect detection and process tracking. Smartphone and professional camera makers use AI for autofocus, scene recognition, image enhancement, and computational photography. With a growing emphasis on safety and usage in diverse applications, the AI cameras market is anticipated to witness healthy growth over the forecast period.
How Does an AI Camera Work?
AI cameras process visual information into classifications, measurements, or alerts through a series of processes.
- Image capture: The image sensor records the light that falls onto it and translates the data received into a digital image. The image sensor’s input depends on parameters such as optical quality, sensor size, exposure, and lighting.
- Image processing: Image signal processing manipulates exposure, color, noise, and sharpness of the image. In addition, smartphones may use computational photography to fuse frames and improve final images.
- Model inference: Computer vision model detects objects, people, vehicles, or any other elements of the visual world. Edge AI camera uses a local processor or neural processor (NPU).
- Event analysis: Rules or contextual information are applied to the model results by software. For instance, a system might recognize a person entering a restricted area, a vehicle crossing a line, or a queue exceeding a defined threshold.
- Data delivery: The camera sends alerts, metadata, selected video clips, or full video streams to a video management system (VMS), cloud platform, or other enterprise application.
Difference Between AI Camera and Traditional CCTV
An AI CCTV/camera combines image capture with automated analysis. A traditional IP or CCTV camera primarily records or streams video, although the wider system may include analytics on a recorder, server, or VMS. The practical difference depends on where processing occurs and which software functions are included.
AI Camera vs Traditional CCTV
| Attribute | AI Camera | Traditional IP / CCTV Camera |
| Core function | Interprets the scene: detects, classifies, and recognizes objects, people, vehicles, and events | Records and streams video for human review |
| Where analysis happens | On the camera (NPU/SoC), at an edge server, or in the cloud | Off-camera, if at all (VMS or manual review) |
| Alerts | Real-time, rule- and model-based (loitering, line crossing, PPE, occupancy) | Basic motion detection; high false-alarm rate |
| Bandwidth and storage | Sends metadata and event clips; lower bandwidth | Continuous full-resolution streams |
| Search | Attribute and natural-language search across footage | Timeline scrubbing |
| Privacy controls | Dynamic privacy masking, on-device processing, auto-redaction | Static masking zones |
| Upfront cost | Higher hardware and software licensing | Lower |
| Typical buyers | Smart cities, retail, banks, hospitals, factories, data centers | Small sites with basic recording needs |
Source: Polaris Market Research Analysis
Market Dynamics
Driver: Rising Demand for Security and Public Safety
Security remains a major driver of the AI camera market. Businesses, public agencies, transport operators, and infrastructure owners use AI video surveillance to improve site monitoring and incident investigation. AI-powered cameras provide object detection, vehicle classification, perimeter alerts, people counting, and event search. Gallup’s 2025 Global Safety Report surveyed more than 145,000 adults in 144 countries. The report states that 73% feel safe walking alone at night. However, in 104 countries, women feel less safe than men. As safety demand rises, especially at night, so does demand for surveillance. Autonomous features of AI camera reduce the need for manual video review, allowing security teams to pinpoint relevant activity. Edge AI processing also allows faster alerts in locations with limited connectivity. Demand is driven by the accuracy of detection, reliability of systems, and ability to integrate into existing security infrastructure. There are still many applications of intelligent surveillance and public safety in transport hubs, warehouses, commercial buildings, and public spaces (Source: Gallup).
Driver: Advances in Edge AI Processing
Enhancements to AI system-on-a-chip (SoC) and neural processing units (NPUs) boost on-device image analysis. Edge AI cameras process video on the edge and transmit only metadata or event clips of interest, reducing network traffic and response time. This ability is useful for security, robotics, automotive vision, and industrial inspection applications. Ambarella announced its CV7 edge AI vision SoC in January 2026 for 8K imaging, multi-stream video, and on-device AI processing in security, consumer, industrial, robotics, and automotive applications. The launch is a result of continued development of AI-enabled vision hardware for compact devices and complex visual tasks. These advances improve the capabilities of AI cameras and their applicability for real-time analytics (Source: Ambarella).
Driver: Expansion of Smart Infrastructure and Industrial Automation
In smart buildings, transport networks, factories and distribution centers, AI cameras are used for connected monitoring and operational control. In smart cities, AI video analytics can be used to detect unusual activity, monitor occupancy, count vehicles and identify visible production defects. Integration with access control, alarms, building management systems and industrial software can trigger specific actions based on visual events. AglaiaSense and Leopard Imaging said in October 2026 that they will demonstrate privacy-first AI traffic cameras at Barcelona’s Smart City Expo World Congress. The cameras can classify vehicles, cyclists, and pedestrians in real time, discarding the raw video and transmitting anonymous metadata. These applications expand AI cameras' role beyond traditional security surveillance. Industrial users also seek better inspection accuracy and less manual monitoring (Source: PR Newswire).
Restraint: Privacy and Regulatory Requirements
Privacy concerns pose challenges to deployment of AI cameras, especially if the technology is analyzing identifiable faces, vehicle information, or biometric data. Facial recognition and biometric recognition also need to be considered carefully for purposes of data collection, access, retention periods and legal obligations. The EU AI Act limits the use of real-time remote biometric identification in public spaces for purposes of law enforcement, subject to exceptions. Requirements are dependent on the application and the legal classification of the system. These obligations could imply higher compliance costs and impact on the procurement decision making for AI surveillance cameras.
Restraint: Cybersecurity and Supplier Requirements
Connected AI cameras pose cybersecurity risks that require secure configuration, firmware updates, identity management, and network controls. Weak device security could permit unauthorized access to video feeds or connected systems. In some markets, the choice of supplier is also limited by procurement constraints. In the U.S., specified telecommunications and video surveillance equipment are addressed in certain circumstances by Section 889 of the 2019 National Defense Authorization Act (NDAA) and related Federal Communications Commission rules. For each deployment, buyers need to assess the applicable rules, contract requirements and equipment limitations. Such cybersecurity and supplier requirements limit the AI camera market growth (Source: U.S. EAC).
Opportunity: Growth in Privacy-Conscious Edge Analytics
Edge AI processing creates new opportunities for cameras to analyze video locally and transmit selected events or metadata. This method could reduce bandwidth requirements and the transfer of raw video to cloud platforms. Privacy outcomes depend on data flows, retention policies, access controls, and system configuration. While edge processing does not eliminate regulatory requirements, it does put more control of the video in the hands of the organization. Demand for privacy-conscious AI video surveillance deployment across commercial, industrial, and public-sector applications may benefit manufacturers who combine efficient on-device inference with secure device management. In October 2026, i-PRO announced a space-saving Remote Head Camera. The camera offers edge-AI analytics and enterprise-grade cybersecurity. It is developed for discreet installation in confined areas, including retail counters, ATMs, and industrial equipment (Source: i-PRO).
AI Camera Market Segmentation Analysis
The AI camera market is segmented on the basis of component, deployment, organization size, product type, technology, industry vertical, and region.
By Component
The hardware segment accounted for 52.40% share of the AI camera market in 2025. AI camera hardware includes image sensors, processors, lenses, memory, and connectivity components that capture and process visual data. Demand for high-resolution imaging, real-time object detection, facial recognition, and edge AI processing drive the adoption of hardware. Video surveillance systems powered by AI need hardware that can analyze feeds and raise alerts. Manufacturers are adding AI processors to cameras to speed up detection and reduce the need for outside computing systems. These capabilities make hardware an integral part of AI camera deployments across security, industrial and consumer applications.
The services segment is expected to register the highest CAGR of 23.18% during the forecast period. AI camera deployments need installation, system integration, software configuration, maintenance, and technical support. Service providers help organizations integrate AI cameras with existing security infrastructure, cloud platforms, and video management systems. Managed services also help businesses track performance and maintain reliable analytics on systems. Demand is likely to increase as organizations introduce computer vision and AI-enabled surveillance across a variety of locations. Specialist providers also offer model updates, troubleshooting, and system optimization. These services help customers deal with the deployment complexity and improve the operational performance of AI camera systems.
By Deployment
The cloud segment accounted for 57.80% share of the AI camera market revenue in 2025. Cloud-based AI cameras use remote infrastructure for video storage, camera management, and AI video analytics. They provide centralized monitoring capabilities over multiple sites. They also enable users to view recorded footage through connected devices. Cloud deployment enables security surveillance, people counting, object detection, and real-time alerting for businesses. The system is also easier to administer because of its integration with cloud-based video management software. Demand is driven by flexible infrastructure, remote access, and scalable analytics. Data privacy, network bandwidth, recurring subscription costs, and internet reliability remain important considerations for cloud-based AI camera deployments.
The on-premises segment is expected to record a CAGR of 22.16% over the period of 2026-2034. On-premises AI cameras process and store video data on local infrastructure, which gives organizations more control over sensitive footage and system access. These deployments are suitable for government facilities, financial institutions, healthcare providers and industrial sites with strict data security requirements. Edge AI processing enables real-time object detection, facial recognition, and event alerts without needing to be constantly connected to the cloud. Organizations can also integrate local camera systems with existing security networks and video management platforms. Demand is a function of privacy requirements, low-latency processing, infrastructure capacity, maintenance costs, and cybersecurity controls.
Cloud vs On-premises vs Hybrid
| Attribute | Cloud (incl. VSaaS) | On-Premises | Hybrid / Edge-First |
| Where video and analytics live | Vendor or hyperscaler cloud | Customer servers / NVR | Analytics on camera; selected clips and metadata to cloud |
| Cost model | Subscription (OpEx) | Upfront capex + maintenance | Mixed |
| Scalability across sites | High | Limited by local infrastructure | High |
| Latency/connectivity dependence | Depends on uplink | Low; works offline | Low; tolerant of outages |
| Data-sovereignty and compliance fit | Region-dependent | Strongest control | Strong (raw video can stay local) |
| Best fit by organization size | SMEs; multi-site retail and banking networks | Large enterprises, government, critical infrastructure | Large enterprises modernizing legacy estates |
Source: Polaris Market Research Analysis
By Organization Size
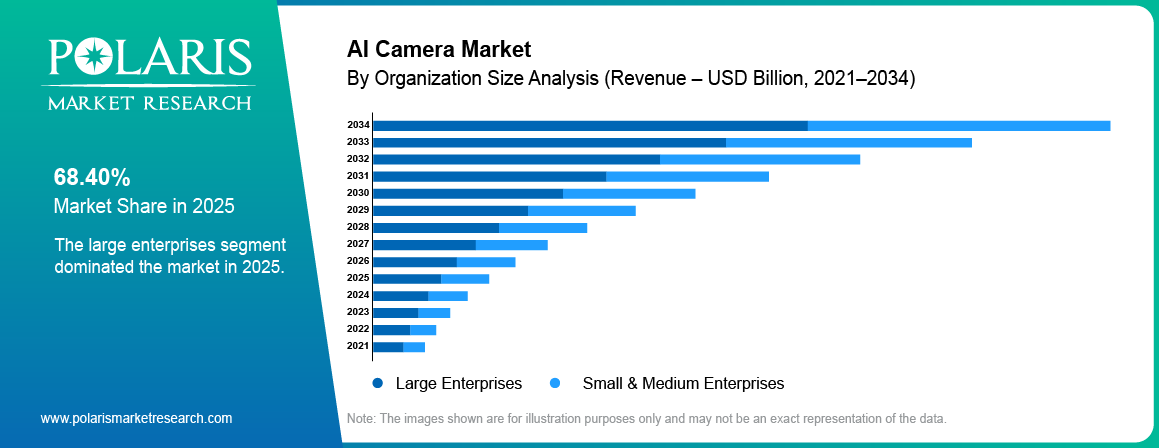
Large enterprises segment dominated the AI camera market share with 68.40% in 2025. Large organizations possess extensive facilities, spread-out offices, warehouses, and production sites, which require centralized security surveillance. These AI cameras also provide object detection, perimeter monitoring, facial recognition, and automated event alerts across these sites. Monitoring efficiency is improved through integration with access control, alarm systems and enterprise security platforms. Bigger companies also have more resources to invest in advanced video analytics, edge AI infrastructure and tailored surveillance solutions. Demand spans BFSI, government, retail, manufacturing and IT facilities. System reliability, cybersecurity, and integration capabilities are among the factors influencing buying decisions.
The small and medium enterprises segment is estimated to register a CAGR of 22.67% during the projected period. SMEs are increasingly using AI cameras to improve site security, monitor customer activity, and reduce the burden of manual surveillance. Cloud-based solutions and small edge AI cameras give companies with limited IT resources more flexible deployment options. Applications include retail surveillance, office security, access management and inventory protection. Managed services and subscription software can eliminate the need for dedicated technical teams. Demand is also driven by easier installation and remote monitoring. Affordability, data protection and compatibility with existing cameras continue to be key to purchase decisions.
Large Enterprises vs. SMEs
| Attribute | Large Enterprises | SMEs |
| Adoption Drivers | Security compliance, scalability, integration with enterprise IT systems | Cost efficiency, ease of deployment, basic surveillance needs |
| Budget Capacity | High. They are able to invest in advanced AI-enabled multi-camera networks | Limited. SMEs focus on affordable, modular solutions |
| Deployment Scale | Wide-scale, multi-site, integrated with analytics platforms | Small-scale, single-site, standalone or cloud-based |
| Use Cases | Smart city surveillance, industrial automation, retail analytics, corporate security | Retail shop monitoring, office security, small manufacturing units |
| Technology Preference | On-premise + hybrid AI solutions with advanced analytics | Cloud-based AI cameras with plug-and-play features |
| Decision Factors | ROI, compliance, vendor reputation, integration with existing infrastructure | Price-performance ratio, ease of use, quick installation |
| Growth Potential | Steady, driven by upgrades and integration with broader AI ecosystems | High, driven by increasing affordability and awareness |
Source: Polaris Market Research Analysis
By Product Type
The surveillance camera segment held 34.20% share in AI camera market in 2025. AI surveillance cameras use image capture and video analysis to recognize objects, spot unusual activity, classify vehicles, and generate security alerts. They are used by businesses and public agencies in commercial buildings, transportation facilities, retail outlets and industrial sites. Computer vision can be used to examine footage, live or recorded, so there is less need for someone to be constantly watching it. They can be integrated with video management systems and access control for further extending their functionality. Demand is driven by security requirements, infrastructure modernization and the need for faster incident detection across monitored environments.
The smartphone camera market is expected to register a CAGR of 19.42% during 2026-2034. Smartphone makers are adding AI features to enhance image quality, portrait effects, scene identification, low-light photography, and video processing. Deep learning models can help optimize exposure, color balance, noise reduction, and image enhancement. Some imaging functions can also be performed on-device with no persistent cloud access due to AI processing. Demand is driven by consumer interest in advanced photography, video creation, and smart image editing. Advances in hardware and software optimization are increasingly bringing AI to mobile imaging. Growth depends on smartphone replacement cycles, feature adoption, device pricing, and competition among manufacturers.
By Technology
The computer vision segment accounted for an 27.40% share of the AI camera market in 2025. Computer vision enables AI cameras to interpret visual information and identify objects, movement, patterns, and activities. These capabilities are used in security surveillance, industrial inspection, traffic monitoring, and retail analytics. Systems with vision algorithms can classify vehicles, detect entry into restricted areas, count people, and find visible product defects. It integrates with edge AI processors to provide real-time analysis at the camera. Real-time analysis near the camera is enabled through integration with edge AI processors. Businesses apply computer vision to increase the accuracy of monitoring and automate visual tasks. It relies on image quality, environmental conditions, model accuracy, and compatibility with existing systems.
The context-aware technology market size is projected to record a CAGR of 24.21% during the forecast period. Context-aware AI cameras analyze visual activity together with factors such as location, movement patterns, time, and surrounding conditions. This allows the system to tell the difference between normal activity and activity that needs attention. Applications include intelligent security alerts, occupancy monitoring, traffic analysis, and industrial safety: Deep learning and edge AI processing let cameras understand complex scenes and tailor analytics to specific operating environments. Demand may increase, as organizations seek fewer false alerts and more relevant notifications. Performance is a function of model training, the availability of contextual data, environmental variability, and deployment requirements.
Comparison Matrix by Technology
| Technology | What it does in an AI camera | Typical use cases | Processing location |
| Computer vision (object detection & tracking) | Locates and classifies people, vehicles, and objects frame by frame | Perimeter security, traffic, retail footfall, industrial inspection | Mostly edge |
| Biometric / facial recognition | Matches faces (or iris) against enrolled templates | Access control, bank branches, airports, attendance | Edge or on-premises server (privacy rules apply) |
| Deep learning (CNN / transformer models) | Underlying models that improve accuracy in low light and crowded scenes | All analytics; smartphone computational photography | Edge NPU; training in cloud |
| Context-aware computing | Combines scene, time and sensor context to judge whether an event matters | Smart buildings, behavior analytics, safety compliance | Edge + cloud |
| Generative / multimodal AI | Describes scenes in text, enables natural-language video search, enhances images | Investigations, VSaaS search, creative photo modes | Mostly cloud; emerging on edge |
| Voice / NLP | Voice commands and audio event detection | Smart home cameras, conferencing cameras | Edge + cloud |
Source: Polaris Market Research Analysis
By Industry Vertical
The government segment accounted for 25.20% share in 2025. AI surveillance cameras are deployed by public agencies in transport facilities, government buildings, public spaces, and critical infrastructure. Uses: perimeter monitoring, vehicle detection, crowd analysis, incident investigation. “AI video analytics allows security teams to find relevant activity and review footage more efficiently. Public facilities benefit from integration with access control and centralized monitoring systems, providing increased operational visibility. The procurement decisions are based on cybersecurity, privacy safeguards, regulatory requirements, and system reliability. AI-enabled monitoring is being driven by demand from investment in smart cities and public safety infrastructure.
The healthcare segment is anticipated to exhibit a CAGR of 23.61% between 2026 and 2034. Hospitals and other healthcare establishments use AI cameras for surveillance, patient tracking, occupancy, and security purposes. Computer vision can be useful in tracking activity in specific areas as well as workflows in clinical and non-clinical areas. AI cameras are used to monitor equipment and operations in some chosen healthcare facilities. The key factor affecting demand for AI cameras for healthcare is the integration capabilities of camera systems with the hospitals’ infrastructures.
Segmentation Summary:
| Segment Type | Dominating Segment with largest share in 2025 | Segment with Highest CAGR during 2026–2034 |
| Component | Hardware (52.40%) | Services (23.18%) |
| Deployment | Cloud (57.80%) | On-Premises (22.16%) |
| Organization Size | Large Enterprises (68.40%) | SMEs (22.67%) |
| Product Type | Surveillance Cameras (34.20%) | Automotive Cameras (24.16%) |
| By Industry Vertical | Government (25.20%) | Healthcare (23.61%) |
Source: Polaris Market Research Analysis
AI Camera Applications and Use Cases
AI cameras are increasingly being adopted for urban surveillance, industrial quality control, healthcare diagnostics, and logistics automation. For instance, in February 2026, 1,150 AI CCTV cameras were deployed across Mumbai. The cameras are expected to improve crowd monitoring and traffic management. In manufacturing firms, AI vision cameras are installed across assembly lines. They help reduce scrap and rework costs. In healthcare, AI-assisted imaging reduces radiologist miss rates. It supports faster anomaly detection. Logistics operators use AI cameras for pallet counting, package damage detection, and barcode scanning. AI camera adoption improves warehouse efficiency. These deployments show AI cameras evolving into critical infrastructure for safety, efficiency, and compliance.
Applications & Use Cases (2025–2026)
| Industry/Sector | Application | Example (2025–2026) |
| Urban Governance | Civic surveillance, traffic monitoring | Mumbai civic body installed 1,150 AI CCTV cameras (Feb 2026) |
| Manufacturing | Defect detection, assembly verification | AI cameras achieving approx. 98–99% defect detection accuracy |
| Healthcare | Medical imaging, patient tracking | AI reduces radiologist miss rate by approx.11% |
| Logistics & Warehousing | Pallet counting, damage detection | AI vision automates barcode scanning & loading verification |
Source: Polaris Market Research Analysis
AI Camera Market Regional Insights
AI camera market by region is segmented into North America, Europe, Asia Pacific, Middle East & Africa, and Latin America.
North America AI Camera Market Trends
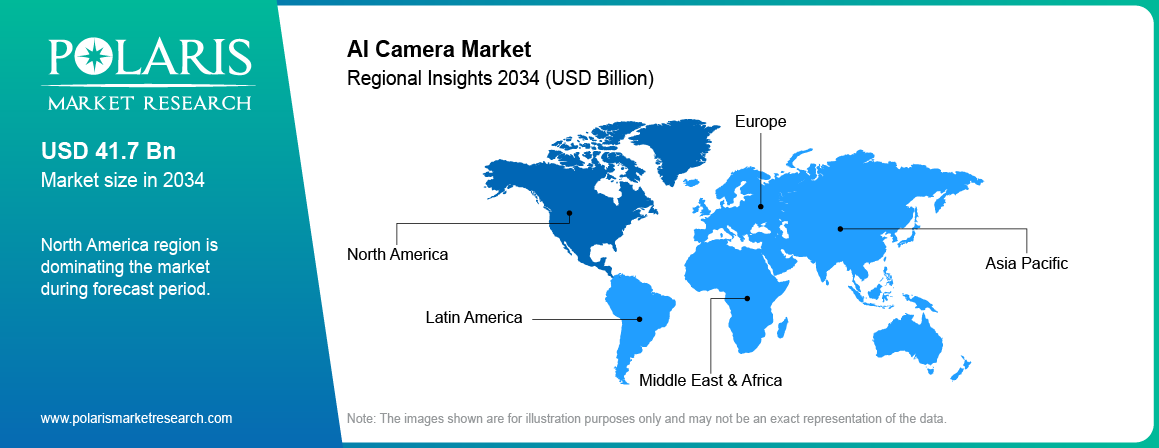
AI camera market North America held the largest revenue share of 34.00% in 2025. High investments by enterprises in security systems, advanced IT infrastructure, and increased adoption of intelligent video surveillance drive regional adoption. Companies deploy AI cameras in access control, object recognition, perimeter protection, and video analytics. The U.S. market gains advantages owing to the adoption of AI computing, security solutions, and smart buildings in the region. Opportunities are also present in Canada, especially in the areas of public safety, transportation, and industry monitoring. The increased adoption of edge AI computing and computer vision technologies is expected to drive the market in the region through 2034. In February 2026, Tenna introduced TennaCAM 2.0 HE 360 AI camera solution with 360° hazard detection and in-cab alerts for heavy equipment safety (Source: Tenna).
Europe AI Camera Market Trends
Europe held a 24.80% AI camera market share in 2025. The factors driving the demand include security needs, increasing automation in industries, and smart infrastructure initiatives. Germany, the UK, and France provide possibilities in manufacturing, transportation, retail, and security sectors. With the use of AI cameras, companies can monitor videos, spot anomalies, and automate visual inspections. EU AI Act and data regulations also play a key role in the development of AI cameras. In February 2026, French video surveillance company Vizzia secured approximately USD 33.7 million in funding in a Series B round for developing an AI-powered city surveillance solution in Europe. These factors are expected to shape regional adoption through 2034 (Source: Kurrant).
Asia Pacific AI Camera Market Trends
Asia Pacific is projected to record the fastest CAGR of 23.16% from 2026 to 2034. Opportunities are in smart city projects, electronics manufacturing, and industrial automation in China, India, Japan and South Korea. Government investments in such devices are fueling the demand for AI surveillance cameras, computer vision and edge AI processing. China leads the market with its dominance in AI camera manufacturing and adoption. The country is also extending the use of AI-based video analytics for city management. In October 2025, Hong Kong announced its plans to deploy tens of thousands of surveillance cameras with AI-enabled facial recognition. Under a police crime-fighting program, the Chinese finance hub had already deployed around 4,000 CCTV cameras. That number is expected to increase more than tenfold by 2028, up to a total of 60,000 (Source: straitstimes.com).
Latin America AI Camera Market Trends
Latin America accounted for 6.70% of the artificial intelligence camera market share in 2025. Brazil and Mexico provide opportunities in public safety, retail, transport, and commercial security. Government agencies are adopting AI video surveillance and facial recognition for better surveillance and incident response. In August 2026, Primero, an AI transformation company for Latin America, raised a USD 12 million seed funding round to help enterprises modernize legacy systems and automate operations with AI agents. Such initiatives are expected to boost the development of intelligent surveillance, video analytics and connected security infrastructure (Source: reuters.com).
Middle East & Africa AI Camera Market Trends
The Middle East & Africa held a 6.10% share of the market in 2025. The growing demand for AI surveillance cameras is attributed to the development of smart cities, infrastructure investment, and public safety needs. The UAE is investing in AI-based urban management and video analytics, while African countries are implementing smart city surveillance systems. In September 2025, Zhejiang Dahua Technology launched its WITHS range of AI-enabled wireless cameras throughout the GCC and MENA regions, with intelligent detection, remote monitoring, and flexible indoor, outdoor, and 4G-enabled surveillance. These projects are driving demand for computer vision, real-time monitoring, and integrated security platforms. But costs of infrastructure, technical skills, and privacy requirements may affect adoption rates across the region (Source: Gulf News).
AI Camera Competitive Landscape and Vendor Comparison
The AI-enabled camera market is fragmented and poised for competitive dynamics due to multiple players. The market ecosystem includes AI camera manufacturers, surveillance device providers, consumer electronics brands, imaging brands, and semiconductor makers. Competitive factors include image quality, performance of analytics, efficiency of computing, security of products, software compatibility, price, and services.
Enterprise surveillance brands compete based on their camera lineups, edge-based analytics, video management system integration, and product support life cycle. Imaging consumer electronics brands emphasize computational photography, autofocus, image processing, and ecosystem integrations. Semiconductor companies supply processors that enable local inference and multi-stream video processing. AI camera companies also focus on strategic partnerships, mergers, and acquisition to stay ahead in the competition.
Vendor Comparison
| Company (HQ) | AI camera offering / platform | Primary segments | Positioning note |
| Hangzhou Hikvision Digital Technology (China) | AcuSense, ColorVu and DeepinView AI cameras | Surveillance, smart city, SMB | Scale and price leader; restricted in US federal procurement |
| Zhejiang Dahua Technology (China) | WizSense / WizMind AI cameras | Surveillance, smart city | Broad portfolio; same US procurement restriction |
| Axis Communications (Sweden; Canon group) | ARTPEC-9 SoC cameras; AXIS Object Analytics | Enterprise, critical infrastructure, traffic | 12 ARTPEC-9 AI domes (Sep 2025); deep-learning traffic camera (Aug 2026) |
| Hanwha Vision (South Korea) | Wisenet 9 SoC; X Series AI cameras | Enterprise, retail, logistics | 2nd-gen X Series compact AI cameras with dual NPU (2026) |
| Motorola Solutions / Avigilon (US) | Avigilon Unity (on-prem) and Alta (cloud) | Public safety, enterprise | Acquisition-led; added long-range thermal via Silent Sentinel (Feb 2025) |
| i-PRO (Japan) | X Series AI cameras with on-site AI learning | Enterprise, public safety | Runs multiple AI apps per camera |
| Teledyne FLIR (US) | Thermal and visible AI cameras (Quasar AI line) | Critical infrastructure, perimeter | Thermal + AI fusion specialist |
| Sony Group (Japan) | Alpha series AI autofocus; IMX500 intelligent vision sensor | Consumer/pro imaging, sensors | Upstream sensor leader |
| Samsung Electronics (South Korea) | Galaxy AI smartphone camera features | Consumer electronics | Volume driver of on-device AI imaging |
| Ambarella (US) | CVflow edge-AI SoCs | Component supplier to camera OEMs | Cloud-orchestrated edge AI via ZEDEDA partnership (Sep 2026) |
Note: Company product descriptions are based on the vendors’ published portfolios. Axis describes its ARTPEC-9 SoC as enabling AI-powered analytics, image processing, and cybersecurity features. Hanwha Vision product information lists AI-based analytics, object detection, people and vehicle counting, and dual-NPU processing on selected models. Ambarella’s CV7 announcement describes edge AI processing for security, consumer, industrial, and automotive vision applications.
Vendor Positioning
| # | Vendor (Legal Name) | Market Position | AI Camera Focus / Core Offering | How They Win |
| 1 | Axis Communications AB | Network video pioneer (Canon Group) | AI-enabled network cameras on in-house ARTPEC chips with deep learning processing units; on-camera analytics (AXIS Object Analytics), open ACAP application platform, AXIS OS | Cybersecurity credentials, long OS support, open ecosystem and VMS integrations, strong partner-led enterprise channel |
| 2 | Motorola Solutions, Inc. | Public safety and enterprise video security | Avigilon and Pelco cameras, Avigilon Unity VMS and Alta cloud video, AI search and appearance analytics, tied to body-worn and in-car video | End-to-end public safety ecosystem (radio, video, command center), analytics-led software, government relationships |
| 3 | Hanwha Vision Co., Ltd. | Enterprise and public sector challenger (Hanwha Group) | Wisenet AI cameras on in-house Wisenet SoCs, edge analytics, AI-based object and anomaly detection, radar-camera and thermal options | In-house chip design, NDAA-compliant supply, strong price-performance and cybersecurity positioning |
| 4 | Bosch Security Systems | Premium European video security | Intelligent Video Analytics built into cameras, IVA-based metadata, strong in critical infrastructure and smart city projects | Edge analytics maturity, German engineering and data-privacy credibility, tender-driven enterprise wins |
| 5 | Honeywell International Inc. | Building technologies and integrated security | AI-enabled IP cameras and video analytics sold within integrated building security and access control suites | Installed base in commercial buildings, bundled security and building-management offerings, global service network |
| 6 | i-PRO Co., Ltd. | Japanese security camera specialist (ex-Panasonic security business) | AI-enabled network cameras with open edge-AI platform for third-party apps, privacy-masking AI, body-worn cameras | Reliability, open on-camera AI ecosystem, NDAA-compliant, public safety and transport focus |
| 7 | Hangzhou Hikvision Digital Technology Co., Ltd. | World's largest video surveillance vendor by volume | Broad AI camera range (AcuSense, DarkFighter, ColorVu, DeepinView), deep learning analytics, own AI platform and NVR/camera-NVR integration | Portfolio breadth, aggressive pricing, vertical integration, scale across Asia, Middle East, Africa and Latin America |
| 8 | Zhejiang Dahua Technology Co., Ltd. | Second-largest volume leader, China-based | WizSense and WizMind AI camera families, AI-enabled NVRs, perimeter protection and traffic analytics | Cost competitiveness, wide range, strong domestic and emerging-market distribution |
| 9 | Huawei Technologies Co., Ltd. | ICT-led smart city and AI vision challenger | HoloSens AI cameras and video platform tied to Huawei cloud, Ascend AI chips and smart city projects | System-level AI stack, government and telecom relationships, bundling with network and cloud |
| 10 | Apple Inc. | Premium on-device computational photography | Neural Engine-driven computational imaging in iPhone and iPad camera pipelines (scene and subject recognition, semantic rendering, video processing) | Vertical integration of silicon and software, ecosystem lock-in, premium installed base |
| 11 | Samsung Electronics Co., Ltd. | Smartphone imaging plus image sensor supplier | Galaxy AI-powered camera features and ISOCELL image sensors with Exynos ISP and NPU | Combines sensor, SoC and device in-house, broad price tiers, global smartphone scale |
| 12 | Google LLC | AI-first computational photography and smart home vision | Pixel computational photography on Tensor chips; Nest cameras and doorbells with AI-based detection and Gemini-powered features | Leading imaging algorithms and generative AI, cloud AI integration, Android and Home ecosystem |
| 13 | Sony Group Corporation | Image sensor leader and imaging brand | Sony Semiconductor Solutions sensors incl. IMX500 intelligent vision sensor with on-chip AI, AITRIOS edge AI platform, Alpha cameras with AI-based subject recognition | Dominant share in CMOS image sensors, sensor-level AI, strong professional and consumer imaging brand |
| 14 | Canon Inc. | Professional imaging plus security via Axis | EOS and cinema cameras with deep learning subject detection and autofocus; owns Axis, Milestone Systems and BriefCam for network video, VMS and video analytics | Optics heritage, strong professional imaging position, broad network video portfolio via acquisitions |
| 15 | Panasonic Holdings Corporation | Consumer and professional imaging, industrial vision | Lumix mirrorless cameras with AI-assisted autofocus and subject detection; industrial and professional camera systems | Imaging engineering, broadcast and professional video heritage |
| 16 | LG Electronics Inc. | Consumer electronics with embedded vision AI | Vision AI in smart home devices and robots; automotive camera modules sit largely with affiliate LG Innotek | Consumer brand reach, appliance and display ecosystem, automotive supply relationships |
| 17 | Ambarella, Inc. | Fabless edge vision SoC specialist | CVflow AI vision processors powering security, automotive and robotics cameras (CV2x, CV5, CV7 families) | Inference efficiency (TOPS per watt), image signal processing quality, strong design wins with leading camera makers |
| 18 | NVIDIA Corporation | AI computing platform for vision applications | Jetson edge modules, Metropolis vision AI framework, DeepStream SDK, GPU servers for video analytics | Developer ecosystem and tooling, scalable compute from edge to cloud, large partner network |
| 19 | Teledyne FLIR LLC | Thermal imaging specialist | Thermal and multispectral cameras with embedded AI analytics for perimeter security, fire detection and industrial inspection | Thermal sensor IP, performance in low light and harsh conditions, defense and critical infrastructure credentials |
| 20 | VIVOTEK Inc. | Taiwan-based network camera maker (Delta Electronics group) | AI-enabled IP cameras and video analytics for mid-market, with OEM and ODM supply | NDAA-compliant Taiwan base, flexible customization, cost-effective mid-range AI cameras |
Source: Polaris Market Research Analysis
List of Key Companies in the AI Camera Market
- Ambarella, Inc.
- Apple Inc.
- Axis Communications AB
- Bosch Security Systems
- Canon Inc.
- Google LLC
- Hangzhou Hikvision Digital Technology Co., Ltd.
- Hanwha Vision Co., Ltd.
- Honeywell International Inc.
- Huawei Technologies Co., Ltd.
- i-PRO Co., Ltd.
- LG Electronics Inc.
- Motorola Solutions, Inc.
- NVIDIA Corporation
- Panasonic Holdings Corporation
- Samsung Electronics Co., Ltd.
- Sony Group Corporation
- Teledyne FLIR LLC
- VIVOTEK Inc.
- Zhejiang Dahua Technology Co., Ltd.
AI Camera Industry Developments
- September 2026: Ambarella and ZEDEDA partnered to enable centralized deployment, security, and management of AI models on Ambarella edge-AI chips across cameras, robots, vehicles, and industrial devices. (Source: Ambarella)
- June 2026: CamThink launched the NeoEyes NE503 edge AI camera platform, combining 4K imaging, on-device AI processing, and application deployment capabilities for industrial vision projects. (Source: CamThink)
- June 2026: indie Semiconductor announced the iND881 edge-AI SoC for intelligent automotive and robotic cameras, including driver monitoring, advanced driver assistance and humanoid robotics applications. (Source: indie Semiconductor)
- May 2026: Hellbender raises USD 12.5 million in seed funding to scale up domestic manufacturing and launch its on-edge AI camera line. (Source: PR Newswire)
- May 2026: Hanwha Vision unveils its second generation X Series AI compact cameras powered by the Wisenet 9 AI-native SoC for enhanced video analytics and intelligent surveillance. (Source: Hanwha Vision)
- December 2025: Axis Communications has launched the AXIS Q6088-E PTZ camera, offering 4K imaging, 34x optical zoom, and edge analytics for object detection and tracking. (Source: Axis Communications)
Future Outlook
As per our AI camera market forecast 2034, the market future outlook is highly promising. The market growth will be driven by rapid adoption across smart cities, industrial automation, healthcare, and retail. From 2026 onward, demand for AI camera will accelerate due to edge AI processing, multimodal analytics, and privacy-compliant surveillance solutions. Large enterprises will continue to dominate share. However, SMEs will fuel growth with affordable cloud-based deployments. Asia Pacific is expected to lead expansion, supported by government initiatives and manufacturing strength. Services, smartphone AI cameras, and interoperability technologies will record the fastest CAGR, while hardware and surveillance cameras remain core revenue contributors. This will ensure a balanced trajectory of scale and innovation in the coming years.
Research Methodology
The AI camera market study uses secondary research, primary research, market sizing, and cross-validation to measure the base year and AI camera market forecast 2034.
Secondary research: A review of company annual reports, investor presentations, product announcements, technical documentation, industry publications, regulatory materials, and relevant market studies is conducted. Research areas include camera hardware, image sensors, edge AI processors, computer vision, video analytics, cloud surveillance and industry applications.
Primary research: The research includes interviews with camera manufacturers, software vendors, system integrators, distributors, enterprise buyers, and industry specialists. It provides a gauge of adoption patterns, purchasing priorities, deployment models, implementation costs, and technology requirements.
Market sizing and validation: Market estimates are calculated using consistent revenue definition across component, deployment, product type, technology, industry vertical, and regional segments. Bottom-up and top-down estimates are cross-checked against company disclosures, product portfolios, customer deployments, and industry activity. Regional and segment estimates are reconciled before the final forecast is published.
AI Camera Market Segmentation
By Component Outlook (Revenue, USD Billion, 2021–2034)
- Hardware
- Solutions
- Software
- Analytics
- Services
- Integration
- Managed Services
- Support
By Deployment Outlook (Revenue, USD Billion, 2021–2034)
- Cloud
- On-premises
By Organization Size Outlook (Revenue, USD Billion, 2021–2034)
- Large Enterprises
- Small & Medium Enterprises
By Product Type Outlook (Revenue, USD Billion, 2021–2034)
- Surveillance Cameras
- Smartphone Cameras
- DSLR/Mirrorless Cameras
- Automotive Cameras
- Others
By Technology Outlook (Revenue, USD Billion, 2021–2034)
- Computer Vision
- Biometric/Face Recognition
- Deep Learning
- Context-Aware Technology
- Others
By Industry Vertical Outlook (Revenue, USD Billion, 2021–2034)
- BFSI
- Healthcare
- IT & Telecommunications
- Government
- Retail
- Others
By Regional Outlook (Revenue, USD Billion, 2021-2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
AI Camera Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 15.48 Billion |
| Market Size in 2026 | USD 18.63 Billion |
| Revenue Forecast by 2034 | USD 82.31 Billion |
| CAGR | 20.41% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
AI Camera Market FAQ's
An AI camera is a camera system that uses artificial intelligence and computer vision to analyze images or video. It can find objects, identify visual features, count people or vehicles, enhance images, and generate alerts for certain events.
The market was valued at USD 15.48 billion in 2025, and is estimated to hit USD 82.31 billion by 2034, growing at a CAGR of 20.41%.
An AI camera uses an image sensor to take pictures, processes the input and runs an AI model to identify selected objects or events. The data may be processed locally on an AI SoC or NPU, on a local server, or in the cloud. It then sends alerts, metadata or video to connected apps.
A traditional CCTV camera is mainly designed to capture and transmit video. An AI camera adds automated analysis, such as object detection, event classification, people counting, or attribute-based search. Some legacy cameras can access similar functions through an external server or video management platform.
Cloud deployments use remotely managed infrastructure for selected analytics, storage, or administration. On-premises deployments process or store video on systems controlled by the customer. Hybrid & Edge First: Local analysis with central control or selected cloud services. It is dependent on latency, network access, data controls, costs, and integration requirements.
North America led the AI camera market in 2025 with a 34.00% share. Asia Pacific is projected to grow fastest, at a 23.16% CAGR through 2034.
Companies active in the market include Axis Communications, Hanwha Vision, Hikvision, Dahua Technology, Motorola Solutions (Avigilon), i-PRO, Teledyne FLIR, Sony Group, Samsung Electronics, and Ambarella. Their roles differ across surveillance cameras, consumer imaging, thermal systems, and AI processors.
Use cases of AI cameras include security surveillance, retail analytics, industrial inspection, healthcare premises monitoring, traffic control, automotive vision, smartphone cameras and data center security.
An edge AI camera performs visual analysis on or near the camera rather than transmitting every frame to a remote system. Some models use an onboard processor, SoC or NPU. This could reduce latency and network traffic, again depending on the system design.
The key drivers are camera and processor costs, model accuracy, network capacity, cybersecurity, privacy needs, compatibility with existing systems and availability of integration services. Adoption also depends on whether analytics improve a measurable business process.
Download Sample Report of AI Camera Market
Please fill out the form to request a customized copy of the research report.


