
AI Vision Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
AI Vision Market Market Summary
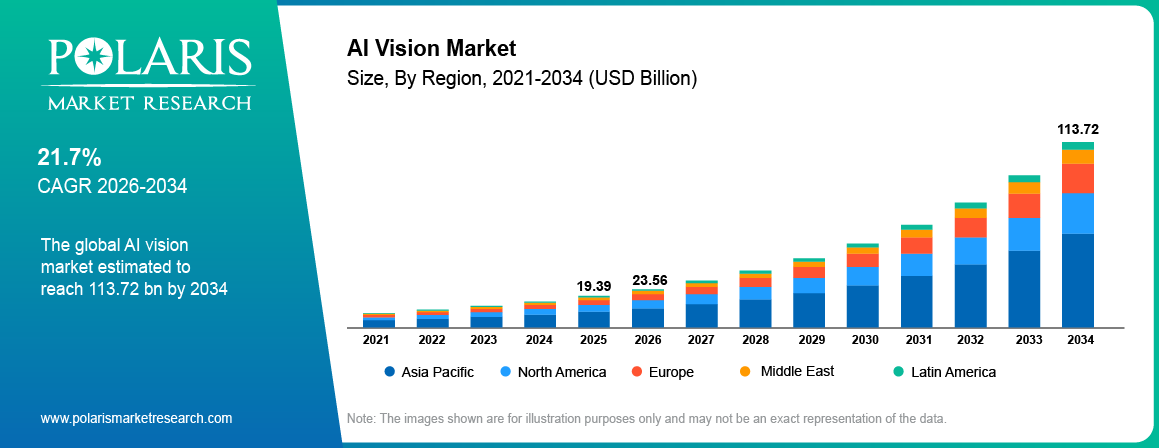
The global artificial intelligence vision market size was valued at USD 19.39 billion in 2025, growing at a CAGR of 21.7% from 2026 to 2034. The growth is driven by the increasing demand for computer vision solutions.
Market Statistics
AI Vision Market Key Takeaways 2025
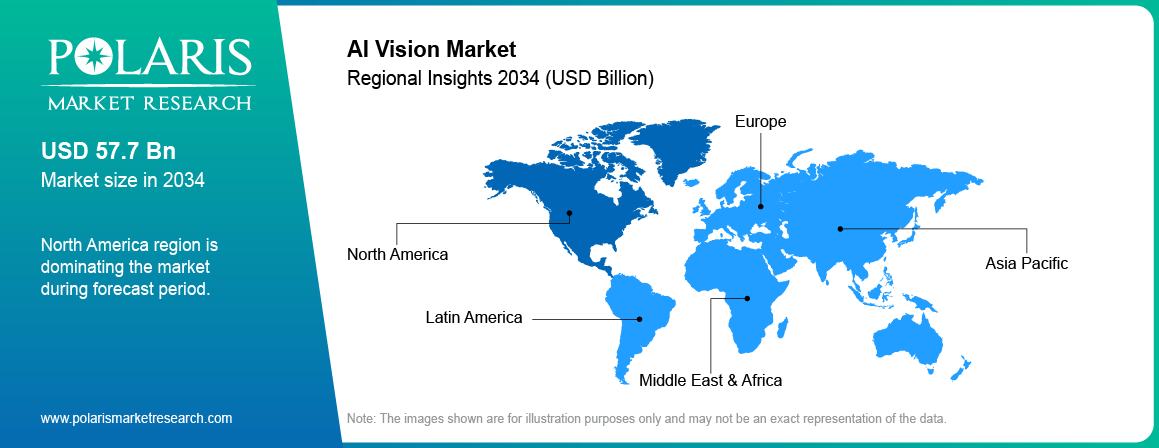
- In 2025, North America led the AI vision market share with 30.47%, supported by strong AI infrastructure, enterprise adoption, and investments in computer vision technologies.
- The Asia Pacific market is expected to register the highest CAGR of 25.68% during the forecast period. This is owing to rising manufacturing automation, robotics, smart-city projects, and rising AI investments.
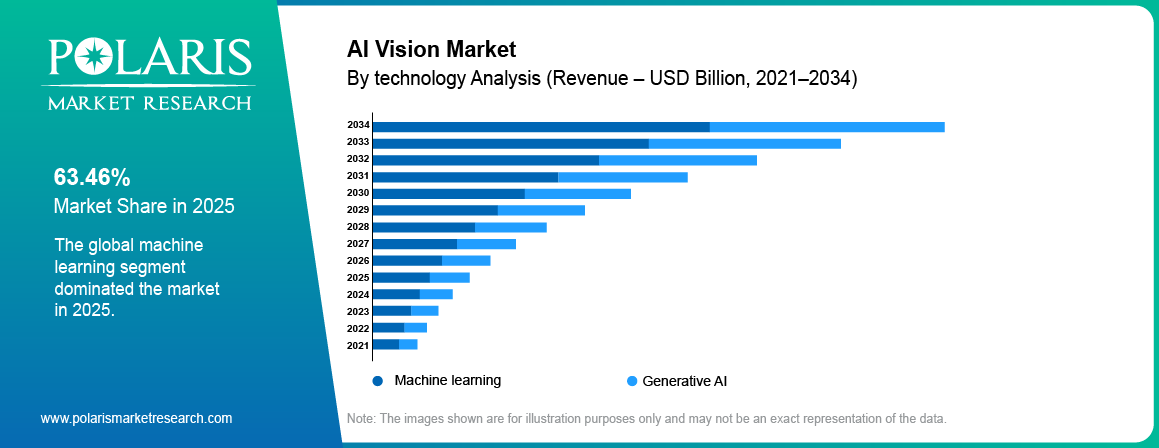
- The machine learning segment accounted for an 63.46% share in 2025, supported by its broad use in image classification, object detection, inspection, and predictive applications.
- Generative AI is expected to grow fastest at 27.14%, driven by vision-language models and multimodal AI.
- The services segment is expected to record a 26.43% CAGR during the projected period, due to demand for system integration, consulting, deployment, and maintenance.
- The edge segment is expected register a CAGR of 22.84% during the forecast period. Rising demand for low latency processing and real-time decision making propels the adoption of edge-based AI vision solutions.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations
What is AI Vision?
In AI vision, artificial intelligence is applied to interpret visual data. This means machines are able to understand and process information from cameras, imaging systems and other visual sensors. The main AI vision use cases by industry include recognizing images, object detection, optical character recognition, facial recognition, behavioral analysis, quality inspection, medical image analysis, autonomous navigation, and visual search.
The artificial intelligence vision market is closely related to the computer vision market and the machine vision market, but is increasingly incorporating advanced AI capabilities. While traditional computer vision relies on manually programmed algorithms and rules, AI-based systems can learn visual patterns from data sets, enhancing their capacity to recognize and interpret complex environments.
AI vision is a subset of AI and computer vision. It uses artificial intelligence to interpret, analyze, and extract meaning from images, video, and other visual data. AI vision technology employs computer vision, machine learning, deep learning, generative AI, image processing, sensors and computing systems to enable machines to recognize objects, recognize patterns, interpret scenes, find anomalies and enable automated decision-making.
Industrial equipment, autonomous vehicles, industrial robotics, smart cameras, healthcare, retail, security, logistics, consumer electronics, and smart city infrastructure are some of the applications in which AI vision technology is being integrated. Such applications enable organizations to automate visual inspection, monitor operations, improve decision making, increase safety and reduce reliance on manual visual analysis. Increasing deployment of robots across industrial and domestic applications is creating lucrative opportunities.
How Does AI Vision Work?
An AI vision system is composed of four components such as cameras and sensors, computing infrastructure, AI algorithms, and software applications that convert visual information into usable information.
The typical process is:
- Image or Video Capture: Image or video or any data captured using cameras and sensors.
- Data Preprocessing: The acquired data is processed using the techniques of image processing, filtering, scaling, and other pre-processing techniques.
- AI Model Analysis: The deep learning and machine learning techniques are used to detect objects, patterns, faces, text, or any visual components.
- Recognition of Feature and Context: The visual data is analyzed on the basis of trained models and application requirements.
- Decision making: The artificial intelligence models classify, raise alerts, give recommendations or make decisions.
- Action or integration: They are sent to robots, enterprise software, security systems, cars, or any other connected device.
- Continuous learning: This new data can be used to enhance the performance of the models in adapting to changing conditions.
AI Vision vs Computer Vision
Artificial intelligence vision and computer vision are related but different, in approach and capabilities. Computer vision is the field of making machines able to acquire, analyze and understand visual information using techniques such as image processing, pattern recognition and machine learning. AI vision is generally a more sophisticated method that employs AI vision technology, deep learning, generative AI and multimodal models to analyze visual data and enable automated decision-making.
AI vision is capable of understanding context, analyzing complicated visual data, generating insights, and identifying patterns with little human assistance. Computer vision is a broader technology area that encompasses traditional rule-based as well as AI-based techniques. The growing convergence of generative AI, edge computing and vision-language models is increasingly pushing the limits of AI vision beyond traditional image detection and analysis.
| Factor | AI Vision | Computer Vision |
| Core Technology | Combines computer vision with machine learning, generative AI, and multimodal models | Primarily uses image processing, pattern recognition, and predefined algorithms |
| Data Understanding | Supports contextual, semantic, and multimodal understanding of visual data | Focuses mainly on detecting, classifying, and analyzing visual information |
| Learning Capability | Can continuously improve through AI models and adaptive learning | Often relies on trained models designed for specific visual tasks |
| Decision-Making | Enables intelligent interpretation, prediction, and autonomous decision-making | Primarily provides visual insights or classifications for downstream decisions |
| Applications | Autonomous systems, robotics, smart manufacturing, healthcare, retail, and intelligent surveillance | Quality inspection, facial recognition, object detection, medical imaging, and image analysis |
Source: Polaris Market Research Analysis
Market Dynamics
Driver: Advancements in Deep Learning and Edge Computing
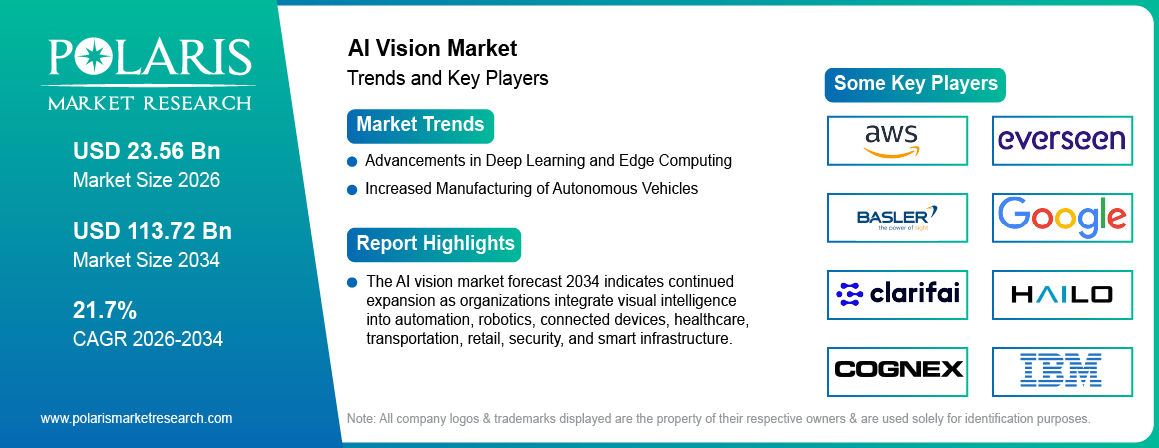
Advancements in deep learning and edge computing are accelerating the market development. Deep learning algorithms improve the ability of vision systems to identify, classify, and interpret complex visual inputs with high precision, even in unstructured or unpredictable environments. Integration with edge computing helps process data directly at the source of capture. AI vision systems operate with reduced latency and increased responsiveness. Advancements in deep learning and edge computing simplifies scaling and reduce operational costs for enterprises. This combination improves performance in time-sensitive applications such as industrial automation and smart surveillance. It also minimizes dependency on cloud infrastructure, further improving data security and reducing bandwidth usage. The integration of deep learning with edge computing is thus enabling scalable and real-time AI vision deployments across various industries.
Driver: Increased Manufacturing of Autonomous Vehicles
The increased manufacturing of autonomous vehicles contributes to the expansion of the artificial intelligence (AI) vision market. Autonomous vehicles rely heavily on vision systems powered by AI to perceive their surroundings, detect obstacles, recognize traffic signs, and make navigation decisions. The need for advanced AI vision technologies becomes necessary to assure safety, efficiency, and seamless human-machine interaction as automakers boost efforts to bring higher levels of vehicle autonomy to the sector. The U.S. dominates the development and deployment of autonomous driving technology. In May 2025, Waymo One, with its partners at Magna, announced investments in a new autonomous vehicle factory in Metro Phoenix to expand manufacturing operations. As a result, the rapid development and deployment of autonomous vehicle technologies are creating an increasing demand for AI-powered vision systems (Source: waymo.com).
Driver: Expansion of Smart Cities and Intelligent Infrastructure
As smart cities come into being, the demand for AI vision systems is increasing, with the need to evaluate traffic, pedestrian activity, public infrastructure, parking availability, road conditions and environmental conditions. AI-enabled cameras allow municipalities and infrastructure operators to convert visual data into operational insights, not manual monitoring.
Recent work published in Sustainable Cities and Society points to the growing adoption of computer vision for built-environment analysis, urban sensing, smart mobility, 3D urban modeling, and automated planning workflows. The research further reveals new applications of foundation models and generative systems in urban visual analytics.
This trend creates opportunities for AI vision companies that supply intelligent traffic management, video analytics, public safety, infrastructure inspection and urban planning solutions. Privacy-preserving architectures are also becoming increasingly relevant as large-scale visual monitoring will require controls around data protection, anonymization, access and model governance.
Restraint: High Deployment and Integration Costs
AI vision systems need cameras, sensors, edge processors, GPUs, AI software, connectivity, data storage, and integration with existing infrastructure. The requirements can mean a higher initial investment, especially for organizations deploying systems in multiple production sites or large physical facilities. Costs may include model development, data preparation, system customization, cybersecurity, maintenance and employee training. Integration with legacy equipment may require additional upgrades or specialized solutions, adding more complexity to deployment. Such financial and technical requirements can be a barrier to adoption, especially for small and medium-sized businesses with more limited technology budgets.
Opportunity: Growth of Edge AI Vision
The development of Edge AI opens many new possibilities for the use of AI vision when fast reaction time, privacy and less connectivity are needed. It enables the cameras and sensors to process data in real time, without having to send every image and video feed back to a centralized cloud computing platform.
Edge AI vision is becoming increasingly common in the areas of manufacturing, retail, transport, security, and autonomy. On May 2026, Cognex launched the In-Sight 3900, a full-featured AI vision system based on Qualcomm technology that enables fast and efficient edge AI inspection without requiring any PC connection. The technology can enable real-time quality inspection, object detection, predictive maintenance and video analytics, while reducing latency and bandwidth requirements (Source: prnewswire.com).
The 2026 product awards from the Edge AI and Vision Alliance highlighted advances in edge AI and computer vision, including technologies from Intel, Nota AI, SiMa.ai, Synaptics and other providers.
AI Vision Market Challenges
- Availability of Data: Data should be both high quality and varied in order to have good performance of AI algorithms.
- Privacy Concerns: Technologies such as facial recognition and behavior analysis may have problems with regulatory issues.
- Model Performance: Model’s performance could be affected by environment, lighting, camera angle, or operation parameters.
- Security Issues: The connectivity of cameras and edge devices could increase attack surface area, leading to demand for AI security operations (AI SOC).
- Integration complexity: AI vision systems often need to connect with existing enterprise and operational technology systems.
AI Vision Market Segmentation Analysis
AI vision market segmentation includes technology, service type, component, mode of operation, vertical, and region.
By Technology Analysis
The segmentation, based on technology, includes machine learning and generative AI. The machine learning segment held the largest share of 63.46% in 2025, primarily due to its advanced capabilities in training systems to analyze vast amounts of visual data with minimal human intervention. Machine learning models improve the accuracy and reliability of image and video analysis by allowing continuous learning and adaptability. These models are widely adopted in industrial automation, healthcare diagnostics, and security systems where high-speed and high-volume processing is critical. Furthermore, their integration with existing vision systems allows for scalable deployment across various sectors, driving their widespread acceptance.
By Service Type Analysis
The segmentation, based on service type, includes behavioral analysis, optical character recognition, spatial analysis, and image recognition. The behavioral analysis segment is expected to witness the fastest CAGR of 27.31% during the forecast period driven by the increasing demand for intelligent systems that can interpret human behavior through facial expressions, gestures, and movement patterns. This service type is gaining traction across sectors such as retail, smart cities, and surveillance, where understanding consumer or public behavior leads to improved service delivery, security, and operational efficiency. The growing adoption of AI-powered behavioral analytics in fraud detection, employee monitoring, and public safety applications further accelerates its market penetration.
By Component Analysis
The segmentation, based on component, includes hardware, software, and services. The services segment is expected to register the highest CAGR of 26.43% during the forecast period, fueled by rising demand for consulting, integration, and maintenance services essential for the deployment and optimization of AI vision systems. The need for expert support in customizing and scaling these systems becomes critical as organizations implement AI vision solutions across diverse applications. Service providers play a major role in assuring smooth transitions, upgrading legacy infrastructure, and allowing real-time analytics capabilities, making this segment essential to the sector’s growth.
By Mode of Operation Analysis
The cloud segment accounted for 56.73% AI vision market share in 2025, propelled by scalable computing capacity, centralized data management, and growing cloud-based AI development platforms. With cloud-based AI vision, organizations can evaluate large volumes of visual data and take advantage of computing resources, without having to make large on-premise investments. It also supports centralized analytics, model management and integration with enterprise applications, for scalable AI vision technology deployment across multiple locations.
The edge segment is projected to grow at CAGR of 22.84% during the forecast period owing to the demand for low-latency processing and real-time visual analysis. Edge AI vision systems bring processing closer to the camera and the connected devices, reducing latency and bandwidth requirements. This methodology is being increasingly used in manufacturing, robotics, autonomous systems, retail, security and logistics. The increasing integration of edge AI vision is also driving AI vision market trends, allowing for quicker and more agile visual decision-making.
Comparison Matrix: Edge vs. Cloud
| Factor | Edge AI Vision | Cloud AI Vision |
| Data Processing | Processes data locally near the source | Processes data through centralized cloud infrastructure |
| Latency | Low latency; supports real-time decision-making | Relatively higher latency due to data transfer |
| Data Privacy | Higher privacy with localized data processing | Data is typically transferred to cloud servers |
| Scalability | Requires additional edge hardware for expansion | Highly scalable through cloud computing resources |
| Key Applications | Manufacturing, robotics, autonomous systems, and smart cameras | Video analytics, healthcare, retail, and enterprise applications |
Source: Polaris Market Research Analysis
By Vertical Analysis
The segmentation, based on vertical, includes government, banking and finance, consumer electronics, healthcare, transport/logistics, defense & security, and others. The banking and finance segment is expected to witness the fastest CAGR of 30.42% during the forecast period as financial institutions increasingly integrate AI vision technologies for improved security, customer experience, and operational efficiency. AI vision is being used in some applications like facial recognition-based authentication, ATM surveillance and fraud detection through behavioral pattern analysis. The sector’s growing emphasis on digital transformation and cybersecurity is resulting in greater demand for intelligent visual systems that facilitate automated and secure financial operations.
Market Segmentation Summary Table
| Dimension | Leading Sub-Segment (2025) | Fastest-Growing Sub-Segment | Key Metric |
| By Technology | Machine Learning | Generative AI | Machine Learning: 63.46% share; Generative AI: 27.14% CAGR |
| By Service Type | Image Recognition | Behavioral Analysis | Image Recognition: 41.61% share; Behavioral Analysis: 27.31% CAGR |
| By Component | Software | Services | Hardware: 45.72% share; Services: 26.43% CAGR |
| By Mode of Operation | Cloud | Edge | Cloud: 56.73% share; Edge: 22.84% CAGR |
| By Vertical | Consumer Electronics | Banking and finance | Consumer Electronics: 25.18% share; Banking and finance: 30.42% CAGR |
Source: Polaris Market Research Analysis
Use Cases & Applications of AI Vision
AI vision is being deployed across a wide range of commercial and industrial applications.
- Inspection in Manufacturing: Helps in detecting defects in the product, dimensions, surface and process defects.
- Robotics: Helps robots identify objects, understand their environment, navigate within it and execute complex tasks.
- Analytics in Retail: Used for analyzing consumer behavior, inventory management, shelf management, loss prevention.
- Imaging in Healthcare: Helps in image analysis, disease diagnosis and medical diagnostics.
- Automated Vehicles: In the automotive industry, vision AI helps in detecting objects, lanes, pedestrians, and the environment.
- Intelligent Surveillance: Identifies unusual behavior, objects, movements, and security incidences.
- Logistics and Warehousing: Helps in detecting packages, inventory control, sorting, and robots in the warehousing field.
- Optical Character Recognition: Helps in converting visual information like printed text and handwriting into digital form.
- Agriculture: Helps in crop monitoring, disease identification, yield estimation, and precision farming.
- Smart Cities: Provides traffic monitoring, public safety, infrastructure monitoring, and urban analytics.
Generative AI's Role in AI Vision
Generative AI computer vision is expanding the horizons of traditional visual AI by combining image and video understanding with generative models, large language models and multimodal reasoning. They can interpret images with natural-language prompts, summarize video activity, generate synthetic visual data, generate visual content, and enable natural-language interaction with visual databases. In three years, the adoption of generative AI globally has reached 53% and the value of consumers in the US alone will be USD 172 billion a year by early 2026, says Stanford University (Source: hai.stanford.edu).
Generative AI helps build AI vision by generating synthetic images to train models, helping with automated image labeling, improving visual search, and creating simulation environments. Models that understand vision and language enable users to query visual information with natural language, which could help users interact with surveillance footage, manufacturing data, retail imagery and other visual data.
Qualcomm has been working to bolster its AI infrastructure to handle computer vision and generative AI workloads on edge and on-premises systems. Its intelligent video solutions combine computer vision, generative AI and camera processing for a range of use cases from security and worker safety to manufacturing, retail, healthcare and site monitoring.
The adoption of generative AI also introduces new challenges. Visual hallucinations, inaccurate descriptions, biased training data and unreliable outputs can influence operational decisions, so organizations should validate information that is generated or interpreted.
Edge AI in Vision Systems
Edge AI vision systems perform visual inference locally on cameras, gateways, robots, vehicles, smartphones, appliances, or industrial equipment instead of sending every visual input to a remote cloud environment. This architecture is becoming increasingly important for applications requiring rapid response and greater control over sensitive visual data.
Edge AI is able to reduce latency, with inference happening close to where the data is generated. It can also reduce bandwidth consumption by transmitting metadata or selected events, rather than continuous raw video. These benefits are especially important for industrial automation, autonomous vehicles, robotics, smart cameras, drones, healthcare devices and security applications.
Qualcomm’s 2026 Dragonwing portfolio includes processors for smart cameras, drones, industrial and machine vision, and other intelligent edge applications. Qualcomm also describes its edge development platforms as supporting real-time object detection, robotics, autonomous drones, surveillance, quality control, and process automation. (Source: qualcomm.com)
The edge model does not eliminate cloud computing. Instead, many deployments are moving toward hybrid architectures in which immediate inference occurs at the edge while model training, centralized analytics, fleet management, and historical data processing occur in the cloud.
AI Vision Market Regional Insights
The report provides market insights into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. The North America AI vision market dominated with 30.47% revenue share in 2025, supported by strong technological infrastructure, significant investments in R&D, and high adoption of AI-powered systems across industries. For instance, IFR said industrial robot installations in the U.S. increased 11% in 2025 to 38,000 units to support demand for machine vision and AI-enabled robotics. The region remains a frontrunner in deploying AI vision across various sectors such as manufacturing, healthcare, and autonomous vehicles, while it is also witnessing an increased interest in smart surveillance and robotics. The presence of major AI solution providers and early adopters contributes significantly to the region’s leadership position (Source: manufacturingdive.com).
The US AI vision market held 72.35% revenue share in North America in 2025, driven by rising focus on AI innovation and the widespread integration of computer vision across numerous industries such as healthcare, defense, and autonomous mobility. The growing demand for real-time surveillance, patient monitoring, and automated quality control in manufacturing is driving the increased adoption of AI vision systems.
The Asia Pacific AI vision market is anticipated to witness the fastest CAGR of 25.68% during the forecast period attributed to rapid industrialization, rising adoption of automation technologies, and rising investments in smart manufacturing and urban infrastructure. The AI vision deployment in the region is being fast tracked by government driven digital transformation initiatives. India is expanding AI applications in healthcare and retail, while countries that lead in smart surveillance and robotics are focusing on factory automation. India plans to build a major AI computing infrastructure with 18,693 GPUs with the ~USD 1.2 billion IndiaAI Mission, boosting the nation’s digital economy (Source: electronicsforyou.biz).
The China AI vision market accounted for 11.36% revenue share in Asia Pacific, due to its aggressive investments in public surveillance systems and industrial automation. The integration of AI vision into large-scale infrastructure and urban monitoring projects is creating vast opportunities for domestic technology providers. Furthermore, China’s expanded manufacturing base is increasingly implementing AI-powered vision systems in defect detection and predictive maintenance.
The Europe AI vision market is projected to witness 21.72% CAGR over the forecast period, due to strong regulatory structures supporting the adoption of AI and growing demand for smart technologies in automotive, logistics, and public safety sectors. Germany is developing AI-based automotive systems, and France is pouring into AI research. The region’s emphasis on the ethical use of AI and the modernization of digital infrastructure is creating an enabling environment for the growth of AI vision technology. In January 2026, the EU invested $356 million in AI and related technologies to promote the development of AI applications related to the AI vision industry (Source: ec.europa.eu).
The UK AI vision market is expected to record a CAGR of 20.74% during the forecast period owing to the continued focus of the country on AI-driven innovation in healthcare, finance, and transportation sectors. The UK is building an ecosystem that supports technological advancements with strong academic and research institutions spearheading advancements in visual artificial intelligence algorithms. Applications such as AI-powered diagnostic imaging, smart traffic monitoring, and biometric security systems are witnessing increased deployment.
Latin America AI vision market is projected to record a CAGR of 22.46% during the projected period. The regional market is expanding as enterprises and governments increase investment in AI infrastructure, smart-city initiatives, industrial automation, and intelligent surveillance. Brazil represents a key regional market. It is supported by AI infrastructure development, precision agriculture, and Industry 4.0 adoption.
The Middle East & Africa AI vision market is expected to exhibit a CAGR of 23.28% during the forecast period. This is gaining momentum from digital transformation, smart-city development, security applications, and industrial automation. Saudi Arabia and the UAE are prominent adoption centers, with computer vision increasingly deployed in surveillance, transportation, manufacturing, healthcare, and oil & gas.
Competitive Insights
The AI vision industry is experiencing substantial growth, fueled by advancements in deep learning and edge computing that improve real-time data processing and accuracy. Major players such as NVIDIA and Intel and emerging startups such as Wayve are making strategic investments, highlighting the sector's revenue potential in areas such as autonomous vehicles, industrial automation, and smart surveillance.
Competition is boosting, with companies focusing on sustainable value chains and partnerships to scale their solutions effectively. However, challenges such as semiconductor supply chain disruptions are encouraging firms to explore new strategies, including localized GPU production. Businesses that leverage these trends while addressing technical and logistical limitations are positioned for long-term success as the industry evolves.
Leading AI vision companies are aiming for autonomous vehicles, industrial automation, smart surveillance, machine vision, and edge AI vision systems. It competes with cloud providers, semiconductor manufacturers, computer vision software companies, and industrial technology providers. The top AI vision companies are increasingly focusing on AI accelerators, generative AI vision, multimodal models, edge inference, intelligent cameras, robotics, and industry-specific solutions.
Trends in the AI vision market are also being driven by strategic alliances between AI model providers, semiconductor companies, camera manufacturers, robotics companies, and system integrators. It enables integrated solutions combining AI models, hardware, connectivity and visual analytics.
List of Top AI Vision Companies 2026
- Amazon Web Services, Inc.
- Basler AG
- Clarifai, Inc.
- Cognex Corporation
- Everseen Limited
- Google LLC (Alphabet Inc.)
- Hailo Technologies Ltd.
- IBM Corporation
- Intel Corporation
- Keyence Corporation
- LandingAI
- Microsoft Corporation
- NVIDIA Corporation
- OMRON Corporation
- Qualcomm Technologies, Inc.
- Siemens AG
- Sony Group Corporation
- STMicroelectronics N.V.
- Teledyne Technologies Incorporated
- Zebra Technologies Corporation
Competitive Benchmarking
| Company | HQ | Primary Focus | Segment Strength |
| NVIDIA Corporation | US | Vision AI, Metropolis, Cosmos, Physical AI | Robotics, video analytics, autonomous systems |
| Microsoft Corporation | US | Azure AI Vision | Enterprise, cloud, analytics |
| Google LLC (Alphabet Inc.) | US | Google Cloud Vision AI, Gemini vision and robotics models | Cloud, enterprise, multimodal AI |
| Amazon Web Services, Inc. | US | Amazon Rekognition, AWS AI services | Retail, security, enterprise |
| IBM Corporation | US | AI and visual analytics | Enterprise, healthcare, industry |
| Intel Corporation | US | Edge AI and computer vision platforms | Edge, industrial, automotive |
| Qualcomm Technologies, Inc. | US | Edge AI and vision platforms; Dragonwing processors | Automotive, IoT, robotics, industrial |
| Cognex Corporation | US | Industrial machine vision; In-Sight embedded AI vision systems | Manufacturing, inspection |
| Basler AG | Germany | AI cameras and vision systems | Manufacturing, logistics |
| Teledyne Technologies Incorporated | US | Imaging sensors and cameras | Industrial, scientific, defense |
| STMicroelectronics N.V. | Switzerland (Geneva); incorporated in the Netherlands | Vision sensors and semiconductors | Automotive, industrial, consumer |
| Keyence Corporation | Japan | Machine vision systems and sensors | Factory automation, inspection |
| OMRON Corporation | Japan | Industrial automation and machine vision | Manufacturing, electronics |
| Sony Group Corporation | Japan | Image sensors and intelligent vision sensors | Consumer electronics, automotive, industrial |
| Zebra Technologies Corporation | US | Machine vision and fixed industrial scanning | Logistics, retail, manufacturing |
| Clarifai, Inc. | US | AI and computer vision platform | Enterprise AI |
| Everseen Limited | Ireland | Vision AI automation for retail | Retail, logistics |
| Hailo Technologies Ltd. | Israel | Edge AI processors for vision | Smart cameras, automotive, industrial |
| Landing AI | US | Vision AI platform (LandingLens) | Manufacturing, inspection |
| Siemens AG | Germany | Industrial automation and AI-based inspection | Manufacturing, industrial |
Source: Polaris Market Research Analysis
Recent Developments
- September 2026: Qualcomm announced the Dragonwing Q-2390 and IQ-2390 processors targeted at smart connected and industrial applications including machine vision and automation. (Source: qualcomm.com)
- September 2026: OpenSpace added Spatial AI and AI-agent features driven by visual and spatial data to support construction teams in understanding jobsite conditions and automating field workflows. Visual AI agents are creating an even bigger market opportunity. (Source: openspace.ai)
- July 2026: Google announced the Gemini Robotics ER 2 with video understanding, spatial reasoning, task planning, and multi-robot collaboration. (Source: blog.google)
- May 2026: Inbolt released AI-enabled robot programming, which allows engineers to generate robot programs from CAD models and adjust them to real-world factory conditions via vision-based guidance. (Source: inbolt.com)
- March 2026: NVIDIA released its Physical AI Data Factory Blueprint to help generate synthetic data, train AI, and develop vision AI agents, robotics and autonomous vehicles. (Source: nvidia.com)
AI Vision Market Segmentation
By Technology Outlook (Revenue, USD Billion, 2021–2034)
- Machine Learning
- Generative AI
By Service Type Outlook (Revenue, USD Billion, 2021–2034)
- Behavioral Analysis
- Optical Character Recognition
- Spatial Analysis
- Image Recognition
By Component Outlook (Revenue, USD Billion, 2021–2034)
- Hardware
- Software
- Services
By Mode of Operation Outlook (Revenue, USD Billion, 2021–2034)
- Edge
- Cloud
By Vertical Outlook (Revenue, USD Billion, 2021–2034)
- Government
- Banking and Finance
- Consumer Electronics
- Healthcare
- Transport/Logistics
- Defense & Security
- Others
By Regional Outlook (Revenue, USD Billion, 2021-2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
AI Vision Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 19.39 Billion |
| Market Size in 2026 | USD 23.56 Billion |
| Revenue Forecast by 2034 | USD 113.72 Billion |
| CAGR | 21.7% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Future Outlook
The AI vision market forecast 2034 indicates continued expansion as organizations integrate visual intelligence into automation, robotics, connected devices, healthcare, transportation, retail, security, and smart infrastructure. Future development will be for edge AI vision, generative AI, multimodal models, vision-language systems, autonomous robotics, smart cameras, and AI-enabled industrial equipment. Cloud infrastructure will still be used to enable centralized analytics and model management, while edge processing will likely continue to be important where low latency and data privacy are priorities.
Generative AI is expected to expand the functionality of AI vision from recognition toward reasoning and natural-language interaction. At the same time, privacy, cybersecurity, model validation, data governance, and regulatory compliance will become increasingly important as AI vision moves into public infrastructure, healthcare, financial services, and consumer environments.
The combination of falling AI inference costs, expanding edge computing capabilities, greater availability of visual datasets, and growing industrial automation is expected to support broader deployment through 2034.
Research Methodology
The Polaris Market Research AI vision market report uses a structured approach combining secondary research, primary research, market sizing, and data triangulation to develop market estimates and forecasts.
Secondary Research: Data collection involves company filings, industry journals, technology white papers, government sources, regulatory databases, product announcements, and industry organizations related to AI vision, computer vision, edge AI, robotics, and related technologies.
Primary Research: Interviews with technology providers, camera and sensor manufacturers, semiconductor companies, software providers, system integrators, robotics companies, consultants and end users confirmed findings.
Market Size Estimation: The report estimates the AI vision market size by applying a top-down and bottom-up approach considering revenue generated from various applications of the AI vision market and its adoption rate in the AI and computer vision ecosystem, deployment of products, regional demand, and company revenues.
Data Triangulation: Market estimates are cross-verified with company data, industry adoption rate, market developments, and inputs from primary research to derive segment, regional, and overall market forecasts.
AI Vision Market FAQ's
AI vision refers to the application of artificial intelligence to analyze images and videos so as to allow machines to identify objects, patterns, environments and activities.
The global AI Vision market is expected to grow from USD 19.39 billion in 2025 to USD 113.72 billion by 2034, driven by rising manufacturing of autonomous vehicles.
The global AI vision market CAGR 2034 is projected to be 21.7%, due to growing requirement for automation across various sectors.
Market drivers consist of industrial automation, robotic applications, real-time analytics, edge AI, generative AI, and demand for automated visual inspection.
The machine learning segment dominated the technology segment with an 63.46% share in 2025. This is attributed to its advanced capabilities in training systems for analyzing vast amounts of visual data with minimal human intervention.
Some of the main hurdles are high implementation cost, data quality issues, privacy concerns, reliability of models, cyber security issues, and complicated integrations.
North America led the market with a share of 30.47% in 2025, owing to sophisticated infrastructure and AI-based automation.
Computer vision is the art of teaching machines how to process visual information. However, AI vision is usually a combination of computer vision with the broader capabilities of AI such as machine learning, generative AI, and reasoning.

Download Sample Report of AI Vision Market
Please fill out the form to request a customized copy of the research report.


