Arteriovenous Fistula Devices Market Size Estimation, Share, and Future Demand, 2026-2034
REPORT DETAILS
Arteriovenous Fistula Devices Market Summary
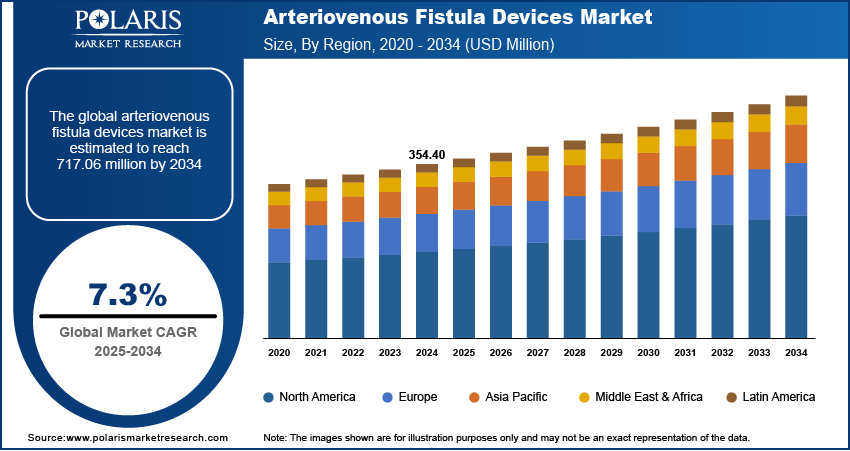
The global arteriovenous fistula devices market size was valued at USD 1.14 billion in 2025, growing at a CAGR of 7.49% from 2026–2034. Global prevalence of CKD and ESRD is growing with increasing aging populations and lifestyle conditions supplemented by growing healthcare spending and investments in the management of chronic diseases.
Market Statistics
Key Takeaways
- North America led in 2025 with 45.0% market share, driven by advanced dialysis infrastructure and robust government programs for the management of chronic kidney disease.
- The U.S. contributed the largest regional share of 79.0% in 2025, owing to high patient awareness and reimbursement schemes for vascular access operations.
- Asia Pacific registered the highest CAGR of 10.30% due to increasing CKD prevalence, growing dialysis networks, and enhanced accessibility of healthcare.
- Regional growth was boosted tremendously by China with 46.0% share of APAC in 2025 through expanding dialysis centers and government programs supporting vascular access programs.
- AVF creation devices dominated in 2025 with 50.0% market share attributable to established long-term patency and extensive usage in open surgery and minimally invasive procedures.
- AVF monitoring devices are anticipated to account for the highest CAGR of 9.25% due to growing usage of real-time imaging and early detection of complications technologies.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
Industry Dynamics
- Increasing incidence of end-stage renal disease (ESRD) and chronic kidney disease (CKD) is driving the demand for arteriovenous fistula devices.
- Increasing healthcare spending and chronic disease treatment investments are propelling market adoption.
- Procedural issues and high device prices are limiting market growth.
- The growth prospects for the industry are high with innovations in minimally invasive devices and AI-enhanced imaging.
What is Arteriovenous Fistula Devices?
Arteriovenous fistula devices support stable vascular access for hemodialysis in patients with end-stage renal disease (ESRD) and chronic kidney disease (CKD). Minimally invasive and advanced device technologies allow for faster procedures, better patient outcomes, and fewer complications like thrombosis and infection. They are used in surgical and image-guided procedures that support clinicians in the management of dialysis treatment, extending vascular life, and promoting patient quality of life.
Government health policy initiatives, chronic disease management schemes, and reimbursement programs encouraging dialysis access are driving demand for AV fistula devices. National kidney disease awareness programs and schemes are increasing access to safe and durable vascular access solutions by patients, benefiting hospital and dialysis center adoption.
Source: Polaris Market Research Analysis
Rising healthcare expenditures, investment in dialysis infrastructure and training of vascular access specialists are driving the market. Rising investment in dedicated dialysis centers and advanced vascular care facilities is leading to increased access to immediate fistula creation, follow-up and maintenance procedures. Moreover, the rising number of specialist training programmes is increasing clinical skills in access management, resulting in improved procedural success rates and increased use of advanced arteriovenous fistula devices. These factors are forecasted to increase access to treatment and drive market growth throughout the forecast period.
Drivers & Opportunities
Which are the driving factors for Arteriovenous Fistula Devices Market?
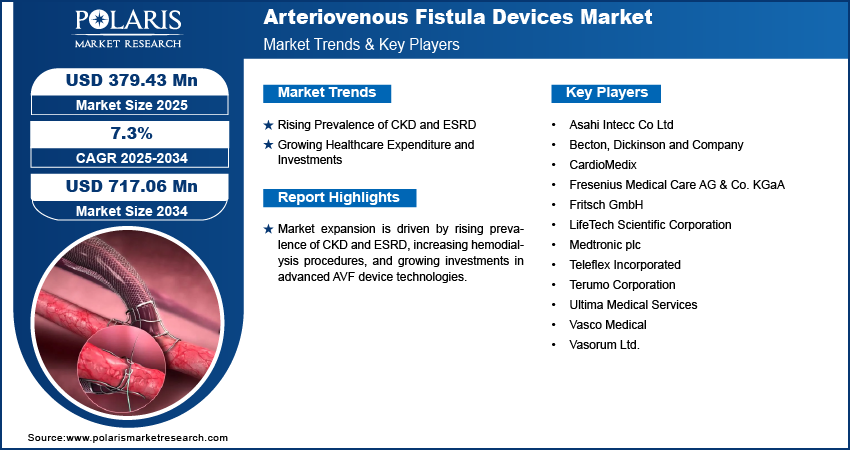
Rising Prevalence of CKD and ESRD: The increasing prevalence of end-stage renal disease (ESRD) and chronic kidney disease (CKD) is generating a high demand for stable vascular access products. World Kidney Day suggests that chronic kidney disease exists in 10% of the global population, and millions of people die every year as they cannot afford the treatment. As an increasing number of patients are in need of long-term hemodialysis, there is a growing demand for arteriovenous fistula devices as they have better patency rates and fewer complications than central venous catheters and synthetic grafts. Such a trend is most prominent in aging societies and countries with increased incidence of diabetes and high blood pressure, which are leading causes of CKD.
Growing Healthcare Expenditure and Investments: Growing healthcare spending and investments in chronic disease care are driving the use of arteriovenous fistula devices. Governments and private healthcare organizations are increasing dialysis infrastructure, renovating surgical centers, and credentialing vascular access specialists to enable quality care. Such investments enhance procedure efficiency, minimize complications, and facilitate broader patient access, positioning AV fistula devices as a solution of choice in both developed and emerging markets.
Difference Between AV Fistula Vs. AV Graft Vs. Central Venous Catheter
Vascular access selection plays a critical role in hemodialysis outcomes. Arteriovenous (AV) fistulas are preferred due to better long-term performance. However, AV grafts and central venous catheters (CVCs) are used where fistula creation is unsuitable or immediate access is required.
| Parameter | AV Fistula | AV Graft | Central Venous Catheter |
| Durability | Highest durability; can function for several years with proper care | Moderate durability; synthetic material may require replacement over time | Lowest durability; designed mainly for temporary or short-term use |
| Infection Risk | Lowest infection risk due to use of patient’s own blood vessels | Higher risk than fistula due to implanted synthetic material | Highest infection risk due to external access and catheter-related infections |
| Blood Flow Efficiency | Excellent blood flow after maturation; supports effective dialysis | Good blood flow but may decline due to narrowing or clot formation | Lower efficiency; flow limitations are more common |
| Complication Rates | Lower complications; possible issues include stenosis, aneurysm, or maturation failure | Higher risk of thrombosis, infection, and graft failure | Higher risk of bloodstream infection, clotting, and vein damage |
| Long-Term Dialysis Suitability | Preferred option for long-term dialysis patients | Suitable alternative when fistula is not possible | Generally not recommended for long-term use |
Source: Polaris Market Research Analysis
Segmental Insights
Type Analysis
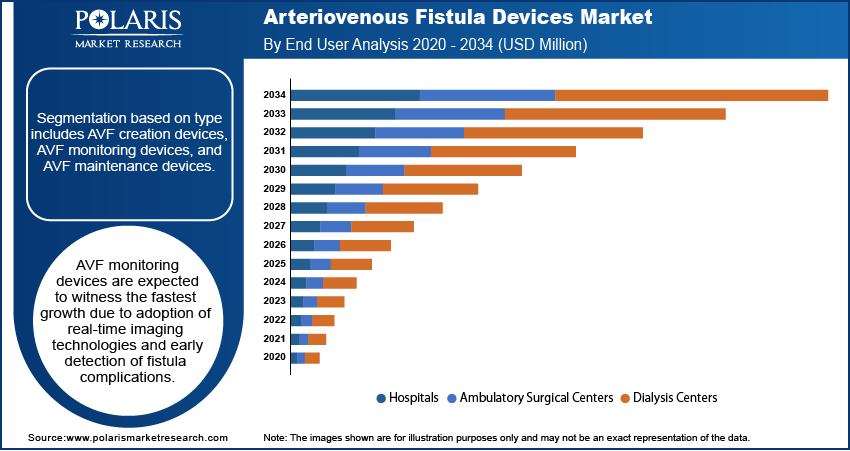
On the basis of type, segmentation is comprised of AVF creation devices, AVF monitoring devices, and AVF maintenance devices. AVF creation devices led the market with 50.0% share in 2025 on account of strong demand for minimally invasive surgery and surgical fistula procedures. Moreover, such devices provide long-term vascular access and less complications as compared to synthetic graft or catheters.
In terms of type, AVF monitoring devices are projected to grow at the fastest CAGR of 9.25% during the forecast period due to rising adoption of real-time imaging technologies. Also, they improve procedure accuracy and enable early detection of fistula complications.
End User Analysis
On the basis of end user, the market is segmented into hospitals, ambulatory surgical centers, and dialysis centers. Hospitals dominated the market in 2025 with 55.0% share, due to their advanced surgical infrastructure and trained vascular specialists. Also, hospitals handle high dialysis patient volumes, and implement long-term care programs that promote AVF device adoption.
Ambulatory surgery centers are predicted to grow fastest at a CAGR of 9.25% as minimally invasive AVF procedures continue to be adapted to outpatient locations. Advances in endovascular fistula creation techniques and procedural efficiencies are providing the ability for appropriate patients to be treated without extended hospitalizations. Moreover, the higher revenue generated by AVF devices, shorter recovery time, and increasing availability of specialized vascular access services, are also contributing the uptake of AVF devices in ASCs.
Technological Advancements in AV Fistula (AVF) Devices
| Technology | Description | Market Impact |
| AI-Assisted Monitoring | Uses AI to analyze blood flow patterns, detect early signs of stenosis, and monitor fistula performance | Improves early complication detection, reduces access failure, and supports personalized dialysis management |
| Ultrasound-Guided AVF Mapping | Advanced imaging techniques used before surgery to assess vessel size, location, and suitability for fistula creation | Enhances fistula success rates and reduces surgical complications |
| Endovascular Creation Systems | Minimally invasive devices that create AV fistulas through catheter-based approaches instead of open surgery | Expands treatment options, reduces recovery time, and improves patient comfort |
| Advanced Angioplasty Balloons | Specialized balloons designed to treat AVF narrowing and restore blood flow with improved precision | Extends fistula lifespan and reduces the need for repeated surgical interventions |
Source: Polaris Market Research Analysis
Regional Analysis
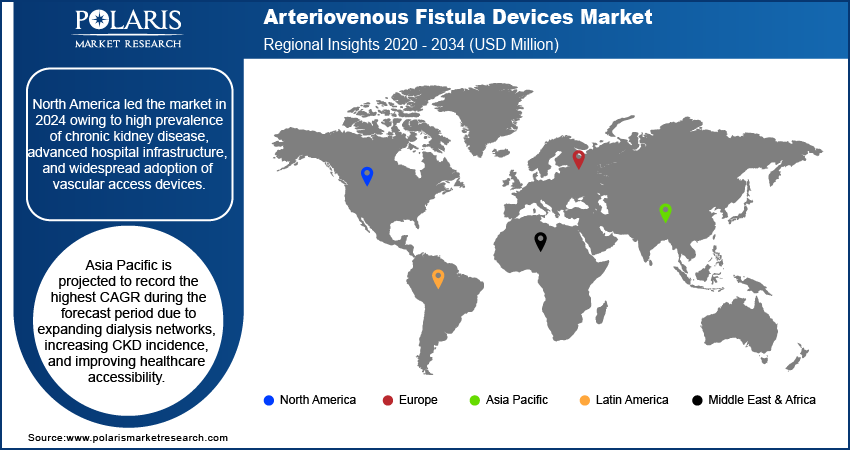
North America held 45.0% market share in 2025, which can be attributed to the related factors such as the high incidence of chronic kidney disease, gigantic dialysis patient population, and well-developed dialysis infrastructure. In light of established reimbursement models and an increasing trend towards long-term vascular access, the deployment of complex AVF creation, surveillance and interventional device systems is taking off. Robust healthcare spending, dedicated vascular access teams along with the introduction of new treatment options are other factors propelling the market dominance in this region
The U.S. Arteriovenous Fistula Devices Market Insight
In 2025, U.S. held a dominant 79.0% share of the North American market, owing to the presence of a large dialysis patient pool, and well-developed hospital infrastructure to carry out AVF surgeries. The increasing prevalence of chronic kidney disease and need for prolonged access to hemodialysis is propelling the demand for innovative devices for fistula formation and maintenance. Furthermore, the support of reimbursement, specialized vascular access centers, and the introduction of minimally invasive procedures will continue to strengthen the market.
Europe Arteriovenous Fistula Devices Market
In 2025, Europe is anticipated to hold 25.0% share due to growing awareness about long-term advantages of vascular access with increasing number of investments for chronic disease management. Hospitals and specialist centres throughout Germany France and the rest of Europe are now integrating state of the art AVF technology to raise the quality of deliverables en procedural outcomes and access durability are enhanced using these new methodologies. In addition, developed healthcare systems, clinical practice guidelines, and increasing availability of specialized dialysis therapy are anticipated to contribute to the steady growth of the market.
Asia Pacific Arteriovenous Fistula Devices Market
Asia Pacific is anticipated to exhibit the highest growth rate of 10.30% CAGR owing to the growing dialysis infrastructure and rising prevalence of chronic kidney disease in geriatric population. Increasing healthcare investments and government policies in China, India and Japan contribute to better access to renal care and specialized vascular access procedures. Moreover, increasing cognition on early fistula creation, rise in the number of trained professionals and usage of minimally invasive AVF procedures are predicted to boost regional market growth.
China Arteriovenous Fistula Devices Market Overview
China is growing rapidly with 46.0% share of APAC in 2025 due to rising CKD prevalence and expansion of dialysis networks across urban regions. Moreover, government policies promote advanced vascular access technologies. In addition, increasing investments in outpatient dialysis centers accelerate adoption of minimally invasive and monitoring devices.
Source: Polaris Market Research Analysis
Key Players & Competitive Analysis Report
The arteriovenous fistula devices market is moderately competitive, with companies expanding capabilities across creation, monitoring, and maintenance devices. Additionally, investments in minimally invasive technologies, advanced imaging systems and strategic partnerships with hospitals and dialysis centers enhance procedural outcomes, patient safety and global market presence.
Who are the key players in arteriovenous fistula devices market?
Key players in the market include B. Braun SE; Becton, Dickinson and Company; Fist Assist Devices, LLC; Fresenius Medical Care AG & Co. KGaA; Getinge AB; LeMaitre Vascular, Inc.; Medtronic plc; Merit Medical Systems, Inc.; Nipro Corporation; Teleflex Incorporated; Terumo Corporation; W. L. Gore & Associates, Inc.
Key Players
- B. Braun SE
- Becton, Dickinson and Company
- Fist Assist Devices, LLC
- Fresenius Medical Care AG & Co. KGaA
- Getinge AB
- LeMaitre Vascular, Inc.
- Medtronic plc
- Merit Medical Systems, Inc.
- Nipro Corporation
- Teleflex Incorporated
- Terumo Corporation
- W. L. Gore & Associates, Inc.
Industry Developments
- August 2025: Venova Medical received FDA IDE approval to start the VENOS-3 pivotal study of its Velocity pAVF system, evaluating safety and effectiveness for hemodialysis access in up to 126 patients across 20 U.S. sites.
- October 2025: Cagent Vascular expanded its Serranator PTA balloon catheter line with 70mm and 80mm sizes to improve arteriovenous fistula treatments using serration technology for safer and more effective lumen expansion.
- July 2025: Vexev and U.S. Renal Care completed enrollment in the CANSCAN trial, evaluating the VxWave ultrasound system for arteriovenous fistula mapping in 120 dialysis patients.
Market Segmentation
By Type Outlook (Revenue, USD Billion, 2021–2034)
- AVF Creation Devices
- Surgical Instruments
- Vascular Grafts
- Angioplasty Balloons
- Others
- AVF Monitoring Devices
- Doppler Ultrasound
- Pressure Monitoring Systems
- Others
- AVF Maintenance Devices
- Central Venous Catheters
- Stents
- Others
By End User Outlook (Revenue, USD Billion, 2021–2034)
- Hospitals
- Ambulatory Surgical Centers
- Dialysis Centers
By Regional Outlook (Revenue, USD Billion, 2021–2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 1.14 Billion |
| Market Size in 2026 | USD 1.23 Billion |
| Revenue Forecast by 2034 | USD 2.19 Billion |
| CAGR | 7.49% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Techniqueat |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Arteriovenous Fistula Devices Market FAQ's
The global market size was valued at USD 1.14 billion in 2025 and is projected to grow to USD 2.19 billion by 2034.
The global market is projected to register a CAGR of 7.49% during the forecast period.
North America led the market with 45.0% share in 2025 due to advanced dialysis infrastructure and strong government support for chronic kidney disease management programs.
A few of the key players in the market are Becton, Dickinson and Company, Terumo Corporation, Medtronic plc, Vasorum Ltd., Teleflex Incorporated, Fresenius Medical Care AG & Co. KGaA, LifeTech Scientific Corporation, Vasco Medical, Fritsch GmbH, Ultima Medical Services, Asahi Intecc Co Ltd, and CardioMedix.
AVF creation devices dominated with 50.0% share in 2025, due to high demand for surgical and minimally invasive fistula procedures with long-term patency and low complication rates.
Ambulatory surgical centers are expected to grow fastest at a CAGR of 9.76% due to increasing preference for outpatient dialysis procedures and minimally invasive AVF creation.
Download Sample Report of Arteriovenous Fistula Devices Market
Please fill out the form to request a customized copy of the research report.