
Automotive Hypervisor Market Size, Share, Trends and Forecast, 2026–2034
REPORT DETAILS
Automotive Hypervisors Market Summary
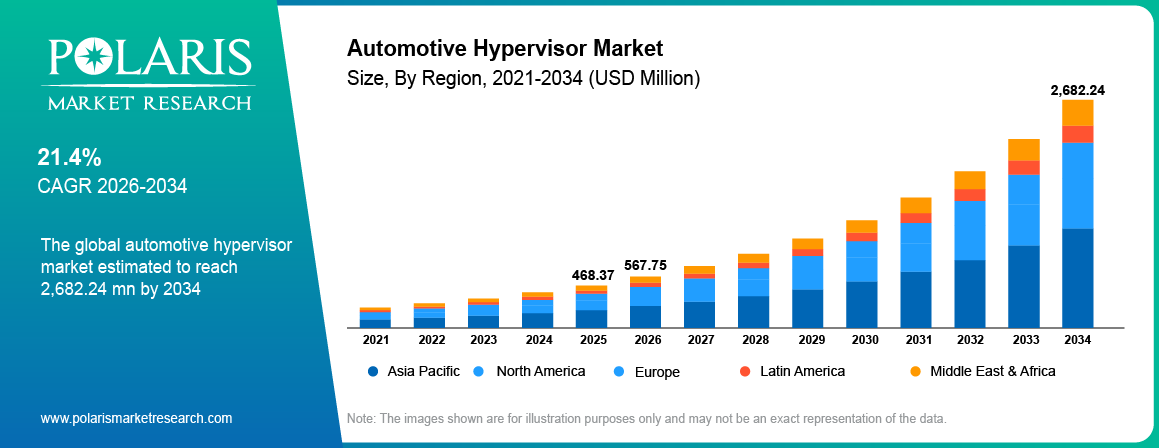
The global automotive hypervisor market size was valued at USD 468.37 million in 2025. The market is projected to grow at a CAGR of 21.4% from 2026 to 2034. The increasing integration of advanced infotainment systems and autonomous driving features is driving the automotive hypervisors market growth. The automotive hypervisors market is also benefiting from the incorporation of vehicle domain controllers, which require robust software virtualization solutions.
Market Statistics
Key Takeaways
- Asia Pacific led the global automotive hypervisor market with an 37.32% share in 2025. This is owing to increased demand for automobiles equipped with hypervisor-powered advanced features.
- North America is projected to account for an 22.8% CAGR during the automotive hypervisor market 2026 to 2034 forecast period. Increased focus on vehicle safety has led to automakers incorporating hypervisors for isolating critical functions.
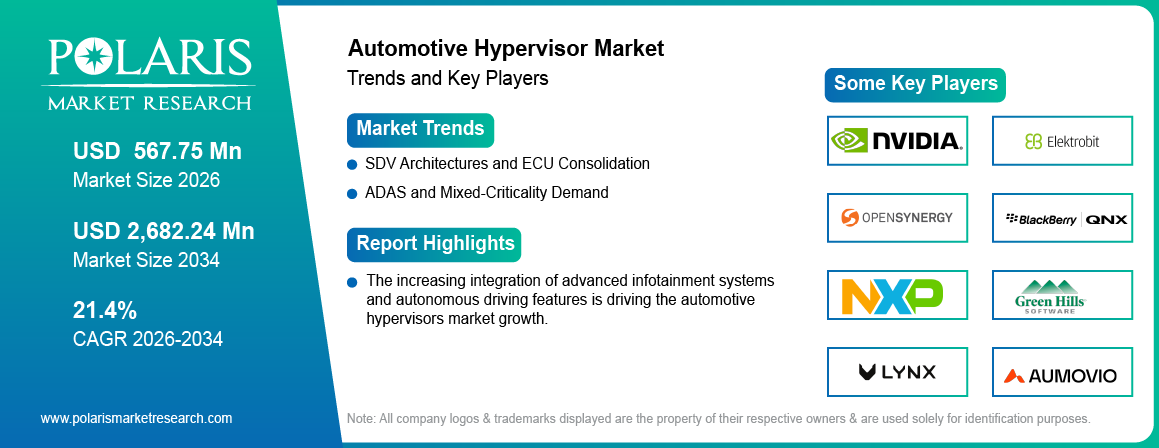
- By type, the Type 1 segment accounted for an 62.58% share in 2025. This is owing to the excellent performance and dependability of this hypervisor type.
- By vehicle type, the heavy commercial vehicles segment is projected to grow at an 23.1% CAGR through the automotive hypervisor market forecast 2034. The rising demand for heavy commercial vehicles shapes the segment’s growth.
- By mode of operation, the semi-autonomous segment led with an 63.21% share in 2025. The segment’s dominance reflects the high usage of Level 2 ADAS systems that need hypervisor-based isolation.
- By end user, the economic vehicles segment is projected to grow at an 22.6% CAGR. This is because digital displays and connectivity are becoming more common in low-cost vehicle models as well.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is an Automotive Hypervisor?
An automotive hypervisor refers to software that allows the coexistence of different operating systems on the same computer. Through this, different operating systems are isolated from one another in such a manner that they can run independently within the same hardware. For example, an automobile can have an operating system for the digital dashboard and another for the infotainment system.
Through the vehicle virtualization software, automobile manufacturers can reduce the number of ECUs on their automobiles. Furthermore, it supports automotive virtualization by allowing the sharing of computing power between different applications. Automotive hypervisors are designed for in-vehicle computing systems. They are distinct from hypervisors used in data centers to manage servers and cloud workloads.
How Does an Automotive Hypervisor Work?
The automotive hypervisor is responsible for managing the use of the shared hardware platform by vehicle software. It creates a separate virtual environment for each automotive function. The process involves several steps.
Electronic Control Unit (ECU): An in-vehicle computer or ECU provides the hardware that is required to run in-vehicle applications.
Hypervisor Layer: The hypervisor layer acts between the hardware and virtual machines. It controls access to the resources of the computer.
Virtual Machines: Different virtual machines are created by the hypervisor for performing various functions of the vehicle.
Operating System per VM: Each virtual machine runs its own operating system. Thus, different applications can work on the same hardware.
Resource Allocation: The processing power and memory are assigned to each virtual machine by the hypervisor according to its needs.
Isolation: Each virtual machine works in its own environment. This protects the rest of the applications from any faults in the particular application.
Parallel Real-time Execution: Several applications run at the same time. Thus, important functions can get their processing time while the infotainment and connectivity systems work with them.
Market Dynamics
Driver : SDV Architectures and ECU Consolidation
Automotive companies are gradually adopting a centralized computing architecture to simplify complex electronic systems. Current cars are designed using separate ECUs for each of the vehicle’s functions. The software-defined car (SDV) design is more advanced because it lets several functions share computing resources. This shift requires increased adoption of automotive hypervisors, which enables the separation of software applications that are used together. Other solutions include the domain controller and the zonal architecture, which help in grouping the vehicle functions and decreasing the number of separate ECUs. In January 2026, Volkswagen Group China started series production of its first vehicle using the China Electronic Architecture. This system represents a zonal approach to vehicle electronics, with high-performance central computing at its core (source: volkswagen-group.com). This step shows how automotive companies are trying to incorporate such architectures into their production process. As more functions run on the same hardware, the automotive hypervisor market grows.
Driver : ADAS and Mixed-Criticality Demand
Driver assistance systems need high-performance computing for processing the data gathered from sensors in order to ensure functions such as collision avoidance or lane keeping. These activities also involve timing and safety considerations. Infotainment and connectivity also need computing power but do not necessarily operate under the same safety conditions. The use of automotive hypervisors ensures that these applications can run on the same computing hardware but in separate software environments. In January 2026, ZF and Qualcomm announced a collaboration to develop a mixed-criticality solution for ADAS and in-car infotainment (source: qualcomm.com). This initiative highlights the necessity to control applications with varying levels of safety requirements from a single computing environment. With increased functionalities within ADAS, SDVs must handle such operations without risking the safety of the safety-related functions. The use of hypervisors is thus becoming increasingly important for ensuring proper isolation and allocation of computing resources.
Driver : Safety and Cybersecurity Regulation
Automobile makers must ensure that software failures do not propagate throughout the vehicle’s systems as more features share computing resources. This is especially important in cases where safety-related functions run on the same computing resources as the infotainment and connectivity software. Automotive hypervisors are useful in separating the workloads and managing access to hardware resources. Their need becomes crucial in achieving predictability of system behavior when vehicle functionalities share the same hardware resources. As such, there is a greater need for automotive hypervisors that ensure reliable software isolation to safeguard safety-related functions from failures in other programs.
Restraints and Challenges : Integration and Certification Costs
The integration of automotive hypervisors in vehicles can require substantial engineering work. Auto manufacturers have to ensure that the software is adapted to the virtualized environment and that the applications are compatible with the particular hardware platform. The older electronic control units may not support virtualization, which may lead to increased efforts in redesigning and increased timeframes. Certification is an additional step since each software environment has to be certified against its functionality. The tests become complicated if there are several operating systems running on one processor. There are restrictions for aftermarket usage. Old cars have a fixed electronic architecture that does not support virtualization, and it will be quite costly to change it, redevelop the software, and do all necessary tests. There are also additional challenges regarding warranty and further maintenance for the manufacturers when modifying the established platforms. This factor may prevent the adoption of the technology by companies with limited development resources.
Opportunities : Commercial Opportunities in Automotive Computing Platforms
For automobile hypervisor providers, there is an opportunity to expand further into the market by offering solutions for new vehicles' computing platforms. Automobile makers require software able to support diverse combinations of applications and hardware. Providers can meet demand by offering products suitable for luxury and mass-market automobiles. Software licensing and technical support services can serve as sources of additional revenue. Collaborations with semiconductor and software vendors can make it easier for hypervisor providers to get into the market. Vendors whose products are easier to integrate by the vehicle makers can benefit from such collaboration.
Opportunities : Specialized Virtualization for Electric and Autonomous Vehicles
The rise of electric and autonomous vehicles provides an opportunity for hypervisor providers to develop products according to specific computational requirements. Software is required in order to control the function of batteries and powertrains in electric cars. Computing systems for automation must be able to perform tasks of perception and decision-making. These systems have different performance requirements, creating the need to develop specialized virtualization products. Vendors may produce solutions for powertrains of electric cars or for automation purposes. This can provide them with the opportunity to meet the technical requirements of different types of vehicles.
Trend : Growth of Open-Source Virtualization Platforms
Automotive software designers are now considering the application of open source software techniques for developing flexible vehicle computing systems. The use of Linux-based systems and open source software virtualization techniques gives more control to software developers. However, extra effort is needed to address hardware requirements and safety. The suppliers of hypervisor systems are also considering offering a platform where several operating systems could be accommodated. This can allow developers to avoid reliance on one software platform and enable them to modify their applications easily during the development process. The availability of appropriate development tools for integration is likely to influence the level of adoption of these platforms.
Trend : Closer Integration of Hypervisors with Automotive Middleware
Hypervisors in the automotive industry are being made increasingly compatible with the middleware, which links the automotive applications with the hardware and operating system. The compatibility allows developers to handle communications between software modules without having to develop every interface individually. Additionally, it becomes easier to deploy applications to various computational environments. Compatibility of hypervisors with the middleware is important since automotive software may be supplied by several suppliers. Hence, hypervisor providers are focusing on interfaces compatible with automotive software frameworks.
Standards and Regulatory Landscape
Automotive hypervisors need to comply with safety and security standards because hypervisors control the software in a shared computing platform on automotive vehicles. ISO 26262 / ASIL defines functional safety for vehicles in road applications. The standard categorizes hazards through the Automotive Safety Integrity Level (ASIL) classification process to determine which safety measures need to be applied to certain features. When designing and validating the hypervisor, the safety considerations of each application used in a virtual machine have to be considered.
The ISO/SAE 21434 addresses cybersecurity engineering throughout the lifecycle of an automotive vehicle. This standard gives manufacturers information on how to identify cybersecurity threats and how to establish appropriate cybersecurity measures to address them. UN R155 requires automotive manufacturers to develop cybersecurity management systems for relevant approvals in vehicle manufacturing. These regulations influence how manufacturers consider software platforms and software suppliers. Hypervisor companies must provide technical specifications and evidence of system behavior to assist automotive manufacturers in evaluating the software platform. However, the hypervisor alone cannot ensure compliance. Manufacturers must evaluate the entire system. This includes the hardware, software, interfaces, and implementation as well.
Automotive Hypervisor vs Traditional ECU Architecture
The traditional design of ECUs uses control units for individual vehicle functions. In a hypervisor-based approach, several operating systems operate on common hardware. This enhances efficiency in the utilization of resources but also increases integration complexity.
| Factor | Traditional distributed ECUs | Hypervisor-based consolidated platform |
| Architecture | One function per ECU | Several operating systems on one ECU or domain controller |
| Hardware count and weight | High | Reduced through ECU consolidation |
| Compute utilization | Low per unit | Higher through shared CPU and memory |
| Software updates | Per-ECU, often tied to hardware | Flexible; update non-critical partitions without touching safety-critical ones |
| Fault and cyber isolation | Physical separation between units | Enforced by virtual-machine boundaries |
| Integration and validation effort | Lower per function | Higher: guest OS porting, certification evidence, inter-VM communication |
| Best fit | Simple, low-volume or legacy functions | Centralized SDV, ADAS and cockpit platforms |
Source: Polaris Market Research Analysis
Technology Landscape
Vehicle computing requirements and software development techniques shape the automotive hypervisor technology. Key categories include mixed-criticality processing, evolving electronic architecture, and the software platform that developers use for building in-vehicle applications.
Mixed-Criticality Systems and RTOS
Each vehicle application has different timing and safety requirements. A real-time operating system (RTOS) caters for the needs of applications that have to react within the set timelines. Hypervisor technology lets an RTOS run alongside other general-purpose operating systems on the same hardware. This configuration enables engineers to handle varying workloads without assigning the same system environment to all the applications. The choice between a hypervisor and a hypervisor-less architecture depends on the hardware capabilities and software requirements.
Domain Controllers and Zonal Architecture
A domain controller brings similar vehicle systems under one system. Zonal architecture groups the electronic systems according to their geographical positions in the vehicle. Both can simplify the wiring system and enable ECU consolidation. The two architectures also change the software deployment across the vehicle hardware. In a software-defined vehicle (SDV), they can make it easier to introduce or revise features through software. The hypervisor may also be used to run different software systems in the same controller.
Software Ecosystem: QNX, Linux, Android Automotive, Middleware
Automotive hypervisors must be compatible with the software operating systems and the middleware used by the automotive manufacturers. For instance, QNX is used for automotive systems that are meant to provide safety, while Linux is useful in automotive computing systems. Android Automotive provides a framework for automotive entertainment services. AUTOSAR standards provide software design and communication in automotive electronics systems. Hypervisor compatibility with these technologies impacts integration processes and software portability. Automakers assess these options based on application needs and system architecture.
Real-World Applications and Use Cases
Automotive hypervisors support different software environments on shared automotive platforms. Applications include cockpit systems and vehicle central computers. The examples listed below include products and platforms related to these applications.
| Use Case | Application | Example |
| Digital Cockpit | Virtualization allows cockpit functions to operate in separate software environments on shared computing hardware. | Qualcomm's Snapdragon Cockpit Platform supports hypervisor-based processing for these applications. |
| Instrument Cluster | A hypervisor can separate safety-critical instrument displays from infotainment software. | BlackBerry QNX offers QNX Hypervisor for Safety, which supports the separation of applications with different safety requirements on shared hardware. |
| Infotainment | Android Automotive OS can run as a guest virtual machine alongside other automotive operating systems. This allows infotainment software to operate within a virtualized vehicle computing platform. | Qualcomm's Snapdragon platform supports Android and other operating systems through virtualization. The specific hypervisor depends on the platform configuration. |
| ADAS | Hypervisor-based platforms can separate operating systems and applications on automotive computing hardware. | NVIDIA DRIVE OS uses a hypervisor to manage partitions and their access to computing resources. |
| Camera and other sensor data must be processed for driver assistance functions. | Qualcomm's Snapdragon Ride platform supports sensor-processing software and virtualization technologies, including the BlackBerry QNX Hypervisor for Safety, for mixed-criticality automotive systems. | |
| Central Vehicle Computing | A hypervisor can run multiple operating systems on one processor, supporting the consolidation of applications previously hosted on separate electronic control units. | Elektrobit EB corbos Hypervisor |
Source: Polaris Market Research Analysis
Report Segmentation
The automotive hypervisor market is primarily segmented based on type, vehicle type, bus system, mode of operation, sales channel, end user, and region.
| Segmentation Axis | Segments |
| By Type | Type 1 · Type 2 |
| By Vehicle Type | Passenger Cars · Light Commercial Vehicles (LCVs) · Heavy Commercial Vehicles (HCVs) |
| By Bus System | Controller Area Network (CAN) · Local Interconnect Network (LIN) · Ethernet · FlexRay |
| By Mode of Operation | Semi-autonomous Vehicles · Autonomous Vehicles |
| By Sales Channel | Original Equipment Manufacturer (OEM) · Aftermarket |
| By End User | Economic Vehicles · Mid-priced Vehicles · Luxury Vehicles |
| By Region | North America (U.S., Canada) · Europe (France, Germany, UK, Italy, Netherlands, Spain, Russia) · Asia Pacific (Japan, China, India, Malaysia, Indonesia, South Korea) · Latin America (Brazil, Mexico, Argentina) · Middle East & Africa (Saudi Arabia, UAE, Israel, South Africa) |
Source: Polaris Market Research Analysis
By Type
The Type 1 segment accounted for the largest automotive hypervisor market share of 62.58% in 2025. Its dominant position is due to the compatibility of Type 1 hypervisors in vehicle systems requiring reliable operation and isolation between different software applications. Its ability to run on hardware makes it possible for Type 1 hypervisors to control computing resources without depending on any operating system in the host computer. This is especially important when considering the safety requirements in automotive computers. This segment also benefits from the use of Type 1 hypervisors in high-performance vehicle computers, where predictable behavior of the system is essential. This feature makes Type 1 hypervisors a suitable choice for car manufacturers developing advanced in-car computing systems.
The Type 2 segment is projected to witness the fastest growth with a 22.9% CAGR. The demand for these hypervisors is driven by their usage in automotive software development and testing environments. They operate on an existing operating system, making it easier for developers to use them when working with various automotive applications. In addition, these hypervisors allow engineers to analyze application behavior without making significant hardware changes. Type 2 hypervisors can also be used by development teams for the testing of software configurations prior to integration into vehicle systems. Due to their versatility, these hypervisors are relevant for automotive suppliers and software developers working on new in-vehicle applications.
Type 1 vs Type 2 Hypervisor Automotive Comparison
| Factor | Type 1 (Bare-metal Hypervisor) | Type 2 (Hosted Hypervisor) |
| Runs on | Directly on the vehicle hardware | On top of a host operating system |
| Typical automotive role | Safety-critical and real-time workloads (ADAS, cluster, control functions). Can also support infotainment and virtual cockpit applications. | Infotainment, development, simulation, virtual cockpit, software-in-the-loop testing. These applications may also run on Type 1 hypervisors, depending on the architecture. |
| Determinism and latency | Direct control of scheduling and interrupts; predictable timing | Host-OS layer adds overhead; less suited to hard real-time |
| Safety certification fit | Preferred where ASIL-rated isolation evidence is needed | Generally used for non-safety or pre-production work |
| Certification Effort | Higher, as safety critical functions need certification such as ISO 26262 | Lower, as it is used mainly outside safety critical functions |
| Typical Use | Safety critical and real time functions such as ADAS and instrument clusters | Development, testing and non safety critical workloads |
Source: Polaris Market Research Analysis
By Vehicle Type
The passenger cars segment led with a 58.31% automotive hypervisor market share in 2025. The electronic systems used in the passenger car segment include driver information, entertainment, connectivity, and vehicle control solutions. This has necessitated the development of computing platforms that enable multiple applications within a single vehicle. Vehicle manufacturers are also introducing additional advanced functionalities into mid-range and luxury passenger cars. Virtualization technology provides an enabling platform to run these software applications on shared computing infrastructure. High production volumes in passenger cars have also helped the segment maintain market dominance because virtualization technology can be adopted into vehicles easily.
The heavy commercial vehicles (HCVs) segment is projected to grow at a 23.1% CAGR. Heavy-duty trucks and other commercial vehicles are incorporating more electronic systems into their designs to enhance vehicle management and control capabilities. Such vehicles use software in areas like vehicle communications, power trains, and driver assist technologies. Managing these software applications is likely to increase the burden on computing systems. The demand is also positively influenced by the increasing application of digital technology in long-haul trucks and commercial vehicles. Such applications need computing systems that can run for longer periods.
By Bus System
The Ethernet segment accounted for a 34.6% automotive hypervisor market share in 2025. Automotive Ethernet provides fast data communication among the various electronic systems in a vehicle. It is becoming increasingly significant in light of the increased amount of data generated by cameras, sensors, and connectivity functions in vehicles. Ethernet could be used for communication between central computing modules and other vehicle modules. This makes automotive Ethernet relevant in cases where multiple sources generate data and where there is a need to use the higher bandwidth required for certain applications. These capabilities support the use of Ethernet in vehicle platforms where complex software functionalities and heavy data communication are involved.
The controller area network (CAN) segment is projected to grow at a 20.8% CAGR. The CAN technology is still widely used for communication between control units in cars. The information transmitted includes braking, powertrain management, and body electronics. CAN's prevalence in the automotive market supports its use even as automakers implement new computer systems. In hypervisor architectures, CAN interfaces may link virtualized applications to the car's existing network. This way, manufacturers can use the same communication protocol while making changes to their electronic architecture. The demand for CAN products will depend on how new computing platforms integrate with existing ones.
By Mode of Operation
The semi-autonomous segment led with a 63.21% automotive hypervisor market share in 2025. These automobiles have driver assistance capabilities including adaptive cruise control, lane keeping, and automatic parking. These capabilities require systems to be electronic in nature and to process information within certain deadlines. Automakers are increasingly incorporating such capabilities into more models, which leads to increased software needs for in-car systems. Automotive hypervisors can help separate driver assistance applications from the infotainment and other applications in the vehicle on a common hardware infrastructure. This partitioning helps isolate applications with diverse operating conditions. Semi-autonomous capabilities being incorporated in modern cars also support the need for such hypervisors.
The autonomous segment is projected to account for the highest CAGR of 24.3%. Advancements in self-driving technology are driving demand for computers that can perform complex autonomous driving functions. Self-driving cars rely on software to process sensory information, evaluate the conditions on the road, and drive without requiring any human assistance. All of this needs to be properly coordinated through software modules. Hypervisors in automotive platforms can create independent spaces for individual workloads on a common hardware system to help developers deal with applications with varying demands. Development of increasingly autonomous driving technology could mean an increased demand for virtualization solutions for such platforms. Validating autonomous driving technology itself creates an application space for hypervisors in development platforms.
By Sales Channel
The original equipment manufacturer (OEM) segment accounted for the largest automotive hypervisor market share of 77.21% in 2025. Hypervisors for automotive vehicles are usually embedded into the development process of the vehicle itself, enabling the manufacturers to select software and hardware that meet the requirements of their respective vehicles. Manufacturers have the opportunity to directly contact hypervisor vendors to check for compatibility of the software with the onboard processor and operating system before manufacturing begins. This approach lets manufacturers address integration needs during design rather than after vehicles are operational. Additionally, this shift is supported by new vehicle models with improved electronics architecture.
The aftermarket segment is projected to grow at a 21.8% CAGR. Growth opportunities may arise from efforts to improve electronic systems as both the car owners and the service providers search for solutions to improve their systems. The implementation of hypervisor technology in cars already on the road could be challenging since there will be differences in both hardware configuration and software requirements between different car models. Aftermarket manufacturers could target those car models for which computing upgrades are technologically feasible. Fleet owners could also provide growth prospects as they seek to upgrade computing power in their vehicles to perform more tasks.
By End User
The luxury vehicles segment held an 18.3% automotive hypervisor market share in 2025. The luxury vehicles feature advanced digital cockpits, connectivity, infotainment systems, and driver assist systems. These functions place greater demands on the computing platform inside the car. Hypervisors enable carmakers to use independent software on a common hardware infrastructure. This may help them avoid using separate control units while keeping applications independent of one another. Luxury carmakers generally bring their devices to market earlier than regular makers. The complexity of these devices is a key driver for automotive hypervisor products.
The economic vehicles segment is projected to grow at a 22.6% CAGR. Digital displays and connectivity are becoming more common in low-cost car models as well. This requires efficient utilization of computational resources available in the vehicle. Automotive hypervisors enable the simultaneous operation of applications on shared hardware, thus eliminating the need for dedicated control units. Price is still a factor to consider in this market segment. Products that offer easy system integration and can be used with cost-effective computing platforms could attract manufacturers who are seeking to integrate digital capabilities into their vehicles without significantly raising the price of the cars.
Regional Insights
The automotive hypervisor market varies across regions owing to automobile manufacturing, software development, and the use of advanced vehicle electronics. The regional demand is also influenced by the level of investment in automotive technology and vehicle electrification.
Automotive Hypervisor Market Asia Pacific
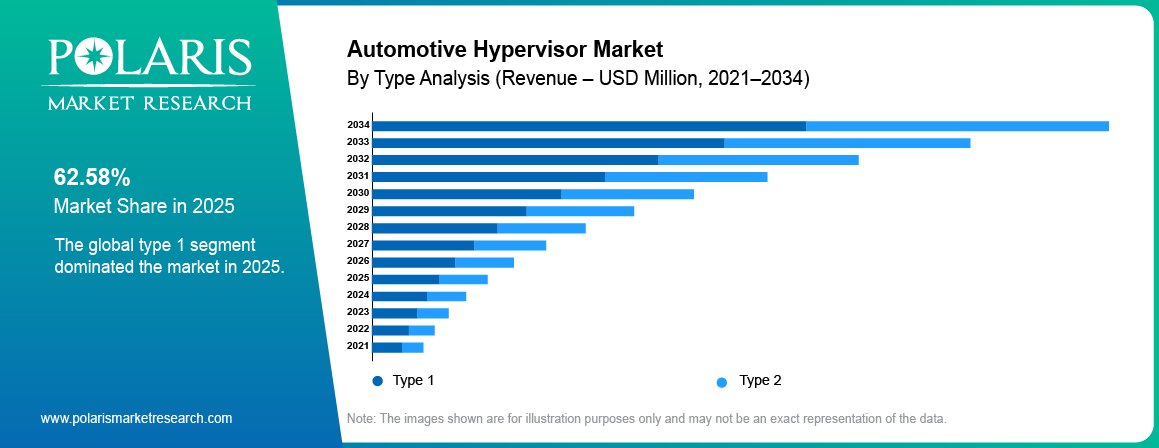
Asia Pacific accounted for the largest automotive hypervisor market share of 37.32% in 2025. There exists a significant market for automotive hypervisors in Asia Pacific owing to the presence of an established automotive manufacturing industry in the region. China, Japan, and South Korea have developed their vehicle manufacturing ecosystems and automotive electronic suppliers. Additionally, there is the development of software-defined vehicles that require flexible vehicle computing architectures. Automakers need to control software in various vehicle functions due to the increasing complexity of the electronics. In February 2026, Panasonic Automotive Systems announced industry-wide support for its VirtIO-based in-vehicle software platform, endorsed by Japanese automakers like Toyota, Honda, Nissan, Mazda, and Mitsubishi Motors (source: panasonic.com). This project highlights the efforts made towards making software more compatible with the virtualized hardware of vehicles. Such cooperation may facilitate the development of software that is compatible with different automotive computing environments. The development of new electronic platforms in China’s electric vehicles industry can also present another relevant market for virtualization technologies. Market opportunities also come from the automotive technology and semiconductor industries in Japan and South Korea.
Automotive Hypervisor Market North America
North America is projected to witness the fastest growth at a 22.8% CAGR during the forecast period. North America continues to be a crucial market for automotive hypervisors because of its automotive software industry and investments made in advanced vehicle technologies. The U.S. contributes significantly, driven by the development of platforms for connected and automated cars. Canada also has an established automotive engineering industry. In January 2026, HARMAN unveiled the latest version of its software-defined vehicle toolchain, including Ready CQuence Run, which is a Type 1 automotive hypervisor and is aimed at isolating software workloads with varying safety levels (source: harman.com). This is in line with the efforts towards meeting software demands of the new vehicle platforms. The regional focus on autonomous driving and digital vehicles offers a strong opportunity for suppliers of hypervisors. Developers of automotive software also require testing applications before installing them in production cars. Therefore, demand for virtualization technologies is growing.
Automotive Hypervisor Market Europe
Europe accounted for a 28.6% automotive hypervisor market share in 2025. Europe has an established automotive hypervisor market. It includes automotive manufacturers and the vehicle engineering sector in the region. Some countries where automotive hypervisors will be used include Germany, France, and the United Kingdom, since carmakers there invest in vehicle software and computing systems. In October 2026, the European Commission announced that the European Connected and Autonomous Vehicle Alliance (ECAVA) would present roadmaps for software-defined vehicles, automotive hardware, and autonomous driving in Paris. The initiative aims to improve cooperation across Europe's automotive industry and help move new technologies toward commercial use (source: europa.eu). Such measures provide automotive hypervisor vendors with opportunities since the vehicles in Europe are becoming software-based.
Latin America
The Latin America automotive hypervisor market is projected to grow at a 19.8% CAGR. The Latin America region provides scope for market growth owing to Brazil and Mexico being important hubs for automotive manufacturing in the region. International automakers operate manufacturing units in both these nations. There are opportunities to introduce vehicle-related innovations here. Also, the growing market for electric vehicles in the region is providing new opportunities for the development of automotive software. As the manufacturers are incorporating digital technologies in the design of their vehicles, there will be increased demand for computing platforms that can support multiple software applications. Automotive suppliers and local manufacturers could collaborate to provide virtualization solutions for their vehicle programs in the region.
Middle East & Africa
The Middle East & Africa automotive hypervisor market is projected to account for a 20.4% CAGR. Demand is driven by investment in automotive technology and deployment of connected car features. Countries like Saudi Arabia and the UAE have been making investments in smart mobility and digital transport solutions. This has created opportunities for innovative in-vehicle computing solutions. In addition to this, South Africa is contributing through its automotive manufacturing industry. With the introduction of digital features by automobile manufacturers, the demand for hypervisor technology will increase. Adoption rates in various countries will depend on vehicle manufacturing and investment in automotive technology.
Key Market Players and Competitive Landscape
The automotive hypervisor market includes software developers, semiconductor suppliers, and automotive parts & components providers. Hypervisor vendors compete based on their software quality, hardware compatibility, and OS compatibility. Safety concerns also affect purchases, especially for those platforms that are capable of performing critical vehicle functions along with infotainment applications.
The automotive hypervisor key players are developing solutions for mixed-criticality systems and centralizing vehicle computing. Some specialize in creating hypervisor software, whereas others provide a combination of virtualization and processors along with automotive platform integration. Partnerships with automakers and semiconductor suppliers can assist in lowering the integration efforts and enhancing compatibility with vehicle hardware.
Competition among automotive hypervisor vendors is also affected by their capabilities to support new vehicle architectures. The product flexibility, technical support, and validation may affect the choice of a particular supplier. As automotive suppliers try to create more software-driven cars, they strive to increase virtualization integration possibilities.
Vendor Positioning
| Vendor | Layer / Role | Relevant Offering | Positioning |
| Safety-certified OS and hypervisor | QNX Hypervisor 8.0; QNX Hypervisor for Safety 8.0 | Direct supplier | |
| AUMOVIO SE | Automotive software virtualization and development | vSDV Composer; Virtual ECU Creator | Adjacent platform |
| Elektrobit (Robert Bosch GmbH) | Automotive hypervisor and embedded software | EB corbos Hypervisor; VirtIO framework | Direct supplier |
| Green Hills Software LLC | Safety-critical OS and virtualization | INTEGRITY Multivisor; µ-visor | Direct supplier |
| Lynx Software Technologies | Secure virtualization and separation kernel | LynxSecure; LYNX MOSA.ic | Direct supplier |
| NVIDIA Corporation | Automotive computing and virtualization | NVIDIA DRIVE OS; DRIVE OS hypervisor | Integrated platform |
| NXP Semiconductors N.V. | Automotive processors and hardware virtualization | S32N5 Vehicle Super-Integration Processor; S32 CoreRide | Hardware platform |
| OpenSynergy GmbH (Panasonic Holdings Corporation) | Automotive hypervisor software | COQOS Hypervisor SDK | Direct supplier |
| Panasonic Automotive Systems Co., Ltd. (Panasonic Holdings Corporation) | In-vehicle software virtualization | VirtIO-based in-vehicle software platform; vSkipGen | Adjacent platform |
| Renesas Electronics Corporation | Automotive semiconductors and virtualization | Zone-ECU Virtualization Solution Platform; Renesas RH850/U2x MCUs with ETAS RTA-HVR | Hardware and partner solution |
| SYSGO GmbH | Safety-critical OS and hypervisor | PikeOS; Secure Automotive Connectivity Platform | Direct supplier |
| Visteon Corporation | Digital cockpit and domain computing | SmartCore cockpit domain controller; multi-OS virtualization | Integrated platform |
| Wind River Systems, Inc. | Automotive virtualization and embedded software | Helix Virtualization Platform | Direct supplier |
Source: Polaris Market Research Analysis
Recent Industry Developments
- September 2026: QNX announced that Coretura, a joint venture between Daimler Truck and Volvo Group, selected their Alloy Kore software platform for its next-generation commercial vehicle architecture. The platform combines QNX's safety-certified operating system with Vector's middleware and software integration capabilities. (source: qnx.software)
- September 2026: QNX and AutoCore announced an expanded collaboration to develop a full-stack software-defined vehicle platform for China's automotive market. The platform combines QNX's hypervisor and safety operating system with AutoCore's software and middleware technologies. It targets domain controllers, high-performance computing platforms, and zonal controllers. (source: autocore.ai)
- August 2026: The Xen Project announced the formation of its Xen Safety Committee to develop and maintain engineering resources for functional safety activities. The initiative covers safety-critical applications in automotive and other industries. It could support wider use of Xen-based virtualization in systems that require functional safety assurance. (source: linuxfoundation.org)
- August 2026: OSYX Technologies joined the Renesas Partner Program, bringing support for the Bao Hypervisor to Renesas RH850 automotive microcontrollers. The collaboration enables developers to explore hardware-enforced isolation and workload consolidation on automotive hardware. (source: osyx.tech)
Future Outlook
The adoption of automotive hypervisors will depend on how automakers design their next-generation vehicle system architecture. Premium vehicles are likely to use this technology earlier since they use more sophisticated computing systems. In addition, commercial vehicle producers might consider the virtualization technology as they upgrade their onboard electronics. But integrating existing software onto a shared platform will require additional time and expense in the vehicle development process. The ability of the hypervisor providers to support various processors and operating systems will play an important role in the adoption process.
Research Methodology
Market Overview: The automotive hypervisors market was assessed using 2025 as the base year, with historical data covering 2021–2024 and forecasts extending to 2034. Market estimates are presented in USD million. The methodology combines top-down and bottom-up approaches.
Data Mining: Data from vendor disclosures, automaker statements, Tier-1 supplier statements, standards bodies, and the automotive industry literature were analyzed. The screening methodology enabled the identification of players, hypervisor technologies, and automotive initiatives disclosed publicly.
Primary Research: Primary research involved interviews with automotive software specialists, Tier-1 suppliers, hypervisor and real-time operating system (RTOS) vendors, and semiconductor platform teams. A total of 20 interviews were conducted to gather industry insights and validate market assumptions.
Secondary Research: Secondary sources included company annual reports, investor presentations, regulatory documents, vehicle production statistics, and industry association publications. Secondary research draws on relevant sources such as paid databases, company annual reports and filings, industry association publications and regulatory documents.
Market Sizing and Forecasting: Market estimates were based on revenue attributable to automotive hypervisor software licenses and related services, in line with the report's scope. Revenue was allocated across market segments and regions. Forecast assumptions considered software-defined vehicle adoption, the pace of electronic control unit (ECU) consolidation, and relevant regulatory timelines.
Data Validation: Market estimates were cross-checked using top-down and bottom-up calculations. Industry inputs and secondary research findings were reviewed to identify inconsistencies and refine assumptions. The analysis was last updated on October 2026.
Automotive Hypervisor Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 468.37 million |
| Market Size Value in 2026 | USD 567.75 million |
| Market Size in 2034 | USD 2,682.24 million |
| CAGR | 21.4% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD million and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Automotive Hypervisor Market FAQ's
An automotive hypervisor is software that runs multiple operating systems on one vehicle computer. It keeps them separate so that applications such as the digital dashboard and infotainment system can use the same hardware.
The automotive hypervisor market size was valued at USD 468.37 million in 2025. The market is projected to grow to USD 2,682.24 million by 2034.
The automotive hypervisor market is projected to grow at an 21.4% CAGR during the automotive hypervisor market forecast 2034.
The hypervisor manages how a vehicle computer shares its processor and memory. It creates separate environments for different operating systems. Each environment can run its assigned applications without directly interfering with the others.
Type 1 hypervisor runs on hardware. Type 2 hypervisors run on an existing operating system. Type 1 hypervisors are commonly applied in automotive embedded systems. Type 2 may be utilized for software development and testing.
Car manufacturers use hypervisors to allow running multiple applications on shared hardware components. It helps to reduce the number of ECUs needed in vehicles. In addition, it becomes possible to have different software running in different environments.
Hypervisors can provide a separation between driver assistance software and other software applications installed in vehicles. This becomes important when systems work with data from cameras and other sensors. Hypervisors should be designed and validated according to the safety-related requirements.
Asia Pacific accounted for the largest market share of 37.32% in 2025. North America is projected to grow at an 22.8% CAGR from 2026 to 2034.
A few of the key automotive hypervisor companies include BlackBerry Limited (QNX); AUMOVIO SE; Elektrobit (Robert Bosch GmbH); Green Hills Software LLC; Lynx Software Technologies; NVIDIA Corporation; NXP Semiconductors N.V.; OpenSynergy GmbH (Panasonic Holdings); Panasonic Automotive Systems Co., Ltd. (Panasonic Holdings Corporation); Renesas Electronics Corporation; Sasken Technologies Ltd.; Siemens EDA (Siemens AG); SYSGO GmbH; Visteon Corporation; Virtual Open Systems; Wind River Systems, Inc.
Automakers may use hypervisors to run multiple operating systems on one vehicle computer. Some may choose a hypervisor-less architecture instead. The choice will depend on the vehicle's computing needs, safety requirements, and the cost of integrating the software.

Download Sample Report of Automotive Hypervisor Market
Please fill out the form to request a customized copy of the research report.


