Defense Cybersecurity Market Trends, Business Growth, 2026-2034
REPORT DETAILS
Defense Cybersecurity Market Summary
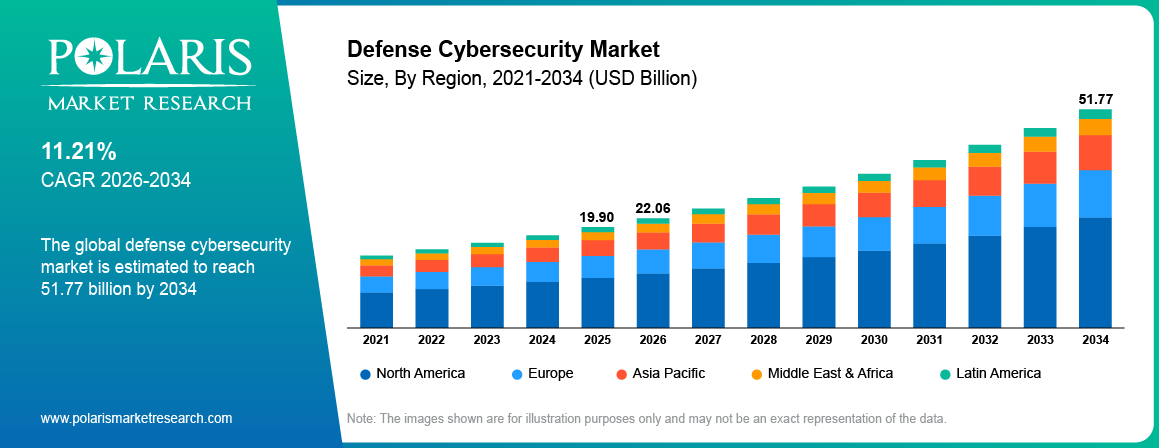
The global defense cybersecurity market was valued at around USD 19.90 billion in 2025 and is projected to reach USD 51.77 billion by 2034, registering a CAGR of 11.21% during the forecast period. The growing cybersecurity needs within the defense industry are fueling further demand for compliance, continuous monitoring, and managed cybersecurity solutions. Programs like CMMC (Cybersecurity Maturity Model Certification) compliance and multinational defense programs are driving investments in inter-operation capabilities, secure data exchange, and cyber defense systems. These developments continue to support long-term growth in the defense cybersecurity market.
Market Statistics
Defense Cybersecurity Market Key Takeaways 2025
- North America dominated the market with 38.1% share in 2025, due to higher defense spending and ongoing zero-trust architecture implementation.
- Solutions accounted for the largest market share of 68.2% in 2025 owing to increasing deployment of network, endpoint, and identity security platforms.
- Services are projected to register the fastest growth witnessing a CAGR of 12.73% from 2026-2034, due to rising demand for integration, consulting, and managed security.
- The identity and access management segment is projected to register the fastest growth witnessing 11.49% CAGR during the forecast period.
- The armed forces segment dominated the market with 58.0% of market share in 2025
- The defense contractors segment is projected to witness the fastest growth witnessing 11.65% CAGR during the forecast period.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Is Defense Cybersecurity? Solutions, Services, Mission Systems & Security Capabilities
Defense cybersecurity is composed of software, hardware, and services for the protection of military networks, command and control systems, intelligence, tactical communications, and supply chain against cyberattacks. While cybersecurity is meant to protect business and other organizations, defense cybersecurity aims to ensure operational assurance, continuity, and protection of classified information. The procurement of defense cybersecurity depends on military needs, regulatory compliance, and emerging cyber threats.
The market encompasses endpoint protection, network security, application security, identity and access management, data protection, cloud security, managed detection and response, and cyber engineering services. Investments have been made in zero trust architecture, cyber resilience, secure cloud platforms, and advanced threat intelligence to enhance the defense infrastructure. In March 2026, Dataminr introduced Dataminr for Cyber Defense, which combines artificial intelligence-based threat intelligence with threat and exposure management to reinforce the proactive cyber defense strategy(Source: www.dataminr.com).
Defense Cybersecurity Market Drivers, Restraints and Opportunities
| Market Driver | Est. CAGR Impact | Geographic Relevance | Impact Timeline |
| Zero trust architecture implementation | +2.4% | US and allied countries | Short to medium term |
| CMMC compliance across the defense industrial base | +1.2% | North America | Short to medium term |
| Secure cloud modernization | +1.8% | Global | Medium term |
| Coalition interoperability initiatives | +1.5% | Europe, North America, Asia Pacific | Medium term |
| Rising state-sponsored cyber threats | +1.3% | Global | Long-term |
| Growing investment in threat intelligence | +1.1% | Global | Long-term |
Source: Polaris Market Research Analysis. CAGR reflect Polaris proprietary sizing methodology.
Defense Cybersecurity Market Drivers Impact Analysis
Growth drivers include increasing cyber-attacks, growing digitalization in military institutions, and modernization of defense communication and information systems.
The defense industry has moved away from independent cybersecurity solutions towards an integrated cybersecurity solution that integrates identity and access management, network security, endpoint security, secure cloud, and threat intelligence. The shift has brought about numerous opportunities for software companies, defense integrators, and managed cybersecurity services.
Investments in cybersecurity are also rising among the defense industrial base, as contractors work on improving their cyber resiliency capabilities and achieving compliance with CMMC requirements in order to retain their defense contracts. The adoption of zero trust architecture and tactical network modernization are expected to ensure consistent growth in the forecast period.
Source: Polaris Market Research Analysis
How is zero trust architecture transforming the defense cybersecurity market?
Zero trust architecture is changing the way defense organizations are securing their military networks, applications, and data. As part of efforts aimed at improving cyber defense, NSA rolled out the Zero Trust Implementation Guidelines in May 2026 to improve defense cybersecurity by providing actionable guidelines on securing national security and DoD systems(Source: www.nsa.gov). Perimeter security models are giving way to continuous authentication, least privilege, and verification to minimize cyber risks on tactical networks and enterprise systems. Investments are being made in areas of identity and access management, micro segmentation, and continuous monitoring in order to build cyber resilience.
Zero trust architecture is expected to create the need for system integration, security assessments, and cybersecurity-managed services. The defense organizations have the need for solutions that work in legacy systems, secure cloud-based platforms, and even classified networks without impacting operational readiness. It is anticipated that vendors with security platform solutions will benefit from such modernization initiatives.
How is CMMC compliance supporting market growth?
The implementation of CMMC is driving up the cybersecurity standards of the defense industrial base through the requirement of contractors to incorporate certain controls before getting into any defense program. In July 2026, the Department of War has decided to suspend CMMC Phase II requirements with an objective to develop scalable and resilient cybersecurity as well as faster defense procurement while maintaining the self-assessment requirements of Phase I(Source: dodcio.defense.gov). The organizations have been putting in efforts to build governance systems, endpoint security, threat intelligence, and continuous monitoring for the protection of controlled unclassified information.
The increasing numbers of suppliers getting cybersecurity evaluated create opportunities for consulting companies, managed security providers, and compliance solutions vendors. The need for the latter services is likely to grow as contractors keep upgrading their cybersecurity infrastructure to remain eligible for participation in defense procurement programs.
What restrains the defense cybersecurity market?
Complex procurement and legacy infrastructure
Longer procurement time frames and legacy military infrastructure continue to act as major roadblocks to growth in the market. Defense platforms have to undergo testing and certification before the implementation of new cybersecurity solutions. This adds to the implementation time frame and cost associated with the projects, which slows down the deployment of modern cybersecurity solutions among defense companies.
What opportunities exist in the defense cybersecurity market?
Growing demand for coalition interoperability
Collaborations among allied defense organizations are providing new avenues for cybersecurity companies. The NVIDIA Open Secure AI Alliance was founded by industry leaders in July 2026 to create open solutions that would enhance the cybersecurity of AI-based defenses, remediate vulnerabilities, and support the development of secure AI systems (Source: nvidia.com). Military activities entail secure information sharing across multiple nations while fulfilling national security requirements. This is leading to a need for identity and access management solutions, secure cloud computing solutions, cross-domain security solutions, and solutions for enhancing coalition interoperability.
Source: Polaris Market Research Analysis
Defense Cybersecurity Market Segmentation Analysis
The report provides a comprehensive analysis of the defense cybersecurity market by component, security type, end user, and region to identify the leading revenue-generating segments and emerging growth opportunities.
Defense cybersecurity market by component
Which component dominated the defense cybersecurity market?
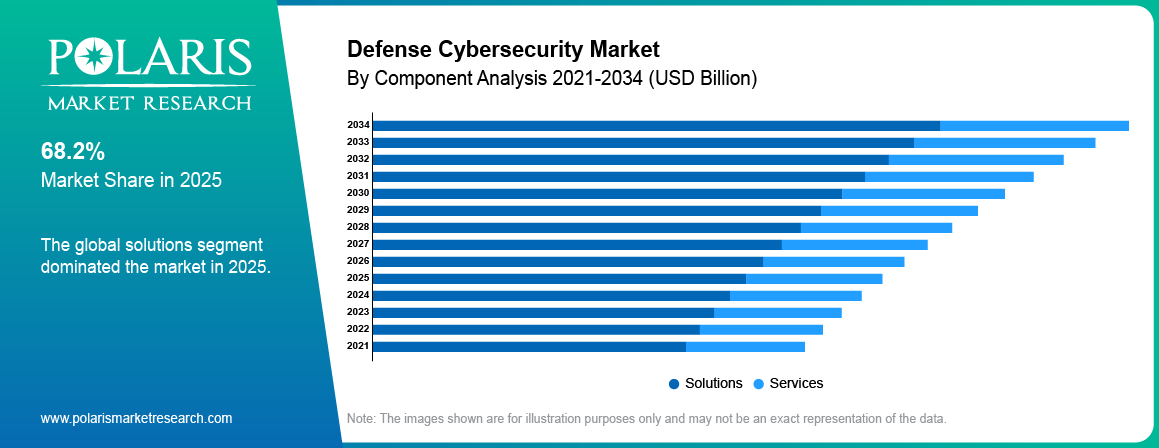
The solutions segment dominated the market with 68.2% share in 2025 due to increasing deployment of network security, endpoint protection, identity and access management, encryption, and security analytics across defense organizations. The governments are investing in integrated cybersecurity platforms that deliver centralized visibility and automated threat detections with enhanced protection of mission-critical infrastructure. The increased usage of the zero trust approach is also fueling the demand for advanced cybersecurity systems.
Which component is projected to grow at the fastest CAGR?
The services segment is projected to grow at the fastest CAGR of 12.73% during the forecast period. Rising demand for cybersecurity consulting, system integration, security assessments, managed detection and response, and compliance support is encouraging defense organizations to partner with specialized service providers. The increasing need for CMMC compliance and modernization of legacy infrastructure is expected to accelerate segment growth.
Defense cybersecurity market by security type
Which security type dominated the defense cybersecurity market?
The network security market held the largest market share of 20.0% in 2025 as there were higher investments being made in securing military communication networks, tactical networks, and command networks. In July 2026, Sophos launched ‘Fusion’ which is an AI-native cybersecurity solution to enhance cyber protection from advanced and AI-powered cyberattacks (Source: www.sophos.com). The defense agencies have been working on improving network visibility, segmentation, and threat detection capabilities to enhance cyber resilience.
Which security type is projected to grow at the fastest CAGR?
The identity and access management segment is projected to register the fastest growth witnessing 11.49% CAGR during the forecast period. Growing implementation of zero trust architecture is increasing demand for continuous authentication, privileged access management, and identity verification across military and contractor environments. These solutions help organizations secure access to classified information while supporting coalition interoperability.
Defense cybersecurity market by end user
Which end user dominated the defense cybersecurity market?
The armed forces segment dominated the market with 58.0% share in 2025 owing to continuous investments in protecting military operations, intelligence systems, and mission-critical communication networks. The rising trend of digital transformation within defense organizations is driving increased investments in cybersecurity technology that enhances operational security and mission assurance.
Which end user is projected to grow at the fastest CAGR?
The defense contractors segment is projected to witness the fastest growth witnessing 11.65% CAGR during the forecast period. Increasing cybersecurity requirements across the defense industrial base and growing adoption of CMMC compliance are encouraging contractors to strengthen cybersecurity capabilities and protect sensitive defense information throughout the supply chain.
Segment Summary Table
| Segment | Category | 2025 Status | Forecast CAGR | Key Driver |
| Solutions | Component | Largest share | High | Deployment of integrated cybersecurity platforms |
| Services | Component | Fastest growing | Highest | Rising demand for integration and managed security services |
| Network security | Security type | Largest share | High | Protection of tactical networks and military communications |
| Identity and access management | Security type | Fastest growing | Highest | Adoption of zero-trust architecture |
| Armed forces | End user | Largest share | High | Modernization of defense communication infrastructure |
| Defense contractors | End user | Fastest growing | Highest | Increasing CMMC compliance requirements |
Source: Polaris Market Research Analysis. Segment share and CAGR reflect Polaris proprietary sizing methodology.
Source: Polaris Market Research Analysis
Defense Cybersecurity Market by Region
North America defense cybersecurity market
North America dominated the defense cybersecurity market with a 38.1% share in 2025 owing to high defense spending, implementation of zero trust architecture, and increasing cybersecurity requirements across the defense industrial base. The US accounted for the largest regional share due to ongoing modernization of military networks, secure cloud adoption, and contractor cybersecurity requirements. In July 2026, The White House launched Gold Eagle, an AI-driven initiative to accelerate vulnerability detection, prioritization, and remediation across US critical infrastructure and defense cybersecurity (Source: www.whitehouse.gov). This trend is encouraging defense organizations and their partners to make investments in identity and access management, threat intelligence, and cyber-resilience solutions.
Canada is also enhancing defense cybersecurity through the collaboration with NATO and the joint defense initiatives with the US. Increasing emphasis on secure data exchange and interoperability is providing cybersecurity companies with opportunities to provide solutions for secure communications, identity management, and cross-domain security.
Europe defense cybersecurity market
The Europe region had a considerable market share of approximately more than 20% in 2025 owing to increasing investment in the modernization of the military and cybersecurity programs under NATO. The setting up of NATO’s Integrated Cyber Defense Center and increasing focus on enhancing cyber resilience have motivated countries to improve the security of their military networks and facilitate the exchange of information. For instance, in August 2026, The COcyber Ambassadors Program was established to improve cooperation between civil and military entities involved in cybersecurity in Europe (Source: cocyber.eu). Such programs are creating increased interest in threat intelligence, secure cloud infrastructure, and coalition interoperability services.
The UK, Germany, and France remain committed to defense cybersecurity via their modernization plans and vendor security programs. Growing focus on sovereign cybersecurity capabilities and secure defense communications is expected to support steady regional market growth.
Asia Pacific defense cybersecurity market
Asia Pacific is projected to register the fastest CAGR of 13.49% during the forecast period owing to rising geopolitical tensions, increasing cyber threats, and rapid military digitalization. The nations such as Japan, India, Australia, and South Korea have started investing in safe tactical networks, cyber resilience, and defense communication systems. Defense modernization initiatives in expansion are expected to create numerous chances for companies providing cybersecurity solutions.
The rise in collaboration among regional allies is also fostering the development of secure information sharing systems, identity and access management systems, and interoperability among coalitions. The increasing usage of secure cloud systems and AI-driven cyber defense tools is anticipated to foster market growth. In August 2026, Google Cloud introduced Google Security Operations in Taiwan (Source: www.googlecloudpresscorner.com), bolstering AI-enabled cyber defense and threat detection capabilities for Taiwanese organizations.
Latin America defense cybersecurity market
Latin America is forecasted to grow at a steady rate of 11.19% in the forecast period due to increasing investments in military communications and cyber defenses. Brazil stands out as the region’s leader in implementing such strategies, with its focus on building robust cyber defense capability and modernizing its defense information infrastructure, while other countries are concentrating on safeguarding their military networks and incident response capabilities.
The realization of cyber threats against the defense infrastructure of states has motivated governments to use advanced cybersecurity measures and managed security services. These developments are expected to create gradual growth opportunities for technology providers.
Middle East & Africa defense cybersecurity market
The Middle East & Africa market is projected to grow steadily witnessing 10.79% CAGR owing to increasing defense modernization programs and rising investment in national cybersecurity strategies. Saudi Arabia, the UAE, and Israel are strengthening cyber resilience by securing military communication systems, critical infrastructure, and defense cloud environments against advanced cyber threats. According to the International Trade Administration, Saudi Arabia has allocated USD 72.5 billion for defense in 2025, and Vision 2030 aims at localizing 50% of its military procurement by 2030 from the current level of 19.35% (Source: www.trade.gov).
Defense organizations in the region are also focusing on security-related activities such as secure defense operations, threat intelligence, and identity and access management to enhance mission assurance. Growing demand for locally designed cybersecurity services and secure digital infrastructure is expected to drive the growth of the market.
Source: Polaris Market Research Analysis
Regulatory Heatmap
| Country | Policy Environment | Key Regulations | Market Implication | Trend |
| US | Favorable | DoD Zero Trust Strategy, CMMC | Accelerates cybersecurity modernization | Expanding |
| NATO | Favorable | NATO Cyber Defence initiatives | Supports coalition interoperability | Expanding |
| UK | Favorable | MOD Cyber Security Model | Strengthens supplier cybersecurity | Expanding |
| Japan | Favorable | National defense cyber initiatives | Increases investment in secure defense systems | Growing |
| Australia | Favorable | AUKUS cyber cooperation | Supports secure military collaboration | Growing |
| India | Developing | Defense modernization programs | Expands demand for cyber resilience | Developing |
| Middle East | Developing | National cybersecurity strategies | Encourages secure defense infrastructure | Developing |
Source: Polaris Market Research Analysis; U.S. Department of Defense, NATO, UK Ministry of Defence, Australian Government Department of Defence, Ministry of Defence (India), and national cybersecurity authorities
Defense Cybersecurity Competitive Landscape by Provider Role & Capability
Defense cybersecurity has a moderate level of consolidation in terms of competition among the following players, such as defense contractors, cybersecurity vendors, cloud providers, and government technology integrators. The following factors determine competitive advantages: product portfolios that are secure; contracts with the government; expertise in cybersecurity; and integration capability in the complicated environment of the military.
The vendors have been increasing their abilities through strategic alliances, acquisitions, and innovations to enhance the areas of zero trust architecture, threat intelligence, secure cloud services, and cyber resilience. Companies are also making efforts to enhance AI-based cybersecurity, automation, and managed security services to enable enhanced capabilities of detection and mission assurance in the defense operations.
Defense Cybersecurity Companies: Provider Role, Core Capability & Geographic Presence
| Company | Est. Market Position | Primary Focus | Geographic Focus |
| Lockheed Martin | Top tier | Mission system integration | Global |
| Northrop Grumman | Top tier | Defense cyber operations | Global |
| RTX | Strong player | Secure defense systems | Global |
| BAE Systems | Strong player | Cyber intelligence solutions | Europe, North America |
| General Dynamics Information Technology | Strong player | Government IT modernization | North America |
| Leidos | Strong player | Managed cybersecurity services | North America |
Source: Company filings and press release
The leading companies operating in the market include Lockheed Martin Corporation, Northrop Grumman Corporation, RTX Corporation, BAE Systems plc, General Dynamics Information Technology, Leidos Holdings, Booz Allen Hamilton, Cisco Systems, Palo Alto Networks, CrowdStrike Holdings, Fortinet, and IBM Corporation. These companies continue to strengthen their portfolios through technology innovation, strategic partnerships, and long-term defense contracts.
Defense Cybersecurity Technology Landscape: Zero Trust, Secure Cloud, AI, Cross-Domain Security & Automation
Technological advancements in the field of defense cybersecurity are mainly oriented towards ensuring mission assurance, enhancing cyber resiliency, and ensuring that military systems remain safe from any kind of cyberattacks. Defense establishments are deploying state-of-the-art cybersecurity solutions that offer 24x7 monitoring, identity management, threat detection, and secure data exchanges in both tactical and enterprise environments.
There has been an increased adoption of zero trust architecture, AI-driven threat intelligence, and secure cloud platforms, which have enhanced the security of critical defense infrastructure. Other technologies being developed by vendors include those that can help in enhancing the capability of inter-operating among coalitions, protecting classified information, and security within the defense industrial base.
| Technology | Adoption Stage | Key Development | Market Impact |
| Zero trust architecture | Growing | Enterprise-wide implementation across defense agencies | Strengthens identity verification and access control |
| Identity and access management | Growing | Continuous authentication and privileged access management | Improves protection of classified systems |
| Secure cloud security | Growing | Expansion of defense cloud modernization programs | Increases demand for cloud-native cybersecurity |
| Early commercial | Automated threat detection and response | Improves cyber resilience and incident response | |
| Cross-domain security | Growing | Secure information exchange across multiple security domains | Supports coalition interoperability |
| Early commercial | Automated incident response and security operations | Reduces response time and operational workload |
Source: Polaris Market Research Analysis, press release, and IP & patent filings
Buyer Use Cases
Organizations conduct defense cybersecurity market research to make decisions regarding technology adoption, procurement preferences, and competitor analysis. The research report enables defense organizations, contractors, investors, and solution vendors to identify growth areas, keep track of regulatory changes, and understand the changing cybersecurity needs of the military and contracting environment.
The market presents high entry barriers due to stringent security requirements, long procurement cycles, and the need for proven deployment capabilities. Vendors must demonstrate compliance with government regulations, support classified environments, and integrate solutions with existing defense infrastructure to establish a strong market presence.
Buyer Decision Framework
| Buyer / Investor Type | Primary Use Case | Key Insight Sought | Decision Horizon |
| Defense agencies | Cybersecurity modernization | Technology roadmap and procurement priorities | 2–5 years |
| Defense contractors | CMMC compliance and cyber resilience | Compliance readiness and supplier security | 1–3 years |
| Technology providers | Product development | Customer demand and technology trends | 2–5 years |
| System integrators | Solution deployment | Integration opportunities | 2–4 years |
| Investors | Market evaluation | Growth potential and competitive landscape | 3–7 years |
| Government organizations | Policy planning | Regional cybersecurity developments | 2–5 years |
Source: Polaris Market Research Analysis
What are the Barriers to Entering the Market?
Regulatory compliance and procurement complexity
There is a need for defense cybersecurity solutions to conform to stringent standards of security requirements, procurement policies, and certifications prior to deployment. The lengthy process of procurement, security clearance, and rigorous testing makes deployment costs and timelines higher for any new entrants in the market.
Integration with legacy defense systems
Several military platforms will continue running on legacy infrastructure, which was never designed to be used with current cybersecurity protocols. It is therefore the responsibility of the vendors to integrate the solution seamlessly into legacy infrastructure without affecting the mission operations.
Premium Insights and Forward Outlook
Defensive cybersecurity is forecast to remain a key strategic area of investment as governments seek to modernize military operations and defend the digital defense infrastructure. Increasing use of zero trust architecture, cloud security platforms, and AI-driven threat intelligence is forecast to drive resilience in cyberspace and ensure mission success within the defense sector. Investment in cybersecurity has also increased throughout the defense industry as contractors improve compliance and cybersecurity of sensitive defense information.
Market growth in the future will be fueled by rising interoperability of alliances, modernizing the tactical network infrastructure, and improving cybersecurity governance in allied defense initiatives. Companies that provide cybersecurity platforms, managed security services, and identity and access management solutions are projected to become more competitive in their business as the defense agencies invest in digital transformation.
Key Players in the Defense Cybersecurity Market
- Lockheed Martin Corporation
- Northrop Grumman Corporation
- RTX Corporation
- BAE Systems plc
- General Dynamics Information Technology
- Leidos Holdings, Inc.
- Booz Allen Hamilton Holding Corporation
- L3Harris Technologies, Inc.
- CACI International Inc.
- SAIC, Inc.
- Thales S.A.
- Airbus Defence and Space
- QinetiQ Group plc
- Palantir Technologies Inc.
- IBM Corporation
- Cisco Systems, Inc.
- Palo Alto Networks, Inc.
- CrowdStrike Holdings, Inc.
- Fortinet, Inc.
Defense Cybersecurity Market Developments: Zero Trust, Classified Cloud, AI Security & Mission-System Resilience
- August 2026: Tidal Cyber partnered with Carahsoft to bring Threat-Led Defense to the public sector, giving government agencies access to its threat and vulnerability prioritization platform. (Source: globenewswire.com)
- July 2026: Tidal Cyber launched Threat-Led Asset Visibility and Vulnerability Prioritization, shifting from static asset inventories and CVSS scoring toward a model built on how adversaries actually execute attacks. (Source: prnewswire.com)
- June 2026: Accenture agreed to acquire a majority stake in Dragos and all of runZero and NetRise for a combined $4.175 billion, building an end to end OT security platform covering critical infrastructure and defense adjacent industrial environments. (Source: accenture.com)
- February 2026: Kyndryl launched its first Cyber Defense Operations Center in Bengaluru, India, a next generation command hub offering global cybersecurity and network operations expertise. (Source: kyndryl.com)
Market Segmentation
By Component Outlook (Revenue, USD Billion, 2021–2034)
- Solutions
- Services
By Security Type Outlook (Revenue, USD Billion, 2021–2034)
- Network Security
- Endpoint Security
- Identity and Access Management
- Cloud Security
- Application Security
- Data Security
- Security Information and Event Management (SIEM)
- Threat Intelligence
- Others
By End User Outlook (Revenue, USD Billion, 2021–2034)
- Armed Forces
- Intelligence Agencies
- Defense Contractors
By Regional Outlook (Revenue, USD Billion, 2021-2034)
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Defense Cybersecurity Market Report Scope: Segmentation, Forecast Period, Competitive Coverage & Methodology
| Report Attributes | Details |
| Market Size in 2025 | USD 19.90 Billion |
| Market Size in 2026 | USD 22.06 Billion |
| Revenue Forecast by 2034 | USD 51.77 Billion |
| CAGR | 11.21% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Defense Cybersecurity Market Research Methodology
This report combines secondary research with primary industry validation to evaluate technology adoption, procurement priorities, and investment trends across the defense cybersecurity market. Secondary research includes publications from the U.S. Department of Defense, NATO, the UK Ministry of Defense, national cybersecurity agencies, defense budget documents, company annual reports, investor presentations, regulatory publications, and industry associations. The primary research will include interviews conducted with cybersecurity leaders, defense technology suppliers, system integrators, procurement experts, and industry advisors for validation of the market assumptions and identification of the emerging procurement priorities.
Market sizing involves both top-down and bottom-up approaches. The top-down approach includes analysis of defense IT & cybersecurity spending, budget for military modernization, and digital transformation projects in the main regions. Bottom-up approach entails the examination of companies’ revenue, government contract spending, deployment of defense cybersecurity solutions, and the use of technology in military establishments and the defense industrial complex. Data triangulation is used to reconcile both approaches.
The forecasts are prepared based on the analysis of long-term procurement plans, zero trust architecture, compliance with CMMC, cloud modernization, coalition interoperability, and cyber threats to military infrastructure. Defense spending per region, regulations, and investment strategies of the suppliers are other factors considered in forecasting. Every market estimate is cross-verified through multiple sources before being finalized using Polaris proprietary validation methodology.
Defense Cybersecurity Market – Research Methodology Overview
| Research Phase | Key Activities | Data Sources | Purpose |
| Secondary research | Review of defense policies, procurement programs, company disclosures, and technology developments | Government publications, defense agencies, company reports, industry associations | Establish market fundamentals and industry trends |
| Primary research | Interviews with defense cybersecurity executives, system integrators, procurement specialists, and technology providers | Industry experts and defense stakeholders | Validate market assumptions and procurement trends |
| Market sizing | Top-down and bottom-up estimation with data triangulation | Defense budgets, cybersecurity spending, contract activity, company revenues | Estimate market size and segment share |
| Forecasting | Assessment of policy, technology, procurement, and investment trends | Modernization programs, regulatory developments, technology adoption | Develop a long-term market forecast |
| Data validation | Cross-verification of quantitative and qualitative findings | Primary interviews and multiple secondary sources | Improve accuracy and consistency |
Source: Polaris Market Research Analysis
Defense Cybersecurity Market FAQ's
The global market size was valued at USD 19.90 Billion in 2025 and is projected to grow to USD 51.77 Billion by 2034.
CMMC strengthens contractor cybersecurity and was a mandatory certification requirement to bid on defense contracts. In July 2026, the Department of War suspended CMMC Phase II requirements to accelerate procurement, while Phase I self assessment obligations remain in effect.
North America dominated the market with 38.1% share in 2025 due to high defense spending and cybersecurity modernization.
The solutions segment accounted for the largest market share of 68.2% due to rising deployment of integrated defense cybersecurity platforms.
It enables continuous authentication and secure access to mission-critical systems under zero trust architecture.
The forecast combines top-down and bottom-up market sizing with validation through primary research and data triangulation.
Market growth is driven by the increasing adoption of zero-trust architecture and investments in cyber resilience by defense organizations.
Strong integration capabilities, regulatory compliance, government partnerships, and experience in defense environments improve competitive positioning.
Yes. In July 2026, the Department of War suspended CMMC Phase II certification requirements to speed up defense procurement, while Phase I self assessment obligations remain mandatory for contractors.
In July 2026, the White House launched Gold Eagle, an AI driven initiative to accelerate vulnerability detection, prioritization, and remediation across US critical infrastructure and defense systems.
Download Sample Report of Defense Cybersecurity Market
Please fill out the form to request a customized copy of the research report.