Drone Warfare Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Drone Warfare Market Summary
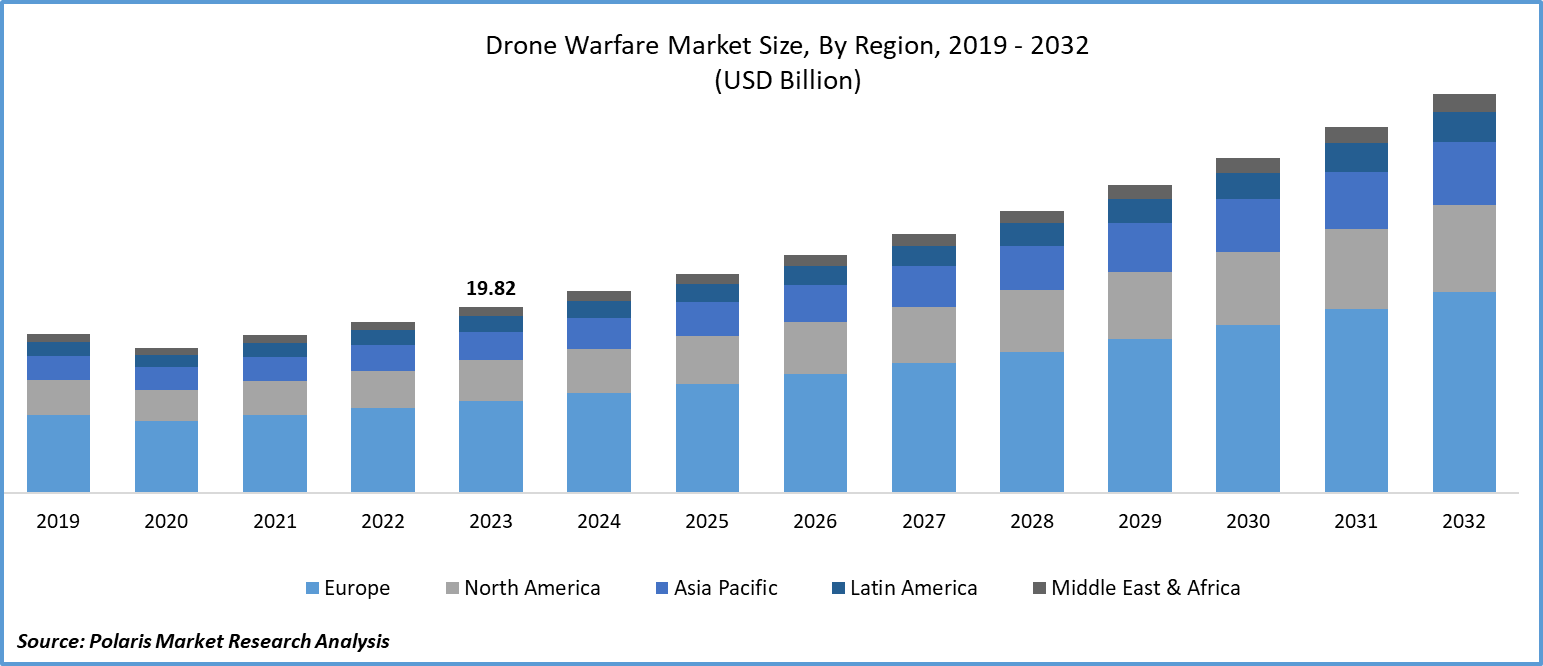
The drone warfare market size was valued at USD 27.83 billion in 2025. The market is expected to grow at a CAGR of 25.63% from 2026 to 2034. The market growth is attributed to rising military expenditure, increasing demand for ISR, autonomous and AI-enabled systems, and growing adoption of unmanned technologies in defense operations.
Market Statistics
Drone Warfare Market Key Takeaways 2025
- North America led the market with an 38.0% share in 2025, supported by high defense spending and military modernization.
- The Asia Pacific market is expected to grow at a 30.24% CAGR during the forecast period. The growth will be supported by rising defense expenditure and local drone manufacturing.
- The semi-autonomous segment led with 58.0% share in 2025. The dominance is attributed to increasing deployment of systems combining automated operations with human supervision.
- The ISR segment had an 40.0% market share in 2025 due to the increasing need for surveillance and war information.
- The share of the fixed-wing segment led with 56.0% in 2025, fueled by its capability to fly for a longer period of time.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is Drone Warfare?
Drone warfare involves using unmanned aerial systems for military missions. Military drones are used for intelligence, surveillance and reconnaissance, combat, logistics, communications, electronic warfare, and other defense missions.
The military drone ecosystem encompasses tactical UAVs, medium-altitude long-endurance (MALE) systems, high-altitude long-endurance (HALE) platforms, unmanned combat aerial vehicles (UCAVs), loitering munitions, autonomous drones, and supporting ground infrastructure.
Modern drone warfare isn't limited to individual planes. It includes mission software, sensors, communication systems, artificial intelligence, autonomous navigation, ground control stations, launch and recovery systems, and data processing capabilities. These technologies are expanding the operational role of drones across all military services.
The growing demand for the military drone market is also driven by the requirement for constant battlefield observation, precision capabilities, lower-cost attritable systems, and reduced exposure of humans to high-risk areas.
Role of Drones in Modern Defense Strategies
Drones are a key component of military modernization, with defense forces increasingly incorporating unmanned systems into surveillance, reconnaissance, combat and intelligence missions. Swarm drone technology in military applications enables coordinated operations across multiple unmanned platforms, while armed systems are driving UCAV market growth.
Drones have tactical advantages such as persistent surveillance, standoff operations, and fast response on the battlefield. High-risk environment applications can minimize personnel exposure to some operational risks and enhance mission flexibility. Increasing integration of autonomous systems, AI, and networked drone platforms is strengthening the role of unmanned systems across the broader defense ecosystem.
How Drone Warfare Systems Work
Drone warfare systems consist of an unmanned aircraft, sensors, communications, mission software, control infrastructure, and the payloads needed to perform a specific military objective.
- Mission Planning: Establish mission objectives, operating requirements, route, and payload.
- Deployment: Launch the drone with a suitable launch mechanism.
- Navigation: Navigate to the designated operational area by using onboard navigation and positioning systems.
- Sensing: Gather visual, infrared, radar, communications, or other mission data.
- Data Processing: Process data on-board or send to operators and command centers.
- Mission Execution: Conduct ISR, logistics, combat support, electronic warfare, or other designated responsibilities.
- Recovery: Continue to the assigned recovery point or complete the mission per system specifications.
AI and autonomous technologies are increasingly used to automate navigation, recognition, data processing, and coordinated operations.
Combat Drones vs. Surveillance Drones
| Attribute | Combat Drones (UCAVs) | Surveillance / ISR Drones |
| Primary Purpose | Precision strikes and target engagement | Intelligence gathering, reconnaissance, and situational awareness |
| Payload Focus | Missiles, bombs, and guided munitions | EO/IR cameras, radar, and SIGINT systems |
| Key Examples | MQ-9 Reaper, Bayraktar TB-2, CASC Rainbow CH-4 | RQ-4 Global Hawk, MQ-4C Triton, Heron |
| Autonomy | Semi-autonomous to autonomous, with human oversight | Highly autonomous navigation with human-supervised analysis |
| Technology Requirements | Targeting systems, encrypted links, and weapons integration | Advanced sensors, real-time data links, and AI-based recognition |
| Military Applications | Counterterrorism, anti-armor, and strike missions | Border monitoring, maritime patrol, and force protection |
Source: Polaris Market Research Analysis
Market Dynamics
Driver: Rising Military Expenditure
The growth in global military spending is a major factor driving the market. Most nations are investing in innovative defense technologies, where drones are playing a crucial part in current battle operations. SIPRI data shows that global military spending rose by 2.9% in real terms to USD 2,887 billion in 2025, the 11th consecutive year of growth and a 41% increase over 2016–25. Drones can be used for surveillance, reconnaissance, and targeted strikes, reducing risk to soldiers. As the military tries to sustain its dominance in disputed territories and respond to emerging threats, the need for more advanced drones equipped with innovative sensors and autonomous technology continues to grow. The expansion of the drone warfare industry is driven by growing geopolitical tensions that are prompting the governments to allocate huge sums to develop and buy drone systems (Source: sipri.org).
Driver: Increasing Emphasis on Counterterrorism Operations
Increasing need for terrorist activities is driving the growth of the drone warfare market. Drones have their advantages. They can gather intelligence in hazardous locations without risking any lives. They can attack with precision and minimum collateral damage. Technologies like increased autonomy and longer flight duration make them more efficient in counterterrorism operations. Many governments worldwide are developing drones to maintain their advantage in the face of future challenges.
Driver: Growing Demand for ISR and Persistent Surveillance
The growing need for real-time intelligence and continuous surveillance has increased the use of drones in border surveillance, field awareness, maritime surveillance, and threat detection. KLM Defense launched two Tactical Intelligence Surveillance Reconnaissance unmanned aircraft systems in July 2026, which can launch from heights of up to 29,400 feet. It can improve drone-based intelligence in extreme cold and low-pressure environments. The efficiency of military UAVs is also being further improved by advances in electro-optical, infrared, radar, and AI-enabled drone sensor technology (Source: unmannedsystemstechnology.com).
Restraint: High Development and Integration Costs
Developing advanced military drones requires large investments in aircraft development, sensors, motors, communications, AI, navigation, and mission systems. The integration of new platforms into existing defense command-and-control infrastructure may further increase procurement costs and extend development cycles. Thus, the high development and integration costs of these drones hinder market expansion.
Opportunity: Integration With Unified Counter-UAS Platforms
The expanding use of military drones is presenting potential for integrated counter-UAS platforms. They combine detection, identification, tracking, electronic warfare, command-and-control, and other mitigating capabilities. Demand for interoperable counter-drone architectures is projected to benefit radar, RF sensing, electro-optical systems, electronic warfare and defense software companies. Therefore, integration with unified counter-UAS platforms would offer lucrative market opportunities in the coming years.
Opportunity: Expansion of AI-Enabled Autonomous Drone Operations
Advancements in AI technology are enabling autonomous navigation, mission planning, sensor fusion, collaborative operations, and swarm intelligence. In September 2026, Ukraine presented the RAM-2X, an AI-powered strike drone including Starlink communication and airborne scouts. The drone has a range of 180 km and over 450 combat-target tests. The demand for autonomous platforms and mission software is also being supported by an increased focus on human-machine teaming and AI military drones (Source: thedefensepost.com).
Challenge: Cybersecurity Vulnerabilities
Cybersecurity risks are one of the drone warfare challenges. Cybersecurity threats can prevent the use of drones. Connected UAVs depend on software, communication linkages, navigation systems, sensors and ground control infrastructure. The potential vulnerabilities of unauthorized access, data interception, signal disruption and software compromise increase the need for secure architectures and continuous defense cybersecurity investment.
Trend: Advanced Technologies Transforming Drone Warfare
Developments in artificial intelligence, autonomous flight, sophisticated sensors, satellite communications, and thermal imaging are extending military drone capabilities. AI-powered drones can process sensor data, recognize objects, assist with navigation, and improve mission planning. Advanced imaging and sensing technologies are also improving the ability to conduct surveillance and target identification in complex operating environments.
Swarm drone technology is gaining attention for military applications, as multiple unmanned platforms can be coordinated for missions such as surveillance and reconnaissance. Secure satellite communications can offer operational connectivity outside of traditional communication networks. Thermal imaging enhances detection in low-light and difficult environmental conditions. Such developments are pushing forward defense drone technology and are broadening the scope of military drones.
Trend: Counter-Drone Warfare and Defense Systems
Demand for counter-drone systems capable of detecting, tracking, identifying, and neutralizing hostile unmanned aircraft is driven by the increasing use of military drones. Detection technologies include radar, electro-optical and infrared sensors, radio frequency systems, and acoustic sensors for layered monitoring of low-altitude airspace.
Electronic countermeasures such as jamming and spoofing, kinetic interceptors, and directed-energy systems can be used to defeat drones. The counter-drone market is therefore expanding toward integrated defense architectures that combine detection, electronic warfare, and physical interception to protect military bases, critical infrastructure, and operational airspace.
Segmentation Analysis
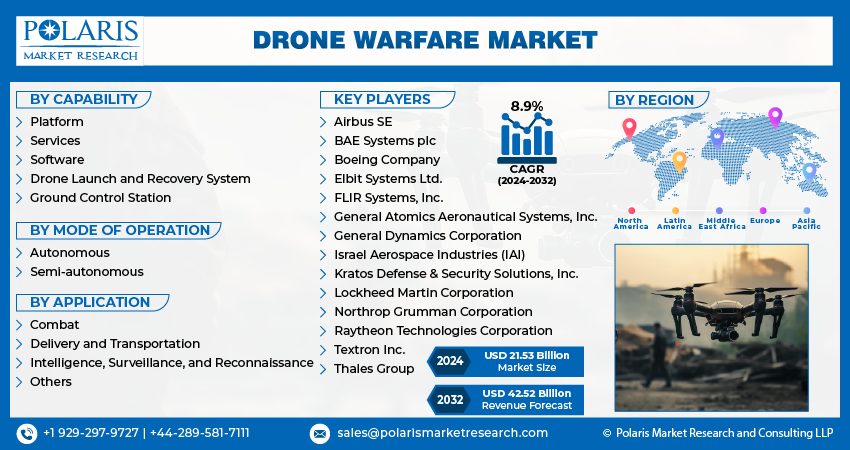
Drone warfare market segmentation includes capability, mode of operation, application, drone type, range, end user, and region.
Market Segmentation Overview
| Dimension | Segments | Key Insight |
| Drone Type | Fixed-wing | Hybrid | Rotary-wing | Fixed-wing held 56.0% share in 2025 |
| Capability | Platform | Services | Software | Drone Launch & Recovery System | Ground Control Station | Platform segment dominated with 36.0% in 2025 |
| Mode of Operation | Autonomous | Semi-autonomous | Autonomous to register fastest CAGR of 29.71% during 2026–2034 |
| Application | UCAVs (Lethal Drones, Stealth Drones, Loitering Munitions, Target Drones) | ISR | Delivery & Logistics | Others | ISR led with 40.0% in 2025 |
| Range | Visual Line of Sight (VLOS) | Extended VLOS (EVLOS) | Beyond VLOS (BVLOS) | EVLOS to record the fastest CAGR during the forecast period |
| End User | Military Forces | Defense Agencies | Government Organizations | Military forces dominated with 68.0% share in 2025 |
Source: Polaris Market Research Analysis
By Capability Analysis
The platform segment dominated the drone warfare market with an 36.0% share in 2025. Continued procurement of military UAV platforms for intelligence, surveillance, and reconnaissance (ISR), combat, battlefield monitoring, and other defense missions boosts the dominance. The segment’s leadership position is also bolstered by the growing use of tactical UAVs and unmanned combat platforms in military forces.
The software segment is expected to register the fastest growth at an 30.27% CAGR during the forecast period. It is driven by increasing integration of artificial intelligence, autonomous navigation, mission planning, sensor fusion, data analytics, and command-and-control capabilities. The rising need for software-defined and autonomous military drones is further boosting the importance of improved mission-management and decision-support systems.
By Mode of Operation Analysis
In 2025, the semi-autonomous category held a 58.0% share of the market. The leading share is propelled by the rising deployment of systems combining automated operations with human supervision. They give military operators enhanced operational flexibility while ensuring human supervision of mission execution. Semi-autonomous systems are appropriate for ISR, surveillance, reconnaissance, and other defense applications.
The autonomous segment is expected to experience the fastest growth at a 29.71% CAGR during the projected period. This is owing to advancements in AI, autonomous navigation, machine learning, sensor fusion, and collaborative unmanned operations. Increasing investments in the autonomous military drones market drive the segment growth. Also, rising emphasis on human-machine collaboration in the defense sector is expected to drive the adoption of autonomous technology during the forecasted period.
By Application Analysis
The intelligence, surveillance, and reconnaissance (ISR) segment led in 2025, accounting for 40.0% share. This is attributed to the high demand for persistent aerial surveillance, intelligence at battlefields, border patrolling, and situational awareness. The persistent use of ISR drones for acquiring and transferring information over harsh operational environments drives the segment growth.
The combat segment is projected to record the highest CAGR of 26.01% during the forecast period. It is driven by the increased development and deployment of loitering munitions and autonomous combat systems. The expansion of the unmanned combat aerial vehicle market will also propel segment growth. Increasing need for unmanned systems to support military missions and reduce crew presence in high-risk settings is further driving segment growth.
By Drone Type Analysis
The fixed-wing segment held the largest 56.0% market share in 2025. This is due to their greater endurance, wider operational coverage, and suitability for persistent ISR and battlefield observation tasks. The unique characteristics of fixed-wing UAVs make them highly appropriate for military purposes where flight time for large geographical areas is required.
The hybrid segment is anticipated to register the highest growth with an 31.74% CAGR. Rising preference for platforms offering vertical takeoff and landing capability along with the endurance offered by the fixed-wing aircraft will drive the growth. The adoption of such unmanned aerial vehicles is expected to rise owing to growing interest in flexible unmanned platforms suitable for tactical missions.
By Range Analysis
The beyond visual line of sight (BVLOS) segment had the biggest market share of 46.0% in 2025. This is due to growing requirements for long-distance surveillance, reconnaissance, and military operations. This technology allows the military to operate beyond the operators' line of sight, widening the scope of unmanned systems' applications.
The extended visual line of sight (EVLOS) segment is projected to register the highest CAGR of 24.70% during the forecast period. The segment is gaining demand for missions requiring greater operational range than VLOS while maintaining closer operator oversight than BVLOS systems. Improvements in communication systems, portable ground-control technologies, and sensor integration are supporting EVLOS adoption.
By End User Analysis
The military forces segment held the largest share of 68.0% in 2025. Military forces make extensive use of UAVs for ISR, combat, surveillance, logistics, reconnaissance, and force-protection tasks. The segment’s leadership position in key markets is supported by ongoing defense modernization and militaries' procurement of advanced unmanned systems.
The defense agencies segment is anticipated to exhibit the highest CAGR of 26.90% during the projected period. This is due to rising purchases of autonomous systems, counter-UAS technologies, ISR platforms, and integrated unmanned solutions. The segment is anticipated to expand due to rising emphasis of governments on enhancing national defense capabilities and integrating evolving drone technologies in broader military frameworks.
Applications of Drone Warfare
- ISR and Battlefield Surveillance Drones: They provide constant aerial surveillance and real-time intelligence.
- UCAVs: Autonomous and remote-controlled ability for military operations.
- Loitering Munitions: Precision strike along with surveillance capability.
- Delivery and Transport: Support unmanned delivery of goods and equipment.
- AI & Autonomous Drones: Navigation, Targeting, Object Recognition, and Mission Planning.
- Swarm Technology: Allows numerous autonomous drones to operate in a coordinated fashion.
- Counter-Drone & Electronic Warfare Drones: Allows for the detection, tracking, jamming, and response to drones.
- Crewed-Uncrewed Teaming: Using drones and crewed aircraft to carry out joint missions.
Regional Insights
North America Drone Warfare Market
North America held the largest 38.0% share of the drone warfare market in 2025. The dominance is attributed to high defense expenditure and the presence of established aerospace and defense businesses. Also, huge investments in military UAVs, autonomous systems, and counter-drone technology fuel the segment growth. The U.S. remains a key market in drone warfare market North America. This is driven by ongoing development of ISR, UCAV, and attritable and autonomous systems. In May 2026, Perennial Autonomy received a USD 500 million contract from the Pentagon to scale AI-enabled counter-drone systems, increasing demand for cost-effective C-UAS technologies (Source: defensenews.com).
Asia Pacific Drone Warfare Market
The drone warfare market Asia Pacific is predicted to expand at the highest CAGR of 30.24% during the projected period. The growth is propelled by military modernization and growing defense budgets. Also, territorial and maritime security requirements and indigenous UAV capabilities development boost the growth. Important regional markets are China, India, Japan and South Korea. SIPRI also noted that Japan’s military expenditure rose from USD 54.25 billion in 2024 to USD 62.16 billion in 2025, with defense investments increasingly centered on AI, unmanned systems, long-range strike, and counter-drone capabilities (Source: tradingeconomics.com).
Europe Drone Warfare Market
The Europe market is expected to exhibit a CAGR of 28.0% during the forecast period. Rising defense budgets, military modernization, and interest in autonomous and uncrewed systems fuel the regional market growth. The European Defense Agency said that EU defense expenditure rose to USD 485.7 billion in 2025 and is predicted to exceed USD 527.5 billion in 2026, highlighting the ongoing increase of European defense investments. European defense agencies are likewise ramping up investments in counter-UAS technologies and capabilities informed by recent battlefield experience (Source: eda.europa.eu).
Latin America Drone Warfare Market
The market is projected to record a CAGR of 27.38% during 2026–2034. Latin America is witnessing increasing demand for military UAVs for border patrolling, marine surveillance, security and defense modernization. Brazil, Mexico, and Argentina represent important markets. Adoption of advanced autonomous and combat systems is expected to develop progressively.
Middle East & Africa Drone Warfare Market
The Middle East & Africa market is expected to record a CAGR of 26.96% during the projected period. The growth is supported by defense modernization, border surveillance, national security requirements, and demand for UAV and counter-UAS capabilities. Israel, Saudi Arabia, and the UAE remain important participants in regional unmanned defense technology development and procurement.
Real-World Use Cases
Military drones serve many functions, including reconnaissance, surveillance, target acquisition, precision strikes, and battlefield intelligence. The Bayraktar TB2 has been used by Ukraine for intelligence and strike missions. The MQ-9 Reaper and MQ-1C Gray Eagle are used to support intelligence, surveillance, reconnaissance, and armed missions.
India is expanding its maritime unmanned capabilities with planned acquisition and deployment of MQ-9B systems for long-range surveillance. The UK is also investing in unmanned capabilities, through its multi-billion-pound unmanned aircraft vehicle program. These deployments are supporting demand across the ISR drones market and loitering munition market as defense forces expand use of unmanned systems.
Competitive Insights
The drone warfare market includes established aerospace and defense contractors, specialized military UAV manufacturers, AI-native defense companies, autonomous-system developers, and sensor technology providers. An expected surge of newcomers is poised to intensify rivalry. Dominant market players continuously enhance their technologies to maintain a competitive advantage, emphasizing efficacy, reliability, and security. These firms prioritize strategic actions such as establishing alliances, improving product portfolios, and participating in collaborative endeavors. They aim to outperform competitors within the industry and secure a significant drone warfare market share. Competition is increasingly shifting from individual drone platforms toward autonomy, AI, ISR capabilities, secure communications, sensors, counter-UAS technologies, interoperability, and integrated defense systems.
Key Players
- AeroVironment, Inc.
- Airbus SE
- Anduril Industries
- BAE Systems plc
- Baykar
- Elbit Systems Ltd.
- General Atomics Aeronautical Systems, Inc.
- General Dynamics Corporation
- Israel Aerospace Industries (IAI)
- Kratos Defense & Security Solutions, Inc.
- Lockheed Martin Corporation
- Northrop Grumman Corporation
- RTX Corporation
- Shield AI
- Teledyne Technologies Incorporated
- Textron Inc.
- Thales Group
- The Boeing Company
- Turkish Aerospace Industries
Competitive Benchmarking
| Company | HQ | Key Drone Products | Primary Segments | Differentiator |
| Northrop Grumman | US | RQ-4 Global Hawk, MQ-4C Triton | ISR, Autonomous | HALE expertise |
| General Atomics (GA-ASI) | US | MQ-9 Reaper, MQ-1C Gray Eagle | UCAV, MALE ISR | MALE market leadership |
| Lockheed Martin | US | Stalker XE, Fury, Desert Hawk | ISR, Tactical | C4ISR integration |
| Boeing | US | MQ-25 Stingray, MQ-28 Ghost Bat | Stealth UCAV, Logistics | Naval & stealth expertise |
| RTX | US | Coyote, Blackjack | Counter-Drone, UCAV | C-UAS & EW capabilities |
| Israel Aerospace Industries (IAI) | Israel | Heron, Harop, Harpy | ISR, Loitering Munitions | Combat-proven systems |
| Elbit Systems | Israel | Hermes 900, Skylark, Watchkeeper | ISR, Tactical | Sensor & EW integration |
| BAE Systems | UK | Taranis, Fury | UCAV, Stealth | European UCAV development |
| AeroVironment | US | Puma, Switchblade, Raven | Tactical, Loitering Munitions | Soldier-portable systems |
| Anduril Industries | US | Anvil, Roadrunner-M, Ghost-X | Autonomous, Counter-Drone | AI-native architecture |
| Shield AI | US | Nova, V-BAT, Hivemind | Autonomous, Swarm | GPS-denied autonomy |
| Baykar | Turkey | Bayraktar TB2, Akıncı, Kızılelma | UCAV, Export | Cost-effective UCAVs |
| Thales Group | France | Watchkeeper, UAS-MTD | ISR, EW | Defense systems integration |
| Kratos Defense | US | UTAP-22 Mako, XQ-58A Valkyrie | Attritable, Autonomous | Low-cost attritable UAVs |
Source: Polaris Market Research Analysis
Recent Developments
- In September 2026, Elbit Systems launched its Fuse unit. The unit will emphasize AI-powered defense technologies, including autonomous drones and military systems. (Source: reuters.com)
- In September 2026, WB Group revealed its Warmate 30, a jet-powered loitering munition system. This jet-powered strike drone can be used for long-range reconnaissance and pinpoint strikes. (Source: breakingdefense.com)
- August 2026: India has signed a contract worth USD 203 million with General Atomics Aeronautical Systems. Through this deal, the country plans to lease two MQ-9B Sea Guardian high-altitude, long-endurance drones. Indian Navy will use these drones for 30 months. (Source: firstpost.com)
- In June 2026, Safran and THEON signed an MoU to establish a joint venture developing next-generation EO/IR systems for UAVs, including lightweight gimbals under 8 kg for ISR and targeting applications. (Source: thedefensepost.com)
Future Outlook
The drone warfare industry is expected to benefit from continued military modernization, rising defense expenditure, and growing demand for persistent ISR and unmanned combat capabilities. Key technical goals will likely continue to include AI, autonomous navigation, swarm technology, enhanced sensors and counter-drone systems.
Competition is likely to focus more on the combined capabilities of UAV platforms, mission software, sensors, communications, autonomous systems, and counter-UAS technology.
The increased use of autonomous defense systems is also likely to affect defense procurement tactics, while cybersecurity, interoperability, reliability, and oversight by humans will remain essential factors.
Research Methodology
The Polaris Market Research drone warfare market report is developed using a rigorous two-stage methodology combining top-down and bottom-up approaches to ensure accuracy and consistency across market estimates and segment forecasts.
Secondary Research: Market sizing and segmentation are supported by defense budgets, procurement records, company annual reports, industry association data, trade publications, government databases, and regulatory filings from organizations including the U.S. Department of Defense, NATO procurement offices, and national defense ministries.
Primary Research: The quantitative findings of the report are validated through discussions with C-level executives, procurement officers, defense engineers, industry analysts, drone manufacturers, defense contractors, system integrators, and military procurement agencies throughout significant regions.
Data Triangulation: Revenue share analysis of the demand side is conducted based on the production analysis of the supply side, purchasing, and trading flow analysis. Regional and segment-level estimates are cross-validated against primary research inputs. Final estimates represent the consensus view of the Polaris analyst team and are periodically reviewed as new procurement and industry data becomes available.
Drone Warfare Market Segmentation
By Capability Outlook (Revenue, USD Billion, 2021–2034)
- Platform
- Services
- Software
- Drone Launch and Recovery System
- Ground Control Station
By Mode of Operation Outlook (Revenue, USD Billion, 2021–2034)
- Autonomous
- Semi-autonomous
By Application Outlook (Revenue, USD Billion, 2021–2034)
- Combat
- Delivery and Transportation
- Intelligence, Surveillance, and Reconnaissance
- Others
By Drone Type Outlook (Revenue, USD Billion, 2021–2034)
- Fixed-wing
- Rotary-wing
- Hybrid
By Range Outlook (Revenue, USD Billion, 2021–2034)
- Visual Line of Sight (VLOS)
- Extended Visual Line of Sight (EVLOS)
- Beyond Visual Line of Sight (BVLOS)
By End User Outlook (Revenue, USD Billion, 2021–2034)
- Military Forces
- Defense Agencies
- Government Organizations
By Regional Outlook (Revenue, USD Billion, 2021-2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Drone Warfare Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 27.83 Billion |
| Market Size in 2026 | USD 34.82 Billion |
| Revenue Forecast by 2034 | USD 216.87 Billion |
| CAGR | 25.63% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Drone Warfare Market FAQ's
Drone warfare refers to the use of unmanned aerial systems to conduct military tasks, including ISR, reconnaissance, combat, logistics, and defense.
The size of the global drone warfare market in 2025 was estimated to be USD 27.83 billion and is forecast to be USD 216.87 billion by 2034. The growth is driven by rising advancements in sensor technology and increasing investments in defense technologies.
The worldwide drone warfare market is estimated to record a CAGR of 25.63% during 2026–2034, due to rising military expenditure.
Military expenditure growth, defense modernization, demand for ISR, deployment of AI-enabled autonomous systems, and the need for counter-UAS are the major driving forces.
The drone warfare market report covering key segments are capability, mode of operation, application, drone type, range, and end user.
Key challenges include cybersecurity threats, communication issues, development expenses, interoperability, legalities, and the complexities of autonomous systems.
North America continued to hold the largest market share of 38.0% in 2025 due to the heavy defense budget and the modernization of the military.
Download Sample Report of Drone Warfare Market
Please fill out the form to request a customized copy of the research report.