Heat Exchangers Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Heat Exchangers Market Summary
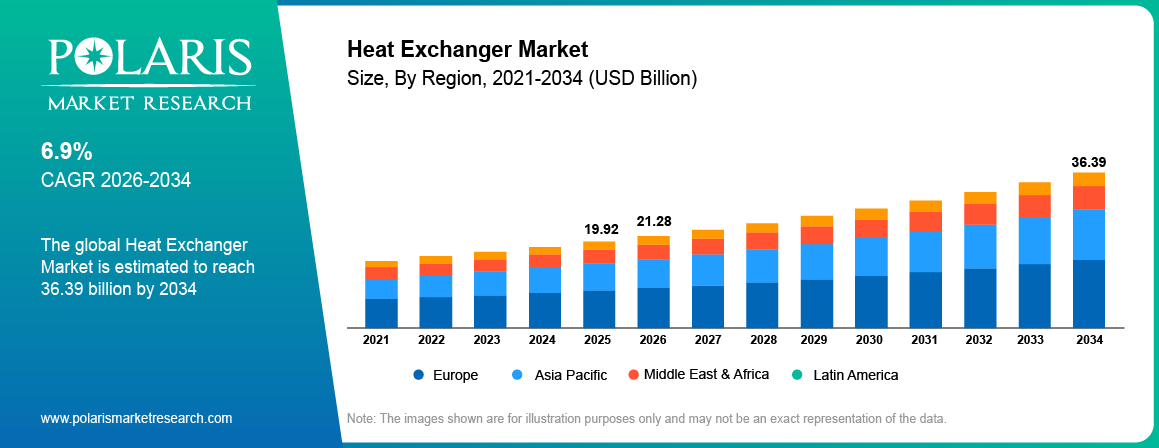
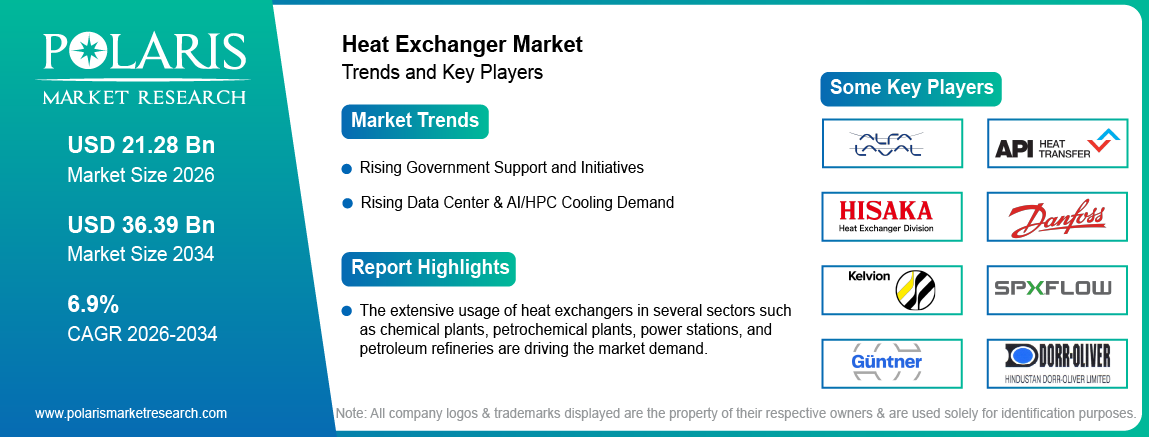
The global heat exchangers market size was valued at USD 19.92 billion in 2025 and is projected to exhibit a CAGR of 6.9% from 2026 to 2034. The extensive usage of heat exchangers in several sectors such as chemical plants, petrochemical plants, power stations, and petroleum refineries are driving the market demand.
Market Statistics
Heat Exchangers Market Key Takeaways
- The shell & tube heat exchanger segment accounted for the largest market share of 32.8% in 2025.
- The chemical & petrochemical segment dominated the revenue share of 22.1% due to them being usually utilized in the chemical processing industry to regulate temperature and enable energy conveyance between fluids.
- Europe heat exchangers market is expected to grow significantly with CAGR 6.7% due to increasing public and private sector funding in Europe which has caused the increased demand for heat exchangers in refrigerant industry.
- Asia Pacific dominated in 2025 with 31.9% share due to manufacturing, chemical, oil and gas, and petrochemical industry being the prominent donors to market demand in this region.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is Heat Exchangers?
A heat exchanger is a device that transfers heat between two or more fluids at varied temperatures. The fluids are separated by a wall having high thermal conductivity. The thickness of the wall is designed such that the fluids don’t mix or come in direct contact. Heat exchangers differentiate themselves from fuel, nuclear, or electrical heat transfer equipment. Here, the heat source and receiving medium need to be fluids. Heat exchangers operate using thermodynamic principles, describing the transfer of thermal energy at the macroscopic level.
Heat exchangers are mainly classified based on their flow configuration and construction type. The most basic heat exchanger involves the movement of cold and hot fluids in the same or opposing directions. Based on their functionality, heat exchangers can be classified as recuperative heat exchangers, regenerative heat exchangers, and direct mixing type heat exchangers. These heat exchangers have a wide variety of applications in several sectors, including chemical plants, petrochemical plants, power stations, and petroleum refineries.
How Heat Exchanger Works?
A heat exchanger is a device which transfers heat from one fluid to another, without mixing them. There are two different flows of fluids in a heat exchanger. One fluid carries heat, while another fluid takes away heat. The heat transfer surface is a separating wall made of metal, through which heat passes from one fluid to another. For instance, hot water can heat cold water in metal tubes. Heat exchangers are widely used in power plants, chemical and petrochemical industries, food processing, and air conditioning systems for controlling the temperatures of various fluids.
The rapid industrialization across the world is one of the key factors driving the heat exchangers market growth. Chemical, HVAC, automotive, food & beverage, and petrochemical are among the top end-use industries driving the global demand for heat exchangers. Further, the increased emphasis on improving energy efficiency and reducing carbon emissions is another factor driving the market forward.
The growing focus on decarbonization in the heating & cooling sector is one of the major industry trends anticipated to boost the adoption of heat exchangers. The rising demand for cost-effective, sustainable, and low-energy consumption heat exchangers is likely to provide lucrative heat exchangers market opportunities during the forecast period.
Heat Exchangers Market Dynamics
Driver : Rising Government Support and Initiatives
Government support and initiatives across different regions and countries have played a significant role in driving the adoption of energy-efficient heat exchangers in various end-use industries. New efficiency standards set by agencies such as the Office of Energy Efficiency and Renewable Energy (DOE), the Paris Agreement, and National Energy Commissions have introduced mandates regarding smart construction and manufacturing practices. These norms and initiatives aim to promote sustainability in the industrial, commercial, and residential sectors by using energy-efficient heat exchangers and other systems. Thus, the implementation of favorable government initiatives and support drives the heat exchangers market expansion.
Driver : Growing Demand for Heat Pumps
Heat exchangers are a vital component of heat pumps. They facilitate the transfer of thermal energy between fluids to heat or cool air. Heat exchangers also play a crucial role in determining the size, refrigerant charge, stability, performance, and longevity of heat pump systems. Heat pumps are commonly used for heating, ventilation, and air conditioning across residential, commercial, and industrial sectors. The growing demand for heat pumps, especially in Europe, is driving the need for heat exchangers and having a favorable impact on the heat exchangers market development.
Driver : Rising Data Center & AI/HPC Cooling Demand
The number of data centers worldwide are rising which fuels the necessity for effective cooling solutions. According to the Indian Ministry of Electronics & IT, the data center capacity in India alone has increased to 1500 MW as of 2025. Complex processes occurring within artificial intelligence and high-performance computing systems create an enormous amount of heat, and heat exchangers are critical components needed to eliminate it and ensure the stability of the aforementioned equipment. New data centers are being built worldwide to meet the rising demands with the rise of cloud computing, AI utilization, and digitalization. Consequently, there is a significant increase in the need for advanced heat exchangers, thereby driving the market growth (Source: pib.gov.in).
Driver : Growing Adoption of Printed Circuit & Compact Heat Exchangers
Printed circuit and compact heat exchangers are being adopted at a by various industries that require high power and density in a small size. The heat exchanger types are considered the most promising solutions concerning energy efficiency and power. They are applied mostly in the most demanding environments, including oil refining, petrochemicals, power generation, and industrial cooling. Additionally, they handle the pressures and temperatures of specific equipment and are highly compact and can be produced accordingly to be easily installed. Thus, there is a growing need for heat exchanger.
Restraining Factors : Fluctuations in Raw Material Prices
Heat exchanger producers utilize various kinds of metal, including stainless steels, copper, aluminum, and others due to its nature. Since the pricing of the raw materials is highly volatile, being influenced by numerous market forces, heat exchanger producers are the ones that bear the impact of price changes. Rising material prices lead to higher manufacturing rates to preserve the profit margin. Thus, the customers are the ones who suffer from the losses as producers try to minimize their expenses or struggle with higher rates to acquire raw materials for production due to market instability.
Restraining Factors : Installation, Operation & Maintenance Overheads
Installation and ongoing maintenance and inspections of industrial heat exchangers are essential for smooth production flow. They incur significant maintenance expenses accompanying all stages of the equipment’s life cycle. Additional operations, including cleaning and commissioning, further limits the manufacturing process. Larger units usually fuels the necessity of utilizing special equipment and highly skilled professionals to maintain them accordingly. Thus, the additional maintenance expenditures limits the widespread utilization of industrial heat exchangers, especially among small and medium-sized enterprises.
Opportunity : Rising Demand for Energy-Efficient Heat Recovery Systems
The global push for energy-efficient solutions fuels manufacturers to develop heat recovery equipment that allows industries to recoup a significant amount of waste heat from various processes. Such solutions are essential to help in reducing the carbon footprint, and energy consumption is one of the primary sources of it. Utilizing this heat recovery systems enables businesses to gain large power and utilize it for heating, cooling, and energy production. They have become highly demanded in the manufacturing industry, power engineering, petrochemical engineering, food processing, and more.
Heat Exchangers Market Segment Insights
Heat Exchangers Market Outlook Based on Product
The heat exchangers market, based on product, is segmented into plate & frame heat exchanger, shell & tube heat exchanger, air-cooled heat exchanger, and others. In 2025, the shell & tube heat exchanger segment accounted for the largest heat exchangers market share of 32.8%. A shell & tube heat exchanger consists of multiple tubes mounted inside a cylindrical shell. It passes heat between two fluids by passing them through separate channels separated by a solid barrier. These heat exchangers are known for their ease of use, cost-effectiveness, and efficiency. They are commonly used in oil refineries and other large chemical processes where a wide temperature and pressure range is required. Thus, the versatility and efficiency of shell & tube heat exchangers contribute to their dominant position in the market.
The Plate & Frame heat exchanger segment is expected to witness significant growth of 7.4% CAGR during the heat exchanger market forecast period driven by its compact design, high level of heat transfer efficiency, and ease of maintenance. This type of heat exchanger is widely applied in food processing, chemical industries, HVAC, and other fields. Moreover, the increasing need for energy-efficient equipment is also driving the growth of the Plate & Frame segment. Brazed, gasketed, and welded designs offer flexibility for different operating needs which is expected to drive demand during the forecast period.
The air-cooled heat exchanger segment is expected to witness significant growth of 7.1% CAGR during the forecast period driven by a decreasing freshwater consumption in various industrial processes. Air-cooled heat exchangers are typically used in the petrochemical, power generation, and chemical industries, among others. The rising scarcity of freshwater sources and the growing need for sustainable sources of water are estimated to propel the growth of this segment. Moreover, the high efficiency of air-cooled heat exchangers allows them to be used in remote areas without a consistent supply of water, which expands the range of potential applications, thereby driving the segment growth.
The Cooling Towers segment is expected to witness significant growth of 6.6% CAGR during the forecast period driven by the increasing need for closed-loop cooling systems in power plants, manufacturing facilities, data centers, and other large-scale operations. Cooling towers are used to cool water that has been heated during the warm process, which allows it to be re-used in the production process, which improves the sustainability of the operation. The growing industrialization of developing regions and the increased focus on energy efficiency and resource conservation is expected to drive the demand for cooling towers during the forecast period.
Heat Exchanger Type Comparison
| Type | Best For | Typical Temp./Pressure Range | Common Materials | Key Limitation |
| Shell & Tube | High-pressure, high-temperature process duty | Wide range; handles high pressure well | Carbon steel, stainless steel, nickel alloys | Larger footprint than plate types |
| Plate & Frame | Hygienic, space-constrained duty (F&B, HVAC) | Moderate pressure/temperature | Stainless steel, titanium plates | Gasket wear on gasketed variants |
| Air-Cooled | Sites with limited water availability | Moderate; ambient-air-dependent efficiency | Carbon steel, aluminum fins | Larger footprint, ambient-temperature-sensitive |
| Cooling Towers | Bulk heat rejection for large facilities/data centers | Low-to-moderate pressure, high volume | Concrete, FRP, galvanized steel | High water consumption; drift/legionella management |
Source: Polaris Market Research Analysis
Heat Exchangers Market Outlook Based on Material
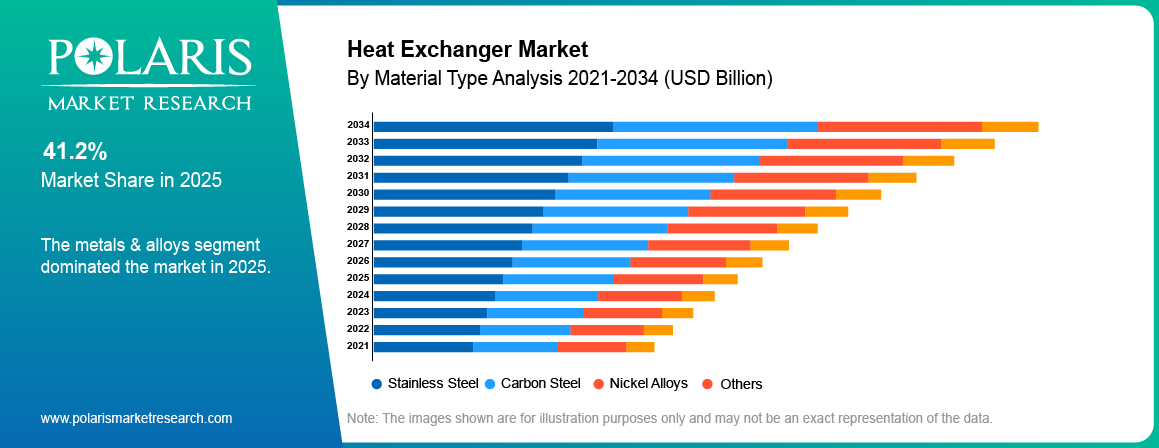
The heat exchangers market, based on material, is segmented into carbon steel, stainless steel, nickel alloys, and others. In 2025, the stainless steel segment accounted for the largest heat exchangers market size of 41.2% driven by its resistance to corrosion, long-term durability, and ability to resist extreme physical conditions. This metal is widely used in food processing, chemical processing, pharmaceuticals, power plants, and the oil and gas industry. The growing need for heat exchangers that can resist extreme physical conditions has increased the demand for this metal. They are highly favorable in the chemical processing industry where the equipment is exposed to high pressure, heat, and corrosive elements.
The Carbon Steel segment is expected to witness growth of CAGR 6.5% during the forecast period driven by its low cost, high strength, and availability which makes it applicable in most of the industrial heat exchangers. The high demand for these materials arises because they operate in less strenuous environments. This metal is widely used due to its cost-effectiveness and is more ductile. It is widely used in the production of large heat exchanging systems because of its ability to withstand huge pressures.
The Nickel Alloys segment is expected to witness growth of CAGR 7.8% during the forecast period driven by the need for heat exchangers that can operate at extremely high temperatures and highly corrosive environments. Nickel Alloys are resistant to high-pressure, highly corrosive environments and are able to sustain high temperatures. This metal is widely used in chemical processing, oil and gas, and power-generation industries. The rising need for advanced chemical processing and industrialization is propelling the demand for nickel alloys in heat exchangers.
Heat Exchangers Market Assessment Based on End Use
The heat exchangers market, based on end use, is segmented into oil & gas, chemical & petrochemical, HVAC & refrigeration, food & beverage, power generation, automobile, pharmaceuticals, pulp & paper, and others. The chemical & petrochemical segment dominated the market with a revenue share of 22.1% in 2025. Heat exchangers are commonly used in the chemical processing industry to control temperature and facilitate energy transfer between fluids. They facilitate energy optimization by enabling the recovery of waste heat from exhaust gases and other process streams. Also, the design flexibility and high corrosion resistance of heat exchangers offer them the ability to handle fluids with varying solid levels. The booming petrochemical industry, driven by the increased demand for plastics packaging, and medical equipment, fuels the high adoption of heat exchangers.
The Oil & Gas segment is expected to witness growth of CAGR 7.2% during the forecast period driven by the need for efficient heating and cooling during oil refining, processing, and transportation. Heat exchangers are widely used in refineries and gas processing plants. Rising energy demand and continued investments in oil and gas infrastructure support their use. The need to improve energy efficiency and reduce heat loss also increases demand for reliable heat exchanger systems.
The HVAC & Refrigeration segment is expected to witness growth of CAGR 7.3% during the forecast period driven by rising demand for heating and cooling systems that are used in residential, commercial, and industrial buildings. Heat exchangers facilitate the conduction of heat from one medium to another, enabling the most appropriate temperature regulation. Rising construction activity, surging need for air-conditioning, and emphasis on energy-efficient systems are factors that would propel the growth of this segment.
The Food & Beverage segment is expected to witness growth of CAGR 6.8% during the forecast period due to the growing requirement of heat exchangers in the food and beverage industry for heating, pasteurizing, and temperature control purposes. These heat exchangers find their application in a wide range of processes, including sterilization, cooling, and condensing. Increasing production rates, especially of processed food and beverages, apart from the need for maintaining hygiene and food safety standards, would propel the segment’s growth.
The Power Generation segment is expected to witness growth of CAGR 6.5% during the forecast period due to high demand for heat exchangers for power generation plants. This is mainly attributed to the rising need for electricity across the globe. Heat exchangers are used for a wide range of applications, including condensing, heating, cooling, and steam generation. Rising emphasis on achieving higher efficiency in power plants while minimizing losses in electricity generation would fuel the growth of the market.
The Pulp & Paper segment is expected to witness growth of CAGR 6.3% during the forecast period driven by the increasing need for heat exchangers in the pulp and paper industry to facilitate paper production with effective temperature control. These heat exchangers could be used in paper mills for various applications, such as cooling, drying, and heating. Growing demand for paper and paper products, coupled with the need for sustainable and cost-effective production methods, would drive the segment growth.
The Automobile segment is expected to witness growth of CAGR 7.5% during the forecast period due to rising demand for heat exchangers in the automobile sector for various applications, such as air conditioning and engine cooling. Growing automotive production, especially of electric and hybrid vehicles, across the globe would propel the segment’s growth. Moreover, the need for reliable and energy-efficient heat exchangers for improved performance and better management of heat in automobile manufacturing units and components would drive the market growth.
The Pharmaceuticals segment is anticipated to witness significant growth of CAGR 7.9% owing to the rising need for heat exchangers in the pharmaceutical industry for heating and cooling diverse drug compounds and achieving desired finished product quality. Increasing pharmaceutical production and rising investments in manufacturing facilities is expected to fuel the segment’s growth.
| Segment | Primary Driver | Representative Buyer Type |
| Chemical & Petrochemical | Waste-heat recovery, temperature control in processing | Refiners, petrochemical processors |
| Oil & Gas | LNG/FGSS cooling, refining and gas processing | Upstream/midstream operators, EPC contractors |
| HVAC & Refrigeration | Building decarbonization, heat-pump adoption | Commercial building owners, HVAC OEMs |
| Power Generation | Thermal and renewable plant efficiency | Utilities, IPPs |
| Food & Beverage | Pasteurization, hygienic processing | F&B manufacturers |
| Automobile | Engine cooling, EV battery thermal management | OEMs, Tier-1 suppliers |
| Pharmaceuticals | Sterile process temperature control | Pharma manufacturers, CDMOs |
| Data Center | AI/HPC rack thermal loads | Hyperscalers, colocation operators |
Source: Polaris Market Research Analysis
Heat Exchangers Market Outlook by Regional Analysis
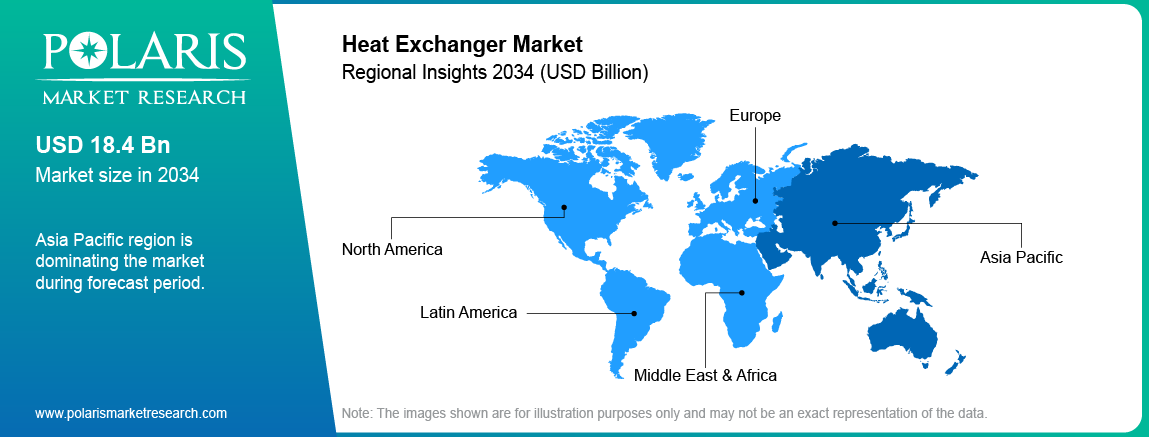
The market report offers heat exchangers market insights into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Asia Pacific dominated with largest share of 31.9% in 2025 due to the presence of substantial industrial activity. China, Japan, and India are key markets for heat exchangers. The rising investments in the manufacturing, power generation, chemical processing, automotive, and HVAC industries are projected to drive the demand for heat exchangers in the region.
China is expected to witness significant growth of CAGR 7.8% during the forecast period due to the presence of numerous manufacturing and industrial facilities. The chemical processing, power generation, automotive, oil and gas, and HVAC industries are key consumers of heat exchangers. Additionally, the growing number of industrial facilities and investments in energy-efficient equipment are projected to propel the market as well.
Japan is expected to witness significant growth of CAGR 6.4% during the forecast period due to substantial automotive, electronic, chemical processing, power generation, and manufacturing sectors. Heat exchangers are widely applied for cooling/temperature control purposes in the mentioned industries. The rising emphasis on energy efficiency and compact equipment as well as advanced industrial technologies is projected to drive the demand in the region.
India is expected to witness significant growth of CAGR 8.1% during the forecast period due to the rising industrialization and development of the manufacturing sector. Power generation, chemical processing, oil and gas, food processing, pharmaceuticals, and HVAC industries are substantial consumers of heat exchangers. Furthermore, the growing number of manufacturing facilities and investments in infrastructure are projected to propel the market as well.
North America
North America expected to witness significant growth of CAGR 6.5% during the forecast period due to the presence of a substantial industrial sector. The region is supported by oil and gas, chemical processing, power generation, HVAC, and manufacturing industries. Furthermore, the rising emphasis on energy efficiency is projected to drive the market as well.
The US expected to witness significant growth of CAGR 6.6% during the forecast period. The demand for heat exchangers is supported by oil and gas, power generation, chemical processing, HVAC, and data center industries. Moreover, the rising investments in industrial facilities and energy-efficient systems are projected to drive the market as well.
Canada is expected to witness significant growth of CAGR 5.8% during the forecast period supported by the oil and gas, mining, power generation, and industrial sectors. Heat exchangers are widely applied for heating/cooling purposes in the respective industries. The growing number of energy projects and the need for efficient equipment are projected to be the key growth drivers for the market.
Europe
Europe expected to witness significant growth of CAGR 6.7% during the forecast period due to the presence of substantial industrial activity. Germany, France, and the UK are important markets for heat exchangers. The rising emphasis on energy savings and improved industrial processes as well as efficient heating/cooling systems are crucial factors driving the market in the region.
Germany expected to witness significant growth of CAGR 6.4% during the forecast period due to the presence of substantial manufacturing and automotive sectors. Furthermore, the demand in the chemical processing and power generation as well as HVAC industries are the key growth drivers for the market. Additionally, the rising emphasis on energy efficiency and industrialization is projected to propel the market as well.
France expected to witness significant growth of CAGR 6.2% during the forecast period due to the presence of power generation, chemical processing, food processing, and HVAC industries. Moreover, the growing investments in energy-efficient systems and new industrial facilities are projected to drive the demand in the region.
The UK expected to witness significant growth of CAGR 6.1% during the forecast period is supported by the demand in the HVAC, power generation, food processing, chemical processing, and industrial sectors. The rising emphasis on energy-efficient systems is projected to drive the demand for heat recovery and cooling/heating equipment.
Middle East & Africa
The Middle East & Africa market is expected to witness significant growth of CAGR 5.9% during the forecast period driven by the oil and gas, petrochemical, power generation, water treatment, and industrial sectors. Saudi Arabia and the UAE are key markets in the region. The growing investments in infrastructure and industrial facilities are projected to increase the demand for heat exchangers.
Saudi Arabia expected to witness significant growth of CAGR 6.3% during the forecast period due to the presence of substantial oil and gas and petrochemical industries. The rising investments in industrial facilities, power generation, and water treatment are projected to be key growth drivers for the market.
The UAE market is expected to witness significant growth of CAGR 6.5% during the forecast period supported by the oil and gas, petrochemical, power generation, and water treatment industries. Additionally, the growing emphasis on commercial construction and infrastructure development is projected to increase the demand for heat exchangers.
Latin America
Latin America is expected to witness significant growth of CAGR 6.2% during the forecast period driven by the oil and gas, mining, power generation, food processing, and manufacturing sectors. Brazil and Argentina are key markets for heat exchangers in the region. The growing investments in energy and industrial facilities are projected to be key growth drivers for the market.
Brazil expected to witness significant growth of CAGR 6.5% during the forecast period due to the presence of oil and gas, power generation, food processing, mining, and chemical processing industries. The rising investments in infrastructure and industrial facilities are projected to drive the market in the region.
Argentina expected to witness significant growth of CAGR 5.8% during the forecast period due to the presence of oil and gas, food processing, chemical processing, power generation, and manufacturing sectors. The growing number of energy projects and industrial facilities are key growth drivers for the market.
Use Cases & Real-World Applications by Product
| Product Category | Main Use Cases | Real-World Applications | Named Product and Brand Examples |
| Plate & Frame Heat Exchanger | Liquid-to-liquid heating and cooling; pasteurization; heat recovery; HVAC water-loop separation; domestic hot-water generation | Dairy milk pasteurization; brewery wort cooling; beverage processing; district heating and cooling; chilled-water systems; data-center cooling loops; pharmaceutical water systems | Alfa Laval M-Series, T-Series, BaseLine and T6 used for general heating and cooling, hygienic processing, pharmaceutical water and CIP heating. API Heat Transfer SIGMA Series used in oil and gas, process industries and data-center cooling. Kelvion NP, GBS and NT Series, used in HVAC, industrial processing and utility systems. |
| Shell & Tube Heat Exchanger | High-pressure and high-temperature heat transfer; boiling and condensation; process heating and cooling; heat recovery; utility services | Crude-oil preheating; refinery product cooling; distillation-column reboilers and condensers; power-plant surface condensers; chiller evaporators and condensers; engine and transmission-oil cooling; seawater cooling | Alfa Laval Olmi Process Shell-and-Tube Exchangers used in refineries, petrochemical plants, power stations and chemical processing. Alfa Laval Aalborg EH, MX, MC and MD Series used in marine, oil, water and utility heating or cooling. Kelvion Smart, Advanced, A-Series, P-Series, R-Series and V-Series used for refrigeration, viscous fluids, high-temperature duties and industrial process cooling. API Heat Transfer Basco Series and Whitlock Series used in oil and gas, power generation, compressor cooling and industrial equipment. |
| Air-Cooled Heat Exchanger | Cooling or condensing process fluids with ambient air; water-free heat rejection; compressor aftercooling; gas and oil cooling; remote or water-scarce operation | Natural-gas compression; gas processing and transmission; LNG facilities; refinery overhead condensation; petrochemical product cooling; power-plant air-cooled condensers; generator and turbine cooling; offshore platforms | Alfa Laval ACE Model A, ACE Model J and Olmi API 661 Air Cooler used in upstream, midstream and downstream oil and gas, gas compression, gas processing and power applications. Chart Air-X-Changers used for upstream, midstream, downstream and power-sector cooling. API Heat Transfer AIRTECH Series used in oil and gas, chemical processing and industrial cooling. Kelvion Güntner Air Coolers used in refrigeration, HVAC and industrial cooling systems. |
| Cooling Towers | Heat rejection from circulating water through evaporation or air cooling; condenser-water cooling; industrial process cooling; centralized utility cooling | Thermal and nuclear power generation; refinery and petrochemical cooling-water systems; chemical plants; HVAC chillers; data centers; steel and metals processing; plastics injection molding; food and beverage plants | SPX Marley NC Cooling Tower used in commercial HVAC, industrial cooling and process-water applications. SPX Marley NC Everest high-capacity crossflow cooling for industrial and commercial facilities. SPX Marley Series 5000 used in large industrial and power-sector cooling systems. Baltimore Aircoil Company Series 3000 Cooling Tower used for HVAC and industrial process cooling. Evapco AT Series used in commercial HVAC and industrial cooling-water systems. |
| Double-Pipe Heat Exchanger | Small-capacity heating, cooling, condensation and vaporization; high-pressure or high-temperature services; pilot and skid-mounted systems | Chemical dosing skids; laboratory process systems; small oil coolers; gas heaters; steam-to-process-fluid heating; compact condensers and evaporators | Alfa Laval Olmi Double-Pipe Quench Exchanger used for demanding process-gas cooling. Kelvion Double Pipe Heat Exchanger used for small industrial heating and cooling duties. API Heat Transfer Hairpin and Double-Pipe Exchangers used in chemical, petrochemical, oil and gas applications. |
| Brazed Plate Heat Exchanger | Compact high-pressure heating and cooling; refrigeration; HVAC; heat recovery; domestic hot-water generation; engine and hydraulic-oil cooling | Refrigeration units; heat pumps; solar-water heating; domestic hot-water systems; absorption chillers; laser cooling; data-center cooling; air dryers | Danfoss B3, B4, B3-095 and B3-260C EnFusion Series used in chillers, heat pumps, economizers, desuperheaters and data-center cooling systems. SWEP B-Series and V-Series used in HVAC, refrigeration, heat pumps and industrial heat recovery. Alfa Laval CB Series used in refrigeration, HVAC and compact industrial cooling. |
| Scraped-Surface Heat Exchanger | Heating or cooling viscous, sticky, crystallizing or fouling fluids; continuous removal of deposits from heat-transfer surfaces | Ice-cream freezing; margarine and shortening production; chocolate and fat processing; sauces and pastes; crystallization processes; high-viscosity chemical products | Alfa Laval Contherm Scraped-Surface Heat Exchanger used for ice cream, margarine, sauces, dairy products and viscous foods. SPX Flow Gerstenberg Schröder scraped-surface exchangers used in margarine, shortening, dairy and food applications. HRS R Series Scraped-Surface Heat Exchanger used for viscous food, chemical and pharmaceutical products. |
| Spiral Heat Exchanger | Heat recovery from fouling, sludge-bearing, slurry or fibrous fluids; compact counter-current heat transfer | Wastewater treatment; pulp and paper; chemical effluent cooling; sludge heating; biomass and biofuel processes; dirty-process heat recovery | Alfa Laval Spiral Heat Exchanger used for wastewater, sludge, pulp and paper, chemical and effluent applications. Kelvion Spiral Heat Exchanger used for fouling fluids, wastewater and process heat recovery. HRS Spiral Heat Exchanger used in wastewater, food, chemical and renewable-energy applications. |
| Plate-Fin and Compact Heat Exchanger | High heat-transfer area in a small volume; gas-to-gas and gas-to-liquid heat recovery; cryogenic service | Aircraft environmental-control systems; aerospace propulsion; LNG and air-separation plants; hydrogen production; industrial gas processing; automotive intercoolers and radiators | Chart Brazed Aluminum Heat Exchangers used in LNG, hydrogen, air separation and industrial gas processing. Linde Brazed Aluminum Heat Exchangers used in cryogenic air-separation and natural-gas processing. Honeywell Aerospace Plate-Fin Heat Exchangers used in aircraft environmental-control and propulsion systems. |
| Heat Pipe Heat Exchanger | Passive heat transfer over a distance; electronics and battery thermal management; ventilation heat recovery; industrial waste-heat recovery | Data centers; telecom equipment; battery packs; semiconductor equipment; building ventilation; industrial furnace exhaust recovery | Thermocore Heat Pipe Systems used in electronics, data-center and battery thermal management. ACT Heat Pipe Heat Exchangers used in electronics cooling, aerospace and industrial heat recovery. Heat Pipe Technology heat-recovery systems used in building ventilation and energy-recovery applications. |
| Air-to-Air Heat Recovery Exchanger | Recovery of sensible and latent heat from exhaust air; reduction of HVAC energy consumption; ventilation conditioning | Commercial buildings; hospitals; cleanrooms; laboratories; data centers; food-processing facilities; industrial ventilation systems | Zehnder ComfoAir Energy Recovery Systems used in residential and commercial ventilation. Munters heat-recovery systems used in industrial, pharmaceutical, food and commercial facilities. Swegon GOLD air-handling units used for ventilation heat recovery in commercial buildings and institutional facilities. |
Source: Polaris Market Research Analysis
Heat Exchangers Market – Key Players and Competitive Insights
The leading players are introducing innovative products in the heat exchangers market to cater to the growing demand from consumers. Further, they are entering new markets in developing regions to expand their customer base, strengthen their market presence, and increase their market share. To expand and survive in a more competitive environment, market participants must offer innovative solutions.
In recent years, the heat exchangers market has witnessed several technological and innovation breakthroughs, with key players seeking to provide advanced solutions that help meet sustainability goals.
Vendor Positioning Snapshot
| Company | HQ | Recent Notable Move (dated) |
| Alfa Laval | Sweden | Aalborg Header-Coil A/S JV launch (Sep 2025); TS25 semi-welded exchanger (Jul 2025); Fives Cryogenics acquisition agreement (Mar 2025) |
| Shenshi | China | PCHE-LNG heat exchanger for offshore FGSS applications (Oct 2025) |
| Danfoss | Denmark | Microchannel Heat Exchanger (MCHE) launch, India (Feb 2024) |
| Kelvion Holding GmbH | Germany | - |
| SPX Corporation / SPX FLOW, Inc. | United States | - |
| Xylem Inc. | United States | - |
Source: Polaris Market Research Analysis
List of Key Companies in Heat Exchangers Market
-
Kelvion Holding GmbH
-
Xylem Inc.
-
Danfoss A/S
-
API Heat Transfer Inc.
-
Guntner GmbH
-
Hamon & Cie International
-
Hindustan Dorr-Oliver Ltd.
-
Hisaka Works, Ltd.
-
Chart Industries
-
GE Vernova
-
GEA Group Aktiengesellschaft
-
Johnson Controls
-
Mersen
-
Modine Manufacturing Company
-
Boyd
-
IHI Plant Services Corporation
-
Tranter, Inc.
-
SWEP International AB
-
Thermax Limited
-
Shenshi
Research Methodology
-
Market estimates are derived using a blend of primary and secondary research, validated through weighted-average and combined top-down/bottom-up modeling approaches.
-
Secondary research covers company filings, industrial capital expenditure and plant capacity data, energy efficiency and emission regulations, industry journals, and paid third-party databases to build baseline estimates.
-
Primary research includes interviews with key industry participants such as heat exchanger manufacturers, EPC contractors, plant engineers, and end-use industry procurement professionals, to validate accuracy and capture forward-looking insights.
-
Base year considered is 2025, with a forecast provided through 2034; revenues are expressed in USD Billion.
-
Parent market is identified as the global process and industrial equipment market; the addressable segment is narrowed using heat exchanger adoption rates across thermal management and energy recovery applications.
-
Bottom-up model aggregates regional heat exchanger demand across product, material, and end use, validated against vendor revenue disclosures from Alfa Laval, GEA Group, Kelvion, Modine Manufacturing, Danfoss, and others.
-
Regional coverage spans North America, Europe, Asia Pacific, Middle East & Africa, and Latin America, further segmented by major countries.
-
Projected 6.9% CAGR (2026–2034) reflects weighted analysis of rising industrial capacity expansions, growing demand for energy-efficient thermal management, expanding data center and HVAC cooling requirements, and increasing investment in oil & gas and power generation infrastructure.
-
Findings are cross-validated across multiple estimation methods to ensure consistency, accuracy, and reliability of the final market sizing.
Heat Exchangers Industry Developments
-
In September 2026, Mitsubishi Electric launched a new plate heat exchanger in September 2026. The company reported that the new design achieved three times higher heat transfer performance than conventional models. It also reduced refrigerant charge by about two-thirds, supporting lower environmental impact and improved safety. (Source: mitsubishielectric.com)
-
In October 2025, Shenshi introduced a PCHE-LNG heat exchanger specifically designed for the Fuel Gas Supply System (FGSS) sector. The unit features high compactness, efficient heat transfer, and excellent anti-freezing performance, making it ideal for offshore vessels with limited space. (Source: heat-exchanger-world.com)
-
In September 2025, Alfa Laval Aalborg Header-Coil A/S, a joint venture between Alfa Laval and Aalborg CSP, launched its first header-and-coil heat exchanger for large-scale thermal energy storage systems. The product offers high thermal efficiency, a compact design, and exceptional reliability under cyclic operating conditions. (Source: alfalaval.com)
Heat Exchanger Market Segmentation
By Product Outlook
-
Plate & Frame Heat Exchanger
-
Brazed Plate & Frame Heat Exchanger
-
Gasketed Plate & Frame Heat Exchanger
-
Welded Plate & Frame Heat Exchanger
-
Others
-
-
Shell & Tube Heat Exchanger
-
Air-Cooled Heat Exchanger
-
Cooling Towers
-
Others
By Material Outlook
-
Carbon Steel
-
Stainless Steel
-
Nickel Alloys
-
Others
By End Use Outlook
-
Oil & Gas
-
Chemical & Petrochemical
-
HVAC & Refrigeration
-
Food & Beverage
-
Power Generation
-
Pulp & Paper
-
Automobile
-
Pharmaceuticals
-
Data Centers
-
Others
By Regional Outlook
-
North America
-
US
-
Canada
-
-
Europe
-
Germany
-
France
-
UK
-
Italy
-
Spain
-
Netherlands
-
Russia
-
Rest of Europe
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Malaysia
-
South Korea
-
Indonesia
-
Australia
-
Rest of Asia Pacific
-
-
Middle East & Africa
-
Saudi Arabia
-
UAE
-
Israel
-
South Africa
-
Rest of the Middle East & Africa
-
-
Latin America
-
Mexico
-
Brazil
-
Argentina
-
Rest of Latin America
-
Heat Exchangers Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 19.92 billion |
| Market Size Value in 2026 | USD 21.28 billion |
| Revenue Forecast by 2034 | USD 36.39 billion |
| CAGR | 6.9% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Heat Exchangers Market FAQ's
The market size was valued at USD 19.92 billion in 2025 and is projected to grow to USD 36.39 billion by 2034.
The market is projected to register a CAGR of 6.9% from 2026 to 2034.
Asia Pacific accounted for the largest heat exchangers region-wise market share of 31.9% in 2025.
Key companies operating in the heat exchanger market include Alfa Laval, Kelvion Holding GmbH, SPX FLOW, Inc., Xylem Inc., Danfoss A/S, API Heat Transfer Inc., Guntner GmbH, Hamon & Cie International, Hindustan Dorr-Oliver Ltd., Hisaka Works, Ltd., Chart Industries, GE Vernova, GEA Group Aktiengesellschaft, Johnson Controls, Mersen, Modine Manufacturing Company, Boyd, IHI Plant Services Corporation, Tranter, Inc., SWEP International AB, Thermax Limited, and Shenshi.
The shell & tube heat exchanger segment accounted for the largest heat exchangers market share of 32.8% in 2025.
The chemical & petrochemical segment accounted for the largest heat exchangers market share of 22.1% in 2025.
A heat exchanger is a device that transfers heat from one fluid to another without mixing them. It is used to heat or cool liquids and gases in industrial, commercial, and energy applications.
The main types include shell & tube, plate & frame, air-cooled, and cooling tower systems. Each type is designed for different temperature, space, and operating requirements.
Shell & tube heat exchangers use tubes inside a larger shell, while plate heat exchangers use a series of thin plates. Plate systems are generally more compact, while shell & tube systems are widely used for high-pressure and heavy industrial applications.
Air-cooled heat exchangers use air to remove heat, while water-cooled systems use water as the cooling medium. Air-cooled systems reduce water use, whereas water-cooled systems can provide efficient cooling where sufficient water is available.
Heat exchangers are widely used in oil & gas, chemical & petrochemical, HVAC & refrigeration, food & beverage, power generation, pharmaceuticals, automotive, and pulp & paper industries.
Download Sample Report of Heat Exchangers Market
Please fill out the form to request a customized copy of the research report.