Hydrogen Hubs Market Share, Size, Trends, Global Report,2026-2034
REPORT DETAILS
Hydrogen Hubs Market Summary
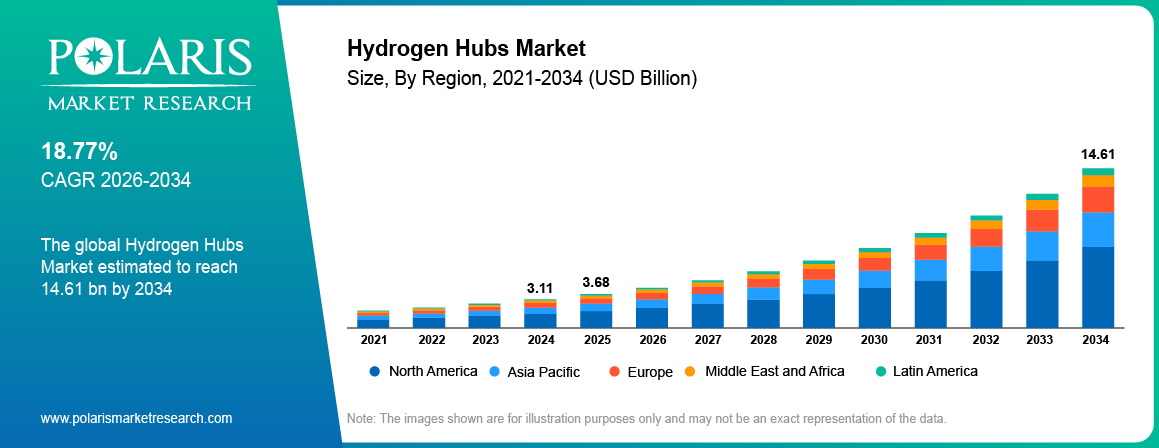
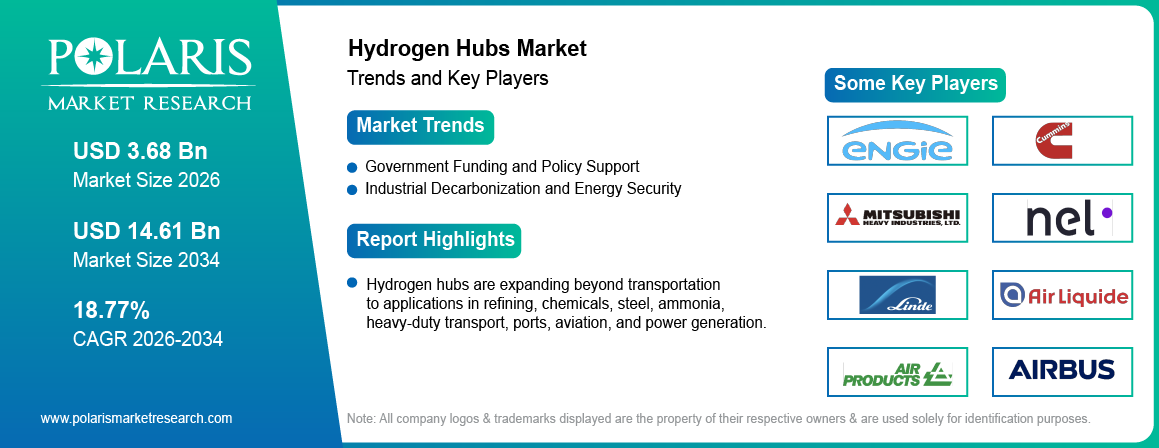
Hydrogen Hubs Market size was valued at USD 3.11 billion in 2025. The market is anticipated to grow from USD 3.68 billion in 2026 to USD 14.61 billion by 2034, exhibiting a CAGR of 18.77% during the forecast period.
Market Statistics
Hydrogen Hubs Market Key Takeaways
- North America dominated, accounting for 35.0% of the market in 2025, supported by government initiatives and hydrogen infrastructure.
- Asia Pacific is the fastest-growing region, registering a 18.00% CAGR, driven by rising hydrogen demand and investments.
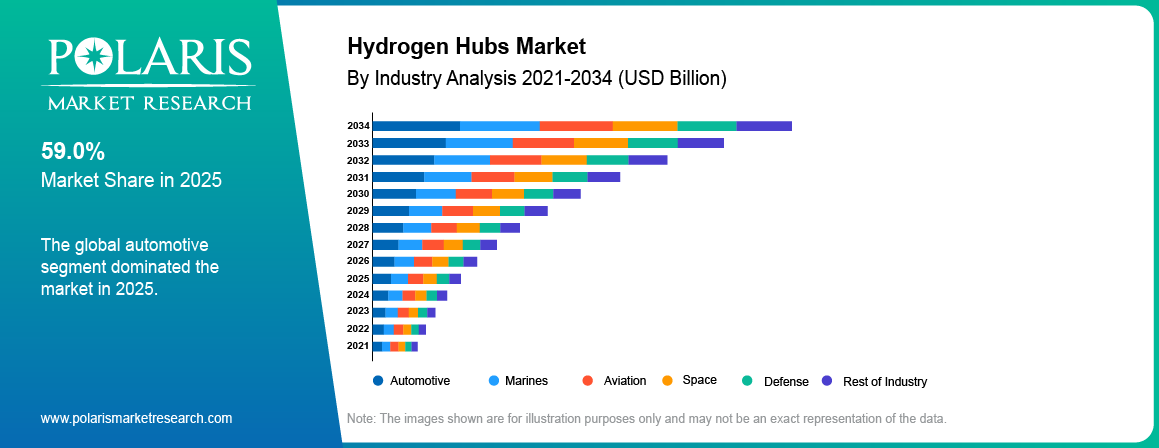
- In 2025, the automotive industry held the largest share of 59.0% of the market supported by hydrogen vehicle adoption
- Electrolysis is the fastest-growing supply technique, registering an 17.60% CAGR, driven by green hydrogen production.
- Hydrogen fuel cells are expected to hold the highest revenue share, registering a 17.50% CAGR. The share is supported by transportation and backup power applications.
- Liquid hydrogen revenue share was 58.0% in 2025, driven by long distance transport and large scale storage.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Are Hydrogen Hubs?
A hydrogen hub refers to a geographic area or industrial complex where various hydrogen-related activities are concentrated, promoting an integrated and collaborative ecosystem for the production, distribution, storage, and consumption of hydrogen. These hubs are crucial components of the emerging hydrogen economy, which aims to utilize hydrogen as a clean and sustainable energy carrier. Hydrogen can be used in various applications, including fuel cells for vehicles, industrial processes, and power generation. Hydrogen is typically stored as compressed gas or in liquid form.
Continuous research and development efforts are essential within hydrogen hubs to advance technologies, improve efficiency, and reduce costs associated with hydrogen production and utilization. Hydrogen hubs are seen as strategic initiatives to accelerate the adoption of hydrogen as a clean energy source. They bring together industry, government, and research organizations to collaborate on developing the necessary infrastructure and technologies. The success of hydrogen hubs depends on a combination of technological advancements, supportive policies, and collaboration across various sectors.
For instance, in 2025, the U.S. Department of Energy continued funding its Regional Clean Hydrogen Hubs program. The selected hubs support hydrogen production, storage, distribution, and end use applications across different regions (Source: www.energy.gov).
However, Hydrogen hubs need robust storage infrastructure to ensure a steady supply for different applications. The concept of hydrogen hubs is gaining attention globally as countries seek to transition to cleaner energy sources and reduce carbon emissions. Governments, industries, and research institutions are exploring ways to create and develop such hubs to foster the growth of the hydrogen economy. Increasing government initiatives increases the market demand for hydrogen hubs and thus anticipates growing hydrogen hubs' market share during the forecast period.
Furthermore, green hydrogen is utilized as a feedstock in industries such as chemicals and refining, reducing carbon emissions in sectors that are challenging to electrify, which increases the opportunities in the hydrogen hubs market.
How Do Hydrogen Hubs Work?
In one geographic area hydrogen hubs connect different parts of the hydrogen supply chain. Hydrogen is generated in various ways, such as electrolysis or steam methane reformation. It is then conditioned and stored before being shipped to consumers by pipelines, trucks or other means of delivery. Storage provides a reliable supply of hydrogen when production and demand are not aligned.
Sectors such as refining, chemicals, steel, transportation, and power generation can be served by hydrogen hubs. They can also include fueling stations, export terminals, and backup power systems. Through the integration of production, storage, distribution, and end use hydrogen hubs can improve the efficiency of infrastructure and enable the broader expansion of the hydrogen economy.
Hydrogen Hubs Market Dynamics
Market Driver- Government Funding and Policy Support
Government funding is supporting the development of hydrogen hubs. The U.S. Department of Energy has allocated $8 billion for Regional Clean Hydrogen Hubs. The program selected seven hubs to support clean hydrogen production and use. Federal incentives also include a production tax credit of up to $3 per kg of hydrogen. These measures are supporting reduce investment barriers and support new hydrogen projects.
Market Driver- Industrial Decarbonization and Energy Security
As industries grow for cleaner energy and more secure supply options, hydrogen is gaining attention. The Hydrogen Council reported $130 billion in committed clean hydrogen investment across more than 570 projects in 2026. Across different sectors these projects cover production and applications. Growing investment can support hydrogen hubs by connecting producers with industrial users, transport operators, and power projects.
Market Opportunity- Expansion of Hydrogen Production and End-Use Projects
For integrated hubs the expansion of hydrogen projects creates opportunities. In 2025, the European Hydrogen Bank received bids representing around 6.3 GW of electrolyzer capacity and more than 7.3 million tonnes of renewable hydrogen production over 10 years. Such projects can stimulate demand for storage, transport, distribution and end-use infrastructure around hydrogen production sites.
Market Opportunity- Development of Hydrogen Infrastructure
Investment in dedicated infrastructure is creating opportunities for companies involved in pipelines, storage, and distribution. Germany approved a 9,040-kilometer hydrogen core network, with expected investment of €18.9 billion. Around 60% of the network will use converted natural gas pipelines. The same infrastructure projects can connect hydrogen production sites with industrial users and other demand centers.
Market Restraint- Infrastructure, Storage and Transport Constraints
High infrastructure requirements remain a challenge for hydrogen hubs. Hydrogen needs special systems to store, move and distribute it, which can raise project costs. Germany’s approved hydrogen network alone needs an investment of €18.9 billion (around USD 22 billion). About 40% of its 9,040-kilometer network needs new pipelines, showing the scale of infrastructure needed for large hydrogen systems.
Hydrogen Hub Infrastructure and Value Chain
Within an integrated ecosystem hydrogen hubs connect production, storage, transportation, distribution, and end-use activities. This infrastructure allows the transport of hydrogen from production to industrial, mobility and energy applications. The value chain can include electrolysis or reforming plants, storage systems, pipelines, trucks, fueling stations and end-use facilities.
Production
Hydrogen can be produced through electrolysis or steam methane reforming. Electrolysis uses electricity to split water into hydrogen and oxygen and can produce green hydrogen when powered by renewable energy. Reforming uses natural gas as a feedstock. Production facilities are often located close to renewable energy sources or major hydrogen users.
Storage and Conversion
To maintain a reliable supply hydrogen needs storage systems. It can be stored as compressed gas or liquid hydrogen. Conversion systems may also be used to transport hydrogen in different forms. Hydrogen production and demand are balanced by storage capacity.
Transportation and Distribution
Hydrogen can be transported through pipelines, trucks, and other distribution systems. For larger and continuous supply networks pipelines are suitable, while trucks can serve locations without pipeline connections. Distribution infrastructure connects hydrogen production and storage facilities with industrial users, fueling stations, and other demand centers.
End-Use Integration
Hydrogen hubs connect supply with multiple end-use applications. These include refining, chemicals, steel, heavy-duty transportation, power generation, and backup power. Integrating different users can create stable hydrogen demand and improve the use of shared hub infrastructure.
Hydrogen Hub Architecture
| Component | Role in a Hub | Main Technologies/Assets | Main Uses |
| Production | Produces hydrogen for nearby or connected users. | Electrolysis, SMR, low-carbon production | Industry, transport, power |
| Storage | Stores hydrogen and supports a steady supply. | Compressed gas, liquid hydrogen, storage tanks | Peak demand, backup power, transport |
| Transportation | Moves hydrogen from production sites to users. | Pipelines, tube trailers, liquefaction | Regional and long-distance supply |
| Distribution | Supplies hydrogen to end users. | Fueling stations, pipelines, terminals | Trucks, buses, ports, industry |
| End Use | Uses hydrogen in different applications. | Fuel cells, industrial furnaces, refining, ammonia, power systems | Industry, transport, power, exports |
Source: Polaris Market Research Analysis
Hydrogen Hubs Market by Segment
By Industry Insights
Based on industry analysis, the market is segmented on the basis of automotive, marines, aviation, space, and defense. In 2025, the automotive segment accounted for the 59.0% largest market share. It is also anticipated that the automotive sector will be a major supplier and user of hydrogen and hydrogen fuel cell stacks inside hubs. In light of the increased emphasis on decarbonization and the search for sustainable substitutes, hydrogen presents itself as a viable option for fuel cell technology-based vehicle fuel. The growing market for hydrogen hubs is being driven by the automotive industry, which is a key user and contributor due to its growing demand for hydrogen-based vehicles and the developments in fuel cell stack technology. It is expected that the automotive sector will see significant investments, partnerships, and innovations during the projected timeframe, which will facilitate the smooth adaptation of H2 Hubs into the larger context of clean and efficient transportation. This shows a significant increase in the market size of the hydrogen hub market.
The aviation segment is projected to grow at a 18.60% CAGR during the forecast period. Hydrogen can support the aviation industry as it looks for lower-carbon fuel options. Hydrogen hubs can provide the infrastructure for production, storage and distribution for aviation-related applications. Liquid hydrogen is also being considered for aircraft as it can offer a high energy content by weight. More research, investment and partnerships in hydrogen powered aviation may create further opportunities for hydrogen hubs.
By End-use Insights
Based on end-use analysis, the market has been segmented on the basis of liquid hydrogen and hydrogen fuel cells. In 2025, the liquid hydrogen segment accounted for 58.0% of the market revenue. Liquid hydrogen is important for storing and transporting hydrogen over long distances. Its high energy density by volume makes it useful where large amounts of hydrogen need to be moved or stored. It is also being explored for aviation, space applications, and other industries that require hydrogen in a compact form. Across different industrial and transportation applications the development of regional green hydrogen hubs can further support liquid hydrogen production, storage, and distribution.
The hydrogen fuel cells are expected to witness the highest revenue share during the forecast period, accounting for 17.50% of the market revenue. Its efficiency and benefits to the environment, hydrogen fuel cells are essential for supplying industrial backup power as well as powering a variety of transportation modes.
By Supply Technique Insights
Based on Supply Technique analysis, the market is segmented on the basis of steam methane reforming and electrolysis. In 2025, the steam methane reforming segment accounted for 61.0% of the market revenue. Steam methane reforming is a well-established method for producing hydrogen from natural gas. It is widely used because of its mature technology and established infrastructure. Within hydrogen hubs, SMR facilities can supply hydrogen to industrial users, transportation applications, and other connected facilities. The use of carbon capture and storage can also help reduce emissions from SMR-based hydrogen production.
During the forecast period the electrolysis segment is projected to grow at a 17.60% CAGR. Electrolysis produces hydrogen by splitting water into hydrogen and oxygen using electricity. Green hydrogen can be produced with a lower carbon intensity via electrolysis from renewable electricity. Hydrogen hubs can couple electrolysis to renewable sources of energy and connect production with storage, transport and end-use facilities. Growing investment in clean hydrogen projects is expected to support the uptake of electrolysis.
Hydrogen Hub Applications by Segment
| Segment | Demand Driver | Infrastructure Need | Example Use Case |
| Automotive / Road Mobility | Zero-emission transport and fleet requirements | Hydrogen production, storage, dispensing, and fueling stations | Fuel-cell buses and passenger/commercial fleets |
| Heavy-Duty Trucking | Long-haul range and fast refueling requirements | High-throughput fueling and regional hydrogen supply | Hydrogen truck corridors |
| Marine / Ports | Port decarbonization and marine fuel transition | Port storage, production, and bunkering/distribution | Port equipment and marine fuel |
| Aviation | Lower-carbon aviation fuel and future hydrogen aircraft | Liquid hydrogen, synthetic fuels, and airport infrastructure | Airport-linked hydrogen systems |
| Industrial | Decarbonization of refining, chemicals, steel, and fertilizers | Large-scale production, pipelines, and storage | Hydrogen feedstock and process fuel |
| Power / Backup | Dispatchable clean energy and resilience | Storage, fuel cells/turbines, and grid connection | Backup generation and grid balancing |
Source: Polaris Market Research Analysis
Regional Insights
North America
North America dominated the largest market share in 2025, accounting for 35.0% of the market share. North America emerged as the dominant force in the global hydrogen hubs market, showcasing robust growth and leadership in the transition towards a hydrogen-based economy. The region's prominence in this market is attributed to the development of hydrogen infrastructure. First and foremost, a supportive policy environment and strategic government initiatives played a pivotal role in incentivizing investments and accelerating the deployment of hydrogen hubs.
Additionally, Hydrogen hubs contribute to the development of a hydrogen infrastructure for FCEVs (fuel cell electric vehicles) in North America. They support the growth of hydrogen-powered transportation, including buses, trucks, and potentially passenger vehicles. The development of hydrogen hubs in North America involves collaboration among government agencies, industry players, research institutions, and technology providers. This collaborative approach fosters innovation, accelerates technology advancements, and supports the growth of the hydrogen economy.
Asia Pacific
The Asia Pacific hydrogen hubs market is anticipated to witness the fastest growth during the forecast period, registering a 18.00% CAGR. Growth is supported by the region’s focus on decarbonization, deployment of renewable energy and development of a hydrogen-based economy. Robust policy frameworks, including substantial investments, incentives, and regulatory support, created a conducive environment for the development of hydrogen hubs. The significant advancements in renewable energy technologies, particularly solar and wind power, played a crucial role in the production of green hydrogen through cost-effective electrolysis. The region's increasing focus on decarbonizing industries, such as manufacturing and transportation, fueled a growing demand for hydrogen, further stimulating the establishment of hydrogen hubs, which anticipates the hydrogen hubs market growth during the forecast period.
Europe
The Europe hydrogen hubs market held 27.0% share in 2025, supported by government policies, clean energy targets, and investments in hydrogen infrastructure. Countries such as Germany, France, the UK, and the Netherlands are developing hydrogen projects that connect production, storage, transport, and industrial demand. The region is also focusing on renewable hydrogen production through electrolysis. Growing demand from industries such as chemicals, refining, steel, and transportation is expected to support the development of integrated hydrogen hubs.
Latin America
As countries increase their focus on renewable energy and clean hydrogen production the Latin America hydrogen hubs market is developing with 16.10% CAGR. Brazil, Mexico, and Argentina have strong renewable energy potential that can support hydrogen projects. Hydrogen hubs can link renewable electricity, electrolysis, storage, transportation and industrial users. The region also has opportunities to expand hydrogen for exports, heavy transport, refining and other industrial applications as infrastructure and investment continue to grow.
Middle East & Africa
The Middle East & Africa hydrogen hubs market is witnessing 19.30% CAGR, driven by investments in clean energy, large-scale hydrogen projects, and the region’s abundant renewable energy resources. Saudi Arabia and the UAE are developing hydrogen projects focused on production and export opportunities. In Africa, renewable energy resources can support green hydrogen production for domestic industries and international markets. Across the region, development of pipelines, storage facilities, ports and export terminals can further support integrated hydrogen hubs.
Hydrogen Hubs Use Cases
| Use Case | Role of Hydrogen Hubs |
| Industrial Feedstock and Refining | Supplies hydrogen for refining processes and industrial feedstock. |
| Steel, Ammonia and Chemicals | Supports low-carbon steel production, ammonia, and chemical manufacturing. |
| Heavy-Duty Mobility and Hydrogen Trucks | Provides hydrogen for trucks and other heavy-duty transport applications. |
| Hydrogen Fueling Stations and Ports | Supports hydrogen fueling for vehicles, port equipment, and marine applications. |
| Power Generation and Backup Power | Provides hydrogen for power generation, backup systems, and energy storage. |
| Hydrogen Export Terminals | Supports hydrogen storage, handling, and export to international markets. |
Source: Polaris Market Research Analysis
Hydrogen Hub Funding Status and Major Projects
Hydrogen hub development is receiving support through government funding, infrastructure investments, and large-scale clean hydrogen projects. The U.S. Regional Clean Hydrogen Hubs program supports projects in multiple regions and international projects are expanding hydrogen production, transport, storage, and end-use applications.
U.S. Regional Clean Hydrogen Hubs Funding Tracker
| Hydrogen Hub | Region | Federal Funding | Funding Status | Key Applications |
| Appalachian H2Hub (ARCH2) | Ohio, Pennsylvania, West Virginia | Up to $925 million | Phase 1 funding announced | Heavy-duty transport and industry |
| California H2Hub (ARCHES) | California | Up to $1.2 billion | Phase 1 funding announced | Public transit, heavy-duty transport, ports |
| Pacific Northwest H2Hub (PNWH2) | Washington, Oregon, Montana | Up to $1.0 billion | Phase 1 funding announced | Transport, ports, power, refining |
| Gulf Coast H2Hub (HyVelocity) | Texas | Up to $1.2 billion | Awarded | Transport, power, ammonia, refining |
| Midwest H2Hub (MachH2) | Illinois, Indiana, Iowa, Michigan | Up to $1.0 billion | Awarded | Steel, glass, refining, power, transport |
| Heartland H2Hub | North Dakota and surrounding states | Up to $925 million | Phase 1 funding announced | Fertilizer and power generation |
| Mid-Atlantic H2Hub (MACH2) | Pennsylvania, Delaware, New Jersey | Up to $750 million | Phase 1 funding announced | Transport, power, industrial applications |
Source: U.S. Department of Energy (DOE), Regional Clean Hydrogen Hubs Program and official H2Hub funding announcements.
Selected International Hub Examples
Europe is developing hydrogen hubs and corridors that connect renewable hydrogen production with industrial and transportation demand. Germany, for example, is developing hydrogen infrastructure that can connect production facilities with industrial users through a dedicated hydrogen network.
Hydrogen projects are also expanding across Northern Europe. Planned hydrogen corridors can connect production centers with ports and industrial regions, supporting cross-border hydrogen transportation. Such projects can help to create links between hydrogen production, pipelines, storage and end users.
International projects are also targeting specific applications such as maritime transport and aviation. Renewable hydrogen can also be used for marine fuel, sustainable aviation fuel and other industrial applications. The development of these projects reflects the growing role of hydrogen hubs in connecting production with a range of end-use sectors
| Project / Hub | Region | Key Development | Main Application |
| H2HubEmden | Germany | 200 MW electrolyzer planned to produce renewable hydrogen and supply the hydrogen core network | Industry and district heating |
| Nordic-Baltic Hydrogen Corridor | Northern Europe | Around 2,492 km of planned hydrogen pipelines connecting six countries | Cross-border hydrogen transport |
| ITAHB | Italy / North Africa–Europe | Around 1,920 km of hydrogen pipelines planned, with more than 60% using repurposed infrastructure | Hydrogen imports and regional distribution |
| Gen2-LH2 | Norway | Selected under the 2025 EU Hydrogen Auction for electrolytic renewable hydrogen supplied to maritime/aviation users | Maritime and aviation |
| RogalandH2 | Norway | Selected under the 2025 EU Hydrogen Auction for renewable hydrogen production | Maritime and aviation |
Source: Polaris Market Research Analysis
Competitive Landscape
The hydrogen hubs market is characterized by intense competition, with established players relying on advanced technology, high-quality products, and a strong brand image to drive revenue growth. These companies employ various strategies such as research and development, mergers and acquisitions, and technological innovations to expand their product portfolios and maintain a competitive edge in the market.
Linde plc is a major industrial gas company with activities across the hydrogen value chain. The company provides hydrogen production, processing, storage, distribution, and fueling solutions. It operates hydrogen plants and fueling stations and is also developing electrolysis projects for low-carbon hydrogen production. Linde's integrated capabilities support hydrogen hubs by connecting hydrogen production with industrial, mobility, and energy applications.
Shell plc is involved in hydrogen production, infrastructure, and end-use applications. The company is developing integrated hydrogen projects that connect production with storage, transportation, fueling, and industrial customers. Shell has also worked on hydrogen hubs and projects supporting heavy-duty transportation and industrial decarbonization. Its activities across different parts of the hydrogen value chain support the development of integrated hydrogen hub ecosystems.
Some of the major market key players operating in the global market include:
- Air Liquide
- Air Products and Chemicals, Inc.
- Airbus
- Cummins Inc.
- ENGIE
- Linde plc
- Mitsubishi Heavy Industries, Ltd.
- Nel ASA
- Plug Power Inc.
- Saudi Aramco
- Shell plc
- Siemens Energy AG
- Sinopec Corp.
- Toyota Motor Corporation
Vendor Positioning
| Company | Position in the Hydrogen Hubs Market |
| Air Liquide | Hydrogen production, infrastructure, and mobility supply |
| Air Products and Chemicals, Inc. | Hydrogen production, supply, and industrial infrastructure |
| Cummins Inc. | Electrolyzers, fuel cells, and hydrogen powertrain solutions |
| Hyundai Motor Company | Fuel-cell mobility and hydrogen ecosystem solutions |
| Linde plc | Hydrogen production, supply, storage, and industrial applications |
| Nel ASA | Electrolyzer and hydrogen fueling technologies |
| Plug Power Inc. | Electrolyzers, hydrogen production, and infrastructure solutions |
| Shell plc | Integrated hydrogen production, infrastructure, and industrial applications |
| Sinopec Corp. | Hydrogen production and energy infrastructure |
| Toyota Motor Corporation | Hydrogen mobility, fuel cells, and stationary power applications |
Source: Polaris Market Research Analysis
Recent Developments
- September 2026: Moeve launched its €1 billion Onuba green hydrogen project in Spain, with more than €300 million in EU support and planned 2 GW electrolysis capacity. (Source: www.moeveglobal.com)
- September 2026: The Hydrogen Council reported more than $130 billion in global clean hydrogen investment across over 570 committed projects. (Source: hydrogencouncil.com)
- April 2026: The U.S. Department of Energy preserved nearly $5 billion in funding for five Regional Clean Hydrogen Hubs. (Source: www.mccormick.senate.gov)
- January 2026: The European Clean Hydrogen Partnership launched its 2026 call with €105 million for hydrogen research and innovation projects. (Source: clean-hydrogen.europa.eu)
Future Outlook
Hydrogen hubs are expanding beyond transportation to applications in refining, chemicals, steel, ammonia, heavy-duty transport, ports, aviation, and power generation. A key trend is the integration of hydrogen production, storage, transportation, and end-use facilities within shared infrastructure.
The market is also moving toward green hydrogen production through electrolysis, supported by renewable energy investments. Future hydrogen hubs are expected to aim on pipelines, storage, fueling stations, export terminals, and industrial clusters, supported by government funding and private investment.
Research Methodology
The hydrogen hubs market study uses secondary and primary research to estimate market size and growth. The market boundary covers integrated regional or geographic ecosystems that connect hydrogen production with storage, transportation, distribution, and end-use demand. Standalone hydrogen production, fueling stations, and individual hydrogen equipment markets are excluded.
Secondary research includes company filings, government funding announcements, project databases, regulatory documents, industry associations, and public project information. Primary research includes inputs from manufacturers, technology providers, infrastructure developers, utilities, industrial users, and other relevant market participants, where applicable.
The market is analyzed by industry, supply technique, end use, and region, with country-level estimates contributing to regional totals. Forecasts consider historical trends, project pipelines, policy support, infrastructure investment, hydrogen demand, and technology adoption. Data is validated through cross checking secondary information, primary inputs, and internal market models. Market size is presented in revenue terms, with CAGR calculated for the stated forecast period.
Hydrogen Hubs Market Segmentation
Hydrogen Hubs, Industry Outlook (Revenue - USD Billion, 2021 - 2034)
- Automotive
- Marines
- Aviation
- Space
- Defense
- Rest of Industry
Hydrogen Hubs, Supply Technique Outlook (Revenue - USD Billion, 2021 - 2034)
- Steam Methane Reforming
- Electrolysis
Hydrogen Hubs, End Use Outlook (Revenue - USD Billion, 2021 - 2034)
- Liquid Hydrogen
- Hydrogen Fuel Cells
Hydrogen Hubs, Regional Outlook (Revenue - USD Billion, 2021 - 2034)
- North America
- U.S.
- Canada
- Europe
- France
- Germany
- UK
- Italy
- Netherlands
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- Japan
- China
- India
- Malaysia
- Indonesia
- South Korea
- Australia
- Rest of APAC
- Latin America
- Brazil
- Mexico
- Argentina
- Rest of LA
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of MEA
Hydrogen Hubs Market Report Scope
| Report Attributes | Details |
| Market size value in 2025 | USD 3.11 billion |
| Market size value in 2026 | USD 3.68 billion |
| Revenue forecast in 2034 | USD 14.61 billion |
| CAGR | 18.77% from 2026 – 2034 |
| Base year | 2025 |
| Historical data | 2021 – 2024 |
| Forecast period | 2026– 2034 |
| Quantitative units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Segments Covered | By Industry, By Supply Technique, By End use, By Region |
| Regional scope | North America, Europe, Asia Pacific, Latin America, Middle East & Africa |
| Customization | Report customization as per your requirements with respect to countries, region, and segmentation. |
Source: Polaris Market Research Analysis
Hydrogen Hubs Market FAQ's
The global hydrogen hubs market size is expected to reach USD 14.61 billion by 2034
Key players in the market are ARAMCO, Shell plc., Linde plc, Airbus, Sinopec
North America contribute notably towards the global Hydrogen Hubs Market
Hydrogen Hubs Market exhibiting the CAGR of 18.77% during the forecast period
The Hydrogen Hubs Market report covering key segments are Industry, supply technique, end use and region.
Download Sample Report of Hydrogen Hubs Market
Please fill out the form to request a customized copy of the research report.