
Artificial Intelligence (AI) in Medical Imaging Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
AI in Medical Imaging Market Summary
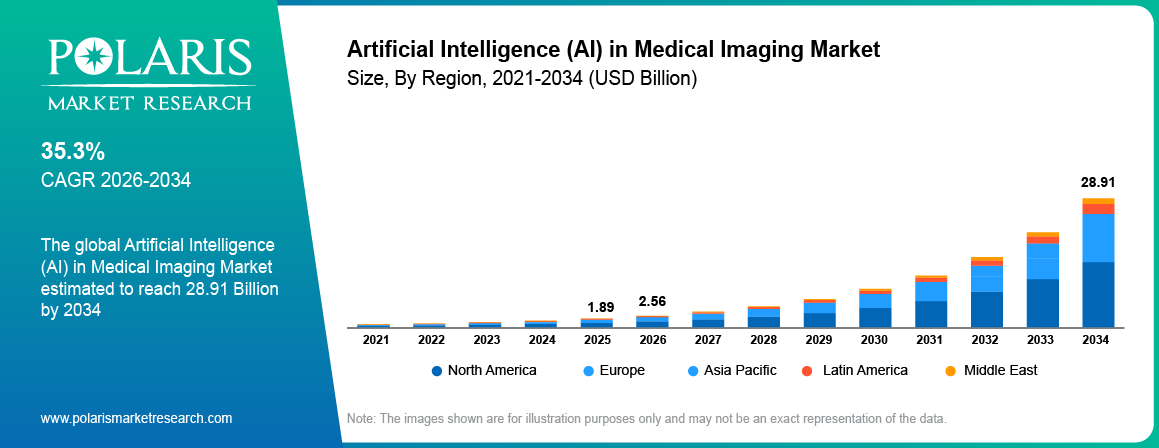
The AI in Medical Imaging market size was valued at USD 1.89 billion in 2025, growing at a CAGR of 35.3% from 2026 to 2034. The rising prevalence of chronic conditions and growing AI adoption in healthcare for improving accuracy and reducing operational costs are driving AI in medical imaging market growth.
Market Statistics
Key Takeaways
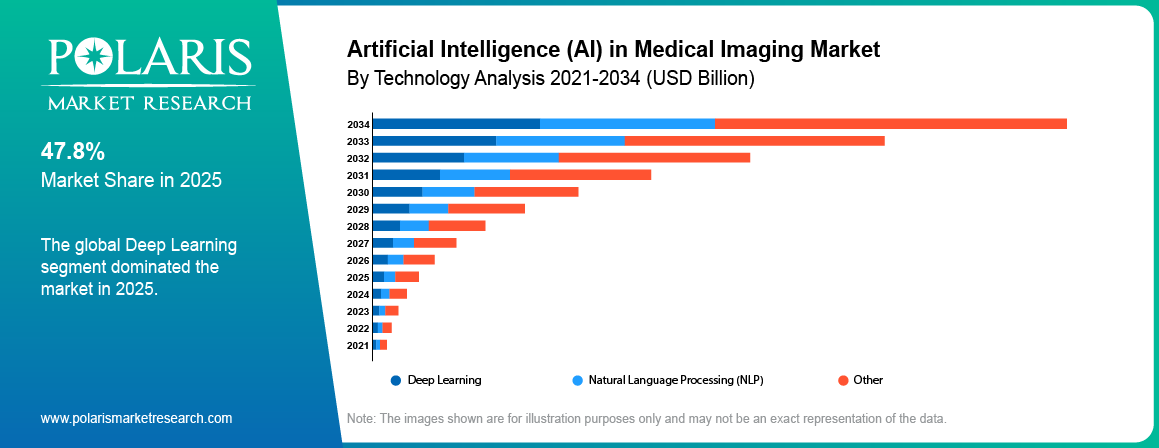
- North America accounted for the largest market share of 41.2% in 2025. The presence of advanced healthcare infrastructure and significant investments in R&D drive regional market dominance.
- Asia Pacific is projected to witness rapid growth at a 38.6% CAGR during the forecast period. The expanding healthcare sector and growing investments in AI technologies contribute to regional market growth.
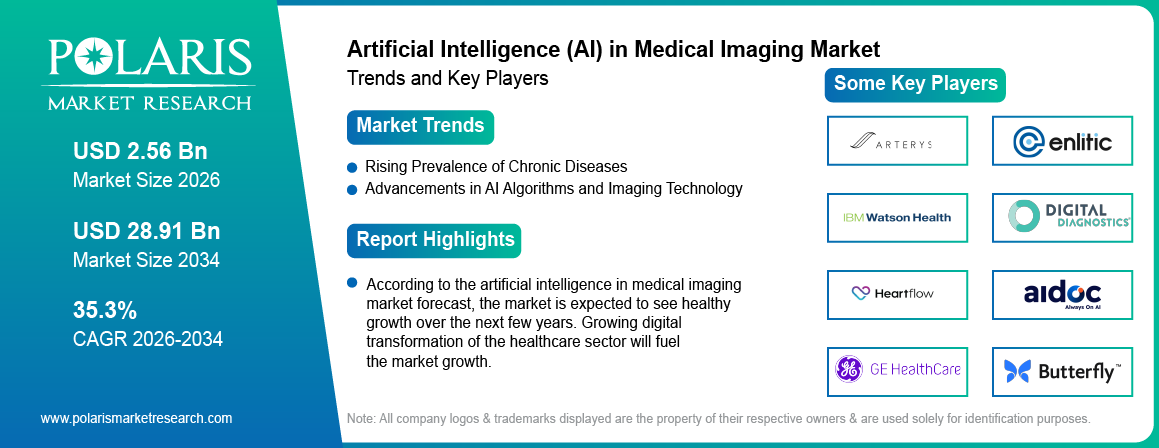
- The deep learning segment accounted for the largest market share of 47.8% in 2025. This is owing to its ability to analyze complex imaging data and identify patterns with high accuracy.
- The neurology segment is poised to register the fastest growth at a 39.4% CAGR during the forecast period. The segment’s growth is driven by the rising prevalence of neurological disorders.
- The CT scan segment led the market with a 32.6% share in 2025. This is due to its widespread use in diagnosing several medical conditions.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is AI in Medical Imaging?
Artificial intelligence in medical imaging involves the use of machine learning (ML), deep learning, and other AI technologies in medical imaging. AI integration improves diagnosis and enhances treatment planning. The increasing prevalence of chronic diseases and the growing need for advanced diagnostic solutions drive market expansion. Also, increasing adoption of AI in the healthcare industry fuels market development. Significant trends include the development of AI-powered imaging software and advancements in imaging equipment with embedded AI capabilities. The growing use of cloud-based AI platforms for image analysis will also fuel the growth. Additionally, regulatory support and increasing investments in AI-driven healthcare technologies are boosting the market growth.
How AI in Medical Imaging Works
AI in medical imaging works by analyzing medical images with advanced computer algorithms. First, the system is trained by using a large set of medical images such as X-rays, CT scans, MRIs, and ultrasounds. AI in radiology helps learn patterns and identify abnormalities in the images. Once the system has been trained, it is used to analyze new images. In a short time, it can detect possible problems. The doctor then looks over the AI results and makes a diagnosis.
AI vs Traditional Medical Imaging
| Dimension | AI-Assisted Imaging | Traditional Imaging |
| Interpretation speed | Automated pre-screening and triage; up to ~25% faster radiologist reporting in published studies | Fully manual read, sequential case-by-case review |
| Diagnostic consistency | Pattern-based detection reduces inter-reader variability | Relies on individual radiologist experience and fatigue level |
| Error/miss rate | Assists in reducing false negatives (e.g., improved negative predictive value in AI-assisted head CT triage studies) | Human error risk rises with caseload and shift length |
| Scalability | Cloud-based platforms scale across sites and support remote/telemedicine reads | Bound to on-site radiologist availability |
| Regulatory pathway | Requires FDA/CE clearance per algorithm and indication; evolving oversight | Established, well-understood regulatory pathway for imaging hardware |
| Cost profile | Upfront integration and licensing cost; subscription/cloud models lower entry cost | Lower software overhead; higher long-run labor cost per read |
Source: Polaris Market Research Analysis
Market Dynamics
Driver: Rising Prevalence of Chronic Diseases
The increasing global burden of chronic diseases, such as cancer, cardiovascular disorders, and neurological conditions, is driving the adoption of AI in medical imaging. According to the World Health Organization (WHO), noncommunicable diseases account for 74% of global deaths annually. Early detection and precision diagnosis are essential in controlling such diseases. AI-based imaging systems help in diagnosing anomalies more accurately than traditional systems. Thus, healthcare providers are adopting AI technology to meet the rising demand for proper and fast diagnosis. Hence, the growing incidence of chronic conditions propels the market growth (Source: who.int).
Driver: Advancements in AI Algorithms and Imaging Technology
Continuous advancements in AI algorithms, particularly in machine learning and deep learning, are transforming the medical imaging landscape. AI models are used to analyze vast datasets with high precision. They help identify subtle patterns in imaging results, providing faster interpretations. AI integration with imaging technologies, such as 3D imaging and 4D imaging, enables detailed and accurate visualization of complex anatomical structures. These technological advancements prompt healthcare institutions to adopt AI-integrated imaging systems. Hence, advancements in AI algorithms and imaging technology are expected to boost the market development.
Driver: Growing Integration of AI in Workflow Automation
The integration of AI into medical imaging workflows is addressing critical challenges such as radiologist shortages and increasing imaging volumes. AI systems streamline operations by automating various tasks such as image acquisition, pre-screening, and generating preliminary reports. Rise in the investment in AI systems to reduce radiologist workflow and dependency is further fueling the growth. For instance, in September 2026, Epsilon Health raise USD 28 million to launch AI in radiology solution which is AI Native group. These systems reduce diagnostic errors and allow radiologists to focus on complex cases, thereby improving overall productivity and patient outcomes. The push for operational efficiency in healthcare facilities is driving the adoption of AI-powered workflow automation in medical imaging. Therefore, the growing integration of AI in workflow automation propels the artificial intelligence in medical imaging market growth (Source: radiologybusiness.com).
Restraint: High Implementation and Integration Costs
Integrating artificial intelligence into medical imaging activities is associated with significant expenses. In particular, hospitals and clinics have to invest heavily in technology and software, hire professional IT and AI specialists, and train their employees in working with this technology. The process of integrating AI into established technologies and medical facilities is resource-intensive and requires a long period of adaptation and technical learning. Moreover, technology must be maintained and upgraded at all levels, which requires additional financial investments. Therefore, in most cases, small clinics and hospitals are extremely reluctant to implement such expensive and time-consuming initiatives.
Restraint: Data Privacy and Regulatory Complexity
Artificial intelligence in medical imaging is highly dependent on vast amounts of patient data. This contains confidential information of a person. Therefore, hospitals that provide their data for AI algorithms’ training need to protect such data from being vulnerable. In addition, AI medical technologies risk being unacceptable because of the significant paperwork required to authorize the technology's use for a person. Moreover, companies need to evolve according to the changing requirements.
Opportunity: Cloud-Based and Federated AI Imaging Platforms
Cloud-based and federated AI imaging platforms are significant growth areas for the market. Cloud-based platforms allow hospitals to adopt AI without having to make large capital expenditures on technology infrastructure. This makes it more accessible and cost-effective to them. Cloud-based storage and processing also facilitate faster data storage and image processing. Federated AI helps in building trust among medical institutions by ensuring that sensitive patient data is not shared during the model training process. The market is expected to grow due to the rising need for better computer-automated solutions as the healthcare industry adopts digitization and the need for secure and scalable AI-based imaging platforms increases.
Market Concentration & Characteristics
The market is moderately consolidated, as many big tech and healthcare companies are already strong players. Moreover, a number of new start-ups emerge and offer their own AI solutions. For example, Perceptra, a Thai-based startup, in August 2026 launched a medical AI system to improve patient screening. The market is competitive, as most of the companies aim to provide the best diagnostic results and work-flows and attract medical centers and imaging facilities as partners. Technical expertise and reliable medical data play an important role in the market, as a company needs to have great technology to work with. Additionally, healthcare regulations are often strict and may limit some potential entrants (Source: globenewswire.com).
Segment Insights
By Technology-Based Insights
The AI in medical imaging market, by technology, is segmented into deep learning, natural language processing (NLP), and other. The deep learning segment holds the largest market share of 47.8% in 2025, driven by its superior ability to analyze complex imaging data and identify patterns with high accuracy. For instance, in April 2026, FDA approved True Definition DL developed by GE healthcare. This uses deep learning in computed tomography. This technology is extensively utilized in detecting abnormalities, enhancing image quality, and predicting disease progression, making it indispensable in radiology and oncology. Deep learning algorithms have demonstrated significant advancements in precision diagnostics, as evidenced by their application in breast cancer screening, where studies report enhanced detection rates and reduced false positives. The widespread adoption of deep learning is further supported by its integration into advanced imaging modalities, such as CT and MRI, and its capability to handle large datasets efficiently (Source: gehealthcare.com).
The natural language processing (NLP) segment is projected to exhibit the highest CAGR of 39.1% over the forecast period. This is because it can derive actionable insights from unstructured clinical information such as radiology reports and medical histories. Using NLP in medical imaging accelerates work processes and boosts efficiency through automated annotation and decision support. It allows NLP in healthcare and life sciences to produce real-time diagnostic summaries. NLP also facilitates smooth communication and data sharing within healthcare networks, thereby improving collaboration between radiologists and clinicians. Thus, the adoption of NLP solutions in telemedicine and remote healthcare settings is contributing to its rapid growth.
By Application-Based Insights
The artificial intelligence in medical imaging market, by application, is segmented into oncology, neurology, respiratory & pulmonary, cardiology, breast screening, orthopedics, and others. The oncology segment dominated with 30.90% share in 2025 due to the high prevalence of cancer. AI can assist medical professionals in analyzing medical images more quickly and accurately by detecting and recognizing tumors at an early stage. It help detect subtle changes in images from scans. The high adoption of CT, MRI, and PET scanners in medical imaging is a major driver for the growth of the AI in segment. According to the Read My MRI, an estimated 375 - 450 million CT scans are performed annually worldwide. Additionally, the increased adoption of AI solutions for diagnosis and treatment across hospitals and significant healthcare expenditure on advanced medical imaging are anticipated to drive the segment growth (Source: readmymri.com).
The breast screening segment holds significant share of 20.4% in 2025, primarily due to the rising prevalence of breast cancer and the growing emphasis on early detection and screening programs. AI in cancer diagnostics are widely integrated into mammography systems to improve the accuracy of breast cancer detection, reduce false positives, and assist radiologists in identifying subtle abnormalities. According to the World Health Organization (WHO), breast cancer is the most common cancer among women globally, with over 2.4 million cases diagnosed annually. The widespread adoption of AI-based breast screening solutions is further propelled by government initiatives and public awareness campaigns promoting regular screenings.
The neurology segment is experiencing the highest growth of CAGR 39.4%, driven by the increasing prevalence of neurological disorders such as Alzheimer’s disease, stroke, and epilepsy. AI applications in neurology focus on advanced imaging techniques, such as MRI and CT, to enhance the detection and monitoring of brain anomalies. These technologies are also being utilized to predict disease progression and assist in surgical planning. For example, AI-powered tools are helping healthcare providers identify ischemic strokes more accurately and rapidly, thereby improving patient outcomes. The growing demand for precision diagnostics in neurology, coupled with advancements in AI algorithms tailored for brain imaging.
By Modalities-Based Insights
The artificial intelligence in medical imaging market, by modalities, is segmented into CT scan, MRI, X-rays, ultrasound, and nuclear imaging. The CT scan segment holds the largest market share of 32.6% in 2025, primarily due to its widespread use in diagnosing a variety of conditions, including trauma, cancer, and cardiovascular diseases. AI technologies are increasingly integrated into CT imaging systems to enhance image reconstruction, reduce scan times, and improve diagnostic accuracy. These advancements are particularly valuable in emergency settings, where rapid and precise diagnostic insights are critical. The segment's dominance is further supported by the growing adoption of AI-powered CT imaging in detecting early-stage diseases and its ability to process large volumes of imaging data efficiently.
The ultrasound segment is registering the highest growth of CAGR 38.4%, driven by its expanding applications in areas such as obstetrics, cardiology, and point-of-care diagnostics. AI integration in ultrasound imaging has revolutionized workflow efficiency by automating image acquisition and interpretation processes. For instance, in March 2026, FDA approves Ultrasound tool for detection of Gestational Age developed by Butterfly Network. Additionally, the portability and cost-effectiveness of AI-enabled handheld ultrasound devices are accelerating adoption, particularly in resource-constrained settings and telemedicine applications. These factors are driving the rapid growth of the ultrasound segment in the AI in medical imaging market (Source: diagnosticimaging.com).
By Deployment Mode Insights
The artificial intelligence in medical imaging market, by deployment mode, is segmented into on-premise, and cloud. The on-premise segment holds the largest market share of 64.2% in 2025, driven by hospitals that want direct control over their AI systems and patient data. Many healthcare providers already have internal IT systems, making on-premise solutions easier to integrate. Data security and privacy need further encourage adoption. Hospitals handling large volumes of medical images may prefer local systems for faster access. Growing concerns about data protection are further supporting demand for on-premise AI solutions in medical imaging.
The cloud segment is registering the growth of CAGR 36.3%, due to its flexibility and easy access. Hospitals can use AI tools without installing large systems on-site. This helps reduce setup and maintenance costs. Cloud solutions further make it easier to store and share medical images between doctors and healthcare facilities. Growing digital healthcare adoption is supporting demand. Better internet connectivity and the need for remote access are further driving the use of cloud-based AI in medical imaging.
By End Use-Based Insights
The AI in medical imaging market, by end use, is segmented into hospitals, diagnostic imaging centers, and others. The hospital segment dominates the artificial intelligence in medical imaging market with 48.9% share, driven by the high volume of imaging procedures performed and the availability of advanced healthcare infrastructure. Hospitals are increasingly adopting AI-powered imaging solutions to enhance diagnostic accuracy, streamline workflows, and manage the growing demand for imaging services. Additionally, the integration of AI technologies into hospital systems facilitates faster decision-making and improved patient outcomes. Government initiatives to equip public hospitals with advanced diagnostic tools and the presence of skilled professionals further fuels the growth.
The diagnostic imaging centers segment is experiencing the highest growth of CAGR 37.2%, fueled by their focus on providing specialized imaging services and adopting innovative AI solutions to enhance operational efficiency. These centers are leveraging AI technologies to offer faster and more accurate diagnostics, attracting a broader patient base. The demand for outpatient imaging services, coupled with the rising prevalence of chronic diseases, is encouraging diagnostic centers to invest in AI-powered modalities. Furthermore, the increasing preference for standalone imaging facilities due to shorter waiting times and cost-effective services is accelerating the demand in the market.
Real-World Use Cases
| Use Case | Clinical Goal | Named AI Product(s) & Company | Imaging Modality | Real-World Deployment / Evidence |
| Stroke triage & care coordination | Rapid detection of large vessel occlusion (LVO) and intracranial hemorrhage; faster notification and transfer to comprehensive stroke centers | Viz.ai (Viz LVO, Viz ICH); Aidoc (ICH/LVO modules); RapidAI; Brainomix e-Stroke | CT/CTA head | Viz.ai deployed in 2,000+ U.S. hospitals; associated with 11–25 min reductions in treatment times and 44% reduction in door-in-door-out transfer times for LVO stroke. Aidoc at Sheba Medical Center showed 30% reduction in mortality for intracerebral hemorrhage patients. |
| Breast cancer screening (mammography & tomosynthesis) | Improve cancer detection, reduce false positives/callbacks, support standalone or concurrent reading | Lunit INSIGHT MMG/DBT (Lunit); ProFound AI (iCAD); Transpara (ScreenPoint) | 2D mammography, digital breast tomosynthesis (DBT) | Lunit INSIGHT deployed at 330+ sites with >1M annual screenings; used for lesion detection and malignancy probability scoring. |
| Cardiac ultrasound quantification | Automated left ventricular ejection fraction (LVEF), global longitudinal strain, and chamber measurements | EchoGo Core/Pro (Ultromics); Caption Guidance & Interpretation (Caption Health); LVivo (DiA Imaging); EchoMD AutoEF (Bay Labs) | Echocardiography (cardiac US) | Multiple FDA-cleared tools in routine echo labs; Caption Guidance assists non-experts in acquiring diagnostic views; EchoGo and LVivo automate EF/strain quantification. |
| Thyroid nodule characterization | Quantify and classify thyroid nodules on ultrasound to support biopsy decisions | AmCAD-UT Detection (AmCAD BioMed); Koios DS (Koios Medical) | Thyroid ultrasound | FDA-cleared systems that analyze user-selected regions and output BI-RADS–aligned risk categories. |
| Pediatric hip dysplasia screening | Assist diagnosis of developmental dysplasia of the hip (DDH) via ultrasound | MEDO ARIA (Medo.ai) | Hip ultrasound | FDA-cleared for quantification and decision support in DDH diagnosis. |
| Bladder volume measurement | Automated 3D bladder volume estimation for urology and critical care | Auto 3D Bladder Volume Tool (Butterfly Network) | Bladder ultrasound | Integrated into Butterfly handheld systems for point-of-care volume reporting. |
| Vascular ultrasound analysis | Carotid intima-media thickness (IMT) and vessel wall segmentation for cardiovascular risk | AVA (Augmented Vascular Analysis) (See-Mode Technologies) | Carotid artery ultrasound | FDA-cleared for automated IMT measurement and vessel segmentation. |
| Emergency department radiology triage | Prioritize critical findings (PE, ICH, fractures, pneumothorax) and accelerate ED throughput | Aidoc (multi-algorithm platform); Viz.ai (multi-disease pathways) | CT, X-ray, MRI | Aidoc integrates with PACS/worklists to auto-prioritize urgent studies; reported faster alert generation and improved ED responsiveness. |
| Lung nodule detection & longitudinal tracking | Detect and monitor pulmonary nodules for lung cancer screening | AI modules within Viz.ai, Aidoc, and vendor-specific lung CT CAD tools | Chest CT | Practical deployments support nodule detection and follow-up tracking across screening programs. |
| Cardiovascular disease classification with biomechanics-informed AI | Provide interpretable biomarkers for cardiac tissue changes and CVD risk | Research-to-clinical pipelines (e.g., JRC-highlighted biomechanics-informed models) | Cardiac MRI/CT | Used to enhance interpretability of AI outputs for cardiologists. |
| Detect and grade cancer in whole-slide images (WSI); support screening and reporting | Paige Prostate (Paige AI); Ibex Galen Prostate (Ibex Medical Analytics); Lunit INSIGHT Pathology (Lunit) | Whole-slide imaging (WSI) | FDA-cleared AI assists pathologists with prostate cancer detection and grading on WSI; Ibex deployed in multiple hospital pathology labs for prostate and breast cancer workflows. |
Source: Polaris Market Research Analysis
Regional Insights
North America
By region, the study provides artificial intelligence in medical imaging market insights into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. North America AI in medical imaging market holds the largest share of 41.2% in 2025, attributed to the region's advanced healthcare infrastructure, early adoption of AI technologies, and significant investments in research and development. The presence of leading AI solution providers and a high prevalence of chronic diseases, such as cancer and cardiovascular disorders, further drive market growth in the region. Favorable regulatory frameworks and initiatives, such as the FDA's support for AI-based medical devices, have also encouraged the integration of AI into medical imaging workflows. Additionally, strong collaboration between healthcare institutions and technology companies in North America enhances the deployment of innovative AI solutions, solidifying the region's leadership in the market.
U.S.
The U.S. artificial intelligence in medical imaging market dominated with 59.22% share in North America in 2025. Hospitals are adopting AI-enabled solutions to transform and improve the decision-making process. The increased healthcare expenditure and high penetration of advanced technologies fuel the demand for AI in the healthcare industry. The growing adoption of computed tomography (CT), magnetic resonance imaging (MRI), and x-ray imaging systems among hospitals also escalates its demand. In addition, favorable government policies and rising R&D investment by major players support market growth. Shortage of medical personnels in the country further fuels the demand for advance technology such as AI in wide range of medical practices. According to the Health Resources and Services Administration National Center for Health Workforce, a shortage of 141,160 full-time physicians is estimated in the country by 2038. Moreover, the significant presence of major electronics and pharmaceutical companies further contributes to the market growth in the country. (Source: bhw.hrsa.gov)
Europe
Europe represents a significant market for artificial intelligence (AI) in medical imaging with 28.6% share in 2025, driven by the increasing adoption of advanced diagnostic technologies, rising adoption of digital pathology and a well-established healthcare infrastructure. The region benefits from strong government support and funding initiatives aimed at integrating AI into healthcare systems. Countries such as Germany, the UK, and France are at the forefront, leveraging AI for precision diagnostics and workflow optimization. Additionally, the growing focus on reducing healthcare costs and improving patient outcomes has encouraged the adoption of AI-enabled imaging solutions across public and private healthcare institutions.
Asia Pacific
The Asia Pacific AI in medical imaging market is experiencing rapid growth with CAGR of 38.6%, fueled by the expanding healthcare sector, rising prevalence of chronic diseases, and increasing investments in AI technologies. Countries such as China, Japan, and India are leading the region's adoption of AI, supported by advancements in healthcare infrastructure and government initiatives to promote AI-driven innovations. The growing demand for affordable diagnostic solutions in rural and underserved areas is also driving the development of AI-powered portable imaging devices, further boosting the artificial intelligence in medical imaging market expansion in the region.
Middle East & Africa (MEA)
The AI in medical imaging market in the Middle East and Africa is expected to witness growth of CAGR 32.8% driven by growing healthcare investments and a rapid digital transformation in the region. The increasing demand for modern equipment as well as the availability of capital in the United Arab Emirates and Saudi Arabia plays a major role in the development of the market. Moreover, an inadequate number of professional radiologists in certain countries is pushing the need for advanced solutions to ensure efficient and effective operations. The rising awareness of early disease detection and modern treatment methods, as well as the development of state-of-the-art healthcare facilities, supports the growth of the Middle East and Africa artificial intelligence in medical imaging market.
Latin America
The AI in medical imaging market in Latin America is expected to witness significant growth of CAGR 34.1% driven by the region's growing investment in digital health and the rising prevalence of chronic illnesses. The major countries in Latin America, including Brazil and Mexico, are witnessing a rising adoption of technologically advanced imaging equipment and AI-based analytical solutions. Moreover, the growing need for faster, smarter medical image interpretation and reduced radiologist workload due to an increased disease prevalence is expected to propel the market growth during the forecast period. The regional market expansion is also supported by increasing healthcare investments, as well as rising awareness about the benefits of AI-driven diagnostics and the need for accessible and affordable healthcare, which is expected to drive the adoption of AI in medical imaging across Latin America.
Key Players and Competitive Insights
A few key players in the artificial intelligence in medical imaging market include Siemens Healthineers AG; GE Healthcare; Philips Healthcare; IBM Watson Health; Medtronic; Canon Medical Systems Corporation; Butterfly Network, Inc.; Zebra Medical Vision; Vuno, Inc.; Arterys, Inc.; Aidoc; Lunit, Inc.; Qure.ai; and Viz.ai, Inc, Microsoft, NVIDIA Corporation, TEMPUS, Digital Diagnostics Inc., HeartFlow, Inc., and Enlitic, Inc. These companies are actively engaged in developing AI solutions for medical imaging, providing a range of products such as AI-powered diagnostic tools, imaging software, and advanced imaging systems. They continue to innovate and expand their market presence, focusing on integrating AI into radiology, oncology, cardiology, and neurology imaging applications.
The competitive landscape of the AI in medical imaging market is characterized by the strong presence of established companies with extensive research and development capabilities. Siemens Healthineers AG and GE Healthcare continue to dominate the market, investing in AI-powered imaging systems that enhance diagnostic accuracy and workflow efficiency. Additionally, smaller firms such as Aidoc and Qure.ai are gaining traction with their specialized AI solutions, providing radiologists with tools for faster and more accurate diagnoses. These companies are increasingly focusing on partnerships and collaborations with healthcare providers to enhance their product offerings and reach broader markets.
While large corporations lead in terms of technological advancements and infrastructure, smaller companies are contributing to the market growth by offering innovative and specialized solutions in areas such as radiology and cardiology. The competitive dynamics in the AI medical imaging space are also shaped by the increasing role of software-driven solutions and cloud platforms, with companies such as Arterys, Inc. and Lunit, Inc. capitalizing on the growing demand for cloud-based AI applications. As AI continues to gain acceptance in medical imaging, market players are focusing on improving the speed, accuracy, and accessibility of diagnostic imaging services, creating a more competitive and evolving landscape.
Siemens Healthineers AG, a global company specializing in medical technology, offers a range of products and services, including imaging systems, laboratory diagnostics, and point-of-care testing. They focus on developing technologies to improve patient care and streamline healthcare processes.
GE HealthCare is a company that provides medical imaging equipment, monitoring systems, and diagnostic technologies. They aim to support healthcare professionals in delivering quality care through their products and services.
FDA Approved Device Count by Companies
| Company | Estimated FDA AI Authorizations | Top / Flagship AI Product(s) in Medical Imaging |
| Aidoc | ~31–33 | Aidoc CARE (multi-disease triage platform for CT/MR/X-ray: ICH, PE, LVO, fractures, pneumothorax) |
| Butterfly Network, Inc. | ~5–10 | Auto 3D Bladder Volume Tool; AI-guided acquisition and auto-measurements on Butterfly IQ devices |
| Canon Medical Systems Corporation | ~45–51 | Advanced intelligent Clear-IQ Engine (AiCE) for deep-learning CT reconstruction; AI-based workflow and dose tools |
| Digital Diagnostics Inc. | ~1–2 | LumineticsCore (IDx-DR) for autonomous diabetic retinopathy detection from retinal images |
| GE Healthcare | ~120–134 | Deep Learning Image Reconstruction (DLIR/TrueFidelity); Edison AI apps for CT/MR/US; AIR Recon DL for MRI |
| HeartFlow, Inc. | ~1–2 | HeartFlow Analysis (CT-based coronary physiology; FFR-CT-like noninvasive coronary assessment) |
| Lunit, Inc. | ~10–20 | Lunit INSIGHT MMG/DBT (breast cancer detection); Lunit INSIGHT CXR (chest X-ray); INSIGHT Pathology (WSI) |
| Philips Healthcare | ~50–62 | IntelliSpace Portal AI apps; AI-enabled CT/MR reconstruction; EchoNavigator DeviceGuide for structural heart interventions |
| Qure.ai | ~5–10 | qER (intracranial hemorrhage triage on head CT); qCT (stroke LVO/ICH); qXR (chest X-ray TB/pneumonia triage) |
| Siemens Healthineers AG | ~89–101 | AI-Rad Companion (multi-modality); Deep Learning Reconstruction (DLR) for CT/MR; syngo.via AI-based workflow apps |
| Viz.ai, Inc. | ~15–25 | Viz LVO, Viz ICH, Viz SDH, Viz PE (AI triage and care coordination for stroke, hemorrhage, PE on CT/CTA) |
| Vuno, Inc. | ~5–10 | VUNO Med series (Brain, Chest, Spine, Liver AI for CT/MR/X-ray triage and quantification) |
| Zebra Medical Vision | ~5–10 | HealthPNX (pneumothorax detection on CXR); 100+ Chest (multi-finding CXR AI); rib/vertebral fracture AI on CT |
List of AI in Medical Imaging Companies
- Aidoc
- Arterys, Inc.
- Butterfly Network, Inc.
- Canon Medical Systems Corporation
- Digital Diagnostics Inc.
- Enlitic, Inc.
- GE Healthcare
- HeartFlow, Inc.
- IBM Watson Health
- Lunit, Inc.
- Medtronic
- Microsoft
- NVIDIA Corporation
- Philips Healthcare
- Qure.ai
- Siemens Healthineers AG
- TEMPUS
- Viz.ai, Inc.
- Vuno, Inc.
- Zebra Medical Vision
Vendor Positioning: Imaging Incumbents vs. AI-Native Specialists
| Vendor type | Representative players | Market positioning |
| Imaging-equipment incumbents | Siemens Healthineers, GE HealthCare, Philips Healthcare, Canon Medical Systems | Embed AI directly into imaging hardware and existing installed base; strongest in hospitals with large capital equipment budgets |
| Diversified technology / compute players | Microsoft, NVIDIA, IBM, Intel, AMD | Supply foundation models, compute infrastructure, and cloud platforms that imaging vendors and hospitals build on top of |
| AI-native specialists (diagnostic) | Aidoc, Lunit, Qure.ai, Viz.ai, Enlitic, HeartFlow, Digital Diagnostics | Focused, often single-modality or single-indication algorithms; fastest-moving on FDA clearances and point solutions |
| AI-native specialists (device/point-of-care) | Butterfly Network, Exo Imaging, EchoNous, Nano-X Imaging | Portable/handheld AI-enabled imaging devices targeting point-of-care and underserved settings |
Source: Polaris Market Research Analysis
Artificial Intelligence (AI) in Medical Imaging Industry Developments
- August 2026: Radiology Partners is expanding overseas. On August 25, it agreed to buy Everlight Radiology, a teleradiology group working with hospitals and imaging centers in the UK, Ireland, Australia, New Zealand and South Africa. Once regulators sign off, Everlight's radiologists should get access to Mosaic Drafting, Radiology Partners' AI tool for preliminary reports. (Source: radpartners.com)
- May 2026: GE HealthCare announced advancements in research tools and MR systems at the International Society for Magnetic Resonance in Medicine (ISMRM) 2026 Annual Meeting. The company revealed U.S. FDA 510(k) pending status of its latest deep-learning acceleration technique, Sonic DL for 2D imaging beyond cardiac cine. (source: gehealthcare.com)
- April 2026: Royal Philips announced receiving U.S. FDA 510(k) clearance for the Philips Spectral CT Verida system. The company stated that the clearance brings next-generation, AI-powered spectral CT innovation to the U.S. (source: usa.philips.com).
- March 2026: GE HealthCare closed its $2.3 billion purchase of Intelerad on March 18. The deal gives GE a stronger foothold in outpatient and ambulatory imaging, alongside its hospital business, and combines both companies' cloud and AI tools. (Source: gehealthcare.com)
- March 2026: Sectra agreed on March 5 to acquire Oxipit, a radiology AI developer based in Lithuania. (Source: oxipit.ai)
- March 2026: RadNet bought Paris-based Gleamer on March 2 and is folding it into DeepHealth, its AI subsidiary. RadNet says the combined business is now the world's largest provider of clinical AI for radiology. (Source: sec.gov)
- February 2026: Qure.ai received FDA clearance for qXR-Detect, which highlights findings on chest X-rays. The clearance includes a predetermined change control plan, so hospitals can receive model updates without a new submission each time. Qure.ai says no other cleared chest X-ray detection tool has one. The company now has 26 FDA-cleared indications across nine X-ray and CT products. (Source: businesswire.com)
- January 2026: Aidoc received FDA clearance on January 21 for a single tool that triages 14 urgent findings on abdominal CT scans, 11 of them newly cleared. It runs on CARE, Aidoc's in-house foundation model. In the study the FDA reviewed, the new indications averaged 97% sensitivity and 98% specificity. (Source: radiologybusiness.com)
Future Outlook
According to the artificial intelligence in medical imaging market forecast, the market is expected to see healthy growth over the next few years. The growing digital transformation of the healthcare sector will fuel the market growth. The expansion is also attributed to the growing requirement for early disease detection and developments in deep learning medical imaging. The integration of AI with cloud computing, generative AI, and automation is helping improve the process of diagnosis and imaging, and making operations more efficient in the healthcare organization. Furthermore, increasing adoption of AI-powered radiology applications by healthcare providers would help boost market growth. Looking ahead, AI will play an increasingly important role in medical imaging.
Artificial Intelligence (AI) in Medical Imaging Market Segmentation
By Technology Outlook
- Deep Learning
- Natural Language Processing (NLP)
- Other
By Deployment Mode Outlook
- Cloud
- On-Premise
By Application Outlook
- Oncology
- Neurology
- Respiratory & Pulmonary
- Cardiology
- Breast Screening
- Orthopedics
- Others
By Modalities Outlook
- CT Scan
- MRI
- X-rays
- Ultrasound
- Nuclear Imaging
By End Use Outlook
- Hospitals
- Diagnostic Imaging Centers
- Others
By Regional Outlook
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Artificial Intelligence (AI) in Medical Imaging Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 1.89 billion |
| Market Size in 2026 | USD 2.56 billion |
| Revenue Forecast by 2034 | USD 28.91 billion |
| CAGR | 35.3% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
How is the report valuable for an organization?
Workflow/Innovation Strategy
The market has been segmented into detailed segments of technology, application, modalities, and end use. Moreover, the study provides the reader with a detailed understanding of the different segments at both the global and regional levels.
Growth/Marketing Strategy
The artificial intelligence in medical imaging market growth and marketing strategy is focused on continuous innovation, strategic partnerships, and expanding customer bases. Companies are investing heavily in research and development to create advanced AI algorithms that improve diagnostic accuracy and operational efficiency. Collaborations with healthcare providers, research institutions, and technology firms are key to driving the adoption and integration of AI solutions in medical imaging. Additionally, companies are focusing on expanding their presence in emerging markets by offering cost-effective solutions and enhancing product accessibility through cloud-based platforms and portable devices. Marketing efforts are concentrated on educating healthcare professionals about the benefits of AI in improving patient outcomes and workflow optimization.
Artificial Intelligence (AI) in Medical Imaging Market FAQ's
The artificial intelligence (AI) in medical imaging market size was valued at USD 1.89 Billion in 2025 and is projected to grow to USD 28.91 Billion by 2034.
The market is projected to register a CAGR of 35.3% during the forecast period.
North America accounted for the largest market share of 41.2% in 2025, driven by strong market demand and advanced infrastructure.
A few key players in the AI in medical imaging market include Siemens Healthineers AG, GE HealthCare, Philips Healthcare, and Canon Medical Systems Corporation, which embed AI into their imaging hardware. AI-native specialists include Aidoc, Lunit, Inc., Qure.ai, Viz.ai, Inc., HeartFlow, Inc., Enlitic, Inc., Digital Diagnostics Inc., Vuno, Inc., and Butterfly Network, Inc. Technology companies such as Microsoft, NVIDIA Corporation, and TEMPUS provide the foundation models, compute, and cloud platforms that imaging AI runs on.
The deep learning segment accounted for the largest market share of 47.8% in 2025, driven by its increasing adoption across various applications.
The breast screening segment accounted for the largest market share of 31.7% in 2025.
Artificial intelligence (AI) in medical imaging refers to the use of machine learning, deep learning, and other AI technologies to enhance the analysis, interpretation, and processing of medical images. AI systems are designed to assist healthcare professionals in diagnosing and treating various conditions by providing faster, more accurate results. These technologies can identify patterns, detect abnormalities, and even predict disease progression from medical imaging data, such as X-rays, MRIs, CT scans, and ultrasounds. AI in medical imaging aims to improve diagnostic accuracy, reduce human error, enhance workflow efficiency, and enable earlier detection of diseases, ultimately contributing to better patient outcomes.
A few key trends in the market are described below: Integration of AI in Radiology Workflows: Increasing adoption of AI technologies to streamline workflows, automate routine tasks, and improve efficiency in radiology departments. AI-Powered Diagnostic Tools: Development of AI-driven solutions to assist in diagnosing a wide range of diseases, such as cancer, neurological disorders, and cardiovascular conditions. Cloud-Based AI Solutions: Growing preference for cloud platforms that enable scalable and accessible AI tools for remote diagnosis and collaboration. Personalized Medicine: AI's role in tailoring treatments based on specific patient data and imaging results, improving the precision of care.
A new company entering the artificial intelligence in medical imaging market should focus on developing AI solutions that enhance real-time diagnostics and automate workflows to improve efficiency for healthcare providers. Emphasizing the integration of AI with cloud-based platforms can offer scalability and accessibility, making solutions more cost-effective and attractive to hospitals and diagnostic centers. Additionally, targeting emerging markets with portable, affordable AI imaging devices can help the company expand its reach. Focusing on niche applications, such as early disease detection or personalized medicine, can also differentiate the company from competitors and address specific healthcare needs. Furthermore, forging partnerships with established healthcare providers and regulatory bodies will ensure faster adoption and credibility in the market.
A few key players in the AI in medical imaging market include Aidoc, Butterfly Network, Inc., Canon Medical Systems Corporation, Digital Diagnostics Inc., Enlitic, Inc., GE Healthcare, HeartFlow, Inc., Lunit, Inc., Medtronic, Microsoft, NVIDIA Corporation, Philips Healthcare, Qure.ai, Siemens Healthineers AG, TEMPUS, Viz.ai, Inc., Vuno, Inc., and Zebra Medical Vision (Nano-X Imaging).
The market is growing due to rising demand for faster diagnosis, increasing adoption of advanced healthcare technologies, and a growing need to improve radiology workflows.
High implementation costs, data privacy concerns, regulatory complexity, and limited access to high-quality medical data are major challenges for the market.

Download Sample Report of Artificial Intelligence (AI) in Medical Imaging Market
Please fill out the form to request a customized copy of the research report.


