Global Electric Vehicle (EV) Charging Infrastructure Market Size, Share Analysis Report, 2026–2034
REPORT DETAILS
Electric Vehicle (EV) Charging Infrastructure Market Summary
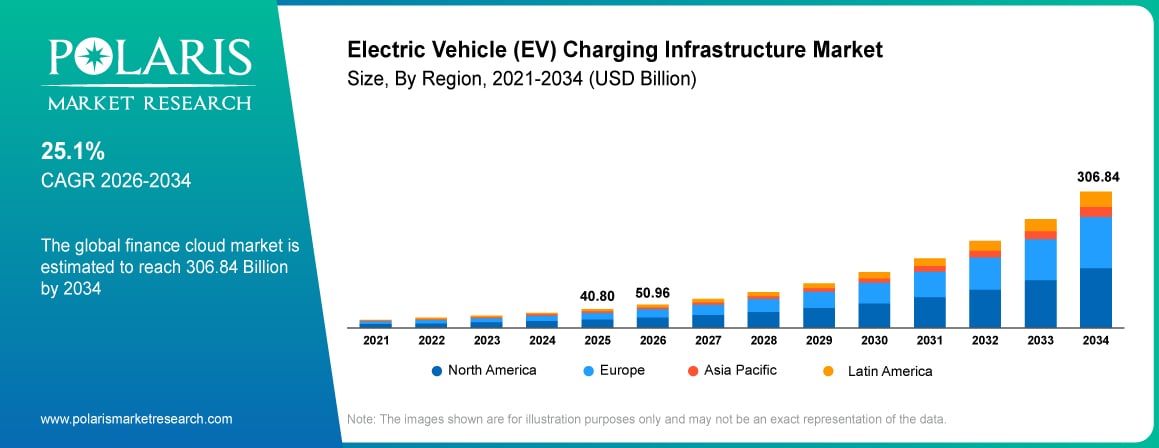
Electric vehicle (EV) charging infrastructure market size was valued at USD 40.80 billion in 2025 and is anticipated to exhibit a CAGR of 25.1% from 2026 to 2034. The growth is driven by rising electric vehicle adoption, government incentives on EV ownership, and technological advancements in charging infrastructure.
Market Statistics
Electric Vehicle Charging Infrastructure Market Key Takeaways
- The North America EV charging infrastructure market is expected to witness significant growth at a 26.3% CAGR due to rising EV sales and increasing public charging infrastructure investments.
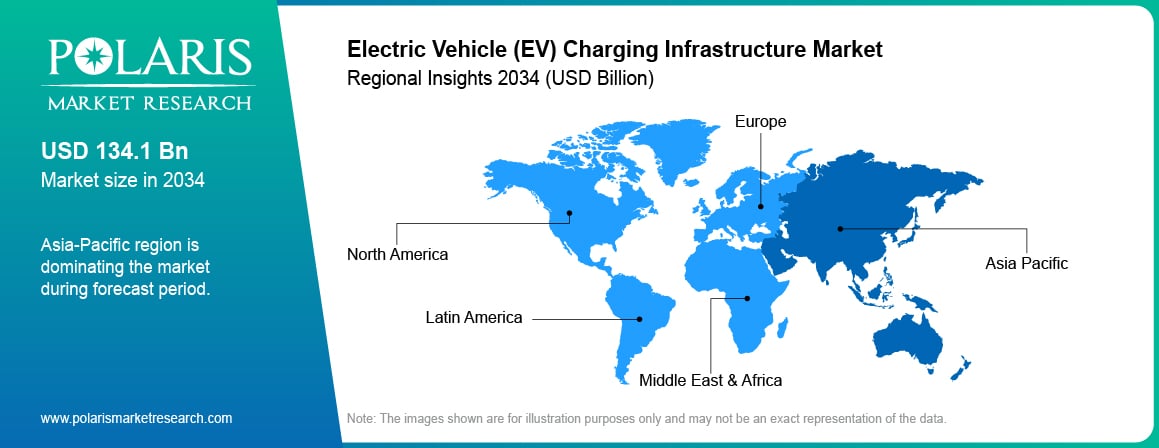
- The Asia Pacific EV charging infrastructure market dominated with the largest share of 43.8% in 2025 due to rising EV demand, supportive government policies, and increasing investments in charging infrastructure.
- The connected segment is expected to witness significant growth at a 27.8% CAGR, driven by the growing need for convenient and easy access to EV charging stations.
- The commercial segment dominated with a 62.4% share in 2025, driven by the rising need for EV charging infrastructure across hotels, office buildings, parking facilities, and gas stations.
- The NACS segment is expected to witness growth at a 29.4% CAGR, driven by the expanding supercharger network and growing popularity among automakers.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observation.
What Is the Electric Vehicle Charging Infrastructure Market?
The EV charging station market refers to the industry that develops and provides charging facilities for electric vehicles. These charging stations are equipped with all kinds of infrastructure and technical equipment. The charging station are located at private parking, workplaces, public parking garages, retail stores, and along highways. This market is being driven by the demand of electric cars and the need to find compatible electricity charging stations. Moreover, government policies and the increasing investment in the development of this infrastructure fuels the growth of the market and promote the use of electric cars across the world.
How Does EV Charging Work?
EV charging infrastructure works by supplying electricity to recharge an electric vehicle’s battery. This is done by plugging the vehicle into a charging station, where electricity is supplied to the battery through a charging cable. The energy is drawn from the grid through the charger and into the battery. These stations can be found at home, at work, public places, and along roadways. Different chargers can charge batteries at different speeds, and can be slow, medium, or fast. Smart software can also monitor charging, payments, and energy use. Having a developed charging infrastructure allows for people to charge their vehicles when needed.
Stringent environmental regulations are propelling the growth of the electric vehicle charging infrastructure market size. Governments globally are imposing emissions reduction targets, pushing for cleaner transportation solutions. In response, businesses and municipalities are investing in robust EV charging networks to facilitate widespread electric vehicle adoption. Environmental regulations, aimed at curbing air pollution and combating climate change, drive the demand for charging infrastructure as a key component of the eco-friendly transportation ecosystem.
Advances in technology, economies of scale, and innovation have led to substantial reductions in the manufacturing and installation costs of charging stations. As the cost of EV charging infrastructure becomes more competitive, businesses and governments find it economically feasible to invest in widespread deployment. Additionally, the long-term operational savings associated with electric vehicles contribute to the attractiveness of charging infrastructure investments. This combination of economic viability and cost-effectiveness fuels the expansion of the EV charging infrastructure market, fostering a more sustainable and accessible charging network.
The research report offers a quantitative and qualitative electric vehicle charging market analysis to enable effective decision-making. It covers the key trends and growth opportunities anticipated to have a favorable impact on the market. Besides, the study covers segment and regional revenue forecasts for market assessment.
Source: Polaris Market Research Analysis
AI Impact on Market
- AI enables smart charging by optimizing charging schedules and energy consumption.
- AI supports predictive maintenance by detecting potential charger failures in advance.
- AI improves demand forecasting by analyzing charging patterns and user behavior.
- AI helps optimize grid loads and supports efficient energy distribution across charging networks.
- AI enhances user experience through real-time availability, route planning, and personalized charging recommendations.
Market Dynamics
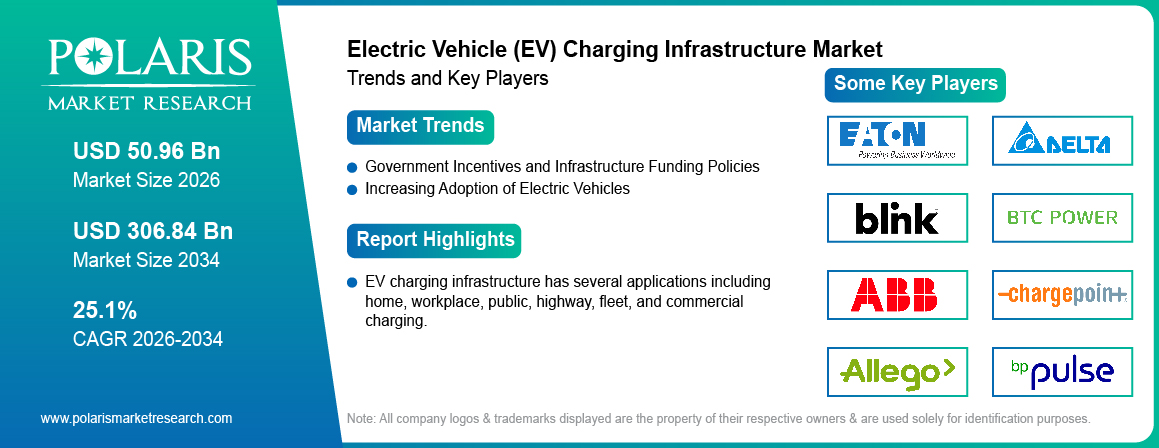
Driver: Government Incentives and Infrastructure Funding Policies
Government EV charging infrastructure funding policies play a pivotal role in propelling the electric vehicle charging market growth. Many governments worldwide are actively promoting sustainable transportation by offering financial incentives, tax credits, and subsidies for the installation of EV charging stations. According to Federal Highway Administration of the U.S. Department of Transportation, USD 1 billion are allocated to National Electric Vehicle Infrastructure (NEVI) Formula Program. Robust regulatory frameworks and mandates further encourage private EV charging infrastructure investment. These supportive measures aim to address range anxiety, boost consumer confidence, and accelerate the transition to electric mobility. By fostering an environment conducive to infrastructure development, governments contribute significantly to EV charging network expansion, creating a sustainable and efficient ecosystem for electric vehicles (Source: highways.fhwa.dot.gov).
Driver: Increasing Adoption of Electric Vehicles
The burgeoning adoption of electric vehicles is catalyzing robust growth in the electric vehicle charging infrastructure market. According to the International Energy Agency, 20 million electric vehicles were sold in 2025 which was increased of 20% compared to the previous year of 2024. As more consumers embrace EVs for their environmental benefits and cost savings, the demand for accessible and efficient charging solutions escalates. This surge in EV ownership propels the expansion of charging networks to meet the escalating needs of a growing user base. Governments, recognizing the pivotal role of EVs in sustainable transportation, are incentivizing and investing in charging infrastructure projects (Source: iea.org).
Driver: Fleet Electrification, and Commercial EVs’ Rising Demand
The adoption of alternative fuel vehicles in commercial settings is rising. Transport firms are investing in battery electric buses and taxis, while delivery companies are using electric vans, and other firms are buying electric trucks. For instance, in May 2026, Amazon India announced plans to deploy around 1,000 electric trucks from Eicher for delivery of goods. Fleets require charging infrastructure at their depots, which has increased the demand for chargers, both fast and slow. The commercialization of electric vehicles will continue to grow, spurring the need for more chargers, thereby fueling the growth of industry (Source: smalltrucks.eichertrucksandbuses.com).
Driver: Smart City & Urban Mobility Initiatives
There is a rising need for smart cities to minimize pollution and promote investment in shared mobility. This has led to government investment in electric buses as well as promoting the use of electric vehicles in general. The smart city and urban charging demand positively impact every aspect of the supply chain, including the provision of charging stations. The installation of chargers in residential, commercial, and garage locations by cities motivates people to buy more electric vehicles since they are able to charge them conveniently. The global investment in smart cities is expected to lead to a greater need for EV charging infrastructure, thereby boosting the market growth.
Challenge: High Installation & Infrastructure Deployment Costs
Installation of equipment, infrastructure, and structures needs high investment. The installation of charging stations demands substantial upfront investments, encompassing equipment procurement, installation expenses, and grid connection outlays. This financial barrier hinders both private enterprises and government initiatives from scaling up the charging network. It also fuels the need for charging station with high load on the power grid in some areas. In some cases, upgrading the power grid to meet the requirements of a high-power charging station is expensive. Such conditions discourage entrepreneurs from investing in such projects, thereby restraining the growth of market.
Challenge: Limited Charging Coverage in Rural Areas
Charging stations for electric vehicles are mostly concentrated in large cities and on highways. The underdeveloped infrastructure of rural areas cannot provide the necessary guarantees for the security of such investments. This creates concerns about long-distance travel and access to reliable charging. A charging station project should have a high load factor to be profitable. Drivers may hesitate to purchase EVs if charging options are limited outside urban areas. Expanding charging networks into rural regions requires additional investment and government support, which can slow overall infrastructure growth.
Challenge: Low Charger Utilization Rates
The utilization rate of a charging station depends on the level of development of the local electric vehicle demand. The presence of a charging station in an area with few electric cars will hardly be profitable. The low utilization rate discourages entrepreneurs from creating new stations, thus slowing down the development of the industry. A charging station network should be established in a area where the electric vehicle demand is growing.
Restraint: Fragmented Charging Standards & Interoperability
The issue of interference of various charging standards complicates the charging process for plug-in car owners. While some drivers may only have access to a Level 1 charger at home, a car owner should purchase a Level 2 charger to enjoy faster charging. Additionally, various car owners should buy different apps to pay for charging services. Lack of interoperability between plug-in cars and levels of chargers can hinder the growth of the charging station industry. To address this issue, industry players should develop standardized mechanisms for interaction and information exchange.
Restraint: Grid Capacity & Electricity Demand Constraints
The need to install several fast chargers at the same time can impose high loads on the power grid. The grid’s capacity is a significant constraint in the process of installing charging stations. Upgrading the power grid in the locality of a charging station is a complex and capital-intensive process. Moreover, the high load during peak hours worsen the grid’s performance and reduce the stability of the electricity supply. These constraints can become an obstacle during the installation of new charging stations.
Opportunity: Declining Costs of Charging Infrastructure
Even if currently EV charger deployment requires high investment, the cost of the infrastructure required for EVs is expected to decrease in the coming years. The production cost of the equipment is also expected to reduce due to high demand and technological advancements. Additionally, the technology is becoming more sophisticated, and the chargers are being manufactured in large quantities. This will lower the prices of the charging infrastructure. The ease of installation and maintenance is also rising. This will make it more affordable to own and operate a network of chargers in both residential and commercial settings, which would create lucrative market opportunities.
Source: Polaris Market Research Analysis
Market Segmentation Overview
The electric vehicle charging infrastructure market analysis is primarily segmented based on the type of charger, charging type, operation, connectivity, level of charging, installation type, end use, and region.
By Type of Charger Analysis
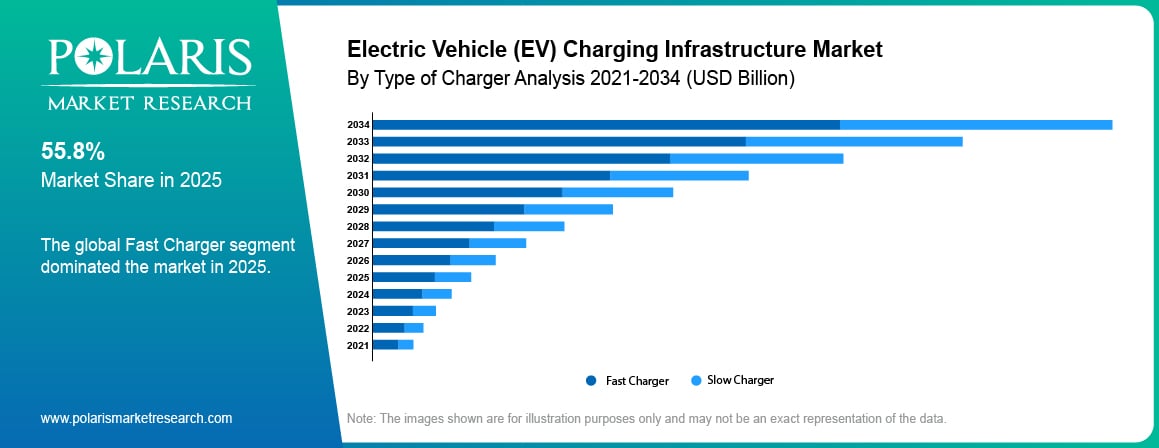
The fast charger segment accounted for largest EV charging infrastructure market share of 55.8% in 2025. Boasting formidable charging power, these chargers minimize EV battery replenishment times, crucial for efficient long-distance travel. The substantial reduction in charging durations compared to standard chargers aligns with the surging demand for swift and hassle-free EV experiences. Strategically positioned in diverse locales, fast chargers cater to short-term urban needs and long-distance travel along major routes. Standardized connectors like CHAdeMO and CCS enhance compatibility. Operating at elevated voltage levels, professional installation ensures safety. Despite higher costs, their proliferation enhances accessibility, integral to developing extensive charging networks.
The slow charging segment is expected to witness significant growth of CAGR 22.7% driven by its low cost, ease of installation and its use for everyday charging of electric vehicles. This charging infrastructure is mostly used in home and workplace with vehicles staying parked for long time. With the help of slow chargers, users can charge their vehicles to full capacity overnight without the hassle of expensive charging equipment. Moreover, the segment is anticipated to benefit from the increasing number of residential EV owners. The growth of this segment is also supported by the development of workplace infrastructure and demand for affordable charging solutions, thereby driving the segment growth
By Charging Type Analysis
The AC charging segment dominated with largest share of 58.3% in 2025 driven by the affordability and ease of installation. AC chargers are mostly used for everyday charging by residential and commercial users. They are cost effective and can easily be installed at home, offices, hotels and parking places. Moreover, these chargers generally require lower maintenance cost as compared to other advanced level chargers. The increasing adoption of electric vehicles and the need for convenient and accessible charging infrastructure are anticipated to drive the growth of this segment
The DC Charging segment is expected to witness significant growth of CAGR 28.6%. The demand for DC charging type is expected to increase during the forecast period. The surge in demand for DC electric vehicle charging infrastructure is propelled by its ability to deliver significantly faster charging times, making it appealing for drivers seeking rapid EV battery replenishment. DC fast chargers strategically positioned along highways support long-distance travel, alleviating concerns about range anxiety. In urban environments, the convenience of rapid charging enhances the appeal of electric vehicles. Government support, regulations, and financial incentives drive the expansion of charging networks, contributing to the widespread deployment of DC charging stations.
Difference Between AC and DC Charging
| Attribute | AC Charging (Alternating Current) | DC Charging (Direct Current) |
| Charging Speed | Slow to Moderate (3–22 kW) | Fast to Ultra-Fast (50–350+ kW) |
| Range Added per Hour | 12–80 miles | 3–20 miles per minute (Level 3) |
| Typical Use Case | Residential, Workplace, Overnight | Highway Corridors, Public Hubs, Fleet Depots |
| Installation Complexity | Low – standard electrical upgrade | High – dedicated grid connection required |
| Cost (Hardware) | $300–$2,000 (Level 2) | $20,000–$150,000+ (DC Fast) |
| Primary Charger Levels | Level 1 (120V), Level 2 (240V) | Level 3 / DC Fast Charging |
| Smart EV Charging Support | Yes – common in connected Level 2 | Yes – AI-enabled fast chargers |
| V2G Capability | Limited | Full bidirectional V2G (Mode 4) |
| Best Connector Standards | J1772, Type 2 (Mennekes), CCS1/2 AC | CCS, CHAdeMO, NACS, GB/T |
Source: Polaris Market Research Analysis
By Level of Charging Analysis
The Level 1 charging is expected to witness significant growth of CAGR 21.9%. This level is primarily driven by its ease of installation and low maintenance cost. Level 1 chargers operate on standard home outlets that are convenient and accessible for every household. They are suitable for low mileage electric vehicle owners with sufficient parking space and who are able to afford to leave their vehicle for a long time in order to fully charge them. The low cost of installation is also a major factor contributing to the growth of this segment. The growing popularity of entry level electric vehicles is further expected to benefit this segment as these vehicles are mostly charged at home with the help of Level 1 chargers.
The Level 2 charging dominated in 2025 with 48.6% share. This is the most preferred level of charging primarily due to its ability to offer faster charge with moderate installation cost. Level 2 chargers are mostly used in home, office, malls, and public places. These level 2 chargers offer a convenient solution for regular and everyday EV owners. The increasing adoption of electric vehicles worldwide and the development of advanced public charging infrastructure is driving the growth of this segment.
The Level 3 charging is expected to witness significant growth of CAGR 29.8%. This segment is majorly driven by the need for faster charging. Level 3 chargers are mostly used for long-haul commercial vehicles and are installed on highway and in public places. The rising adoption of electric vehicles worldwide is creating a need for faster and efficient charging technologies. The development of charging infrastructure on highways in various government and private initiatives and the popularity of commercial electric taxis and buses is also anticipated to contribute to the growth of this segment.
| Feature | Level 1 | Level 2 | Level 3 (DC Fast) |
| Voltage | 120V AC | 208–240V AC | 400–1,000V DC |
| Power Output | 1.4–1.9 kW | 3.3–22 kW | 50–350+ kW |
| Charging Time (60 kWh EV) | 16–20 hours | 3–8 hours | 15–45 minutes |
| Range Added per Hour | 3–5 miles | 12–80 miles | 3–20 miles/minute |
| Installation Cost | Minimal – uses standard outlet | $500–$2,500 installed | $20,000–$150,000+ |
| Primary Location | Home, Emergency use | Home, Workplace, Public | Highway, Urban Hub, Fleet Depot |
| Best Suited For | Overnight home charging | Daily commuter top-up | Long-distance, commercial fleets |
| Connector Standard | J1772, Standard outlet | SAE J1772, Type 2 | CCS, CHAdeMO, NACS, GB/T |
Source: Polaris Market Research Analysis
By Connector Type Analysis
The CCS segment is expected to witness growth of CAGR 26.7% driven by its high adoption rate by various electric vehicle manufacturers and charging station providers. This versatility of this connector design is providing convenience to the users by enabling both AC and DC charging. The segment is further benefited by the development of extensive public charging infrastructure. Moreover, this connector is popular among the users, especially in countries, where there is high adoption rate of electric vehicles. The rising popularity of electric vehicles and demand for standard connector design with improved convenience are further expected to drive the growth of this segment.
The CHAdeMO is expected to witness share of 16.8% in 2025 due to its popularity in many of the existing electric vehicle models. The wide adoption rate of this connector design in the past years has led to the production of wide range of compatible charging stations. This compatibility between the connectors and the charging stations across the globe would continue to drive the demand. Additionally, the demand for fast charging technology has further contributed to the segment’s popularity. The existing investment in the CHAdeMO platform has led to its widespread use around the world, thereby driving the growth.
The NACS segment is expected to witness growth of CAGR 29.4% driven by the large development of supercharger network and its popularity among various automakers. The network provides faster and convenient charging infrastructure to the users. Additionally, the demand for this type of connector is further increasing among non-Tesla car owners as this connector is becoming more compatible with other car manufacturers. The convenience and availability of this connector across the globe is expected to further boost the sales of NACS/Tesla Supercharger.
The GB/T segment dominated with share of 38.9% in 2025 driven by the rapid development of the electric vehicle market in China. The government of China is taking initiatives for promoting the use of electric vehicles and installing charging infrastructure in the country. The increasing popularity of electric vehicles and the growing need for efficient and convenient charging solutions has resulted in higher demand for GB/T connector in China. Additionally, the extensive public and private investment in the development of EV charging infrastructure is further contributing to the growth of this segment. The popularity of this connector is further fueled by the large domestic EV manufacturing activities and investment in infrastructure in the country.
| Connector | Region | Power Type | Max Power | Key Feature |
| CCS (Type 1/2) | US, Europe | AC + DC | 350 kW+ | Unified AC/DC plug; OEM standard |
| CHAdeMO | Japan, EU | DC only | 200 kW | Strong V2G capability |
| NACS / Tesla SC | US, expanding globally | AC + DC | 250+ kW | US OEM adoption surge; open network |
| GB/T | China | AC + DC | 250 kW | China mandatory standard |
Source: Polaris Market Research Analysis
By Installation Type Analysis
The fixed segment accounted for 71.6% share in 2025 driven by the demand for permanent and reliable electric vehicle charging infrastructure. Fixed installation type can be seen in home, commercial places, parking lots, highway, and other EV charging station places. These types of installation provide a reliable and continuous supply of electricity to the charging stations. With the growing popularity of electric vehicles, the demand for such reliable installation is also increasing in order to provide convenient and accessible charging to the consumers. The government and private entities are also taking initiatives for developing public infrastructure with such type of installations.
The portable segment is expected to witness significant growth of CAGR 28.2% driven by the need for improved convenience and flexibility. The demand for portable charger is increasing among the users because these types of chargers can be easily accessed and carried anywhere to gain access to electric vehicle charging. They are mostly used as a backup charger when there is no permanent charging station available to the consumer. The rising number of portable EV charging stations is also supported by the growing need for flexible and convenient charging solutions. These charging stations offer the advantage of being able to be moved from one place to another at a much lesser installation cost.
By End Use Analysis
The residential segment is expected to witness significant growth of CAGR 26.9% driven by the increasing demand for residential EV ownership. Charging at home offers convenience and flexibility to EV owners. Charging at home is particularly beneficial for consumers who have long parking duration and would like to charge their vehicles to full capacity overnight. These types of charging solutions are cost-effective and easy to access. There are various government incentives and rebates offered to the residential EV owners in several countries. This propels the demand for residential EV charging.
The commercial segment dominated with 62.4% share in 2025 driven by the rising need for commercial infrastructure for EVs. Commercial EV charging infrastructure is primarily installed in hotels, office buildings, parking facilities, gas stations, and other commercial places. This are provided in order to provide convenient and accessible charging to the consumers. The increasing popularity of electric vehicles and the growing demand for convenient and flexible EV charging solutions are expected to drive the segment growth.
| End Use | Sub-Segments | Charger Type | Key Trend |
| Residential | Private houses, MDUs/Apartments | Level 1, Level 2 | Smart home integration; solar tie-in |
| Commercial – Fleet | Logistics depots, bus depots, ride-share | Level 2, DC Fast | Fleet electrification surge |
| Commercial – Destination | Hotels, retail, parking | Level 2 | Dwell-time charging; customer loyalty |
| Commercial – Highway | Motorway service areas, truck stops | DC Fast, MCS | Ultra-fast corridor expansion (NEVI, TEN-T) |
| Commercial – Public Urban | Street parking, city hubs | Level 2, DC Fast | Smart city EV mandates |
| Commercial – Bus/Transit | Electric bus depots | Pantograph, DC Fast | Public transit electrification targets |
Source: Polaris Market Research Analysis
By Connectivity Analysis
The connected segment is expected to witness significant growth of CAGR 27.8% driven by the growing need for convenient and easy access to EV charging stations. Connected EV charging stations offer a smart solution to the users as it can provide information on availability of charging stations and also help the owner manage the charging process according to their needs. The segment is further beneficial for the operators as it helps them to monitor the performance of their charging system. The popularity of smart cities and smart parking solutions and the increasing adoption of connected electric vehicles expected to fuel the demand for connected EV charging stations across the world.
The non-connected segment dominated with 54.7% share in 2025 driven by the easy availability and low maintenance of these types of EV charging stations. Non-connected EV charging stations are mostly used for home and some commercial uses. This are convenient for those consumers who do not want the complex processes involved with connected stations. These charging stations provide a simple and easy method for charging electric vehicles without the hassle of monitoring and managing them, thereby driving the growth
Connected vs. Non-Connected EV Chargers
| Parameter | Connected | Non-Connected |
| Connectivity | Internet-enabled | Standalone |
| Monitoring | Remote monitoring | Manual monitoring |
| Payment | Digital payment | Basic payment |
| Smart Charging | Supported | Limited |
| Cost | Higher | Lower |
| Applications | Public, fleet, commercial | Residential, basic use |
| Outlook | High growth potential | Stable niche demand |
Source: Polaris Market Research Analysis
By Operation Analysis
The mode 3 segment dominated with largest share of 46.8% in 2025 driven by the increasing need for faster and more convenient charging of electric vehicles, as well as their rising popularity. These charging stations are installed at home, at work, and on the street. Additionally, state incentives are fueling adoption through their installation, as they allow balancing charging speed and are relatively affordable equipment. The growing number of private and commercial infrastructures is also driving the development of this technology. The tendency of consumers to opt for convenient overnight and destination charging is expected to drive the segment growth
The mode 1 segment is expected to register a CAGR of 21.4% during the forecast period due to less complex charging process and its relatively low cost. This mode is used when a private EV owner wants to recharge their vehicle at the standard sockets. This type of charging is applicable to low-power EVs. The growing popularity of such vehicles and the increasing number of consumers who opt for domestic electricity as a source of energy contribute to the growth of the segment. Moreover, the growing demand for affordable and convenient methods of EV charging is further driving the segment growth.
The mode 2 segment is expected to exhibit a CAGR of 23.6% during the forecast period as it offers more reliable and convenient home or office EV charging. It is based on the use of a special cable with built-in protection. Moreover, this mode is characterized by a higher degree of convenience and safety compared to the first mode. The increasing popularity of home charging and the growing number of residential EV owners contribute to the growth of the segment.
The mode 4 segment held a significant share of 28.5% in 2025 due to growing need for a faster and more convenient charging method. It is based on the provision of direct current and provides a much shorter charging time. The growing popularity of long-distance EVs fuels the need for faster charging. Additionally, a number of public charging station providers are built worldwide. The growing need for this mode is further driven by investments in the development of charging infrastructure along highways.
Operation Mode Comparison Table
| Mode | Power Type | Communication | Typical Power | Application |
| Mode 1 | AC | No protection | Up to 16A | Basic home charging; limited markets |
| Mode 2 | AC | In-cable control box | Up to 32A | Emergency / portable travel charging |
| Mode 3 | AC | IEC 61851 / OCPP | Up to 43 kW | Public/workplace; Level 1 & 2; most deployed |
| Mode 4 | DC | IEC 61851-23 | Up to 350+ kW | DC fast charging; highways; highest CAGR |
Source: Polaris Market Research Analysis
Real-World Use Cases & Applications
EV charging infrastructure has several applications including home, workplace, public, highway, fleet, and commercial charging. Home charging is a process where people plug in their electric cars overnight to ensure they have enough charge to run the following day. Workplace charging is where car owners charge their vehicles at work. Charging stations are also placed in malls and other popular places by the public. Highway charging is also a common application of EV charging infrastructure. It includes the installation of quick chargers on roads to enable faster travel. Fleet charging application uses the EV fleet charging infrastructure in different businesses to charge electric buses, taxis, and trucks. Commercialization involves firms that own and control EV charging stations and provide charging services to the public, where people connect their cars to charge.
Emerging Technology Trends Shaping the Market
Smart Charging & AI-Driven Energy Management
Smart charging employs software and AI to regulate EV charging, thus reducing electricity grid load and cost. The software manages the timing of the charging process. Smart charging can be combined with AI to analyze patterns and optimize charging, thus enabling affordable and reliable EV charging.
Vehicle-to-Grid (V2G)
The vehicle-to-grid (V2G) technology enables bidirectional electricity flow. In this case, the car’s battery can store and supply energy to the grid. V2G EVs contribute to a stable electricity supply by providing renewable energy with vehicle batteries. The technology helps EV owners earn income while balancing the electricity supply-demand.
Ultra-Fast / Megawatt Charging Systems (MCS)
Ultra-fast and Megawatt Charging Systems are intended to reduce the vehicle charging time. The MCSs enable faster charging and higher power for commercial vehicles, such as buses and trucks, with bigger batteries. The rising demand for electric commercial vehicles and improving transportation logistics is expected to fuel the MCS demand.
Wireless EV Charging
Wireless EV charging eliminates the need for plugging in a charging cable. Instead, the electricity is wirelessly transferred to the vehicle’s on-board charger. This technology is expected to gain significant traction in the near future, enabled by its potential to offer more convenience than a charging plug. Wireless charging is expected to initially applied in passenger cars, taxis, and buses before being integrated into future smart energy systems.
Battery Swapping
Battery swapping infrastructure technology enables swapping a dead battery for a charged one. The method is important for electric two-wheelers, taxis, and commercial vehicles, where battery swapping stations can significantly reduce vehicle downtime. A growing emphasis on faster EV energy replacement and shorter downtime is expected to fuel the battery swapping demand.
Renewable-Integrated EV Charging
Renewable-integrated EV charging offers a clean energy solution by incorporating electricity generation and battery storage. The renewable charging system can utilize solar and wind power to charge EVs and control the electricity flow in the system.
Commercial Charging Infrastructure
Companies are replacing their traditional vehicles with electric mid and large buses, delivery, taxis, and trucks to reduce the cost of fuel and emissions. Thus, there is a rising demand for commercial EV charging infrastructure. Commercial electric vehicles tend to run for an extended period of time and need to be charged frequently. Consequently, companies are building charging stations at depots, warehouses, and worksites that provide commercial grade electric vehicle charging. Commercial charging infrastructure allows businesses to optimize fleets of vehicles while reducing the time spent charging. The increasing adoption of battery electric commercial vehicles in public transport, logistics and delivery, and taxis are expected to drive the demand for large scale and high power commercial EV fleet depot charging infrastructure.
Source: Polaris Market Research Analysis
Regional Insights
| Region | CAGR/Share | Key Policy Drivers | Leading Countries |
| Asia-Pacific | 43.8% Share | China NEV quotas; PM E-DRIVE in India; Japan 2050 neutrality | China, Japan, South Korea, India |
| North America | 26.9% CAGR | NEVI program charging infrastructure ($5Bn project); Bipartisan Infra Law | US (dominant), Canada |
| Europe | 27.6% Share | EU AFIR regulation; Fit for 55; TEN-T corridor mandates | Germany, Netherlands, Norway, UK |
| Latin America | 22.8% CAGR | Public-private EV investments | Brazil, Mexico, Argentina |
| Middle East & Africa | 23.4% CAGR | UAE/Saudi smart mobility; HPCL India | UAE, Saudi Arabia, South Africa |
Source: Polaris Market Research Analysis
Asia-Pacific
The Asia-Pacific EV charging infrastructure market dominated with largest share of 43.8% due to the rising demand for electric vehicles, supportive government policies, and the increasing investments in the charging infrastructure. The growing demand for electric vehicles is fueled by the rising population in urban areas and the adverse impact of pollution on the environment. Moreover, the growing automotive sector in the region is also contributing to the demand for EVs. The rising adoption of electric two-wheelers, buses, and commercial vehicles is expected to propel the growth of EV charging market Asia Pacific region.
North America
The EV charging infrastructure market in North America is expected to witness significant growth of CAGR 26.9% due to a rise in the sales of electric vehicles and the increasing public charging infrastructure investment. The demand for EVs is increasing due to government support and the growing preference of the consumers towards eco-friendly vehicles. The rising installation of DC fast-charging stations across the region is further fueling the demand. Moreover, the growing demand for electric pick-up, sport-utility vehicles, and commercial vehicles is expected to result in the need for additional charging stations and infrastructure, thereby driving the growth in region.
Europe
Europe’s EV charging infrastructure market accounted for 27.6% share in 2025 driven by the region’s environmental regulations and government support for adopting electric vehicles. The increasing initiatives by the governments of various European countries to promote the EV manufacturing and sales are fueling the demand for electric vehicle charging stations. Moreover, the government support for sustainable transportation is also encouraging private players to invest in the EV charging infrastructure. The implementation of climate action plans in various European countries focusing on reducing carbon emissions and switching to alternative transportation fuel is further driving the EV charging market Europe growth.
Latin America
The Latin America is witnessing growth of CAGR 22.8% during EV charging infrastructure market forecast 2034 due to the rising awareness about electric mobility and sustainable transportation. Several governments in the region are taking initiatives like EV subsidies to promote electric vehicles. This is driving the demand for charging infrastructure. The surging fuel prices are further influencing consumers to consider electric mobility as a cheaper and cost-effective alternative to conventional vehicles. The increasing investments by the private players in electric bus services and adopting electric commercial vehicles by various private-jet airports in the region are also contributing to the growth of the EV charging infrastructure market.
Middle East & Africa
The Middle East and Africa EV charging infrastructure market are witnessing substantial growth of CAGR 23.4% due to the increasing investments in the sustainable energy sector and developing smart cities across the region. Various governments are taking initiatives for cleaner transport systems and reducing carbon emissions in the countries. The growing need for smart city projects and EV charging infrastructure in urban areas is further encouraging private players to set up EV charging stations across commercial and public places, thereby fueling the market growth in the region.
Source: Polaris Market Research Analysis
Competitive Insights
The electric vehicle charging infrastructure market displays a wide range of participants, and the influx of numerous newcomers is anticipated to intensify rivalry. Established frontrunners in the market continually upgrade their technologies to sustain a competitive edge, with a key emphasis on efficiency, reliability, and safety. These organizations prioritize strategic initiatives such as forming partnerships, enhancing products, and engaging in collaborative ventures to outperform their peers. Their objective is to secure a significant electric vehicle charging infrastructure market share.
List of Key EV Charger Companies
- ABB
- Allego B.V.
- Blink Charging
- BP Pulse
- BTC Power
- BYD
- ChargePoint
- ClipperCreek (an Enphase Energy brand)
- Delta Electronics, Inc.
- Eaton Corporation
- EFACEC
- Electrify America
- EVBox
- EVgo
- General Electric Company
- IONITY
- Kempower
- Leviton Manufacturing Co., Inc.
- Schneider Electric
- SemaConnect
- Shell
- Siemens
- StarCharge
- State Grid Corporation of China
- Tesla
- TotalEnergies
- Wallbox
- Webasto SE
Competitive Positioning Table
| Company | Primary Role(s) | Strategic Positioning | Geographic Focus | Typical Use Cases / Segments |
| ABB | Hardware OEM, solutions provider | High‑power DC technology leader with strong grid/industrial integration; turnkey projects for highways, fleets, transit. | Global (strong in EU, NA, APAC) | Public DC fast hubs, bus/truck depots, industrial sites, OEM partnerships. |
| Allego B.V. | Hardware OEM, CPO | European AC/DC charger supplier with focus on reliability and service; expanding DC portfolio. | Europe | Public charging, workplace, destination, some fleet applications. |
| Blink Charging | Hardware OEM, CPO | Owner‑operator of distributed L2/DCFC network; focuses on smaller sites and municipal/destination charging. | Primarily North America, some EU | Public L2/DCFC, workplace, municipal, destination charging. |
| BP Pulse | Energy major, CPO, solutions | High‑utilization public fast‑charging network; strong retail/forecourt and fleet depot strategy. | Global (EU, UK, US growth) | Urban fast hubs, highway corridors, retail forecourts, fleet depots. |
| BTC Power | Hardware OEM | DC fast charger manufacturer targeting commercial and public charging; value‑oriented DCFC. | North America, expanding globally | Public DCFC, commercial sites, fleet charging. |
| BYD | Hardware OEM, solutions, partial CPO | Integrated EV ecosystem (vehicles + chargers); strong in AC/DC hardware and depot solutions. | Global (strong in China, EU, LATAM) | Bus/truck depots, public charging, commercial fleets, destination charging. |
| ChargePoint | Hardware OEM, CPO, software platform | Leading open network in North America; cloud‑connected hardware, strong software/energy management. | North America, Europe | Workplace, public L2/DCFC, fleets, commercial real estate, retail. |
| ClipperCreek (Enphase) | Hardware OEM (residential/commercial) | Residential and light commercial AC chargers integrated with Enphase energy ecosystem. | North America | Home charging, small commercial, energy‑managed sites. |
| Delta Electronics, Inc. | Hardware OEM, solutions | Broad AC/DC portfolio; strong in APAC; focuses on efficiency and integration with energy systems. | Global (strong in APAC, EU) | Public charging, commercial/industrial, fleet depots, OEM supply. |
| Eaton Corporation | Hardware OEM, solutions, energy management | Electrical infrastructure leader; EV charging integrated with power distribution, microgrids, and buildings. | Global | Commercial/industrial sites, campuses, fleets, behind‑the‑meter solutions. |
| EFACEC | Hardware OEM, solutions | Chinese DC fast charger supplier; cost‑competitive DCFC for public and fleet applications. | China, expanding internationally | Public DCFC, fleet depots, commercial charging. |
| Electrify America | CPO, solutions | Large US DC fast network focused on highway corridors and retail hubs; high‑power, reliability‑driven. | United States | Highway DC fast corridors, retail destination charging, some fleet. |
| EVBox | Hardware OEM, solutions | European AC/DC charger manufacturer with strong commercial/industrial focus; integrated energy management. | Europe, expanding globally | Workplace, public, commercial/industrial, fleet depots. |
| EVgo | CPO, solutions | US urban DC fast network with emphasis on metros, retail partnerships, and 100% renewable energy. | United States | Urban DC fast hubs, retail partnerships, fleet charging. |
| General Electric Company | Solutions, energy infrastructure | Grid and energy infrastructure provider; EV charging as part of broader electrification/microgrid offerings. | Global | Industrial/commercial sites, grid‑interactive charging, large campuses. |
| IONITY | CPO, joint venture (OEMs) | High‑power European highway network backed by major automakers; premium HPC experience. | Europe | Highway DC fast corridors, premium long‑distance travel. |
| Kempower | Hardware OEM, solutions | Modular, scalable DC fast charging systems with dynamic load management; strong in heavy‑duty and hubs. | Europe, expanding globally | Bus/truck depots, public HPC hubs, commercial/industrial sites. |
| Leviton Manufacturing Co., Inc. | Hardware OEM | AC and some DC charging hardware for commercial and residential; strong in electrical distribution channels. | North America | Workplace, commercial buildings, residential multi‑unit, light public. |
| Schneider Electric | Hardware OEM, solutions, energy management | Building and energy management leader; EV charging integrated with EcoStruxure and DERs. | Global | Commercial/industrial, campuses, public charging, energy‑managed sites. |
| SemaConnect | Hardware OEM, CPO, solutions | Networked AC/DC chargers with focus on commercial properties and managed charging. | North America | Workplace, multi‑unit residential, commercial properties, light public. |
| Shell | Energy major, CPO, solutions | Rapidly expanding Shell Recharge network at fuel retail sites and dedicated hubs; integrated mobility strategy. | Global | Retail forecourts, highway hubs, urban fast charging, fleet solutions. |
| Siemens | Hardware OEM, solutions, energy management | Industrial automation and building tech leader; EV charging integrated with grid, buildings, and industry. | Global | Industrial/commercial hubs, smart buildings, public charging, fleets. |
| StarCharge | Hardware OEM, CPO | Major Chinese private CPO and DC/AC hardware supplier; large connector base in China. | China, some international | Public charging networks, commercial/industrial, fleet depots. |
| State Grid Corporation of China | CPO, grid operator | China’s largest grid operator and public charging network owner; massive scale in AC/DC public charging. | China | Public charging (AC/DC), highway corridors, urban networks, grid services. |
| Tesla | Hardware OEM, CPO, vehicle OEM | Proprietary Supercharger network with NACS standard; opening to other OEMs; vertically integrated ecosystem. | Global (strong in US, EU, China) | Highway DC fast corridors, destination charging, fleet (Tesla & other OEMs). |
| TotalEnergies | Energy major, CPO, solutions | Expanding EV charging at fuel retail and commercial sites; integrated energy and mobility strategy. | Europe, growing globally | Retail forecourts, urban fast hubs, commercial/industrial sites. |
| Wallbox | Hardware OEM, solutions | Strong in residential and commercial AC/DC; focus on smart, connected chargers and V2G/bidirectional tech. | Europe, North America, LATAM | Home, workplace, public L2/DCFC, prosumer/V2G applications. |
| Webasto SE | Hardware OEM, solutions | AC/DC charging hardware with focus on commercial, fleet, and OEM partnerships; strong in EU. | Europe, global presence | Fleet depots, commercial/industrial, public charging, OEM supply. |
Source: Polaris Market Research Analysis
Recent Developments
- August 2026, Ather Energy launched Ather Node, a connected EV charging solution for apartments and housing societies. The system connected multiple chargers without requiring major power infrastructure upgrades. The company planned to roll out the solution across six cities by the end of 2026. (Source: ndtvprofit.com)
- April 2026, Trinity Cleantech launched India’s first bioethanol-based 150 kW rapid EV charger, the ME Energy Rapid Charger 150. The mobile, off-grid solution enabled fast deployment, reduced dependence on grid infrastructure, and supported EV charging across highways, rural areas, and commercial locations. (Source: trinitycleantech.com)
- August 2026, Hyundai Motor India partnered with Jio-bp to integrate over 7,000 charging points across 300 cities into the myHyundai app, expanding accessible EV charging points beyond 37,000. Hyundai also announced plans to increase its DC fast-charging stations to 600 by 2030. (Source: sahi.com)
Future Outlook
The Level 3 charging segment is expected to witness strong growth in the coming years. EV adoption is accelerating and charging networks is expanding. There will be rising demand for high-power chargers that minimize charging time on highways, at public stations, commercial locations, and fleet depots. Advancements in battery technology and higher charging capacities will support faster charging speeds. Governments and utilities would promote DC fast-charging infrastructure by offering incentives and charging-network investments. Integration with renewable energy, battery storage, smart charging, and digital payment systems will improve network efficiency. This will boost the adoption of Level 3 charging as a critical component of EV infrastructure.
Report Coverage
The electric vehicle charging infrastructure market report emphasizes on key regions across the globe to provide a better understanding of the product to the users. Also, the report provides market insights into recent developments, and trends and analyzes the technologies that are gaining traction around the globe. Furthermore, the report covers an in-depth qualitative analysis pertaining to various paradigm shifts associated with the transformation of these solutions.
The report provides a detailed analysis of the market while focusing on various key aspects such as competitive analysis, type of chargers, charging types, levels of charging, end uses, and their futuristic growth opportunities.
Electric Vehicle (EV) Charging Infrastructure Market Segmentation
By Type of Charger Outlook (Revenue, USD Billion, 2021–2034)
- Fast Charger
- Slow Charger
By Charging Type Outlook (Revenue, USD Billion, 2021–2034)
- DC
- AC
By Level of Charging Outlook (Revenue, USD Billion, 2021–2034)
- Level 1
- Level 2
- Level 3
By Connector Type Outlook (Revenue, USD Billion, 2021–2034)
- CHAdeMO
- CCS
- NACS
- GB/T
By Connectivity Outlook (Revenue, USD Billion, 2021–2034)
- Connected
- Non-Connected
By Operation Outlook (Revenue, USD Billion, 2021–2034)
- Mode 1
- Mode 2
- Mode 3
- Mode 4
By Installation Outlook (Revenue, USD Billion, 2021–2034)
- Fixed
- Portable
By End Use Outlook (Revenue, USD Billion, 2021–2034)
- Residential
- Commercial
By Regional Outlook (Revenue, USD Billion, 2021–2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Electric Vehicle (EV) Charging Infrastructure Market Report Scope
| Report Attributes | Details |
| Market size in 2025 | USD 40.80 billion |
| Market size in 2026 | USD 50.96 billion |
| Revenue Forecast in 2034 | USD 306.84 billion |
| CAGR | 25.1% from 2026 – 2034 |
| Base year | 2025 |
| Historical data | 2021 – 2024 |
| Forecast period | 2026 – 2034 |
| Quantitative units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Segments Covered |
|
| Regional scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, region, and segmentation. |
Source: Polaris Market Research Analysis
Electric Vehicle (EV) Charging Infrastructure Market FAQ's
The global Electric Vehicle (EV) Charging Infrastructure market size is expected to reach USD 306.84 billion by 2034
ABB, Blink Charging, BP Chargemaster, Eaton Corporation, General Electric Company, Schneider Electric are the top market players in the market
The Asia-Pacific region contributed notably to the global Point of Electric Vehicle (EV) Charging Infrastructure Market, accounting for a 43.8% share in 2025.
Electric Vehicle (EV) Charging Infrastructure Market CAGR of 25.1% during the forecast period.
The Point of Electric Vehicle (EV) Charging Infrastructure Market report covering key segments aretype of charger, charging type, level of charging, end use, and region
Growing EV adoption, government incentives, expanding charging networks, technological advancements, and increasing investments in sustainable mobility infrastructure are driving market growth worldwide.
High installation costs, grid capacity constraints, interoperability issues, uneven infrastructure deployment, lengthy approval processes, and concerns regarding charging speed continue to challenge market expansion.
Smart charging, ultra-fast chargers, wireless systems, IoT connectivity, mobile applications, and energy management solutions are improving charging efficiency, accessibility, convenience, and network reliability.
Governments support infrastructure development through subsidies, tax incentives, regulatory policies, public-private partnerships, and funding initiatives aimed at accelerating electric vehicle adoption and deployment.
Fast-charging infrastructure reduces charging time, improves convenience, supports long-distance travel, enhances consumer confidence, and addresses range anxiety, encouraging greater adoption of electric vehicles.
Renewable energy integration helps reduce carbon emissions, lowers dependence on conventional electricity sources, supports sustainable transportation, and enables cleaner, more environmentally responsible EV charging operations.
Level 3 charging (or DC fast charging) rapidly charges EVs using direct current. This charging level significantly reduces charging time compared with Level 1 and Level 2 chargers.
Download Sample Report of Electric Vehicle (EV) Charging Infrastructure Market
Please fill out the form to request a customized copy of the research report.