Fitness Trackers Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Fitness Trackers Market Summary
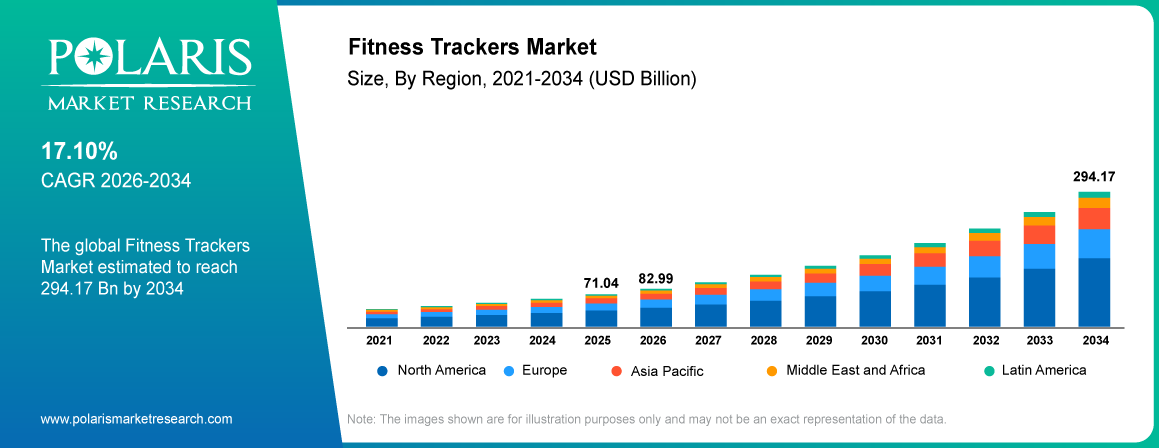
The global fitness trackers market size was valued at USD 71.04 billion in 2025, growing at a CAGR of 17.10% from 2026 to 2034. Rising awareness of health and wellness and technological advancements and integration enhancing user experience drive the market growth. Also, government initiatives and public health programs promoting active lifestyles and growing integration with corporate wellness programs and health insurance incentives fuel the growth.
Market Statistics
Fitness Trackers Market Key Takeaways
- According to our fitness trackers industry analysis, North America dominated with 43.0% revenue share in 2025, owing to the rising health consciousness among consumers in the U.S. and their higher purchasing power. Also, advanced digital health infrastructure and increasing penetration of connected wearables boost the dominance.
- The Asia Pacific market is anticipated to register the highest CAGR of 19.7% during the forecast period. The growth is attributed to growing smartphone penetration and increasing disposable income of middle-class population. Further, the domestic production and availability of low-cost products and rising penetration of e-commerce will propel the regional market expansion.
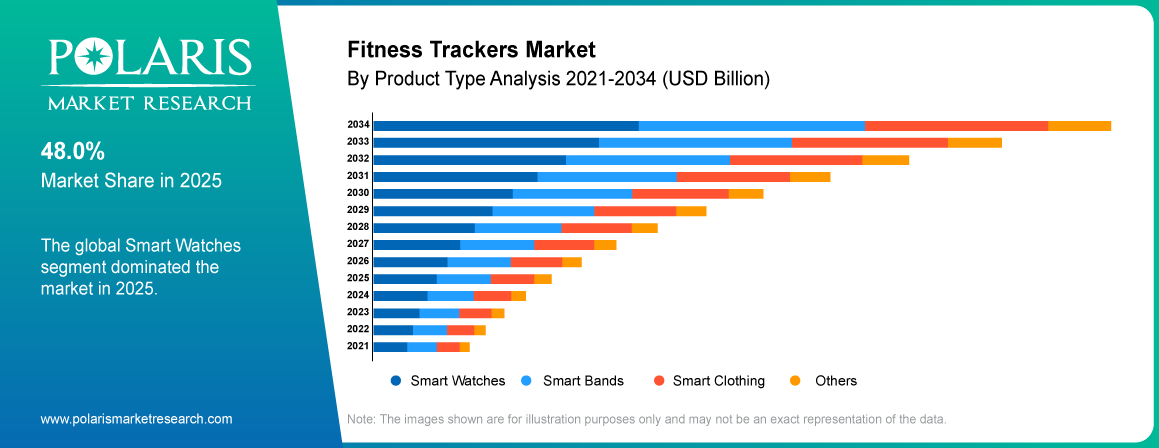
- Among the product categories, the smartwatches segment held the largest share of 48.0% in 2025. Smartwatches offer various features such as fitness and health monitoring, calling, and messaging, driving the segment dominance.
- The glucose monitoring segment is expected to register a CAGR of 21.83% during the forecast period. The growth is propelled by rising demand for non-intrusive monitoring systems and increasing adoption in diabetes management.
- The legwear segment is projected to exhibit the highest CAGR of 15.50% during 2026-2034. This growing adoption is led by the emergence of the wearable technology market.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is the Fitness Trackers Market?
The fitness trackers encompasses wearable electronic devices and applications designed to monitor and track various aspects of an individual's physical activity, physiological responses, and overall wellness. These devices typically track metrics such as steps taken, distance traveled, calories burned, heart rate, and sleep patterns, providing users with valuable insights into their daily activity levels and health trends.
The fitness trackers industry involves wearables technology, embedded sensors, software platforms, mobile applications, and related connected services that can be used to track physical activities and physiological parameters. Products include fitness bands, smartwatches, smart rings, smart clothes, monitoring patches, and others. The fitness trackers offer various functions such as heart-rate monitoring, sleep monitoring, GPS tracking, blood oxygen measurement, and health insights enabled by AI. Thus, they are used for personal wellness, sports performance, preventive healthcare, chronic disease management, and remote patient monitoring.
How do Fitness Trackers Work?
The fitness tracker processes raw body movement and physiological signals through a sensor-to-software solution to output meaningful health and activity metrics.
- Sensor Data Acquisition: Inertial dynamic sensor information of the motion activity is collected using embedded accelerometers and gyroscopes. Heart rate and blood oxygen levels can be monitored with optical sensors. Sophisticated hardware includes GPS, ECG electrodes, skin temperature sensors, or barometers.
- Signal Transformation: The signals detected in physical and biological domains are digitized by the instrument. On-chip processors eliminate background interference, extract useful signal information from noise, and format the data into a convenient output.
- Activity Recognition: Some preinstalled algorithms can detect activities such as walking, running, cycling, swimming, and resting/sleeping based on motion patterns. The tracker then predicts the step counts, distance walked, calories burned, exercise time, and exercise intensity.
- Data Transfer: The information is transferred from the user to a paired smartphone, tablet, or cloud platform through Bluetooth Low Energy, Wi-Fi, or cellular service. A conventional sync creates an ongoing record of the user's activity and health data.
- Software and AI Analysis: Mobile applications and AI-based analytics solutions can process real-time measurements within the context of historical trends, personal thresholds, and predefined health boundaries. Sleep scoring, recovery assessment, fitness-status evaluation, and identification of abnormal changes are facilitated using this methodology.
- Tailored Recommendations: Dashboards, alerts, scores, and recommendations are based on tracker results. Consumers get alerts/notifications in case of any anomalous readings. Some products can also synchronize/transfer data with health, telehealth, or company wellness platforms.
Sensor Technology Overview
Sensors are enabling fitness trackers to be more precise, practical and even to have medical uses. Accelerometers are used to measure motion, posture, gait sequence, and intensity of exercise, enabling activity recognition and energy expenditure estimation. PPG uses light signals to monitor blood volume changes to allow continuous heart rate monitoring. In outdoor settings, GPS monitors consumer’s location, distance, speed, elevation, and route. ECG electrodes detect the electrical activity of the heart, which enables devices like the Apple Watch to identify rhythm abnormalities, including possible atrial fibrillation. SpO₂ sensors exploit the difference in absorption of light in different layers of the skin to estimate the blood oxygen saturation. Along with onboard algorithms, these allow for sophisticated exercise metrics, sleep monitoring, recovery assessment and early warning detection of anomalous physiological events.
Fitness Tracker Vs Smartwatch Difference
| Parameter | Fitness Tracker | Smartwatch |
| Primary purpose | Health and fitness monitoring | Fitness tracking + smart connectivity |
| Smart features | Limited notifications | Calls, messages, apps, voice assistants, payments |
| Display | Small or minimal display | Larger, interactive display |
| GPS | Often smartphone-connected; some models have built-in GPS | Built-in GPS common in many models |
| Battery life | Generally longer | Generally shorter due to larger display and processing |
| Design | Slim, lightweight, fitness-focused | Larger, watch-like, multifunctional |
| Price | Generally affordable | Generally expensive |
| Best suited for | Fitness-focused and continuous health monitoring | Users seeking fitness + everyday smartphone functionality |
Source: Polaris Market Research Analysis
AI Integration and Data Transmission Analysis
Fitness trackers use Bluetooth Low Energy to sync health and activity data with a paired smartphone without significantly affecting battery life. It is then transferred to cloud platforms for safe storage, availability across devices, and more advanced analytics. Meanwhile, edge AI also quickly analyzes time-critical signals on the local device with higher response speed and without relying on internet connectivity. On a new reading, the AI models are compared with historical patterns to evaluate exercise, sleep, stress and recovery. These insights are turned into customized goals, coaching suggestions, rest recommendations, and notifications that evolve with the user’s habits and physiological responses.
Source: Polaris Market Research Analysis
Market Dynamics
Driver: Rising Awareness of Health and Wellness
Increasing health and wellness awareness among consumers drives the fitness trackers market growth. Individuals are focusing on a healthy lifestyle that includes tracking physical activities, diet, sleep pattern, and emotional well-being. According to the July 2026, UK Chief Medical Officers guidelines, being active regularly can reduce a risk of developing type 2 diabetes by 40%, cardiovascular disease by 35%, falls and depression by 30%, and some cancers by 20%. As consumers become more aware of the benefits, they are increasingly seeking tools to keep them moving. Fitness trackers meet this demand by converting personal routines into quantifiable data that users can analyze and make sense of. Motivations to work out, notifications about goals, and reports on achievements also contribute to their health routine. The tools help make the management of wellness a little more fun. Social fitness communities and the common discussion of healthy living purchasing decisions positively influence the adoption of fitness trackers. Consequently, the growing number of consumers concerned about self-improvement or self-care continues to drive the demand for wearable technology that offer convenient access to information related to one's health in the mindset of daily life (Source: gov.uk).
Driver: Technological Advancements and Integration Enhancing User Experience
Rising technological advancements and integration to enhance user experience propel the market expansion. The fitness tracker technology is advancing and the required tracking to use them is diminishing with quick technological evolution. Sensor accuracy, power consumption, lightweight design, and processing complexity impact the reliability and comfort of the device. In September 2025, Apple released the Apple Watch Series 11 with high blood pressure alert, sleep scoring, 5G connectivity, and 24 hours battery life. Such product upgrades improve consumer retention and make the ecosystem more engaging. It promotes the proliferation of wearables beyond traditional exercise tracking. In addition, integration with smartphones, fitness equipment, payment networks, and digital applications allows a single device to perform multiple roles in a connected ecosystem. Regular software updates add functionality, so users don't need to replace hardware. This combination of convenience, functionality, and personalization has a positive effect on user satisfaction, promotes product upgrades, and contributes to attract broader consumer groups (Source: apple.com).
Driver: Government Initiatives and Public Health Programs Promoting Active Lifestyles
Government support and public health initiatives that promote active lifestyles drive the market development. Programs in the public sector and government action to make use of fitness trackers widespread also position physical activity as a national and community health matter. In September 2025, the CDC renewed its Active People, Healthy Nation initiative. The initiative aims to raise the physical activity levels of 27 million Americans by 2027. It promotes activity-friendly streets, proximity to everyday destinations, and community designs that make walking, biking, and playing safer and easier. Beyond this, schools, cities, and health organizations introduce step challenges or activity goals. Fitness trackers let participants track their progress against broader guidelines through daily numerical goals. Thus, as policymakers help shape healthier communities and encourage sustained participation, wearable AI is becoming increasingly important as a tangible tool for conceptualizing and quantifying physical activity initiatives for different groups (Source: cdc.gov).
Driver: Growing Integration with Corporate Wellness Programs and Health Insurance Incentives
Corporate wellness programs and insurance rewards fuel the adoption of wearables among a large group of users. Employers often offer corporate wellness wearables as part of work benefit packages and run company challenges to boost participation, morale, and employee engagement. Insurers could potentially link authenticated activity achievements to reward points, premium cuts, or other financial benefits. These configurations help reduce upfront costs for users while giving organizations quantifiable proof of program participation. They generate a steady demand for device replacements as well as platform subscriptions and analytics services. As a result, enterprise deals provide wearable manufacturers and software vendors with an additional revenue stream beyond the consumer purchase.
Opportunity: Expanding Applications in Remote Patient Monitoring and Chronic Disease Management
Clinical practice fitness trackers are evolving from general wellness devices into connected care medical tools. Healthcare providers use remote patient monitoring devices to monitor health of their patients remotely. They are especially preferred for treating diabetes, heart conditions, obesity, or sleep disorders. Supported wearables are capable of tracking activity, heart rate, sleep, blood oxygen, weight, glucose, and others between visits. The devices send pertinent readings to clinicians. This continuous monitoring can enable earlier intervention, better treatment evaluation, and stronger patient engagement, driving demand for fitness trackers in telehealth, home care, and chronic disease management markets. Moreover, patients receive clearer feedback on how well they adhere to prescribed activity or rehabilitation regimens, and caregivers gain better insight into day-to-day condition management. This part of decentralized healthcare delivery makes compatible wearables more valuable to hospitals, telehealth providers, clinicians, caregivers, and people who need permanent assistance.
Challenge: Data Accuracy and Reliability
Data accuracy and reliability hinder the adoption of fitness trackers. Fitness trackers are indicative and rely on sensors and algorithms. They respond differently to skin tone, body position, movement intensity, environmental factors, and individual physiology. Variations in heart rate, calories, sleep stages, blood oxygen, or stress readings can undermine user trust, especially when these values are inconsistent between devices or with clinical measurements.
Challenge: Limited Clinical Reliability
Limited clinical reliability is restraining market expansion. Most consumer fitness trackers are intended for wellness, not medical diagnosis. Alerts or scores might be interpreted as medical statements, which poses risks of raising their worries unnecessarily, giving them false reassurances, or leading them to take the wrong direction in managing their health. Definition of need and clinical accuracy should drive device design so that the important limitations of the device are clearly communicated to the user and resources should be focused on sensor validation, algorithm testing and regulatory approval for medical.
Restraint: Declining User Engagement
Reducing user engagement can limit the growth of the market. The initial enthusiasm is likely to fade once the newness of the product has worn off and users are getting the same summaries and reminders ad nauseam. Manual syncing, frequent charging, clunky designs, too many alerts and complicated dashboards also can deter consistent use. Underwear wear time reduction also results in non-continuous datasets, which limits the potential of personalized analysis.
Restraint: Difficulty in Maintaining Retention
Difficulty in maintaining retention adversely influences the market development. Long-term engagement relies on users continuing to derive value from the system after reaching their initial fitness goals. Generic advice, subscription fatigue, lack of cross-platform support, and weak differentiation between device generations may also lead to abandonment. Vendors need to deliver adaptive coaching, significant progress meters, socialization, changing software features, and context-aware feedback to maintain the experience as rewarding without distracting the user.
AI Coaching and Other Technologies in Fitness Trackers
Technology and AI trends in fitness trackers increasingly focus on personalized advice, greater health visibility, and continuous intelligence in smaller, more convenient wearable forms. Development is active in various product lines, including AI coaching, cardiac assessment, oxygen measurement, smart rings, and continuous glucose monitoring wearables. This allows these smart health devices to have an even stronger presence in personal fitness and wellness.
AI coaching is now tailored to what people actually do, rather than relying on generic workout templates. These systems monitor exercise history, sleep quality, recovery status, resting heart rate, and training intensity to identify optimal actions. The recommendations could be on the exercise selection, the target pace, the recovery intervals, or the training load adaptation. Natural language interfaces are enabling users to better understand what drives changes in performance and more easily explain why a given recommendation is produced.
With ECG capabilities, premium health monitoring wearables are bolstering their heart rate offerings. Eligible devices can take electrical readings from the heart and alert users if they detect an irregular rhythm. SpO₂ monitoring enhances such competence by measuring blood oxygen saturation at rest, during sleep, under physical exertion or at high altitude. As a pair, these tools offer even more insight into exertion, recovery, breathing quality, and overall cardiovascular health, although consumer readings are not to be considered equivalent to professional diagnosis.
The focus areas for technology development are:
- AI coaching: Customized training, readiness, recovery, and lifestyle guidance.
- ECG and SpO2: Structures of high-rate multi-lead ECGs and oxygen saturation, sleep, and exercise.
- Smart Rings: All the benefits of Sleep, Temp, HRV, and Recovery monitored discreetly 24/7.
- CGM Integration: Real-time evaluation of glucose responses to meals, exercise, stress, and sleep.
Demand for smart ring fitness trackers is rising because they can be worn for extended periods, unlike the screen-centric experience of a smartwatch. They are less obtrusive, monitoring sleep and recovery statistics to attract those who want a lighter touch. And now, CGM integration is bringing wearables into metabolic health. Active monitoring of glucose trends relative to exercise, meals and sleep also enables users to assess the impact of daily choices on their bodies.
Collectively, these factors are creating new opportunities for fitness trackers and connected, personalized systems that monitor dozens of health signals and provide more meaningful guidance throughout the day.
AI-Powered Health Analytics
AI-based health-status models are evolving to provide continuous insights into performance and physiological changes. Personalized training engines analyze training load, training intensity, recovery time, sleep regularity, and past trends to provide actionable and realistic training plans. Predictive fatigue models incorporate heart-rate variability, resting pulse, sleep interruptions, and accumulated training load to detect under-recovered states before performance declines or injury risk rises. Anomaly-detection provide personalized baseline and notify users of anomalies that range from irregular heart rhythm and sudden drops in oxygen to prolonged change in resting numbers. Instead of focusing on single readings, AI-based pattern analysis provides timely, personalized recommendations to help make better training decisions and take better care of one’s health.
Emerging Form Factors
Innovation in form factors is starting to take fitness tracking beyond traditional wrist-worn devices. Rings provide unobtrusive, continuous measurement of sleep, heart-rate variability, skin temperature, and recovery with much better wearability and lead to fewer screen-related distractions. In May 2026, Oura launched Ring 5, which can track over 50 health metrics, showing the growing potential of tiny wearables. Moreover, smart insoles and trackers worn on the legs can analyze balance, stride, cadence, and the performance of the lower body, while adhesive patches capture metabolic or physiological signals non-stop. These designs meet different user requirements by providing enhanced comfort, allowing specialized sensor placement, and being suitable for continuous monitoring (Source: ouraring.com).
Medical-Grade Monitoring Features
Medical functionalities are bringing advanced fitness trackers closer to the healthcare realm. ECG records electrical activity of the heart and can be used in the detection of irregular rhythms, while SpO₂ allows users to see their oxygen saturation whilst they are sleeping, exercising, or at altitude. HRV analysis provides information about autonomic balance, recovery, and physiological stress. Motion sensors can be turned into fall-detection systems and combined with algorithms to detect a hard fall and send out an urgent alert if the person doesn’t move. At the same time, technology to measure blood pressure without a cuff is advancing. These features enable earlier risk identification and more informed clinician discussions, though regulatory clearance and measurement reliability differ across devices and regions.
Real World Use Cases
Fitness trackers support distinct health, wellness, performance, and safety requirements across consumer, workplace, athletic, and healthcare settings.
- Personal Fitness and Weight Management: People use fitness trackers and smartwatches to count their steps, track exercise length, calories burnt, and exertion. Progress trackers and goal prompts promote consistency, enable users to monitor their behavioral changes, and help them stay motivated in the weight management program.
- Chronic Disease Management: Continuous glucose monitoring CGM wearables such as Dexcom Stelo, and Abbott Lingo provide eligible users with real-time on how they are affected by meals, exercise, sleep, and stress. This information can enhance everyday condition management as well as enable better conversations with your doctor.
- Corporate Wellness Programs: Employers weave health monitoring wearables into their workforce programs, through activity competitions, rewards programs, and insurance-based wellness perks. The consolidated participation stats enable corporate to gauge program engagement, while employees have tangible goals that motivate them to keep moving and not sit for too long.
- Athletic Performance Optimization: Professional and recreational athletes are using GPS enabled devices, such as Garmin Fenix and Polar Vantage series, to analyze pace, distance, elevation, heart rate, training load, and recovery. Using these metrics, coaches can adjust the training intensity, fatigue management, and the athlete’s peaking process for competition.
- Remote Patient Monitoring: Healthcare professionals may be able to link certain compatible wearable data to telehealth platforms or EHRs. Real-time monitoring of cardiac rhythms, blood oxygen, sleep, activity, and blood pressure trends enables between-visit follow-up and enhances clinicians’ ability to identify changes that warrant further workup.
- Senior Safety and Independent Living: Fall detection, location tracking, and emergency SOS are features that help keep seniors safe, especially those who live alone or like to travel. Devices such as the Apple Watch and Samsung Galaxy Watch can raise alerts in the event of a fall or other critical event, enabling faster communication with caregivers or emergency contacts and helping seniors continue living at home.
Regulatory Landscape
The regulation of fitness trackers is increasingly being established by whether the device is providing general information related to wellness or has functionality that is used in medical evaluation, diagnosis, or treatment.
In the European Union (EU), certain fitness trackers that incorporate software or functions as a medical device are subject to the EU Medical Device Regulation (MDR) and shall comply with the applicable classification, clinical evaluation, conformity assessment, and post-market requirements. In contrast, software that is developed exclusively for health or fitness purposes is not medical device software under the MDR. The EU AI Act introduces a further regulatory layer for AI-enabled wearable technologies. AI systems serving as safety components of a medical device, or as a medical device, are subject to high-risk classification if the product with which they are integrated requires third-party conformity assessment, introducing additional demands in relation to risk management, documentation, transparency, and regulatory compliance.
In January 2026, the U.S. Food and Drug Administration (FDA) issued an update to its General Wellness Policy for Low-Risk Devices guidance. The 21st Century Cures Act now clarifies the agency’s enforcement policy regarding certain low-risk products that encourage healthy habits, including certain non-invasive, wearable devices. Devices with higher risks to patients may continue to be subject to formal device regulation, validation, and premarket requirements (Source: fda.gov).
In connected-wearable services, data governance plays a further role. HIPAA is implicated when a covered entity or business associate possesses PHI via mobile app or track technology. But consumer fitness data collected independently may not be subject to HIPAA unless it’s processed within a regulated healthcare relationship.
Source: Polaris Market Research Analysis
Segmental Insights
By Product
The market, by type, is segmented into smartwatches, smart bands, smart clothing, and others. The smartwatches segment held the largest share of 48.0% in 2025. This is due to their multi-dimensional features, which are more than just simple smartwatch health tracking, but also include communication, applications, and advanced health features. Due to the fact that smartwatches have a wider range of applications, they are able to serve a larger group of customers, not only fitness enthusiasts, but also those seeking all-in-one wearable fitness device to manage their day-to-day life.
The smart clothing segment is projected to register a 21.38% CAGR during the forecast period. This massive growth is driven by rising research and development activities in embedding sensing technology into textiles. Smart clothing can enable continuous and modest monitoring of physiological parameters under different circumstances without using another wearable device. The development of textile-based sensors, data processing, and wireless communication is turning smart clothing into a reality for the monitoring of sports performance, healthcare, and even workplace safety, increasingly becoming more practical and attractive.
Comparison Matrix for Product Type
| Product Type | 2025 Market Share | Growth Rate (CAGR) | Key Features | Primary Users | Price Range |
| Smartwatches | 48.0% | Moderate-high | ECG, SpO₂, GPS, NFC, app ecosystem | General consumers, professionals | USD 100–800+ |
| Smart Bands / Fitness Bands | 27.0% | Fastest overall | Step count, HR, SpO₂, sleep; long battery | Budget-conscious consumers, entry-level users | USD 20–150 |
| Smart Clothing | 15.0% | Fastest CAGR (21.38%) | Textile sensors, gait, posture, muscle monitoring | Athletes, sports scientists, rehab patients | USD 80–300+ |
| Smart Rings | 6.0% | High growth | Sleep, HRV, temperature, SpO₂; discreet form | Sleep-focused users, privacy-conscious consumers | USD 200–500 |
Source: Polaris Market Research Analysis
By Application Analysis
By application, the market is segmented into heart rate tracking, sleep monitoring, glucose monitoring, sports, running tracking, cycling tracking, and others. In 2025, the heart rate tracking segment held the largest share of 28.0%. This is largely due to the prevalence of heart rate monitoring devices in most, if not all, fitness trackers, from simple smart bands to health monitoring wearables. Heart rate monitoring is a core tracker most consumers use daily in their general wellness. Continuous tracking of heart rate now plays a pivotal role in cardiovascular health that users can see in both exercise and rest. Thus, these devices are becoming fundamental, as users across the board, from simple wellness to the elite physically active, want good, solid heart rate tracking. The well-established usefulness and almost universal presence of heart rate tracking features on many types of devices that play this genre of games also help it maintain its top ranking.
The glucose monitoring segment is anticipated to grow at the highest CAGR of 21.83%. The increasing prevalence of diabetes drives growth in the glucose monitoring wearable marketgrowth . Developments in wearable sensor technology and device miniaturization are enabling the inclusion of glucose monitoring features in wearable fitness monitors. Technological developments are making glucose monitoring more accurate, convenient, and accessible. Rising demand for non-intrusive monitoring systems and rising requirements in diabetes management are expected to offer massive growth opportunities for glucose monitoring applications in the fitness trackers market.
By Wearing Type
The fitness trackers market segmentation, by wearing type, includes hand wear, leg wear, head wear, and others. The hand wear segment accounted for the maximum share of 78.0% in 2025. This is largely attributed to the massive popularity and firmly established trust on wrist-worn devices like smartwatches or smart bands. The comfort of wearing these devices on the wrist and their seamless integration with daily activities and fashion tastes have contributed to making these devices the top choice among consumers who want to track their fitness. The maturity of the technology, the range of designs and uses, and consumers being already used to it mean the handwear segment is the dominant one.
The legwear segment is expected to register the highest CAGR of 15.50% during the forecast period. This growing adoption is led by the emergence of new age wearable technology such as smart socks and legwear embedded with sensors of detecting biometric data. These help in analyzing walking patterns and, thereafter, sports performance, or follow up on rehabilitation. The legwear segment within the industry is rapidly expanding due to its specialized features and the ability to collect data without being too intrusive. Rising interests in biomechanics and the advent of sophisticated textile-based sensors are among the reasons behind this high growth curve.
Distribution Channel
By distribution channel, the market is segmented into online and offline. The offline distribution channel is expected to witness 14.42% CAGR during the forecast period. This dominance is largely attributed to the high preference for traditional brick-and-mortar electronics retail stores, sporting goods stores, and department stores, which have long been well-established and afford customers the opportunity to hold the products in their hands before making a decision. Being able to try on devices and in-person assistance from sales staff boost the dominance of the offline channel segment.
At present, the online distribution channel accounted for a major share of 64.0% in 2025. This explosive growth is fueled by increasing e-commerce penetration and consumers' rising preference to shop from the comfort of their own home. The online channel has the benefit of a more extensive product range, better prices, and the convenience of shopping at any time and any place. In addition, online stores tend to include detailed product information, customer reviews, and comparison tools. Using these insights, consumers can make informed decisions. The growing popularity of electronic commerce and increasing internet coverage promote the adoption of the online distribution channel in the fitness trackers industry.
Source: Polaris Market Research Analysis
Regional Analysis
North America Fitness Trackers Market Assessment
North America accounted for the largest share of 43.0% in the fitness trackers market in 2025 owing to the high health consciousness, rising disposable income, and early adoption of connected health devices in the region. The region has established retail, e-commerce, healthcare, and corporate wellness channels that make wearable products more easily available. Demand is also driven by growing consumer interest in tracking exercise, sleep analysis, heart monitoring, and preventive health. As of April 2026, the CDC stated that 47.2% of U.S adults met federal guidelines for aerobic physical activity, while 54.0% of adults between the ages of 18 and 34 were physically active. With an active consumer base and established digital-health infrastructure, the region appears to be the leader in the global market.
U.S. Fitness Trackers Market Assessment
The U.S. fitness trackers market held the largest revenue share of 82.0% in 2025. It is attributed to the fact that consumers spend a high amount on electronics, followed by a high rate of adoption of wearable fitness devices and a high penetration of smartphones. Established technology companies, growing corporate wellness programs, advanced digital health infrastructure, and increasing consumer demand for personalized monitoring also enhanced the fitness trackers market share.
Asia Pacific Fitness Trackers Market Trends
The market in Asia Pacific is expected to register a 19.7% CAGR during the forecast period. This is owing to increasing disposable income, rapid urbanization, and growing inclination of people toward maintaining personal health. The growing penetration of smartphones is enabling consumers to use trackers along with mobile health applications, digital payment platforms, and online fitness platforms. The demand is also driven by domestically produced products and their low cost. Wider penetration of e-commerce and the rising awareness of sedentary lifestyles and associated illnesses also fuel the growth. As per a Government of India March 2026 report, 85.5% of Indian homes owned a smartphone, and the internet was accessed by over 1.09 billion people. This seamless connectivity enables stronger adoption of wearables in urban, second city, and even rural consumer markets in India (Source: pib.gov).
Japan Fitness Trackers Market Insights
The fitness trackers market in Japan is expected to grow at a 17.40% CAGR during the forecast period. This is owing to the rising elderly population, increasing health consciousness, and rising adoption of health tracking with smartwatches. Increasing focus on preventive healthcare wearables, remote health management, and sophisticated consumer electronics is further boosting the demand for connected fitness solutions.
China Fitness Trackers Market Analysis
China accounted for the largest share of 45.0% in the Asia Pacific market in 2025, owing to the presence of large-scale electronics manufacturing, low prices, and high penetration of activity tracker devices in the country. The growing adoption of e-commerce channels, rising health consciousness, smartphone integration, and increasing adoption of AI fitness tracker solutions accelerate market penetration.
Europe Fitness Trackers Market Assessment
In 2025, the fitness trackers market in Europe represented a share around 17.0%. This is owing to the presence of high-level interest in preventive health and active aging, and digitally enabled wellness. Products that offer a convergence of fitness metrics with sleep, heart health, stress, and recovery data have become more popular with consumers. The region’s mature healthcare system also facilitates strong connections between consumer wearables and wider digital health solutions. Demand remains particularly strong in Germany, the UK, France, Italy, and the Nordic countries. High standards around privacy, product safety, and measurement accuracy also influence purchasing decisions and push vendors to compete on the basis of trustworthy data practices, validated technology, robust designs, and transparent health claims.
Latin America Fitness Trackers Market Overview
Latin America held a 17.0% revenue share in 2025. The market's expansion in Latin America is attributed to growing health consciousness, rising smartphone penetration, and the increasing availability of low-cost fitness bands and smartwatches. Additionally, interest in exercise tracking, weight management, sleep monitoring, and connected well- being applications is increasing among urban consumers. E-commerce channels have expanded product availability beyond major retail hubs and allow buyers across regions to compare more models. Budget products still have their place as the buying power of consumers is highly variable between countries and demographics. Brazil and Mexico are the major centers of demand, although improving digital access and a pervasive fitness culture are driving take-up in other markets of the region.
Middle East & Africa Fitness Trackers Market Outlook
The Middle East and Africa fitness trackers market is expected to register a CAGR of 14.0% during the forecast period. People are becoming more health-conscious and digitally connected. The majority of demand is in the richer Gulf states, where consumers show a strong interest in premium smartwatches, connected fitness services and wellness driven by technology. Increasing concern about obesity, diabetes, and cardiovascular health is also promoting more focus on daily activity and lifestyle. Adoption is also being driven by the penetration of smartphones and the increasing availability of lower-cost wearables in developing African countries.
UAE Fitness Trackers Market Assessment
The UAE fitness trackers market is expected to exhibit a CAGR of 19.40% over the forecast period. Rising health consciousness, digital healthcare initiatives, high smartphone usage, among others are driving the growth. Increasing demand for health monitoring wearables, sleep tracking wearable solutions, and connected heart rate monitoring devices is driving adoption as consumers place greater emphasis on technology-enabled wellness and preventive healthcare.
| Region | 2025 Revenue Share | CAGR (2025–2034) | Market Status | Key Growth Driver | Notable Country |
| North America | 43.0% | 16.04% | Largest market | Corporate wellness programs, FDA cleared wearable health devices, strong tech adoption | USA — 30%+ of global market |
| Asia Pacific | 30.0% | 19.71% (fastest) | Fastest-growing | Rising middle class, local brands, smartphone penetration, APAC manufacturing hubs | China + India dual-engine growth |
| Europe | 17.0% | 16.10% | Mature, steady | Preventive healthcare, aging population, Cyber Resilience Act raising quality bar | Germany, UK leading |
| Latin America | 17.0% | 17.80% | Emerging | Digital banking fitness rewards (Brazil), urban fitness culture, affordable smart band adoption | Brazil strongest |
| Middle East & Africa | 14.0% | 18.60% | Nascent / growing | Government chronic disease screening (Gulf states), urban health awareness | UAE, Saudi Arabia lead |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
Competitive Analysis
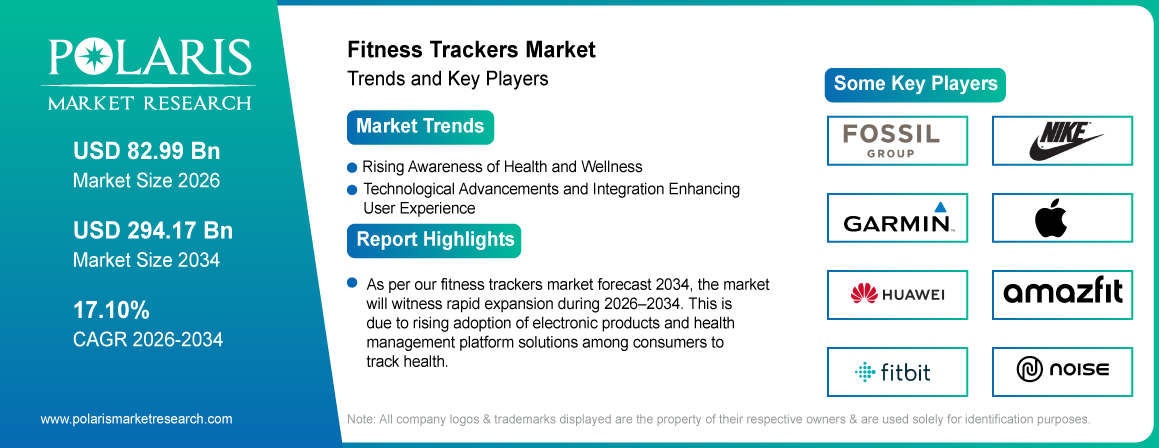
Major companies in the market offer a diverse range of products, including smartwatches and smart bands. Market players are increasingly emphasizing the AI integration with smart tracking devices, catering to various consumer needs and preferences in health and wellness monitoring. The competitive environment is evolving with a degree of innovation, product differentiation, and strategic collaboration. Companies are rising up to the challenge of making tracking more precise. They are focusing on tracking not just basic fitness metrics but more advanced health monitoring options such as SpO2 and ECG. They are emphasizing delivering a better user experience through deeper software integration and longer battery life. Price levels, design aesthetics, and brand name popularity can also affect consumers’ decisions. The market is becoming more competitive as established technology giants and new entrants compete for market share through novel features and the target users they want to serve. Competition is also shifting toward ecosystem-based business models that combine wearable hardware with subscription services, cloud analytics, mobile apps, and personalized coaching. Mainstream brands have the advantage of large customer bases and compatible device portfolios, and specialized brands compete with each other in sleep assessment, athletic recovery, metabolic health, and women’s wellness. Regional manufacturers add to the price competition and provide higher-featured devices for price-sensitive consumers. Distribution through e-commerce channels, as well as telcos, healthcare partners, and corporate wellness programs, also expands market growth. As product functionality converges, companies will need to differentiate on the quality of their data, privacy protections, user retention, platform interoperability and ongoing software support.
Key Players
- Amazfit (Zepp Health Corporation)
- Apple Inc.
- Fitbit LLC (Google LLC)
- Fossil Group Inc.
- Garmin Ltd.
- Huawei Technologies Co., Ltd.
- Nike Inc.
- Noise (Go Noise)
- Oura Health Oy
- Polar Electro Oy
- Samsung Electronics Co., Ltd.
- Suunto Oy (Amer Sports)
- Ultrahuman
- Whoop Inc.
- Xiaomi Corporation
Competitive Comparison Table
| Company | Flagship Products | Market Position | Key Differentiator | Target Segment | Notable 2025–2026 Move |
| Apple Inc. | Apple Watch Series 10, Ultra 2 | Premium leader | Ecosystem integration, FDA-cleared health features | General & health consumers | Sleep apnea FDA clearance 2024; AI health coaching watchOS 27 (2026) |
| Google (Fitbit) | Fitbit Charge 6, Sense 3 | Mid-market | Google Health integration, community-driven data | General fitness users | Deeper Google AI health integration; EHR data export |
| Samsung Electronics | Galaxy Watch 7, Watch Ultra | Premium-mid | AI health analytics, Galaxy ecosystem tie-in | Android users, tech enthusiasts | AI overnight vital-sign monitoring (2026); glucose trend research |
| Garmin Ltd. | Fenix 8, Forerunner 965 | Performance niche | Military-grade durability, advanced GPS, 2-week battery | Endurance athletes, outdoor users | 6-year refurbishment program; Leiden Univ. depression prediction study |
| Xiaomi Corporation | Smart Band 9 Pro, Redmi Watch | Value leader | Sub-USD 50 pricing, wide distribution in APAC | Budget / mass market | 150+ sports modes, integrated GPS in Band 9 Pro (2023) |
| Huawei Technologies | Watch GT 5 Pro, Band 9 | Mid-market (APAC focus) | Long battery life, health-focused features | APAC consumers | Watch FIT 5 partner ecosystem expansion (June 2026) |
| Oura Health Oy | Oura Ring Gen 4 | Premium niche | Ring form factor, sleep/recovery depth, subscription model | Sleep-focused, biohackers | USD 75M Dexcom investment; CGM data fusion partnership |
| Whoop Inc. | Whoop 5.0, Whoop MG | Performance subscription | No screen, strain/recovery focus, 14-day battery | Athletes, fitness professionals | Whoop 5.0 launch May 2025; medical-grade subscription tier |
| Amazfit (Zepp Health) | Active 2, T-Rex Ultra | Value-premium | PulsePrecision algorithm, 160+ sports modes | Budget-to-mid performance users | Active 2 India launch April 2025 with PulsePrecision & RestoreIQ |
| Ultrahuman | Ring AIR | Emerging niche | Metabolic health analytics, no subscription | Biohackers, quantified-self users | Growing in India & Western markets; AI metabolic scoring |
| Polar Electro | Pacer Pro, Grit X2 | Sports niche | Elite heart rate accuracy, training analytics | Endurance athletes | 5-year research partnership with Leiden University (via Garmin) |
| Noise (Go Noise) | Noise Colorfit Ultra 3 | India value brand | Aggressive pricing, India-first features | India mass market | Rapid SKU expansion in Tier 2/3 Indian cities |
Source: Polaris Market Research Analysis
Industry Developments
- June 2026: Huawei expanded its watch's health app ecosystem with partners like Life, Clue, and The Ginger Club. This strategic move focuses on delivering cycle tracking, data-driven health insights, and personalized training features directly to users' wrists through an open platform. (Source: app.dealroom.co)
- May 2026: Google launched Fitbit Air, their smallest, screenless wellness tracker, designed for 24/7 comfort and simplicity. It offers advanced health monitoring and seamlessly integrates with the Google Health Coach app. It features up to a week of battery life and various stylish, swappable bands. (Source: blog.google)
- March 2025: Radicle Science launched Journey, the first health-impact tracker for wellness brands, enabling real-world data collection, personalized health insights, and real-time visualization for consumer engagement programs. (Source: prnewswire.com)
- May 2025: Whoop launched its new wearables, Whoop 5.0 and Whoop MG, featuring 14-day battery life, sleeker hardware, enhanced health insights, and new membership tiers, aiming to help users optimize performance, monitor stress, and track aging more effectively. (Source: whoop.com)
Future Outlook
As per our fitness trackers market forecast 2034, the market will witness rapid expansion during 2026–2034. This is due to rising adoption of electronic products and health management platform solutions among consumers to track health. Developments in biosensors, artificial intelligence (AI), edge processing, and battery efficiency will enable smaller devices to provide continuous, increasingly accurate physiological insights. Medical-grade innovation will remain key aspect, with ECG, blood oxygen, heart rate variability, sleep apnea evaluation, fall detection, cuffless blood pressure monitoring, and continuous glucose monitoring seeing wider adoption. Regulatory approval and clinical validation will become more stringent competitive differentiators as companies move into preventive health care, remote patient monitoring, and chronic disease management. Smart rings, clothes with embedded sensors, and wearables without screens will expand the types of people who participate by offering fewer invasive ways to monitor oneself. At the same time, the data from wearables will flow on through integration with telehealth systems, electronic health records, insurance and corporate wellness programs to inform organized care and workplace health offerings. Providers that can offer secure data management, interoperable ecosystems, personalized coaching, and subscription-based analytics services will be best positioned to drive recurring revenues and stay engaged with consumers over the long term.
Market Segmentation
By Product Type Outlook (Revenue – USD Billion, 2021–2034)
- Smart Watches
- Smart Bands
- Smart Clothing
- Others
By Application Outlook (Revenue – USD Billion, 2021–2034)
- Heart Rate Tracking
- Sleep Monitoring
- Glucose Monitoring
- Sports
- Running Tracking
- Cycling Tracking
- Women's Health & Fertility
- Senior Safety & Occupational
- Others
By Wearing Type Outlook (Revenue – USD Billion, 2021–2034)
- Hand Wear
- Leg Wear
- Head Wear
- Others
By Distribution Channel Outlook (Revenue – USD Billion, 2021–2034)
- Online
- Offline
By Regional Outlook (Revenue – USD Billion, 2021–2034)
- North America
- U.S.
- Canada
- Europe
- France
- Germany
- UK
- Italy
- Netherlands
- Spain
- Russia
- Asia Pacific
- Japan
- China
- India
- Malaysia
- Indonesia
- South Korea
- Australia
- Latin America
- Brazil
- Mexico
- Argentina
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
Fitness Trackers Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 71.04 billion |
| Market Size Value in 2026 | USD 82.99 billion |
| Revenue Forecast by 2034 | USD 294.17 billion |
| CAGR | 17.10% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Volume Tons; Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Insights |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Fitness Trackers Market FAQ's
The fitness trackers market size was valued at USD 71.04 billion in 2025 and is projected to grow to USD 294.17 billion by 2034.
The market is projected to register a CAGR of 17.10% during the forecast period of 2026–2034.
North America held the largest market share of 43.0% in 2025. The dominance is driven by rising health consciousness among consumer and advanced digital health infrastructure.
Key players in the fitness trackers market include Amazfit (Zepp Health Corporation); Apple Inc.; Fitbit LLC (Google LLC); Fossil Group Inc.; Garmin Ltd.; Huawei Technologies Co., Ltd.; Nike Inc.; Noise (Go Noise); Oura Health Oy; Polar Electro Oy; Samsung Electronics Co., Ltd.; Suunto Oy (Amer Sports); Ultrahuman; Whoop Inc.; Xiaomi Corporation.
The online distribution channel held a 64.0% share in 2025. Rising penetration of e-commerce and increasing preference of consumers to shop from the comfort of their home drives the dominance.
Fitness trackers are wearable devices or apps that monitor physical activity and physiological data like steps, heart rate, and sleep. Using sensors, they sync data to smartphones for tracking progress and health insights. Their purpose is to motivate healthier habits and monitor key health indicators over time.
A fitness tracker primarily focuses on health and activity monitoring (steps, heart rate, sleep, calories) and typically lacks advanced smartphone features. However, a smartwatch extends these capabilities to include calls, messaging, app ecosystems, contactless payments, and navigation.
Fitness trackers use hardware sensors, including accelerometers, photoplethysmography (PPG) sensors for heart rate, GPS modules, and ECG electrodes, to collect continuous physiological data. This data is processed by on-device AI chips and synced via Bluetooth to smartphone apps, where AI algorithms generate personalized health insights, coaching recommendations, and anomaly alerts.
A few main types of fitness trackers are smartwatches, fitness/smart bands, smart clothing, smart rings, and CGM patches & other wearables, including glucose monitoring devices and clip-on trackers.
Accuracy varies by device tier and feature. FDA-cleared features on premium smartwatches (e.g., Apple Watch's ECG and sleep apnea detection) meet medical-grade standards. Basic step counting and heart rate tracking in mainstream devices have accuracy rates above 90% in controlled studies. Budget devices may show reduced accuracy for SpO? and stress metrics. Continuous glucose monitoring wearables that have received FDA OTC clearance (e.g., Dexcom Stelo) meet clinical accuracy standards.
By 2034, fitness trackers are expected to evolve into comprehensive health management platforms, combining consumer convenience with medical-grade diagnostics. Key developments include cuffless blood pressure monitoring, continuous non-invasive glucose sensing, AI-driven early disease detection, integration with digital therapeutics reimbursement pathways (via CMS CPT codes), and expanded adoption among older adults and chronic disease patients.
Download Sample Report of Fitness Trackers Market
Please fill out the form to request a customized copy of the research report.