Healthcare Interoperability Solutions Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Healthcare Interoperability Solutions Market Summary
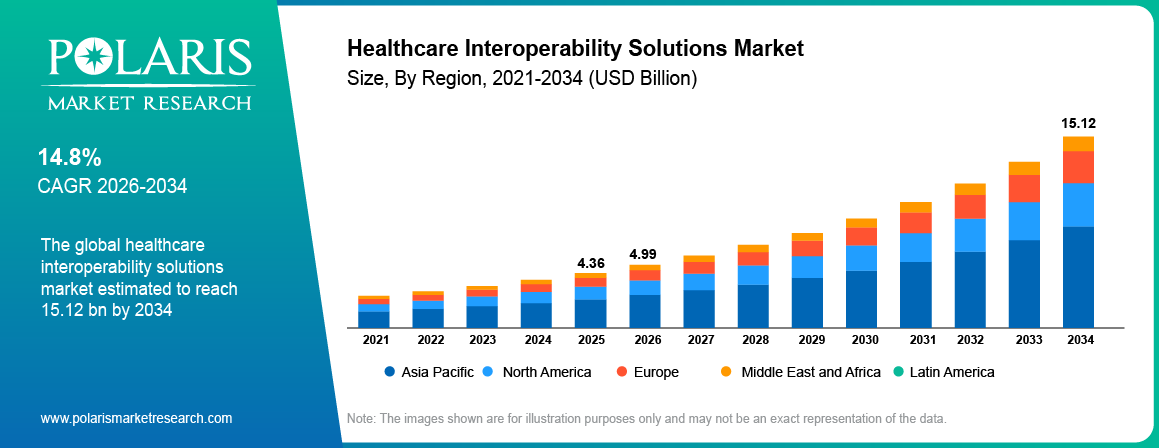
The global healthcare interoperability solutions market size was valued at USD 4.36 billion in 2025. The market is projected to account for an 14.8% CAGR from 2026 to 2034. The rising adoption of electronic health records (EHRs) is one of the primary factors driving the healthcare interoperability solutions market growth. The market is also shaped by favorable government regulations supporting interoperability.
Market Statistics
Key Takeaways
- North America held the largest healthcare interoperability solutions market share of 42.27% in 2025. Its strong EHR interoperability adoption and advanced healthcare IT infrastructure contribute to the regional market dominance.
- Asia Pacific is projected to witness the fastest growth at a 16.63% CAGR. Rising government spending on healthcare facilities is driving the regional market growth.
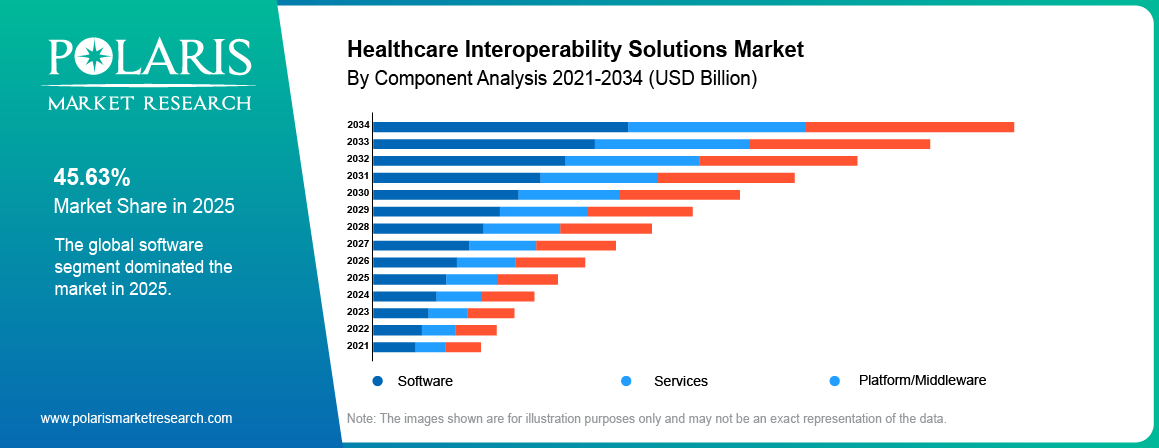
- By component, the software segment held a 45.63% market share in 2025. This is owing to the need to eliminate information silos across disparate platforms.
- By deployment model, the on-premises segment accounted for a 52.37% healthcare interoperability solutions market share in 2025. This is attributed to the growing preference for internal data control among large organizations.
- By interoperability level, the structural segment led with a 39.46% share in 2025. It provides the foundational framework needed for passing standardized data.
- By end user, the healthcare payers segment is projected to grow at a 16.85% CAGR. The rising adoption of payer-provider interoperability services contributes to the segment’s rapid growth.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Is the Healthcare Interoperability Solutions Market?
Healthcare interoperability solutions enable the exchange of patient data through various healthcare systems using a standard data format. These solutions connect EHRs, hospitals, laboratories, pharmacies, and other healthcare platforms, enabling data interchange. The healthcare interoperability market encompasses the software and services required for EHR interoperability and EHR integration.
The value chain includes technology vendors, healthcare organizations, and other entities involved in linking systems, sharing information, and making use of patient data.
How Healthcare Interoperability Works?
Healthcare interoperability refers to linking various systems so healthcare data can travel across systems in order to become usable. In general, this process entails several phases.
- Data creation: This is the stage at which patient data is generated in systems such as EHR systems, lab platforms, and hospital information systems.
- Data structuring: This stage is characterized by the structuring of the generated data in a way that can be understood by other healthcare systems.
- Connection of the systems: Healthcare interoperability allows for connecting healthcare platforms with each other in order to exchange information.
- Data exchange: Patient data is then exchanged between authorized healthcare platforms.
- Interpretation of Data: The receiver’s system interprets the information and translates it into its data format for appropriate use.
- Usage of Information: The health workers are able to utilize the relevant information from their system for various purposes related to healthcare provision.
Market Dynamics
The healthcare interoperability market is influenced by developments in healthcare technology, data exchange requirements, and care delivery. The increasing adoption of EHRs and digital health platforms increases the demand for interoperable systems. At the same time, the expenses of implementation, legacy infrastructures, and issues related to data security can slow implementation. New opportunities are emerging through artificial intelligence and FHIR data exchange.
Drivers : Rising Adoption of Electronic Health Records
Increasing adoption of electronic health records is contributing to the growing need for connections between patients' data in various healthcare organizations. Hospitals, physician offices, laboratories, and other types of providers may have a variety of systems in use, which means that it is hard to share information in the absence of interoperability technologies. Data provided by the latest National Electronic Health Records Survey indicate that adoption of EHRs by office-based physicians in the U.S. is almost universal (source: healthit.gov). With telehealth services gaining popularity, there is an increased need to connect information in records. Healthcare organizations need to process large amounts of information received from diagnostic systems, medical devices, and digital health platforms. In March 2026, HL7 International introduced the Caliper FHIR Accelerator that allows exchanging data from medical devices using FHIR standards in real time (source: hl7.org). The increasing need for connected information is driven by the growth of value-based care and data sharing, as providers need to have access to patient information from different places. Adoption of AI technology is yet another factor contributing to the increased need for structured and accessible healthcare data.
Drivers :Government Regulations Supporting Interoperability
The ongoing modernization of healthcare systems through government interventions is prompting healthcare providers to move away from fragmented IT solutions. Public health care systems today emphasize digitization and information exchange through digital means. This has led to the increased demand for systems that would be able to integrate with the existing technologies without the need to replace the entire IT system infrastructure. Digital health programs funded by governments are helping the adoption of standardized methods of exchanging data. In the U.S., ongoing investments in health information infrastructure at the national level are raising awareness about the concept of interoperability among healthcare organizations. Similar efforts in Europe and other parts of the world are contributing to the adoption of digital health programs as well as cross-system data exchange. Interoperability, in this regard, is an integral part of digital transformation rather than just a technological investment.
Restraints and Challenges : High Implementation Costs and System Integration Challenges
High costs of implementation and maintenance can hinder the healthcare interoperability solutions market development, especially in small healthcare facilities with limited technology budgets. Another challenge is associated with the integration of new technology with existing ones. The older infrastructure may not always be able to process new data exchange standards. Differences in standards and formats used in healthcare systems can hinder information exchange and require data integration. Moreover, interoperable solutions also pose cybersecurity challenges, since implementing interoperability increases the number of endpoints that process patient data. Healthcare facilities should invest in protecting patients' information as it moves from one platform to another. The complexity of regulatory requirements can also be the source of increased expenditures related to implementation.
Opportunities : AI-Based Data Mapping and FHIR Exchange
AI can be helpful in resolving discrepancies in the way patient information is captured by healthcare organizations. Applications that can extract information from unstructured records and convert it into standardized forms can facilitate the utilization of legacy data across healthcare platforms. This opens up a possibility for interoperability vendors to integrate AI with data mapping and normalization functions. In June 2026, Google announced that India's National Health Authority had used the company's Medical Data Toolkit and Gemma 4 open models on its Aarogya Setu 2.0 application. The tools can detect health-record types, extract information such as names of laboratory tests and their results from text and imagery, and normalize the extracted information to FHIR data format. The Medical Data Toolkit has been made freely accessible by Google as an open-source software solution (source: blog.google). Such solutions would help in digitizing and normalizing legacy health record information. FHIR-based exchange can also assist in integrating information among EHRs and other digital health applications. As the need for interoperability between different data sources increases, the solutions for automated mapping and normalization become necessary. This, in turn, presents opportunities for healthcare interoperability solutions market providers.
TEFCA & U.S. Regulatory Landscape
TEFCA has become a key part of the U.S. approach to nationwide health information exchange. Its framework connects health information networks under common terms, while CMS and ONC set separate requirements for health IT, data access, and interoperability. Privacy and security rules apply to the exchange of protected health information.
TEFCA Participation in 2026
TEFCA refers to a national framework that facilitates the exchange of electronic health information between various health information networks. The organizations that participate in this exchange form Qualified Health Information Networks (QHINs). Some of the exchanges covered under the TEFCA framework include treatment, individual access, public health, and payment exchanges.
Participation has increased dramatically since the launch of TEFCA in December 2023. The RCE reported more than 23,000 participants through QHINs, Participants, and Subparticipants as of September 2026 (source: rce.sequoiaproject.org). There are over 104,000 connections to health care organizations and other entities. More than 1 billion documents have been exchanged through TEFCA since launch (source: hhs.gov). The RCE maintains the current designated QHIN list, while its TEFCA map shows organizations connected through participating QHINs.
TEFCA participation can take place through a QHIN or through a Participant or Subparticipant connected to one. This structure gives organizations another route for exchanging information outside their existing networks. In comparison, a traditional HIE may operate within a particular region or group of healthcare organizations. This distinction is useful when considering TEFCA vs health information exchange. For further context, check the health information exchange market report.
CMS and ONC Interoperability Rules
CMS and ONC have established separate requirements covering health information access, certified health IT, and electronic prior authorization. The CMS Interoperability and Prior Authorization Final Rule, CMS-0057-F, requires certain payers to implement FHIR-based APIs, including Provider Access, Payer-to-Payer, and prior authorization API capabilities. Certain operational requirements began in 2026, while the main API compliance dates generally begin in 2027. CMS also released the 2026 Interoperability Standards and Prior Authorization for Drugs proposed rule, CMS-0062-P, in 2026 (source: cms.gov). On the health IT side, ONC adopted USCDI v3 as the baseline standard for its certification program from January 1, 2026 (source: healthit.gov). Its HTI-1 rule also revised information-blocking provisions and added an exception related to secure, standards-based exchange. These measures are part of the interoperability framework established under the 21st Century Cures Act.
Privacy, Security & Compliance
Privacy and security requirements remain a separate consideration when organizations exchange patient information. HIPAA establishes guidelines about the security of health information and its use and disclosure. Control mechanisms are required by healthcare organizations regarding the identity of users, authentication, authorization, and access to records. Zero-trust frameworks can be used for authentication and authorization of users and devices prior to giving them access rather than relying only on network location. Such control mechanisms become necessary while moving information among providers, payers, applications, and information exchange platforms. Security requirements can add technical and administrative work to interoperability projects, particularly when several organizations share responsibility for the same data. For related market context, see the healthcare cybersecurity market report.
Standards & Technology: FHIR, HL7 and APIs
FHIR is a standard for exchanging healthcare information in a structured, machine-readable format, while HL7 develops standards that support the exchange of health data between different systems. APIs provide the connection through which applications can request and exchange this information. Together, these technologies support healthcare data integration, EHR interoperability, and EHR integration. Additional content can be gained from our analysis of the healthcare data Integration market.
Technology Comparison
Different interoperability technologies in the healthcare interoperability solutions market handle healthcare information in different ways. The table below compares their main functions and typical use within healthcare data exchange.
| Technology | Primary Role | Typical Use |
| HL7 | Defines standards for healthcare data exchange | Clinical and administrative information |
| FHIR | Uses modern, modular resources for data exchange | EHRs, applications, and digital health tools |
| APIs | Connects applications and allows data requests | Patient access and system integration |
Source: Polaris Market Research Analysis
Interoperability Levels Explained
Interoperability can be viewed across several levels, depending on how systems exchange and use information. Each level addresses a different part of the data-sharing process.
| Level | Description |
| Foundational | Creates the basic link required between systems for sharing information. |
| Structural | Details how information is formatted and structured when shared. |
| Semantic | Ensures understanding of the information by the system that receives it. |
| Organizational | Makes sure that policies, processes, and workflows match so that information shared is useful to the organization. |
Source: Polaris Market Research Analysis
It can be seen from these levels that simply making connections between two systems is not enough for interoperability. The data should also preserve its structure and semantics at the destination system.
Role of AI in Interoperability
Artificial Intelligence technology is now being used to process information that cannot easily be fitted into the healthcare standardization format. It is capable of finding relevant information within clinical documents, other unstructured texts, and mapping the information into standard formats. This technology may facilitate the conversion of unstructured data to FHIR standards and reduce the manual labor in preparing the information. Artificial Intelligence technologies may also help match fields and normalize the data when information comes from various sources. These applications contribute to AI healthcare interoperability by improving the usability of the data. This approach is helpful in cases of medical device interoperability (FHIR), as healthcare institutions collect information from devices into connected platforms. FHIR-based APIs can further process the information and deliver it to other applications.
Interoperable vs Siloed Healthcare Systems
Interoperability refers to the extent to which healthcare systems enable data sharing between different platforms. The interoperable system enables organizations to access information through common standardization interfaces. The siloed system keeps information confined within different platforms.
| Feature | Interoperable systems | Siloed systems |
| Regulatory readiness | Supports CMS/ONC requirements and TEFCA exchange | Often relies on manual workarounds |
| Duplicate testing | Less likely | More likely |
| Data format | HL7, FHIR, USCDI | Proprietary formats or separate interfaces |
| Patient access | APIs and TEFCA Individual Access Services | Separate portals |
| Data sharing | Across connected healthcare organizations | Mostly within individual systems |
| Integration | Common interfaces can connect systems | Separate connections may be needed |
| Care records | Information can be viewed across connected providers | Records may stay with the original provider |
Source: Polaris Market Research Analysis
Market Segmentation Analysis
The healthcare interoperability solutions market is segmented by component, interoperability level, deployment model, end user, and region. These segments reflect the main variations in technology, deployment, and customers within the market.
| Segmentation Axis | Segments |
| By Component | Software · Services · Platform/Middleware |
| By Interoperability Level | Foundational · Structural · Semantic · Organizational |
| By Deployment Model | Cloud-based · On-Premises · Hybrid |
| By End User | Hospitals & Clinics · Healthcare Payers · Pharmacies · Laboratories · Ambulatory Care Centers · Others |
| By Regional Outlook | North America (US, Canada) · Europe (Germany, France, UK, Italy, Spain, Netherlands, Russia, Rest of Europe) · Asia Pacific (China, Japan, India, Malaysia, South Korea, Indonesia, Australia, Vietnam, Rest of Asia Pacific) · Middle East & Africa (Saudi Arabia, UAE, Israel, South Africa, Rest of Middle East & Africa) · Latin America (Mexico, Brazil, Argentina, Rest of Latin America) |
Source: Polaris Market Research Analysis
By Component
The software segment held an 45.63% healthcare interoperability solutions market share in 2025. Use of software solutions aids in the exchange of information among different systems and applications. An interoperability platform helps connect EHRs with other applications. API management helps facilitate access to applications in terms of using API for data exchange. These features are deployed in order to facilitate the exchange of patients' data across different healthcare environments. Software implementation is also driven by the necessity to integrate the current systems without having to replace the entire IT infrastructure. With the increase in the volume of digital documents in healthcare organizations, software solutions are increasingly being used to improve access to information across connected systems.
The platform/middleware segment is projected to grow at an 17.47% CAGR. These solutions provide the technology layer for the integration of healthcare applications as well as the flow of data across them. An integration engine is capable of receiving data from various sources, transforming the same into a usable form, and delivering it to the respective application. This is applicable to those healthcare providers who have multiple systems from different vendors. Platform and middleware solutions also allow data mapping, message routing, and monitoring of the system. The use of such platforms eliminates the need for connecting every application independently. In the current environment where healthcare IT infrastructure is increasingly becoming integrated, healthcare providers are using middleware for managing data transfer within their existing systems.
By Interoperability Level
The structural segment held an 39.46% healthcare interoperability solutions market share in 2025. Structural interoperability may become necessary if healthcare institutions require the uniform management of clinical information in various systems. This type of interoperability facilitates the transfer of records between EHRs, lab information systems, hospital information systems, and other healthcare applications. The use of standardized data structures can minimize differences in how information is structured in separate systems. This allows for efficient processing of transferred records without a lot of manual manipulation. The segment is also facilitated by the increasing adoption of digital health platforms where information is transferred between several applications. Healthcare organizations can leverage structural interoperability in order to maintain uniform data management when integrating systems from different vendors.
The semantic segment is projected to grow at an 17.45% CAGR. Semantic interoperability can assist healthcare organizations in maintaining the meaning of clinical information when data is transferred between applications. Semantic interoperability is especially important for records containing medical terminology, diseases, medications, or lab results, which may differ in various systems. Standardized terminologies or code systems can help in mapping and understanding such differences. The segment is also relevant for health information exchange, as data could be transmitted between organizations working with different electronic health record systems. Improved semantic consistency will lower the chances of misunderstanding patient data and make the use of such records much more dependable.
By Deployment Model
The on-premises segment held an 52.37% healthcare interoperability solutions market share in 2025. On-premises deployment helps run interoperability systems in one’s own IT infrastructure. This solution might be appropriate for healthcare providers that want to have more control over access to the systems, storage of data, and network configuration. This solution might also be used by healthcare providers with existing data centers and IT departments that can manage the infrastructure. Some healthcare providers might prefer this solution if they have sensitive information within their system or have certain internal security policies to meet. On-premises solutions can also help with the integration of legacy systems that are difficult to migrate to the cloud.
The cloud-based segment is projected to grow at an 16.75% CAGR. With cloud deployment, healthcare organizations can run interoperability solutions using hosted infrastructure, rather than having the necessary hardware available within their own physical premises. In this way, it may be easier to upgrade the capacities of the system according to rising data volumes and additional applications. It may also provide remote capabilities for the organization operating in multiple locations. Cloud deployments are well suited for healthcare organizations looking to cut back on their infrastructural needs and upgrade the interoperability solution without major modifications to their premises. The increasing use of cloud deployments for EHRs and other digital health applications is also supporting cloud adoption in healthcare interoperability.
By End User
The hospitals & clinics segment led with an 40.23% healthcare interoperability solutions market share in 2025. Hospitals and clinics maintain and process patient data across various departments and specialties, hence the demand for interoperability solutions. These organizations are usually dealing with EHRs along with lab systems, pharmacies, imaging, billing, and other clinical information systems. The interoperability solutions may facilitate access to the required data without having to switch from one system to another. Moreover, the segment’s development is fueled by the growth of digital health services as well as by the necessity to synchronize patients' records from various locations. Networks of large hospitals also need interoperability solutions capable of connecting systems of several facilities at once.
The healthcare payers segment is projected to grow at an 16.85% CAGR. Payers deal with substantial amounts of member, claim, eligibility, and authorization data that often originate from various healthcare institutions. Interoperability technologies can help connect the payer IT infrastructure with the provider database and speed up access to the necessary information. Such functionality proves valuable when dealing with claims processing, care coordination, and cooperation between payers and providers. The increased prevalence of digital workflows in prior authorization and other administrative procedures is also driving the demand for more interconnected data systems. Using interoperability technologies, payers can cut back on manual data processing and improve data exchange.
| End User | Use of Interoperability Solutions |
| Hospitals/Clinics | Exchange of patient data between clinical and administration systems. |
| Healthcare Payors | Access provider and member data for claims, eligibility and authorization. |
| Pharmacies | Exchange of prescriptions and medications with healthcare providers and pharmacies. |
| Laboratories | Exchange of lab orders and test results with healthcare providers. |
| Ambulatory Care Centers | Exchange of patient data with other healthcare providers providing ambulatory services. |
| Others | Includes any other healthcare entity needing exchange and integration of patient and operational data. |
Source: Polaris Market Research Analysis
Healthcare Interoperability Use Cases
Healthcare interoperability solutions are applied in a range of healthcare processes. In EHR integration, patient records are linked to different applications within the healthcare sector, whereas HIE provides for data exchange among various organizations. Other applications include telemedicine, analytics, clinical workflows, and patients’ access to healthcare information.
| Use case | Named example |
| Payer–provider prior authorization | CMS Electronic Prior Authorization Acceleration initiative (29 organisations) |
| Payer coverage verification and data sharing | Humana and Epic: Coverage Finder and Digital Insurance Card Exchange |
| Medical-device data into EHRs and analytics | HL7 Caliper FHIR Accelerator |
| Patient access to records nationwide through healthcare data exchange | TEFCA Individual Access Services |
| Government benefits determination | Social Security Administration via the TEFCA Government Benefits Determination exchange purpose |
| Exchange between national networks through health information exchange (HIE) | Oracle Health Information Network as a Designated QHIN |
| Unstructured data to FHIR | HealthLX and Clairity Solutions, Anything to FHIR |
| EHR integration where no API exists | 10Bridge AI Agent Automation |
| EHR interoperability for clinical-trial data capture | IgniteData Archer at Cambridge University Hospitals with AstraZeneca |
| Healthcare data integration across EDI, FHIR, HL7, and NCPDP | Edifecs Healthcare Interoperability Cloud |
Source: Polaris Market Research Analysis
Regional Analysis
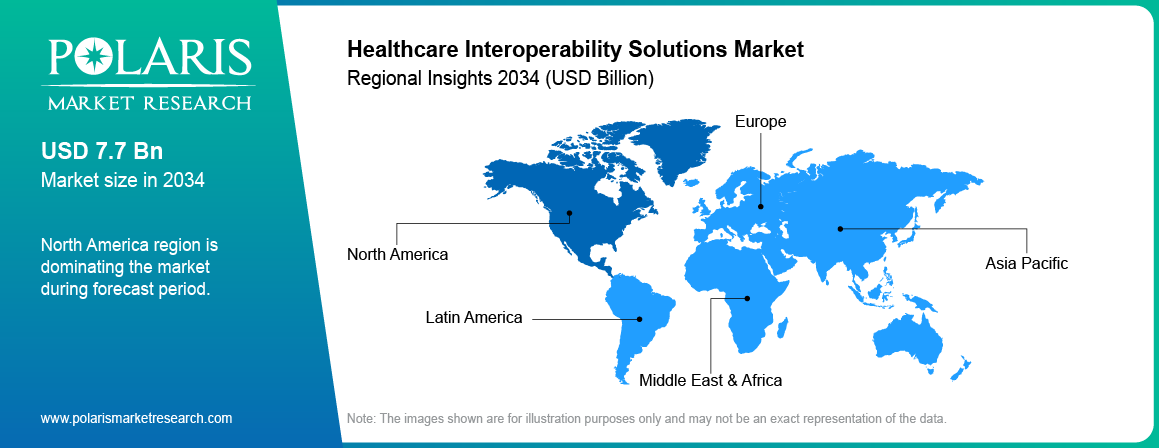
The healthcare interoperability solutions market varies across regions based on the use of digital health technologies, healthcare information technology infrastructure, and government policies. North America is characterized by an established environment of interoperability, whereas Europe is advancing in cross-border exchange of health data. The adoption of digital health technologies in the Asia Pacific region is increasing. Other regions are also focusing on developing their connected health care infrastructure and interoperability technology.
North America
North America accounted for the largest healthcare interoperability solutions market share of 42.27% in 2025. The U.S. accounts for a major share of the regional market because of its advanced healthcare sector and application of digital health solutions. The hospitals, physician practices, laboratories, and payer organizations operating in the country make use of various health IT solutions and require effective data exchange between the platforms. Canada is also developing its digital health infrastructure, where healthcare organizations use connected health IT solutions to access patient information. Both countries have established healthcare IT markets and a wide range of organizations that use electronic health records. Health information networks and interoperability vendors also support the development of the market in the region. Moreover, the investment in digital healthcare services increases the requirement for data exchange from different sources and healthcare organizations.
Asia Pacific
Asia Pacific is projected to witness the fastest growth at an 16.63% CAGR. China, Japan, India, South Korea, and Australia are among the important regions, where healthcare facilities have been utilizing digital records and connected health applications. In India, digital healthcare systems are increasingly being implemented in both the private and public sectors. China and Japan have well-established IT-based healthcare markets, while South Korea continues to add new digital health services. Similarly, Australia is investing in the development of its digital health network and data-sharing capability. With the number of healthcare facilities opting for digital systems in these countries, there is a need for interoperability among various platforms. Further, increased healthcare digitization in emerging Asian countries will drive regional demand during the forecast period.
Europe
Europe accounted for an 25.18% share of the healthcare interoperability solutions market in 2025. Germany, the UK, France, Italy, Spain, and the Netherlands are some of the key markets in the region. In Europe, there is increased attention being focused on the coordination of care and secure access to patients’ health information. There are also advancements in the exchange and use of electronic health data due to the European Health Data Space interoperability framework. There are already developed IT networks in healthcare systems across France and Germany, while the UK is expanding digital health offerings within the NHS. There are different healthcare systems in Europe that result in diverse needs for data management and interconnection systems.
Latin America
The Latin America healthcare interoperability solutions market is projected to grow at an 14.40% CAGR. Latin America is enhancing its capabilities in digital health care through the implementation of digital record-keeping and digital health management systems. Brazil is an important market within this region due to the growth in its national health data system. In July 2025, the Brazilian government introduced Decree No. 12,560, which regulates the operation of Rede Nacional de Dados em Saúde (RNDS) as the national interoperability platform for the healthcare system in the country (source: ibanet.org). Other important markets within Latin America for digital health include Mexico and Argentina, with various entities within the health sector in the region embracing electronic platforms. This is resulting in higher needs for interoperability systems within clinical data and other health data.
Middle East & Africa
The Middle East & Africa healthcare interoperability solutions market is anticipated to account for an 15.40%. Saudi Arabia and the UAE are among the key markets in the Middle East owing to the continuous digital transformation in the healthcare sector. Healthcare providers have started to use connected platforms for enhancing the flow of patient data through different healthcare facilities. Digital health is being adopted at an increasing rate in Africa, owing to improvements in health information infrastructure. South Africa has a well-developed healthcare IT infrastructure, whereas other countries are developing their digital capabilities from a smaller base. The differences in healthcare infrastructure and technology preparedness in the region have become the driving force behind the adoption of interoperability solutions.
Competitive Landscape
The healthcare interoperability solutions market is moderately fragmented, as there is competition among large healthcare IT companies as well as interoperability firms. Various vendors have different ranges of interoperability solutions in terms of platform and level of integration. Established firms compete with companies specialized in specific data exchange needs.
Key Players & Competitive Strategies
Key players include Oracle Health, Epic Systems Corporation, InterSystems Corporation, Medical Information Technology, Inc. (MEDITECH), NextGen Healthcare, Inc., Veradigm Inc., Infor, Inc., Orion Health, Redox, Inc., Koninklijke Philips N.V., Siemens Healthineers AG, GE HealthCare Technologies Inc., IBM Corporation, Hyland Software, Inc., and Cotiviti, Inc. Enhancements to FHIR functionalities are underway to provide integration between EHRs, applications, and third-party systems. Cloud-based interoperability is yet another trend where vendors provide hosted solutions that allow data exchange among various healthcare settings. AI technology is being integrated for such purposes as data extraction, mapping, and workflow automation. Partnerships assist healthcare interoperability vendors in establishing connections between their solutions and EHRs, healthcare networks, and other specialized apps. QHIN solutions have become an area of competition in the U.S., with Oracle Health Information Network holding Designated QHIN status under TEFCA.
| Vendor | Positioning | TEFCA / QHIN status (RCE) |
| Payer-provider data exchange and FHIR integration | No QHIN designation identified | |
| Epic Systems Corporation | EHR-led exchange | Designated QHIN (Epic Nexus) |
| GE HealthCare Technologies Inc. | Medical device and healthcare-system interoperability | No QHIN designation identified |
| Hyland Software, Inc. | Healthcare content, imaging, and data interoperability | No QHIN designation identified |
| IBM Corporation | Healthcare application integration and FHIR support | No QHIN designation identified |
| Infor, Inc. | Healthcare integration through Cloverleaf | No QHIN designation identified |
| InterSystems Corporation | Healthcare data platform and integration | No QHIN designation identified |
| Koninklijke Philips N.V. | Medical device and clinical-system interoperability | No QHIN designation identified |
| EHR and interoperability platform | TEFCA-enabled exchange through Traverse Exchange | |
| NextGen Healthcare, Inc. | EHR and API-based interoperability | No QHIN designation identified |
| Oracle Health (Oracle Corporation) | Cloud health data platform; formerly Cerner | Designated QHIN (Oracle Health Information Network) |
| Orion Health | Healthcare interoperability and data integration | No QHIN designation identified |
| Redox, Inc. | Cloud-based healthcare data exchange | No QHIN designation identified |
| Siemens Healthineers AG | Connected healthcare systems and clinical data integration | No QHIN designation identified |
| Veradigm Inc. | EHR data exchange and FHIR APIs | TEFCA Participant/Subparticipant through MedAllies |
Source: Polaris Market Research Analysis
Cost Benchmarking & ROI
The healthcare interoperability cost varies by organization size, system complexity, and the number of applications that need to be connected. Implementation cost also depends on integration requirements, cybersecurity controls, data migration, and ongoing support.
Deployment Cost Benchmarking
| Organization Type | Estimated Deployment Cost |
| Small Clinic | USD 50,000–150,000 |
| Mid-Sized Hospital | USD 500,000–2 Million |
| Large Health System | USD 5–20 Million |
Source: Polaris Market Research Analysis
Note: Estimates are based on market assessment of typical interoperability deployments and are indicative rather than vendor-specific. Costs vary by scope, integration complexity, infrastructure, security requirements, and number of connected systems. As of September 2026.
ROI Analysis
Healthcare organizations can calculate ROI on interoperability in terms of reduced costs and enhanced workflows. These levers of ROI would be:
- Reduced need for repeat testing owing to greater availability of the patients’ records.
- Reduced costs associated with manual data entry due to direct data transmission between systems.
- Increased efficiency in claims processing due to reduced inconsistencies.
- Reduced costs associated with prior authorizations through electronic data exchange.
- Decreased costs of integration maintenance through standard interfaces rather than multiple point-to-point connections.
Buyer-Focused Insights
Interoperability solutions vendors are usually evaluated by the CIO and IT procurement departments before implementing a full-scale deployment. This process involves assessing various aspects, including:
- Compliance, scalability, and cybersecurity preparedness in the vendor procurement checklist.
- APIs and EHR integration when assessing integration solutions providers.
- Deployment timeline to avoid delays and disruptions to healthcare delivery processes.
- Scalability to handle larger amounts of data and multiple facility deployments.
- TEFCA/QHIN connectivity for an assessment of the solution to facilitate nationwide health information exchange.
Emerging Trends & Investment Insights
In the recent period of investment and partnering activity, there is ongoing interest in developing infrastructure for healthcare data exchange. Investments in the healthcare interoperability solutions market have focused on connectivity and digital trust built on FHIR standards. Acquisitions have strengthened payer-provider interoperability offerings.
In August 2026, Metriport secured USD 26 million to expand its healthcare data infrastructure platform. The technology developed by Metriport uses HL7 and FHIR standards to facilitate connections and organization of data from various sources for patients. (source: metriport.com)
In July 2026, IDENTOS received USD 1 million from Ontario’s Life Sciences Scale-Up Fund. This funding will be used for the development of its Digital Trust Exchange, a FHIR-based platform to facilitate the data exchange of healthcare and government organizations. (source: identos.com)
In January 2026, Onyx acquired InteropX to strengthen its interoperability offering. This deal will help Onyx develop its ePA, payer-to-payer data exchange, and provider access APIs. (source: onyxhealth.io)
Recent Developments
September 2026: Redox announced its approval and active participation in the CMS Health Tech Ecosystem as an Aligned Network. The company stated that it received approval across four critical categories. These are Bulk FHIR, Data Networks, Electronic Prior Authorization, and Pharmacies & Pharmacy Systems. (source: prnewswire.com)
August 2026: The Sequoia Project announced its continued role as the Recognized Coordinating Entity (RCE) to support the implementation of the Trusted Exchange Framework and Common Agreement (TEFCA). It was awarded the next option year with a funding increase of more than 15%. (source: rce.sequoiaproject.org)
Future Outlook
The healthcare interoperability solutions market is poised for growth as healthcare establishments integrate an increasing number of systems and data sources. The development of the market will increasingly depend on how easy it is to implement the solutions into healthcare operations. There will also be a variance in demand based on the scale of establishments. Larger health organizations will need more extensive integration between facilities. Smaller healthcare establishments may opt for solutions that require few internal IT resources. Solution providers will focus on ease of deployment, wide compatibility with systems, and low maintenance costs. The use of interconnected healthcare services is expected to contribute to a greater amount of data being exchanged between organizations. Competitiveness over the forecast period will revolve around providing connectivity without creating extra complexity in healthcare operations.
Research Methodology
Scope and Definitions
The healthcare interoperability solutions market covers software, platforms, middleware, and services used to connect healthcare systems and exchange patient and healthcare data. The analysis covers component, interoperability level, deployment model, end user, and regional outlook. Market revenue is measured in USD billion, with 2025 as the base year and 2021–2024 as the historical period.
Estimation Approach
Market estimates are developed using both top-down and bottom-up approaches. Vendor information, healthcare IT adoption, interoperability activity, regulatory developments, and industry data are reviewed to build the market estimates. Results from both approaches are compared to improve consistency.
Secondary Sources
Secondary research uses information from ASTP/ONC, CMS, the TEFCA Recognized Coordinating Entity, HL7 International, company filings, annual reports, investor materials, company announcements, and industry publications. These sources are used to assess market activity, technology adoption, regulatory changes, company developments, and interoperability initiatives.
Primary Research
Primary research covers healthcare IT decision-makers, hospital and health-system technology leaders, healthcare payers, EHR and integration-platform vendors, and HIE and QHIN participants. Interviews are used to validate market estimates, deployment costs, adoption patterns, and technology requirements.
Estimation Steps
Vendor revenues are assessed and allocated across components, deployment models, end users, and regions. The assessment is validated by benchmarking it against healthcare IT adoption, EHR adoption, connectivity metrics, and healthcare interoperability activities. The forecast is based on regulatory considerations, FHIR adoption, cloud deployment, healthcare digitization, and data sharing requirements.
Validation
Market assessments are compared with company disclosures, regulatory disclosures, industry trends, and primary research insights. The key assumptions of the market are also evaluated for each segment and region. Sensitivity analysis is also performed to evaluate changes in growth rate and market assessments.
As-of Date and Limitations
The healthcare interoperability solutions market study is based on data as of September 2026. Market assessments can be subject to variations due to limited disclosures by private companies and variations in the definition of healthcare interoperability by external sources. Costs of deployment are indicative and can vary across organizations based on size, extent of integration, cybersecurity considerations, and number of connected systems.
Healthcare Interoperability Solutions Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 4.36 billion |
| Market Size Value in 2026 | USD 4.99 billion |
| Market Forecast 2034 | USD 15.12 billion |
| CAGR | 14.8% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Healthcare Interoperability Solutions Market FAQ's
The global healthcare interoperability solutions market size was valued at USD 4.36 billion in 2025. It is projected to reach USD 15.12 billion by 2034. It is anticipated to register a 14.8% CAGR from 2026 to 2034.
Interoperable healthcare solutions help various healthcare systems share information about their patients. These interoperable healthcare solutions help to integrate EHRs, hospitals, labs, pharmacies, payers, and other healthcare systems.
EHR adoption and mandatory government interoperability are key factors that contribute to market growth. Healthcare providers require easy access to information about patients from different healthcare setups.
Data is captured using various systems such as EHRs and Laboratory systems. It is then transferred to another system, authorized using standards such as FHIR and HL7, and used in the destination system.
A health information exchange allows healthcare organizations to share electronic health information. It can connect providers, laboratories, pharmacies, and other organizations that need access to patient records.
North America led with a 42.27% share in 2025. The region benefits from established healthcare IT infrastructure. It also has widespread use of electronic health records.
TEFCA is an information-sharing structure in the United States for national healthcare. Over 23,000 entities had joined TEFCA as of September 2026, as participants or subparticipants, through QHINs.
Software led by component with a 45.63% healthcare interoperability solutions market share in 2025. Hospitals & clinics accounted for the largest end-user share of 40.23% in 2025.
Major companies in the healthcare interoperability solutions market include Cotiviti, Inc.; Epic Systems Corporation; GE HealthCare Technologies Inc.; Hyland Software, Inc.; IBM Corporation; Infor, Inc.; InterSystems Corporation; Koninklijke Philips N.V.; Medical Information Technology, Inc. (MEDITECH); NextGen Healthcare, Inc.; Oracle Health (Oracle Corporation); Orion Health; Redox, Inc.; Siemens Healthineers AG; Veradigm Inc.
Estimated costs range from USD 50,000–150,000 for a small clinic. The cost is USD 500,000–2 million for a mid-sized hospital. It is estimated at USD 5–20 million for a large health system. Costs vary based on the scope and complexity of the deployment.
Download Sample Report of Healthcare Interoperability Solutions Market
Please fill out the form to request a customized copy of the research report.