Autonomous Forklift Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Autonomous Forklift Market Summary
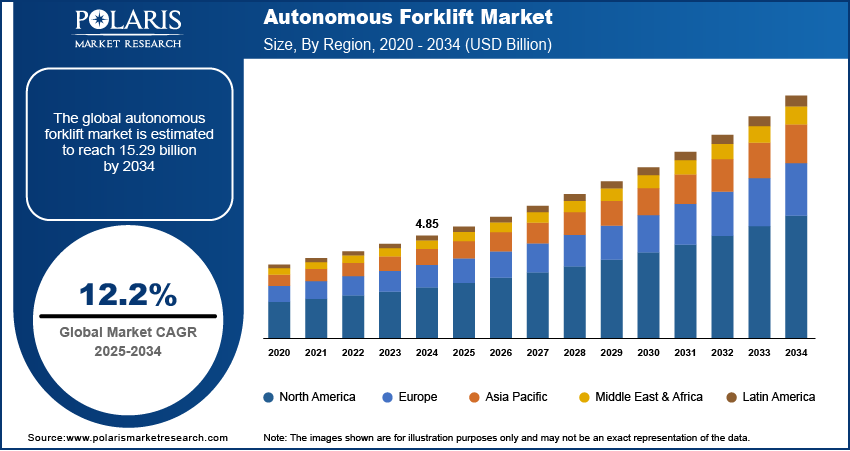
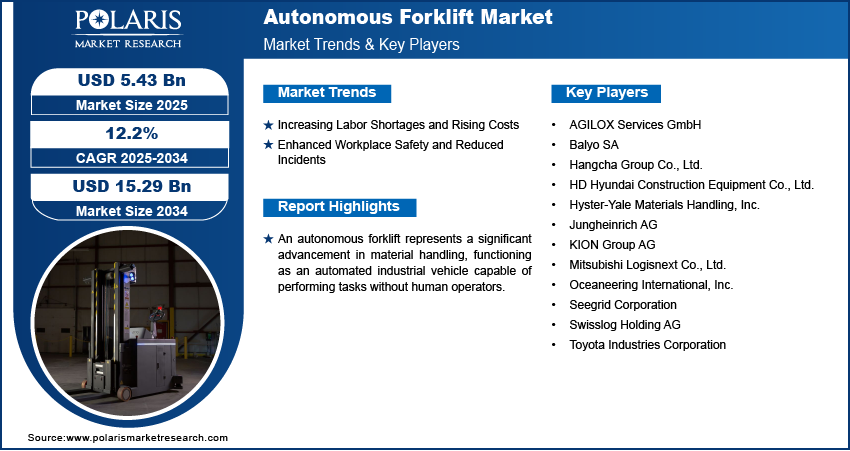
The autonomous forklift market size was valued at USD 5.32 billion in 2025, growing at a CAGR of 13.9% from 2026 to 2034. Key factors driving demand for autonomous forklifts include increasing labor shortages and rising costs, enhanced workplace safety and reduced incidents, and e-commerce growth.
Market Statistics
Autonomous Forklift Market Key Takeaways
- Asia Pacific held the largest market share of 41.1% in 2025. The dominance is attributed to strong manufacturing sectors and expanding warehouse automation across countries, including China, Japan, South Korea, and India.
- The North America autonomous forklift market is projected to register a CAGR of 15.7% during the forecast period. The growth is driven by the region's increasing focus on optimizing supply chain efficiency and addressing labor shortages.
- The market in Europe is expected to register a 13.2% CAGR during the forecast period, owing to the high adoption rates of warehouse automation and shortages of skilled labor.
- The below 5 tons segment held the dominant market share of 61.5% in 2025. This is mainly fueled by the widespread use of lower-capacity material handling equipment in e-commerce fulfillment centers, retail warehouses, and general distribution facilities.
- The warehousing segment accounted for the largest market share of 52.8% in 2025, due to the rising importance of automation across distribution and storage centers, e-commerce fulfillment hubs, and large-scale storage facilities.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is the Autonomous Forklift Market?
The autonomous forklift market involves the development, designing, manufacturing, and selling of autonomous forklifts. An autonomous forklift is a transport machine that can move or haul goods with little or no human intervention. These forklifts are used in manufacturing warehouses, factories, and distribution centers. They offer a major advantage to businesses by increasing productivity while reducing operating costs. The autonomous forklift market size is mainly driven by the growing need for automation, reduction in labor costs, and improved operational efficiency across industries.
Autonomous Forklift vs Traditional Forklift
| Attribute | Autonomous Forklift | Traditional Forklift |
| Operator requirement | None, self-navigating via sensors, LiDAR, and AI | Requires a trained human operator |
| Labor dependency | Low; reduces reliance on operator recruitment and training | High; subject to labor shortages and turnover |
| Operating hours | Continuous, 24/7 capable | Limited to shift schedules and operator breaks |
| Safety profile | Predictable, sensor-based obstacle detection reduces collision risk | Human-error-related incidents (collisions, tip-overs) more common |
| Upfront cost | Higher. Sensors, navigation software, fleet management software forklift | Lower initial purchase price |
| Integration complexity | Requires WMS/WES integration and facility layout considerations | Minimal integration requirements |
| Best fit | High-throughput, repetitive-task warehouses and fulfillment centers | Variable, low-volume, or highly dynamic environments |
Source: Polaris Market Research Analysis
How do Autonomous Forklifts work?
Autonomous forklifts use sensors, video cameras, software, and GPS to lift and drive materials autonomously with little or no human input.
- The forklifts first scan their surroundings or map the environment.
- They then plan a route to navigate the truck and move goods from one point to another.
- These machines use sensors to identify objects in their path and avoid collisions. Sensors and GPS ensure the trucks operate smoothly.
- The forklifts can also be controlled through software and computer programs. Computer algorithms support decision-making and navigation.
Autonomous Forklift vs AGV vs AMR
| Attribute | Autonomous Forklift | Automated Guided Vehicle (AGV) Forklift | Autonomous mobile robot (AMR) Forklift |
| Navigation method | Sensors, LiDAR, cameras; may use fixed or dynamic routes | Fixed paths via magnetic tape, wires, or lasers | Dynamic, infrastructure-free navigation via SLAM and AI |
| Flexibility | Moderate to high, depending on model | Low (route changes require physical infrastructure changes) | High: adapts to layout changes in real time |
| Primary task | Lifting, stacking, and transporting palletized loads | Point-to-point material transport along a set path | General-purpose transport, often lighter payloads |
| Typical payload | Matches forklift-class loads (pallets, heavy tonnage) | Varies; often used for towing or cart transport | Typically lighter than forklift-class loads |
| Relationship | A functional subset that can be built on AGV or AMR technology | A navigation category some autonomous forklifts use | A navigation category some autonomous forklifts use |
Source: Polaris Market Research Analysis
Source: Polaris Market Research Analysis
AI Impact on Autonomous Forklift Market
- AI is transforming the autonomous forklift market by enabling smarter navigation, real-time decision-making, and safer material handling operations.
- Advanced AI algorithms allow autonomous forklifts to identify obstacles, optimize routes, and adapt efficiently to changing warehouse environments.
- AI-powered systems improve operational efficiency by reducing idle time, optimizing workflows, and enabling continuous automated operations.
- The integration of AI, machine learning, and computer vision enhances forklift safety by accurately detecting workers, vehicles, and potential hazards.
- AI enables autonomous forklifts to continuously learn from operational data, improving their navigation accuracy and performance over time.
Autonomous Forklift Market Dynamics
Driver: Increasing Labor Shortages and Rising Costs
Escalating labor shortages and rising costs in the logistics and manufacturing sectors are major drivers of autonomous forklift adoption. Businesses globally are facing difficulties in recruiting and retaining skilled workers for material handling roles. Such labor shortage is leading to operational inefficiencies and increased expenditure. This situation compels companies to seek automated solutions to maintain productivity and reduce reliance on a volatile labor pool. Furthermore, the rising wages of skilled forklift operators contribute to higher operational overheads. It makes the investment in autonomous systems increasingly economically viable.
Driver: Rising Focus on Improving Workplace Safety and Reduced Incidents
Rising emphasis on workplace safety and initiatives to reduce occupational injuries and fatalities propel the adoption of autonomous forklifts. Traditional forklift operations pose inherent risks, including collisions, tip-overs, and workers being struck by equipment. Autonomous forklifts, equipped with advanced navigation, obstacle detection, and safety protocols, significantly minimize human error, which is a major contributor to these incidents. Their predictable and consistent operation reduces the potential for accidents, thereby improving overall warehouse safety and lowering associated costs like workers' compensation claims and lost productivity. This enhanced safety potential is a critical growth factor for the autonomous forklift market.
Driver: E-commerce Growth
The exponential growth of the e-commerce sector and the high demand for faster, more efficient logistics operations boost the demand for autonomous forklifts. According to the U.S. Census Bureau, the U.S. recorded sales worth USD 340.2 billion through e-commerce platforms in second quarter of 2026. The rapid increase in online sales necessitates quicker order fulfillment, higher throughput in warehouses, and optimized inventory management. This surge in e-commerce directly translates into increased package volumes and a need for highly automated distribution centers. Autonomous forklifts offer the scalability, precision, and continuous operation required to meet these stringent e-commerce demands, ensuring goods move efficiently and accurately (Source: census.gov).
Restraint: High Initial Investment and Implementation Costs
High autonomous forklift costs are hindering the adoption of these systems. This equipment requires a substantial amount of advanced machinery and devices to function. The initial investment in the technology may seem too high for companies with limited capital. Businesses are required to renovate their existing infrastructure to use autonomous forklifts in their warehouses. This limitation could become especially apparent for small and medium-sized enterprises. Additionally, additional expenses could occur if companies need to update their software and maintain the newly-purchased machinery, thereby restraining the industry growth.
Restraint: Safety Concerns and Complex Operating Environment
Safety concerns limit the adoption of autonomous forklifts. The equipment operates in a complex setting that involves other vehicles, workers, and obstacles. The forklift is required to avoid obstacles while carrying goods. The autonomous forklift can recognize them with a high degree of precision to avoid accidents. Poor navigation or system errors can create operational risks. Moreover, the equipment might struggle with the diverse conditions that it would encounter in different facilities, which would reduce its level of safety and effectiveness. These factors adversely impact the market expansion.
Opportunity: Growing Demand for Warehouse Automation
The growing demand for warehouse automation creates a strong opportunity for the self-driving forklift market. Companies increasingly seek ways to improve productivity and handle higher order volumes. E-commerce growth and faster delivery expectations are increasing pressure on warehouse operations. Autonomous forklifts can operate for longer hours and reduce dependence on manual labor. They can also improve accuracy and support safer material movement. As labor shortages continue in many regions, businesses are expected to invest more in automation. This trend offers significant growth opportunities for autonomous forklift manufacturers and technology providers in the coming years.
Trend: Industry 4.0 and Smart Warehouses
Industry 4.0 and the trend of smart warehouses are likely to boost the autonomous forklifts industry in the near future. Advanced technologies and equipment allow the warehousing sector to create smart solutions and make the supply chain more efficient. Autonomous forklifts can be controlled remotely or programmed within the framework of the warehouse management system. It allows companies to organize the material flow more efficiently and eliminate the need for human labor. Such equipment can collect and provide real-time data about its location, which makes it possible to monitor and control the work process. Moreover, the integration of information technologies and modern machinery will fuel the demand for autonomous forklifts in the smart warehouse systems in the coming years.
Source: Polaris Market Research Analysis
Segmental Insights
By Type
By type, the segmentation includes pallet jacks, counterbalance, reach trucks, order pickers, and stacker forklifts. The pallet jacks segment dominated with the largest share of 36.8% in 2025. The growing trend of automation, in combination with the development of e-commerce, is driving the need for more efficient pallet handling in warehouses and distribution centers. Autonomous pallet jacks are well-suited for repetitive work and can substitute for manpower. Moreover, their compact design allows their use in small spaces, thereby driving segment growth.
The counterbalance segment is expected to register a CAGR of 14.8% during the forecast period. This type of equipment is suitable for a wide range of applications, including lifting and transporting heavy items. The need for counterbalance forklifts is increasing due to growing industrialization, logistics, and warehousing. Companies are constantly looking for ways to optimize operations and reduce manual labor, thereby driving the segment growth.
By Navigation Technology
By navigation technology, the segmentation includes LiDAR, vision guided, SLAM, magnetic guided, geofencing based, and others. The SLAM segment is expected to grow at a CAGR of 15.6% during the forecast period. The technology allows autonomous forklifts to navigate workplaces without magnetic tracks and other infrastructure. Additionally, SLAM navigation forklift can be used in warehouses where conditions and layouts are constantly changing because it has the ability to determine its location and build maps. The development of smart technologies and the need for automated equipment in warehouses have increased the demand for this type of navigation.
The magnetic guided segment is projected to exhibit a CAGR of 12.4% during the projected period. The technology enables high accuracy and reliable operations in structured environments. Magnetic-guided forklifts can operate in places where specific technology, such as magnetic tracks, is installed. Moreover, this system is useful for industrial manufacturing facilities because it allows for predictable and reliable automation. The popularity of magnetic guided forklifts is expected to increase as automated solutions in the logistics industry develop, thereby fueling segment growth.
By Tonnage Capacity
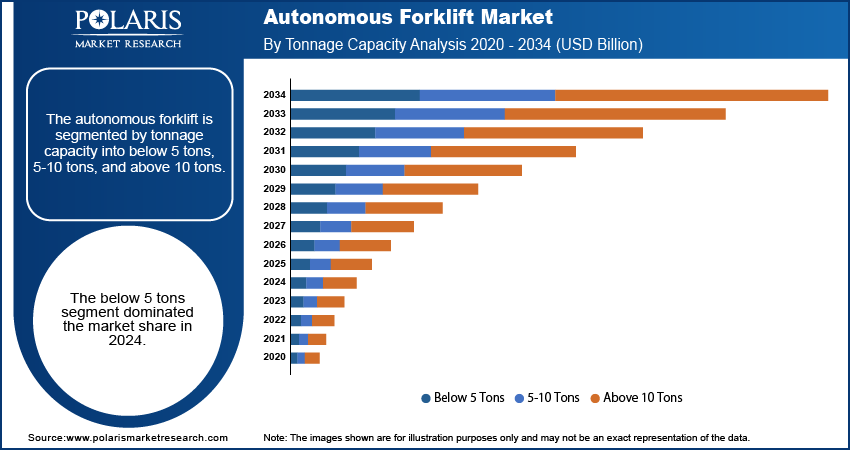
By tonnage capacity, the segmentation includes below 5 tons, 5-10 tons, and above 10 tons. The below 5 tons segment accounted for a major market share of 61.5% in 2025. This is mainly attributed to the widespread use of lower-level material handling equipment in e-commerce fulfillment centers, retail warehouses, and general distribution centers. These types of environments usually emphasize agility, speed, docking, and space-efficient design. Building and implementing autonomous systems for these lighter loads has been straightforward, driving greater adoption and more installed systems. These smaller, highly automated vehicles are incredibly versatile, which makes them crucial to modern logistics systems operations.
The 5-10 tons segment is projected to grow at a robust CAGR of 14.6% in the coming years, driven by growing automation needs in the manufacturing, automotive, and industrial sectors that handle moderately heavy raw materials or components. Companies in these industries are realizing the efficiency and safety benefits of automating medium-duty material transport and minimizing manual labor for physically strenuous tasks. This shift toward automating more robust material flows is a primary driver of broader market penetration in this capacity range.
By Application
In terms of application, the segmentation includes manufacturing, warehousing, material handling, logistics & freight, and others. The warehousing segment held the largest market share of 52.8% in 2025 due to the growing importance of automation in distribution and storage centers, e-commerce fulfillment hubs, and storage facilities. Warehousing operations involve monotonous activities such as picking, putting away, and transporting goods, making them well-suited for automation. The need to maximize throughput in these environments, coupled with lower labor costs and improved safety, has increased the use of autonomous forklifts, thus making warehousing the primary area for their widespread application and establishing their dominance.
By Industry
Based on industry, the segmentation includes 3rd party logistics, food & beverages, automotive, paper & pulp, metals & heavy machinery, e-commerce, aviation, semiconductors & electronics, healthcare, and others. The e-commerce industry dominated the market with a 29.7% share in 2025. E-commerce businesses handle immense volumes of diverse products. It requires rapid order fulfillment, precise forecasting, and a continuous flow of materials within large distribution centers. Autonomous forklifts automate these tasks and operate around the clock, improving throughput and accuracy.
The semiconductors & electronics sector is expected to grow at a CAGR of 15.3% during the forecast period. This growth is supported by the demanding containment control, precision handling, and traceability requirements in manufacturing sensitive, high-value electronic components. There is an ever-increasing need for electronic devices, which fuels the need for fully automated, error-free material transport, especially within cleanroom environments and highly automated production lines. Forklifts that are autonomous provide the needed dependability, gentle handling, and accuracy required for these delicate materials to avoid damage, and refine complex cargo-handling supply chain processes within this specialized sector.
By Fuel Source
Based on fuel source, the segmentation includes electric, ICE, LPG / CNG, and hydrogen fuel cell. The electric segment dominated with largest share of 72.5% in 2025 driven by the rising need for sustainable and energy-efficient warehouse operations and the replacement of fuel-based equipment by companies to reduce emissions and costs. These forklifts also reduce noise levels, making them ideal for indoor operations. Moreover, the advancement and ease of charging batteries have further contributed to the segment’s growth. The need for sustainability and energy efficiency in the warehouse and manufacturing industry is estimated to drive the demand for electric autonomous forklifts in the coming years.
The ICE segment is expected to witness growth of 10.8% during the forecast period driven by the demand for high-performance equipment by industries. These forklifts are mostly used for material handling tasks in outdoor operations and for extended working hours. Their use in the warehouse, manufacturing, and logistics sectors for heavy lifting fuels their demand. Moreover, the refueling time of these forklifts reduces the idle time of the equipment. This has increased their demand in the manufacturing and industrial facilities with high-performance needs.
Electric vs. ICE/Alternate
| Dimension | Electric | ICE / Alternate |
| Typical use | Indoor warehouses, clean rooms, food/pharma | Outdoor yards, heavy industry, cold chain, multi‑shift |
| Emissions | Zero tailpipe; low noise | Tailpipe emissions (diesel/LPG); fuel cells = water vapor only |
| Energy efficiency | ~85–90% motor efficiency; ~30% less energy vs. IC | ~30–35% thermal efficiency (diesel/LPG engines) |
| Operating cost | Lower energy & maintenance (~$1.5–2.5/hr electricity) | Higher fuel & maintenance (~$3–5/hr diesel/LPG) |
| Maintenance | Fewer moving parts; longer intervals | More parts (engine, exhaust, fluids); frequent servicing |
| Refuel/charge | Opportunity/fast charging; shift‑based planning | Fast refuel (minutes); continuous multi‑shift operation |
| Upfront cost | Higher (battery + chargers/infra) | Often lower truck‑only capex; fuel storage/infra varies |
| Performance | Smooth torque; precise control; good indoors | High peak torque; better on grades/rough terrain |
| Regulatory fit | Preferred where air/noise rules apply | Restricted indoors; allowed outdoors/industrial zones |
Source: Polaris Market Research Analysis
By Sales Channel
Based on sales channel, the segmentation includes in-house and leasing/RaaS. The in-house segment dominated with 64.2% revenue share in 2025. This lead is driven by companies' preference for direct ownership of autonomous forklifts and machines. This segment has witnessed significant growth due to the need for full control of the equipment by large-scale warehouses and manufacturing companies. This benefits the companies with high-volume and continuous production needs. The preference toward warehouse robotics automation and high-performance equipment further fuels segment growth.
The leasing/RaaS segment is expected to register a CAGR of 16.1% during the forecast period. Demand for forklift leasing is driven by the need to reduce high upfront investment costs. This channel provides flexible payment options that benefit small and mid-sized companies and eliminate the need for large-scale investments. The option also offers maintenance and technical services to keep the equipment running smoothly. The rising need for robotic automation in the warehouse and manufacturing sectors is expected to fuel segment growth.
In-house vs. Leasing/RaaS Autonomous Forklift
| Dimension | In‑House / Direct Purchase | Leasing / RaaS (Subscription) |
| Ownership | Customer owns hardware & software | Vendor/lessor owns; customer rents capacity |
| Capex vs. Opex | High capex; opex for service/energy | Low/no capex; monthly opex fee |
| Typical cost | $150k–$500k+ per system (incl. integration) | ~$2k–$10k/robot/month (bundled) |
| Contract term | One‑time purchase; 3–5 yr refresh | 12–36 months typical; flexible scaling |
| Maintenance & support | Customer manages (or pays annual service) | Included in fee (SLA, updates, repairs) |
| Deployment speed | Longer (procurement, integration) | Faster (vendor‑led, turnkey) |
| Scalability | Add units via new capex projects | Add/remove units per season/demand |
| Technology risk | Customer bears obsolescence | Vendor bears; easier upgrades |
Source: Polaris Market Research Analysis
Autonomous Forklift Use Cases
Autonomous forklifts are used in warehouses, distribution centers, and manufacturing plants to transport palletized goods, restock pick faces, and perform cross-docking without requiring a driver. Twelve Toyota autonomous forklifts are operating 24 hours a day at a cheese factory in the Netherlands, piling and unpacking cheese boxes between the production and ripening halls, resulting in 99.9% of cheese being handled by automated forklifts. The driverless pallet stackers from BALYO have helped a paper manufacturer to optimize storage space and ensure safety, while VisionNav’s VNE20 series enables a leading antibiotics producer to transfer heavy loads from indoors to outdoors and automate loading trucks, thus saving time and reducing costs.
Source: Polaris Market Research Analysis
Regional Analysis
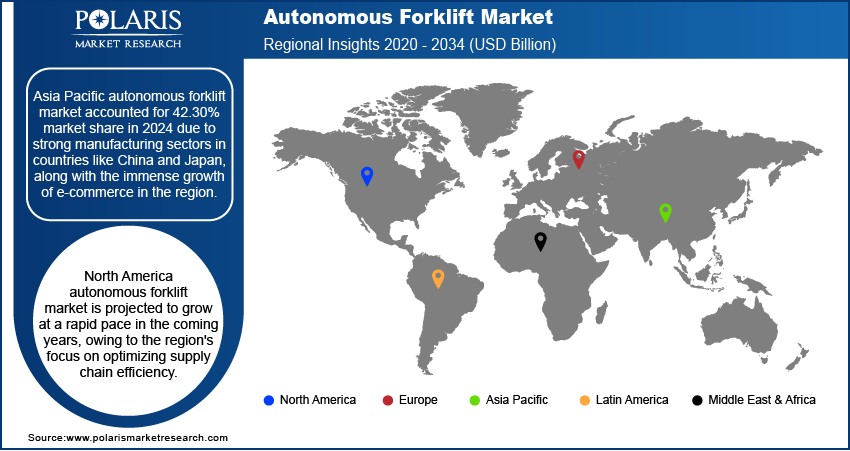
The autonomous forklift market by region is segmented into Asia Pacific, North America, Europe, Latin America, and the Middle East & Africa.
Asia Pacific accounted for 41.1% of the global autonomous forklift market share in 2025. The dominance is attributed to strong manufacturing sectors in countries like China and Japan, along with the immense growth of e-commerce in the region. According to the United Nations Industrial Development Organization, China's manufacturing output increased by 1.3% in the third quarter of 2025. Rapid industrialization, investments in smart warehouses, and the growing need to tackle labor shortages also contributed to market expansion in the region. Moreover, expanding urbanization is further fueling the demand for autonomous forklifts as urban warehouses and distribution centers often face significant space limitations (Source: stat.unido.org).
The North America autonomous forklift market is projected to record the CAGR of 15.7% in the coming years, owing to the region's focus on optimizing supply chain efficiency. The growing labor shortage in countries such as the U.S. is also driving market expansion in the region. High spending power in the country is further contributing to the U.S. autonomous forklift market growth. The presence of large economic distribution networks and e-commerce fulfillment centers is also driving major corporations in the region to invest in smart warehouse automation, therefore boosting demand for autonomous forklifts.
The market in Europe is expected to register a CAGR of 13.2% during the forecast period, driven by high adoption rates of warehouse automation and the shortage of skilled labor. Many companies in the region are adopting automation to increase productivity and reduce costs associated with manual labor. Growth in the e-commerce and distribution sector is supporting broader material handling automation trends across the region. According to the European Commission, 78% of internet users in Europe purchased goods or services through online platforms in 2025. Additionally, workplace safety regulations are prompting companies to adopt autonomous forklifts. Moreover, Europe has well-established manufacturing capabilities and is home to many companies that are investing in Industry 4.0 technologies. As a result, autonomous forklifts have seen high adoption in the manufacturing and logistics sector in the region, thereby driving the market growth (Source: ec.europa.eu).
The Latin America autonomous forklift market is expected to record a CAGR of 12.6% during the forecast period, driven by the gradual rise of e-commerce, warehousing, and logistics industries. Companies are adopting automation to improve operational efficiency while reducing costs associated with high labor costs in the region. Growing industrial activity in countries such as Brazil and Colombia makes the adoption of automated solutions appealing. Additionally, International companies are building modern distribution centers throughout the region, thereby driving regional growth.
The Middle East & Africa autonomous forklift market is expected to record growth at a CAGR of 11.9% during the forecast period. The growth is supported by the rising need to adopt modern logistics and warehousing solutions. Companies in the Middle East are building smart warehouses and logistics parks in the region to match the rising demand from the e-commerce sector. The need to transform and diversify economies is driving investment in manufacturing and logistics in the Middle East. For instance, in November 2025, DHL invested USD 580.64 million (EUR 500 million) in the Middle East. Additionally, African countries are witnessing improved industrialization and modernization of supply chains at a steady rate, thereby driving the region growth (Source: group.dhl.com).
Source: Polaris Market Research Analysis
Autonomous Forklift Safety Regulations
| Standard / Regulation | Scope & Application | Key Requirements |
| ISO 3691-4 (2020/2023) | Driverless industrial trucks (AGV/AMR forklifts) and their systems; global/CE-marked markets. | Safety requirements for vehicle design, control systems, hazard identification, risk assessment; mandates minimum Performance Level (PL) per ISO 13849-1 for safety-related control functions. |
| ANSI/ITSDF B56.5 | Driverless automatic guided industrial vehicles and automated functions of manned trucks; U.S. and Canada. | Primary AGV/autonomous forklift safety framework covering navigation, obstacle detection, emergency stopping, and system integration; widely referenced by OSHA and insurers. |
| ANSI/RIA R15.08-1 & -2 (2020/2023) | Industrial mobile robots (IMRs), including autonomous forklifts, in warehouses and factories; U.S. | Part 1: robot-level safety (sensors, speed, stopping); Part 2: system integration, fleet management, and attachment safety; aligns closely with ISO 3691-4. |
| OSHA 29 CFR 1910.178 | Powered industrial trucks (including autonomous forklifts) in general industry; U.S. | Operator training (or equivalent system validation), maintenance, safe operating procedures, and workplace conditions; autonomous systems must meet equivalent safety outcomes. |
| ISO 13849-1 / IEC 62061 | Safety-related control systems for machinery, including autonomous forklifts. | Specifies Performance Level (PL) or Safety Integrity Level (SIL) targets for electronic safety functions such as emergency stop, collision avoidance, and speed limiting. |
| ANSI/ITSDF B56.1 (and revisions) | Low- and high-lift powered industrial trucks (manned or automated functions). | Design, operation, and maintenance safety for forklifts; relevant where autonomous functions are added to conventional truck platforms. |
| CE Marking (EU Machinery Directive / Regulation) | Autonomous forklifts sold or operated in the European Economic Area. | Requires conformity assessment against applicable harmonized standards (e.g., ISO 3691-4), technical documentation, and declaration of conformity before market placement. |
Source: Polaris Market Research Analysis
Total Cost of Ownership & ROI Considerations
The main costs linked with autonomous forklifts are hardware, fleet software, integration, charging, maintenance, and training; hence, the overall expense may reach 2-2.5 times the cost of a machine within five years. The significant value drivers are substitution of labor costs, accident and damage reduction, and higher utilization. Most multi-shift operations recover the investment within a year and a half to two years and can profit from lower overall operating costs with autonomous forklifts over seven to ten years.
Competitive Insights
Autonomous forklift players offer a range of products and services, from autonomous pallet movers to counterbalanced forklifts. They cater to diverse requirements and operational scales. The autonomous forklift ecosystem is diverse and hybrid in nature, featuring both traditional material handling equipment OEMs and robotics firms as competitors. Competition focuses on core technologies such as navigation and AI for task integration, as well as interfacing with existing warehouse management systems and software. Key players are focusing on improving system safety, reliability, and flexibility. Collaboration initiatives are common between conventional forklift builders and robotics engineers, merging market knowledge with innovative automation skills. The market for responsive, adaptable, and precise integrated systems is forcing all stakeholders to continuously evolve products, add features, and differentiate themselves from other players.
List of Key Companies:
- AGILOX Services GmbH
- Anhui Heli Co., Ltd.
- Balyo SA
- BlueBotics SA
- Daifuku Co., Ltd.
- GreyOrange
- Hangcha Group Co., Ltd.
- HD Hyundai Construction Equipment Co., Ltd.
- Hyster-Yale Materials Handling, Inc.
- Jungheinrich AG
- KION Group AG
- Mitsubishi Logisnext Co., Ltd.
- Oceaneering International, Inc.
- Seegrid Corporation
- Swisslog Holding AG
- Toyota Industries Corporation
- VisionNav Robotics
- Crown Equipment Corporation
Competitive Benchmarking
| Company | Headquarters | Notable Autonomous Forklift Focus |
| Toyota Industries Corporation | Japan | Broad autonomous forklift portfolio; launched Toyota Automated Logistics in April 2026 |
| KION Group AG | Germany | AI-powered Omniverse solution with NVIDIA/Accenture; functional-safety work with NVIDIA |
| Jungheinrich AG | Germany | Continuous R&D investment in sensors, AI algorithms, and cloud connectivity |
| Mitsubishi Logisnext Co., Ltd. | Japan | AI-enabled deployment for high-volume material handling |
| Hyster-Yale Materials Handling, Inc. | USA | ERP/WMS-integrated automated forklifts; new automated stacker launch (2026) |
| AGILOX Services GmbH | Austria | Infrastructure-free AMR navigation (X-SWARM); OFL omnidirectional free lifter |
| Swisslog Holding AG (KUKA AG) | Switzerland | IntraMove AMR line for dynamic horizontal pallet transport |
| GreyOrange | USA/Singapore | GreyMatter-enabled Certified Ranger Network forklifts handling up to 3,000 kg payloads |
Source: Polaris Market Research Analysis
Industry Developments
- September 2026: Hyundai Wia developed a fully autonomous forklift for cargo loading and material handling. The company equipped it with LiDAR, vision sensors, safety scanners, and digital twin technology. The forklift carried up to four tons and was scheduled to begin operations at Kia’s Hwaseong factory. (Source: koreatimes.co.kr)
- August 2026: Pudu Robotics launched the MP2000 autonomous forklift. The AI-powered pallet handler enabled fast, heavy-load transport in warehouses and factories. It used 3D LiDAR and depth cameras to identify pallets, avoid obstacles, and adjust routes in real time. (Source: therobotreport.com)
- July 2026: ABB Robotics announced the launch of Flexley Stack F712, an addition to its AMR portfolio. Flexley® Stack F712 expands ABB Robotics’ AI-enabled Visual SLAM technology to autonomous forklifts. It facilitates pallet transport and high-density storage. (Source: abb.com)
- April 2026: Reeman launched the X-ant Autonomous Forklift for precision pallet handling. The 2-ton intelligent forklift used Laser SLAM navigation, multi-sensor perception, and automated charging to improve safety, efficiency, and flexible material handling across warehouses and factories. (Source: reemanrobot.com)
Future Outlook
The autonomous forklift market is expected to experience strong growth in the coming years. Rising warehouse automation, labor shortages, and e-commerce expansion will continue to drive demand. Best autonomous forklift companies will increasingly adopt AI-based navigation, advanced sensors, and smart fleet management systems. Electric autonomous forklifts and flexible SLAM-based solutions are also expected to gain wider acceptance. Subscription-based models such as Robotics-as-a-Service may help reduce upfront investment barriers. Integration with smart warehouses and Industry 4.0 platforms will further expand applications. Overall, autonomous forklifts are likely to become an essential part of modern material handling and logistics operations.
Research Methodology
- Market estimates are derived using a blend of primary and secondary research, validated through weighted-average and combined top-down/bottom-up modeling approaches.
- Secondary research covers vendor filings, warehouse automation and material handling investment data, robotics as a service forklift adoption trends, industry journals, and paid third-party databases to build baseline estimates.
- Primary research includes interviews with key industry participants such as autonomous forklift manufacturers, AGV/AMR technology providers, warehouse and logistics operators, and fleet integrators, to validate accuracy and capture forward-looking insights.
- Base year considered is 2025, with a forecast provided through 2034; revenues are expressed in USD Billion.
- Parent market is identified as the global material handling equipment market; the addressable segment is narrowed using autonomous and AGV/AMR forklift adoption rates across warehousing and manufacturing environments.
- Bottom-up model aggregates regional autonomous forklift demand across type, navigation technology, tonnage capacity, fuel source, application, industry, and sales channel, validated against vendor revenue disclosures from KION Group, Toyota Industries, Jungheinrich, Hyster-Yale, and others.
- Regional coverage spans North America, Europe, Asia Pacific, the Middle East & Africa, and Latin America, further segmented by major countries.
- Projected 13.9% CAGR (2026–2034) reflects a weighted analysis of rising labor shortages, growing e-commerce and warehousing throughput demand, increasing adoption of robotic forklift, and advancements in LiDAR navigation forklift and SLAM-based navigation technologies.
- Findings are cross-validated across multiple estimation methods to ensure consistency, accuracy, and reliability of the final market sizing.
Autonomous Forklift Market Segmentation
By Type Outlook (Revenue – USD Billion, 2021–2034)
- Pallet Jacks
- Counterbalance Forklifts
- Reach Trucks
- Order Pickers
- Stacker Forklifts
By Navigation Technology Outlook (Revenue – USD Billion, 2021–2034)
- LiDAR
- Vision-guided
- SLAM (Simultaneous Localization and Mapping)
- Magnetic-guided
- Geofencing-based
- Other
By Tonnage Capacity Outlook (Revenue – USD Billion, 2021–2034)
- Below 5 Tons
- 5-10 Tons
- Above 10 Tons
By Fuel Source Outlook (Revenue – USD Billion, 2021–2034)
- Electric (Li-ion / Lead-acid)
- ICE
- LPG / CNG
- Hydrogen Fuel Cell
By Application Outlook (Revenue – USD Billion, 2021–2034)
- Manufacturing
- Warehousing
- Material handling
- Logistics & Freight
- Others
By Industry Outlook (Revenue – USD Billion, 2021–2034)
- 3rd Party Logistics
- Food & Beverages
- Automotive
- Paper & Pulp
- Metals & Heavy Machinery
- E-commerce
- Aviation
- Semiconductors & Electronics
- Healthcare
- Others
By Sales Channel Outlook (Revenue – USD Billion, 2021–2034)
- In-house
- Leasing/RaaS
By Regional Outlook (Revenue-USD Billion, 2021–2034)
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Brazil
- Argentina
- Rest of Latin America
Autonomous Forklift Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 5.32 billion |
| Market Size in 2026 | USD 6.05 billion |
| Revenue Forecast by 2034 | USD 17.14 billion |
| CAGR | 13.9% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Insights |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Autonomous Forklift Market FAQ's
The global market size was valued at USD 5.32 billion in 2025 and is projected to grow to USD 17.14 billion by 2034.
The market is projected to register a CAGR of 13.9% during the forecast period, 2026-2034.
Asia Pacific had the largest share 41.1% of the market.
Some key players include Toyota Industries Corporation, KION Group AG, Mitsubishi Logisnext Co., Ltd., Jungheinrich AG, Hyster-Yale Materials Handling, Inc., Hangcha Group Co., Ltd., AGILOX Services GmbH, Oceaneering International, Inc. (Oceaneering Mobile Robotics), Swisslog Holding AG (KUKA AG), Balyo SA, HD Hyundai Construction Equipment Co., Ltd., and Seegrid Corporation.
The below 5 tons segment accounted for the largest market share of 61.5% in 2025, driven by rising demand for vehicles with lower payload capacities.
The following are some of the market trends:Appeal of Artificial Intelligence technologies and Machine Learning Applications: There is an increased application of AI and ML-powered frameworks for enhanced autonomous systems decision making, navigation, and predictive maintenance. ? Enhancement of Exploitative Sensor Methods: There are notable improvements in multiple working conditions sensors such as LiDAR, Vision Guidance, and 3D cameras, which are increasing precision, multifunctional reliability, and multifaceted safety in the autonomous forklift operating environments.
An autonomous forklift is a self-operating industrial forklift that undertakes material handling activities without human help. Such a vehicle is outfitted with sensors, cameras, and AI, allowing it to automatically navigate surroundings, recognize obstacles, and perform actions such as lifting, transporting, and stacking materials. Autonomous forklifts, which are frequently considered a subset of automated guided vehicles (AGV) or autonomous mobile robots (AMR), help warehouses, manufacturing plants, and distribution centres by taking over repetitive labor tasks, enhancing productivity, safety, and reducing costs.
Autonomous forklifts cost 2–2.5 times the price of a comparable manual unit once sensors, fleet software, integration, and training are included. Many multi-shift warehouse operations recover the autonomous forklift cost within 1.5 to 2 years after installation.
Download Sample Report of Autonomous Forklift Market
Please fill out the form to request a customized copy of the research report.