Glass Interposers Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Glass Interposers Market Summary
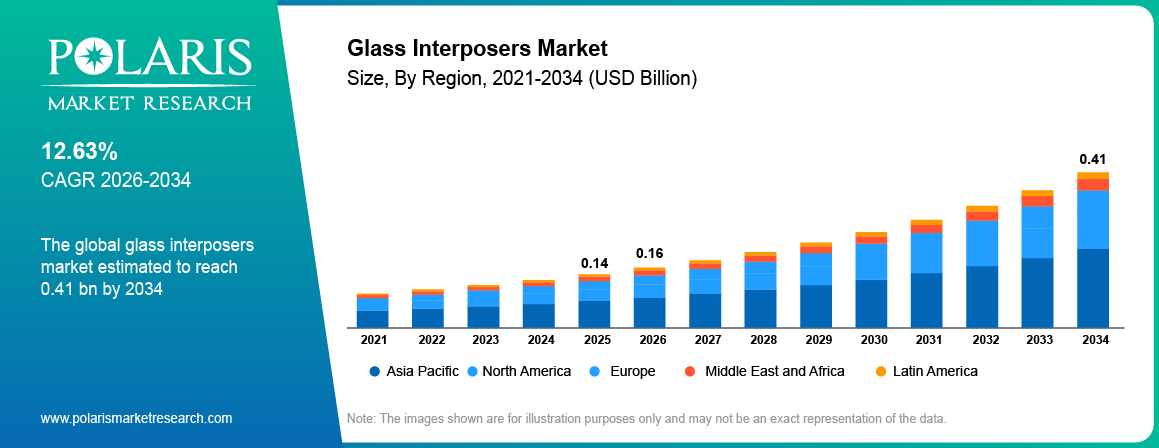
The glass interposers market size was valued at USD 0.14 billion in 2025. The market is expected to register a CAGR of 12.63% from 2026 to 2034. Market expansion is being driven by increasing adoption of AI accelerators, high-performance computing (HPC), data-center infrastructure, chiplet-based architectures, 2.5D and 3D packaging, and high-density semiconductor integration.
Market Statistics
Key Takeaways
- Asia Pacific dominated with 53.70% of the glass interposers market share in 2025. The regional dominance is driven by increasing investments in AI, data centers, and cloud infrastructure.
- In 2025, the U.S. accounted for the largest revenue share of 71.43% in the North American market. The leading share is attributed to the rising advancements in advanced packaging, AI chips, and system-in-package solutions
- The North America market is expected to register the significant CAGR of 12.05% during 2026 and 2034, owing to growing investments in semiconductors and advanced packaging.
- The 300 mm segment held the largest share of 60.30% in 2025, driven by its efficiency for high-volume manufacturing.
- The TGV segment led the market with 48.62% share in 2025 due to the rising interest in miniaturized, multilayer packages.
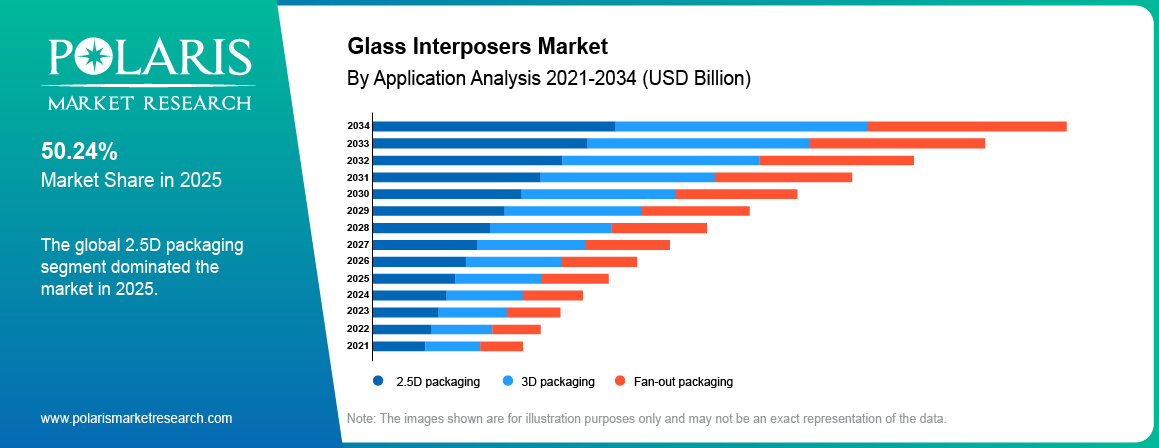
- 2.5D packaging held the leading share of 50.24% in 2025, owing to the rising adoption of AI accelerators and GPUs.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What are Glass Interposers?
The glass interposers market covers the manufacture and use of glass substrates that enable electrical connections between multiple semiconductor dies in advanced packaging. Glass interposers offer high dimensional stability, high-density interconnection, thermal stability, low dielectric loss, electrical insulation, and fine-pitch routing through glass vias (TGV). These properties are suitable for advanced semiconductor packaging applications and high density interconnect substrate applications. These features make them essential in high-performance computing, 5G, AI, and miniaturized electronics.
Expanding 5G infrastructure for technology requires miniaturized, high-frequency components. Glass interposers offer low signal loss and impressive RF performance, making them ideal for antenna-in-package and RF module integration in 5G base stations and devices. The technology is maturing to replace silicon interposers for high performance applications requiring higher interconnect density, larger package sizes and improved signal integrity. The adoption of new trends such as 2.5D and 3D IC packaging is accelerating the transition to glass-based semiconductor packaging, especially for AI accelerators, HPC systems, data centers and HBM packaging.
Their flatness, scalability, and high I/O density make them ideal for advanced semiconductor integration. Moreover, advanced driver assistance systems (ADAS) and autonomous driving technologies require high-speed data processing. Glass interposers support the integration of high-frequency components, enabling reliable signal transmission in automotive radar and sensor systems.
How are Glass Interposers Made?
Precision glass processing, TGV formation, metallization, RDL fabrication, and surface finishing are used to achieve high density interconnects in the manufacturing of glass interposers.
- Glass Pre-processing: Glass is cut, thinned, and polished in order to get a specific size.
- TGV Formation: Microvias in the glass are formed by lasers/chemicals.
- Metallization: Filling or metallization of TGVs using conductive metals such as copper.
- Redistribution Layer (RDL) Formation: Formation of redistribution layers with fine pitch to allow dense routing.
- Finishing and Testing: The glass substrate is polished and tested.
- Integration: Integration of the interposer with the chiplets/CPU/HBM stack.
Glass Interposer vs Silicon Interposer
| Factor | Glass Interposers | Silicon Interposers |
| Material | Glass substrate | Silicon wafer |
| Thermal expansion / dimensional stability | Superior stability; tunable CTE to match silicon | Higher CTE mismatch concerns at scale |
| Electrical performance | Low dielectric loss, strong RF/high-frequency performance | High performance but higher signal loss at scale |
| Manufacturing cost potential | Potentially lower at scale (cheaper raw material, panel-level processing) | Higher, mature but costlier manufacturing base |
| Panel/wafer format | Compatible with large-format panel-level packaging (PLP) | Limited to wafer-level formats |
| Market maturity | Emerging, rapidly scaling advanced packaging option | Established, dominant in current 2.5D/3D packaging |
Source: Polaris Market Research Analysis
Market Dynamics
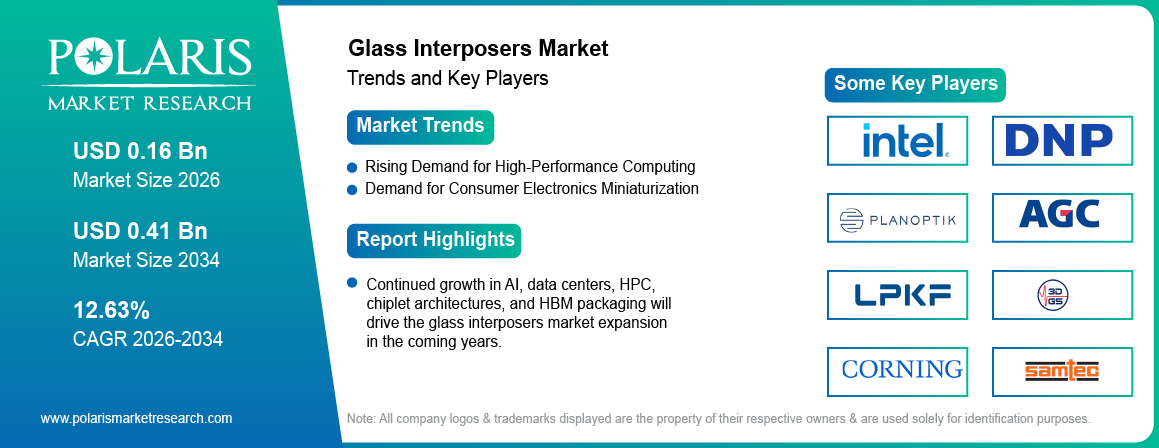
Driver: Rising Demand for High-Performance Computing
High-performance computing environments such as data centers, AI accelerators, and high-speed processors are placing increasing demands on semiconductor packaging. According to Goldman Sachs Research, data center power demand in the U.S. is expected to increase from 31 GW in 2025 to 41 GW in 2026 and 66 GW in 2027. These systems need components that can support high bandwidth, low latency, and strong thermal performance to run efficiently under heavy workloads. Glass interposers are perfect for this need, as they can provide dense interconnections between chips whilst maintaining signal integrity. They are thermally stable, meaning that the heat is properly dissipated and the risk of failure during heavy-duty work is thus minimized. As the need for faster computing and parallel processing increases, glass interposers are becoming a key component for the development of advanced chip architectures that can support today’s performance requirements (Source: goldmansachs.com).
Driver: Demand for Consumer Electronics Miniaturization
The consumer electronics industry is constantly striving for thinner, lighter, and more powerful devices, which is creating a demand for compact packaging technologies. Glass interposers support this trend, allowing multiple chips to be stacked or placed side-by-side in a smaller footprint without sacrificing electrical or thermal performance. They are flat and dimensionally stable, making them perfect for tight spaces such as smartphones, augmented reality headsets and wearable devices. It allows manufacturers to pack more functions into smaller devices, and increase speed and efficiency. Miniaturization trend of electronics is expected to continue, which will boost demand for glass interposers in consumer technology segment.
Driver: AI Accelerator and Chiplet Integration Demand
The increasing use of AI accelerators is driving demand for chiplet architectures that combine multiple dies in a single package. The glass interposer enables fine routing, large package size, and high interconnect density for chiplet and heterogeneous integration. The Semiconductor Industry Association said global semiconductor sales were $403.3 billion in Q2 2026, an increase of 35.1% from Q1 2026, driven by strong demand for advanced computing and electronic components. Thus, rising AI accelerator and chiplet integration demand propel the market expansion (Source: semiconductors.org).
Restraint: High Manufacturing Costs and Technical Complexity
Glass interposers are manufactured via precision-intensive TGV formation, metallization, RDL processing, inspection, and package integration. The manufacturing process requires special equipment, high yields, process control, and semiconductor qualification. These can lead to higher investment and production costs. High costs and technical complexity could impede commercialization and limit the adoption by manufacturers lacking advanced packaging capabilities.
Restraint: Competition from Silicon and Organic Interposers
Glass interposers are in competition with established silicon and organic interposer technologies. Silicon and organic interposers have the benefit of established manufacturing processes, supply chains, and qualification frameworks. Thus, glass-based solutions are required to show benefits in dimensional stability, high-density routing, signal integrity, and larger package formats. As existing alternate interposer technologies meet application needs, the market witnesses limited expansion.
Opportunity: Panel-Level Packaging & Automotive Electrification
The rising emphasis on panel-level packaging and automotive electrification is expanding potential applications for glass interposers. Panel-level packaging enables larger-format processing, better material utilization, and scalable glass-core substrates for AI and high-performance applications. Automotive electrification is accelerating the semiconductor content in applications such as power management, sensing, connectivity, and computing systems. Growing adoption of ADAS and autonomous driving is creating demand for compact, high-density interconnect solutions. As a result, the market is projected to offer lucrative opportunities in the coming years.
Challenges in Glass Interposers Market
TGV construction, metallization, RDL processing, inspection, and glass handling remain major manufacturing challenges. Brittleness and thermal-mechanical stress may reduce yield and reliability at larger substrate sizes.
- TGV Processing: Needs high-precision manufacturing.
- Yield: Defects can hamper manufacturing efficiency.
- Glass Handling: Fragility adds to processing difficulty.
- Thermal Stresses: Can impact packaging reliability.
- Process Integration: Needs packaging machinery compatibility.
- Qualification: Extensive testing can delay commercialization.
To commercialize glass-based semiconductor packaging, make it cost-effective, and enable wider adoption, it is important to improve process control, defect management, and volume yield.
Commercial adoption will depend on management of TGV faults, metallization quality, warpage, thermal stress, and package reliability for large substrates. Achieving consistent yields at wafer and panel scale remains a key industry challenge. Maintaining uniform process performance across larger substrates will be critical for achieving cost-effective high-volume manufacturing.
Segmentation Analysis
Glass interposers market segmentation includes wafer size, substrate technology, application, end-use industry, and region.
By Wafer Size
Based on wafer size, the segmentation includes less than 200 mm, 200 mm, and 300 mm. The 300 mm segment accounted for 60.30% revenue share in 2025 on account of their compatibility with high-volume manufacturing and higher cost efficiency per die. Foundries and OSATs are building advanced interposers on 300 mm substrates to address high-performance computing, AI and advanced packaging applications. Larger wafer size means more chips on the wafer, and better use of processing capacity, so less material waste. Other drivers are consistent quality, improved flatness and ability to scale across production lines. With growing demand for advanced semiconductor packaging, manufacturers are increasing their investments in 300 mm glass interposer technology to improve throughput and satisfy performance requirements.
The 200 mm segment is expected to witness a substantial CAGR of 12.14% during the forecast period, owing to its increasing relevance in mid-range semiconductor applications. Foundries manufacture 200 mm interposers for consumer electronics, sensors, and IoT devices in a less complex and more affordable way. Demand for 200 mm substrates is being driven by growth in applications that do not require large-scale integration, such as wearables, mobile peripherals and edge devices. Furthermore, its wafer size offers flexibility for prototyping and early-stage development, making it attractive for fabless semiconductor startups and small-volume customers. The increasing adoption of this format can also be attributed to the availability of refurbished equipment and enhanced process maturity.
By Substrate Technology
The segmentation in substrate technology is through-glass vias (TGV), redistribution layer (RDL) first/last, and glass panel level packaging (PLP). The through-glass vias segment accounted for the largest share of 48.62% in 2025. Growing interest in miniaturized, multilayer packages is boosting TGV popularity. TGVs provide high-density vertical interconnections with strong signal integrity and low thermal expansion mismatch. TGV allows fine-pitch routing and dense via placements, which are well suited for 2.5D and 3D integration in high-performance chipsets. The technology allows for precise alignment, thin profiles, and high electrical isolation, all of which are critical for RF, AI, and memory modules. TGV's manufacturing maturity and compatibility with high-frequency signal transmission give it a distinct advantage over other substrate technologies.
The glass panel level packaging segment is expected to record the highest CAGR of 14.85% during the forecast period. This growth is attributed to its advantages in semiconductor packaging, such as higher throughput and lower cost per unit. PLP uses large glass panels instead of circular wafers, this provides better space utilization and high volume production. The scalability is valuable, especially for consumer electronics, where cost and performance must meet. Manufacturers are embracing PLP to boost yield, cut edge loss, and support larger form factors. Enhanced panel processing and alignment accuracy are accelerating this. This approach has a strong potential for mass-market applications such as display drivers, power management and sensors.
By Application
Based on application, the segmentation is 3D packaging, 2.5D packaging, and fan-out packaging. The 2.5D packaging segment led the market with 50.24% share in 2025, due to its balance of performance, cost, and complexity. This enables multiple dies to be placed side by side on an interposer and provides high-bandwidth communication without full 3D stacking. Glass interposers are well suited to this architecture because of their dimensional stability and dense I/O routing capability. Meanwhile, the application of 2.5D in advanced computing and data center environments is propelled by the demand for AI accelerators, GPUs, and server processors. It is easier to manufacture and has less thermal stress than full 3D packages. Thus, 2.5D packaging is preferred for high-performance but cost-sensitive designs.
The fan-out packaging segment is anticipated to exhibit a CAGR of 13.54% during 2026–2034. The growth is fueled by its ability to provide compact form factors with sustained performance and thermal efficiency. This packaging approach allows for I/Os re-distribution without the need for an interposer, which is ideal for space-limited devices. The use of glass interposers in fan-out architectures gives better mechanical stability and heat dissipation, which is important for mobile and wearable electronics. “Manufacturers are exploring fan-out technologies to meet the demand for thinner, lighter solutions for smartphones, RF modules and edge computing. The move to heterogeneous integration and system-in-package (SiP) designs will likely drive further adoption over the next few years.
Comparison Matrix: 3D Packaging Vs 2.5D Packaging Vs Fan-Out Packaging
| Packaging Type | Description | Current Position | Growth Outlook |
| 2.5D Packaging | Side-by-side die integration on an interposer for high-bandwidth, lower-complexity designs | Led the market in 2025 | Steady growth, driven by AI/HPC |
| 3D Packaging | Vertically stacked dies for maximum density | Smaller share | Growing with chiplet adoption |
| Fan-Out Packaging | Redistributes I/O without an interposer; compact form factor | Smaller share, growing fast | Expected to grow significantly from 2026 to 2034 |
Source: Polaris Market Research Analysis
By End-Use Industry
In terms of end-use industry, the segmentation includes consumer electronics, telecommunications, automotive, defense & aerospace, healthcare, data centers, and others. The consumer electronics segment accounted for the largest revenue share of 38.61% in 2025, due to the high adoption of advanced packaging in smartphones, tablets, AR/VR headsets, and wearables. These devices require high-speed processing, compact size, and efficient thermal management, making glass interposers a suitable solution. Glass substrates enable multi-chip integration while maintaining low power consumption and signal integrity. Major OEMs are pushing for thinner, multifunctional devices, which is driving the use of glass-based interposer solutions. Strong demand for premium and performance-focused gadgets also encourages semiconductor manufacturers to adopt advanced glass interposer-based packaging that meets the rigorous performance expectations of tech-savvy consumers.
The automotive segment is projected to register the highest CAGR of 14.34% during the forecast period, driven by the electrification of vehicles and rising adoption of advanced driver-assistance systems (ADAS). These applications require reliable, high-speed data transmission between sensors, processors, and control units, which glass interposers can support through low signal loss and high thermal stability. The integration of radar, LiDAR, infotainment, and autonomous driving modules demands miniaturized, high-performance packaging solutions. Glass interposers help meet safety and reliability standards crucial in automotive environments. Increased semiconductor content per vehicle and the push toward intelligent mobility systems are expected to fuel long-term growth in this segment.
Real-World Applications & Use Cases
Glass interposers are increasingly being employed in AI accelerators, GPUs, high-performance computing, and data centers as they are needed to provide dense interconnects and chiplet integration. Low dielectric loss and dimensional stability allow for larger packages and high-speed signal transmission.
- AI & HPC: Offers high-density chiplet and processor integration.
- Data Centers: Enabling large packages and high-speed interconnects.
- HBM Packaging: Provides high-density processor-memory connectivity.
- Telecom: Facilitates high-speed compact packaging.
- Automotive: Leads to advanced semiconductor packaging.
- Consumer Electronics: Enabling compact, high-performance packages.
Glass interposers are being investigated for 2.5D/3D IC packaging, telecommunications, automotive electronics and advanced consumer products, thereby extending their use in high-performance semiconductor applications.
Regional Insights
North America Glass Interposers Market
The North America market accounted for 24.40% of the revenue share in 2025, due to strong demand from high-performance computing and advanced packaging sectors. Major investments in AI, data centers, and cloud infrastructure require highly efficient and reliable semiconductor integration. In June 2025, Governor Josh Shapiro announced Amazon’s plan to invest USD 20 billion in Pennsylvania to develop AI infrastructure. This investment will help advance artificial intelligence (AI) technologies, increase data processing, grow machine learning capabilities, and support AI applications across multiple industries. The region has a mature semiconductor ecosystem with established foundries and OSATs that support the adoption of glass interposer solutions for 2.5D and 3D packaging. The region’s emphasis on defense, aerospace, and telecom innovation also promotes the use of advanced interposer technologies. Research institutions and public-private partnerships also support new packaging methods, further strengthening the market position across North America (Source: pa.gov).
U.S. Glass Interposers Market Insights
The U.S. led North American market with 71.43% revenue share in 2025. The dominances is attributed to the rising innovation in AI chips, advanced packaging, and system-in-package solutions. Leading semiconductor and tech companies are investing in custom chip architectures that demand reliable and scalable interconnect technologies. Demand for advanced consumer electronics, high-performance processors, and data center hardware creates a strong market pull for glass interposers. Strategic initiatives around reshoring semiconductor manufacturing and supporting domestic foundries through federal funding are further strengthening U.S. capabilities. A strong presence of technology hubs, innovation clusters, and research programs positions the country as a key adopter of next-generation interposer materials and packaging formats.
Asia Pacific Glass Interposers Market
The Asia Pacific market dominated the market with 53.70% in 2025, owing to its strong base for semiconductor manufacturing, advanced packaging capacity, and demand from the consumer electronics and telecom sectors. Regional growth is being fueled by government support in South Korea, Taiwan and India. Taiwan holds 21% share of global semiconductor manufacturing capacity and 92% of advanced chip manufacturing. The APAC data center pipeline reached 26.5 GW in H1 2026, up 17% year-on-year, driven by AI and cloud demand, according to Cushman & Wakefield. Rising semiconductor investments in China, Japan, South Korea, Taiwan, and India will boost TGV and glass core technologies (Source: cushmanwakefield.com).
China Glass Interposers Market Overview
In Asia Pacific, China held a dominant share of 36.10% in 2025, due to strategic push to localize semiconductor supply chains and reduce reliance on imports. Foundries at home are increasingly investing in innovative packaging technologies to support the growing needs of consumer electronics, electric vehicles, and 5G infrastructure. Local production of high-end interposer substrates is driven by favorable policy initiatives and expanding fabrication capacity. The growing emphasis on AI, computing, and edge-processing hardware development is also increasing demand for high-density, thermally stable interconnect solutions. This national focus on tech self-sufficiency is driving large-scale adoption and innovation in the glass interposer segment.
Europe Glass Interposers Market Outlook
The market in Europe is projected to register a CAGR of 11.62% during the forecast period. The growth will be supported by rising investments in automotive electronics, especially for electric and autonomous vehicles. The region’s focus on developing semiconductor manufacturing capacity under initiatives such as the EU Chips Act is encouraging adoption of advanced packaging solutions. The EU Chips Act is mobilizing up to USD 50.3 billion of public and private investment, and the IPCEI Microelectronics project has unlocked USD 9.5 billion to boost Europe’s semiconductor R&D and manufacturing ecosystem. The demand for reliable thermally efficient interposer materials is growing in ADAS, power modules, and infotainment systems. R&D infrastructure and academia-industry collaborations are helping the development of high-performance interposer technologies adapted to European use cases. Other companies in the region focus on electronics manufacturing, where glass interposers’ recyclable, stable substrate option supports sustainability (Source: euacc.ai).
Innovation & Technology Trends
Innovation centers on TGV, fine-pitch RDL, glass core substrates, and larger panel formats. These technologies are expected to enhance the interconnect density, dimensional stability, processing efficiency, and packaging scalability.
- Advanced TGV: Provides finer vertical interconnects.
- Fine Pitch RDL: Allows for more dense routing.
- Glass Core: Provides better stability and scaling.
- Glass PLP: Allows larger-format processing.
- Chiplet Integration: Provides heterogeneous package capabilities.
- Optical Integration: Uses glass in photonics.
The growing development of glass panel level packaging (PLP), HBM integration and co-packaged optics is expanding the role of glass interposer technology in future generation packaging.
Competitive Insights
The competitive landscape of the glass interposer market is changing rapidly due to developments in semiconductor packaging, rising demand for heterogeneous integration, and increasing need for high-performance interconnect solutions. Industry analysis highlights increased focus on market expansion strategies, including capacity scaling and geographic diversification to address high-growth regions in Asia Pacific and North America.
Glass interposer key players are involved in mergers and acquisitions to strengthen their technological edge and integrate vertically across interposer value chain. Strategic alliances and joint ventures are being formed to co-develop through-glass via (TGV) processes, panel-level packaging and redistribution layer innovations. Post merger integration efforts are geared toward making supply chains more streamlined and improving the efficiency of R&D. Advances in glass handling, etching accuracy, and thermal stability are defining a competitive edge. As the adoption of AI, 5G and automotive electronics increases, glass interposer manufacturers are focusing on innovation, cost control and time-to-market to stay ahead in this high-density packaging and interconnection segment.
Key Players
- 3D Glass Solutions
- AGC Inc.
- Corning Incorporated
- Dai Nippon Printing
- Intel Corporation
- LPKF Laser & Electronics
- PLANOPTIK AG
- RENA Technologies
- Samtec
- Samsung Electro-Mechanics
- SCHOTT AG
- TECNISCO
- TSMC
- Workshop of Photonics
Competitive Benchmarking
| Company | HQ | Glass Interposer / Packaging Focus | Key Positioning |
| AGC Inc. | Japan | TGV substrates, glass cores, glass carriers | Active development of glass-based semiconductor packaging solutions |
| Corning Incorporated | U.S. | Semiconductor glass wafers, TGV, glass carriers | Strong focus on high-performance glass substrates for advanced packaging |
| SCHOTT AG | Germany | Specialty glass wafers and substrates | Provides specialty glass solutions for semiconductor applications |
| TSMC | Taiwan | Advanced packaging, heterogeneous integration | Strong capabilities in chiplet and 2.5D/3D packaging |
| Samsung Electro-Mechanics | South Korea | Glass core substrates, advanced package substrates | Developing glass-based substrates for AI, servers, and data centers |
| Intel Corporation | U.S. | Glass substrates, advanced packaging | Developing glass substrates for larger, higher-density packages |
| 3D Glass Solutions | U.S. | Glass interposers, TGV technology | Specialized provider of glass-based interposer solutions |
| LPKF Laser & Electronics | Germany | Glass structuring, TGV processing | Develops laser-based technologies for glass substrate manufacturing |
| RENA Technologies | Germany | TGV and glass panel processing | Provides processing solutions for glass-based advanced packaging |
Source: Polaris Market Research Analysis
Recent Developments
- In September 2026, Anycasting raised USD 5.4 million to build a glass substrate and interposer plating pilot line in South Korea and advance its all-wet, void-free plating technology. (Source: finance.biggo.com)
- In August 2026, Atomica launched an AI photonic integration platform. The platform combines microfabrication technologies for silicon and glass interposers, through-silicon and through-glass vias. (Source: chiplet-marketplace.com)
- In July 2026, Samsung Electronics and Samsung Display announced a partnership on glass interposers to support next-generation AI semiconductor packaging. (Source: thelec.net)
- In June 2026, Qnity Electronics, Inc. launched advanced packaging material solutions for organic interposer applications, Intervia 8540HSP multi-role copper and Cyclotene™ DF6800M dry film photo-imageable dielectric. They are expected to support advanced interconnect formation, RDL designs, and emerging glass substrate structures. (Source: businesswire.com)
- In May 2026, Rapidus announced that, with Lam’s panel-level solutions, it is developing a 2.xD packaging technology that forms RDL on 600mm-square glass carriers. (Source: trendforce.com)
Future Outlook
Continued growth in AI, data centers, HPC, chiplet architectures, and HBM packaging will drive the glass interposers market expansion in the coming years. Larger package sizes and denser interconnects are driving demand for advanced packaging interposer solutions with high dimensional stability and fine routing.
The development of TGV, glass core substrates, glass PLP, RDL, and 2.5D/3D packaging is expected to improve technology scalability. Greater integration of electrical and optical functions could further expand the use of glass-based semiconductor packaging across high-performance and data-intensive applications.
Research Methodology
The Polaris Market Research glass interposers market report uses a rigorous two-stage methodology combining top-down and bottom-up approaches to ensure consistency across market estimates, segment analysis, and regional forecasts for the 2025 base year and 2026–2034 forecast period.
Secondary Research: Market sizing and segmentation are supported by semiconductor industry data, company reports, industry associations, government databases, regulatory filings, and technical publications covering TGV, RDL, glass core substrates, 2.5D/3D IC packaging, HBM, and chiplet integration.
Primary Research: The research findings have been validated by discussions with C-level executives, semiconductor packaging engineers, substrate manufacturers, equipment vendors, industry analysts, foundry representatives, and advanced packaging specialists from key locations.
Data triangulation: Estimates are triangulated with demand side analysis, supply side production data, firm level information, packing capacity, technology adoption and investment trends. Regional and segment estimates are cross-validated with primary research, with final estimates reflecting the consensus view of the Polaris analyst team.
Glass Interposers Market Segmentation
By Wafer Size Outlook (Revenue, USD Billion, 2021-2034)
- Less than 200 mm
- 200 mm
- 300 mm
By Substrate Technology Outlook (Revenue, USD Billion, 2021-2034)
- Through-Glass Vias (TGV)
- RDL-First/RDL-Last
- Glass Panel Level Packaging
By Application Outlook (Revenue, USD Billion, 2021-2034)
- 3D
- 2.5D
- Fan-Out
By End-Use Industry Outlook (Revenue, USD Billion, 2021-2034)
- Consumer Electronics
- Telecommunications
- Automotive
- Defense & Aerospace
- Healthcare
- Data Centers
- Others
By Regional Outlook (Revenue, USD Billion, 2021-2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Glass Interposers Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 0.14 Billion |
| Market Size in 2026 | USD 0.16 Billion |
| Revenue Forecast by 2034 | USD 0.41 Billion |
| CAGR | 12.63% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Glass Interposers Market FAQ's
Glass interposers are substrates that employ TGVs and RDLs to connect several semiconductor dies in advanced packaging.
The global glass interposers market size was valued at USD 0.14 billion in 2025 and is projected to reach USD 0.41 billion by 2034. Growing demand for AI accelerators and 5G devices fuels the market expansion.
Global glass interposers market is anticipated to exhibit a CAGR of 12.63% during 2026 to 2034, due to increasing demand from high-performance computing environments, such as data centers, AI accelerators, and high-speed processors.
It employs glass substrates with small electrical traces for 2.5D/3D IC packaging, chiplets, and HBM assembly.
Key applications are AI accelerators, GPUs, HPC, data centers, HBM packaging, telecoms, and consumer electronics.
The through-glass vias segment held the largest revenue share in 2025. It is attributed to its ability to provide high-density vertical interconnections while maintaining signal integrity and low thermal expansion mismatch.
In the application segment, 2.5D packaging accounted for the largest share of 50.24% in 2025, as it provides a balance between performance, cost, and complexity
Asia Pacific dominated the market with 53.70% in 2025, driven by investments in semiconductor manufacturing and advanced packaging.
The 300 mm segment accounted for 60.30% of the revenue share in 2025. The leading position is fueled by high-volume semiconductor manufacturing and production efficiency
AI and data-center growth, chiplet integration, HBM demand and increasing adoption of advanced semiconductor packaging are major drivers.
Key companies are AGC Inc., Corning Incorporated, Intel Corporation, Samsung Electro-Mechanics, SCHOTT AG, TSMC, LPKF Laser & Electronics, 3D Glass Solutions and others.
Download Sample Report of Glass Interposers Market
Please fill out the form to request a customized copy of the research report.