Food Inclusions Market Size & Share Global Analysis Report, 2026-2034
REPORT DETAILS
Food Inclusions Market Summary
The global food inclusions market size was valued at USD 15.07 billion in 2025, growing at a CAGR of 5.66% during 2026–2034. Changing consumer preferences, evolving eating habits, and growing demand for premium food products are a few of the key factors driving market growth.
Market Statistics
Key Takeaways
- Europe led the global market with a 36.0% share in 2025. The region’s strong bakery tradition and high dairy consumption drive its dominance.
- Asia Pacific is projected to witness robust growth at a 4.80% CAGR. The regional market growth is driven by shifting dietary habits.
- The solid & semi solid segment accounted for the largest market share of 84.0% in 2025. This is owing to the segment’s strong consumer appeal.
- The bakery products segment is anticipated to register the highest CAGR of 5.20%. The segment’s growth is primarily due to growing consumer demand for innovative baked goods.
- The nuts & seeds segment led with a 21.0% share in 2025. This is because consumers increasingly favor natural and functionally healthy ingredients.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
Industry Dynamics
- Rising consumer preference for value-added food products is fueling demand for food inclusions. Food inclusions help brands meet evolving consumer expectations by adding texture, variety, and premium appeal.
- The expansion of the plant-based food sector is fueling the need for food inclusions that help improve the appeal and functionality of plant-based food products.
- The exploration of novel flavors, textures, and formats by manufacturers to cater to a more discerning customer base presents a major market opportunity.
- Fluctuating raw material costs may present market challenges.
AI Impact on Food Inclusions Market
- AI assists in formulating new foods for inclusion in manufacturing by using consumer behavior analysis and market trends.
- AI makes formulation development easy as it can discover ingredient combinations that help to improve taste, texture, and stability.
- AI contributes to maintaining the quality of the products through real-time tracking of the production process.
- AI aids in forecasting the demand and assists in managing inventories as well as logistics.
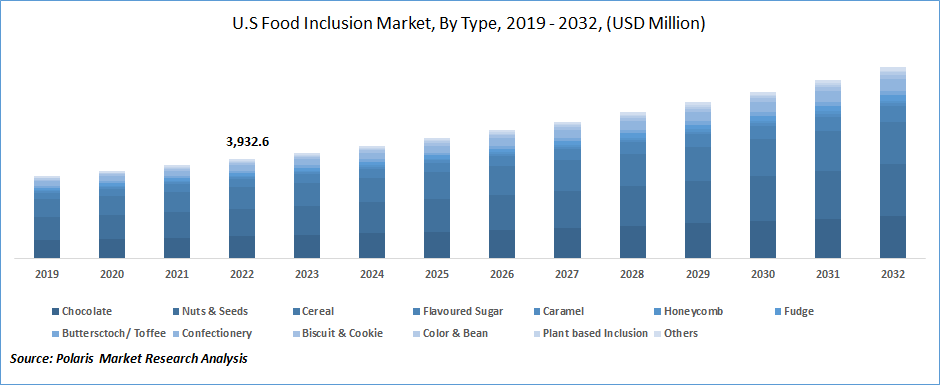
Source: Polaris Market Research Analysis
To Understand More About this Research:Download Sample Report
Food inclusions refer to edible components added to food products to enhance their flavor, texture, appearance, and nutritional value. These can include fruits, nuts, chocolates, candies, cereals, herbs, and more. They are commonly used in bakery, dairy, confectionery, snacks, and frozen foods. The purpose of food inclusions is to elevate the sensory appeal and consumer experience of everyday food items. As brands seek differentiation in a crowded marketplace, food inclusions have become a strategic tool for innovation and value addition.
The global food inclusions market growth is attributed to changing consumer preferences and evolving eating habits. The shifting trends toward personalized and indulgent eating experiences have created strong momentum for the adoption of innovative inclusions. Manufacturers are exploring novel textures, flavors, and formats to cater to a more discerning customer base. This shift represents a significant market growth opportunity, encouraging investments in research and development to create standout products.
The rising demand for premium and artisanal food products is playing a vital role in fueling the food inclusions market expansion. Consumers actively seek authenticity and uniqueness in their food choices, favoring handmade or high-quality offerings that feature distinctive ingredients. Artisanal brands are using inclusions such as gourmet nuts, exotic fruits, or small-batch chocolates to craft exclusive products that resonate with modern expectations.
The increasing consumer preference for texture-rich foods amplifies this trend. Crunchy, chewy, or creamy inclusions add a multisensory dimension, making food more engaging. This growing demand for texture-rich and sensory-enhanced products is pushing brands to innovate continuously, unlocking new avenues for the market growth opportunity.
Natural vs Artificial Food Inclusions
| Aspect | Natural Foods Additives | Artificial Foods Additives |
| Source | Natural sources like fruits, nuts, seeds, and cocoa | Human-made additives |
| Flavor | Authentic flavor | Highly standard |
| Nutrition | Higher nutritional contribution | Low nutritional content |
| Shelf Life | Shorter | Usually longer |
| Clean-Label Appeal | High | Lower |
| Processing Requirements | More complicated procedures | Easier to standardize |
Market Dynamics
Growing Preference for Value-Added Food Products
Growing consumer preference for value-added food products is significantly driving the demand for food inclusions. Modern consumers are no longer satisfied with basic offerings and actively seek foods that provide enhanced taste, nutrition, and sensory experience. Food inclusions such as fruits, nuts, chocolates, and grains help brands meet these evolving expectations by adding variety, texture, and premium appeal to standard products. Health-conscious buyers also favor inclusions that offer functional benefits, such as protein-rich seeds or antioxidant-packed berries. This shift in consumer behavior encourages manufacturers to innovate, incorporating high-quality inclusions to stay competitive. The rising interest in indulgent yet nutritious foods continues to expand the demand for food inclusions, creating numerous opportunities for product diversification and market growth across multiple food categories.
Expanding Plant-Based Food Sector
The expanding plant-based food sector is significantly driving the market growth. Consumers are increasingly seeking innovative, health-conscious alternatives that also deliver on taste and texture. This surge spans categories such as plant-based meat, milk, yogurt, cheese, ice cream, and fish, emphasizing the growing consumer shift. Food inclusions such as fruit pieces, nuts, grains, and flavor clusters play a crucial role in enhancing the appeal and functionality of these products. Manufacturers are nowadays leveraging inclusions to differentiate offerings and meet evolving preferences, further fueling market demand across diverse segments within the plant-based landscape.
Snack Food and Cereal Inclusion Trends
Rising demand for food products that offer convenience, nutrition, and ease of consumption is driving the use of food inclusions in snack foods and breakfast cereals. Consumers seek food products that deliver not only tasty but also texturally appealing and nutritious attributes. Thus, companies have begun introducing nuts, seeds, dried fruits, chocolate bits, protein crisps, and cereal clusters into formulations. Examples of such products include granola bars, snack mixes, breakfast cereals, and health bars. Moreover, rising consumers' interest in proteins and fiber has prompted manufacturers to create new inclusion ingredients as part of an effort to differentiate their products on the market.
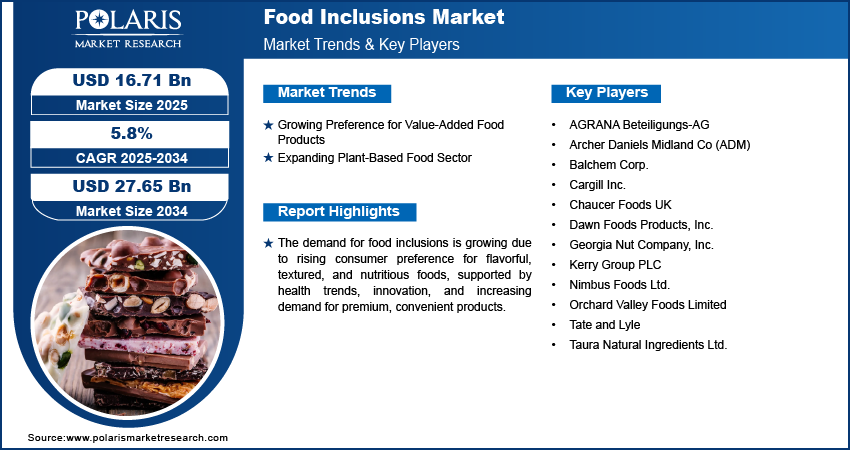
Source: Polaris Market Research Analysis
Food Inclusions Market Segment Analysis
Market Assessment by Form
The global food inclusions market segmentation, based on form, includes solid & semi solid and liquid. The solid & semi solid segment accounted for 84.0% of the food inclusions market share in 2025 due to their versatility, ease of incorporation, and strong consumer appeal. These formats enhance texture, flavor, and visual appeal in a wide range of products such as bakery, confectionery, dairy, and snacks. Manufacturers prefer solid and semi-solid inclusions for their stability during processing and storage. Growing demand for premium and indulgent food experiences has further driven the adoption of chunks, chips, flakes, and similar formats. Their compatibility with multiple food matrices significantly contributes to the dominance of the solid & semi solid segment in the market.
Market Evaluation by Application
The global food inclusions market segmentation, based on application, includes cereal products, snacks & bars, bakery products, dairy, frozen desserts, chocolate & confectionery products, and others. The bakery products segment is expected to register the highest CAGR of 5.20% during the forecast period due to increasing consumer demand for innovative, flavorful, and textured baked goods. The rising interest in premium bakery items such as filled pastries, flavored breads, muffins, and cookies is driving the use of food inclusions such as fruits, nuts, chocolate chips, and seeds. Changing lifestyles and a growing preference for convenience foods are encouraging manufacturers to enhance product appeal through inclusions. The popularity of artisanal and health-focused bakery products is also contributing to this trend. The expanding product lines and frequent product launches in the bakery sector are significantly supporting the growth of the segment.
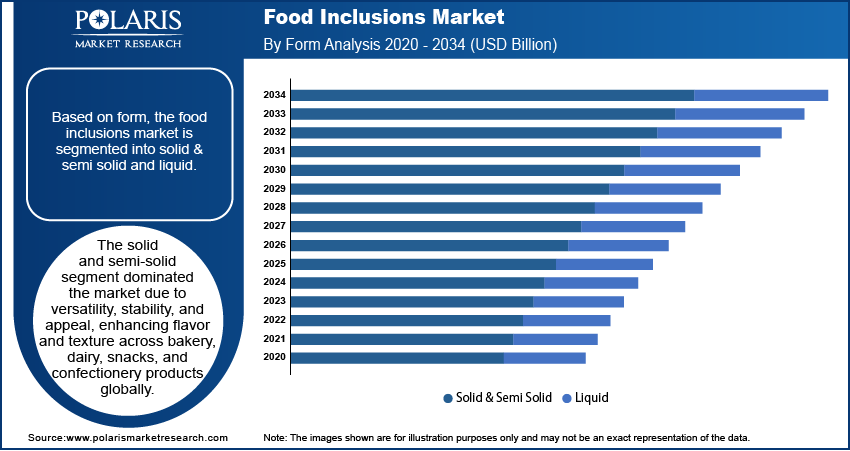
Source: Polaris Market Research Analysis
Food Inclusions Market Regional Analysis
By region, the study provides market insights into North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Europe dominated the global market share of 36.0% in 2025 due to its strong tradition of bakery, confectionery, and dairy consumption, which consistently drives innovation in food textures and flavors. The high consumer awareness regarding premium and indulgent products has fueled demand for inclusions such as fruits, nuts, chocolates, and cereals. The presence of major food manufacturers and a mature food processing industry further supports the integration of diverse inclusions into everyday products. Stringent quality standards and growing interest in clean-label and natural ingredients have encouraged the use of high-quality inclusions. Constant product innovation, supported by a strong retail infrastructure, continues to meet evolving consumer preferences, reinforcing Europe’s position as a leading region in the global market.
The Asia Pacific food inclusions market is experiencing substantial growth with 4.80% CAGR due to rapid urbanization, rising disposable incomes, and changing dietary habits. Consumers in the region are increasingly seeking premium, flavorful, and convenient food products, driving the demand for inclusions in bakery, dairy, and snack items. The expanding middle-class populations and growing interest in Western-style foods are boosting the appeal of products containing chocolate chips, fruit pieces, nuts, and other inclusions. Local manufacturers are also innovating to cater to regional tastes, further fueling food inclusions demand. The combination of economic development and evolving consumer preferences positions Asia Pacific as a key growth region in the global market.
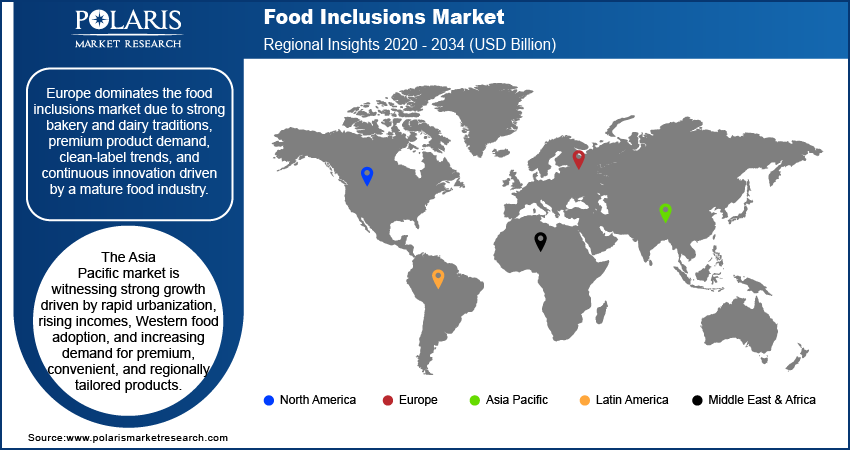
Source: Polaris Market Research Analysis
Food Inclusions Market – Key Players and Competitive Analysis Report
The market is highly dynamic, driven by innovation in taste, texture, and health-conscious formulations. Competitive positioning among key players reflects strategic investments in R&D, flavor diversification, and clean-label offerings. ADM; AGRANA Beteiligungs-AG; Balchem Corporation; Cargill, Incorporated; Chaucer Foods Ltd.; Dawn Foods Products, Inc.; Georgia Nut Company, Inc.; IFF / Taura; Kerry Group plc; Meadow Inclusions; OV Group are among the leading companies shaping the market landscape. Competitive trends indicate a growing emphasis on plant-based, allergen-free, and functional inclusions to meet evolving consumer demands. Companies are leveraging advanced processing technologies and sustainable sourcing to strengthen market share. Partnerships, mergers, and global expansions are further intensifying competition as firms aim to secure broader distribution channels and enhance product portfolios. Innovation-driven differentiation and customer-centric approaches define the current competitive positioning in this fast-evolving industry.
List of Key Companies
- ADM
- AGRANA Beteiligungs-AG
- Balchem Corporation
- Cargill, Incorporated
- Chaucer Foods Ltd.
- Dawn Foods Products, Inc.
- Georgia Nut Company, Inc.
- IFF / Taura
- Kerry Group plc
- Meadow Inclusions
- OV Group
Future Outlook
The global food inclusions market is forecasted to expand steadily in the next few years on account of increasing demand for high-end baked goods, functional snacking, natural ingredients, and personalization of foods. Food inclusions are being used by manufacturers to add value to food products, such as enhancing flavors, textures, appearances, and nutrient content in a variety of products. Innovations in flavor protection systems, freeze drying, plant-based food inclusions, and nutritional enhancement are leading to new growth areas in bakery, dairy, confectionery, cereals, snacks, and frozen desserts categories. Moreover, increasing consumer inclination toward visually attractive and nutritious foods is fueling demand for food inclusions.
Food Inclusions Industry Developments
- May 2026: CSM Ingredients launched Creami. It is an innovative line of indulgent fillings that offer a combination of highly structured textures and unique inclusions, like Crunchy Pistachio and Crunchy Hazelnut, created by caramelizing kataifi. (source: csmingredients.com)
- January 2026: Cargill officially broke ground on the expansion of its Beijing plant in Changping District. The company stated that the expansion project includes the development of two independent production lines for flavored beverage powders and flavored coatings. The project is expected to be operational by the first half of 2027. (source: cargill.com)
Food Inclusions Market Segmentation
By Product Outlook (Revenue, USD Billion, 2021–2034)
- Chocolate
- Nuts & Seeds
- Cereal
- Flavored Sugar
- Caramel
- Honeycomb
- Fudge
- Butterscotch/Toffee
- Confectionery
- Biscuit & Cookie
- Color & Bean
- Plant-Based Inclusion
- Others
By Form Outlook (Revenue, USD Billion, 2021–2034)
- Solid & Semi Solid
- Pieces
- Nuts
- Flakes & Crunches
- Chips & Nibs
- Powder
- Liquid
By Application Outlook (Revenue, USD Billion, 2021–2034)
- Cereal Products
- Snacks & Bars
- Bakery Products
- Dairy
- Frozen Desserts
- Ice Cream
- Chocolate & Confectionery Products
- Others
By Regional Outlook (Revenue, USD Billion, 2021–2034)
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Food Inclusions Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 15.07 Billion |
| Market Size Value in 2026 | USD 15.90 Billion |
| Revenue Forecast by 2034 | USD 24.74 Billion |
| CAGR | 5.66% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Food Inclusions Market FAQ's
The global market size was valued at USD 15.07 billion in 2025 and is projected to grow to USD 24.74 billion by 2034.
The global market is projected to register a CAGR of 5.66% during the forecast period.
Europe led the global market with a 36.0% share in 2025.
A few key players in the market are ADM; AGRANA Beteiligungs-AG; Balchem Corporation; Cargill, Incorporated; Chaucer Foods Ltd.; Dawn Foods Products, Inc.; Georgia Nut Company, Inc.; IFF / Taura; Kerry Group plc; Meadow Inclusions; OV Group
The solid & semi solid segment accounted for the largest market share of 84.0% in 2025.
The bakery products segment is anticipated to register the highest CAGR of 5.20%.
Download Sample Report of Food Inclusions Market
Please fill out the form to request a customized copy of the research report.