
Lithium Chemicals Market Size, Share, Trends and Forecast, 2026–2034
REPORT DETAILS
Lithium Chemicals Market Summary
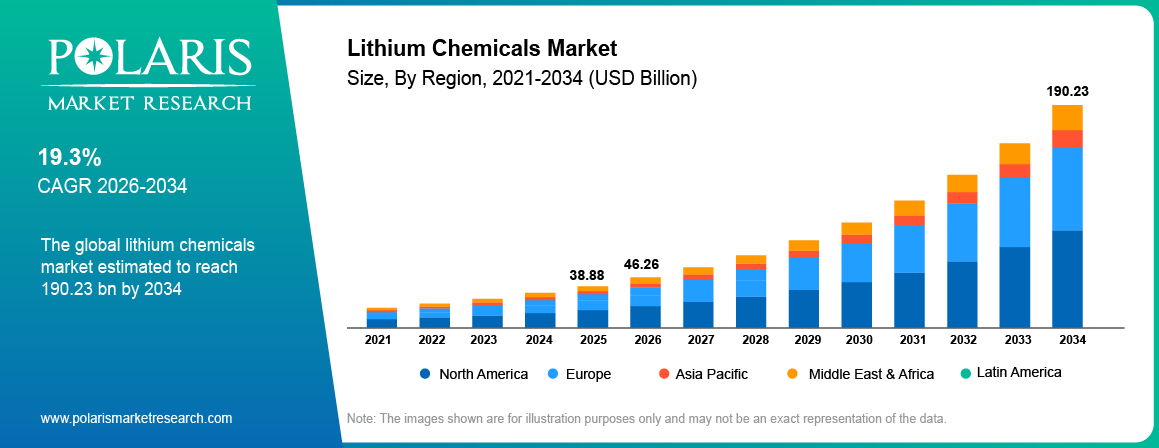
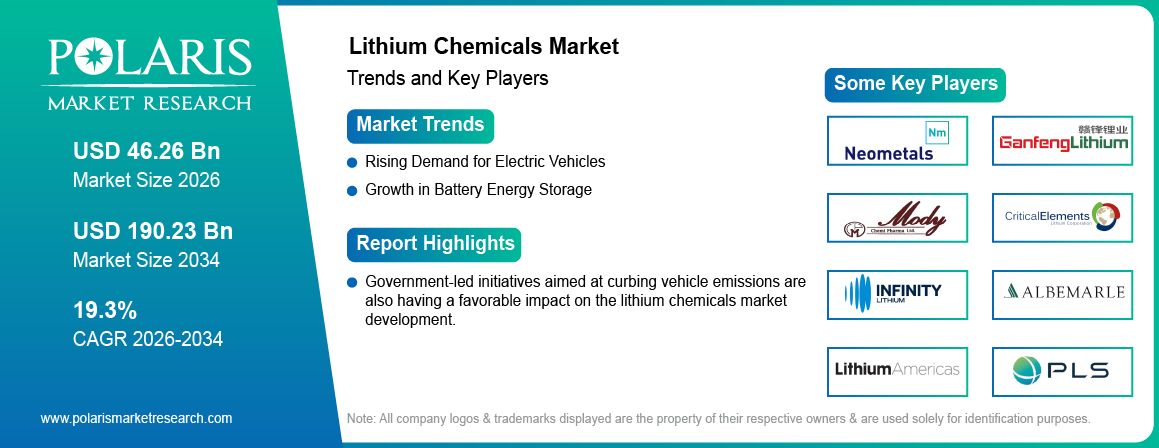
The global lithium chemicals market size was valued at USD 38.88 billion in 2025. The market is projected to grow at a CAGR of 19.3% from 2026 to 2034. The rising adoption of electric vehicles (EVs) globally has accelerated the demand for lithium compounds. Government-led initiatives aimed at curbing vehicle emissions are also having a favorable impact on the lithium chemicals market development.
Market Statistics
Key Takeaways
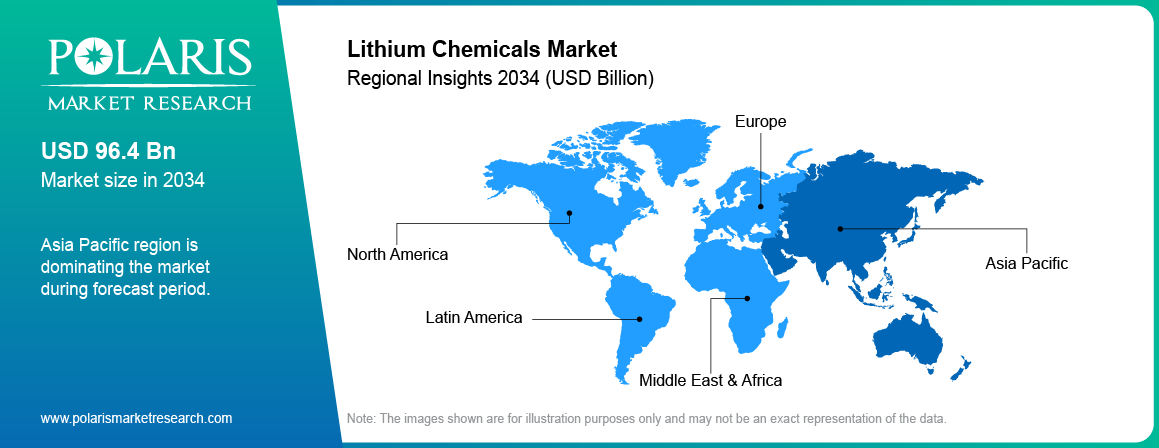
- Asia Pacific led the global market with an 59.8% share in 2025. The presence of favorable government initiatives and availability of raw materials contribute to the regional market dominance.
- North America is projected to witness the fastest growth at a 20.1% CAGR. Rising EV adoption and favorable policy frameworks drive the regional market growth.
- By product, the carbonate segment accounted for the largest lithium chemicals market share of 60.3% in 2025. This is owing to its extensive use in lithium-ion batteries.
- By product, the hydroxide segment is projected to register notable growth at an 21.4% CAGR during the lithium chemicals market forecast 2034 period. The growing adoption of high-nickel cathode chemistries such as NCM 811 and NCA contributes to the segment’s rapid development.
- By application, the batteries segment held an 78.5% market share in 2025. The expansion of renewable energy has resulted in increased demand for large-scale grid and residential battery storage systems.
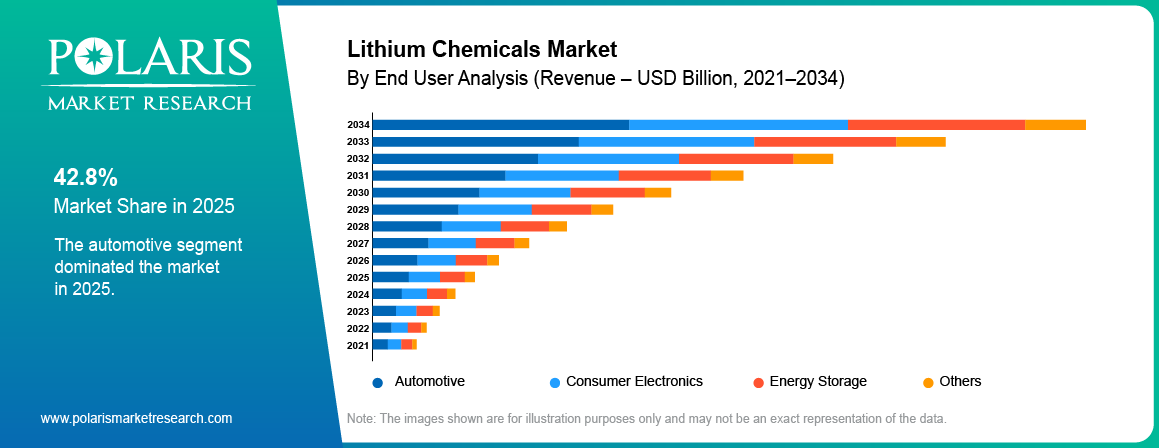
- By end user, the automotive segment led with an 42.8% lithium chemicals market share in 2025. The rapid penetration of EVs and hybrid vehicles drives the segment’s leading position.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What Are Lithium Chemicals?
Lithium chemicals are compounds that are used to make lithium-ion batteries and other products. Lithium carbonate and lithium hydroxide are some common examples of such lithium chemicals. These lithium chemicals are used by battery makers to manufacture the cathode for EV batteries and energy storage systems.
Battery-grade lithium refers to lithium compounds that meet the purity standards for batteries. The quality of such materials influences the performance of battery materials. Lithium carbonate equivalent (LCE) is used by the industry to compare various forms of lithium on a common basis. These measures help track lithium supply, demand, and production.
How Are Lithium Chemicals Made?
Lithium chemicals are produced by mining lithium from natural resources and converting it into lithium chemicals. This varies with the source of lithium.
Extraction of lithium: There are two main sources of lithium. The first is spodumene/hard rock ore, which is extracted from the earth. The second one is underground brine that has dissolved lithium salts.
Processing of raw materials: Processing of the hard rock ore is done through crushing and heating the material. The extraction of brine involves bringing the material to the surface of the earth for further processing. Sometimes evaporation ponds are used to concentrate the lithium material.
Lithium separation: Lithium is separated through chemical treatment from other materials contained within the hard rock ore. There is also the direct lithium extraction process (DLE). It involves the capture of lithium from water using special materials.
Chemical production: Lithium is used to make chemicals such as lithium carbonate and lithium hydroxide. These lithium chemicals serve different purposes in various industries.
Purification and purity test: The produced lithium chemicals are purified prior to any purity level test. Lithium that is intended for batteries has very stringent requirements in terms of purity.
Production-Route Comparison
| Route | Feedstock | Output | Strength | Constraint |
| Brine evaporation | Salt-lake brines (Chile, Argentina, China) | Lithium carbonate, chloride | Low cost at source | Water use; slow cycle; climate dependent |
| Hard-rock conversion | Spodumene concentrate (Australia, others) | Carbonate or hydroxide | Faster ramp; hydroxide route | Energy and reagent intensity |
| Direct lithium extraction (DLE) | Brines, including lower-grade | Carbonate or chloride | Higher yield; smaller footprint | Scale-up and cost still being proven |
| Recycling (black mass) | End-of-life batteries, scrap | Recovered lithium salts | Reduces mining dependence | Collection volumes and recovery rates |
Source: Polaris Market Research Analysis
2026 Lithium Chemicals Price and Capacity Update
The price of lithium chemicals has witnessed a lot of volatility in 2026. This is because of the demand from electric vehicle manufacturers and battery energy storage applications. The factors that have impacted prices include inventory changes and expectations for new production. There was a significant fall in prices for lithium carbonate in September in China. This trend continued in October.
Expansion in capacity is one of the key areas for lithium suppliers. Many companies have been expanding their projects so as to produce more lithium. Production, however, will depend on timelines for these projects and operating conditions. These will impact the 2027 supply-demand balance for lithium chemicals. Buyers and manufacturers are also paying attention to lithium price trends to assess market conditions.
Lithium Carbonate Price Trend in 2026
The lithium carbonate prices per ton 2026 have varied substantially during the year. China's domestic market provides a useful reference to analyze these variations. The table below indicates selected price points.
| Period | Price (RMB per tonne) | Market movement |
| Mid-May 2026 | Approximately 210,000 | Prices reached a high during the year. |
| End-August 2026 | Approximately 159,300 | Prices eased from the May level. |
| September 30, 2026 | 127,750 | Prices fell sharply during September. |
| October 21, 2026 | Approximately 102,000 | Prices remained under pressure. |
| October 26, 2026 | Approximately 98,300 | Prices continued to reflect weaker market conditions. |
Source: Polaris Market Research Analysis
Note: These figures are indicative market observations for China. Prices can vary by product grade and assessment method. Prices can also vary by supplier.
The lithium price trend reflects changes in supply prospects and battery demand. Buyers often ask why have lithium prices fallen when demand for electric vehicles is high. One reason is that prices depend on not only consumption but also the available supply. If there is increased supply and prospects of future production, prices may drop.
Lithium carbonate price forecasts are influenced by how these variables shift in the coming months. When purchasing, buyers need to pay attention to the production level and inventory shift. They should also consider the lithium carbonate vs lithium hydroxide price difference. Both products serve the battery industry. However, the application areas and manufacturing processes differ.
Capacity and Supply Additions
Lithium mining companies are making investments in expansions at current plants as well as in building new projects. These investments include projects using brine sources as well as hard rock sources. Some projects have commenced operations, while other projects are still under development. Their contribution to the global supply will depend on the construction progress and production ramp-up.
| Company / Project | Location | Capacity or planned addition | Status |
| Cauchari-Olaroz Stage 2 | Argentina | Planned additional capacity of 45,000 tonnes of LCE per year | Expansion plan |
| Centenario-Ratones | Argentina | Proposed additional capacity of 11,000 tonnes of LCE per year | Development stage |
| Thacker Pass Phase 1 | United States | Planned capacity of 40,000 tonnes of battery-quality lithium carbonate per year | Production targeted for a later phase |
| SQM's Chilean operations | Chile | Target of more than 300,000 tonnes of LCE in production capacity by the end of 2027 | Capacity growth plan |
Source: Polaris Market Research Analysis
Note: LCE means lithium carbonate equivalent. Figures represent stated capacity targets and should not be treated as confirmed new production available in 2026.
These projects demonstrate lithium capacity growth in the major production areas. However, the announced capacities do not necessarily mean increased supplies. Delays in construction and permit processes may influence project timelines. Producers must also assess whether the price level in the market justifies adding additional capacity.
Supply–Demand Outlook for Buyers and Producers
The lithium supply and demand 2027 outlook will be influenced by the rate of production and consumption of batteries. Electric vehicles continue to be one of the sources of lithium consumption. Energy storage batteries are another source of demand. If the growth of supply is greater than that of consumption, the prices may fall. Delays at large projects may have an opposite effect.
For buyers, the lithium carbonate price forecast can improve procurement decisions. Manufacturers should consider the market prices in order to decide on additional capacity increases. The demand for lithium batteries will be based on battery manufacturing needs and availability of materials. Using the lithium carbonate equivalent (LCE) in the reporting of supply allows comparison of production volumes across different lithium products.
Lithium Chemicals Market Dynamics
The lithium chemicals market is shaped by factors like battery requirements, production capacity, and variations in supply of raw materials. However, price volatility and processing costs remain concerns. The introduction of innovative technologies in terms of extraction and recycling is reshaping the producers’ approach to supply.
Driver: Rising Demand for Electric Vehicles
Demand for lithium chemicals is rising due to increased usage of electric vehicles. Key raw materials used in making lithium-ion batteries include lithium carbonate and lithium hydroxide. As car companies expand their EV portfolios, there is a need for a steady supply of raw materials. This is prompting investments in the capacity to process and refine lithium. An increase in electric vehicle production is driving demand across the wider battery value chain.
Driver: Growth in Battery Energy Storage
Renewable energy expansion has increased demand for battery energy storage solutions. Battery energy storage is required to store the power generated using solar and wind sources to be used during low generation periods. These batteries have been widely used due to their higher energy density and reliability. The need for storage is growing to maintain the stability of the grid and to control variations in renewable energy production. This is driving the use of lithium chemicals outside the electric vehicle industry.
Driver: Expanding Electronics Market
There has been an increase in the use of smartphones, laptops, tablets, and wearable devices. This has driven the demand for lithium chemicals. These devices use small, rechargeable lithium-ion batteries. Newer electronics are also demanding better batteries to provide more energy efficiency. Lithium-based compounds are needed by manufacturers of these devices to manufacture their batteries. Therefore, there is increased demand for lithium chemicals due to continued growth in consumer electronics.
Driver: Government Policies and Critical Minerals Strategies
Governments have been creating policies to promote the adoption of electric vehicles and the manufacturing of batteries in their jurisdictions. Such policies include tax breaks, subsidies, and investments in infrastructure related to charging electric vehicles. Additionally, many governments are seeking ways to secure supplies of critical minerals such as lithium in order to limit reliance on imports and to enhance local refining capabilities. Consequently, there has been an increase in the number of investments in lithium mining and refining as well as battery material production.
Driver: New Gigafactory Investments
Battery manufacturers and automakers are investing in large-scale battery production facilities. These facilities are commonly known as gigafactories. Large quantities of lithium chemicals are required for manufacturing lithium-ion batteries at such factories. The construction of new facilities is under way due to the growing requirements from electric vehicles and batteries for energy storage. It leads to an increase in the requirements for reliable sources of battery-grade lithium products. At the same time, it encourages investments in refining capacity and regional supply chains.
Restraints and Challenges: High Cost of Lithium Processing
The manufacturing of battery-grade lithium compounds involves the use of special processing equipment. This can raise operating costs, especially in cases where companies are establishing their refining units. Processing costs differ depending on the extraction method used and the quality of the crude materials used. Small companies may face challenges in competing with the existing suppliers owing to economies of scale. These cost pressures may impact profitability. They may also hinder capacity growth in certain markets.
Restraints and Challenges: Environmental Concerns and Regulatory Requirements
Lithium mining is prone to delays because of potential environmental issues that may arise during project implementation. This is more pronounced in places where water is scarce. In addition, the activities associated with mining may produce hazardous waste. In addition, firms may be required to manage such wastes in an environmentally friendly way. They also have to get permission before commencing their operations or expanding them. Getting the permission takes time, particularly if there is opposition to the project and more stringent environmental assessments. Such problems may make the project costly and delay the supply of lithium chemicals to the market.
Trends and Opportunities: Direct Lithium Extraction and New Processing Methods
Direct lithium extraction (DLE) is emerging as an option for producers seeking an alternative approach to extracting lithium from brine. Some DLE methods may shorten the extraction time for lithium compared to that of traditional evaporation ponds. Each DLE technology and its water efficiency and recovery rate will depend on the specific site. Technological advancements in DLE may enable producers to utilize deposits from which it has been challenging to extract lithium with traditional methods. Additionally, advancements in spodumene/hard rock processing provide opportunities to enhance lithium recovery rates and reduce lithium waste. These methods give producers greater flexibility due to the rising demand for lithium chemicals.
Trends and Opportunities: Battery Recycling and Sustainable Supply
Battery recycling and black mass recovery are creating another opportunity in the lithium chemicals industry. There are lithium as well as other valuable compounds that exist in batteries that are used and can be recovered and processed to be used again. Various recycling companies are trying to find ways to extract lithium from black mass, which forms when batteries are broken down. This provides another avenue for sourcing raw materials without the need for new extraction efforts. An improved circular chain may also assist battery makers in overcoming material shortages and reducing waste. Effective means of recycling and efficient recovery techniques will be important due to the rising number of retired batteries.
Lithium Chemicals Market Segmental Insights
| Segmentation Axis | Segments |
| By Product | Carbonate · Hydroxide · Chloride · Metal · Fluoride · Others |
| By Application | Batteries · Glass & Ceramics · Lubricant · Polymers · Metallurgy · Medical · Air Treatment · Others |
| By End User | Automotive · Consumer Electronics · Energy Storage · Others |
| By Region | North America (US, Canada) · Europe (Germany, France, UK, Italy, Spain, Netherlands, Russia, Rest of Europe) · Asia Pacific (China, Japan, India, Malaysia, South Korea, Indonesia, Australia, Vietnam, Rest of Asia Pacific) · Middle East & Africa (Saudi Arabia, UAE, Israel, South Africa, Rest of Middle East & Africa) · Latin America (Mexico, Brazil, Argentina, Rest of Latin America) |
Source: Polaris Market Research Analysis
By Product
The carbonate segment accounted for a 60.3% lithium chemicals market share in 2025. Lithium carbonate is one of the main raw materials used to manufacture cathodes for lithium-ion batteries. It is utilized in battery cathode chemistry that consists of LFPs, which are commonly utilized in EVs and stationary energy storage applications. Moreover, LFP batteries are used when cost and battery lifespan are significant. Apart from battery manufacturing, lithium carbonate has applications in glass, ceramics, and other industrial applications. Thus, its use supports demand from battery manufacturers and other industrial sectors. The expansion of battery production contributes to its significance as a major product category in the lithium chemicals industry.
The hydroxide segment is projected to witness rapid growth at a 21.4% CAGR. Lithium hydroxide is mainly used to make cathode materials in lithium-ion batteries, where the battery needs to have high energy density. In this regard, it is particularly useful in the making of NCM 811 / high-nickel cathodes and NCA cathodes in electric vehicles. Such battery technologies enable battery manufacturers to increase energy capacity while using less cobalt. Lithium hydroxide is, thus, an essential material for making batteries with increased driving range capabilities. Its application in high-nickel cathode production supports demand from battery manufacturers for electric vehicles.
Lithium Carbonate vs Lithium Hydroxide
| Basis of Comparison | Lithium Carbonate | Lithium Hydroxide |
| Chemical formula | Li₂CO₃ | LiOH |
| Appearance | White crystalline powder | White solid, usually obtained in powder form or monohydrate |
| Chemistry used for batteries | Often utilized in LFP cathodes | Extensively utilized in high-nickel cathodes |
| Examples of cathode | LFP and some NMC cathodes | NCM 811 and NCA |
| Use in EV batteries | Common lithium source in batteries in mass-produced EVs | Used in cathodes that give more energy density |
| Other industrial uses | Glass and ceramics | Lithium grease |
| Process by which it is produced | Lithium recovery from brine or hard-rock ore | Lithium processing, lithium carbonate conversion |
| Primary battery usage | LFP batteries in EVs and stationary power | High-nickel batteries in some long-range EVs |
Source: Polaris Market Research Analysis
By Application
The batteries segment held a 78.5% lithium chemicals market share in 2025. Lithium chemicals are used in the production of key battery parts such as cathodes. Lithium carbonate is commonly used in LFP batteries whereas lithium hydroxide is often used in high-nickel batteries. Such batteries provide power for electric vehicles and serve as means of energy storage for households, business enterprises, and electricity networks. This application has become one of the significant factors that impact the lithium chemicals market because of demand coming from battery makers. Production of batteries is no longer limited to cars; it is also used in commercial transport and renewable energy storage. The range and volume of lithium chemicals vary according to the battery chemistry used.
The lubricant segment is projected to grow at a 16.8% CAGR. Lithium compounds are used extensively in manufacturing lithium grease, which helps reduce friction between the moving parts. The uses of lithium grease include vehicles, machinery, construction equipment, and manufacturing processes. The grease operates under various operating conditions and serves as a protector against wear. Lithium hydroxide is a vital component used in the production og lithium greases through a reaction with fatty acids to make the thickener. The need for lithium greases in the maintenance of automobiles and industrial machinery supports this application. The use of lithium greases in machinery that needs constant lubrication drives the demand for lithium compounds.
By End User
The automotive segment led with a 42.8% lithium chemicals market share in 2025. Lithium chemicals serve as raw materials for batteries needed in passenger cars, electric buses, and commercial vehicles. The consumption will depend on the battery capacity and the chemistry used by the respective automobile manufacturers. For instance, some automobiles meant to travel long distances can have a different battery chemistry from automobiles meant for shorter distances. Lithium chemicals enter the supply chain through the manufacturers of batteries and cathodes rather than just the automobile makers. As such, the automotive segment is closely linked with the production volumes of the batteries and design of the automobiles. The segment’s market share reflects the high use of lithium batteries in automobiles.
The consumer electronics segment is projected to witness rapid growth at an 18.7% CAGR. Lithium chemicals are utilized in rechargeable batteries found in smartphones, laptops, and tablets. These devices require lithium batteries to supply the energy needed by the device. The quantity of lithium used varies depending on the size of the battery as well as the volume of production. Manufacturers of consumer electronics require batteries that can be fitted into their devices without adding much weight to the device. Lithium chemicals are required to manufacture such batteries. This makes the consumer electronics industry a major source of demand for lithium chemicals.
Key Use Cases and Real-World Applications
| Use Cases and Real-World Applications | Date and Location | Program / Company | Application and Market Relevance |
| Commercial lithium refining | April 2026, British Columbia, Canada | Mangrove Lithium’s commercial electrochemical refining facility | Mangrove Lithium opened a commercial facility in Delta, British Columbia, designed to produce 1,000 tonnes of battery-grade lithium annually. The output can support batteries for approximately 25,000 electric vehicles. The project strengthens Canada's domestic battery supply chain. |
| Lithium-ion cell manufacturing | July 2026, Telangana, India | Amara Raja Giga Corridor | Amara Raja commissioned a 60 MWh Customer Qualification Plant to manufacture and validate lithium-ion cells before commercial-scale production. The facility forms part of its INR 9,500 crore gigafactory program. It supports the development of domestic battery manufacturing capacity. |
| Direct lithium extraction from brine | August 2026, Utah, United States | Lilac Solutions' Great Salt Lake lithium project | The U.S. Department of Energy selected Lilac Solutions for a $100 million award to support a planned lithium production facility. Phase 1 targets 5,000 tonnes of battery-grade lithium carbonate annually from brine. The project aims to expand domestic access to critical minerals for battery production. |
Source: Polaris Market Research Analysis
Lithium Chemicals Market Regional Analysis
The lithium chemicals market varies across regions based on battery production capacity, lithium chemical facilities, and the availability of raw materials. The Asia Pacific market is supported by the existing battery industry. North America and Europe are developing their own local supply chains to lower reliance on imports.
Asia Pacific
Asia Pacific accounted for the largest market share of 59.8% in 2025. The Asia Pacific region has a prominent role in the lithium chemicals market because of its existing battery manufacturing industry. In China, Japan, and South Korea, there are well-developed supply chains for lithium-ion batteries. They supply electric vehicle makers and consumer electronics firms. The other source of demand for lithium chemicals is through energy storage devices that support electricity grids. Battery manufacturers need lithium carbonate and lithium hydroxide for the preparation of cathode materials for batteries. China plays an important role in the processing and manufacturing of lithium chemicals as well as battery materials. Japan and South Korea contribute through the technologies involved in battery making and the production of battery materials. There are also developments going on in India for battery manufacturing due to growing local demand for electric cars. Australia's hard-rock lithium supplies also add to the Asia Pacific supply chain.
China
China held a 62.5% share of the regional market in 2025. China has a significant lithium processing sector that provides raw materials to battery producers. It produces lithium carbonate and lithium hydroxide used to make rechargeable batteries. Lithium carbonate is popularly used in making LFP batteries, while lithium hydroxide is used by high-nickel cathode manufacturers. The lithium chemicals are supplied to battery manufacturers catering to the electric vehicle and energy storage sectors. The lithium chemicals market in China is influenced by its role in battery material processing. The companies in China deal with both domestic and imported materials. They have multiple sources of raw materials. Price changes for lithium can influence processing margins and purchasing decisions.
North America
North America is projected to witness rapid growth at an 20.1% CAGR. North America is developing lithium chemical capacity to support battery manufacturers and electric vehicle producers. North America has lithium deposits but lacks local processing capacity, which is a critical segment of development. Lithium carbonate and lithium hydroxide are required for manufacturing batteries. Other consumers of battery materials are stationary storage projects where lithium-ion batteries are used to store electricity. Another source of demand for battery materials is linked to the growth of the battery energy storage system market. Development of local lithium processing facilities will help decrease dependence on imports of the chemicals. However, construction of such facilities requires considerable investments and time.
United States
The U.S. is projected to grow at a 19.5% CAGR. The U.S. lithium market demand is influenced by projects designed to develop domestic lithium production and increase processing capacities. Lithium chemicals are necessary in order to manufacture batteries for electric cars and stationary energy storage systems. Several companies are working on projects designed to mine lithium from brine and hard rock sources. Other companies in the lithium chemicals market U.S. are exploring ways of recycling lithium from other sources. These projects might result in additional supply of raw materials for the domestic production of batteries. The pace of these developments will be defined by their cost-effectiveness, permitting, and their ability to compete with overseas suppliers.
Europe
Europe accounted for a 19.6% lithium chemicals market share in 2025. Europe has an established automotive sector as well as battery manufacturing facilities. There is a large number of electric vehicles produced in Germany, while Spain and France are developing their battery manufacturing industries. Both sectors need lithium carbonate and lithium hydroxide in order to produce batteries. The region is also working on establishing its own lithium mining and refining facilities. Recycling of batteries is another area of activity in the region. Recovered material may be used to produce batteries once again. The lithium chemicals market Europe is closely linked to the region’s electric vehicle battery manufacturing industry. Lithium chemicals are also required for energy storage batteries used in the power grid.
Latin America
The Latin America lithium chemicals market is projected to grow at an 18.9% CAGR. Argentina is one of the largest producers of lithium extracted from brine, with output being processed in battery material plants in international markets. Brazil contributes through its hard rock lithium deposits and mining activity. Mexico also has its own lithium deposits; however, the commercial development of the deposits is not as advanced as that of Argentina and Brazil. Lithium extraction and processing activities in the Latin America region vary by country. The brine production of lithium in Argentina and the hard rock lithium production in Brazil give the region various lithium feedstock supplies. Lithium feedstock production and mineral processing in other parts of Latin America also contribute to the region’s role in the lithium chemicals industry.
Middle East & Africa
The Middle East & Africa accounted for a 4.2% lithium chemicals market share in 2025. Both Saudi Arabia and the UAE are exploring battery manufacturing as they diversify away from their traditional oil and gas industry. For these countries, lithium chemicals could be used for battery manufacturing and storage facilities in the future. The role of Israel in the industry is different. Israeli companies focus on research in battery technologies and materials. Other countries in the region vary in their involvement in lithium activities based on their resource availability and industrial focus. Their activities vary in development, ranging from research and investment to actual mineral extraction.
Key Players and Competitive Landscape
Competition in the lithium chemicals market is based upon the availability of feedstocks and capability to manufacture battery-grade chemicals. The largest lithium producers include firms engaged in extraction from brines as well as hard rock mining operations. Some of them have refining operations where the lithium feedstocks are turned into lithium carbonate and lithium hydroxide. Other lithium chemicals companies specialize in processing and supplying lithium chemicals to battery manufacturers. Product quality is an essential factor, as battery manufacturing companies need a certain purity of chemicals. It is also necessary to develop new processing technologies and increase manufacturing capabilities in response to changing customer needs. Establishing long-term supply contracts with the battery makers can help in securing demand.
Vendor Positioning
| Company | Position in Chain | Positioning Note |
| Albemarle Corporation | Lithium extraction and chemical processing | An established producer with operations spanning lithium resources and chemical conversion. Its product portfolio includes lithium carbonate and lithium hydroxide for battery and industrial applications. |
| Critical Elements Lithium Corporation | Upstream project development | Developing the Rose Lithium-Tantalum Project in Quebec. Its planned spodumene concentrate production could supply downstream lithium processing, subject to project development and commercial execution. |
| Ganfeng Lithium Group Co., Ltd. | Integrated lithium production and processing | Operates across lithium resource development and battery-related businesses. Its involvement in lithium compounds and recycling extends its reach beyond raw material extraction. |
| Infinity Lithium Corporation Limited | Lithium project development and planned chemical production | Focuses on the San José Lithium Project in Spain. Its proposed development is aimed at supplying lithium chemicals to the European market. |
| Lithium Americas Corp. | Lithium resource development and planned chemical production | Developing the Thacker Pass project in Nevada, which is intended to produce lithium carbonate for battery supply chains in North America. |
| Mody Chemi-Pharma Limited | Specialty chemical manufacturing | Has a broader chemical product portfolio that includes lithium salts. Its position is more closely linked to chemical supply than to large-scale lithium mining. |
| Neometals Ltd | Lithium processing technology and material recovery | Develops processing technologies and recovery solutions. Its lithium-related role is linked to process development and potential commercial partnerships rather than established large-scale chemical production. |
| PLS Group Limited | Hard-rock mining and downstream conversion | Produces spodumene concentrate from its Pilgangoora operation and has exposure to lithium hydroxide conversion through its South Korean joint venture. |
| Rio Tinto Lithium | Lithium resource development and chemical production | Combines Rio Tinto's mining capabilities with lithium assets and processing expertise acquired through Arcadium Lithium. This expands its presence across the lithium value chain. |
| Sichuan Brivo Lithium Materials Co., Ltd. | Lithium materials production | Included among lithium materials suppliers. Its precise product range, production scale, and role in battery-grade chemical supply should be confirmed against current company information. |
| Sociedad Química y Minera de Chile S.A. (SQM) | Lithium extraction and chemical processing | Produces lithium compounds from Chilean resources. These compounds include lithium carbonate and lithium hydroxide. Its products serve battery manufacturing and industrial applications. |
| Talison Lithium Pty Ltd | Hard-rock mining and concentrate production | Operates the Greenbushes lithium mine in Western Australia. It produces spodumene concentrate for downstream processing into lithium chemicals. |
Source: Polaris Market Research Analysis
List of Key Players
- Albemarle Corporation
- Critical Elements Lithium Corporation
- Ganfeng Lithium Group Co., Ltd.
- Infinity Lithium Corporation Limited
- Lithium Americas Corp.
- Mody Chemi-Pharma Limited
- Neometals Ltd
- PLS Group Limited
- Rio Tinto Lithium
- Sichuan Brivo Lithium Materials Co., Ltd.
- Sociedad Química y Minera de Chile S.A. (SQM)
- Talison Lithium Pty Ltd
Recent Industry Developments
- October 2026: EnergyX signed a 10-year binding supply agreement with Trafigura valued at $2 billion. The agreement covers planned lithium carbonate and lithium hydroxide production from projects in Chile and the United States. Deliveries depend on the development of the planned facilities. (source: energyx.com)
- September 2026: E3 Lithium signed a non-binding memorandum of understanding with India's Epsilon CAM. The proposed agreement covers potential annual supplies of up to 5,000 metric tons of lithium carbonate from E3's Clearwater project in Alberta over five years. (source: reuters.com)
- August 2026: LG Energy Solution signed a 10-year offtake agreement with Smackover Lithium. The agreement is for 8,000 metric tons of battery-grade lithium carbonate annually. The material will come from the South West Arkansas project and support battery production in the United States. (source: lgensol.com)
Future Outlook
The lithium chemicals market is expected to benefit from the growing demand for batteries in electric vehicles and energy storage. Energy storage systems are a growing demand driver along with electric vehicles. Lithium carbonate is projected to remain significant for the manufacture of LFP batteries, whereas lithium hydroxide will be required for high-nickel cathode production. Direct lithium extraction and battery recycling can become new sources of supply. Investments in local refining facilities across various regions may also shape the lithium chemicals industry in the future.
Research Methodology
The lithium chemicals market estimate is based on a combination of top-down and bottom-up approaches. The study covers market revenue in USD billion from 2021 to 2034, with 2025 as the base year. The analysis covers lithium carbonate, hydroxide, chloride, metal, fluoride, and other lithium compounds.
Data Mining and Secondary Sources: The research draws on company annual reports, financial filings, and official industry publications. Data from the International Energy Agency (IEA), the U.S. Energy Information Administration (EIA), and government mining agencies is also used. Data from these sources helps assess lithium production, trade, and consumption. Industry reports and lithium price assessments provide additional information on market prices and supply conditions.
Primary Research: Interviews with industry participants help validate the findings from secondary research. Relevant participants include lithium producers, chemical processors, battery material suppliers, cell manufacturers, and distributors. Discussions focus on pricing, production capacity, purchasing patterns, and demand across key applications.
Triangulation and Validation: The supply-side numbers are triangulated against the demand generated by battery manufacturers and industrial uses. Company-level production figures are analyzed together with the trade and consumption data. Discrepancies between various sources are evaluated before preparing the estimates. The results are arranged by product type, end-use industry, end-user, and geography for consistency.
Lithium Chemicals Market Report Scope
| Report Attributes | Details |
| Market Size Value in 2025 | USD 38.88 billion |
| Market Size Value in 2026 | USD 46.26 billion |
| Lithium Chemicals Market Forecast 2034 | USD 190.23 billion |
| CAGR | 19.3% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Lithium Chemicals Market FAQ's
The lithium chemicals market size was valued at USD 38.88 billion in 2025. The market is projected to reach USD 190.23 billion at a CAGR of 19.3% from 2026 to 2034.
Lithium compounds are chemicals that are utilized to manufacture various industrial products. Common types of lithium compounds include lithium carbonate, lithium hydroxide, lithium chloride, and lithium fluoride. They are used by battery manufacturers in rechargeable batteries. Other industries use them to manufacture products like glass and greases.
The application of lithium carbonate can be seen in the manufacturing of LFP batteries and glass. Lithium hydroxide is used in the manufacturing of cathodes of high-nickel batteries, including EV batteries. The choice depends upon the type of battery being manufactured.
Battery-grade lithium carbonate in China was assessed at approximately RMB 98,300 per tonne on 26 October 2026, down from about RMB 210,000 in mid-May and RMB 127,750 on 30 September. Prices vary by grade, location and contract terms, so this is a market benchmark, not a universal price.
The carbonate segment led with an 60.3% share in 2025. Lithium carbonate is one of the main raw materials used to manufacture cathodes for lithium-ion batteries. The hydroxide segment is projected to grow at an 21.4% CAGR. Lithium hydroxide is mainly used to make cathode materials in lithium-ion batteries.
Lithium prices declined in late 2026 owing to concerns regarding demand and oversupply. There were also uncertainties regarding inventory estimates during September. Weak battery demand expectations also weighed on prices.
Asia Pacific led the global lithium chemicals market with a 59.8% share in 2025. The region’s lead reflects its concentrated battery manufacturing base and China’s lithium processing capacity, supported by Australian spodumene supply.
Key lithium chemicals companies include Albemarle Corporation; Critical Elements Lithium Corporation; Ganfeng Lithium Group Co., Ltd.; Infinity Lithium Corporation Limited; Lithium Americas Corp.; Mody Chemi-Pharma Limited; Neometals Ltd; PLS Group Limited; Rio Tinto Lithium; Sichuan Brivo Lithium Materials Co., Ltd.; Sociedad Química y Minera de Chile S.A. (SQM); and Talison Lithium Pty Ltd.
There has been an increase in the adoption of electric vehicles worldwide. This has resulted in high demand for lithium chemicals. The market is also benefiting from the growing consumer electronics industry. Investments in new gigafactories further drive market growth.
Lithium chemicals are produced from lithium-containing sources such as spodumene and lithium brine. The extraction process involves treating lithium ores or concentrating lithium brines. Further chemical processes produce materials such as lithium carbonate and lithium hydroxide. The materials may be purified for use in batteries.
Download Sample Report of Lithium Chemicals Market
Please fill out the form to request a customized copy of the research report.


