Edge AI Accelerator Market Size, Share, Trends & Forecast, 2026–2034
REPORT DETAILS
Edge AI Accelerator Market Summary
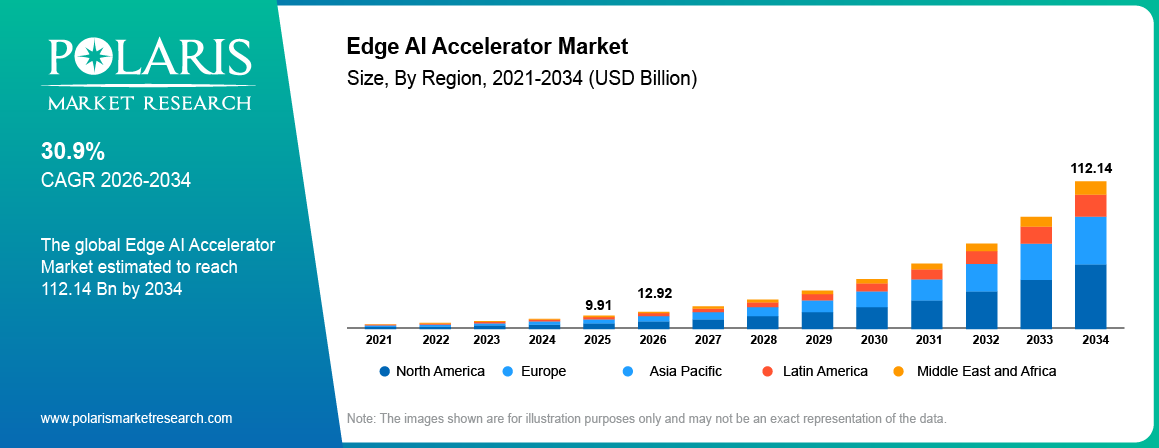
Edge AI accelerator market size was valued at USD 9.91 billion in 2025 and is projected to exhibit a CAGR of 30.9% from 2026 to 2034. The growth is driven by the rising adoption of wearable devices and smartphones. Increasing investments in smart home technology will also fuel market growth.
Market Statistics
Edge AI Accelerator Market Key Takeaways
- North America dominated the global market with 37.5% revenue share in 2025. The leading position is attributed to its strong technological ecosystem, robust investments in AI research, and early adoption of advanced computing solutions.
- The market in Asia Pacific is expected to grow at the highest CAGR of 34.2% during the projected period, owing to rapid digital transformation, expanding 5G networks, and aggressive industrial automation. China is estimated to dominate the region, supported by substantial investments in AI and semiconductor technologies.
- The Europe edge AI accelerator market is expected to register a CAGR of 29.8% during the forecast period. The growth is driven by the rising adoption of artificial intelligence and machine learning in automotive, industrial, and healthcare applications.
- The graphics processing unit (GPU) segment held a major market share of 42.6% in 2025. It is due to its unparalleled processing capabilities and flexibility in handling complex AI workloads at the edge.
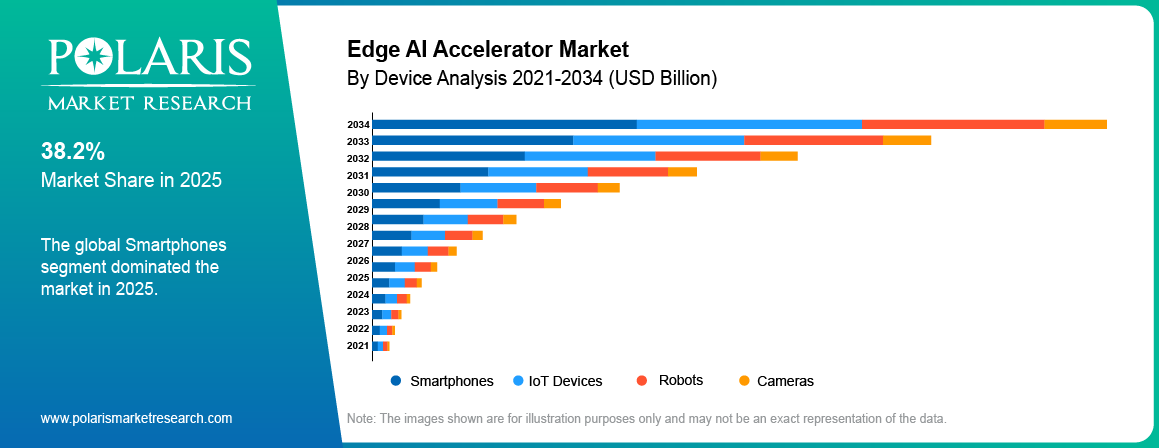
- The smartphone segment dominated the edge AI accelerator market with 38.2% share in 2025 due to the widespread integration of AI features and the proliferation of 5G technology.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
What is an Edge AI Accelerator?
An edge AI accelerator is a specialized hardware component designed to efficiently process artificial intelligence (AI) workloads, particularly on devices located at the edge of a network, such as smartphones, IoT sensors, and smart cameras. These accelerators are crucial for edge AI, which involves running AI algorithms directly on local devices rather than relying on cloud servers. This approach enables real-time data processing, reduced latency, enhanced data privacy, and lower bandwidth costs. These benefits make it ideal for applications requiring immediate responses and high reliability, such as autonomous vehicles and healthcare devices. Edge AI accelerators, often in the form of GPUs, TPUs, or NPUs, are optimized for parallel computation. They enable fast execution of machine learning tasks such as object detection and image classification. The usage of edge AI accelerators spans various industries and devices. They are used in smart speakers to quickly detect wake words, in wearables for real-time health monitoring, and in manufacturing for automated defect detection.For example, NVIDIA Jetson is a standalone System-on-Module (SoM) and features an integrated multi-core ARM CPU. Hailo-8 is a dedicated coprocessor and Neural Processing Unit that is typically deployed as an M.2 or PCIe add-on module that pairs with an external host CPU. (Source: arxiv.org, hailo.ai).
The growing focus on cloud computing worldwide is driving growth in the edge AI accelerator market. Cloud computing generates vast amounts of data that need real-time processing and analysis. Edge AI accelerators play a crucial role in this environment. They enable data processing closer to the source, reducing latency, and enhancing the efficiency of cloud operations. For example, NVIDIA Jetson is a standalone System-on-Module (SoM) and features an integrated multi-core ARM CPU. Hailo-8 is a dedicated coprocessor and Neural Processing Unit that is typically deployed as an M.2 or PCIe add-on module that pairs with an external host CPU. Moreover, edge AI accelerators enhance the reliability and security of cloud computing systems by processing data locally. This localized processing also mitigates the impact of network outages, ensuring continuous operation even when cloud connectivity is disrupted. These benefits offered by edge AI accelerators make them a critical component in cloud computing. Therefore, the demand for edge AI accelerators is increasing with the rising focus on cloud computing across the globe (Source: arxiv.org, hailo.ai).
Edge AI Accelerator vs Cloud AI Processing
| Criteria | Edge AI Accelerator | Cloud AI Processing |
| Latency | Milliseconds, on-device | Higher, dependent on network |
| Data privacy | Data stays on device | Data transmitted to servers |
| Connectivity dependence | Works offline | Requires stable connection |
| Compute ceiling | Bounded by device hardware | Effectively unlimited (scalable) |
| Cost model | Upfront hardware cost | Ongoing usage-based cost |
Source: Polaris Market Research Analysis
The edge AI accelerator market demand is driven by the increasing penetration of smartphones globally. Smartphones handle complex tasks such as real-time language translation, advanced photography, and augmented reality, which require instant data analysis. Edge AI accelerators enable these features by performing computations directly on the device. It reduces latency and improves user experience compared to cloud-dependent solutions. Additionally, smartphone applications increasingly rely on AI-driven features such as voice assistants, facial recognition, and predictive text. They must operate seamlessly even without internet connectivity. Edge AI accelerators keep these functions reliable by providing the computational power needed for real-time inference. According to the Indian Ministry of Statistics & Programme Implementation, 97.6% of population of age group 15-29 living in urban areas of India use smartphone as of 2025. As smartphone penetration grows globally, demand for edge AI accelerators is increasing (Source: pib.gov.in).
Market Dynamics
Driver: Increasing Adoption of Wearable Devices
Wearables such as fitness trackers and health monitors generate continuous streams of biometric data that require instant analysis. Edge AI in wearables enables these devices to process heart rate, sleep patterns, and activity metrics locally without relying on cloud servers. The technology ensures faster insights and reduces latency for critical health alerts. Privacy and security concerns further drive the shift toward edge AI processing in wearables. Health and fitness data are highly sensitive, and transmitting this information to the cloud increases exposure to breaches. Edge AI accelerators let wearables analyze data directly on the device, minimizing data transfers and helping comply with strict regulations such as HIPAA and GDPR. This localized processing builds user trust and meets growing regulatory demands, making edge acceleration essential for next-generation wearables. Thus, as the adoption of wearable devices increases globally, the demand for edge AI accelerators also increases.
Driver: Rising Investment in Smart Home
Smart home ecosystems rely on real-time decision-making for tasks such as security monitoring, energy management, and voice-controlled automation. Edge AI accelerators enable devices like smart cameras, thermostats, and speakers to analyze data locally, reducing dependence on cloud servers and minimizing latency, offering real-time decision-making. Energy efficiency and cost savings further fuel demand for edge AI solutions in smart homes. Cloud-based processing requires constant connectivity and increases operational expenses for manufacturers and users. Adoption of edge AI in smart homes helps optimize power usage by handling computations locally, extending device battery life, and reducing bandwidth costs. Hence, rising investment in smart homes is driving edge AI accelerator market revenue.
Driver: On-device Generative AI/LLM Inference
The increasing adoption of generative AI/large language models (LLM) across industry is driving demand for edge AI accelerators. A growing number of AI inferencing workloads are being offloaded from the cloud to end devices, including smartphones, cameras, cars, and industrial machinery. This trend is driven by the need to reduce latency, improve response time, and enhance privacy. However, these AI workloads are extremely compute intensive. Edge AI accelerators enable such devices to perform AI inference at higher speeds while being power efficient. There is an increased demand for such edge AI accelerators with large number of devices adopting AI functionalities, thereby driving the growth.
Restraint: High Development and BOM Cost
High development and bill of materials (BOM) cost is restraining the growth rate of the edge AI accelerator market. The development of a dedicated application-specific integrated circuit (ASIC) for AI acceleration requires extremely high R&D, testing, software development, and manufacturing costs. Similarly, the utilization of such ICs on end devices increases the overall BOM cost of the product, which could make such products cost-prohibitive for some applications. Companies targeting price-sensitive markets would prefer lower-cost CPU-based solutions, thereby restraining the industry growth.
Restraint: Limited Power and Thermal Capacity
Limited power and thermal capacity of devices is limiting the growth of the edge AI accelerator market. Edge AI accelerators target a wide range of devices including smartphones and wearable gadgets, which have lower power and thermal budgets. AI processing is a power-intensive task that could drain batteries faster and generate extreme heat. Therefore, manufacturers need to optimize the power consumption of accelerators to ensure longer battery life and stable performance. The need for thermal management in small-sized devices further restricts the adoption of large power accelerators, thereby restraining the market growth.
Opportunity: Neuromorphic/Spiking-Architecture Accelerators
Neuromorphic computing and spiking-architecture accelerators are a significant opportunity for manufacturers in the ultra-low-power segment. These accelerators are extremely power-efficient and are suitable for a wide range of applications, including wearables, smart sensors, robots, and video surveillance. These accelerators mimic the human brain's information-processing mechanism, reducing unnecessary computation. Manufacturers can develop and target these low-power accelerators for computer vision and voice-based applications. Rising demand for always-on AI is expected to drive adoption of such accelerators across a wide range of applications. A wide range of companies would benefit from neuromorphic accelerators, creating significant growth opportunities for manufacturers in the ultra-low-power segment.
Segmental Analysis
Market Evaluation by Processor
Based on processor, the edge AI accelerator market is divided into central processing unit (CPU), graphics processing unit (GPU), application-specific integrated circuits (ASICs), and field-programmable gate array (FPGA). The graphics processing unit (GPU) segment held a major market share of 42.6% in 2025 due to its unparalleled processing capabilities and flexibility in handling complex AI workloads at the edge. GPUs are highly efficient in processing multiple data streams simultaneously. This makes them ideal for running deep learning algorithms and neural networks required in edge computing scenarios. The broad compatibility of GPUs with AI frameworks such as TensorFlow and PyTorch further accelerated their adoption across industries such as autonomous vehicles, smart surveillance, and robotics. Companies increasingly favored GPUs for their ability to deliver high throughput and low latency, crucial for real-time inference at the edge. Additionally, advancements in power efficiency and thermal design allowed GPUs to meet the stringent requirements of edge environments without compromising performance.
The application-specific integrated circuits (ASICs) segment is expected to grow at a robust CAGR of 32.4% in the coming years, driven by their optimized architecture for specific AI tasks and unmatched energy efficiency. ASICs significantly reduce inference time and power consumption by eliminating the overhead of general-purpose hardware. Thus, they have become ideal for deployment in power-sensitive and space-constrained devices such as smart cameras, wearables, and industrial IoT devices. Major tech firms are heavily investing in custom AI chips tailored for edge inference, enabling faster processing, lower costs, and improved scalability. Hence, there is a rising demand for application-specific integrated circuits (ASICs) across end-use industries.
GPU vs ASIC vs FPGA vs CPU: Which Processor Is Best for Edge AI?"
| Processor | Strength | Best Fit | Trade-off |
| GPU | High throughput, broad framework support | Vision, robotics, autonomous vehicles | Higher power draw |
| ASIC | Best energy efficiency for fixed tasks | Wearables, smart cameras, industrial IoT | Inflexible once fabricated |
| FPGA | Reconfigurable, low-latency | Prototyping, defense, telecom edge nodes | Higher unit cost, harder to program |
| CPU | General-purpose, easiest integration | Low-complexity inference, legacy devices | Lowest AI throughput per watt |
Source: Polaris Market Research Analysis
Market Insight by Device
In terms of device, the market is segregated into smartphones, IoT devices, robots, and cameras. The smartphone segment dominated the edge AI accelerator market share by holding 38.2% in 2025 due to the widespread integration of AI features and the proliferation of 5G technology. Manufacturers embedded advanced neural processing units (NPUs) into mobile chipsets, enabling on-device inference for tasks such as real-time language translation, facial recognition, and camera scene detection. Consumers increasingly demanded enhanced user experiences powered by AI, prompting smartphone manufacturers to prioritize edge computing capabilities. The rapid global adoption of 5G further accelerated the demand for smartphones, contributing to edge AI accelerator market expansion.
The IoT devices segment is estimated to grow at a robust CAGR of 34.1% during the forecast period. The growth is fueled by their growing presence in smart homes, industrial automation, and connected healthcare. Developers are designing IoT devices with energy-efficient AI chips capable of handling inference tasks such as anomaly detection, predictive maintenance, and environmental monitoring without relying on cloud connectivity. Governments and enterprises are heavily investing in smart infrastructure, further boosting demand for intelligent edge devices, including IoT devices.
Market Insight By Power Consumption
In terms of power consumption, the edge AI accelerator market is segmented into <1W, 1-3W, 5-10W, 3-5W, >10W. The 5-10W segment accounted for a 38.6% share in 2025, driven by the demand for better AI performance at the edge. Industrial machinery requires heavy-duty edge processors to enable effective monitoring and automation. Similarly, smart cameras also require improved AI performance to enable better video analysis and recognition. Automotive systems are further expected to drive the growth of the 5-10W segment as connected cars and advanced driver-assist systems adopt AI to improve performance. Edge servers and gateways further require heavy-duty accelerators to enable better processing at the edge, thereby driving the segment growth.
The <1W segment is expected to witness growth of CAGR 31.8% driven by the demand for lower power accelerators in a variety of battery-powered and space-constrained devices. Wearables are expected to benefit from lower power accelerators as they enable better AI processing at the edge with reduced power consumption. Smart sensors further utilize AI processing at the edge to ensure improved performance. Earbuds and other small devices are also adopting AI to improve the performance. Moreover, the proliferation of the IoT has created a demand for lower power accelerators as the gadgets offer better performance while being battery-powered and placed in remote locations
Regional Analysis
By region, the edge AI accelerator market report provides insight into North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. North America held the largest edge AI accelerator market share of 37.5% in 2025. The dominance is attributed to its strong technological ecosystem, robust investment in AI research, and early adoption of advanced computing solutions. The U.S. led the regional market. This is driven by the presence of major semiconductor companies, such as NVIDIA, Intel, and AMD, along with prominent cloud and AI service providers. These firms continuously innovated to deliver high-performance, low-latency edge computing solutions tailored for applications in autonomous vehicles, smart cities, and defense systems. Government initiatives are promoting AI development, such as the National AI Initiative Act. Such activities played a crucial role in accelerating the deployment of edge AI accelerators. Furthermore, an established infrastructure and high penetration of connected devices in the region allowed enterprises across industries to adopt edge AI accelerators. For instance, according to data published by the Pew Research Center, 91% of Americans own a smartphone as of June 2025 (Source: pewresearch.org).
The Asia Pacific edge AI accelerator market is expected to register a CAGR of 34.2% during the projected period. The growth is driven by rapid digital transformation and expanding 5G networks. Also, aggressive adoption of industrial automation across countries fuels the regional market expansion. China dominated the region in 2025. It is supported by substantial government funding and a vast manufacturing base. Also, the strategic focus of companies such as Huawei, Alibaba, and Baidu on AI and edge technologies boosts the China edge AI accelerator market growth. The country has integrated smart surveillance systems, autonomous mobility platforms, and AI-driven manufacturing at a large scale, contributing to market expansion. South Korea, Japan, and India are further making substantial advancements in edge AI accelerators. They are making significant investments in smart infrastructure and localized AI innovation.
The Europe edge AI accelerator market is expected to witness a CAGR of 29.8% during the projected period. This is driven by the rising adoption of artificial intelligence and machine learning in automotive, industrial, and healthcare applications. The region’s well-established automotive sector creates a strong demand for localized AI processing in cars. Europe’s growing trend toward smart manufacturing further fuels demand for accelerators that process data closer to the source in real-time. Enterprises are increasingly relying on on-premise AI processing solutions to reduce exposure of private data to external platforms. This is due to strict data privacy laws. Additionally, there is a growing demand for smart devices in the region, including connected gadgets and AI-equipped healthcare machinery. Additionally, increased investment in research and development in AI, robotics, and advanced semiconductors is expected to further fuel the market growth.
The Middle East and Africa edge AI accelerator market is expected to witness a growth rate of 27.6% CAGR during the forecast period. The growth is fueled by rising investments in smart systems and devices, security systems, and connected devices. Governments in the Middle East are investing heavily in AI-based technologies for transportation, public safety, and city management. The growing popularity of smart cameras and sensors creates demand for accelerators that process data closer to the source. Additionally, the rising adoption of connected devices and gadgets is expected to fuel the demand for accelerators. Moreover, demand from African enterprises for AI-driven solutions in agriculture, healthcare, and the telecommunication industry drives the market growth. Saudi Arabia is driving the adoption of artificial intelligence, smart cities, and digital transformation to further invest in edge AI, transportation, and security. The United Arab Emirates (UAE) is also embracing artificial intelligence in its smart cities, autonomous transportation, security, and connected infrastructure to meet the demand for high-performance edge AI accelerators.
The Latin America edge AI accelerator market is expected to record a CAGR of 29.2% during the forecast period. Growing demand for smart devices, connected gadgets, smartphones, and automotive systems drives the regional market growth. The region is witnessing a rise in the adoption of AI and robotics in its industries and manufacturing companies. The market is expected to benefit from the rising investment in smart devices and gadgets in the region. The popularity of smart, connected, and autonomous cars drives the demand for accelerators in Latin America. Additionally, the growing adoption of security cameras and systems is expected to fuel the demand for accelerators, thereby driving the industry growth. Brazil is an emerging market due to the growing investments in artificial intelligence (AI), industrial automation, smart cities, and connected things in diverse sectors such as manufacturing, agriculture, and transport. Argentina is also embracing AI and connected devices in various industries, including agriculture, telecommunication, and manufacturing, which is expected to fuel the demand for AI chips and edge-based solutions in the forecast period.
Impact of Regulatory & Data Privacy Policies
The regulatory and data-privacy landscape for edge AI accelerators is significantly shaped by the EU AI Act, the GDPR, and a growing number of U.S. state-specific AI and consumer-privacy laws. The EU AI Act contains risk-specific requirements such as data governance, technical documentation, human oversight, cybersecurity, and robustness. These requirements directly apply to high-risk AI systems, including those deployed on edge accelerators from August 2027.At the same time, the GDPR promotes “privacy by design” (Art. 25) and data minimization (Art. 5). It favors on-device or edge execution to avoid cross-border data transfers and third-party processing. Colorado, California, and other states focus on introducing AI regulations and consumer-privacy laws. These laws cover automated decision-making, profiling opt-outs, biometric consent, and retention periods for sensitive data. This adds additional constraints on edge AI accelerator manufacturers, which must be prepared to implement secure boot, encrypted storage, audit trails, and data-flow tracking. Market players are required to ensure compliance in both the U.S. and EU ecosystems.
What are Edge AI Accelerator Use Cases?
Edge AI accelerators are used in wide range of devices for better performance and improved capabilities. The major use cases of edge AI accelerators are as followed:
| Domain | Named, Concrete Use Case | Typical Edge AI Workload | Example Hardware / Platforms |
| Autonomous Vehicles | L2/L2+ ADAS perception stack: camera + radar + LiDAR fusion for object detection, lane tracking, free-space estimation, collision avoidance, emergency braking. | Real-time multi-sensor perception pipeline (detection, tracking, fusion, trajectory planning). | NVIDIA DRIVE Orin/Xavier; TI TDA4VM (FastBEV); Qualcomm Snapdragon Ride; Mobileye EyeQ. |
| Smart Cameras | On-device person/vehicle detection and analytics for security/NVR (e.g., Frigate with Google Coral TPU; Ambarella H32-based AI cameras sending only metadata events). | Real-time video analytics: object detection, re-identification, counting, zone intrusion alerts. | Google Coral TPU; Hailo-8; NVIDIA Jetson Orin/Nano; TI TDA4VM; Ambarella H32 SoC; Sony IMX500 AI sensor. |
| Wearables | Edge AI-enabled ECG wearable for immediate cardiac-event detection; IMU-based fall detection and gait/frailty assessment on watches/patches. | Biosignal processing (ECG/PPG/IMU) with compact 1D CNN/TCN models for arrhythmia screening, fall alerts, activity recognition. | Ultra-low-power MCUs/MPUs with AI extensions (e.g., TI MSP, ARM Cortex-M with Ethos); specialized biosensor SoCs. |
| Industrial IoT | Predictive maintenance on motors/pumps via vibration and current signatures; arc-fault detection in electrical panels; visual inspection on production lines. | Time-series anomaly detection (vibration, current), visual defect detection, equipment health monitoring. | Hailo-8; NVIDIA Jetson; Google Coral; Microchip SAMA7G54; FPGA/SoC-based edge gateways. |
| Robotics & Intralogistics | Autonomous forklifts/AGVs/AMRs: segmentation, localization, collision avoidance in warehouses and yards (e.g., Locus Robotics AMRs; Outrider yard trucks; Caterpillar autonomous haul trucks). | On-robot perception and navigation stack (SLAM, obstacle detection, path planning). | NVIDIA Jetson; Hailo-8; Intel Movidius/Coral-class accelerators on embedded PCs. |
Source: Polaris Market Research Analysis
Competitive Analysis
The edge AI accelerator market is highly competitive, driven by the rapid adoption of AI technologies in various industries and the growing demand for real-time data processing at the edge. Top edge AI accelerator vendors are leveraging strategic mergers, acquisitions, partnerships, and collaborations to strengthen their market position and expand their product portfolios. These strategies enhance their technological offerings. They also enable them to cater to diverse industry needs, from autonomous vehicles to smart cities. Meanwhile, startups such as Hailo and Mythic are gaining traction through innovative architectures and securing funding via strategic alliances with automotive and consumer electronics giants.
EdgeCortix Inc., founded in July 2019, is a fabless semiconductor company headquartered in Tokyo, Japan. It has a global presence spanning Singapore, India, and the U.S. The company specializes in developing energy-efficient AI accelerators for edge computing. It addresses the growing need for near cloud-level performance with significantly reduced power consumption and cost. EdgeCortix's innovative approach integrates software-driven hardware design, exemplified by its proprietary dynamic neural accelerator (DNA) architecture and MERA Compiler framework. These technologies enable real-time processing of complex AI models, including Generative AI and Large Language Models (LLMs), in low-power environments. EdgeCortix's focus on co-developing software IP and chip design has positioned it as a major player in the edge AI market, solving critical challenges such as energy efficiency and latency.
Intel Corporation, a global semiconductor company, has been expanding its presence in the edge AI market through innovative solutions and strategic partnerships. Intel's edge AI offerings are designed to empower enterprises to integrate AI into existing infrastructure seamlessly, leveraging its extensive experience in edge computing. The company's Edge Platform is a modular and open software platform that enables businesses to build, deploy, manage, and scale edge and AI applications efficiently. This platform supports heterogeneous components, reducing total cost of ownership (TCO) and providing zero-touch, policy-based management across a fleet of edge nodes with a unified interface.
List of Key Edge AI Accelerator Companies
- Ambarella
- Apple Inc.
- BrainChip Holdings
- EdgeCortix Inc.
- Google LLC
- Hailo Technologies Ltd.
- Huawei Technologies Co., Ltd.
- IBM
- Infineon Technologies
- Intel Corporation
- Mythic
- NVIDIA Corporation
- Qualcomm Technologies, Inc.
- Rapidus Corporation
- SiMa.ai
- Untether AI
Edge AI Accelerator Industry Developments
- September 2026: Telit Cinterion launched its Edge AI SDK. The solution enabled machine learning models to run directly on selected 4G and 5G cellular modules. It combined AI processing and connectivity, reducing the need for external AI accelerators and simplifying industrial IoT deployments. (Source: prnewswire.com)
- September 2026: Nokia launched its Cognitive Operations platform combining edge computing, AI, and mission-critical communications. Its Cognitive Edge Node used on-device GPU-accelerated computing for real-time video analytics, predictive maintenance, safety monitoring, and AI processing in mining, public safety, and defense applications. (Source: telecomtv.com)
- September 2026: Amlogic launched its C305X2 and A123X 6nm SoCs. The new platforms integrated AI processing, low-power features, and advanced security for smart cameras, industrial vision, IoT devices, and battery-powered applications, supporting faster and more efficient on-device AI workloads. (Source: natlawreview.com)
- July 2026: Astronics launched its Ballard NG3 AI Accelerator. The rugged platform combined Hailo-8R AI processing with avionics computing for aerospace and defense applications. It delivered low-power, on-device AI for vision, sensor fusion, object detection, tracking, and decision support. (Source: investors.astronics.com)
- June 2025: EdgeRunner AI secured USD 12 million in Series A funding to develop air-gapped generative assistants designed for defense and healthcare applications. (Source: finance.yahoo.com)
Future Outlook
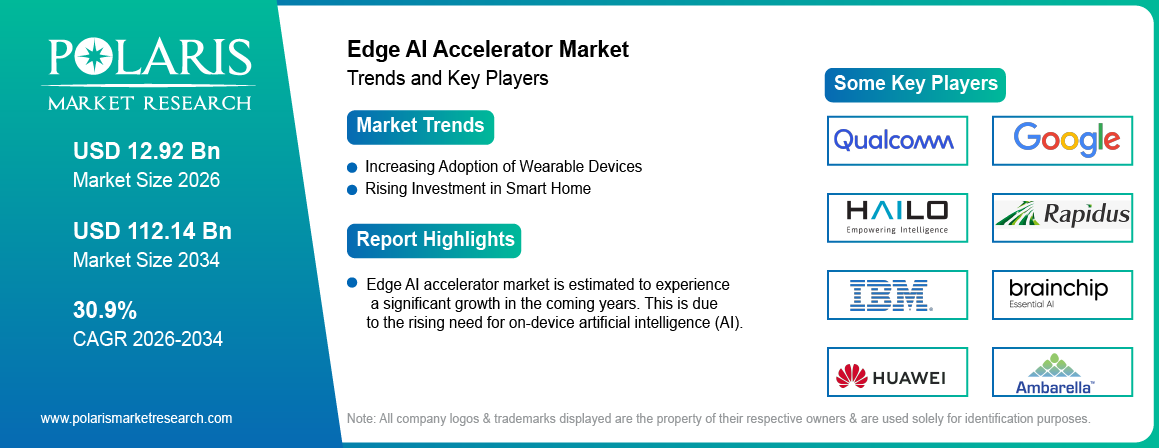
Edge AI accelerator market is estimated to experience a significant growth in the coming years. This is due to the rising need for on-device artificial intelligence (AI). The demand is anticipated to grow in diverse end-use industries, including smartphones, smart cameras and sensors, automotive, robotics, industrial, and IoT. Moreover, the need for low-power chips for faster AI processing and reducing energy consumption will propel the market growth. Additionally, with increasing emphasis on edge AI data privacy compliance, organizations are opting for localized processing of data. The manufacturers are also anticipated to develop application-specific accelerators for generative AI, computer vision, and other time-critical applications.
Edge AI Accelerator Market Segmentation
By Processor Outlook (Revenue, USD Billion, 2021–2034)
- Central Processing Unit (CPU)
- Graphics Processing Unit (GPU)
- Application-Specific Integrated Circuits (ASICs)
- Field-Programmable Gate Array (FPGA)
By Device Outlook (Revenue, USD Billion, 2021–2034)
- Smartphones
- IoT Devices
- Robots
- Cameras
By Power Consumption Outlook (Revenue, USD Billion, 2021–2034)
- <1W
- 1-3W
- 3-5W
- 5-10W
- >10W
By End Use Outlook (Revenue, USD Billion, 2021–2034)
- Healthcare
- Natural Language Processing (NLP)
- Retail
- Manufacturing
- Security and Surveillance
- Others
By Function Outlook (Revenue, USD Billion, 2021–2034)
- Training
- Inference
By Regional Outlook (Revenue, USD Billion, 2021–2034)
- North America
- U.S.
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Edge AI Accelerator Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 9.91 Billion |
| Market Size in 2026 | USD 12.92 Billion |
| Revenue Forecast By 2034 | USD 112.14 Billion |
| CAGR | 30.9% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021– 2024 |
| Forecast Period | 2026 – 2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Market Competitive Landscape, Growth Factors, and Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Edge AI Accelerator Market FAQ's
The global edge AI accelerator market size was valued at USD 9.91 billion in 2025 and is projected to grow to USD 112.14 billion by 2034.
The global market is projected to grow at a CAGR of 30.9% during the forecast period.
North America dominated the global market with 37.5% revenue share in 2025. The leading position is attributed to its strong technological ecosystem, robust investments in AI research, and early adoption of advanced computing solutions.
Some of the key players in the market are Apple Inc., EdgeCortix Inc., Google LLC, Hailo Technologies Ltd., Huawei Technologies Co., Ltd., IBM, Intel Corporation, Infineon Technologies, Mythic, NVIDIA Corporation, Qualcomm Technologies, Inc., Rapidus Corporation, SiMa.ai , Untether AI, BrainChip Holdings, and Ambarella.
The graphics processing unit (GPU) segment accounted for the largest market share of 42.6% in 2025, driven by increasing demand for high-performance AI computing.
The IoT devices segment is expected to grow at the fastest pace in the coming years.
It processes AI tasks locally on devices, enabling faster responses, lower power use, reduced data transfer, and improved privacy.
GPUs offer flexibility, ASICs provide efficiency, while FPGAs balance performance and flexibility for different edge AI applications.
Major applications include smartphones, smart cameras, vehicles, robotics, healthcare devices, industrial equipment, and IoT systems.
Download Sample Report of Edge AI Accelerator Market
Please fill out the form to request a customized copy of the research report.