Food Pathogen Testing Market Growth Analysis, Trends, 2026-2034
REPORT DETAILS
Food Pathogen Testing Market Summary
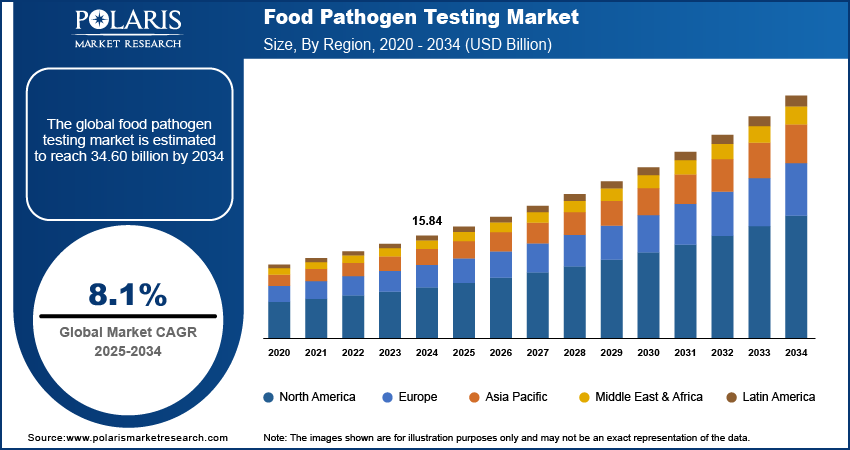
The global food pathogen testing market size was valued at USD 15.79 billion in 2025, growing at a CAGR of 7.75% during 2026–2034. Increasing foodborne disease cases and higher consumption of packaged and ready-to-eat foods are driving the need for robust pathogen testing solutions.
Market Statistics
Key Takeaways
- Asia Pacific, is projected to register a CAGR of 10.46% (2026–2034), driven by expanding food processing and stronger food safety investments.
- North America accounted for the largest revenue share of 37.0% in 2025, supported by stringent food safety regulations and rapid testing adoption.
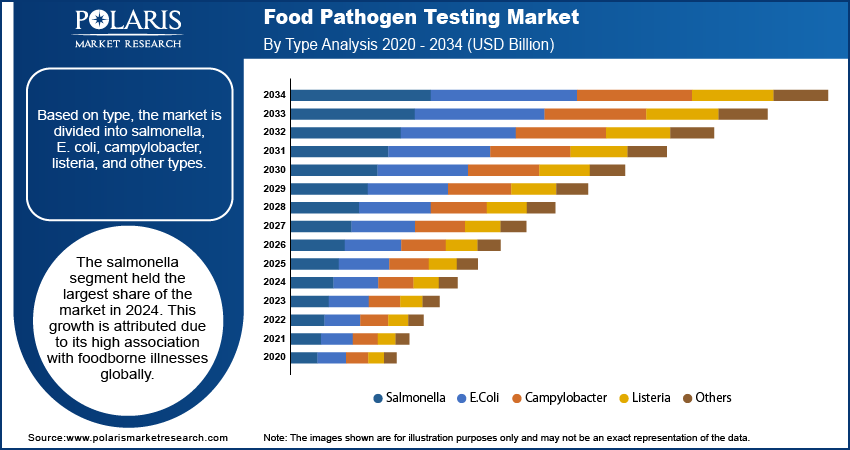
- The salmonella segment held the largest revenue share of 26.0% in 2025, owing to high foodborne infection rates and mandatory testing requirements.
- The quality control laboratories segment is expected to grow at a CAGR of 3.89% (2026–2034), driven by rising outsourcing of food safety testing services.
- The meat & poultry segment captured 31.0% revenue share in 2025, driven by high contamination risks and routine regulatory testing.
- The rapid technology segment accounted for 62.0% revenue share in 2025, fueled by increasing demand for fast and accurate pathogen detection.
Note: Figures and projections outlined in this report are the result of Polaris Market Research’s proprietary analytical processes, grounded in the latest available datasets and market observations.
Industry Dynamics
- Rising foodborne diseases are increasing the need for routine food pathogen testing to reduce contamination and meet food safety regulations.
- Growing consumption of packaged and ready-to-eat foods is increasing demand for pathogen testing across production and distribution.
- Expansion of global food trade is driving manufacturers to adopt pathogen testing to comply with import and export standards.
- Increasing use of rapid molecular diagnostics and automated testing systems is supporting faster and more accurate pathogen detection.
- High costs of advanced testing equipment and laboratory infrastructure limit adoption, especially among small manufacturers and developing countries.
AI Impact on Food Pathogen Testing Market
- AI-powered diagnostics improve pathogen detection speed and accuracy.
- Automated laboratory workflows reduce testing time and manual errors.
- Smart sensors enable real-time contamination monitoring across food production.
- AI-based traceability systems improve food safety and supply chain tracking.
What is Food Pathogen Testing?
Food pathogen testing is a diagnostic process applied to detect harmful microorganisms in food products across categories such as dairy food, meat, seafood, bakery products, packaged foods, and beverages. It involves microbiological, molecular, and immunological techniques to identify pathogens including salmonella, listeria monocytogenes, E. coli, and campylobacter. This is integrated into food safety testing protocols to ensure product quality, verify regulatory compliance, and minimize contamination risks throughout production and distribution stages.
Stricter global food safety standards and heightened consumer awareness are increasing the demand for efficient testing systems. Food manufacturers are adopting rapid detection methods with automated workflows to reduce turnaround time and limit recall exposure. Advancements in multiplex assays, sensor technologies, and laboratory automation are improving test reliability and throughput. Stakeholders are upgrading quality assurance infrastructure to meet with certification frameworks such as HACCP and ISO 22000, food pathogen testing remains an essential component of risk management and product integrity in modern food supply chains.
Source: Polaris Market Research Analysis
To Understand More About this Research: Download Sample Report
Food pathogen testing is increasingly being adopted across food processing, packaging, and distribution facilities to maintain hygiene, support quality assurance, and comply with evolving food safety regulations. Its use in dairy plants, meat processing lines, ready meals units, and beverage bottling systems helps detect microbial contamination at critical control points, reducing the risk of outbreaks and recall-related disruptions. Integration of automated detection platforms in production environments enables consistent monitoring and faster response times, helping manufacturers maintain throughput and meet certification requirements under frameworks such as FSMA and ISO 22000.
The growing focus on regulatory frameworks and traceability across the food industry is influencing technology investments in microbial testing infrastructure. Also, rapid test kits, real-time PCR systems, and lab-on-chip platforms are growing steadily due to companies focus on faster, more accurate methods for detecting pathogens. Procurement teams are choosing testing solutions that minimize false positives, support data traceability, and reduce operational delays. These efforts help to attain broader sustainability and compliance goals while contributing to long-term risk reduction and cost efficiency.
Rapid Testing vs Traditional Food Pathogen Testing
| Parameters | Rapid Testing | Traditional Testing |
| Detection Time | Provides faster detection results | Requires longer testing time |
| Accuracy | High sensitivity with PCR and molecular methods | Highly validated culture-based accuracy |
| Pathogen Identification | Enables rapid and precise pathogen identification | Identification takes more time |
| Operational Impact | Reduces food recall risks and production delays | May delay product release and recall decisions |
Industry Dynamics
Rising Incidence of Foodborne Diseases
Foodborne illnesses have emerged as a growing public health concern across both developed and developing regions. Contaminated food products remain a major source of gastrointestinal infections, often caused by pathogens such as salmonella, listeria monocytogenes, escherichia coli, and campylobacter.
Food manufacturers are strengthening their internal quality control protocols to reduce contamination risks and meet compliance requirements. The rising frequency of contamination-related recalls, legal penalties, and reputational damage is strengthening the need for consistent and precise pathogen detection systems. Laboratories and production facilities are increasingly integrating advanced diagnostic tools that offer rapid detection and quantifiable results. The emphasis on early identification and prevention of microbial hazards is expanding the adoption of food pathogen testing solutions across primary production, processing, and packaging operations.
Growth in Packaged and Ready-to-Eat Food Consumption
The global shift toward urban living, busy work schedules, and changing dietary preferences significantly increasing the demand for packaged and ready-to-eat (RTE) foods. These products are convenient but more prone to microbial contamination due to extended shelf life, complex supply chains, and multiple points of handling. With the rising volume of RTE foods across supermarket shelves, vending outlets, and food delivery platforms, food safety stakeholders are compelled to implement more frequent and rigorous pathogen testing to protect consumers and ensure brand integrity.
Producers of packaged and RTE foods are adopting standardized pathogen screening protocols at every critical control point, from raw material intake to final packaging. Maintaining microbial stability throughout storage and distribution is essential to prevent product recalls and retain consumer confidence. The increasing reliance on cold chain logistics and multi-region distribution adds further complexity to contamination control. As a result, companies are investing in advanced testing technologies that deliver high sensitivity, shorter detection times, and compatibility with high-throughput production environments. This market dynamic is driving continuous demand for scalable and reliable pathogen testing frameworks across the global food industry.
Source: Polaris Market Research Analysis
Segmental Insights
Type Analysis
The global segmentation, based on type includes, salmonella, E.Coli, campylobacter, listeria, and other type. The salmonella segment held the largest share of the market capturing 26.0% in 2025. This growth is attributed due to its high association with foodborne illnesses globally. It is frequently detected in meat, poultry, eggs, and dairy, leading to strict regulatory oversight. Food manufacturers prioritize salmonella testing to prevent large-scale recalls and ensure public safety. With growing global trade and stringent export regulations, the adoption of PCR and immunoassay-based kits is rising. Continued prevalence in high-risk food categories and regulatory pressure are expected to sustain its dominance over the forecast period.
The listeria segment is projected to grow at a robust pace of 9.26% CAGR in the coming years, due to its ability to thrive in cold environments and its severe impact on health in vulnerable groups. Its presence in refrigerated and ready-to-eat foods, such as soft cheeses and deli meats led to increased testing. Rapid detection methods, including real-time PCR and DNA-based assays are being adopted to meet compliance with food safety regulations. As manufacturers prioritize zero-tolerance policies for listeria, this segment is witnessing accelerated growth across cold-chain dependent product categories.
Food Test Analysis
The global segmentation, based on food test includes, meat & poultry, fish & seafood, dairy, processed food, fruits & vegetables, cereals & grains, and other food test. The meat and poultry segment dominated the market with 31.0% share in 2025, due to high contamination risks from pathogens such as salmonella and E. coli. Regulatory bodies in regions such as the US and EU mandate routine testing in meat-processing facilities, driving demand for advanced detection solutions. Producers are investing in rapid diagnostics to ensure quality and avoid shipment delays. The segment’s large-scale production volumes, complex supply chains, and public health sensitivity support its continued market leadership.
The dairy segment is projected to grow at a 6.82% CAGR during the assessment phase, driven by rising consumption of pasteurized and minimally processed dairy products. Products such as milk, yogurt, and cheese are prone to contamination by pathogens such as listeria and salmonella. Manufacturers are enhancing their testing capabilities using molecular diagnostics to comply with strict hygiene regulations. Demand for clean-label and high-quality dairy offerings further accelerates adoption of reliable pathogen screening solutions in export-focused markets.
Technology Analysis
The global segmentation, based on technology includes, traditional and rapid. The rapid segment was valued at 62.0% share in 2025, as food producers increasingly require faster and more efficient pathogen detection. These methods, including PCR and immunoassays, enable early identification, minimize downtime, and reduce risks of product recalls. Rapid solutions integrate easily into automated systems, making them suitable for high-throughput food manufacturing environments. Their enhanced accuracy and compatibility with digital reporting systems further support broad adoption across global facilities.
The traditional segment is expected to witness 4.56% CAGR, particularly in developing regions where cost-effectiveness and consumer familiarity drive adoption. Techniques such as culture-based identification are widely used in small and medium-sized enterprises due to their cost-effectiveness and regulatory acceptance. Government support for building food safety infrastructure and conducting laboratory-based testing programs contributes to continued demand in regions with limited access to advanced testing platforms.
Pathogen Type Analysis
The global segmentation, based on pathogen type includes, bacteria, viruses, protozoa, and fungi. The bacteria segment held 76.0% share in 2025, as it is responsible for the majority of foodborne illnesses. Common bacterial contaminants include salmonella, listeria, and E. coli, all requiring frequent testing in food production. Their widespread presence across different food types makes bacterial detection a routine requirement in compliance with global food safety standards. Bacterial testing dominates due to its relevance, regulatory focus, and technological advancement in detection methods.
The viruses segment is estimated to hold 10.68% CAGR, due to heightened focus on viral contamination risks such as norovirus and hepatitis A. Rising awareness of their impact on public health in ready-to-eat and frozen food items is pushing food companies to expand testing. Improved molecular diagnostic tools are enhancing the detection of viral pathogens, even at low concentrations. This segment is growing rapidly as food supply chains become more complex and require broader microbial risk coverage.
End User Analysis
The global segmentation, based on end user includes, food manufacturers, food retailers, quality control laboratories, and government agencies. The food manufacturers segment held 54.0% share in 2025 as it is directly responsible for product quality and safety. Routine pathogen testing is integrated into production workflows to comply with HACCP, ISO 22000, and regional food laws. Investment in high-throughput, rapid testing systems enables early contamination detection and prevention of costly recalls. Their central role in food safety and traceability drives their dominance in end-user adoption.
The quality control laboratories segment is estimated to grow at a 9.15% CAGR from 2026-2034, due to increased outsourcing of food safety testing. Small and mid-sized food businesses rely on third-party labs to meet compliance without investing in in-house infrastructure. Laboratories are adopting rapid and automated testing platforms to enhance service capacity and turnaround. Rising demand for third-party certifications and export compliance further boosts their role in the global food safety ecosystem.
Source: Polaris Market Research Analysis
Regional Analysis
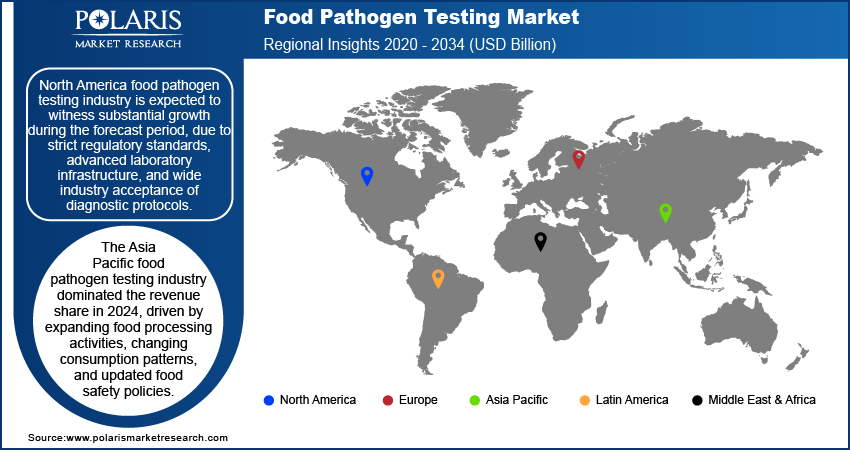
North America food pathogen testing industry held 37.0% share in 2025, due to strict regulatory standards, advanced laboratory infrastructure, and wide industry acceptance of diagnostic protocols. The region’s food manufacturers are adopting pathogen testing to meet compliance and avoid product recalls. Testing is conducted frequently across meat, poultry, dairy, and packaged foods. Agencies such as the FDA and USDA enforce safety checks at different stages of production. Increasing focus on product transparency and consumer safety is driving consistent use of rapid diagnostic tools. Investments in automation, traceability, and lab certifications are supporting food companies in maintaining quality and minimizing microbial risks.
US Food Pathogen Testing Market Insight
The US food pathogen testing market with 82.0% share in 2025 is driven by the strong food safety framework coupled with the strict laws such as Food Safety Modernization Act (FSMA) across the country. Thus, companies are extensively trying to improve testing protocols that drives the demand for the food pathogen testing in this region. Food processors are adopting rapid test kits and molecular detection tools across high-risk categories. The country also benefits from strong infrastructure, skilled workforce, and accredited laboratories. Increasing consumer demand for food safety and shelf-stable products is influencing companies to enhance quality controls. This industry continues to grow steadily through industry modernization and strict enforcement measures.
Asia Pacific Food Pathogen Testing Market Trend
The Asia Pacific food pathogen testing industry is expected to witness 10.46% CAGR, driven by expanding food processing activities, changing consumption patterns, and updated food safety policies. Countries such as China, India, and Japan are increasing investment in food testing infrastructure to meet domestic and international standards. Rapid urbanization and rising demand for packaged foods are creating a need for reliable contamination detection. Food exporters are also upgrading testing facilities to meet import regulations. Adoption of compact diagnostic tools is increasing in metropolitan food production zones. As regulatory awareness grows and production scales expand, the region is becoming a key focus for market participants.
Europe Food Pathogen Testing Market Overview
Europe food pathogen testing market growth with 29.0% share in 2025 is fueled by its strict safety regulations, high food quality standards, and regular industry audits. Countries such as Germany, France, and Italy conduct frequent microbiological testing across meat, dairy, and fresh produce categories. Food processors in the region follow EU safety directives that mandate pathogen detection before products reach retail distribution. The Energy Efficiency Act and sustainability-focused production standards are driving the use of automated testing systems. Adoption of rapid diagnostic tools is increasing across centralized laboratories and in-house testing units, improving contamination control and supply chain integrity.
Source: Polaris Market Research Analysis
Key Players & Competitive Analysis Report
The food pathogen testing industry is moderately consolidated, featuring global diagnostic firms, assay developers, and contract laboratories offering solutions across multiple food sectors. Competition focuses on test accuracy, processing speed, compliance, and integration with modern technologies. Companies are enhancing portfolios with rapid test kits, PCR tools, and multiplex platforms to meet food safety standards across categories such as meat, dairy, and seafood. Investments in AI-driven analytics, digital traceability, and automation-based processing support product differentiation. Strategic alliances, partnerships, and lab accreditations are improving market reach, while ISO 17025 and HACCP compliance remains a key priority. Localized testing infrastructure and region-specific panels are shaping procurement decisions.
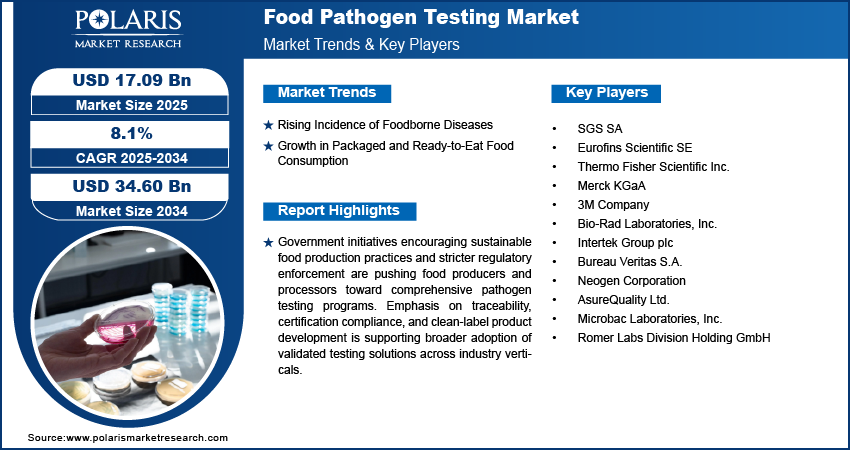
Key companies in the industry include SGS SA, Eurofins Scientific SE, Thermo Fisher Scientific Inc., Merck KGaA, 3M Company, Bio-Rad Laboratories, Inc., Intertek Group plc, Bureau Veritas S.A., Neogen Corporation, AsureQuality Ltd., Microbac Laboratories, Inc., and Romer Labs Division Holding GmbH.
Key Players
- SGS SA
- Eurofins Scientific SE
- Thermo Fisher Scientific Inc.
- Merck KGaA
- 3M Company
- Bio-Rad Laboratories, Inc.
- Intertek Group plc
- Bureau Veritas S.A.
- Neogen Corporation
- AsureQuality Ltd.
- Microbac Laboratories, Inc.
- Romer Labs Division Holding GmbH
Industry Developments
- January 2026: Hygiena launched AlerTox Sticks Peanut and DNAllergen2 PCR kits for rapid on-site allergen and contaminant detection. (Source: hygiena.com)
- June 2026: bioMérieux launched the GENE-UP TYPER SLM PCR assay for rapid Salmonella differentiation in food testing laboratories. (Source: biomerieux.com)
Challenges in Food Pathogen Testing Market
- High equipment costs: Advanced pathogen testing systems require significant investment.
- Regulatory compliance: Meeting different food safety regulations across countries is challenging.
- Limited infrastructure: Developing regions often lack modern testing laboratories and facilities.
- Slow traditional methods: Conventional microbiology testing increases turnaround time.
Future Outlook
The food pathogen testing market is expected to witness steady growth due to rising food safety concerns, increasing global food trade, stricter regulatory standards, and growing demand for packaged and ready-to-eat foods. AI-driven diagnostics, rapid PCR technologies, automated laboratory systems, smart biosensors, and real-time contamination monitoring are improving testing efficiency and accuracy. Increasing adoption of digital traceability, molecular diagnostics, and high-throughput testing platforms will further support market growth. These advancements will continue strengthening food safety, quality assurance, and regulatory compliance across the global food industry.
Food Pathogen Testing Market Segmentation
By Type Outlook (Revenue, USD Billion, 2021–2034)
- Salmonella
- E.Coli
- Campylobacter
- Listeria
- Other Type
By Food Test Outlook (Revenue, USD Billion, 2021–2034)
- Meat & Poultry
- Fish & Seafood
- Dairy
- Processed Food
- Fruits & Vegetables
- Cereals & Grains
- Other Food Test
By Technology Outlook (Revenue, USD Billion, 2021–2034)
- Traditional
- Quantitative Culture
- Qualitative Culture
- Rapid
- Convenience-based
- PCR
- Immunoassay
- Other Molecular based test
By Pathogen Type Outlook (Revenue, USD Billion, 2021–2034)
- Bacteria
- Viruses
- Protozoa
- Fungi
By End User Type Outlook (Revenue, USD Billion, 2021–2034)
- Food Manufacturers
- Food Retailers
- Quality Control Laboratories
- Government Agencies
By Regional Outlook (Revenue, USD Billion, 2021–2034)
- North America
- US
- Canada
- Europe
- Germany
- France
- UK
- Italy
- Spain
- Netherlands
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- Malaysia
- South Korea
- Indonesia
- Australia
- Vietnam
- Rest of Asia Pacific
- Middle East & Africa
- Saudi Arabia
- UAE
- Israel
- South Africa
- Rest of Middle East & Africa
- Latin America
- Mexico
- Brazil
- Argentina
- Rest of Latin America
Food Pathogen Testing Market Report Scope
| Report Attributes | Details |
| Market Size in 2025 | USD 15.79 Billion |
| Market Size in 2026 | USD 16.99 Billion |
| Revenue Forecast by 2034 | USD 30.91 Billion |
| CAGR | 7.75% from 2026 to 2034 |
| Base Year | 2025 |
| Historical Data | 2021–2024 |
| Forecast Period | 2026–2034 |
| Quantitative Units | Revenue in USD Billion and CAGR from 2026 to 2034 |
| Report Coverage | Revenue Forecast, Competitive Landscape, Growth Factors, and Industry Trends |
| Segments Covered |
|
| Regional Scope |
|
| Competitive Landscape |
|
| Report Format |
|
| Customization | Report customization as per your requirements with respect to countries, regions, and segmentation. |
Source: Polaris Market Research Analysis
Food Pathogen Testing Market FAQ's
The global market size was valued at USD 15.79 billion in 2025 and is projected to grow to USD 30.91 billion by 2034.
The global market is projected to register a CAGR of 7.75% during the forecast period.
North America accounted for the largest revenue share of 37.0% in 2025.
A few of the key players in the market are SGS SA, Eurofins Scientific SE, Thermo Fisher Scientific Inc., Merck KGaA, 3M Company, Bio-Rad Laboratories, Inc., Intertek Group plc, Bureau Veritas S.A., Neogen Corporation, AsureQuality Ltd., Microbac Laboratories, Inc., and Romer Labs Division Holding GmbH.
The salmonella segment held the largest revenue share of 26.0% in 2025.
The dairy segment is projected to grow at a significant pace of 6.82% CAGR during the assessment phase.
Download Sample Report of Food Pathogen Testing Market
Please fill out the form to request a customized copy of the research report.